ZYDUSLIFE
Equity Metrics
September 24, 2026
Zydus Lifesciences Limited
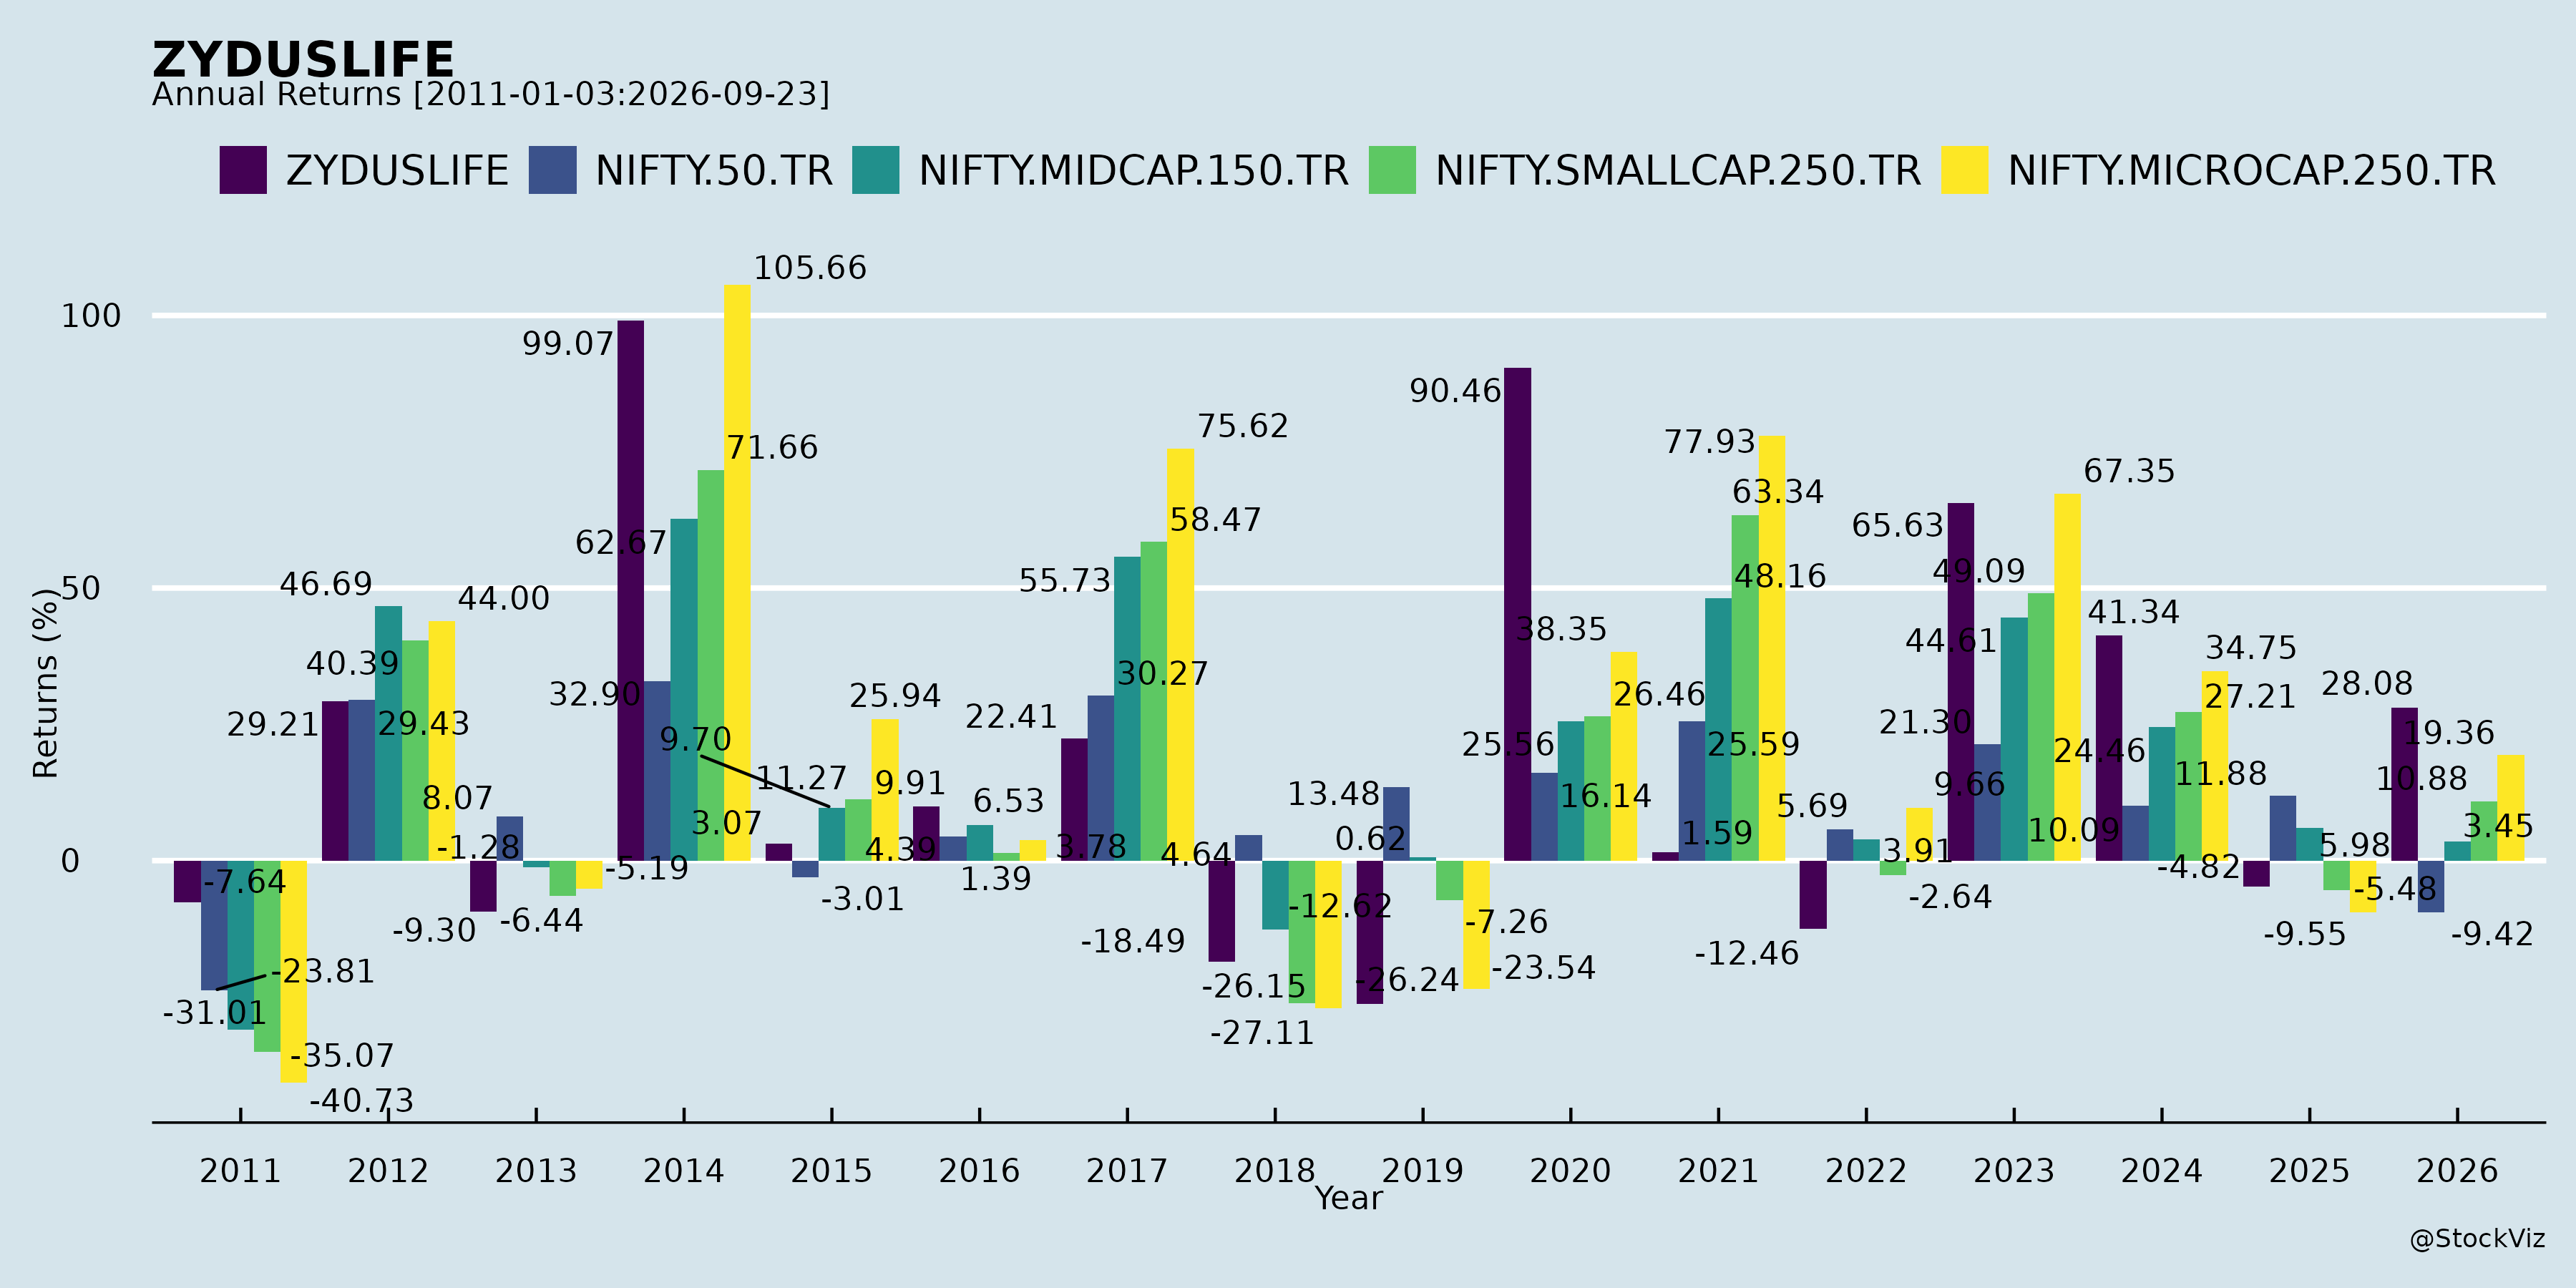
Annual Returns
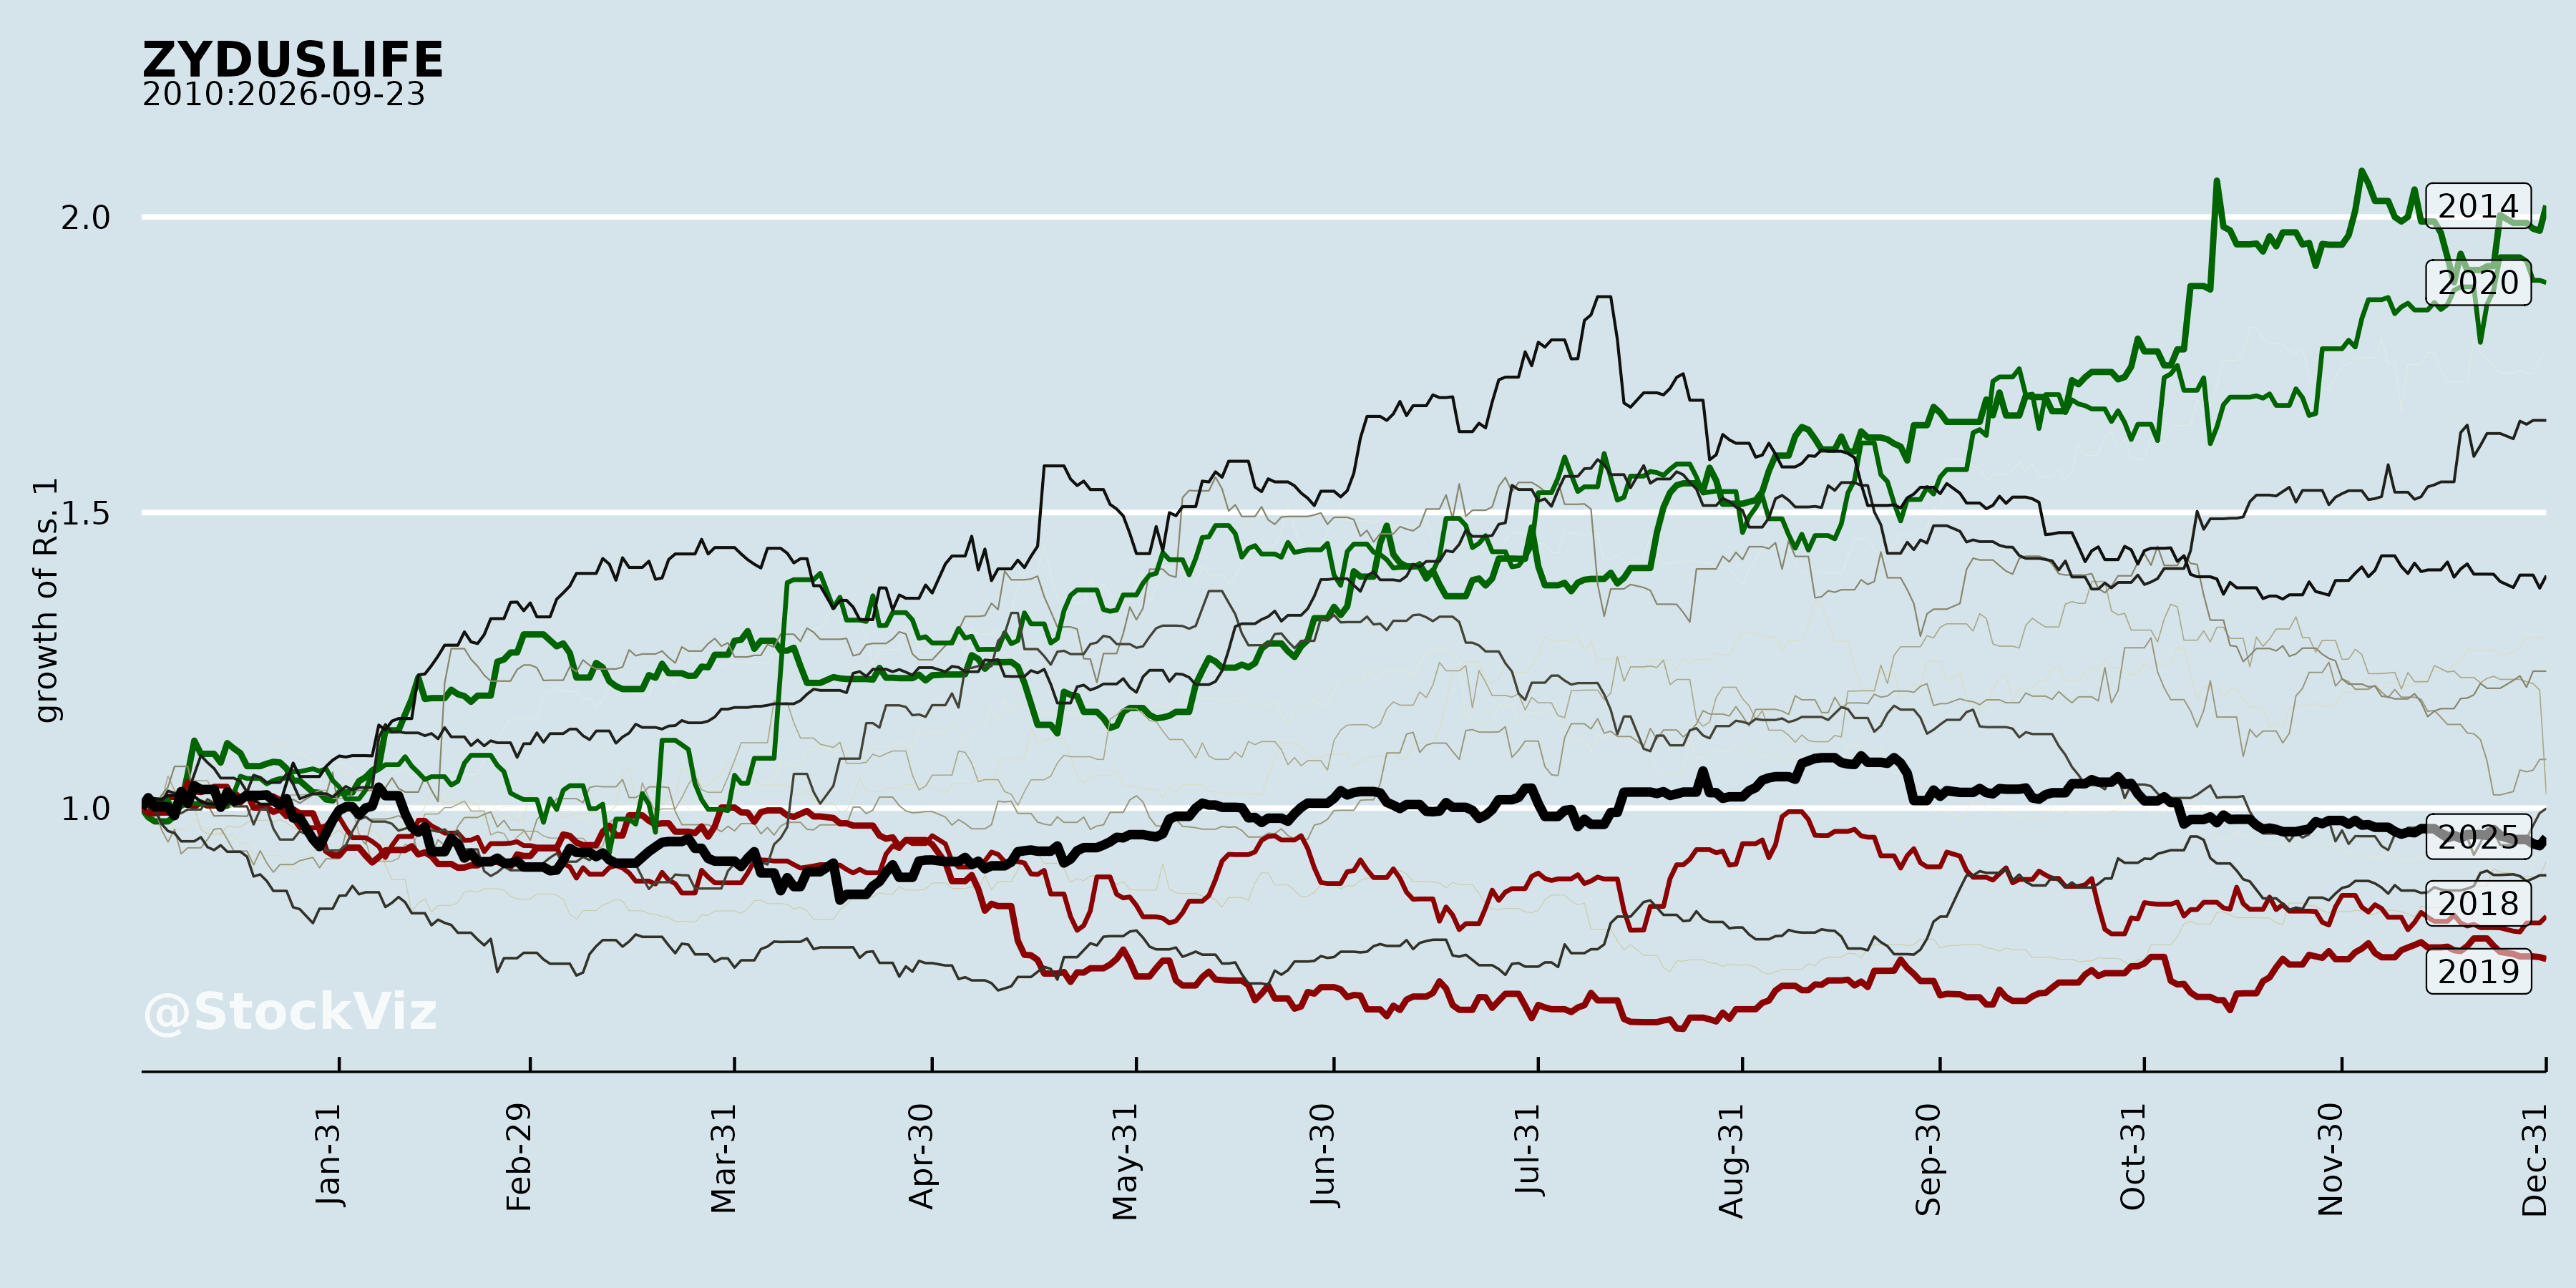
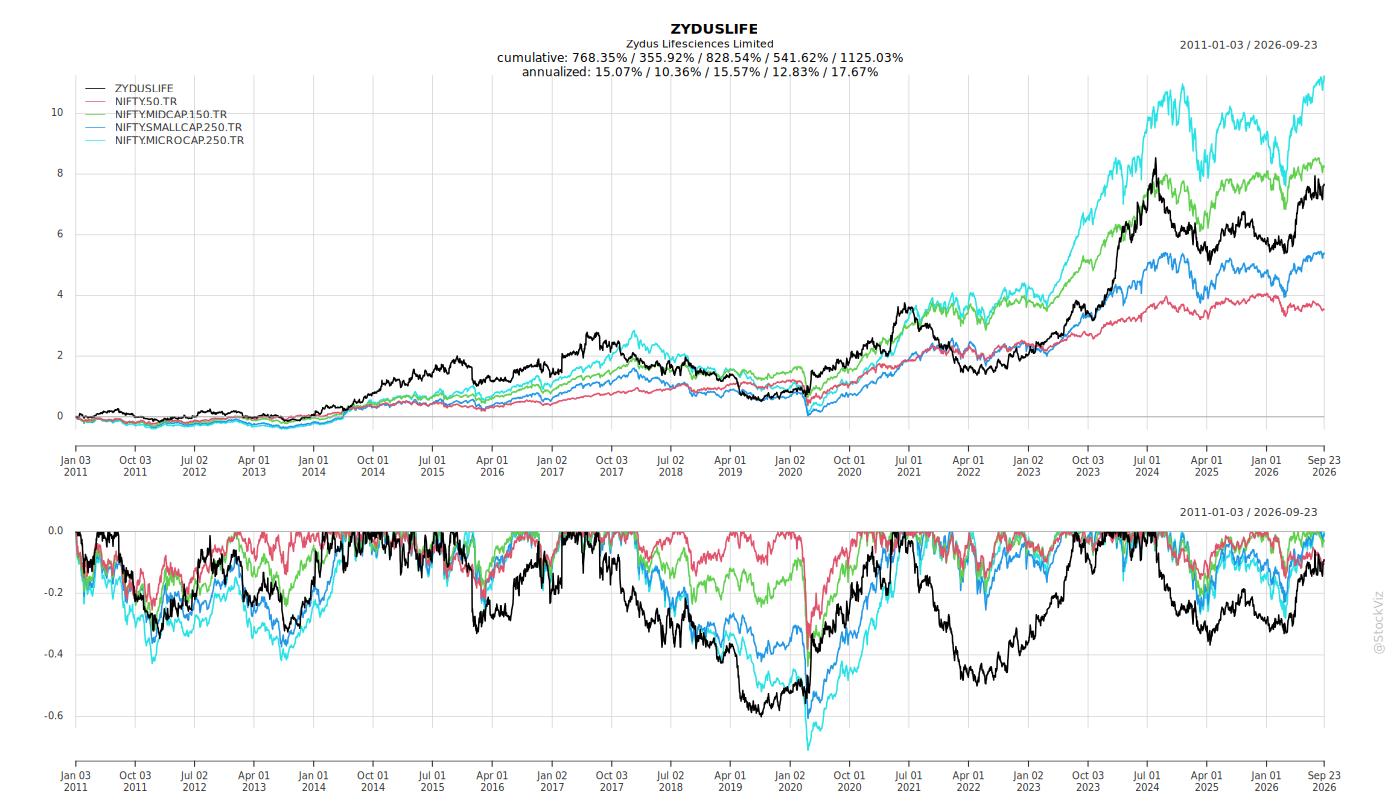
Cumulative Returns and Drawdowns
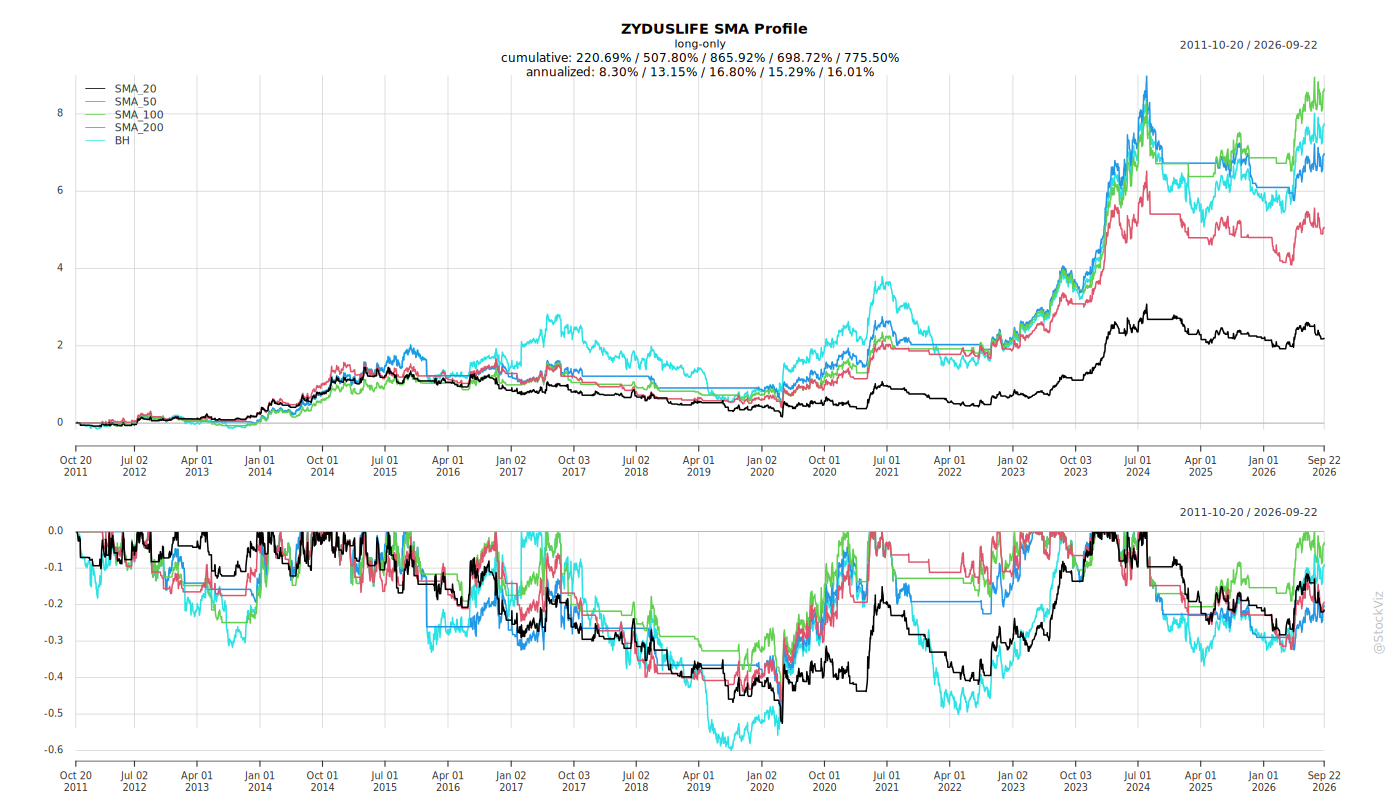
Fundamentals
Ownership
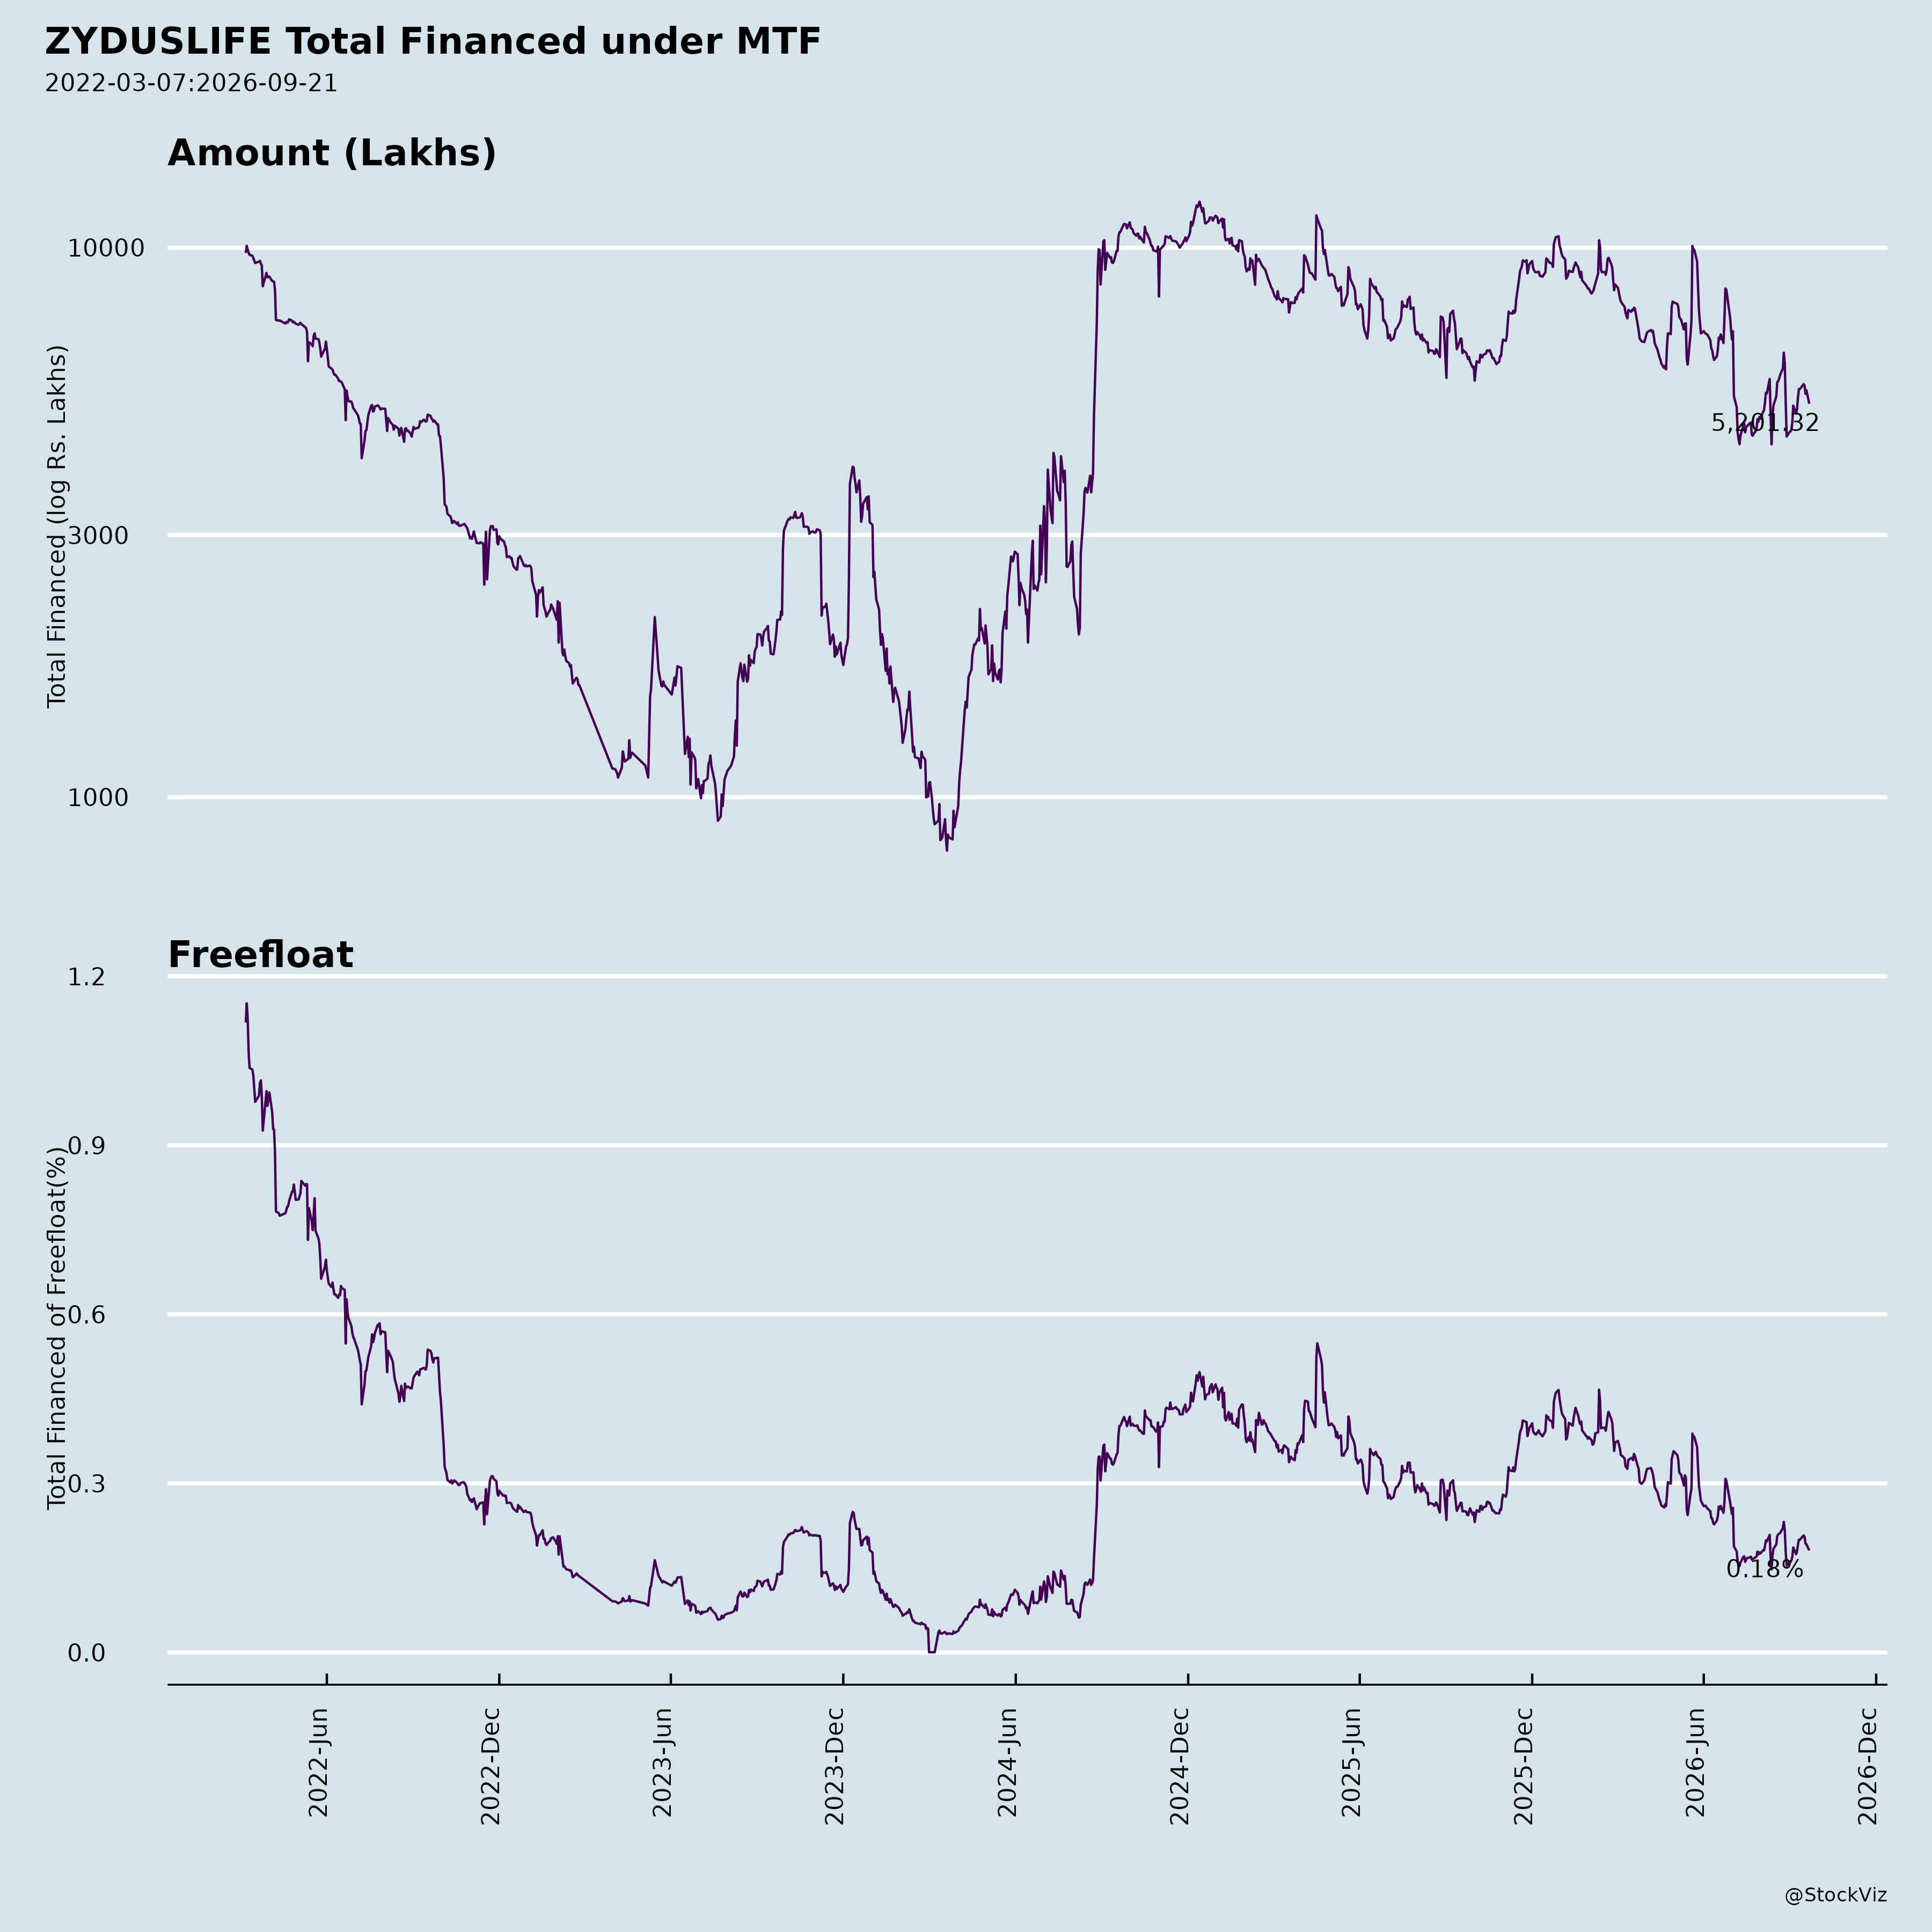
Margined
AI Summary
asof: 2026-09-14
Headwinds and Challenges
- US pricing, regulatory and market pressures: Shareholders at the Thirty First AGM on August 11, 2026 raised questions on the plan to handle US-pricing, regulatory and other market pressures, and on the effect of US tariffs on the business.
- USFDA inspections: Questions were raised regarding USFDA inspection at various manufacturing facilities.
- Lower standalone results: Shareholders questioned the lower standalone results.
- Litigation: Zydus Pharmaceuticals USA Inc. is party to litigation proceeding as part of MDL No. 2724 (Case No. 16-md-2724), In re Generic Pharmaceuticals Pricing Antitrust Litigation. A Settlement Agreement was entered to pay USD 5.9 million to resolve litigation matters with a putative class of Indirect Reseller Plaintiffs, without any admission of fault or wrongdoing.
- Saroglitazar Mg regulatory status: Saroglitazar Mg is an investigational compound in the United States and has not yet been approved by the U.S. Food & Drug Administration (FDA) or the European Medicines Agency (EMA) for the treatment of MASH and MASLD. MASH remains a significant global health burden affecting millions worldwide with limited approved treatment options.
- Forward-looking statement risk: Actual results, performance, or achievements could differ materially from those projected in forward-looking statements due to risks, uncertainties, and other factors.
Tailwinds and Growth Prospects
- Saroglitazar Mg clinical success: The EVIDENCES-X global Phase II(b) clinical trial of Saroglitazar Mg in MASH was successfully completed, achieving its primary endpoint of resolution of steatohepatitis with no worsening of fibrosis with a treatment difference of 26.5%. The trial enrolled 189 subjects across the USA, Turkey, and Argentina randomized in a 1:1:1 ratio to receive Saroglitazar 2 mg, Saroglitazar 4 mg, or placebo over 52 weeks. Saroglitazar Mg was approved by the Drug Controller General of India (DCGI) for the treatment of MASH and MASLD in India in 2020.
- India formulations: Scaling innovation and differentiated portfolios in India formulations.
- US generics and specialty: Scaling up differentiated generics and specialty businesses in the US.
- International markets: Expanding global portfolio and pipeline presence in international markets.
- Biosimilars and vaccines: Expanding biosimilars and vaccines portfolios.
- MedTech: Executing global MedTech strategy focusing on orthopaedics, cardiology, and nephrology.
- Inorganic growth: Leveraging acquisitions to fill portfolio gaps; shareholders asked about plans for further acquisitions (inorganic growth) and the shareholding of the Company in Assertio, the acquired entity.
- Global biosimilar strategy: Shareholders asked about global biosimilar strategy plans to reduce debt.
Key Risks
- Litigation risk: The MDL No. 2724 generic pharmaceuticals pricing antitrust litigation, partially resolved through a USD 5.9 million settlement with Indirect Reseller Plaintiffs.
- Regulatory approval risk: Saroglitazar Mg remains investigational in the US and EU, with no FDA or EMA approval for MASH and MASLD.
- US market pressures: Pricing, regulatory, tariff and market pressures in the US, and USFDA inspection outcomes at manufacturing facilities.
- Debt-related risk: Shareholder questions on plans to reduce debt and repay debt.
- Forward-looking statement risk: Projected results may differ materially due to risks and uncertainties.
Management Guidance Versus Observed Business Performance
- FY26 performance: Zydus Lifesciences achieved FY26 revenue of over US$ 3 billion (INR 2,71,484 Mn) and FY26 EBITDA of US$ 959 million (INR 84,751 Mn). It has 44 manufacturing facilities, 10 R&D centres, and approximately 30,000 employees globally. It holds strong market positions including #3 in the US Gx market by prescriptions and leading positions in various consumer wellness and specialty therapy segments.
- Saroglitazar NDA guidance: Management expects NDA approval for Saroglitazar by Q4FY27. This follows the completed EVIDENCES-X Phase II(b) trial, which achieved its primary endpoint with a 26.5% treatment difference. Data from the trial will be presented at upcoming scientific meetings and submitted for publication in a peer-reviewed medical journal, with further details to be presented at the upcoming Liver Congress.
- Ongoing guidance themes: Continuous targets for R&D investments, global product filings, and expansion in international markets and MedTech.
- AGM engagement: At the AGM on August 11, 2026, the Chairman briefed members on business performance, financial highlights and other major developments during the financial year ended March 31, 2026, and responded to shareholder questions on capacity expansion, standalone results, Assertio shareholding, domestic business growth prospects, export turnover and hedge strategy, global biosimilar strategy, debt reduction, US pricing and regulatory pressures, USFDA inspections, inorganic growth, R&D spends, debt repayment, and US tariff effects. The Managing Director also provided general guidance on future prospects.
- Dividend: A final dividend of Re. 1.00 (100%) per equity share for FY ended March 31, 2026 was declared and passed with 99.9999% votes in favour.
- Board and governance approvals: All 9 resolutions at the AGM were passed with requisite majority. Dr. Sharvil P. Patel was re-appointed as Managing Director for five years effective April 1, 2027 to March 31, 2032. Mr. Kulin S. Lalbhai was appointed as Independent Director for five years from May 19, 2026. Commission to non-executive directors of up to 1% of net profits per annum, capped at INR 40 million in any financial year, was approved for five years from April 1, 2026 to March 31, 2031.
- Q1 FY27 results: The Board at its meeting on August 11, 2026 approved the unaudited financial results for the quarter ended June 30, 2026, reviewed by the Audit Committee and with limited review reports from Deloitte Haskins & Sells LLP.
- Investor engagement: The Company is participating in the J.P. Morgan India Conference, 2026, on September 21, 2026.
Broker Narrative
The narrative shifted from an unqualified Buy built on broad-based revenue strength, US launch momentum, and a strong balance sheet to a cautious Accumulate dominated by margin compression, R&D drag, and US product erosion. Persistent themes include R&D investment pressure, US pricing/generic headwinds, India chronic portfolio growth, and the long-dated nature of US biosimilars. Early optimism about near-term US launches/one-time opportunities and vaccines was replaced by concerns over gRevlimid decline, a ~5% US CAGR, and delayed biosimilar scale-up.
Fears that came true
- Elevated R&D spend for NCE clinical trials materialized: R&D expense rose 32.3% YoY and helped drive a 755 bps EBITDA margin decline, and the last Accumulate call was a DISAPPOINTMENT (-7.4% actual).
- US price erosion/generic competition in key products materialized, with gRevlimid declining and US growth capped at ~5% CAGR, contributing to the negative actual return on the last call.
Optimism that failed
- The early US one-time opportunities and gRevlimid ramp-up did not prove durable, as gRevlimid subsequently declined and US growth slowed to ~5% CAGR.
- The TCV/MR vaccine revenue opportunity cited in the first report was not visible as a material growth driver by the last report.
- Near-term biosimilar scale-up did not materialize; the last report pushed meaningful US biosimilar scale-up to around CY29.
Broker Timeline
39 broker calls · 2023-05-19 to 2026-08-12
Copyright © 2023 SAS Data Analytics Pvt. Ltd. All rights reserved.