WIPRO
Equity Metrics
November 18, 2026
Wipro Limited
Computers - Software & Consulting
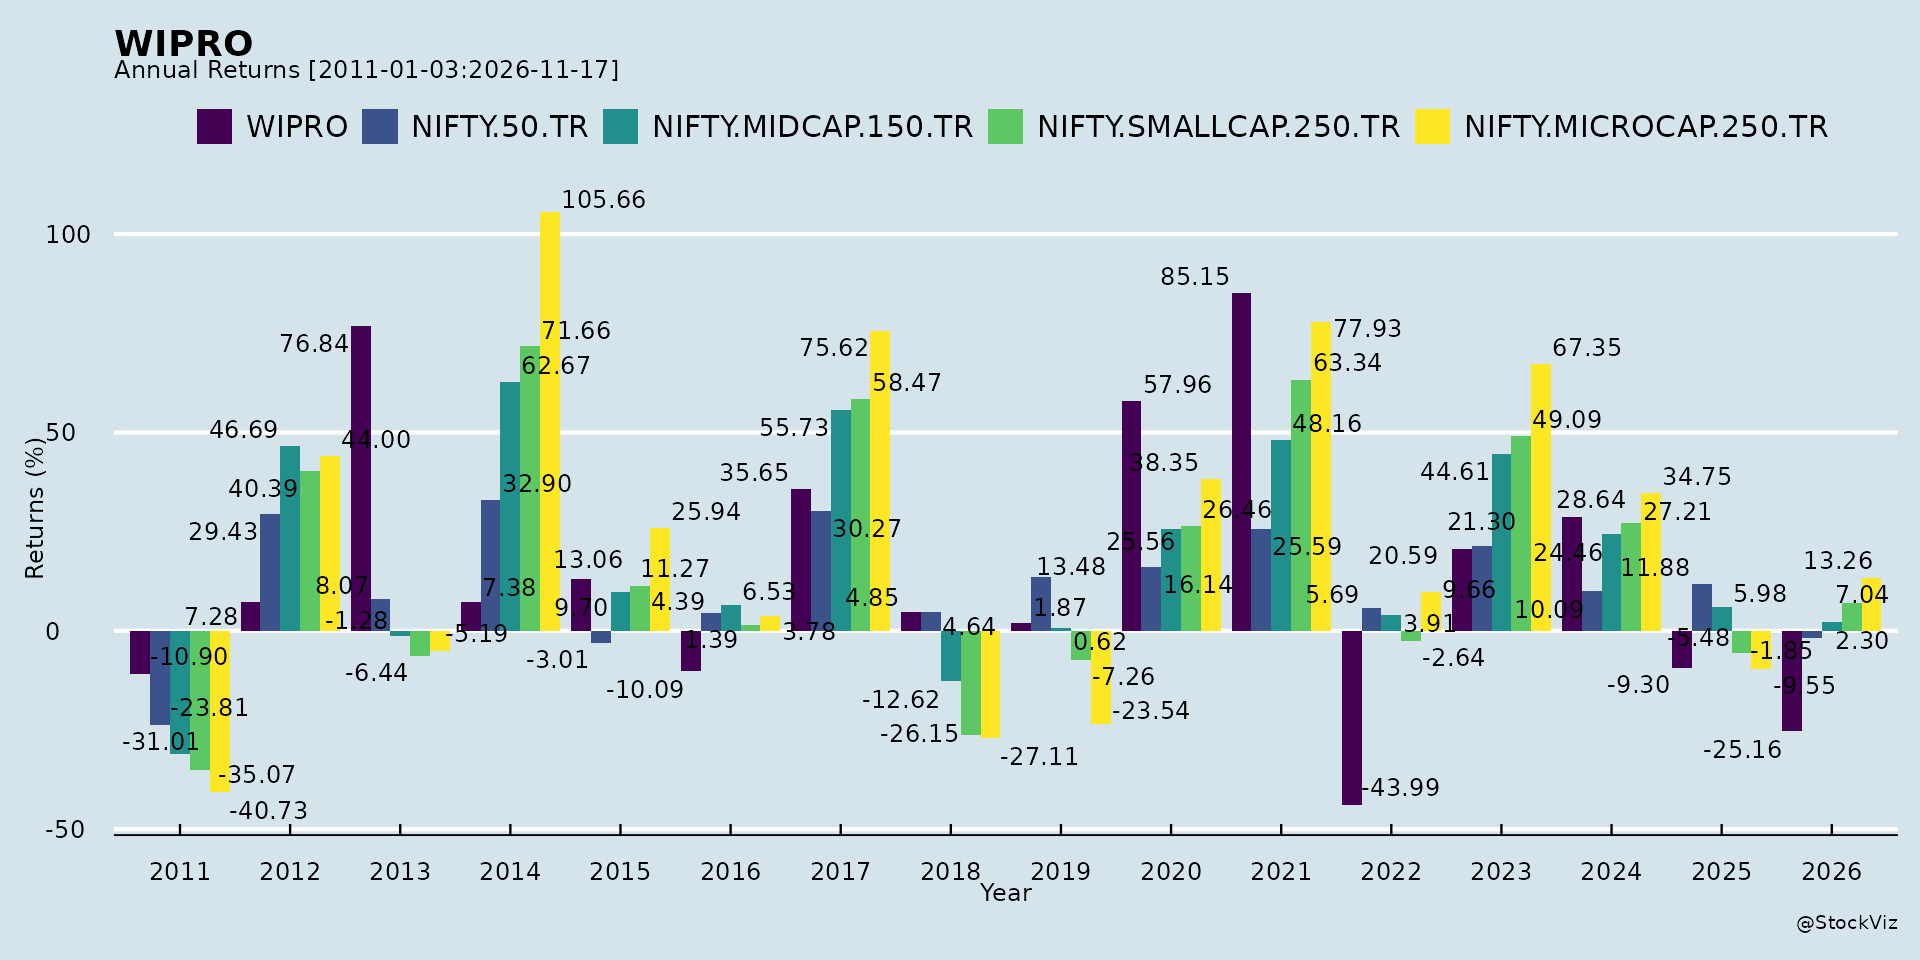
Annual Returns
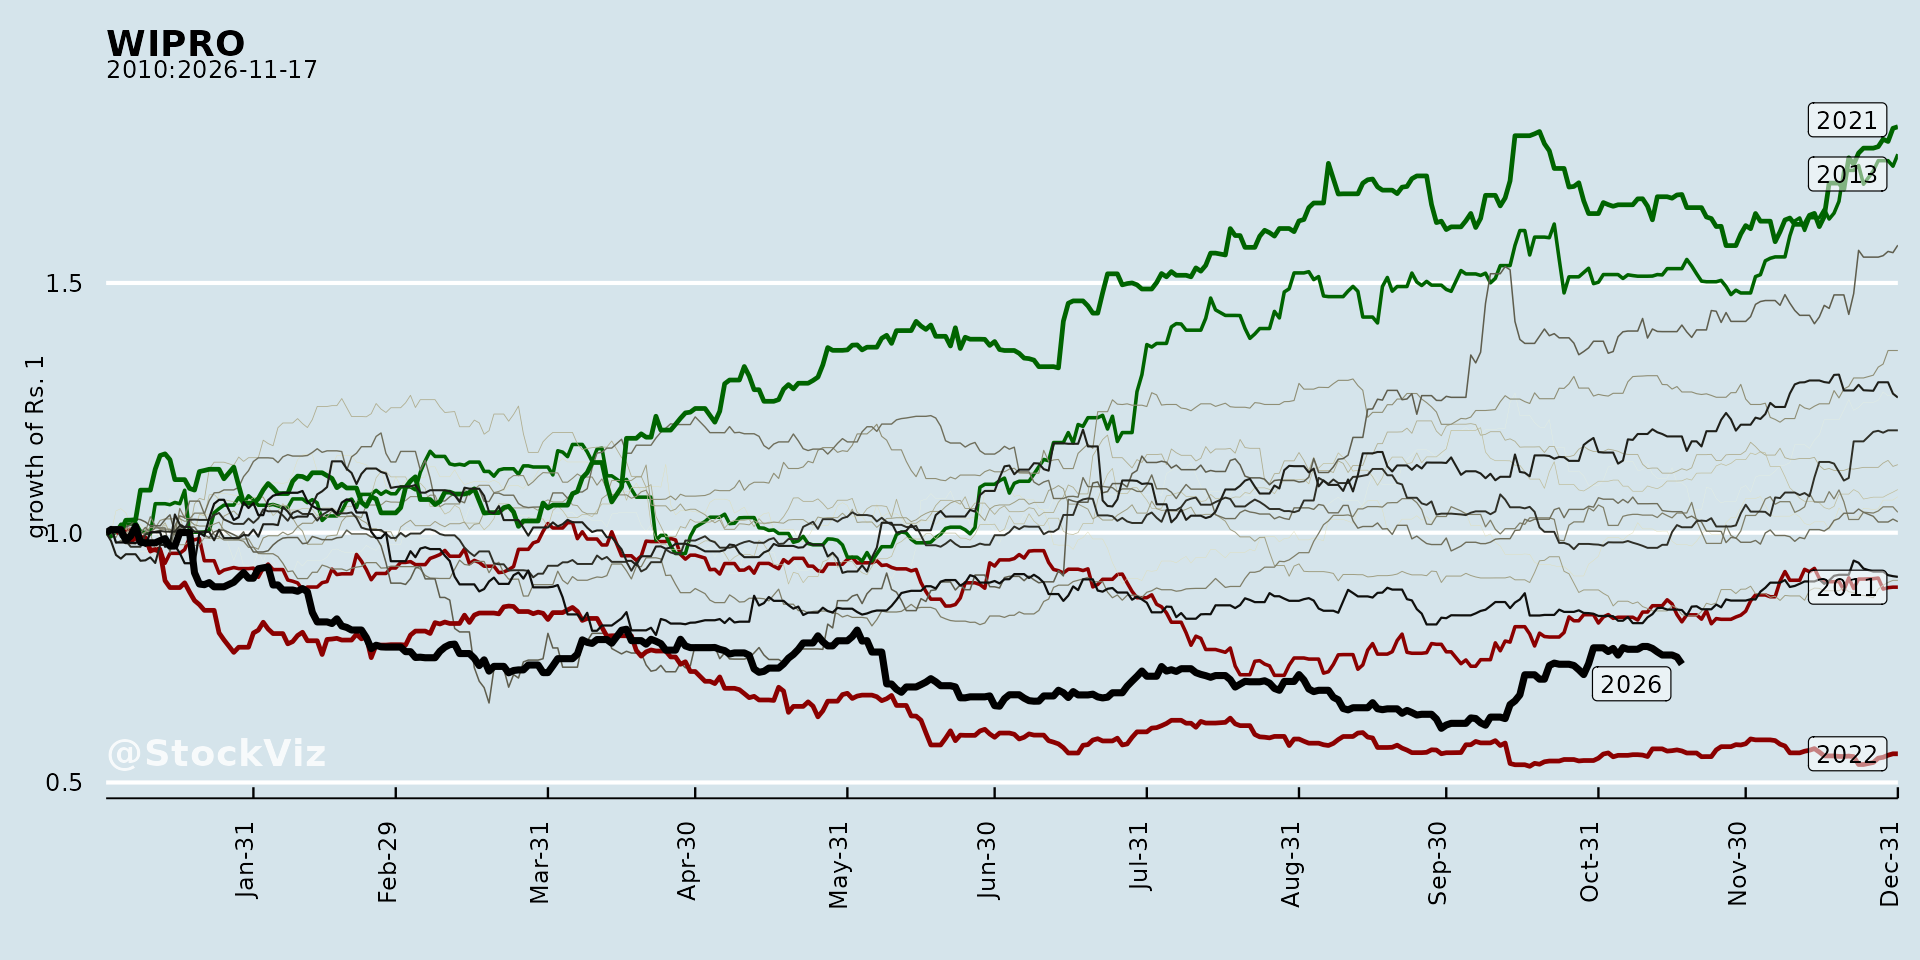
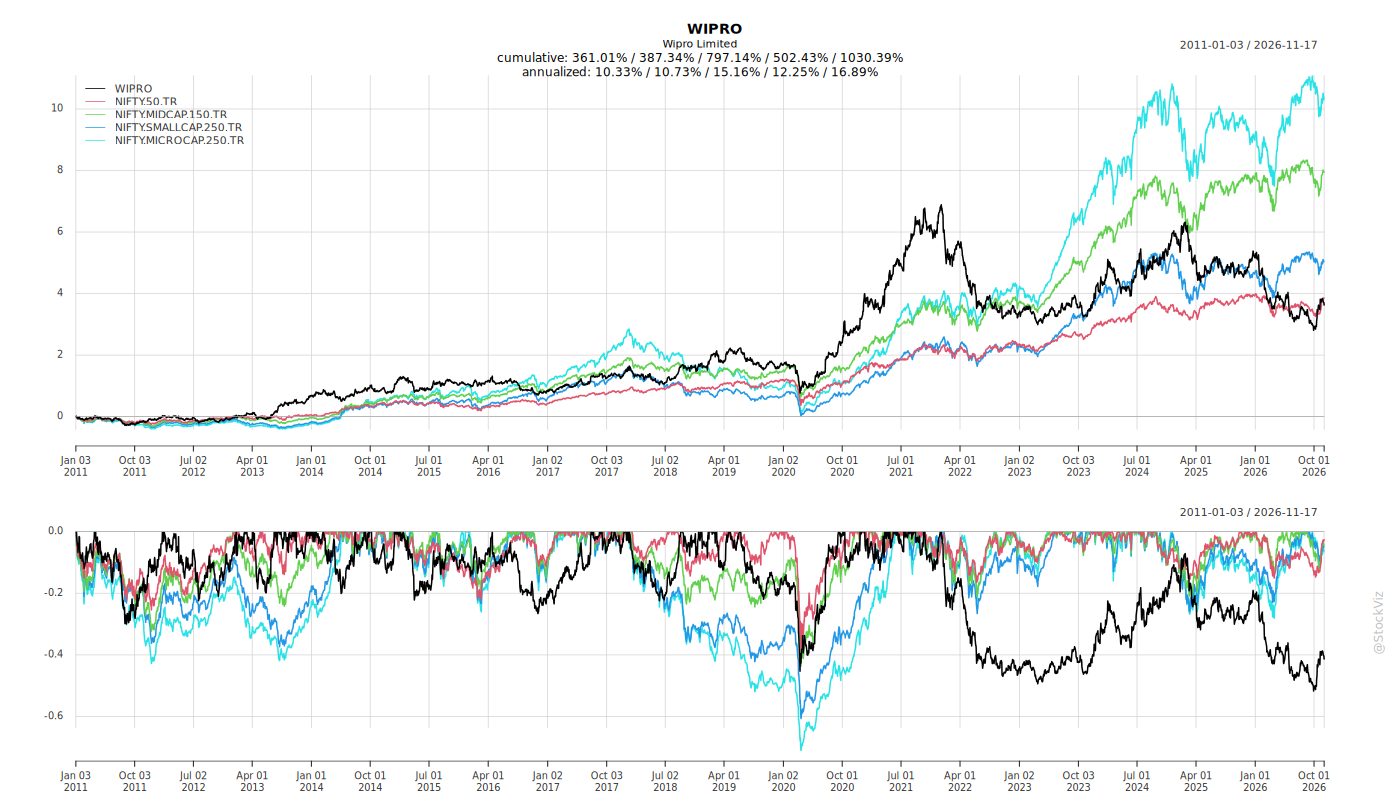
Cumulative Returns and Drawdowns
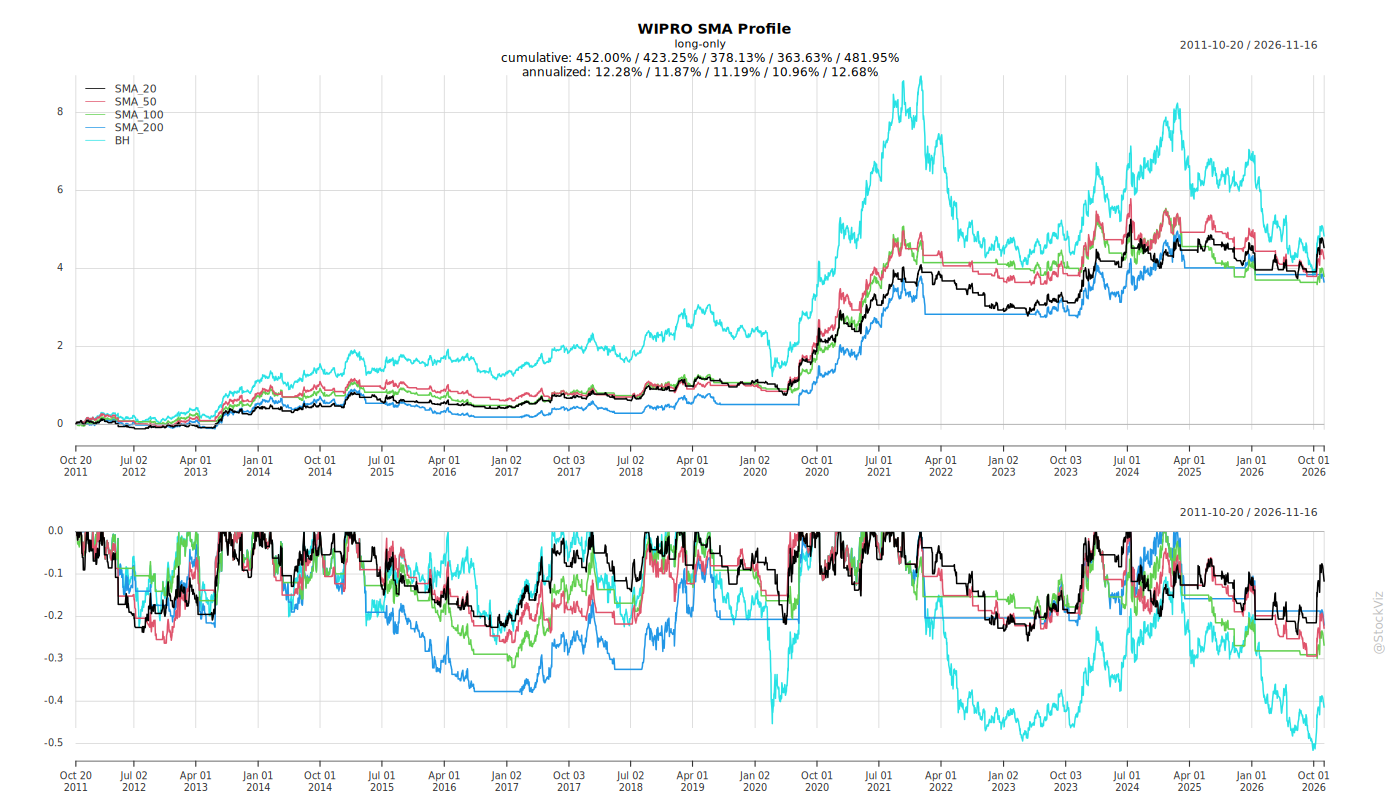
Fundamentals
Ownership
Margined
AI Summary
asof: 2026-09-16
Wipro — Recent Corporate Announcements: Summary
1. Headwinds and Challenges
The supplied material does not disclose any operational or financial headwinds. The only challenge-related signal is governance and shareholder-engagement related:
- At the 80th Annual General Meeting (AGM) held on July 15, 2026, the resolution to reappoint Mr. Azim H. Premji as a director retiring by rotation (Resolution No. 3) attracted the highest dissent among the resolutions put to vote. While 99.72% of valid votes were cast in favour, 0.28% were cast against — equivalent to 2,44,53,693 votes — a materially larger “against” block than Resolutions 1 and 2, where dissent was 0.01% each.
- Abstentions were recorded across all three resolutions: 76 shareholders holding 26,24,194 shares abstained on Resolution 1; 70 shareholders holding 3,30,389 shares on Resolution 2; and 81 shareholders holding 8,22,671 shares on Resolution 3.
- The AGM was conducted entirely through video conferencing, with the Annual Report, Notice and e-voting instructions sent only by electronic mode to members registered as of the cut-off date of July 8, 2026. Remote e-voting ran from July 11 to July 14, 2026, and votes were unblocked on July 15, 2026 at 11:36 AM IST.
2. Tailwinds and Growth Prospects
The material points to continued institutional investor engagement and external ESG recognition:
- Wipro has scheduled an extensive analyst and institutional investor meeting programme between August 12 and September 10, 2026, spanning Mumbai, Hong Kong, New York and San Francisco. This includes a Non-Deal Road Show in Mumbai (August 12) and San Francisco (September 10), the Equirus Annual India Conference in Mumbai (August 14), the Goldman Sachs Asia Leaders Conference in Hong Kong (August 31 and September 1), and the Citi Flagship Overseas Conference in New York (September 8 and 9).
- SES ESG Research Private Limited voluntarily assigned Wipro an ESG Rating of ‘80.6’ for the period ending FY26, as intimated on August 7, 2026. Wipro noted that it had not engaged SES ESG Research for this rating and that the report was independently prepared based on FY 2025-26 data available in the public domain.
- All resolutions at the 80th AGM — adoption of audited financial statements for FY ended March 31, 2026, confirmation of dividends, and reappointment of Mr. Azim H. Premji — were approved by members with the requisite majority, indicating broad shareholder support.
3. Key Risks
The supplied documents do not set out a formal risk register. The observable risk-relevant items are:
- Shareholder dissent concentration: The 0.28% votes against the director reappointment resolution, though small in percentage terms, represents a substantially higher opposition level than the other resolutions, and abstentions were recorded on all resolutions.
- Reliance on external, unsolicited assessments: The ESG rating of ‘80.6’ was assigned voluntarily by SES ESG Research without Wipro’s engagement, based solely on public-domain FY 2025-26 data. The rating is therefore outside the company’s direct control or verification.
- Concentration of investor engagement in a short window: The road shows and conferences are clustered between August 12 and September 10, 2026, across multiple geographies.
4. Management Guidance Versus Observed Business Performance
The supplied material contains no management guidance on financial or operational performance, and no forward-looking financial targets. The only performance-related evidence available is:
- The audited financial statements (standalone and consolidated) for the financial year ended March 31, 2026 were received, considered and adopted at the AGM on July 15, 2026, with 99.99% of valid votes in favour.
- Dividend history confirmed at the AGM: an interim dividend of ₹5 per equity share declared by the Board on July 17, 2025, and ₹6 per equity share declared on January 16, 2026, were confirmed as the final dividend for FY ended March 31, 2026, with 99.99% of valid votes in favour.
No comparison between stated guidance and observed performance can be made on the basis of the supplied documents.
Broker Narrative
Across the four-year span the broker stance stayed cautious and non-committal, drifting only from a 2022 Neutral to a 2026 Hold. The core concerns persisted almost unchanged: Healthcare weakness and client cost-optimization, chronic deal-closure/execution weakness, and rupee depreciation as a margin support all appear in both the first and last reports. What evolved was the AI framing, which shifted from a near-term margin headwind and ‘early traction’ theme in 2022 to a broader structural growth thesis (AI-led transformation, legacy modernization, agentic AI) by 2026. The demand backdrop also worsened from a one-off furlough-affected weak quarter to a record-low TCV environment (total TCV -22.9% QoQ to USD 2.6bn, large-deal TCV -58.6%).
Fears that came true
- The Healthcare headwind from US policy changes and discretionary-spend cuts materialized, reappearing in the 2026-10-16 report as a -3.8% segment decline with clients focused on cost optimization, consistent with the long stretch of negative actual returns through 2024-2025.
- The feared delayed deal closures persisted into a full execution slump, with the final report showing total TCV down 22.9% QoQ to a record-low USD 2.6bn and large-deal TCV down 58.6%, matching the sustained run of DISAPPOINTMENT outcomes.
Optimism that failed
- The ‘strong pipeline leading to improved 3Q bookings’ thesis repeatedly failed to convert, as the last report still leans on the same ‘robust pipeline’ optimism while TCV hits record lows and numerous Buy/Add calls (predictions of +14% to +34%) returned -12% to -35% as DISAPPOINTMENTs through 2024-2025.
- The view of BFSI and Technology as growth drivers did not hold, with Tech & Communications turning into a -2.6% drag in the final report.
- Early AI-native and mid-market traction (AI capability centers, digital plant implementations) never scaled into a realized growth driver, as AI is still described as an aspirational ‘growth opportunity’ in 2026 rather than a delivered one.
Broker Timeline
126 broker calls · 2022-07-25 to 2026-10-16
CNBC-TV18: ratings, targets and commentary
No recorded CNBC-TV18 statements for this ticker.
Management comments
No recorded management comments with an explicit designation and affiliation for this ticker.
Copyright © 2023 SAS Data Analytics Pvt. Ltd. All rights reserved.