WESTLIFE
Equity Metrics
November 18, 2026
WESTLIFE FOODWORLD LIMITED
Annual Returns
Cumulative Returns and Drawdowns
Fundamentals
Ownership
Margined
AI Summary
asof: 2026-09-17
Headwinds and Challenges
- Input cost inflation. Like-for-like gross margin declined sequentially, impacted by input cost pressures across fuel, food and packaging. Management expects these inflationary headwinds to ease with improving geopolitical conditions.
- Margin compression at the restaurant level. Restaurant Operating Margin declined by approximately 130 bps year-on-year (18.6% in Q1 FY27 versus 19.9% in Q1 FY26), even as operating EBITDA margin remained broadly stable.
- Near-term inflationary pressures. The Chairperson’s statement acknowledged that the company continued to deliver sustained profitability “despite near-term inflationary pressures.”
- Gross margin dilution from regrouping. A regrouping of processing charges from other operating expenses into cost of goods sold increased reported COGS, decreased gross profit and margin, while leaving sales, restaurant operating margin, EBITDA and PAT unchanged.
- Store closures alongside openings. The company added 5 restaurants in Q1 FY27 but also closed 1 restaurant.
- Soft comparable AUV. Comparable AUV (TTM) stood at ₹60.8 million, down 0.6% year-on-year.
- Thin reported profitability. Reported PBT was ₹7.9 million and PAT ₹5.9 million in Q1 FY27, with an exceptional item of ₹15.5 million. Prior periods also carried exceptional items, including impairment of investment (₹536.07 lakh) and the impact of new labour codes (₹968.59 lakh) in FY26.
Tailwinds and Growth Prospects
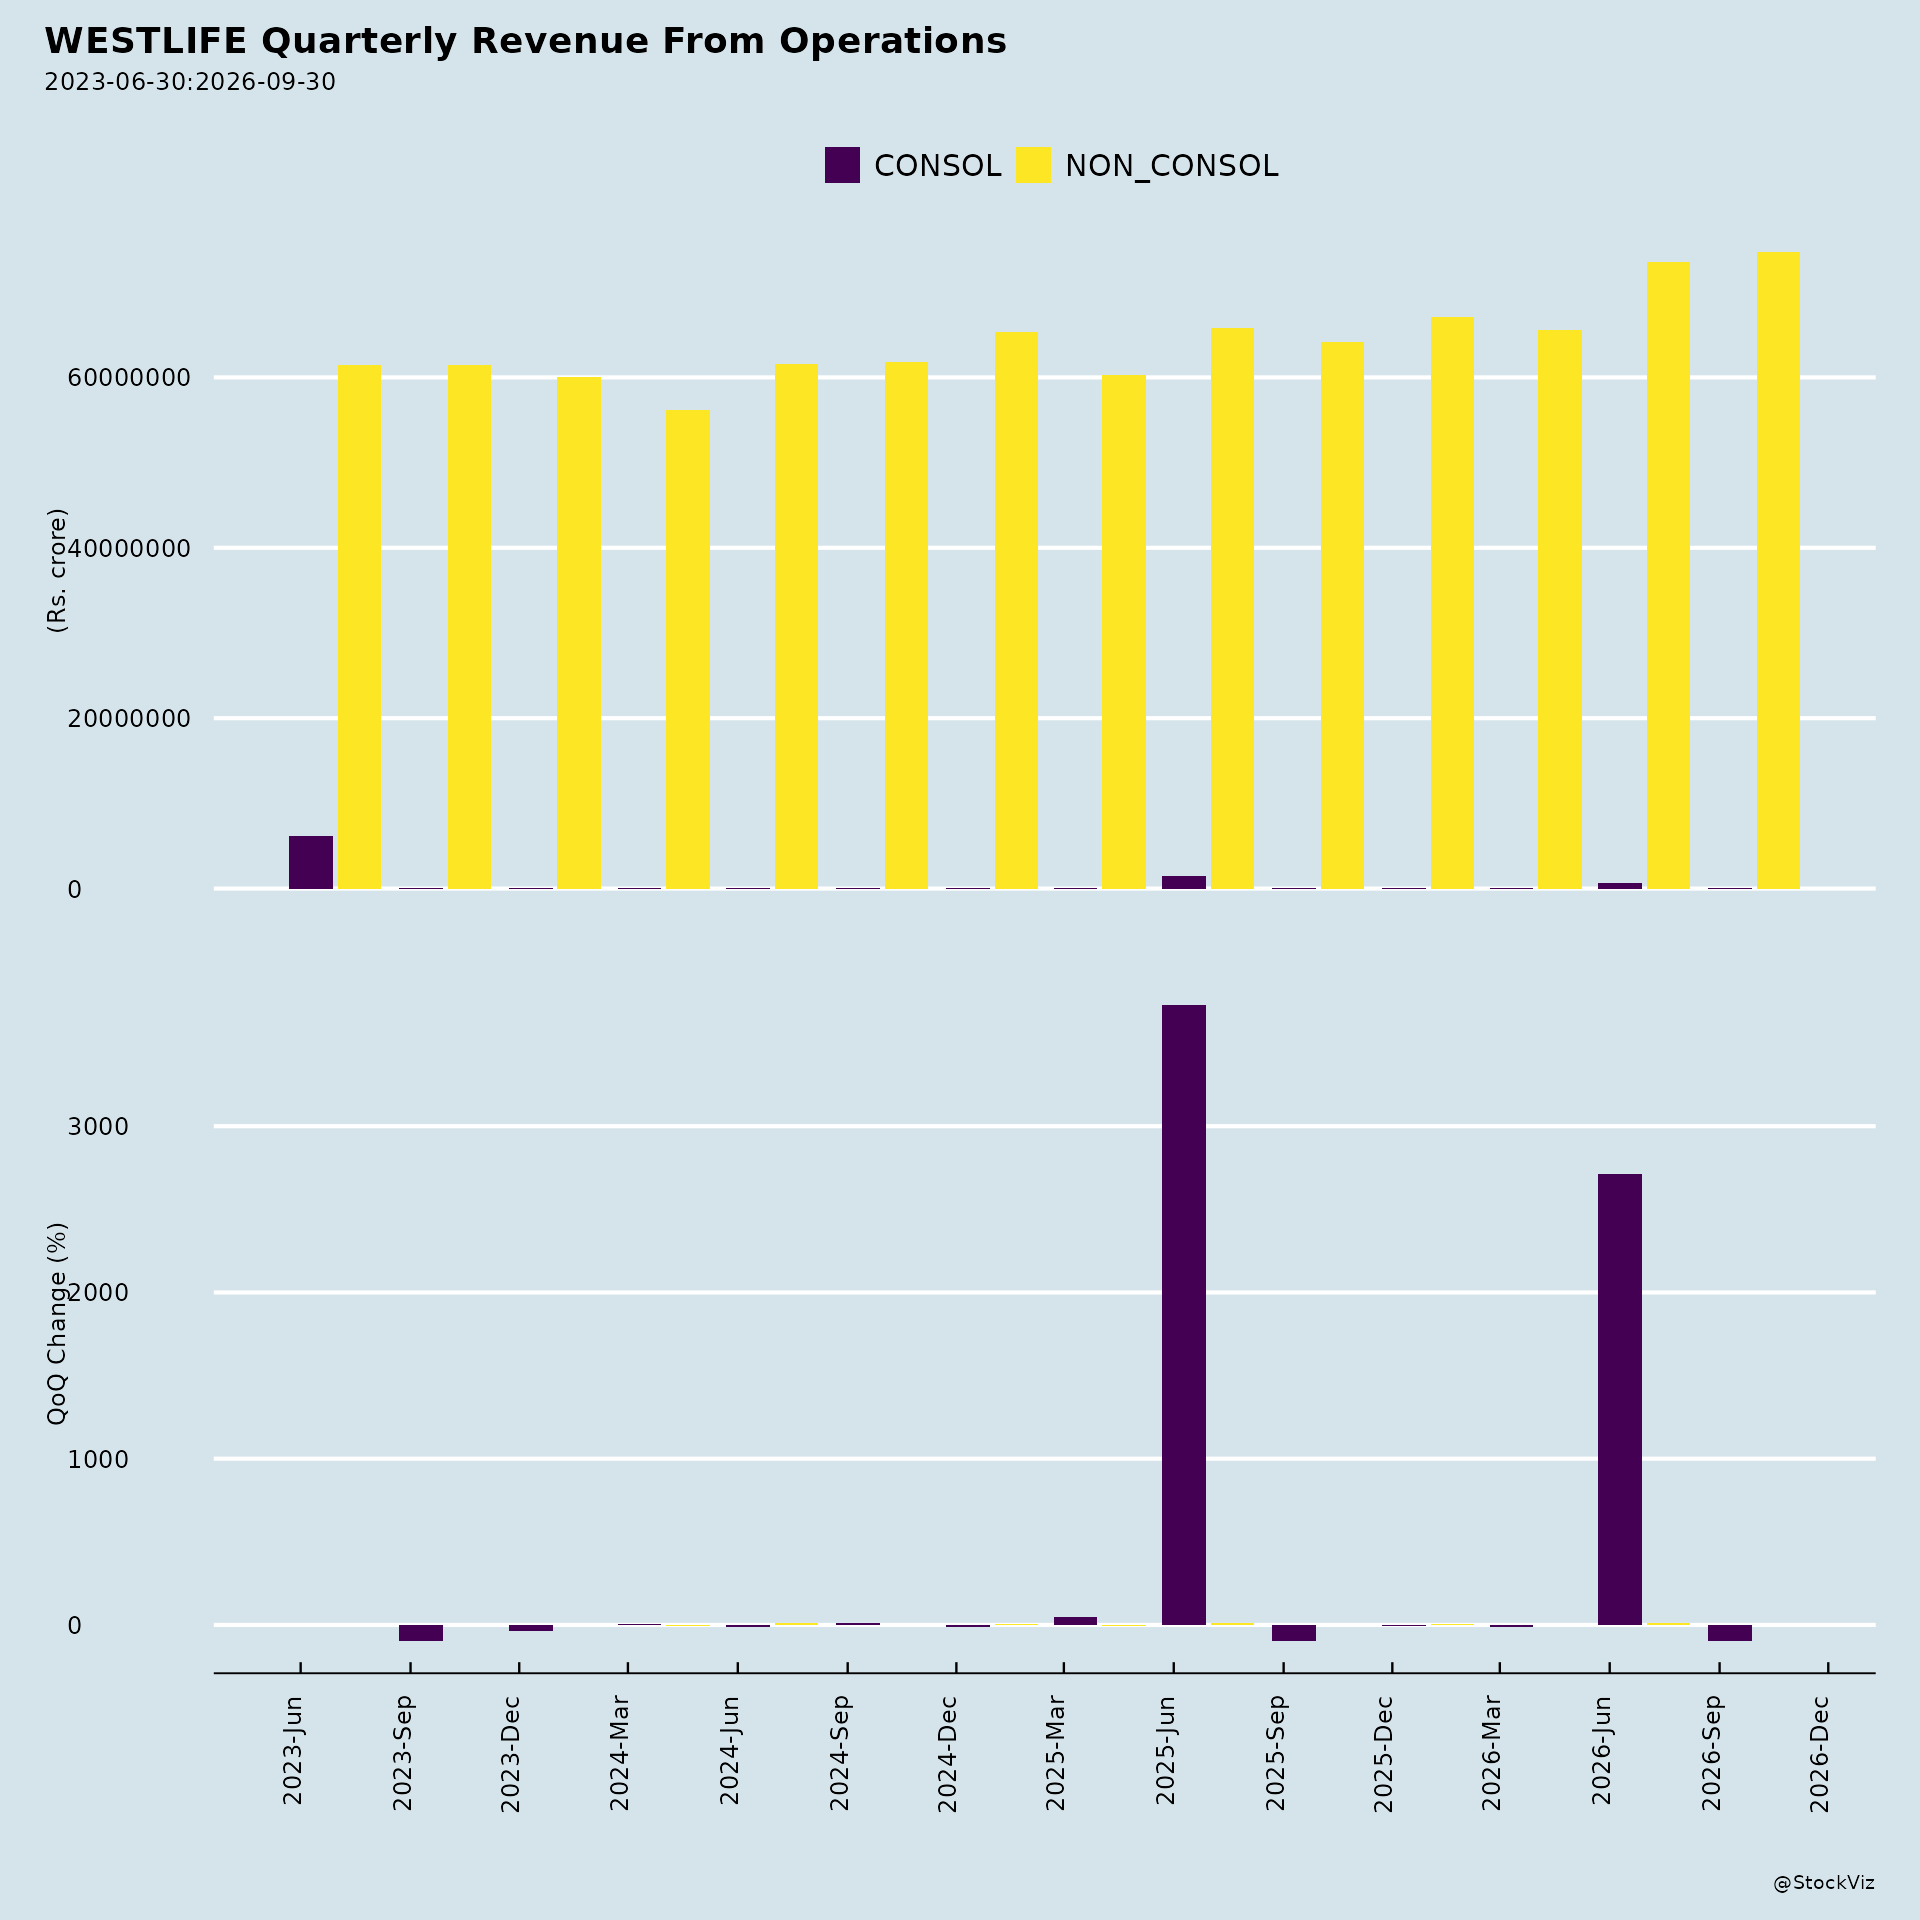
- Accelerating topline. Q1 FY27 sales grew 11.9% year-on-year to ₹7,356.4 million, described as the strongest momentum in recent quarters, versus 6.7% in Q1 FY26 and 8.7% in Q4 FY26.
- Improving same-store sales. SSSG improved to 4.3% in Q1 FY27, from 0.5% in Q1 FY26 and 1.5% in Q4 FY26, driven by double-digit guest count growth across the West and South markets. May and June were particularly strong, delivering mid-single-digit SSSG.
- Everyday value platform. The ₹99 Everyday Value platform remained the primary catalyst for guest count growth, supported by menu innovation and operational excellence.
- Balanced channel performance. On-premise sales contributed 59% of system sales; off-premise grew broadly in line, with McDelivery continuing to outperform as a key growth engine.
- Digital scale. Digital sales contributed approximately 74% of sales, up 150 bps year-on-year, with over 55 million cumulative app downloads and more than 3.7 million monthly active users.
- Network expansion runway. With 482 restaurants across 79 cities as of June 2026, the company targets 580–630 restaurants by December 2027, with 60+ new store openings targeted in FY27.
- Brand initiatives. The “Let’s Family at McD” campaign marking 30 years of McDonald’s in India, the limited-time Mango Burst Range, and targeted brand initiatives aimed at strengthening consumer connect and top-of-mind recall.
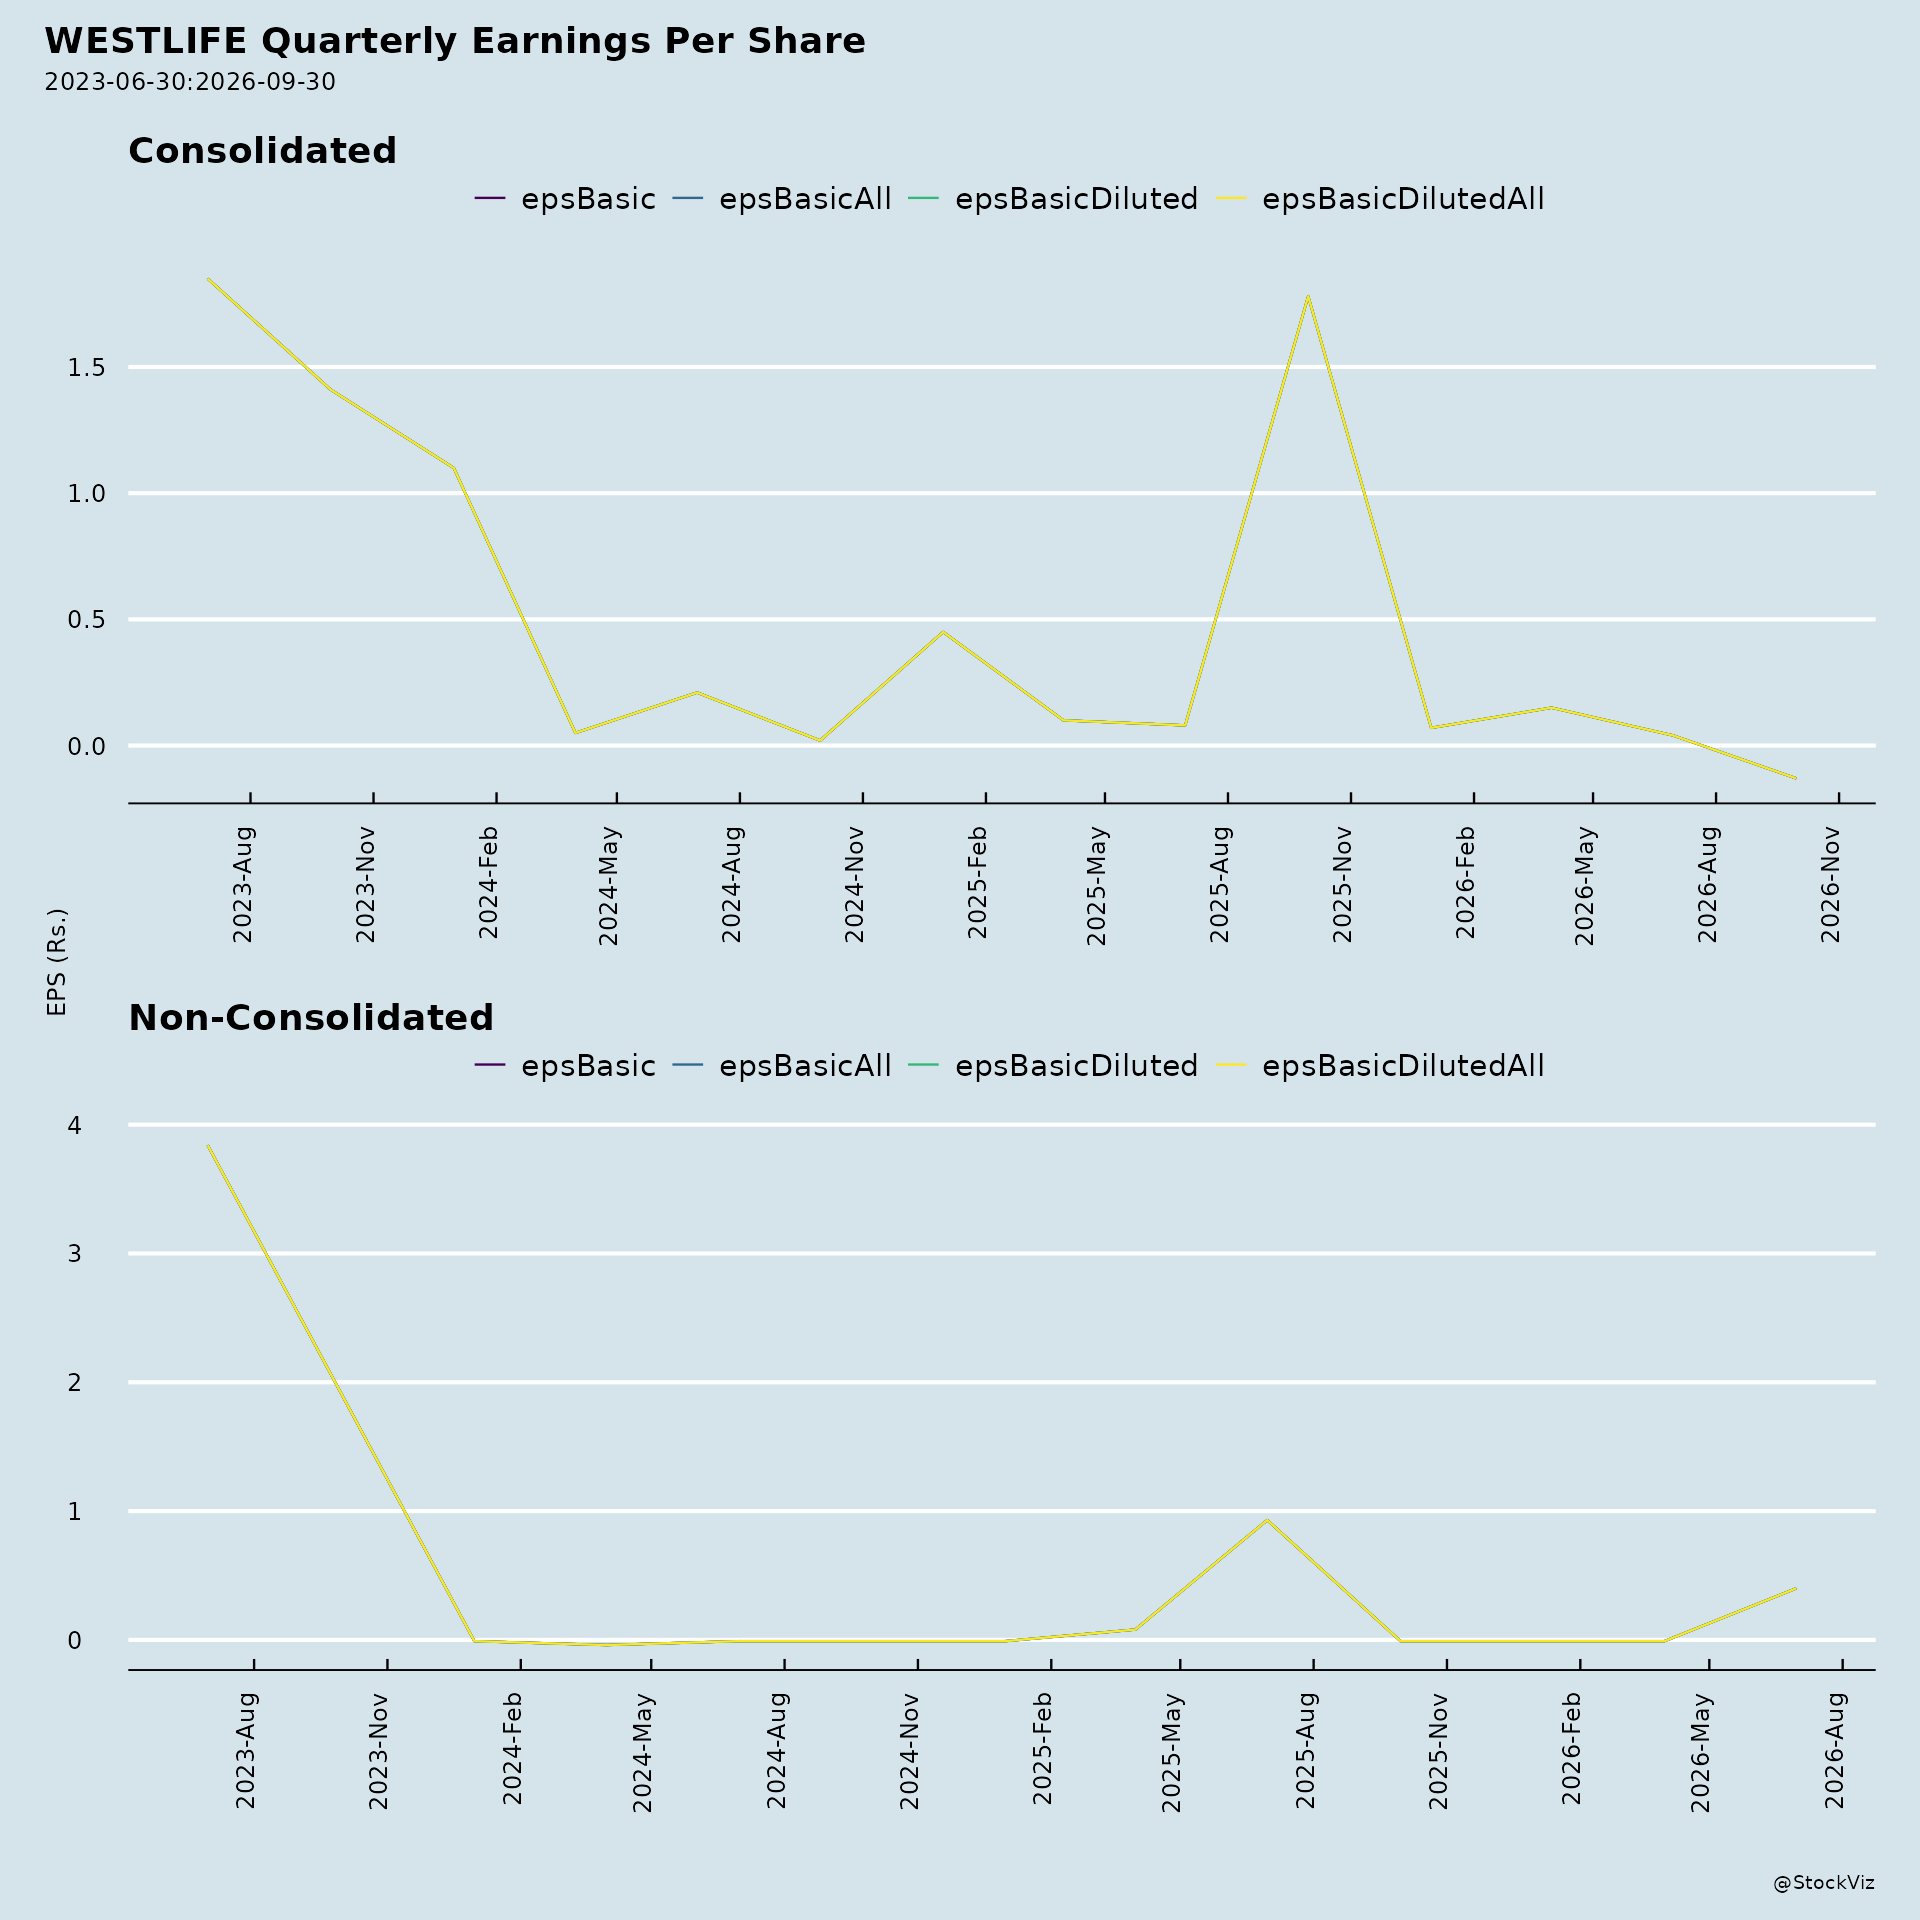
- Profitability resilience. Operating EBITDA rose 10.7% year-on-year to ₹945.5 million; Cash PAT stood at ₹516.8 million, representing 7.0% of sales.
- Shareholder returns. The Board approved an interim dividend of ₹0.40 per equity share of face value ₹2 each for FY27, with a record date of 7 August 2026 and payment on or before 29 August 2026. The subsidiary HRPL approved a final dividend of ₹72 per equity share of face value ₹1,000 each for FY2025-26.
Key Risks
- Inflation and input costs. Fuel, food and packaging cost pressures weighed on gross margin, with the outlook tied to geopolitical conditions.
- Margin protection. Restaurant-level margins declined year-on-year, and the company’s stated framework targets volume-led, margin-protected growth, implying execution risk in balancing value pricing with profitability.
- Execution of expansion plans. The 580–630 restaurant target by December 2027 and 60+ openings in FY27 depend on continued site acquisition and ramp-up.
- Dependence on the value platform. The Everyday Value platform at ₹99 is described as the primary driver of guest count growth, concentrating growth reliance on that proposition.
- Digital concentration. Digital channels account for approximately 74% of sales, making the business sensitive to app, kiosk and delivery platform performance.
- Regulatory and labour costs. The new labour codes, effective 21 November 2025, produced an estimated incremental gratuity impact of ₹968.59 lakh due to a change in wage definition, presented as an exceptional item in FY26.
- Forward-looking statement risk. The company’s own safe harbour disclosure notes known and unknown risks, uncertainties and other factors that could cause actual results to differ materially from projections.
Management Guidance Versus Observed Performance
- Gross margin guidance. Management stated gross margin is expected to remain above 67% in the near to mid term. Observed: adjusted gross margin was 67.6% in Q1 FY27, 67.6% in Q1 FY26, 68.1% in Q4 FY26, 67.7% in FY26, 66.3% in FY25 and 66.8% in FY24 — consistent with the stated floor on an adjusted basis.
- Network expansion guidance. Management targets 580–630 restaurants by December 2027 and 60+ openings in FY27. Observed: 5 restaurants added and 1 closed in Q1 FY27, taking the network to 482 restaurants across 79 cities; the company stated it remains on track.
- Growth momentum. Management characterised Q1 FY27 as the strongest business momentum in recent quarters. Observed: sales growth of 11.9% and SSSG of 4.3%, both above the comparable prior-quarter figures of 6.7% and 0.5% in Q1 FY26 and 8.7% and 1.5% in Q4 FY26.
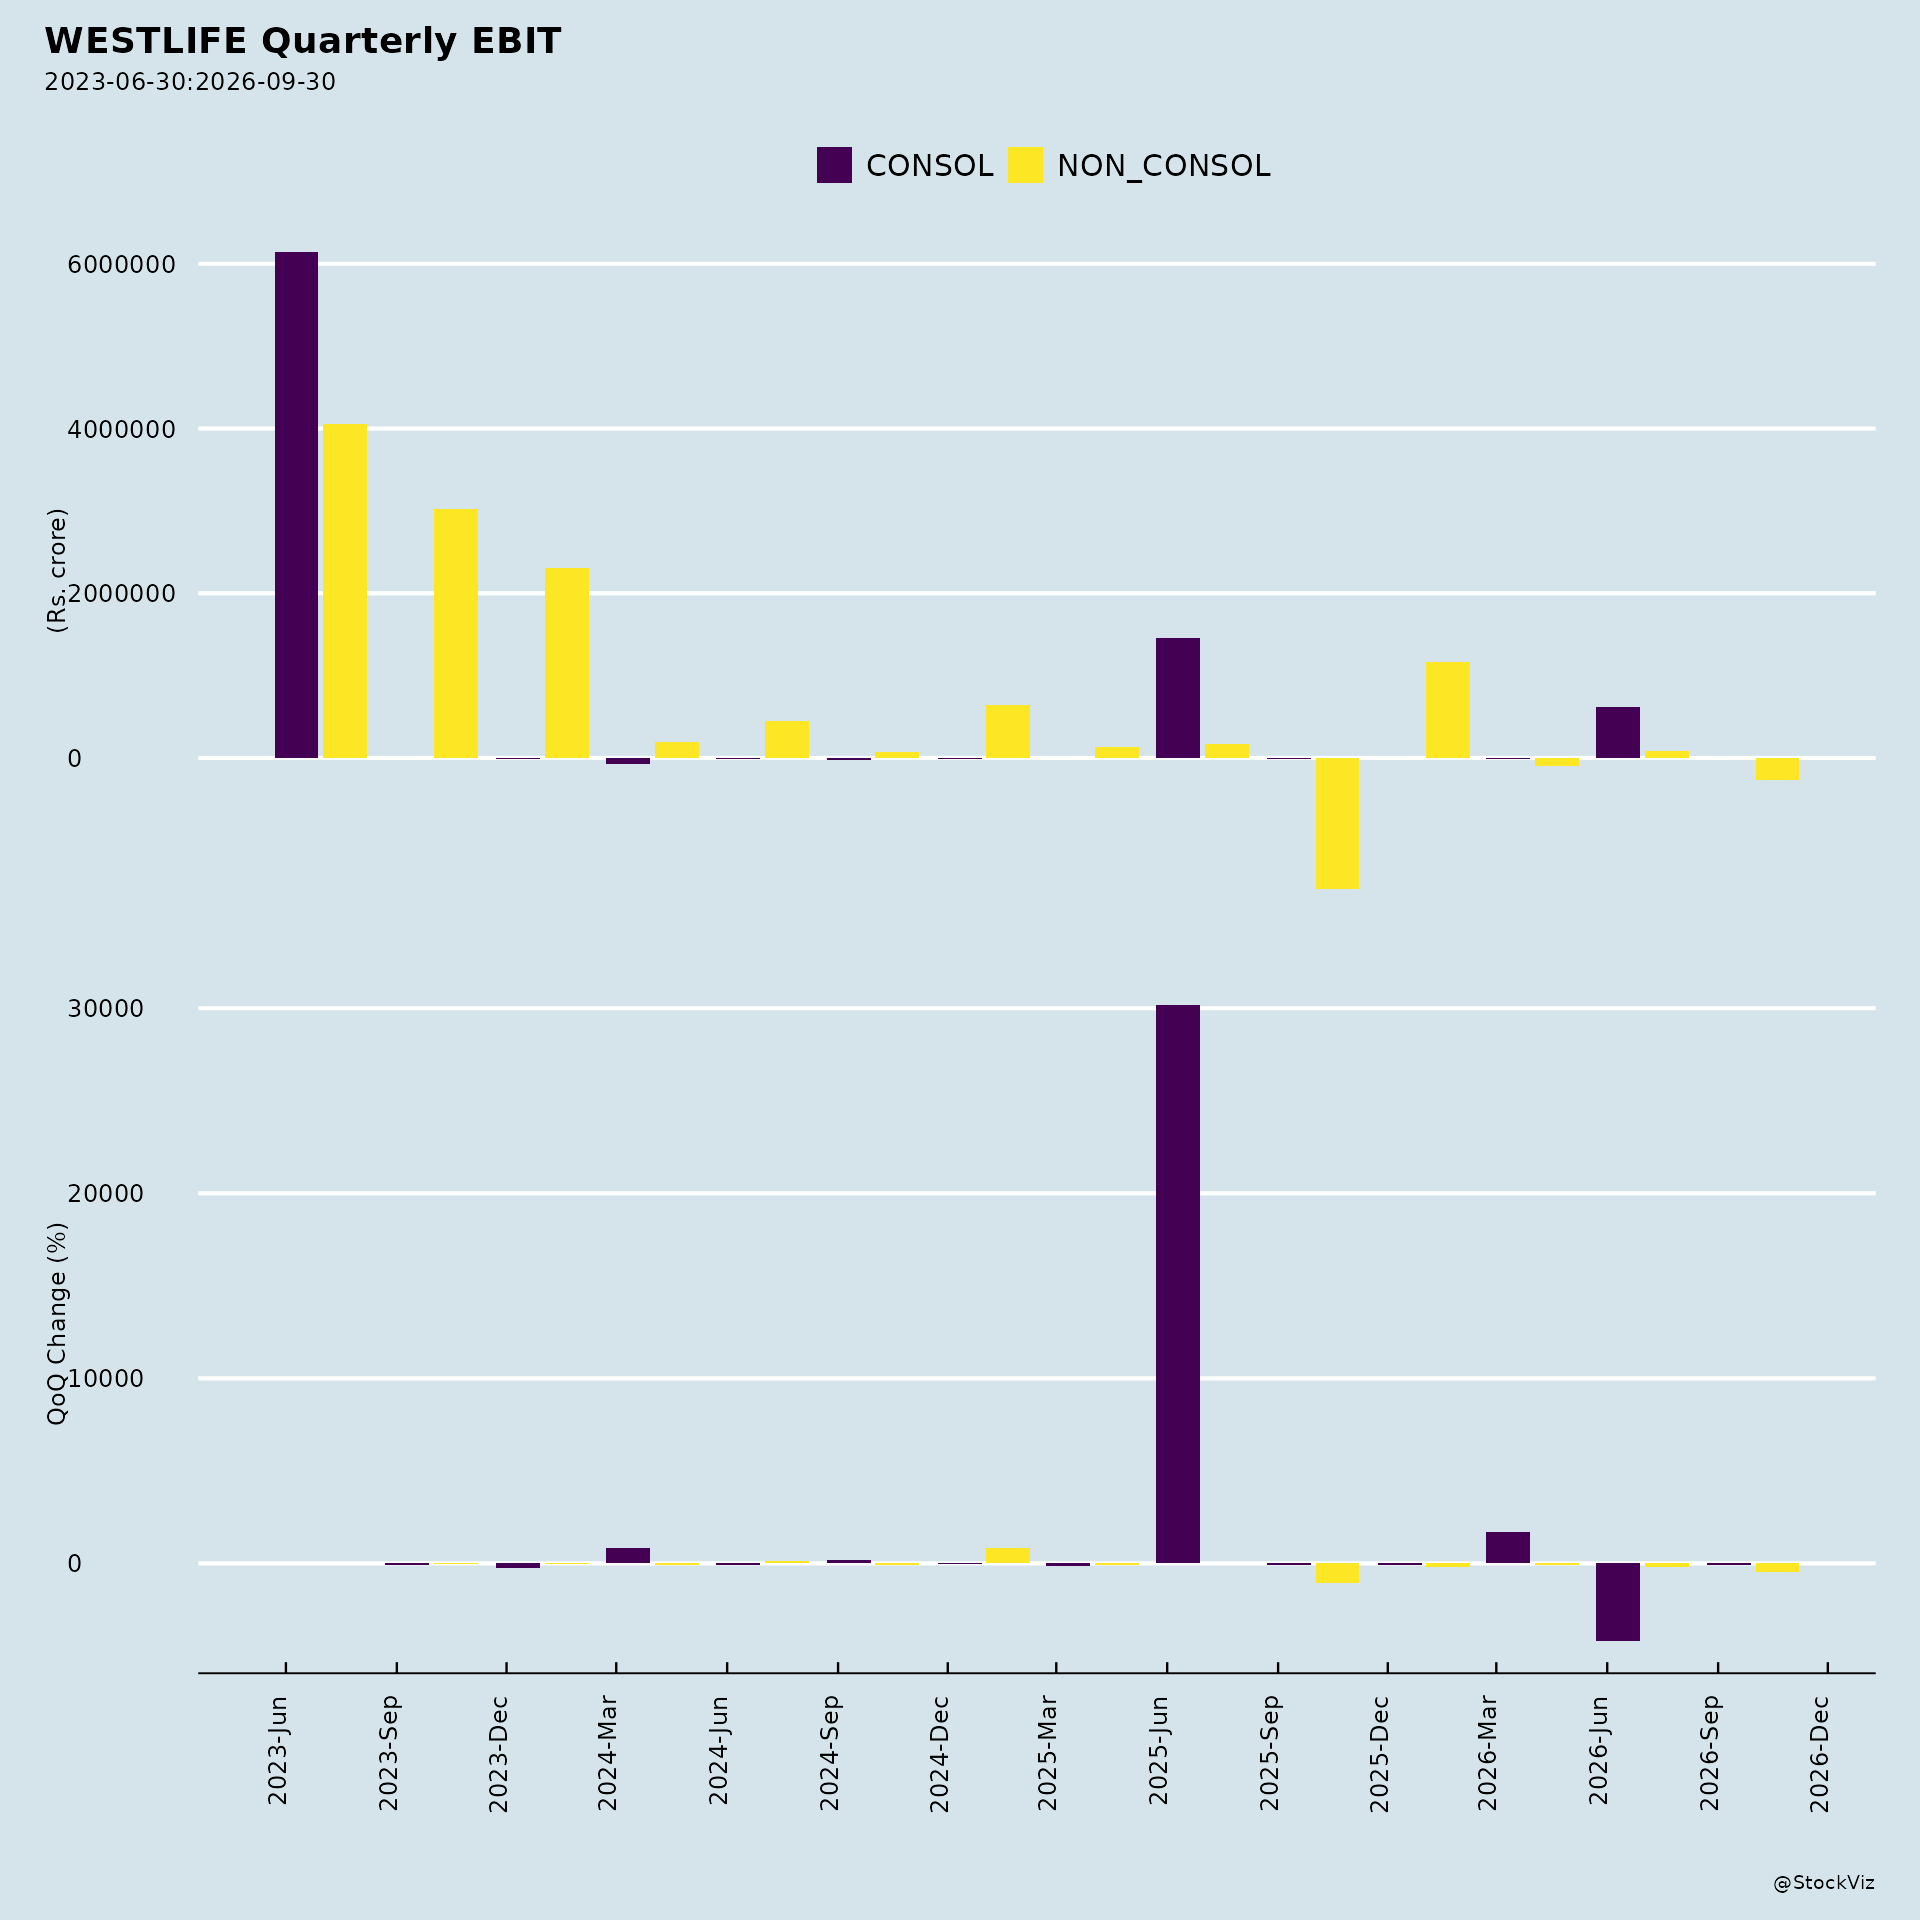
- Profitability. Management cited disciplined cost management, operating leverage and execution excellence supporting sustained profitability. Observed: operating EBITDA margin of 12.9% versus 13.0% in Q1 FY26 and 13.3% in Q4 FY26, with operating EBITDA up 10.7% year-on-year.
- Inflation outlook. Management expects inflationary headwinds to ease with improving geopolitical conditions; no specific timeline was provided.
Key Facts for Investors
- Q1 FY27 results (quarter ended 30 June 2026) were approved by the Board on 30 July 2026 and carry a limited review report from statutory auditors SRB C & CO LLP.
- The company operates McDonald’s restaurants in West and South India through wholly owned subsidiary Hardcastle Restaurants Pvt. Ltd., a master franchisee relationship with McDonald’s Corporation USA.
- The 43rd Annual General Meeting was scheduled for Wednesday, 26 August 2026 at 2:00 p.m. IST via video conference and other audio-visual means; the notice and FY2025-26 annual report were dispatched on 4 August 2026.
- All resolutions (Item Nos. 1, 2 and 3) proposed at the 43rd AGM held on 26 August 2026 were passed with the requisite majority.
- The company held an earnings call on 30 July 2026 at 4:30 p.m. IST, and participated in the Ashwamedh – Elara India Dialogue 2026 on 3 September 2026.
- The Group operates as a single business segment and single geographical segment (domestic market only).
- The Group completed a redevelopment transaction involving a Mumbai ownership store property in FY26, transferring rights in exchange for an alternate store property and monetary consideration, resulting in a net aggregate gain of ₹5,816.68 lakh.
- HRPL’s shareholders approved a final dividend of ₹72 per equity share for FY2025-26 on 18 June 2026, recognised as revenue in the standalone results and eliminated in the consolidated results.
- The Board declared an interim dividend of ₹0.40 per equity share for FY27, with a record date of 7 August 2026.
Broker Narrative
The broker narrative shifted from early optimism about surging revenue, 14% SSSG, digital acceleration, gross margin expansion to 71.9%, and a store rollout toward a more cautious view that revenue and digital channels remain strong but persistent wage, utility and commodity cost inflation absorbed operating leverage, leaving restaurant operating margin flat at 19.3% and gross margin capped at 67–68% by value-meal competition. Themes that persisted include store expansion/digital dominance and competitive/demand pressures, while the expected EBITDA margin expansion to 17.5–18.0% and pricing power faded into limited 2–4% annual price hikes and few near-term margin triggers, ending in a Reduce call.
Fears that came true
- Cost inflation in wages, utilities and commodities persisted and absorbed operating leverage, leaving restaurant operating margin flat at 19.3% despite 10% SSSG, validating the early employee/raw-material cost inflation warning and consistent with repeated DISAPPOINTMENT outcomes where actual returns were negative.
- Intense QSR competition and weak consumer demand forced a value-meal push that capped gross margin at 67–68% and created downside risk of slower growth, corroborating early fears of prolonged demand weakness and chicken-portfolio competition amid many negative-return DISAPPOINTMENTs.
- Earnings repeatedly missed estimates, with bullish predicted returns followed by double-digit negative actual returns across numerous DISAPPOINTMENT outcomes, confirming the early flag that Q4FY23 Reported and Adjusted PAT came in well below projections.
Optimism that failed
- The expected gross margin expansion to 71.9% and EBITDA margin gains toward 17.5–18.0% in FY24E failed, with gross margin now capped at 67–68% and restaurant operating margin flat at 19.3% despite better store throughput.
- Menu innovation optimism around Chicken Big Mac, McCafe and long-term chicken burger growth did not translate into margin expansion, as competitive intensity in chicken and value-meal pricing constrained profitability.
- Planned 2–3% price hikes to mitigate inflation and drive margin expansion failed to materialize as a sufficient offset, with price hikes limited to 2–4% annually and guest count prioritized over pricing, leaving cost pressures absorbed.
Broker Timeline
56 broker calls · 2023-05-09 to 2026-10-26
CNBC-TV18: ratings, targets and commentary
No recorded CNBC-TV18 statements for this ticker.
Management comments
No recorded management comments with an explicit designation and affiliation for this ticker.
Copyright © 2023 SAS Data Analytics Pvt. Ltd. All rights reserved.