WAAREEENER
Equity Metrics
September 24, 2026
Waaree Energies Limited
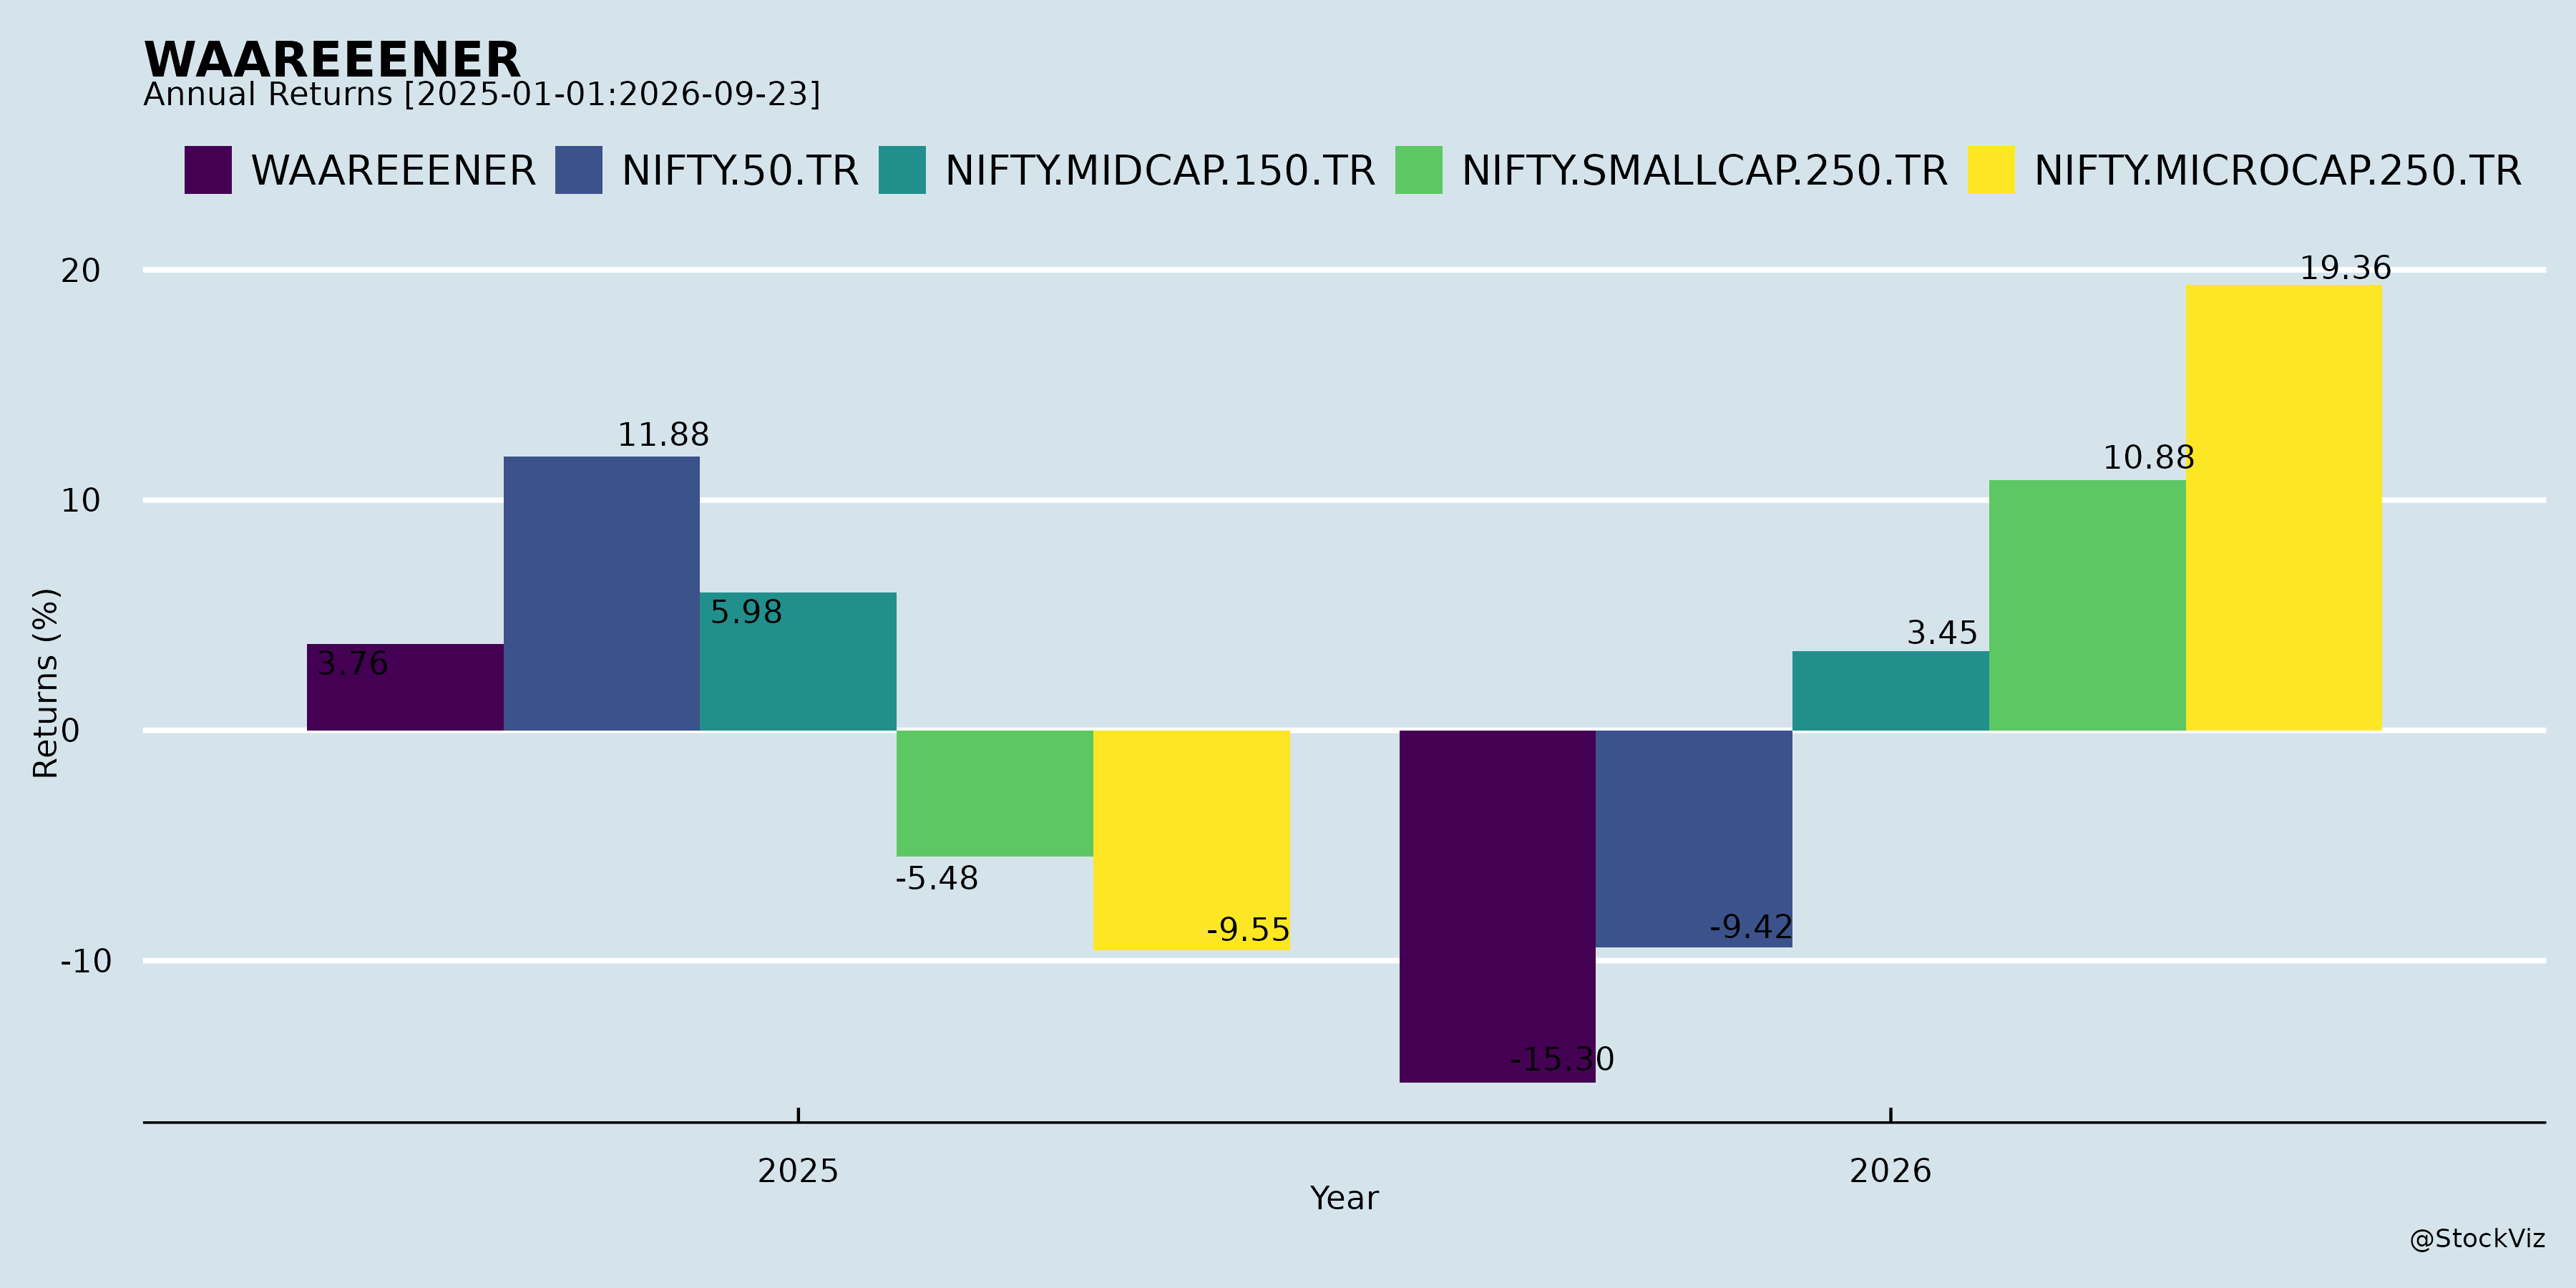
Annual Returns

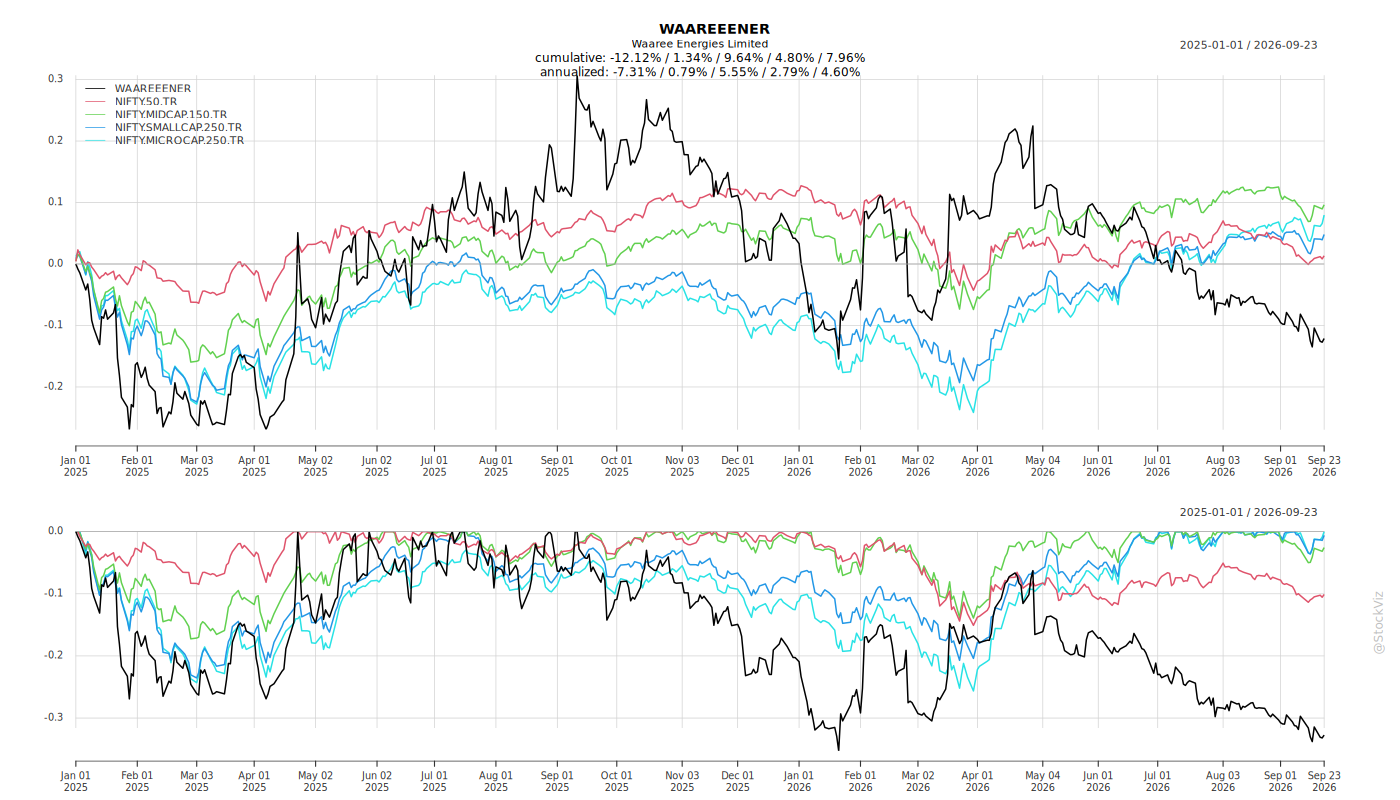
Cumulative Returns and Drawdowns
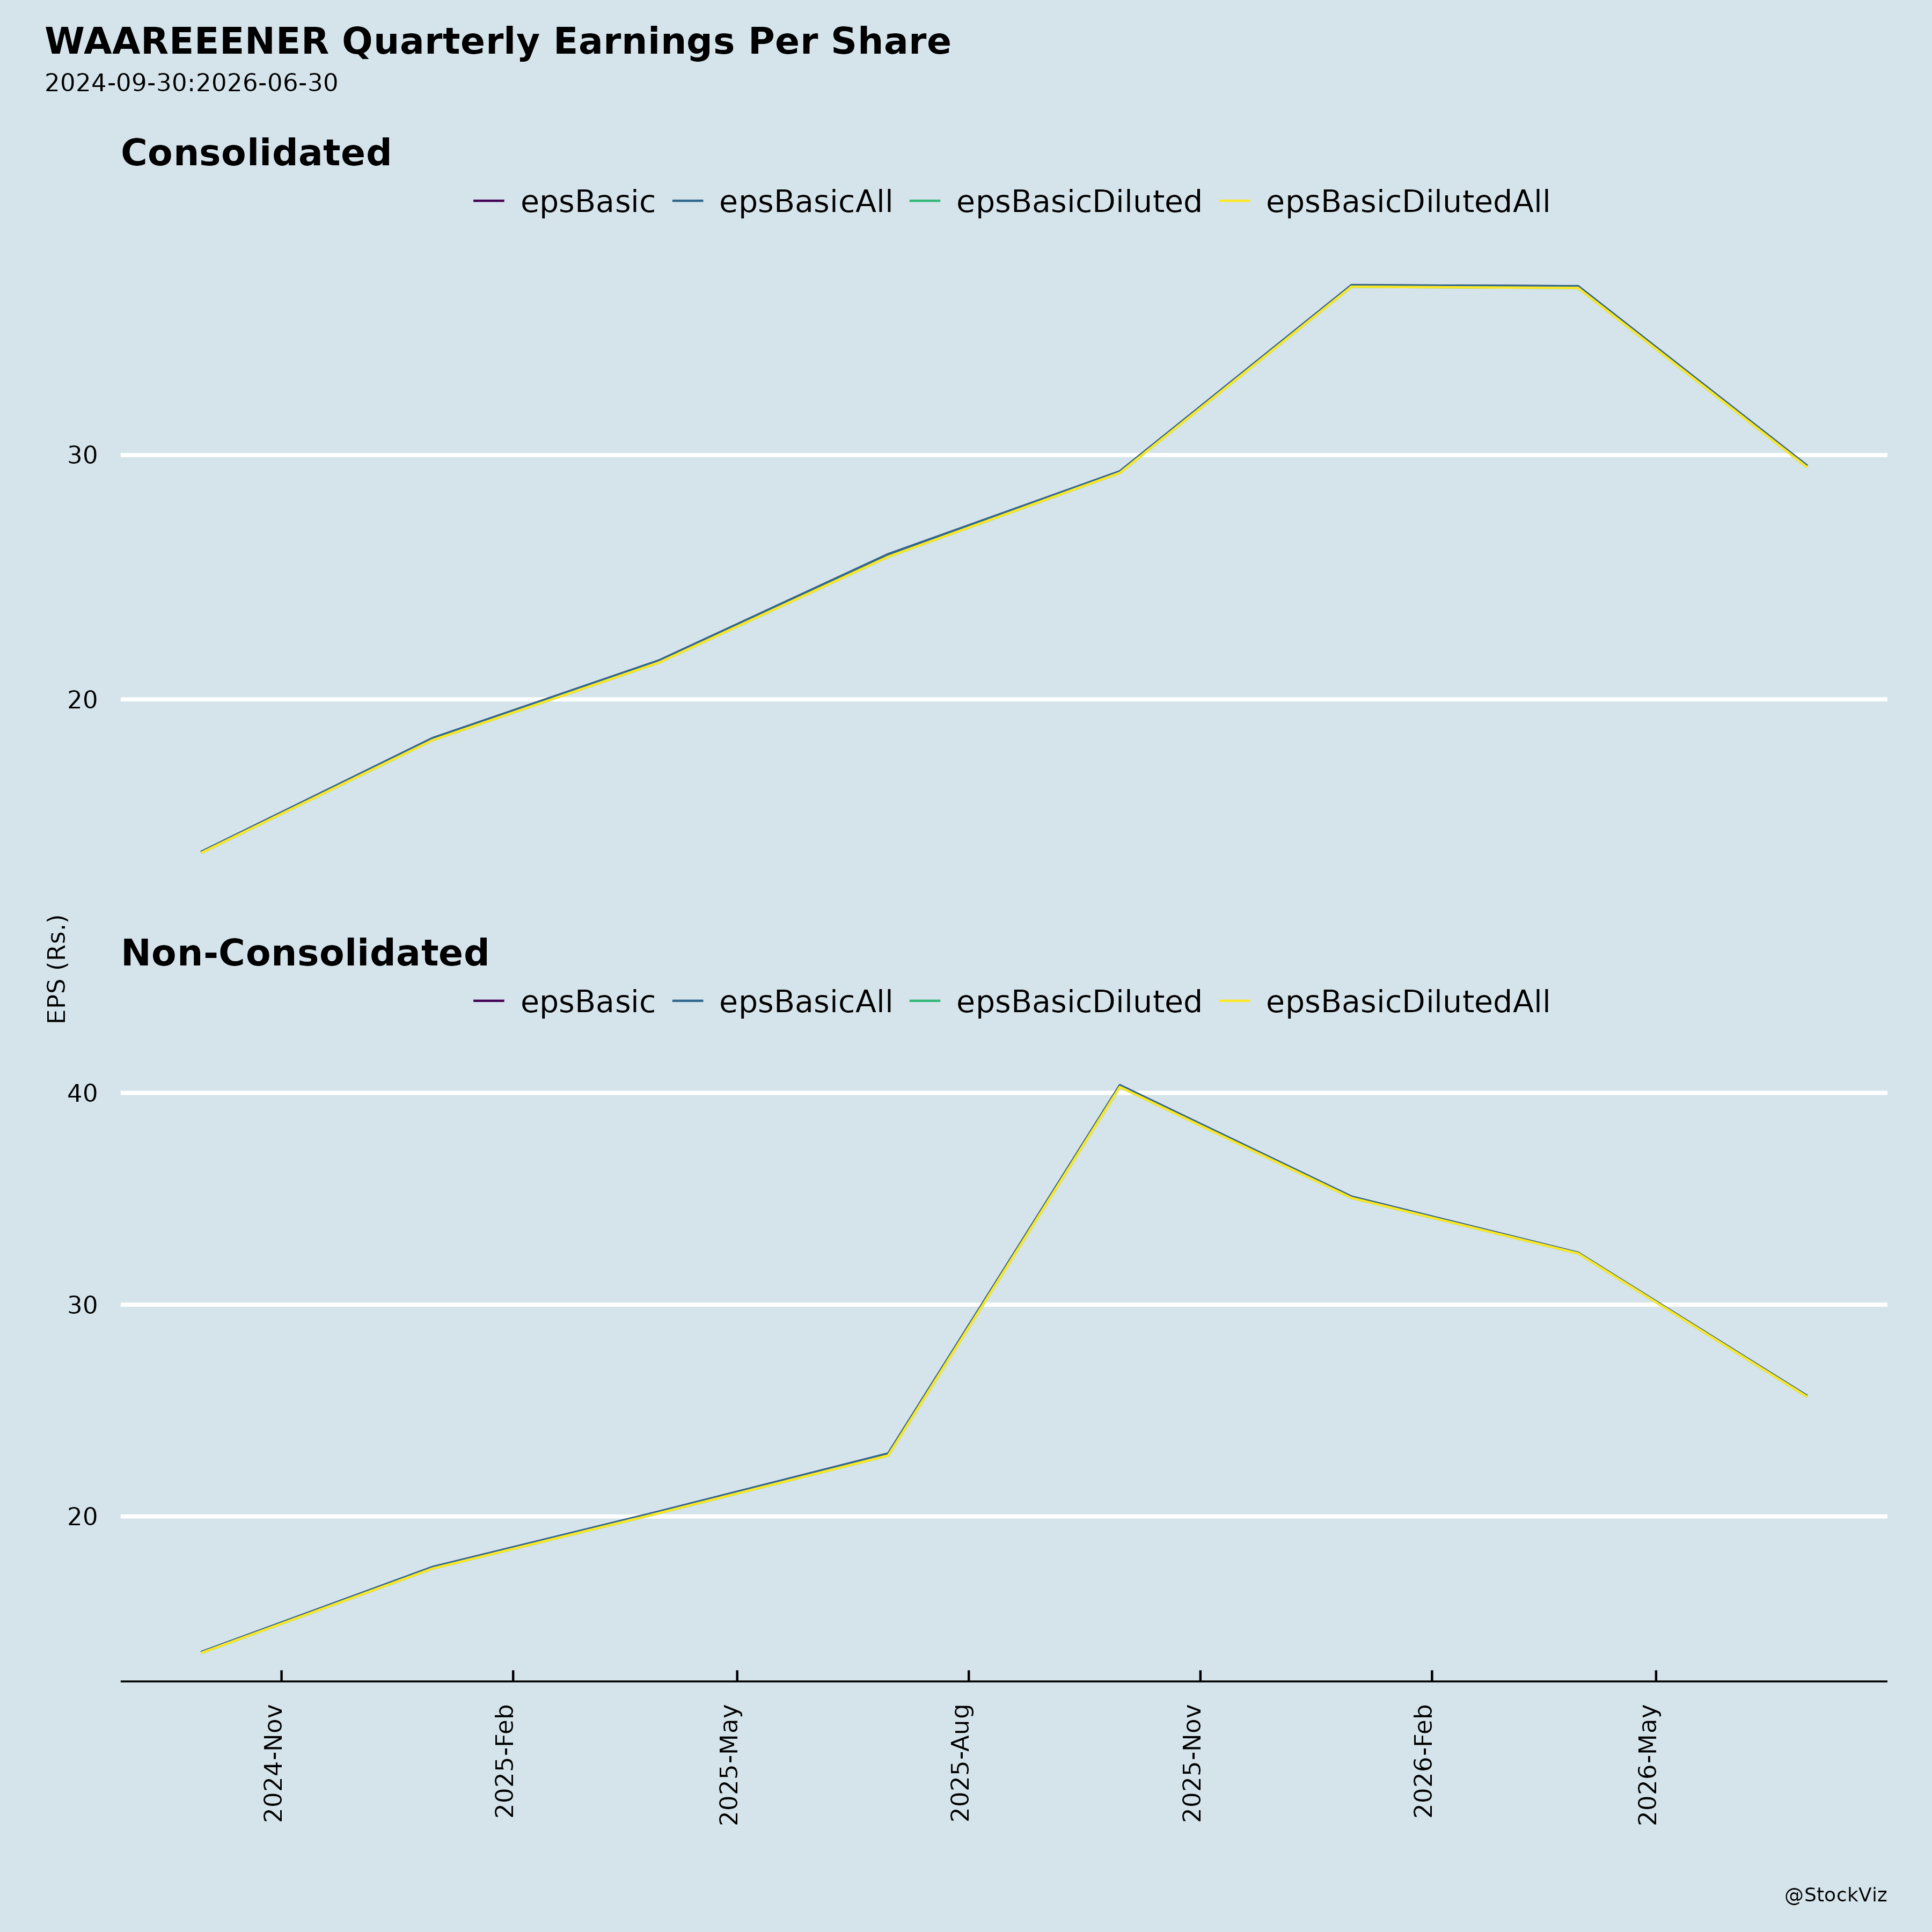
Fundamentals
Ownership
Margined
AI Summary
asof: 2026-09-16
Waaree Energies — Recent Corporate Announcements: Summary
1. Headwinds and Challenges
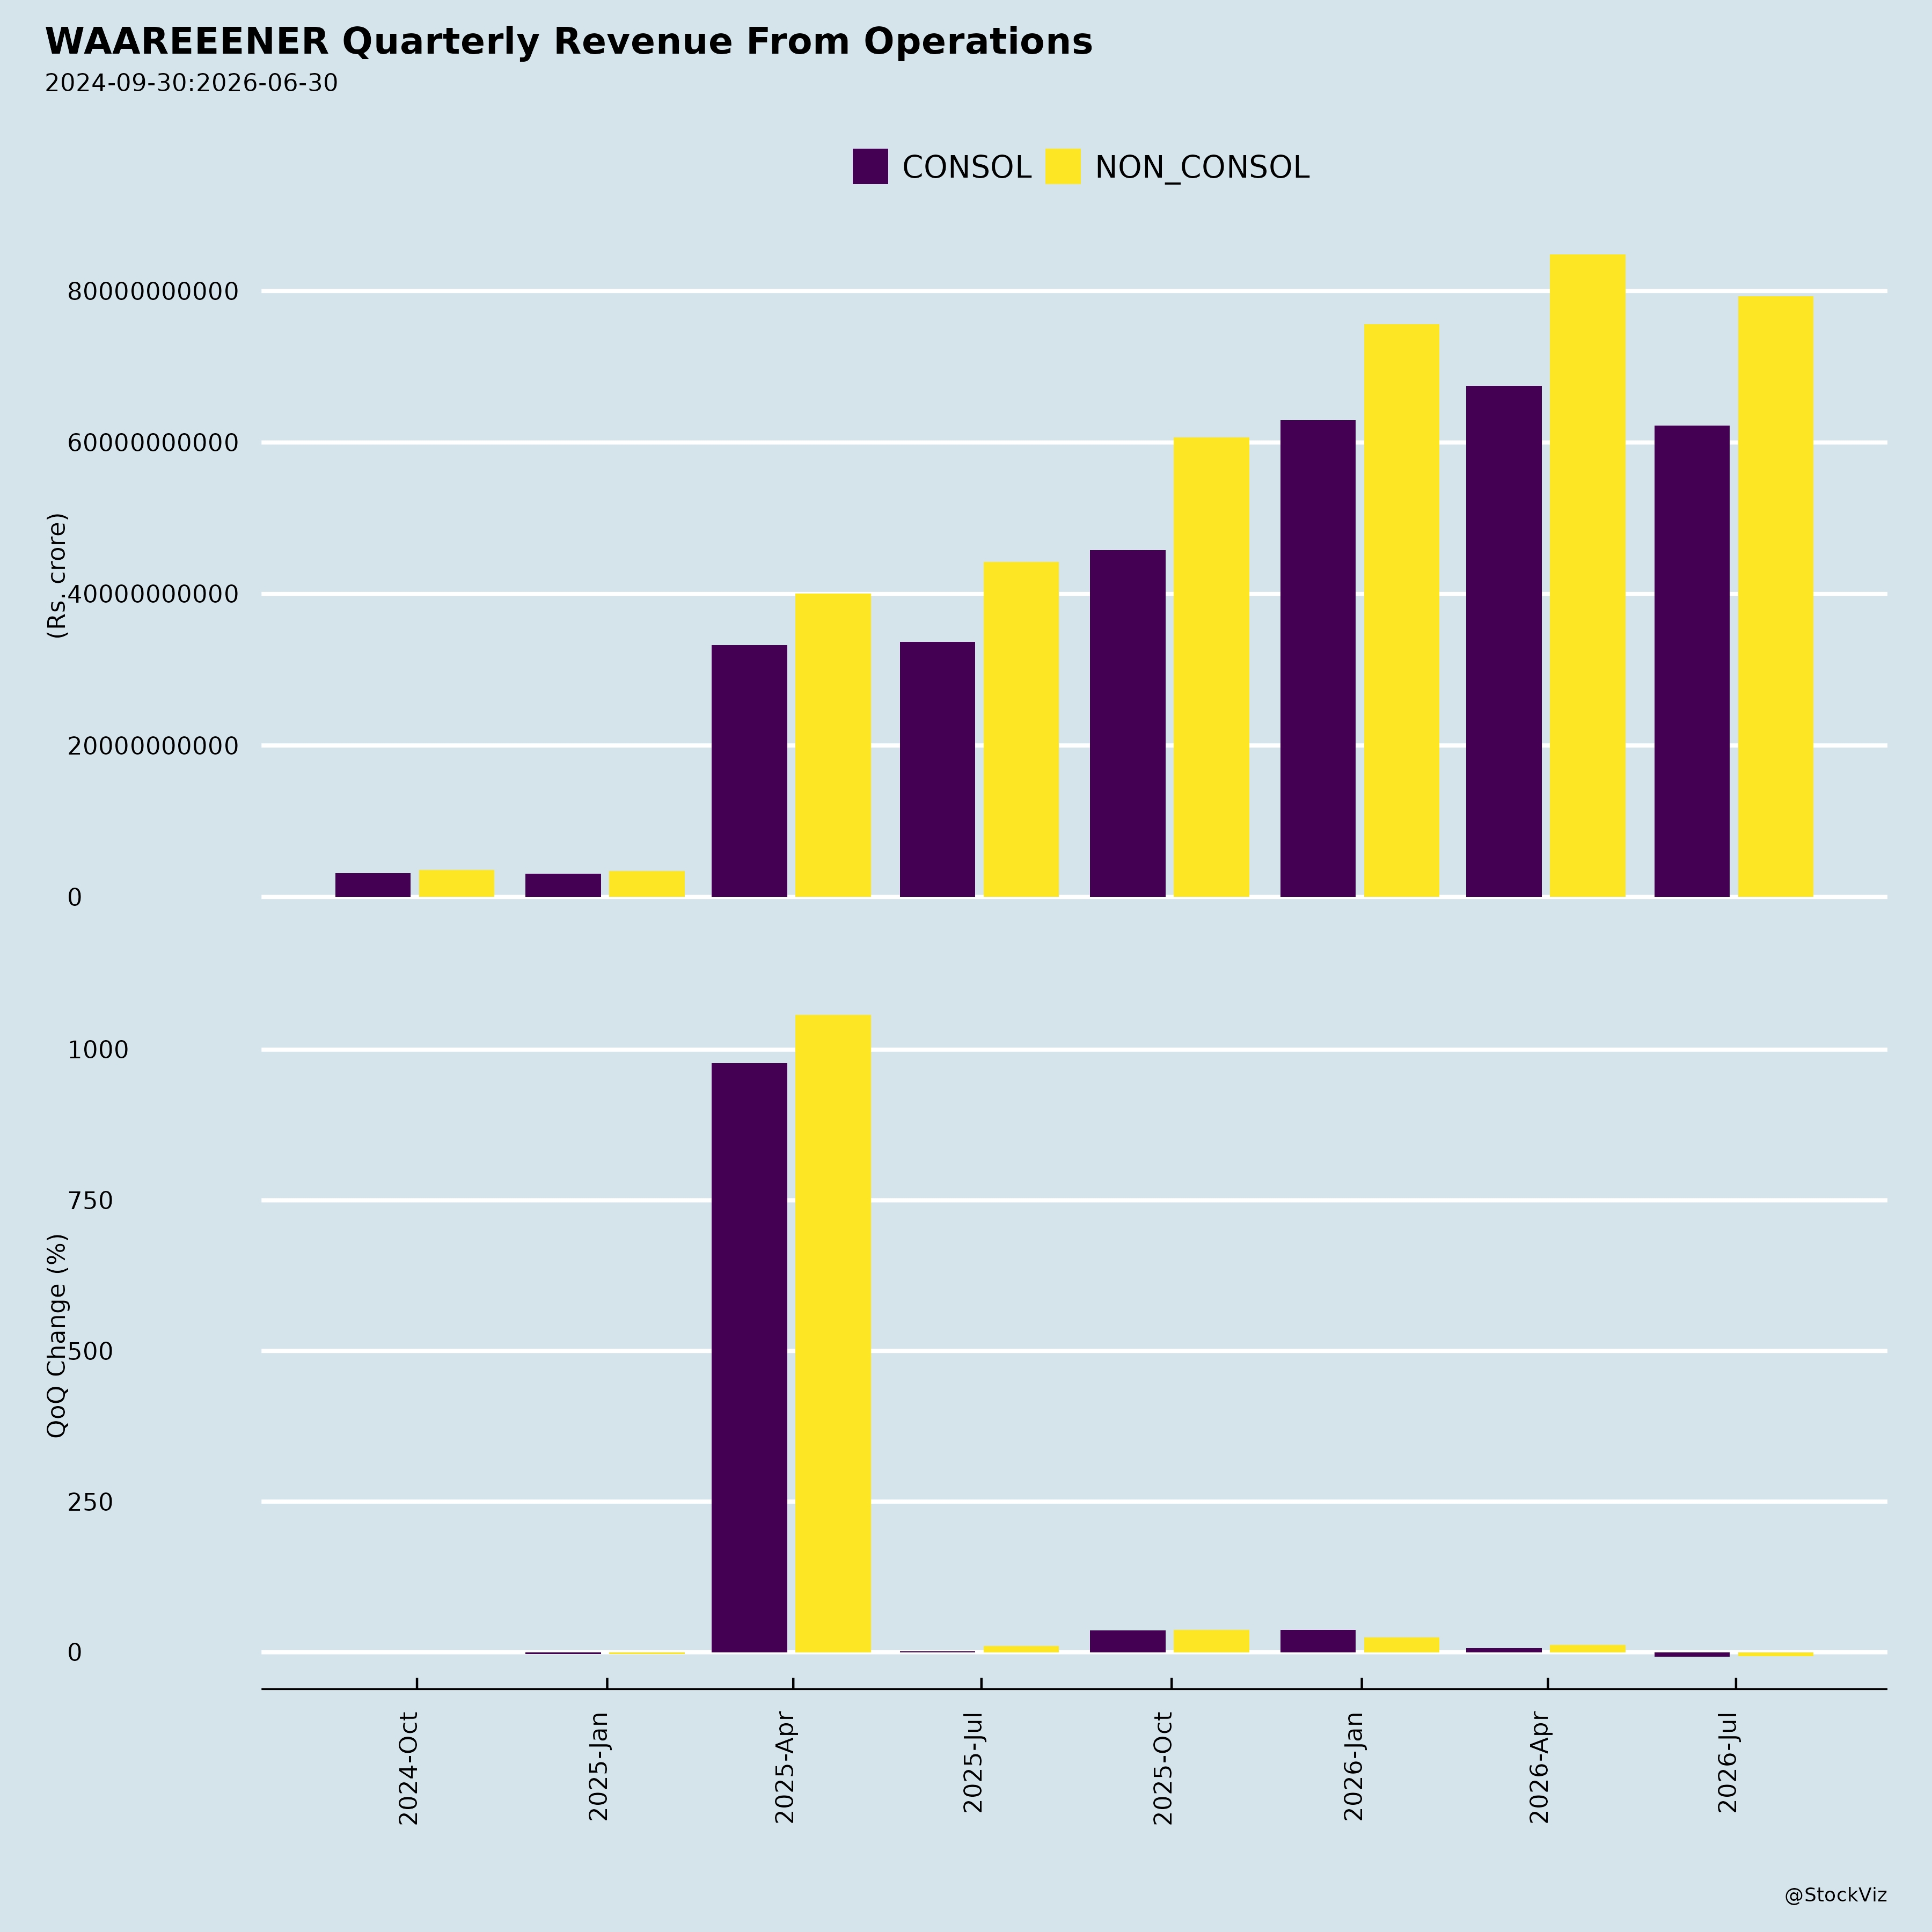
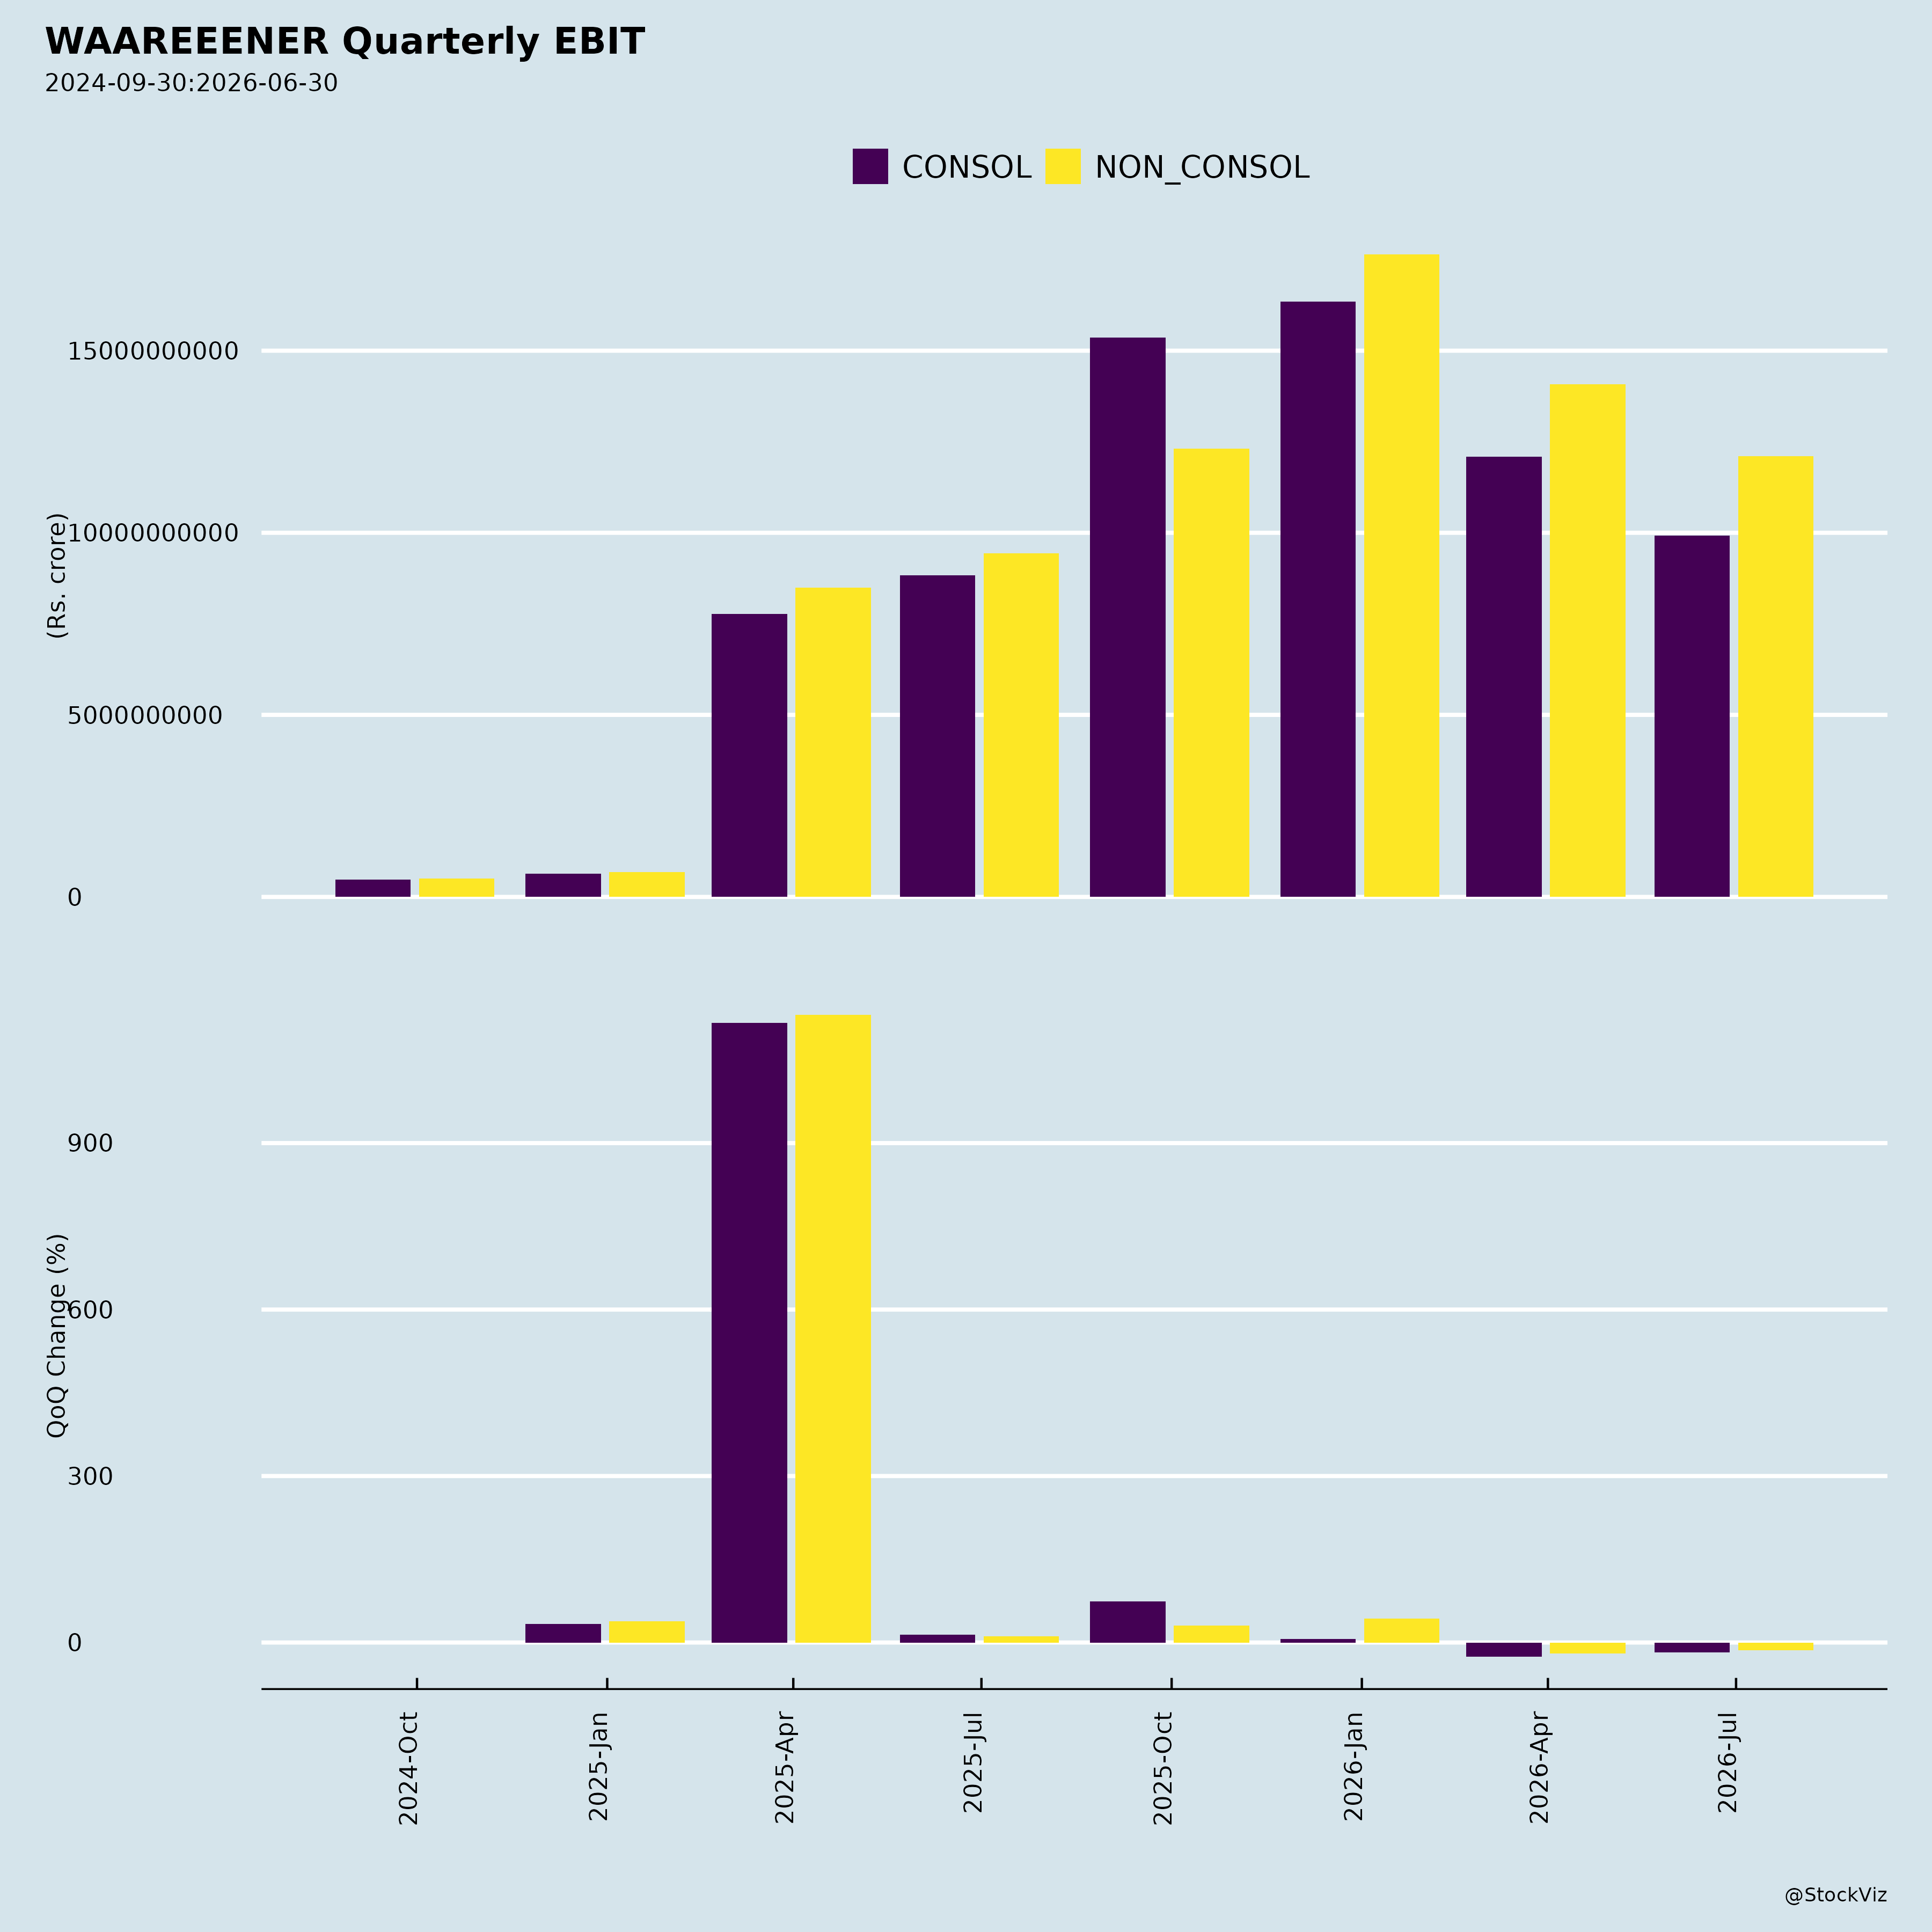
- Margin compression despite revenue growth. In Q1 FY27 (quarter ended June 30, 2026), revenue from operations rose 79.22% YoY to ₹7,931.79 crore, but Operating EBITDA margin fell to 18.15% from 22.53% in Q1 FY26, and PAT margin declined to 11.01% from 16.81%. Operating EBITDA grew 44.38% YoY and PAT 15.39% YoY — both slower than revenue growth.
- Sequential decline. Compared with Q4 FY26, Q1 FY27 revenue fell 6.47% (from ₹8,480.25 crore), Operating EBITDA fell 8.68%, and PAT fell 20.81% (from ₹1,126.26 crore).
- Regulatory/enforcement action. A search was conducted by the Directorate of Revenue Intelligence (DRI) on August 27, 2026 at the manufacturing plant of wholly owned subsidiary Sangam Solar One Private Limited, under Section 105 of the Customs Act, 1962, relating to classification of certain imported stainless-steel pipes and tubes under the EPCG Scheme and consequent applicability of Anti-Dumping Duty. The company paid Anti-Dumping Duty of ₹2,33,82,930 plus interest, and stated no further payment or impact on financials, operations, or other activities is expected beyond the amount paid.
- Facility consolidation and relocation. Manufacturing facilities at Tumb and Nandigram were consolidated into Chikhli, Gujarat, with the relocation estimated to close on or before December 31, 2026.
- Board transition. Ms. Richa Goyal completed her term as Independent Director; Ms. Mona Bhide was appointed as an Additional Non-Executive Independent Director (and proposed for a 5-year term at the AGM).
2. Tailwinds and Growth Prospects
- Record order book. Order book of approximately ₹61,500 crore as on July 28, 2026, with new orders worth approximately ₹16,000 crore added during the quarter.
- Capacity expansion. Additional 3 GW module capacity commissioned at Samakhiali, Gujarat in April 2026; module capacity at approximately 26 GW (25.8 GW per the press release) and cell capacity of 5.4 GW (India’s largest). The 10 GW cell facility at Unn, Gujarat is progressing as planned and expected to start production in the current financial year.
- New business engines (“Waaree 2.0”). Commenced 5.15 GWh automated BESS container capacity at Rola, Gujarat (versus 3.5 GWh planned); Waaree Transpower began production of 17.6 MVA inverter duty transformers; planned 20 GWh BESS capacity by FY28 with ~₹10,000 crore capex; 4 GW inverter capacity planned by FY27; 20,000 MVA transformer capacity planned; 1 GW electrolyser capacity planned by FY27; 2,500 TPD solar glass capacity planned (₹3,900 crore capex).
- EPC and infrastructure momentum. Waaree RTL received a 1,520 MWh BESS EPC order, two ground-mounted solar EPC orders of 800 MWac, and signed an ECI agreement for a utility-scale solar-plus-BESS project in New Zealand. EPC order book of ~₹5,300 crore including ₹2,700 crore+ from APSPL; ~2.4 GWp projects under execution. Renewable power infrastructure: 1,000+ MW PPAs signed, ~8 GW pipeline, ₹3,250+ crore total commitment.
- Acquisition. Waaree RTL acquired ~55% equity stake in Associated Power Structures Pvt. Ltd. (APSPL) for ~₹1,225 crore, enhancing power infrastructure capabilities.
- International expansion. First HJT module order of 125 MW under Waaree Solar Americas; new business opportunities across Europe, the Middle East, New Zealand, and Australia. US subsidiary Waaree Solar Americas Inc. is investing approximately US$37 million to revamp the Arizona facility, increasing capacity from 1 to 1.6 GW and bringing total US manufacturing capacity to 4.8 GW.
- New project award. Wholly owned subsidiary Waaree Forever Energies Private Limited received a Letter of Award on August 27, 2026 from Solar Energy Corporation of India Limited for a 700 MW solar and 700 MW/2800 MWh energy storage renewable energy power project in Solapur, Maharashtra, with a 25-year PPA.
- Policy tailwinds. PLI incentives, ALMM Lists I–III, 20% BCD on imports, PM Surya Ghar and PM-KUSUM schemes, BESS VGF, ISTS waivers, mandatory 2-hour ESS norms, ACC battery PLI, Green Hydrogen Mission, and a 5-year anti-dumping duty on Chinese and Vietnamese solar glass (effective December 2024).
- Retail and channel strength. Retail, services, and overseas segments contribute 60–70% of revenue; presence across ~15,000 pin codes; two new product launches (Radiance Kusum Agri Kit and a fleet-level data offering).
3. Key Risks
- Margin pressure from the shift in revenue mix and cost structure, evidenced by the YoY and QoQ margin declines.
- Execution risk on the large capex pipeline across BESS, cells, ingots/wafers, glass, electrolysers, inverters, and transformers, with timelines spanning FY27–FY29.
- Regulatory and customs risk, as illustrated by the DRI search and Anti-Dumping Duty payment at Sangam Solar One.
- Relocation risk tied to the Chikhli consolidation and the December 31, 2026 closure timeline.
- Dependence on policy support (PLI, ALMM, BCD, VGF, anti-dumping duties) across solar, BESS, and green hydrogen.
- Competition and global supply-chain dynamics, including FEOC compliance requirements and non-China supply-chain rules in the US and EU.
4. Management Guidance vs. Observed Performance
- FY27 Operating EBITDA guidance reaffirmed at ₹7,000–7,700 crore. Q1 FY27 Operating EBITDA was ₹1,439.92 crore, implying roughly 19–21% of the guidance range achieved in the first quarter.
- Module production of 3.24 GW in Q1 FY27, a growth of 41.51% YoY.
- 10 GW Unn cell facility — management states it is progressing as per plan and expected to start production in the current financial year.
- BESS capacity — 5.15 GWh commenced versus 3.5 GWh originally planned, ahead of the stated plan.
- US capacity — Arizona revamp expected to take aggregate US manufacturing capacity to 4.8 GW upon completion.
- Chikhli relocation — estimated closure on or before December 31, 2026.
- Capital position — net debt to equity of -0.08x; ROCE 28.5% and ROE 24.8% (Q1 FY27 annualized); management states the balance sheet, phased capital deployment, and expected cash flow generation over the next two years position it to fund expansion while maintaining disciplined capital allocation.
5. Other Key Investor Facts
- The 36th Annual General Meeting is scheduled for Thursday, September 24, 2026 at 11:00 A.M. IST via video conferencing/other audio-visual means. Agenda items include adoption of financial statements, declaration of a final dividend of ₹2 per equity share (20% on face value) for FY ended March 31, 2026, re-appointment of Whole-Time Director Mr. Viren Chimanlal Doshi, ratification of Cost Auditors M/s V. J Talati & Co remuneration (₹1,30,000 plus out-of-pocket expenses and GST), and appointment of Ms. Mona Bhide as Independent Director for 5 years.
- Record date for the final dividend: Friday, September 11, 2026.
- Management is scheduled to interact with DAM Capital Renewable Energy in Mumbai on Thursday, August 27, 2026, from 10:00 a.m. to 5:00 p.m. in person, based solely on publicly available information.
- Credit rating upgraded to AA- by CareEdge Ratings.
Broker Narrative
The narrative shifted from initial caution (Not Rated in Mar 2025) to repeated Buy calls despite deteriorating fundamentals. Early themes of export concentration, China dependency, and IRA uncertainty persisted as material headwinds in the latest report, while initial optimism around US manufacturing and backward integration was tempered by承认 that captive US capacity hadn’t yet delivered IRA benefits and execution risks materialized after a weak Q1 FY27. The record order book of Rs615bn provided revenue visibility but failed to protect against significant negative returns in May-Jun 2026.
Fears that came true
- Export concentration risk (57.6% of revenue in FY24) materialized as export mix fell to 22% in Q1FY27 from 32% in Q1FY26 with softer exports and US tariff disruptions.
- China dependency (~60%) materialized through elevated China-linked raw-material costs flagged in the latest report.
- IRA uncertainty materialized as higher reliance on US merchant sales reduced the benefit of IRA incentives from captive manufacturing.
- Declining realizations materialized via lower industry-wide module realisations and module utilisation at 56% below the normalised >70% level.
- Execution risk materialized with weak Q1 FY27 increasing execution risk and delayed project offtake amid ALMM-II uncertainty.
Optimism that failed
- US expansion (Texas 1.6GW, 3.75GW supply agreement, federal incentives) failed to deliver expected margin restoration — IRA benefits were reduced and tariff uncertainty weighed on margins instead.
- Export opportunities in USA/Europe/Middle East failed as exports weakened and export mix fell from 32% to 22%.
- Backward integration improving margins failed as China-linked raw-material costs remained elevated and margins compressed despite cell capacity ramp-up.
- Strong orderbook (26.5GW) driving positive returns failed — record Rs615bn (25.2GW) order book coincided with DISAPPOINTMENT outcomes (-15.5% to -18.3%).
Broker Timeline
15 broker calls · 2025-03-07 to 2026-07-30
Copyright © 2023 SAS Data Analytics Pvt. Ltd. All rights reserved.