VIKASLIFE
Equity Metrics
September 24, 2026
Vikas Lifecare Limited
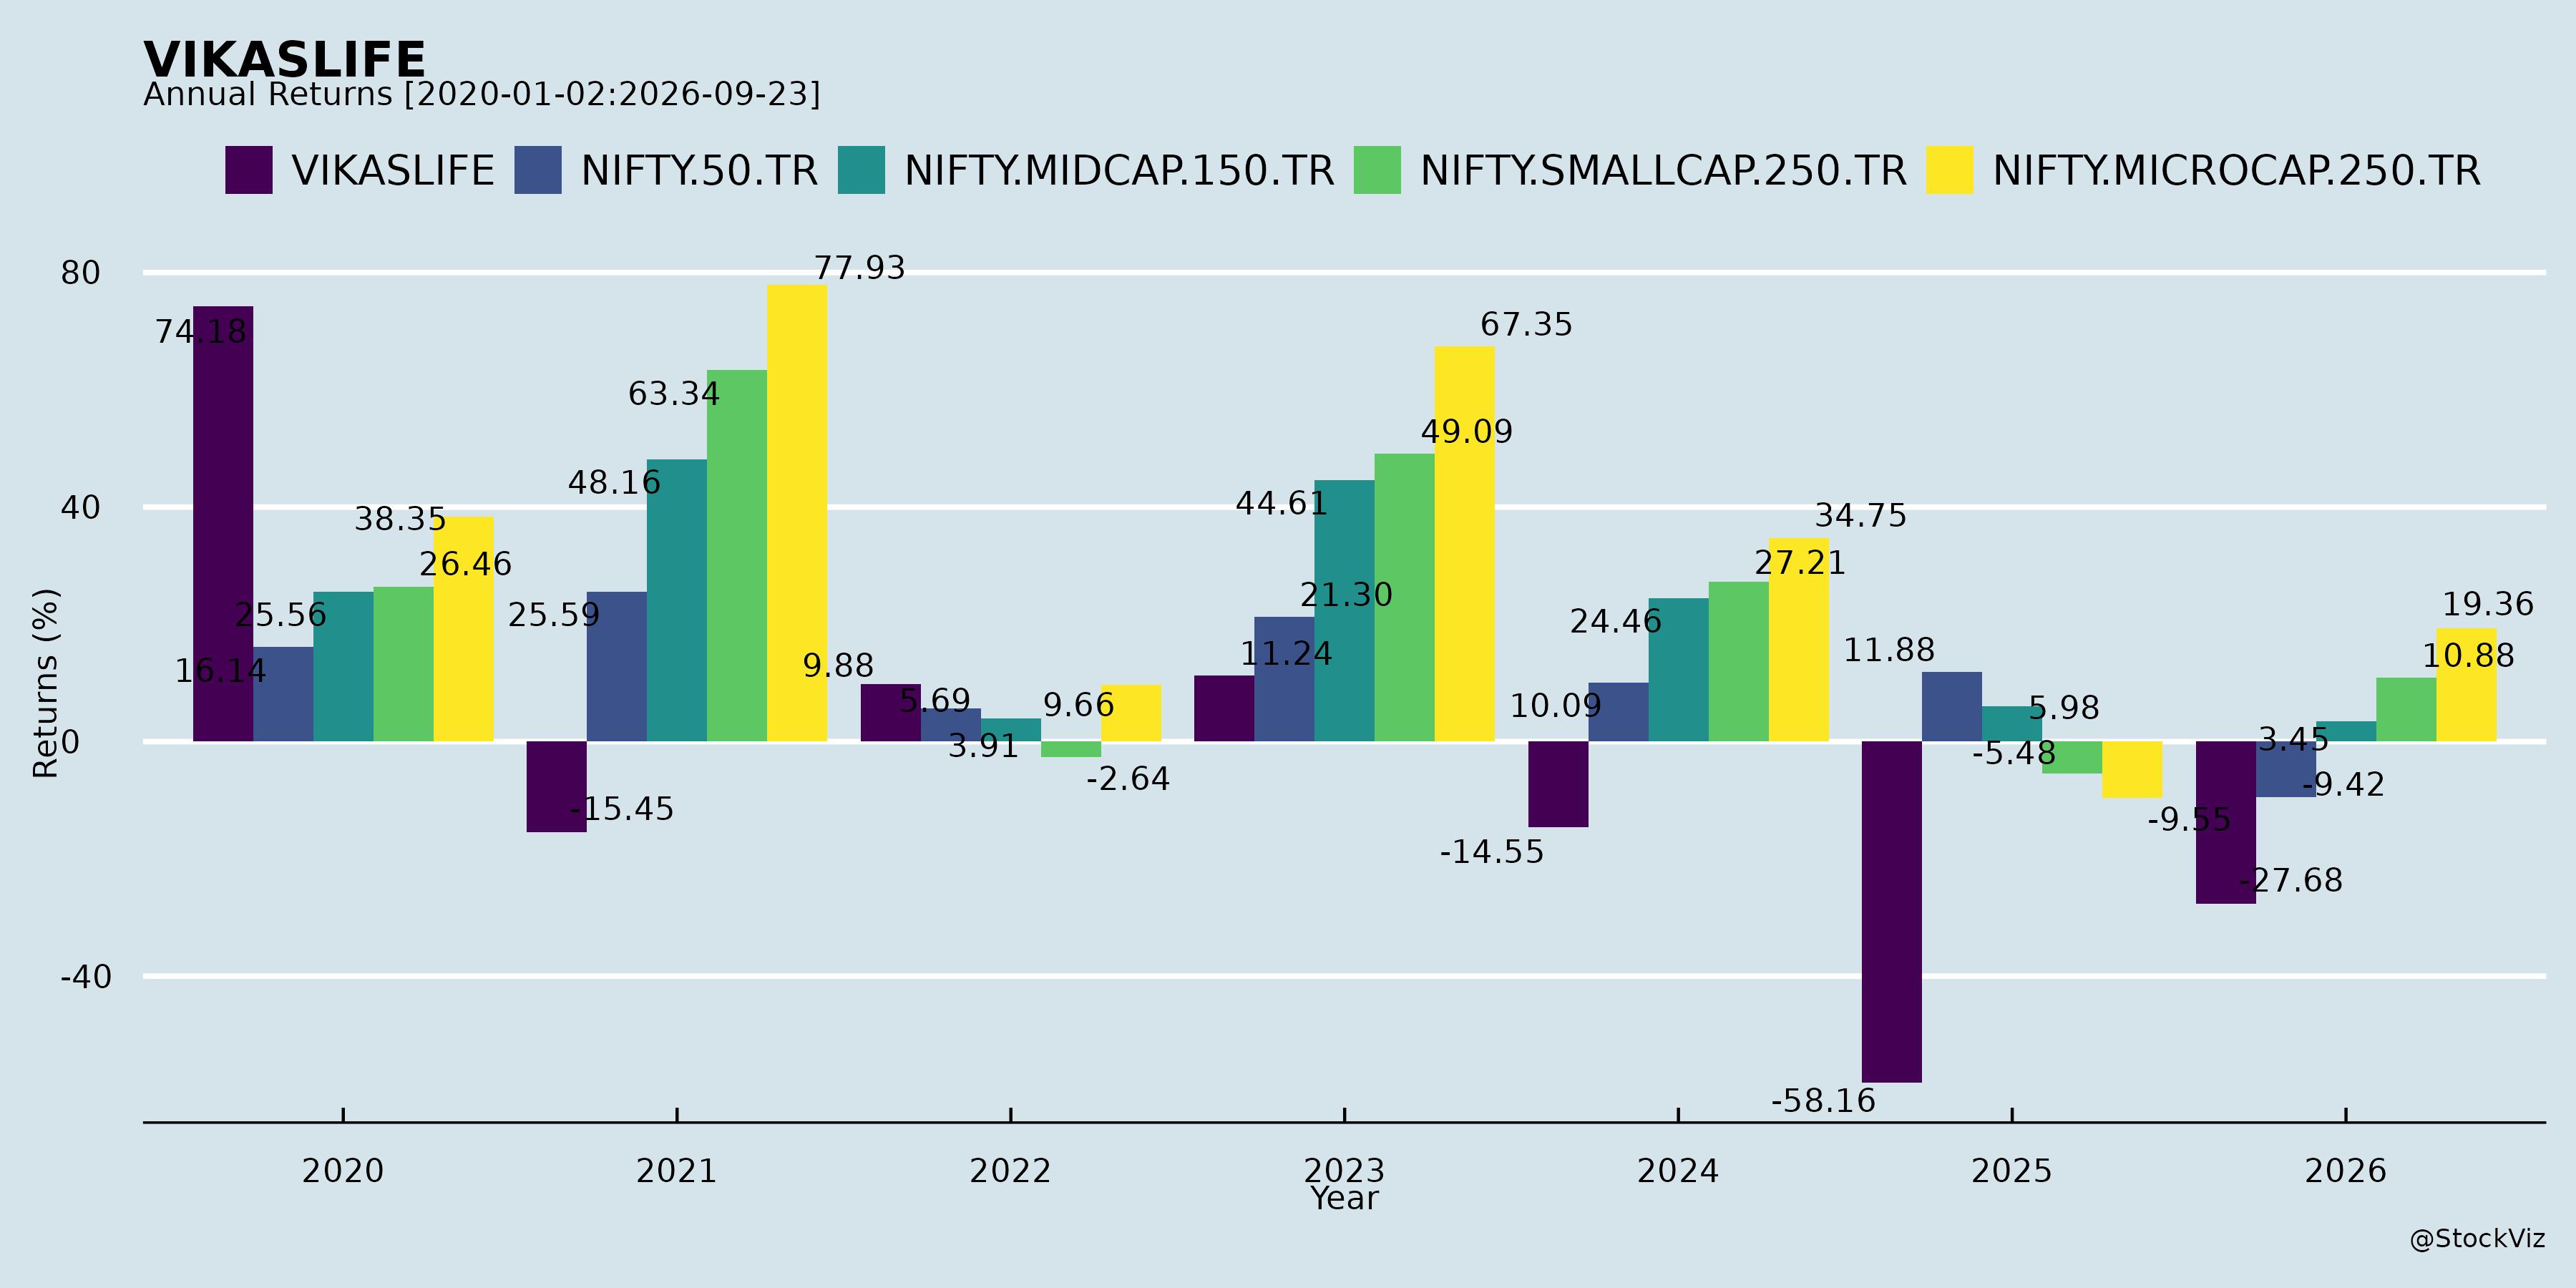
Annual Returns
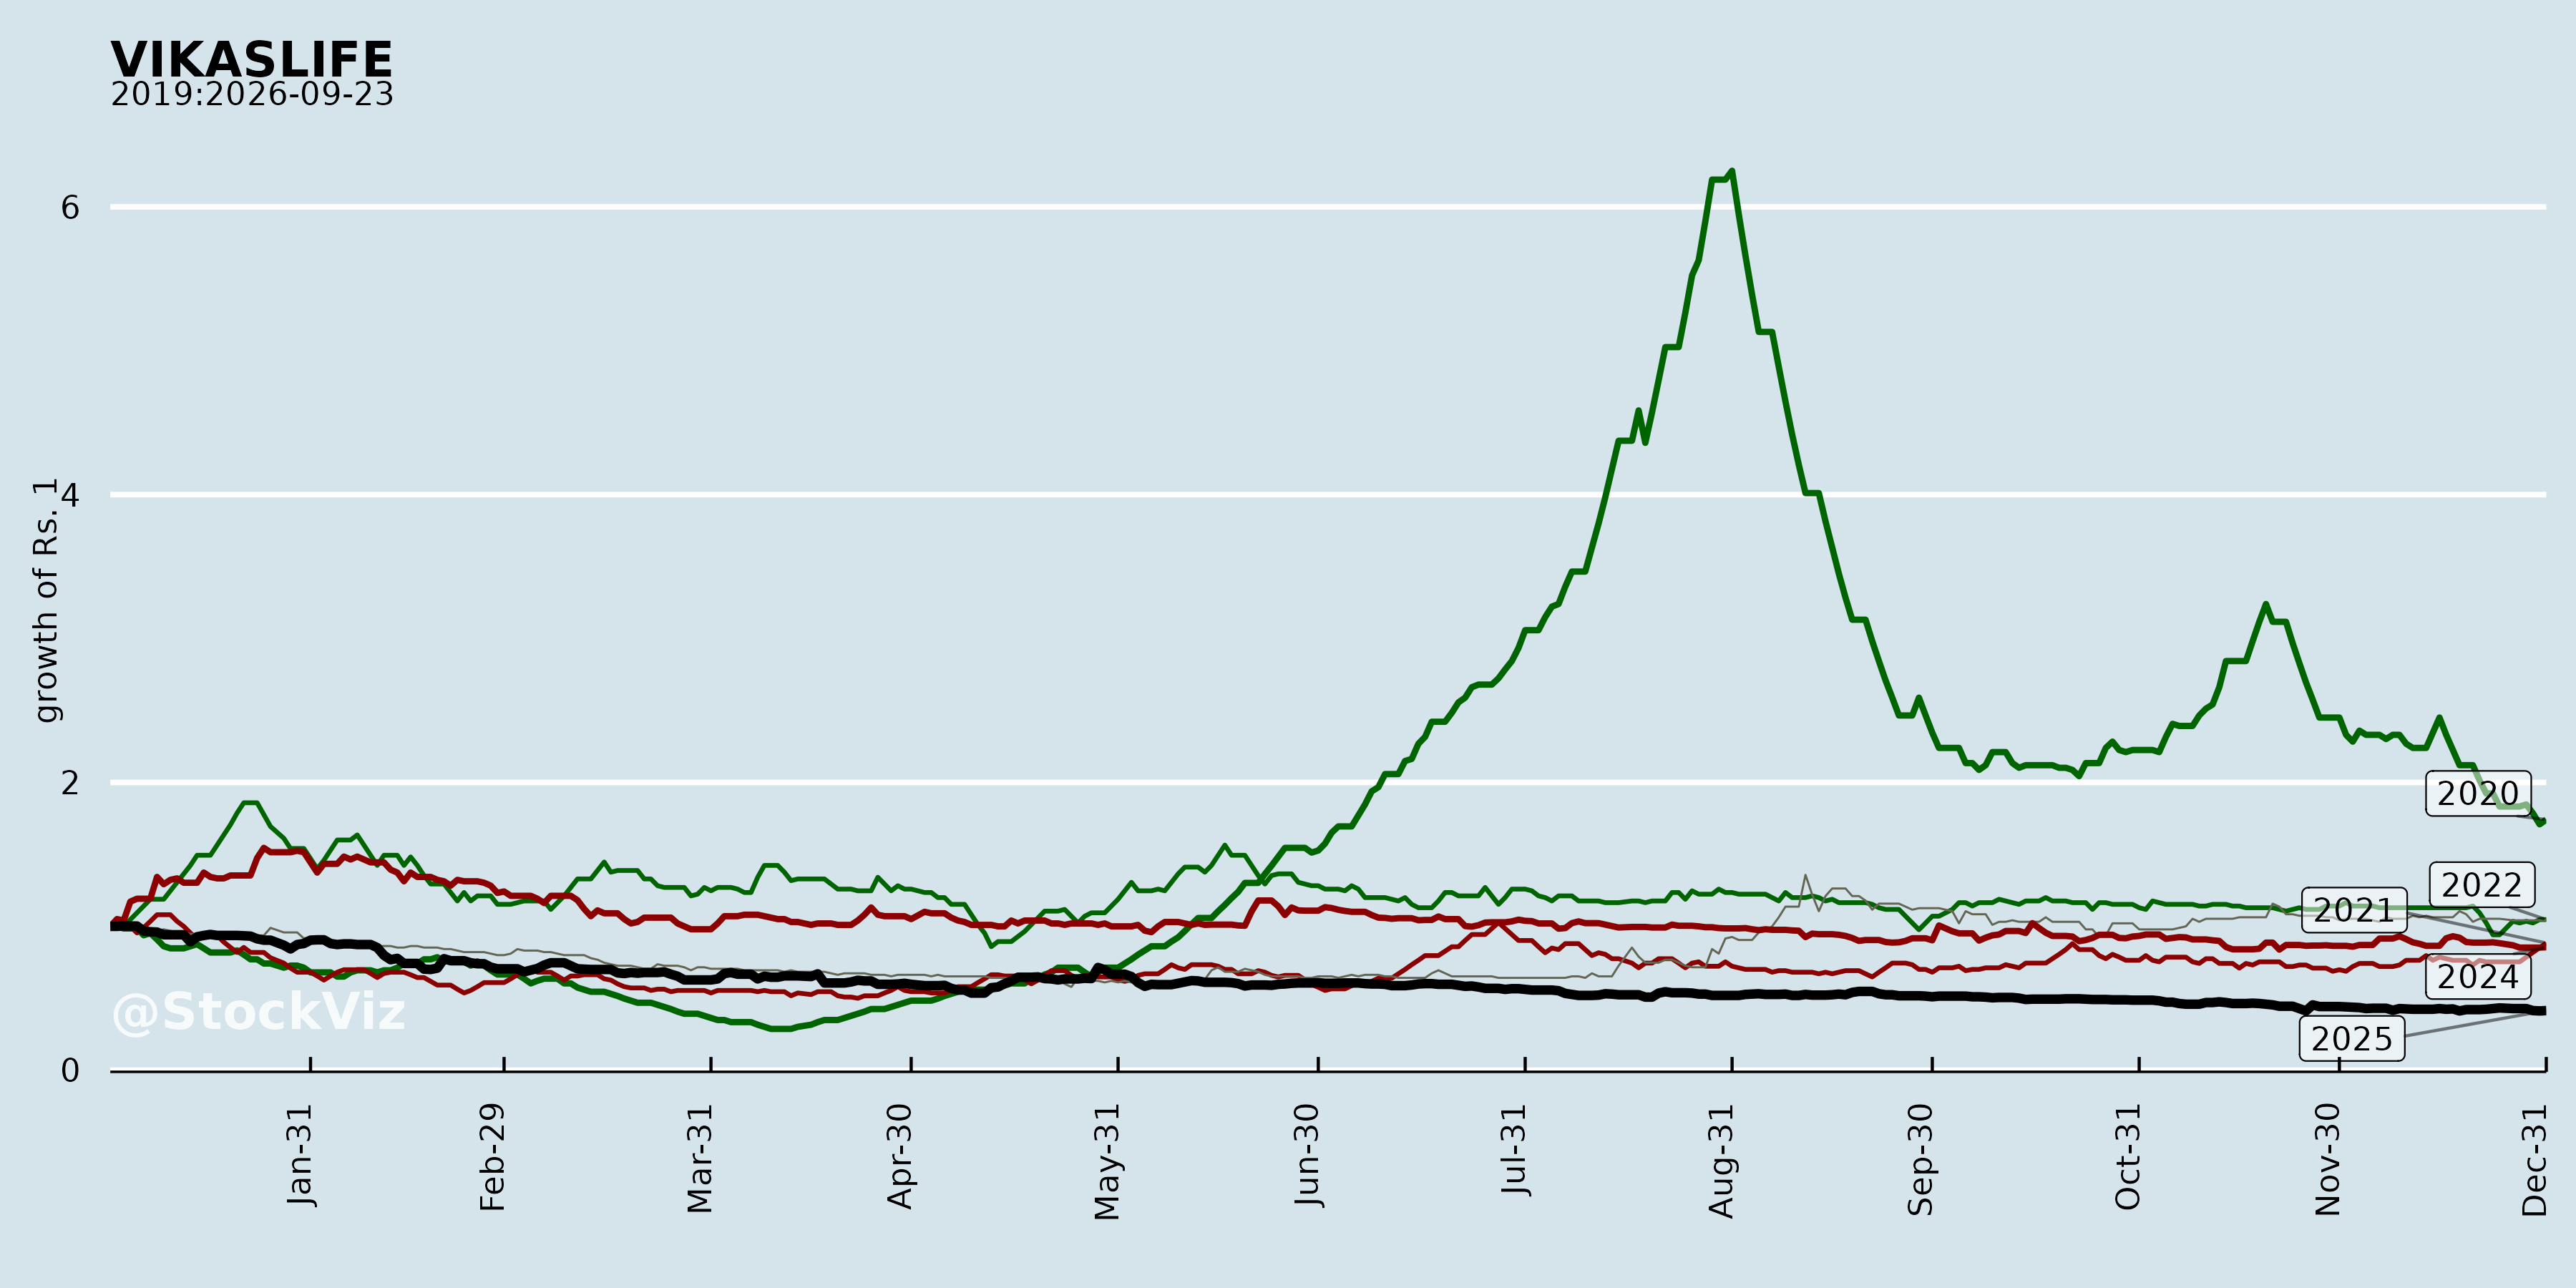
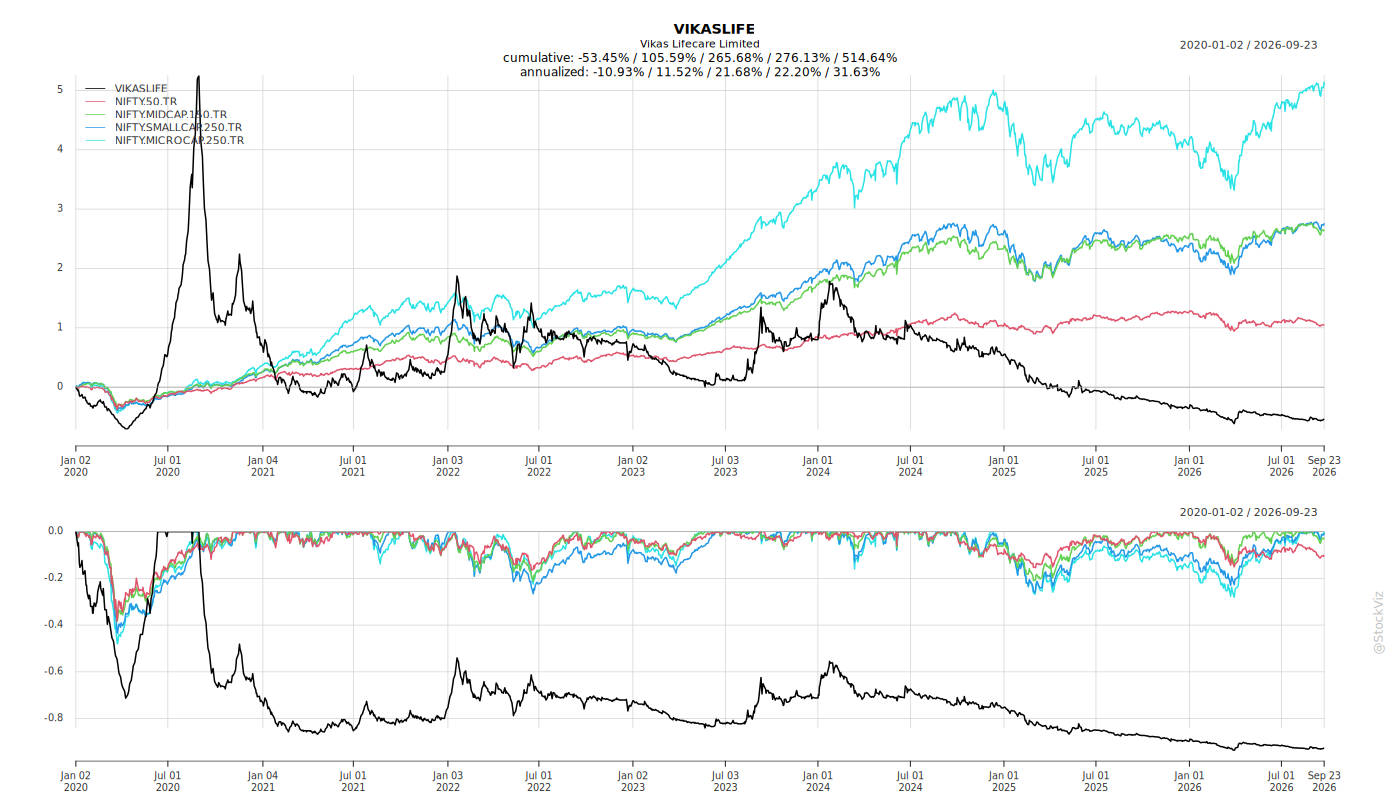
Cumulative Returns and Drawdowns
Fundamentals
Ownership
Margined
AI Summary
asof: 2026-09-19
Vikas Lifecare Limited — Analysis of FY2025-26 Audited Results and Corporate Announcements
1. Headwinds and Challenges
Audit qualification and unresolved evidence gaps. The standalone and consolidated results for the quarter and year ended March 31, 2026, approved by the Board on June 24, 2026, carry a qualified opinion from KSMC & Associates. The auditors state they were not provided sufficient appropriate audit evidence regarding the business rationale of investments in shares and inter-corporate deposits made during the year, at a time when substantial statutory dues remained outstanding. They also flag material related party transactions — inter-corporate deposits, acquisition of investments, and other transactions with promoter group entities, subsidiaries, step-down subsidiaries and associates — for which prior shareholder approval under Regulation 23 of the SEBI LODR Regulations and Section 188 of the Companies Act, 2013 had not been obtained as of the date of approval of the results.
Statutory dues and Section 186 non-compliance. Note 13 records delays in remittance of statutory dues, with certain statutory liabilities still outstanding at the reporting date. Note 11 states that investments and loans were made in non-compliance with Section 186(8) of the Companies Act, 2013 because of existing defaults in repayment of loan and interest on certain borrowings.
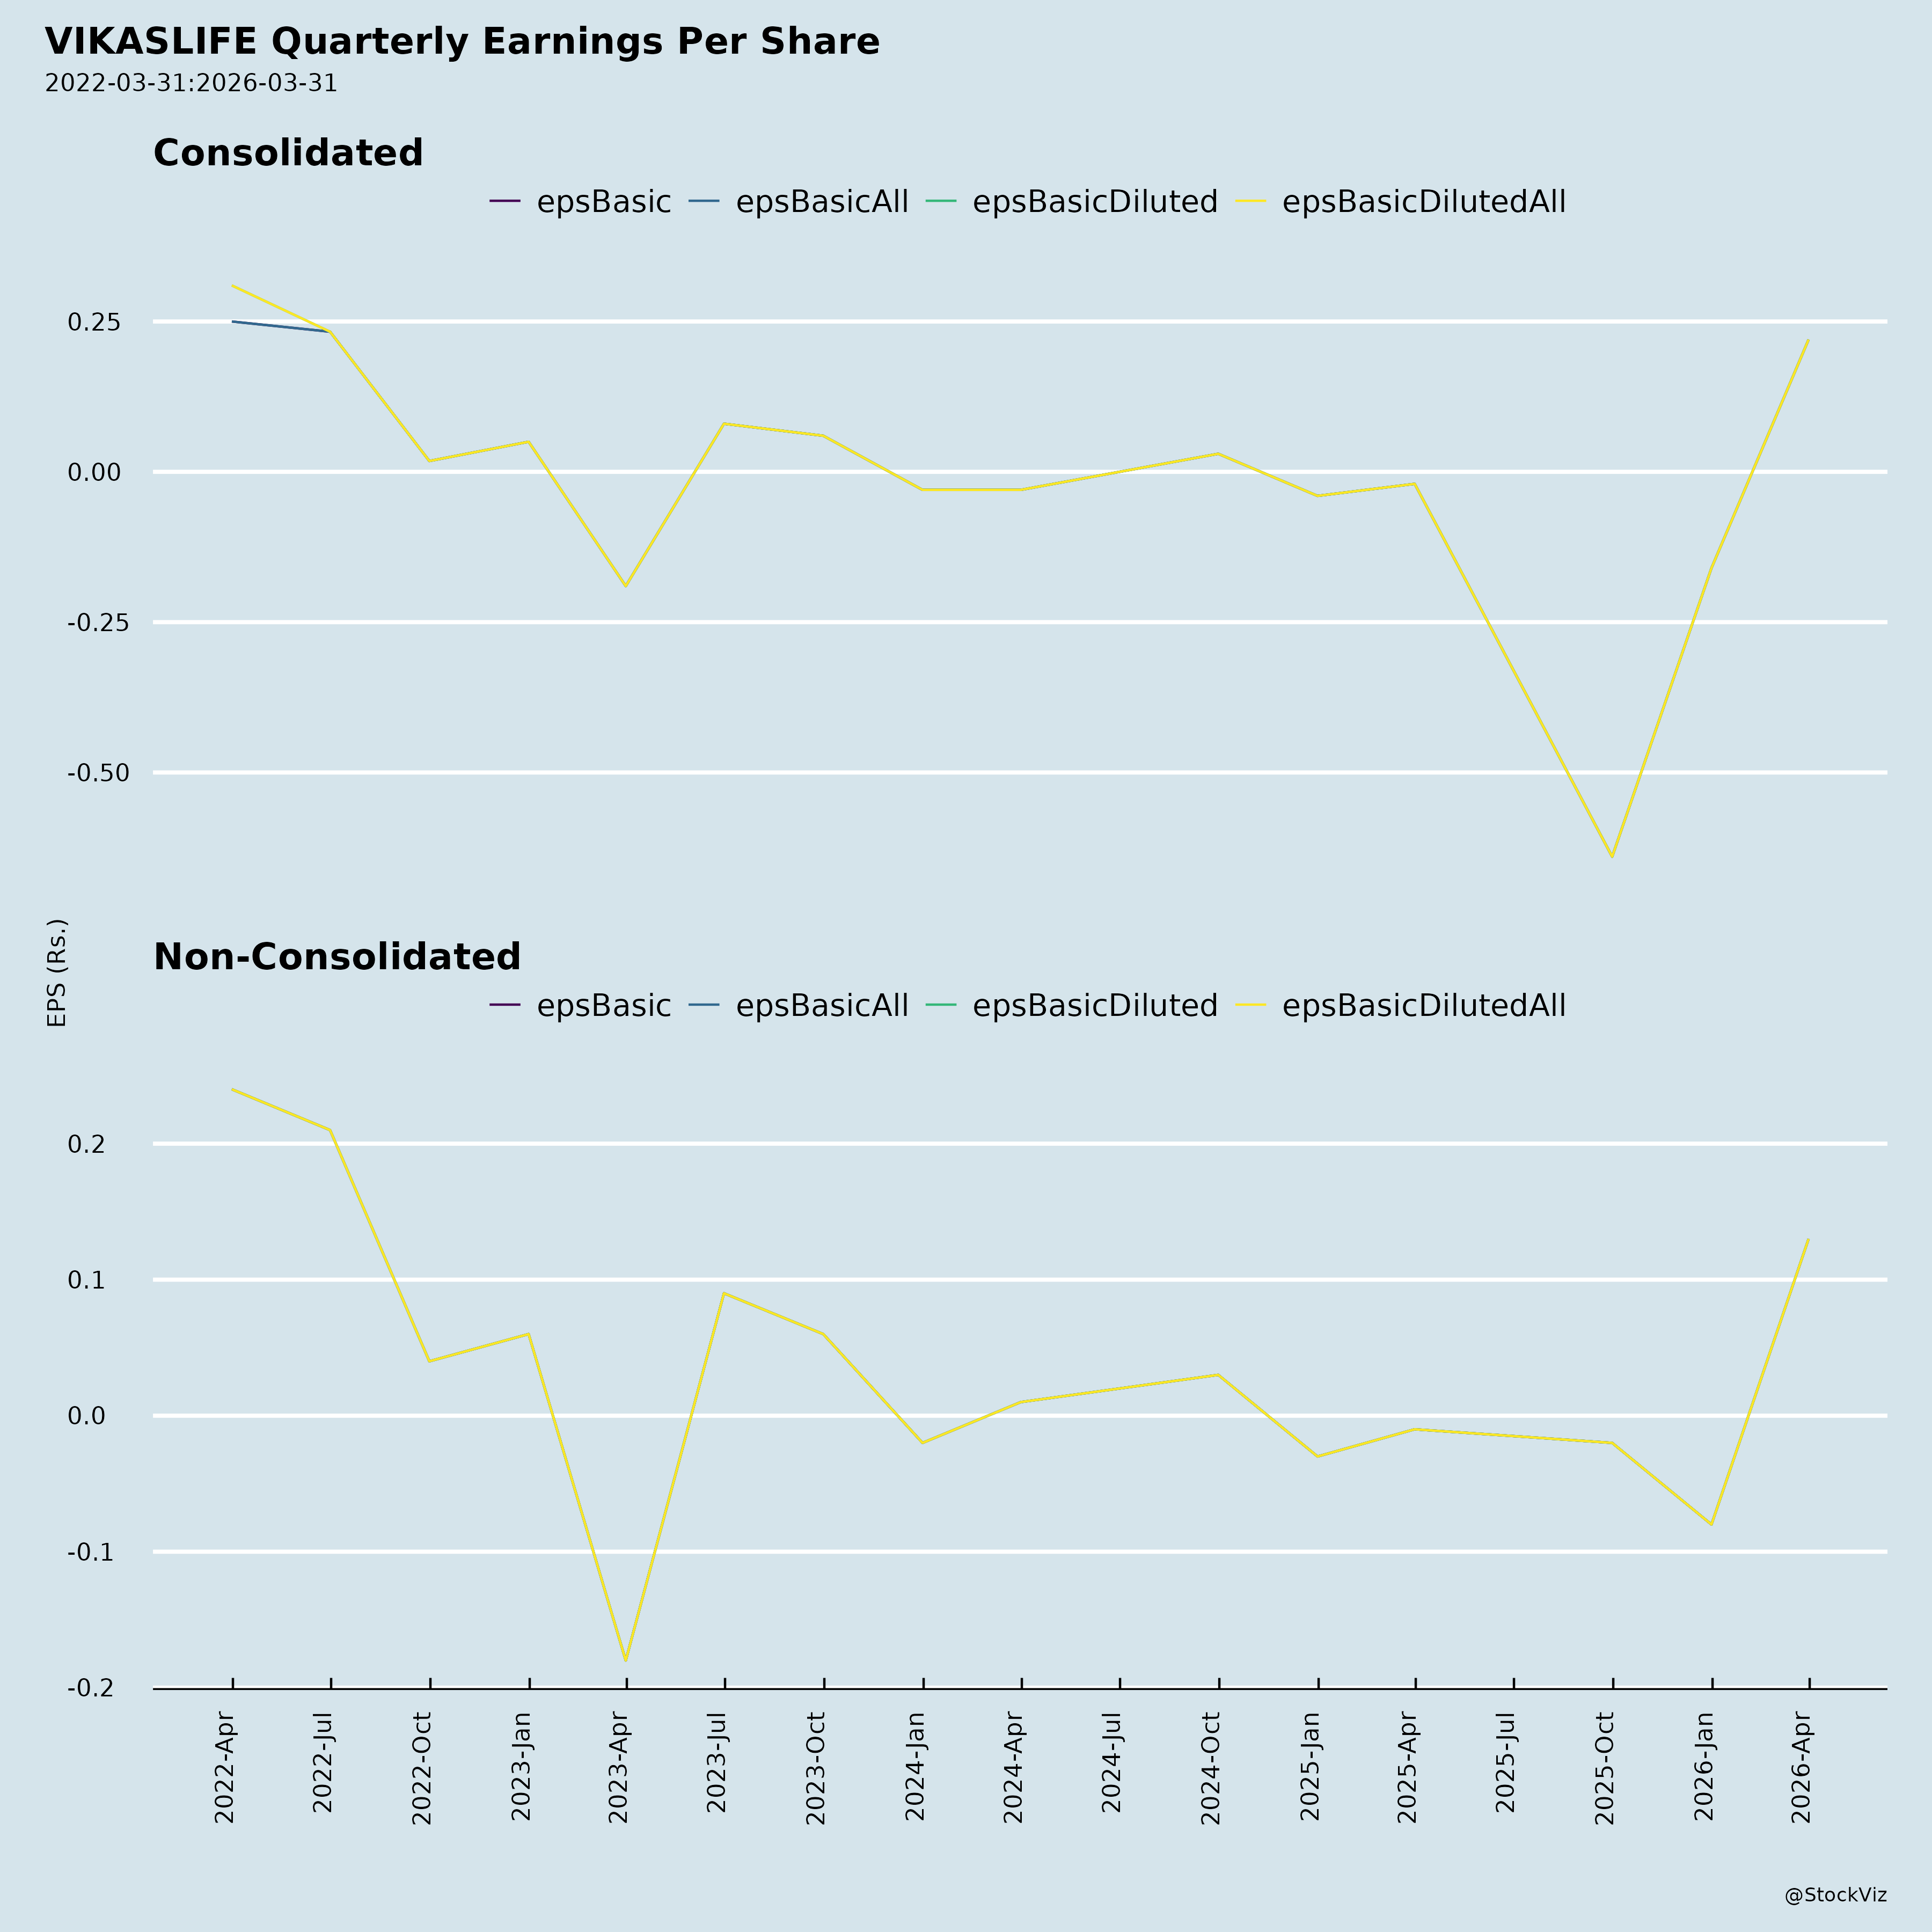
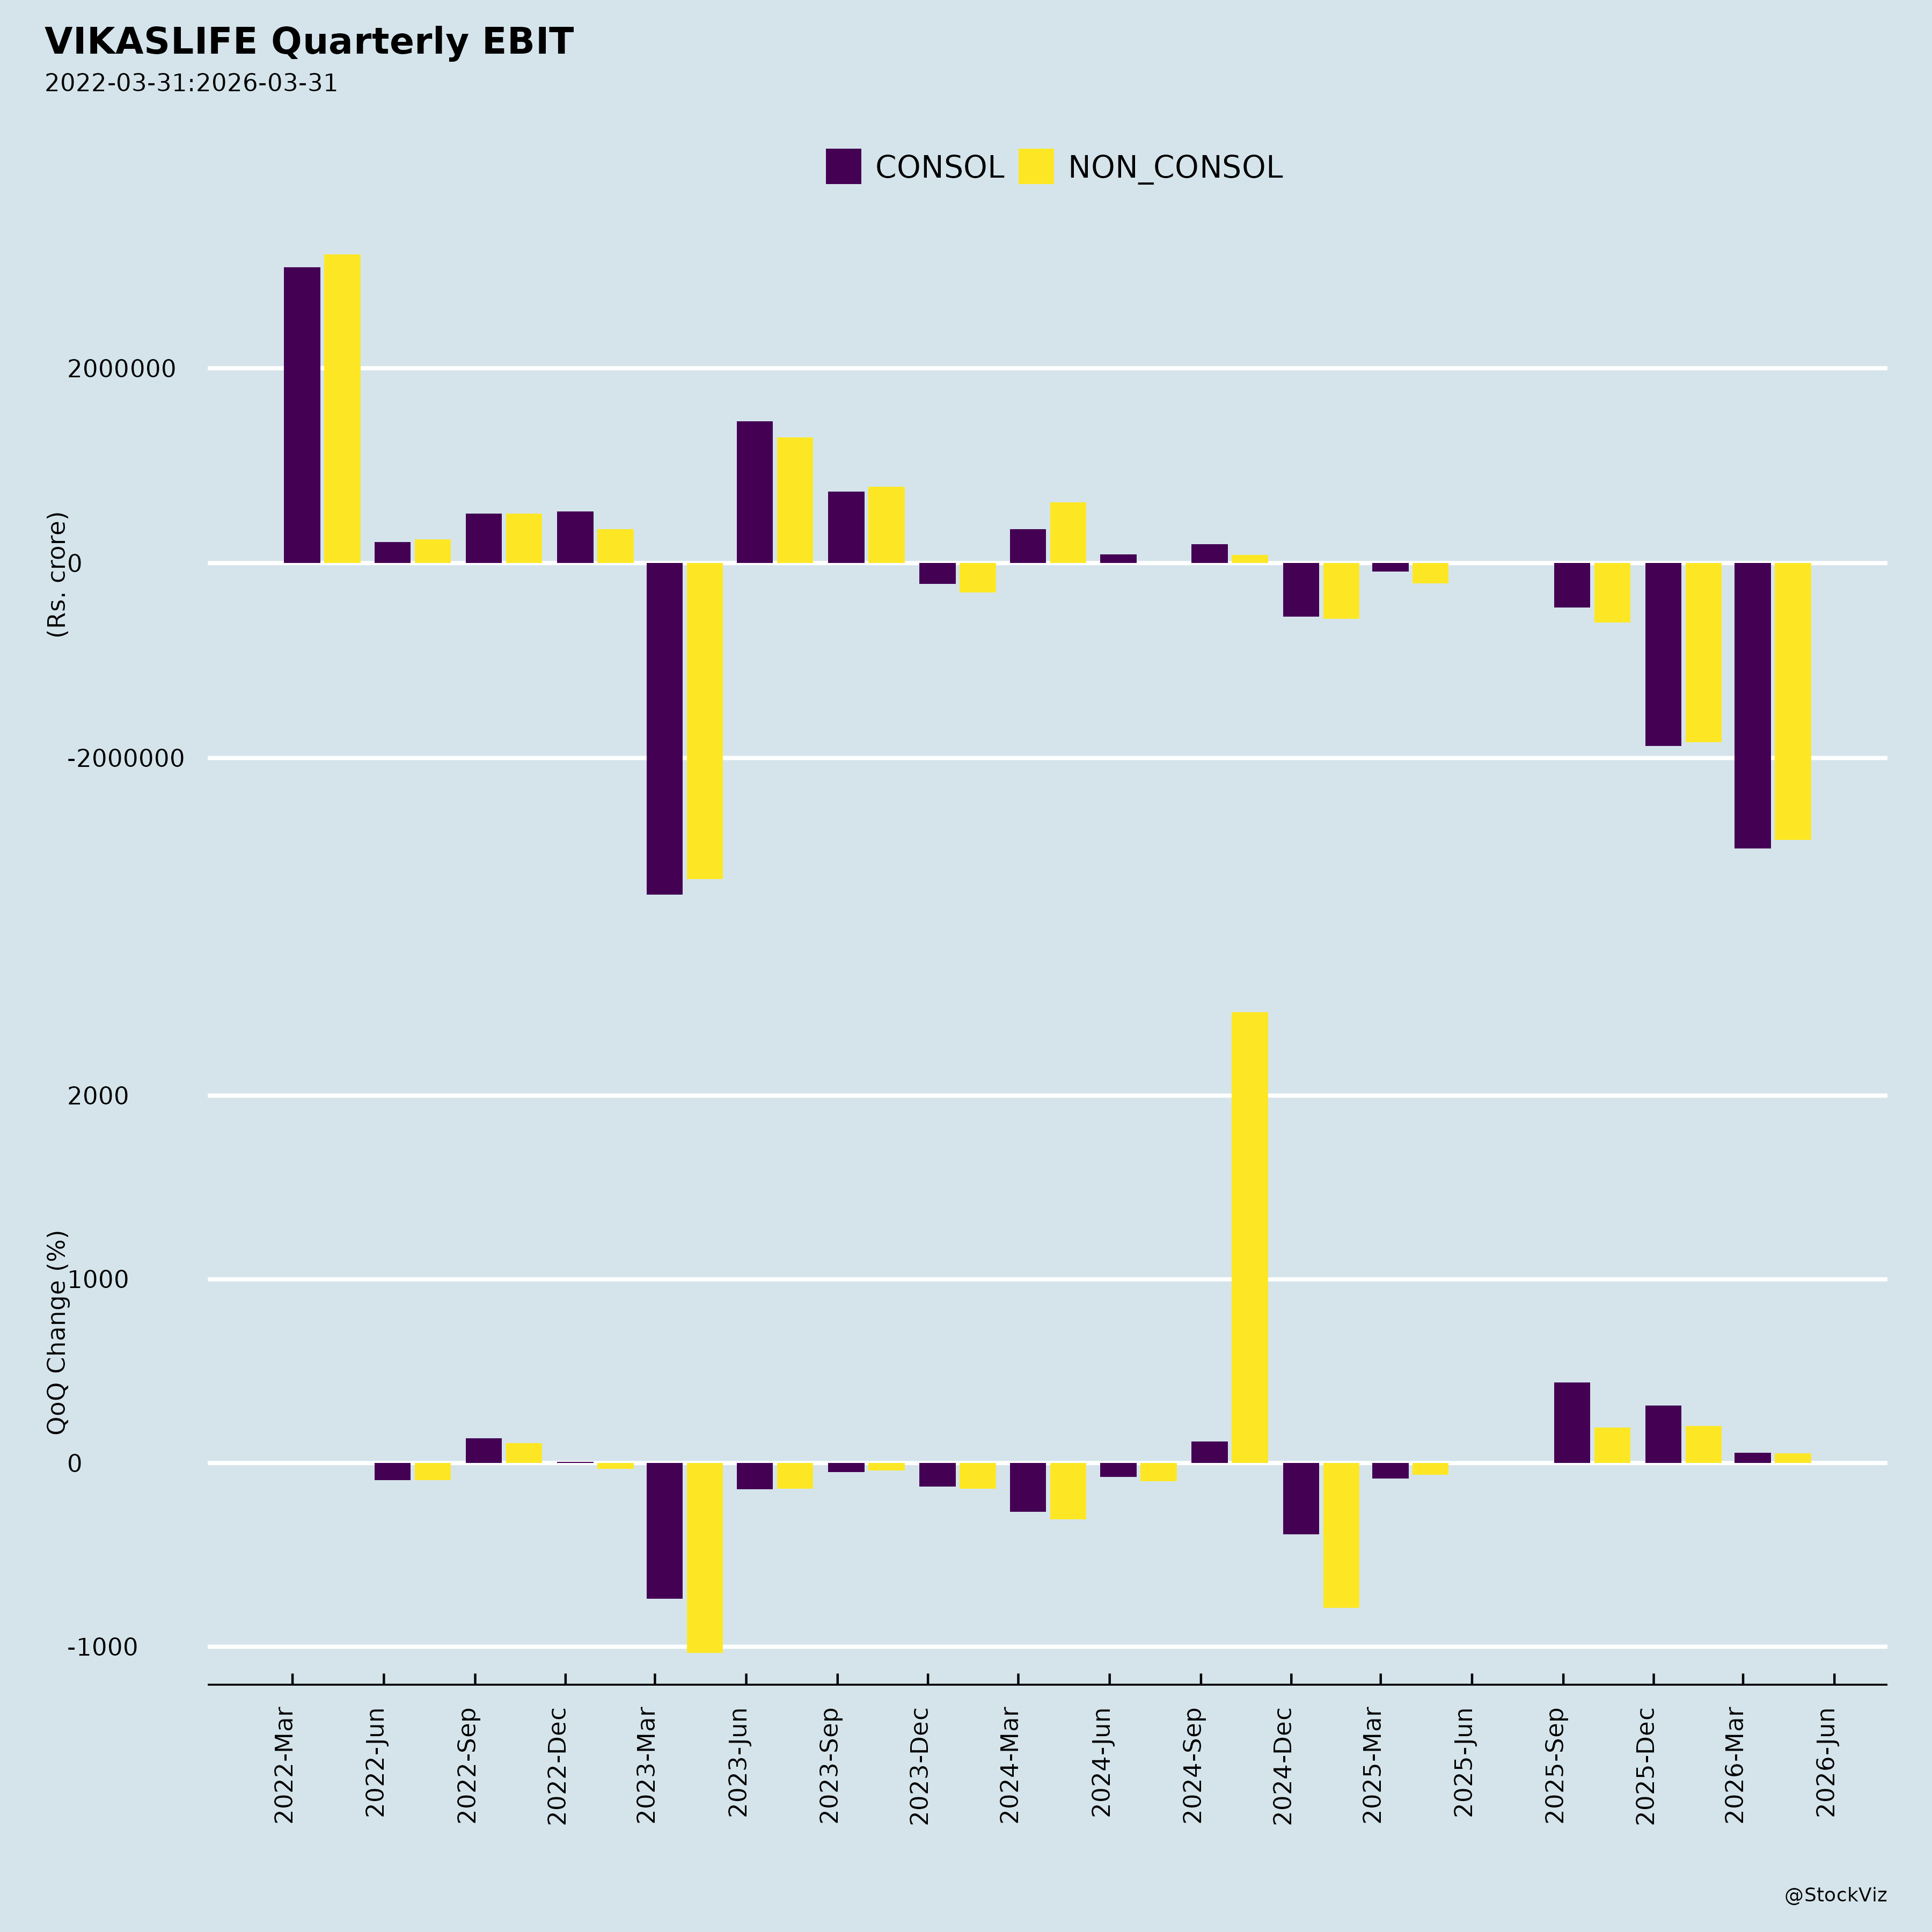
Loss-making quarter. On a standalone basis, the quarter ended March 31, 2026 recorded a loss before tax of ₹(2,930.04) lakhs and a net loss of ₹(2,325.15) lakhs, following a loss of ₹(1,876.25) lakhs in the December 2025 quarter. Total expenses of ₹19,536.52 lakhs exceeded total income of ₹16,606.48 lakhs for the quarter. On a consolidated basis, the March 2026 quarter showed a profit before tax of ₹3,526.75 lakhs and net profit of ₹4,159.62 lakhs, but this was after including a share of profit in an associate of ₹6,366.71 lakhs; the pre-associate profit was a loss of ₹(2,839.96) lakhs.
Losses on disposals and impairments. The company disposed of its entire 51.38% stake in Shashi Beriwal and Co Private Limited for ₹4.15 crores against a carrying amount of ₹11.21 crores, recognising a loss of ₹7.06 crores. It sold an immovable property at Arihant Nagar, Delhi for ₹3.00 crores against a carrying amount comprising land of ₹4.36 crores and building of ₹1.02 crores, recognising a loss of ₹2.56 crores. An advance of ₹5.00 crores paid towards a proposed 30% acquisition of Abhhyam Services Private Limited was impaired, with a dispute over a purported transfer of shares and legal proceedings initiated.
Regulatory and investigative matters. A provisional attachment order dated June 5, 2026 was issued by the Enforcement Directorate under Section 5(1) of the PMLA, attaching immovable properties with an approximate purchase value of ₹1,333.84 lakhs in connection with an investigation relating to the Mahadev Online Book matter. A SEBI investigation under Section 11C of the SEBI Act, 1992 is ongoing, with no final conclusion or order passed. Income tax demand notices aggregating ₹26.44 crores were received for various assessment years, which the company is contesting.
Inter-corporate borrowing issues. Demand notices were received from M/s Capital Tradelinks Limited in relation to inter-corporate borrowings and interest. Outstanding unsecured loans and accrued interest payable to Vitasta Software India Private Limited, which is undergoing CIRP, remain unconfirmed by the lender, with reconciliation pending.
Unconfirmed balances and pending approvals. The ₹52.00 crore outstanding from Hallow Securities Private Limited as at March 31, 2026 remains unconfirmed, with no independent balance confirmation received. The transfer of 51% equity shares of Ebix International Holdings Limited to the company is subject to regulatory approvals yet to be obtained. The transfer of shares of IGL Genesis Technologies Limited, executed in dematerialised form in May 2025, remains subject to conditions precedent and approvals from the boards of Indraprastha Gas Limited and IGTL, and has not been given effect in the books.
2. Tailwinds and Growth Prospects
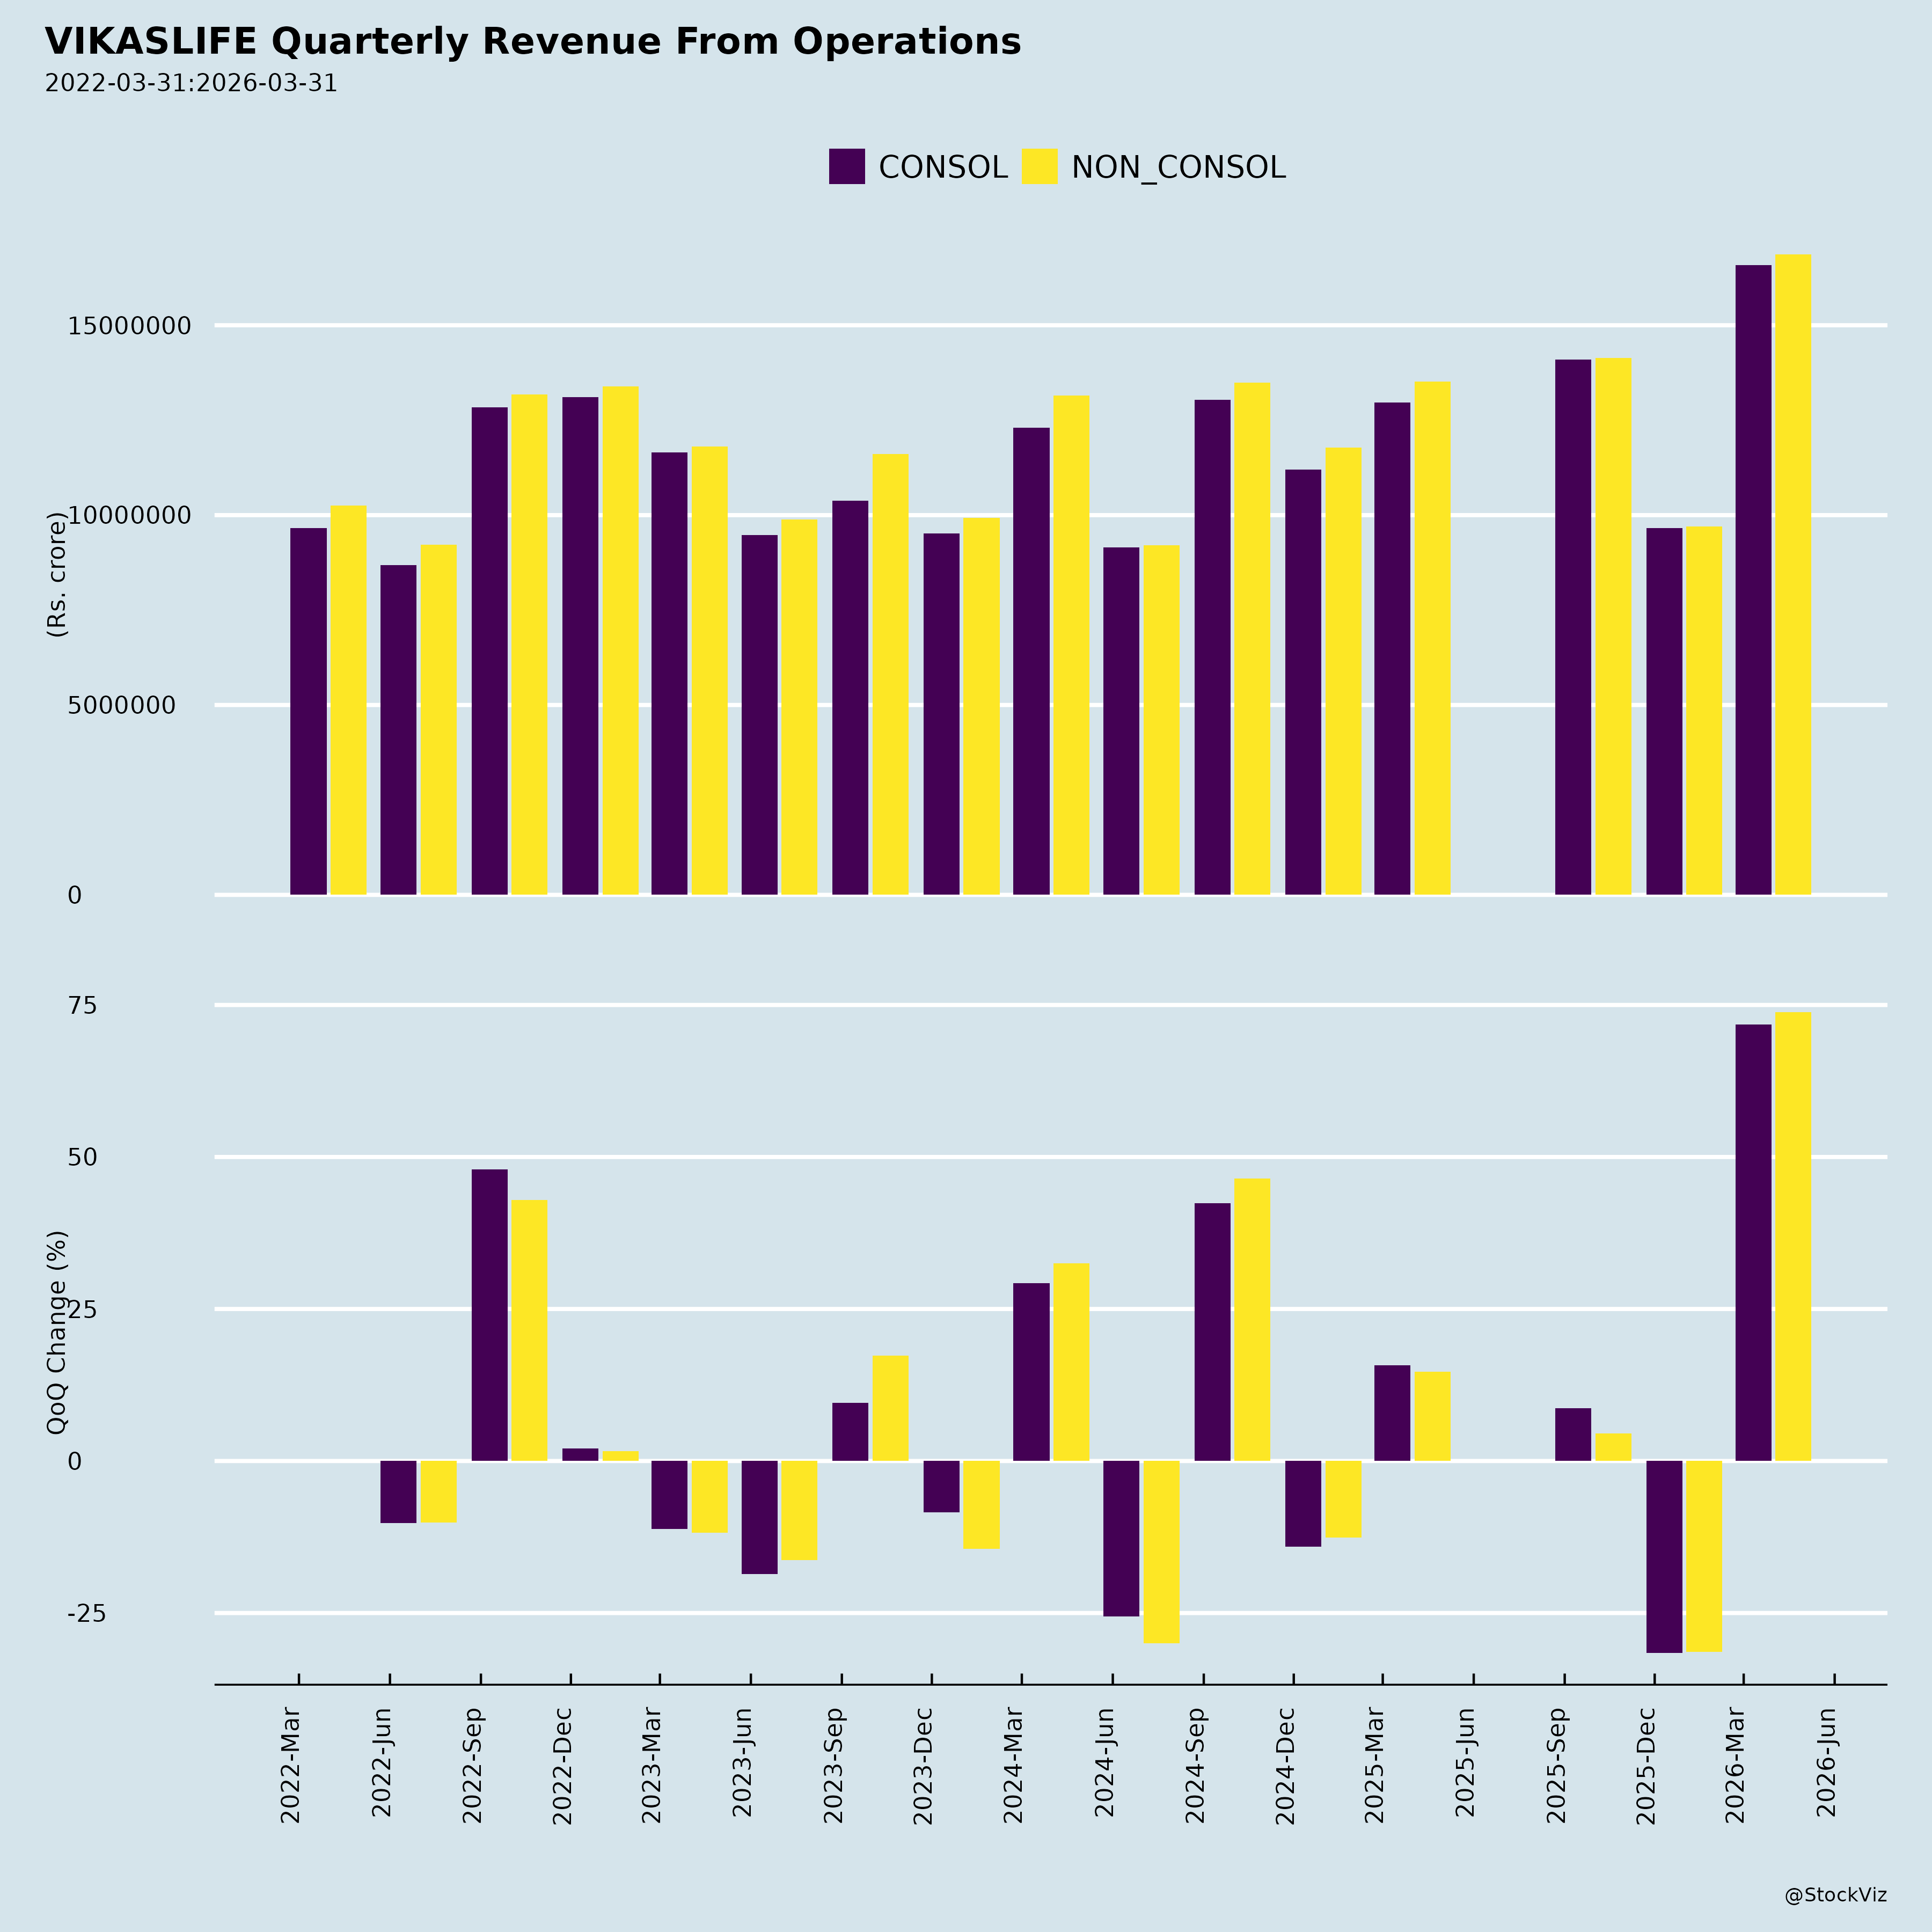
Revenue growth. Standalone revenue from operations rose to ₹49,205.46 lakhs for FY2025-26 from ₹46,357.62 lakhs in FY2024-25. Consolidated revenue from operations rose to ₹49,936.33 lakhs from ₹48,002.24 lakhs. The March 2026 quarter standalone revenue of ₹16,584.72 lakhs was higher than both the December 2025 quarter (₹9,653.77 lakhs) and the March 2025 quarter (₹12,966.91 lakhs).
Return to full-year profitability. Standalone profit before tax for FY2025-26 was ₹7,509.36 lakhs against a loss of ₹(355.24) lakhs in FY2024-25, and net profit was ₹8,617.23 lakhs against a net loss of ₹(225.66) lakhs. Standalone basic and diluted EPS for the year was ₹0.46 versus ₹(0.01). Excluding the re-measurement loss on investments fair valued through FVTPL of ₹(2,546.24) lakhs, standalone profit was ₹10,055.59 lakhs, compared with ₹1,604.51 lakhs on the same basis in the prior year.
Other income contribution. Standalone other income rose to ₹13,350.14 lakhs for FY2025-26 from ₹2,632.65 lakhs, including interest income of ₹13,178.24 lakhs recognised in the cash flow statement.
Segment performance. The Agro division remained the largest segment, with revenue of ₹40,684.31 lakhs and segment results before tax and interest of ₹1,206.26 lakhs. The Polymers division revenue rose to ₹2,726.24 lakhs from ₹1,753.87 lakhs, with segment results improving to ₹137.47 lakhs from ₹32.61 lakhs. Infrastructure division revenue was ₹5,794.92 lakhs with a segment loss of ₹(68.45) lakhs.
Ebix associate contribution. The consolidated results include a share of profit in an associate of ₹6,545.51 lakhs for the quarter ended March 31, 2026 and a share of loss of ₹(6,171.46) lakhs for the period from June 7, 2025 to March 31, 2026 in respect of Ebix International Holdings Limited and its underlying entities, accounted for under the equity method. The company holds 51% equity in EIHL but, based on contractual arrangements and governance structure, treats it as an associate rather than a subsidiary.
Settlement recoveries. A Settlement Agreement dated May 30, 2026 with Hallow Securities Private Limited settled the principal amount of ₹52.00 crores, with an additional lumpsum compensation of ₹3.00 crores agreed to be paid to the company. Part payments were received subsequent to the reporting date, and the financial asset is considered recoverable with no impairment provision recognised. The ₹3.00 crore compensation has not been recognised in FY2025-26 as the right arose after the reporting date.
Balance sheet expansion. Standalone total equity rose to ₹63,067.69 lakhs as at March 31, 2026 from ₹54,496.64 lakhs. Non-current investments increased to ₹46,470.67 lakhs from ₹4,840.65 lakhs. Deferred tax assets (net) rose to ₹1,464.74 lakhs from ₹344.89 lakhs. Cash flow from operating activities was ₹28,344.60 lakhs for FY2025-26 against negative ₹(21,308.64) lakhs in the prior year.
3. Key Risks
- Audit qualification risk: The qualified opinion and the auditors’ inability to determine the impact of unverified investments, deposits and related party transactions create uncertainty over the reliability of reported figures.
- Regulatory non-compliance risk: Pending shareholder approvals for material related party transactions, Section 186(8) non-compliance, and pending FEMA/ODI compliances (including Form ODI Part II and Annual Performance Reports, with potential Late Submission Fees or compounding) expose the company to regulatory action.
- Enforcement and investigation risk: The ED provisional attachment of properties valued at approximately ₹1,333.84 lakhs and the ongoing SEBI investigation have outcomes that cannot presently be determined.
- Tax risk: Income tax demands of ₹26.44 crores are under appeal or rectification; the company has made no adjustment, believing it has adequate grounds to challenge them. The tax treatment of the Ebix transaction relies on an independent expert opinion that no liability arises, with no provision recognised.
- Recoverability risk: The ₹52.00 crore HSPL balance was unconfirmed at the reporting date; the ₹5.00 crore Abhhyam advance was impaired and is subject to litigation; the IGTL share transfer remains incomplete with conditions precedent outstanding.
- Liquidity and default risk: Existing defaults in repayment of loan and interest on certain borrowings, delays in statutory dues, demand notices on inter-corporate borrowings, and an unconfirmed balance with a lender in CIRP.
- Cross-border compliance risk: The Ebix transaction spans jurisdictions, with regulatory approvals and ODI compliances still to be completed.
- Dependence on associate income: Consolidated profitability in the March 2026 quarter was driven by the share of profit in the Ebix associate, while the pre-associate result was a loss.
4. Management Guidance Versus Observed Business Performance
Statutory dues. Management states it is in the process of regularising outstanding statutory dues and believes the delays are temporary, while continuing normal business and investment activities, including investments in shares and granting of inter-corporate loans. Observed: the auditors note that substantial statutory dues remained outstanding while such investments and deposits continued, and they were not provided sufficient evidence on the business rationale.
Related party approvals. Management represents that it is in the process of obtaining the requisite approvals for material related party transactions. Observed: approvals had not been obtained up to the date of approval of the financial results.
Ebix compliance. Management states it is undertaking a comprehensive review of compliance requirements across jurisdictions and coordinating with legal and regulatory advisors to regularise compliances. Observed: requisite approvals, including regulatory approvals, were yet to be obtained, and FEMA/ODI compliances, including prescribed forms and returns, were yet to be completed.
HSPL recoverability. Management assessed the ₹52.00 crore financial asset as recoverable based on the Settlement Agreement dated May 30, 2026, receipt of part payments, and its recoverability assessment, recognising no impairment. Observed: the balance remained unconfirmed by HSPL as at March 31, 2026, and the ₹3.00 crore compensation was not recognised in FY2025-26.
IGTL transfer. Management states that necessary steps are being undertaken to obtain required approvals and that stakeholders will be informed upon receipt. Observed: conditions precedent remained pending and the transfer had not been given effect in the books.
Income tax demands. Management believes it has adequate grounds to challenge the ₹26.44 crore demands and does not expect a material adverse impact, making no adjustment. Observed: appeals and rectification applications are in process, with the outcome not yet determined.
ED attachment. Management believes it has adequate grounds to challenge the attachment and is pursuing legal remedies. Observed: the matter is under adjudication/investigation and the ultimate outcome and impact cannot presently be determined.
Abhhyam advance. Management recognised an impairment loss on the ₹5.00 crore advance based on recoverability assessment, while stating this does not constitute a waiver of legal rights and that recovery will be recognised when received. Observed: legal proceedings are ongoing and the outcome is uncertain.
Discontinued subsidiary. Management completed the disposal of Shashi Beriwal and Co Private Limited based on an independent registered valuer’s report under Rule 11UA using the Net Asset Value method. Observed: the sale consideration of ₹4.15 crores against a carrying amount of ₹11.21 crores resulted in a recognised loss of ₹7.06 crores.
Property sale. Management obtained a valuation report and architect’s certificate indicating no material deviation between the agreed consideration and estimated realisable value, believing the transaction was at fair value. Observed: the ₹3.00 crore consideration against a carrying amount of ₹5.38 crores (land ₹4.36 crores plus building ₹1.02 crores) resulted in a recognised loss of ₹2.56 crores.
Copyright © 2023 SAS Data Analytics Pvt. Ltd. All rights reserved.