URBANCO
Equity Metrics
November 18, 2026
Urban Company Limited
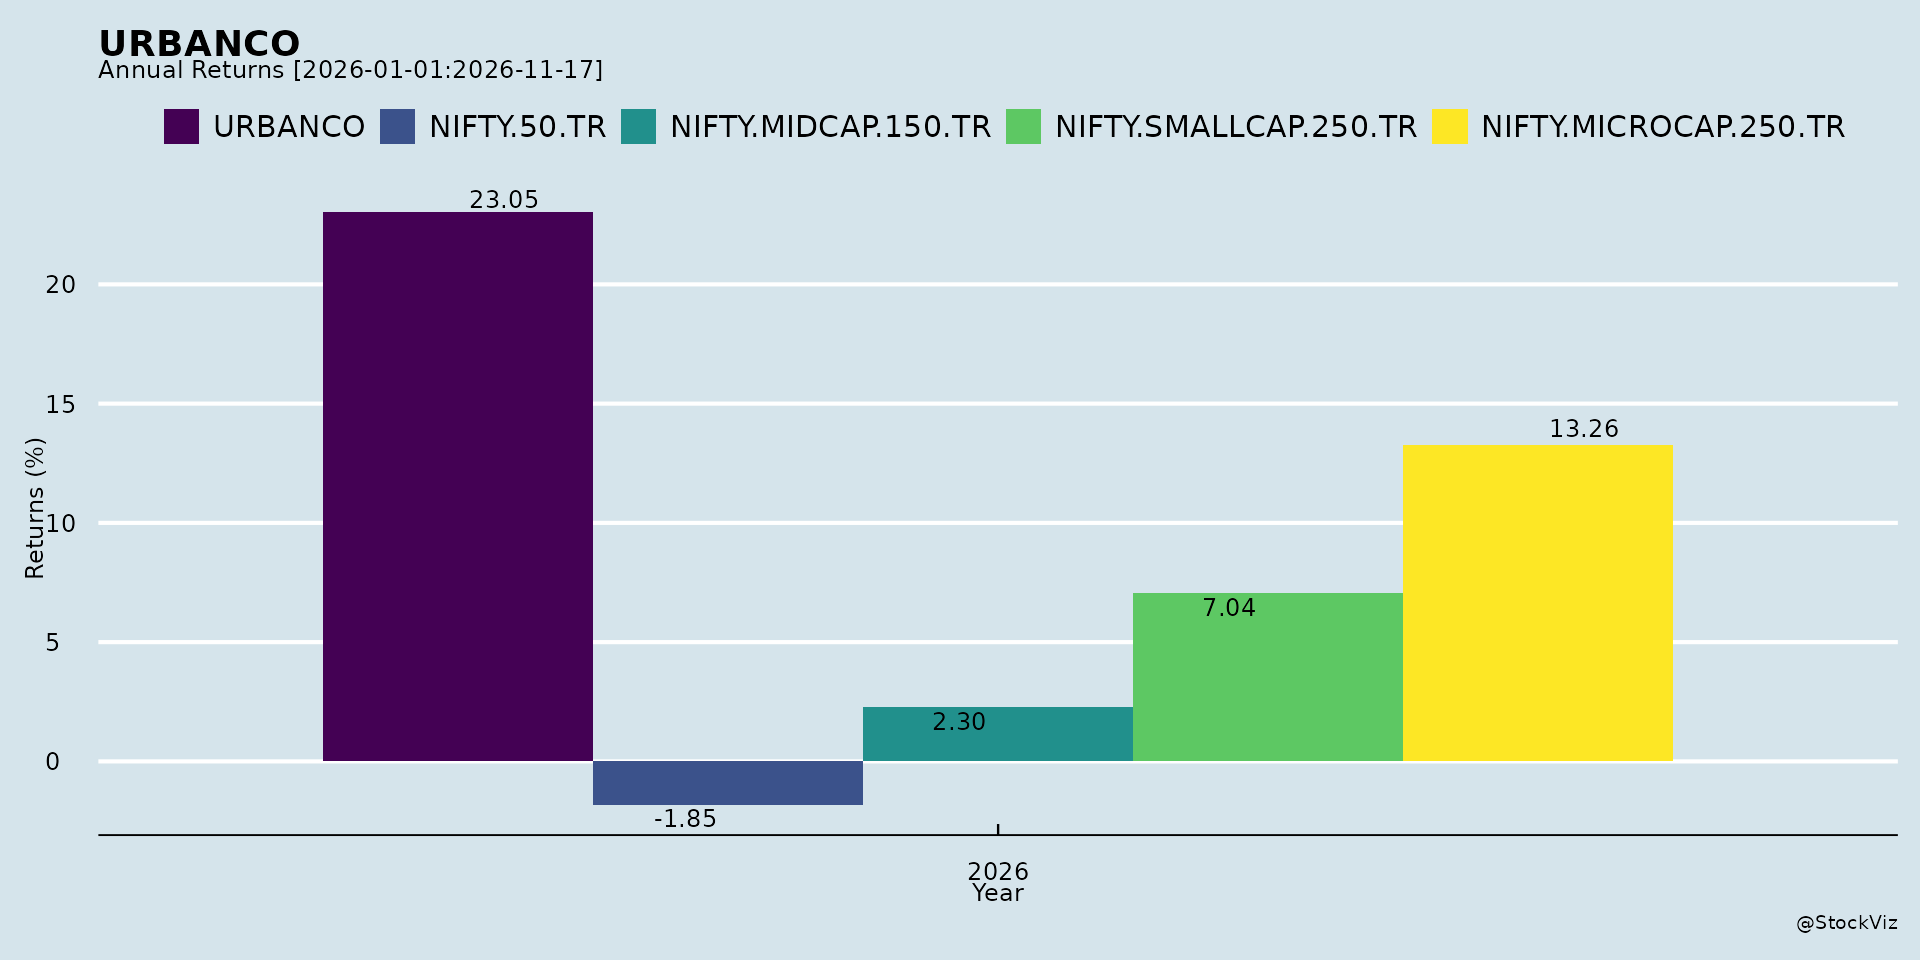
Annual Returns

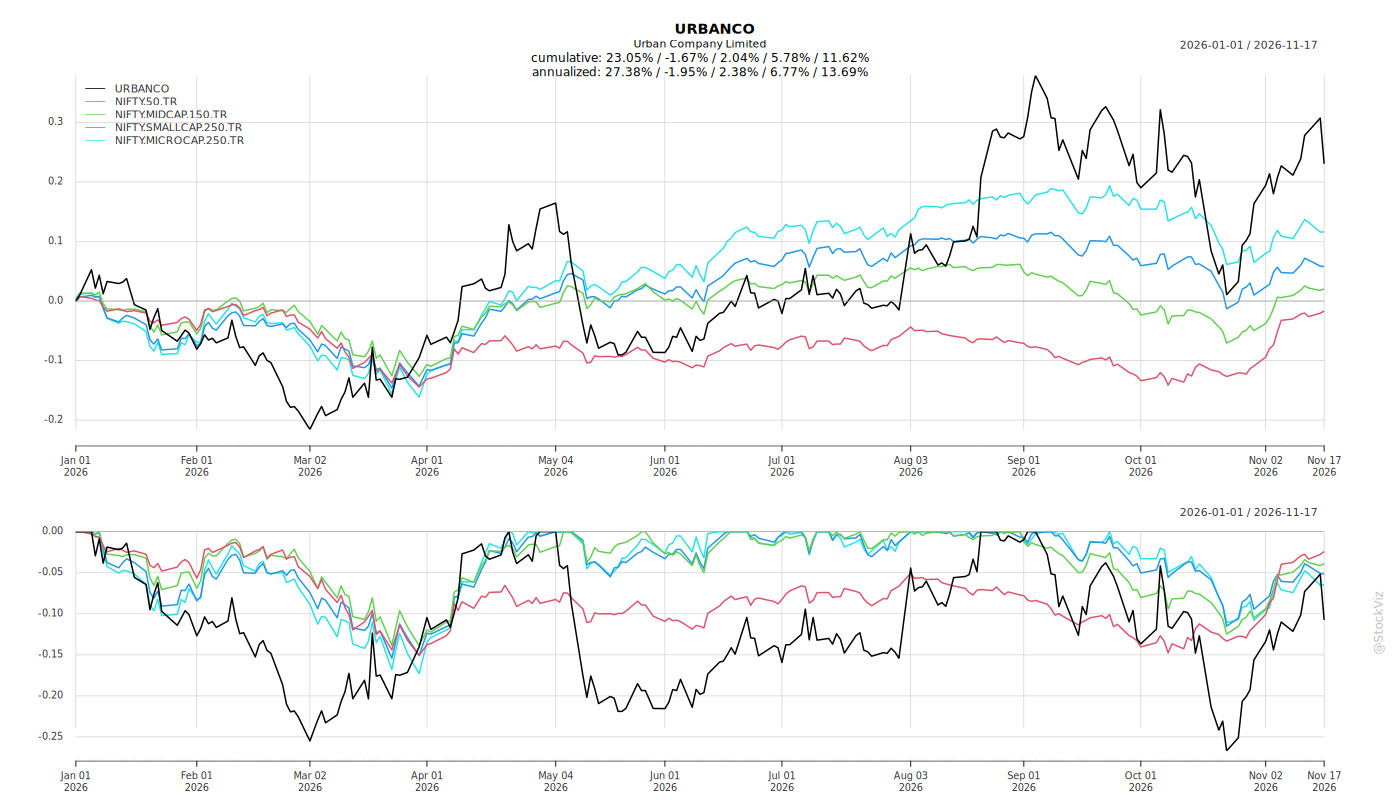
Cumulative Returns and Drawdowns
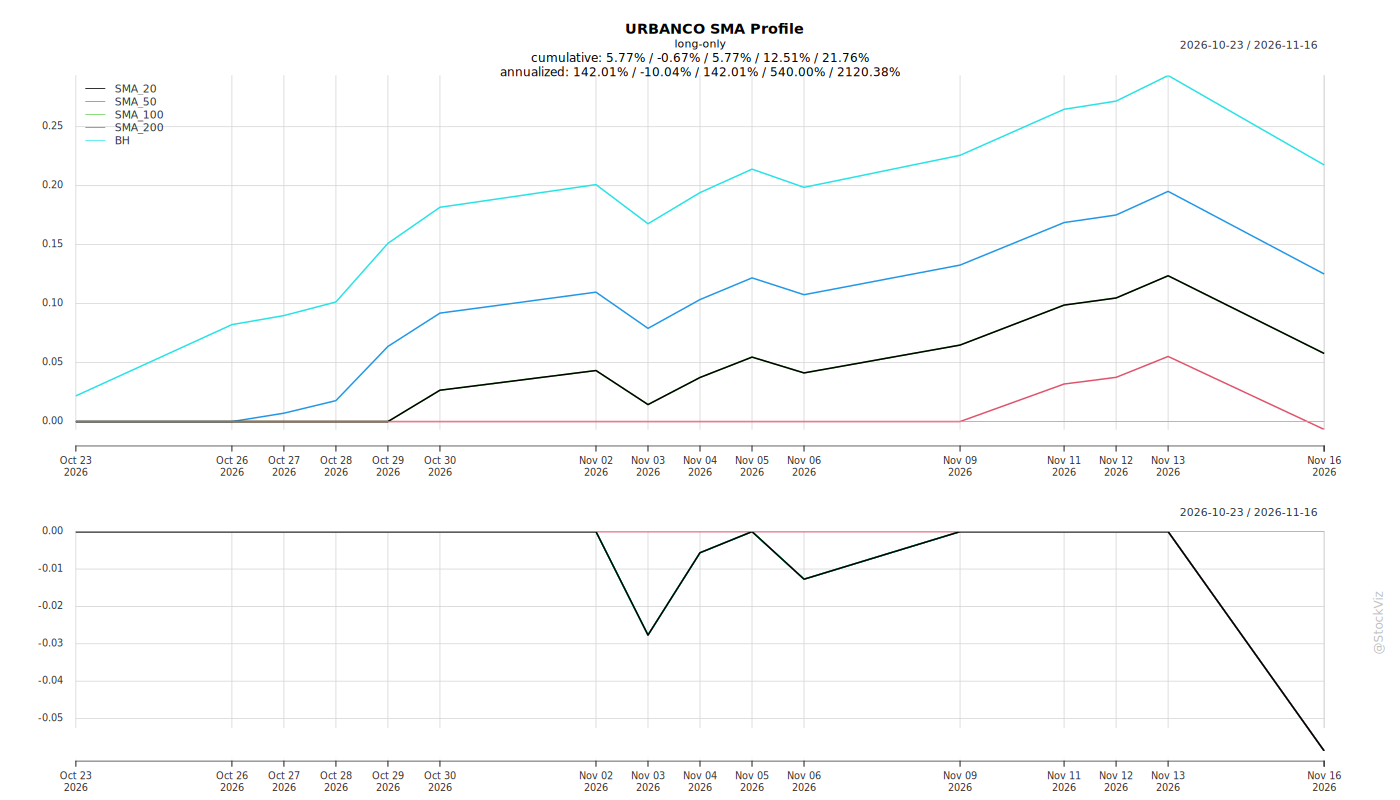
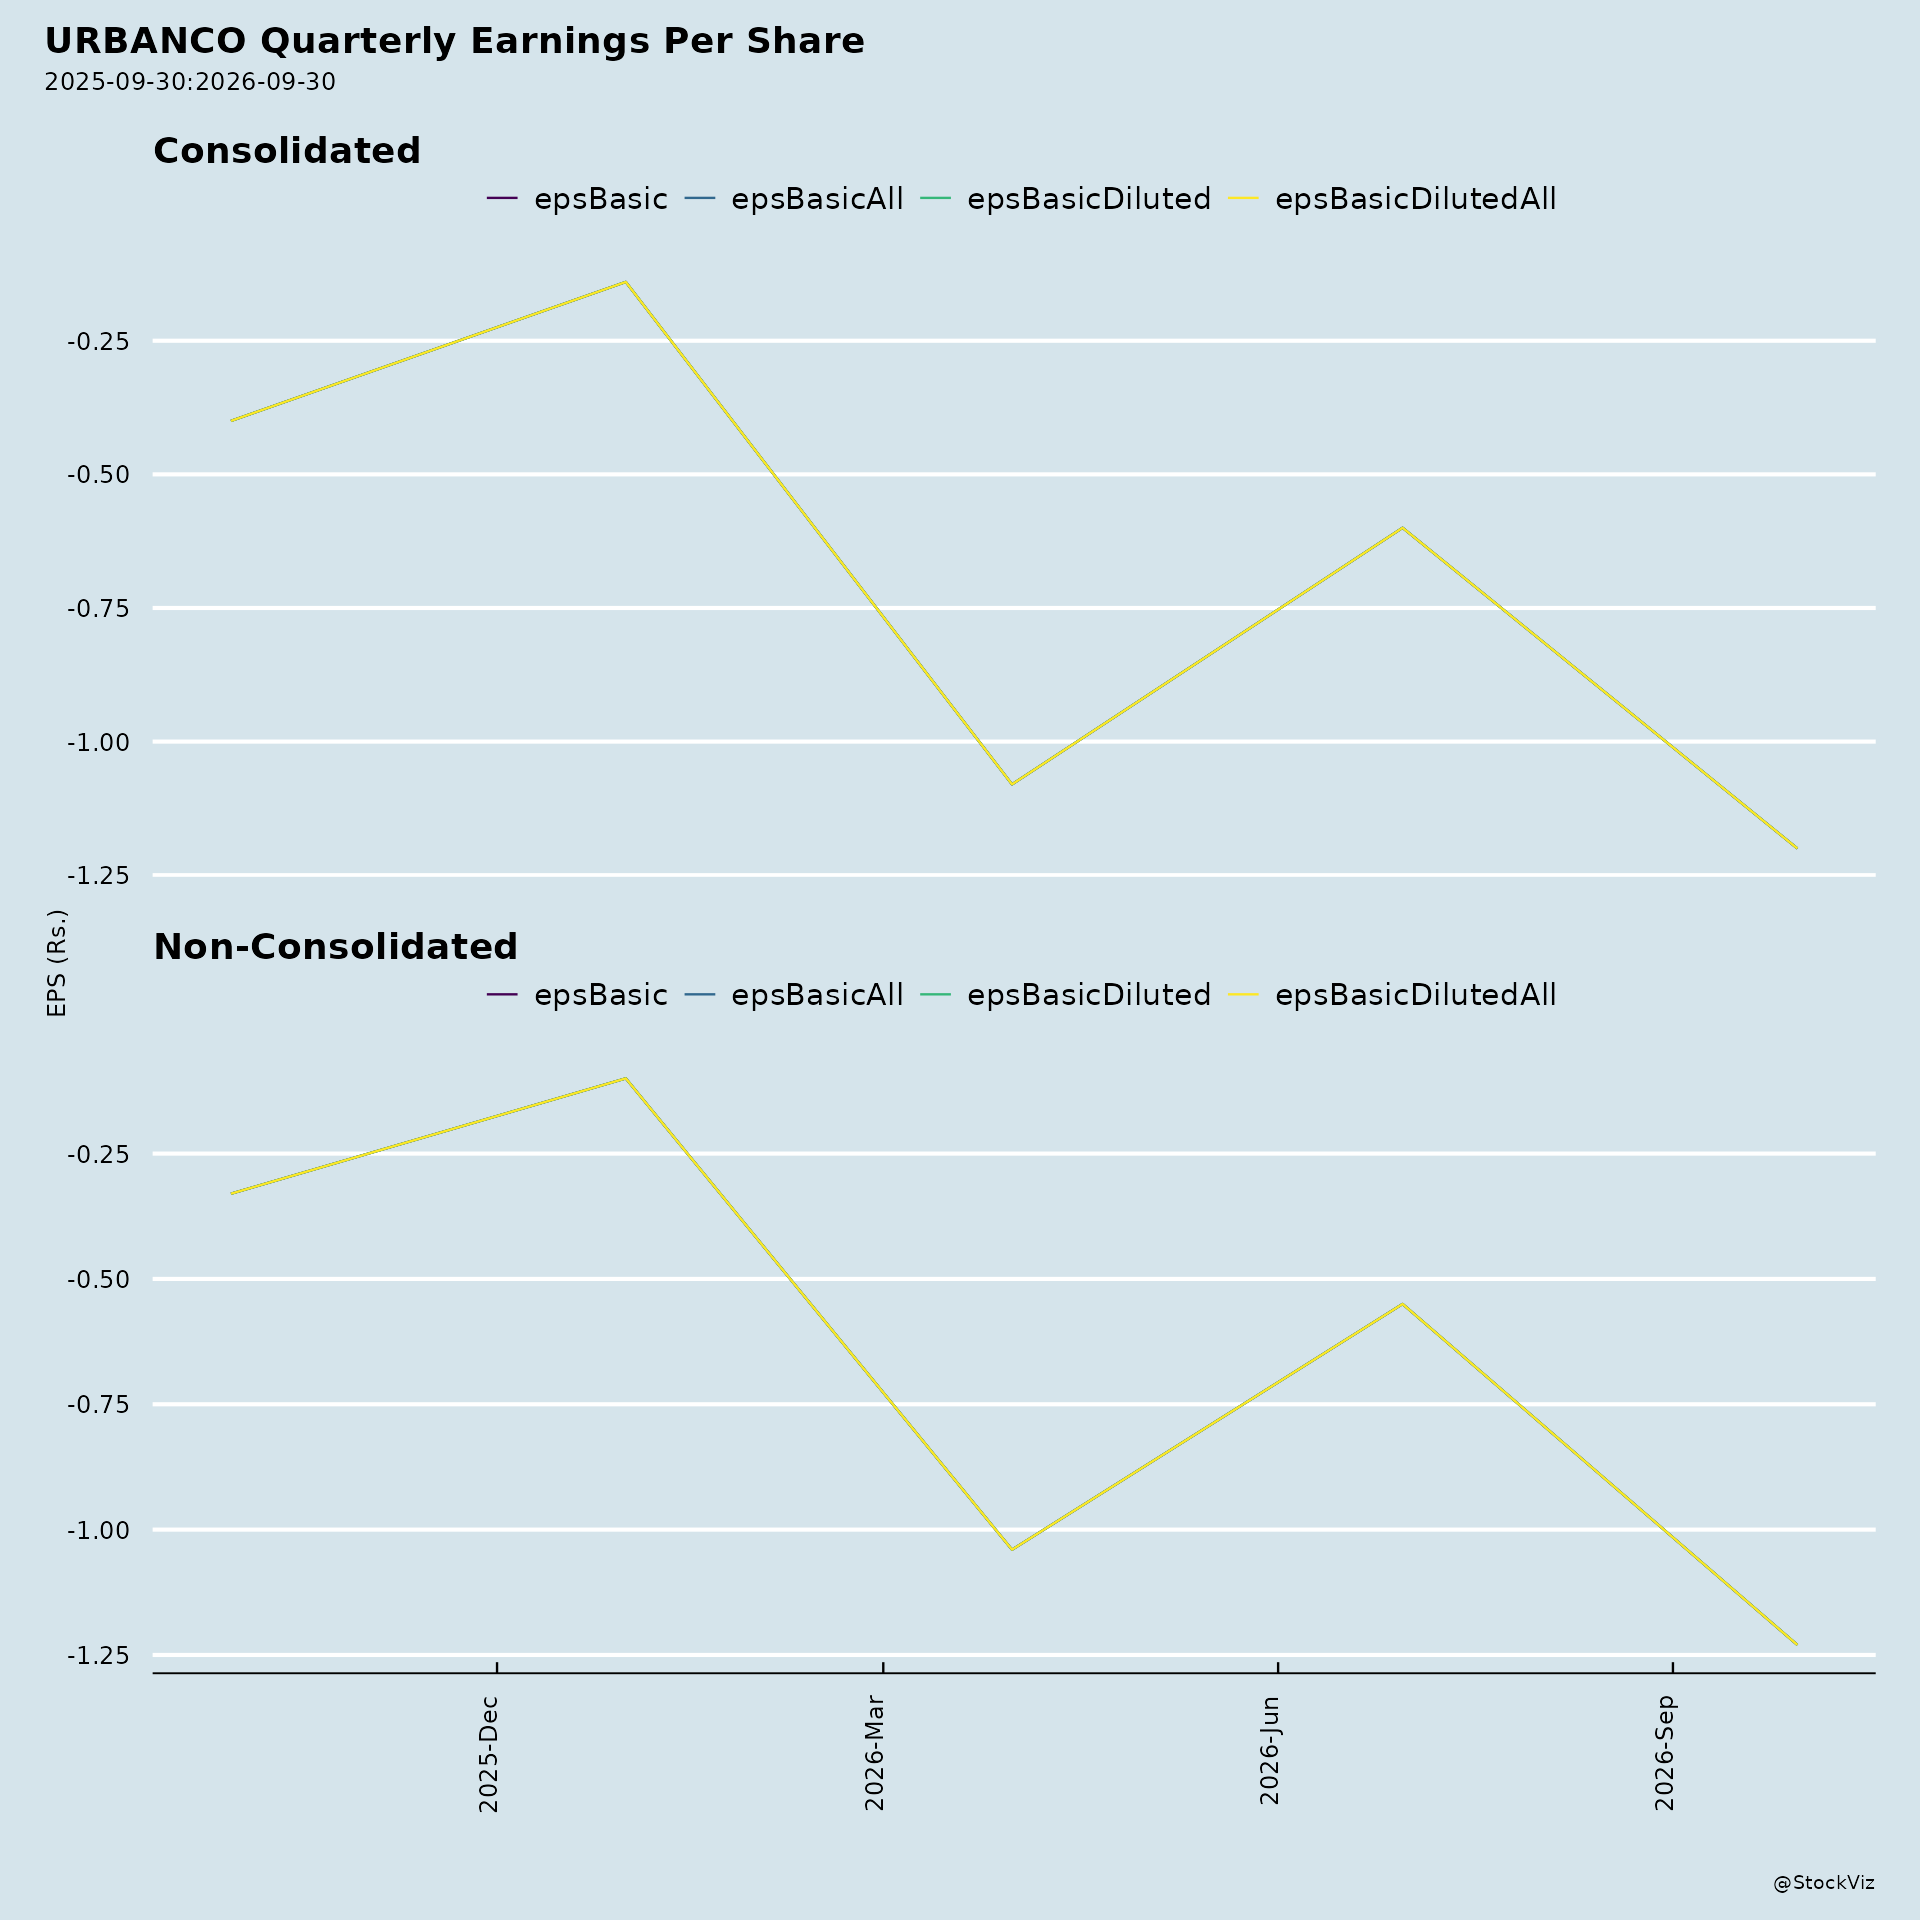
Fundamentals
Ownership
Margined
AI Summary
asof: 2026-09-16
URBANCO: Recent Corporate Announcements — Summary
1. Headwinds and Challenges
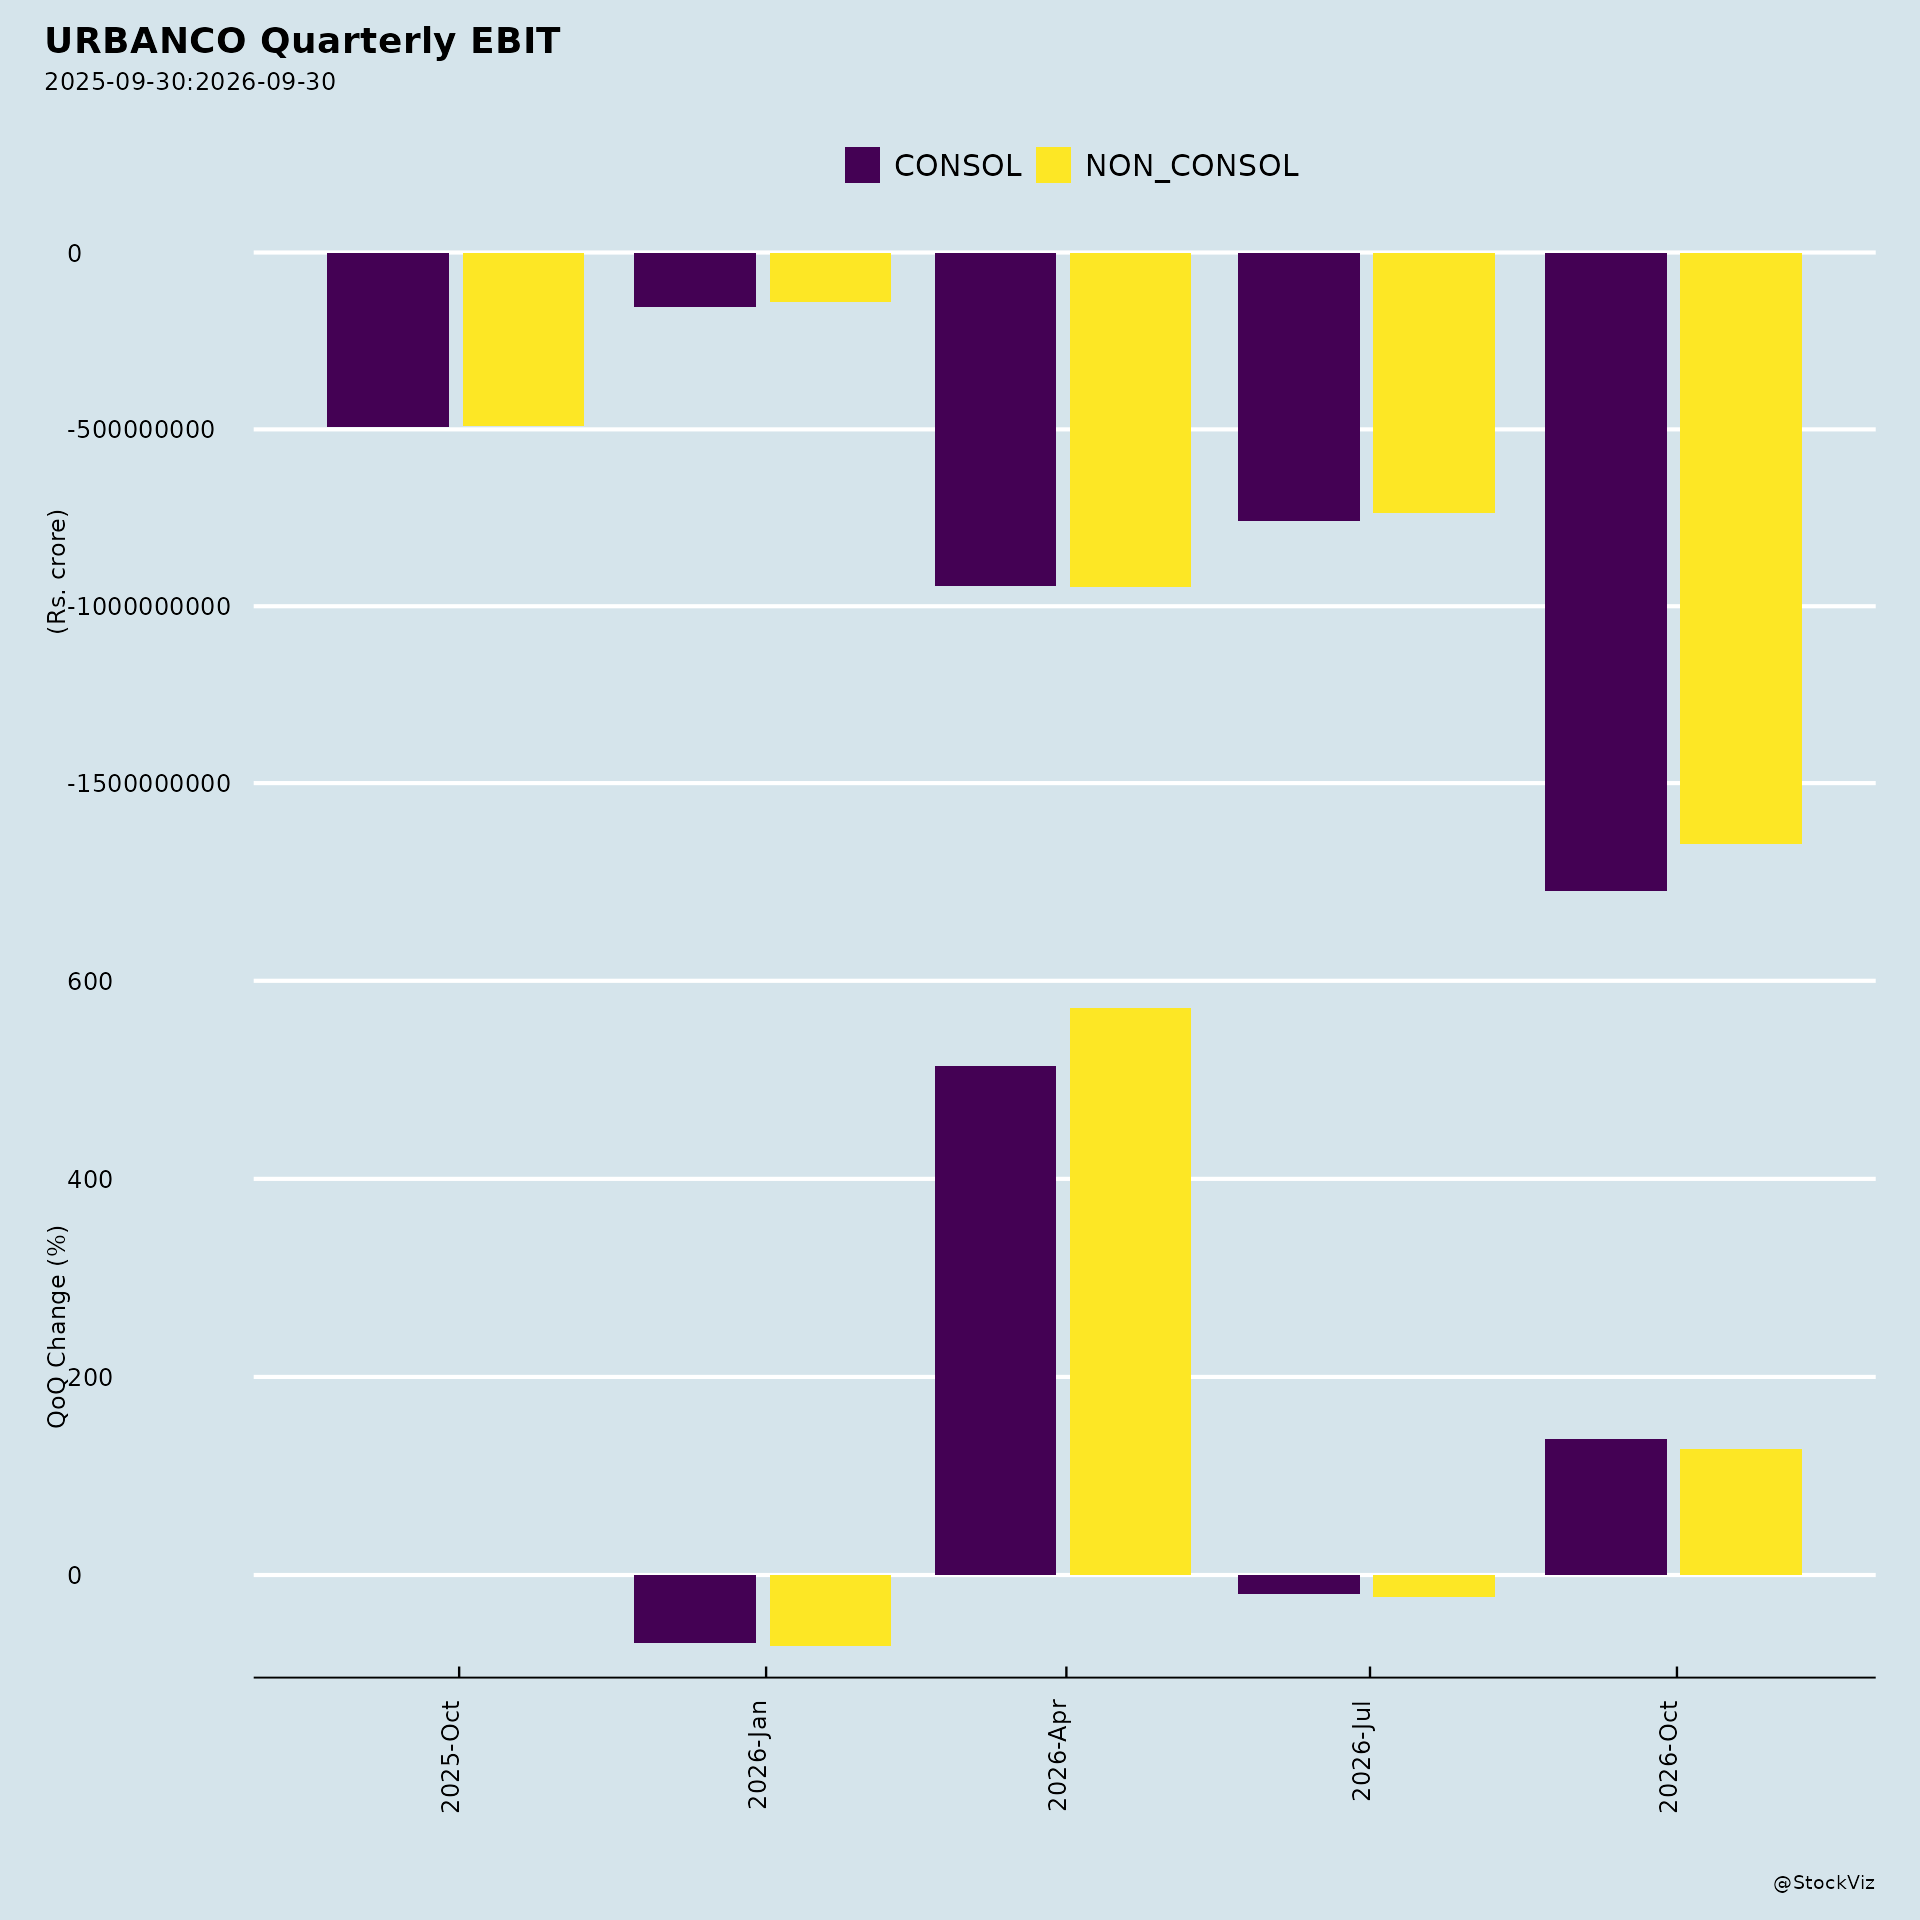
Losses at the consolidated level. For the quarter ended June 30, 2026, URBANCO reported a consolidated loss before tax of ₹83.75 crore, compared with a profit before tax of ₹5.64 crore in the quarter ended June 30, 2025. Loss after tax for the June 2026 quarter was ₹92.12 crore, versus a profit of ₹6.94 crore a year earlier. For the full year ended March 31, 2026, the consolidated loss after tax was ₹234.81 crore.
InstaHelp is the dominant drag. The InstaHelp segment recorded a segment loss of ₹131.58 crore in the June 2026 quarter, compared with a loss of ₹9.24 crore in the June 2025 quarter and ₹118.73 crore in the March 2026 quarter. For FY26, the InstaHelp segment loss was ₹231.79 crore. InstaHelp revenue was ₹11.22 crore in the June 2026 quarter.
Native remains loss-making at the segment level. The Native segment reported a loss of ₹7.75 crore in the June 2026 quarter, compared with losses of ₹8.06 crore in the March 2026 quarter and ₹10.87 crore in the June 2025 quarter. For FY26, the Native segment loss was ₹33.35 crore.
Rising cost base. Consolidated employee benefits expense rose to ₹151.15 crore in the June 2026 quarter from ₹99.22 crore a year earlier. Other expenses rose to ₹369.85 crore from ₹193.28 crore. Share-based payment expense increased to ₹38.49 crore from ₹23.04 crore. Depreciation and amortisation rose to ₹15.79 crore from ₹9.50 crore.
Prior-year comparatives not reviewed. The financial results note that the figures for the quarter ended June 30, 2025 were neither subject to limited review nor audit, and the auditor’s report draws attention to this. The March 31, 2026 quarter figures are balancing figures between audited full-year figures and previously reviewed year-to-date figures.
Exceptional item. The closure of the step-down subsidiary Urban Company Arabia for Information Technology, formally dissolved on May 24, 2026, led to reclassification of an accumulated Foreign Currency Translation Reserve of ₹5.27 crore from Other Comprehensive Income to the Consolidated Statement of Profit and Loss as an exceptional item in the June 2026 quarter.
Dissent at the AGM. At the 12th AGM held June 30, 2026, all five resolutions passed with requisite majority. Resolution 2 (re-appointment of Mr. Abhiraj Singh Bhal as Director liable to retire by rotation) received 99.8915% votes in favour and 0.1085% against. Resolution 5 (contribution to bona fide, charitable and other funds) received 99.785% in favour and 0.215% against.
2. Tailwinds and Growth Prospects
Native product expansion. On August 5, 2026, URBANCO announced the launch of the Native M3 and M3 Pro water purifiers, priced at ₹22,000 onwards, available on the Urban Company app and website. The M3 Pro features filters designed to last up to three years, an unconditional three-year warranty, 100% RO purification, a food-grade stainless-steel storage tank, app-enabled monitoring of filter health and water quality, advanced mineralisation and pH balancing, and a dot-matrix smart display. The company states customers can save over ₹26,000 over nine years through long-life filters and reduced maintenance.
Native growth. In FY26, Native recorded ₹267 crore in revenue from operations, representing 130% year-on-year growth, while Net Transaction Value grew 122% year-on-year to ₹345 crore. Native maintains an average 4.5-star customer rating across platforms and a 75% customer renewal rate. In the June 2026 quarter, Native revenue from external customers was ₹95.28 crore, up from ₹59.55 crore in the June 2025 quarter and ₹70.22 crore in the March 2026 quarter.
India consumer services (excluding InstaHelp) profitability. This segment reported a segment result of ₹82.02 crore in the June 2026 quarter, up from ₹40.30 crore in the June 2025 quarter and ₹35.64 crore in the March 2026 quarter. FY26 segment result was ₹138.22 crore. Revenue from external customers in this segment was ₹356.42 crore in the June 2026 quarter, versus ₹271.61 crore a year earlier.
International business turned profitable at segment level. The international business segment reported a segment result of ₹3.16 crore in the June 2026 quarter, compared with a loss of ₹1.95 crore in the June 2025 quarter. FY26 segment result was ₹7.56 crore. Revenue from external customers was ₹65.42 crore in the June 2026 quarter, up from ₹35.89 crore a year earlier.
InstaHelp revenue scaling. InstaHelp revenue from external customers was ₹11.22 crore in the June 2026 quarter, compared with ₹0.22 crore in the June 2025 quarter and ₹8.94 crore in the March 2026 quarter. FY26 revenue was ₹17.38 crore.
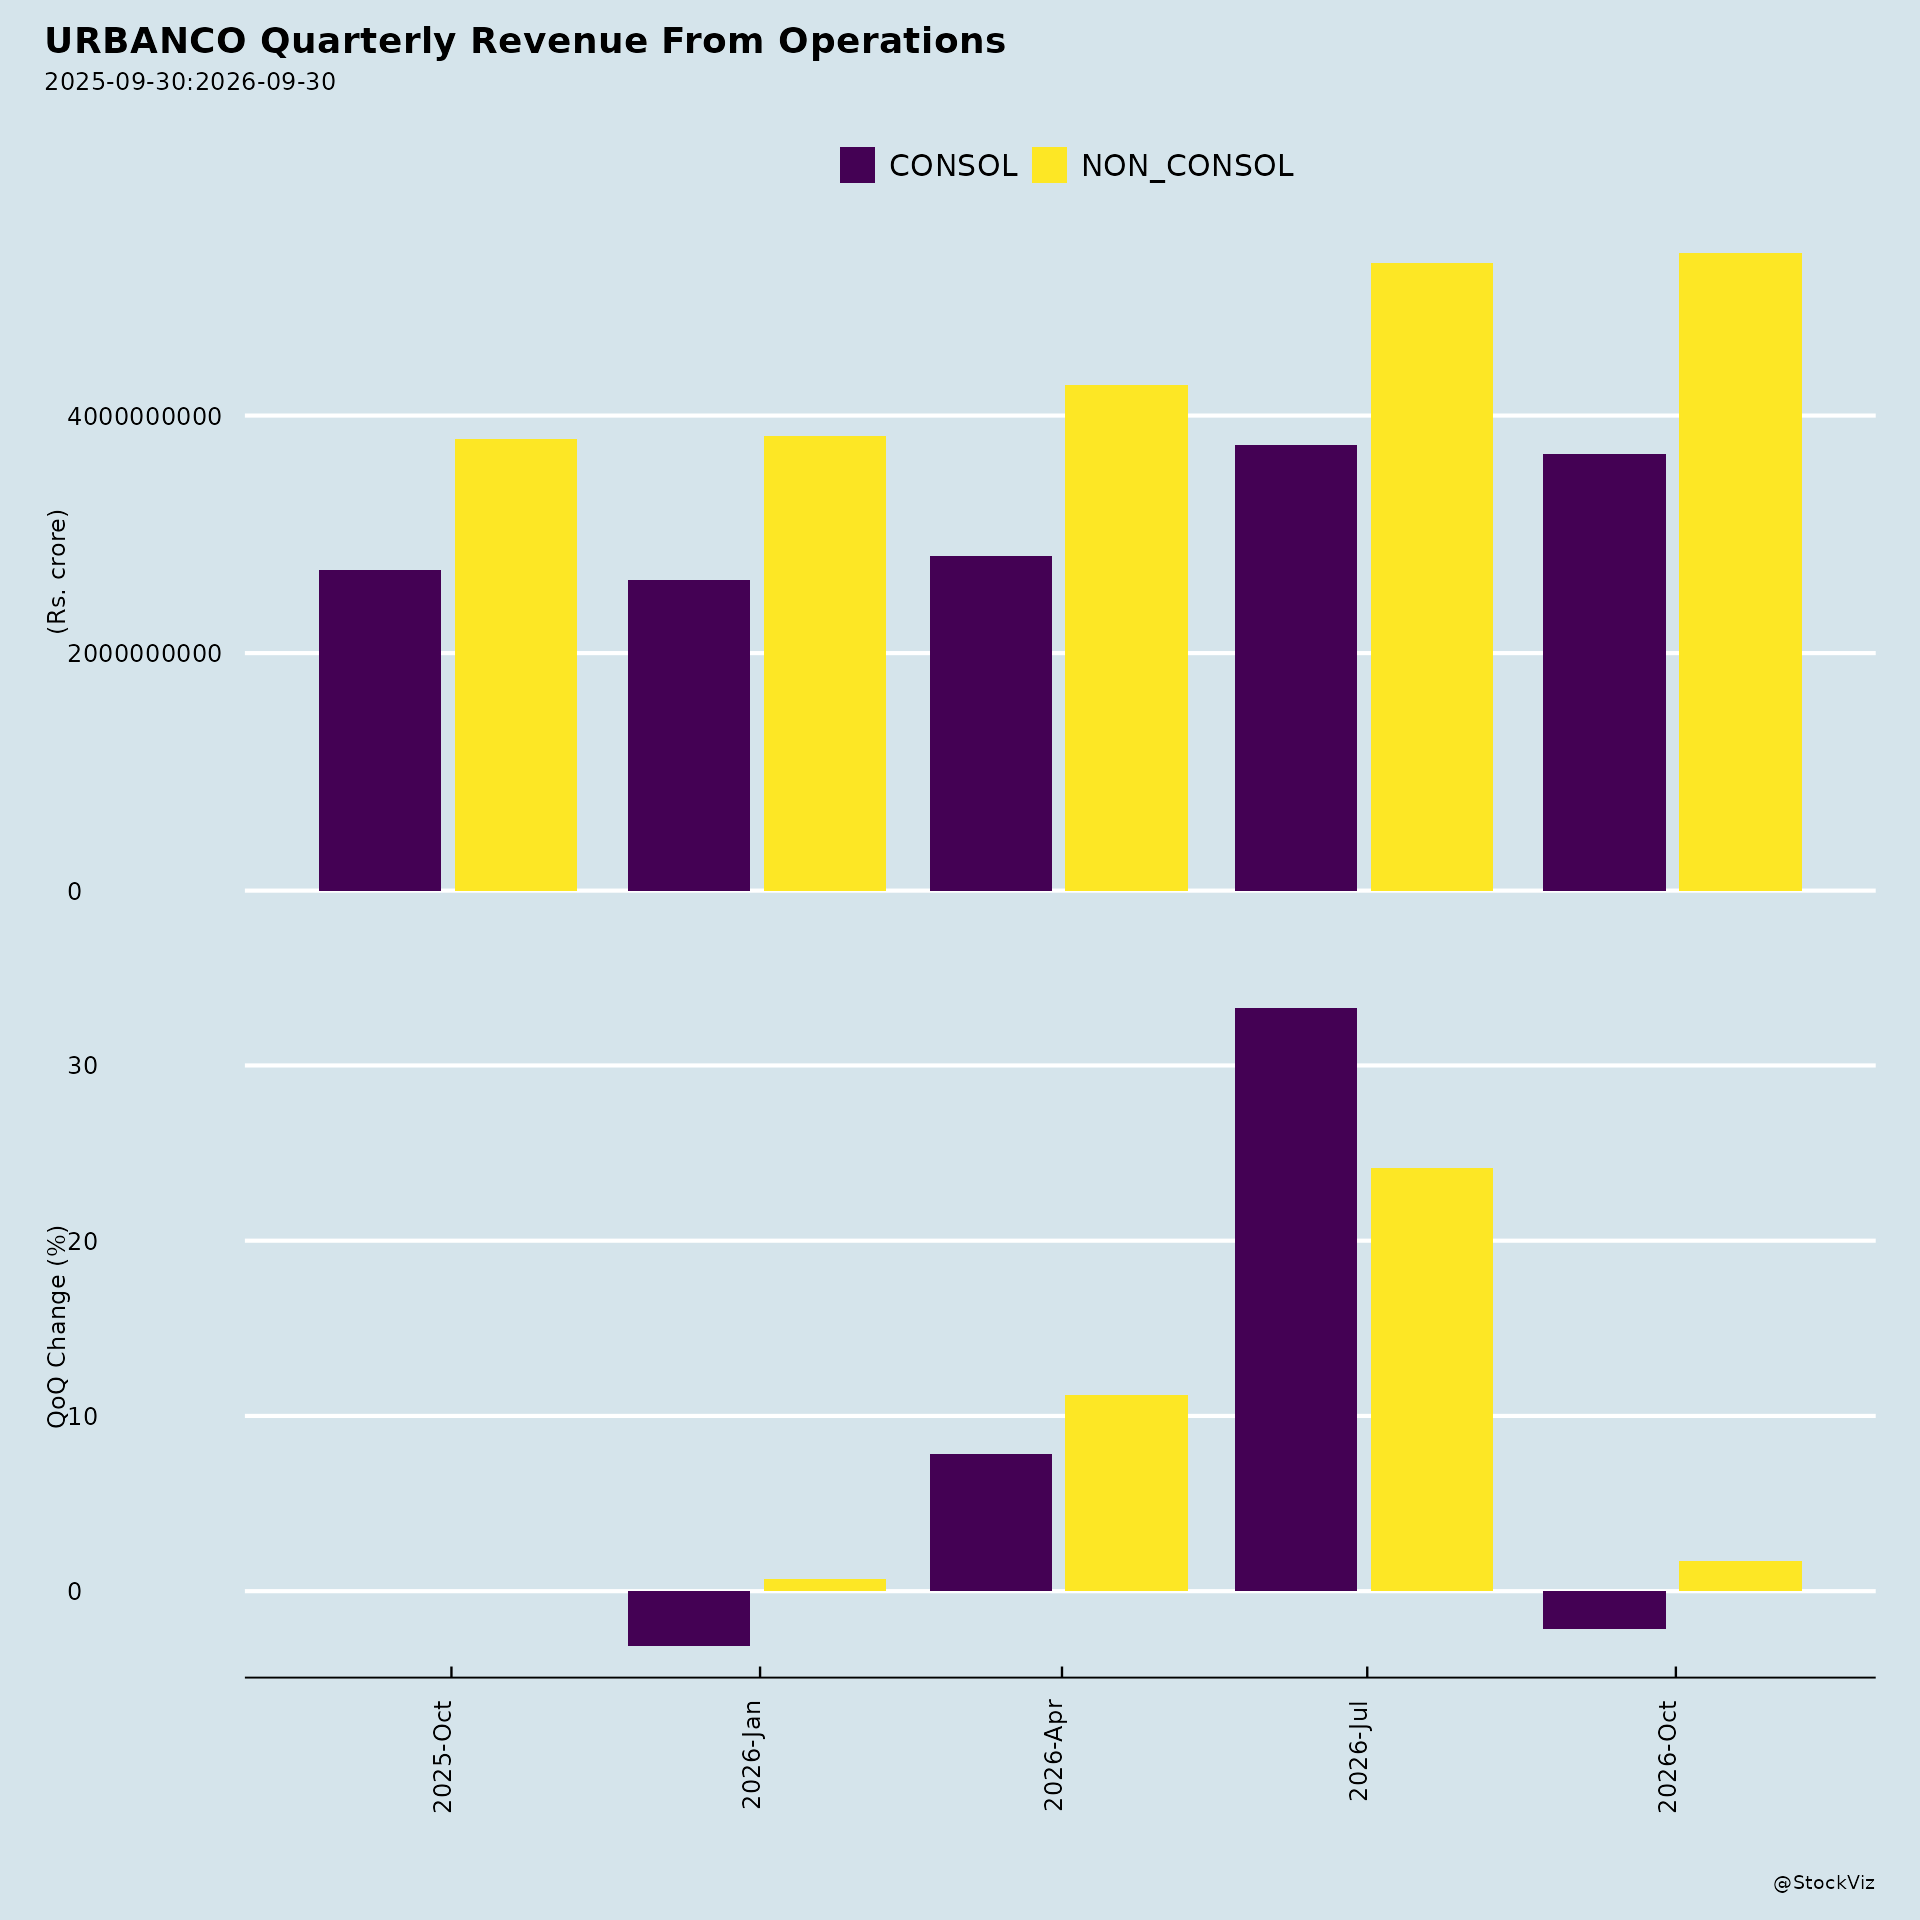
Overall revenue growth. Consolidated revenue from operations was ₹528.34 crore in the June 2026 quarter, up from ₹367.27 crore in the June 2025 quarter and ₹425.56 crore in the March 2026 quarter. FY26 revenue from operations was ₹1,555.54 crore.
Service professional earnings and benefits. Per the 9M FY26 Earnings Index cited in the August 5, 2026 release, average monthly net earnings in-hand reached INR 28,322 for all active service professionals (excluding InstaHelp), while the top 5% earned INR 51,673. All active service professionals are covered under group life and accidental insurance, including life insurance cover of up to INR 10 lacs, disability cover of up to INR 6 lacs, and accidental hospitalisation and OPD treatment coverage.
3. Key Risks
Continued losses and cash burn. The consolidated loss after tax for the June 2026 quarter was ₹92.12 crore, and the FY26 loss after tax was ₹234.81 crore. Total comprehensive loss for the June 2026 quarter was ₹86.88 crore.
InstaHelp concentration of losses. The InstaHelp segment loss of ₹131.58 crore in the June 2026 quarter exceeded the consolidated segment loss of ₹54.15 crore, indicating that other segments’ profits are offsetting InstaHelp losses. Continued InstaHelp losses could pressure overall profitability.
Native segment profitability. Despite strong revenue growth, the Native segment remains loss-making at the segment level, with a loss of ₹7.75 crore in the June 2026 quarter and ₹33.35 crore in FY26.
Dependence on long-life filtration claims. The M3 Pro’s value proposition rests on filters designed to last three years and an unconditional three-year warranty. Any deviation from these performance claims could affect customer renewal rates and after-sales costs.
Foreign subsidiary dissolution. The dissolution of Urban Company Arabia for Information Technology on May 24, 2026 resulted in a ₹5.27 crore exceptional charge. The group’s international structure includes multiple step-down subsidiaries across the UAE, Saudi Arabia, and other jurisdictions.
Tax expense volatility. Deferred tax expense was ₹8.37 crore in the June 2026 quarter, compared with a deferred tax credit of ₹1.30 crore in the June 2025 quarter. FY26 deferred tax expense was ₹60.21 crore.
Share-based payment expense. Share-based payment expense rose to ₹38.49 crore in the June 2026 quarter from ₹23.04 crore a year earlier, and was ₹103.55 crore for FY26.
4. Management Guidance Versus Observed Business Performance
Native growth trajectory. The August 5, 2026 release states that the launch of the M3 series comes as the Native business “continues to witness strong growth,” citing FY26 revenue from operations of ₹267 crore (130% year-on-year growth) and NTV growth of 122% year-on-year to ₹345 crore. Observed performance: Native revenue from external customers was ₹95.28 crore in the June 2026 quarter, up from ₹59.55 crore in the June 2025 quarter, consistent with the stated growth trajectory. However, the Native segment remained loss-making at ₹7.75 crore in the June 2026 quarter.
Customer trust metrics. The release cites an average 4.5-star customer rating across platforms and a 75% customer renewal rate for Native. These metrics are presented as reflecting strong customer trust in Native’s lifecycle service model.
InstaHelp performance versus segment losses. InstaHelp revenue grew from ₹0.22 crore in the June 2025 quarter to ₹11.22 crore in the June 2026 quarter, but segment losses widened from ₹9.24 crore to ₹131.58 crore over the same period. The June 2026 quarter InstaHelp loss of ₹131.58 crore compares with ₹118.73 crore in the March 2026 quarter.
India consumer services profitability. The segment result for India consumer services (excluding InstaHelp) improved to ₹82.02 crore in the June 2026 quarter from ₹40.30 crore in the June 2025 quarter, with FY26 segment result at ₹138.22 crore.
International business. The international business segment turned profitable at the segment level in the June 2026 quarter (₹3.16 crore) compared with a loss in the June 2025 quarter (₹1.95 crore), and FY26 segment result was ₹7.56 crore.
Overall profitability. Despite revenue growth from ₹367.27 crore in the June 2025 quarter to ₹528.34 crore in the June 2026 quarter, the consolidated segment result swung from a profit of ₹18.24 crore to a loss of ₹54.15 crore, and loss before tax was ₹83.75 crore in the June 2026 quarter.
Broker Narrative
The narrative shifted from Neutral caution in March 2026 to a Buy conviction by October 2026, as brokers moved from questioning habit formation and online penetration to emphasizing hyperlocal network effects, Tier 2 and international momentum, and a funded path to breakeven. Persistent themes included intense InstaHelp competition, cash burn, delayed profitability, and unit-economics monitoring. New concerns emerged around gig-worker supply costs, diminishing currency tailwinds, and Rs25bn fund-raise dilution, while the bull case increasingly rested on Native adjacencies and KSA JV scalability.
Fears that came true
- The early warning that instant-services competition would raise discounts and acquisition costs materialized as InstaHelp price wars prolonging cash burn, which coincided with the negative August 2026 return (-3.7%) and October 2026 negative prints (-3.4%).
- The concern that InstaHelp would sustain cash burn and near-term EBITDA losses materialized as delayed profitability and pricing/unit economics remaining key monitorables around the October 2026 DISAPPOINTMENT (-3.4% actual).
- The risk of supply churn and partner cost pressure materialized as gig-worker availability shortages and rising partner acquisition/payout costs that constrained fulfillment and pressured unit economics during the late-2026 negative returns.
Optimism that failed
- The optimism that InstaHelp would provide low-risk optionality failed, as it instead became a heavy upfront investment driving sustained cash burn and delayed profitability.
- The expectation that paying service professionals 30-40% more than offline peers would ensure supply stability failed, as the last report flags seasonal labor shortages and rising partner payout costs pressuring availability and unit economics.
Broker Timeline
6 broker calls · 2026-03-01 to 2026-10-18
CNBC-TV18: ratings, targets and commentary
No recorded CNBC-TV18 statements for this ticker.
Management comments
No recorded management comments with an explicit designation and affiliation for this ticker.
Copyright © 2023 SAS Data Analytics Pvt. Ltd. All rights reserved.