UPL
Equity Metrics
November 18, 2026
UPL Limited
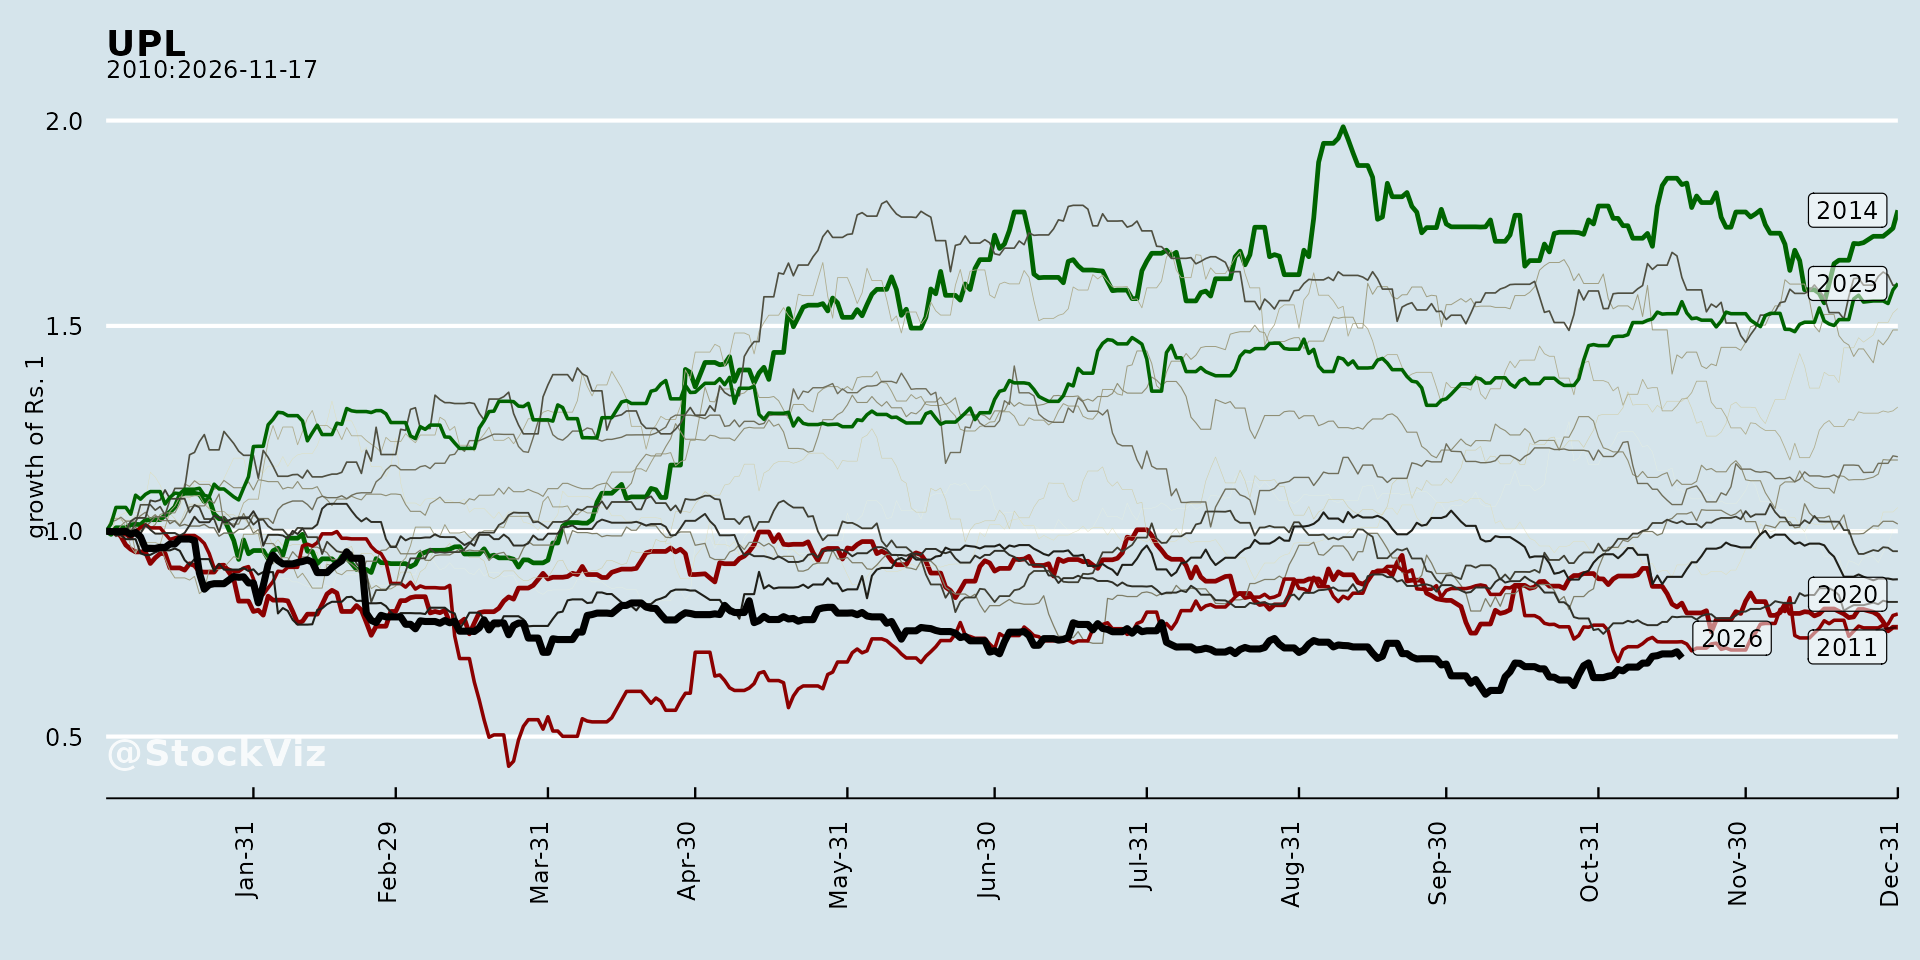
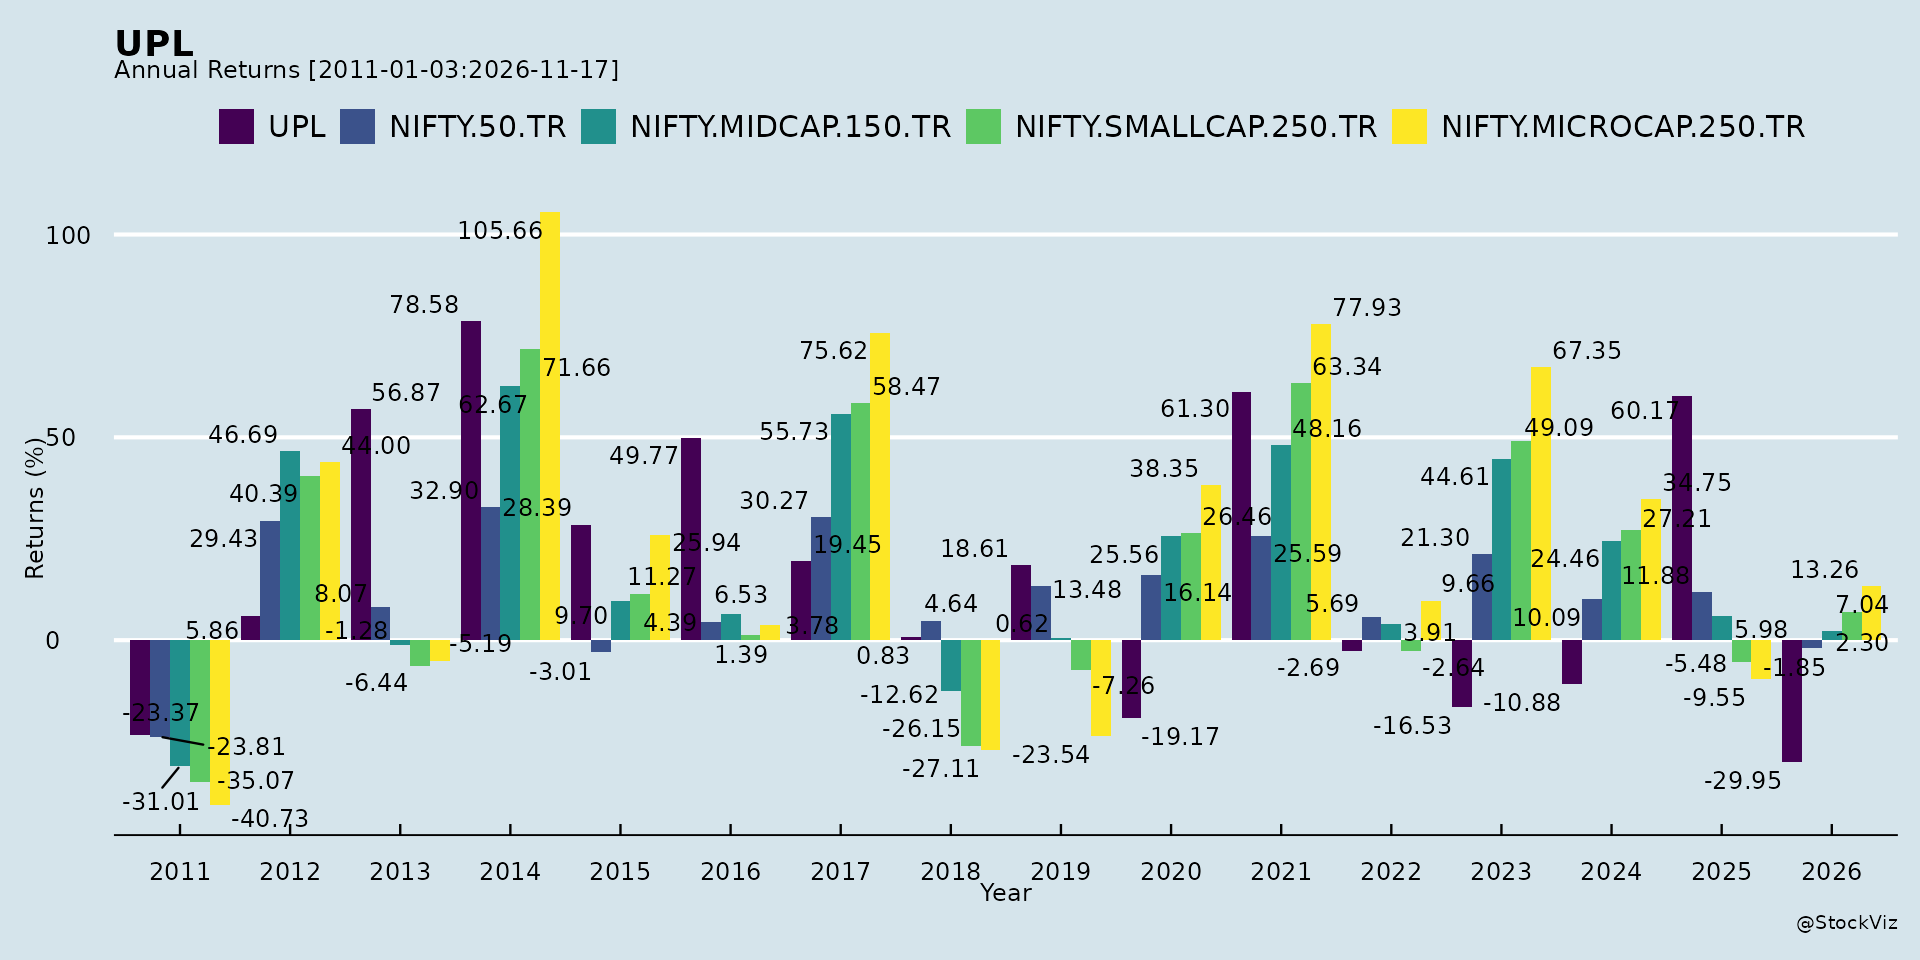
Annual Returns
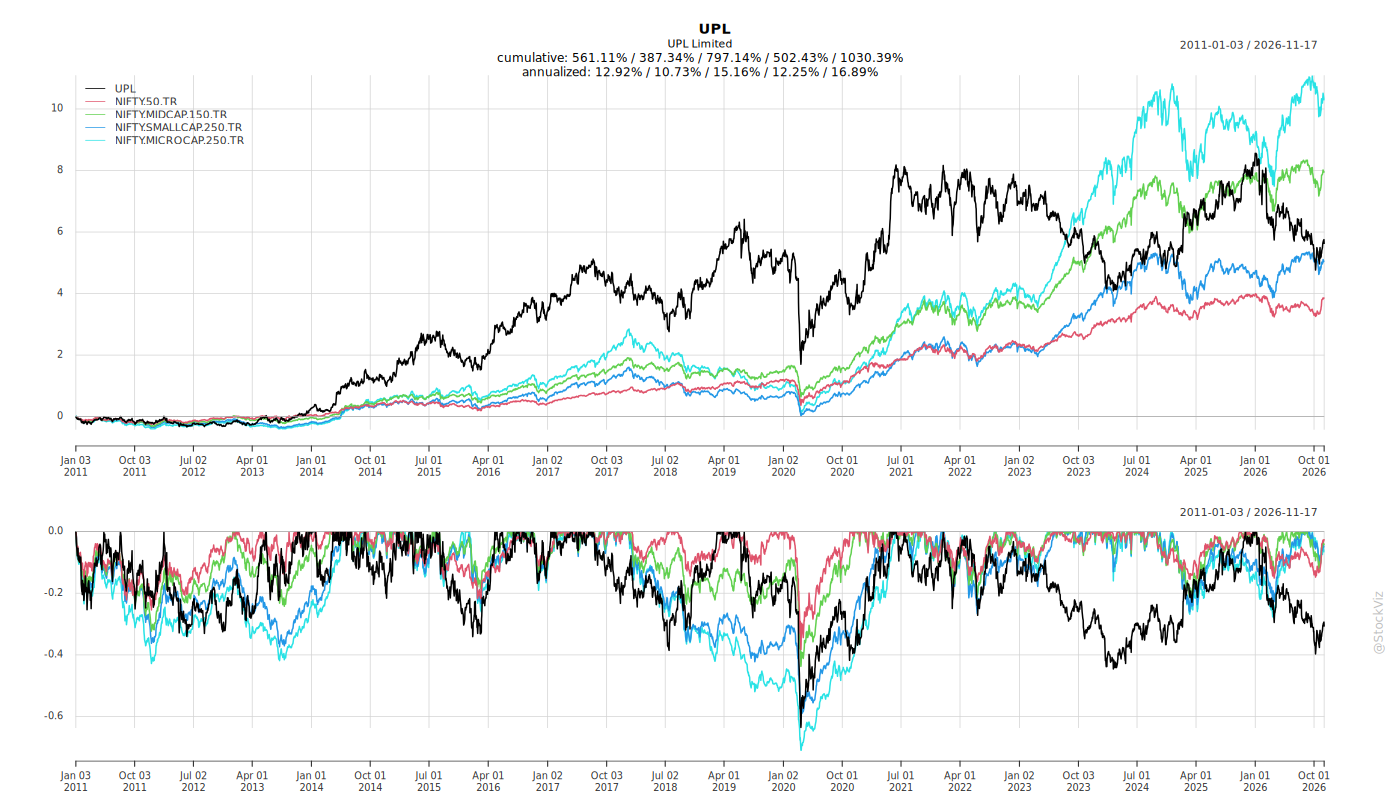
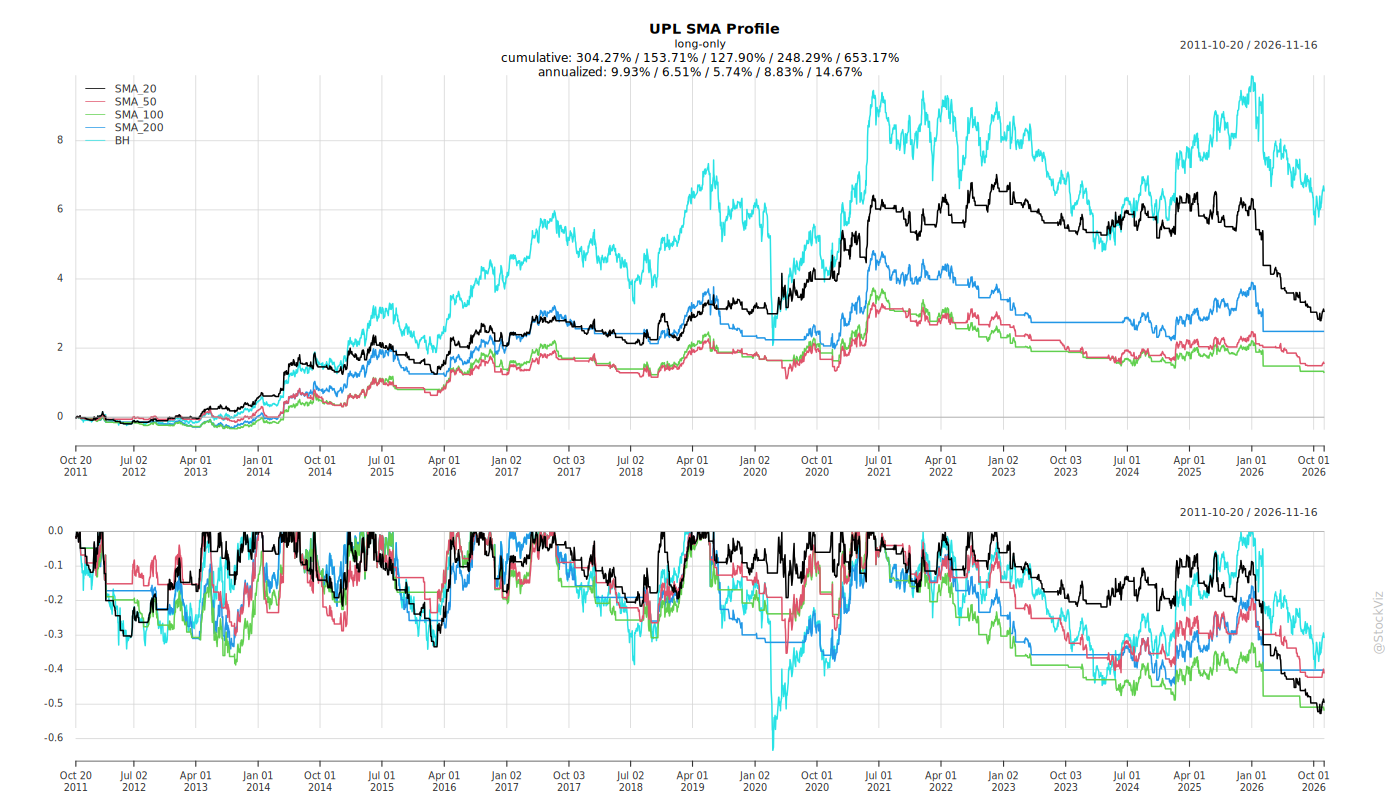
Cumulative Returns and Drawdowns
Fundamentals
Ownership
Margined
AI Summary
asof: 2026-09-16
UPL: Recent Corporate Announcements — Headwinds, Tailwinds, Risks, and Guidance vs. Performance
1. Headwinds and Challenges
- Macro and geopolitical uncertainty: UPL describes operating against “current macro uncertainty” and “ongoing geopolitical volatility,” with management’s FY27 guidance explicitly conditioned on no major escalation in West Asia disrupting logistics and input prices.
- Weather disruption: El Niño conditions caused planting delays across major regions including India and Europe. Unfavourable weather impacted Europe and Latin America, with weather-related volume pressure specifically noted in Europe.
- Farm income stress: Farm income stress continued across key regions, weighing on grower spending.
- Volume pressure in crop protection: The crop protection segment saw volume decline, even as pricing actions supported revenue and margins.
- Working capital build: Net working capital rose to 110 days, up 24 days versus June 2025, driven by a strategic inventory build-up and FX translation impact, alongside the seasonality-led increase in working capital.
- Advanta revenue flatness: At Advanta, strong positive pricing action was offset by delayed weather conditions, resulting in flat revenue year-on-year.
- Margin dilution at SUPERFORM: Despite 14% revenue growth, SUPERFORM’s contribution margin was flat and EBITDA margin declined 70 bps, as strong contribution growth was offset by higher overheads, limiting EBITDA growth to 7%.
2. Tailwinds and Growth Prospects
- Structural demand: Management frames rising global food demand as keeping seeds, crop protection, and bio-solutions at the heart of agriculture — a structural need described as enduring despite macro uncertainty.
- Broad-based growth: Q1 FY27 revenue growth was broad-based across most platforms and regions, with overall pricing up 3% versus last year.
- Platform momentum: UPL Corp revenue rose 7%, Advanta 26%, and SUPERFORM 14%. UPL SAS revenue was positive year-on-year.
- Regional momentum: Growth was led by India (+15%), North America (+18%), Latin America (+8%), Rest of World (+7%), and Europe (+4%).
- Margin expansion: Contribution margin expanded 180 bps, led by pricing action, higher capacity utilisation, and favourable portfolio mix; EBITDA margin expanded 60 bps.
- Specialty chemicals strength: SUPERFORM’s specialty chemicals business grew 51% year-on-year on volume and price, with agchem growth led by pricing.
- Advanta profitability: Favourable product mix drove a 28% contribution increase (margin up 890 bps) and 34% EBITDA growth (margin up 750 bps) despite flat revenue.
- UPL Corp profitability: Contribution rose 18% (margin up 340 bps) and EBITDA rose 38% (margin up 190 bps), with margin expansion driven by Europe and North America.
- Balance sheet improvement: Gross debt was $3.0 Bn and net debt $2.5 Bn, with net debt maintained versus June 2025 despite higher working capital; Net Debt/EBITDA improved to 2.4x from 2.6x, and Net Debt/Equity was 0.6x. CARE Edge upgraded UPL’s long-term rating to CARE AA+ (Stable).
- Strategic value-unlocking: Management points to the proposed single, focused global crop protection platform and value unlocking of the seeds and post-harvest businesses, while leveraging synergies across shared manufacturing, R&D, and innovation.
3. Key Risks
- Weather risk: Guidance assumes no further adverse weather conditions, including El Niño; actual outcomes could differ if planting delays or unfavourable weather persist in Europe, Latin America, or other key regions.
- Geopolitical and logistics risk: A major escalation in West Asia disrupting logistics and input prices is an explicit assumption behind guidance.
- Farm income and demand risk: Continued farm income stress across key regions could weigh on grower consumption.
- Volume risk in crop protection: Volume decline in the crop protection segment, alongside an uneven demand environment, remains a pressure point.
- Working capital and gearing risk: The strategic inventory build-up and FX translation impact raised net working capital by 24 days; further builds could affect gearing metrics, though net debt was maintained and gearing improved in Q1 FY27.
- Margin mix and overhead risk: SUPERFORM’s higher overheads offset strong contribution growth, showing that cost pressures can dilute margin gains even when revenue grows.
- Forward-looking statement risk: UPL’s safe harbour statement notes that strategy implementation, new product development, legislation, legal claims, exchange and interest rates, tax rates, raw material and employee costs, acquisitions and integrations, exits and restructurings, technological change, political and economic developments in operating countries, industry consolidation, and competition could cause actual results to differ materially from plans and expectations.
4. Management Guidance vs. Observed Business Performance
- FY27 guidance: Management guides for full-year revenue growth of 7–11% and EBITDA growth of 10–14%, assuming no further adverse weather (including El Niño) and no major escalation in West Asia disrupting logistics and input prices.
- Q1 FY27 performance against the growth trajectory: Revenue reached ₹10,181 cr, up 10% year-on-year, within the guided 7–11% revenue growth band. EBITDA reached ₹1,500 cr, up 15% year-on-year, above the guided 10–14% EBITDA growth band. Contribution rose 15% year-on-year with margin at 45.2% (up 180 bps), and EBITDA margin was 14.7% (up 60 bps).
- Track record: Q1 FY27 marked the seventh consecutive quarter of revenue and EBITDA growth, and the strongest Q1 net income (PATMI) in the past three years. Operational PATMI was ₹19 cr. Profit Before Tax improved by ₹80 cr versus last year.
- Platform performance versus commentary: UPL Corp delivered its seventh consecutive quarter of EBITDA growth, with EBITDA up 38% and margin up 190 bps, supported by strategic pricing actions in key regions even as weather-related volume pressure affected Europe. Advanta grew revenue 26% with EBITDA up 24%, although contribution margin slipped 50 bps and EBITDA margin slipped 20 bps. SUPERFORM grew revenue 14% but EBITDA rose only 7%, with EBITDA margin down 70 bps.
- Balance sheet versus guidance context: Net debt was maintained versus last year despite macro headwinds and higher working capital, with gearing ratios improving — consistent with management’s emphasis on disciplined execution and “Accelerating Profitable Growth.”
- Management framing: Chairman & Group CEO Jai Shroff stated that FY27 began with strong momentum and high-quality, profitable growth, and that the company is well positioned to deliver another year of profitable, high-quality growth. Group CFO Bikash Prasad described the quarter as one of disciplined, high-quality execution, with expanding margins and improving return ratios even as net debt was maintained and gearing improved.
Broker Narrative
The broker narrative evolved from a crop-protection story dominated by channel destocking, margin compression, adverse weather, plant under-utilization and Europe/NAFTA macro risks to a specialty-chemicals thesis built on China+1, backward integration across phosphorus/cyanation/phosgene/sulfur, flame retardants, and early-stage battery-grade PCl5. Persistent themes included crop-protection cyclicality, reducing dependence on it, and adverse regional/product mix toward lower-margin LATAM. Changed themes included the fading focus on working-capital and debt reduction, domestic UPL SAS/Advanta growth, and broad geographic revenue outperformance, replaced by Superform capex, cyanide capacity expansion, and synthetic caffeine opportunities.
Fears that came true
- High channel inventory and NAFTA channel destocking persisted through negative actual returns (-19.9% to -10.7%) and repeated DISAPPOINTMENT outcomes after 2023 Buy calls.
- Pricing pressure and an 890bps YoY gross-margin contraction in 4QFY23 materialized as Buy calls predicting +18.9% and +41.8% were followed by negative actuals and DISAPPOINTMENT results.
- Adverse weather in NAFTA and Argentina disrupted product placement and demand, consistent with negative actual returns across multiple 2023 DISAPPOINTMENT cases.
- European geopolitical and macro pressures from Russia-Ukraine, currency devaluation and product bans persisted as actual returns missed optimistic predictions.
- Adverse regional/product mix toward lower-margin LATAM revenue contributed to earnings weakness and negative actual returns in 2023 DISAPPOINTMENT outcomes.
Optimism that failed
- Broad geographic revenue growth (LATAM +12%, Europe +7%, RoW +6%, India +15%) failed to translate into predicted upside, as Buy calls were followed by negative actual returns and DISAPPOINTMENT outcomes.
- Traction in differentiated and innovation products (Feroce, Evolution, Shenzi; Rs 13.1bn FY23 contribution; ITI target 24% by FY27) did not prevent negative actual returns across DISAPPOINTMENT calls predicting double-digit gains.
- Working capital efficiency and debt reduction (WC to 64 days; net debt down Rs 20.04bn YoY) failed to support the stock, with Buy calls still yielding negative actuals and DISAPPOINTMENT results.
Broker Timeline
20 broker calls · 2023-05-09 to 2026-10-11
CNBC-TV18: ratings, targets and commentary
Extracted from CNBC-TV18 posts; ratings and targets are as published, not current consensus. OCR may contain errors. Speaker attribution is retained; not all speakers are brokers. These statements are separate from the Broker Narrative and Broker Timeline and have no calculated performance or outcomes.
Other company commentary (not broker ratings)
| Published / source (IST) | Speaker / affiliation | Rating / target | Commentary |
|---|---|---|---|
| 2026-11-17 |
Brokerages
|
—
|
Brokerages Talked About Update On Reorganisation As A Key Catalyst For The Stock |
| 2026-11-17 |
Brokerages
|
—
|
Brokerages Say, Proposed Reorganisation Could Lead To Sizeable Holding Co Discounts |
| 2026-11-17 |
UPL
|
—
|
UPL In Q2 Call: Market Feedback Is Shared With The Board, Any Dvpts Will Be Disclosed |
| 2026-11-17 |
Sources
|
—
|
UPL Likely To Soon Revise The Restructuring Announced In February 2026 |
Management comments
No recorded management comments with an explicit designation and affiliation for this ticker.
Copyright © 2023 SAS Data Analytics Pvt. Ltd. All rights reserved.