TVSELECT
Equity Metrics
September 24, 2026
TVS Electronics Limited
Computers Hardware & Equipments
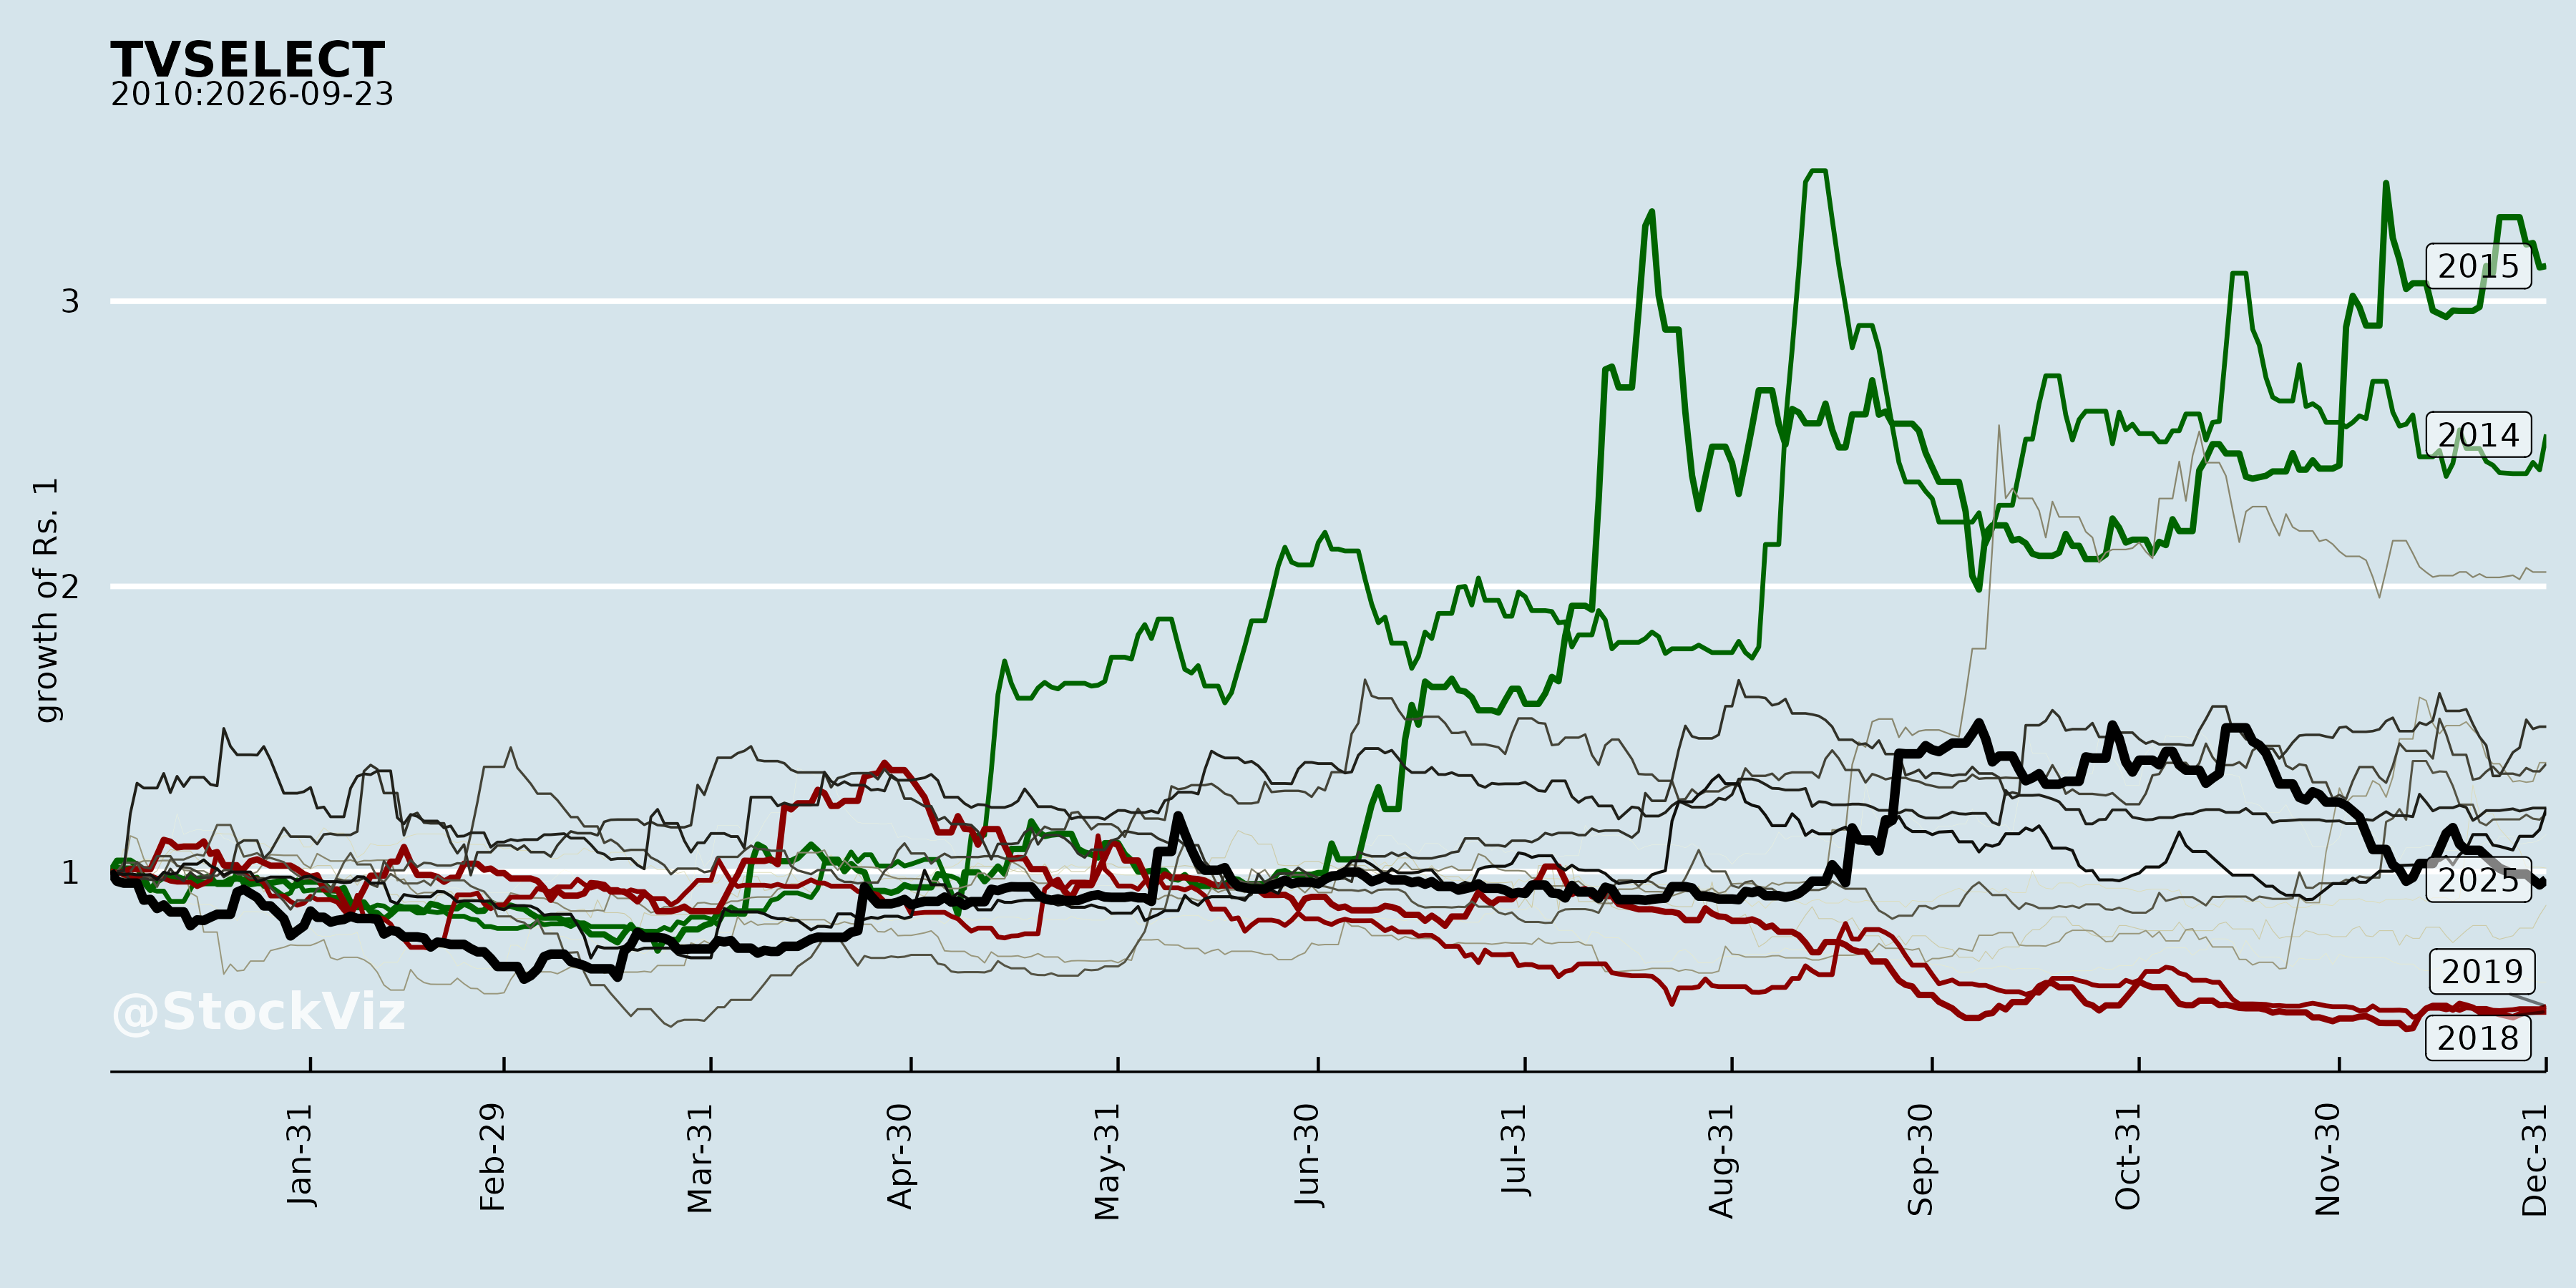
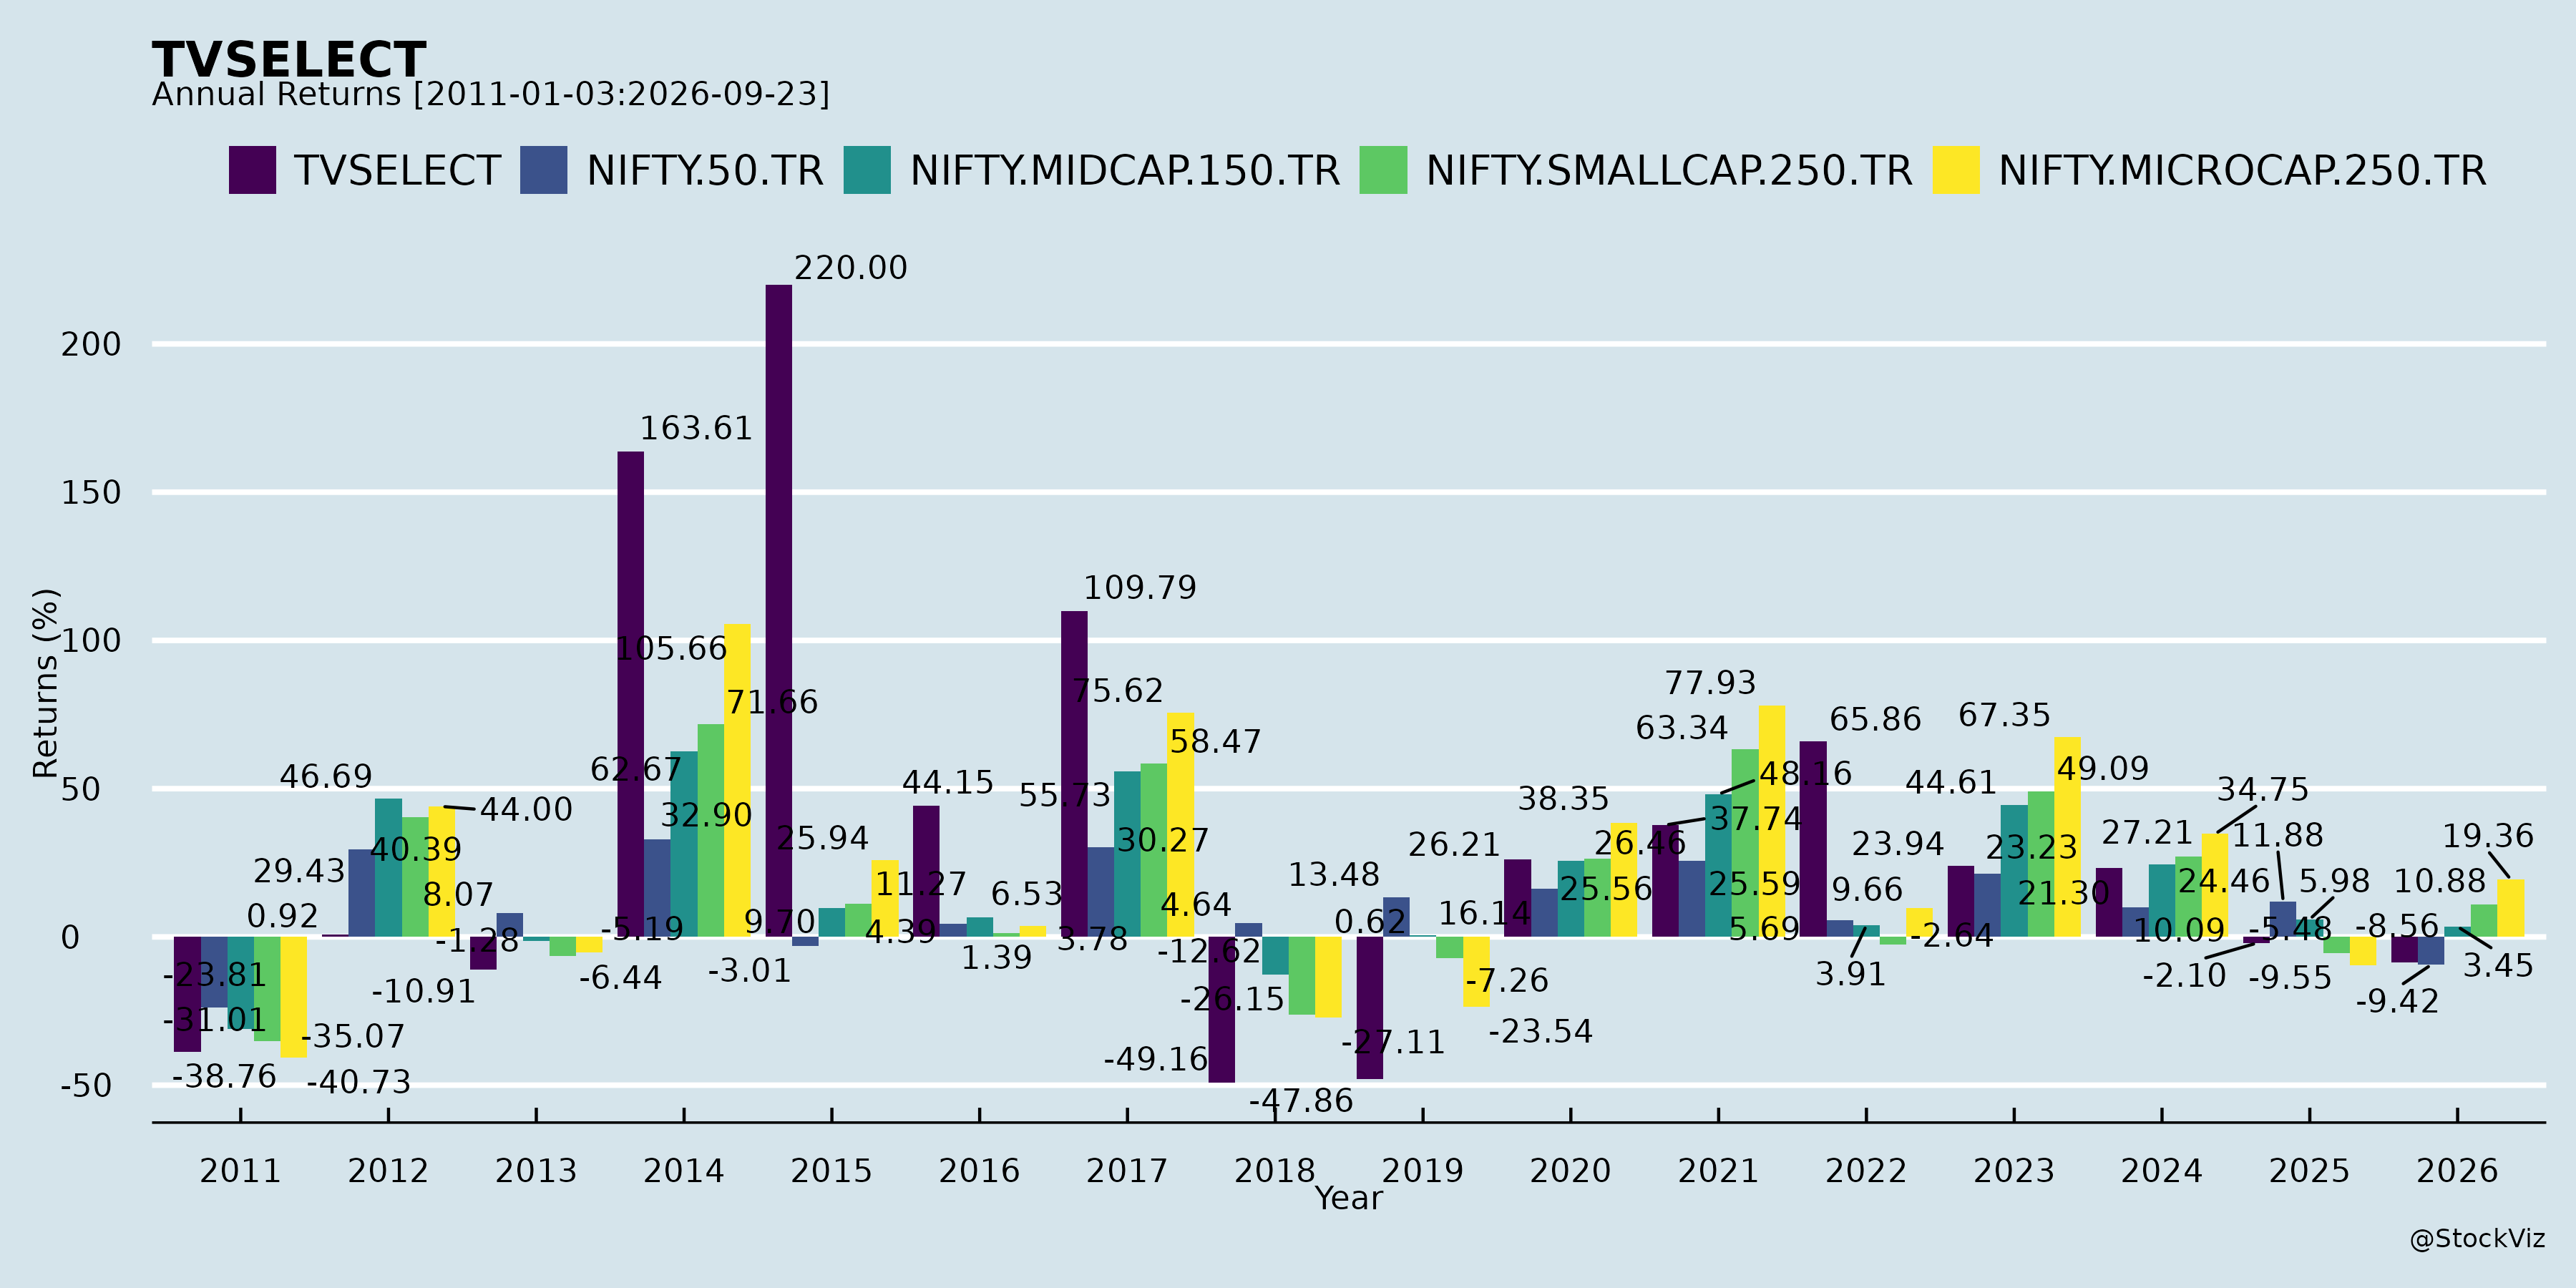
Annual Returns
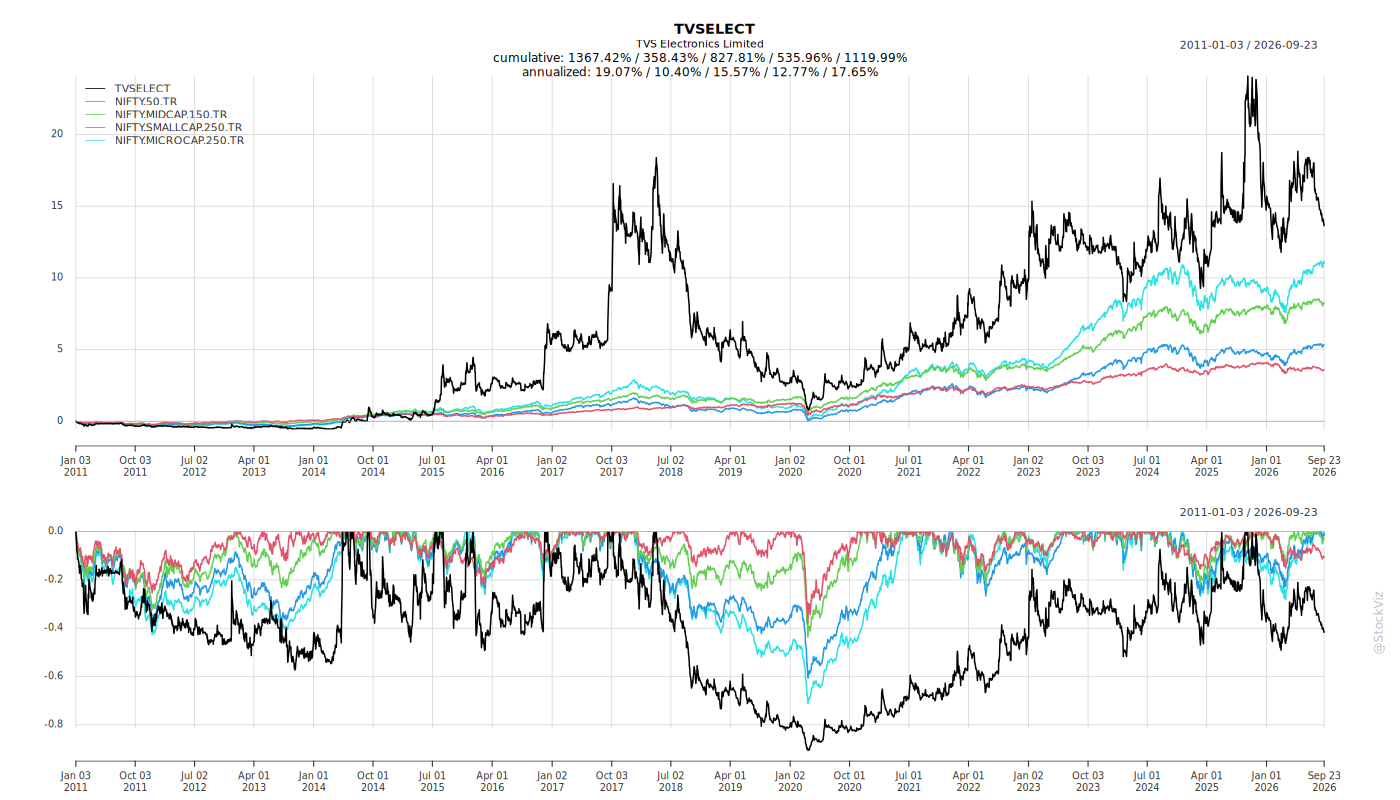
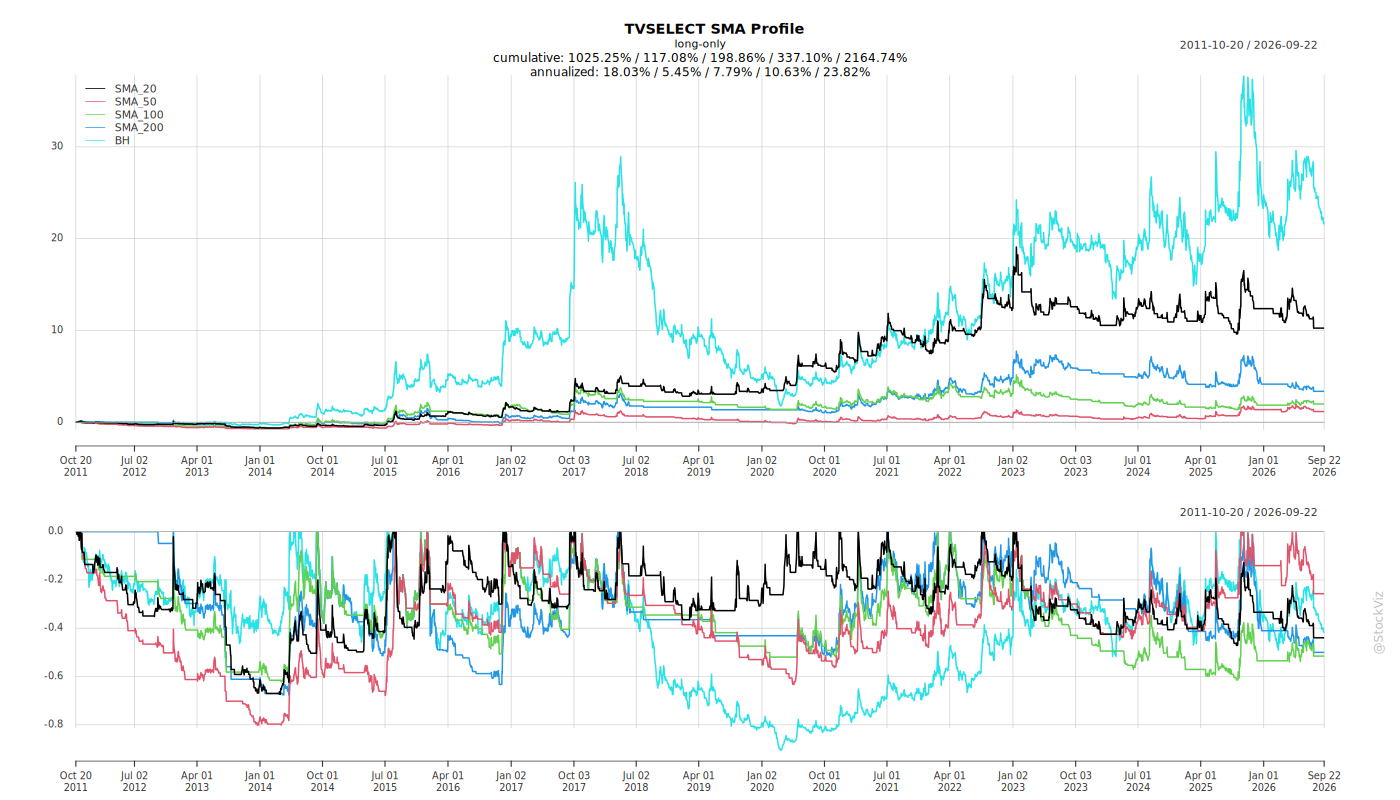
Cumulative Returns and Drawdowns
Fundamentals
Ownership
Margined
AI Summary
asof: 2026-09-18
TVSELECT: Recent Corporate Developments
1. Headwinds and Challenges
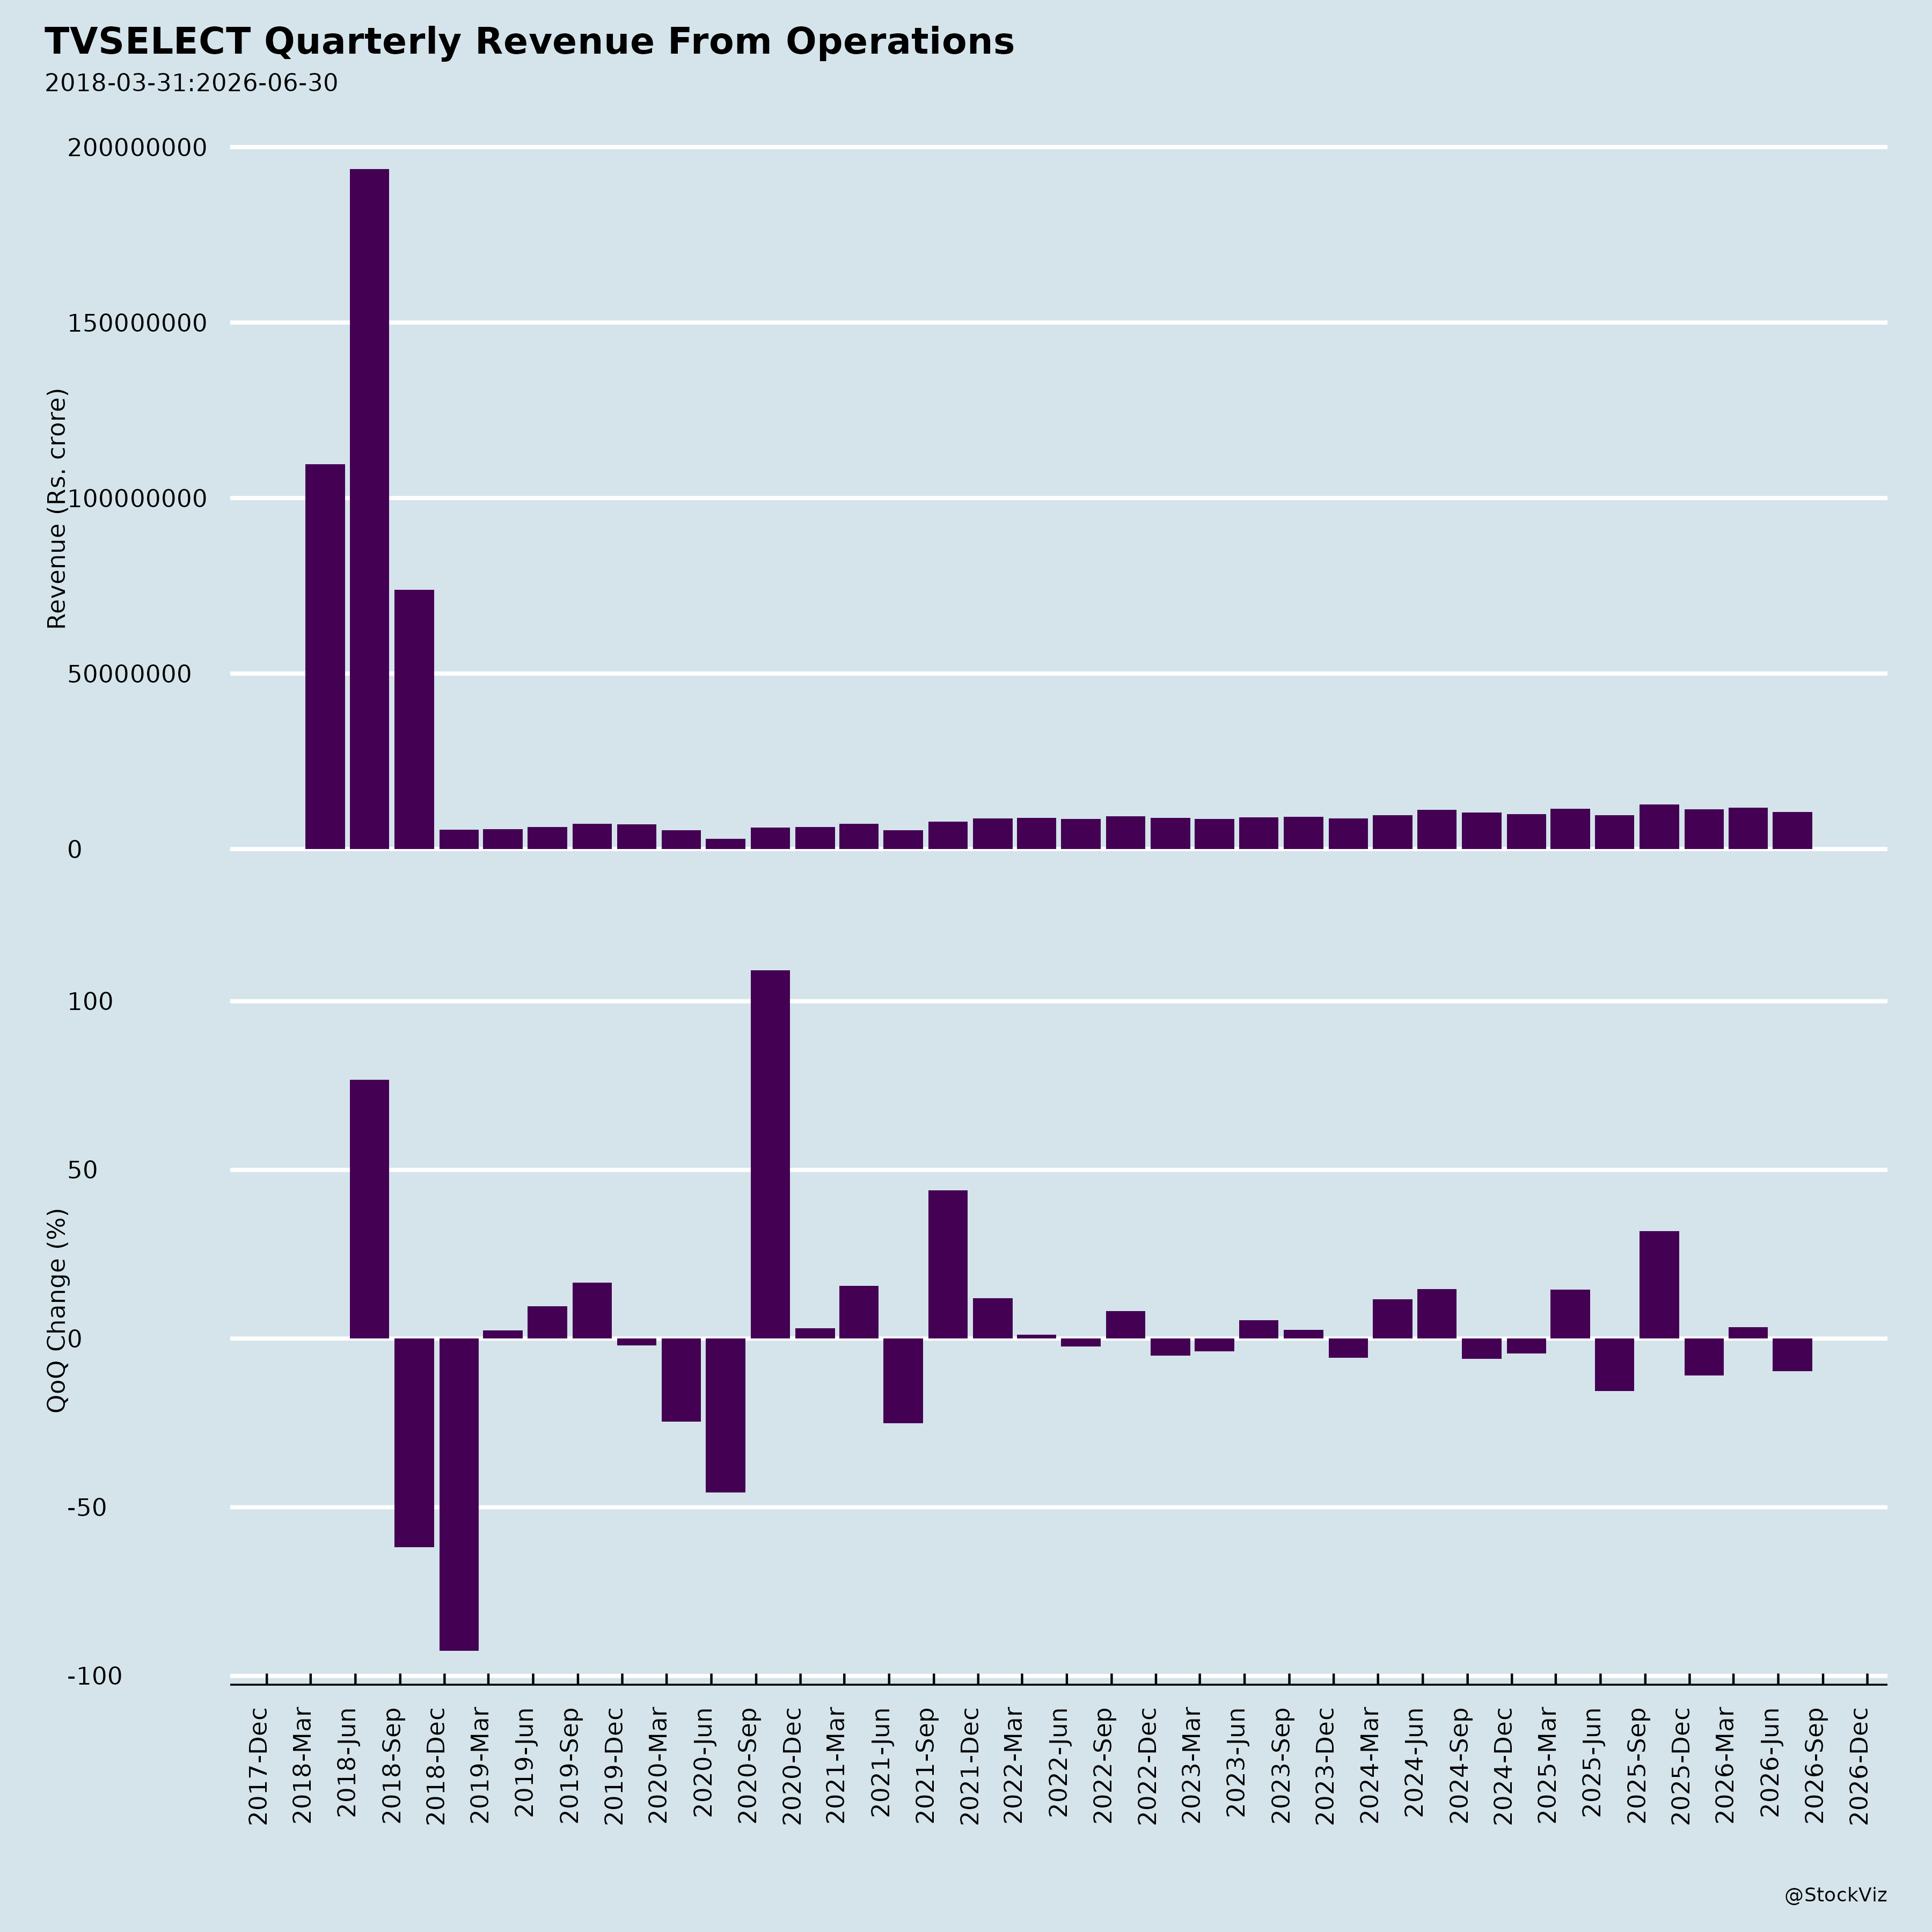
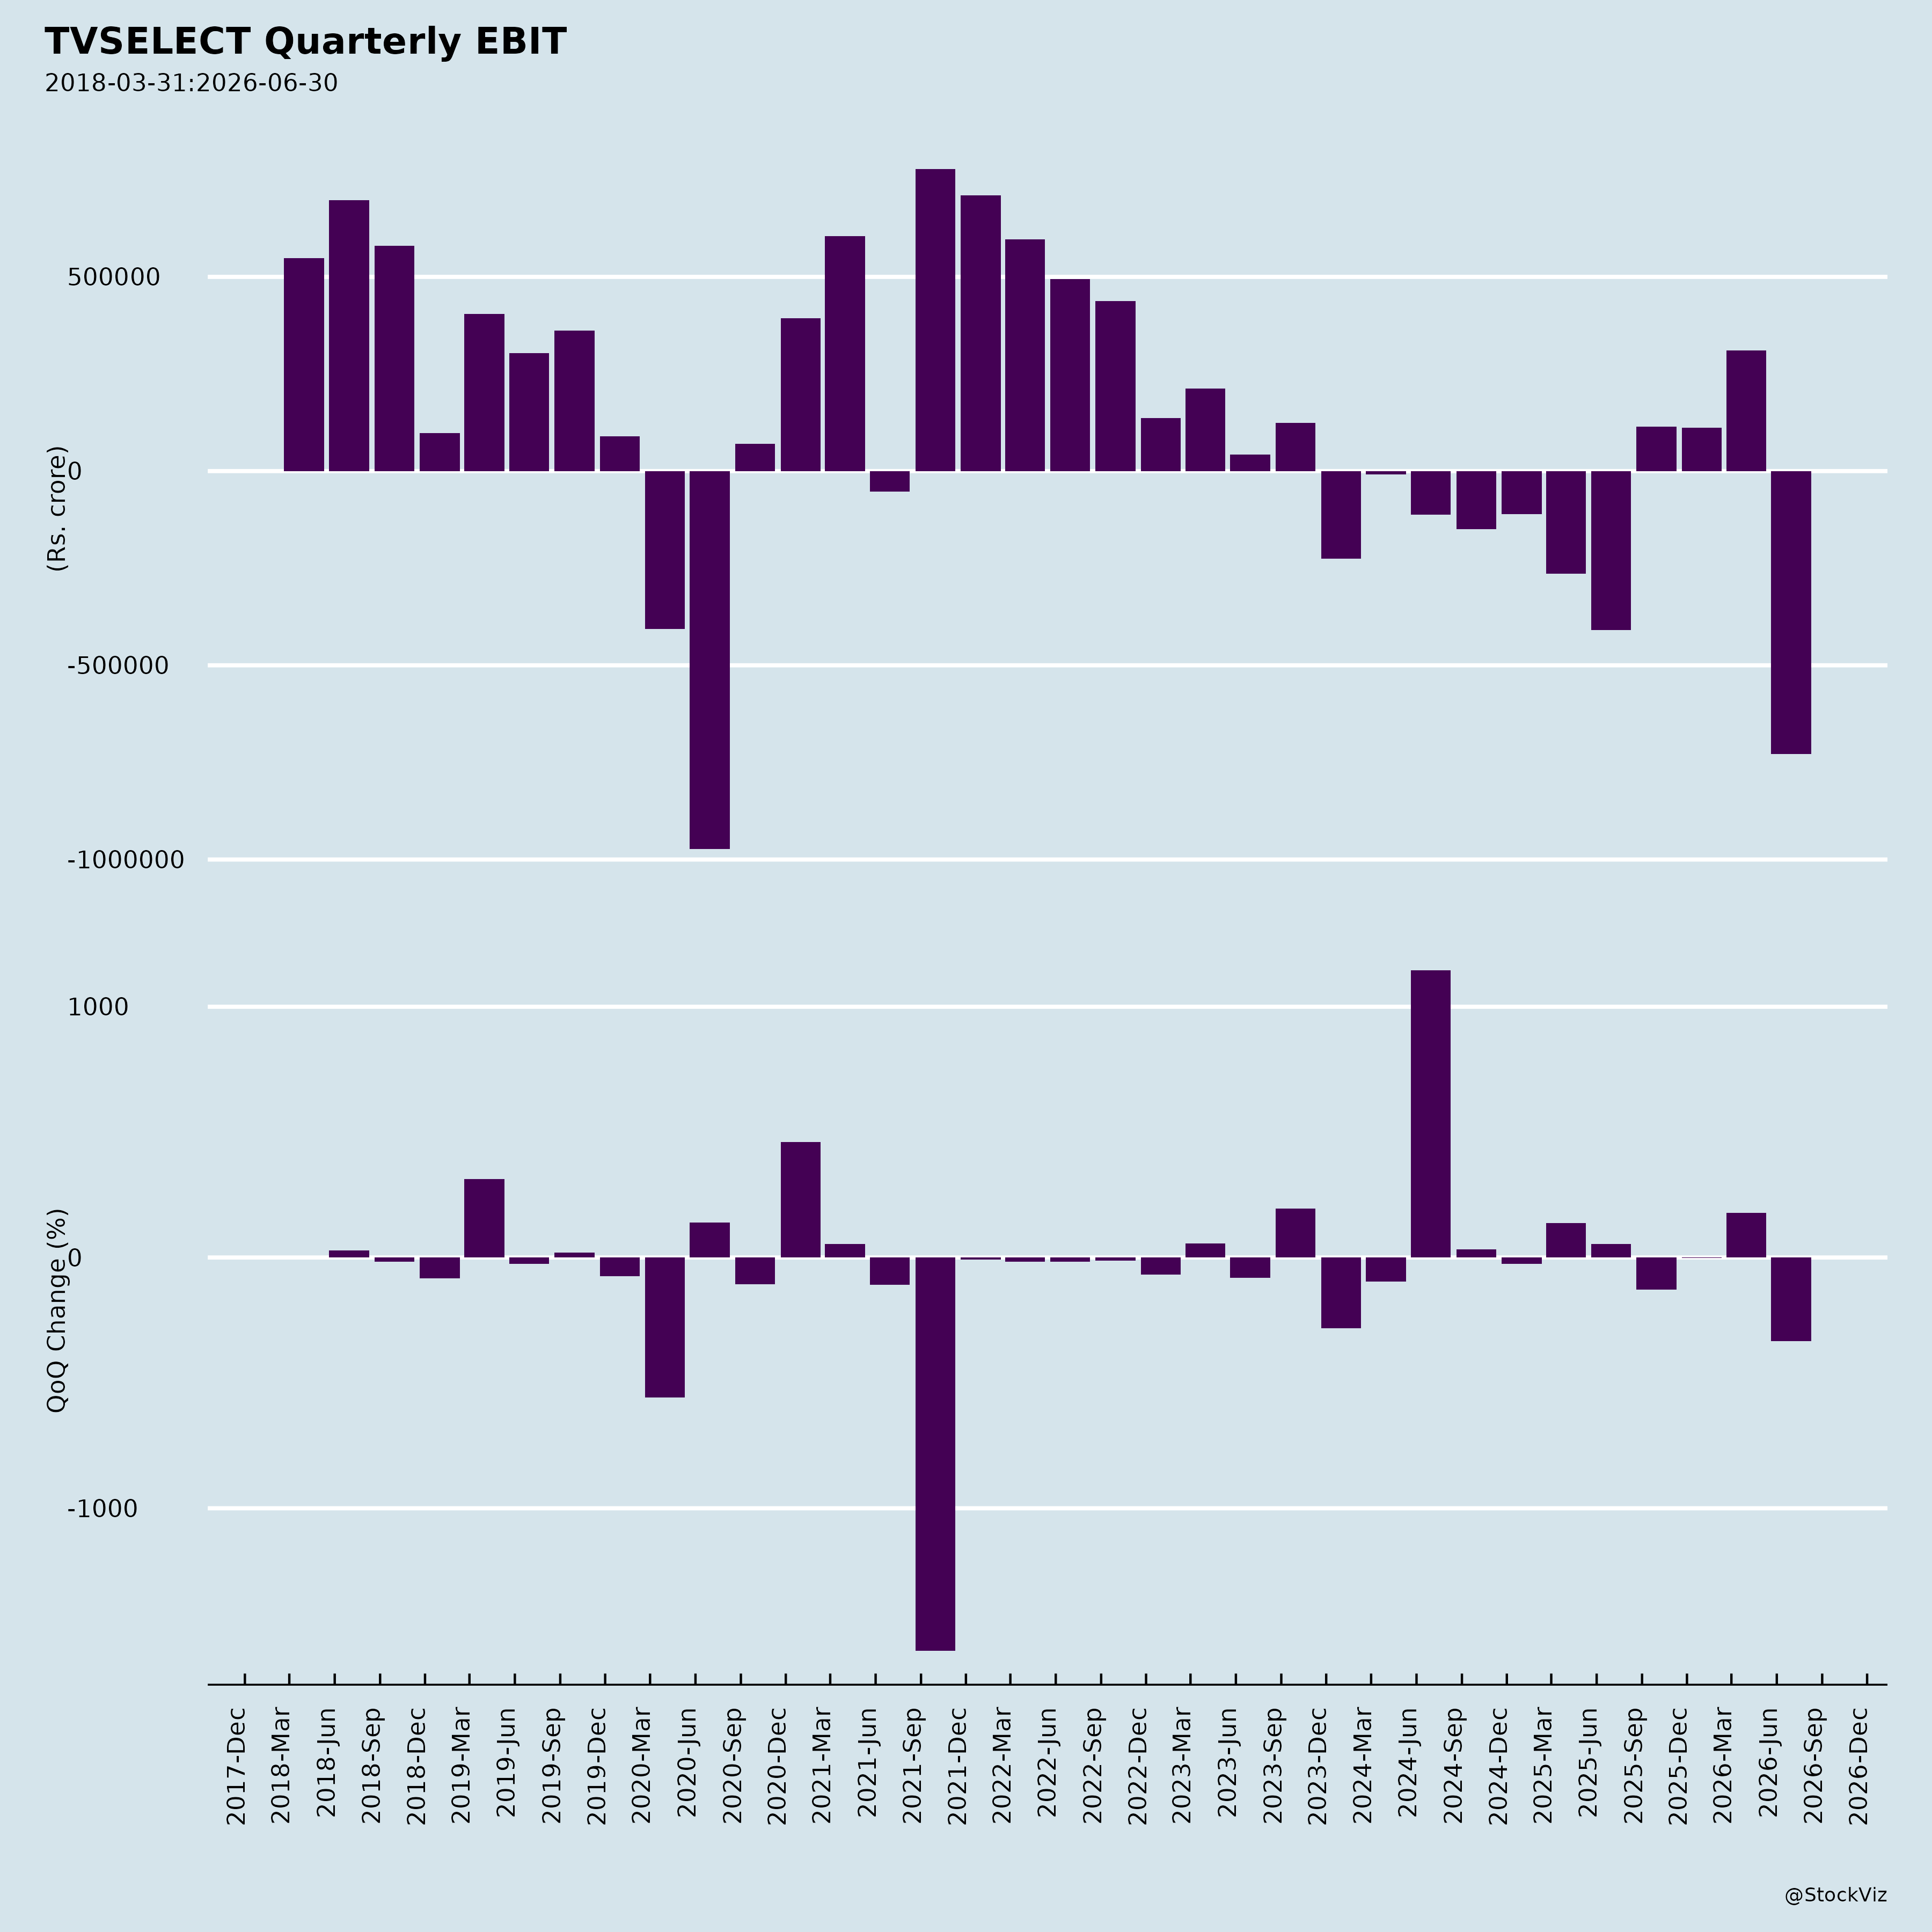
Profitability in Q1-FY27 was affected by higher material costs and by continued spending on new business initiatives and capability building. Revenue declined sequentially, which the company attributes primarily to lower call volumes and delays in the execution of corporate orders.
2. Tailwinds and Growth Prospects
Growth prospects cited include digital transformation in the retail and parking sectors, which is expected to increase demand for integrated software and hardware solutions. The company is also expanding manufacturing capabilities through SKD and CKD operations at its Tumakuru factory, enhancing own-designed technology products via its engineering development centre in Bangalore, and pursuing contract manufacturing opportunities for technology partners in support of the Make in India initiative.
3. Key Risks
The disclosed results point to pressure on profitability from elevated material costs and from ongoing investment in new business initiatives and capability building. The sequential revenue decline linked to lower call volumes and delayed execution of corporate orders highlights exposure to variability in service demand and to timing risk on corporate order execution.
4. Management Guidance Versus Observed Performance
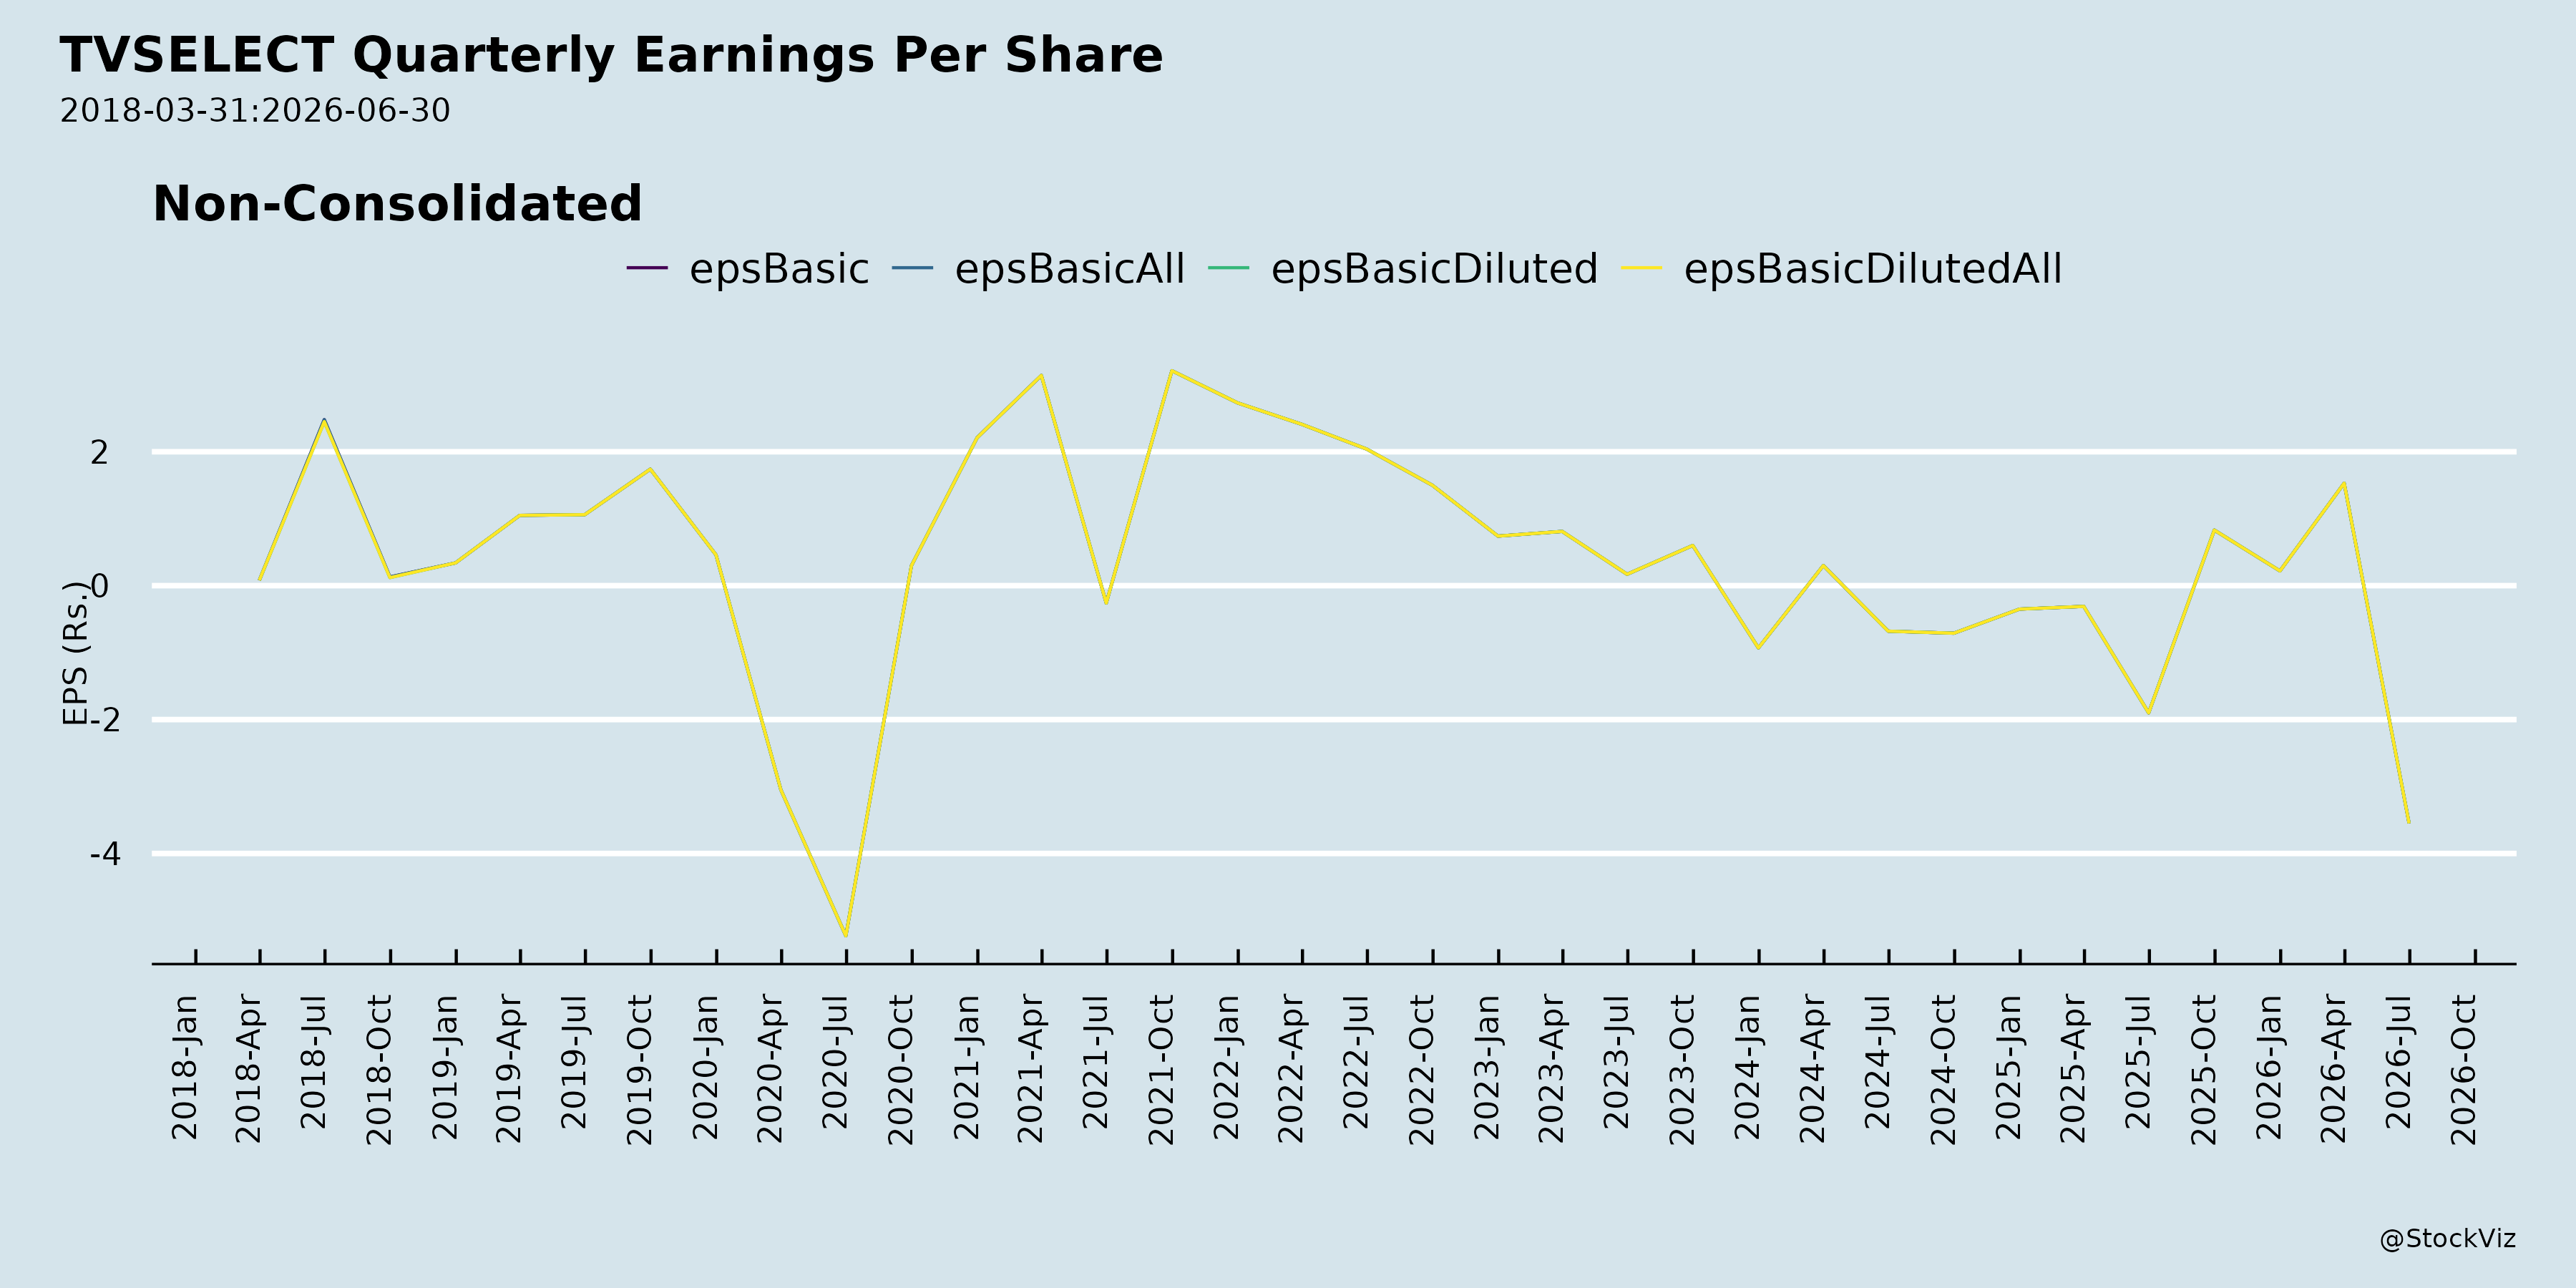
Management stated that the company continues to focus on cost optimisation, improving operational efficiencies, and driving sustainable revenue growth and margin improvement. Against this, the Q1-FY27 results show revenue from operations of INR 1,060 Mn (up 9.6% year-on-year but down 9.7% quarter-on-quarter), EBITDA of INR (24) Mn, and PAT of INR (66) Mn, a PAT margin of (6.23)%. For the full year FY26, revenue was INR 4,552 Mn, EBITDA was INR 195 Mn, and net profit was INR 13 Mn. The business mix as of Q1-FY27 was 68% Product & Solutions Group (PSG) and 32% Customer Support Services (CSS).
Copyright © 2023 SAS Data Analytics Pvt. Ltd. All rights reserved.