TITAN
Equity Metrics
November 11, 2026
Titan Company Limited
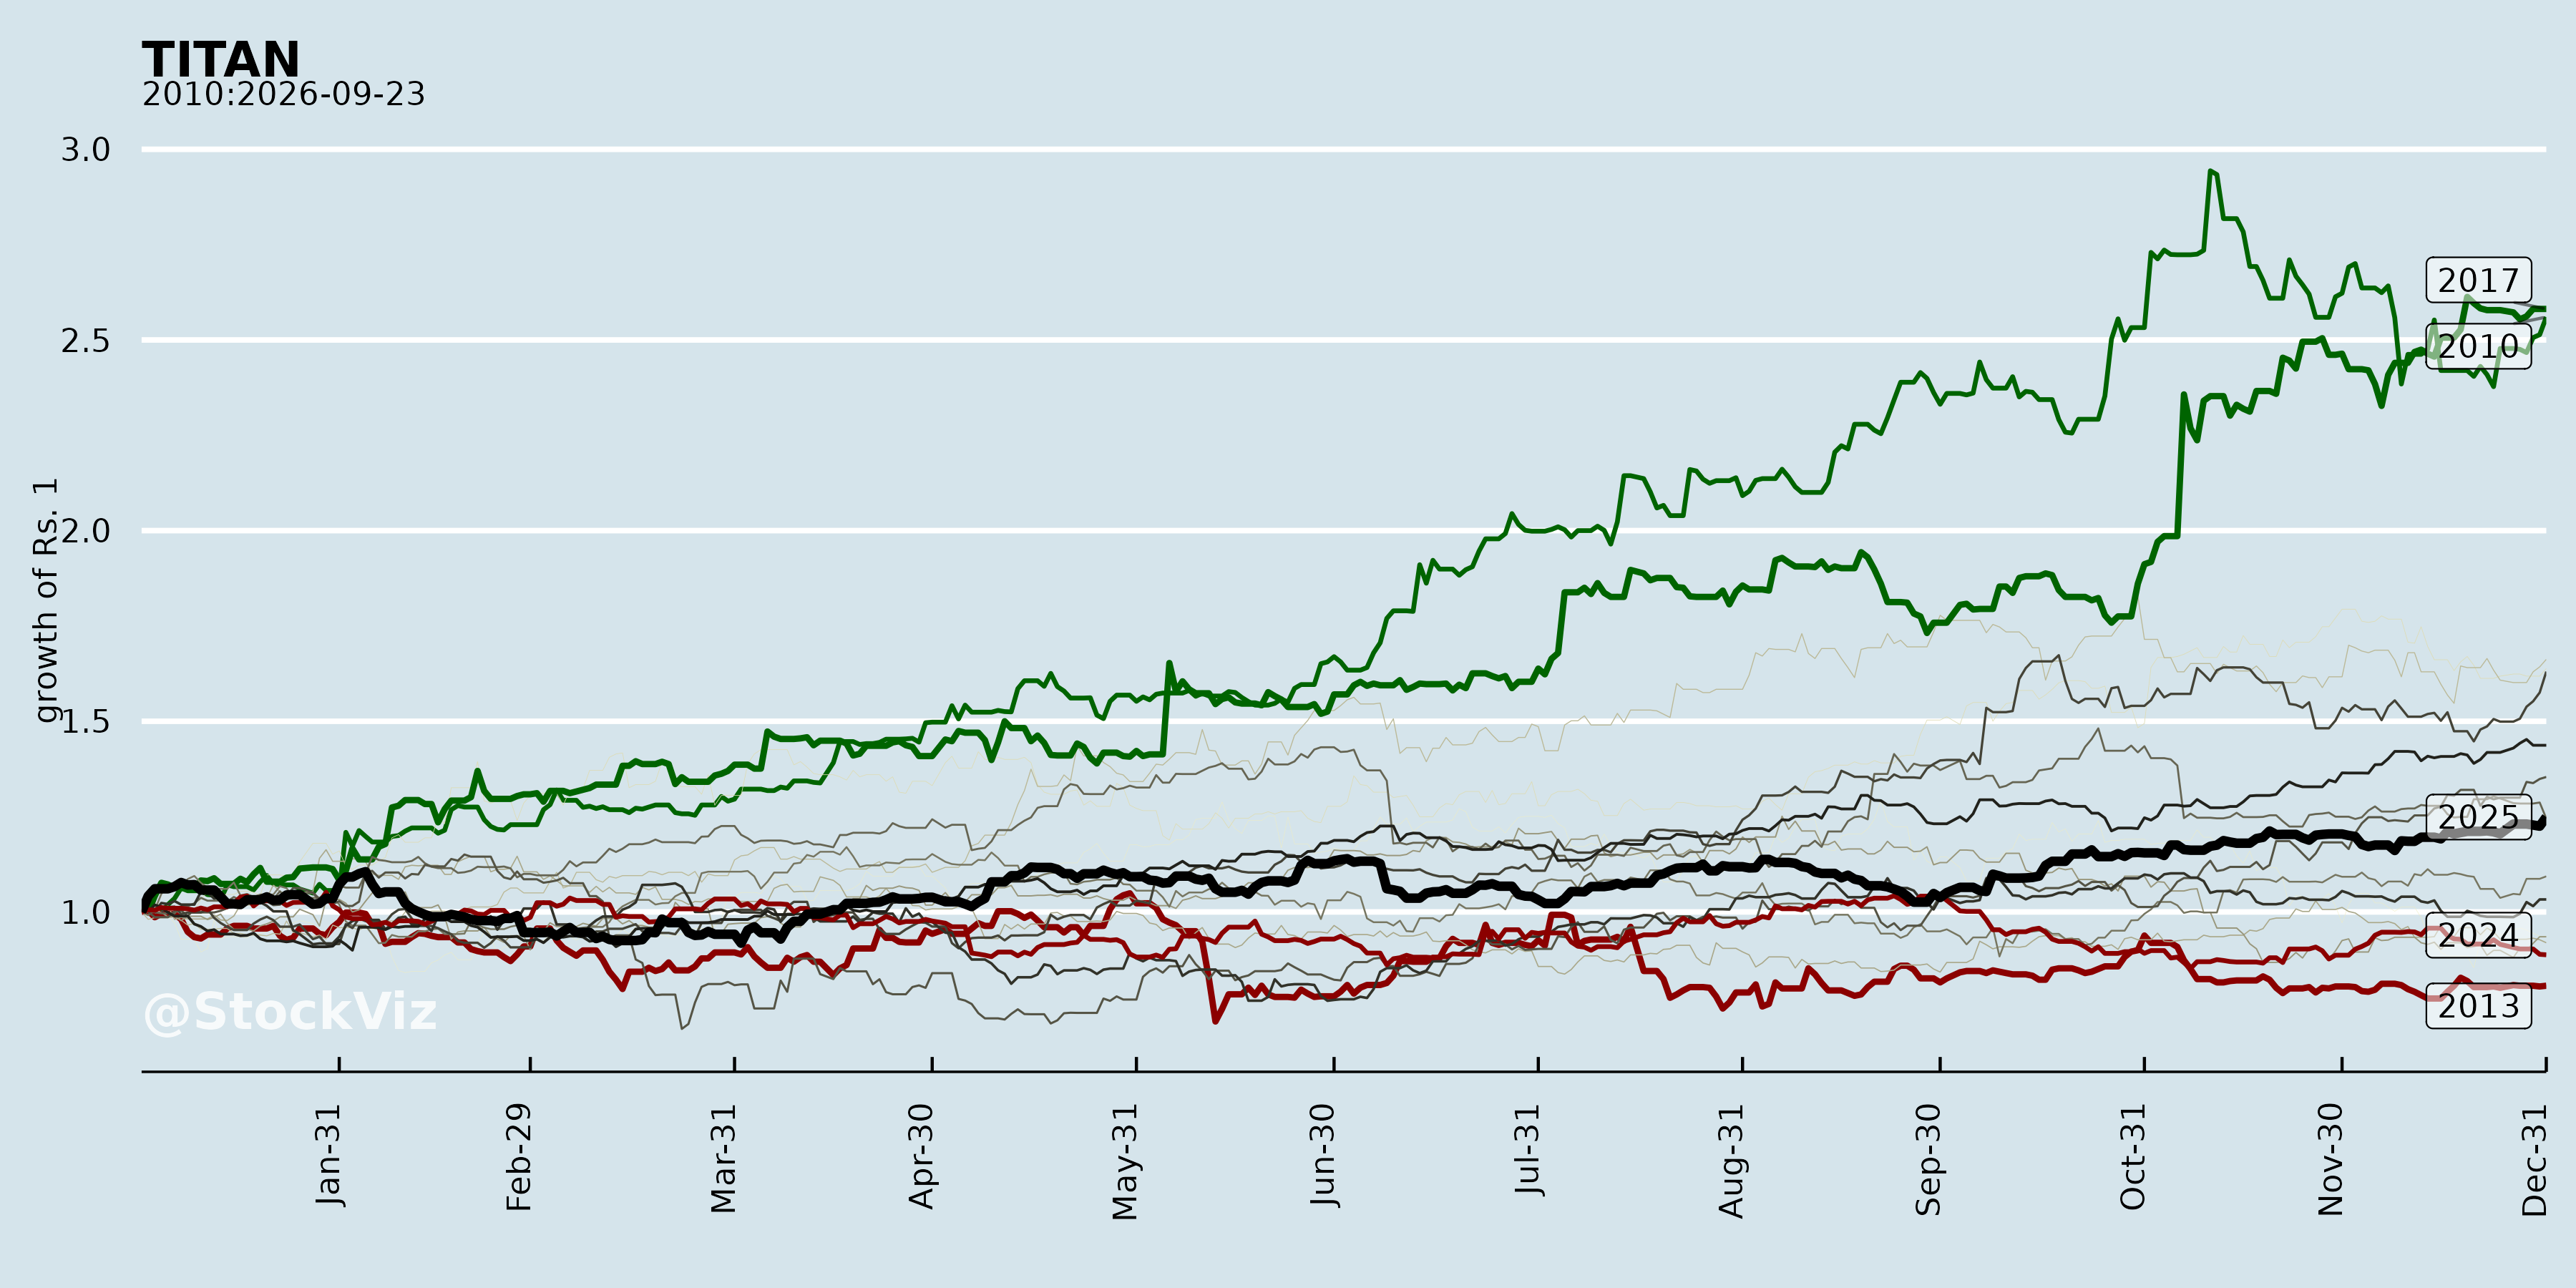
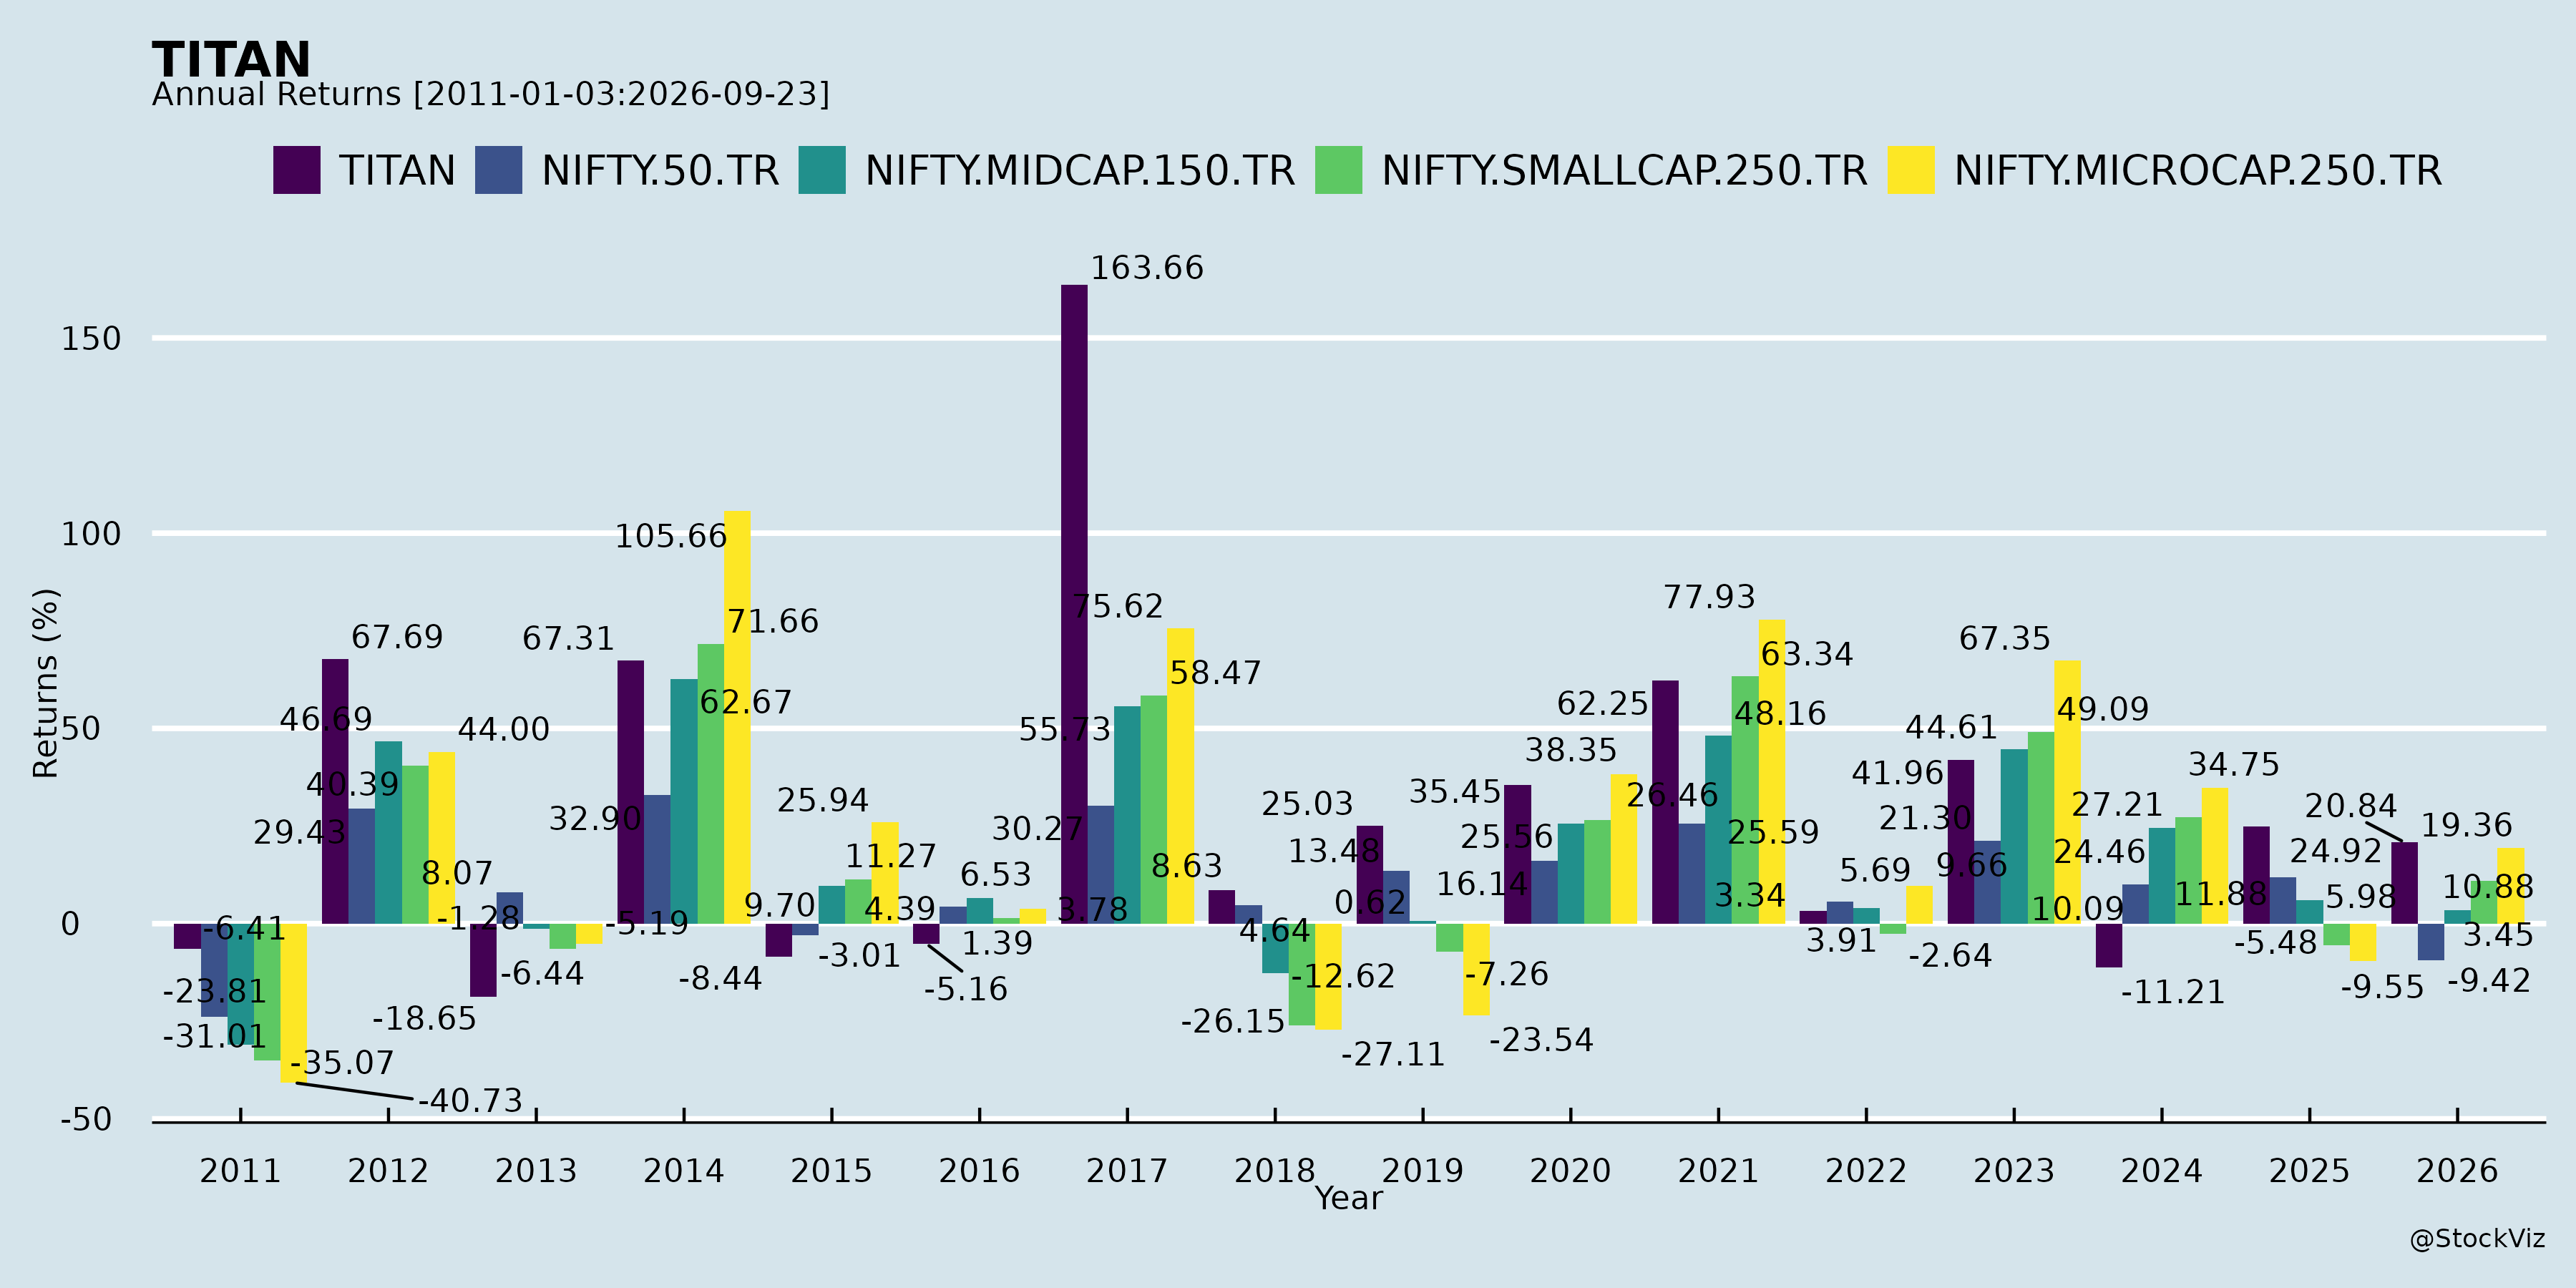
Annual Returns
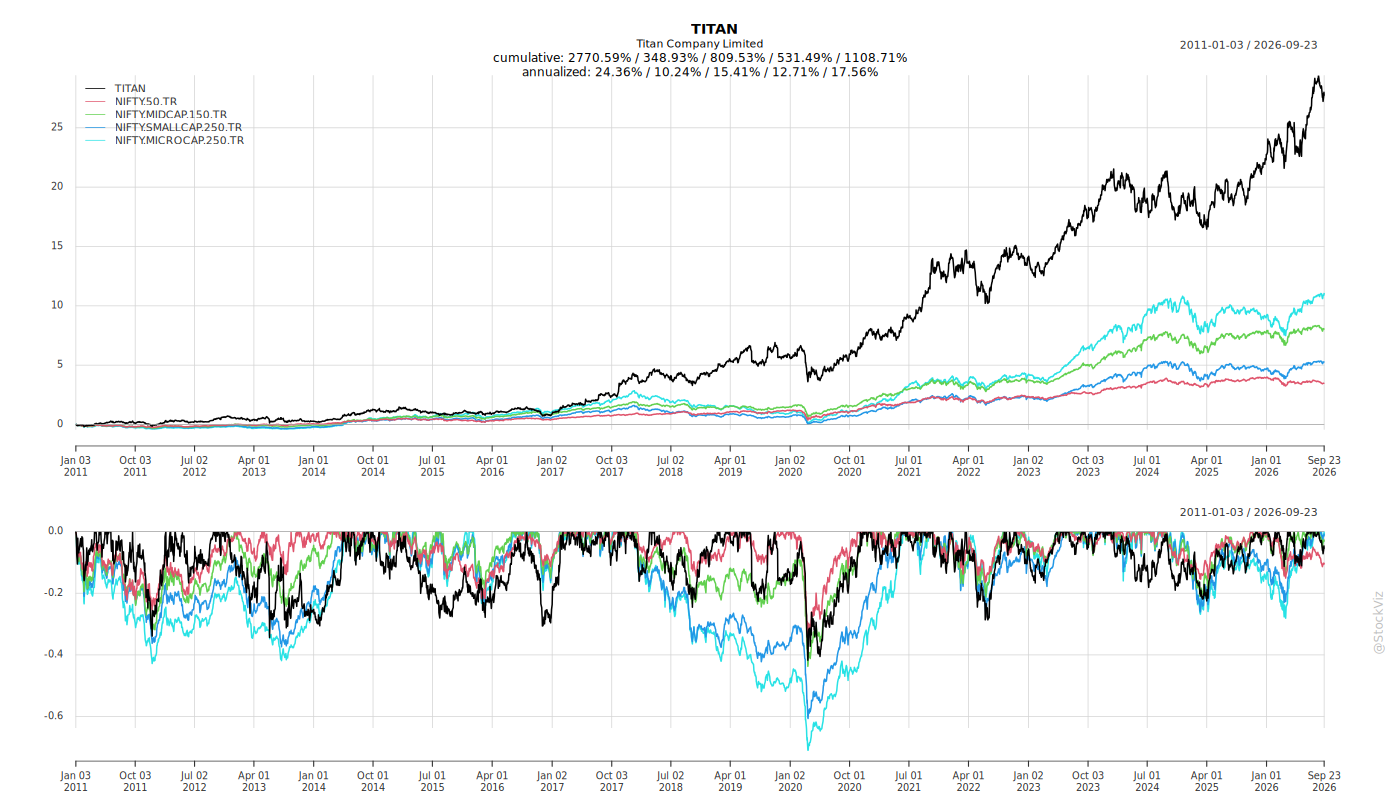
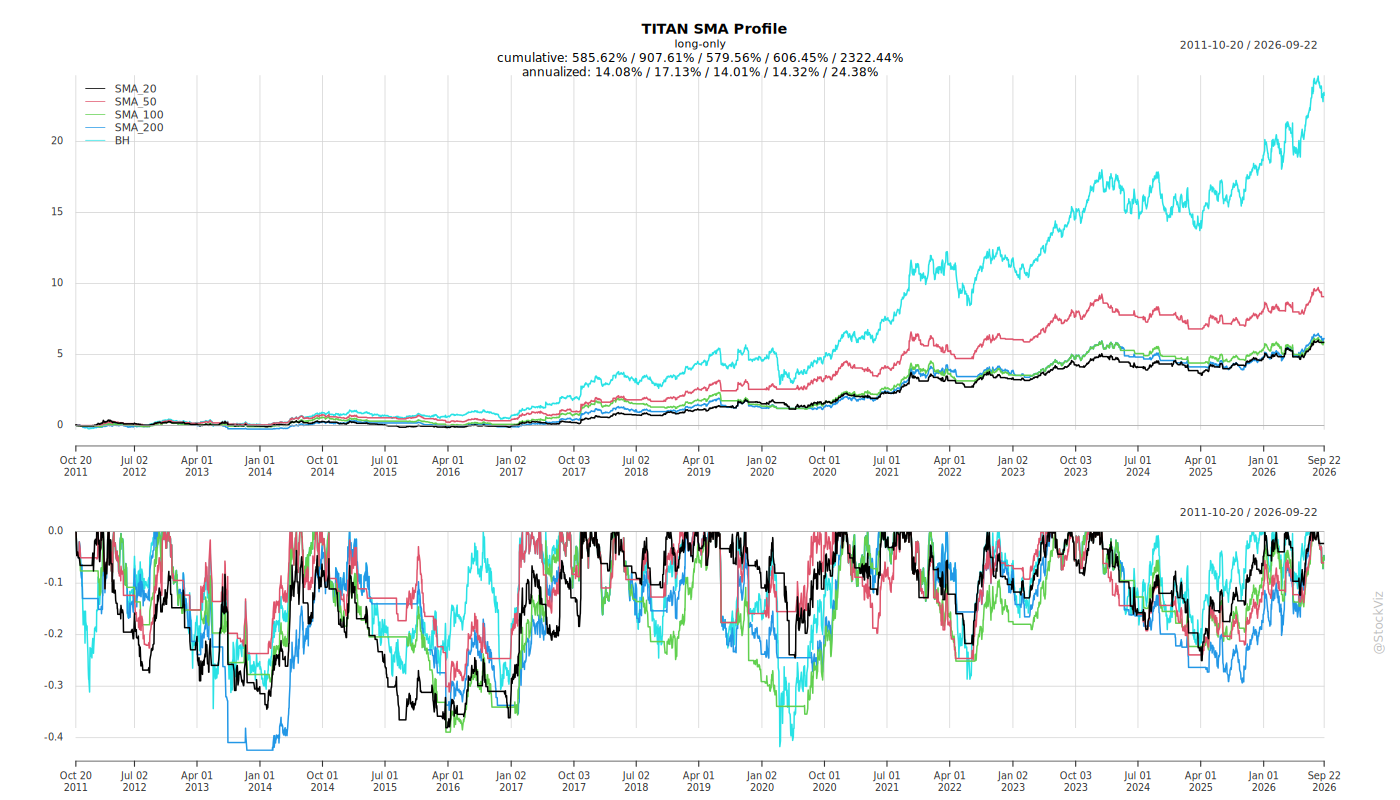
Cumulative Returns and Drawdowns
Fundamentals
Ownership
Margined
AI Summary
asof: 2026-09-14
Titan Company: Recent Corporate Developments
1. Headwinds and Challenges
- Gold prices and duty structure: Management identifies navigating gold prices and sharp changes in the duty structure as material challenges.
- Geopolitical exposure: Geopolitical headwinds across international operations are flagged, with consumer demand in the GCC impacted by regional geopolitical disruptions.
- Talent market competition: The Scheme 2026 explanatory material notes an “increasingly competitive talent market,” which the new performance stock unit scheme is partly designed to address through attraction, motivation and retention of key talent.
- Leadership transition: The current Chief People Officer, Mr. Swadesh Behera, superannuates on 31 March 2027; Ms. Priya Mathilakath has been appointed as CPO effective 1 April 2027.
- Administrative/shareholder matters: A notice was issued regarding loss of share certificates for certain shareholders, with claims to be lodged within 15 days of the 5 September 2026 notice date before duplicate certificates are issued.
2. Tailwinds and Growth Prospects
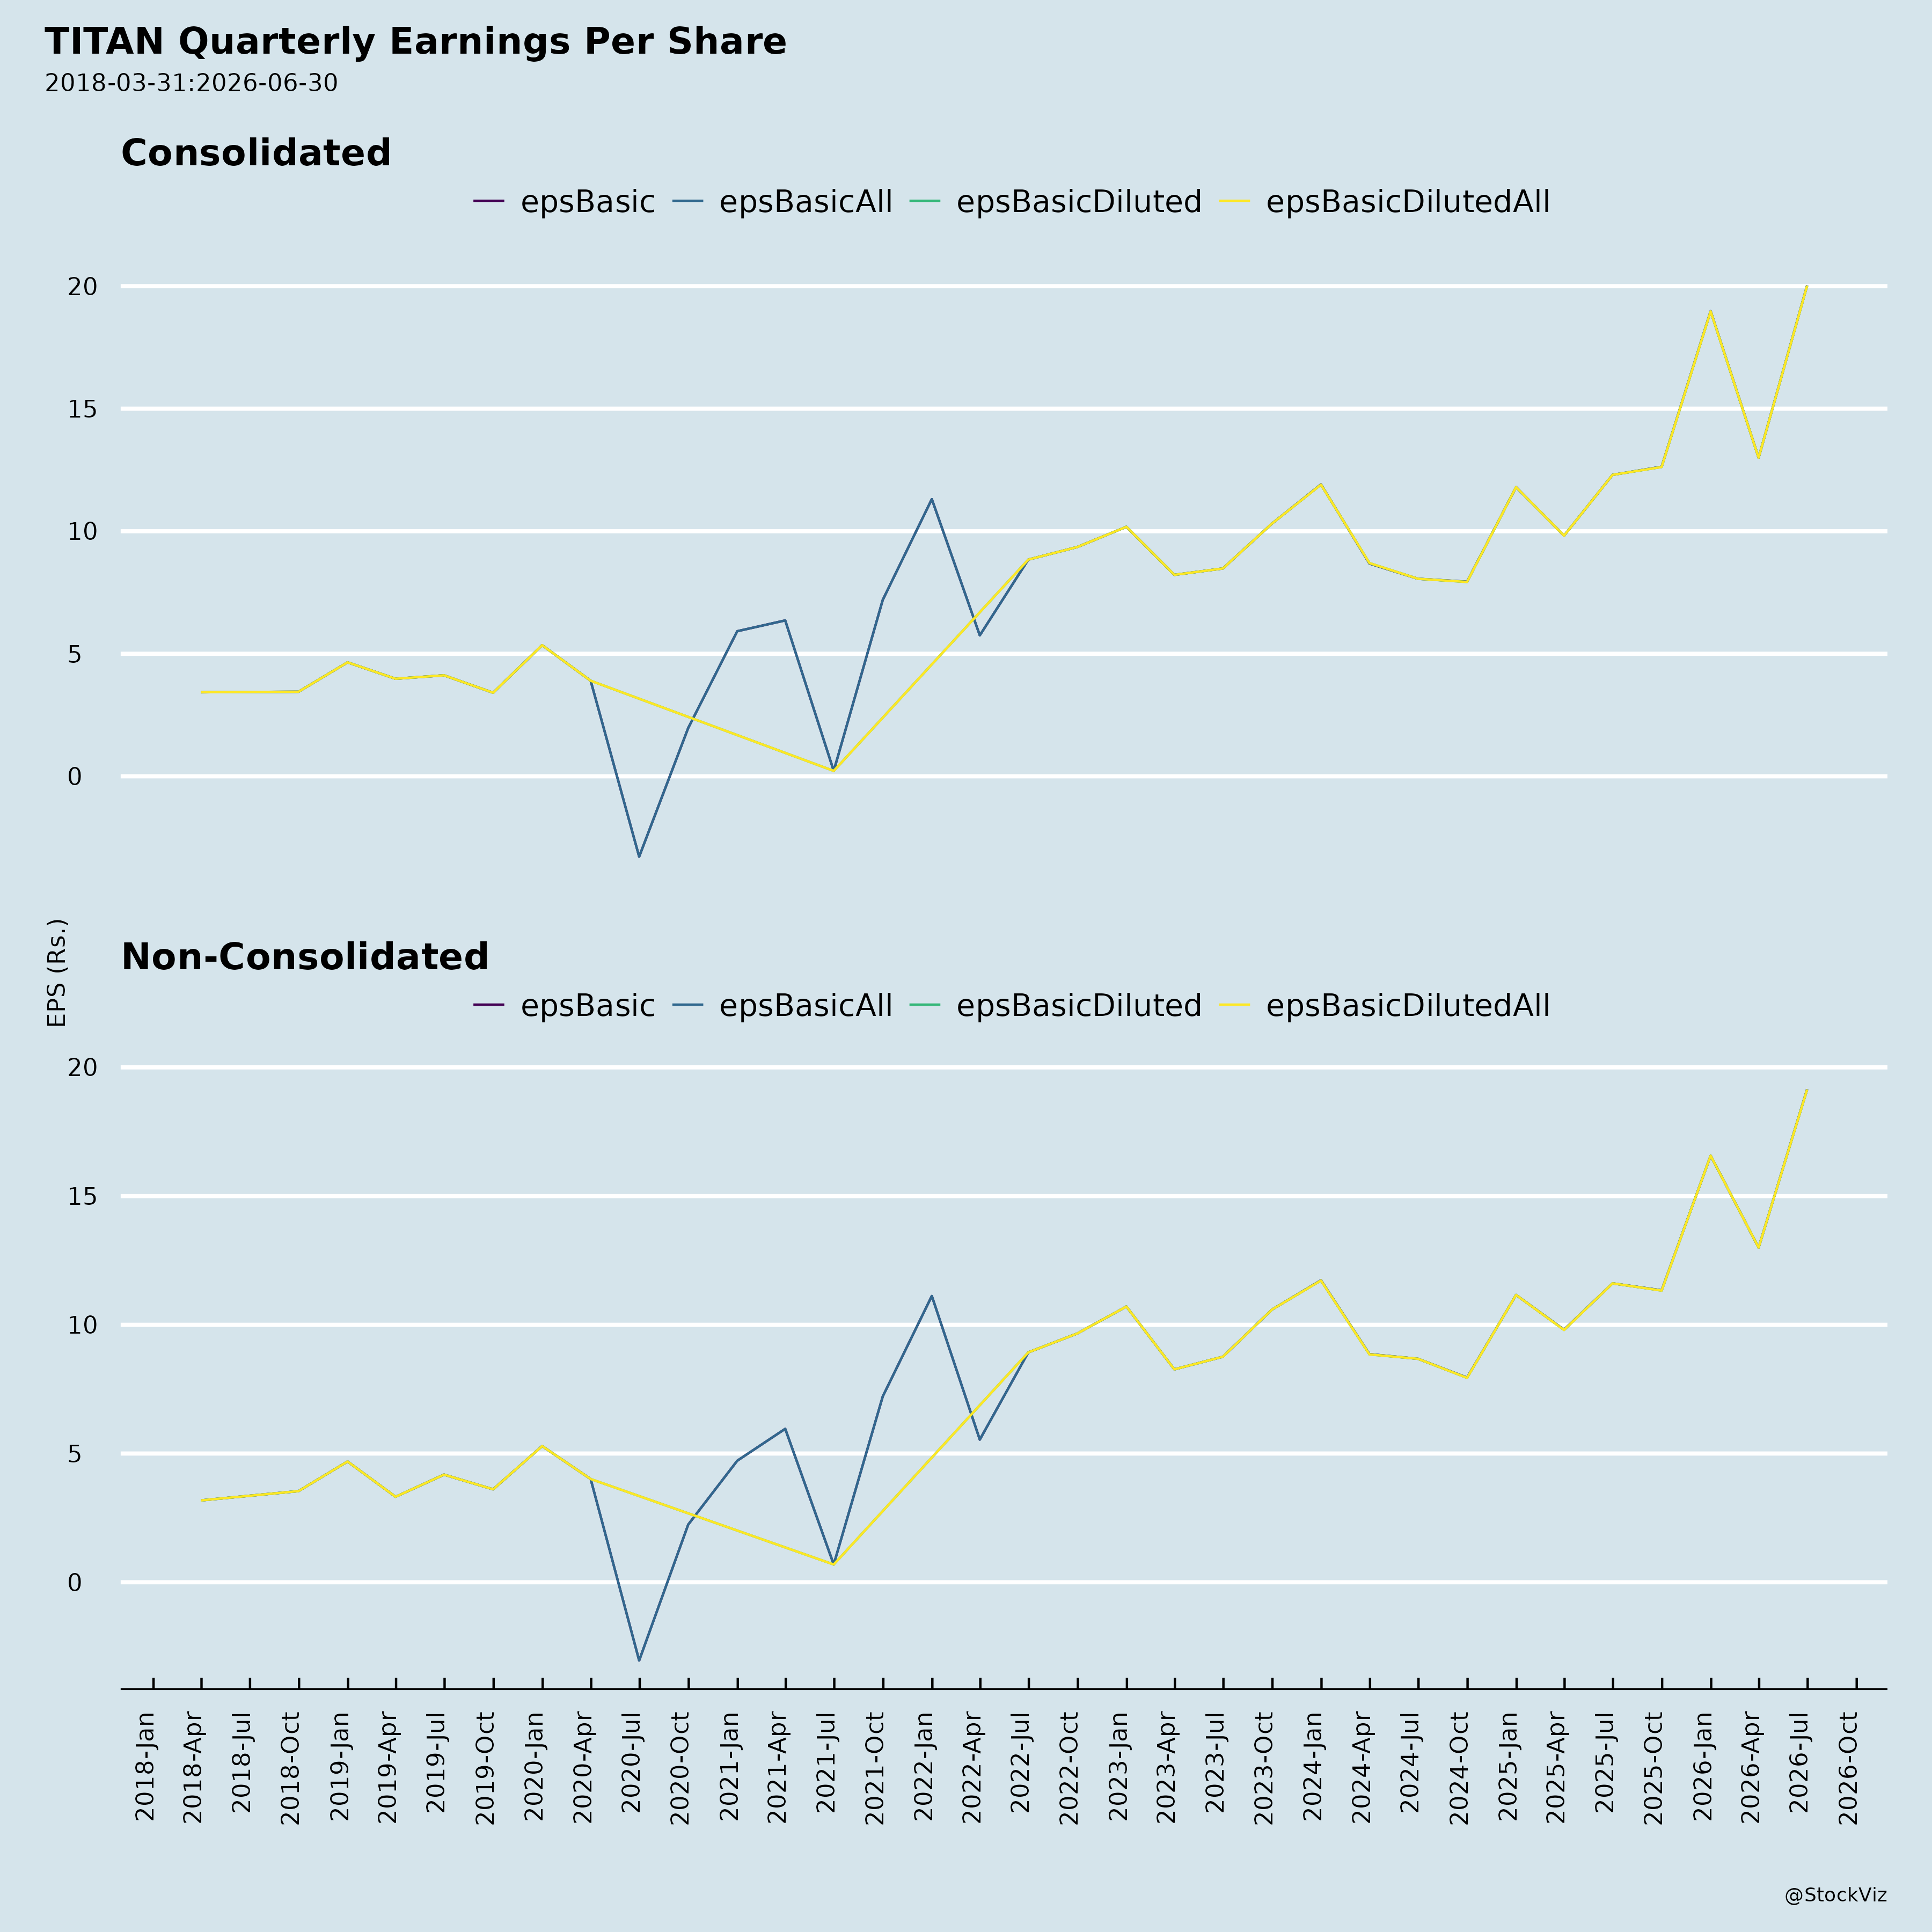
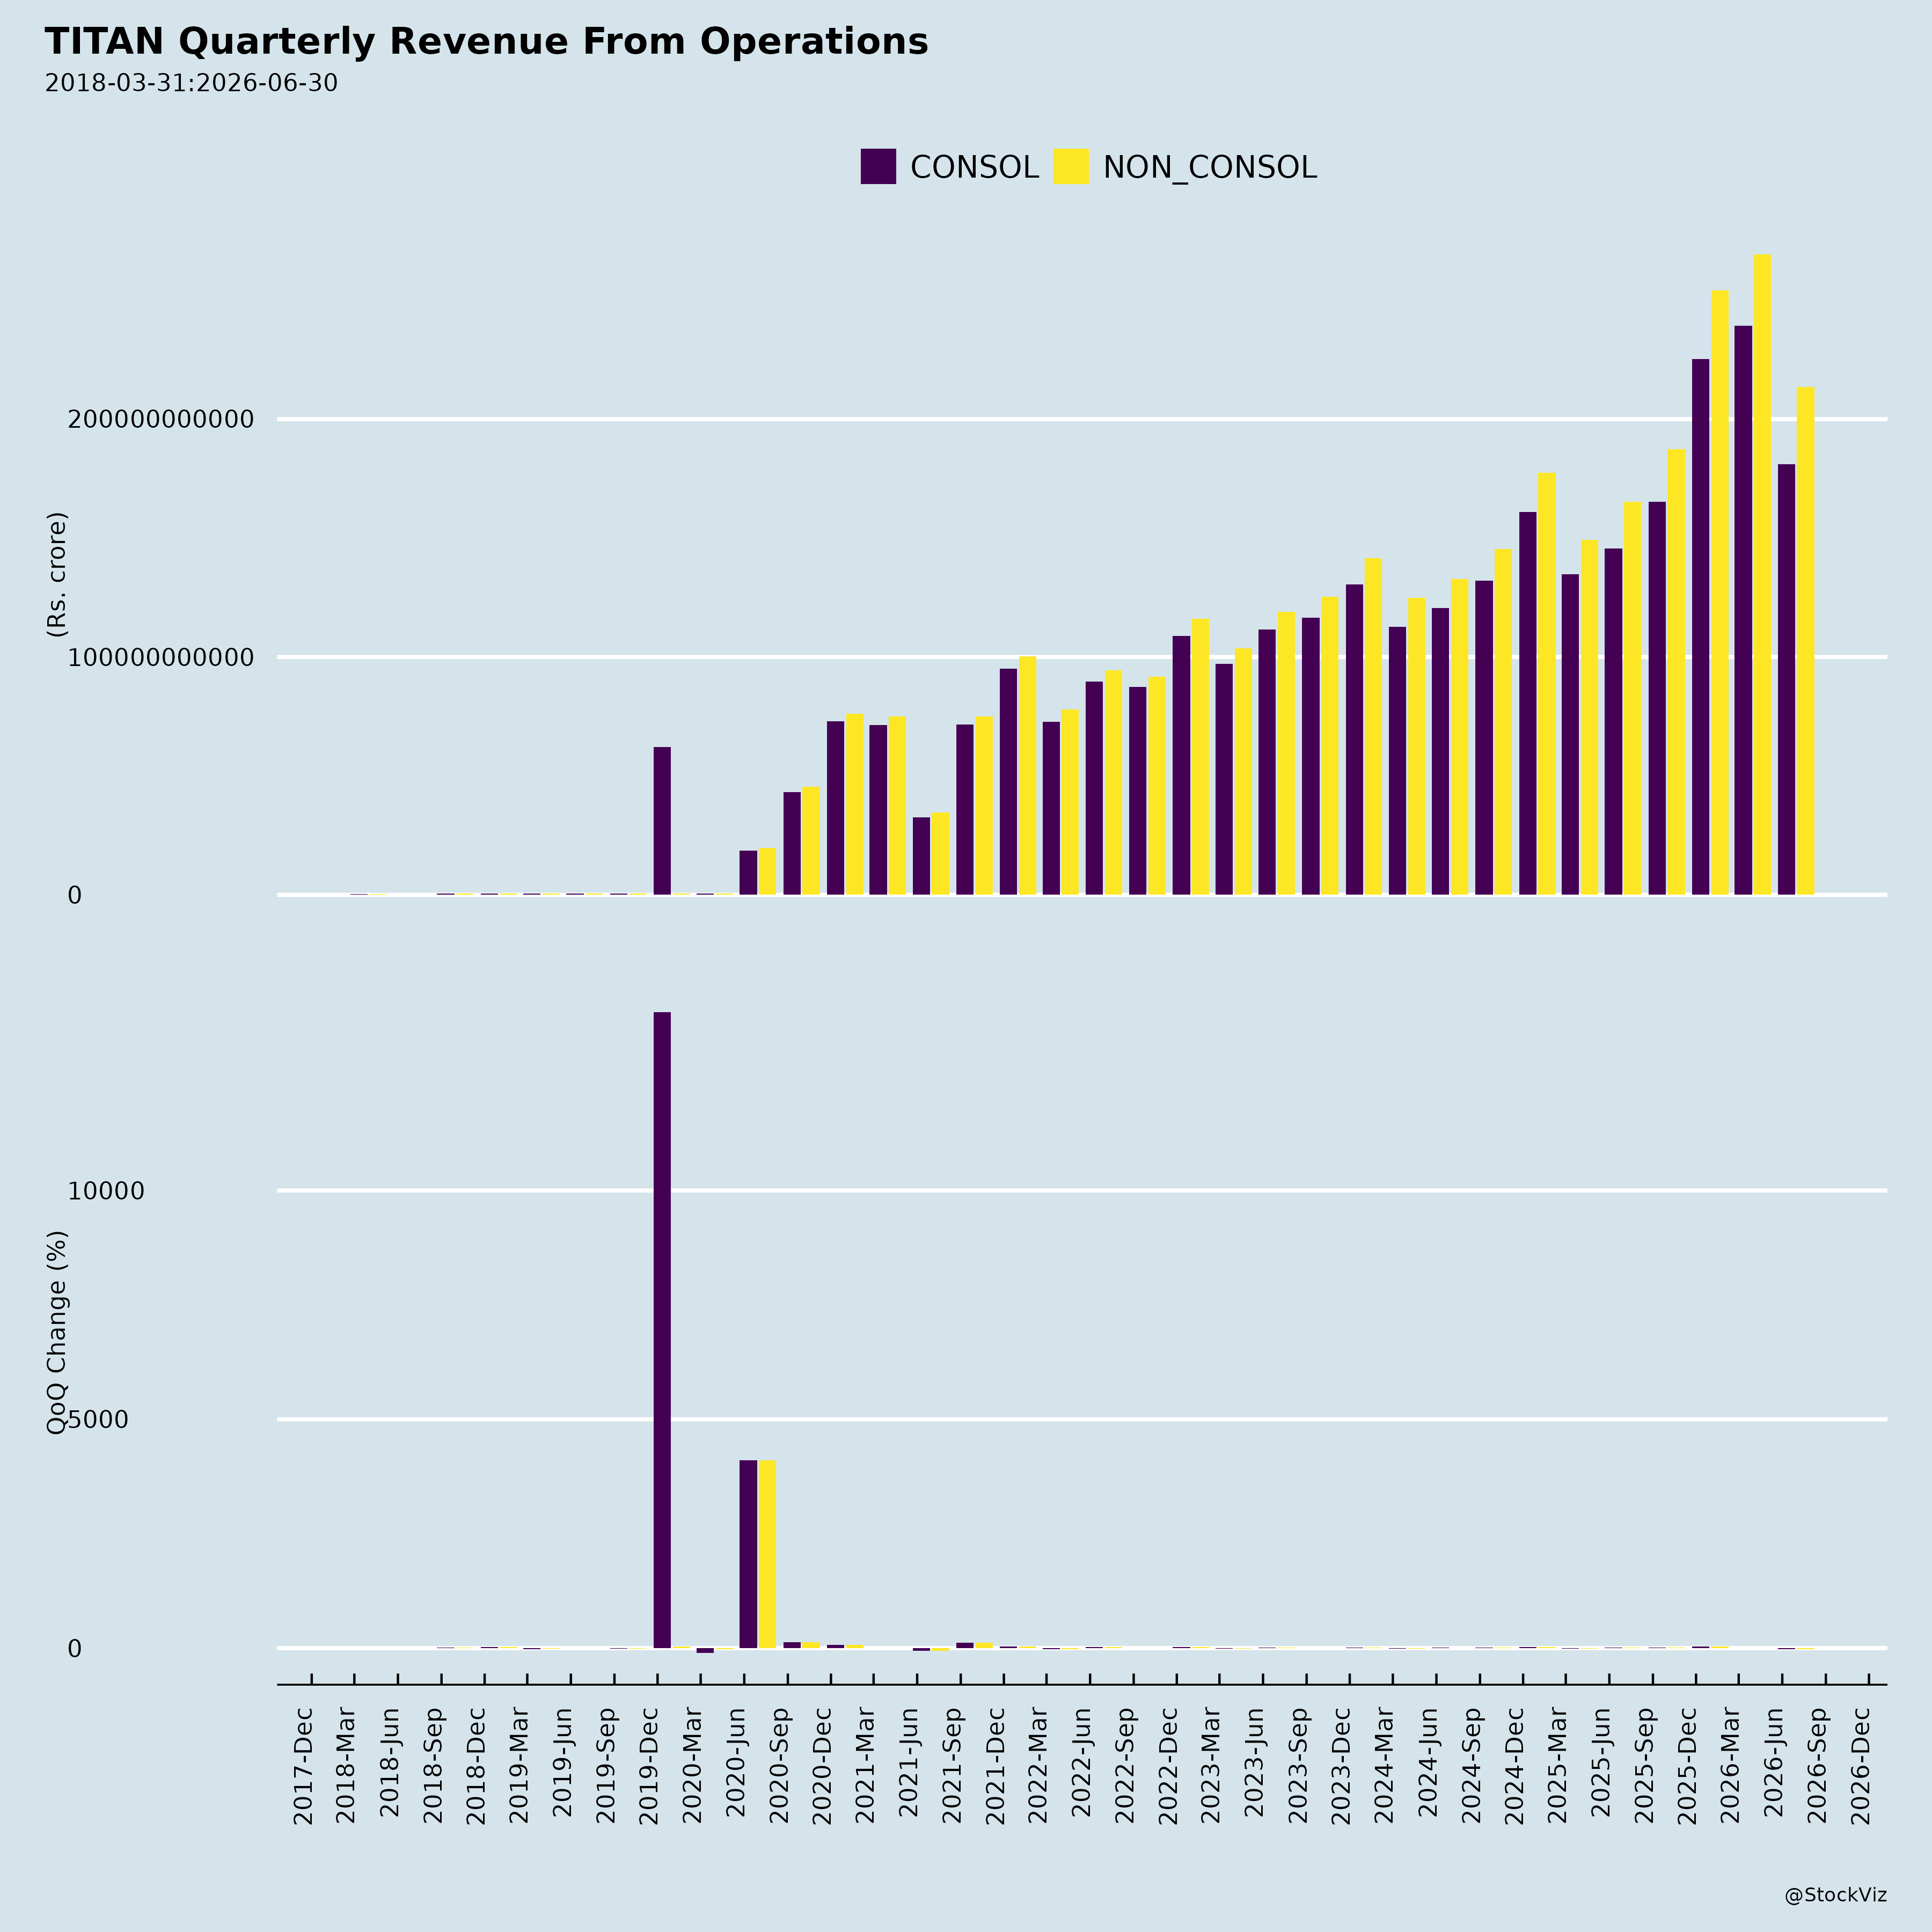
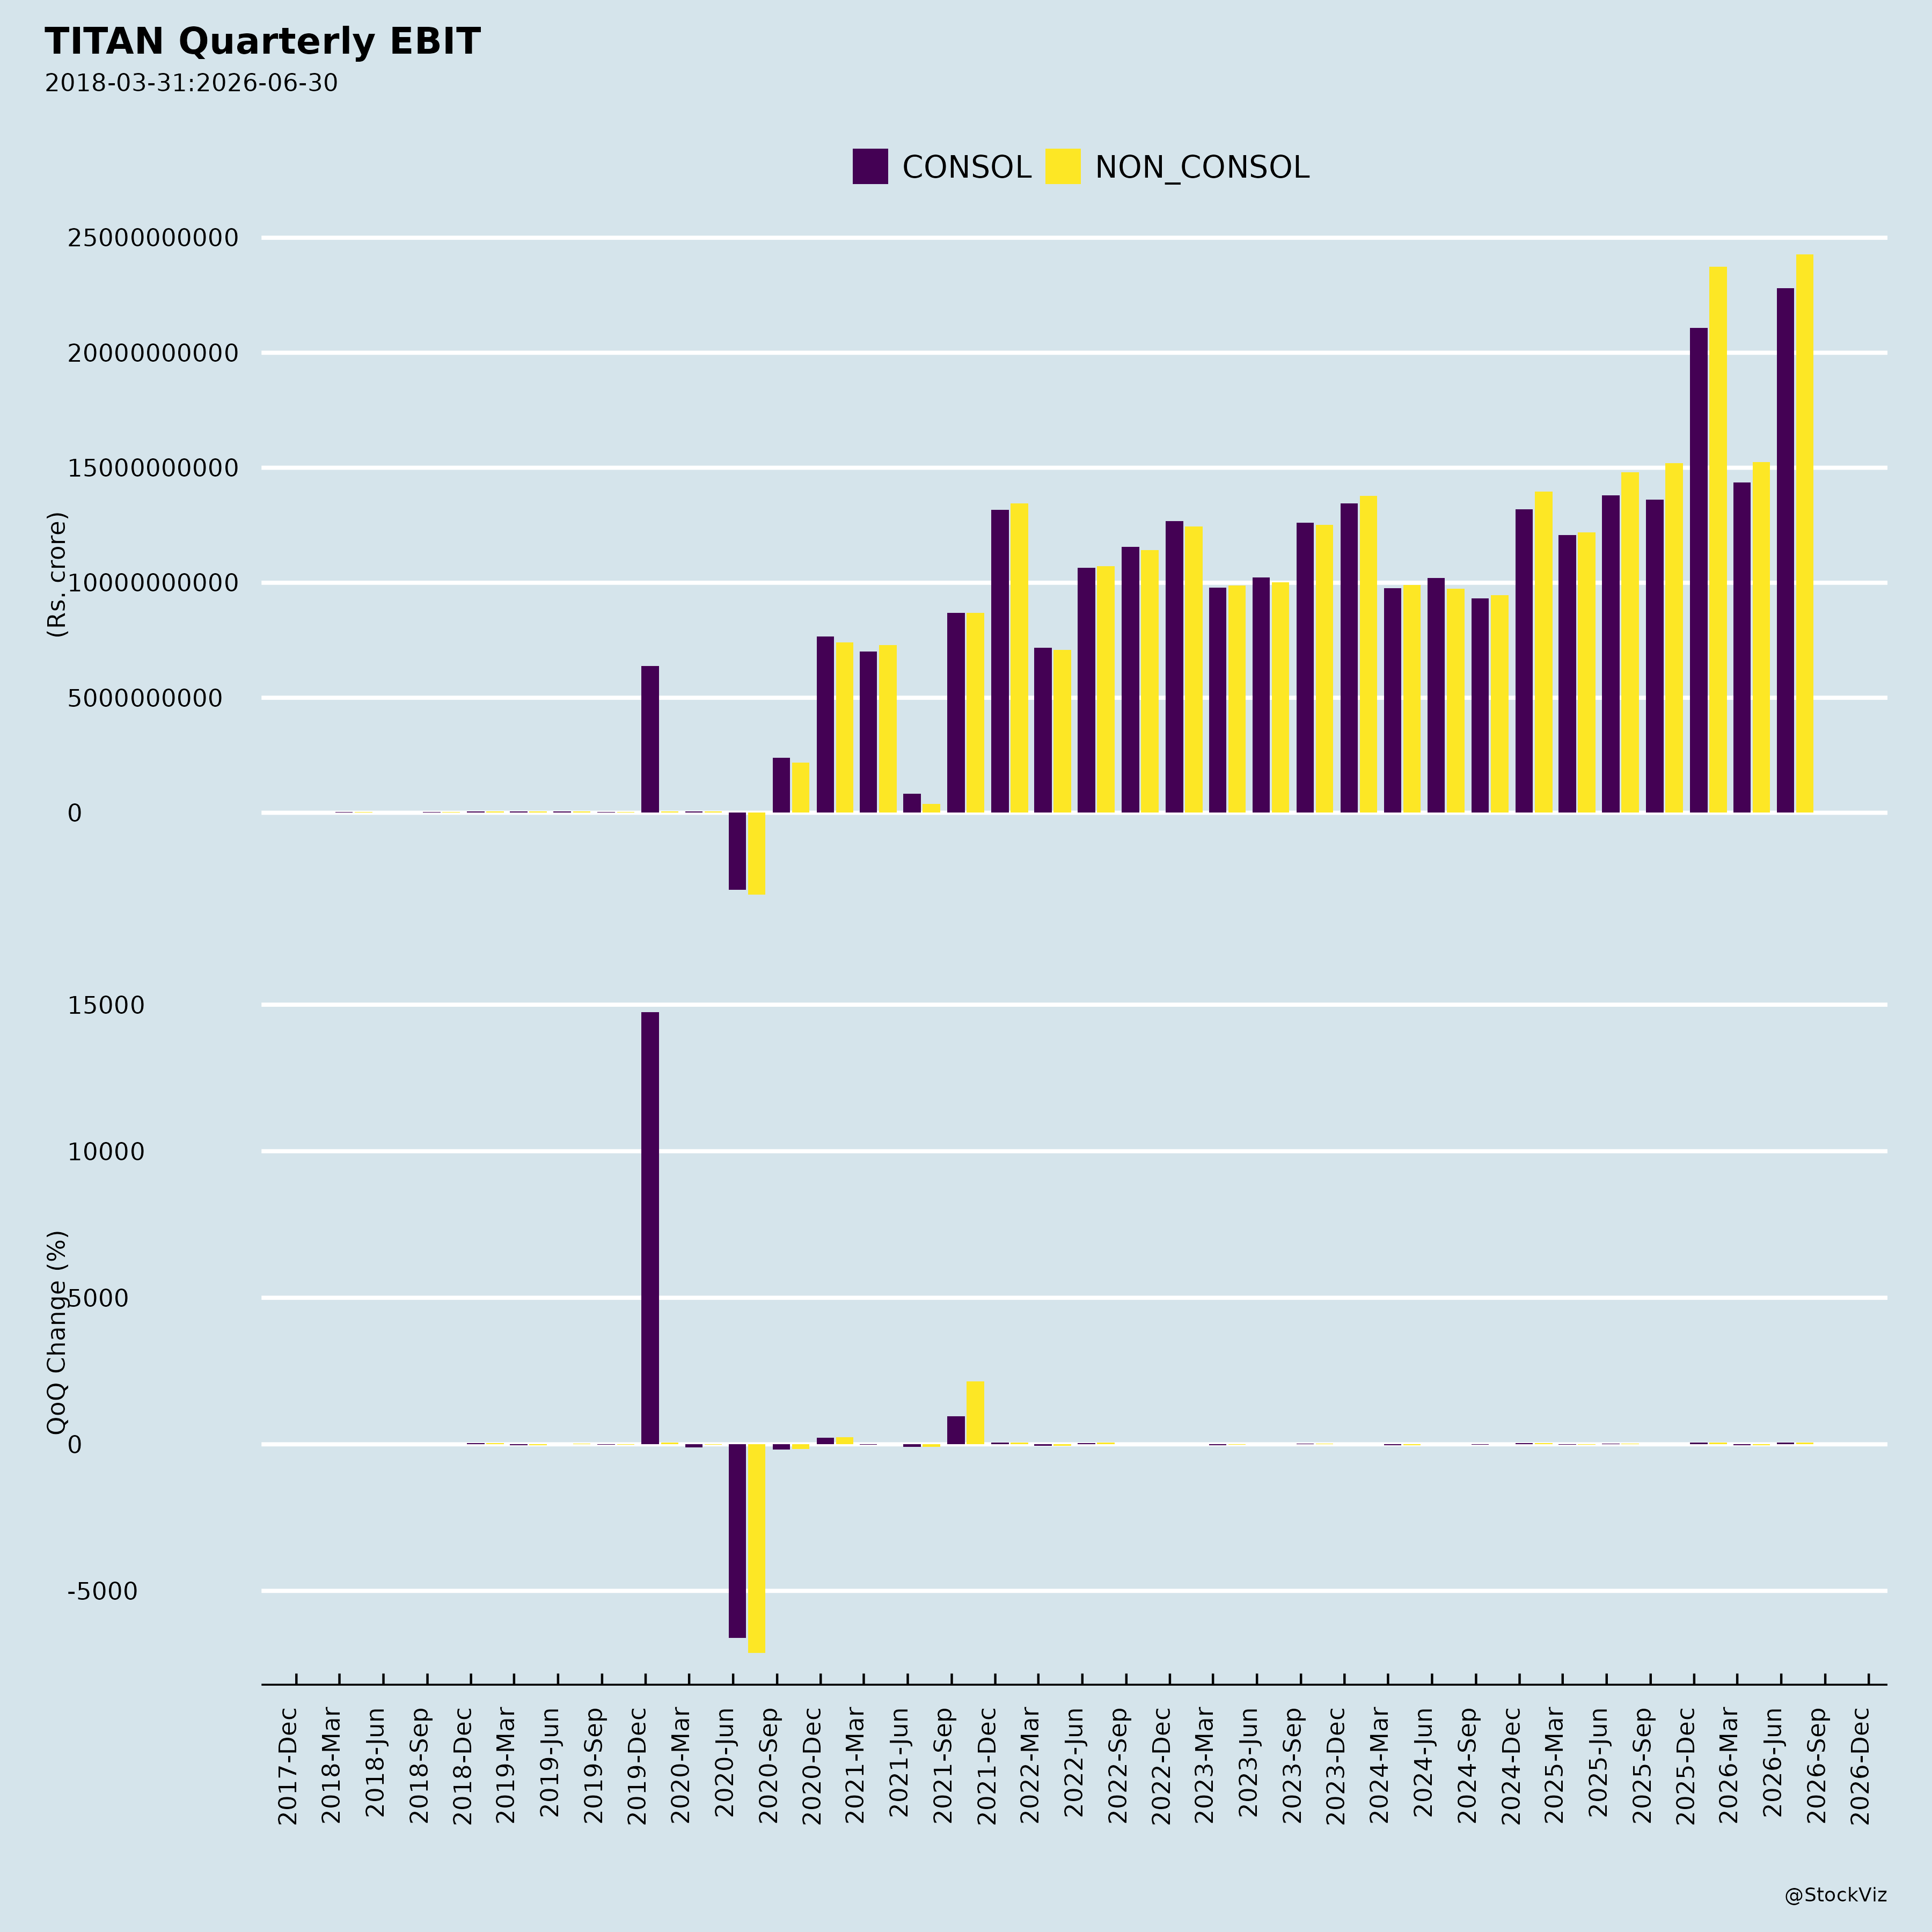
- Strong Q1FY27 performance: Consumer Businesses registered 40% YoY growth in Q1FY27. Total income reached ₹21,502 crores (up 29% YoY) and reported consolidated PAT was ₹1,777 crores (up 62.9% YoY). TTM Profit After Tax stands at ₹58 bn.
- Demand environment: Healthy Akshaya Tritiya and wedding-led demand supported the quarter.
- Premiumisation: Portfolio premiumisation trends are noted across Jewellery, Watches and EyeCare.
- Network expansion: Ongoing network expansion is cited as a growth lever.
- TEAL business: Strong performance in the TEAL business is highlighted.
- International expansion: The Board approved incorporation of a wholly owned subsidiary in Canada for entry of the Tanishq business into Canada, with additional disclosures to follow once incorporated.
- Employee alignment: The proposed Scheme 2026 (up to 15,00,000 PSUs, ~0.17% of paid-up equity capital as on 30 June 2026) is intended to align employee interests with long-term shareholder value, support retention, and reward performance, with vesting tied to NSV/EBIT-based company, business and individual parameters over a performance period of three financial years (not exceeding five years from grant).
3. Key Risks
- Performance-linked vesting risk: PSU vesting under Scheme 2026 depends on achievement of targets; below 85% or 90% of target achievement (based on applicable business division criteria) results in no vesting, and between thresholds vesting is proportionate.
- Attrition/forfeiture conditions: Unvested PSUs lapse or terminate on resignation, breach of policy, or violation of post-employment obligations; vested but unexercised PSUs also terminate on certain breaches.
- Execution and external environment: Management’s stated focus on disciplined execution sits alongside acknowledged gold price, duty structure and geopolitical uncertainties.
- No fresh capital issuance: Scheme 2026 is to be implemented only through secondary acquisition by the Titan Employee Stock Option Trust, with no fresh shares issued; the Trust will not exercise voting rights on shares it holds.
- Dilution consideration: The company states there will be no equity dilution for shareholders, as shares available with the Trust plus secondary acquisitions fall within the overall 15,00,000 share limit under Scheme 2026.
4. Management Guidance Versus Observed Performance
- Management states it remains focused on brand investment, customer engagement and disciplined execution, aiming to continue its growth journey, while noting it does not undertake to update forward-looking statements.
- Observed Q1FY27 performance shows total income up 29% YoY, consolidated PAT up 62.9% YoY, and Consumer Businesses up 40% YoY, alongside healthy festive/wedding demand and premiumisation trends.
- For investor meetings scheduled on 10 September 2026 (UBS Conference) and 11 September 2026 (Axis Conference), management stated that no price sensitive information or forward-looking statements would be disclosed or discussed.
- The company fully redeemed Commercial Papers worth ₹1,000 crore (ISIN: INE280A14575, issued 12 June 2026), with maturity proceeds paid to all holders as of 10 September 2026.
- Scheme 2026 follows the conclusion of the Scheme 2023 performance period (FY2023–2026); under Scheme 2023, 2,51,276 PSUs remained outstanding for vesting/exercise as of the notice date, with 2,51,276 equity shares earmarked, and the Trust held 4,38,347 equity shares.
Broker Narrative
The narrative evolved from an eyewear-led thesis in 2023 built on under-penetration, franchisee expansion and backward integration into a broader multi-pillar story by 2026 spanning jewellery, watches and TEAL as a third growth engine. Competitive intensity persisted, shifting from online eyewear discounters and Lenskart to regional jewellers with pricing flexibility, while margin pressure remained constant and was compounded by gold-price MTM volatility. Valuation optimism anchored to Lenskart comparables gave way to segment-margin guidance, TEAL order-book strength and FY27-29 EPS CAGR expectations.
Fears that came true
- Early fears that online eyewear competition and deep discounts would hurt profitability materialized as eyewear margins contracted 346bps YoY to 9%, aligning with negative actual returns such as minus 17.6% in March 2024.
- The risk that unorganized players would lure value-conscious buyers with low pricing persisted as competitive intensity from regional jewellers retaining inventory gains with pricing flexibility, coinciding with disappointing outcomes like Centrum’s minus 1.8% actual return in February 2024.
- The franchisee-store quality risk resurfaced through compressed eyewear economics despite network expansion, showing asset-light growth did not shield margins and reflecting in multiple DISAPPOINTMENT outcomes across 2024 and 2025.
Optimism that failed
- The view that backward integration into frames and lenses would lower costs and protect profitability failed as eyewear margins contracted 346bps YoY to 9%, indicating cost gains were overwhelmed by competitive pricing.
- The thesis that the eyecare profitability turnaround from minus 2.6% in FY20 to 14.2% in FY23 would sustain failed, with the latest report showing eyewear margins down to 9% despite only tentative calls for improving economics.
- The valuation uplift case pegging Titan Eye+ at roughly 126 rupees per share based on Lenskart’s USD 4.5 billion valuation failed to materialize because persistent competition and margin erosion prevented the expected premium rerating.
Broker Timeline
54 broker calls · 2023-07-12 to 2026-11-06
CNBC-TV18: ratings, targets and commentary
No recorded CNBC-TV18 statements for this ticker.
Copyright © 2023 SAS Data Analytics Pvt. Ltd. All rights reserved.