THELEELA
Equity Metrics
November 18, 2026
Leela Palaces Hotels & Resorts Limited
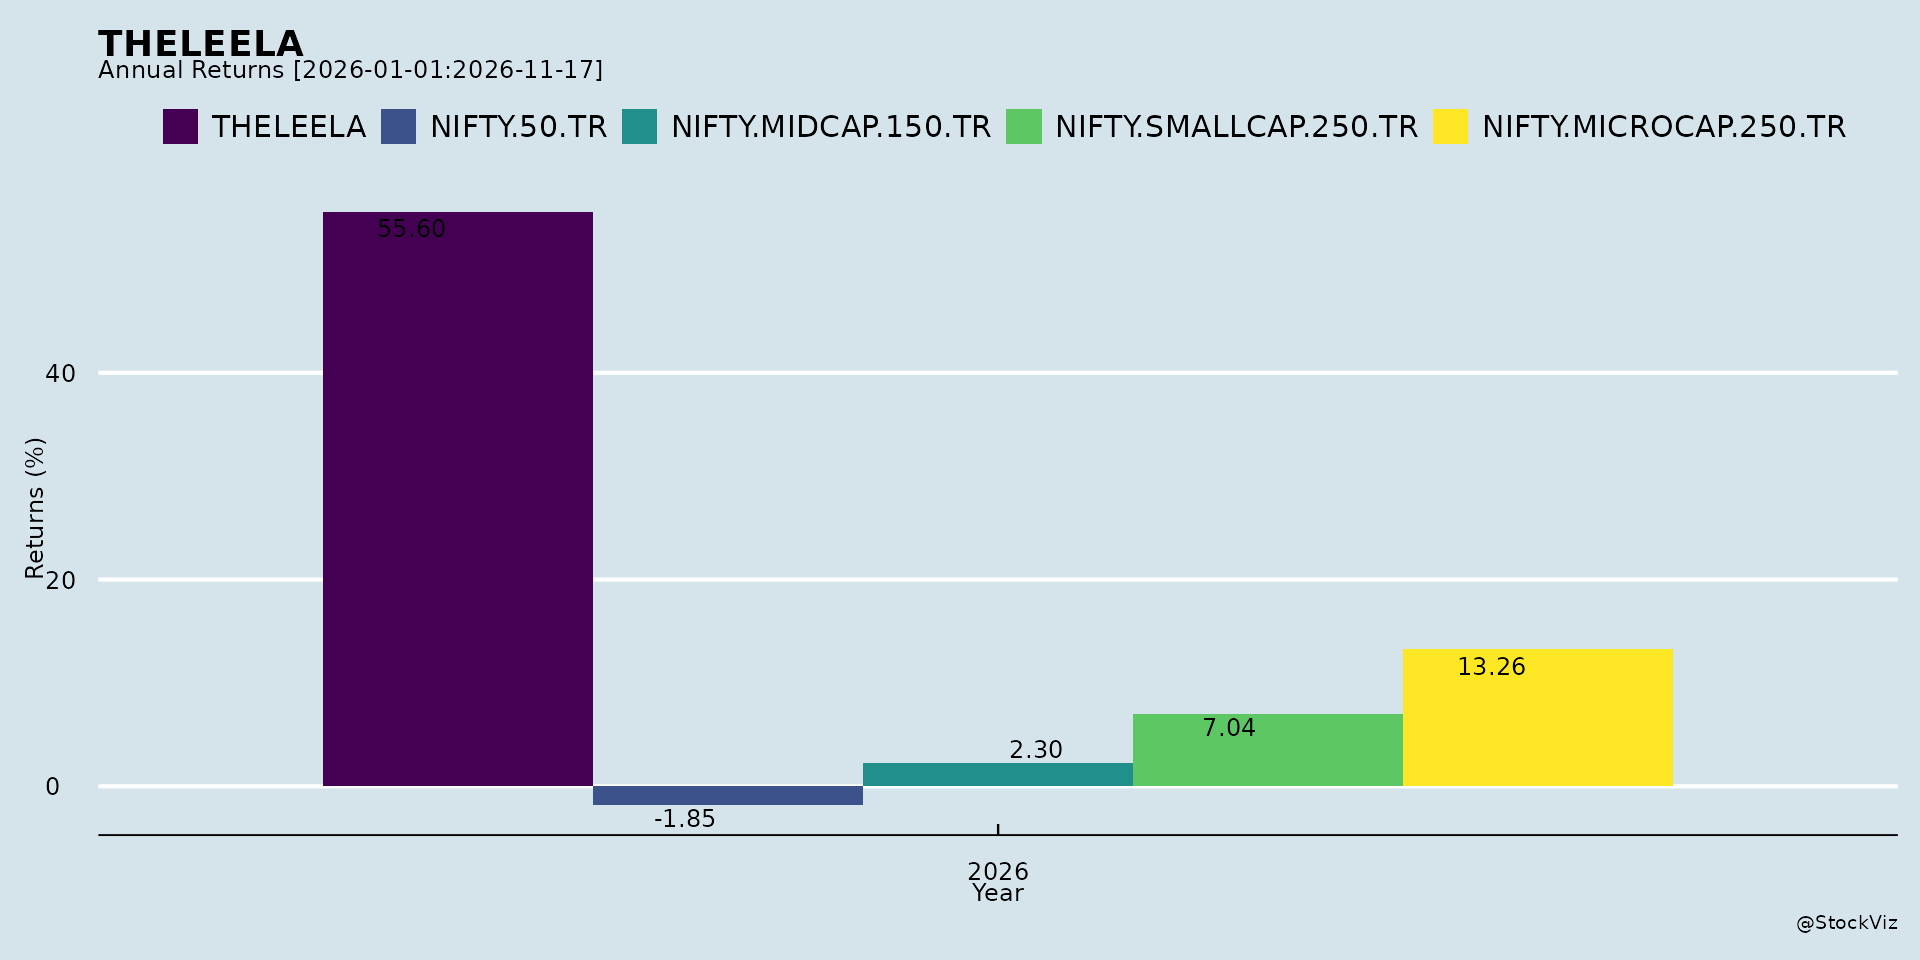
Annual Returns

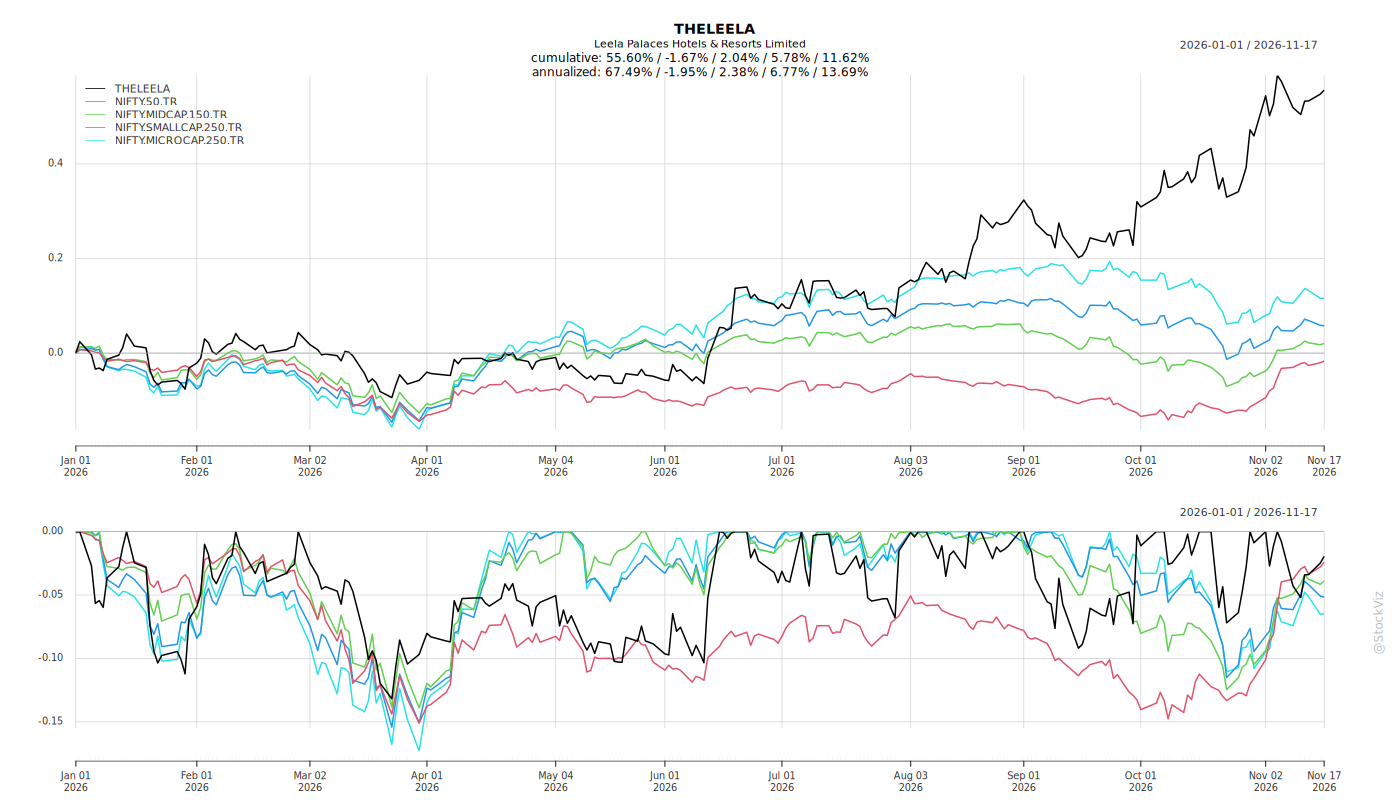
Cumulative Returns and Drawdowns
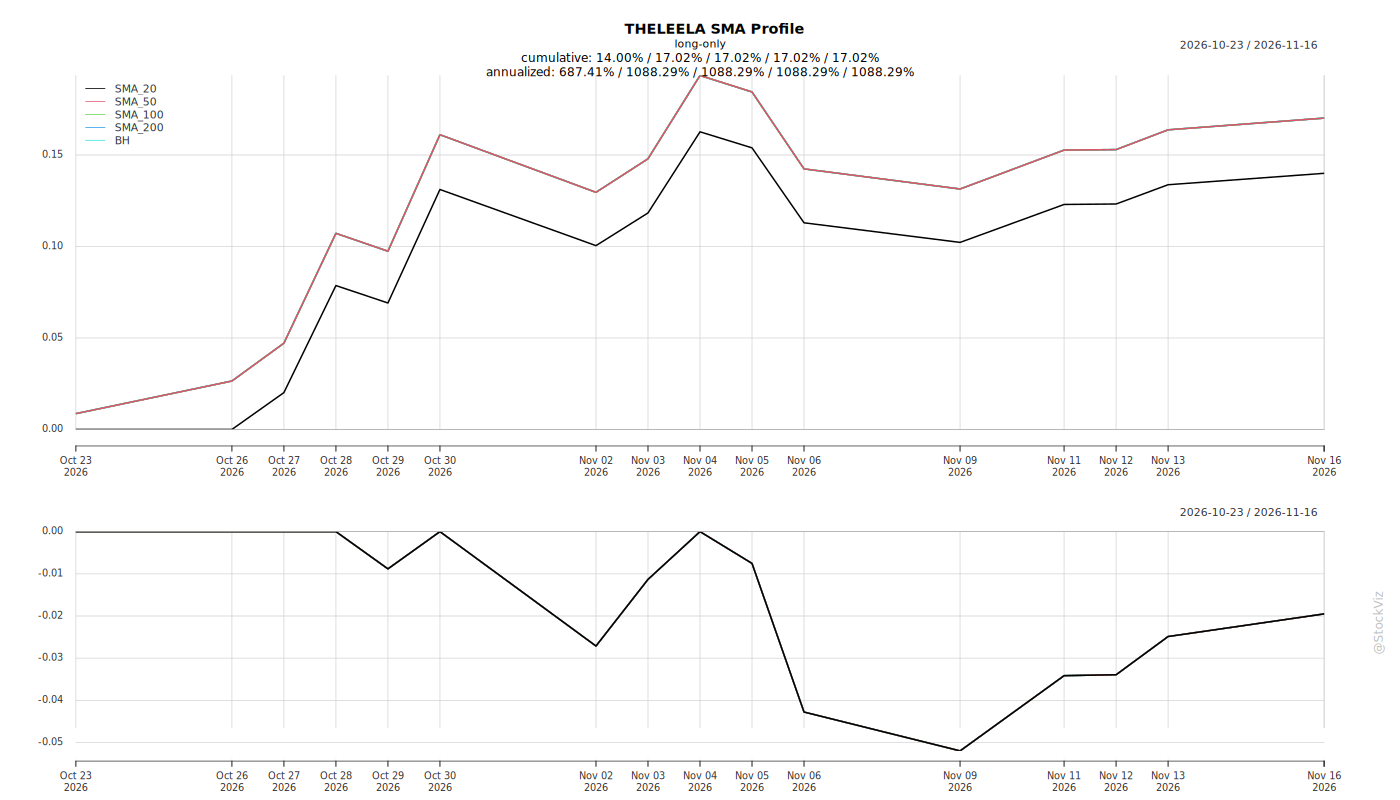
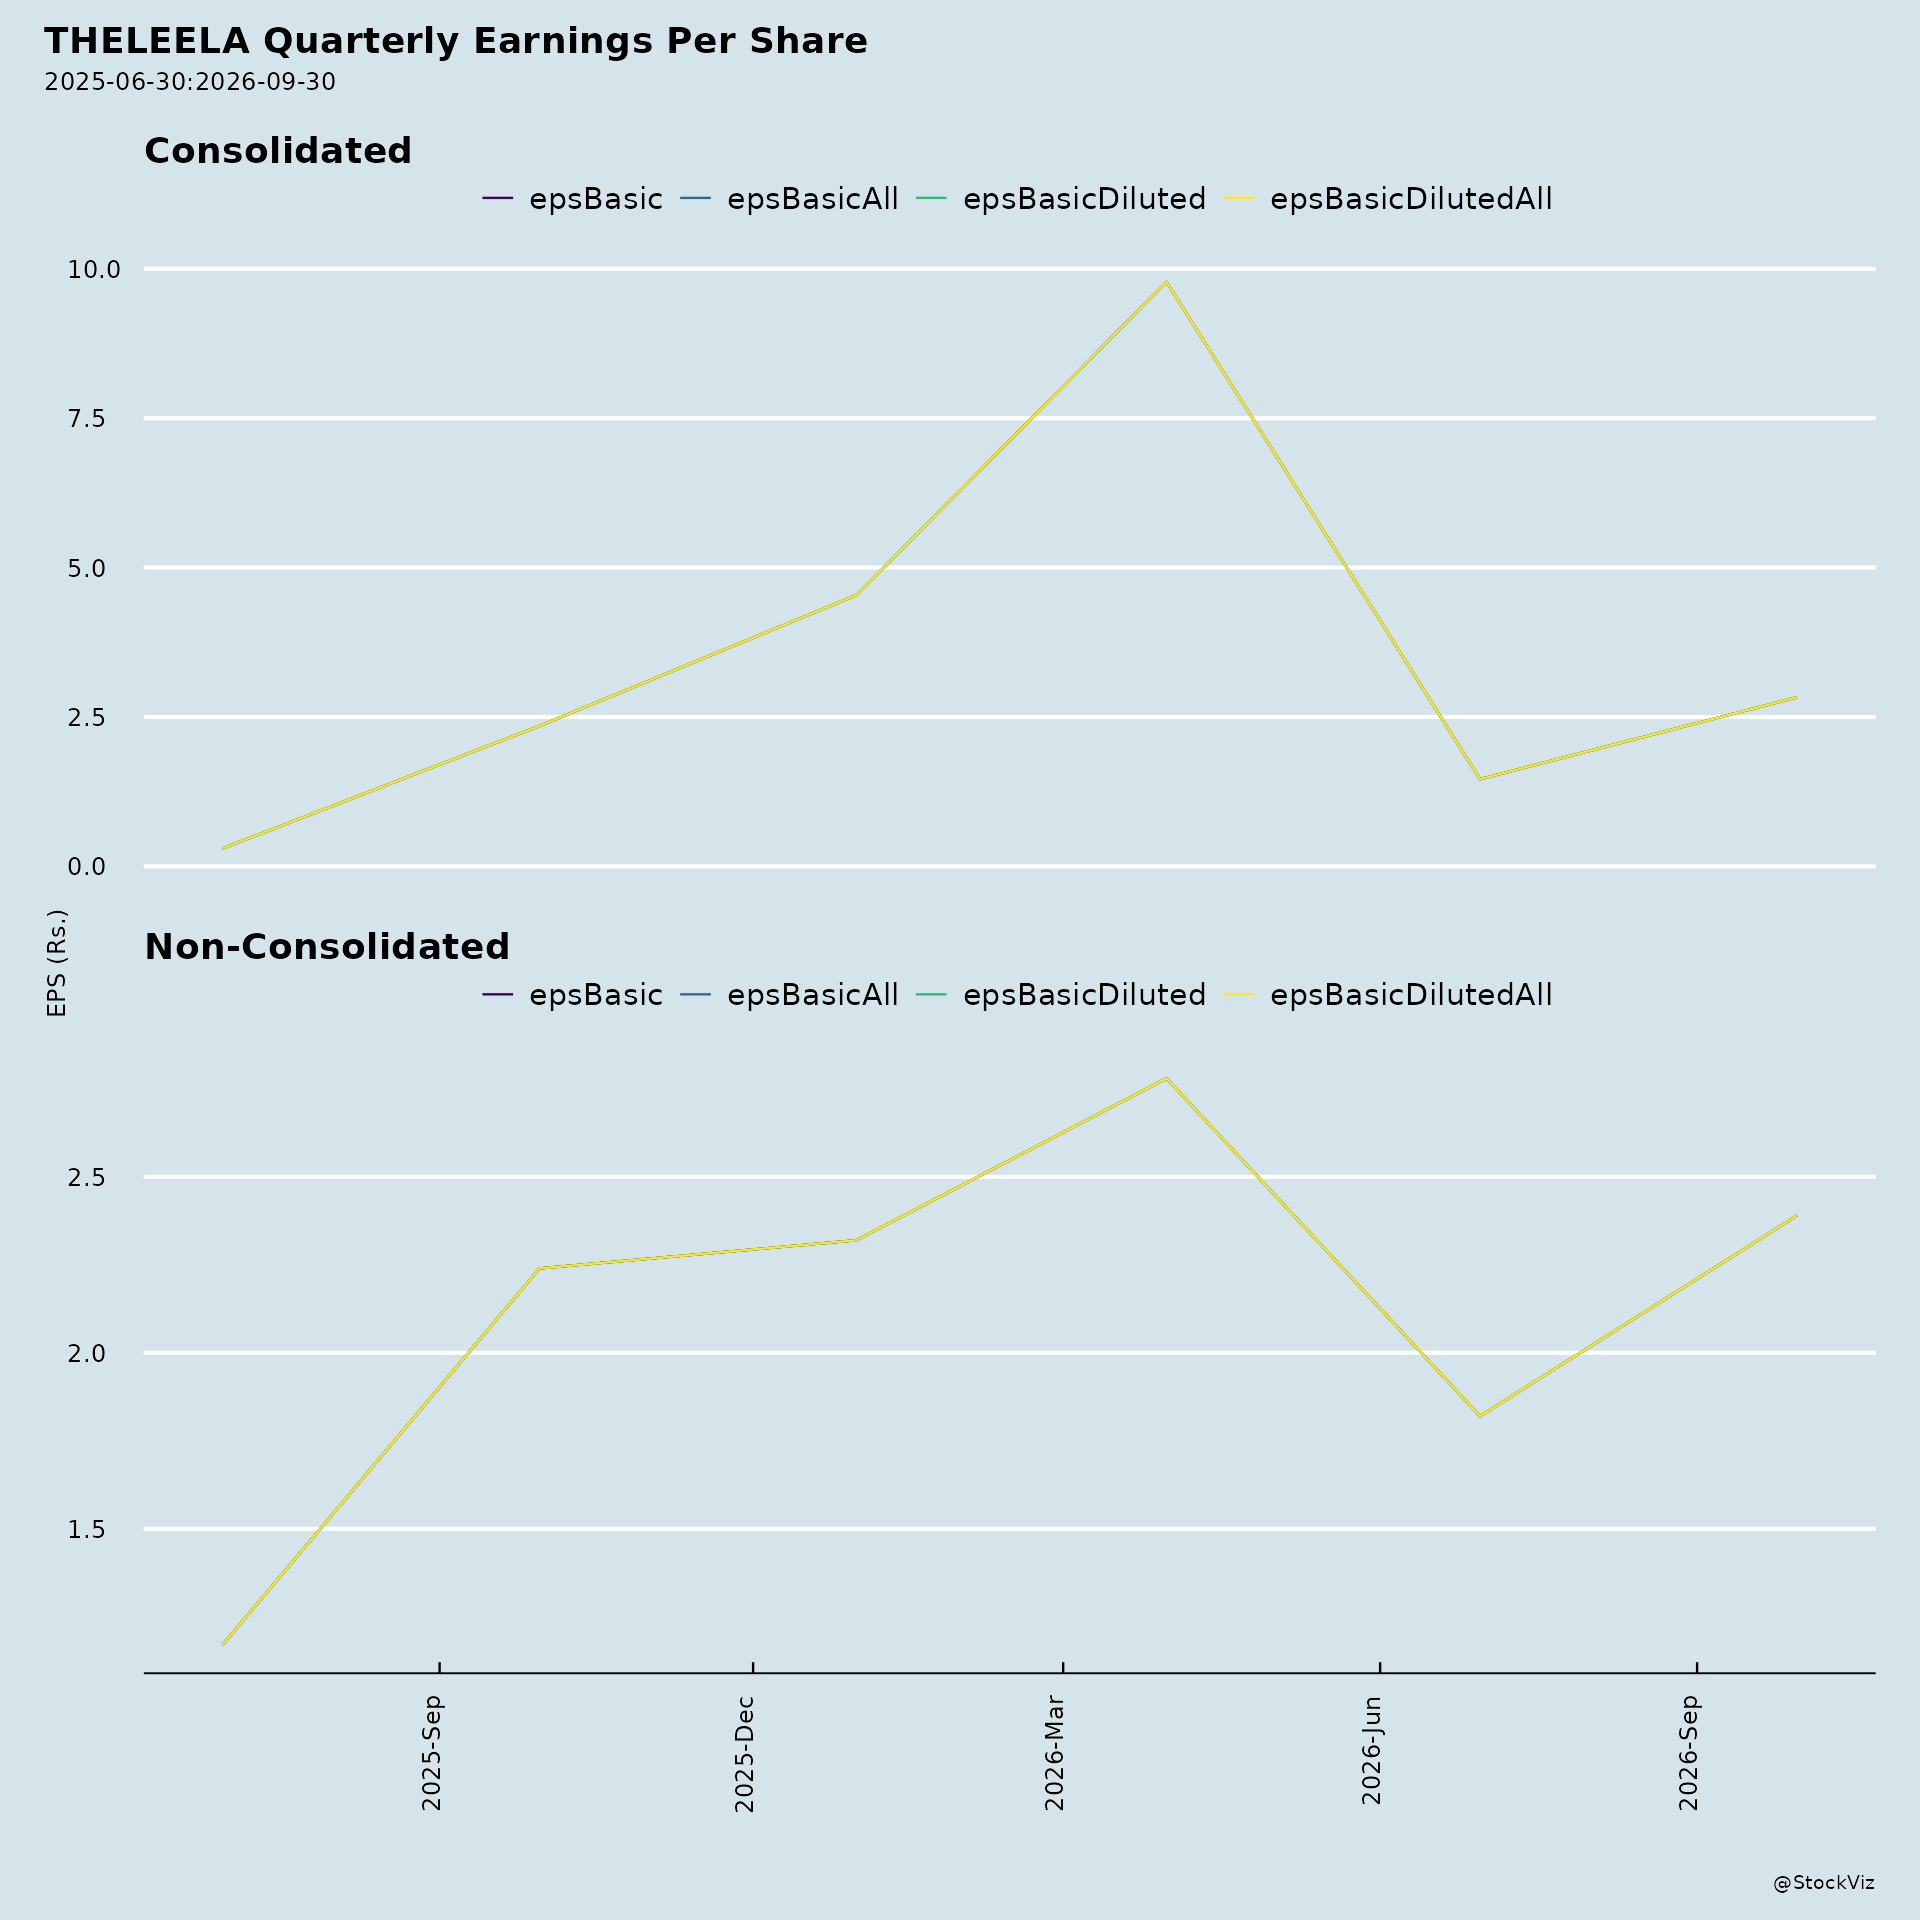
Fundamentals
Ownership
Margined
AI Summary
asof: 2026-09-16
Headwinds and Challenges
- Temporary international travel headwinds. The Q1 FY27 press release states that RevPAR growth of 17% was achieved “despite temporary international travel headwinds.” The earnings presentation notes that “Domestic Demand Offset Temporary FTA Impact” and that “International Mix has Significantly Recovered by June.”
- Dubai market disruption. The Q1 FY27 presentation attributes a loss in the share of profit of joint ventures to “Temporary Dubai market headwinds from West-Asia conflict,” which affected JV profit and is “expected to ease as regional travel normalizes.” Consolidated share of net (loss)/profit of joint ventures and associate was negative ₹156.15 million in Q1 FY27 versus positive ₹0.87 million in Q1 FY26.
- Lower other income. Consolidated other income fell 68% year-on-year to ₹85.45 million in Q1 FY27 from ₹265.40 million in Q1 FY26, which the presentation links to the prior-year period including IPO-related inflows.
- Seasonality. The standalone and consolidated results notes state that “in view of the seasonality of the sector, the financial results for the quarters are not indicative of the full year’s expected performance.” The quarterly KPI table shows occupancy and ADR peaking in Q3 and Q4 and moderating in Q1.
- Labour Codes implementation. The Government of India notified four Labour Codes on November 21, 2025. The Company restructured employee compensation and recognised an incremental impact of ₹16.40 million (standalone) and ₹64.00 million (consolidated) as exceptional items in FY26. The Company continues to monitor finalisation of Central/State Rules and may provide further accounting effects.
- Regulatory delay in disclosure. The August 11, 2026 intimation regarding the Equirus India Growth Summit notes that “the delay in informing about the investor meet is due to challenges in finalising the meeting schedule and confirming the availability of participants.”
Tailwinds and Growth Prospects
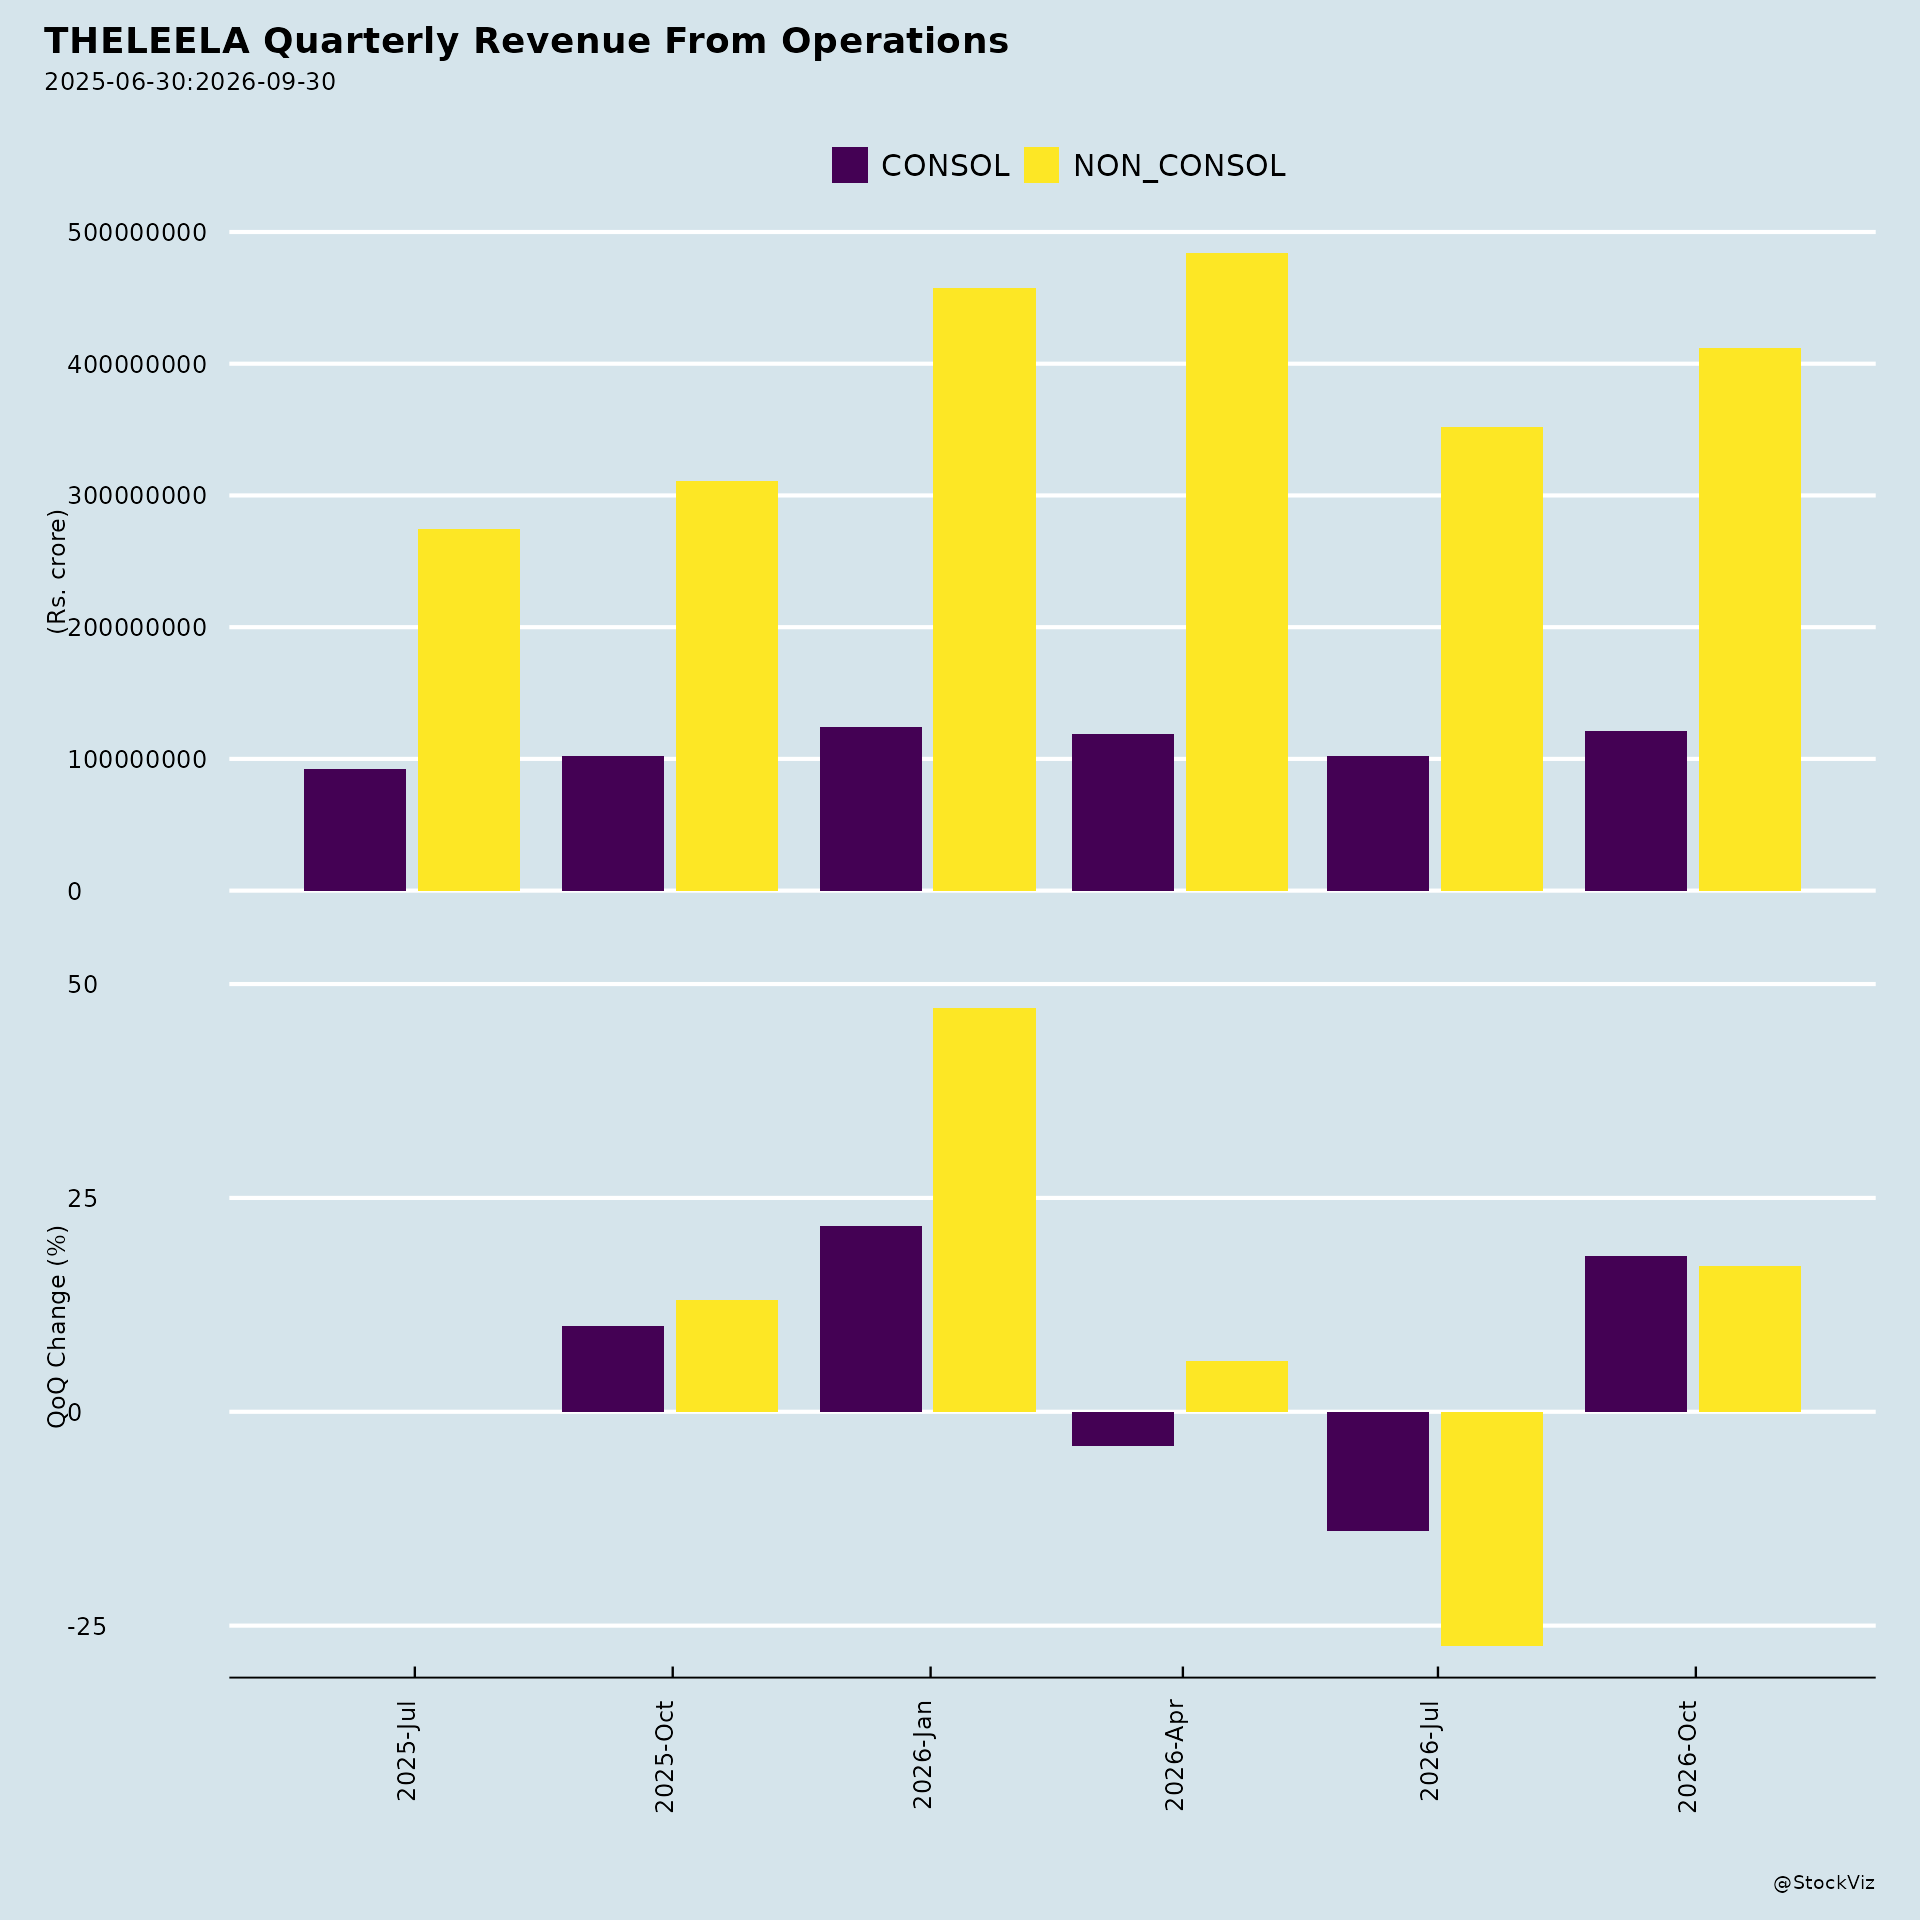
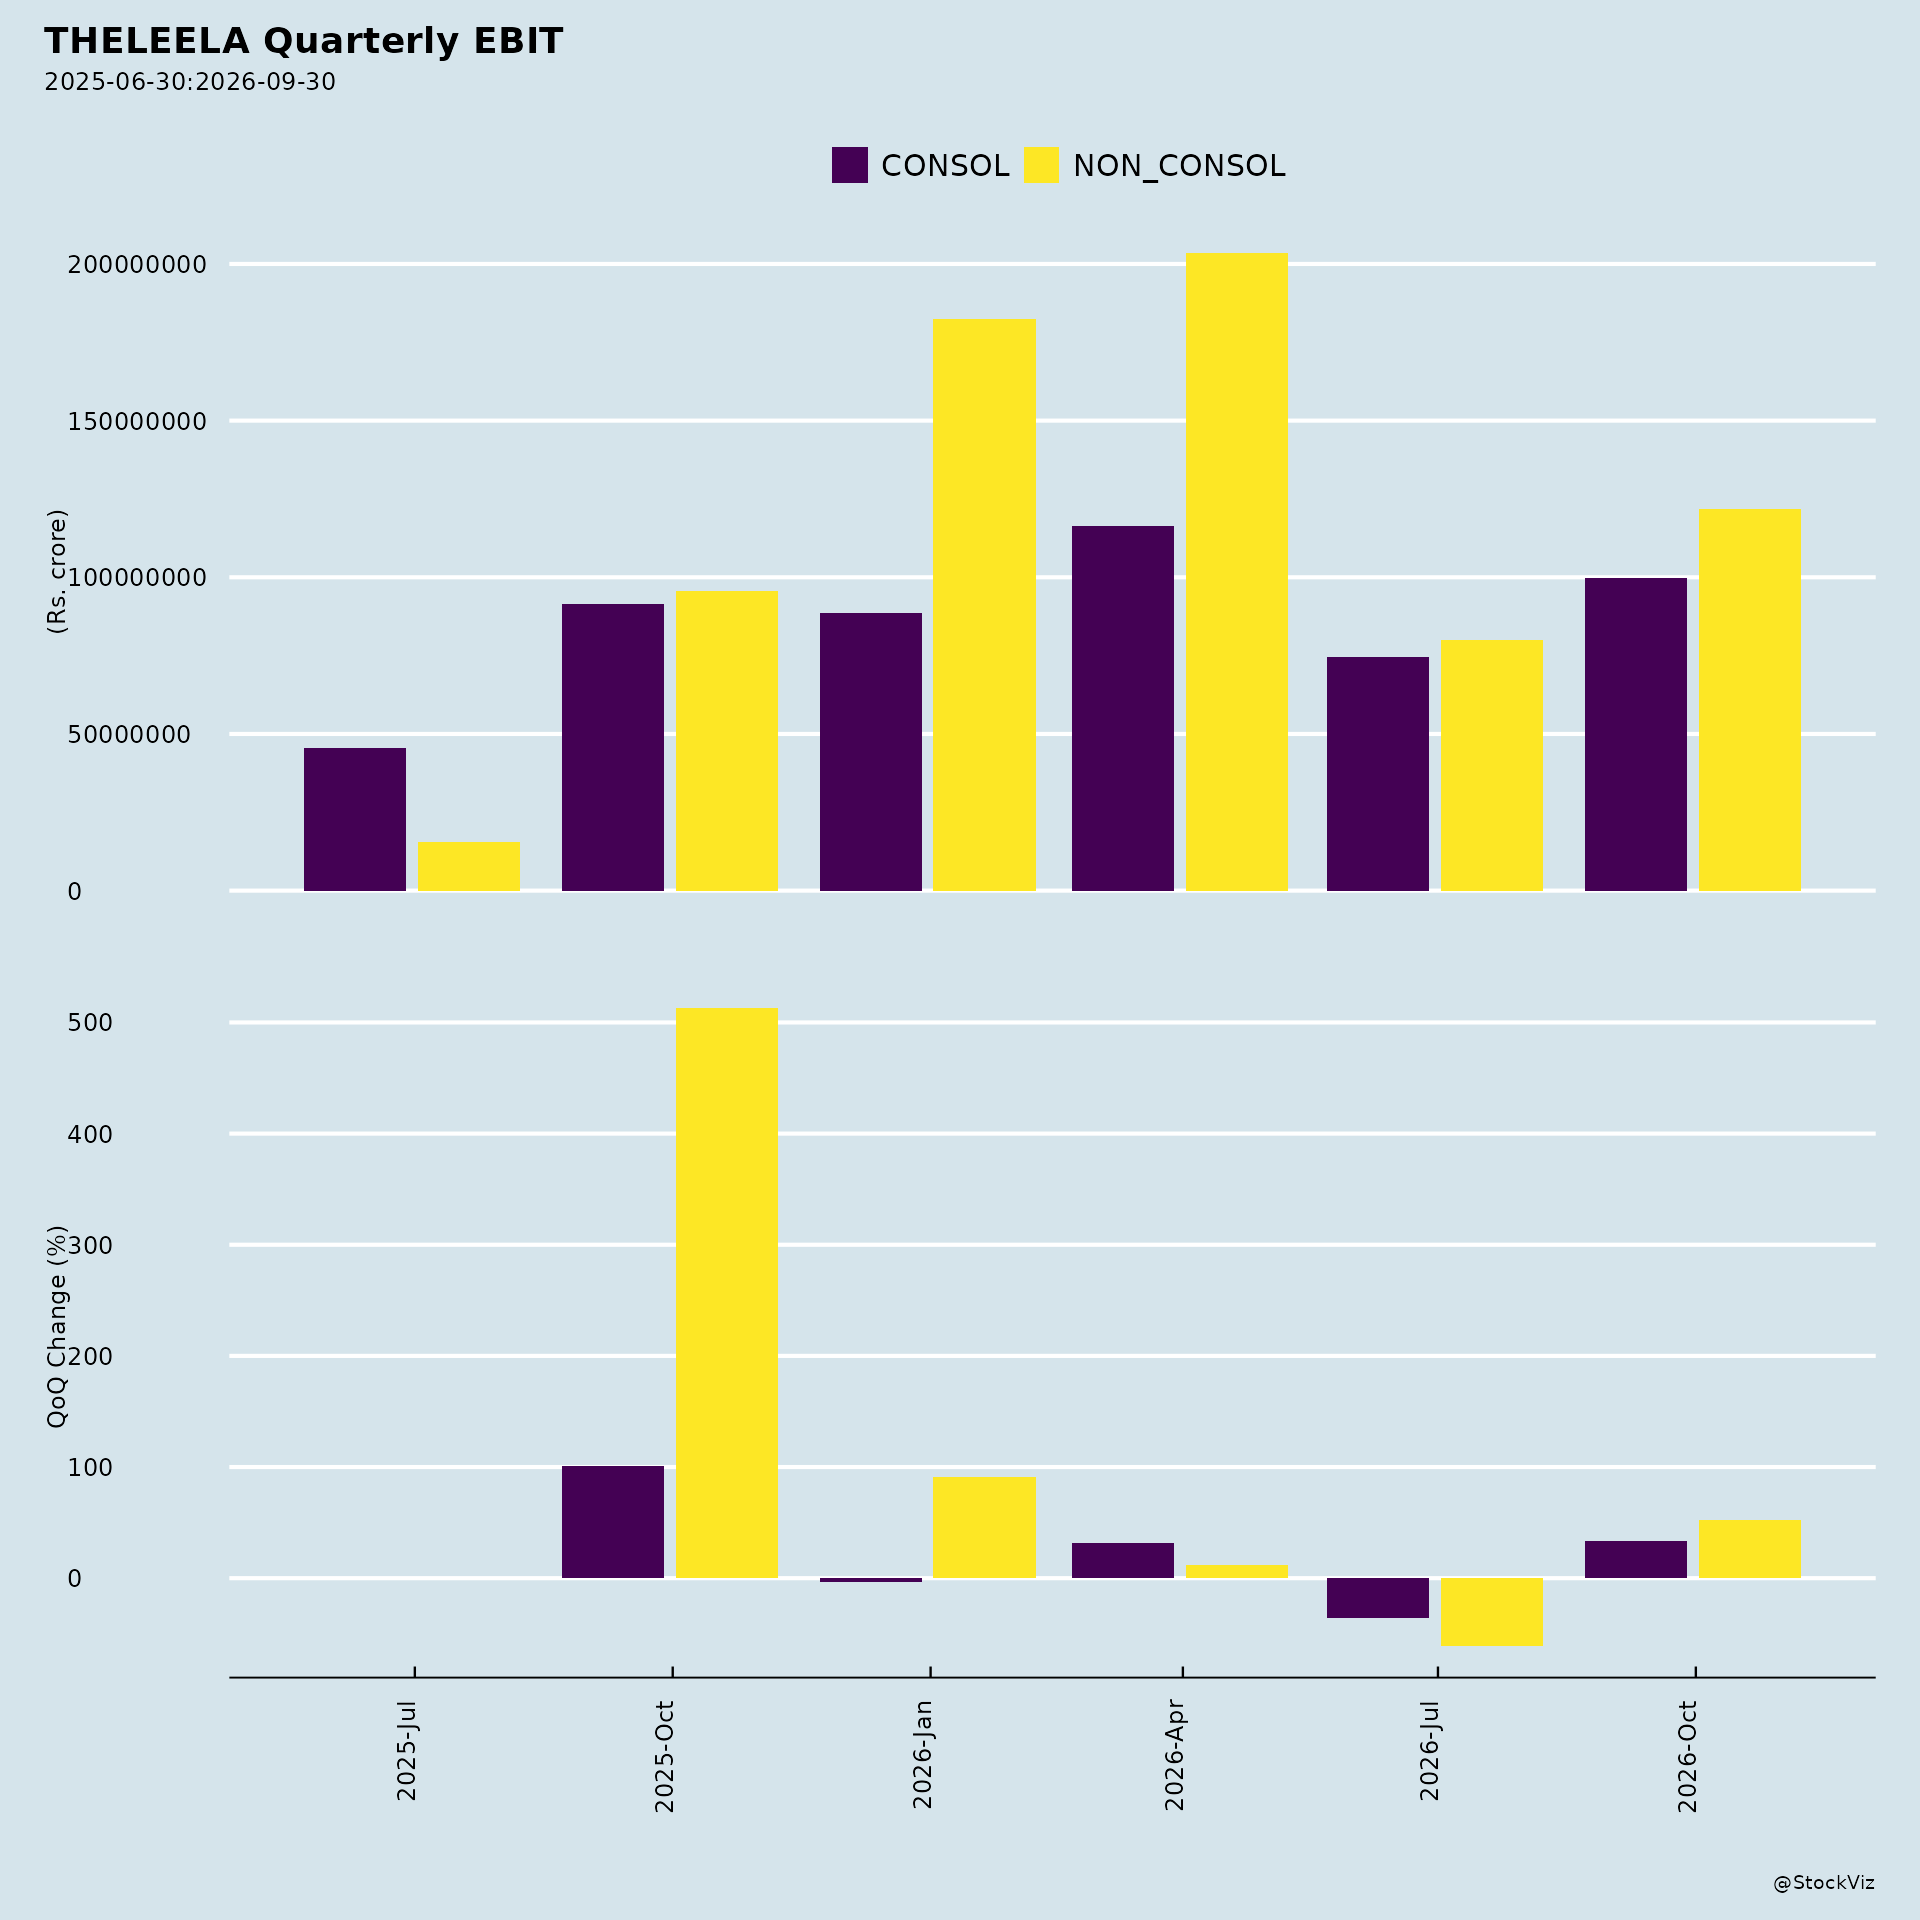
- Strong Q1 FY27 performance. Operating revenue grew 28% year-on-year to ₹3,520 million; operating EBITDA rose 41% to ₹1,434 million; PAT rose approximately 4.6x to ₹488 million. Operating EBITDA margin was 41%, the highest-ever Q1 margin for the Company.
- RevPAR and ADR leadership. RevPAR rose 17% to ₹13,982, ADR rose 10% to ₹20,722, and occupancy improved to 67.5% (+3.9pp) on an expanded portfolio including Coorg.
- Domestic demand. The presentation cites 25% growth in domestic room revenue and states that domestic demand offset the temporary FTA impact. Non-resident contribution to F&B covers at city hotels grew 26%, reaching 54%.
- Brand recognition. The Leela was ranked #2 globally among the best hotel brands by the Travel + Leisure World’s Best Awards 2026, the fifth time since 2020 it has ranked among the top three globally. Flagship properties in Udaipur, New Delhi and Jaipur were individually recognised among India’s top-ranked hotels.
- NPS leadership. NPS stood at 86 in Q1 FY27 versus a luxury segment APAC benchmark of 74.
- Expansion pipeline. The Company has 25 properties: 15 operational hotels (4,162 keys) and a pipeline of 10 hotels (1,095 keys). The pipeline table lists Jaisalmer (80 keys, CY26), Mumbai Waterstones (63 keys, CY26), Srinagar (170 keys, CY27), Bandhavgarh (30 keys, CY27), Sikkim (140 keys, CY28), Ayodhya (100 keys, CY28), Agra (99 keys, CY28), Ranthambore (76 keys, CY28), Tadoba (30 keys, CY30) and Mumbai BKC (250 keys, CY30), totalling 1,038 keys.
- New verticals and assets. ARQ expanded to a second club in New Delhi; The Leela Coorg Forest Sanctuary was launched and rebranded on 8 July 2026; a 30-key wildlife resort at Tadoba Tiger Reserve was signed under a 60-year concession with estimated capex of ~₹1,200 million and target completion in CY30. The Leela Luxury Residences, Mumbai (63 keys, managed) is a new business vertical in pre-opening.
- Financial flexibility. Net debt stood at ₹13,319 million as of June 30, 2026, with net debt to EBITDA at 1.6x. Finance costs fell 54% year-on-year to ₹393 million, attributed to deleveraging and interest cost reduction. IPO proceeds of ₹23,644.02 million (net) were fully utilised, including ₹23,000 million for repayment of borrowings.
- Long-term targets. The presentation cites FY30 goals of 25 properties and 5,257 keys (1.9x FY26), 14 owned properties and 2,646 keys (1.7x), RevPAR of ₹17,460 (2.3x over FY20), EBITDA of ₹8,133 million (4.2x over FY20) and EBITDA margin of 51%.
- ESG positioning. All Palace hotels and The Leela Coorg Forest Sanctuary are Green Building Platinum certified; the portfolio is the largest in South-East Asia to receive an EDGE Advanced Rating; the Company targets net zero by 2050 and elimination of single-use plastics by 2030.
- Talent pipeline. The Leela Centre of Excellence, in partnership with Le Cordon Bleu, is a 9,600 sq. ft. facility intended to train 3,000+ personnel over three years to support portfolio expansion.
Key Risks
- Joint venture and associate losses. Consolidated share of net loss of joint ventures and associate was ₹156.15 million in Q1 FY27, driven by Dubai market headwinds, versus a small profit in the prior-year quarter.
- Subsidiary losses. The limited review report notes one subsidiary with a net loss after tax of ₹176.92 million and four subsidiaries with a net loss of ₹0.33 million for the quarter ended June 30, 2026, whose interim results were not reviewed by the statutory auditor.
- Dependence on domestic demand. The presentation indicates that domestic demand offset the temporary FTA impact, implying sensitivity to domestic luxury demand conditions.
- Execution and timeline risk on pipeline. The pipeline spans CY26 to CY30 across multiple locations, with construction at various stages (design development, piling, walling, fort wall stabilisation, lease premium paid). The Tadoba investment of up to ₹1,200 million is to be funded in one or more tranches through equity shares, preference shares, equity-linked instruments, debt instruments, inter-corporate deposits, loans or other structured instruments.
- Regulatory and accounting uncertainty. The finalisation of Central/State Rules and clarifications on the Labour Codes remains pending, and the Company states it would provide appropriate accounting effect as developments occur.
- Forward-looking statement risk. The Company’s disclaimer states that statements relating to future status, events or circumstances are subject to numerous risks and uncertainties and are not necessarily predictive of future results, and that actual results may differ materially.
- Seasonality risk. Quarterly results are not indicative of full-year performance due to sector seasonality.
Management Guidance Versus Observed Business Performance
- FY27 openings. The presentation lists FY27 openings as The Leela Coorg Forest Sanctuary (71 keys, owned, rebranded 8 July 2026), The Leela Jaisalmer (80 keys, managed, pre-opening in progress) and The Leela Luxury Residences, Mumbai (63 keys, managed, pre-opening in progress). Coorg has been rebranded and is included in the Q1 FY27 operational portfolio; Jaisalmer and Mumbai Residences remain in pre-opening.
- Pipeline timelines. The pipeline table targets Jaisalmer and Mumbai Waterstones in CY26, Srinagar and Bandhavgarh in CY27, Sikkim, Ayodhya, Agra and Ranthambore in CY28, and Tadoba and Mumbai BKC in CY30. Status updates show public area works underway at Jaisalmer, interior fit-outs in advanced stage at Mumbai Waterstones, room walling and landscaping in progress at Srinagar, villa construction in progress at Bandhavgarh, main block and villa civil works underway at Sikkim, design development and test piling completed at Ayodhya with main piling to commence, piling underway at Agra, fort wall stabilisation in progress at Ranthambore, concession agreement executed at Tadoba, and lease premium paid with design finalisation and site preparation in progress at Mumbai BKC.
- Tadoba investment. The Board approved investment of up to ₹1,200,000,000 in Schloss Tadoba Private Limited, with indicative completion by end of CY 2030, matching the CY30 project completion target in the presentation.
- FY30 targets. The presentation sets FY30 goals of 25 properties, 5,257 keys, 14 owned properties, 2,646 owned keys, RevPAR of ₹17,460, EBITDA of ₹8,133 million and EBITDA margin of 51%. These are forward-looking targets; the Q1 FY27 actuals show operating EBITDA margin of 41% and RevPAR of ₹13,982.
- International recovery. The presentation states international mix “has significantly recovered by June,” and management expects Dubai JV headwinds “to ease as regional travel normalizes.” Q1 FY27 JV share of profit was negative ₹156.15 million.
- Margin trajectory. Management describes the 41% operating EBITDA margin as the highest-ever Q1 margin and cites operating leverage. The FY30 target of 51% EBITDA margin implies further expansion from the Q1 FY27 level.
- AGM outcome. The Seventh Annual General Meeting was held on September 4, 2026, where all three ordinary resolutions regarding adoption of standalone and consolidated financial statements and re-appointment of director Ms. Ananya Tripathi were duly approved by shareholders with the requisite majority.
Broker Narrative
The story remained centered on THELEELA’s pure-play luxury positioning, RevPAR/ARR outperformance, and pipeline expansion, with the target multiple rerated higher from 18.0x to 22.0x FY28E EV/Adj. EBITDA on brand strength. Broad early risks about occupancy slowdowns and project delays evolved into specific issues: Coorg’s ramp-up weighing on occupancy, a ~73.6% promoter share pledge for investor distributions and shareholder-loan repayment, and softer Dubai transaction volumes. Newer tailwinds emphasized suite occupancy gains of over 700 bps, 76% management-fee growth, direct website bookings rising to 15.1% of room revenue, and event-led demand such as the BRICS Summit, alongside the previously flagged Dubai/BKC accretion and key pipeline.
Broker Timeline
4 broker calls · 2025-12-15 to 2026-10-15
CNBC-TV18: ratings, targets and commentary
No recorded CNBC-TV18 statements for this ticker.
Management comments
No recorded management comments with an explicit designation and affiliation for this ticker.
Copyright © 2023 SAS Data Analytics Pvt. Ltd. All rights reserved.