TENNIND
Equity Metrics
November 18, 2026
Tenneco Clean Air India Limited
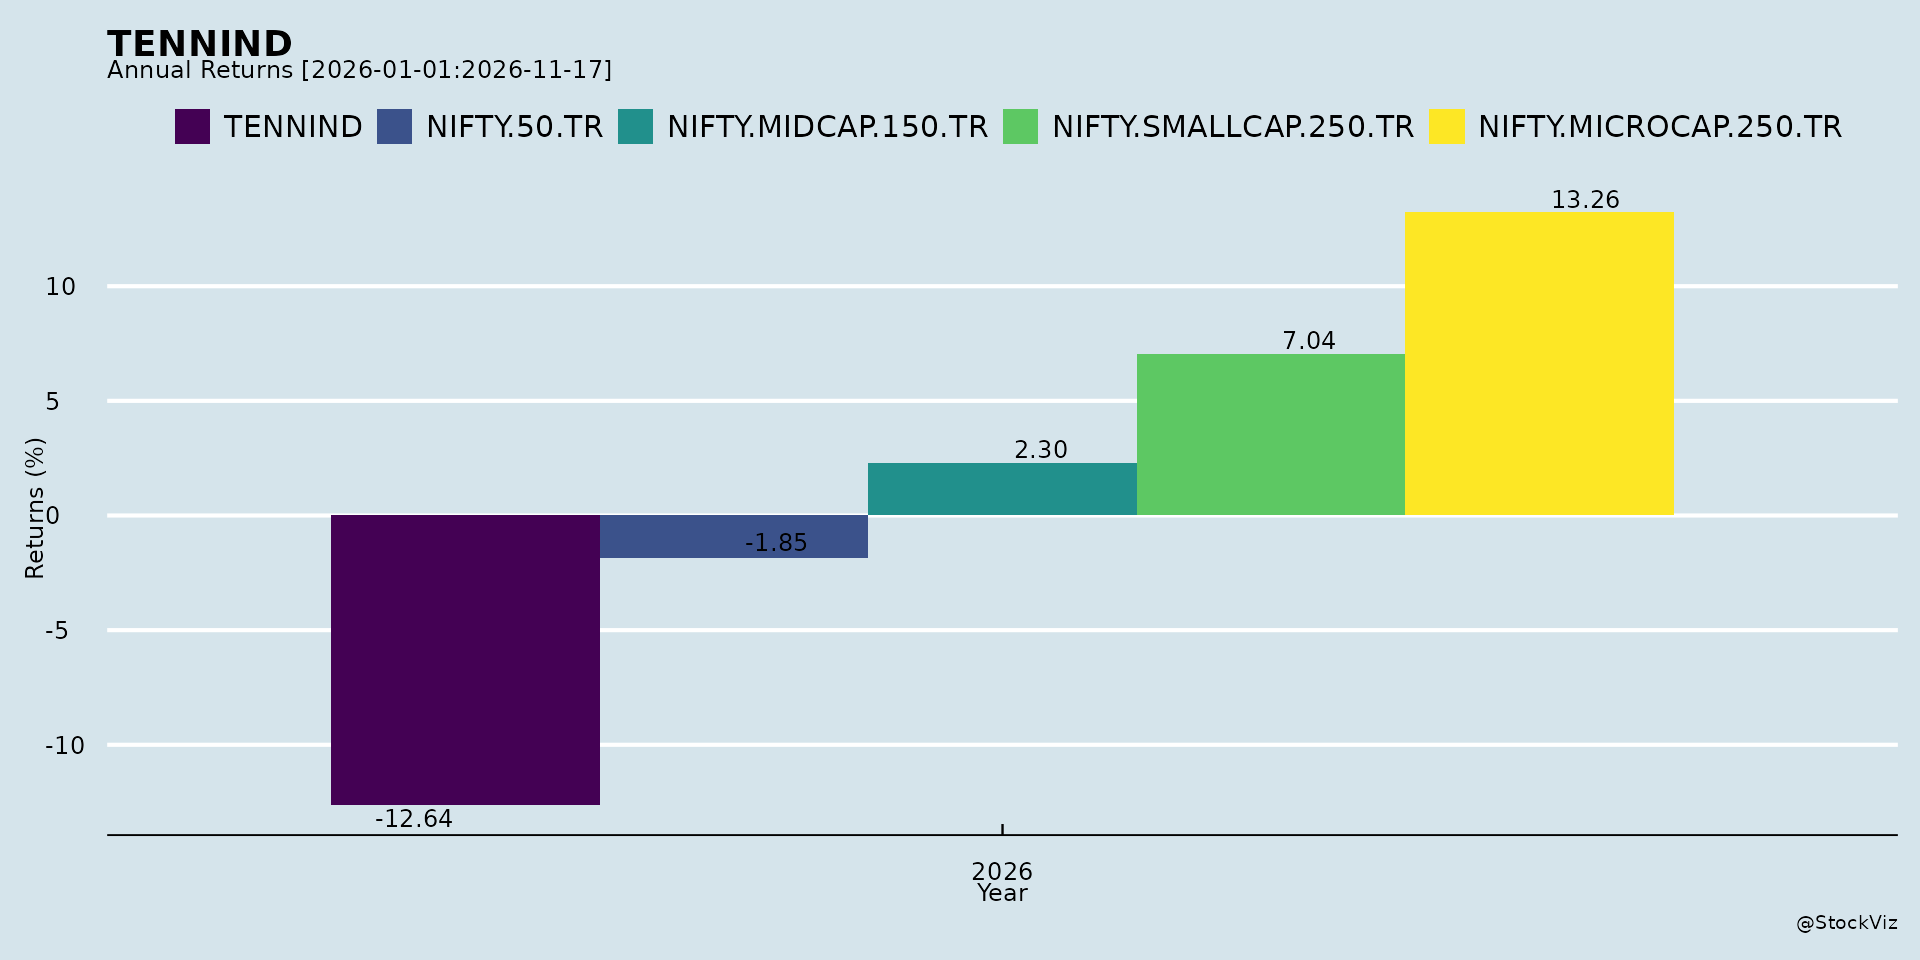
Annual Returns

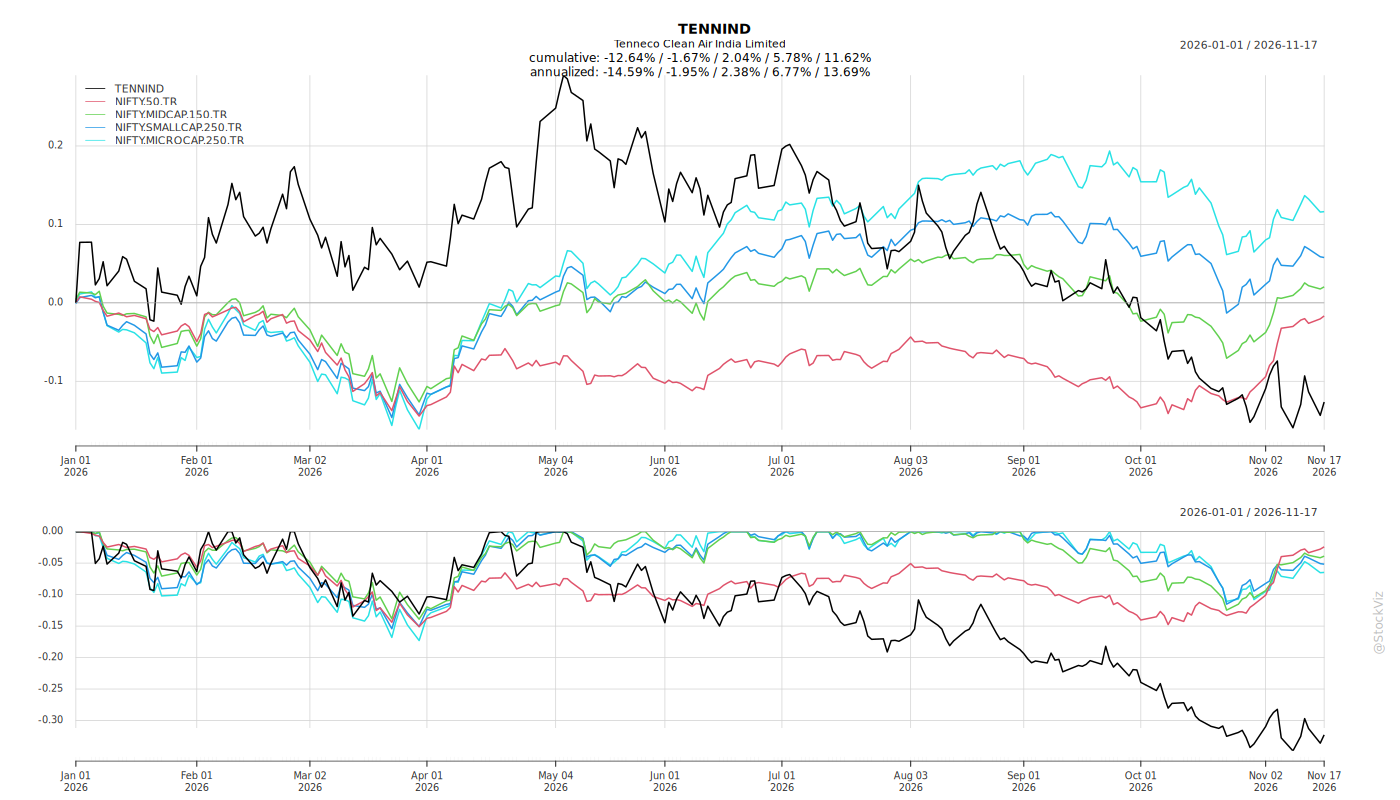
Cumulative Returns and Drawdowns
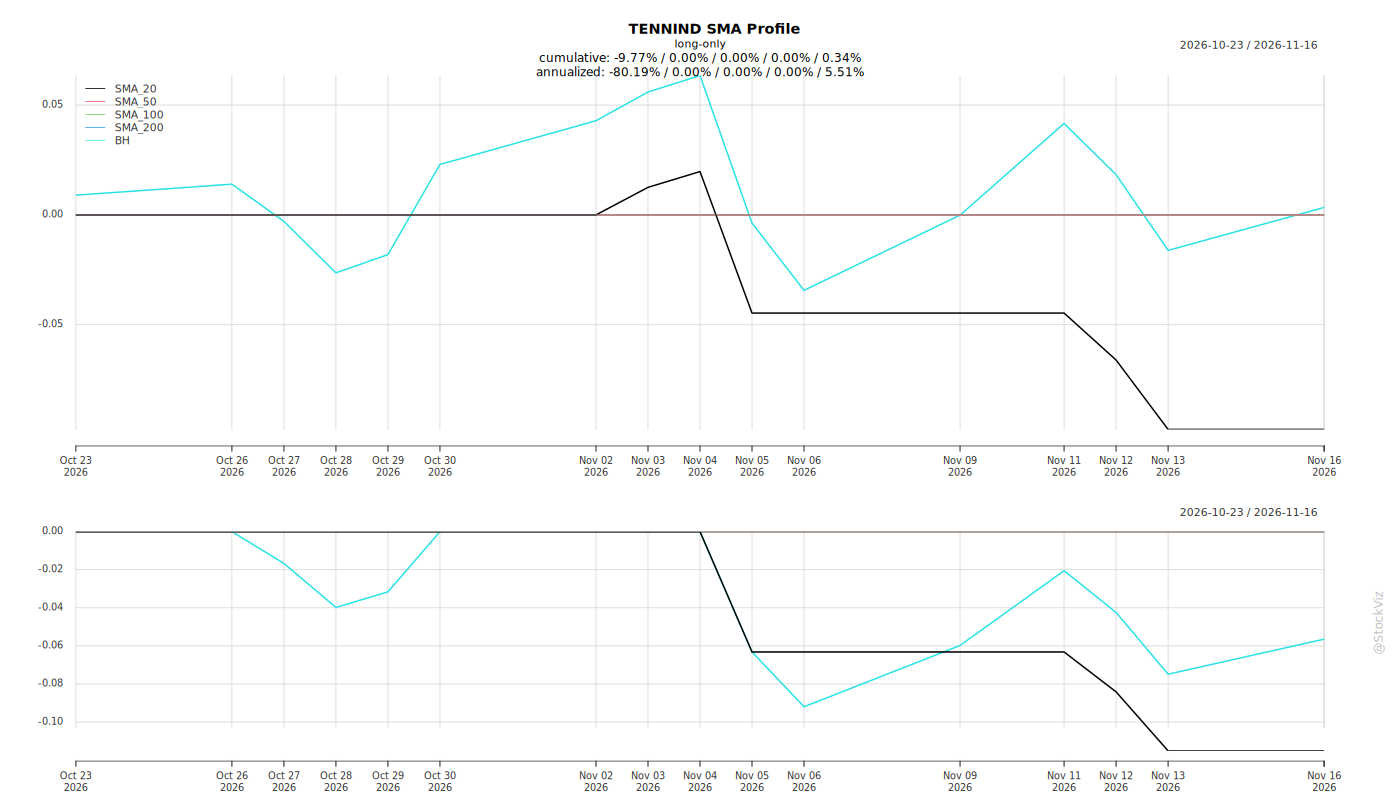
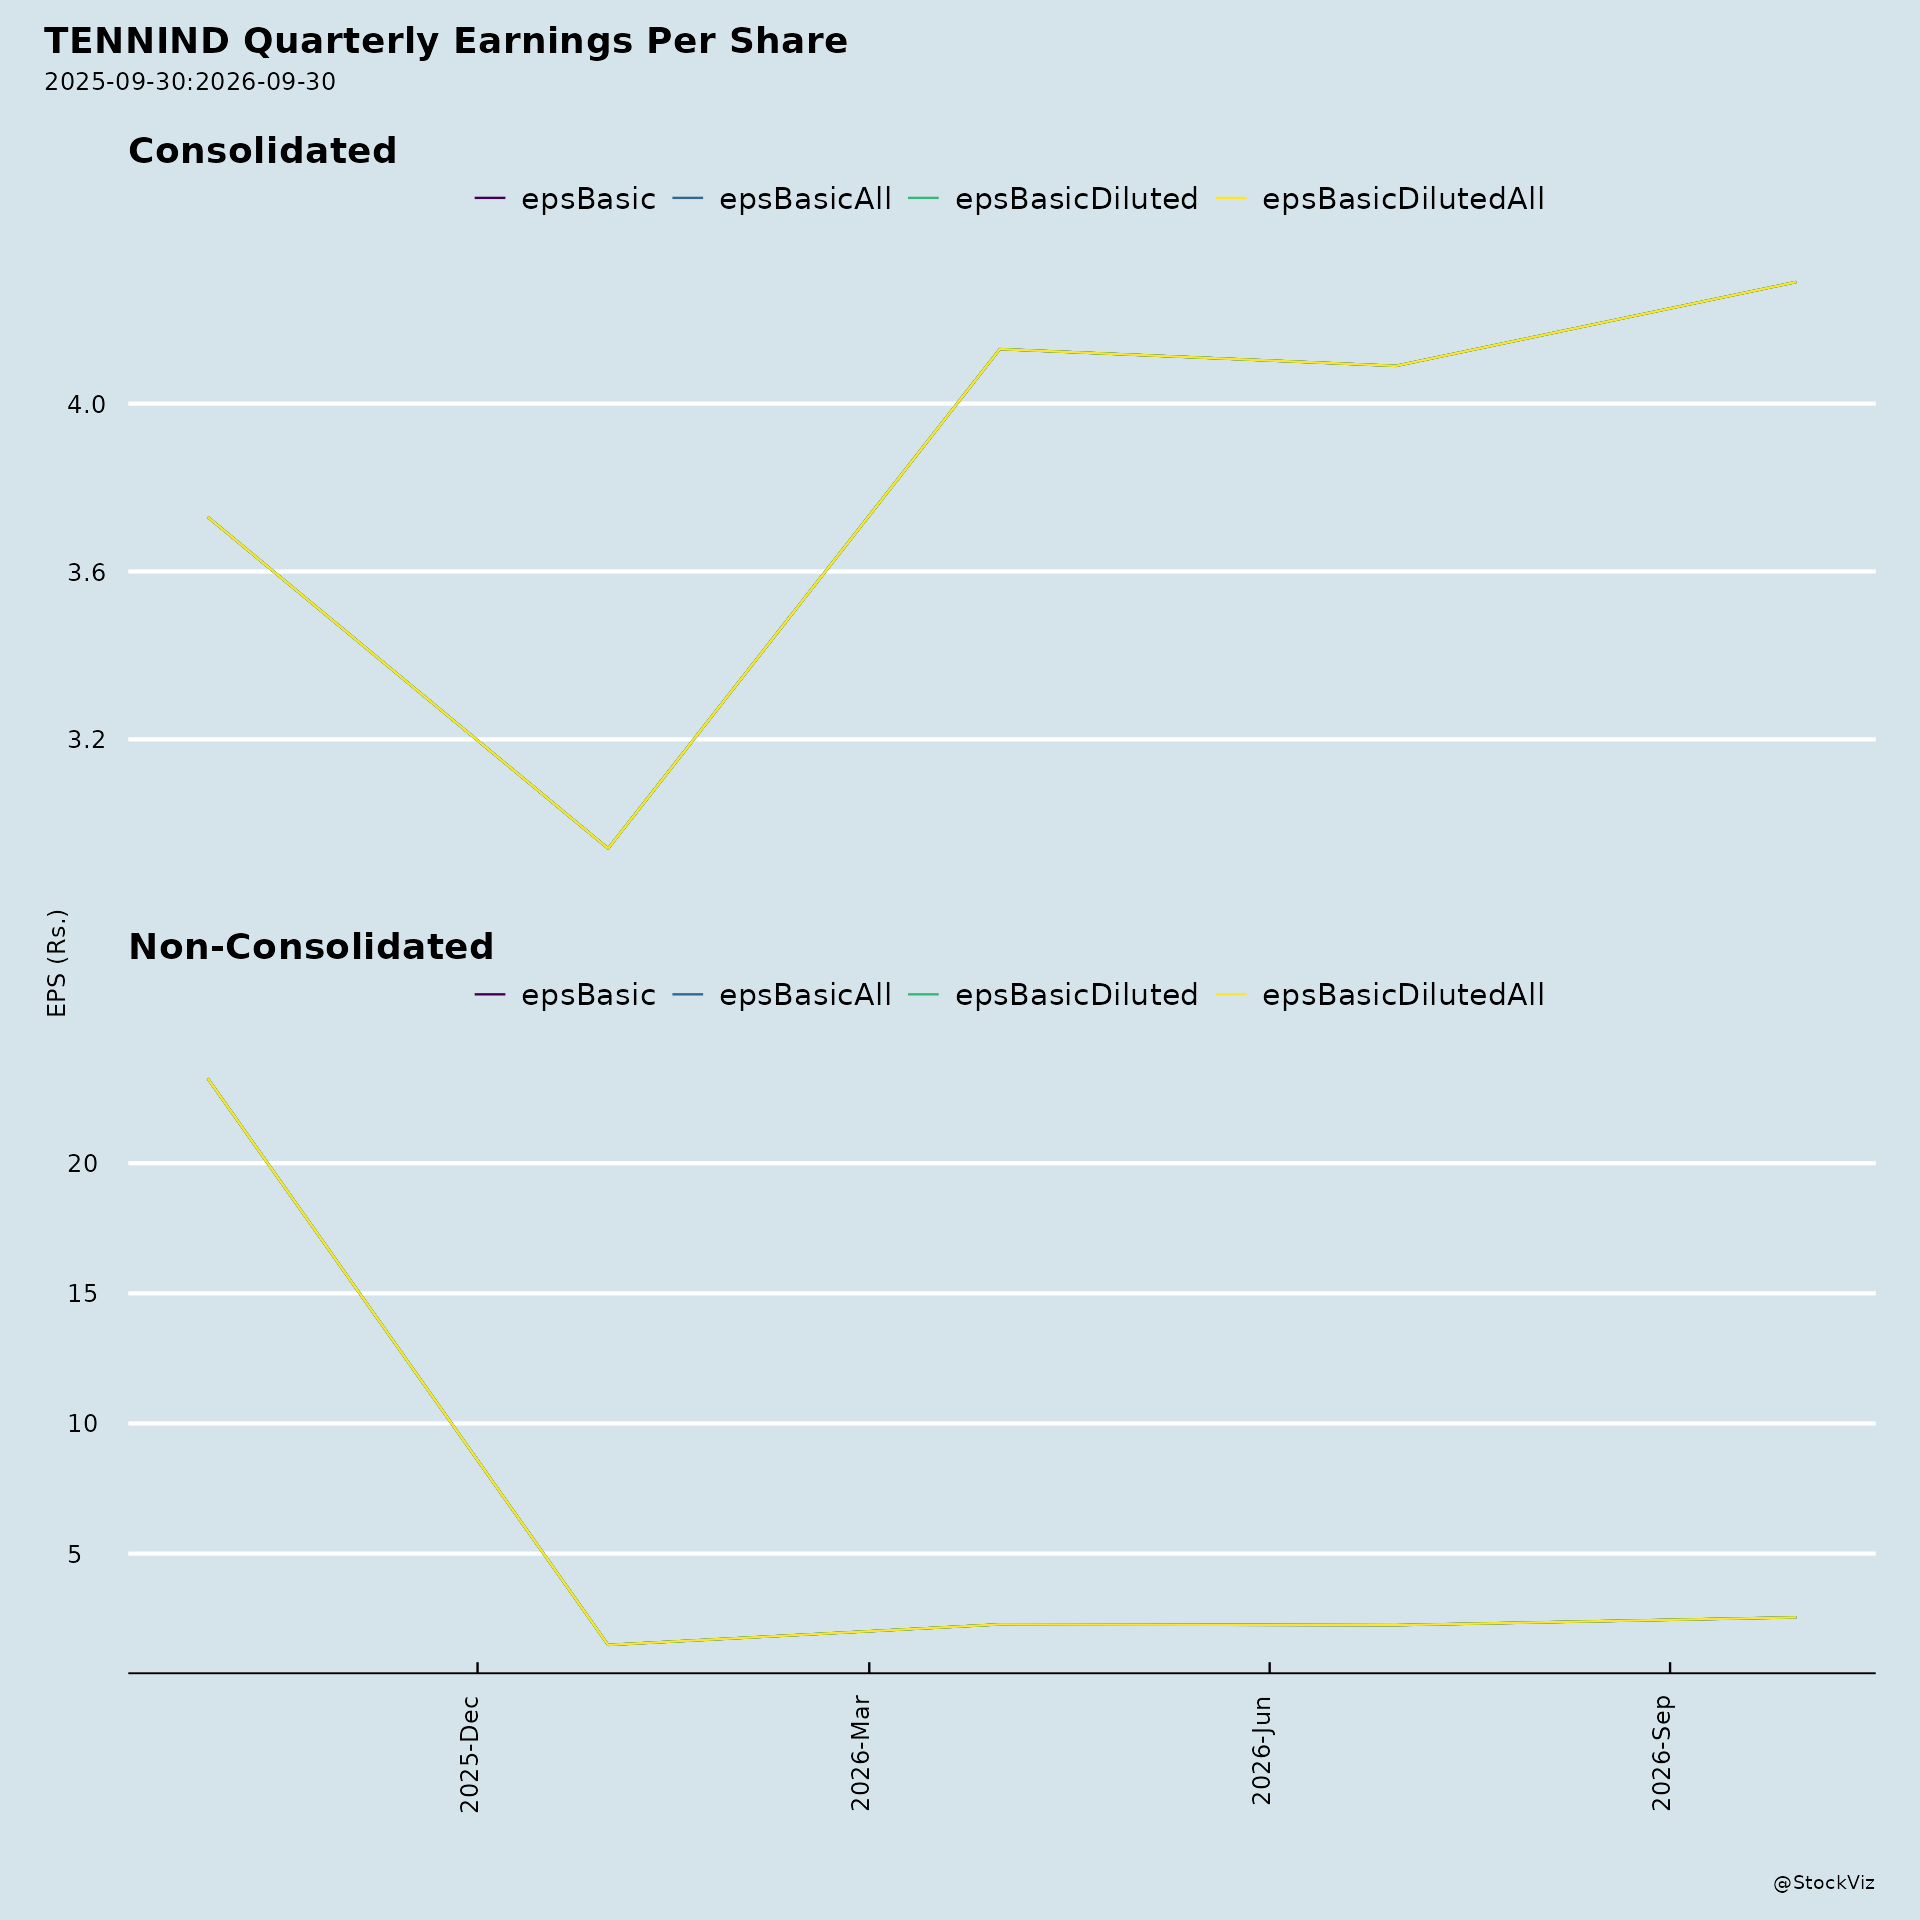
Fundamentals
Ownership
Margined
AI Summary
asof: 2026-09-16
Tenneco Clean Air India Limited — Recent Developments Summary
1. Headwinds and Challenges
- Commodity cost escalation: Q1 FY2027 EBITDA margin was affected by significant commodity increases attributed to the current geopolitical situation.
- Listing transition costs: The cost of moving from a private to a listed public company weighed on Q1 FY2027 EBITDA/margin.
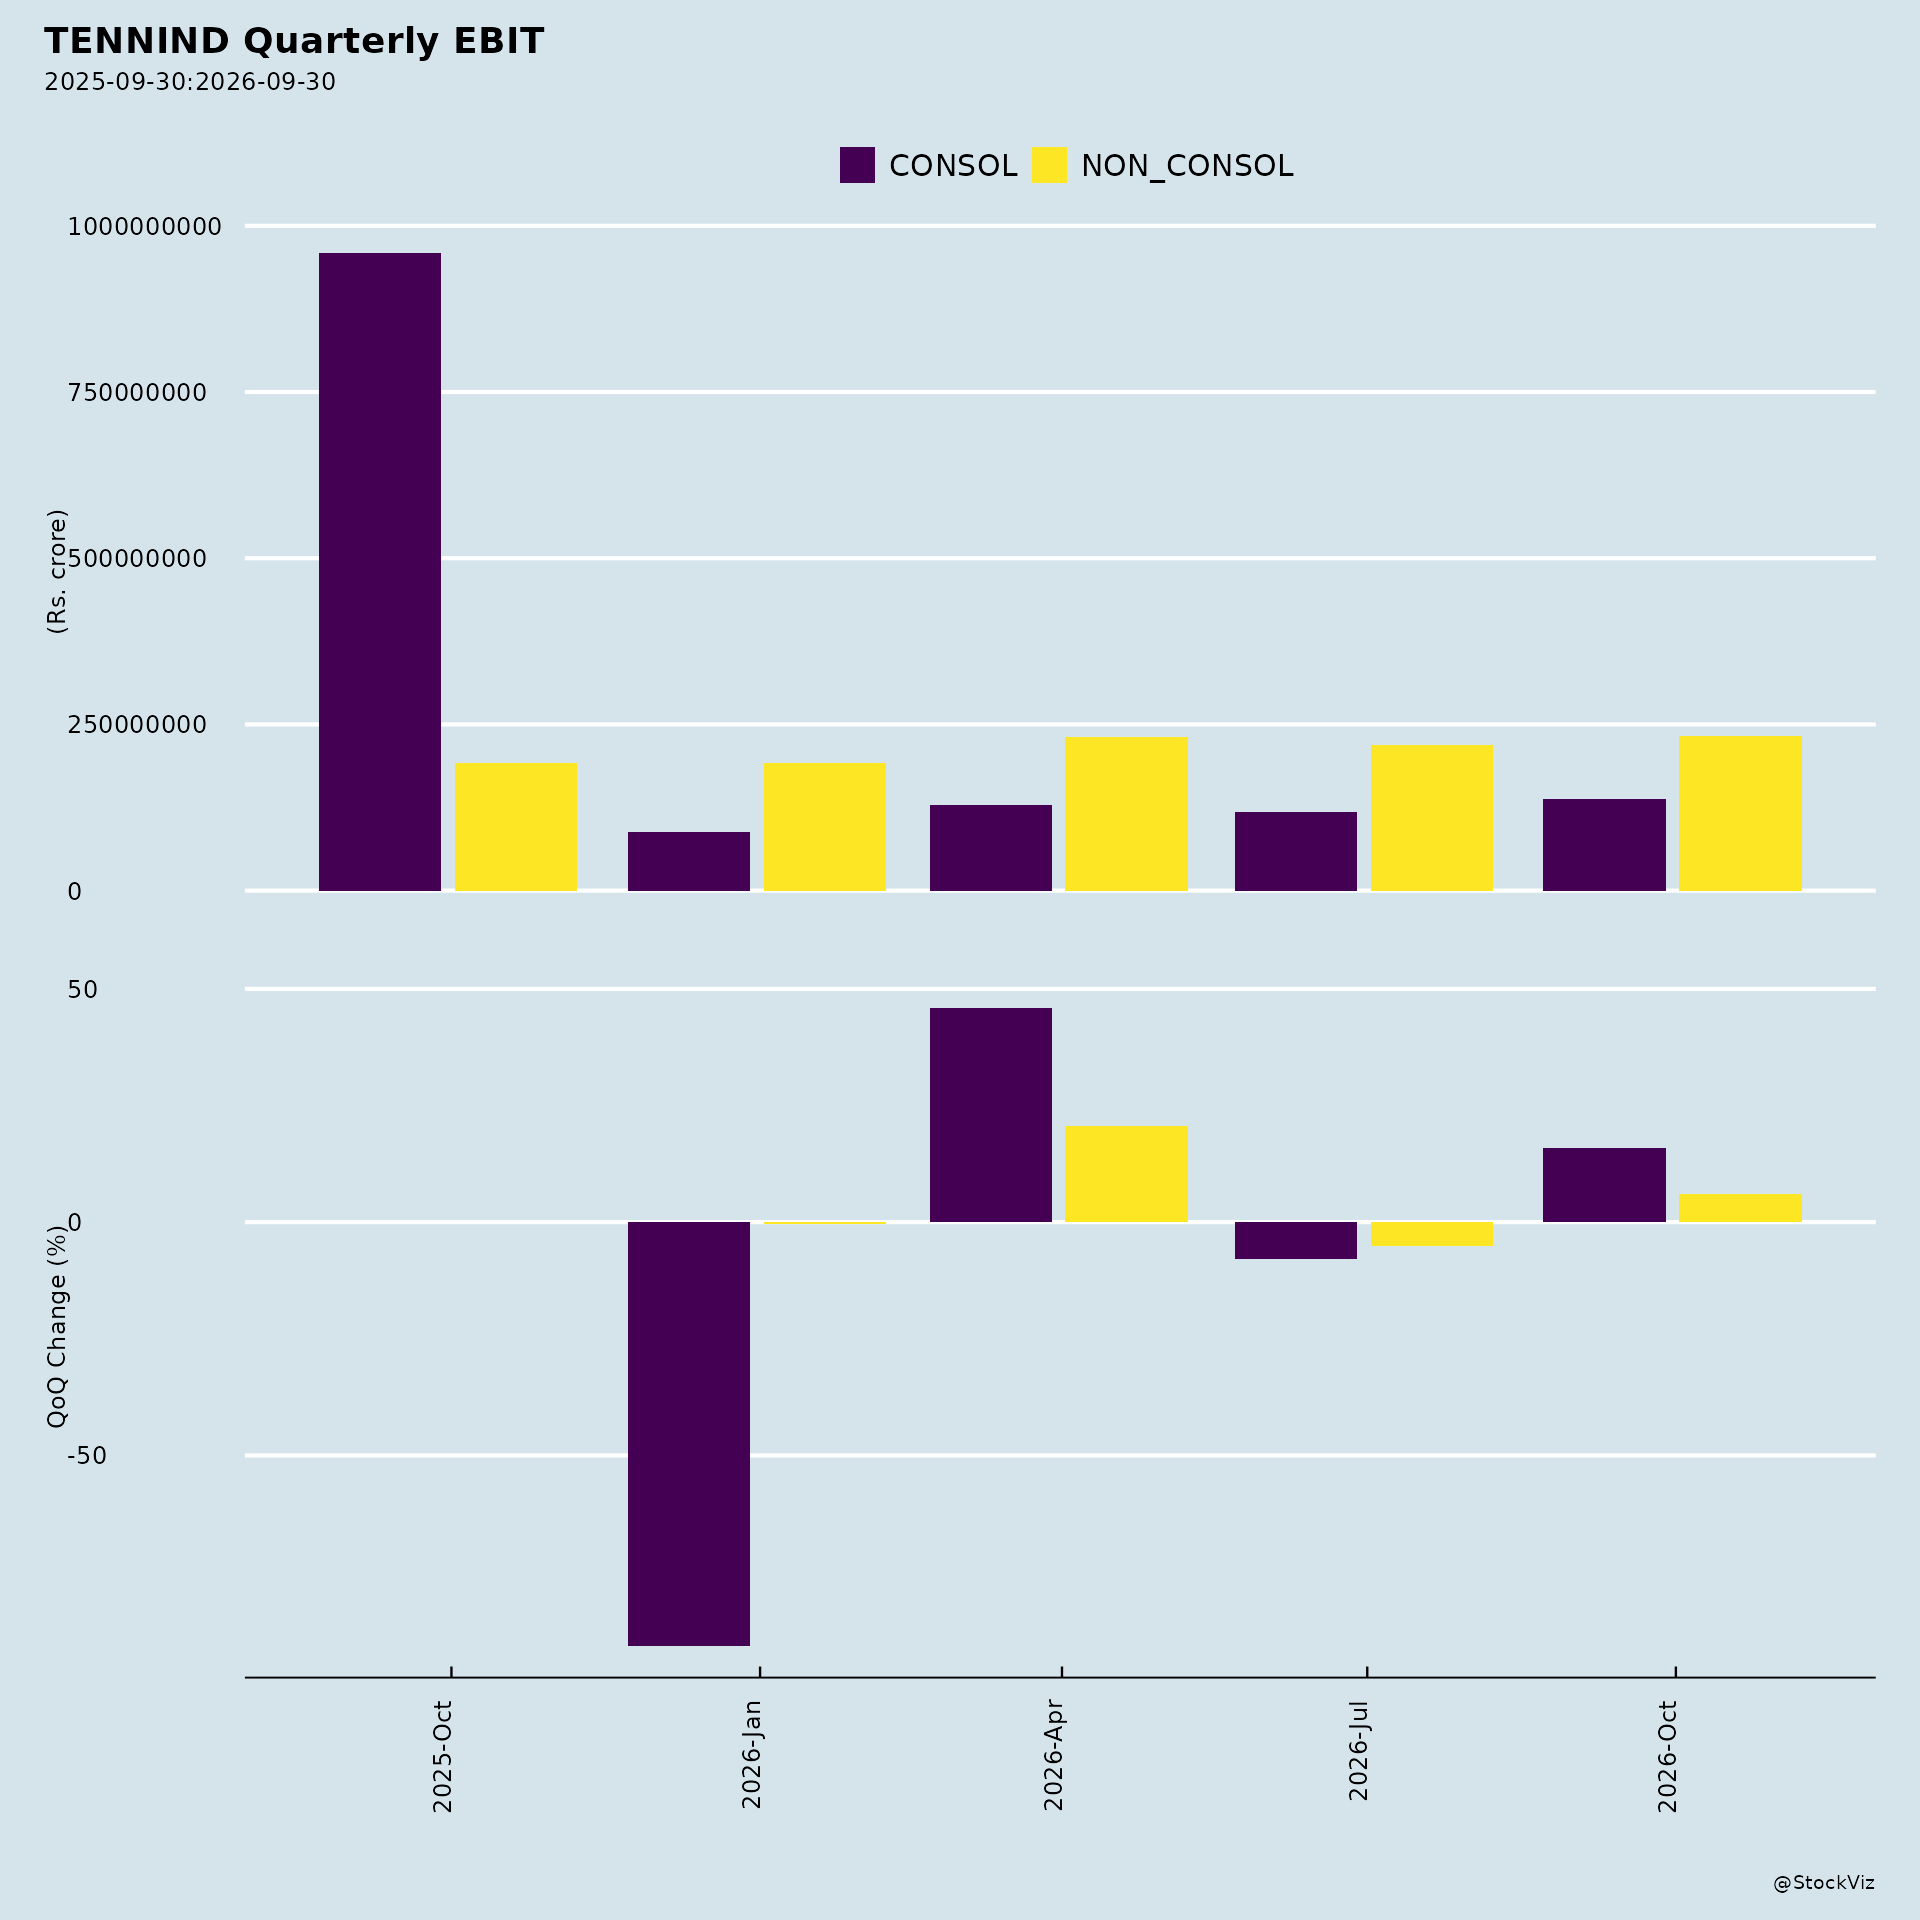
- Margin compression: EBITDA margin on VAR declined to 17.9% in Q1 FY2027 from 19.6% in Q1 FY2026 (down 175 bps), even as EBITDA grew 7.9% year-on-year.
- PAT decline: PAT/margin (VAR) fell to INR 1,652 million / 12.0% in Q1 FY2027 from INR 1,681 million / 14.4% in Q1 FY2026 (down 245 bps). The prior-year quarter included a one-time interest income benefit of approximately INR 187 million (net of tax) related to the sale of the Motocare entity; excluding this non-recurring item, PAT growth in Q1 FY2027 would have been broadly in line with EBITDA growth.
- Market headwinds and execution challenges: Management referred to market headwinds and anticipated further headwinds, alongside execution challenges, in its outlook commentary.
2. Tailwinds and Growth Prospects
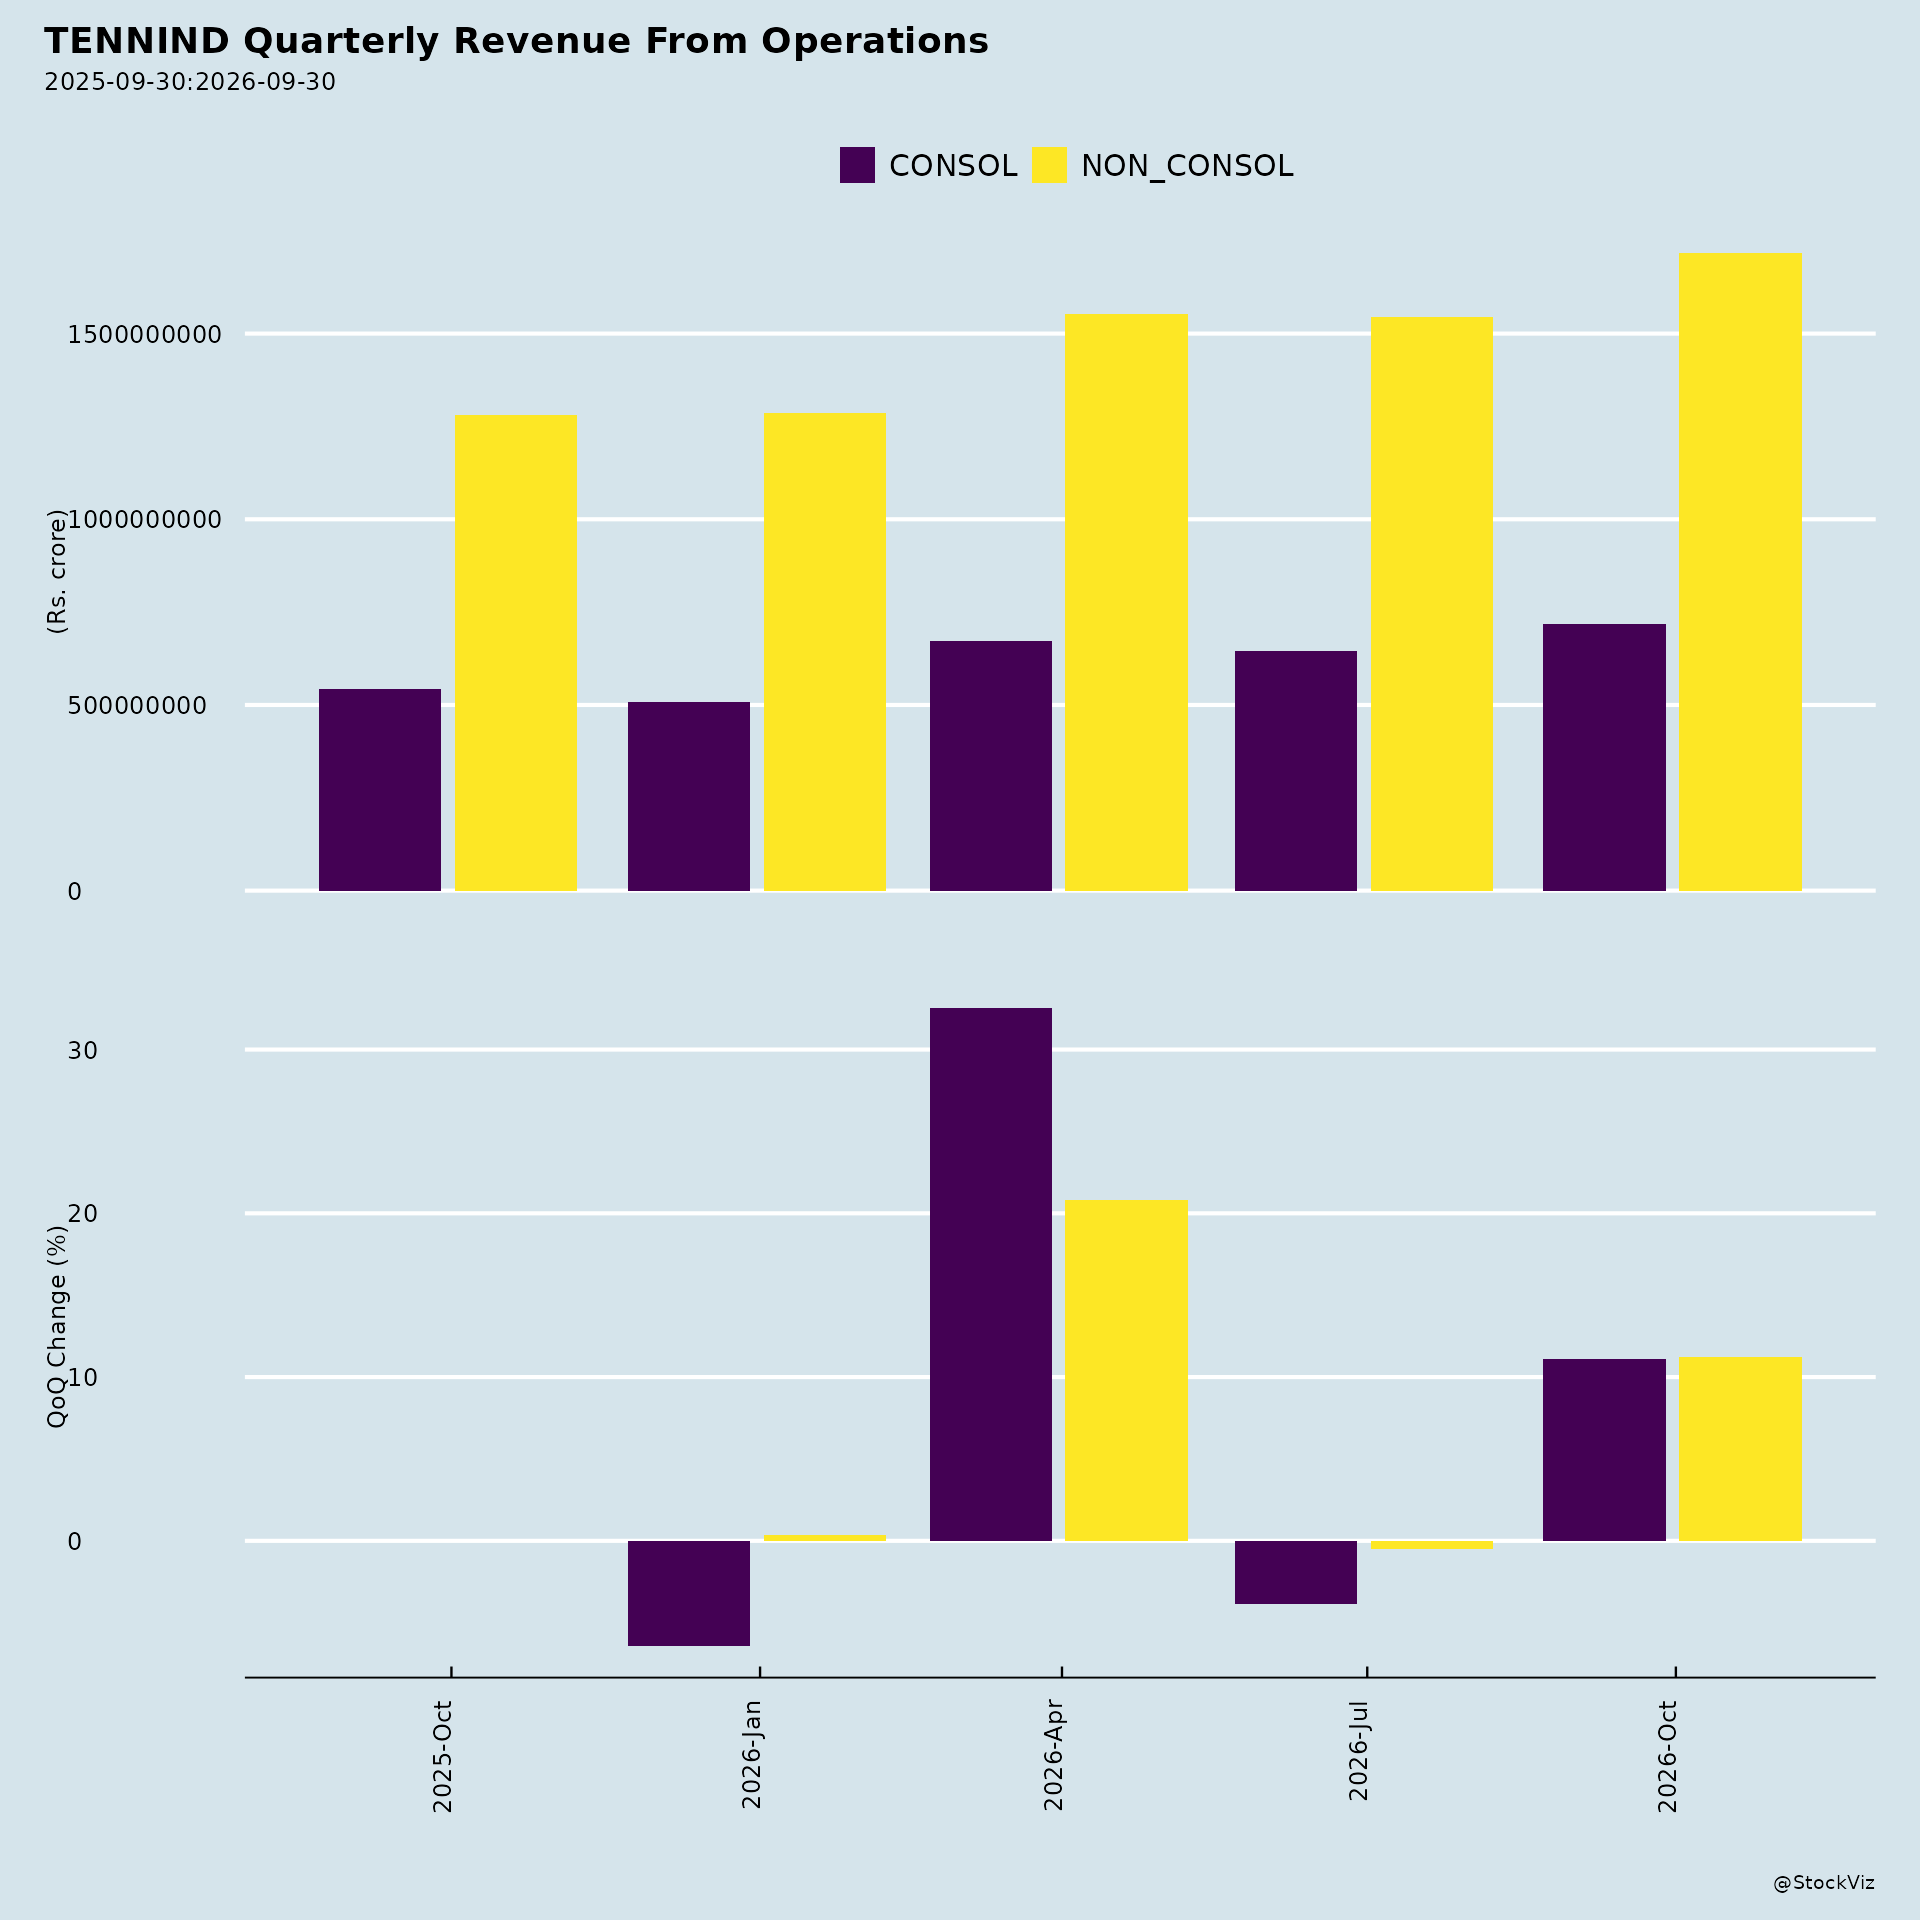
- Value-Added Revenue (VAR) growth: VAR rose 18.4% year-on-year to INR 13,816 million in Q1 FY2027, outpacing served-market industry volume growth of 16.2%.
- Revenue growth: Revenue from operations increased 20.2% year-on-year to INR 15,448 million.
- Segment performance: Advanced Ride Technologies VAR grew 27.9% to INR 7,190 million; Clean Air & Powertrain Solutions VAR grew 9.6% to INR 6,626 million.
- Market share gains (FY2026 value market share): Commercial vehicle Clean Air Solutions at 58% (+1% YoY); passenger vehicle shock absorbers and struts at 55% (+3% YoY, described as a 300 bps YoY expansion); off-highway Clean Air Solutions sustained at 68%.
- Advanced Ride Technologies (ART): Expanded DCx Da Vinci suspension footprint through multiple new application wins across existing customers; added four new customers in 2026 and three models for DCx applications; introduced DCx32 targeting smaller A/B segment vehicles, increasing the addressable market; completed fitment and benchmarked performance of MARD (Mechanical Adaptive Roll Damping) dampers with a leading domestic OEM, developed entirely in India.
- Clean Air & Powertrain nominations: Multiple
new program wins from leading passenger and commercial vehicle OEMs
covering ignition, hot-end, cold-end, and pipe assembly applications,
including:
- A strategic spark plug order from India’s leading passenger vehicle OEM, entering a new whitespace opportunity.
- A new passenger vehicle exhaust program (hot end) from a leading Indian passenger car OEM.
- A new CNG platform cold-end assembly program from a global OEM for two models in India.
- An upcoming 2.0L engine emission after-treatment system program from a leading domestic commercial vehicle OEM for its SCV range.
- Alternative fuels: Reinforced spark plug compatibility with flex-fuel applications up to E85.
- Exports: ART secured its maiden order from a leading European ATV manufacturer (new whitespace); won a heat shield (PT segment) order from Tenneco America.
- Recognition: Won the Innovation and Performance Award from Mahindra, the Ride Performance Award 2026 from The Economic Times, and the “Technology & Innovation Award” from DICV (Daimler India Commercial Vehicles).
- Investor engagement: Scheduled participation in the UBS Conference 2026 on September 10, 2026, and the Axis Capital Consumer & Tech Conference on September 11, 2026, both in Mumbai, with management attending in person.
3. Key Risks
- Commodity price escalation linked to the geopolitical situation.
- Costs and adjustments associated with the private-to-public listing transition.
- Margin pressure despite revenue growth, as reflected in the EBITDA and PAT margin declines in Q1 FY2027.
- Comparability risk from non-recurring items: the prior-year quarter’s one-time interest income benefit of approximately INR 187 million (net of tax) from the Motocare entity sale distorts year-on-year PAT comparisons.
- Execution risk, referenced by management in the context of “flawless P3 execution” and “prudent risk management.”
- Anticipated further headwinds, per management’s outlook.
- Conference schedule risk: management noted the meeting schedule may change on the part of the Analyst/Institutional Investor/Company.
4. Management Guidance vs. Observed Business Performance
- Guidance/outlook: Management stated it remains focused on executing its strategy, investing in future technologies, creating long-term value for all stakeholders, flawless P3 execution, prudent risk management, and commercial discipline to deliver profitable growth and long-term value creation amidst anticipated further headwinds. Management also stated that no unpublished price sensitive information shall be disclosed or shared at investor meetings.
- Observed performance versus stated focus:
- The strategy execution focus is evidenced by Q1 FY2027 VAR growth of 18.4% and revenue growth of 20.2%, both outpacing served-market volume growth of 16.2%.
- The commercial discipline and productivity focus is reflected in a sustained EBITDA margin of 17.9% on VAR despite commodity escalation and listing costs, though this is below the prior-year 19.6%.
- The investment in future technologies is evidenced by DCx32 introduction, MARD damper benchmarking with a domestic OEM, E85 flex-fuel spark plug compatibility, and new program nominations across hot-end, cold-end, and powertrain applications.
- The long-term value creation focus is supported by FY2026 ROCE of 94%, Q1 FY2027 EPS of INR 4.1, and the maiden European ATV order plus Tenneco America heat shield order strengthening exports.
- The “anticipated further headwinds” guidance is consistent with the observed margin compression and the one-time prior-year benefit that flattered the year-on-year PAT comparison.
- Governance and shareholder matters: The 8th Annual General Meeting held on August 28, 2026 passed all 7 resolutions concerning financial statement adoptions, director re-appointments/appointments, remuneration revisions, and auditor appointments with the requisite majority. The NRC on August 21, 2026 approved the grant of 2,00,453 employee stock options under the ESOP Scheme 2025, within the shareholders-approved limit of 8,072,086 options, at an exercise price of INR 10 per option, with an exercise period of 5 years from vesting. The ESOP Scheme 2025 was ratified by shareholders post-IPO via Postal Ballot Notice dated March 25, 2026.
Broker Timeline
1 broker calls · 2026-09-01 to 2026-09-01
CNBC-TV18: ratings, targets and commentary
No recorded CNBC-TV18 statements for this ticker.
Management comments
No recorded management comments with an explicit designation and affiliation for this ticker.
Copyright © 2023 SAS Data Analytics Pvt. Ltd. All rights reserved.