TANLA
Equity Metrics
September 24, 2026
Tanla Platforms Limited
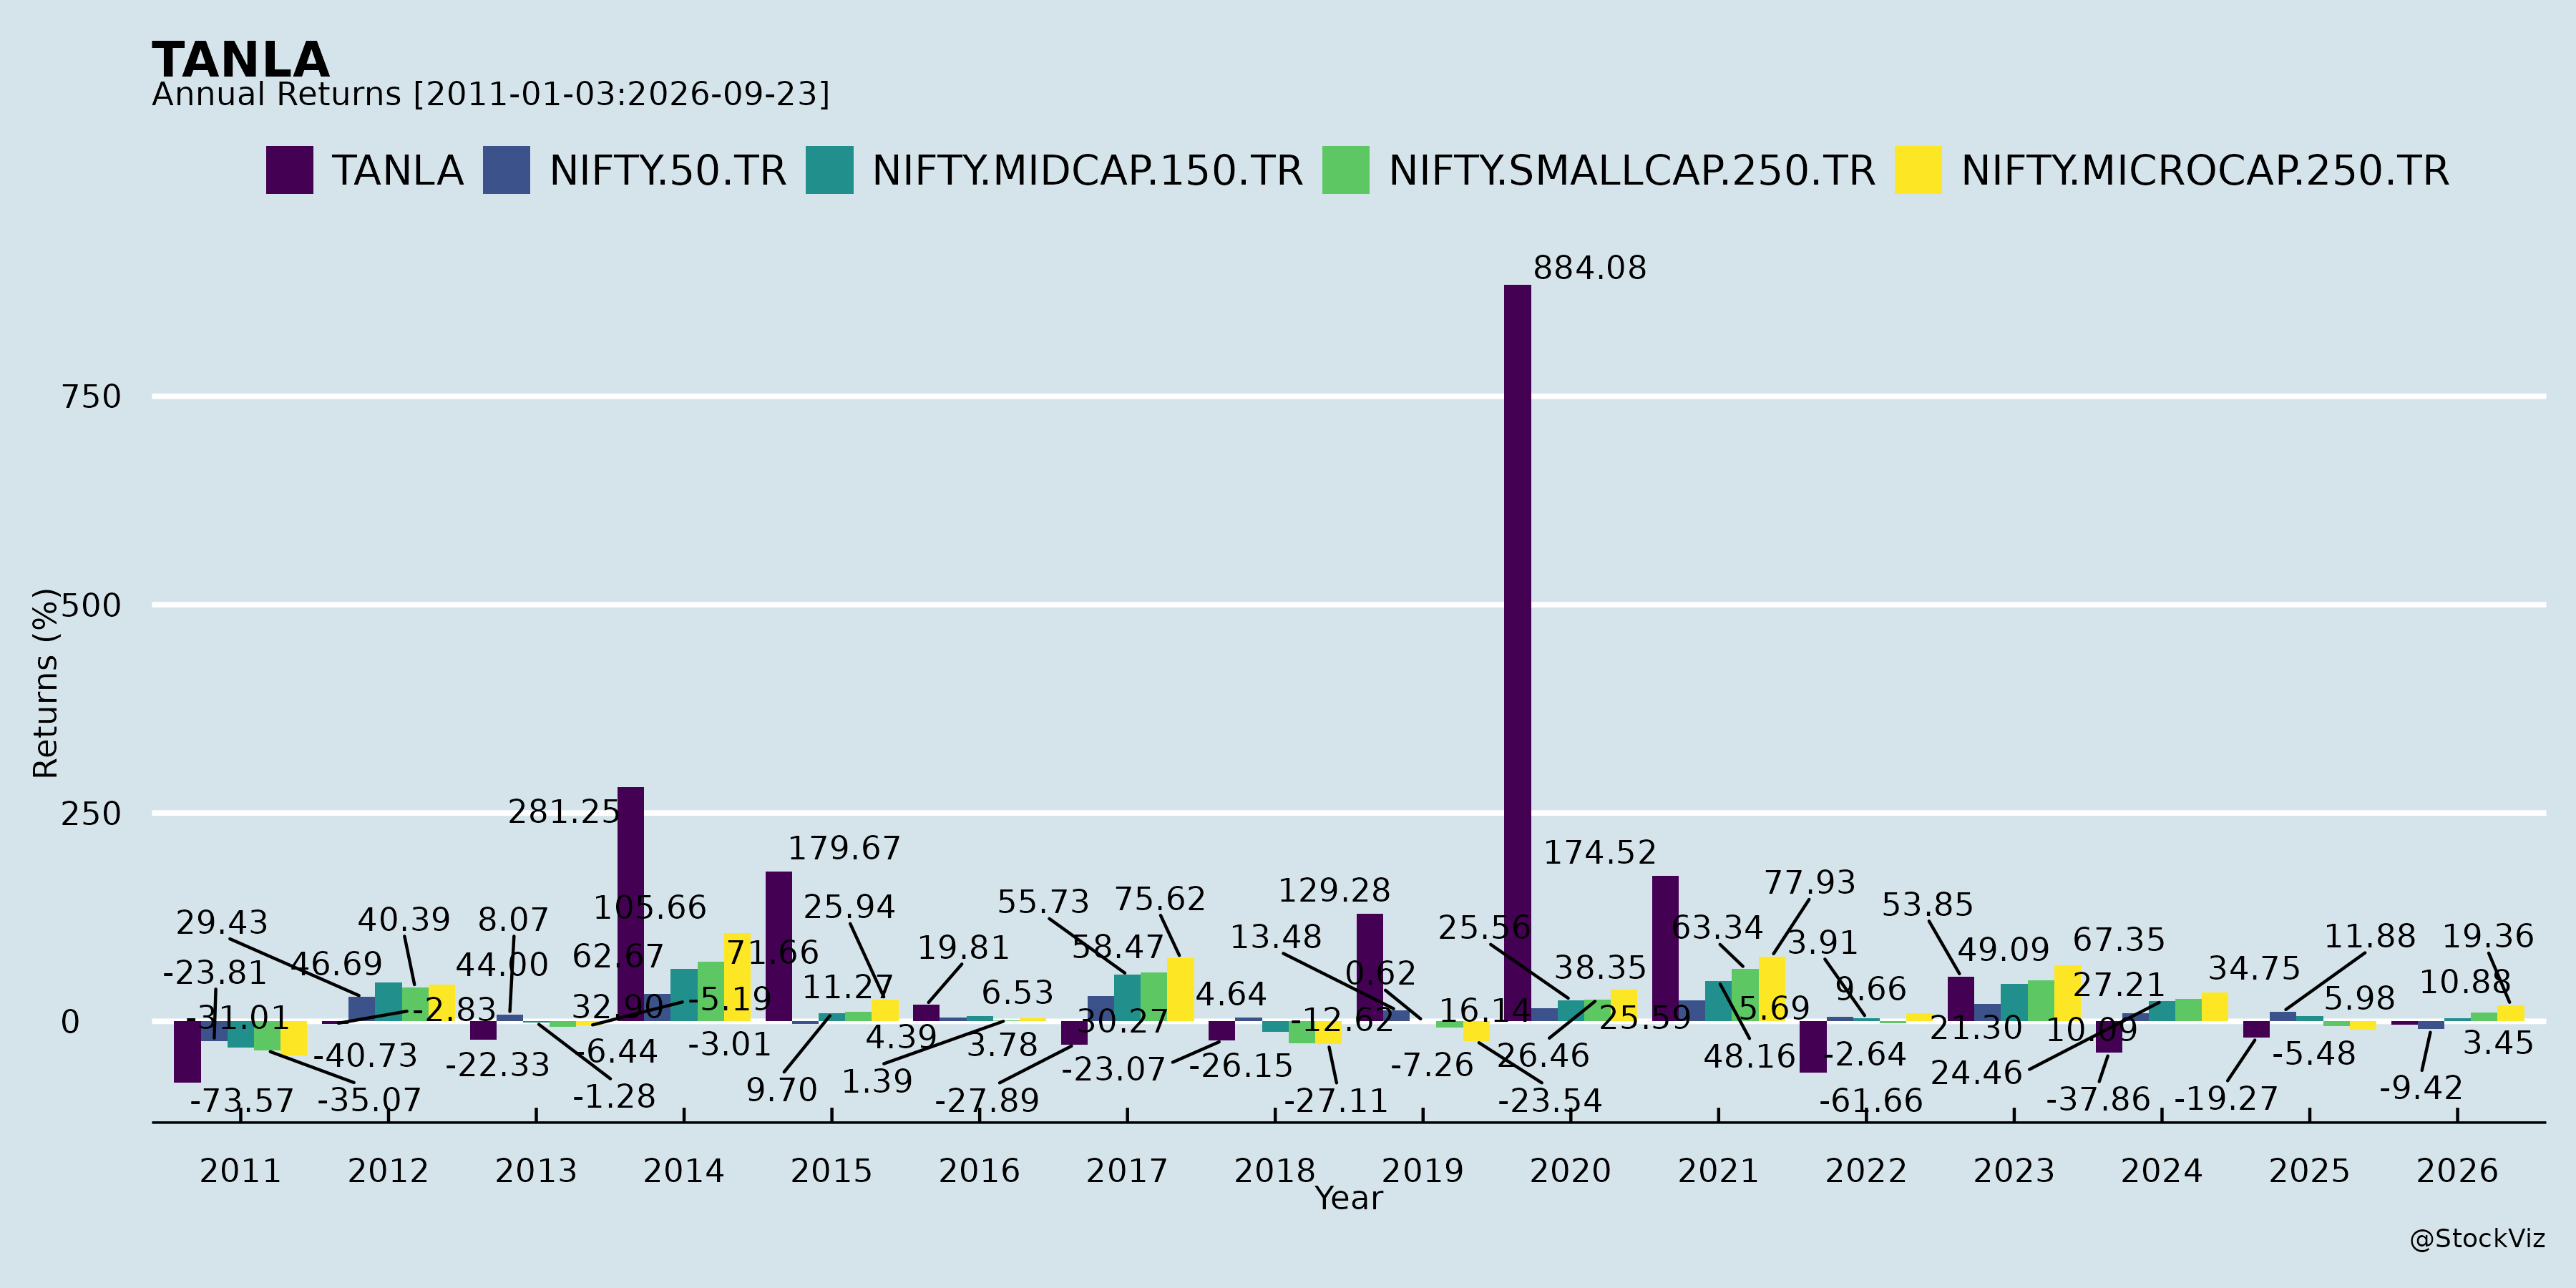
Annual Returns
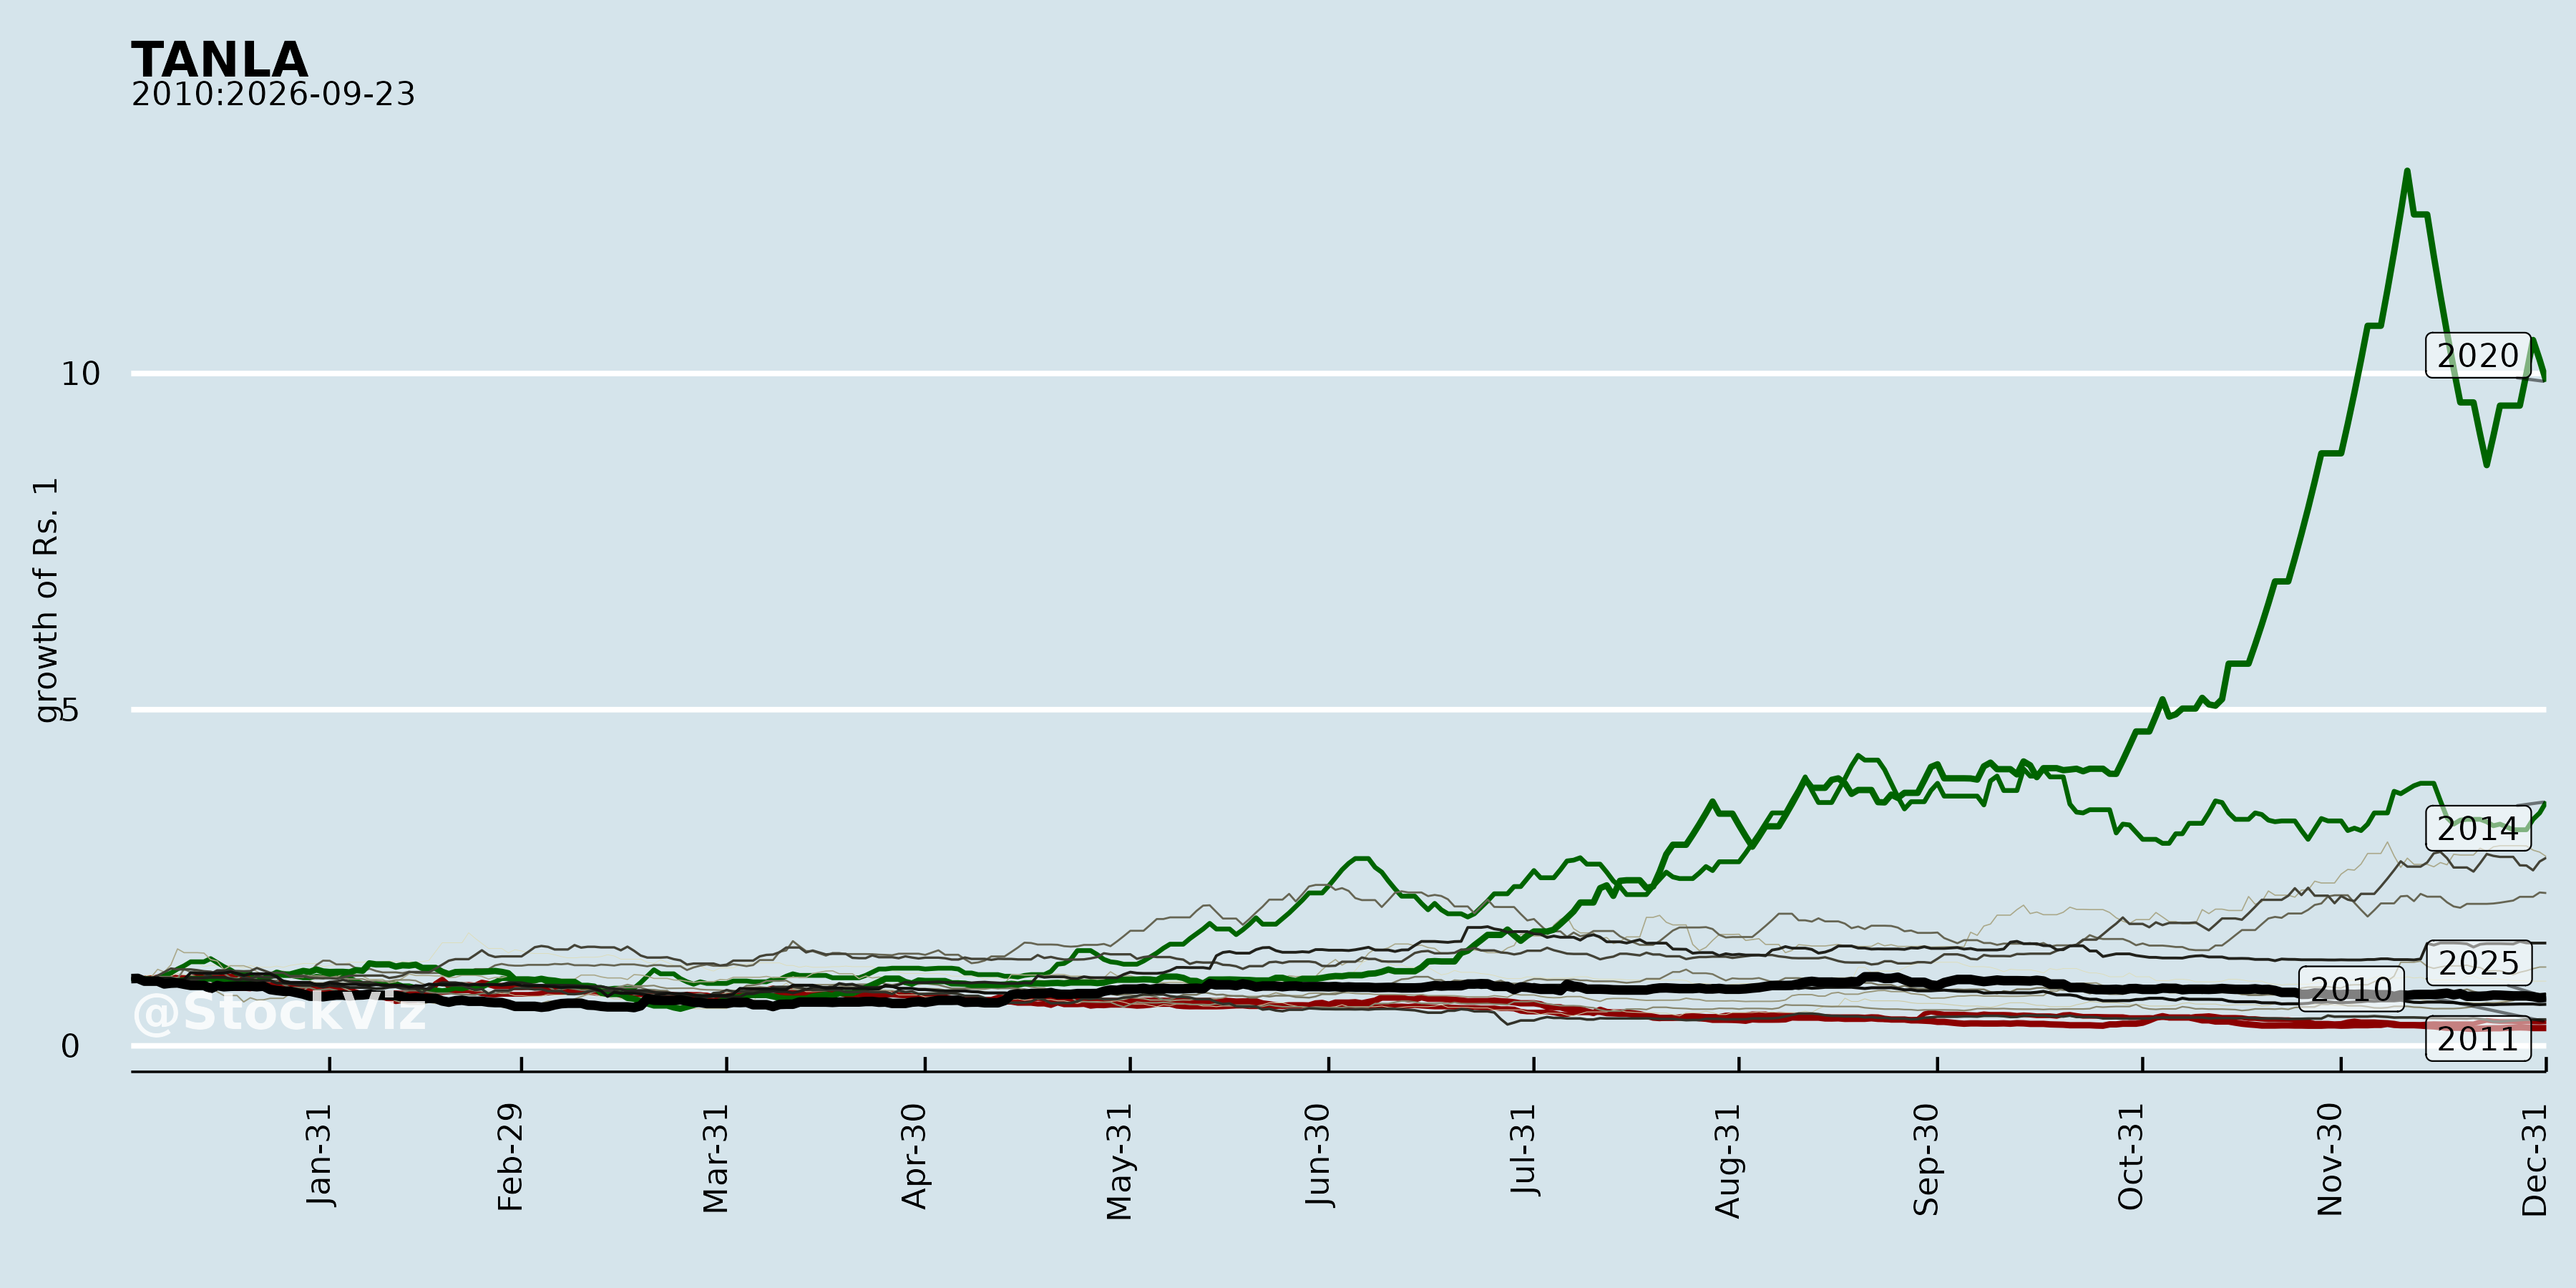
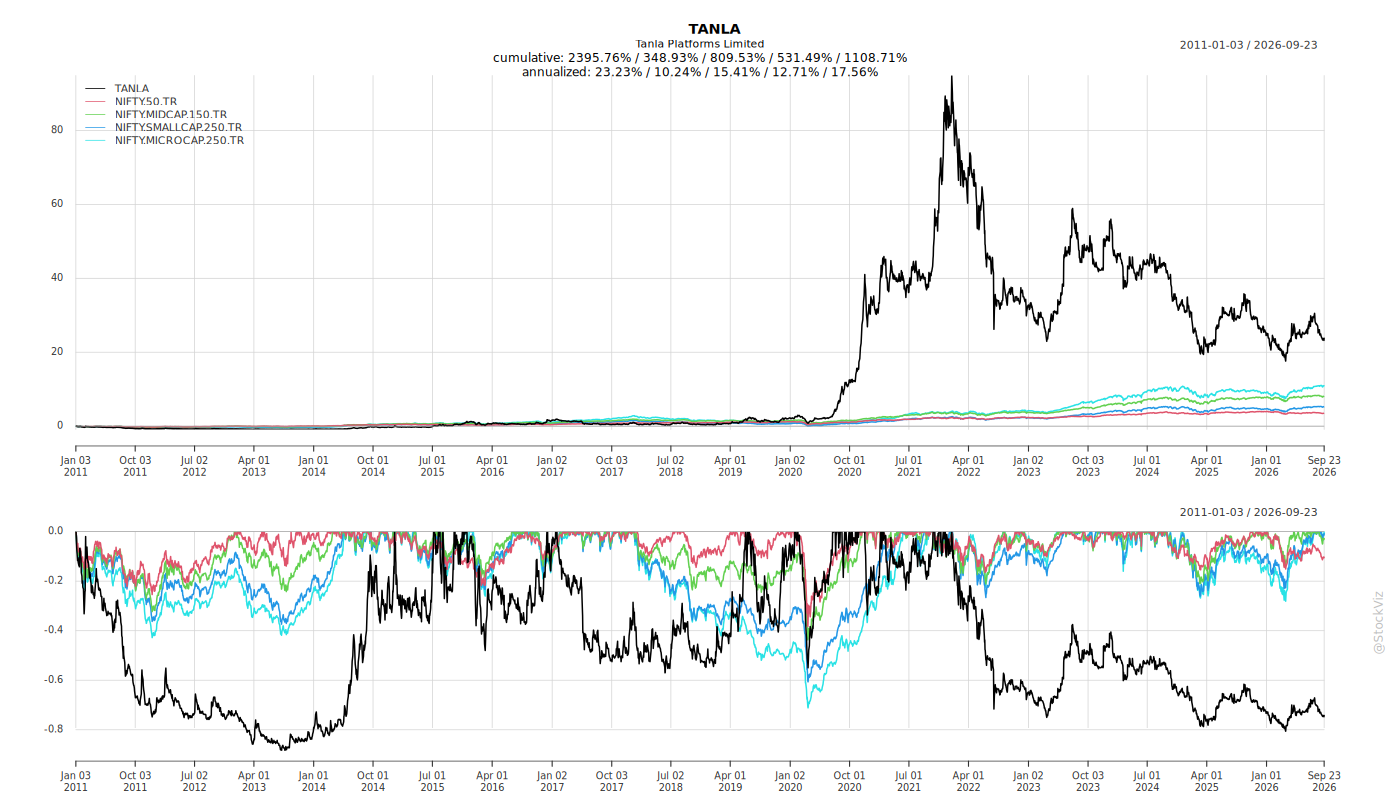
Cumulative Returns and Drawdowns
Fundamentals
Ownership
Margined
AI Summary
asof: 2026-09-17
Tanla Platforms: Recent Corporate Developments
1. Headwinds and Challenges
The company operates in an environment shaped by changes in market conditions, the pace of digital communication adoption, pricing pressure and competition, customer concentration, and shifts in technology standards and platform interoperability. Additional challenges include cyber security incidents, vendor or network dependency, execution and scaling of strategy, changes in applicable laws, regulations and government policies (including adverse regulatory or judicial actions), macroeconomic volatility, geopolitical tensions, sanctions and trade restrictions, global technology-supply-chain disruption, public health events, and political or social instability affecting customers, vendors, partners or infrastructure.
The acquisition of ValueFirst Middle East FZC (VF FZC) brings its own set of considerations. VF FZC’s turnover declined from AED 152.57 million (INR 351.20 crore) in FY 25 to AED 75.50 million (INR 181.63 crore) in FY 26, following an increase from AED 116.51 million (INR 262.63 crore) in FY 24. As on March 31, 2026, VF FZC had a negative net worth of AED 53.54 million (INR 136.52 crore). The aggregate enterprise consideration of AED 58.25 million (INR 148.52 crore) comprises AED 4.61 million (INR 12.00 crore) payable in cash and AED 53.54 million (INR 136.52 crore) representing the assumption and/or discharge of liabilities of VF FZC, including amounts payable to Tanla group entities.
2. Tailwinds and Growth Prospects
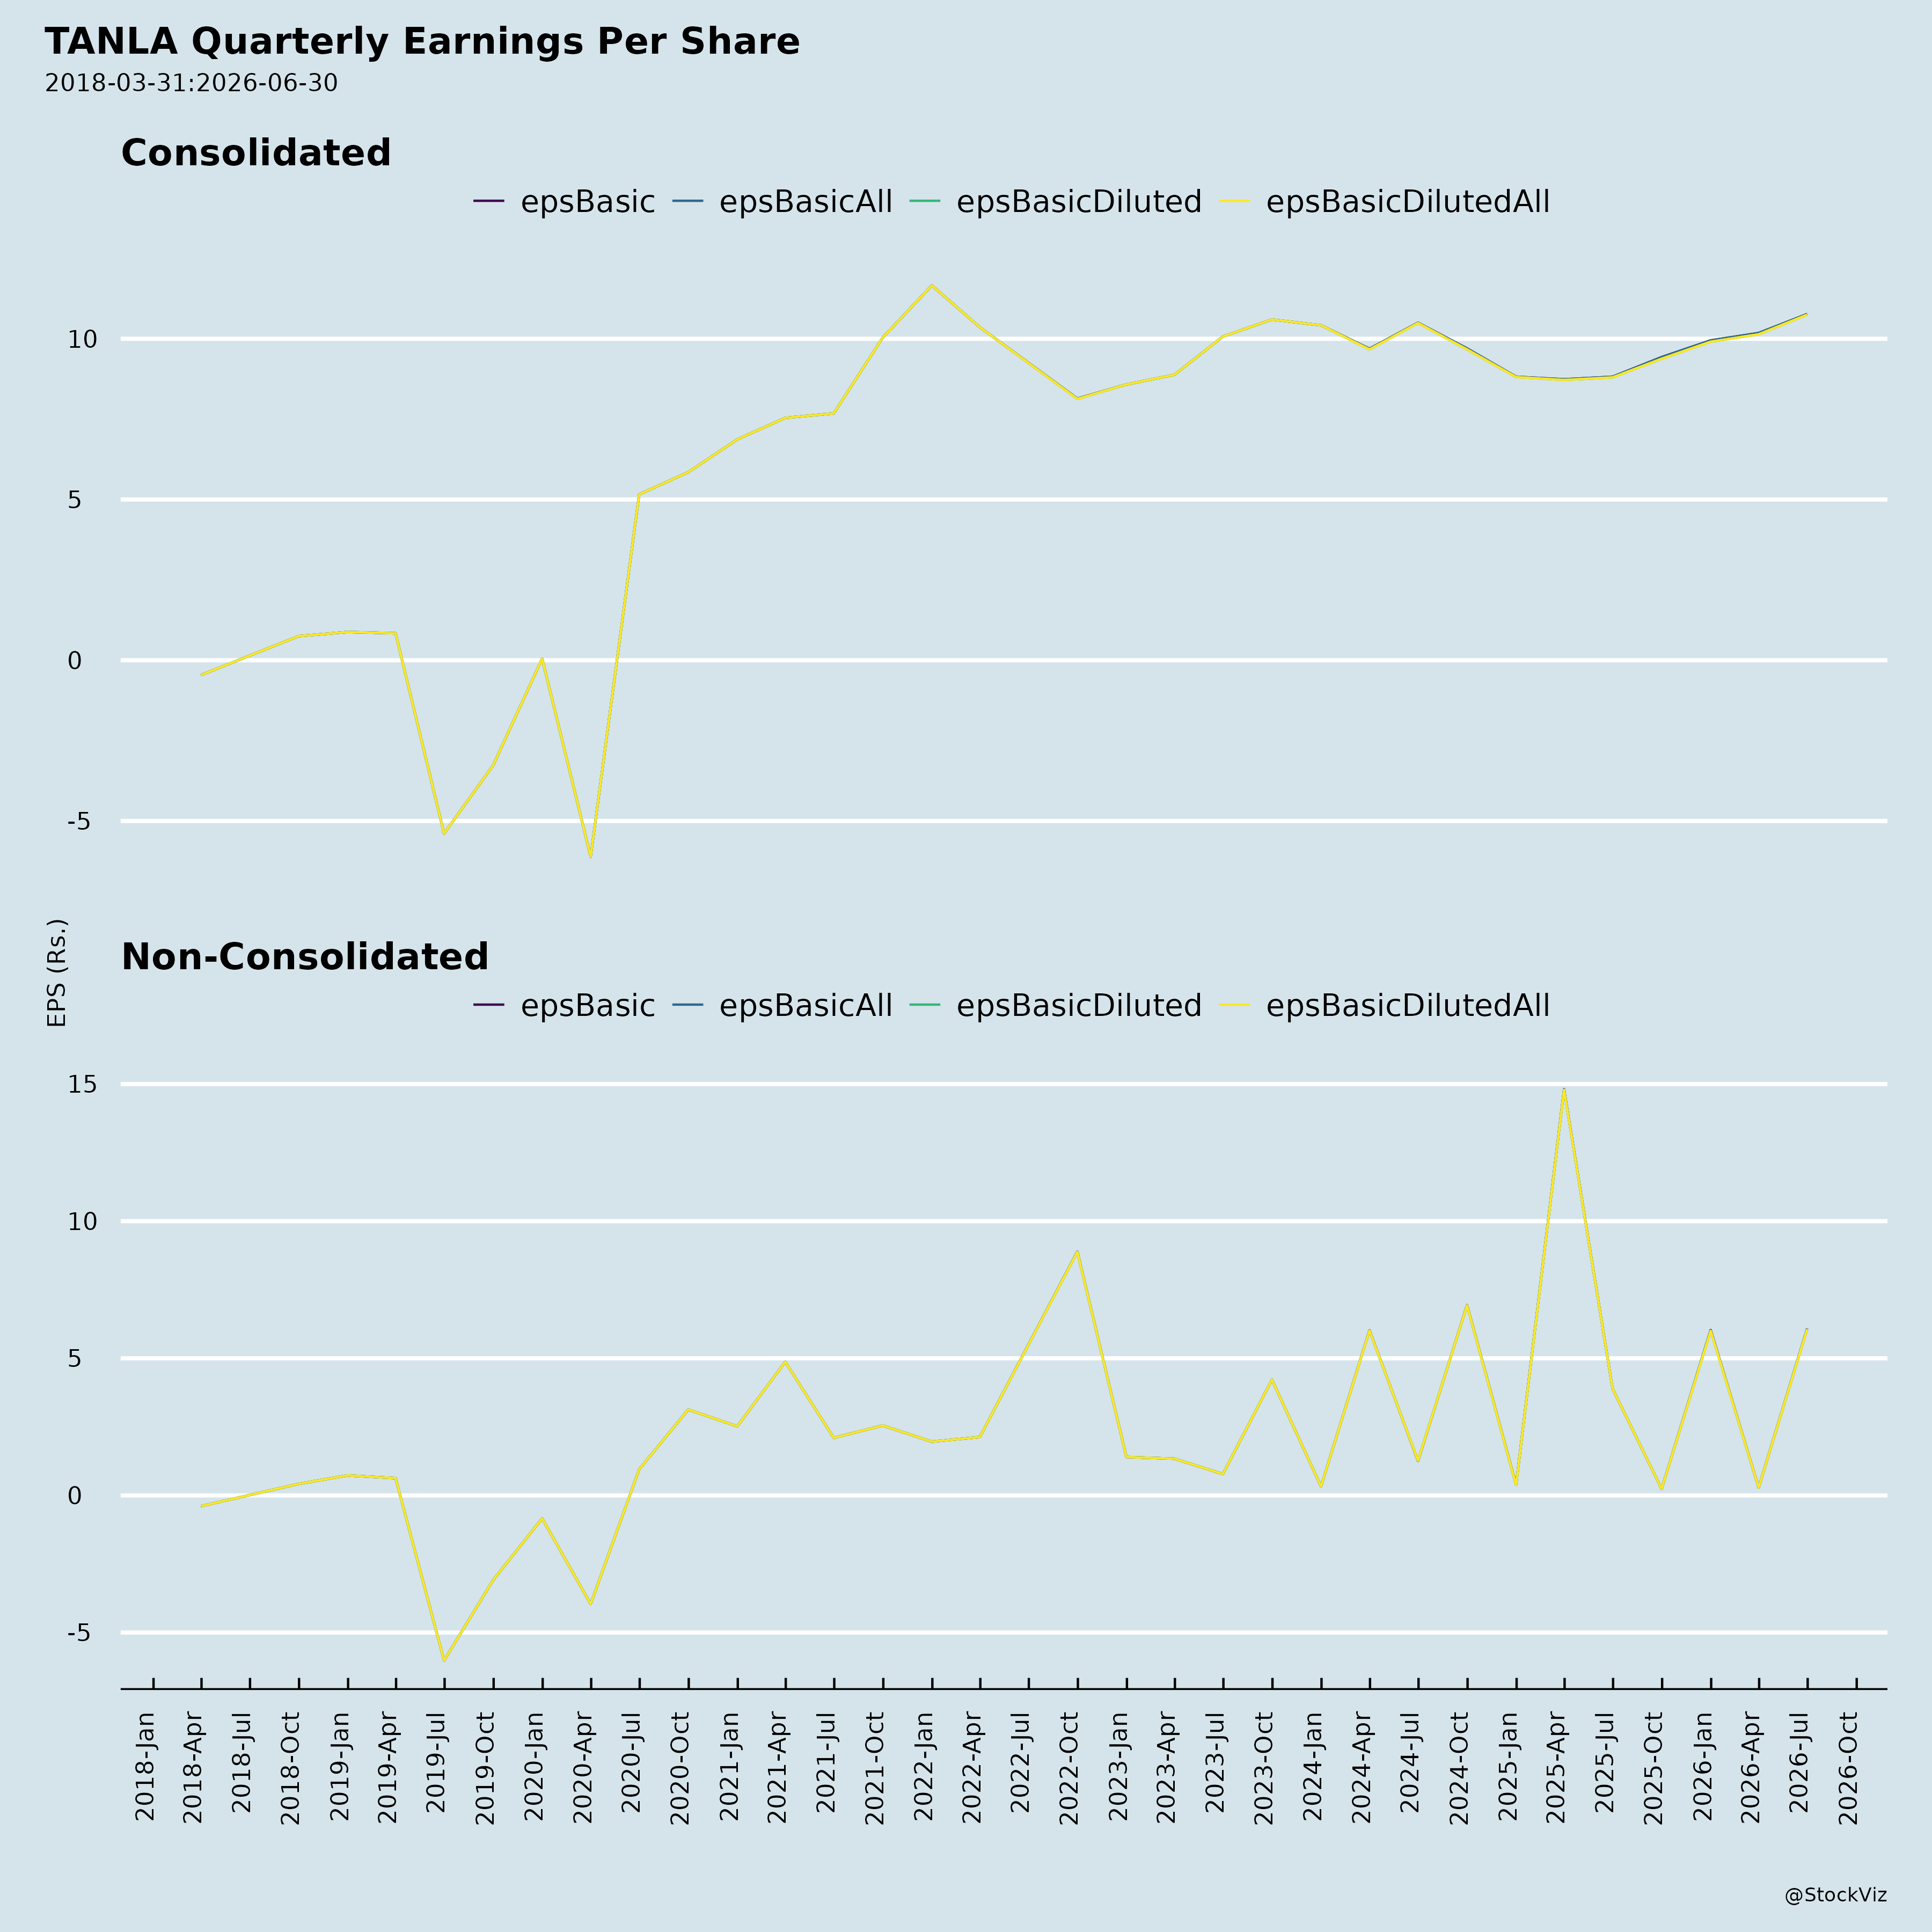
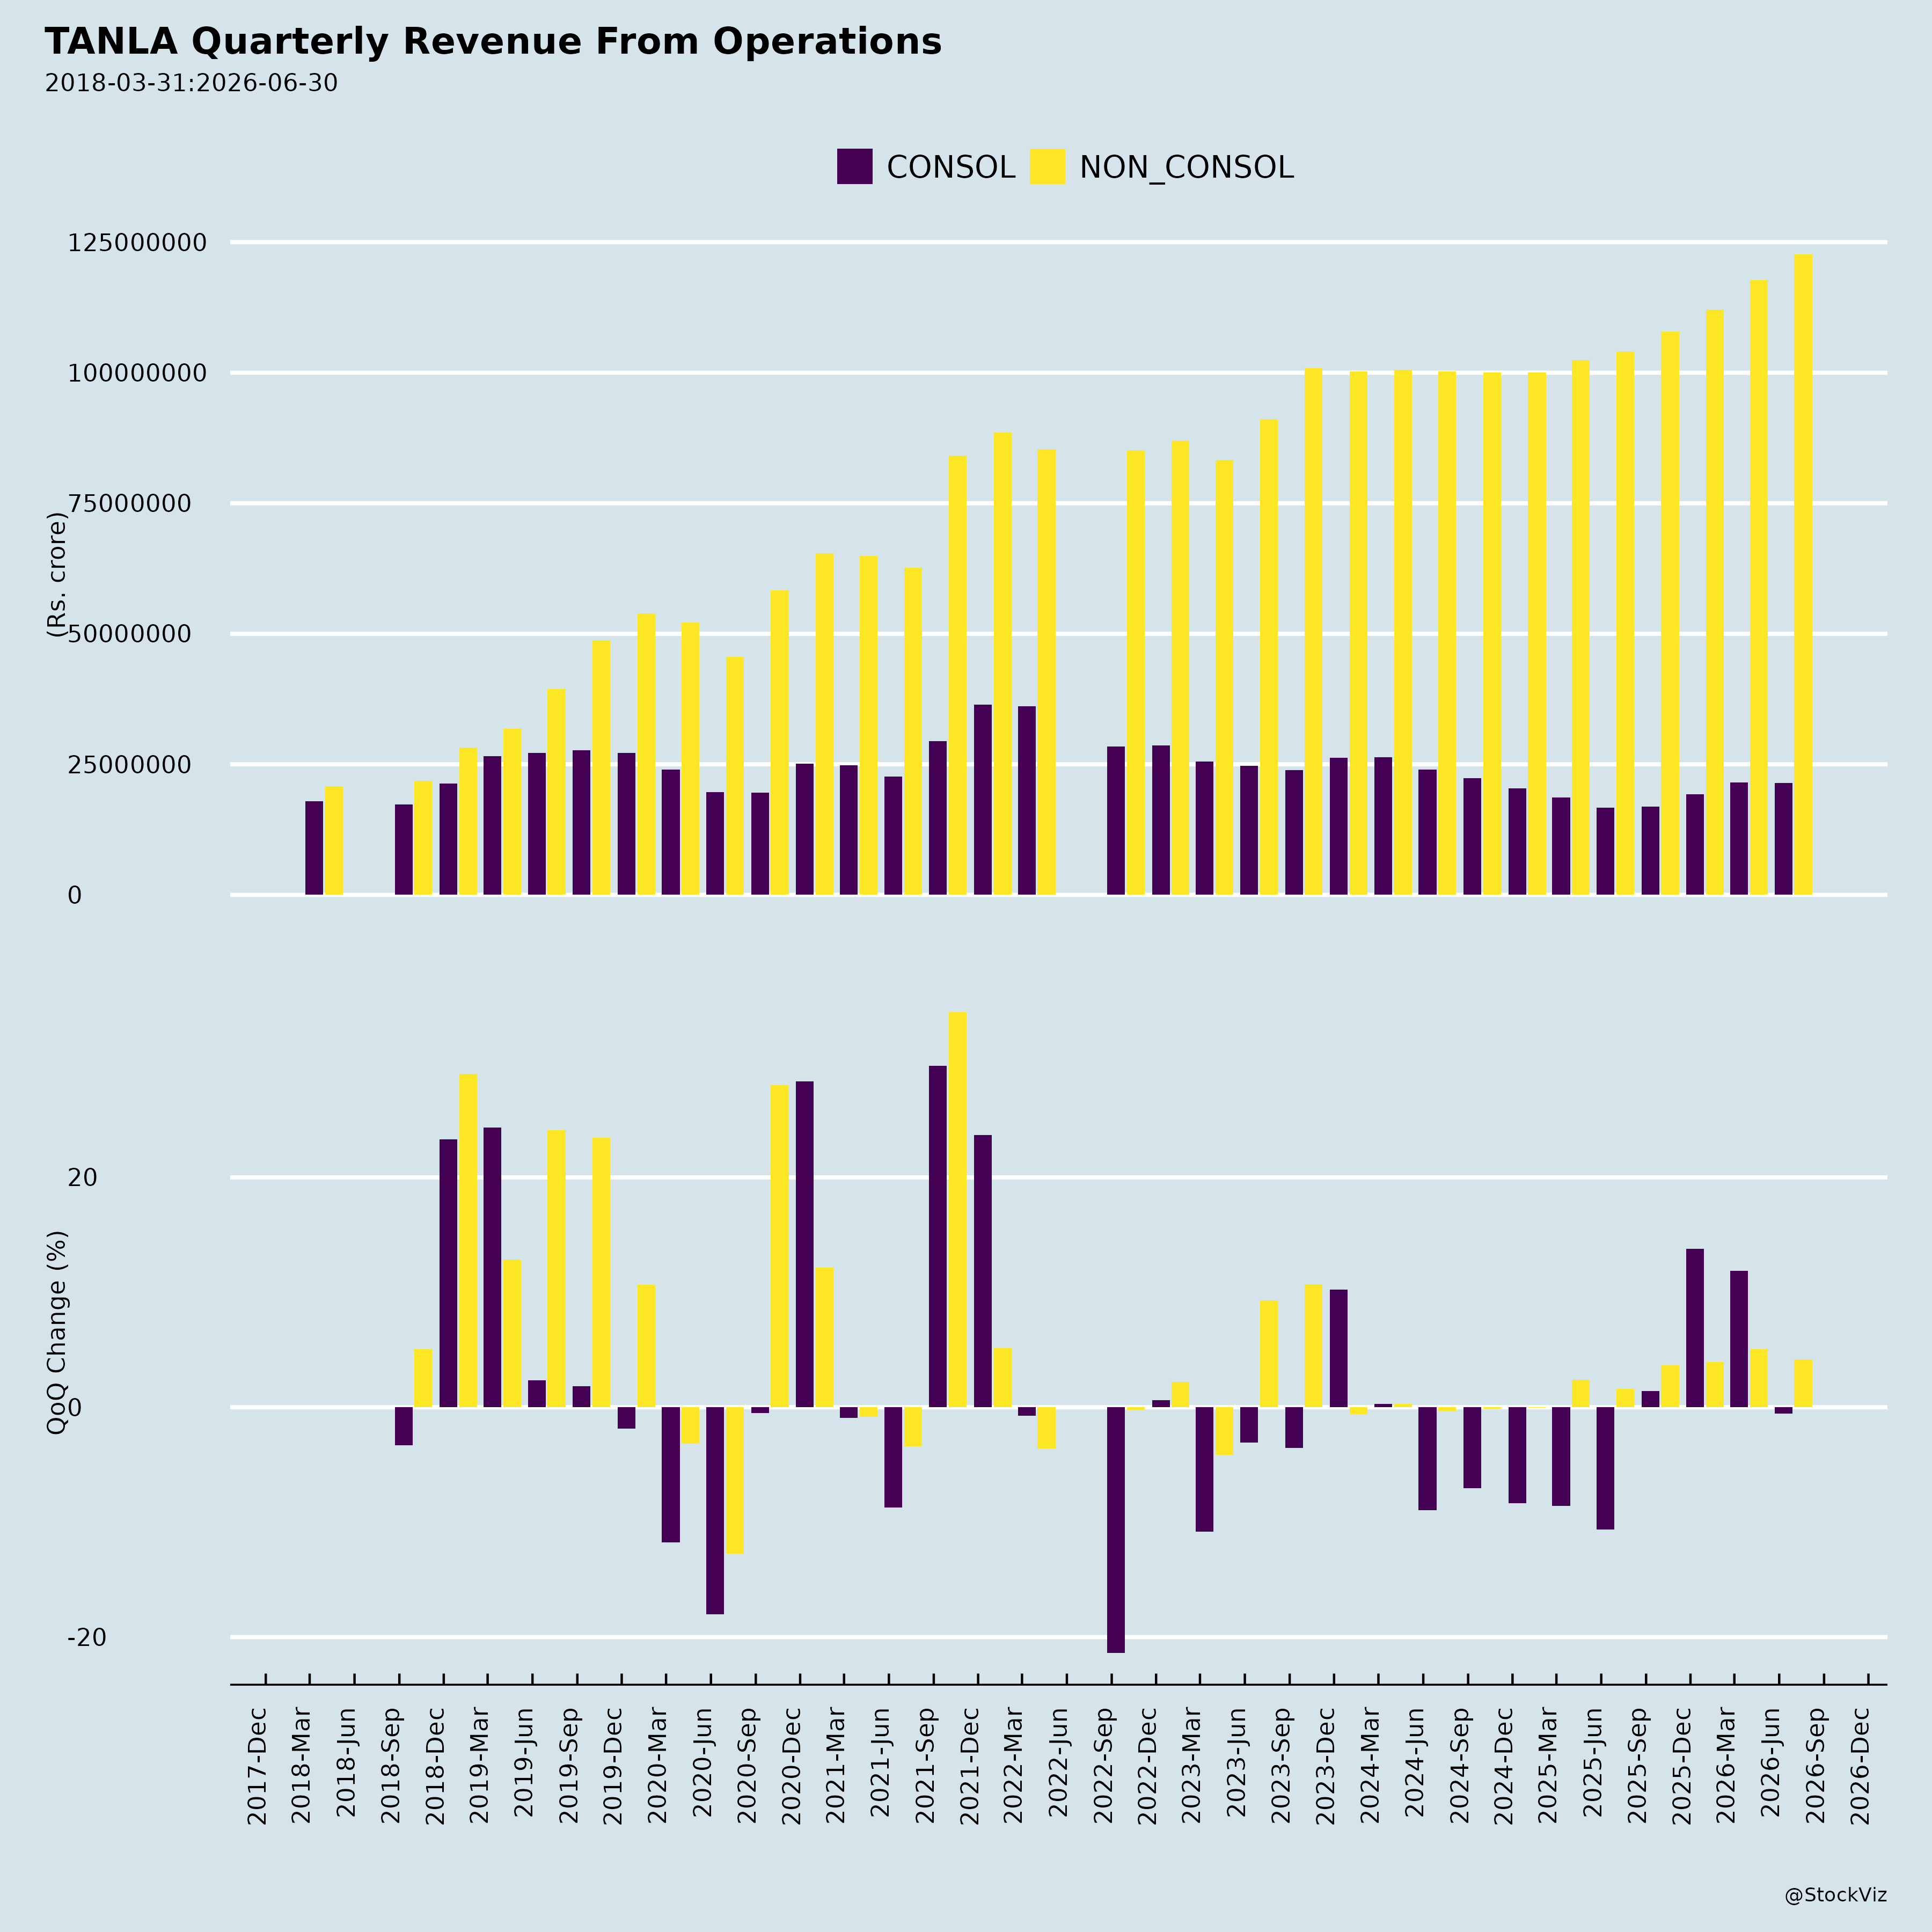
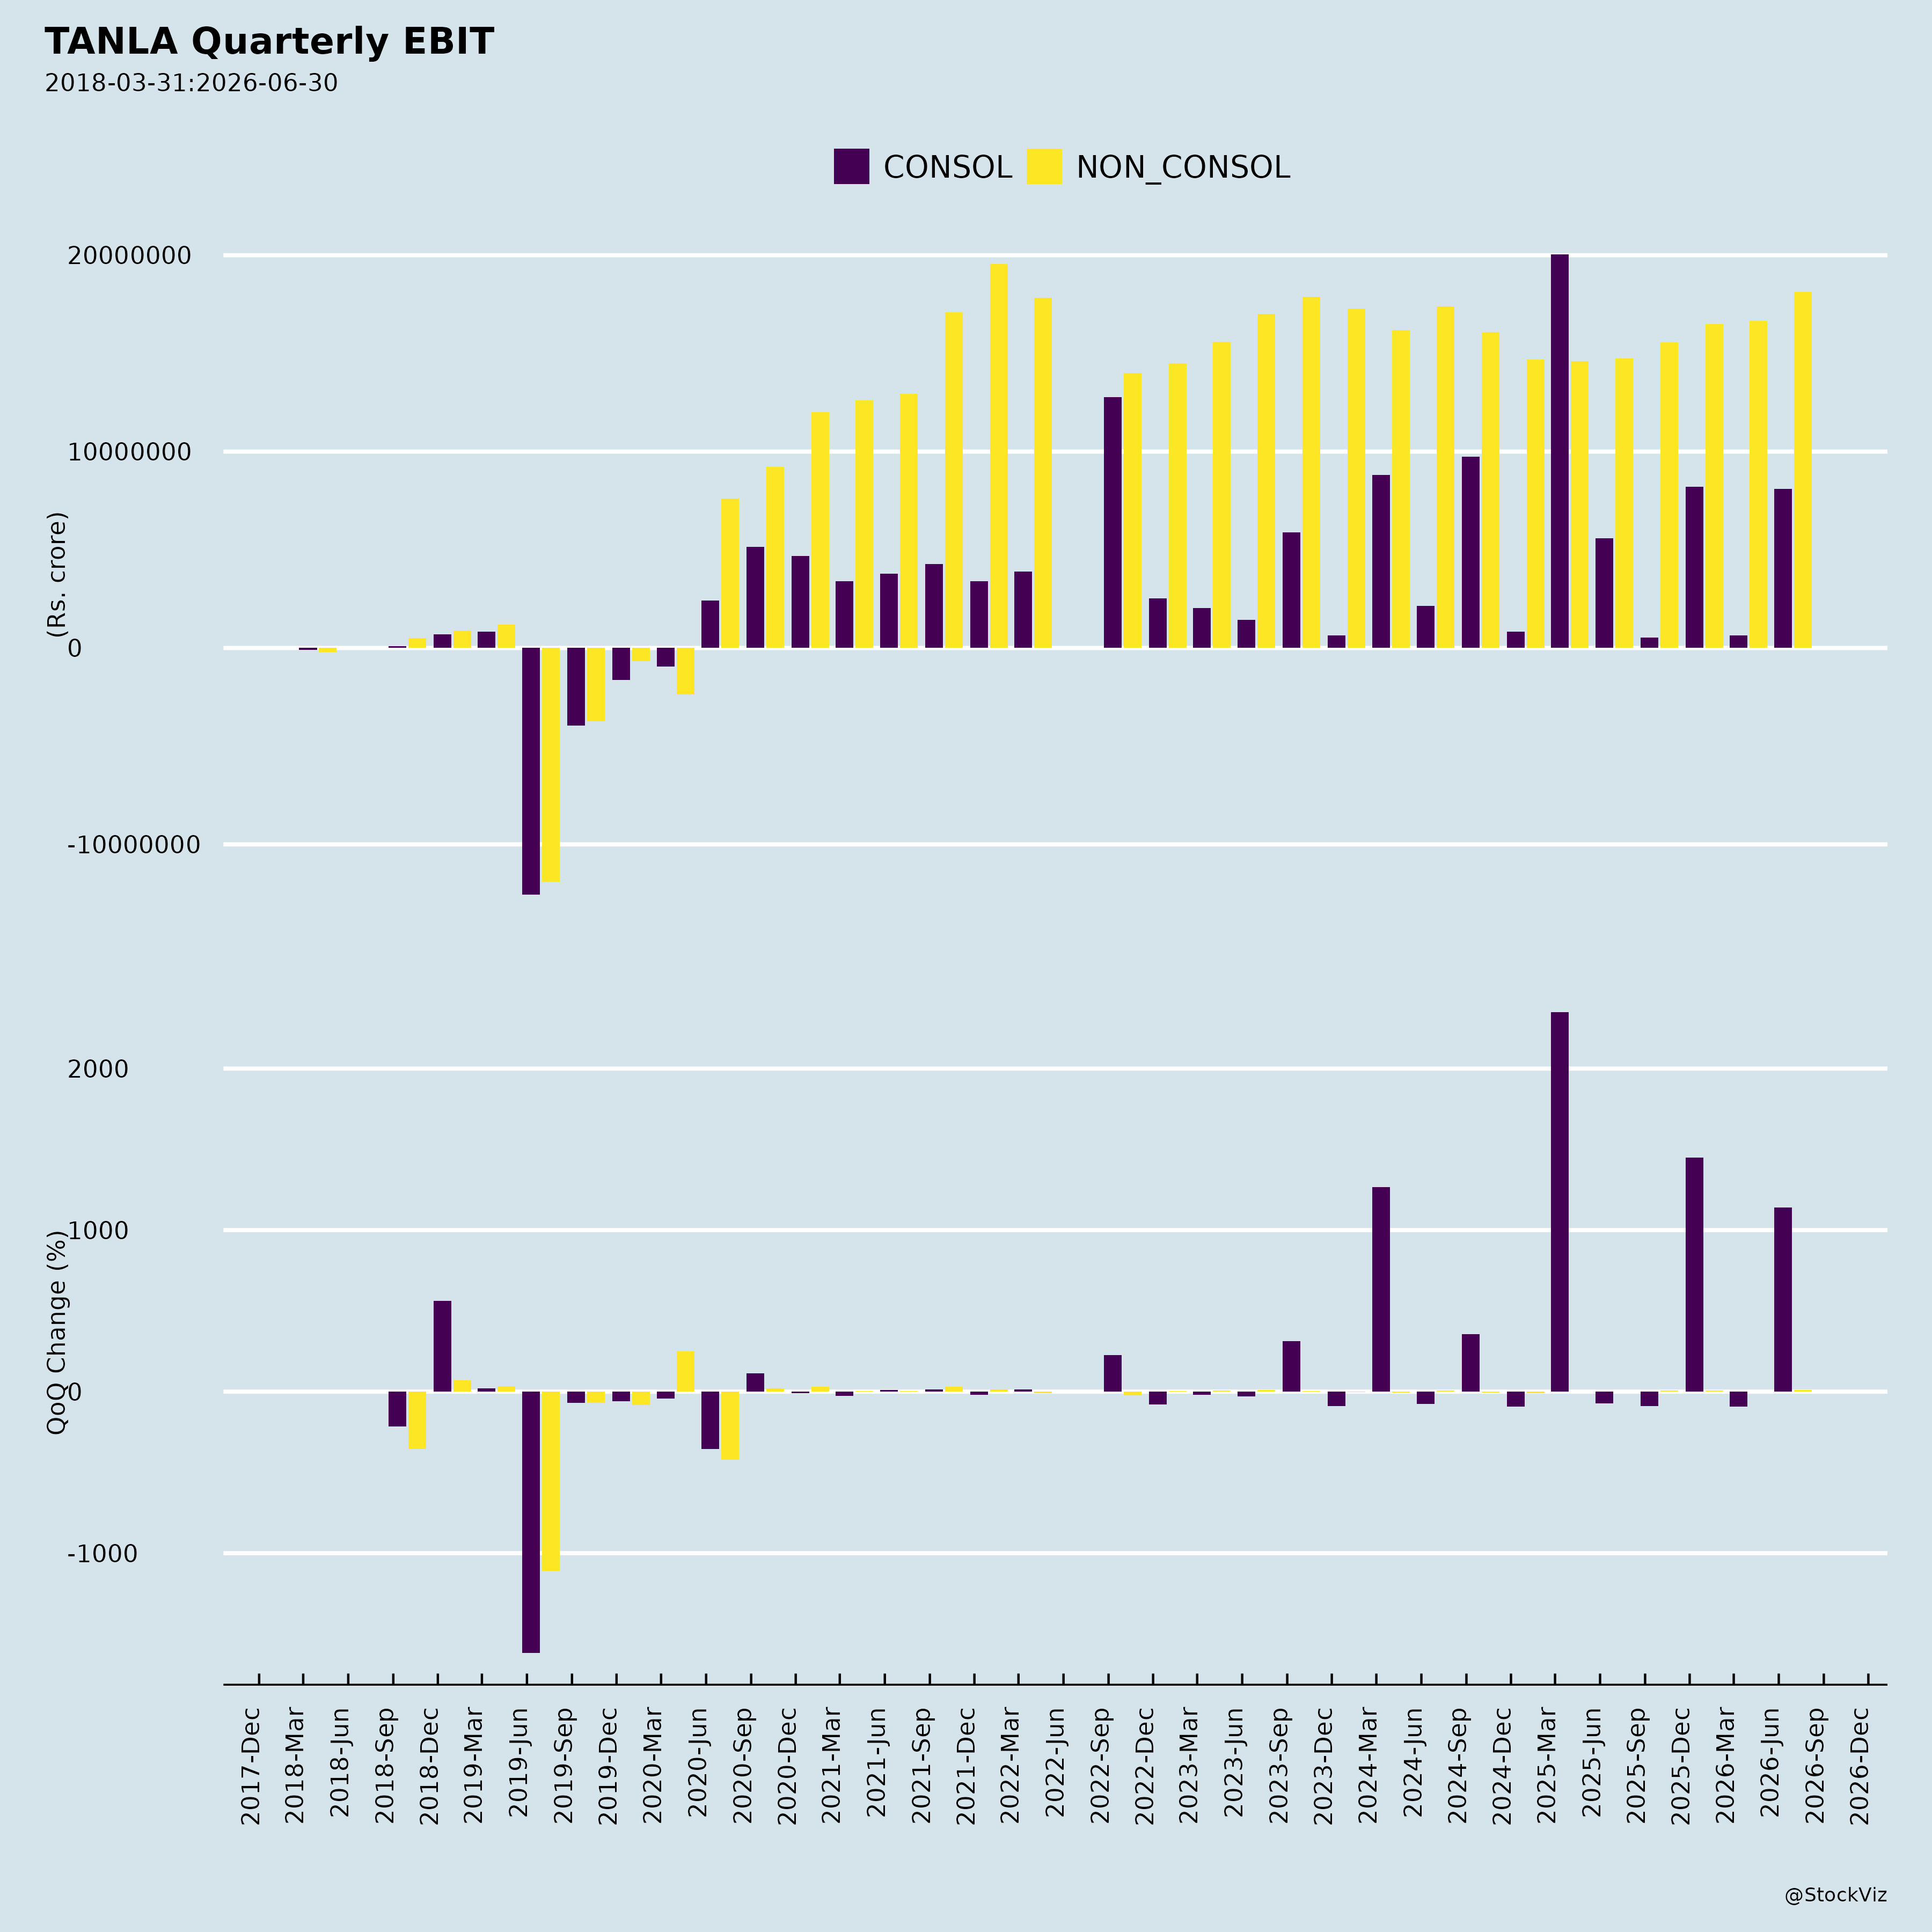
In Q1 FY27 (April–June 2026), revenue was ₹1,226 crore, growing 4.1% QoQ and 17.8% YoY. Gross profit was ₹326 crore, up 2.6% QoQ and 25.1% YoY. EBITDA was ₹201 crore, up 4.9% QoQ and 22.7% YoY. Profit after tax was ₹142 crore, up 5.8% QoQ and 20.1% YoY. Earnings per share stood at ₹10.77, and free cash flow was ₹126 crore, representing 89% of PAT. The company reported a fifth consecutive quarter of revenue growth, double-digit YoY growth across business segments, strong equity and reserves of ₹25,573 Mn, cash and cash equivalents of ₹11,970 Mn, a debt-free status, expansion of customer relationships, and increasing wallet share. Digital Platforms and Enterprise Communications grew by 12.2% and 18.4% YoY respectively.
The proposed acquisition of VF FZC is intended to provide access to the markets and customers in which VF FZC and its subsidiaries operate and to facilitate administrative efficiency. Upon completion, VF FZC and its subsidiaries—ValueFirst Technologies LLC (wholly-owned), PT ValueFirst Komunikasi Indonesia (wholly-owned), and ValueFirst For Telecom & IT Co., KSA (70% owned)—will become indirect subsidiaries of Tanla. VF FZC (including through these subsidiaries) has a presence in UAE, the Kingdom of Saudi Arabia, and Indonesia. The acquisition is estimated to be completed by Q2 of FY 27.
Other developments during the quarter include a London Business School case study on Tanla’s Wisely.ai deployment with Indosat, documenting how the AI-native platform protects over 100 million users in Indonesia from spam and scam communications, and a Special Recognition at the IIT Madras Social Impact Awards 2026 for the Cyberabad Traffic Pulse initiative, building on recognition at the Global CSR and ESG Awards in 2025. Tanla was recognized as a ‘Visionary’ in the 2026 Gartner® Magic Quadrant™ and ranked among the “1000 High-Growth Companies in Asia Pacific” by the Financial Times.
3. Key Risks
The material risks include changes in market conditions; the pace of digital communication adoption; pricing pressure and competition; customer concentration; shifts in technology standards and platform interoperability; cyber security incidents; vendor or network dependency; the ability to execute strategy and scale operations; changes in applicable laws, regulations and government policies, including adverse regulatory or judicial actions; macroeconomic volatility; geopolitical tensions; sanctions and trade restrictions; global technology-supply-chain disruption; public health events; and political or social instability affecting customers, vendors, partners or infrastructure.
Specific to the VF FZC transaction, the acquisition is subject to the terms and conditions set out in the Share Purchase Agreement executed by and amongst Karix Mobile FZ LLC (a subsidiary of the Company), VF FZC, and the existing shareholders of VF FZC. The transaction involves the assumption and/or discharge of liabilities, including amounts payable to Tanla group entities. No governmental or regulatory approvals are required for the acquisition.
4. Management Guidance Versus Observed Business Performance
Management stated that Q1 FY27 is a strong start to the year, with revenue growing 17.8% YoY and gross profit and EBITDA growing even faster, reflecting an improving quality of growth. Management emphasized that the objective is not revenue growth at any cost, but profitable growth that consistently converts into cash. Observed performance for Q1 FY27 shows revenue of ₹1,226 crore (up 17.8% YoY), gross profit of ₹326 crore (up 25.1% YoY), EBITDA of ₹201 crore (up 22.7% YoY), PAT of ₹142 crore (up 20.1% YoY), and free cash flow of ₹126 crore (89% of PAT). The company reported a fifth consecutive quarter of revenue growth and double-digit YoY growth across business segments.
The proposed acquisition of VF FZC is estimated to be completed by Q2 of FY 27, with the Board approving the execution of the Share Purchase Agreement on July 28, 2026. The 30th Annual General Meeting was held on July 20, 2026, through video conferencing and other audio-visual means, and all resolutions set out in the notice dated June 23, 2026, were passed with the requisite majority.
Broker Narrative
The first report built a Buy thesis on CPaaS market growth, telco A2P SMS price hikes, ValueFirst acquisitions, and high-margin platform economics, while flagging enterprise margin compression and flat message volumes. By the last report, the TANLA-specific narrative was effectively abandoned: the headwinds/tailwinds listed there refer to KG D6, CBM, polyester, and O2C margins, which are unrelated to the original CPaaS/enterprise-messaging setup. The only persistent theme across all seven reports is a reiterated Buy call that produced uniformly negative actual returns and DISAPPOINTMENT outcomes.
Fears that came true
- Enterprise gross margin compression from 20.1% in Q4FY23 to 19.0% in Q1FY24 was flagged early and the stock still delivered -51.7% on the first horizon, indicating the pressure was not resolved.
- Flat Trubloq message volumes at 82 billion QoQ were flagged as a stagnation risk, and every subsequent report ended in DISAPPOINTMENT, suggesting messaging volumes did not become a growth driver.
- The increase in DSO to 67 days, higher depreciation, and higher finance costs were flagged as cost/working-capital drags, and the repeated negative returns imply those pressures continued to weigh on the investment case.
Optimism that failed
- The expectation that CPaaS market growth at >20% CAGR and telco A2P SMS price hikes would drive TANLA failed to materialize in returns, as the stock fell -51.7%, -42.8%, and -41.9% in the first three horizons.
- The major client win with the world’s largest e-commerce/cloud company and the ValueFirst acquisitions did not prevent negative outcomes, with the post-acquisition horizon returning -42.8%.
- The high-margin platform segment and improved EBITDA-to-gross-profit conversion did not translate into shareholder value, as every report in the call history ended in DISAPPOINTMENT.
Broker Timeline
4 broker calls · 2024-04-16 to 2025-10-20
Copyright © 2023 SAS Data Analytics Pvt. Ltd. All rights reserved.