SYRMA
Equity Metrics
November 16, 2026
Syrma SGS Technology Limited
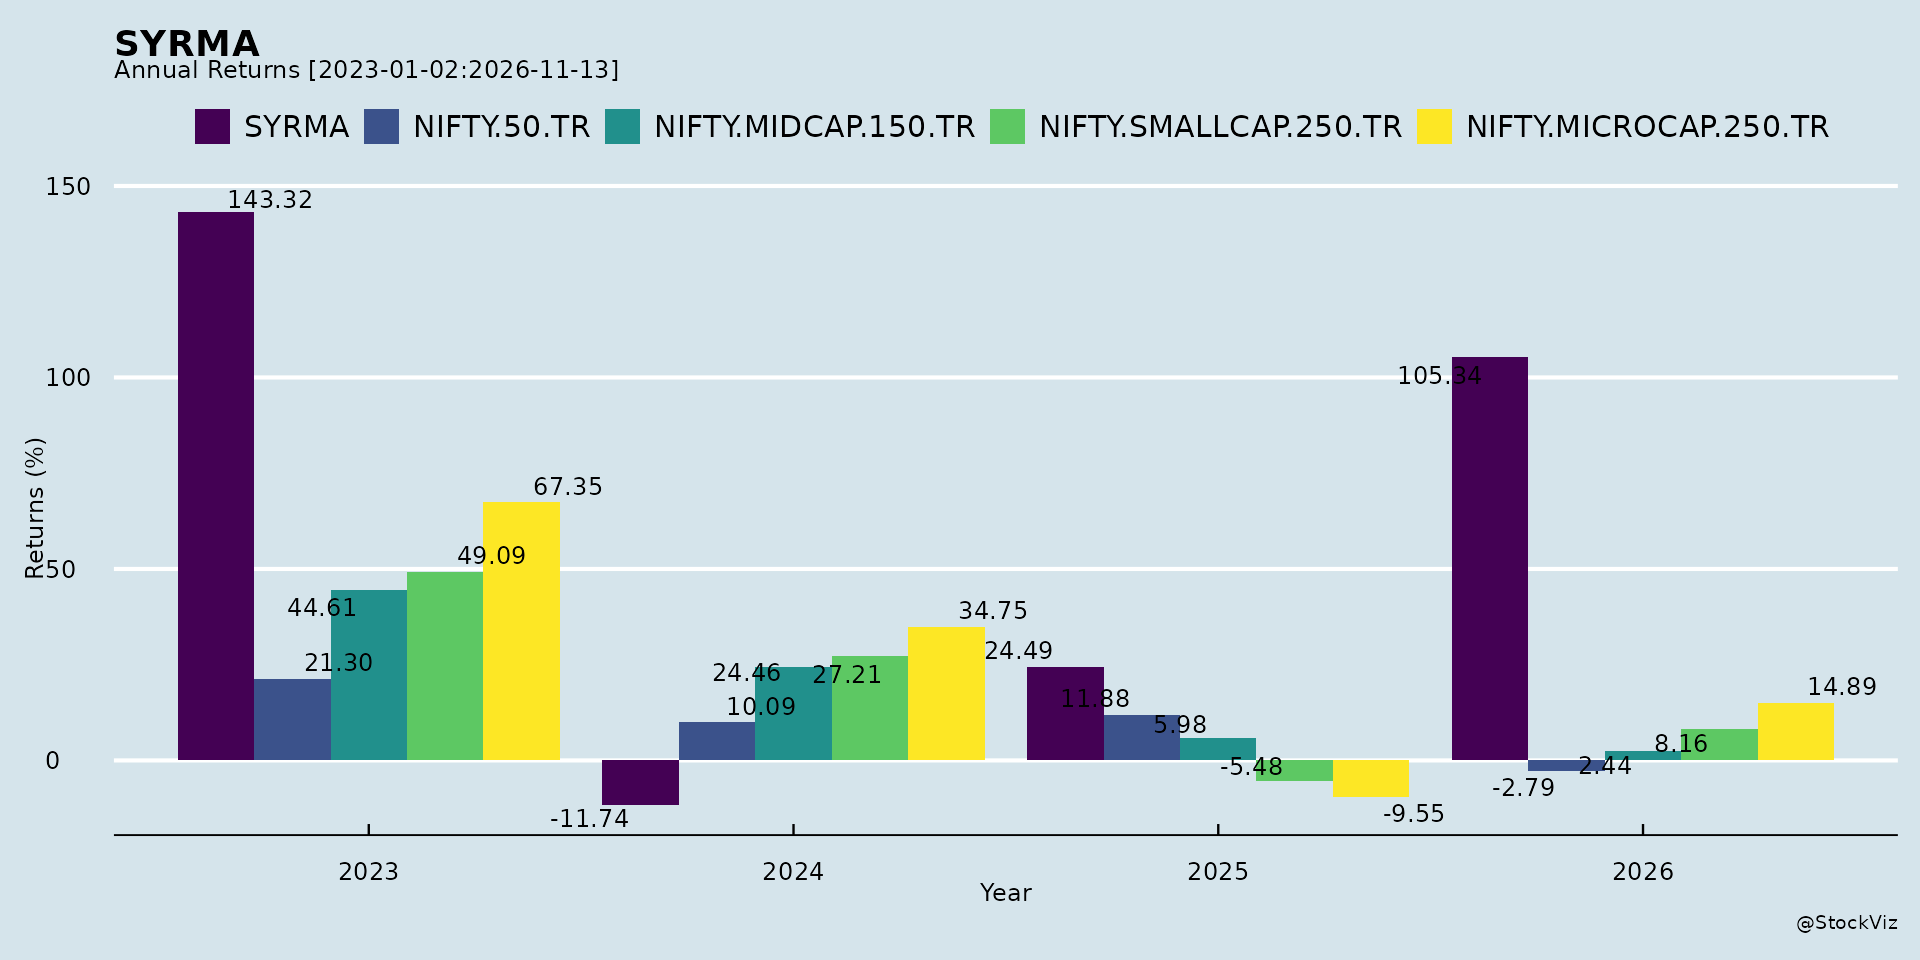
Annual Returns
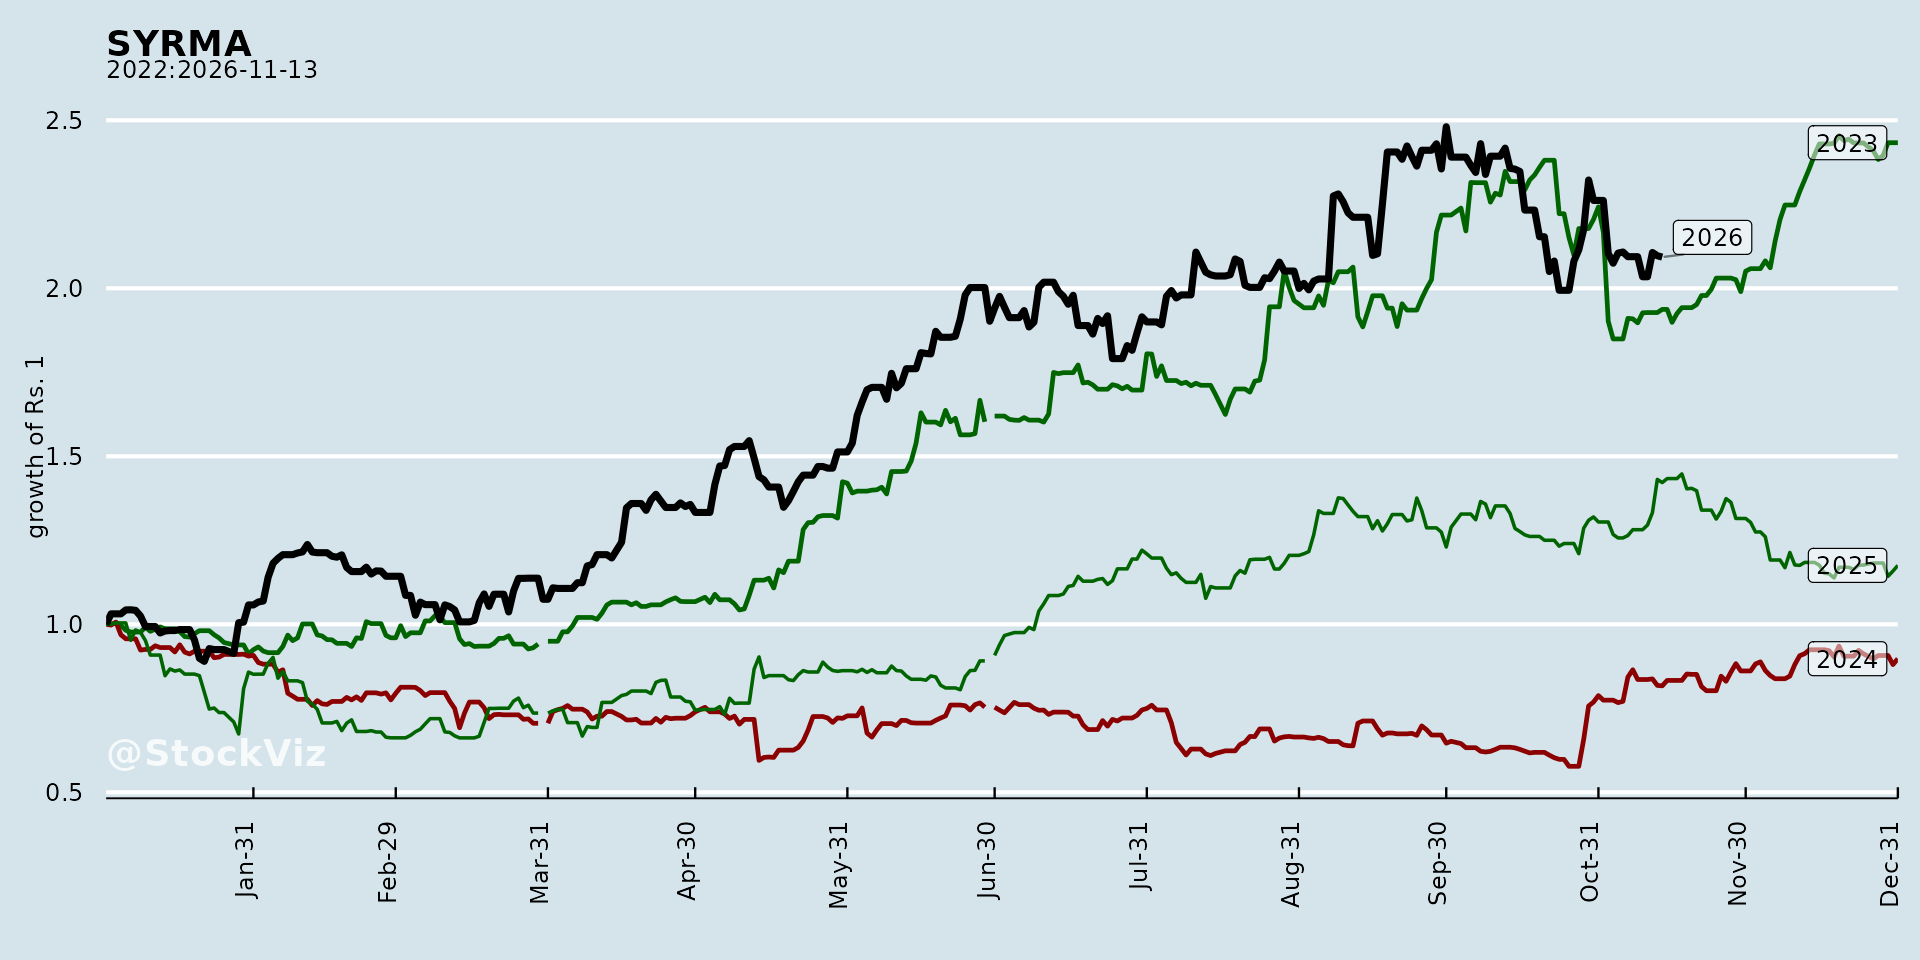
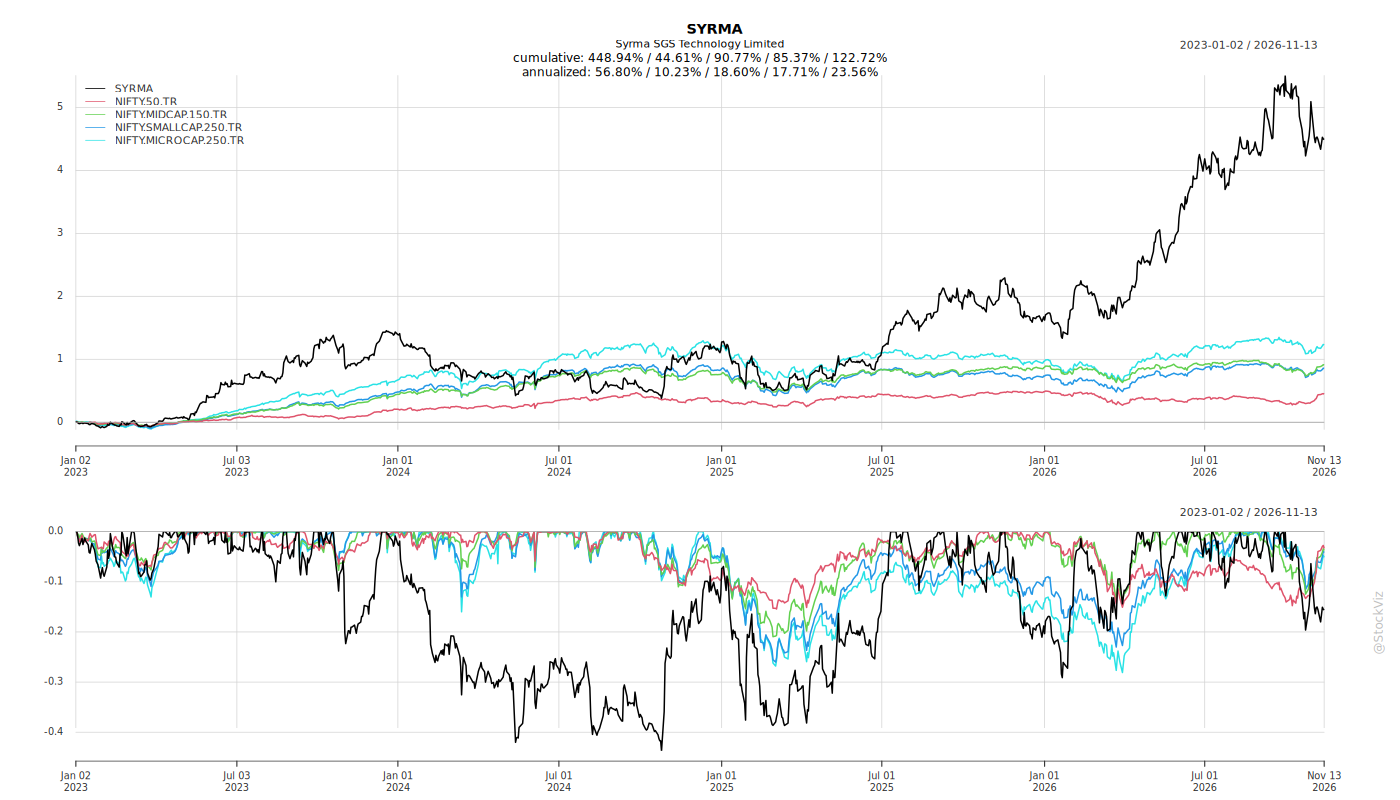
Cumulative Returns and Drawdowns
Fundamentals
Ownership
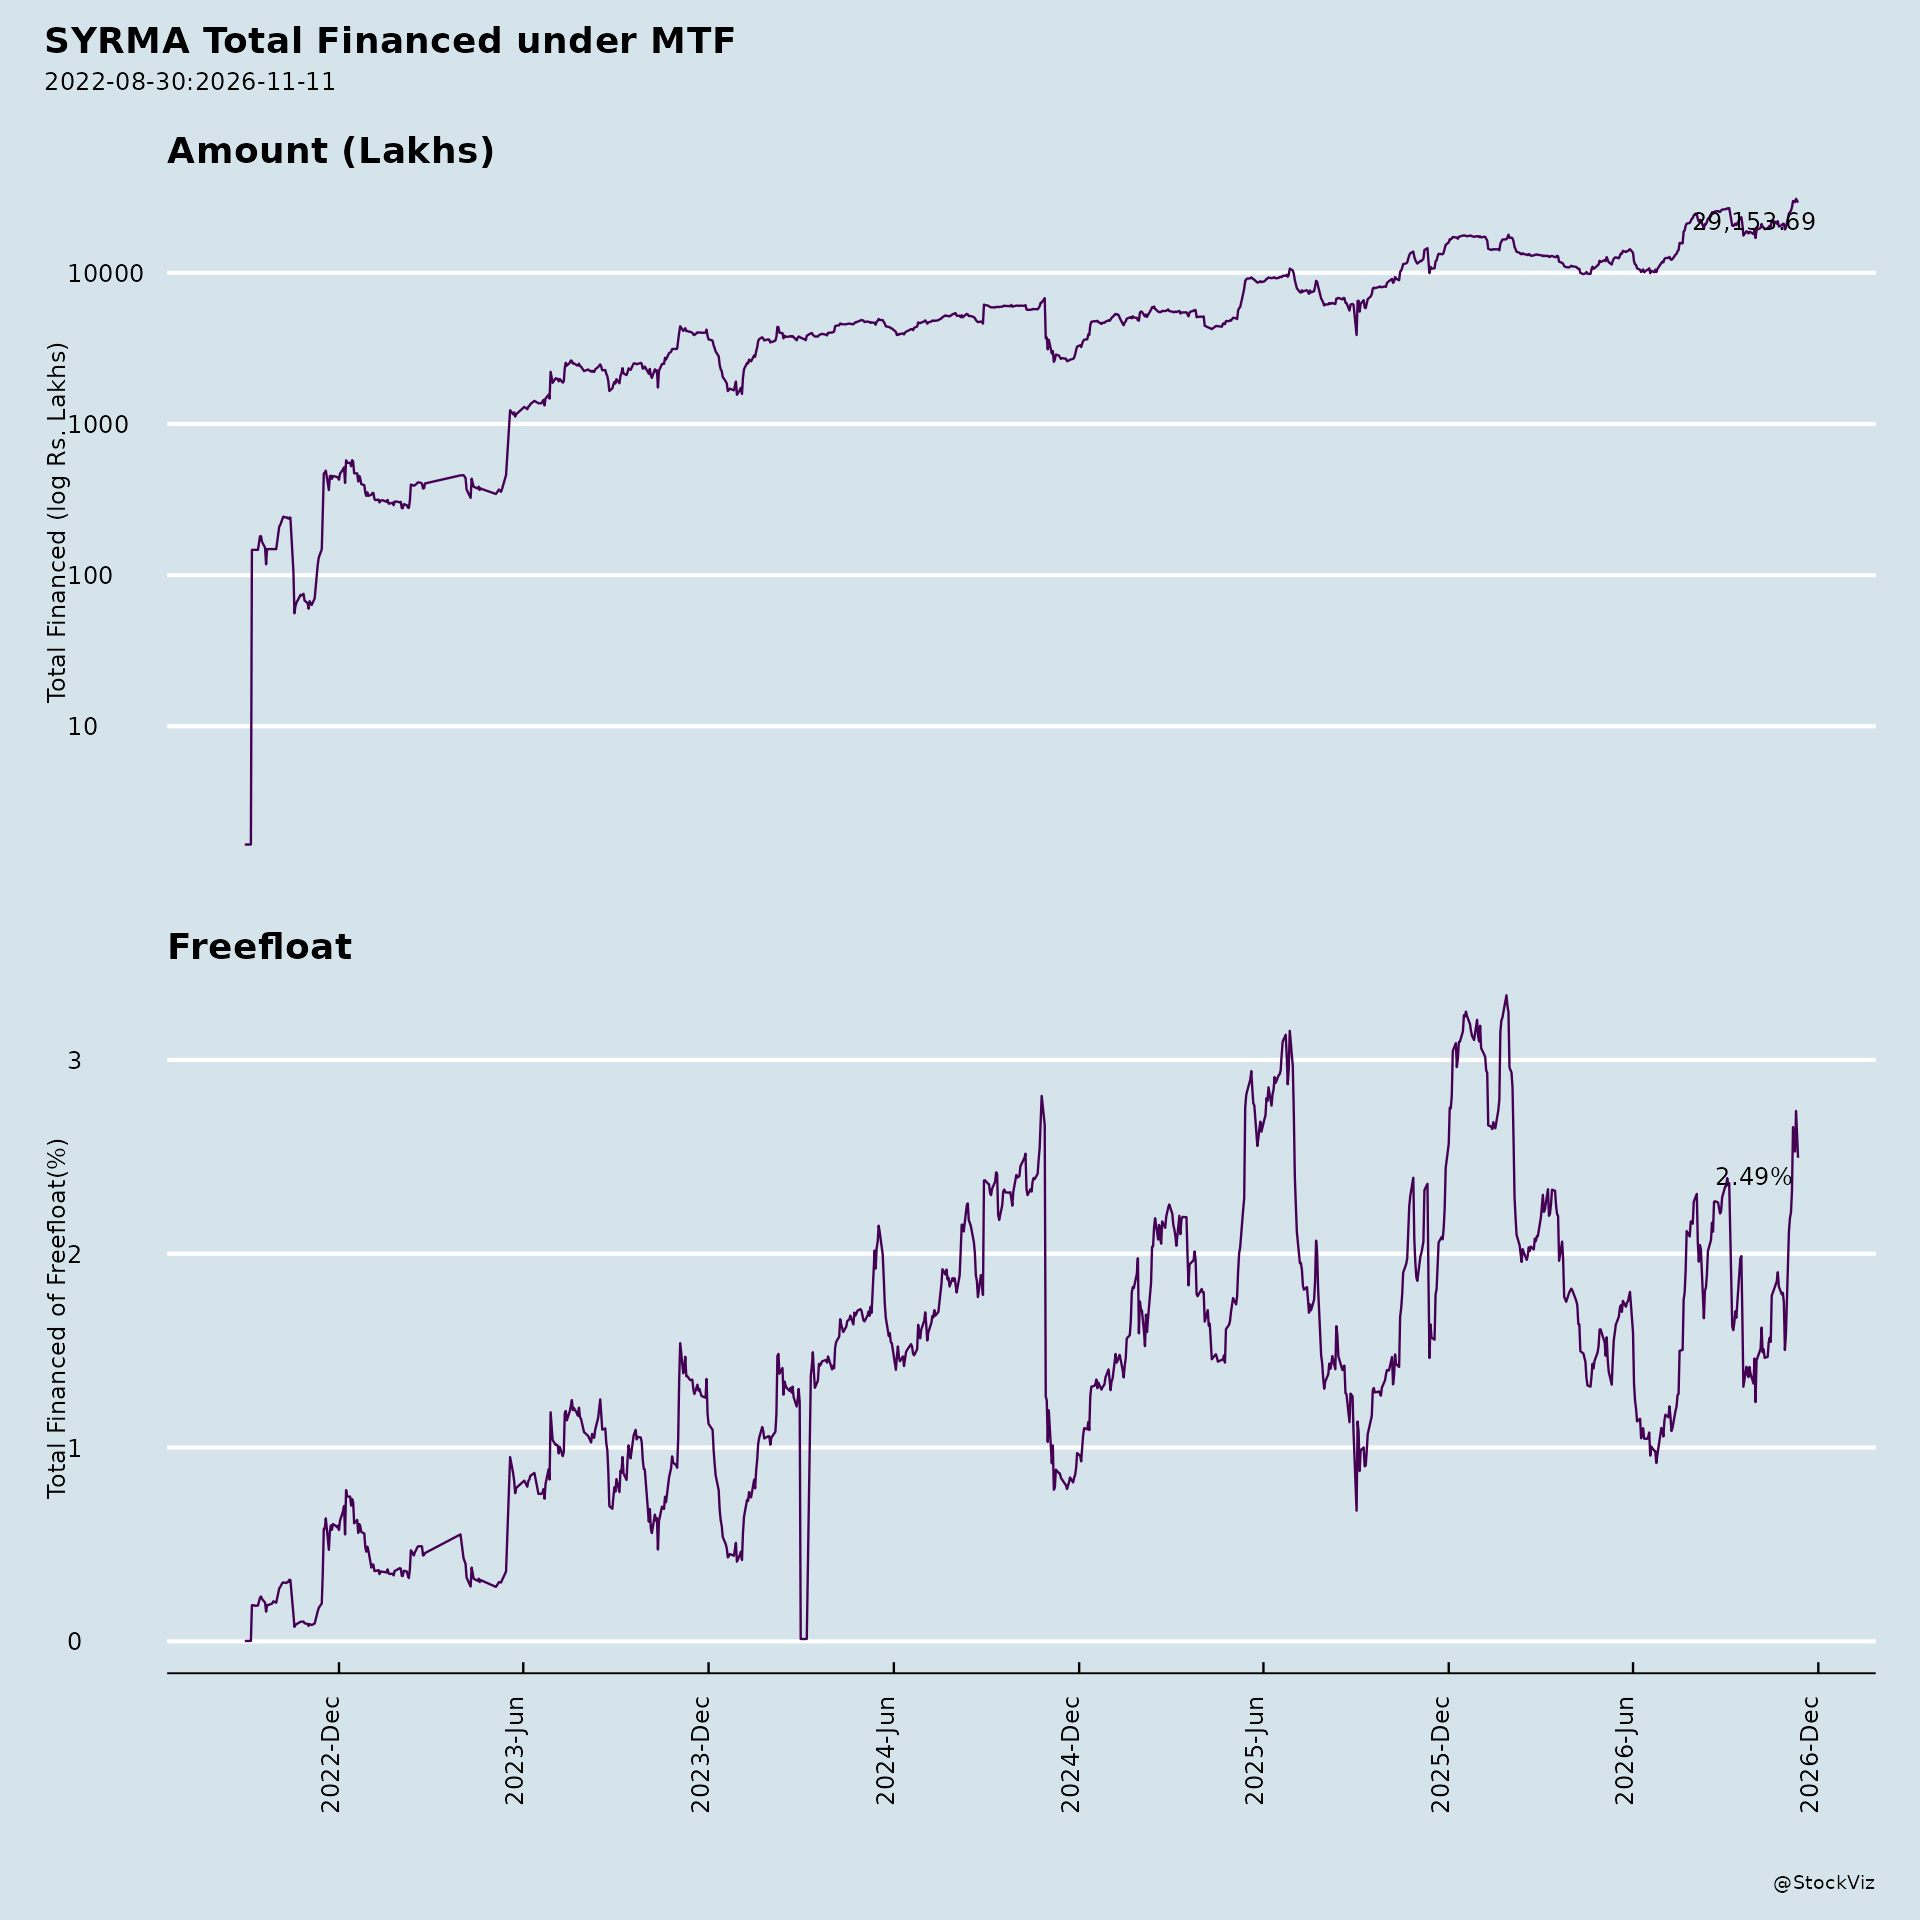
Margined
AI Summary
asof: 2026-09-16
Syrma SGS Technology — Recent Corporate Developments
1. Headwinds and Challenges
- Foreign exchange movements. For the quarter ended June 30, 2025, the company recorded a net gain on foreign currency fluctuations (Rs. 88.98 million standalone; Rs. 91.08 million consolidated). In the remaining periods, including the quarter ended June 30, 2026, there was a loss on foreign currency fluctuation classified under other expenses. This indicates that currency movements have shifted from a tailwind to a cost headwind.
- Finance costs. Standalone finance cost rose to Rs. 113.09 million in Q1 FY27 from Rs. 91.27 million in Q4 FY26, though it was lower than Rs. 139.50 million in Q1 FY26. Consolidated finance cost was Rs. 133.37 million, up from Rs. 130.15 million sequentially.
- Tax burden. Standalone current tax (including earlier period/year taxes) increased to Rs. 269.65 million in Q1 FY27 from Rs. 188.15 million in Q4 FY26 and Rs. 175.75 million in Q1 FY26. Consolidated current tax rose to Rs. 309.86 million from Rs. 182.88 million a year earlier.
- General economic and regulatory risks. The company cites known and unknown risks, uncertainties, and factors beyond its control, including general economic and business conditions in India and overseas, changes in government regulations, tax laws, and other statutes affecting its business and operations.
- Dependence on external approvals and conditions. The proposed transaction with Kaga Electronics India Private Limited is subject to customary conditions precedent and closing conditions. The QIP fundraising is subject to applicable laws and further board/committee decisions.
- Unreviewed subsidiary. One subsidiary’s interim financial information (total revenues of Rs. 6.01 million, net loss after tax of Rs. 7.37 million for Q1 FY27) was not reviewed by its auditors, though management states it is not material to the Group.
2. Tailwinds and Growth Prospects
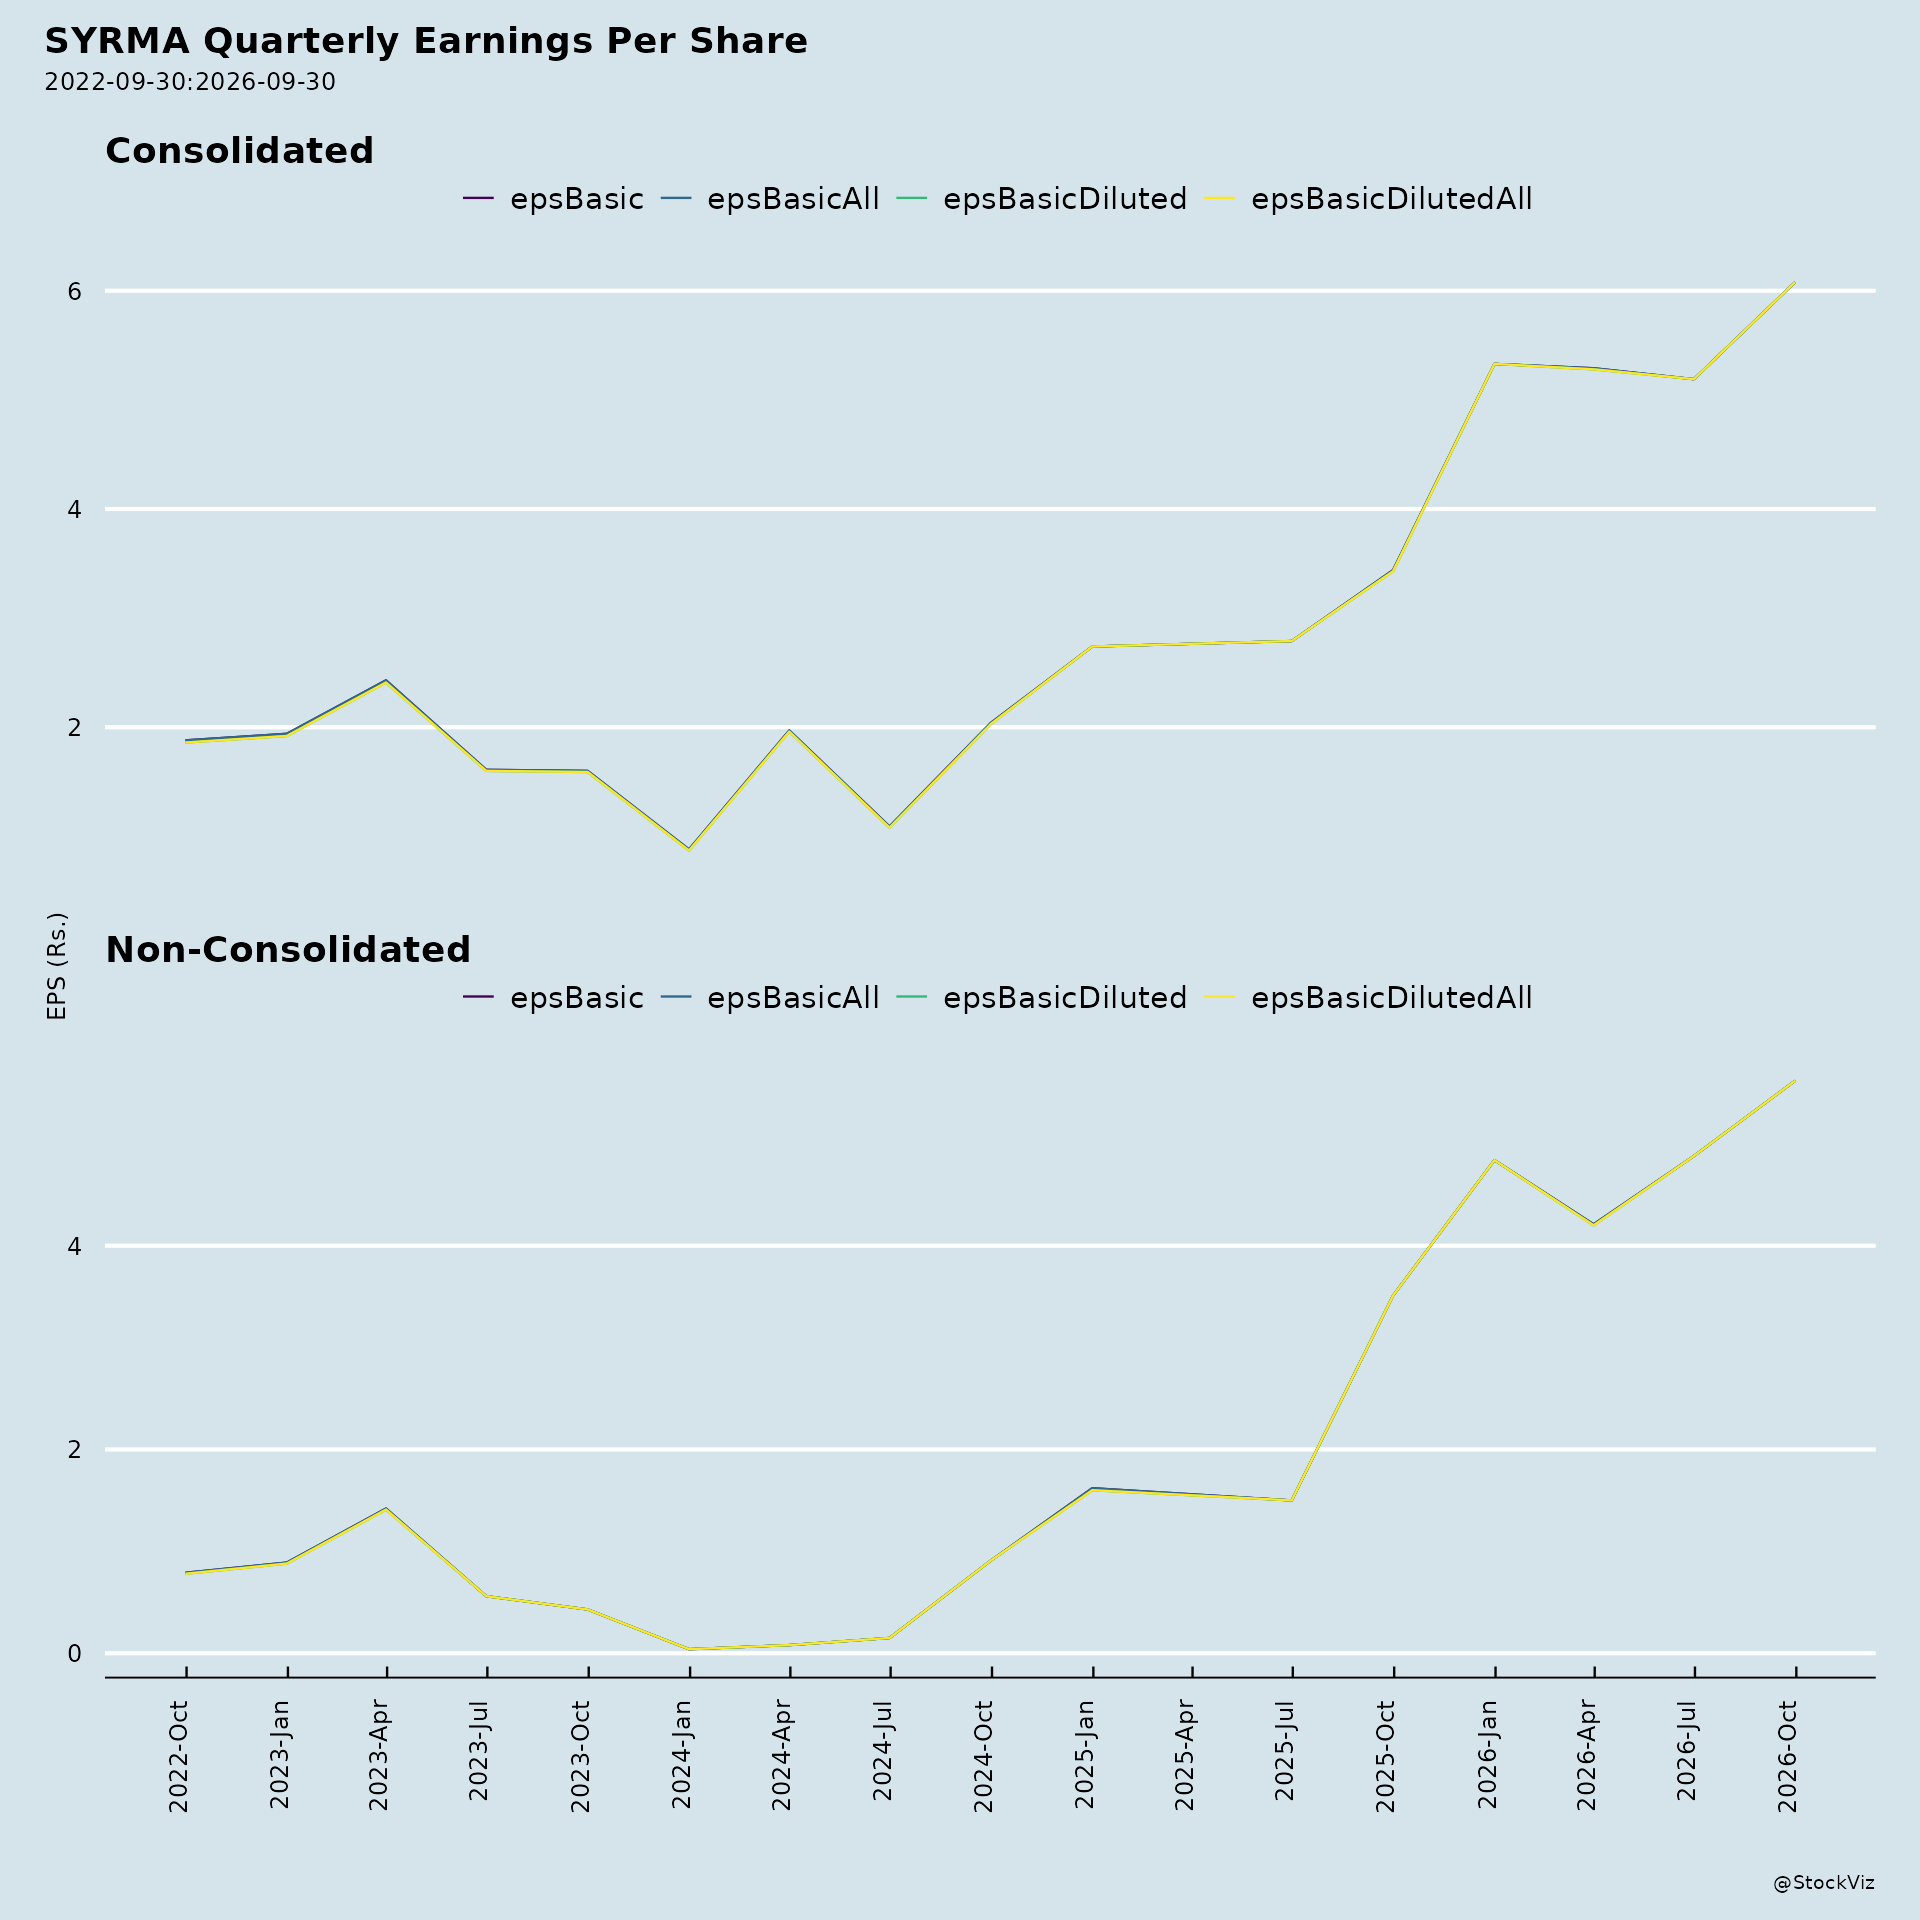
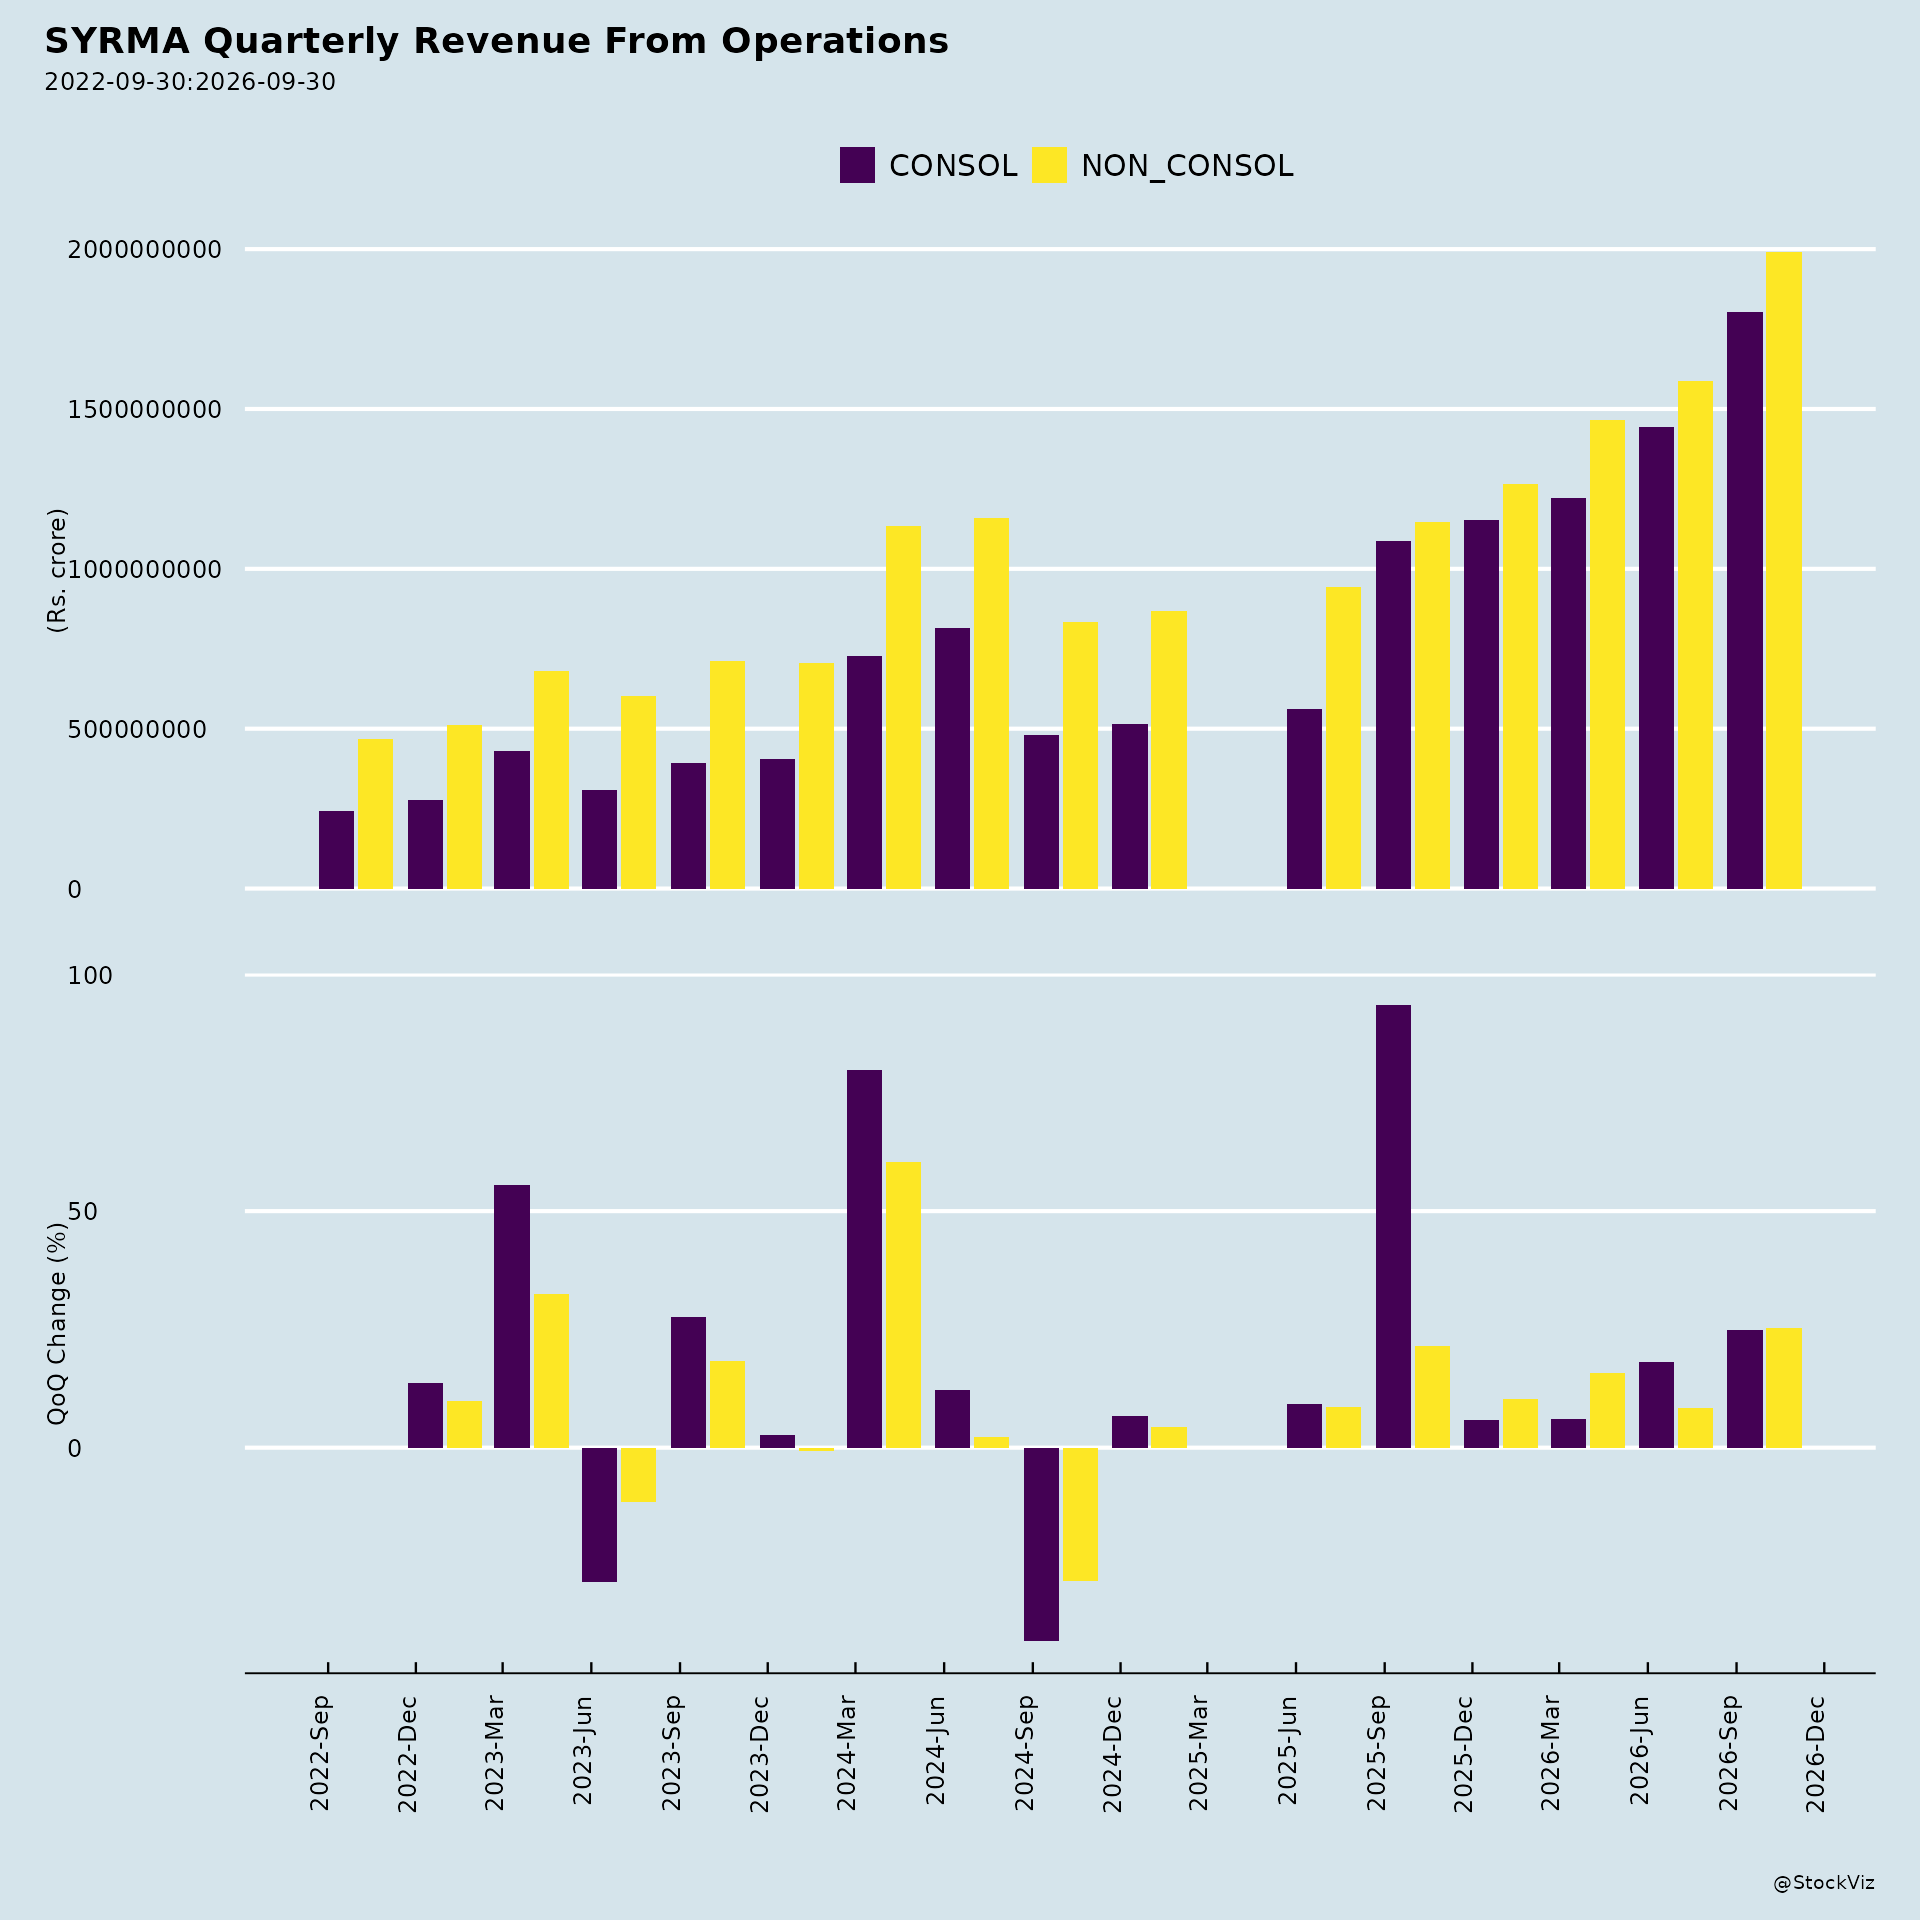
- Strong revenue growth. Standalone revenue from operations rose to Rs. 14,428.21 million in Q1 FY27 from Rs. 12,207.26 million in Q4 FY26 and Rs. 9,080.56 million in Q1 FY26 (restated). Consolidated revenue rose to Rs. 15,886.18 million from Rs. 14,650.12 million sequentially and Rs. 9,439.80 million a year earlier.
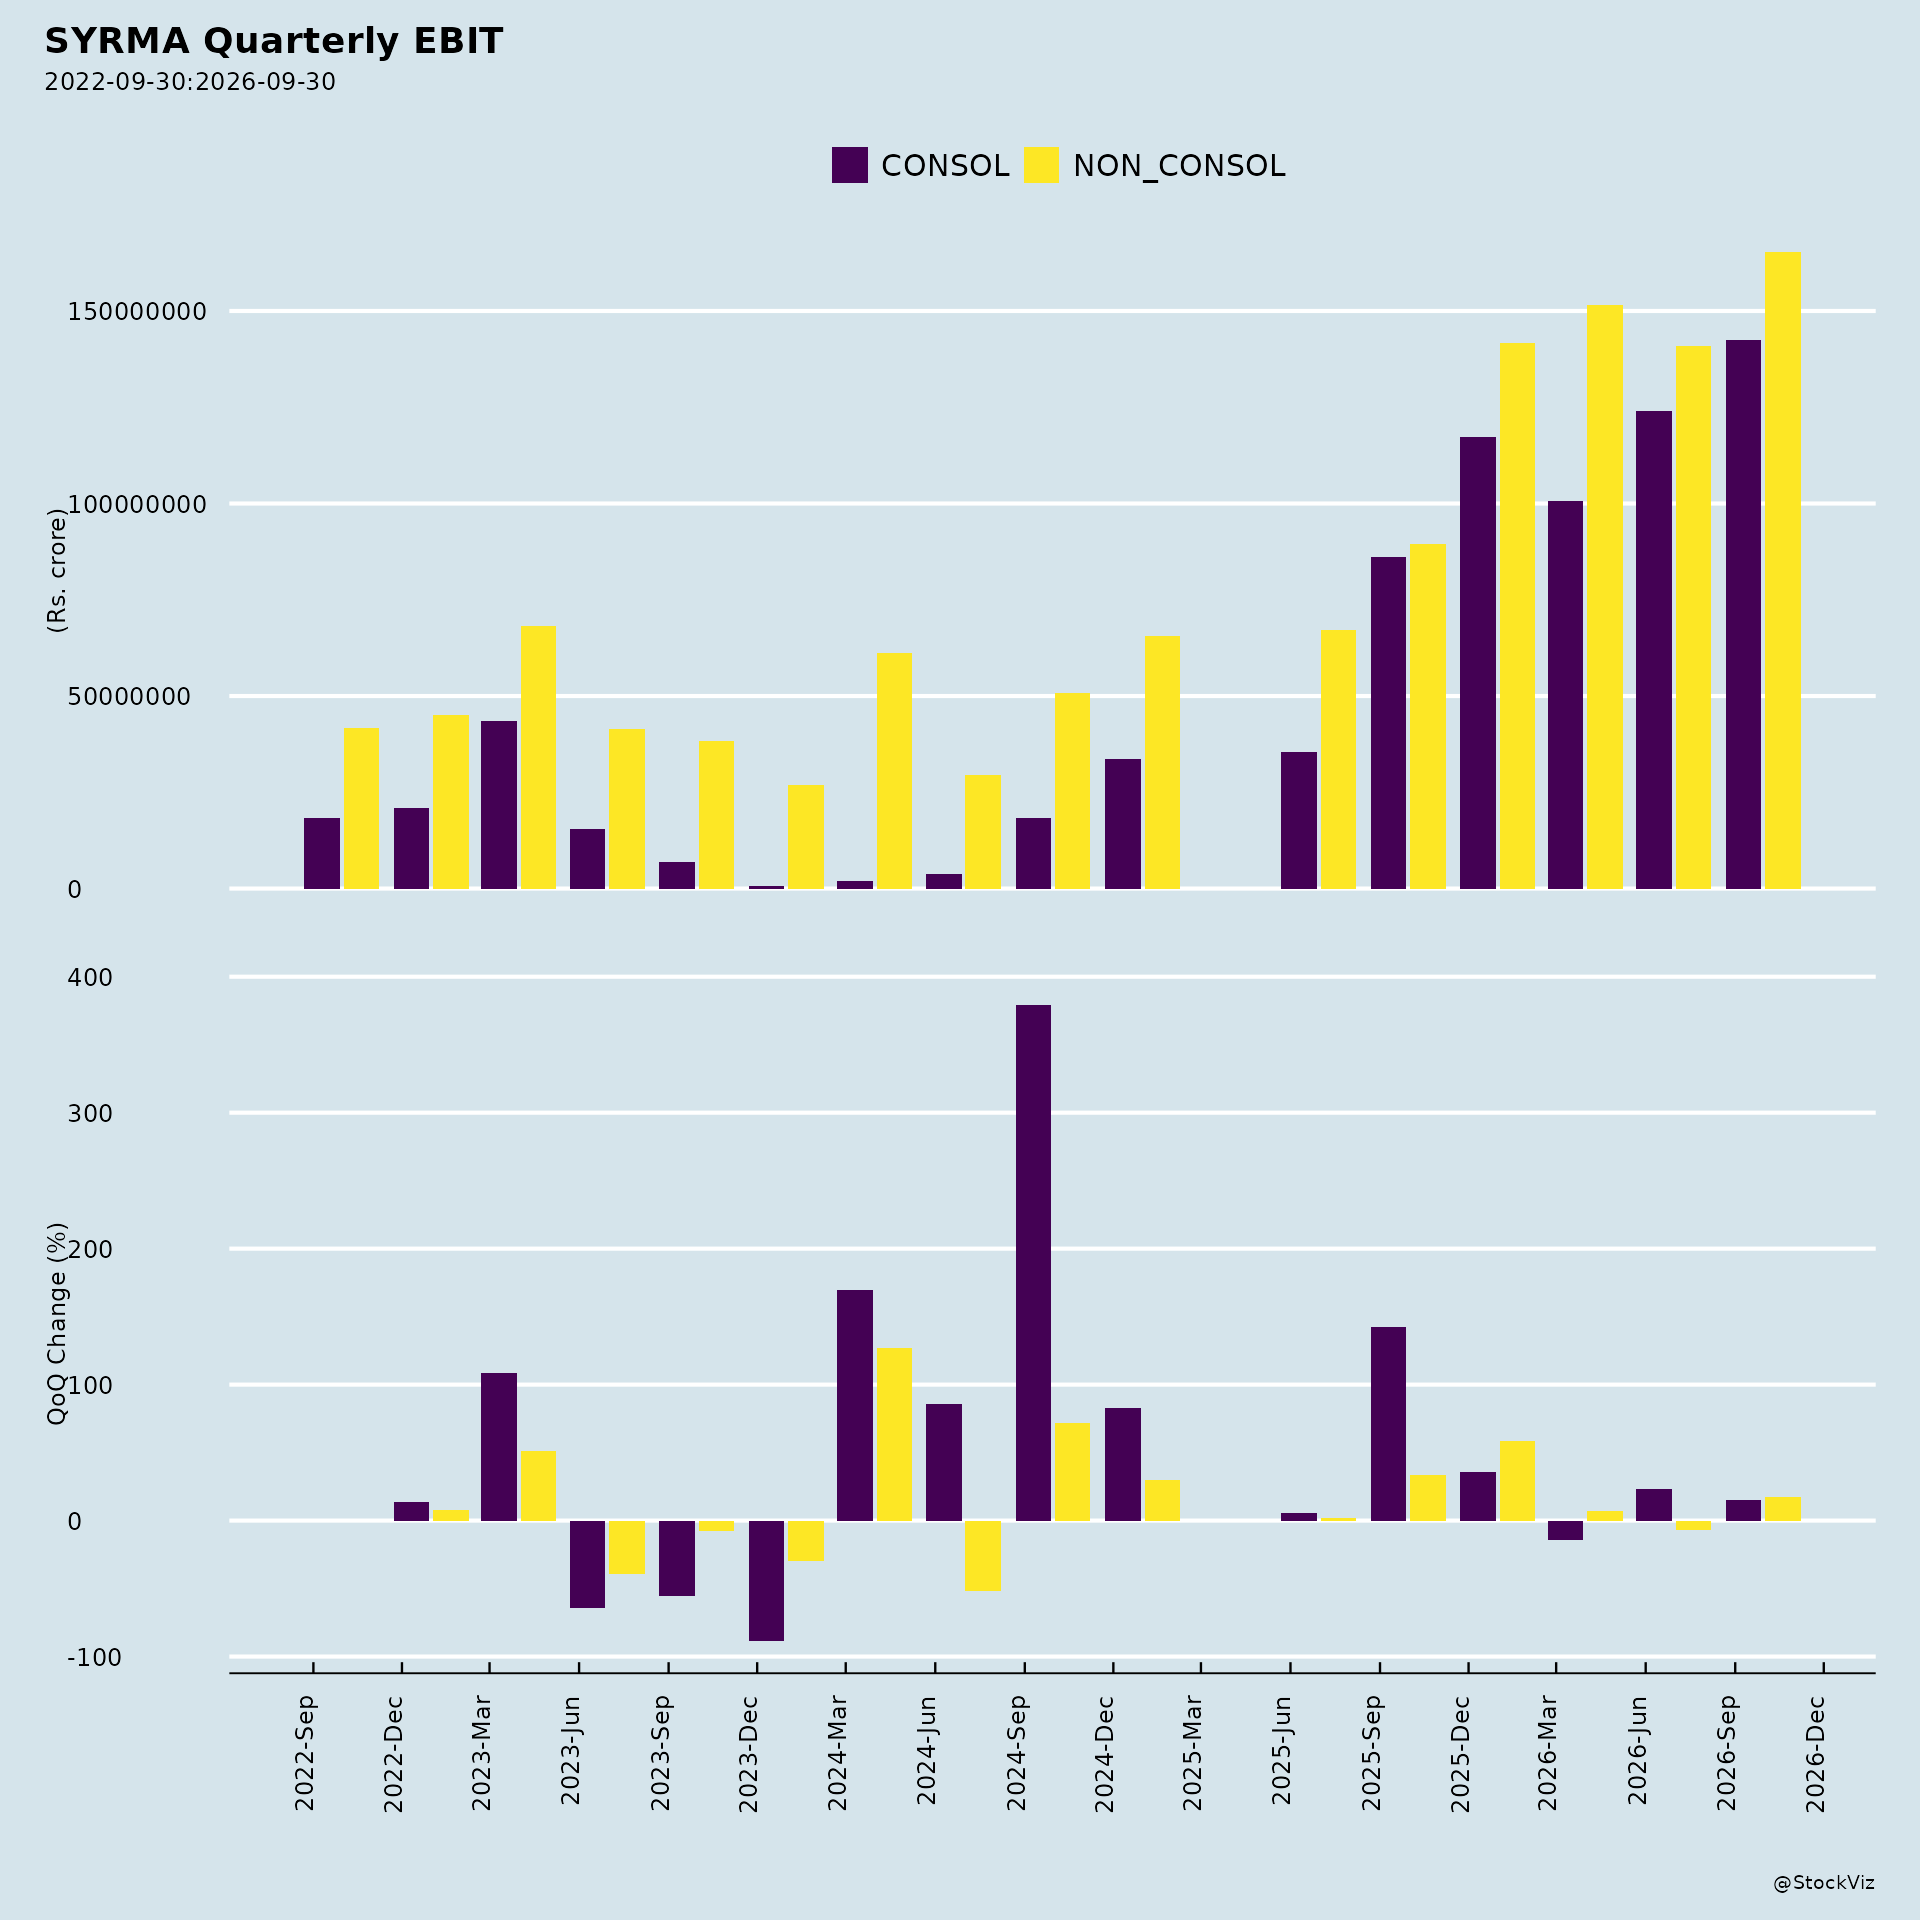
- Profit growth. Standalone profit after tax was Rs. 940.61 million in Q1 FY27 versus Rs. 808.88 million in Q4 FY26 and Rs. 537.73 million in Q1 FY26 (restated). Consolidated PAT was Rs. 1,056.92 million versus Rs. 1,192.31 million sequentially and Rs. 499.20 million a year earlier.
- Growing demand for high-reliability electronics across sectors such as railways, transportation, industrial electronics, energy, and medical electronics.
- Expansion of global customers from India and efforts to build India into a globally competitive hub for high-reliability electronics manufacturing, integrating India into global electronics supply chains, aligned with the broader ‘Make in India’ ambition.
- New manufacturing facility. Syrma SGS Technology Limited and Elemaster S.P.A Tecnologie Elettroniche (holding 60% and 40% stakes respectively in their JV, Syrma SGS Elemaster Private Limited) inaugurated a new 20,000 sq. ft. high-reliability electronics manufacturing facility in the Bommasandra Industrial Area, Bengaluru, equipped with SMT, THT, and box-build assembly lines.
- Joint venture with Kaga Electronics. During the quarter ended June 30, 2026, the company executed an electronics manufacturing services business agreement with Kaga Electronics India Private Limited, under which the company shall invest for an aggregate ownership stake of up to 60% in a new company to be incorporated, and Kaga shall invest for up to 40%.
- Increased stake in design and manufacturing subsidiary. The company made an additional investment of Rs. 326.99 million (1,143,322 equity shares) in Syrma SGS Design & Manufacturing Private Limited. That subsidiary issued 768,881 equity shares to Elemaster S.P.A. Tecnologie Elettroniche for consideration of Rs. 219.90 million. Following these transactions, the company holds 60% equity stake in the subsidiary as of June 30, 2026.
- Fundraising capacity. The board approved raising funds via Qualified Institutional Placement or other permissible mode for an aggregate amount not exceeding Rs. 1,000 Crores.
- Dividend recommendation. The board recommended a final dividend of 15% (Rs. 1.5 per equity share of Rs. 10 each) for FY 2025-26, subject to shareholder approval.
- Investor engagement. Management participated in a Non-Deal Roadshow with Axis Capital in the USA from September 08, 2026, to September 16, 2026.
3. Key Risks
- Currency risk. Foreign exchange fluctuation losses are classified under other expenses in most periods, exposing earnings to currency volatility.
- Execution and integration risk. The Kaga joint venture and the Elemaster JV facility involve conditions precedent and closing conditions; the new entity’s incorporation and operational ramp-up carry execution uncertainty.
- Regulatory and tax risk. Changes in government regulations, tax laws, and other statutes in India and overseas could affect operations.
- Macroeconomic risk. General economic and business conditions in India and overseas may impact demand and operations.
- Dependence on approvals. The QIP fundraising and the re-appointment of the Executive Chairman are subject to shareholder approval; the cost auditor appointment is subject to confirmation of remuneration by shareholders.
- Scheme of amalgamation accounting. The company gave effect to the Scheme of Amalgamation involving SGS Infosystems Private Limited and SGS Tekniks Manufacturing Private Limited with an appointed date of April 1, 2023, as approved by the NCLT vide order dated October 7, 2025. Comparative financial information for the quarter ended June 30, 2025 has been restated from April 1, 2025. The amalgamation impact on Q1 FY26 restated figures: revenue increased from Rs. 5,617.47 million (reported) to Rs. 9,080.56 million (restated); profit before tax from Rs. 355.34 million to Rs. 713.10 million; profit after tax from Rs. 267.51 million to Rs. 537.73 million.
- Reliance on other auditors. The consolidated results include thirteen subsidiaries reviewed by other auditors (total revenues of Rs. 892.42 million, net profit after tax of Rs. 73.41 million for Q1 FY27) and one subsidiary not reviewed by auditors.
4. Management Guidance Versus Observed Business Performance
- Fundraising. The board approved a QIP or other permissible mode for raising funds up to Rs. 1,000 Crores on July 29, 2026. Details are to be disclosed as and when decided by the board or an authorized committee. No specific timeline or pricing guidance was provided.
- Kaga joint venture. The agreement contemplates the company investing for up to 60% ownership in a new company, with Kaga investing up to 40%. The transaction is subject to conditions precedent and closing conditions. No financial projections or completion timeline were disclosed.
- Elemaster JV. The JV company’s name was changed from ‘Syrma SGS Design and Manufacturing Private Limited’ to ‘Syrma SGS Elemaster Private Limited’ with effect from September 09, 2026, following a fresh Certificate of Incorporation from the Ministry of Corporate Affairs. The new 20,000 sq. ft. facility in Bengaluru was inaugurated, equipped with SMT, THT, and box-build assembly lines. No production or revenue guidance was provided.
- Forward-looking statements. Management states that forward-looking statements are based on current expectations, assumptions, estimates, and projections about the business, industry, and markets, and that the company undertakes no obligation to publicly update or revise any forward-looking statement unless required by law.
- Investor communications. During the Non-Deal Roadshow in the USA (September 08–16, 2026), management stated that discussions would be based on general business outlook and information already in the public domain, and that no unpublished price sensitive information would be disclosed.
- Observed performance versus prior periods. Revenue and profitability improved substantially year-on-year in Q1 FY27 on both standalone and consolidated bases. Sequentially, standalone revenue and PAT increased, while consolidated PAT declined from Rs. 1,192.31 million in Q4 FY26 to Rs. 1,056.92 million in Q1 FY27, partly due to lower non-controlling interest contribution (Rs. 56.18 million versus Rs. 180.37 million) and higher tax expense.
- Dividend. The board recommended a final dividend of 15% (Rs. 1.5 per share) for FY 2025-26 on May 11, 2026, subject to shareholder approval at the AGM. All nine resolutions at the 22nd AGM held on August 25, 2026 were approved by shareholders with the requisite majority.
- IPO proceeds utilization. The company received Rs. 7,257.22 million (net of IPO expenses of Rs. 402.78 million) from a fresh issue of equity shares in FY 2022-23. As of June 30, 2026, the entire amount was utilized: Rs. 4,030.00 million for funding capital expenditure, Rs. 1,315.80 million for funding working capital requirements, and Rs. 1,911.42 million for general corporate purposes. No unutilized amount remains.
Broker Narrative
Early coverage framed SYRMA as a PLI and China+1 beneficiary powered by multi-vertical electronics adoption and 30-40% vertical revenue CAGR, while warning of import dependence, client concentration, valuation risk, and pricing pressure. As the stock more than doubled, broker calls rotated between Buy and Hold with mixed price-target accuracy, though overall conviction stayed positive. The latest report confirms strong export and vertical demand but pivots to margin defense, citing elevated commodity costs, supply-chain overhang, cost pass-through without value addition, and a 50bps FY27 EBITDAM cut to 10-10.5%.
Fears that came true
- Valuation and result deviations materialized as repeated negative prints after Buy calls, including -16.6%, -2.6%, -6.3%, and -3.5% on 2026-11-02, all logged as DISAPPOINTMENT, confirming that earnings disappointment could trigger sharp de-ratings.
- High import dependence persisted into supply-chain challenges identified as the main overhang in the last report, with elevated commodity costs pressuring gross margins ahead of the recent negative outcomes.
- Pricing pressures resurfaced as cost pass-through without corresponding value addition, contributing to weaker 3QFY27 margin expectations and the FY27 EBITDAM guidance cut to 10-10.5%.
Optimism that failed
- Margin and return expansion through operating leverage and backward integration failed to hold, as FY27 EBITDAM guidance was cut 50bps to 10-10.5% and weaker margins are expected in 3QFY27.
Broker Timeline
50 broker calls · 2023-07-12 to 2026-11-03
CNBC-TV18: ratings, targets and commentary
Extracted from CNBC-TV18 posts; ratings and targets are as published, not current consensus. OCR may contain errors. Speaker attribution is retained; not all speakers are brokers. These statements are separate from the Broker Narrative and Broker Timeline and have no calculated performance or outcomes.
Ratings and targets
| Published / source (IST) | Speaker / affiliation | Rating / target | Commentary |
|---|---|---|---|
| 2026-11-16 |
Equirus Securities
Manoj Gori
|
top pick
|
Relatively positive in the EMS space, Syrma & Avalon are top picks |
Management comments
No recorded management comments with an explicit designation and affiliation for this ticker.
Copyright © 2023 SAS Data Analytics Pvt. Ltd. All rights reserved.