SYNGENE
Equity Metrics
November 18, 2026
Syngene International Limited
Healthcare Research Analytics & Technology
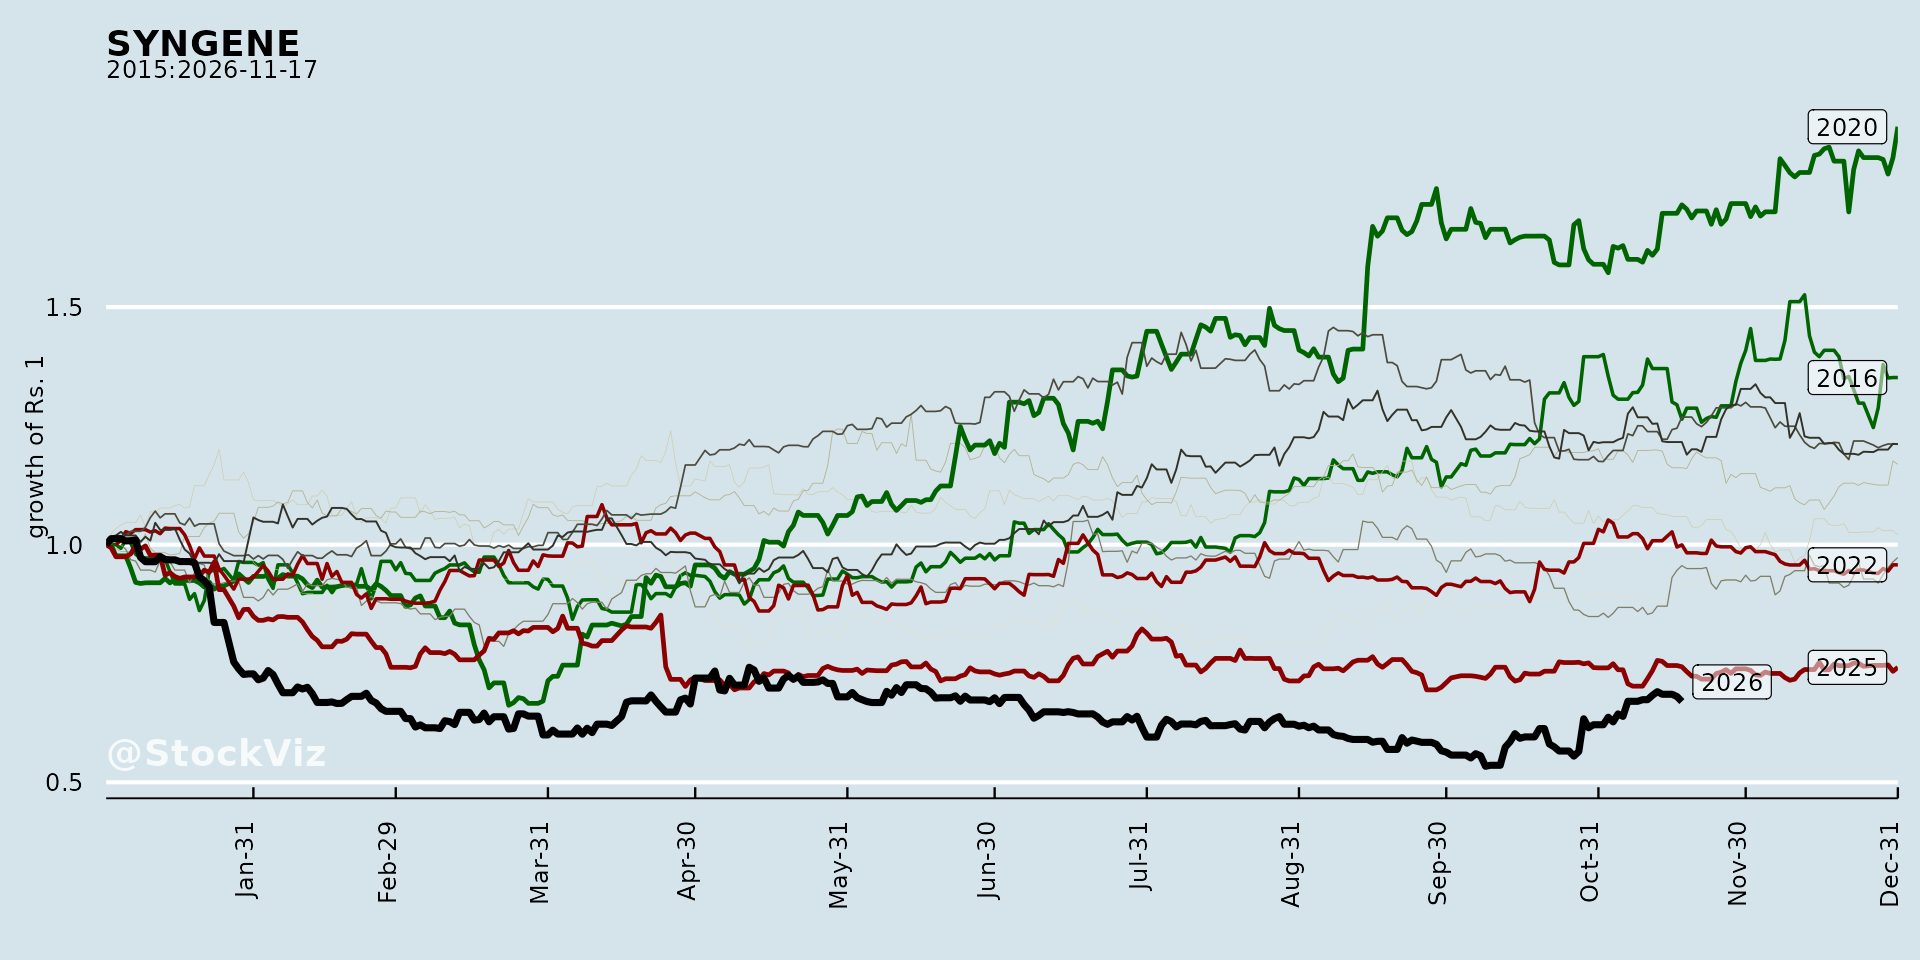
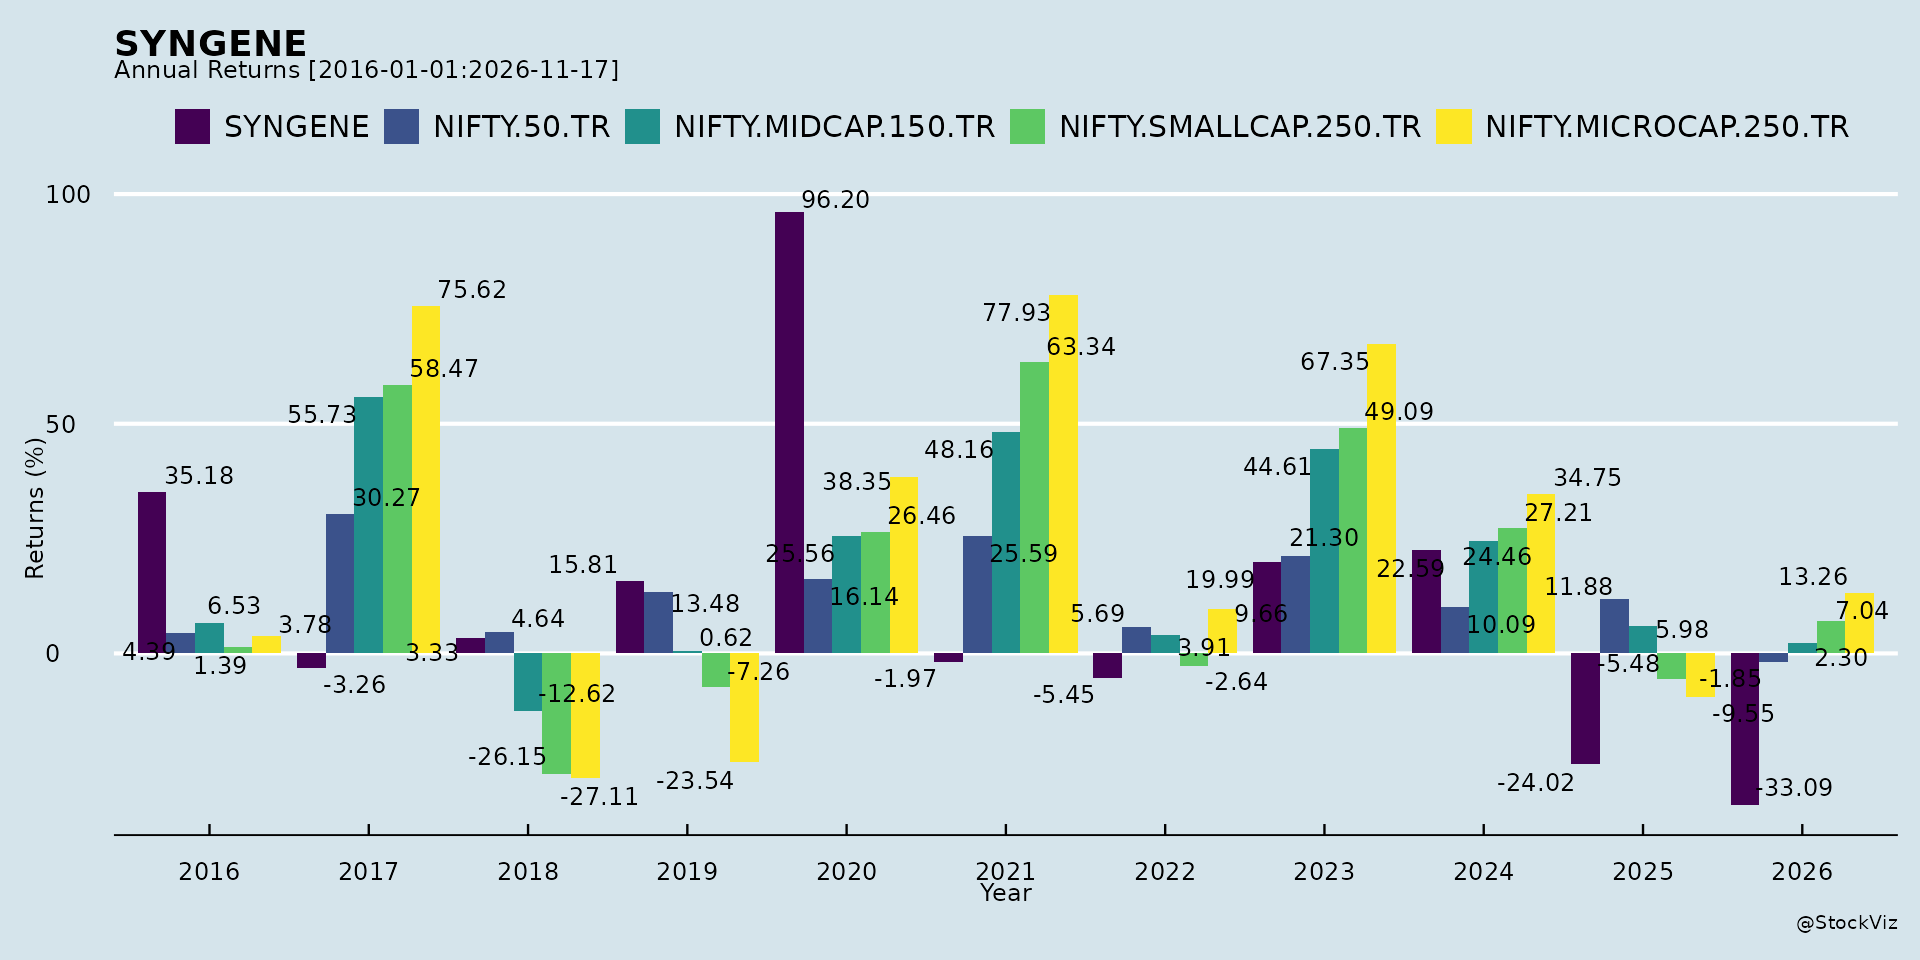
Annual Returns
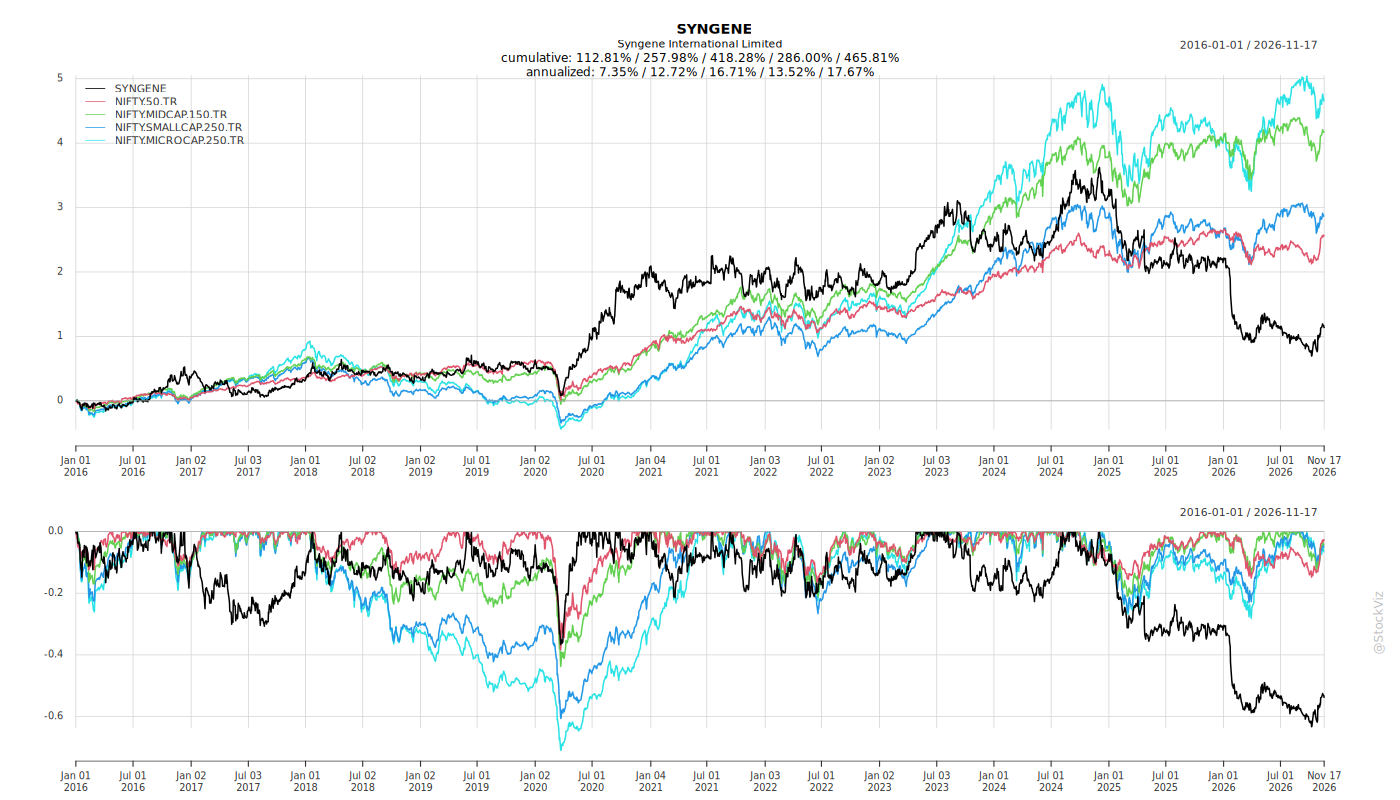
Cumulative Returns and Drawdowns
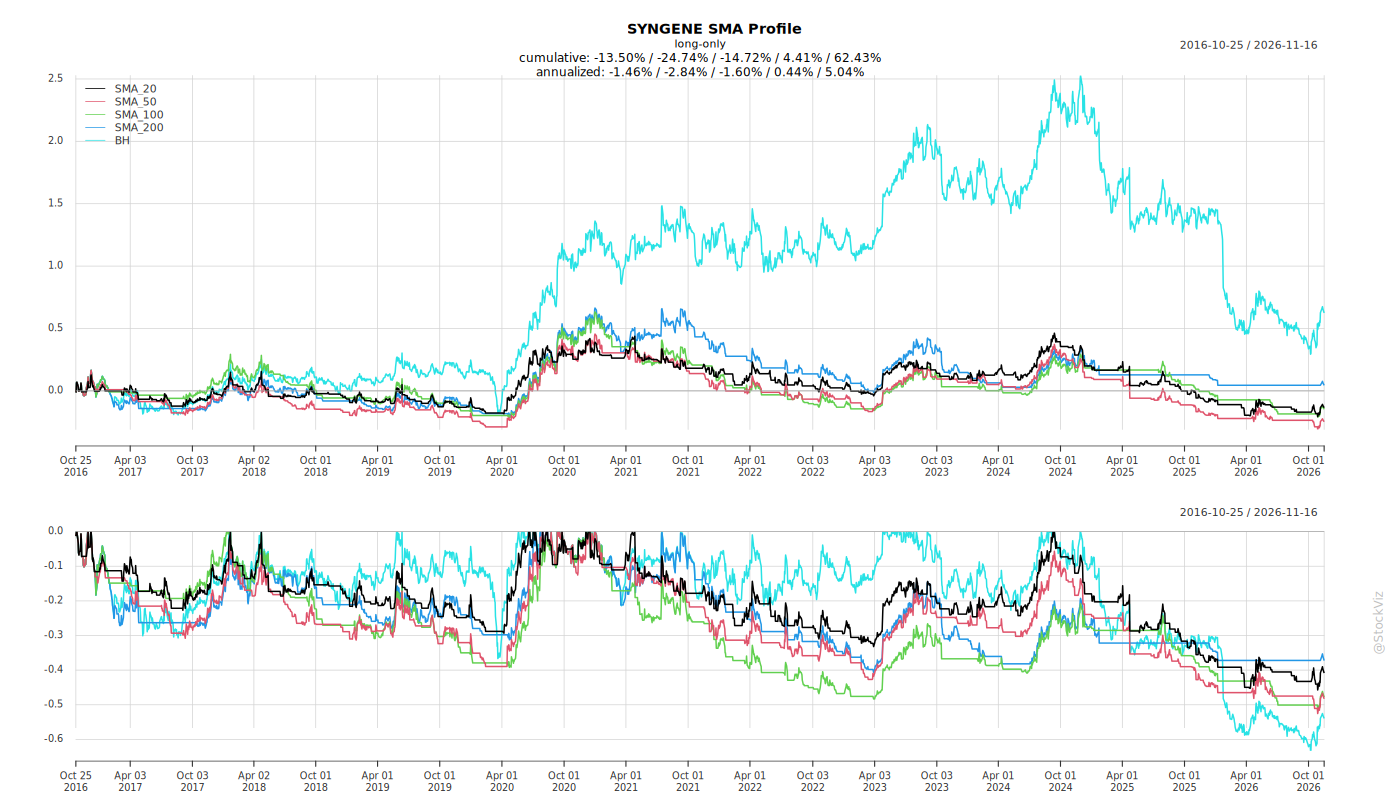
Fundamentals
Ownership
Margined
AI Summary
asof: 2026-09-16
Syngene International — Recent Corporate Announcements: Analysis
1. Headwinds and Challenges
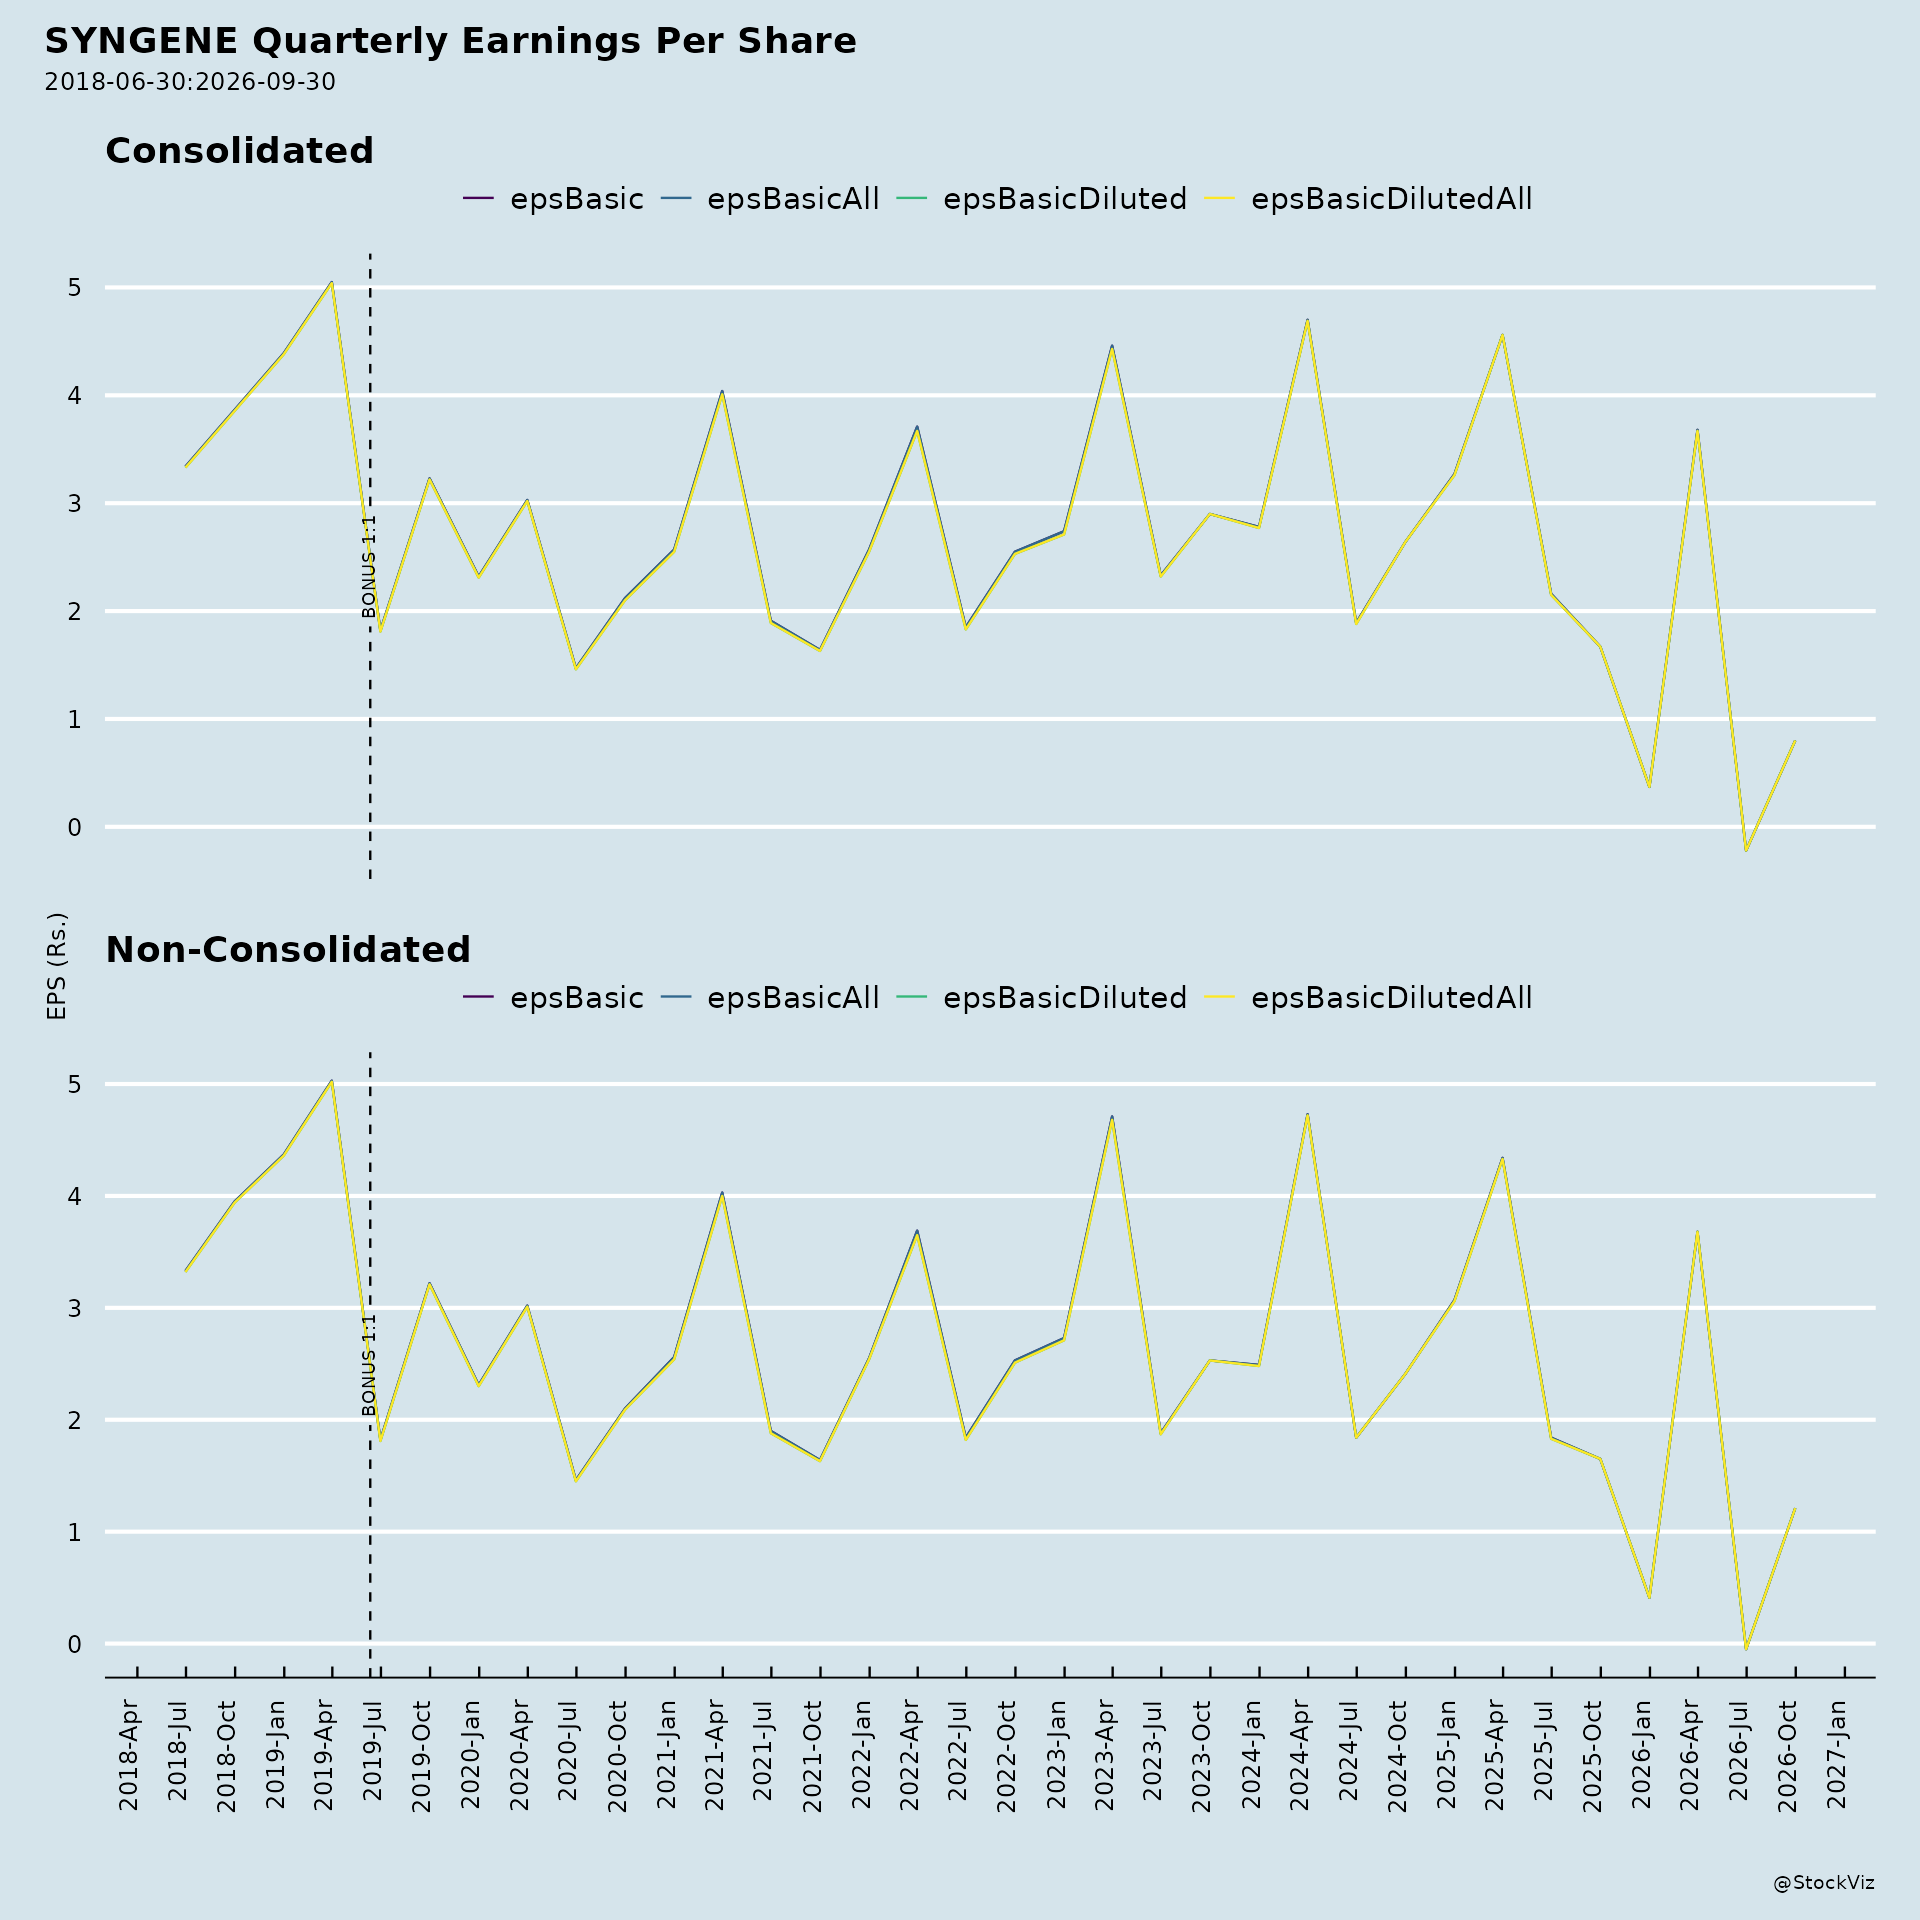
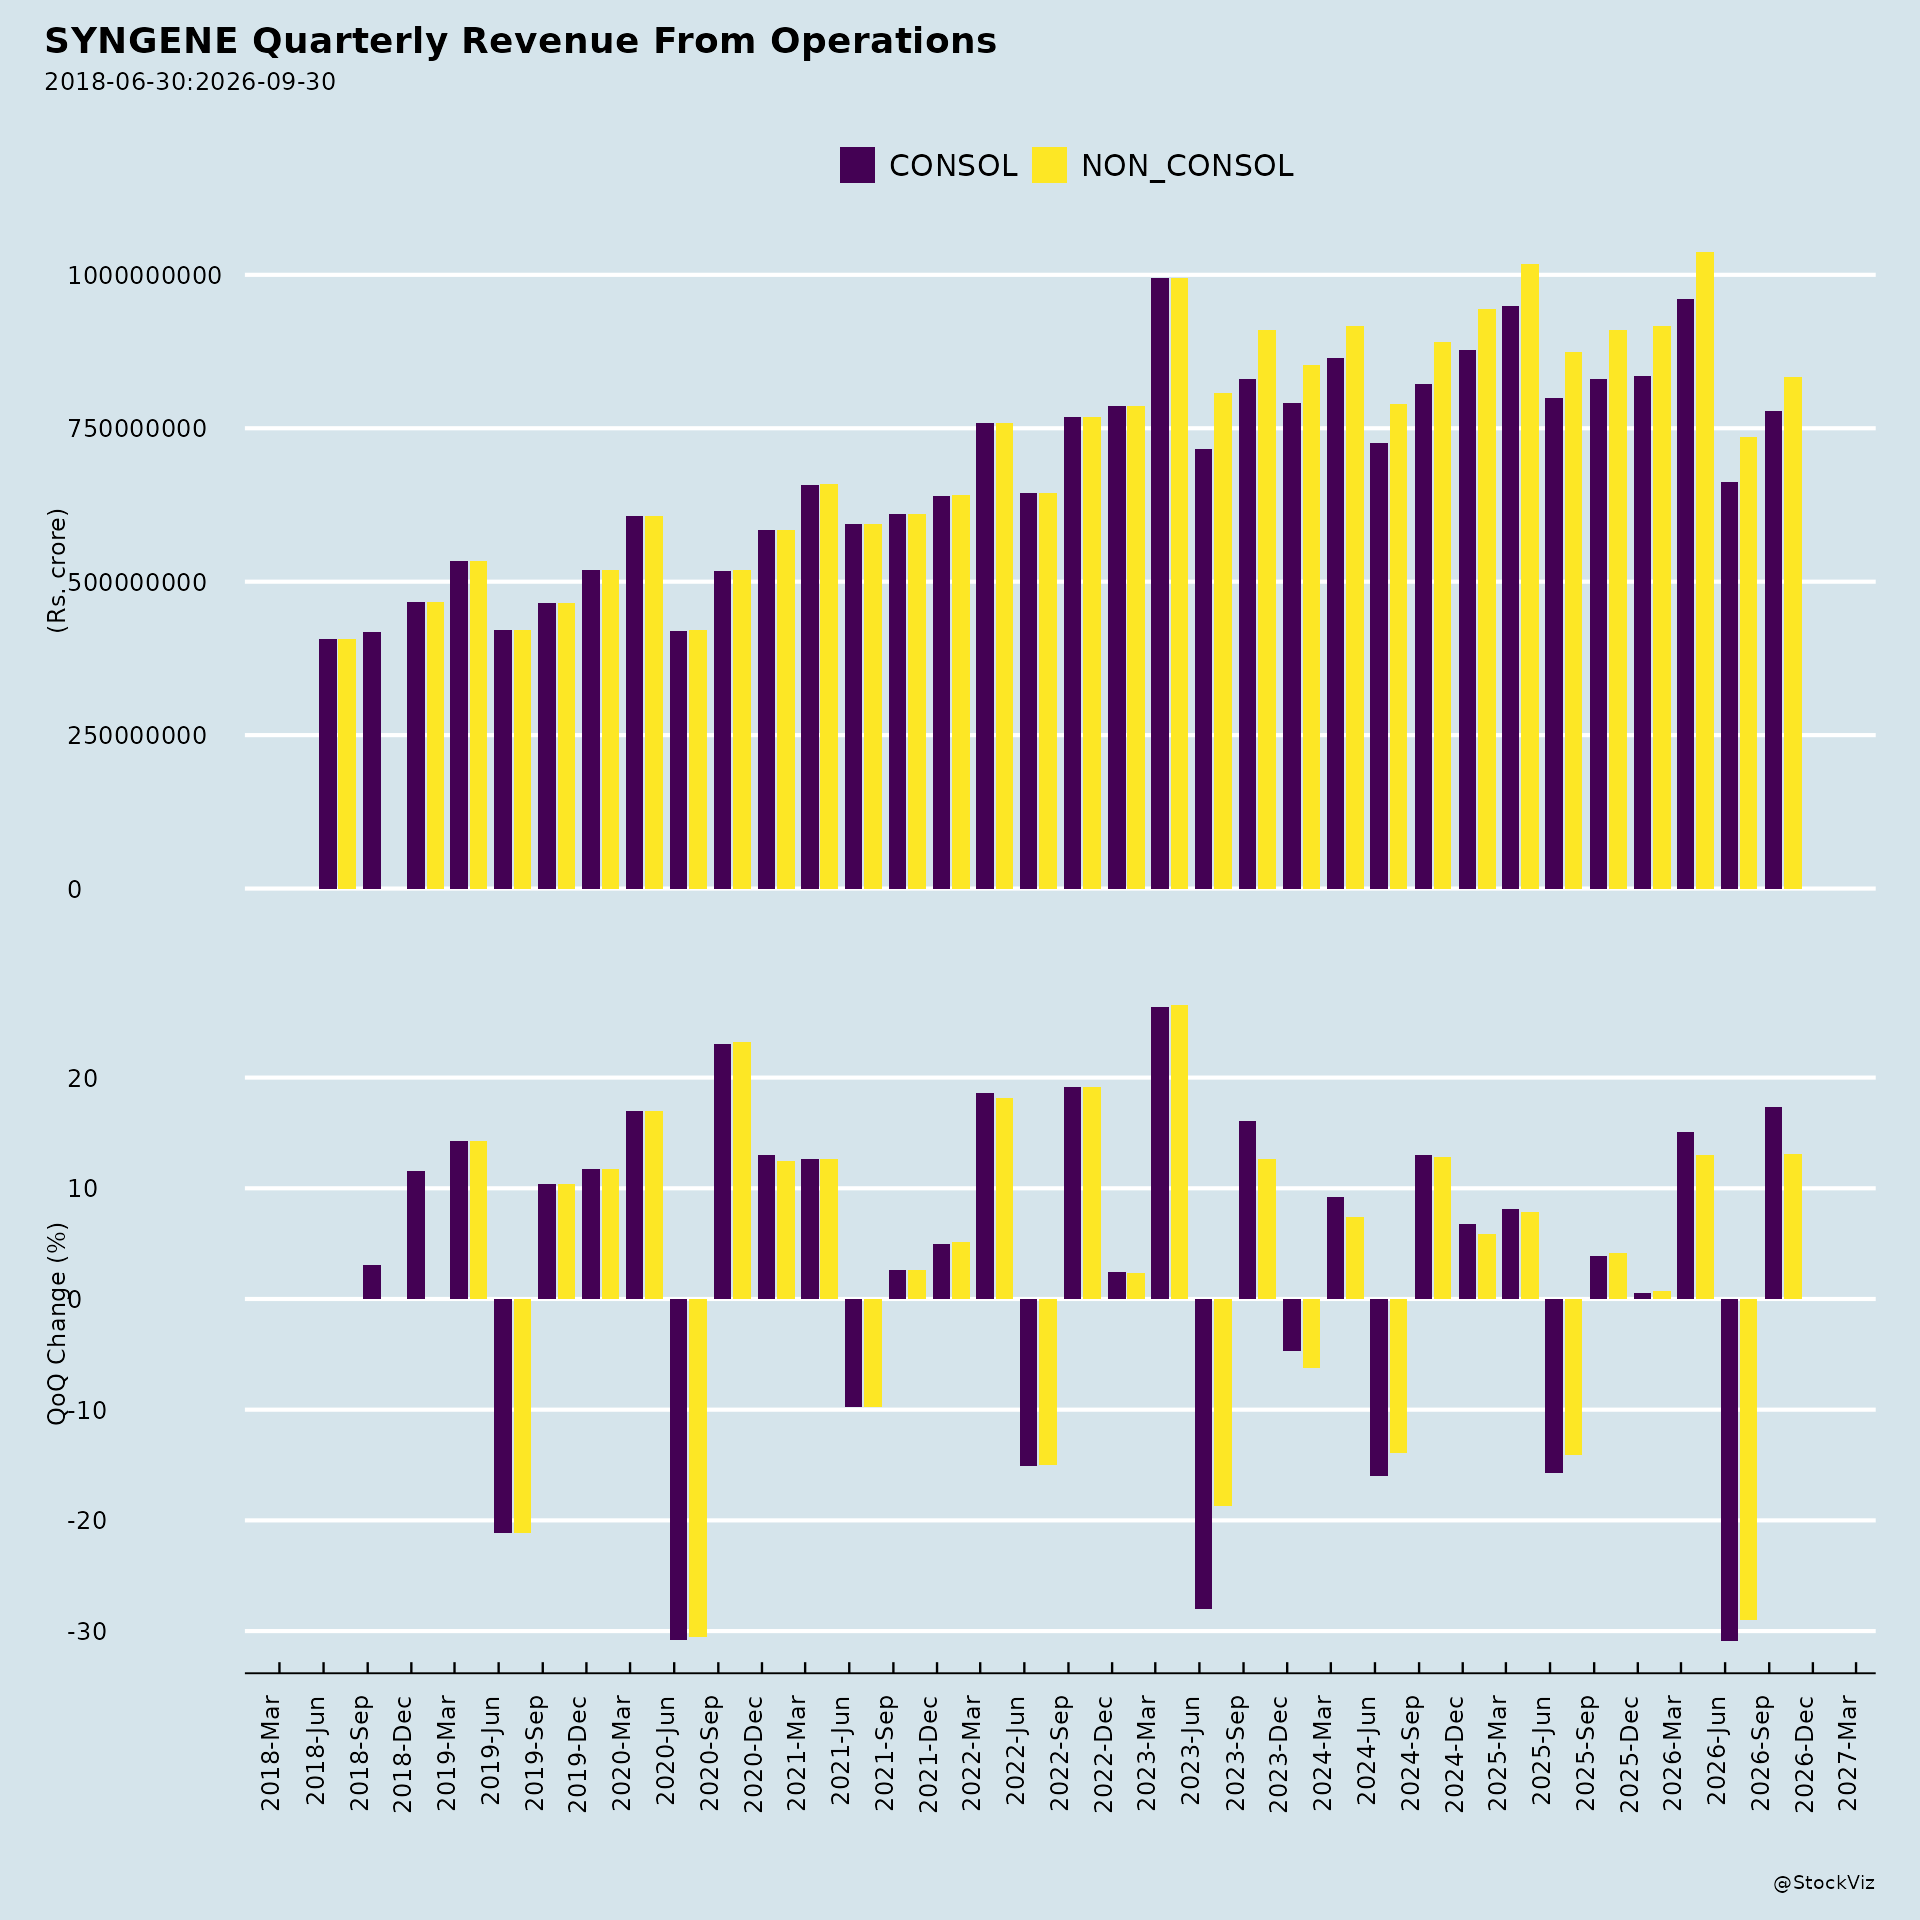
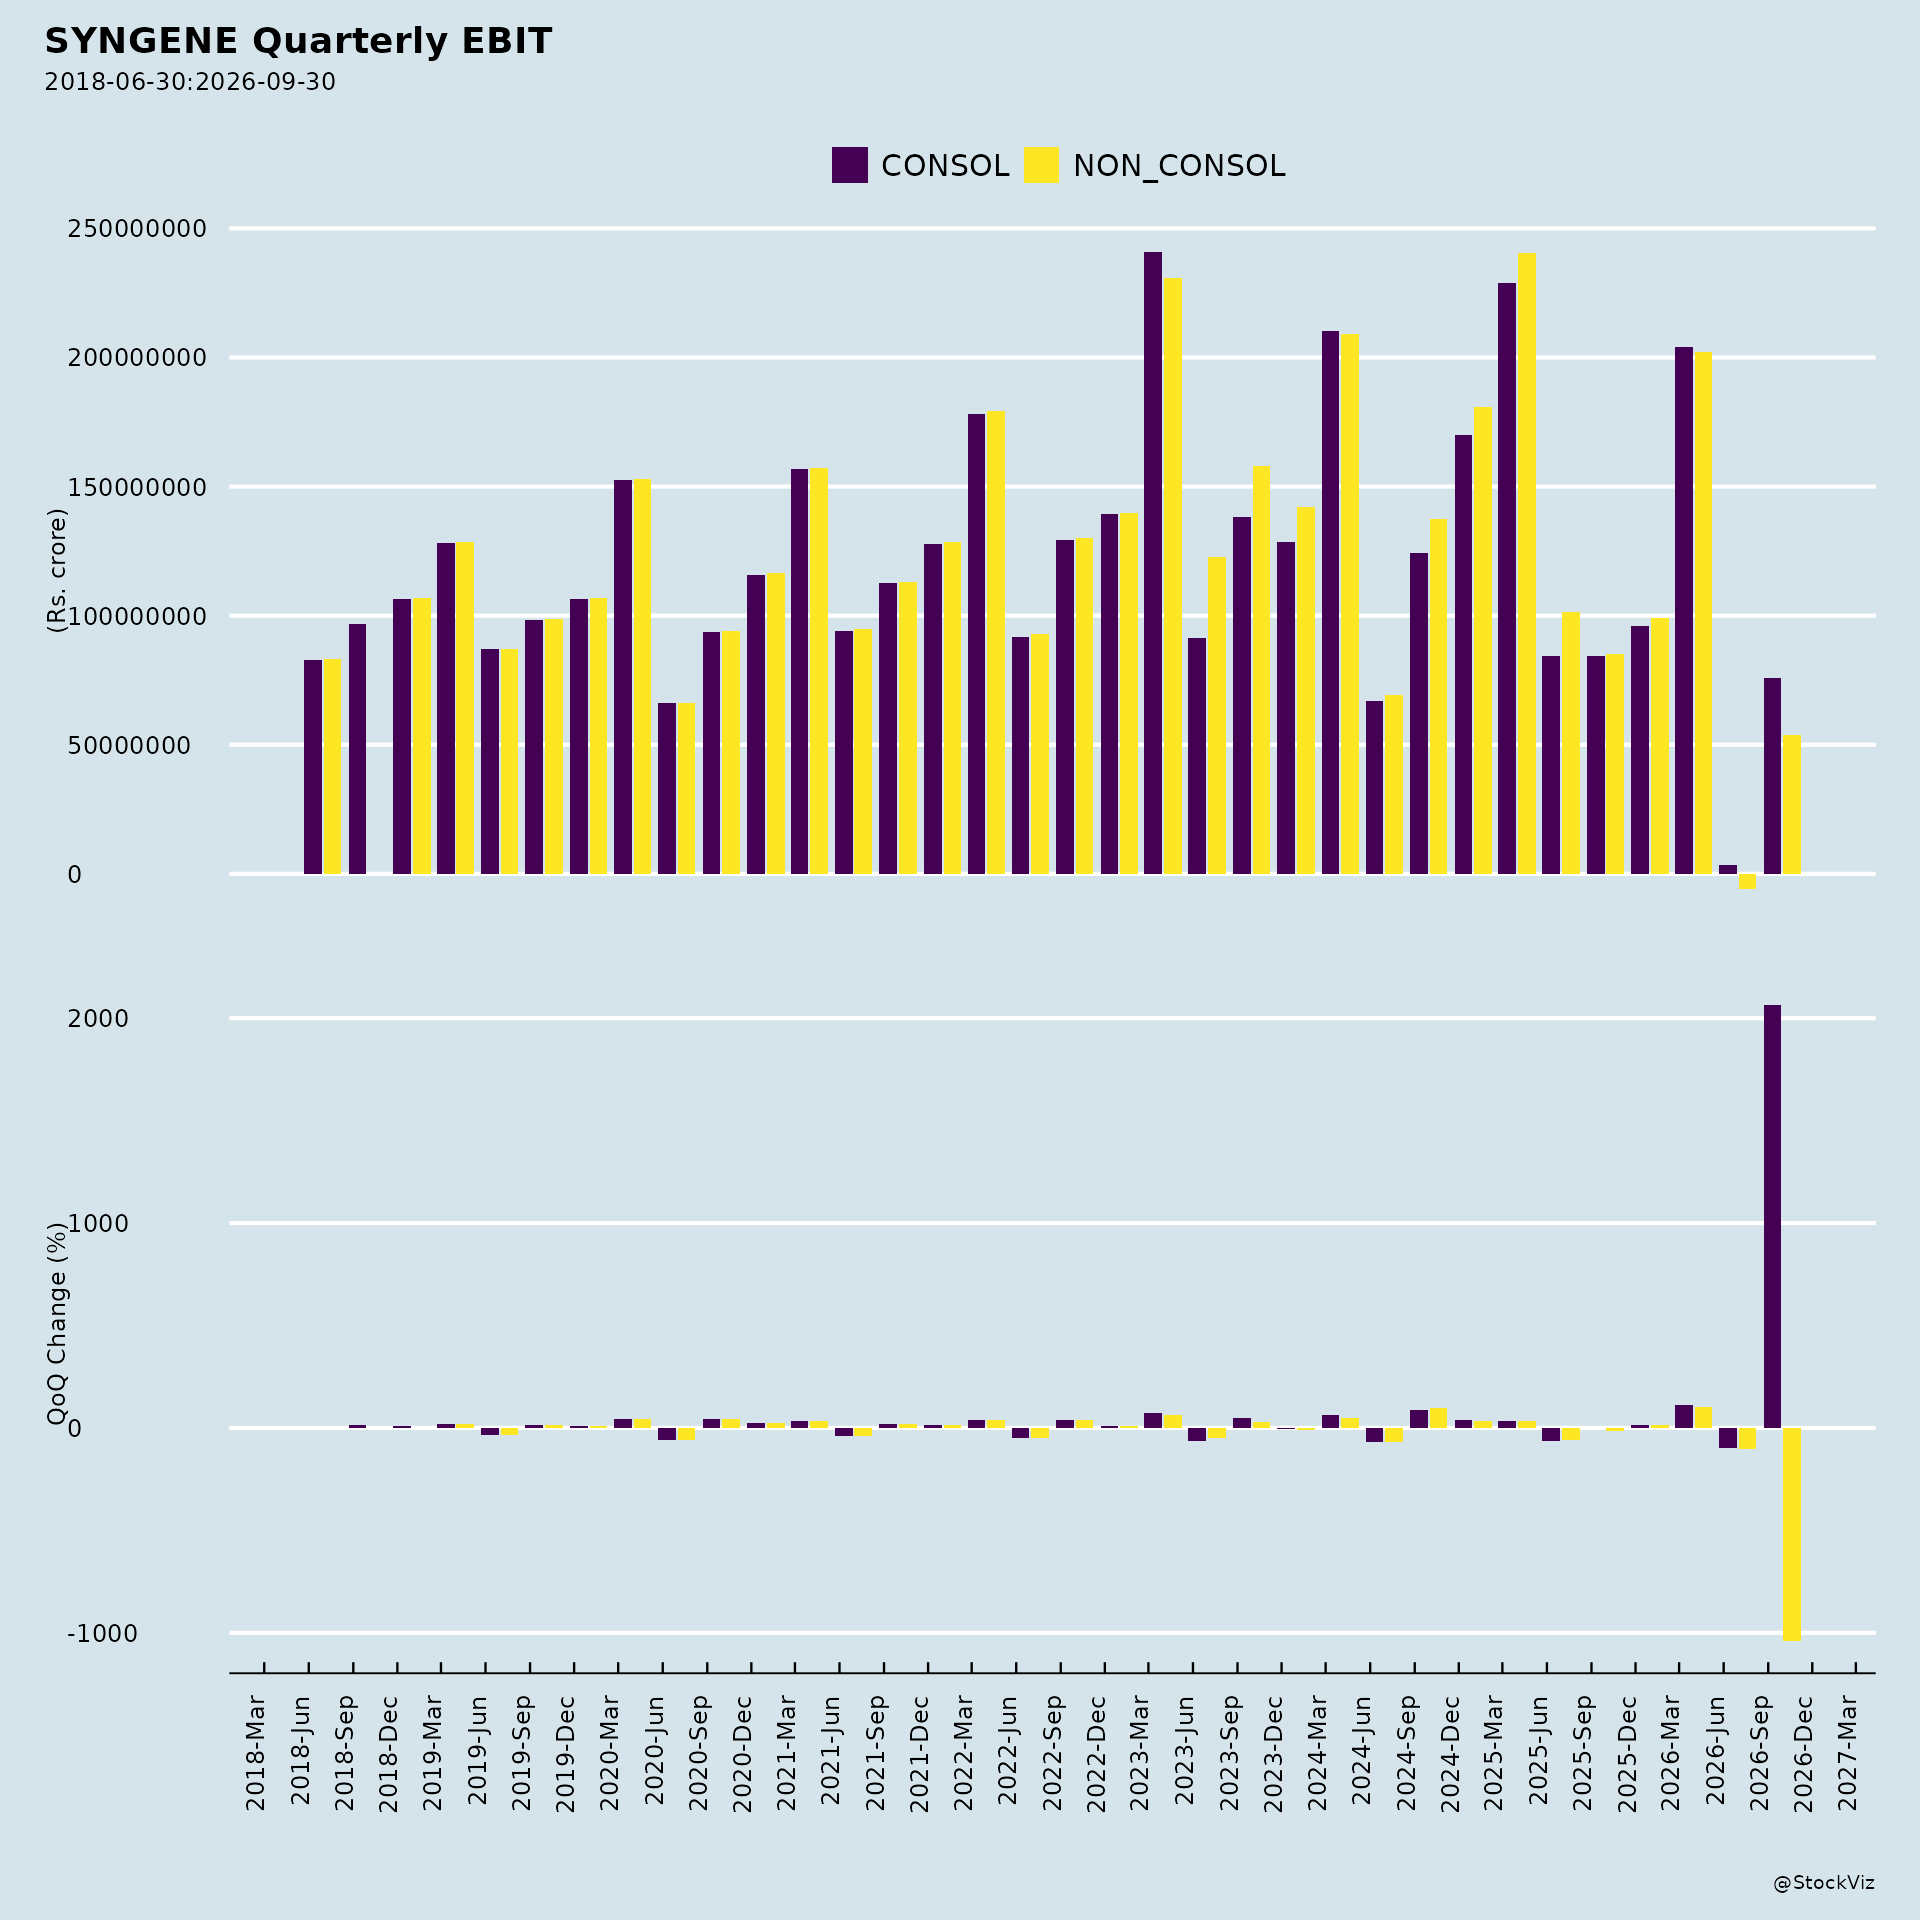
Weak Q1 FY27 operating performance (quarter ended June 30, 2026). Revenue from operations stood at Rs 736 Cr, down 16% year-on-year. Operating EBITDA margin fell to 12%, compared with 24% in Q1 FY26. PAT before exceptional items was Rs 1 Cr, and PAT after exceptional items was negative at Rs -9 Cr.
Stated causes of the weak quarter. The company attributes the performance primarily to the lack of offtake from a major LMCDMO (large molecule contract development and manufacturing) client, compounded by a forex hedge loss. Ongoing cost optimization initiatives partially offset these pressures.
First-half degrowth expected. Management expects degrowth in the first half of the fiscal year, with business momentum only expected to improve in the second half.
Shareholder dissent on certain resolutions at the 33rd AGM (held July 29, 2026). While all nine resolutions passed, some attracted notable opposition: - Resolution 8 (appointment of Dr. Arun Chandavarkar as Independent Director): 23.75% of votes polled were against, with public institutions voting 59.72% against. - Resolution 5 (remuneration to directors in case of absence/inadequate profits): 10.01% of votes polled were against, with public institutions at 25.16% against. - Resolution 9 (appointment of Ms. Vinita Bali as Non-Executive Director): 1.04% against. - Resolution 6 (appointment of Mr. Siddharth Mittal as MD & CEO and his remuneration): 0.59% against.
2. Tailwinds and Growth Prospects
Leadership transition. Siddharth Mittal assumed charge as Managing Director & CEO on July 1, 2026. His appointment and remuneration were approved by shareholders at the AGM on July 29, 2026.
New partnership with BRIC-THSTI. Syngene signed a Memorandum of Understanding with BRIC-Translational Health Science and Technology Institute (THSTI), an institute under the Biotechnology Research Innovation Council, Department of Biotechnology, Ministry of Science and Technology, Government of India. The collaboration establishes a joint operational partnership for early and late-phase clinical development, translational research, and bioanalytical sciences.
AI platform expansion (Syn.AI). Syngene strengthened its AI-enabled scientific platform for accelerating drug discovery services. It developed gigascale virtual screening capabilities, enabling larger libraries of molecules to be screened and prioritized to help clients identify promising drug candidates faster. It also advanced AI-driven de novo (new molecule) design capabilities for faster design and optimization of novel drug candidates.
Sustainability recognition. Syngene was featured in TIME Magazine and Statista’s “World’s Most Sustainable Companies 2026” ranking for the second consecutive year, selected from more than 5,800 companies across 43 countries, ranked among the world’s top 750 most sustainable companies.
Second-half recovery anticipated. Management expects business momentum to improve in the second half of the fiscal year.
Scale and capabilities. The company reports more than ~5,700 scientists out of a total headcount of 8,300+, operating across four global campuses in Bangalore, Mangalore, Hyderabad, and the USA (Baltimore), with integrated solutions across research, development, and manufacturing, and sector expertise spanning pharmaceuticals, biotech, nutrition, animal health, consumer goods, and specialty chemicals.
3. Key Risks
Client concentration / offtake risk. The Q1 FY27 shortfall was driven by the lack of offtake from a major LMCDMO client, illustrating exposure to the ordering patterns of large clients.
Currency and hedging risk. A forex hedge loss contributed to the weak quarter, and the safe harbour statement notes changes in the value of the Rupee and other currencies as a factor that could cause actual results to differ from expectations.
Forward-looking statement risk factors. The company’s safe harbour disclosure lists general economic and business conditions in India, business outlook of clientele and their R&D efforts, ability to implement strategy, growth and expansion plans, technological changes, Indian and international interest rates, changes in laws and regulations applying to Indian and global biotechnology and pharmaceuticals industries, increasing competition, changes in political conditions in India, and changes in foreign exchange control regulations in India.
Governance-related shareholder dissent. The level of votes against Resolution 8 (23.75% overall; 59.72% of public institution votes) and Resolution 5 (10.01% overall; 25.16% of public institution votes) indicates meaningful shareholder opposition on specific appointment and remuneration matters.
4. Management Guidance Versus Observed Business Performance
Guidance for FY27. Management expects a degrowth in the first half of the fiscal year, with business momentum improving in the second half, resulting in single-digit revenue degrowth in rupee terms for the full year and EBITDA margins in the mid-20s.
Observed performance in Q1 FY27. Revenue from operations was Rs 736 Cr, down 16% year-on-year. Operating EBITDA margin was 12%, against 24% in Q1 FY26. PAT before exceptional items was Rs 1 Cr; PAT after exceptional items was Rs -9 Cr.
Comparison. The Q1 FY27 revenue decline of 16% and EBITDA margin of 12% are steeper than the full-year guidance of single-digit revenue degrowth and mid-20s EBITDA margins, consistent with management’s stated expectation that the first half will be weaker and that improvement is expected only in the second half. The Q1 margin of 12% is well below the guided mid-20s full-year level, indicating the anticipated second-half recovery would need to be substantial to align full-year performance with guidance.
Dividend. A final dividend of Rs 1.25 per equity share for the financial year ended March 31, 2026 was declared with shareholder approval at the AGM on July 29, 2026.
Audited financial statements. The audited standalone and consolidated financial statements for the financial year ended March 31, 2026, along with the Board’s and auditors’ reports, were adopted at the AGM.
Broker Narrative
The broker moved from an early Sell focused on margin pressure and weak operating leverage to a prolonged Add/Buy stance in 2024, then reverted to Neutral after growth stayed subdued. Persistent themes were the drag from rising development/manufacturing mix, high overheads, and a lacklustre core research outlook. What changed was the tone: early cautions about no operating leverage were eventually confirmed, and the final report leaned on long-term capability stories like ADCs, peptides, and biologics rather than near-term earnings acceleration.
Fears that came true
- The early warning that the shift toward development/manufacturing would keep overheads higher materialized: last report noted staff costs and other expenses rose 9-14% YoY, pressuring margins.
- The concern that operating leverage would be unlikely in FY24 due to biologics and Mangalore capacity materialized: actual EBITDA margin fell 379 bps YoY to 23.2% and PAT declined.
- The fear of subdued core research growth materialized: the final report called recent years lacklustre, said FY26 would be a wash-out, and gave no guidance upgrade implying no H2 revenue acceleration.
Optimism that failed
- Management’s reiterated FY24 guidance of ~30% hedged margin and mid-teens PAT growth failed to materialize, with the last report showing EBITDA margin at 23.2% and falling PAT.
- The expectation that the Zoetis/Stelis deals would fill biologics capacity and support growth was undermined by the inventory correction in biologics manufacturing that dampened growth.
- The hope that Mangalore FDA approval would set up increased contribution did not translate into sustained earnings; by the last report it was only being developed for peptide capabilities while FY26 was called a wash-out.
Broker Timeline
7 broker calls · 2023-07-28 to 2025-11-06
CNBC-TV18: ratings, targets and commentary
No recorded CNBC-TV18 statements for this ticker.
Management comments
No recorded management comments with an explicit designation and affiliation for this ticker.
Copyright © 2023 SAS Data Analytics Pvt. Ltd. All rights reserved.