Healthcare Research Analytics & Technology
Industry Metrics
April 16, 2026
Annual Returns
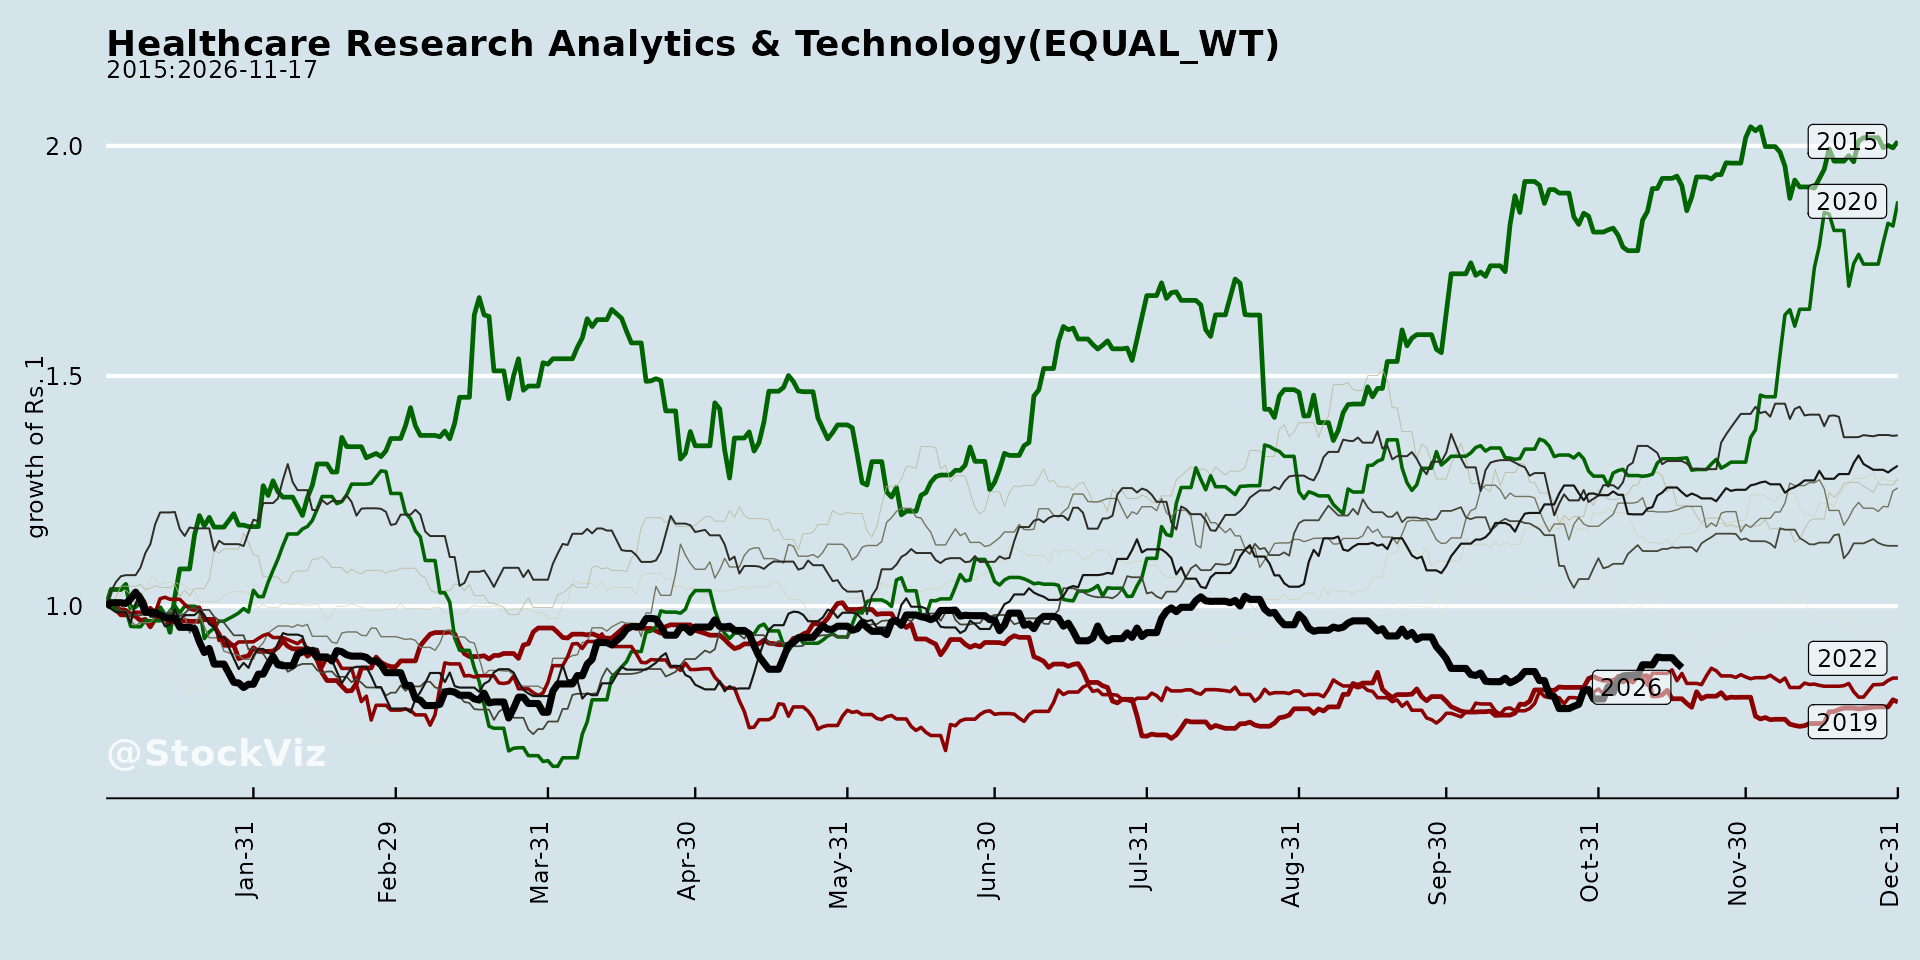
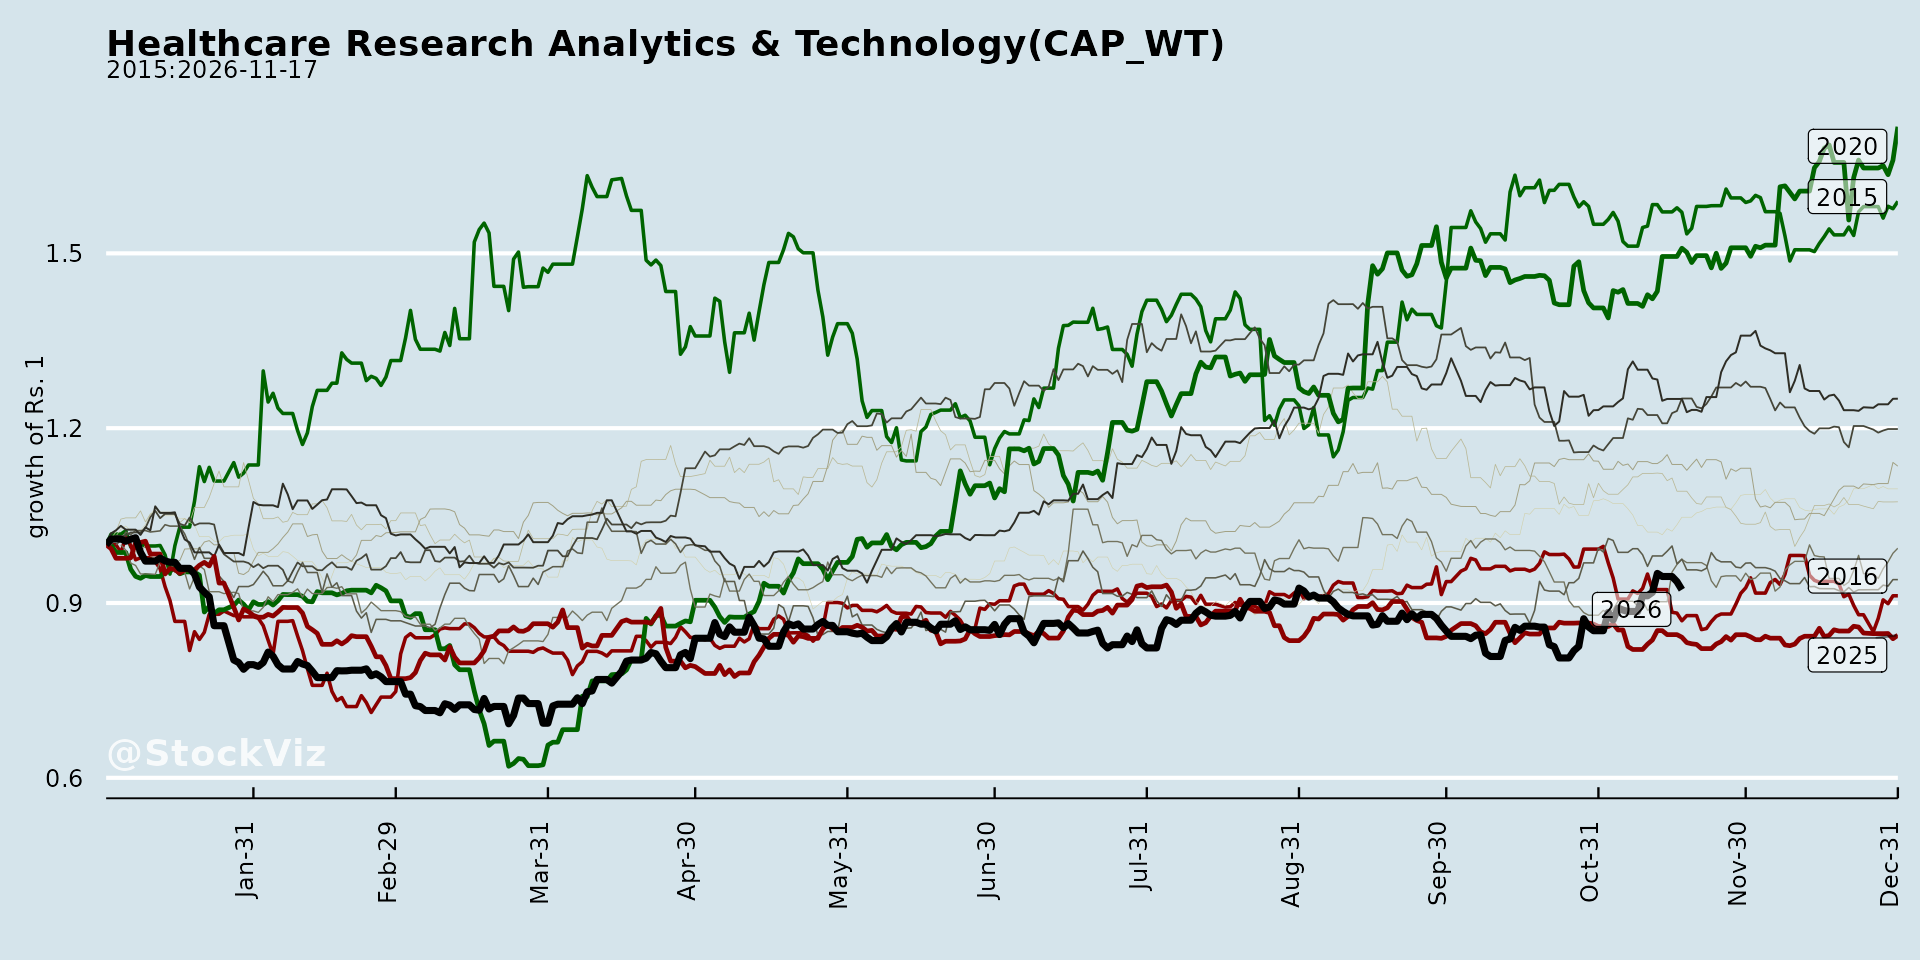
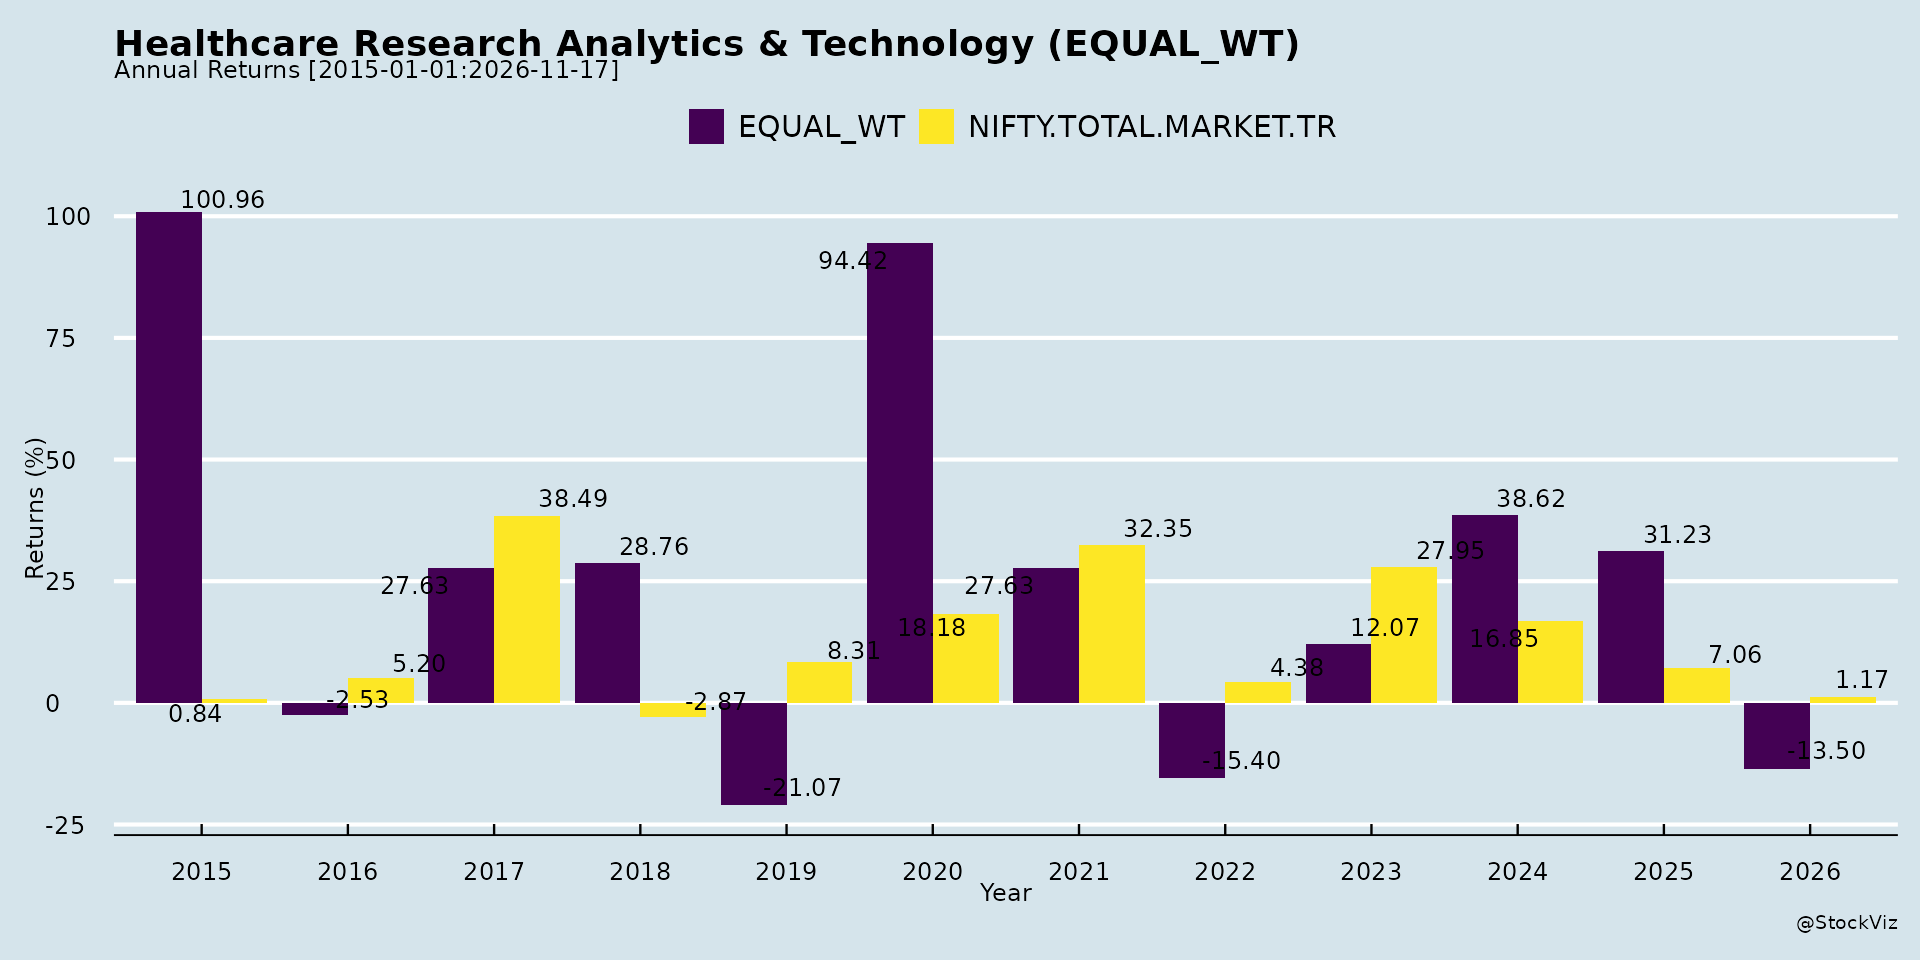
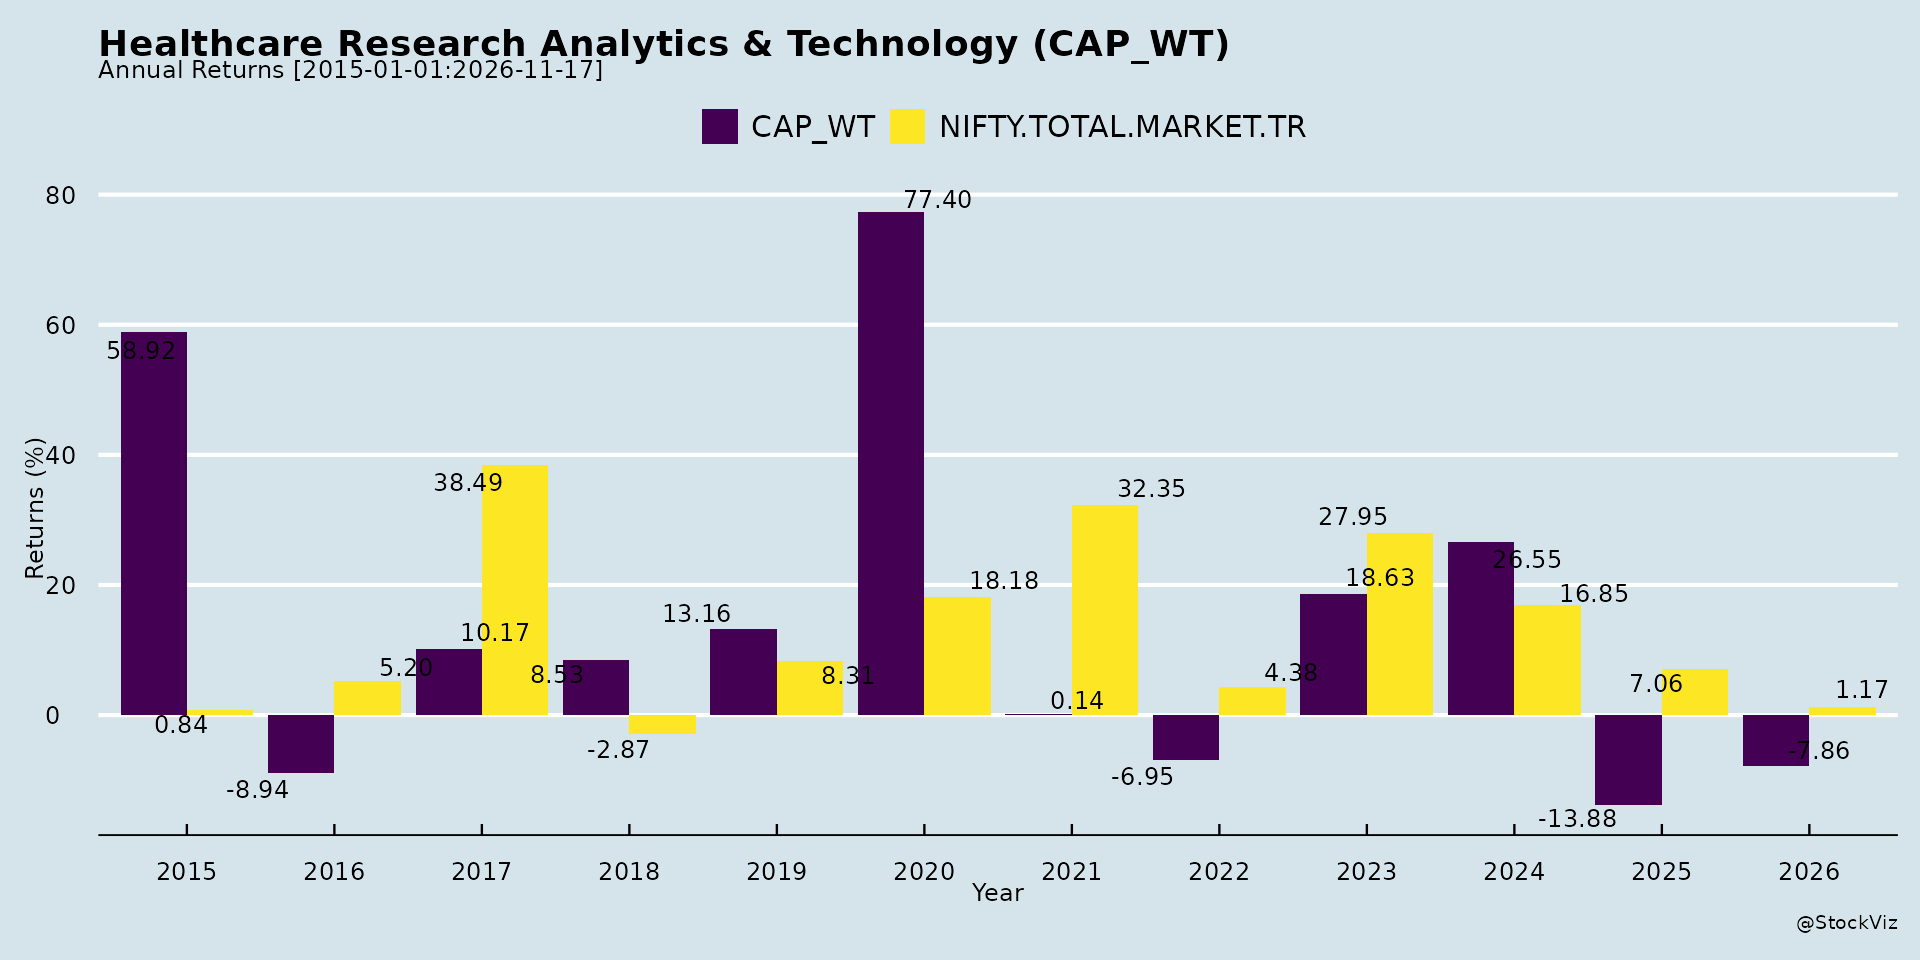
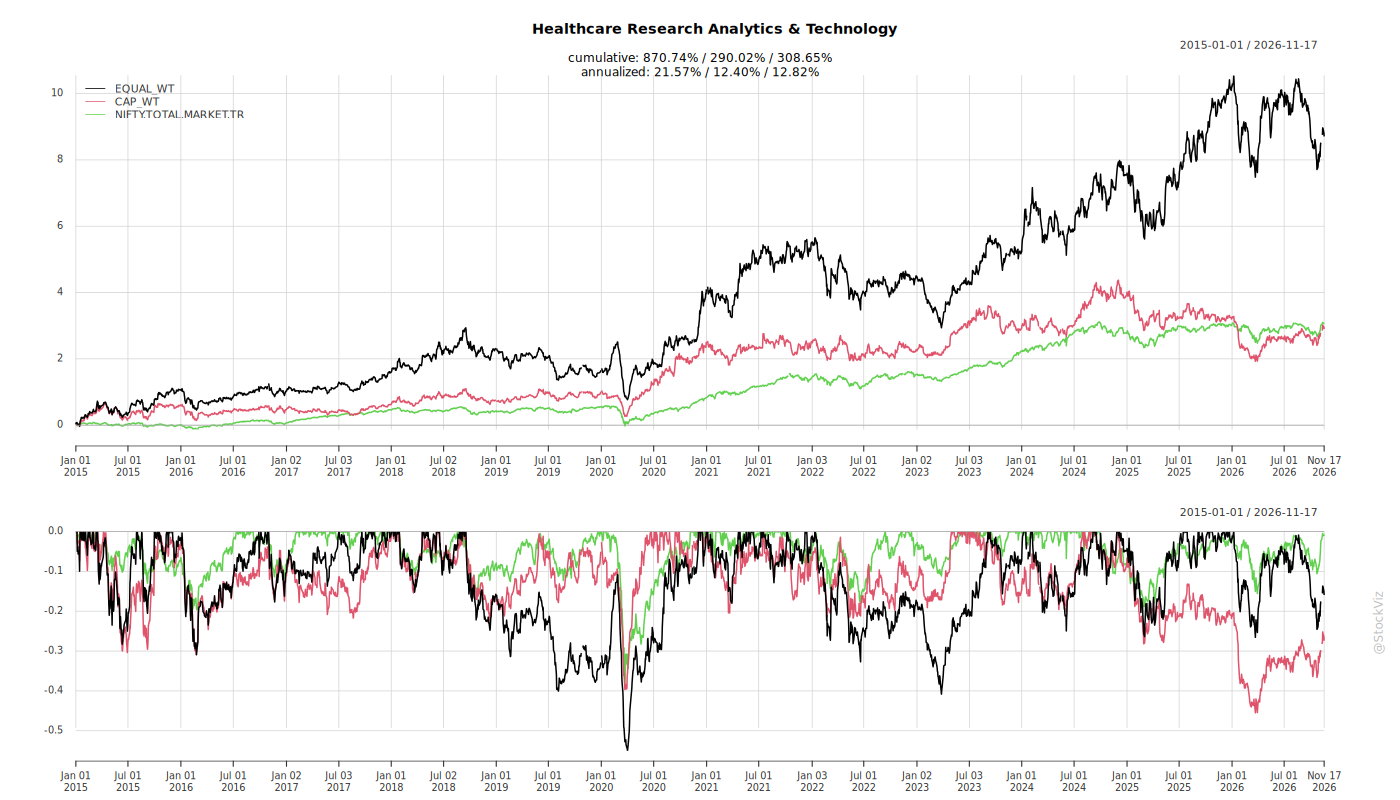
Cumulative Returns and Drawdowns
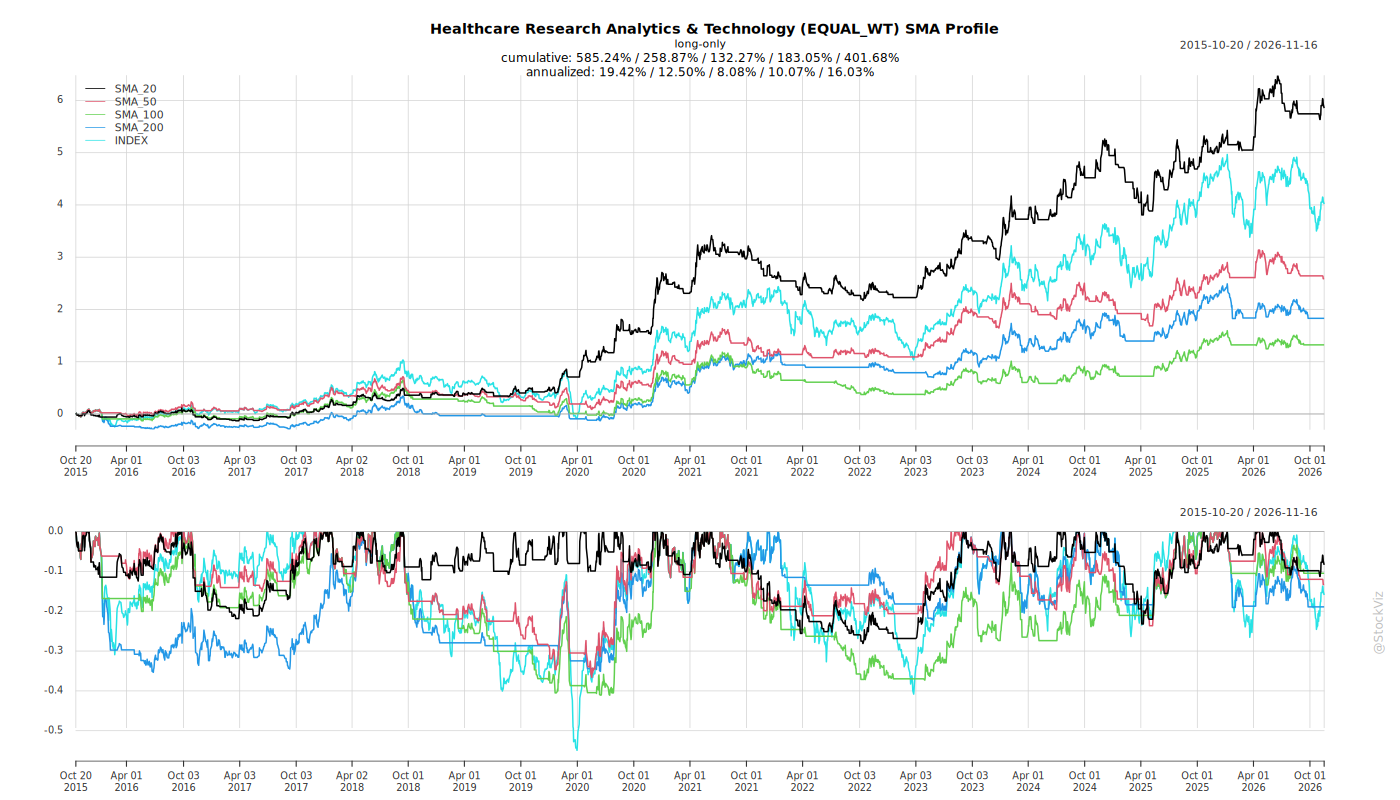
SMA Scenarios
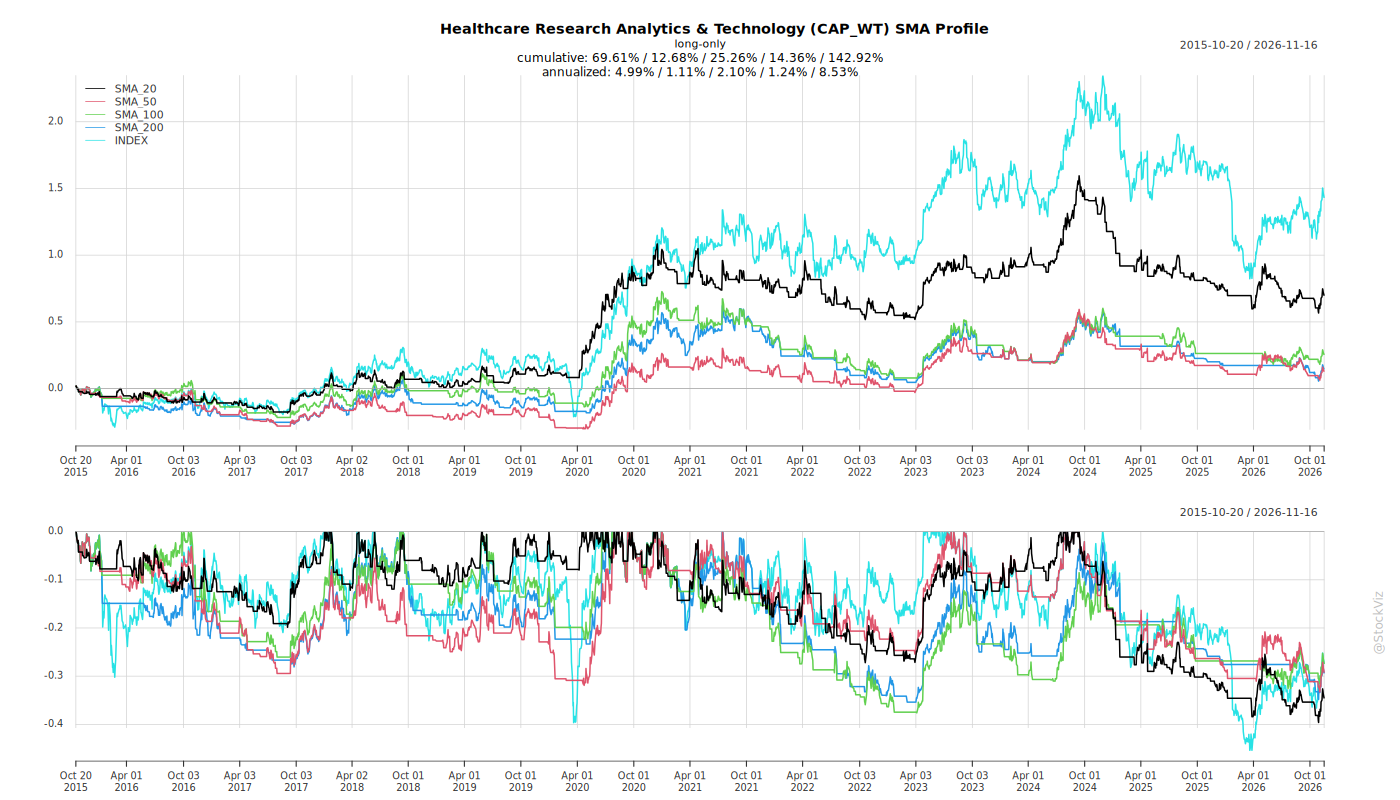
Current Distance from SMA
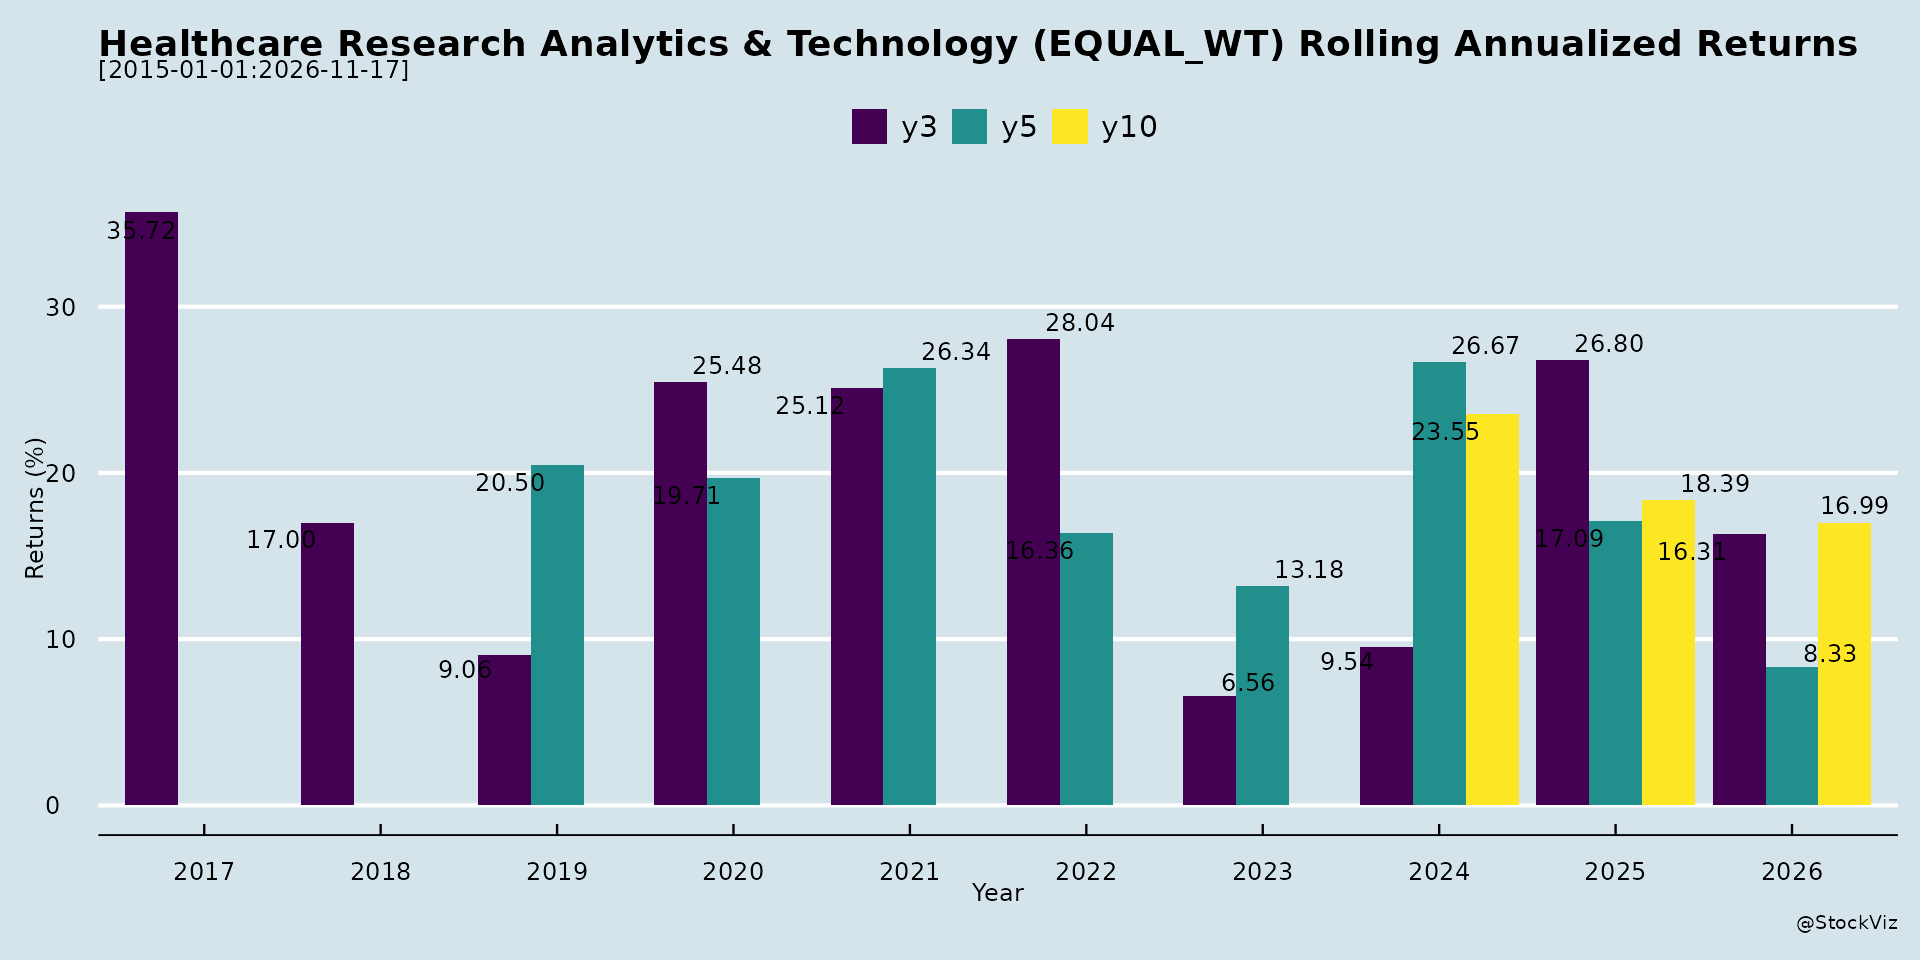
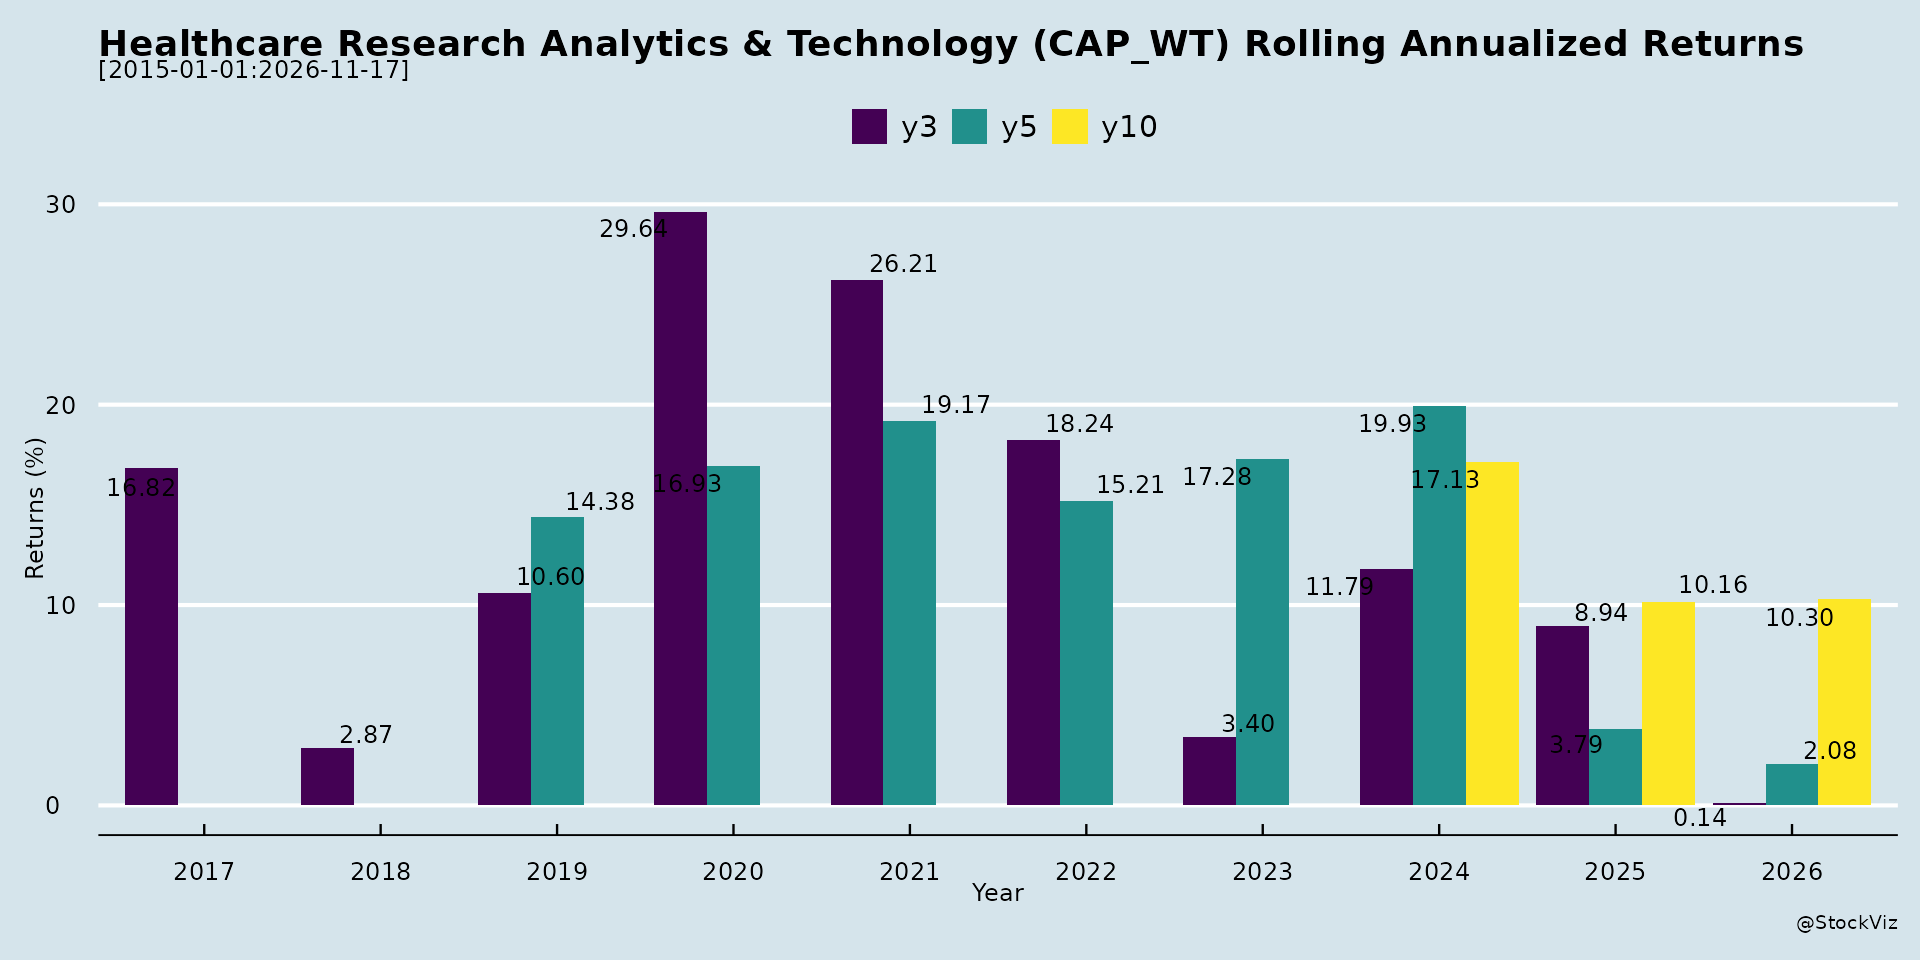
Rolling Returns
Fundamental Ratios
AI Summaries
Analyst
asof: 2025-12-03
Summary Analysis for Indian Healthcare Research, Analytics & Technology Sector
(Based solely on the provided Syngene International and Indegene Limited regulatory filings under SEBI Reg 30, focusing on investor/analyst engagement as a proxy for market sentiment. Syngene represents CRO/discovery services; Indegene represents healthcare analytics/tech. These indicate active roadshows in Dec 2025 amid a sector characterized by outsourcing demand, digital transformation, and global pharma reliance on Indian players.)
Tailwinds
- Strong Institutional Investor Interest: Multiple one-on-one meetings with high-profile investors (e.g., HDFC Mutual Fund for Syngene; WFM Asia, Nalanda Capital, Capital Group, Polunin Capital for Indegene). Singapore roadshows (in-person) signal international appeal, especially from Asia-Pacific and global funds.
- Timely Engagement: Clustered schedules (Dec 1-5, 2025) post-listing cycles (Indegene recently listed), reflecting sustained post-IPO momentum and proactive IR efforts.
- Sector Synergies: Highlights outsourcing tailwinds in healthcare R&D/tech amid global cost pressures on pharma, positioning Indian firms like these as beneficiaries.
Headwinds
- None Explicitly Indicated: Filings show no disruptions; however, Indegene notes schedules “subject to change due to exigencies,” implying operational/logistical vulnerabilities in international roadshows.
- Regulatory Constraints: Strict no-UPSI disclosure underscores limited scope for material updates, potentially capping short-term hype.
Growth Prospects
- Investor Roadshow Momentum: 9+ meetings across virtual (Syngene) and in-person (Indegene) formats suggest building conviction for FY26 growth narratives, e.g., Syngene’s SEZ-based CRO expansion and Indegene’s analytics/digital services scaling.
- Capital Inflow Potential: Engagement with long-only funds (e.g., Nalanda, Capital Group) points to prospects for stake builds, funding M&A/tech investments in a sector growing ~15-20% CAGR (inferred from typical Indian CRO/tech trends).
- Global Footprint: Singapore focus enhances visibility in high-growth Asia markets, aiding deal pipelines in clinical/research analytics.
Key Risks
- Schedule Volatility: Indegene explicitly flags changes; cancellations could signal internal issues (e.g., earnings misses or macro slowdowns).
- No Material Disclosure: Emphasis on no UPSI limits upside surprises, with risks of unmet expectations if meetings underwhelm.
- Execution/Geo Risks: In-person Singapore events expose to travel/logistics disruptions; sector risks include US FDA scrutiny on Indian CROs, talent shortages in analytics, and forex volatility (INR vs. USD client revenues).
- Market Dependency: Reliance on institutional buy-in; any broader equity sell-off (e.g., high valuations in healthcare tech) could amplify downside.
Overall Outlook: Positive sentiment driver with robust IR activity outweighing minor risks. These filings signal sector resilience and growth storytelling potential, meriting monitoring for Q3FY26 updates. No quantitative financials provided; analysis qualitative.
Financial
asof: 2025-11-29
Indian Healthcare Research, Analytics & Technology Sector Analysis
Based on Q3 & 9M FY25 Financial Results (ended Dec 31, 2024) of Key Players: Syngene Intl., Indegene Ltd., Suven Life Sciences, Vimta Labs, TAKE Solutions
This analysis synthesizes insights from the provided filings for listed players in India’s CRO (Contract Research Orgs.), pharma services, testing labs, digital commercialization, and life sciences IT/analytics space. The sector benefits from global outsourcing trends but faces volatility from high R&D costs and execution risks. Data in ₹ Mn unless noted.
Tailwinds (Positive Drivers)
- Robust Revenue Growth in Core Players:
- Indegene: Revenue from ops up 7% QoQ/YoY to ₹7,204 (9M: ₹20,857, +9% YoY). Strong other income (₹457) from contingent consideration reversals. Profit before tax ₹1,463 (9M: ₹3,949).
- Vimta Labs (Standalone/Consol.): Revenue +8% QoQ to ₹885/₹899 (9M: ₹2,450/₹2,495, +15-16% YoY). PAT from continuing ops ₹170/₹175 (9M: ₹467/₹484).
- Profitability & Efficiency: Indegene EPS ₹4.95 (basic); Vimta EPS ₹7.65/₹7.86 (continuing). Syngene clarified steady reporting (INR Mn basis).
- Strategic Moves:
- Indegene: IPO proceeds (₹760 Cr) deployed; acquisitions (e.g., Trilogy) integrated.
- Vimta: NFL lab PPP with FSSAI operational; diagnostics business sold for ₹70 Mn (+royalties).
- Sector Enablers: Rising global demand for India-based R&D outsourcing, digital analytics (Indegene’s strength), and testing (Vimta). Post-IPO liquidity for expansion.
Headwinds (Challenges)
- Persistent Losses in R&D-Heavy Firms:
- Suven Life Sciences: Revenue flat ~₹161 (9M: ₹519, -44% YoY); PAT loss ₹3,911/₹1,327 (9M: ₹11,680 loss). High R&D (₹3,413) & employee costs dominate.
- TAKE Solutions: Minimal continuing revenue (₹9 9M); massive discontinued losses (₹747 9M standalone). Group PAT swing to ₹477 profit (from ₹90 loss YoY) driven by one-off EAL divestment gain.
- High Costs & Impairments: Employee expenses 50-60% of revenue (Indegene: ₹4,438; Suven: ₹487); R&D burn (Suven); past impairments (TAKE: ₹484 FY24).
- Operational Scale-Down: TAKE/Suven near-zero revenue from ops; TAKE’s CRO ops discontinued post-EAL sale.
Growth Prospects (Outlook)
| Company | Key Drivers | Projected Catalysts |
|---|---|---|
| Indegene | 9% YoY revenue growth; digital-led model. | Inorganic growth (IPO funds); Trilogy/Cult integrations; FY25 guidance intact. |
| Vimta Labs | 15%+ YoY topline; lab expansions. | NCLT-approved EMTAC merger; ESOP grants; brand royalties from Thyrocare deal. |
| Syngene | Steady (clarified reporting); Biocon synergy. | CRDMO demand; SEZ advantages. |
| Suven | Rights issue (₹400 Cr utilized 94%). | Pipeline clinical trials; R&D pivot (balance ₹22 Cr GCP). |
| TAKE | EAL divestment (USD 6.5 Mn); diversification. | M&A/partnerships in non-CRO verticals (FY26 closure eyed). |
- Sector-Wide: 10-15% CAGR potential from US/EU outsourcing, AI/analytics adoption (Indegene), testing labs boom (Vimta). Rights/IPOs fund capex/R&D.
Key Risks (Material Concerns)
| Risk Category | Details | Impacted Cos. |
|---|---|---|
| Going Concern | Negative networth/working capital (TAKE: erosion FY24); unpaid dues/litigations. Qualified audit opinions (TAKE). | TAKE (high); Suven (med). |
| Tax/Regulatory | ₹88-119 Mn tax assets (recoverability doubt); ₹113-726 Mn contingents (Ind AS 37). Statutory dues defaults. | All (TAKE/Suven acute). |
| Operational | R&D overruns (Suven 80%+ expenses); revenue concentration; discontinued ops (TAKE/Vimta diagnostics). | Suven/TAKE. |
| Compliance/Gov. | No CS/Compliance Officer (TAKE); suboptimal Board (Reg 17 LODR violation). | TAKE. |
| Financial | Deviation in IPO/GCP use (Indegene: rectified ₹38 Cr transfer); ECL impairments. Negative EPS in distressed firms. | Indegene (low); TAKE/Suven (high). |
| Macro | Forex (multi-country subs); clinical trial delays; US FDA scrutiny. | All. |
Overall Sector Summary: Mixed bag – Indegene/Vimta shine (growth engines) with 10-20% revenue/PAT uptick; Suven/TAKE drag (turnaround bets) with losses but asset sales/R&D bets. Tailwinds from outsourcing/digital outweigh headwinds for leaders; risks cluster in distressed players (litigation, liquidity). Selective optimism: Prioritize Indegene/Vimta (buy/hold); monitor Suven/TAKE for pivots. Sector FY25 growth ~12% est., but volatility from R&D cycle.
Note: Analysis based solely on filings; no external data. Figures rounded; consult full reports.
General
asof: 2025-11-29
Summary Analysis: Indian Healthcare Research, Analytics & Technology Sector
Using the provided regulatory filings from Syngene International (CRO/CMO), Indegene (healthcare tech/services), and Vimta Labs (testing/analytics), the analysis highlights sector dynamics as of Oct-Nov 2025. These documents reflect routine governance but signal underlying operational health, compliance focus, and employee incentives amid stable growth.
Tailwinds (Positive Catalysts)
- Strong Regulatory Compliance & Shareholder Engagement: Syngene’s proactive participation in MCA’s ‘Saksham Niveshak’ campaign (emailing ~thousands of shareholders for unclaimed dividends) underscores efficient investor relations and risk mitigation before IEPF transfers. This enhances trust and liquidity.
- Employee Incentives & Retention: Vimta Labs secured in-principle approvals for listing ~11.81 lakh ESOP shares (post-bonus issue of 1:1 on June 2025), signaling robust talent retention in a competitive talent market. Bonus issues reflect cash-rich balance sheets.
- Transparency in Trading: Indegene’s trading window opening (Nov 2, 2025) ahead of Q2 FY26 results promotes governance, potentially building investor confidence pre-earnings.
Headwinds (Challenges)
- Administrative Inefficiencies: Syngene notes unclaimed dividends (e.g., pre-2019 FYs; no dividends in FY20-21 likely due to COVID disruptions), indicating legacy KYC/bank update gaps among shareholders. This could signal broader communication hurdles in fragmented investor bases.
- Routine Delays in Approvals: Vimta’s post-bonus ESOP refiling (July 2025 approvals) highlights procedural lags post-corporate actions, common in SEBI-regulated ESOPs.
Growth Prospects
- High: Employee stock programs (Vimta’s ESOP expansion) and bonus issues point to internal confidence in scaling R&D/testing capacities amid India’s pharma outsourcing boom (CAGR ~10-12% projected). Syngene/Indegene’s filings imply steady quarterly momentum, with trading windows signaling upcoming positive results disclosures. Sector tailwinds include rising global demand for Indian CROs/tech (e.g., US FDA approvals, AI-driven analytics).
- Outlook: Moderate acceleration in FY26, driven by talent-aligned incentives and compliance maturity.
Key Risks
| Risk Category | Details | Mitigation from Filings |
|---|---|---|
| Compliance/Regulatory | IEPF transfers (Syngene); ESOP listing delays (Vimta). | Active campaigns & approvals demonstrate proactivity. |
| Dilution & Capital | ESOP issuance (~Rs. 2 par; Vimta: 11.81L shares) post-bonus could dilute EPS mildly. | Offset by growth in testing/CRO revenues. |
| Insider Trading/Governance | Trading window norms (Indegene); unclaimed dividends expose inactive shareholders. | Strict SEBI adherence reduces volatility risks. |
| Sector-Specific | Legacy dividend gaps hint at investor apathy; no major red flags but monitor Q2 results for macro headwinds (e.g., US election impacts on outsourcing). | Low immediate; filings show operational stability. |
Overall: Mildly positive sentiment with governance focus outweighing minor admin headwinds. No acute distress; growth intact via incentives. Monitor Q2 earnings for revenue validation. Sector PE multiples (20-30x) likely supported.
Investor
asof: 2025-12-03
Summary Analysis: Indian Healthcare Research Analytics & Technology Sector (Based on Syngene and Indegene Announcements)
Using the provided documents from Syngene International Limited (CRDMO/biotech services) and Indegene Limited (healthcare commercialization, analytics, and technology), both key players in India’s healthcare R&D, analytics, and tech ecosystem, the following analysis focuses on headwinds, tailwinds, growth prospects, and key risks. These disclosures under SEBI Regulation 30 highlight investor engagement activities but contain no financials, UPSI, or operational details—limiting depth to qualitative inferences on market sentiment and IR activity.
Tailwinds
- Robust Institutional Investor Interest: Multiple one-on-one meetings scheduled with high-profile global and domestic funds (e.g., HDFC Mutual Fund for Syngene; WFM Asia, Nalanda Capital, Capital Group, Polunin Capital, Oxbow for Indegene). This signals strong demand for exposure to Indian healthcare tech/services amid sector tailwinds like digital transformation, outsourcing from Big Pharma, and India’s cost-competitive R&D hub status.
- Proactive IR in Key Hubs: Indegene’s in-person roadshow in Singapore (Dec 1-4, 2025) targets Asia-Pacific investors, leveraging proximity and time-zone alignment (SST timings). Syngene’s virtual format enhances accessibility, reflecting operational efficiency in a hybrid post-pandemic world.
- Regulatory Compliance & Transparency: Explicit no-UPSI commitment builds trust, supporting sector tailwinds from improving governance perceptions.
Headwinds
- None Directly Evident: Documents show no explicit challenges. However, inferred sector headwinds (e.g., global pharma R&D budget pressures, US FDA scrutiny on Indian CROs, or geopolitical supply chain risks) are not referenced, suggesting companies view current momentum positively enough for investor outreach.
- Logistical Dependencies: Indegene notes schedules “subject to change due to exigencies,” hinting at minor operational headwinds like travel disruptions in international roadshows.
Growth Prospects
- High Confidence in Narrative: Scheduling ~8 meetings across two firms in early December 2025 implies upcoming catalysts (e.g., Q3FY26 earnings previews or pipeline updates), positioning the sector for growth via:
- Outsourcing Boom: Syngene’s Bengaluru SEZ focus aligns with CRDMO expansion; Indegene’s analytics/tech stack taps AI/ML in healthcare commercialization.
- Global Footprint: Singapore roadshows target APAC capital, signaling scalability beyond India (e.g., Syngene’s Biocon ties, Indegene’s digital platforms).
- Sector Outlook: Positive IR cadence suggests 15-20%+ CAGR potential (historical sector trends), driven by telemedicine, real-world evidence analytics, and biologics R&D.
- Digital/Tech Edge: Virtual (Syngene) and hybrid formats underscore tech-savvy operations, a growth driver in analytics-heavy sub-sectors.
Key Risks
- Information Asymmetry: Strict no-UPSI policy limits insights, risking investor disappointment if meetings yield no new positives; potential for stock volatility post-meetings.
- Execution & External Factors: Schedule changes (Indegene), venue dependencies (Singapore travel), or broader risks like regulatory delays (SEBI scrutiny), forex volatility (INR vs. USD inflows), or sector-specific issues (e.g., clinical trial slowdowns, AI ethics in healthcare analytics).
- Concentration Risk: Reliance on one-on-one formats (no group events) could amplify impact if key investors (e.g., Nalanda, Capital Group) react negatively.
- Macro Risks: Implicit in sector—US election outcomes, global inflation curbing pharma capex, or competition from peers like IQVIA/TCS Lifesciences.
Overall Summary: These announcements portray a bullish IR momentum for Indian healthcare R&D/analytics/tech, with strong tailwinds from investor appetite outweighing muted headwinds. Growth prospects appear solid, fueled by proactive engagement, but risks center on execution and lack of substantive disclosures. No red flags; monitor post-meeting outcomes and company websites for updates. Sector sentiment: Positive (Buy/Hold bias inferred).
Analysis strictly derived from documents; broader fundamentals require financial filings.
Meeting
asof: 2025-11-29
Analysis of Indian Healthcare Research, Analytics & Technology Sector (Based on Q2 FY26 Results of Key Players: Syngene, Indegene, Suven Life Sciences, TAKE Solutions)
The provided documents represent unaudited Q2/H1 FY26 financial results (ended Sep 30, 2025) from four listed players in India’s Healthcare Research, Analytics & Technology ecosystem: - Syngene Intl.: CRAMS/CDMO (contract research/manufacturing). - Indegene Ltd.: Healthcare analytics, tech, and commercial services. - Suven Life Sciences: Drug discovery (CNS focus). - TAKE Solutions: Life sciences IT/services (under distress).
Overall Sector Snapshot (H1 FY26 vs. H1 FY25, Consolidated where available): - Revenue: Mixed; Indegene +15% YoY (₹15,650 Mn), Syngene +6% (₹17,851 Mn); Suven flat/minimal (₹279 Mn); TAKE negligible. - PAT: Indegene +22% (₹2,185 Mn); Syngene -15% (₹1,538 Mn); Suven deep losses (₹12,883 Mn); TAKE breakeven post-divestments (₹54 Mn profit but qualified audit). - Key Trends: Revenue resilience in services/digital (Indegene/Syngene), R&D drag (Suven), distress/divestments (TAKE). High capex (Syngene ₹11 Bn CWIP), funding raises (Suven warrants ₹3 Bn), acquisitions (Indegene).
Below is a structured analysis of headwinds, tailwinds, growth prospects, and key risks for the sector, derived from financials, notes, cash flows, and auditor commentary.
Headwinds (Challenges Pressuring Performance)
- High Operating Costs & Losses: R&D intensity (Suven: ₹11.2 Bn expenses, 70% of costs); employee costs up 11-15% YoY across firms (Syngene ₹5.4 Bn); forex losses (Syngene ₹166 Mn net).
- Forex & Impairment Volatility: Syngene bad debt write-off ₹277 Mn (10% of PAT impact); TAKE ECL ₹16 Mn; OCI forex swings (Syngene -₹1.2 Bn).
- Cash Burn & Liquidity Strain: Negative operating cash flows (Syngene -₹700 Mn standalone; TAKE -₹31 Mn); Suven/Take heavy capex/debt paydown despite raises.
- Distressed Players: TAKE facing “material uncertainty” on going concern (qualified audit, unpaid dues, divestments); minimal revenue across board.
- Macro Pressures: US/EU slowdown in outsourcing? (Implied by flat/minimal revenues in Suven/TAKE).
Tailwinds (Supportive Factors)
- Revenue Momentum in Core Services: Indegene +15% YoY (segments: Medical +13%, Commercial +23%); Syngene +6% (ops revenue ₹17.9 Bn), driven by biologics/manufacturing.
- Strategic Expansions: Syngene capex (biologics site USD 35 Mn, new lines ₹3.4 Bn capitalized); Indegene acquisitions (MJL, BioPharm ₹9 Bn deal, Ireland €8.5 Mn invest).
- Profitability in Digital/Tech: Indegene EBITDA margins ~25%, PAT margins 14%; share-based incentives for talent retention.
- Funding Inflows: Suven preferential warrants ₹3 Bn (94 Mn shares allotted); Indegene ESOP/RSU grants.
- Pipeline/Portfolio Strength: Suven 17 patents (CNS drugs in Ph3); Syngene single-use bioreactor to 50kL capacity.
Growth Prospects (Forward Opportunities)
| Driver | Key Evidence | Potential Impact |
|---|---|---|
| Outsourcing Boom | Syngene/Indegene revenue +6-15%; global biologics/digital demand. | H2 FY26: 10-20% sector growth; Indegene targets commercialization via AI/AdTech. |
| Pipeline Milestones | Suven: SUVN-502 Ph3 (Alzheimer’s, end-2026); SUVN-G3031 Ph3 prep (Narcolepsy). | Partnerships/licensing deals; peak sales potential in CNS (unmet needs). |
| M&A/Expansion | Indegene (BioPharm USD104 Mn, Warn & Co GBP3 Mn); Syngene US biologics site. | Revenue synergies 20-30%; Ireland/Europe scaling (Indegene €739k turnover). |
| Digital/Analytics | Indegene segments (Medical 28%, Commercial 60% of rev); Brand Activation pivot. | 15-25% CAGR; AI-driven pharma marketing (Omnicom-like scale). |
| Capex Ramp | Syngene CWIP ₹10 Bn; Suven ESOP for talent. | FY26E revenue 10-15% up; EBITDA margins 25-30% (ex-Suwen). |
Outlook: Sector FY26E growth 12-18% (services-led), led by Indegene/Syngene (60-70% share); Suven turnaround via pipeline (high-risk/high-reward); TAKE recovery via M&A/diversification.
Key Risks (High-Impact Threats)
| Risk | Probability/Impact | Mitigants/Evidence |
|---|---|---|
| Forex & Write-offs | High/Medium (Syngene ₹182 Mn loss). | Hedging (derivatives ₹830 Mn assets). |
| Tax/Regulatory Litigations | High/High (Syngene/TAKE ₹100-700 Mn contingents; Vivad se Vishwas partial relief). | Settlements (Indegene TDS resolved ₹95 Mn). |
| Going Concern/Liquidity | Medium/High (TAKE qualified audit; cash burn). | Divestment proceeds (TAKE Ecron ₹ proceeds used). |
| Pipeline/Clinical Failures | High/High (Suven 100% R&D loss). | Diversified (Ph1-Ph3); 17 patents. |
| Capex Overruns | Medium/Medium (Syngene ₹28 Bn assets). | Insurance claims (past ₹320 Mn); steady revenue. |
| Auditor Qualifications | Medium/High (TAKE modified opinion on recoverability). | Management plans (M&A diversification). |
| Competition/Geopolitics | Low/Medium (US tariff risks?). | India cost-edge; global network. |
Overall Summary: - Bullish Core: Services/digital tailwinds (Indegene/Syngene) drive 10-15% growth amid global outsourcing; expansions/M&A enhance prospects. - Caution on Edges: R&D drags (Suven losses) and distress (TAKE) cap sector upside; forex/tax risks persistent. - Net View: Moderate Positive (Hold/Buy services leaders; Avoid high-burn biotech/distressed). FY26E sector PAT growth ~10%, but volatility from externalities. Monitor Q3 capex utilization, pipeline updates, tax resolutions. Sector resilient but bifurcated (winners: tech/services; laggards: pure R&D/distressed).
Data as of Nov 2025 filings; Ind AS compliant; all figures ₹ Mn unless stated.
Press Release
asof: 2025-11-29
Indian Healthcare Research Analytics & Technology Sector Analysis
Based on Q1/Q2 FY26 Results from Syngene, Indegene, Suven Life Sciences, and Vimta Labs (Key Players in CRO/CDMO, Testing, Drug Discovery, and Life Sciences Tech Services)
The sector demonstrates resilient revenue growth amid cost pressures and investments, driven by global demand for biologics, clinical trials, and tech-enabled services. Mixed performance: Strong top-line momentum (avg. ~15-20% YoY in most), but profitability challenged by expenses and FX. H1 FY26 aggregate revenue trends positive, with expansions in high-growth areas like ADCs and digital commercialization.
Tailwinds (Positive Drivers)
- Robust Revenue Growth: Indegene +17% YoY (₹804 Cr Q2), Vimta record +22% YoY (₹1045 Mn Q2, +27% H1), Syngene H1 +6% (₹1785 Cr). Driven by pharma research/testing, clinical services, and deal wins.
- Strategic Wins & Expansions: Syngene’s first global Phase III trial (US/India), ADC bioconjugation suite, US Bayview facility progress; Indegene’s BioPharm/WARN acquisitions for omnichannel/media expertise; Vimta’s WHO audit success; Suven’s pipeline (Phase 3 Alzheimer’s/Narcolepsy drugs) and ₹8576 Mn fundraise.
- High Margins in Leaders: Vimta EBITDA ~35% (stable), Indegene adj. EBITDA 18%; Syngene maintains FY26 guidance despite dips.
- Sector Enablers: Improving US biotech funding; geographic expansion (Syngene: Australia/UK/Europe; Indegene digital summits); sustainability leadership (Syngene top EcoVadis percentile); tech integration (Indegene AI/Tectonic models).
Headwinds (Challenges)
- Margin Compression: Syngene Q2 EBITDA -18% YoY (23.2% margin vs. 28.8%), PAT -37% (7.3%); H1 EBITDA flat/-2%. Factors: biologics inventory correction, staff costs +13-14% YoY, FX losses (₹118 Mn Q2), receivables write-off (₹277 Mn).
- High Expenses & Losses: Suven Q1 loss ₹515 Mn (R&D ₹526 Mn burn); sector-wide staff/other costs up 8-14% YoY.
- Modest/Volatile Growth: Syngene Q2 +2% YoY (sequential +4%); Suven revenue down to ₹25 Mn (clinical-stage drag).
- External Pressures: Negative FX (Syngene H1 -₹166 Mn); divestitures (Vimta diagnostics sale for focus).
Growth Prospects
- High-Potential Areas: ADCs/peptides/biologics manufacturing (Syngene/Vimta capacities); global clinical trials (Phase III wins, multi-region execution); digital/commercialization tech (Indegene 17% growth flywheel via acquisitions).
- Pipeline & Capacity: Suven’s Phase 2B/3 trials (Alzheimer’s, Narcolepsy, MDD) by FY26-27; Syngene’s 50KL US bioreactor scale-up; Vimta’s food/pharma testing ramp.
- Outlook: Strong pipelines/deal momentum (Indegene/Syngene); FY26 guidance intact (Syngene revenue/EBITDA/PAT); 15-25% sector growth potential from US recovery, new modalities, M&A.
- Medium-Term: Diversified services (400+ clients for Syngene), AI/tech enablement, ESG edge for global contracts.
Key Risks
| Risk Category | Details | Impacted Companies |
|---|---|---|
| Financial/Operational | Margin erosion from costs/FX (staff +14%, FX losses); inventory/receivables write-offs; high R&D burn (Suven losses). | All (Syngene heavy) |
| Clinical/Regulatory | Trial delays/failures (Suven pipeline); audit/approval risks despite positives (Vimta WHO pass). | Suven, Syngene |
| Market/External | US biotech funding volatility; client concentration (global pharma/Biotechs). | Syngene, Indegene |
| Execution | Capex delays (Syngene US facility); integration risks from M&A (Indegene). | Syngene, Indegene |
| Macro | FX volatility, geopolitical/tariff issues; economic slowdowns affecting outsourcing. | All |
Summary Verdict: Moderate Growth with Resilience. Tailwinds from demand for advanced modalities/tech services outweigh headwinds, supporting 10-20% FY26 growth. Risks center on costs/FX and clinical outcomes—mitigated by strong balance sheets (Syngene net cash), guidance, and strategic investments. Selective outperformance: Testing/tech (Vimta/Indegene) > CDMO (Syngene) > Discovery (Suven). Monitor US funding and Q3 execution for upgrades.
Copyright © 2023 SAS Data Analytics Pvt. Ltd. All rights reserved.