SUZLON
Equity Metrics
September 24, 2026
Suzlon Energy Limited
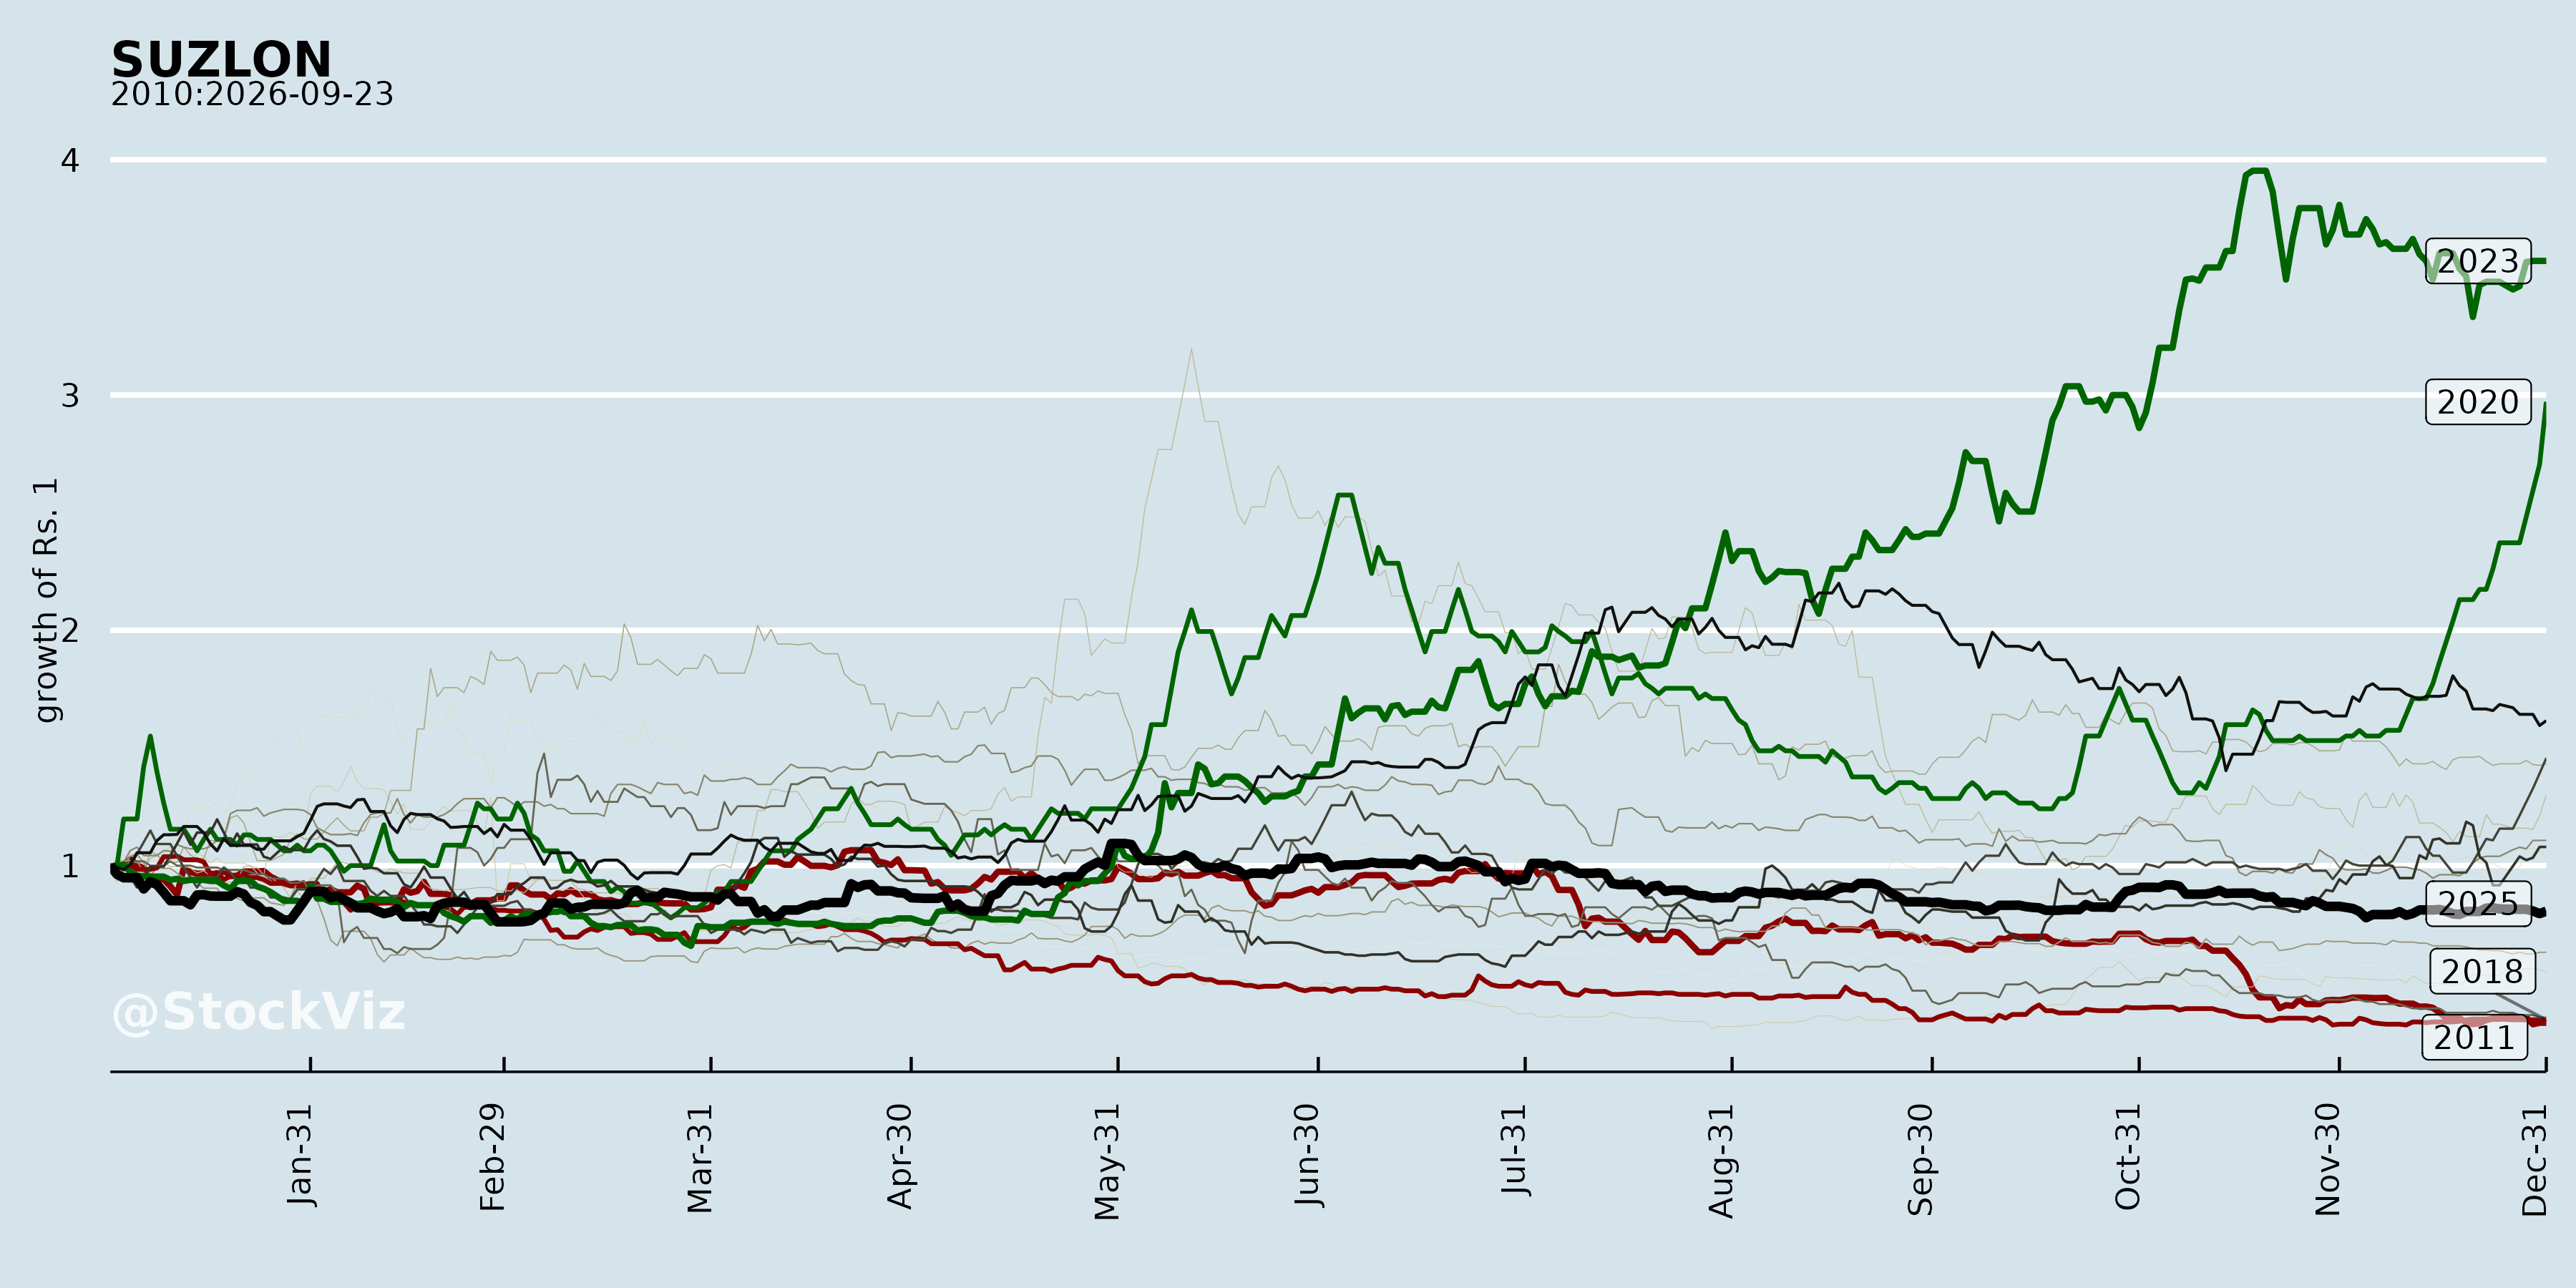
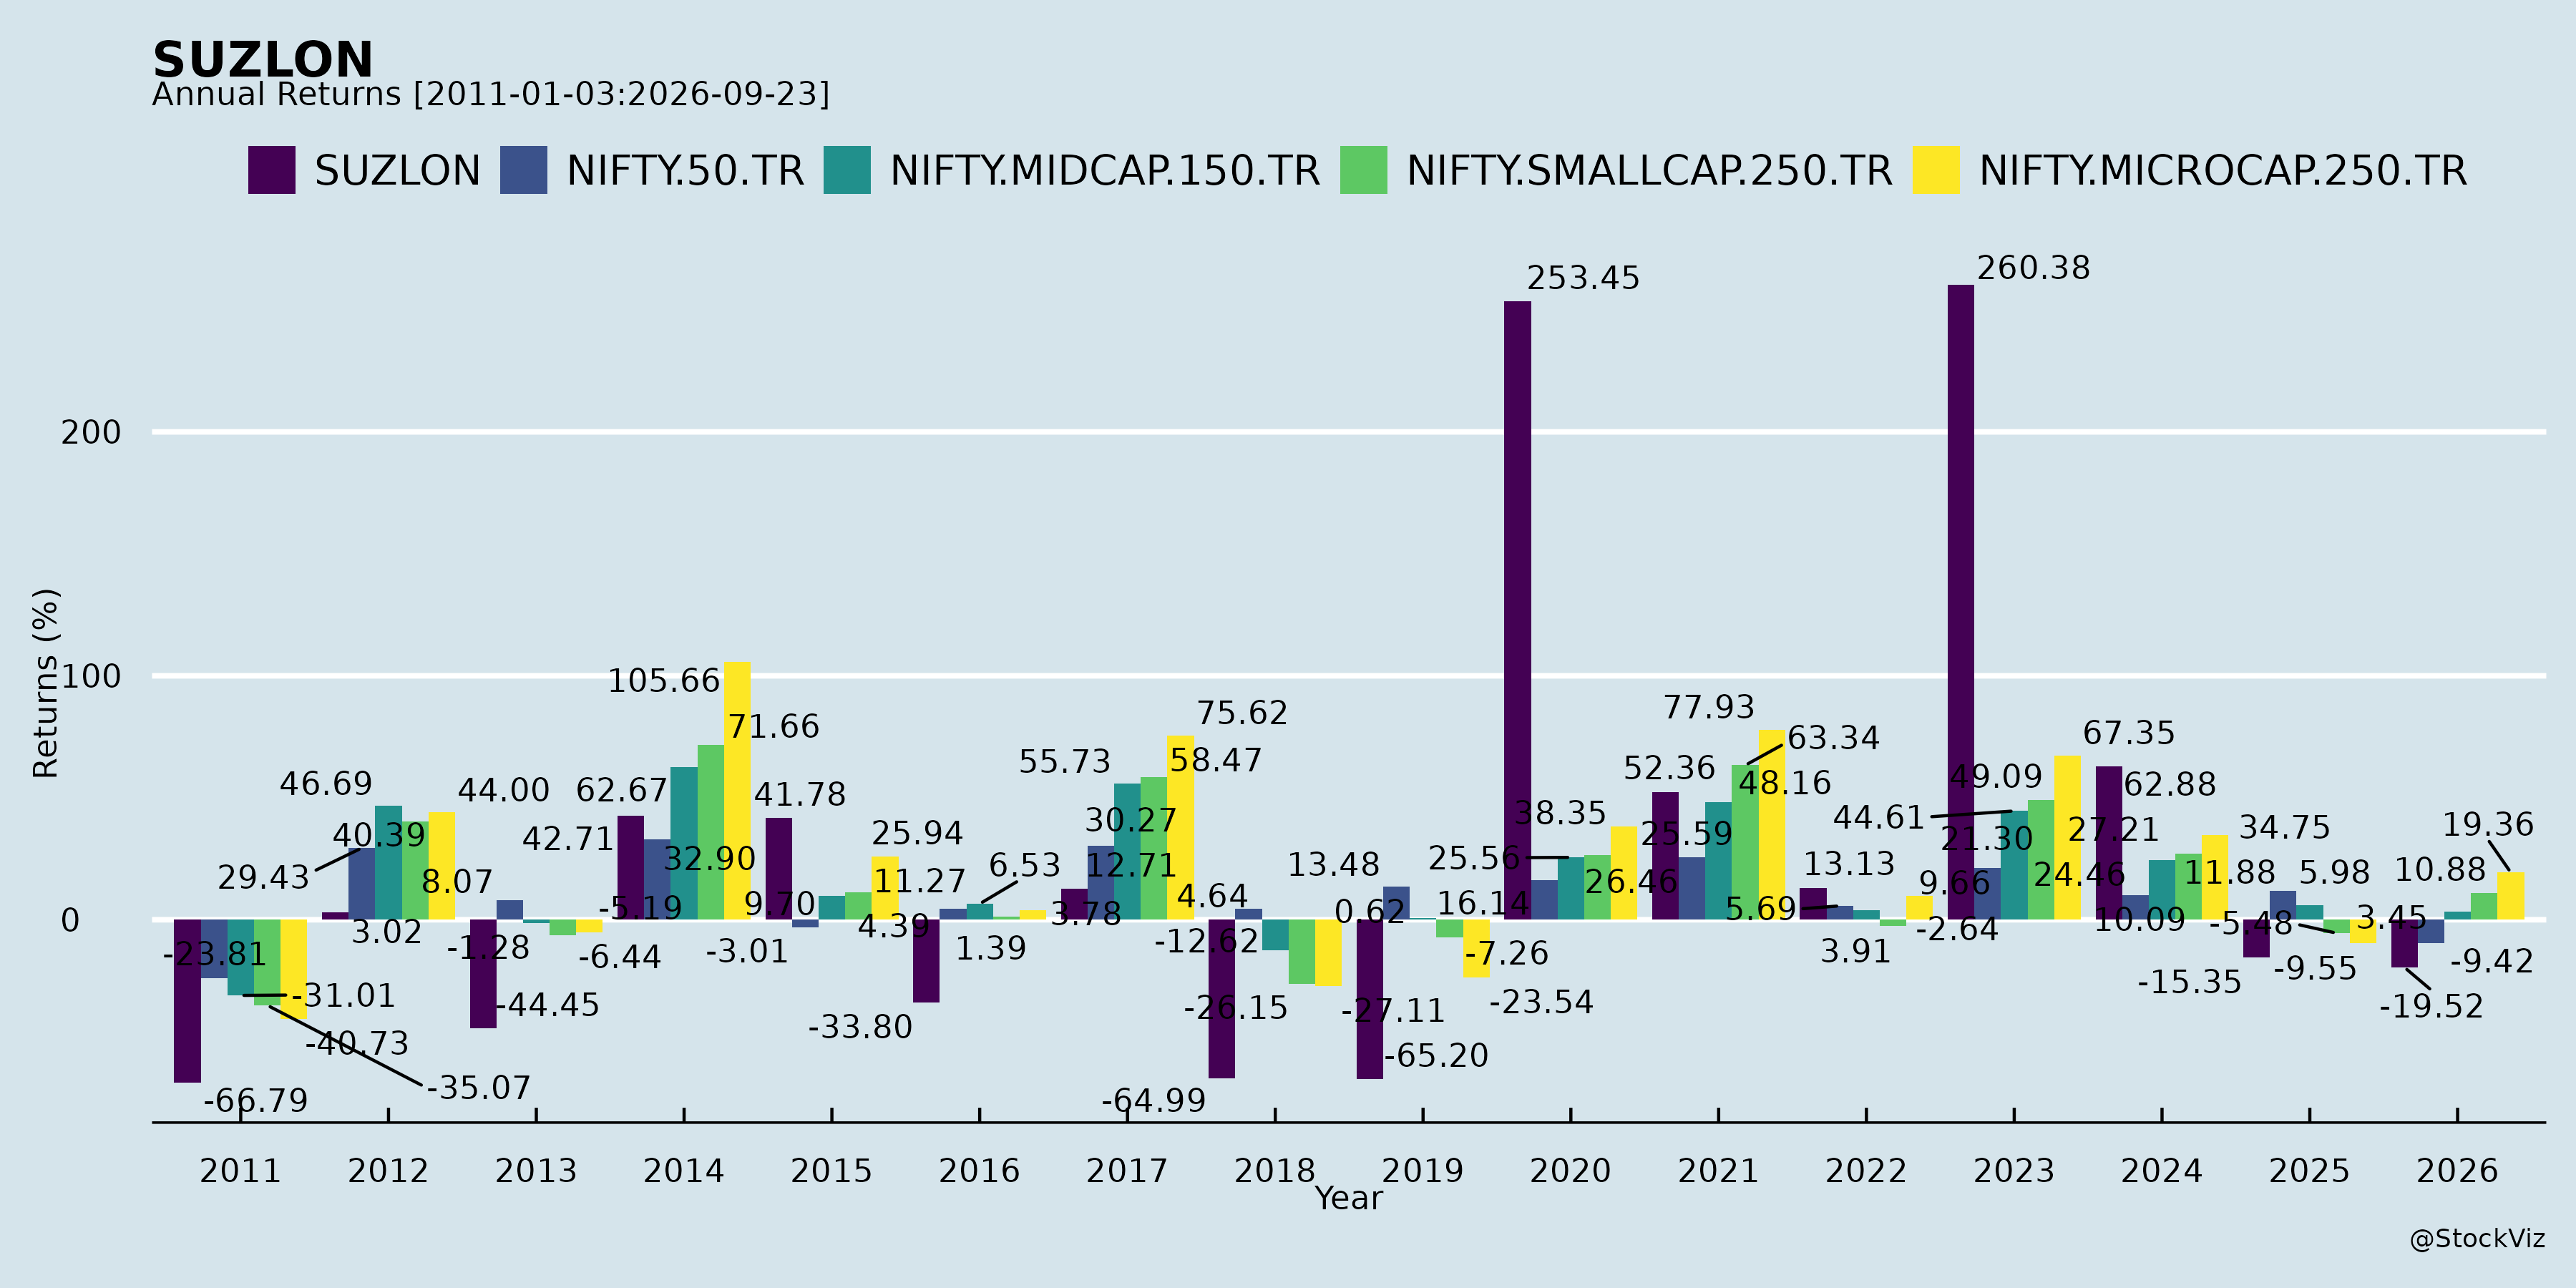
Annual Returns
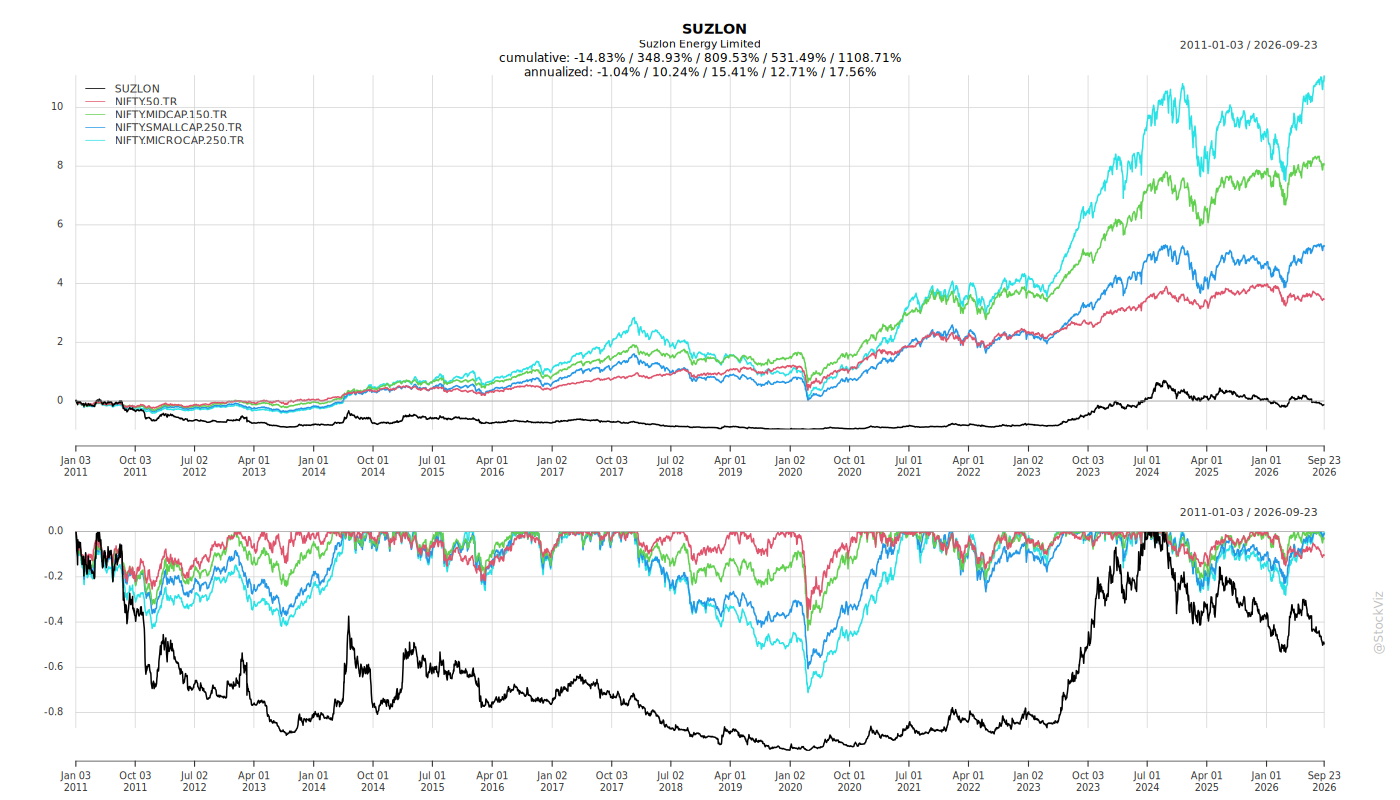
Cumulative Returns and Drawdowns
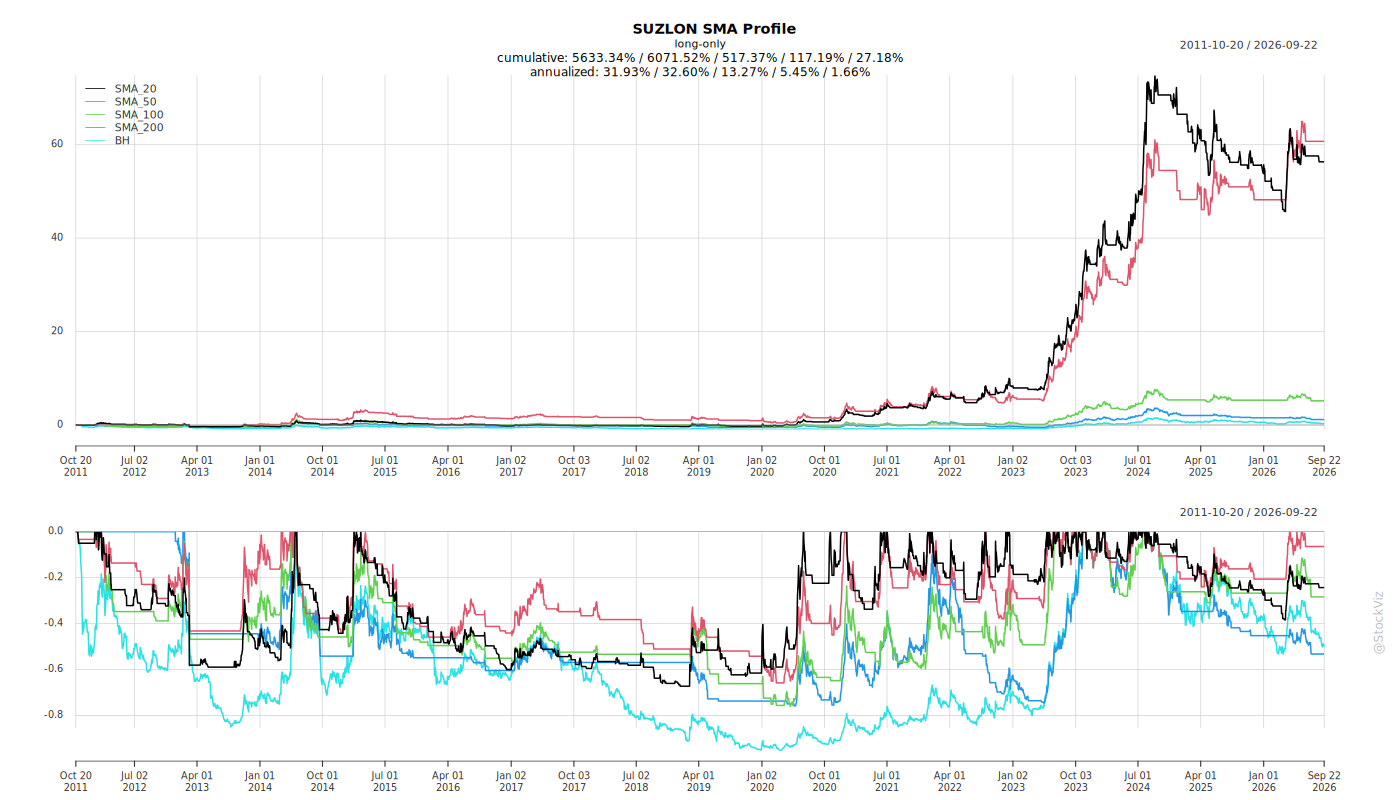
Fundamentals
Ownership
Margined
AI Summary
asof: 2026-09-16
Headwinds and Challenges
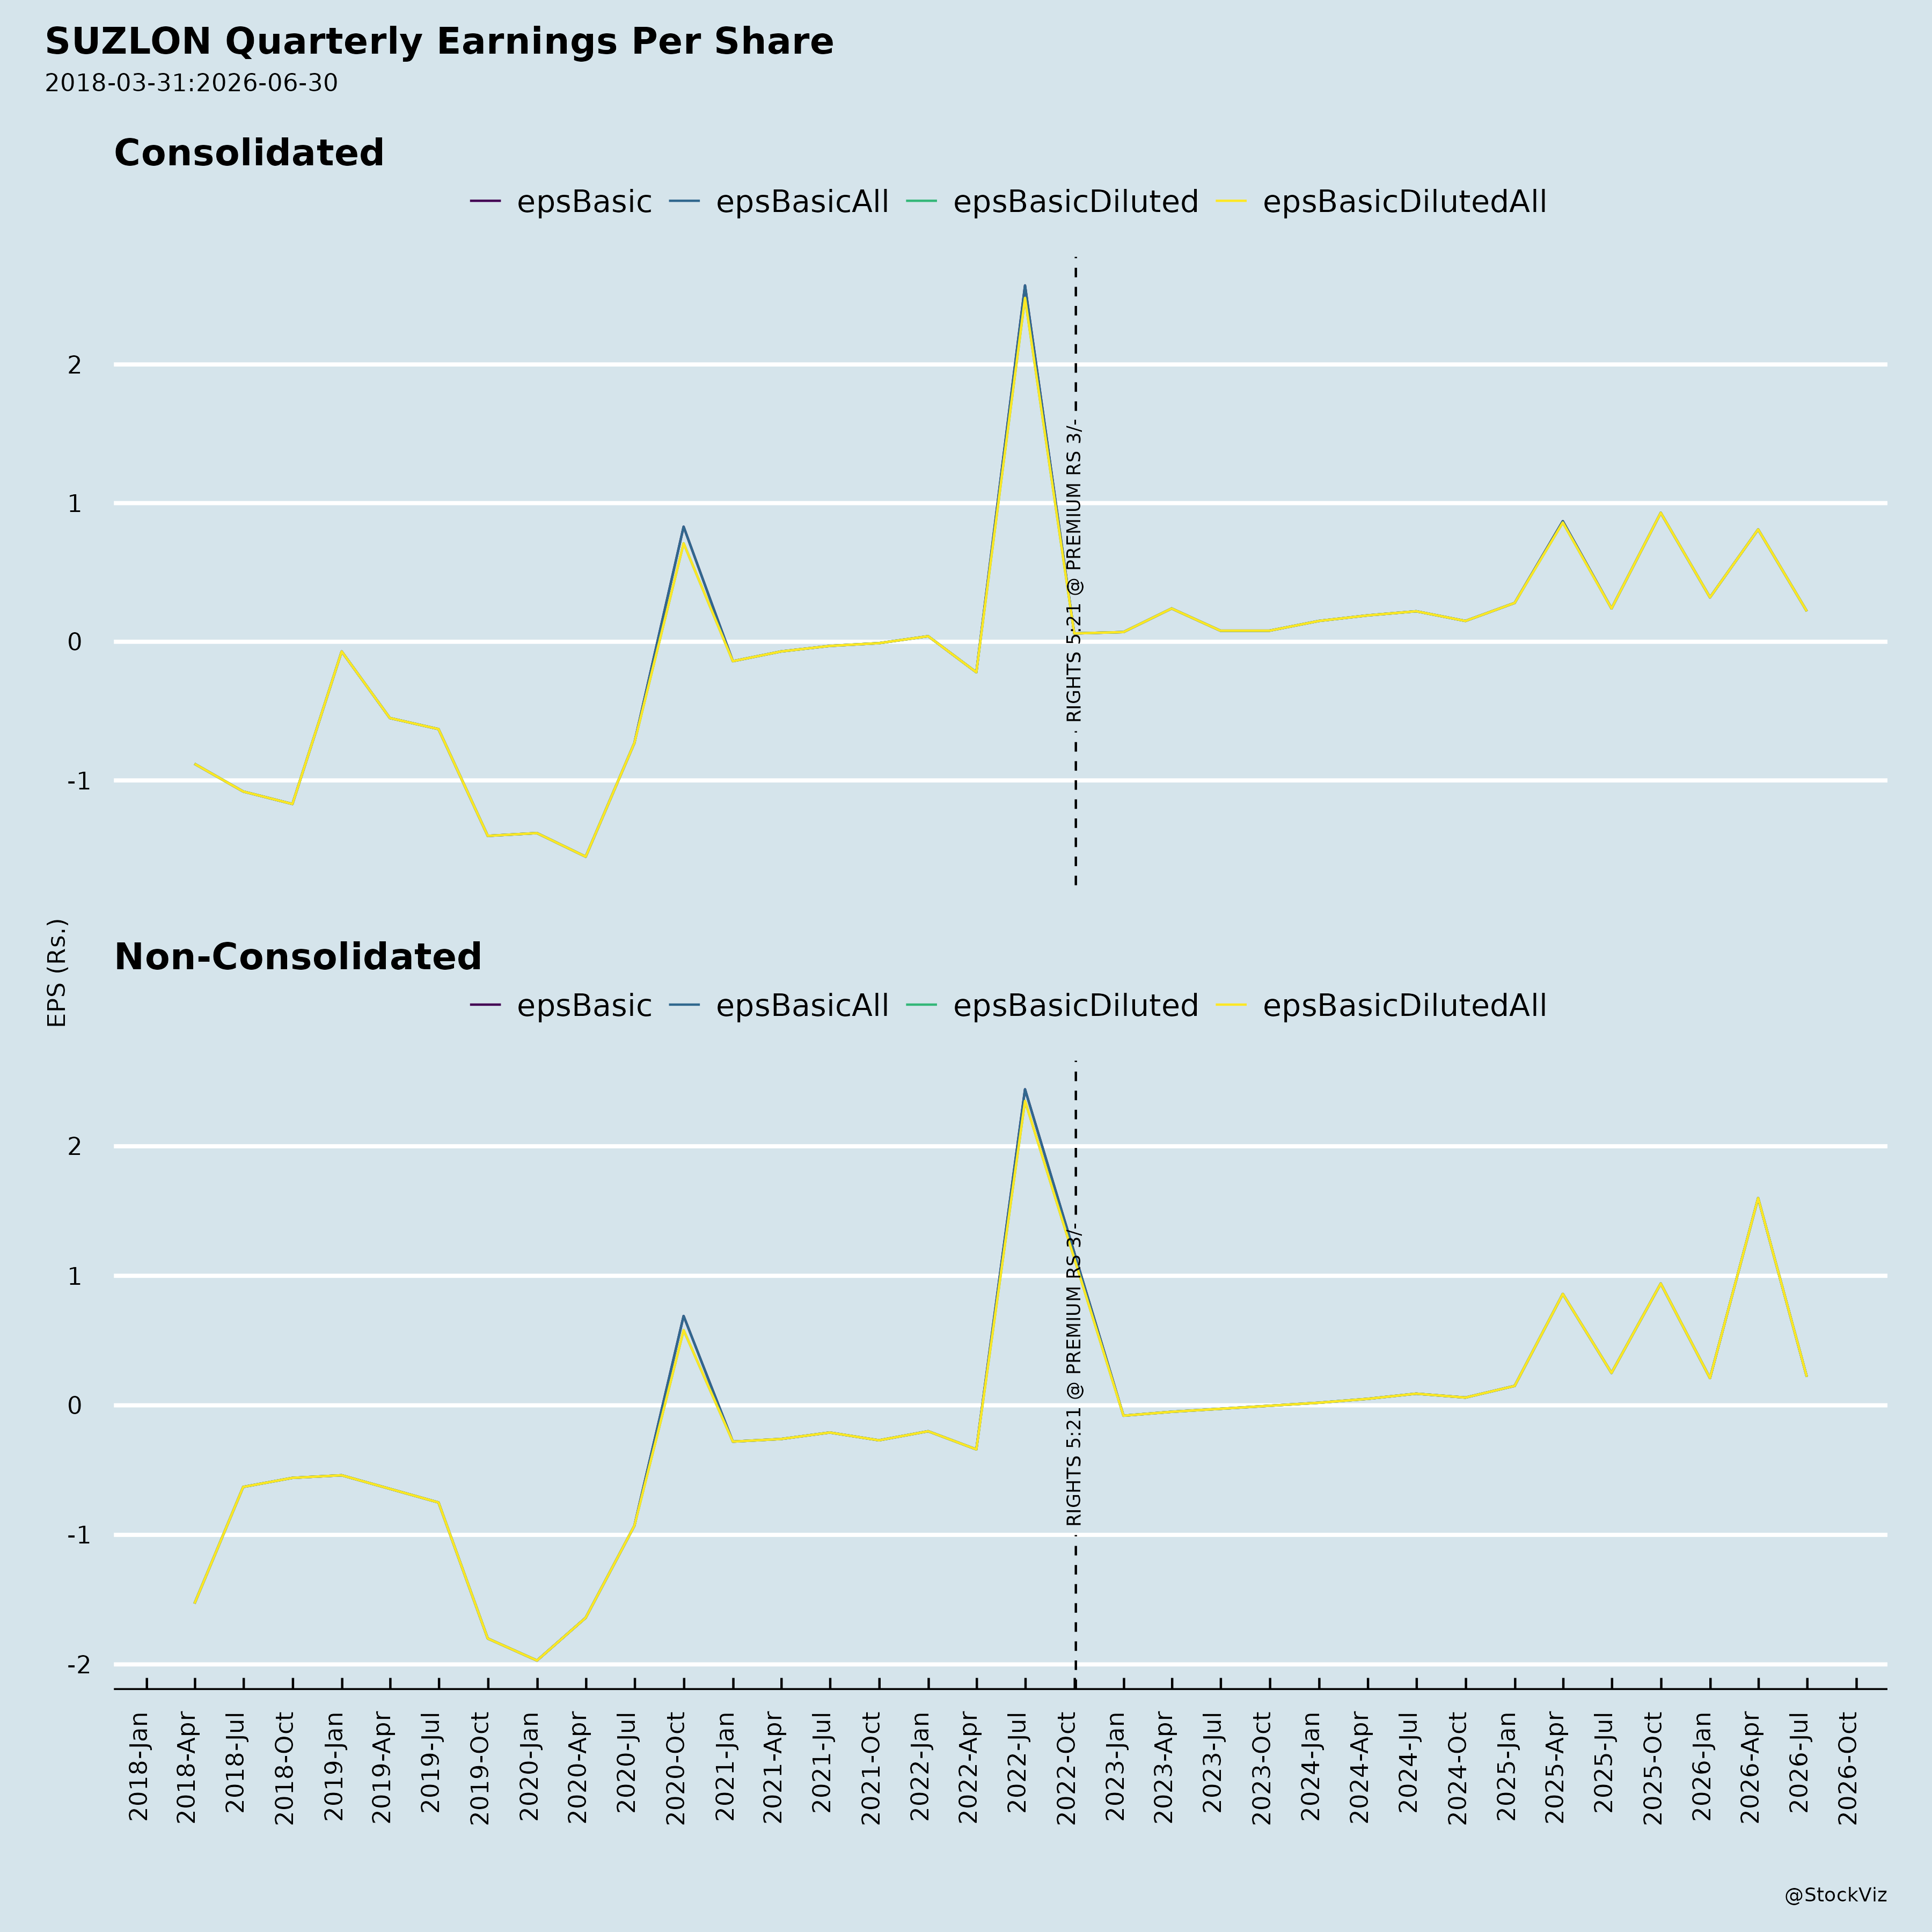
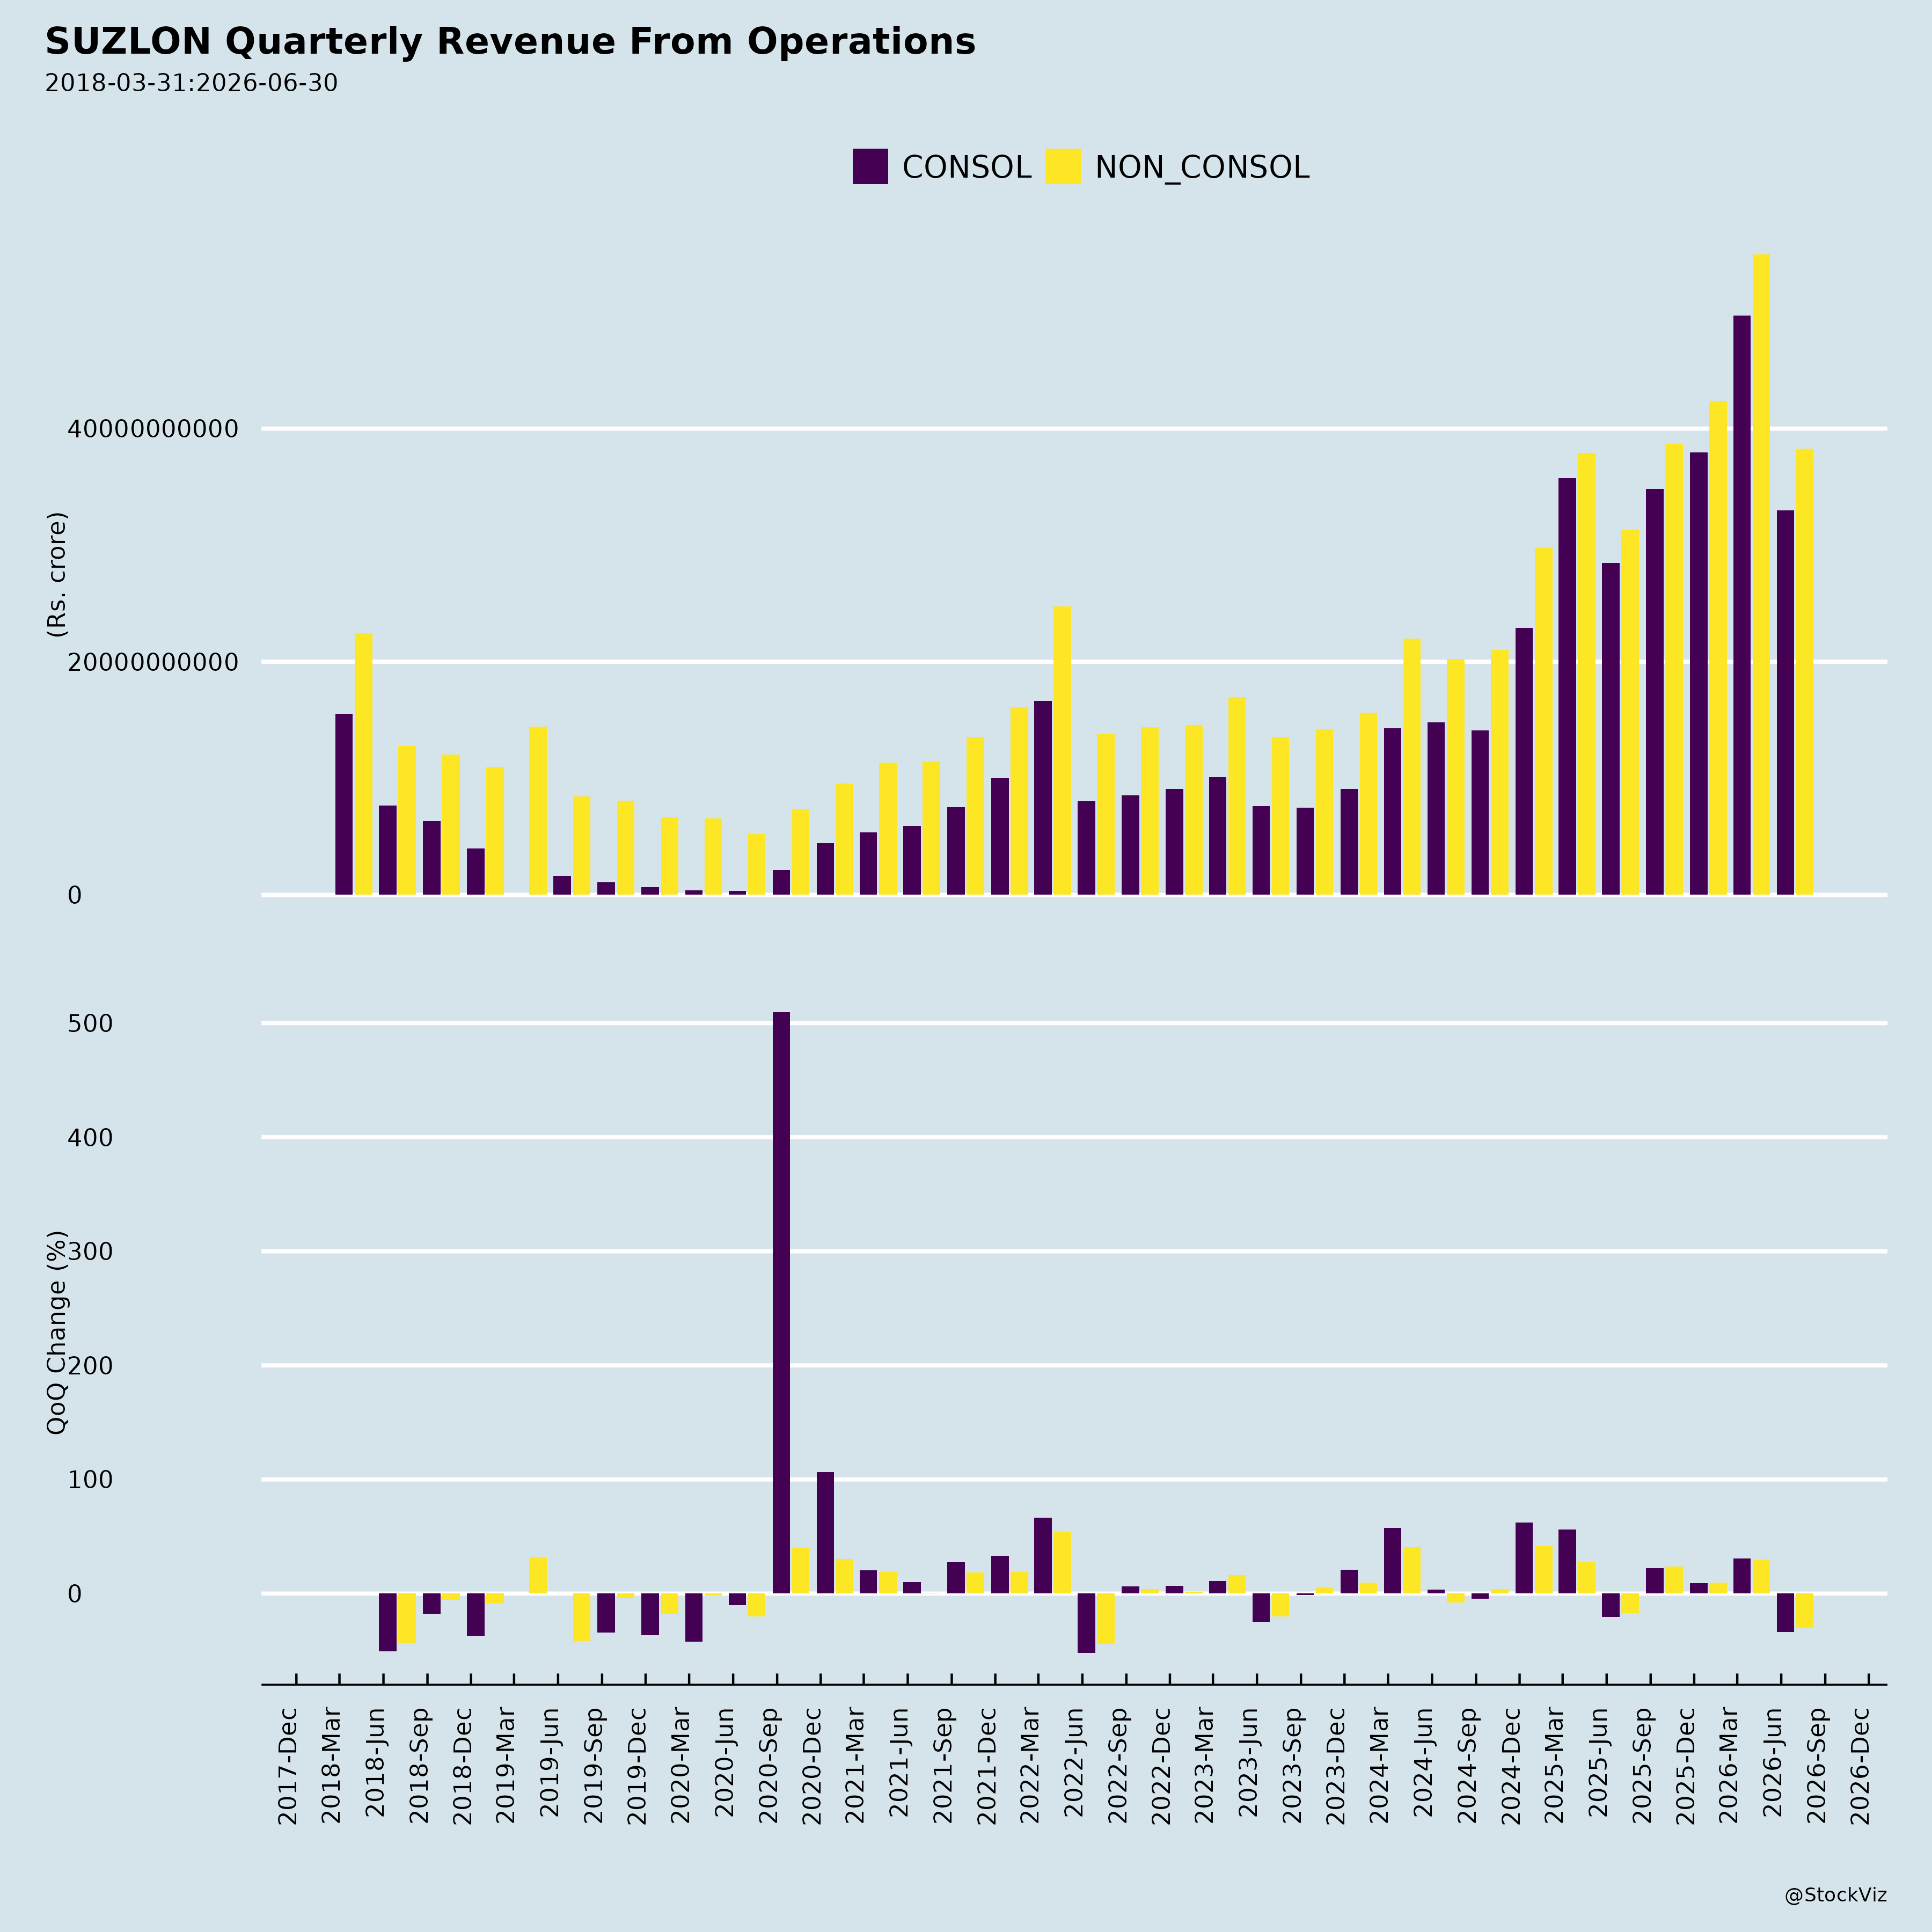
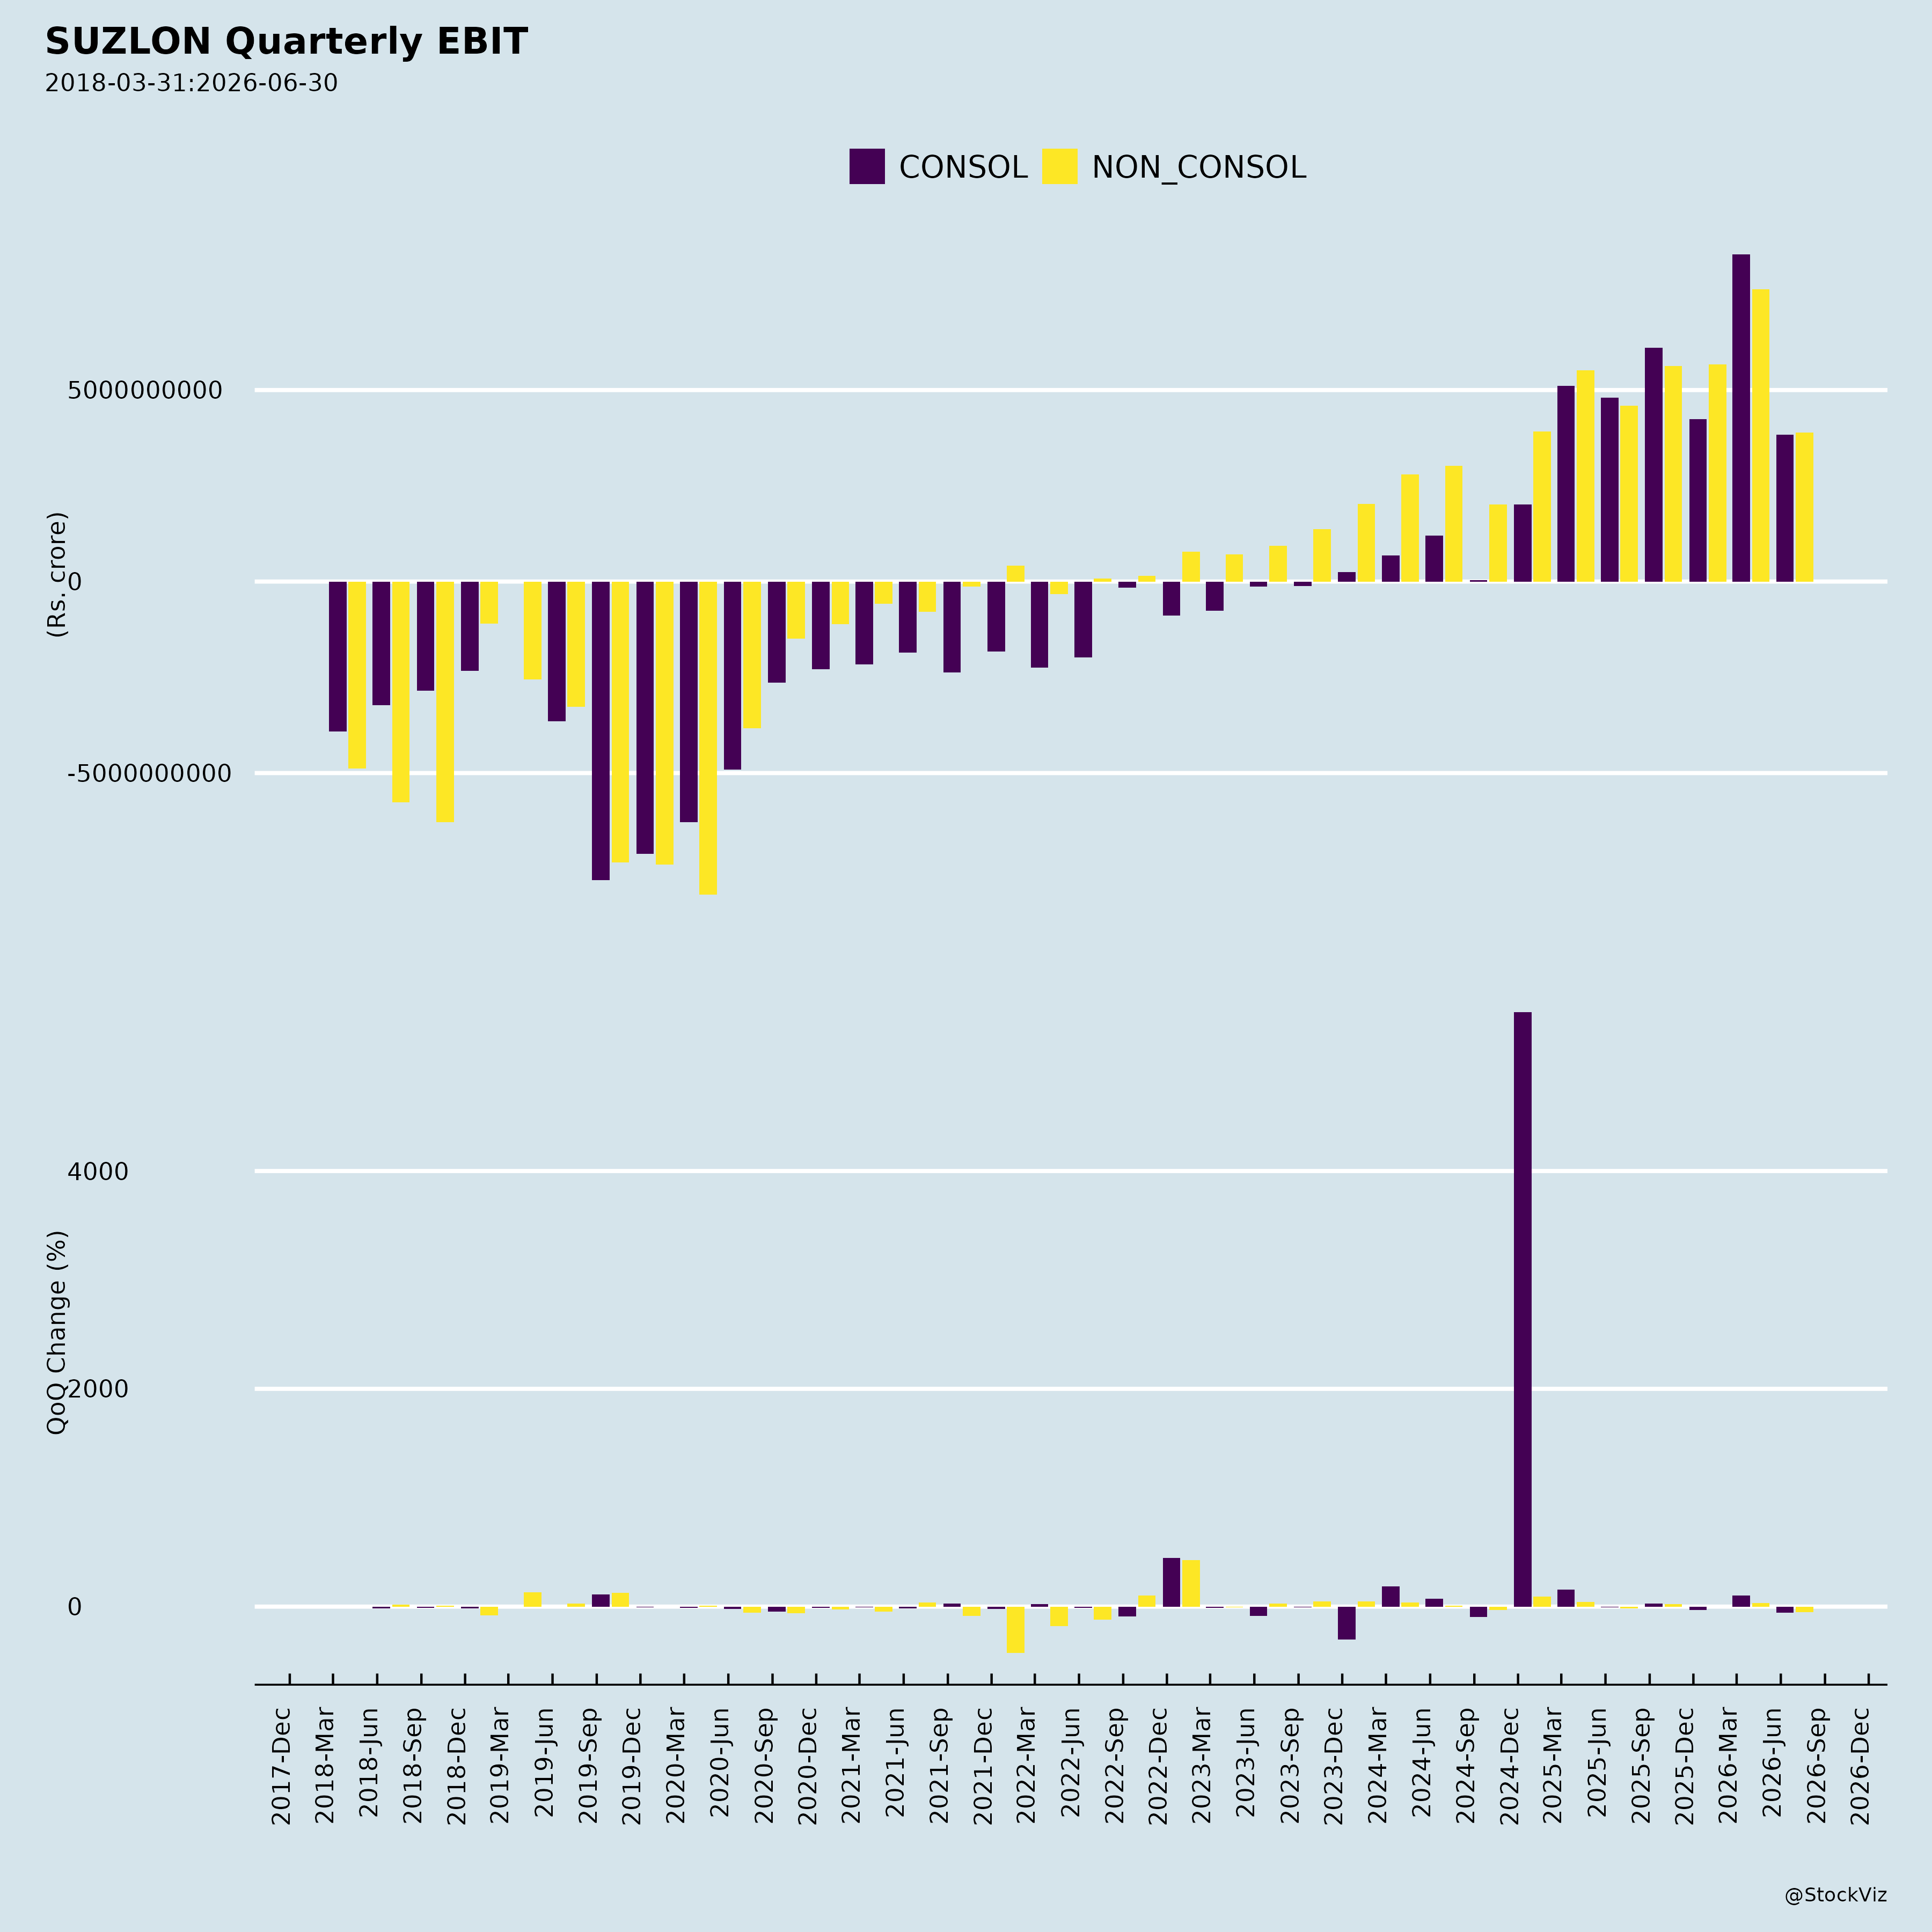
- Margin compression despite revenue growth. Q1 FY27 consolidated revenue rose 23% year-on-year to ₹3,819 crore, but EBITDA was broadly flat at ₹595 crore versus ₹599 crore in Q1 FY26, and the EBITDA margin fell to 15.6% from 19.2%. Net profit declined to ₹305 crore from ₹324 crore. The CFO attributed the margin outcome to temporary logistics disruptions arising from the geopolitical situation, certain strategic investments, and change of scope and segment mix.
- Cost pressures. Finance cost rose to ₹133.62 crore in Q1 FY27 from ₹103.07 crore a year earlier, and depreciation increased to ₹105.59 crore from ₹70.24 crore. Other expenses (net) rose to ₹362 crore from ₹241 crore. Contribution margin declined to 32.1% from 35.1% year-on-year, with the WTG contribution margin at 23.4% on account of scope mix.
- Regulatory/legal matter. SEBI, by order dated 29 May 2026, set aside an earlier adjudication order dated 27 June 2025 (which had been in the Company’s favour) concerning specified transactions with domestic subsidiaries and disclosure of contingent liabilities for FY 2013-14 to FY 2017-18, and imposed an aggregate penalty of ₹28.95 crore on the noticees, of which ₹15.95 crore is attributable to the Company. The Company filed an appeal before the Securities Appellate Tribunal on 13 July 2026 and, based on an external legal assessment, believes it has a strong case and that there is no material impact on the results.
- Global disruptions. The company described its performance as robust “despite global headwinds,” and cited temporary logistics disruptions from the geopolitical situation as a factor in margins.
Tailwinds and Growth Prospects
- Record operational momentum. Highest-ever Q1 deliveries of 506 MW (+14% YoY); commissioning of 269 MW (2.3x YoY); ~1 GW of new orders announced YTD FY27 from customers including Tata Power, Sunsure Energy and Waaree; cumulative order book of ~6.1 GW with 84% from PSU and C&I sectors. EPC share rose from 22% in Q1 FY26 to 32%.
- Suzlon 2.0 strategy. Four businesses launched — RE Tech, RE DevCo, RE Projects and RE AMS. Segment nomenclature was aligned accordingly: “Wind Turbine Generator” renamed “Renewable Energy Solutions” and “Operation & Maintenance Service” renamed “RE Asset Management Services,” with no change to segment composition or amounts previously reported.
- New products and capacity. The S175 (5 MW) platform was unveiled in India and Europe with a first order secured in India; the S144-3.x MW order book is building momentum. Rotor blade capacity at Jaisalmer was doubled from 630 MW to 1,260 MW with two additional lines, capable of both S144 and S175 blades. Domestic manufacturing capacity is stated at 4,500 MW, with three new smart blade factories under construction.
- International expansion. The Board approved setting up a wholly owned subsidiary in Singapore to augment the international wind energy and OMS business.
- Industry demand drivers cited. Energy security as the top transition driver; structural electricity super-cycle with India expected to have the fastest growth; global wind installations averaging 194 GW annually over the next five years; C&I potential of ~100 GW by 2030; repowering potential of ~25.4 GW (NIWE); onshore potential of 1,164 GW at 150m hub height; VGF scheme with ~₹7,500 crore outlay for 1 GW of offshore wind; wind on track to exceed 100 GW by 2030.
- Services annuity. RE AMS (India) has a 16+ GW installed base, 10,000+ turbines, USD 10+ billion assets under management, yearly O&M fee escalation of 4-5%, and a stable annuity cash flow model. Renom provides a multi-brand O&M platform.
- Order wins and state potential. Suzlon secured a maiden 200 MW order from Ayana Renewable Power for 64 S144 turbines (3.15 MW each) at Limbawas, Madhya Pradesh — its third DevCo-led wind order across Madhya Pradesh and Andhra Pradesh. The S144 surpassed 10 GW in cumulative orders. Madhya Pradesh has over 55 GW of wind potential at 150 metres.
- Balance sheet. Net worth rose to ₹9,869 crore at June 2026 from ₹9,464 crore at March 2026; net cash was ₹2,322 crore; the company cites strong cash balance and working capital lines to support growth.
Key Risks
- Margin pressure from logistics disruption, strategic investments, and scope/segment mix, as flagged by the CFO.
- The SEBI penalty and appeal outcome, with ₹15.95 crore attributable to the Company, though management believes there is no material impact.
- Rising finance costs and depreciation as the business scales.
- Dependence on order execution and conversion, including the 1.2 GW NTPC project in Gujarat and DevCo-led EPC orders.
- Exposure to global supply chain and geopolitical disruption, partially mitigated by >80% local sourcing from Indian Tier-1 suppliers for S120 and S144 turbines.
Management Guidance Versus Observed Performance
- Management characterised the quarter as a strong start to FY27 with disciplined execution, and stated the company is “well-prepared to meet future demand” following the S175 launch and scaled Bhuj manufacturing. Observed performance supports the volume narrative: record Q1 deliveries of 506 MW and commissioning of 269 MW.
- On margins, management stated EBITDA and PAT margins were “in line with ongoing developments,” citing temporary logistics disruptions, strategic investments, and change of scope and segment mix. Observed performance shows EBITDA margin at 15.6% versus 19.2% a year earlier and PAT of ₹305 crore versus ₹324 crore, indicating margin pressure alongside revenue growth.
- Management highlighted a robust pipeline providing “strong growth visibility” and a fortified balance sheet with adequate working capital limits to cater to a large order book. Observed indicators include a ~6.1 GW order book, ~1 GW of orders announced YTD FY27, net cash of ₹2,322 crore, and net worth of ₹9,869 crore.
- Management expressed that it looks forward to delivering long-term value and contributing to India’s clean energy transition, and noted Madhya Pradesh is well positioned to drive the next phase of India’s wind energy growth.
Key Facts for Investors
- Q1 FY27 results were approved by the Board on 28 July 2026; the Audit Committee reviewed them and statutory auditors (Walker Chandiok & Co LLP) conducted a limited review.
- The Thirty First Annual General Meeting was held on 11 September 2026 via VC/OAVM. Three ordinary resolutions were passed with the requisite majority: adoption of financial statements for 2025-26, re-appointment of Mr. Vinod R. Tanti as Director, and approval of Cost Auditors’ remuneration for FY 2026-27. The Register of Members and Share Transfer Books were closed from 5 September 2026 to 11 September 2026.
- The Board approved setting up a wholly owned subsidiary in Singapore for augmenting international wind energy and OMS business.
- ESOP 2022 allotments occurred during the quarter across Grants 1-5 at prices of ₹5, ₹24, ₹30, ₹40 and ₹45 per share, on 13 April, 13 May, 3 June, 20 June and 9 July 2026. Paid-up equity share capital rose to ₹2,750.61 crore at 30 June 2026 from ₹2,744.99 crore at 31 March 2026.
- Exceptional items: consolidated gain from settlement of contractual matter of ₹70.00 crore in Q4 FY26; standalone exceptional items in Q4 FY26 included reversal of impairment provision on subsidiaries (₹694.42 crore) and extinguishment/reversal of financial liabilities, financial assets and impairment allowance (₹546.00 crore).
- The consolidated statement includes 32 subsidiaries whose interim results were not reviewed by their auditors, reflecting total revenues of ₹10.38 crore, net profit after tax of ₹1.21 crore and total comprehensive income of ₹1.21 crore for the quarter; management stated these are not material to the Group.
- Company representatives will attend an Analysts/Investors’ Conference organised by Anand Rathi on 22 September 2026 in physical mode, where only the Company’s IR presentation available on the company and stock exchange websites will be discussed, with no unpublished price sensitive information shared.
- ESG recognitions cited include being the only Indian company in the S&P Global Sustainability Yearbook 2026, Platinum-Level Zero Waste to Landfill and Single-Use Plastic-Free certifications across all 12 assessed manufacturing facilities, ISO 20400:2017 Sustainable Procurement Certification, an ‘Excellent’ ESG rating from ESGRisk.ai, and inclusion in the Emerging ESG Index and FTSE Emerging ESG Low Carbon Select Index.
- Anjali Byce joined as Group Chief Human Resource Officer; the company recorded appreciation for Rajendra Mehta’s contributions over almost four years.
- FY26 revenue was USD 1.75+ billion and market capitalisation USD 8.0+ billion as of 30 June 2026; ~22+ GW of wind capacity installed across 17 countries; 28% cumulative market share in India; 8,600+ workforce.
Broker Narrative
Brokers kept a Buy stance from first to last report, but the narrative shifted from macro/policy recovery and balance-sheet repair to operational execution and margin delivery. Early optimism about policy reversals, deleveraging, and the order-book/market-position advantage largely carried through—order book grew to ~6.1GW and O&M margins improved—while the original debt, reverse-auction, and land/transmission risks receded from the story. The later reports instead focus on Suzlon 2.0 costs, unfavorable EPC mix, DevCo working capital, logistics disruptions, and delayed international scaling, with the post-2024 disappointment streak showing these execution/margin risks dominated the outcome.
Broker Timeline
26 broker calls · 2023-06-29 to 2026-07-29
Copyright © 2023 SAS Data Analytics Pvt. Ltd. All rights reserved.