SUNTV
Equity Metrics
September 24, 2026
Sun TV Network Limited
TV Broadcasting & Software Production
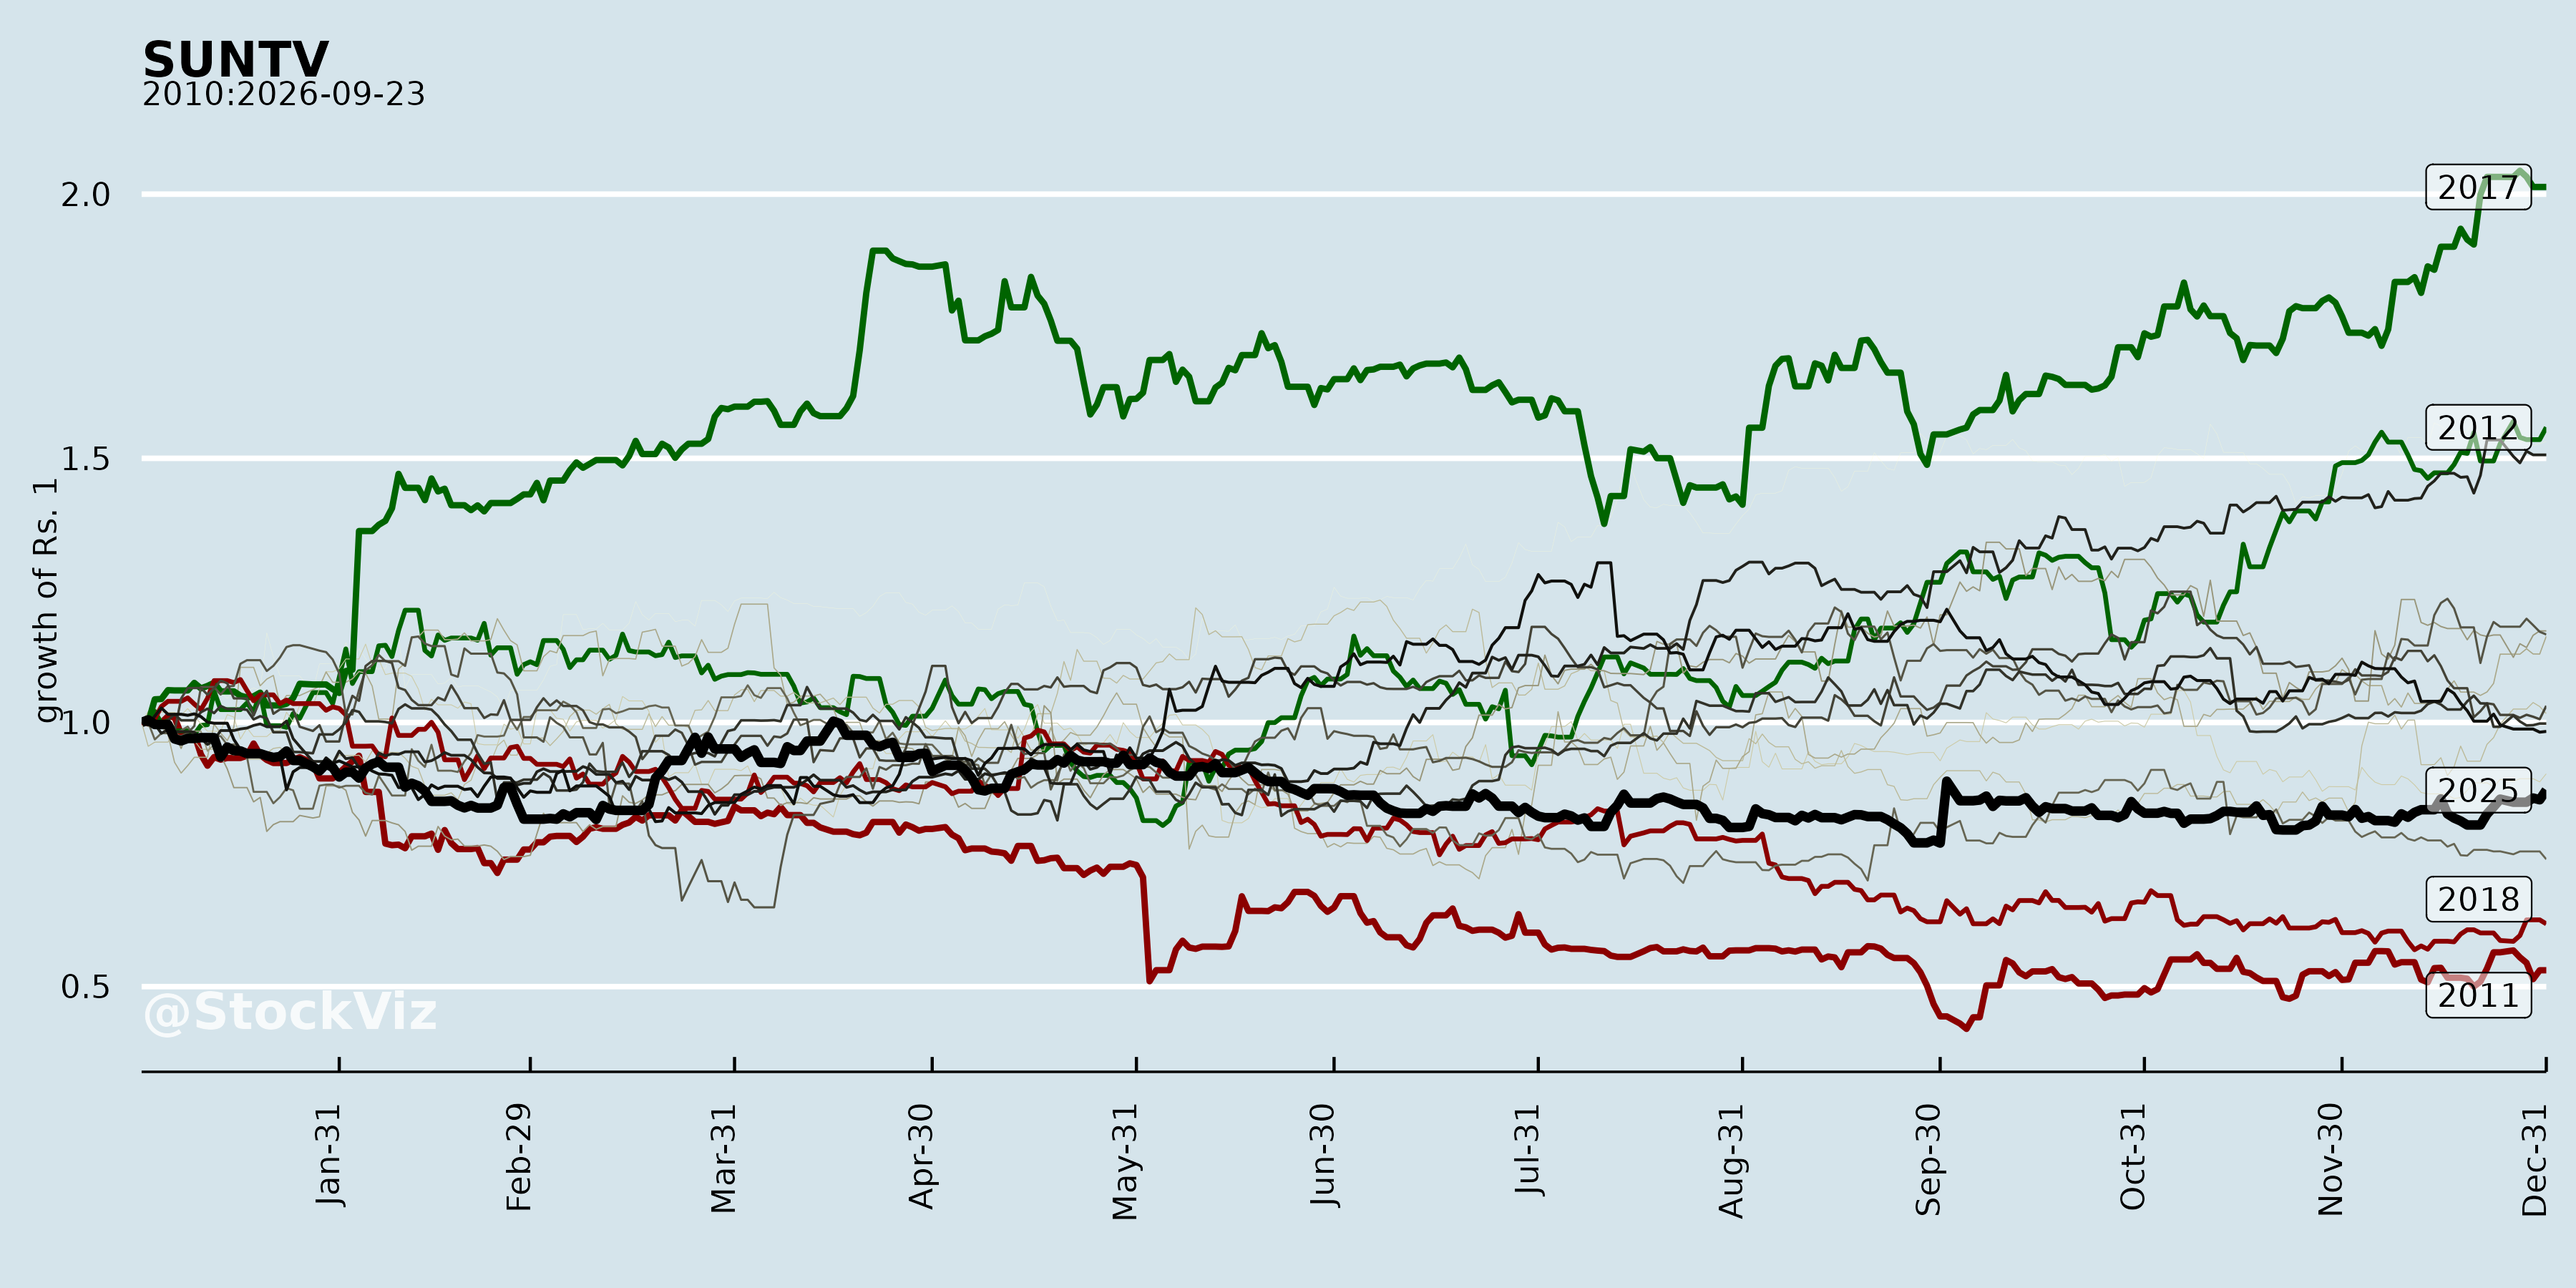
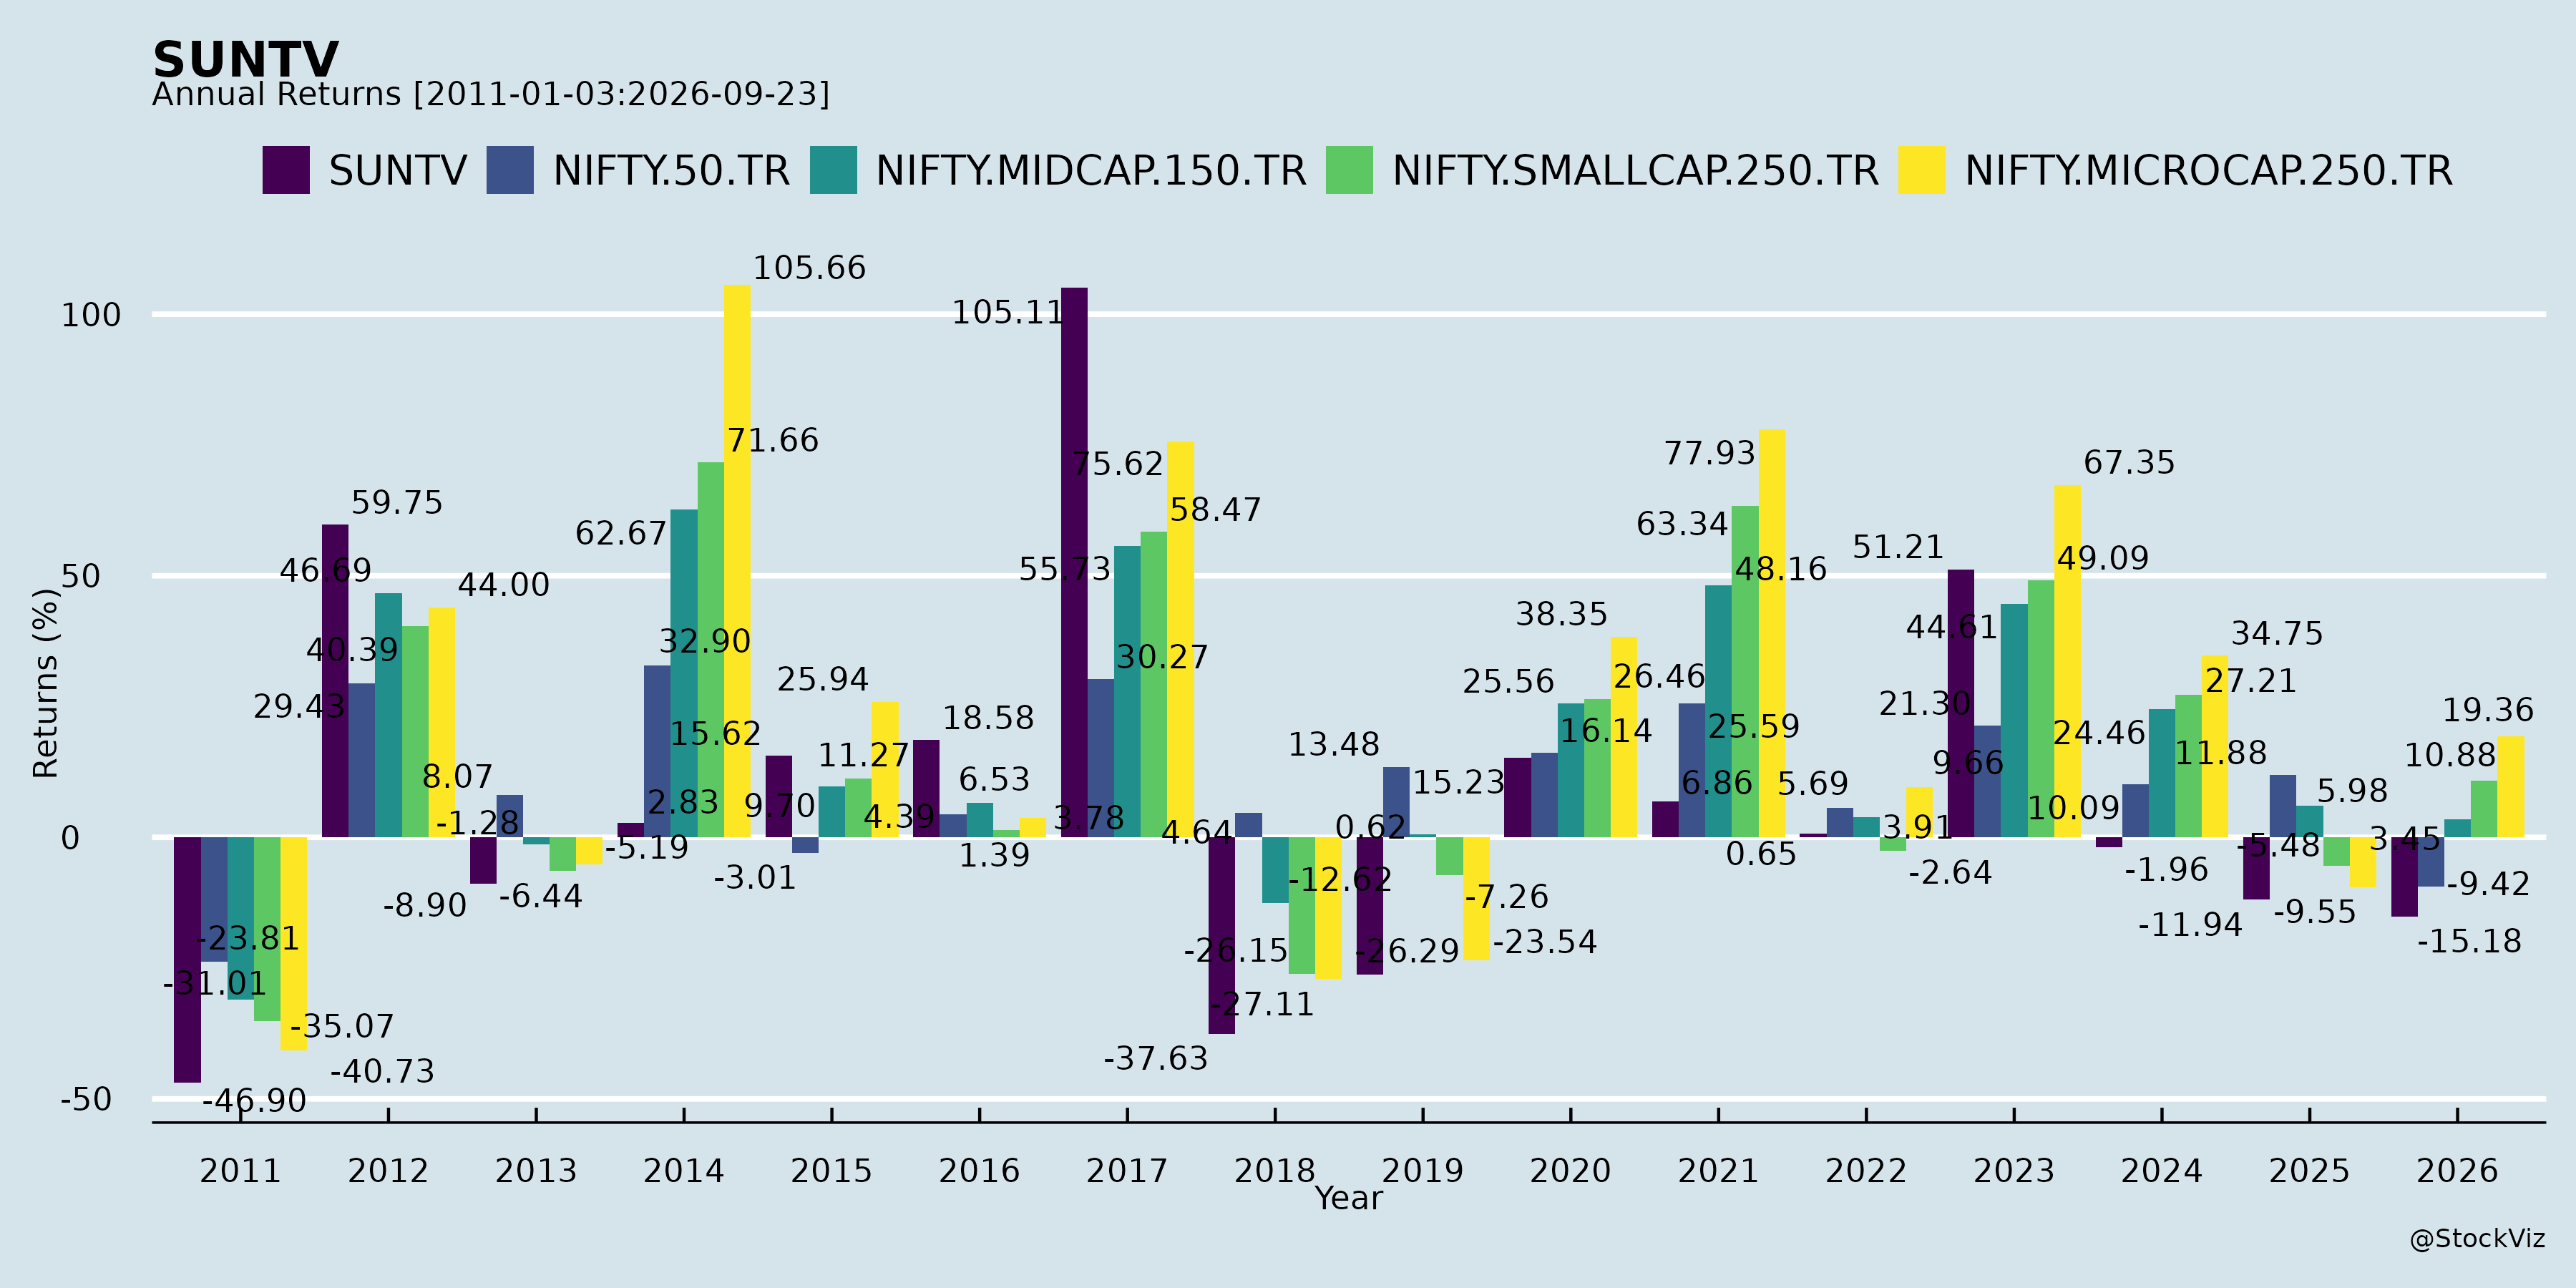
Annual Returns
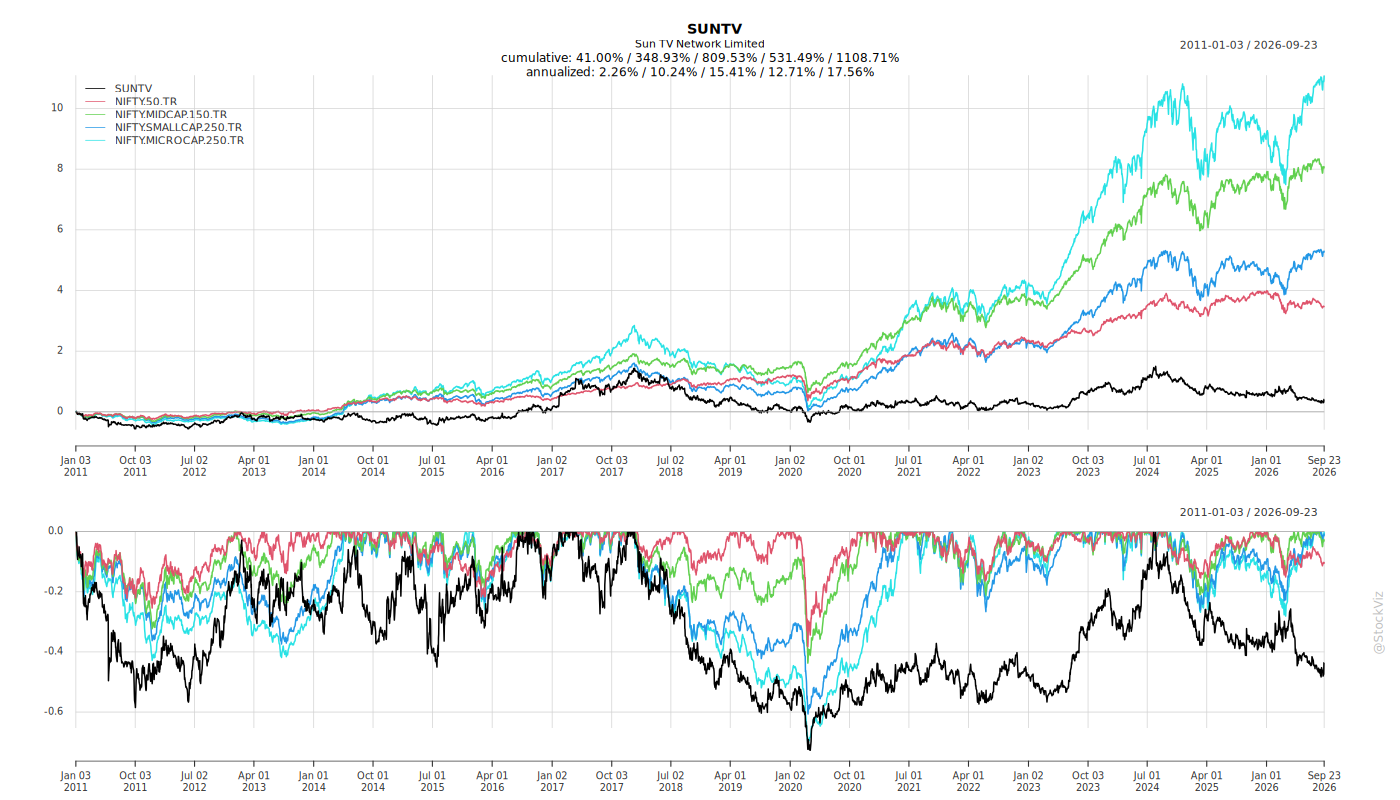
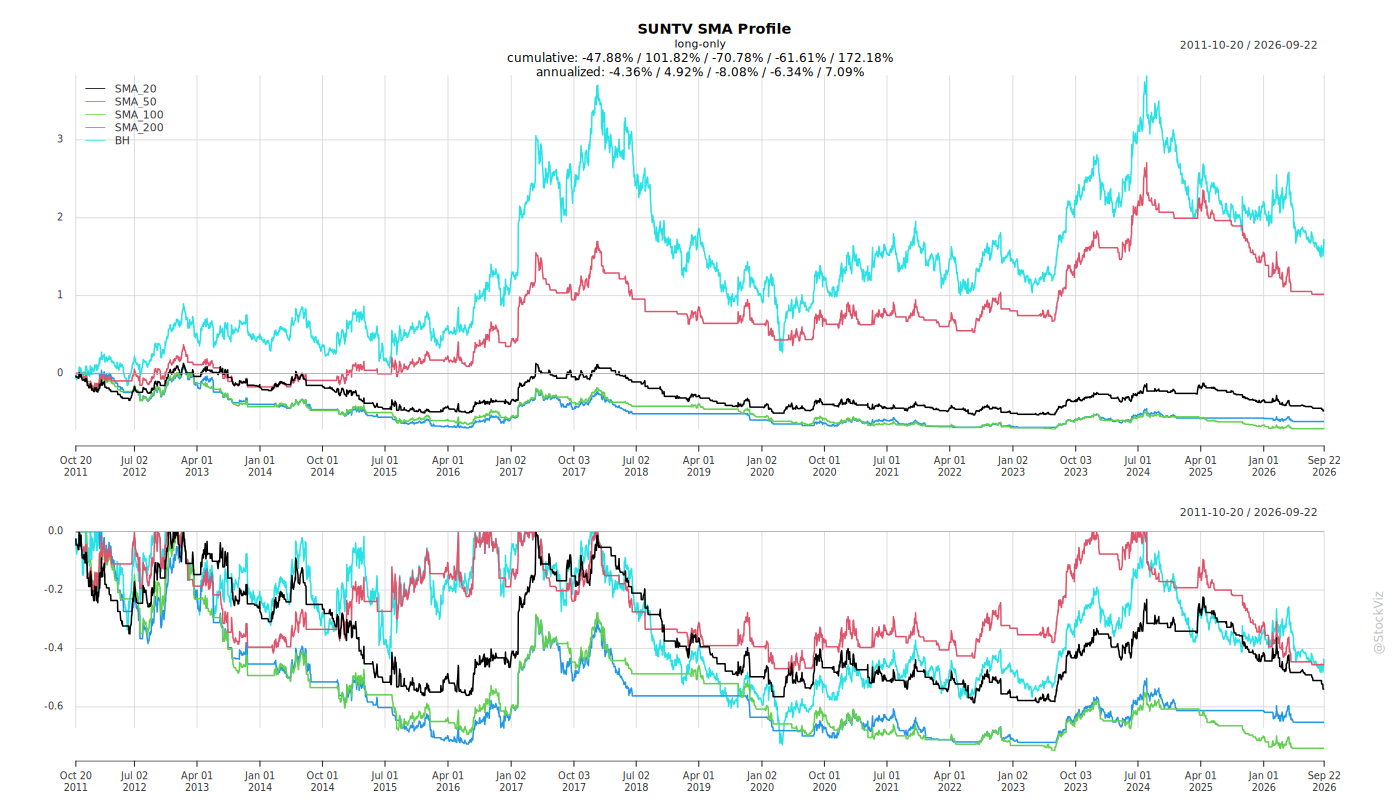
Cumulative Returns and Drawdowns
Fundamentals
Ownership
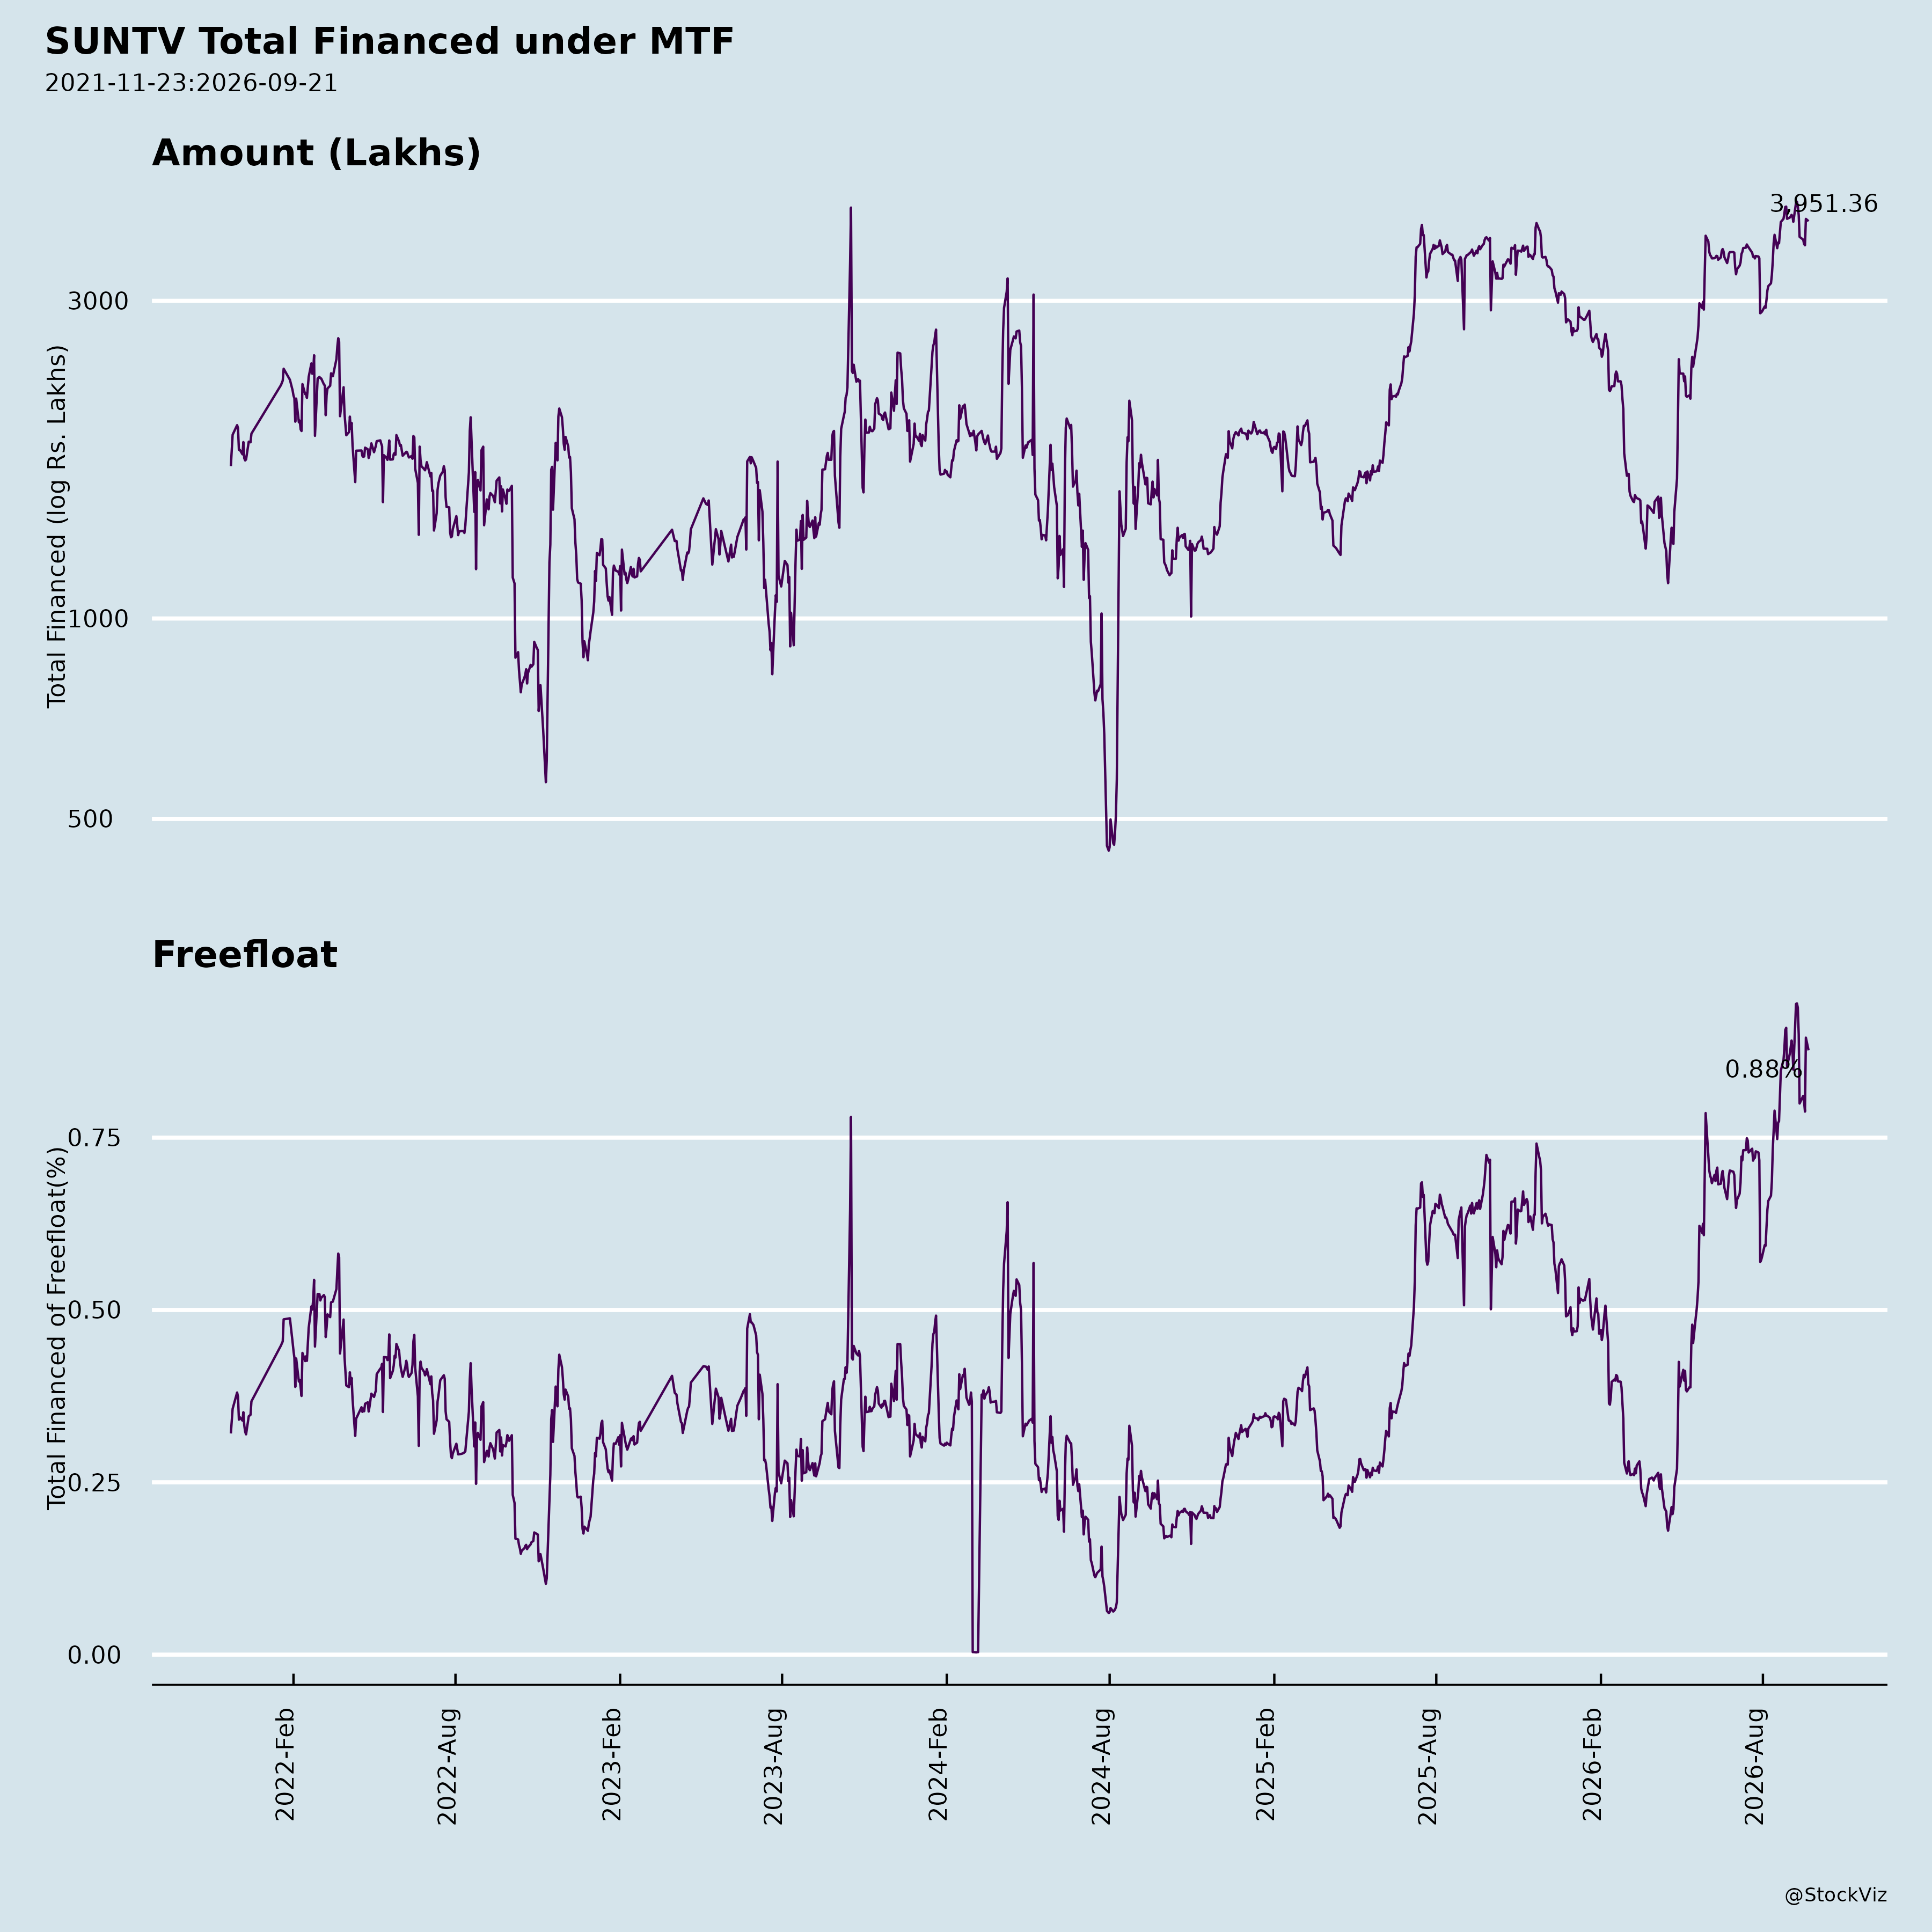
Margined
AI Summary
asof: 2026-09-16
Sun TV Network — Recent Corporate Announcements: Analysis
1. Headwinds and Challenges
- Advertising revenue softness. Advertisement revenues for the quarter ended June 30, 2026 were Rs. 282.51 crores, lower than Rs. 289.94 crores in the corresponding quarter ended June 30, 2025. Sequentially, they were only marginally higher (~2%) than Rs. 276.45 crores in the quarter ended March 31, 2026.
- Intense competition from traditional broadcasters, OTT platforms and digital-first content providers.
- Content piracy and unauthorized distribution.
- Evolving regulations, cybersecurity threats, and rapid technological disruption.
- Rising costs for premium content acquisition, sports broadcasting rights, and creative talent.
- Revenue concentration risk — dependence on subscription and advertising revenues, which are exposed to competitive intensity, economic conditions, and shifts in advertising spending patterns.
- Leadership transition. Mr. C Praveen, Chief Operating Officer, retired with effect from the close of business hours on August 31, 2026.
- Exceptional items in prior periods. Exceptional items for the quarter and year ended March 31, 2026 related to a provision for impairment of the Company’s investment in a Joint Venture and the incremental impact from implementation of the Labour Codes.
2. Tailwinds and Growth Prospects
- Digital adoption and connectivity. Increasing digital adoption, changing consumer preferences, and continuous technological advancements; growing internet penetration, smartphone usage, and affordable data services are expanding digital content consumption across urban and rural markets.
- Connected TV and streaming. Increasing popularity of Connected TVs, OTT platforms, and mobile streaming.
- Regional language content is seeing strong growth.
- Advertising shift to digital platforms.
- Cricket franchise expansion. The addition of the international cricket franchise business (SunRisers Leeds) broadens the portfolio. The Group now owns three cricket franchises — SunRisers Hyderabad (IPL), SunRisers Eastern Cape (Cricket South Africa T20 League), and SunRisers Leeds Limited (The Hundred, UK).
- Cricket franchise income growth. Income from the Company’s cricket franchises for the quarter ended June 30, 2026 was Rs. 629.83 crores, up from Rs. 473.03 crores in the quarter ended June 30, 2025.
- Domestic subscription growth. Domestic subscription revenues rose ~3% year-on-year to Rs. 485.46 crores (from Rs. 470.12 crores) and ~3% sequentially (from Rs. 472.47 crores).
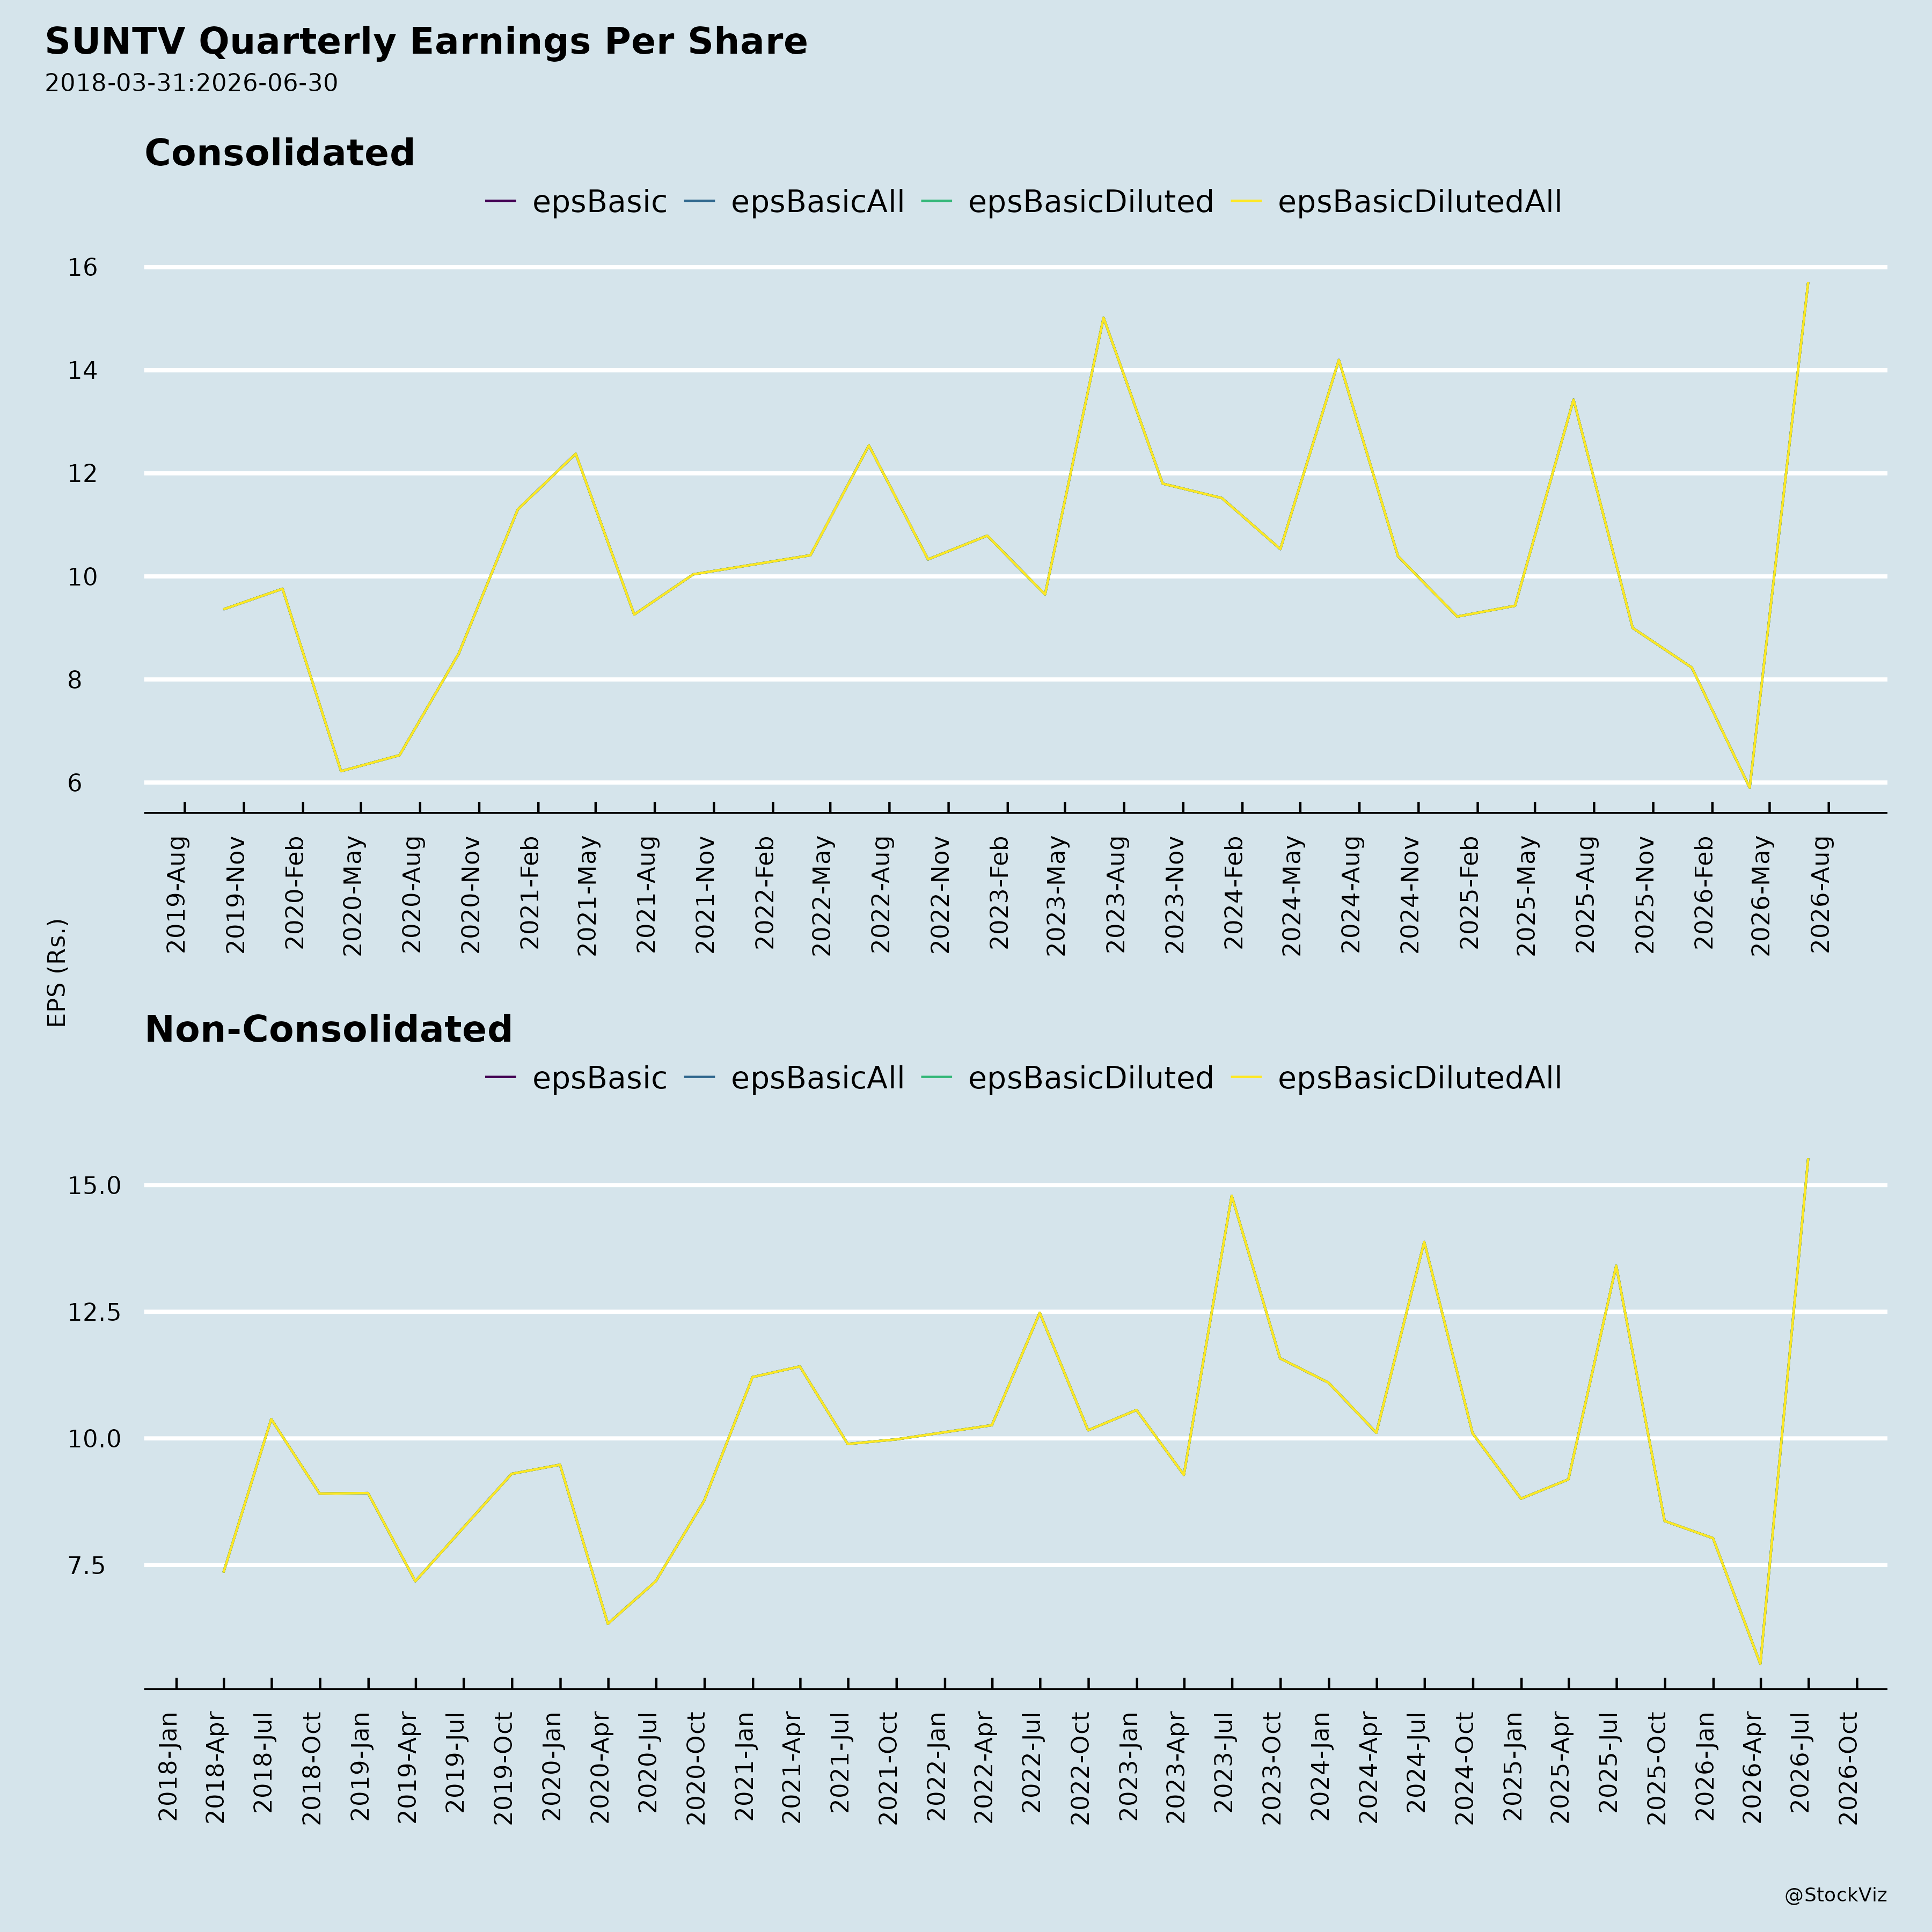
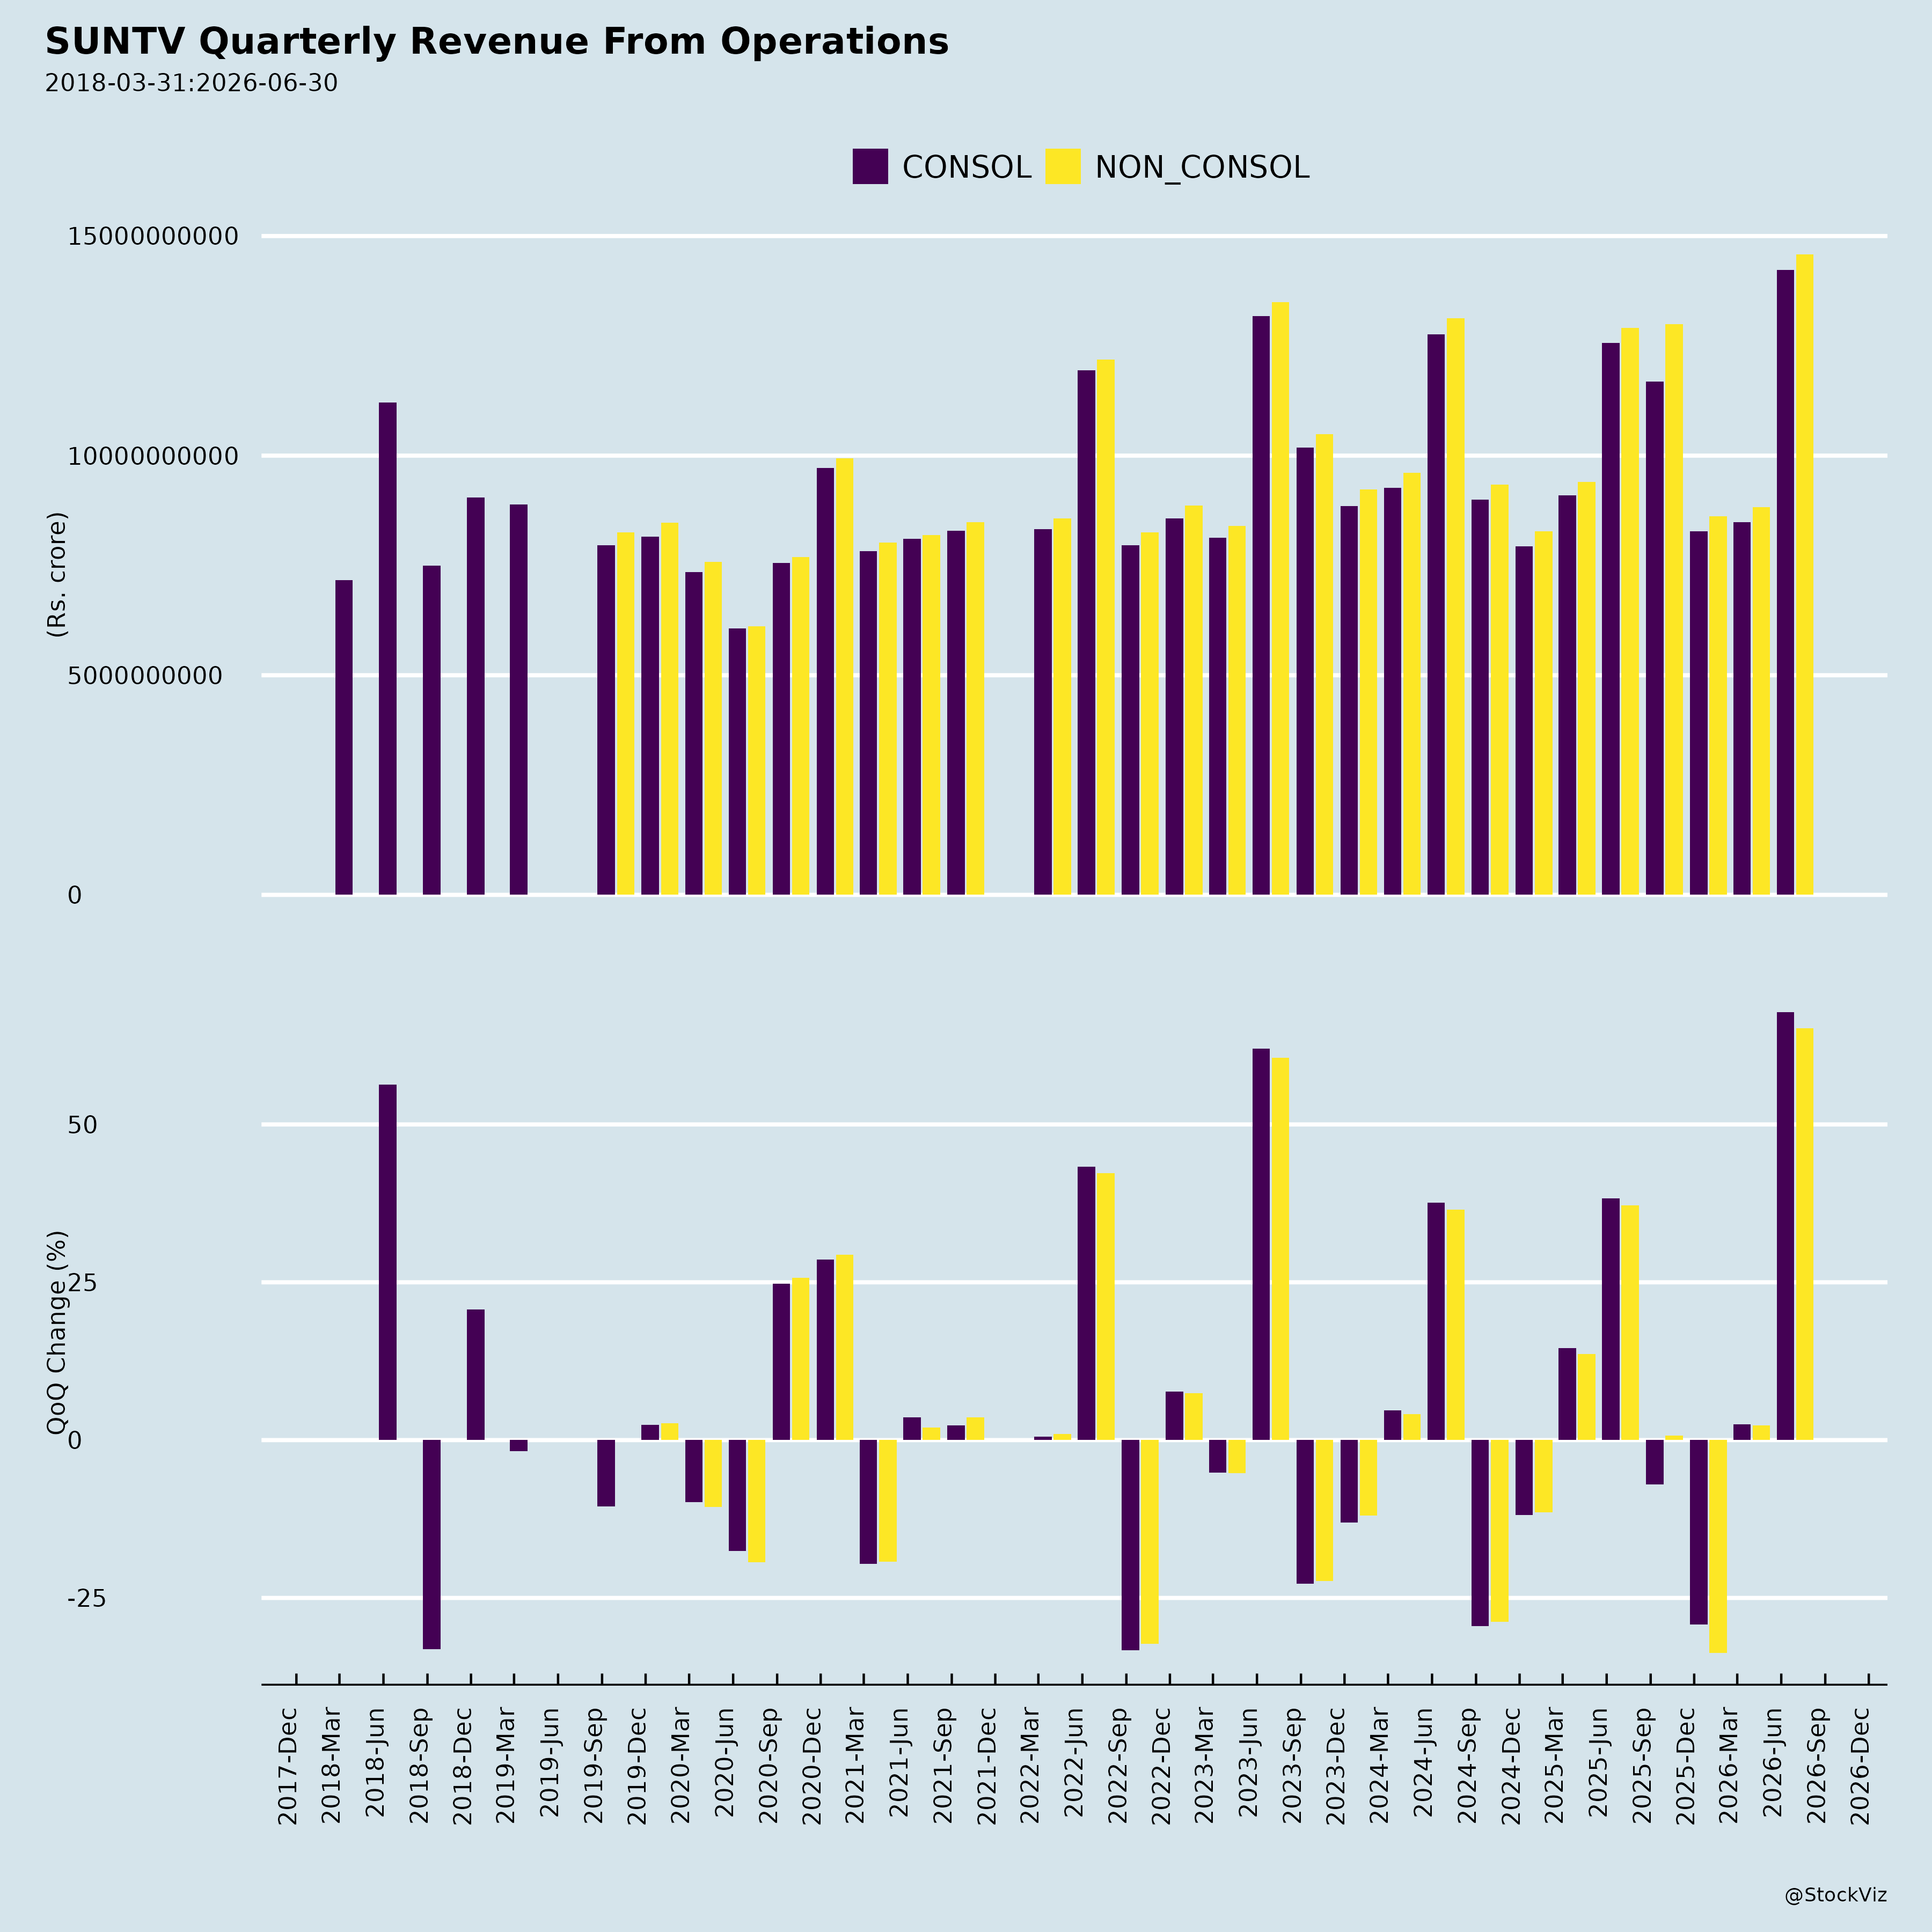
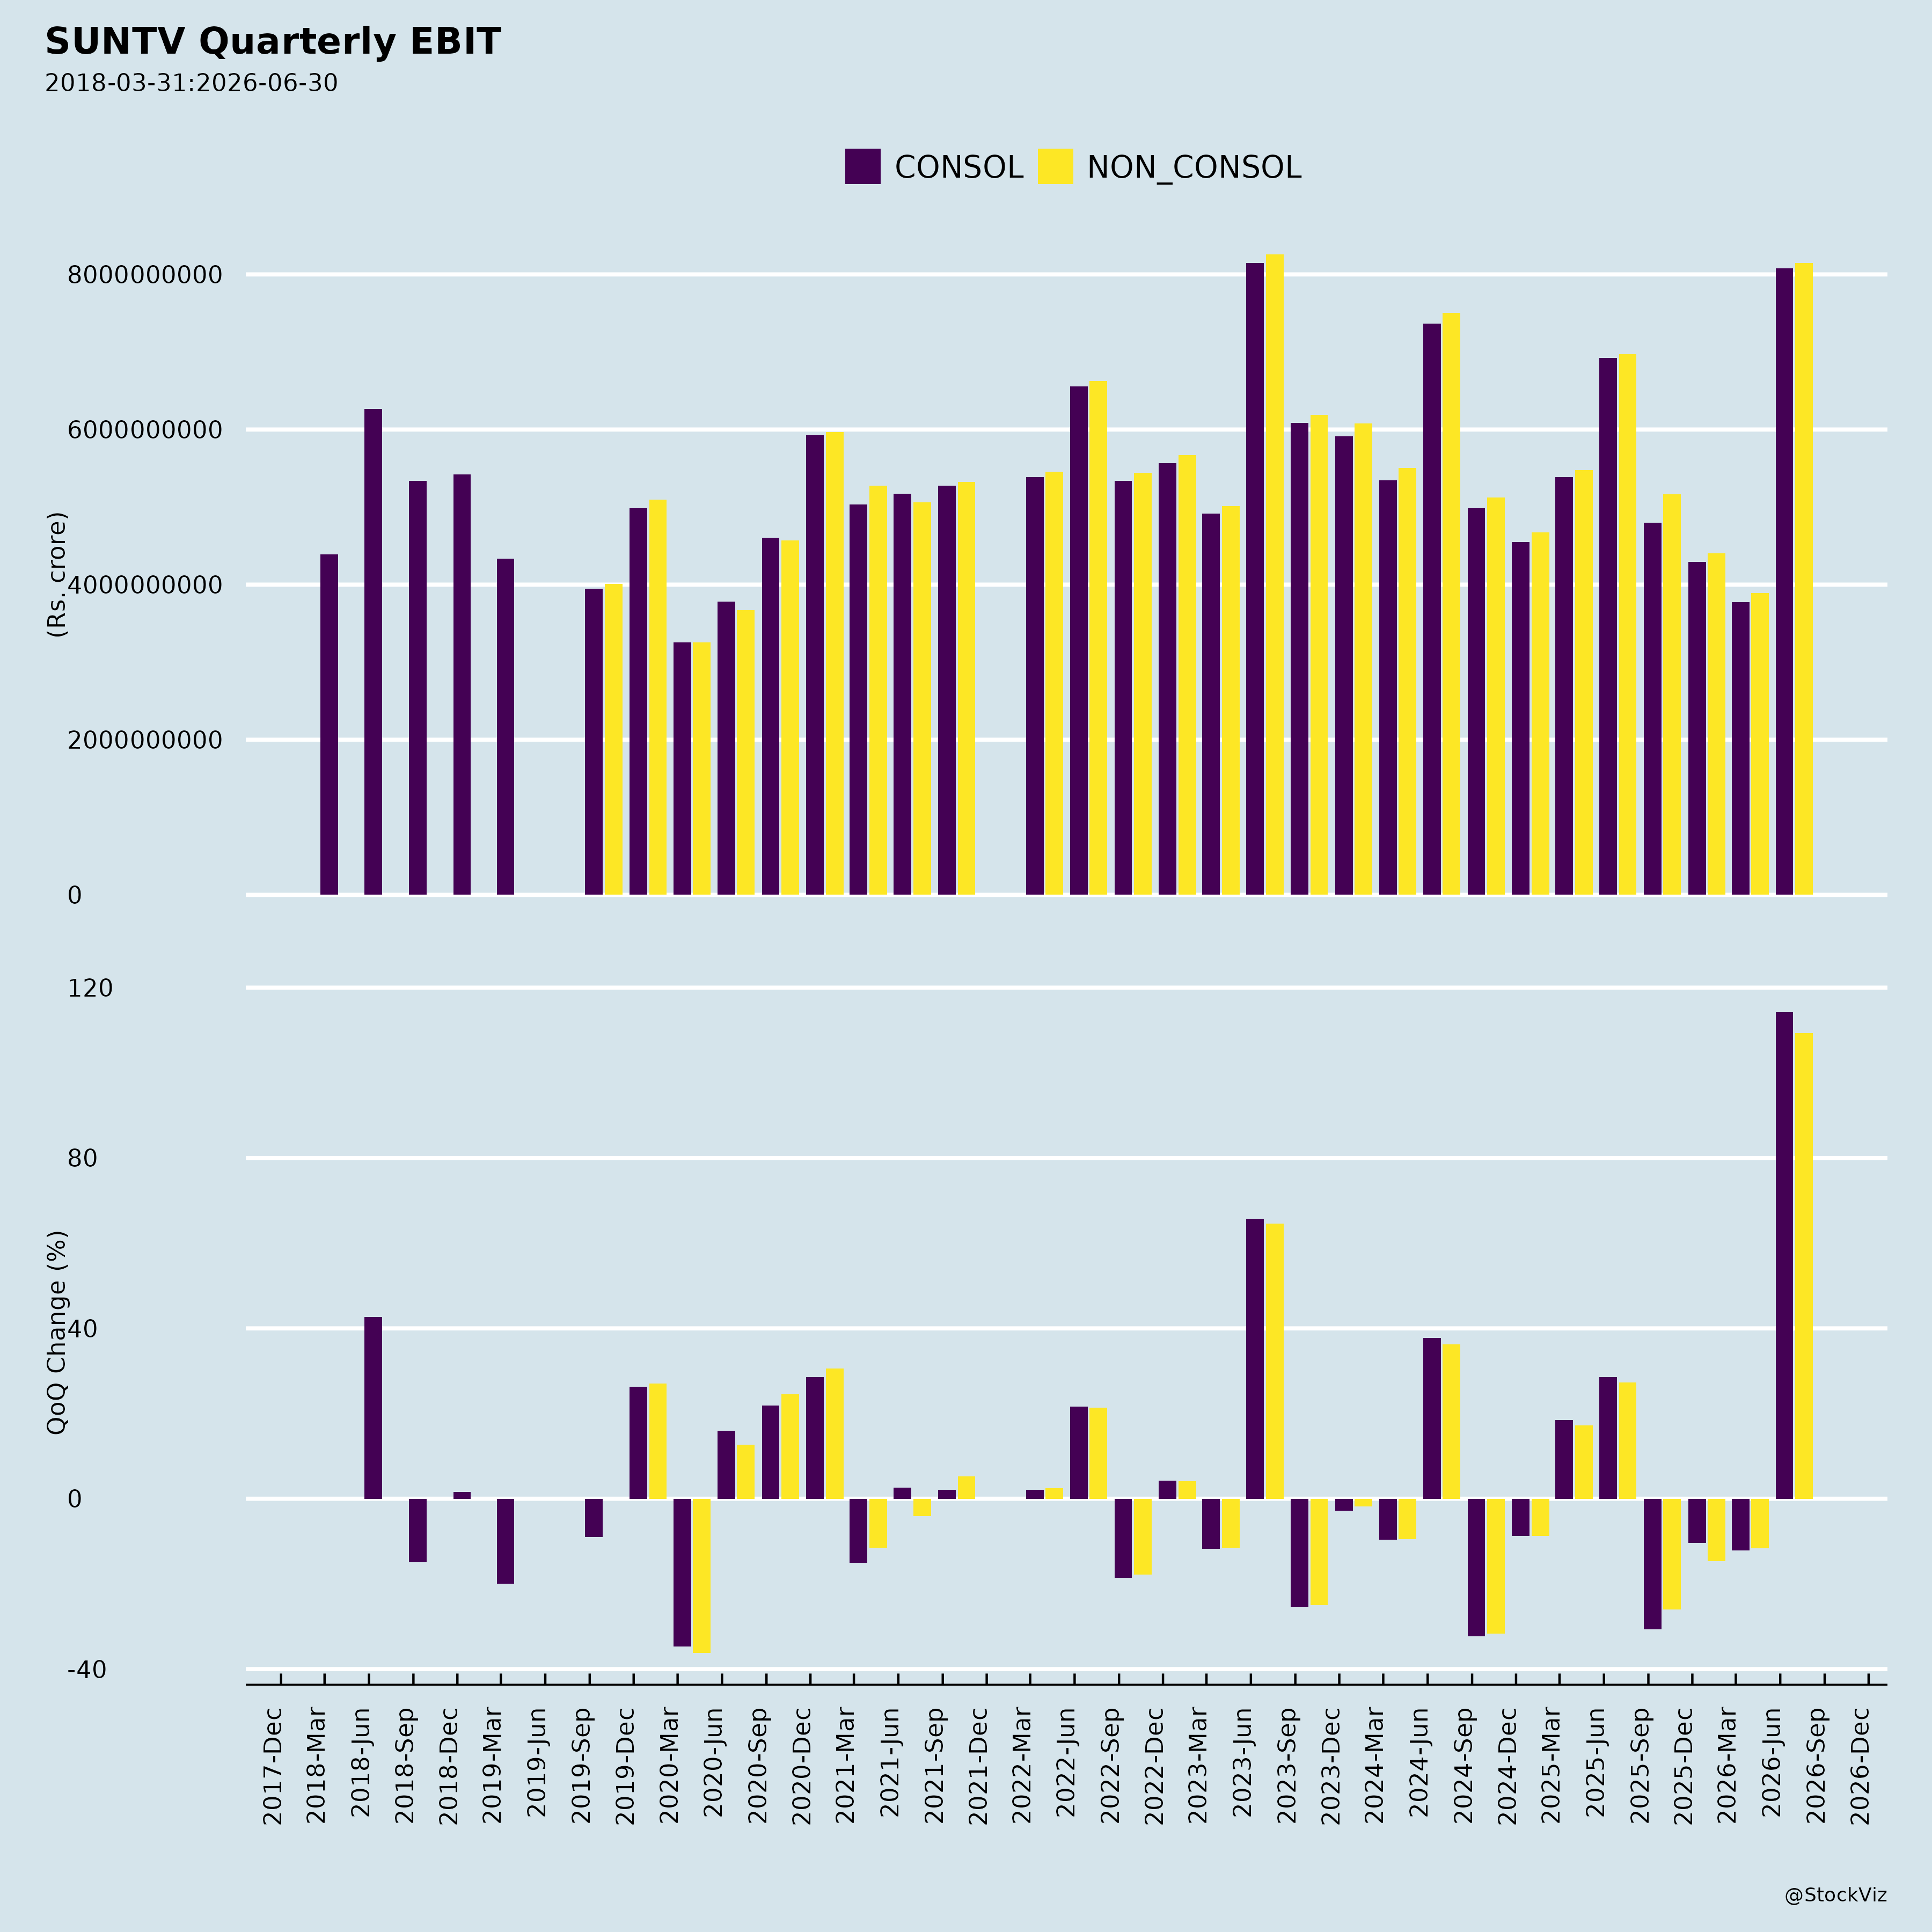
- Overall financial momentum. Revenues for the June 2026 quarter rose ~13% year-on-year to Rs. 1,423.39 crores; EBITDA rose ~19% to Rs. 732.99 crores; Profit after tax rose ~16% to Rs. 611.97 crores. Sequentially, revenues rose ~68%, EBITDA ~93%, and PAT ~180%.
- Digital and content investment. Continued investments in digital platforms, content creation, and distribution are expected to strengthen the competitive position.
- Balance sheet strength. The Company is debt-free with zero loan funds as of March 31, 2026.
- Shareholder returns. The Board declared an interim dividend of Rs. 5.00 per share (100%) for FY 2026-27 at its meeting on August 12, 2026. For FY 2025-26, interim dividends totaling 250% (Rs. 12.50 per equity share) were declared, with no final dividend recommended.
3. Key Risks
- Competitive pressure across traditional broadcasting, OTT, and digital-first content.
- Piracy and unauthorized distribution of content.
- Regulatory evolution, cybersecurity threats, and rapid technological disruption.
- Cost inflation in premium content, sports rights, and talent.
- Dependence on subscription and advertising revenues, sensitive to economic conditions and advertising spend patterns.
- Concentration of cricket franchise income within overall revenues (Rs. 629.83 crores of income in the June 2026 quarter, with corresponding costs of Rs. 321.17 crores standalone / Rs. 124.31 crores consolidated).
- Key personnel risk, illustrated by the COO’s retirement effective August 31, 2026.
4. Management Guidance vs. Observed Performance
- Guidance: Management anticipates improved growth from its cricket franchise and movie production and distribution businesses, which are expected to further diversify earnings and enhance shareholder value. Continued investments in digital platforms, content creation, and distribution are expected to strengthen the competitive position. The company states it remains well-positioned to capitalize on industry opportunities through its strong leadership in southern markets and diversified channel portfolio.
- Observed performance: The June 2026 quarter showed year-on-year revenue growth of ~13%, EBITDA growth of ~19%, and PAT growth of ~16%, alongside a ~3% rise in domestic subscription revenues. Cricket franchise income rose to Rs. 629.83 crores from Rs. 473.03 crores a year earlier, consistent with the stated expectation of improved growth from the cricket business. However, advertisement revenues declined year-on-year (Rs. 282.51 crores vs. Rs. 289.94 crores), indicating that the advertising environment remained soft even as overall revenues grew.
- Capital returns: The declaration of a 100% interim dividend for FY 2026-27 (Rs. 5.00 per share) on August 12, 2026, and total interim dividends of 250% for FY 2025-26, are consistent with the stated focus on enhancing shareholder value.
- Governance calendar: The 41st Annual General Meeting is scheduled for Friday, September 18, 2026, to be held through Video Conferencing/OAVM.
Broker Narrative
The narrative shifted from an initial Buy built on economic recovery, IPL rights, cash pile, and a possible acquisition/re-rating to a Neutral focused on structural ad weakness and digital shift. Persistent themes were IPL-led growth, ad revenue pressure, and valuation support; the changed elements were fading optimism on macro/subscription growth, while core ex-IPL weakness and FMCG migration to digital became the dominant risks.
Fears that came true
- The weak macro/ad competition risk materialized as domestic advertising revenue declined 2.6% YoY in 1QFY27, coinciding with multiple DISAPPOINTMENT outcomes and negative actual returns such as -36.7% and -40.4%.
- The ‘onslaught of digital’ materialized as FMCG ad spends shifted toward digital platforms, becoming a structural headwind for linear TV broadcasters.
- The low growth/under-investment concern materialized as ex-IPL core revenue grew only ~1% YoY, with persistent ad weakness weighing on the core business.
Optimism that failed
- The upbeat economic outlook supporting ad revenue growth failed: 1QFY27 domestic ad revenue declined and core revenue ex-IPL stagnated.
- The expected re-rating from a potential acquisition or higher payout did not materialize; no acquisition was cited and only an INR5 interim dividend was declared, while the stock suffered repeated negative returns.
Broker Timeline
18 broker calls · 2023-08-11 to 2026-08-12
Copyright © 2023 SAS Data Analytics Pvt. Ltd. All rights reserved.