SUMICHEM
Equity Metrics
October 23, 2026
Sumitomo Chemical India Limited
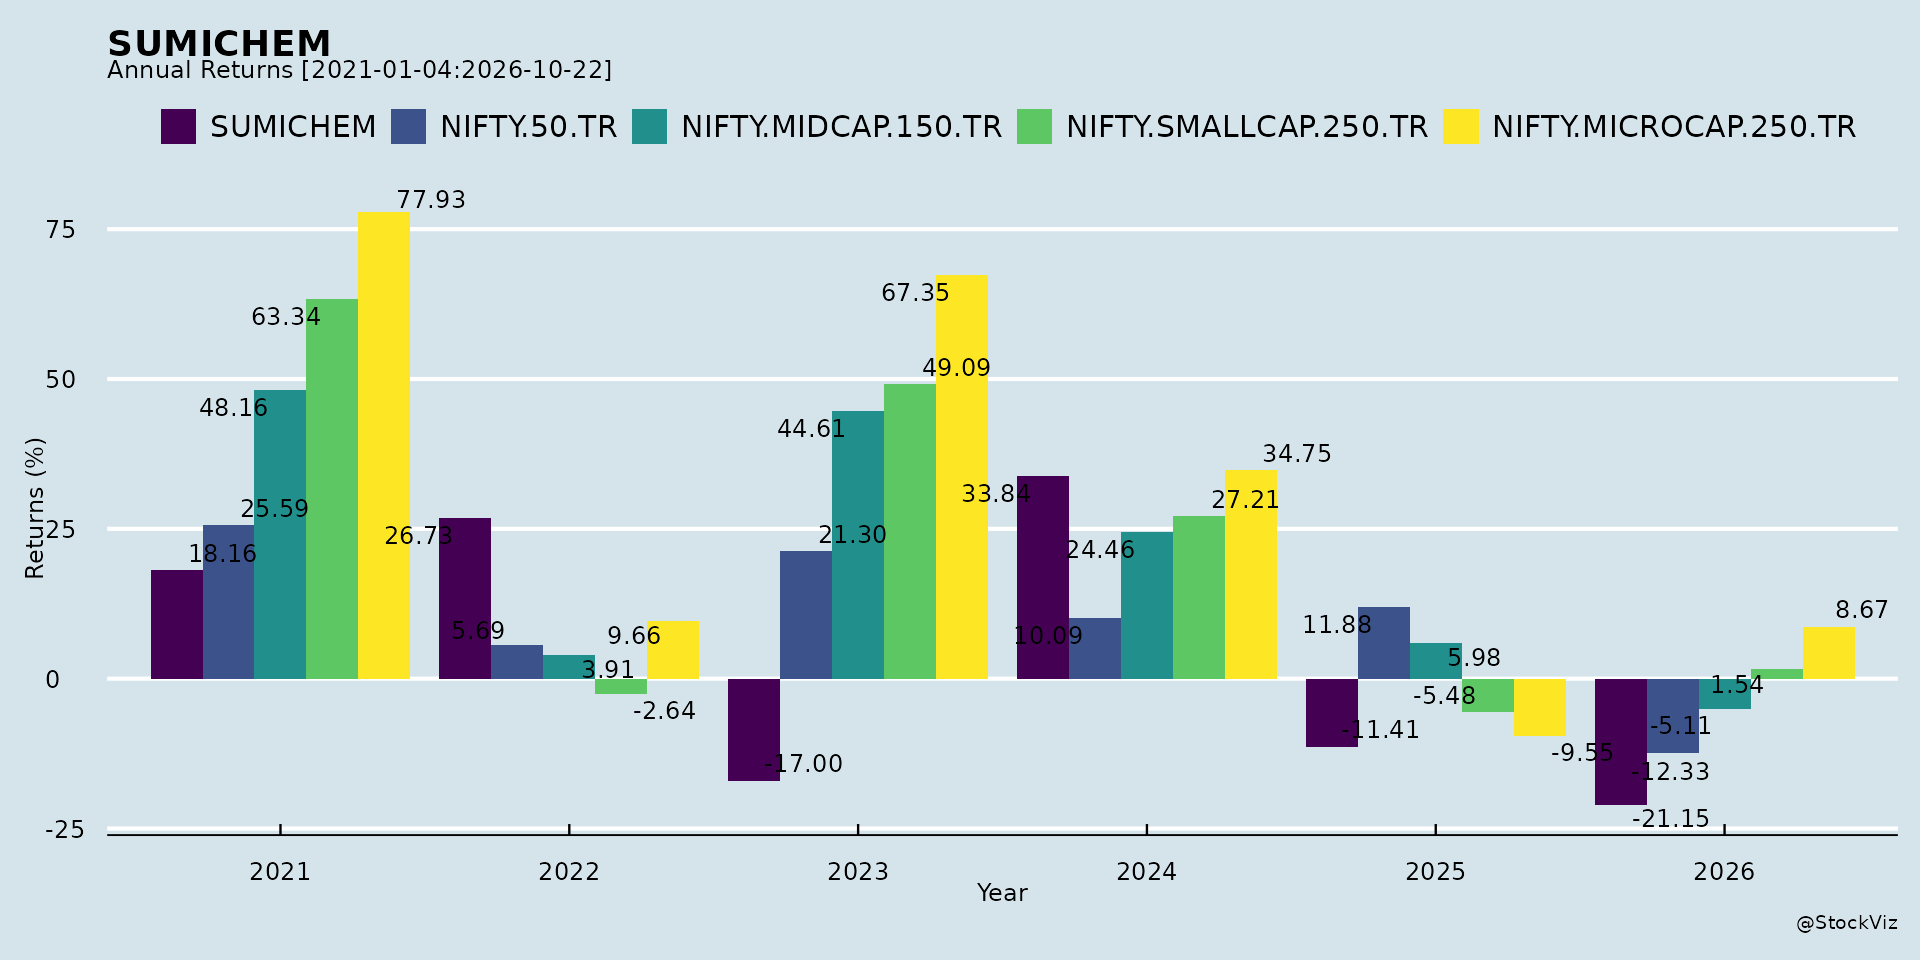
Annual Returns
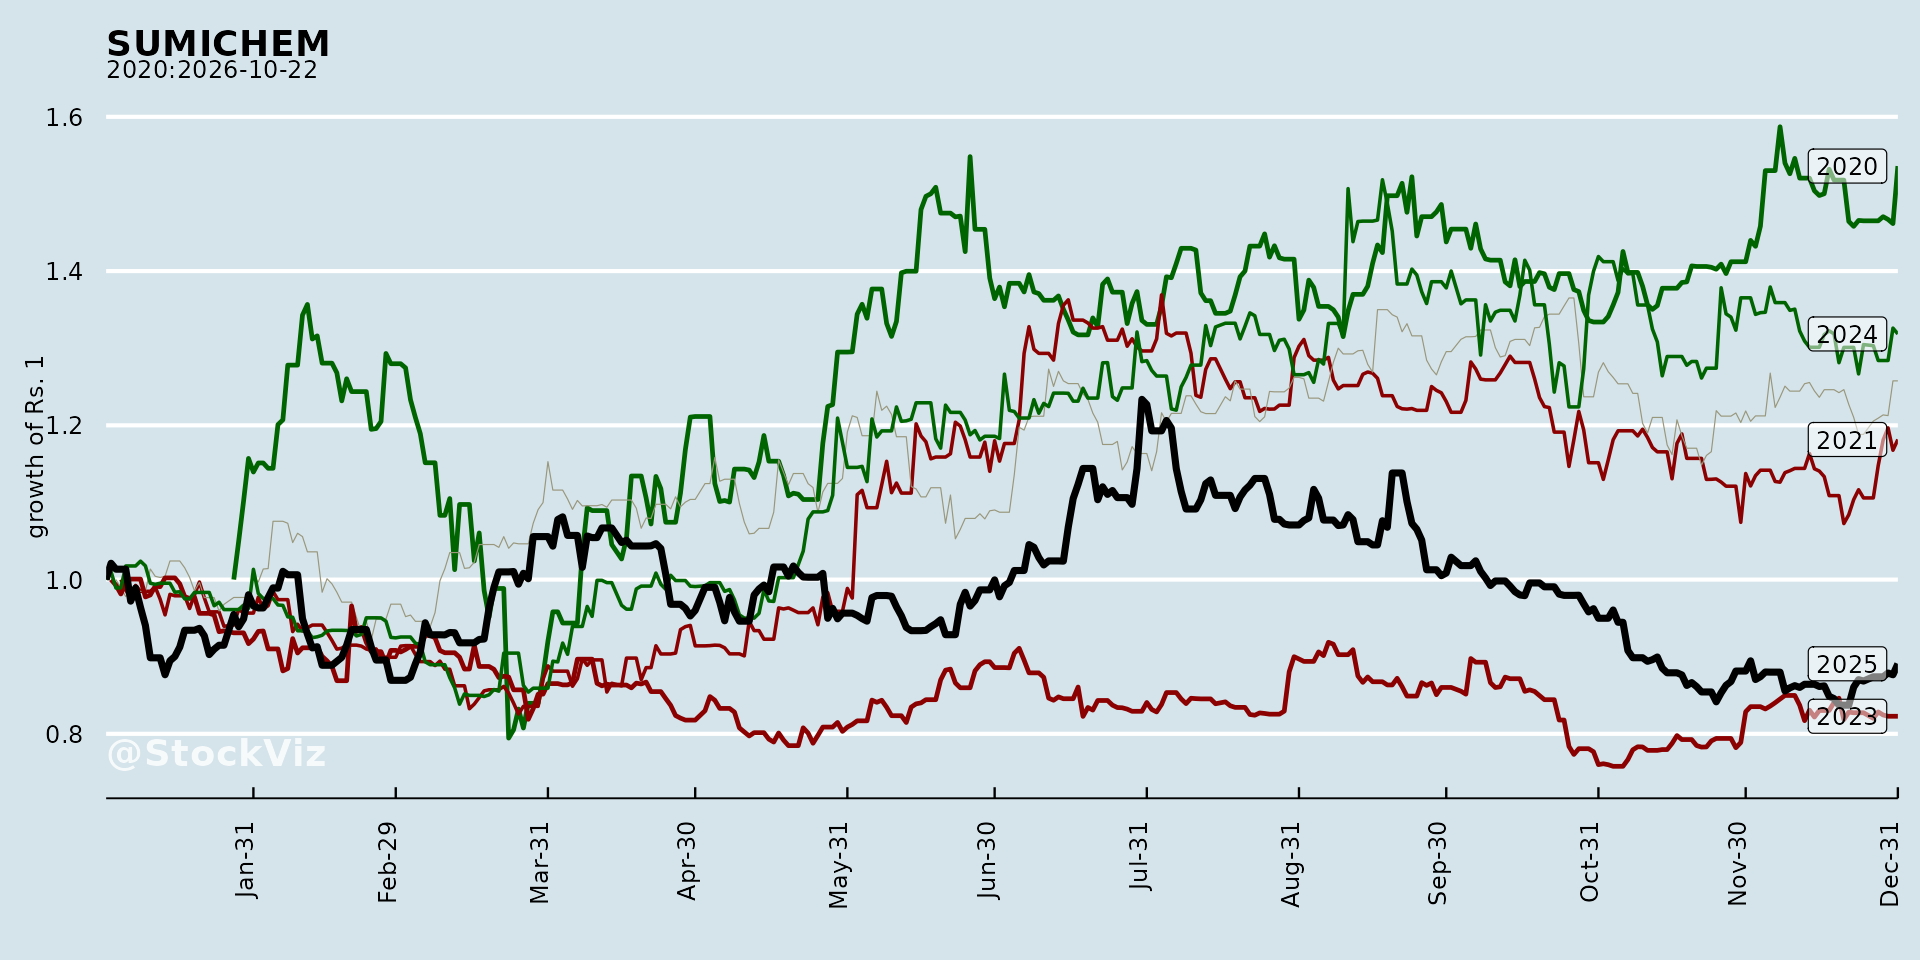
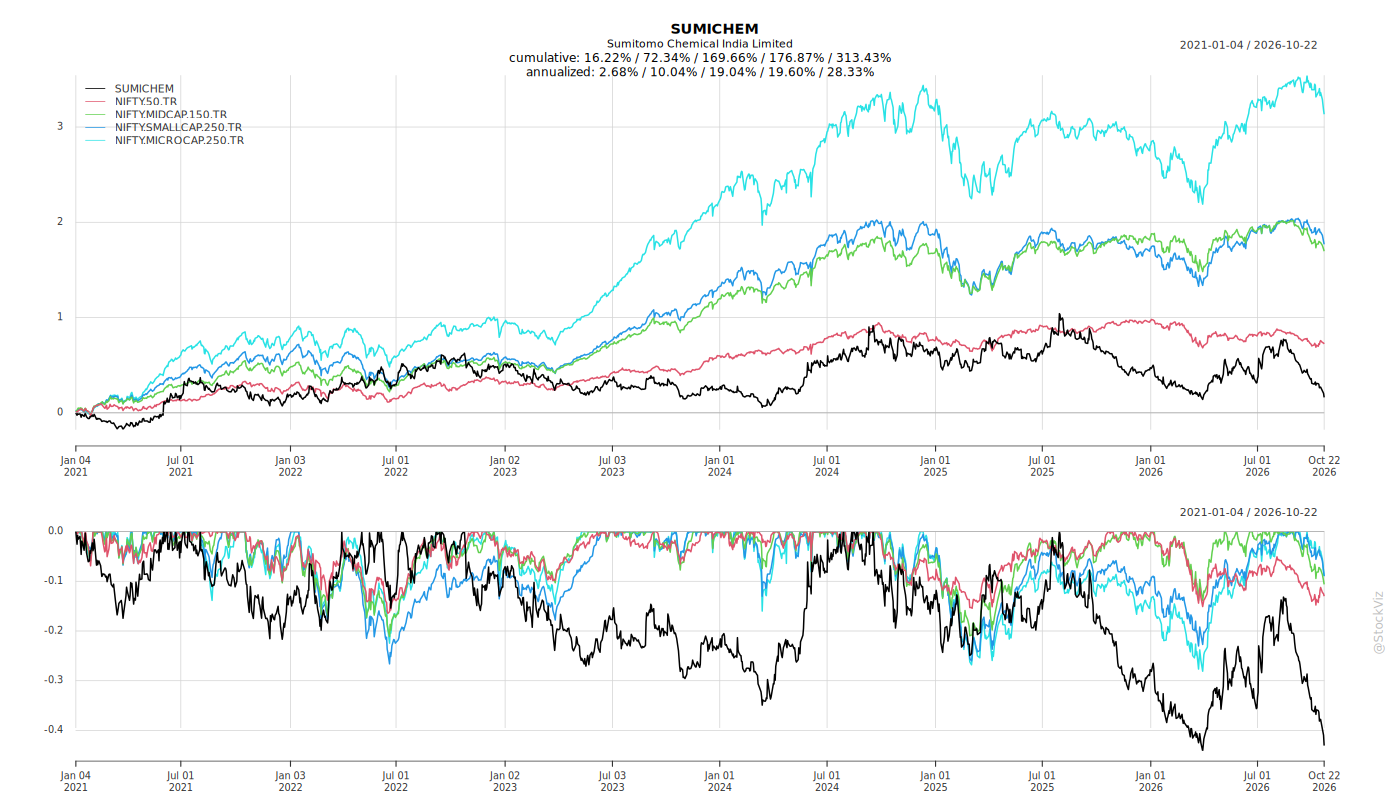
Cumulative Returns and Drawdowns
Fundamentals
Ownership
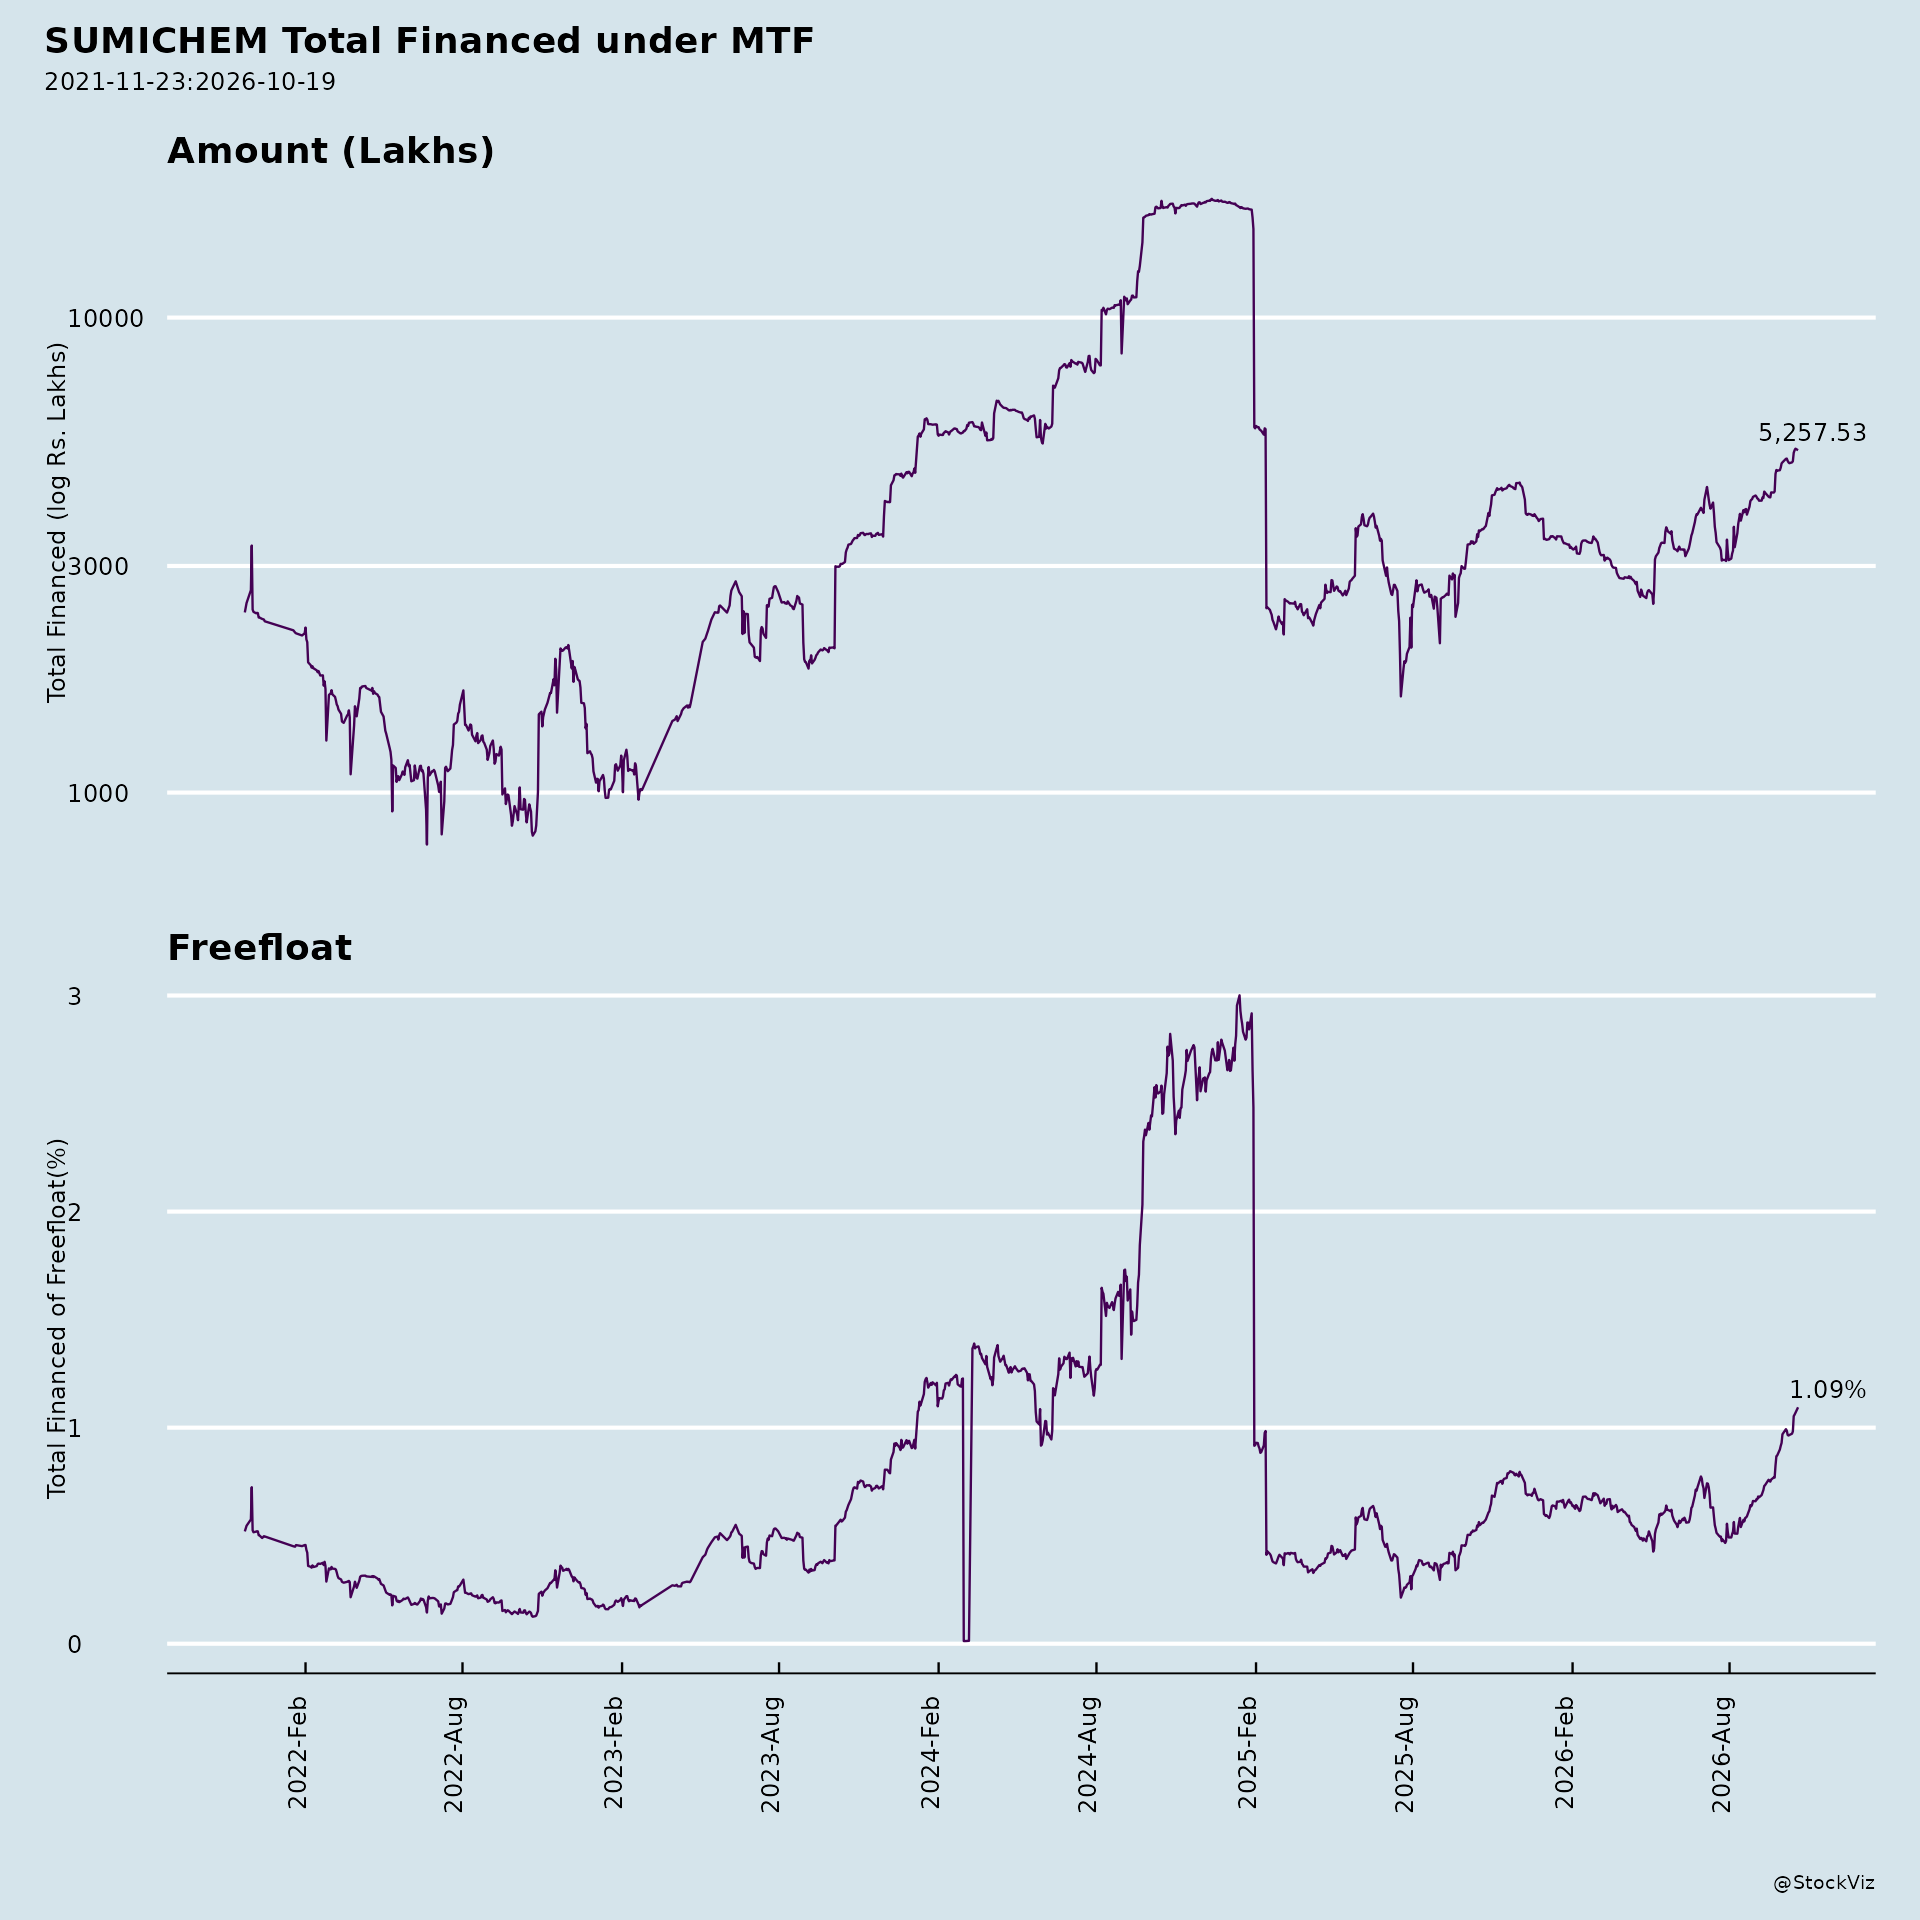
Margined
AI Summary
asof: 2026-09-16
Sumitomo Chemical India Limited — Q1FY27 Analysis
1. Headwinds and Challenges
Monsoon and sowing disruption: The Indian agrochemical sector faced an adverse operating environment in Q1FY27. The South-West monsoon was delayed, with a 40% rainfall deficit through June-end, lower reservoir levels, and a roughly 20% decline in kharif sowing area during the early part of the season.
Channel inventory and pricing pressure: Elevated channel inventories following advance purchases in March–April, combined with subsequent price corrections, weighed on demand during the quarter.
Subdued domestic demand: Domestic demand remained weak due to the delayed monsoon and lower acreage. Softer demand was recorded in Herbicides, Fungicides, and Plant Growth Regulators.
Input cost inflation: The company undertook calibrated price revisions during April and May to mitigate input cost inflation while maintaining market competitiveness.
Export softness in some regions: Although overall exports grew 26% YoY, sales in Japan and North America were lower.
Working capital build: Net working capital days rose to 56 days in June 2026 from 43 days in June 2025, largely due to seasonal inventory build-up ahead of kharif and higher inventory carrying value. Inventory days increased to 124 (June 2026) from 90 (June 2025).
Regulatory overhang: A Central Government notification (October 2022) mandates that Glyphosate — an important product — be used only through Pest Control Operators. Industry petitions challenging the notification are pending before the Delhi High Court; the Government’s counsel has stated the notification will not be implemented until the petitions are disposed of.
Board reconstitution: Several directors are at the end of their terms effective 31 August 2026, including the Chairman (Mr. Mukul Govindji Asher), the Managing Director (Mr. Chetan Shantilal Shah, transitioning to Non-Executive Non-Independent Director and proposed Chairman), the Executive Director (Mr. Sushil Champaklal Marfatia), and Non-Executive Director (Mr. Ninad D. Gupte). Dr. Suresh Ramachandran is to be appointed Managing Director effective 1 September 2026.
2. Tailwinds and Growth Prospects
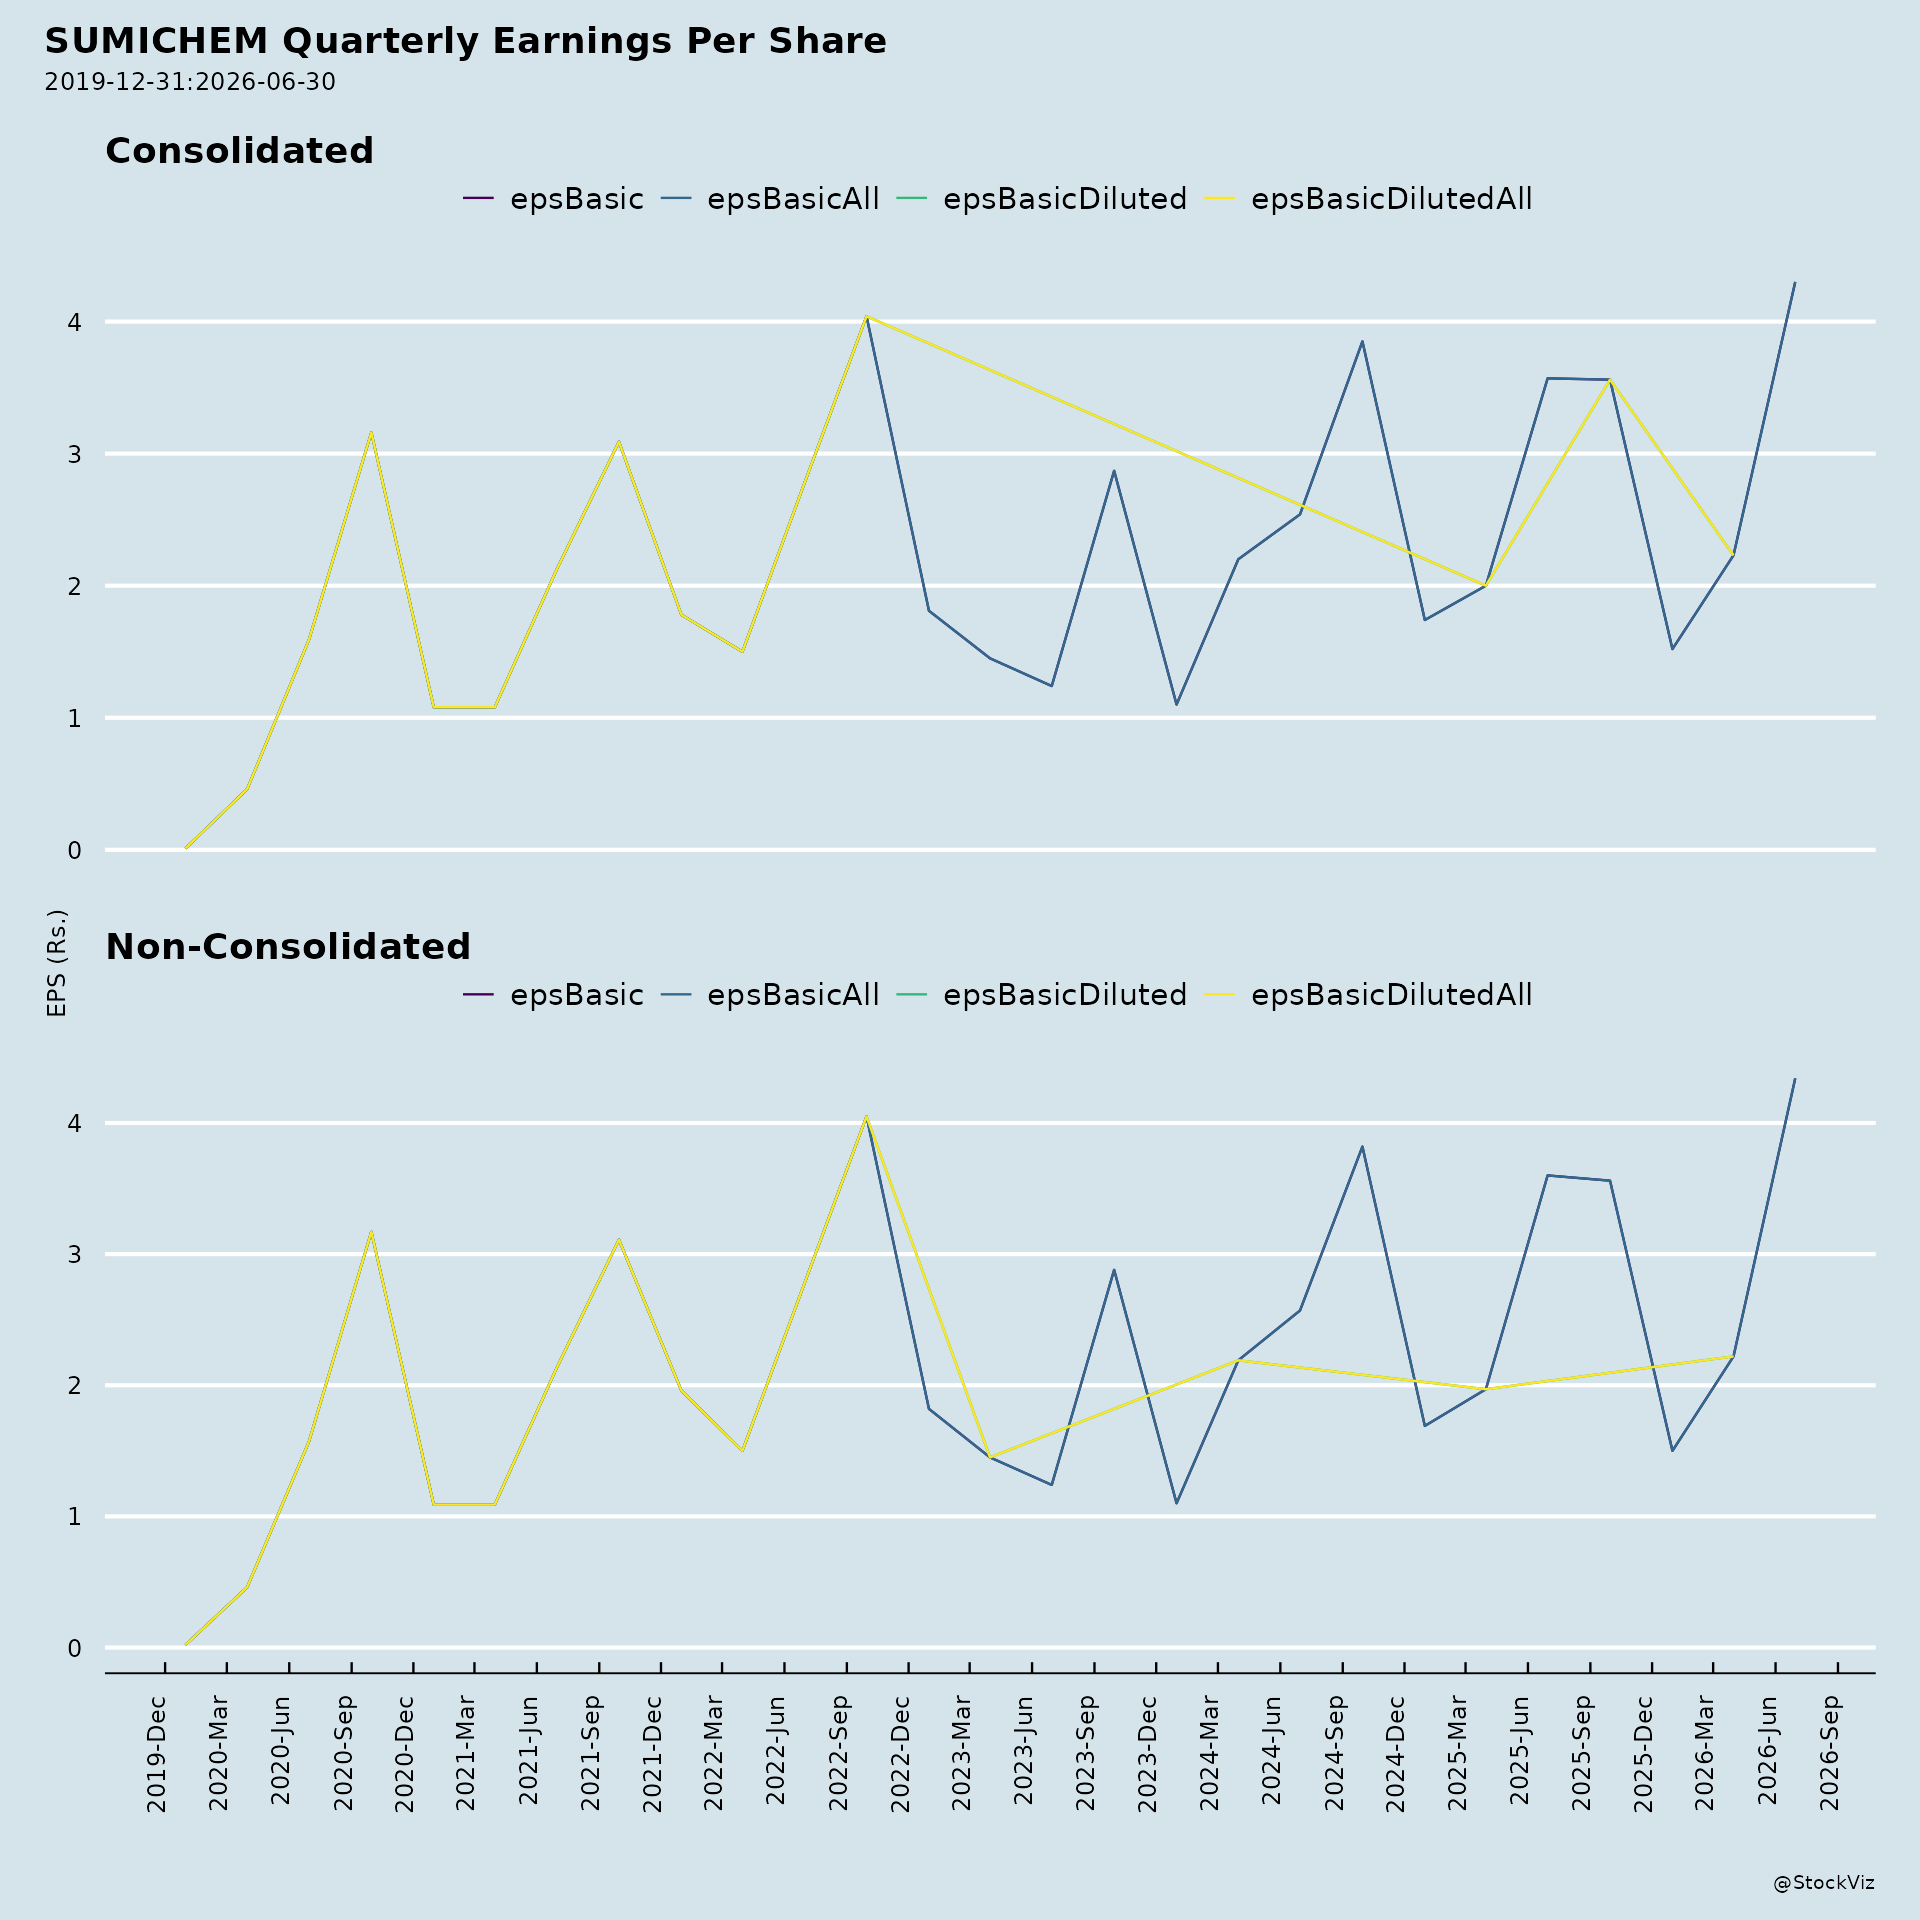
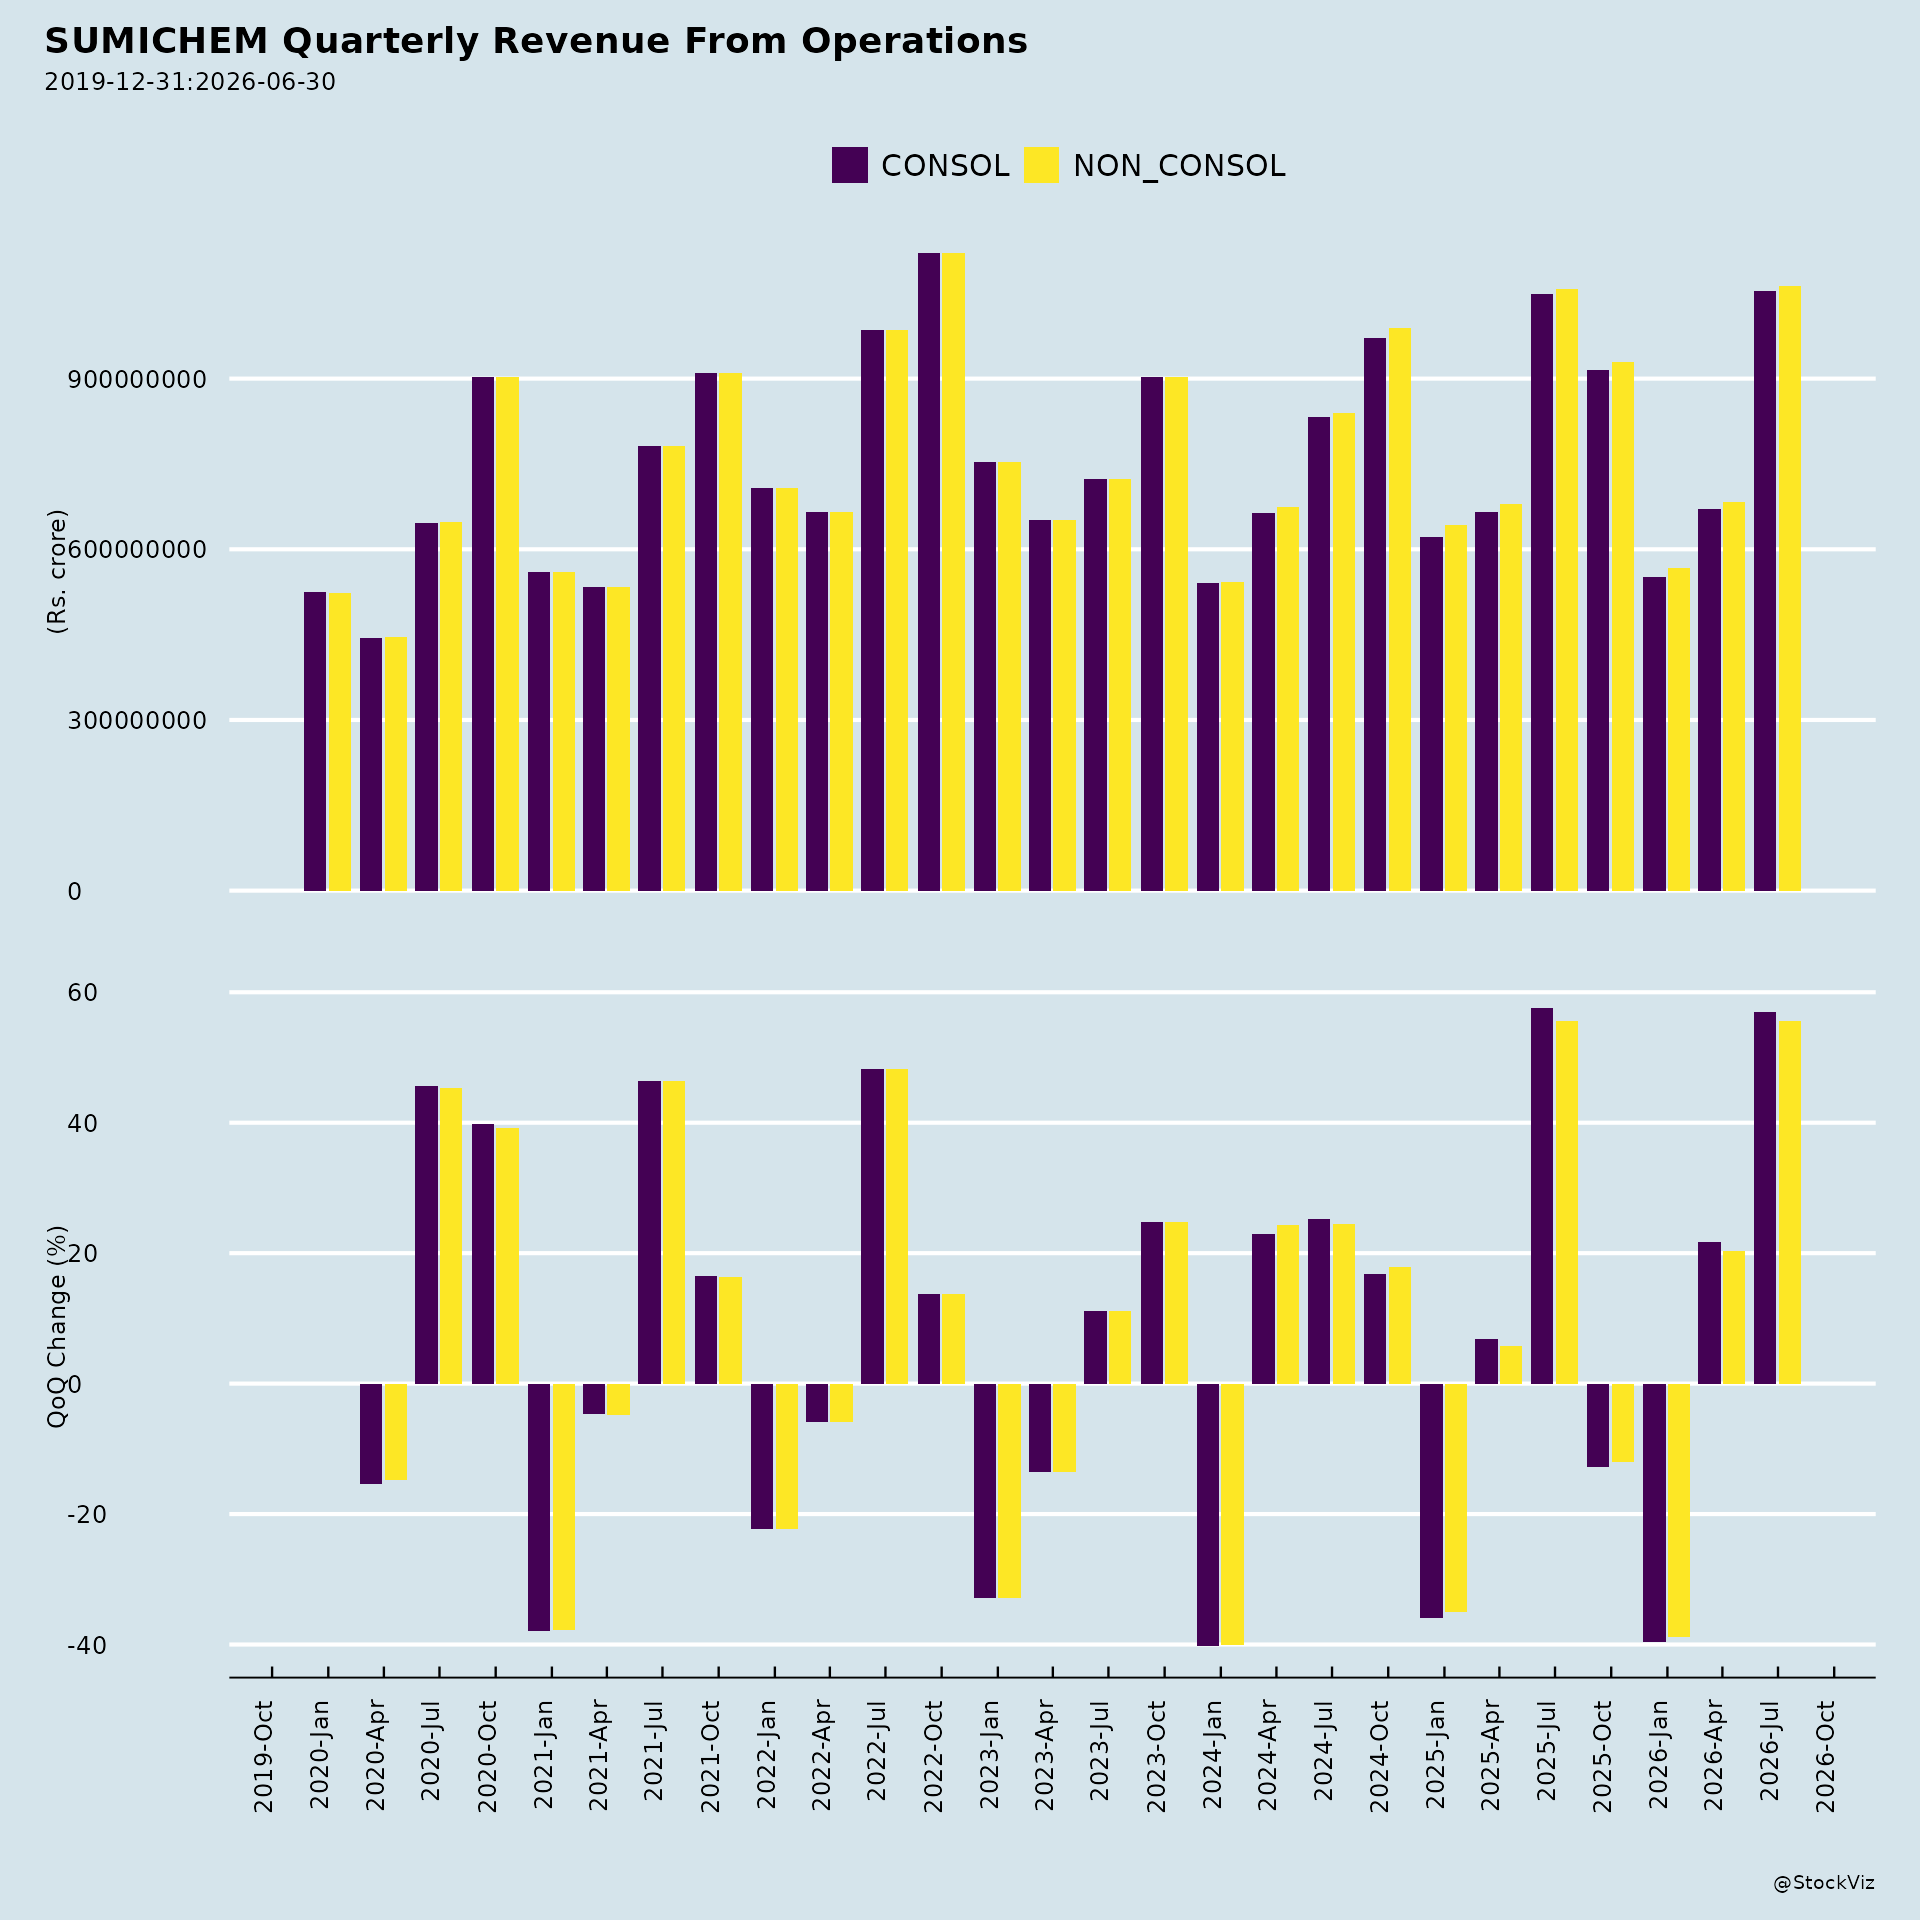
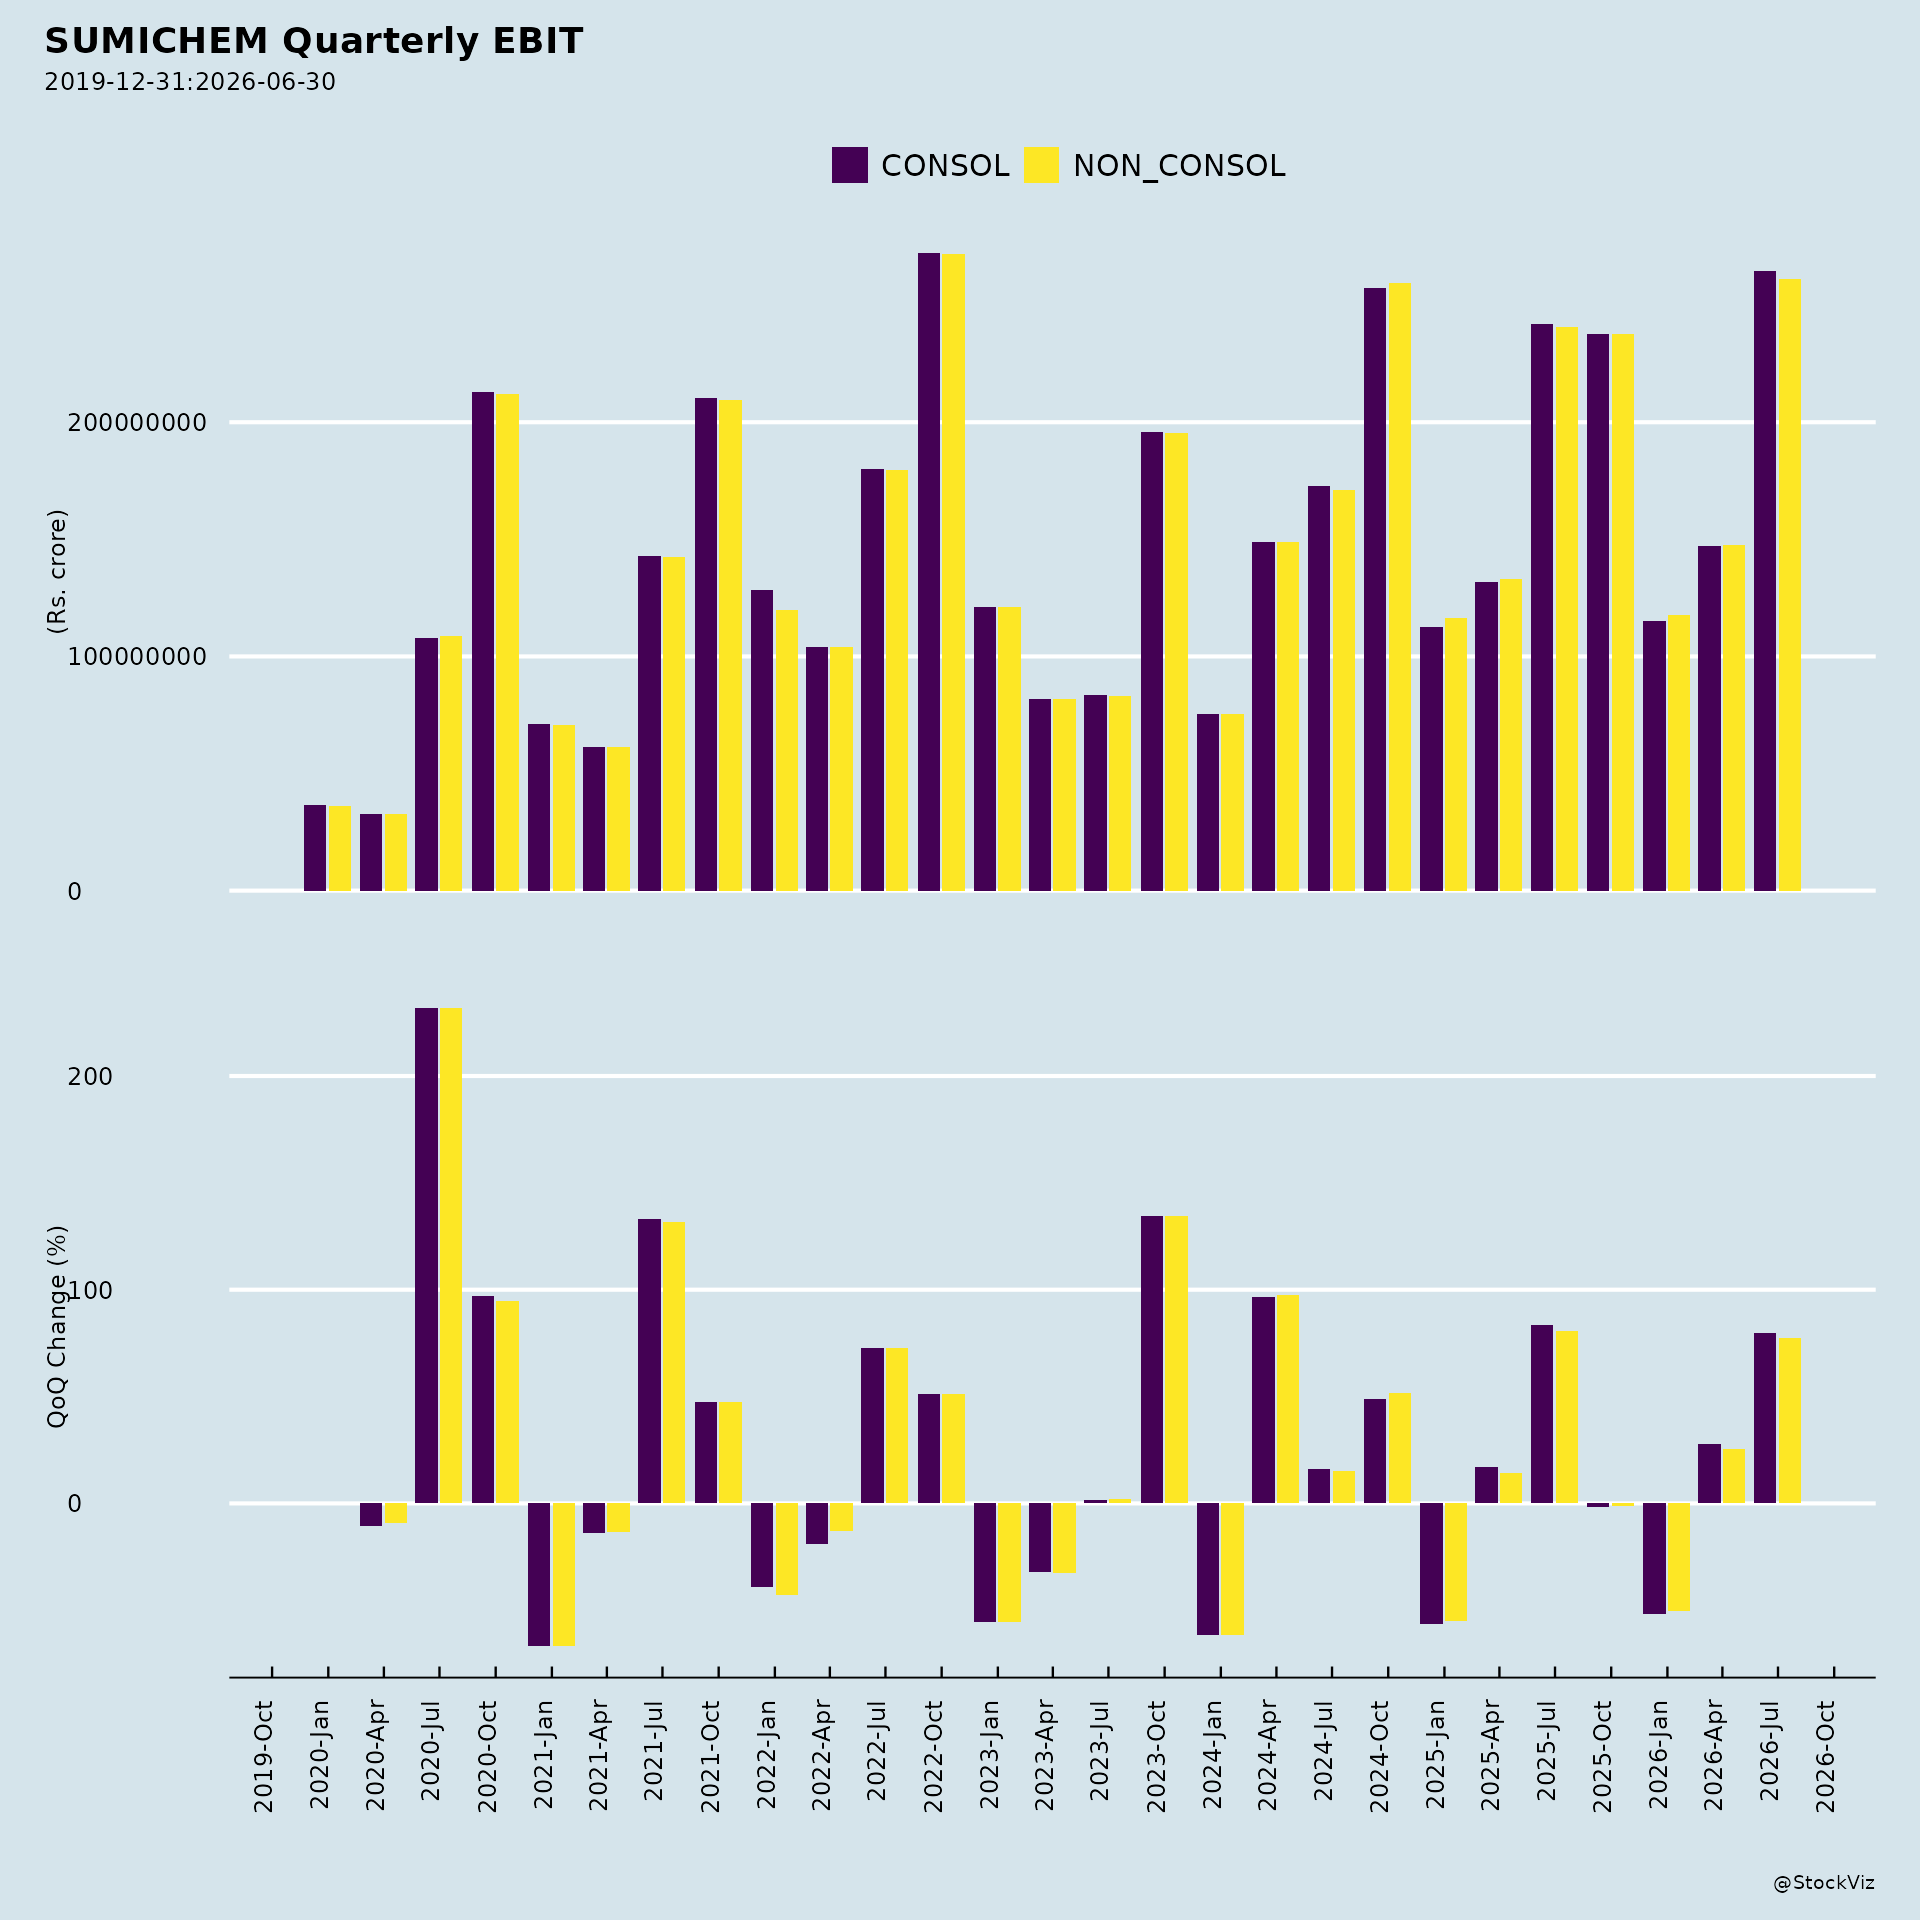
Resilient operating performance: Despite headwinds, revenue rose 1% YoY to Rs. 1,063 crore, supported by disciplined execution, timely pricing actions, and a favourable product mix. Gross Profit rose 4% YoY with Gross Margin expanding 111 bps to 39.2%. Operating EBITDA rose 6% YoY to Rs. 233 crore, with EBITDA Margin up 120 bps to 21.9%. PBT (before exceptional item) grew 9% YoY.
Export momentum: Exports grew 26% YoY, contributing 16% of revenues, driven by strong growth in South America, Asia (ex-India), and Africa.
Product mix strength: Growth in Metal Phosphides (+21% YoY) and AND & EHD (+11% YoY) helped offset softer demand elsewhere.
New launches: Topgrain and Helibax (Pyridalyl + Emamectin) remain on track for launch during Q2FY27.
Monsoon recovery: Monsoon progress improved during July, with gradual recovery in sowing activity and a strengthened commercial pipeline.
Capacity expansion and parent-linked projects: - A herbicide intermediate plant at Dahej for supply to the parent company — capex budget ~Rs. 150 crore, estimated commercialization Q2 FY2028-29. This is the first strategic investment at Dahej, positioning it as a strategic global manufacturing hub for the parent’s high-potential patented molecules. - Fitment at Tarapur for two additional molecules (one fungicide, one herbicide) primarily for supply to the parent — capex budget ~Rs. 10 crore, estimated commercialization Q4 FY2027-28, payback less than 5 years from start of operations. - Two additional land parcels acquired: ~20 acres adjoining Bhavnagar and ~50 acres at Dahej (environmental clearance recently received).
Financial strength: Cash & cash equivalents stood at Rs. 2,549 crore as on 30 June 2026; collections of ~Rs. 1,178 crore during Q1FY27. The company is debt-free with strong return ratios.
Strategic initiatives: Continued investment in R&D (3 DSIR-approved labs, 75+ scientists, 25+ patents granted, 9 applications filed), brand development, digital/phygital transformation (14.2 crore digital touchpoints, 17.2% reduction in engagement costs), and a diversified portfolio (200+ brands, 700+ SKUs, exports to ~50 countries).
Growth strategy framework: Balanced portfolio of specialty and off-patent products, manufacturing excellence and Make in India projects, organizational transformation, and sustainable financial results. The company aims to invest ~15% of consolidated EBITDA annually in manufacturing upgradation and capacity expansion.
3. Key Risks
- Monsoon/climatic dependence: The business is seasonal and performance depends on monsoon and other climatic conditions.
- Regulatory risk: The pending Glyphosate notification and related litigation before the Delhi High Court.
- Demand and channel risk: Channel inventory build-up and price corrections can weigh on demand.
- Input cost inflation: Requires calibrated price revisions, which may affect competitiveness.
- Geographic concentration in exports: Performance varied by region, with declines in Japan and North America.
- Working capital volatility: Seasonal inventory build-up increased net working capital days.
- Subsidiary performance: Two subsidiaries (Barrix Agro Sciences Private Limited and Excel Crop Care (Africa) Limited, under liquidation) had interim financial information reflecting total revenues of Rs 220.37 million, net loss after tax of Rs 19.09 million, and total comprehensive loss of Rs 20.05 million for the quarter ended 30 June 2026 (before consolidation adjustments); these were not reviewed and are not material to the Group.
- Leadership transition: Multiple board and senior management changes effective 1 September 2026.
4. Management Guidance vs. Observed Performance
Guidance/forward-looking statements: - Topgrain and Helibax (Pyridalyl + Emamectin) launches on track for Q2FY27. - Dahej herbicide intermediate plant: commercialization estimated Q2 FY2028-29. - Tarapur fitment for two additional molecules: commercialization estimated Q4 FY2027-28, payback less than 5 years. - Intent to invest ~15% of consolidated EBITDA annually in manufacturing upgradation and capacity expansion. - Focus on driving sustainable growth through differentiated products, disciplined execution, enhanced channel engagement, and operational excellence. - Growth strategies targeting market leadership in India, export expansion, and leveraging SCC’s global supply chain.
Observed performance against prior context: - Q1FY27 revenue of Rs. 1,063.3 crore vs. Q1FY26 Rs. 1,056.8 crore (up 1% YoY); Q4FY26 was Rs. 683.7 crore (up 56% QoQ). - FY26 full-year revenue was Rs. 3,238.3 crore with EBITDA margin of 20.7%; Q1FY27 EBITDA margin of 21.9% exceeded the FY26 level. - FY26 net profit was Rs. 543.0 crore; Q1FY27 net profit was Rs. 214.5 crore (including the Rs. 26.9 crore exceptional insurance claim). - The company noted that given seasonality, the business is best monitored on an annual basis. - The Q1FY27 exceptional item of Rs. 26.9 crore relates to an insurance claim for business interruption from the FY23 Bhavnagar fire incident; FY26 had an exceptional charge of Rs. 16.1 crore related to newly notified Labour Codes.
Key investor facts: - The 26th AGM was held on 27 July 2026; all ten resolutions passed with requisite majority, including adoption of financial statements, a dividend declaration of Rs 1.30 per share, director appointments/re-appointments, and related party transactions. - Company officials are scheduled to meet institutional investors and analysts (1x1/Group Meetings) organized by Elara Capital on 3 September 2026 in Mumbai; discussions will be based solely on publicly available information, with no UPSI intended to be discussed. - The Board meeting on 27 July 2026 commenced at 11:10 A.M. and concluded at 01:10 P.M. - The company has one reportable segment (agro-chemicals). - The company has grown 14x+ over FY11-26.
Broker Narrative
Brokerage coverage swung from an initial Cautious stance dominated by El Niño/deficient-monsoon and inventory risks to a Buy stance by FY26 led by export growth, margin expansion, new product launches, parent SCC support, and a semiconductor-chemical opportunity. The monsoon and channel-inventory concerns persisted into the last report, but were outweighed by improving profitability and structural growth drivers. The narrative changed from defensive caution to confidence in earnings resilience despite recurring domestic demand headwinds.
Fears that came true
- El Niño/deficient monsoon materialized: the last report notes delayed SW monsoon, 40% June-end rainfall deficit and ~20% lower kharif sowing, a demand shock that coincided with the Aug-2025 DISAPPOINTMENT calls (-11.5% actual return).
- Channel inventory/price-correction risk materialized: elevated inventory from March–April advance purchases and price corrections weighed on demand, matching the early caution and contributing to disappointing returns.
- Muted volumes/price cuts under monsoon stress materialized: domestic revenues fell ~3% YoY and herbicides 8% YoY, validating the early fear of below-normal monsoon hurting volumes.
Optimism that failed
- IMD’s hoped-for rainfall revival from late June to mid-July failed to materialize; the last report still flagged a 40% June-end rainfall deficit and delayed sowing.
- The belief that overall channel inventory was comfortable failed; elevated inventory in insecticides extended into broader price corrections and demand weakness in the last report.
Broker Timeline
12 broker calls · 2023-06-19 to 2026-04-13
Copyright © 2023 SAS Data Analytics Pvt. Ltd. All rights reserved.