SOBHA
Equity Metrics
November 18, 2026
Sobha Limited
Residential Commercial Projects
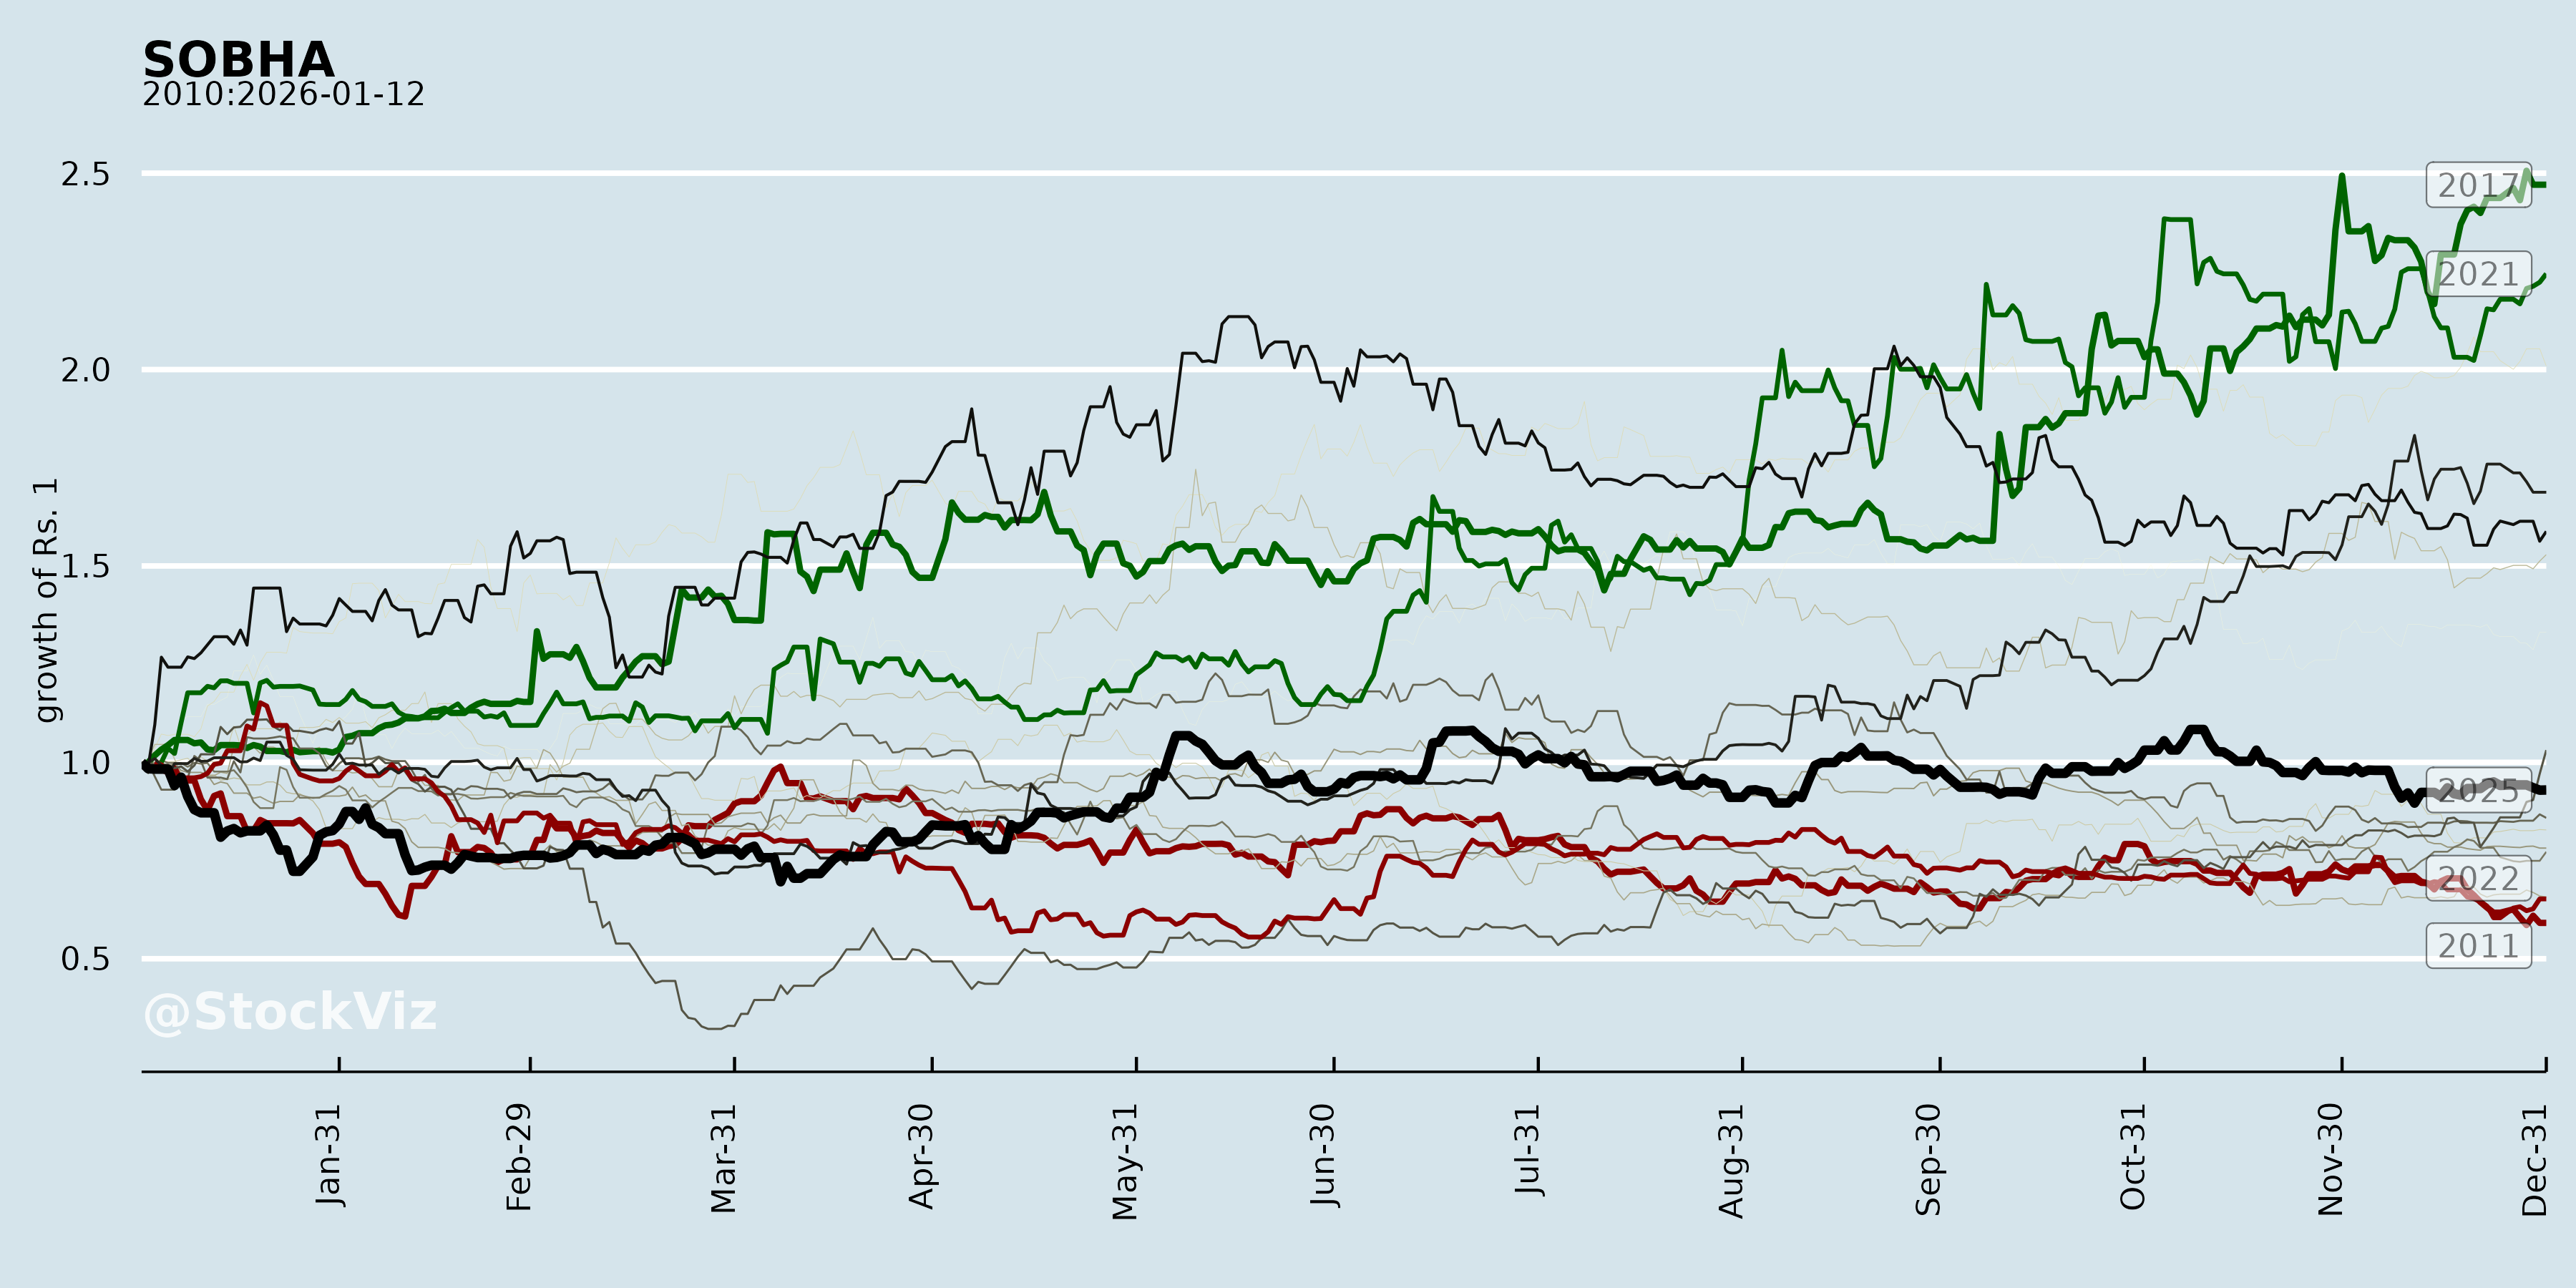
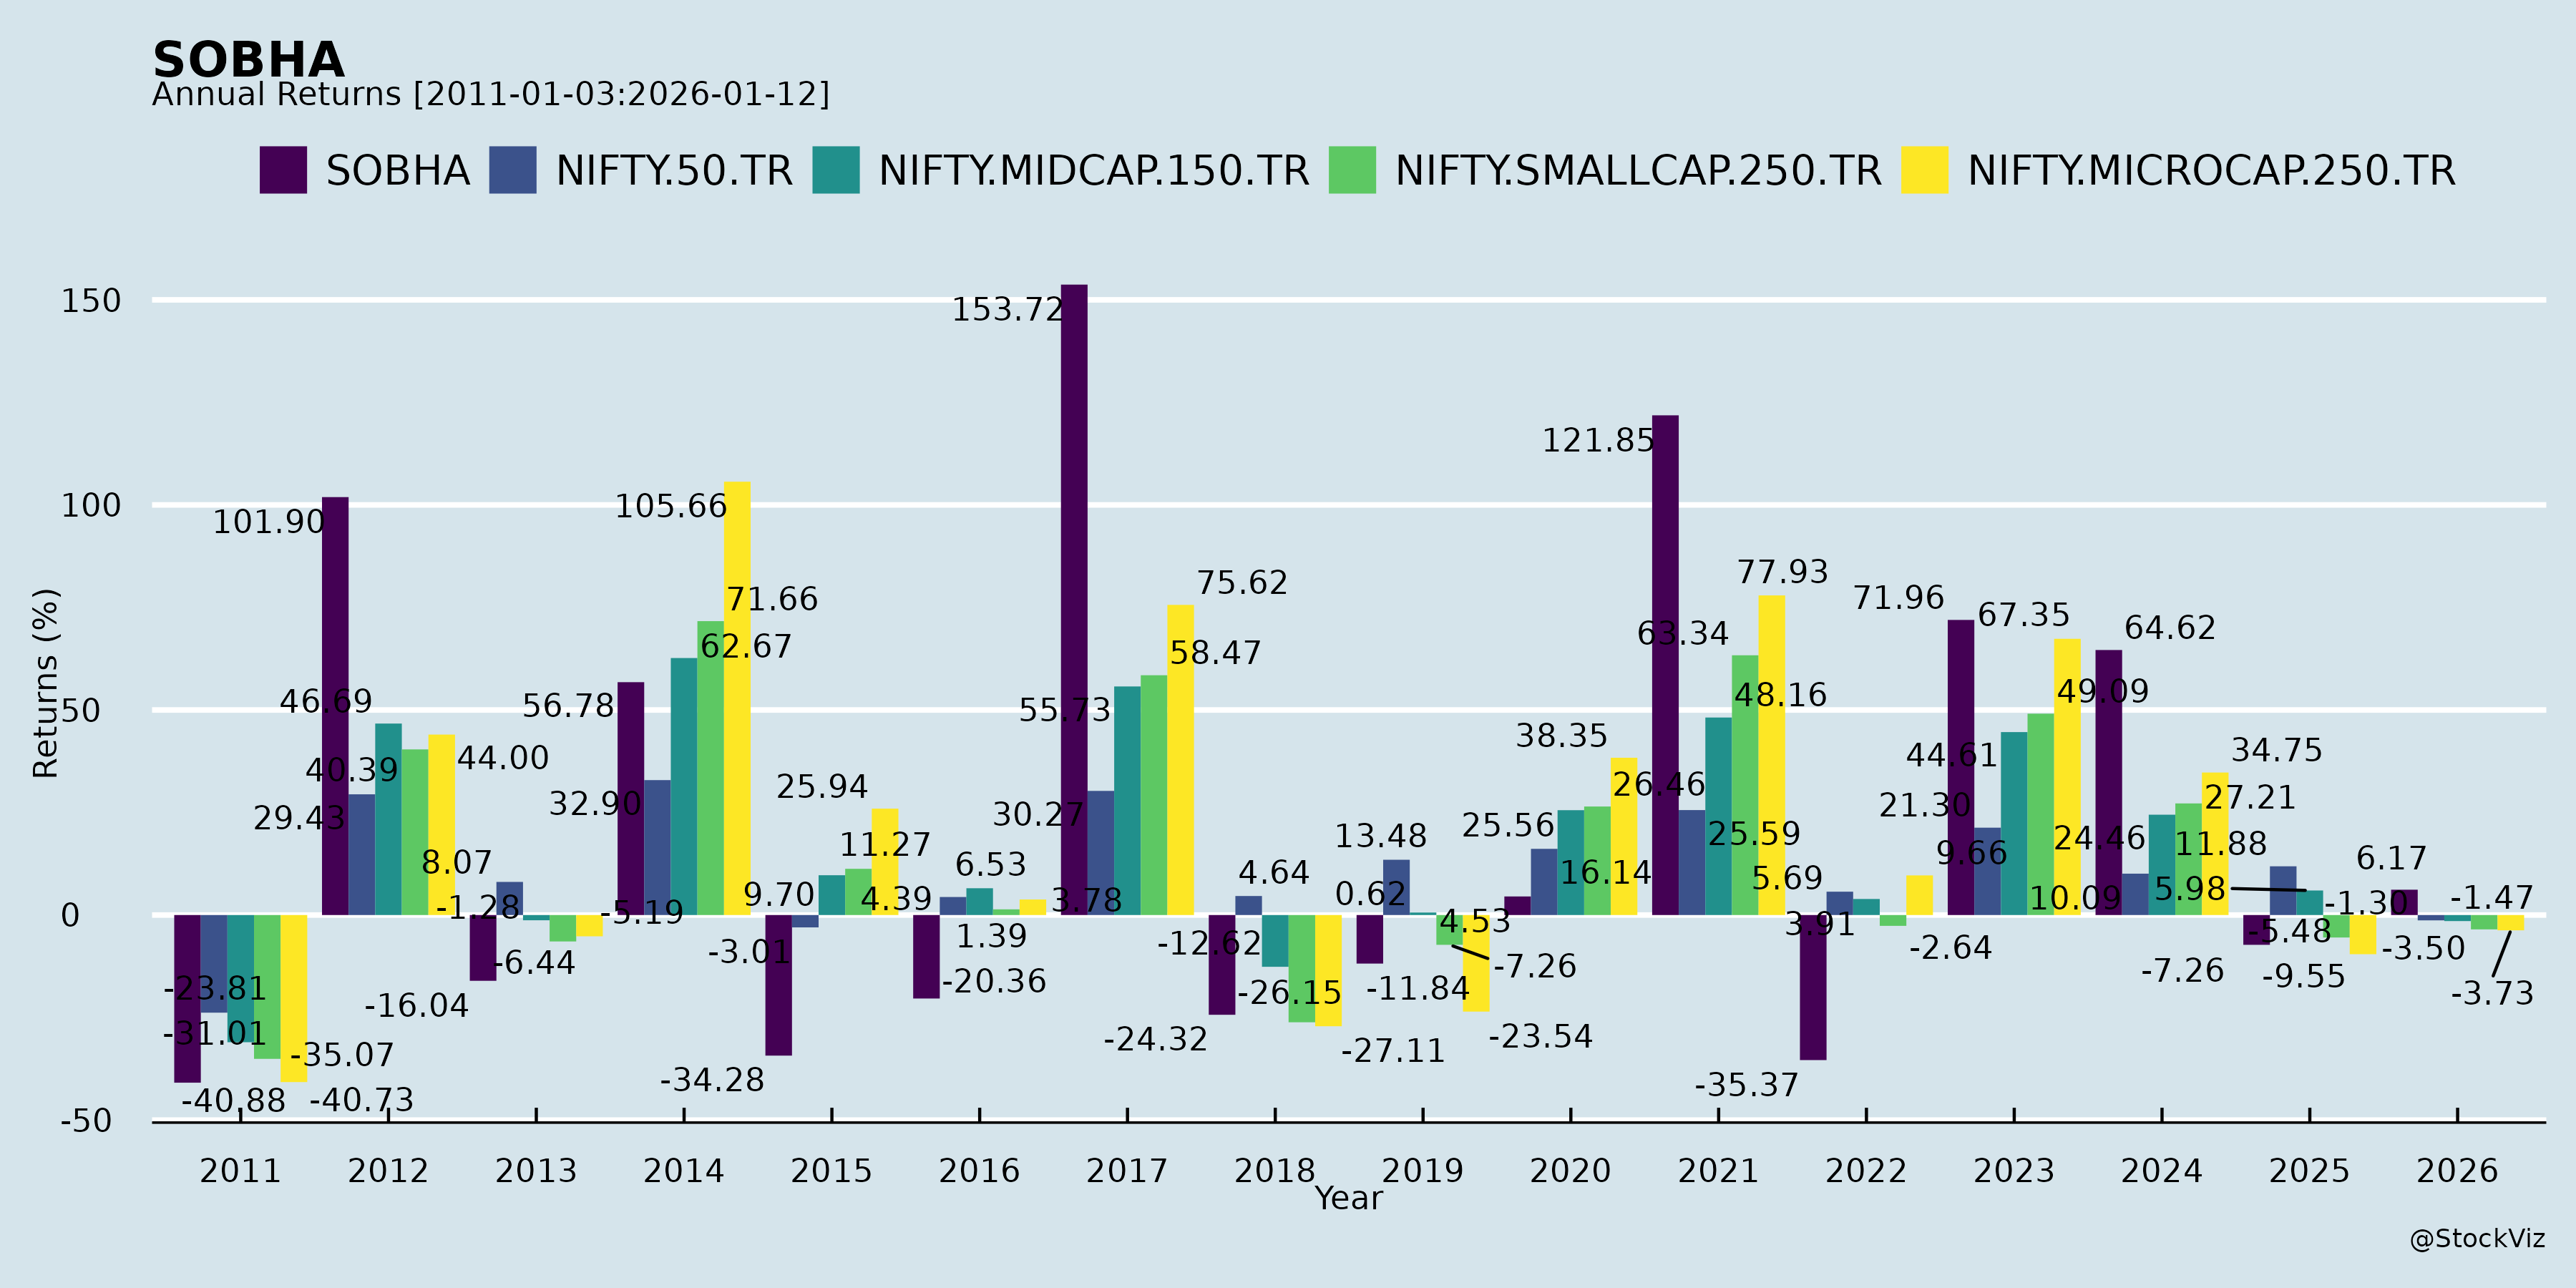
Annual Returns
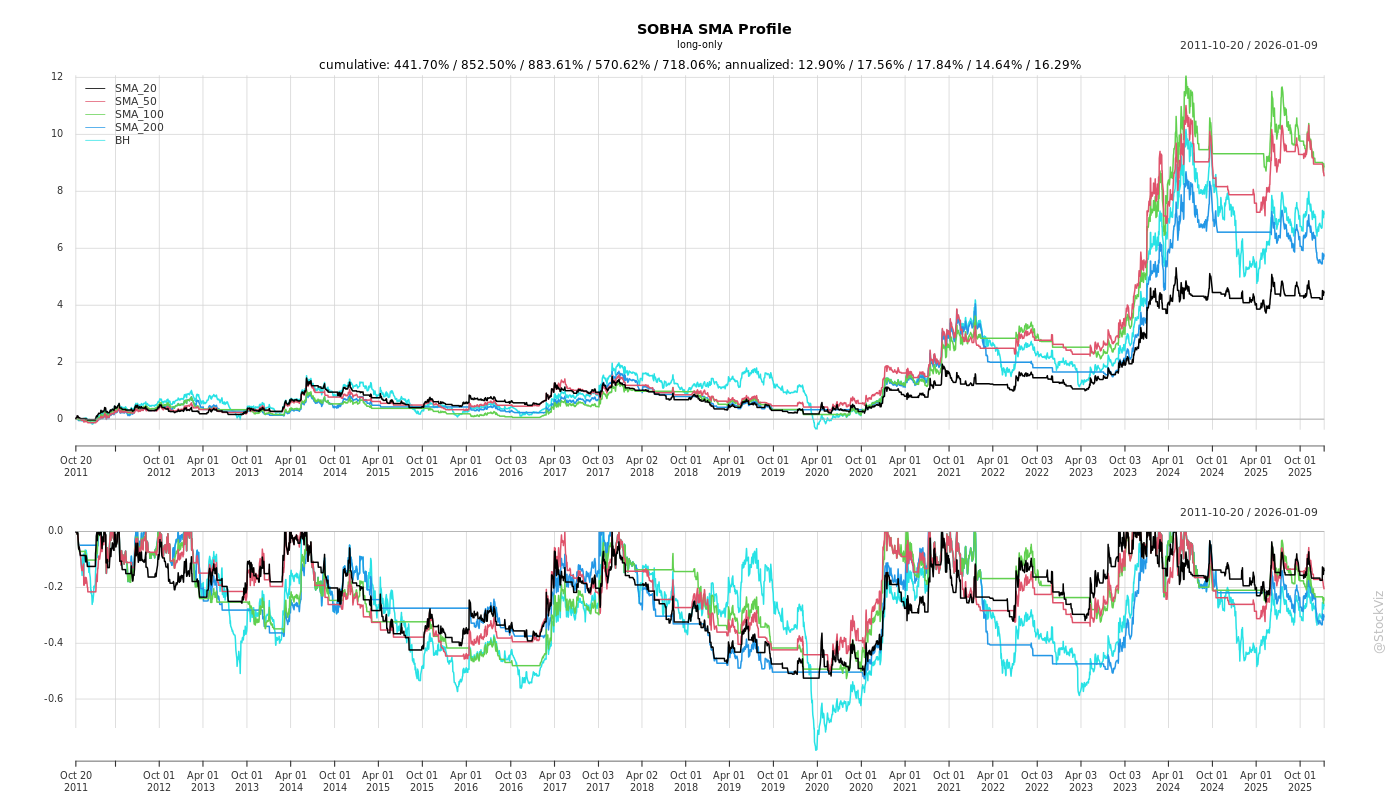
Cumulative Returns and Drawdowns

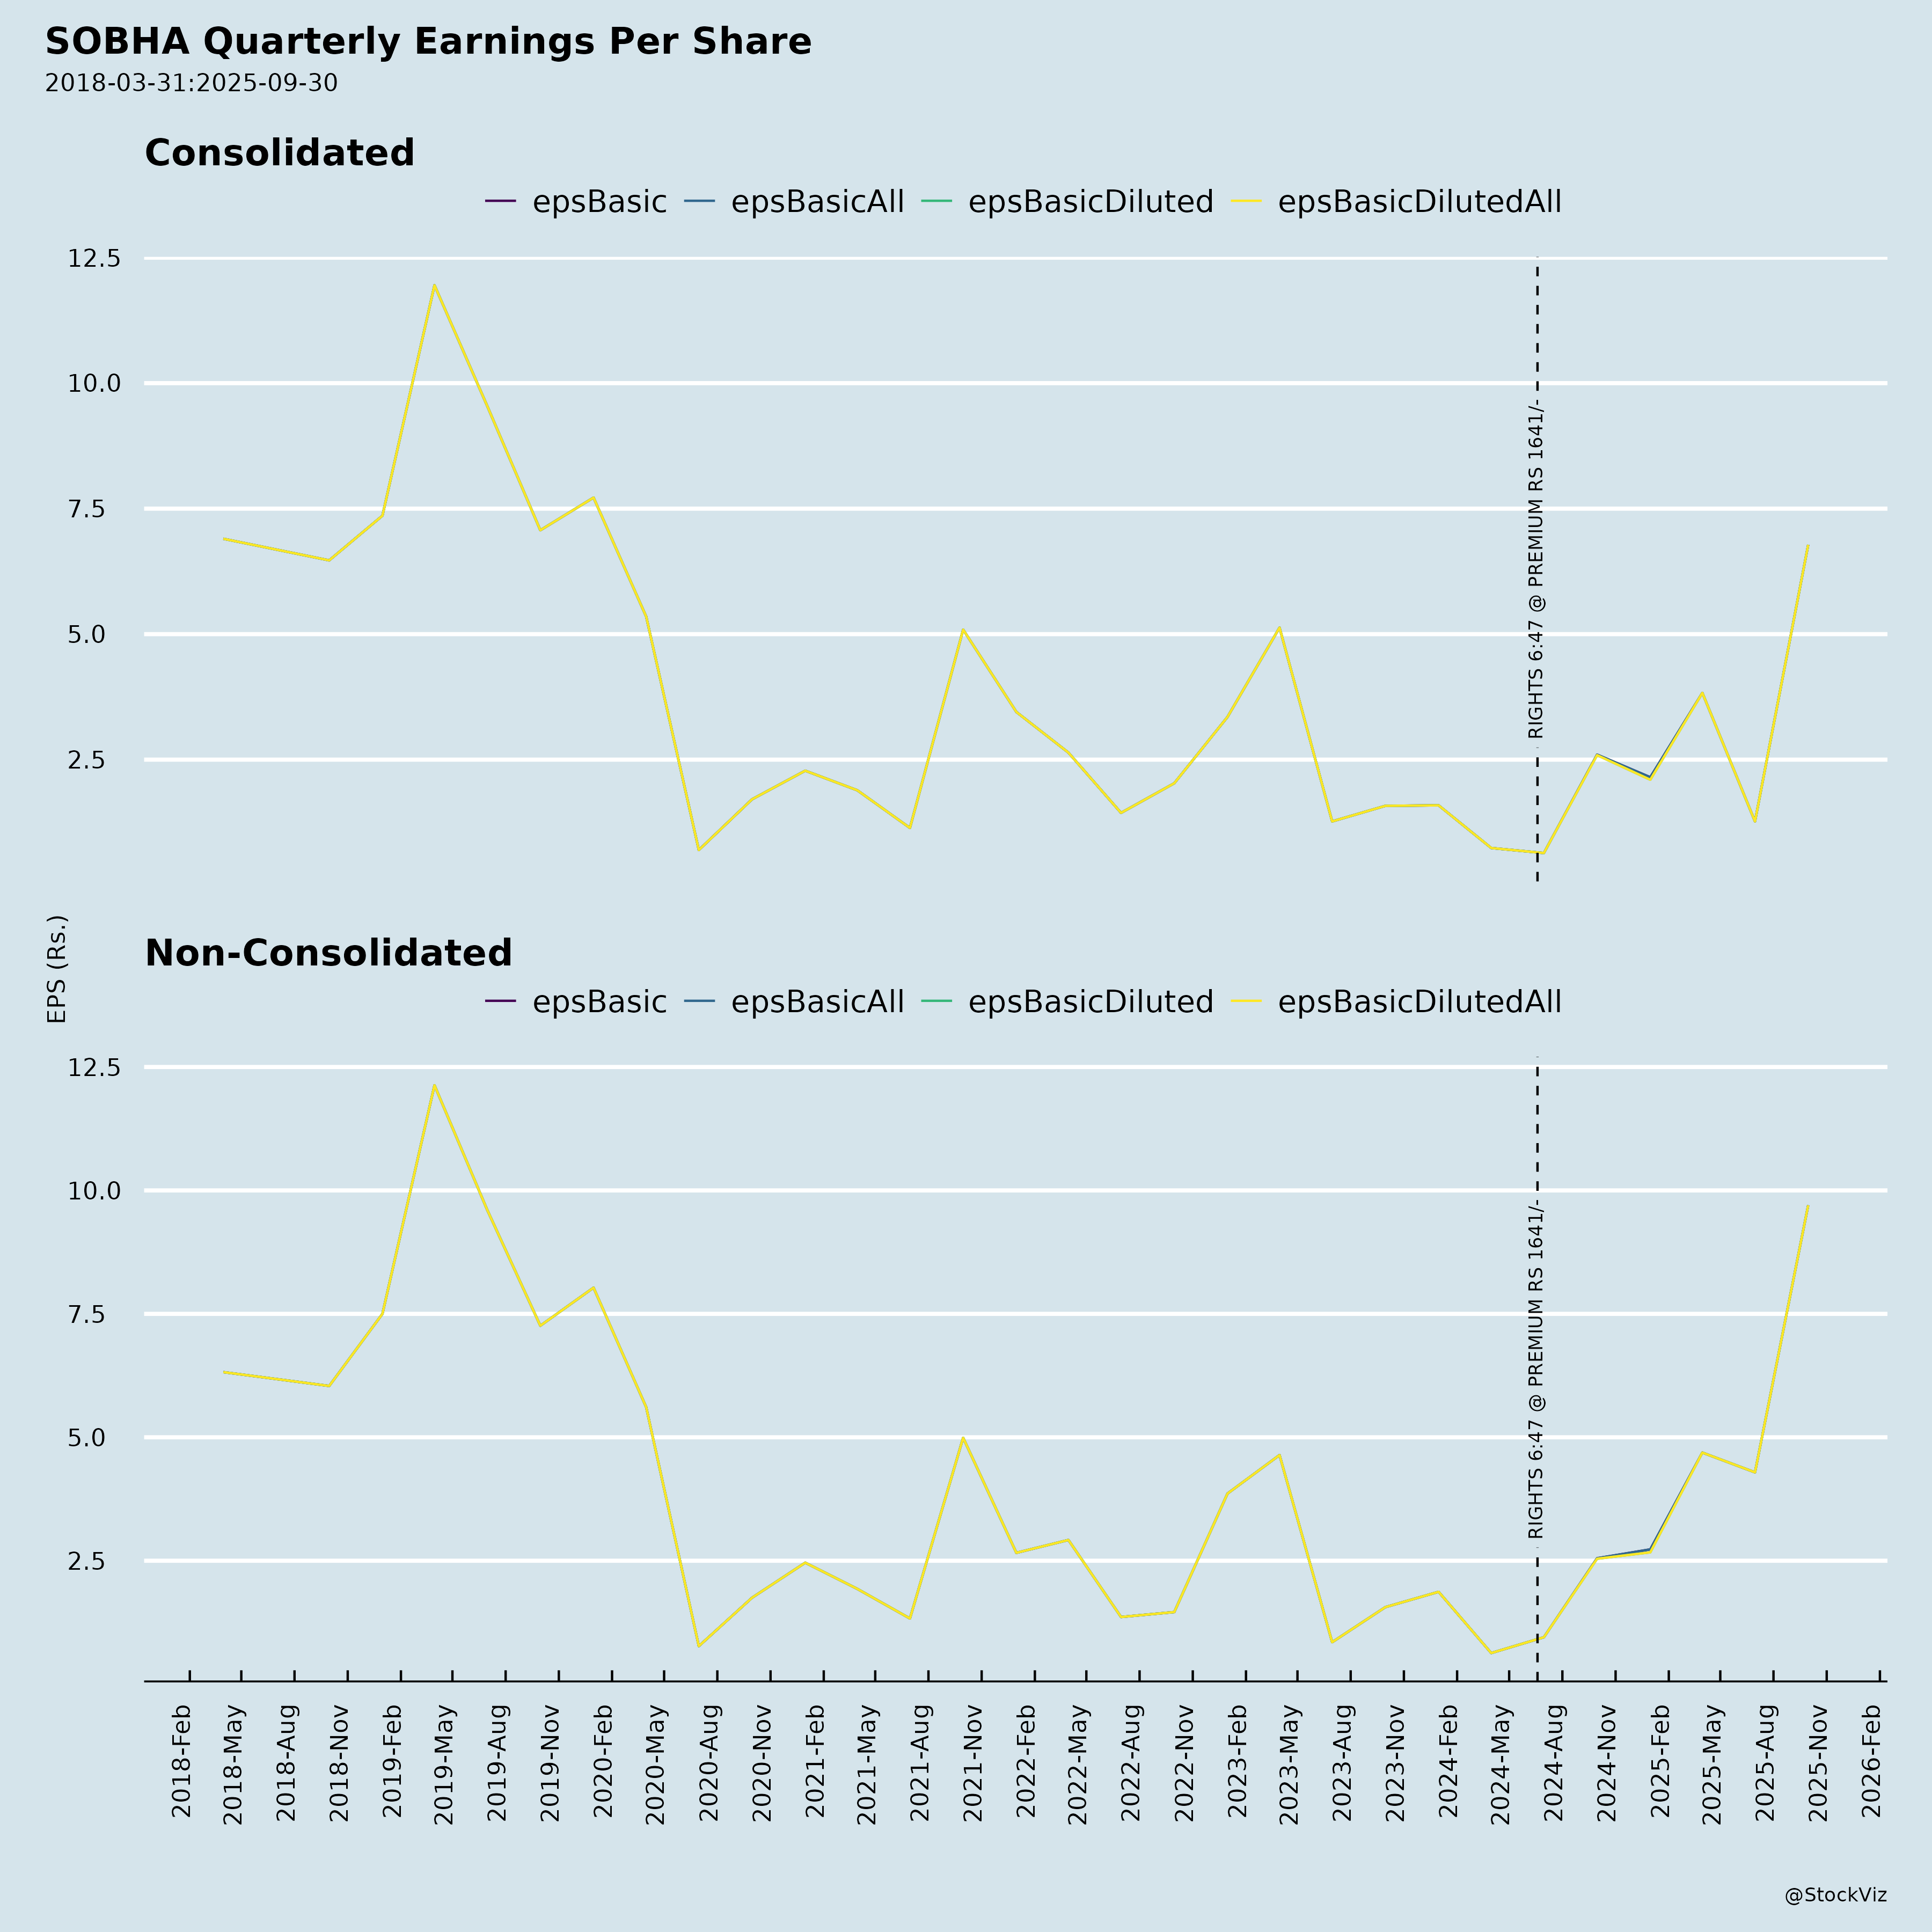
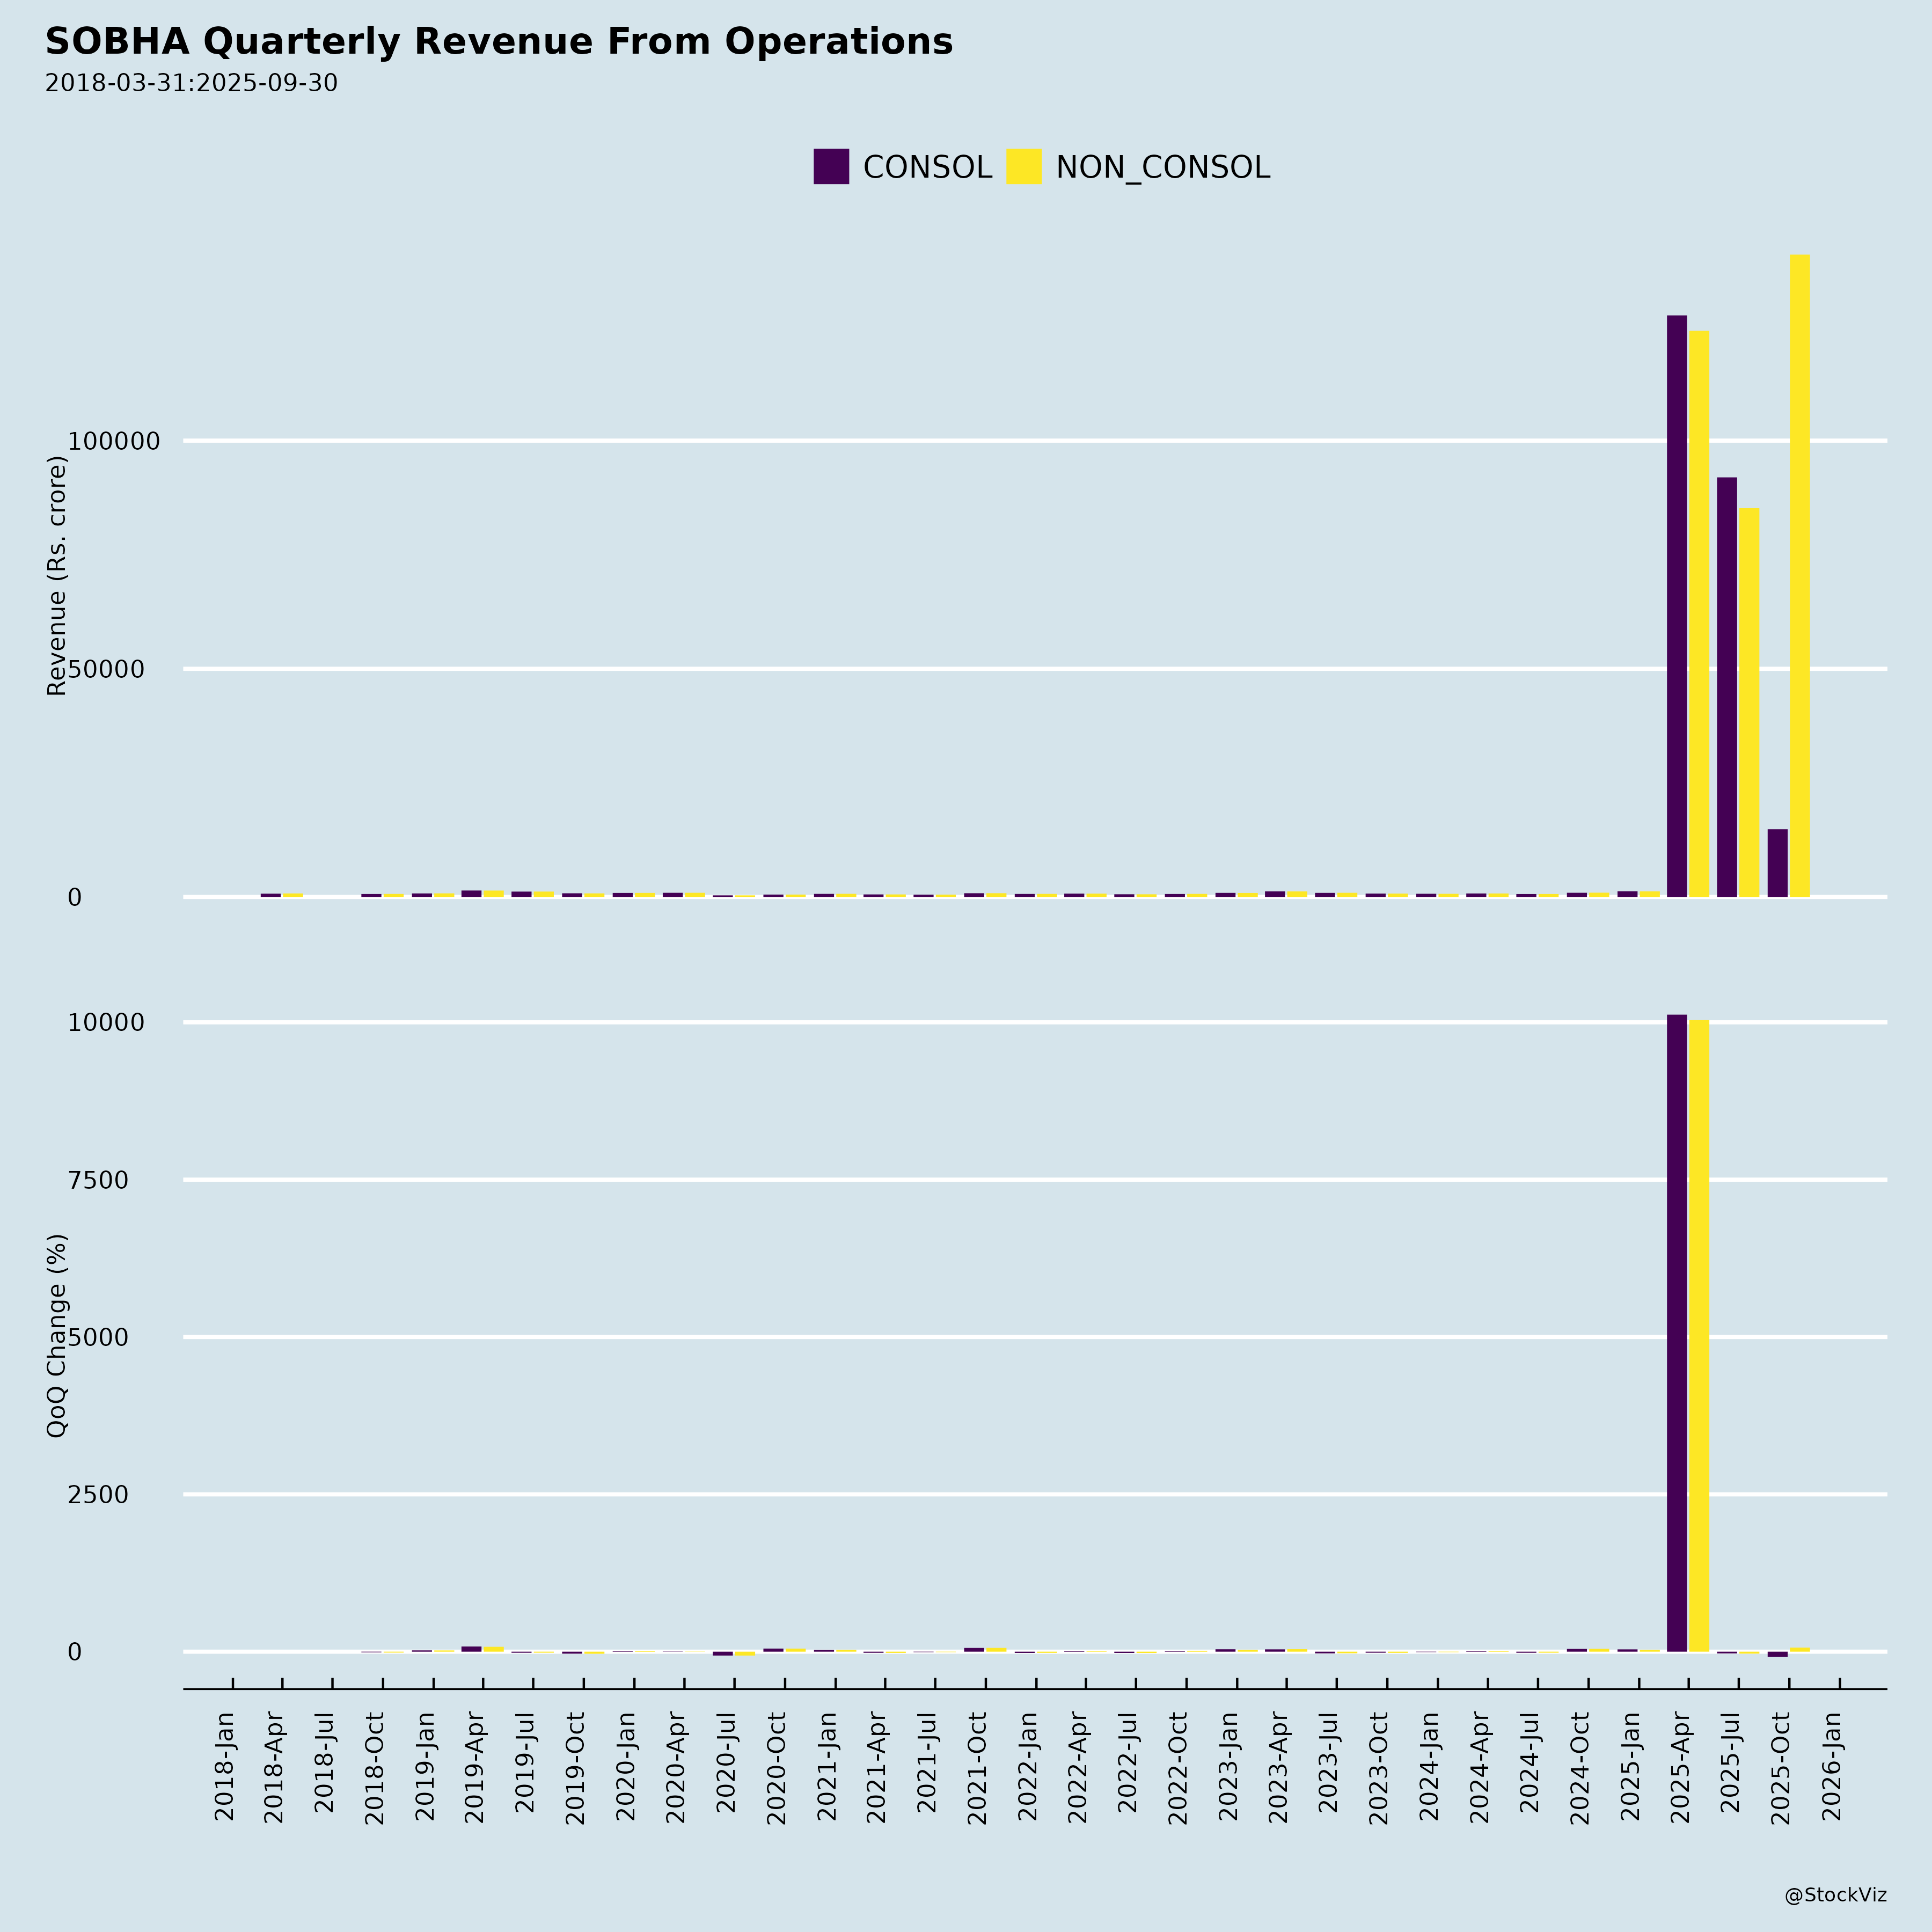
Fundamentals

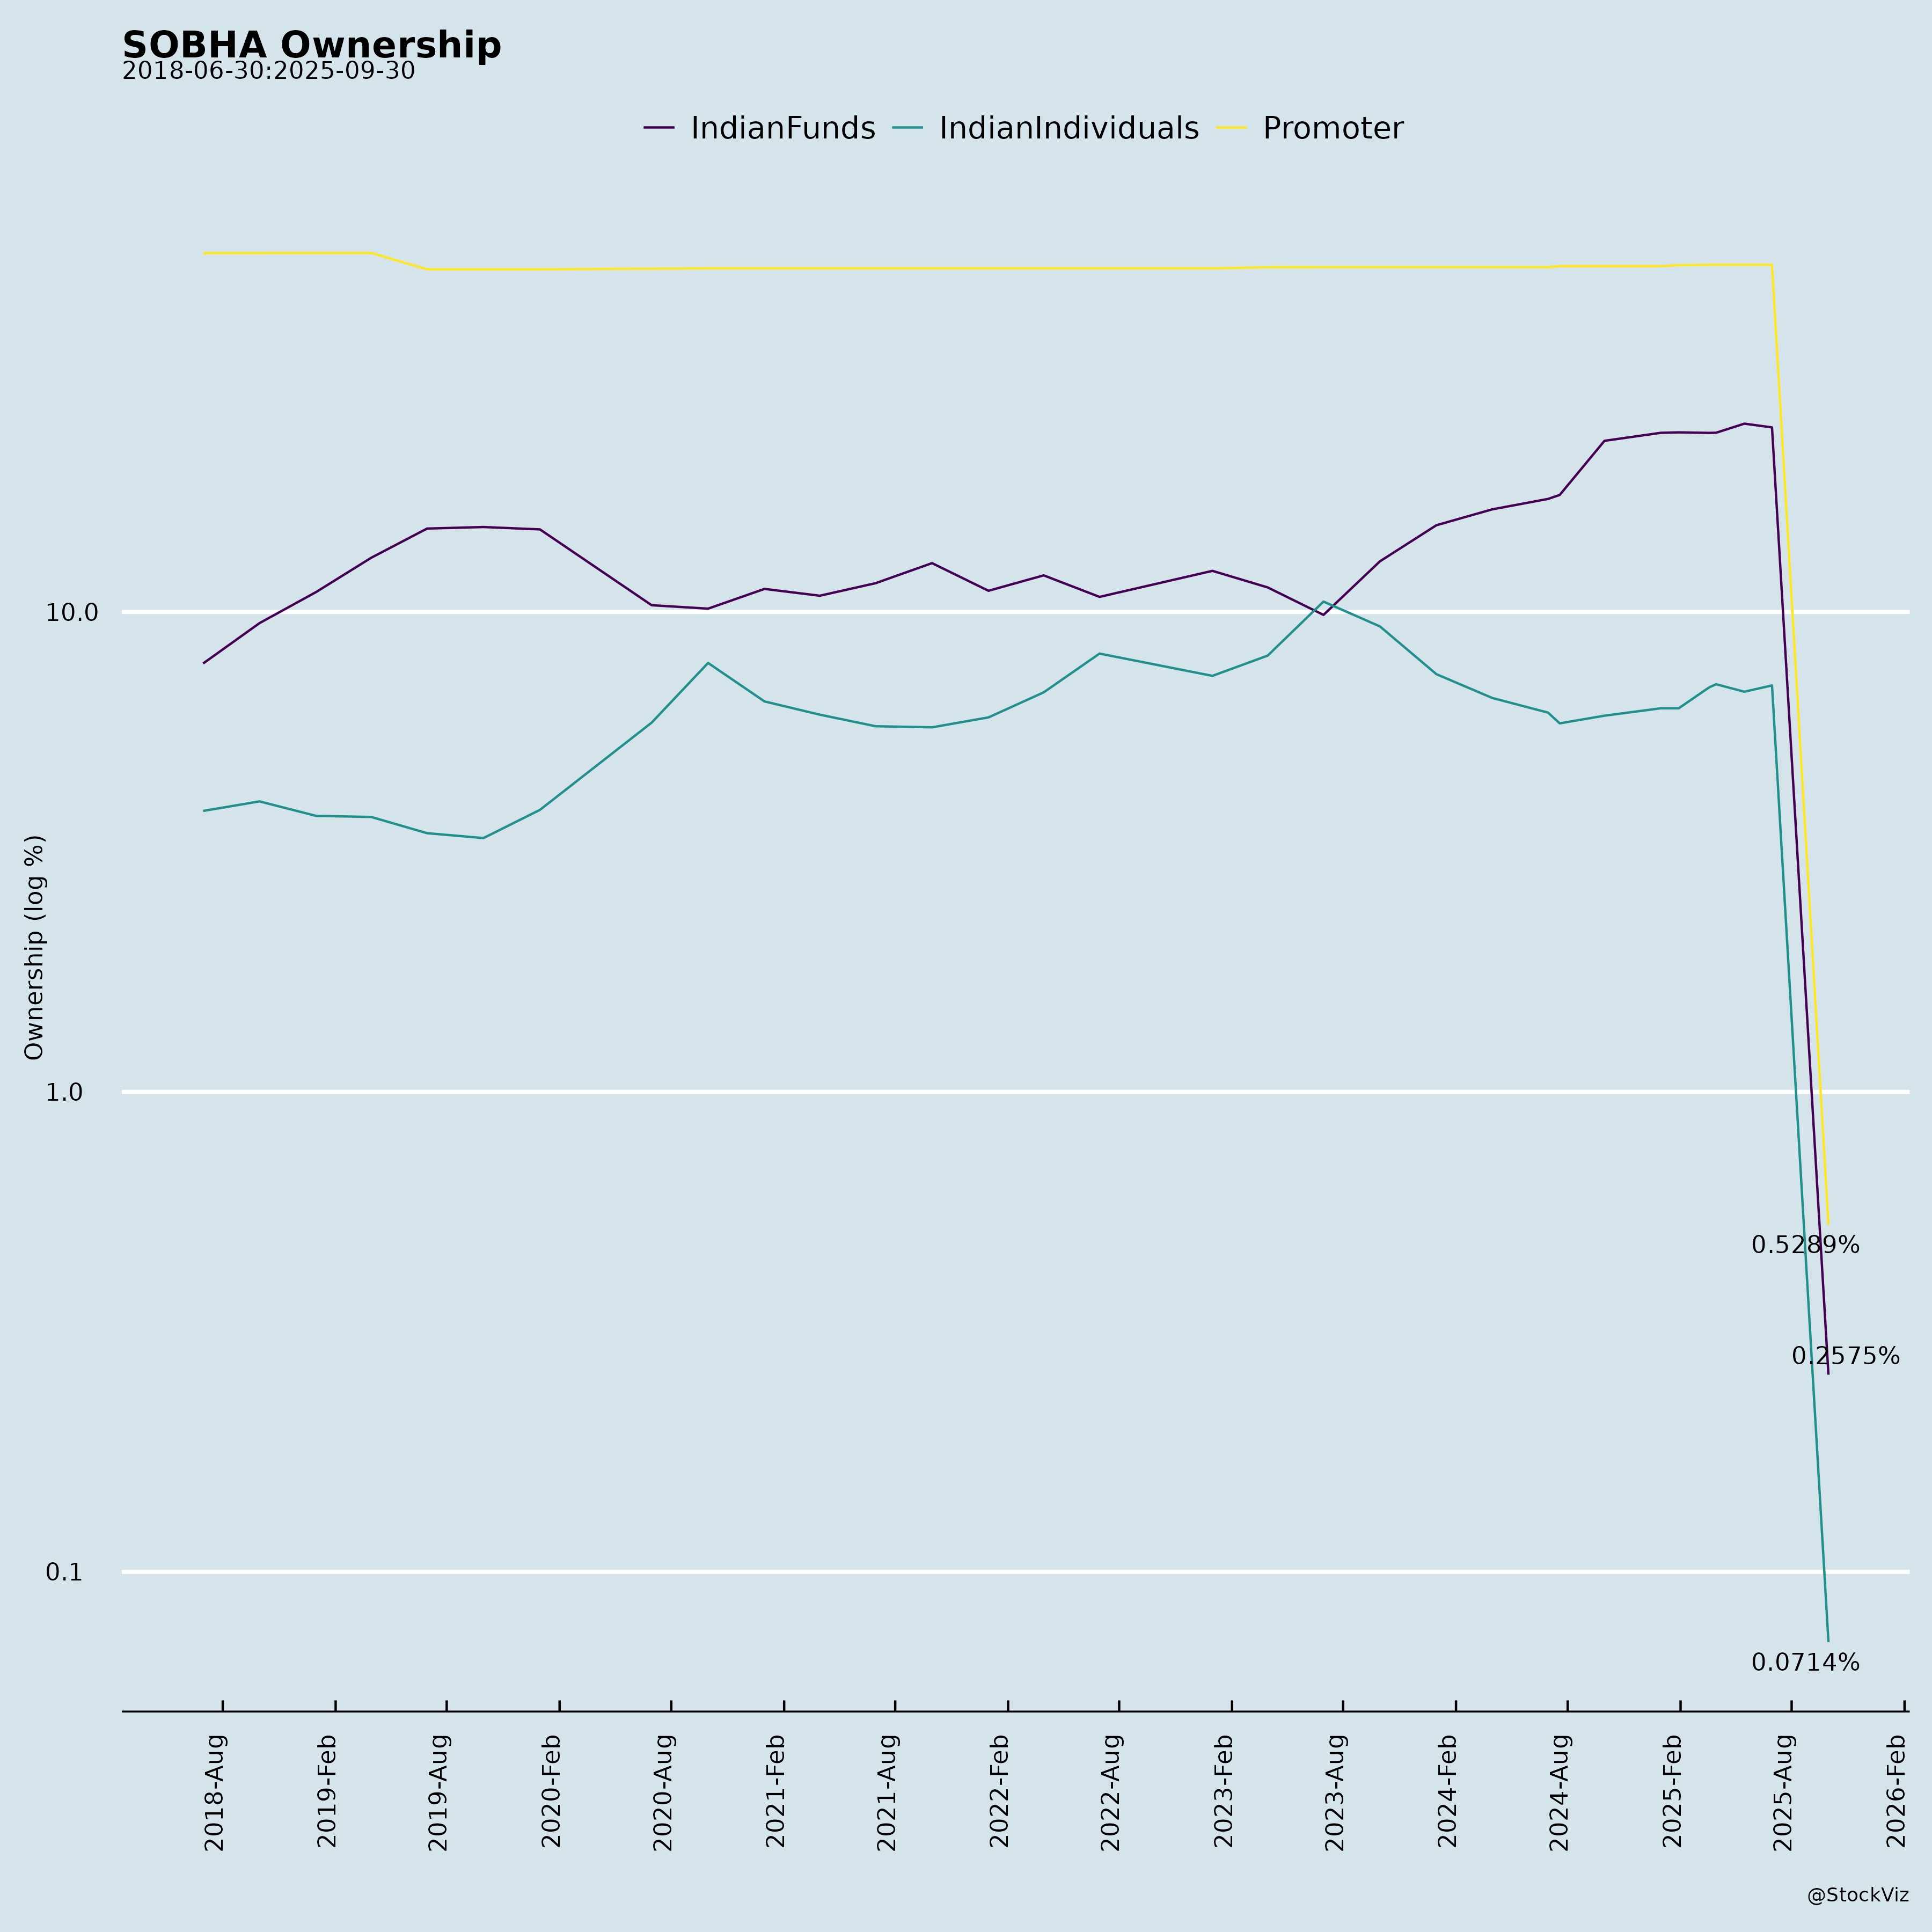
Ownership
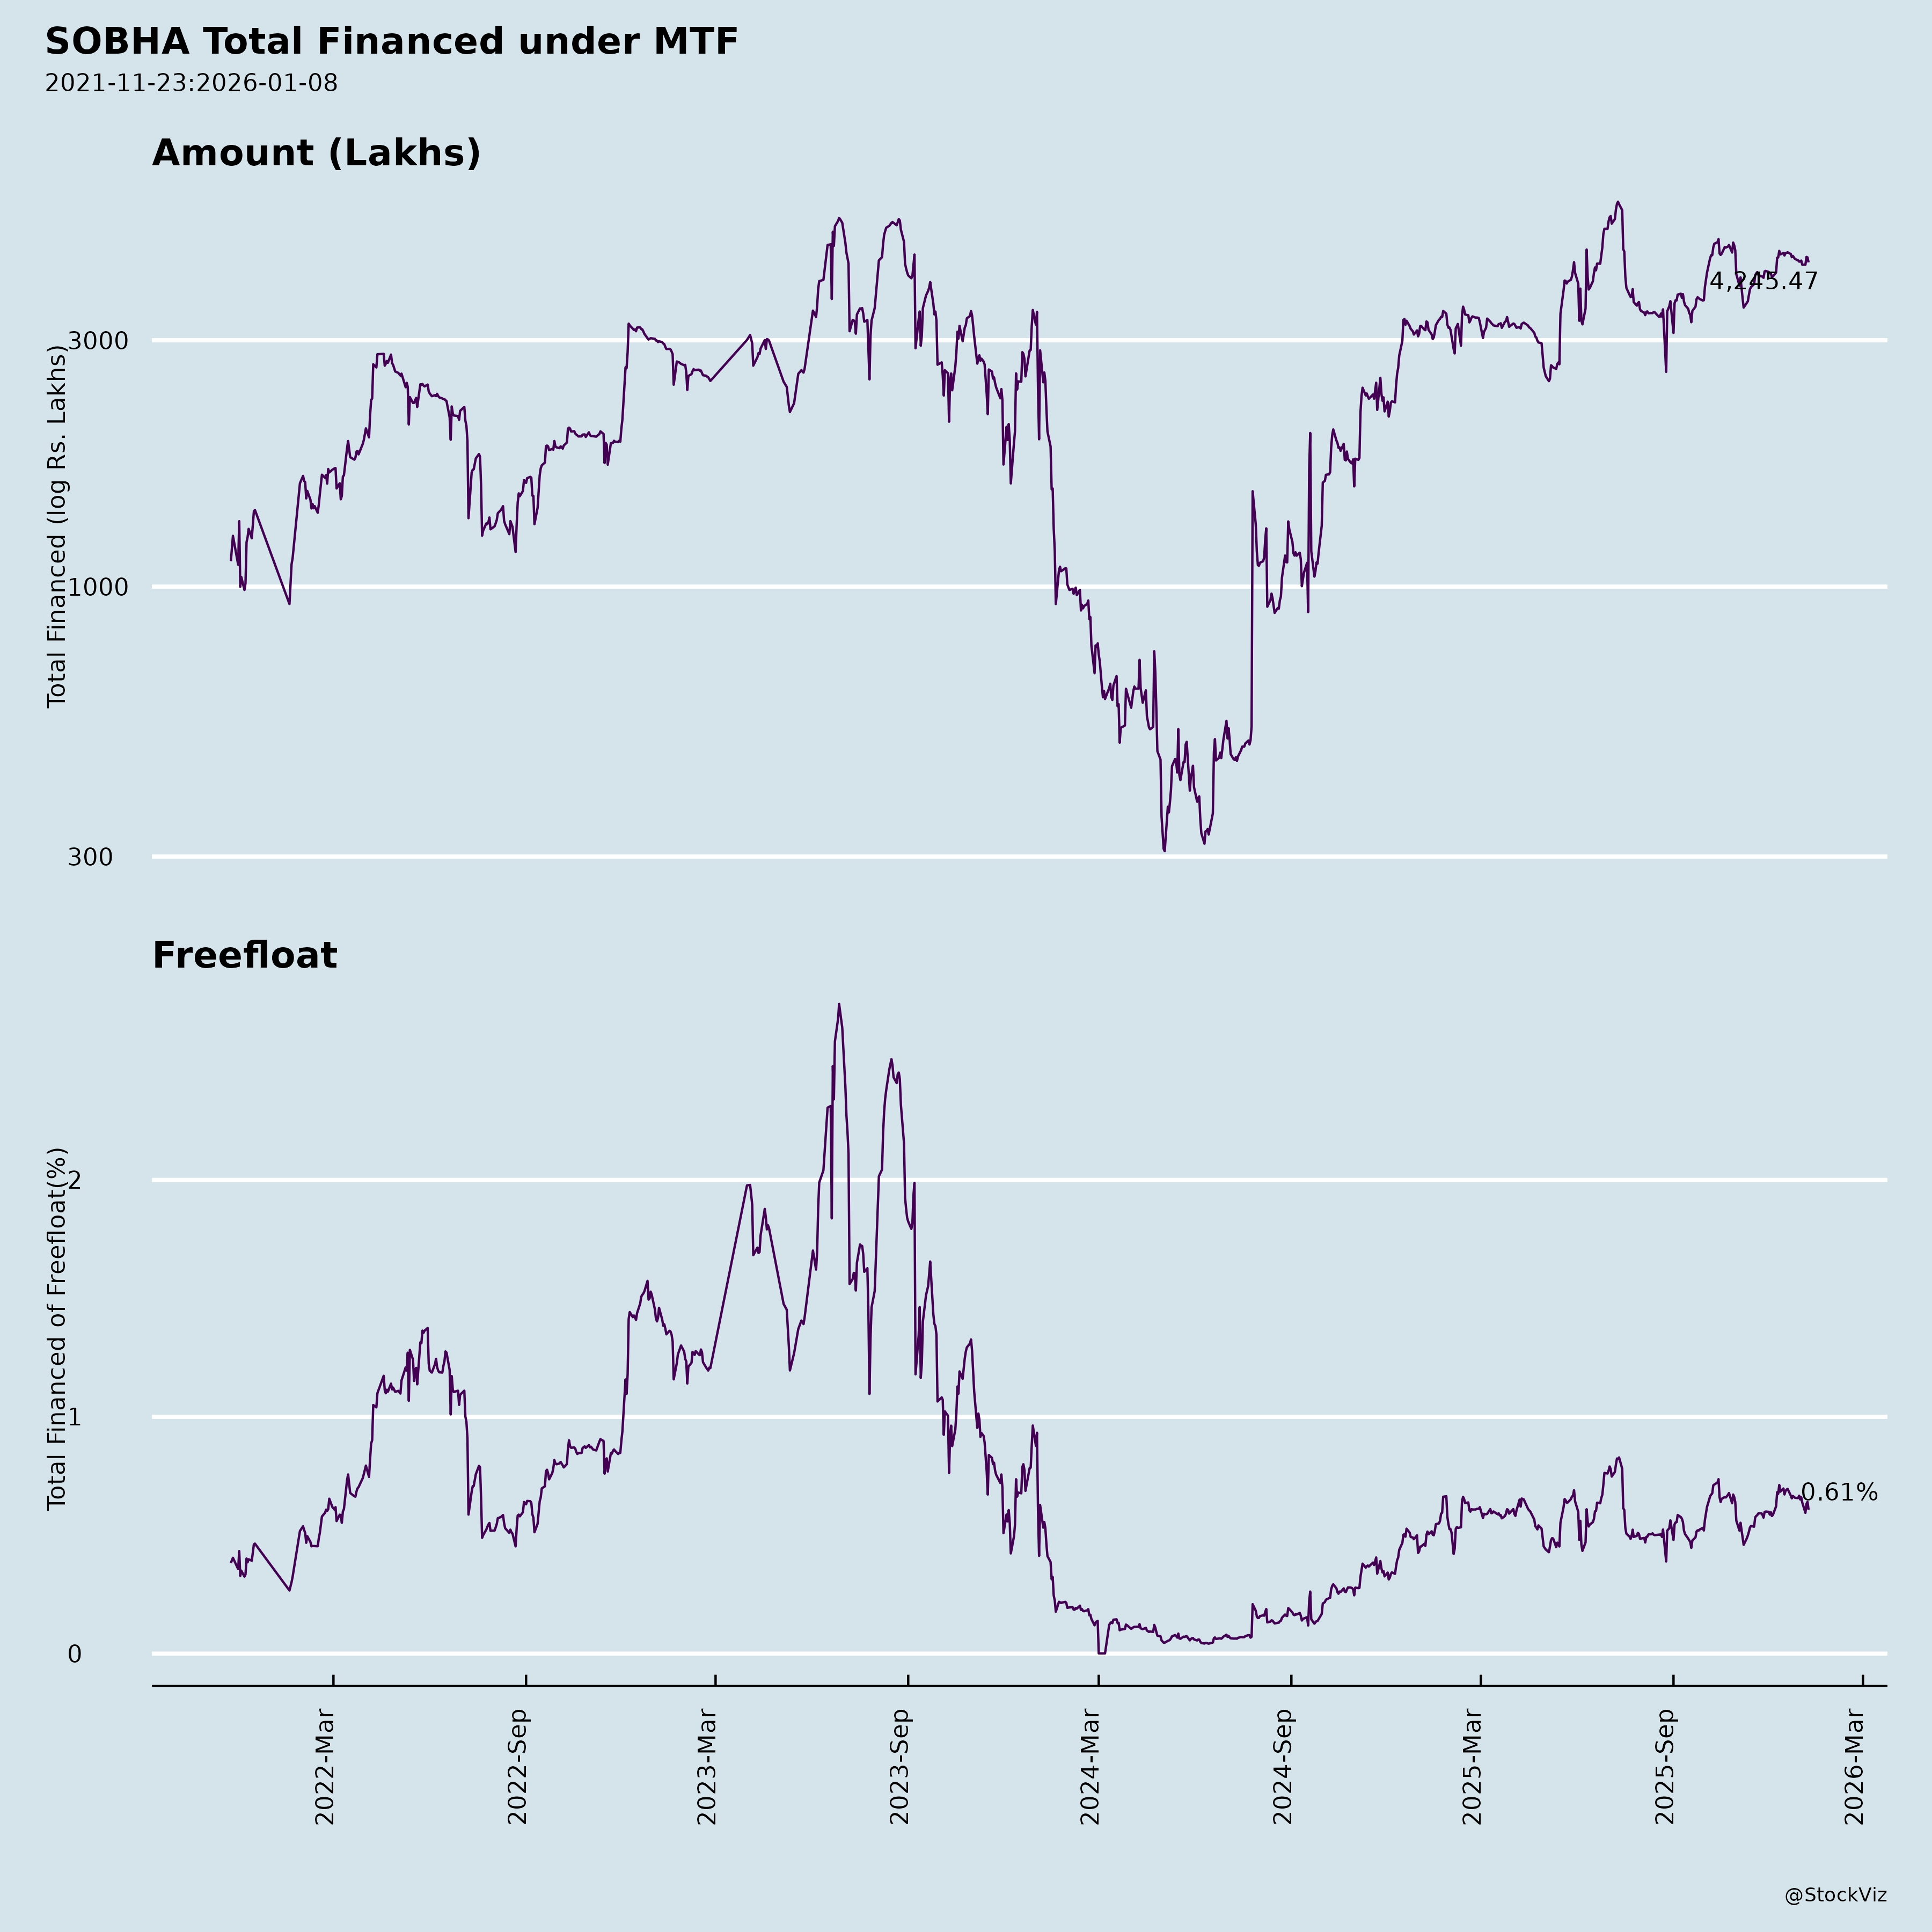
Margined
AI Summary
asof: 2026-09-17
SOBHA Q1 FY27: Analysis of Recent Corporate Announcements
1. Headwinds and Challenges
Collections lagging presales. Real estate collections of ₹1,756 crore in Q1 FY27 grew only ~9.9% YoY against 76% YoY presales growth. Management attributed this to two factors: new sales closing toward the end of the quarter, and milestone billings falling short because some milestones could not be achieved due to labour shortage, mainly in April and May.
Margin pressure. EBITDA margin was 9.7% in Q1 FY27 (₹1.30 bn EBITDA on ₹13.30 bn total income). Management acknowledged this remains low and that Q2 may be similar, with improvement expected only from Q3/Q4 as high-margin projects are completed and handed over.
Lower marginal cashflow disclosure for forthcoming projects. The projected margin cashflow for forthcoming projects was ₹68.3 bn against a higher figure (~₹86 bn) in the previous presentation, despite a smaller saleable value then. Management attributed this to a greater mix of joint development projects (versus owned land such as Hoskote previously) and to GDV now being stated gross, including the landowner share.
Labour cost regulation. A ~60% hike in Karnataka minimum wages in May was noted. Management said most of its technician force is already above minimum wage, the impact is still under evaluation, and it expects to absorb it within project budgets.
Net cash outflow in the quarter. The quarter recorded a net cash outflow of ₹149 crore, driven by ~₹370 crore of land investment and ~₹70 crore of capex, alongside higher sales and marketing spend (₹0.88 bn, +79% YoY). Net operational cashflow declined 21% YoY to ₹312 crore.
Legal and regulatory matters (per auditor notes and financial statement notes). These include: an Enforcement Directorate complaint before the Adjudicating Authority (PMLA) alleging irregularities in a Gurugram joint development project, resulting in provisional attachment of land parcels valued at ~₹2,016.05 million held by Technobuild Developers Private Limited, over which the Company claims absolute rights via an MoU; an appeal filed before the Appellate Tribunal against the confirming order. An Income Tax search under Section 132 in March 2023 led to multiple demand orders for AY 2015-16 to AY 2023-24 aggregating ~₹842 million, against which appeals are pending before CIT (Appeals). A subsidiary (SAPL) faces a terminated project development contract with a compensation demand of ~₹2,956.13 million plus forfeiture claims, under arbitration. A fire NOC/clearance defect at one project led to revocation of the modified sanction plan and occupancy certificate in January 2023, with a stay granted by the Karnataka Appellate Tribunal and a criminal complaint stayed by the Karnataka High Court. Management, based on legal opinions, believes these will not have adverse material impact and no provisions have been made.
Commercial project in Gurgaon removed from pipeline. A ~6 lakh sq ft commercial project in Gurgaon no longer appears in the launch pipeline; management said it is evaluating retaining it for rental income rather than selling, and it will be brought back if a sale model is decided.
2. Tailwinds and Growth Prospects
Record quarterly sales. Q1 FY27 real estate sales value was ₹3,656 crore, up 76% YoY, the highest ever quarterly sales. Volume was 2.34 mn sq ft across 1,432 homes, with average realization of ₹15,655/sq ft. SOBHA share was ₹2,992 crore (81.8% of total sale).
Regional performance. Bangalore contributed 57% of sales (~₹2,067 crore), its best ever quarter, driven by SOBHA One World and Sacred Grove (plotted development). NCR delivered its highest ever quarterly sales (~₹1,384 crore), driven by the SOBHA Crescent launch in Gurgaon. Bangalore and NCR together contributed ~87% of sales.
New launches. Three projects were launched in Q1 FY27 across Bangalore and Gurgaon with combined saleable area of 6.89 mn sq ft and potential sale value of ~₹10,000 crore: SOBHA Crescent (Sector 63A, Gurgaon; 6.2 acres; 869,578 sq ft; 336 homes; sale potential ₹22 bn), SOBHA One World (Hoskote, East Bangalore; 47.4 acres; 5,393,060 sq ft; 3,484 homes; sale potential ₹75 bn), and Sacred Grove (Chikka Tirupati, Bangalore; 26.1 acres; 625,172 sq ft; 388 plots; sale potential ₹2.5 bn). In SOBHA One World, 3.4 mn sq ft was released and ~40% of that was sold at launch; in SOBHA Crescent, ~60% was sold in Q1.
Forthcoming launch pipeline. Total forthcoming pipeline is 20.77 mn sq ft across 17 projects with a sale potential of ₹295.57 bn. Management is confident of launching 9 projects aggregating ~8.2 mn sq ft during the remaining FY27: 4 projects in Bangalore (~3 mn sq ft), 2 in NCR (~2 mn sq ft), 1 in Hyderabad (~1.7 mn sq ft), and 2 in Kerala (~1.5 mn sq ft). At current average realization, this translates to ~₹12,000 crore of GDV. About 3 projects are expected in the current quarter (two in Kerala and a plotted development in Bangalore, plus a small 0.4 mn sq ft Bangalore project), with the remainder in Q3 and Q4. SOBHA Crescent Phase 2 is expected in late Q3 or early Q4.
Unsold inventory and revenue visibility. Unsold inventory was 14.94 mn sq ft as of end-Q1 FY27. Revenue yet to be recognized from sales already done was ₹20,553 crore. Total inventory visibility (completed, ongoing released/unreleased, and forthcoming residential) was 35.71 mn sq ft with a total sales value of ₹531.99 bn.
Projected cashflow. Total receivables plus unsold value of ~₹31,000 crore against estimated remaining cost of ~₹19,000 crore yields projected marginal cashflow of ~₹12,000 crore from completed and ongoing projects. The presentation states total marginal cashflow (completed, ongoing and forthcoming) of ₹194.81 bn.
Completions and delivery. 677 homes (1.08 mn sq ft) were completed in Q1 FY27. Management plans 6–6.5 mn sq ft of completions in FY27 versus ~5.4 mn sq ft last year, ~20% higher.
Balance sheet strength. Net cash position of ₹659 crore as of 30 June 2026; gross debt ₹1,110 crore; cash and equivalents ₹1,769 crore; net debt-to-equity of negative 0.14; average borrowing cost 7.62%. Credit rating AA- with positive outlook (Ind-RA upgraded outlook; ICRA AA- Stable). Management envisages net debt at about zero level for the year.
Land bank and new market entry. Developable land bank of 361 acres with 36.94 mn sq ft potential (SOBHA share 76.0%), plus 1,749 acres under various stages of consolidation, monetization and self-use. The company entered two new markets in 2026 — Greater Noida (SOBHA Aurum) and Mumbai (SOBHA Inizio). In Q1, it acquired a ~1.3-acre Mumbai land parcel for ~₹180 crore and invested in a Greater Noida joint development; combined GDV for these is ~₹2,700–3,000 crore. The Greater Noida project is targeted for launch this financial year; the Mumbai project’s timeline depends on approvals and is not included in the 8.2 mn sq ft FY27 launch projection.
Other businesses. Contractual, manufacturing and retail revenue was ₹171 crore in Q1 FY27 (vs ₹162 crore YoY); commercial rental total income was ~₹23 crore; NOI from the operating commercial portfolio was ₹146 mn. Management expects other-business revenue for the year to be similar to last year.
Fundraising capacity. The Board approved issuance of non-convertible debentures up to ₹1,000 crore in tranches on a private placement basis, with terms to be finalized by the Investments and Borrowings Committee. Management expects to use this over the next couple of quarters, in at least two tranches, as acquisition opportunities firm up.
3. Key Risks
- Execution and approval risk: The Mumbai land acquisition timeline is uncertain pending approvals; management has excluded it from FY27 launch projections. Launch timing generally depends on preparation and approvals.
- Margin recovery risk: The expected sequential margin improvement to ~17–20% by Q4 FY27 depends on completing high-margin projects and handing over; Q2 may remain similar to Q1.
- Collection risk: Milestone billing and collection shortfalls (labour availability) could persist; collections in Q1 grew only ~9.9% YoY against much faster presales.
- Regulatory and legal risk: The PMLA attachment matter, Income Tax demand orders, the SAPL arbitration, and the fire NOC/occupancy certificate proceedings remain pending; outcomes and durations are uncertain, and recoverability of the ~₹2,016.05 million land advance against provisionally attached parcels is described as presently uncertain.
- Cost inflation risk: The Karnataka minimum wage hike impact is still being assessed.
- Capital allocation risk: Higher land investment (₹370 crore in Q1; potentially ₹1,500–1,600 crore for the year if identified opportunities close) contributed to the quarterly net cash outflow; the NCD issuance adds funding capacity but also leverage if drawn.
- Joint development mix: The shift toward joint development projects reduces SOBHA’s share of marginal cashflow relative to owned-land projects.
4. Management Guidance Versus Observed Performance
Presales growth. Management guided at least 30% growth in presales for FY27 (stated at the end of the last financial year), with the possibility of doing slightly better if all launches happen on time. Observed: Q1 FY27 presales grew 76% YoY to ₹3,656 crore, well ahead of the full-year guidance pace.
Operating cashflow. In response to a question on the ~₹2,000 crore operating cashflow target, management said it is an average over the next few years at an aggregate level and that the company should be able to touch that number as it grows. Observed: Q1 FY27 net operational cashflow was ₹312 crore, down 21% YoY.
Completions. Management plans 6–6.5 mn sq ft of completions in FY27 versus ~5.4 mn sq ft in FY26 (~20% higher). Observed: 1.08 mn sq ft completed in Q1 FY27.
Launches. Management is confident of launching 9 projects (~8.2 mn sq ft) in the remaining FY27, with ~3 projects in the current quarter and the rest in Q3/Q4. Observed: 6.89 mn sq ft launched in Q1 FY27 across 3 projects.
Margins. Management expects margins to be significantly better in H2 FY27, sequentially improving from Q3, reaching closer to 17–20% by the end of Q4, from 9.7% EBITDA in Q1 FY27; Q2 may be similar to Q1. Observed: Q1 FY27 EBITDA margin was 9.7% (Q1 FY26: 8.1%; Q4 FY26: 9.6%).
Net debt. Management envisages net debt at about zero level for the year. Observed: net cash position of ₹659 crore as of 30 June 2026 (net debt negative ₹6.59 bn), with a net cash outflow of ₹149 crore in the quarter.
Land investment. Management indicated FY27 land payments could be closer to ₹1,500–1,600 crore if identified Bangalore and NCR opportunities are completed, versus ~₹1,160 crore last year. Observed: ~₹370 crore invested in land in Q1 FY27, including the Mumbai acquisition and Greater Noida investment.
Other businesses. Management expects other-business revenue for FY27 to be similar to last year. Observed: Q1 FY27 contractual and manufacturing revenue was ₹171 crore versus ₹162 crore in Q1 FY26.
Financial performance. Total income grew 47.6% YoY to ₹13.30 bn; real estate revenue grew 60.4% YoY to ₹11.07 bn; EBITDA grew 78.1% YoY to ₹1.30 bn; PAT grew 264.3% YoY to ₹0.51 bn (₹508 mn consolidated, ₹507 mn after OCI). PBT margin was 5.2% and PAT margin 3.8%.
Broker Narrative
The broker narrative stayed bullish on pre-sales and launches—from record FY23 pre-sales and a planned 7–8 msf FY24 pipeline to 1HFY27 best-ever half-yearly and quarterly pre-sales, a 12 msf 2HFY27 pipeline, and expansion into Greater Noida, Mumbai, Hyderabad, Chennai and Kerala—while repeatedly pushing margin recovery from the initially expected post-4QFY24 inflection to 2HFY27 and FY28. What changed was the financial profile: early reports emphasized record collections and net debt reduced to INR16.4b (0.66x equity), but the last report shows 1HFY27 revenue down 1%, PAT down 3%, EBITDA margins still muted at 6.5%, operating cash flow down 17%, gross debt up Rs5.0bn, and net cash down Rs4.3bn. As a result, broker calls shifted from large 2023 SUCCESS outcomes to repeated DISAPPOINTMENTs and negative actual returns across 2024–2026 despite maintained Buy ratings.
Fears that came true
- Subdued EBITDA margins (~10%) from contractual-segment losses and low-margin project recognition persisted, with 1HFY27 margins still muted at 6.5% and recovery deferred to 2HFY27/FY28, overlapping the 2024–2026 DISAPPOINTMENT calls and negative actual returns.
- Higher construction outflows pressuring operating cash flow recurred, as 1HFY27 net operating cash flow fell 17% YoY to Rs7.5bn alongside a 1% YoY revenue decline and 3% YoY PAT decline.
- Balance-sheet deterioration materialized as gross debt increased Rs5.0bn YoY to Rs15.1bn and net cash decreased Rs4.3bn YoY, contrasting with the earlier net-debt reduction story and coinciding with 2026 negative-return outcomes.
Optimism that failed
- The expected margin recovery—residential EBITDA above 15%, PAT in double digits, and overall margins more than doubling after 4QFY24—did not materialize, as 1HFY27 EBITDA remained at 6.5% and the inflection was pushed to FY28.
- The record collections and net-debt reduction thesis (INR14.2b collections in 4QFY23; net debt of INR16.4b at 0.66x equity) reversed, with 1HFY27 operating cash flow down 17%, gross debt up Rs5.0bn, and net cash down Rs4.3bn.
Broker Timeline
35 broker calls · 2023-05-29 to 2026-10-20
CNBC-TV18: ratings, targets and commentary
No recorded CNBC-TV18 statements for this ticker.
Management comments
No recorded management comments with an explicit designation and affiliation for this ticker.
Copyright © 2023 SAS Data Analytics Pvt. Ltd. All rights reserved.