SCI
Equity Metrics
November 18, 2026
Shipping Corporation Of India Limited
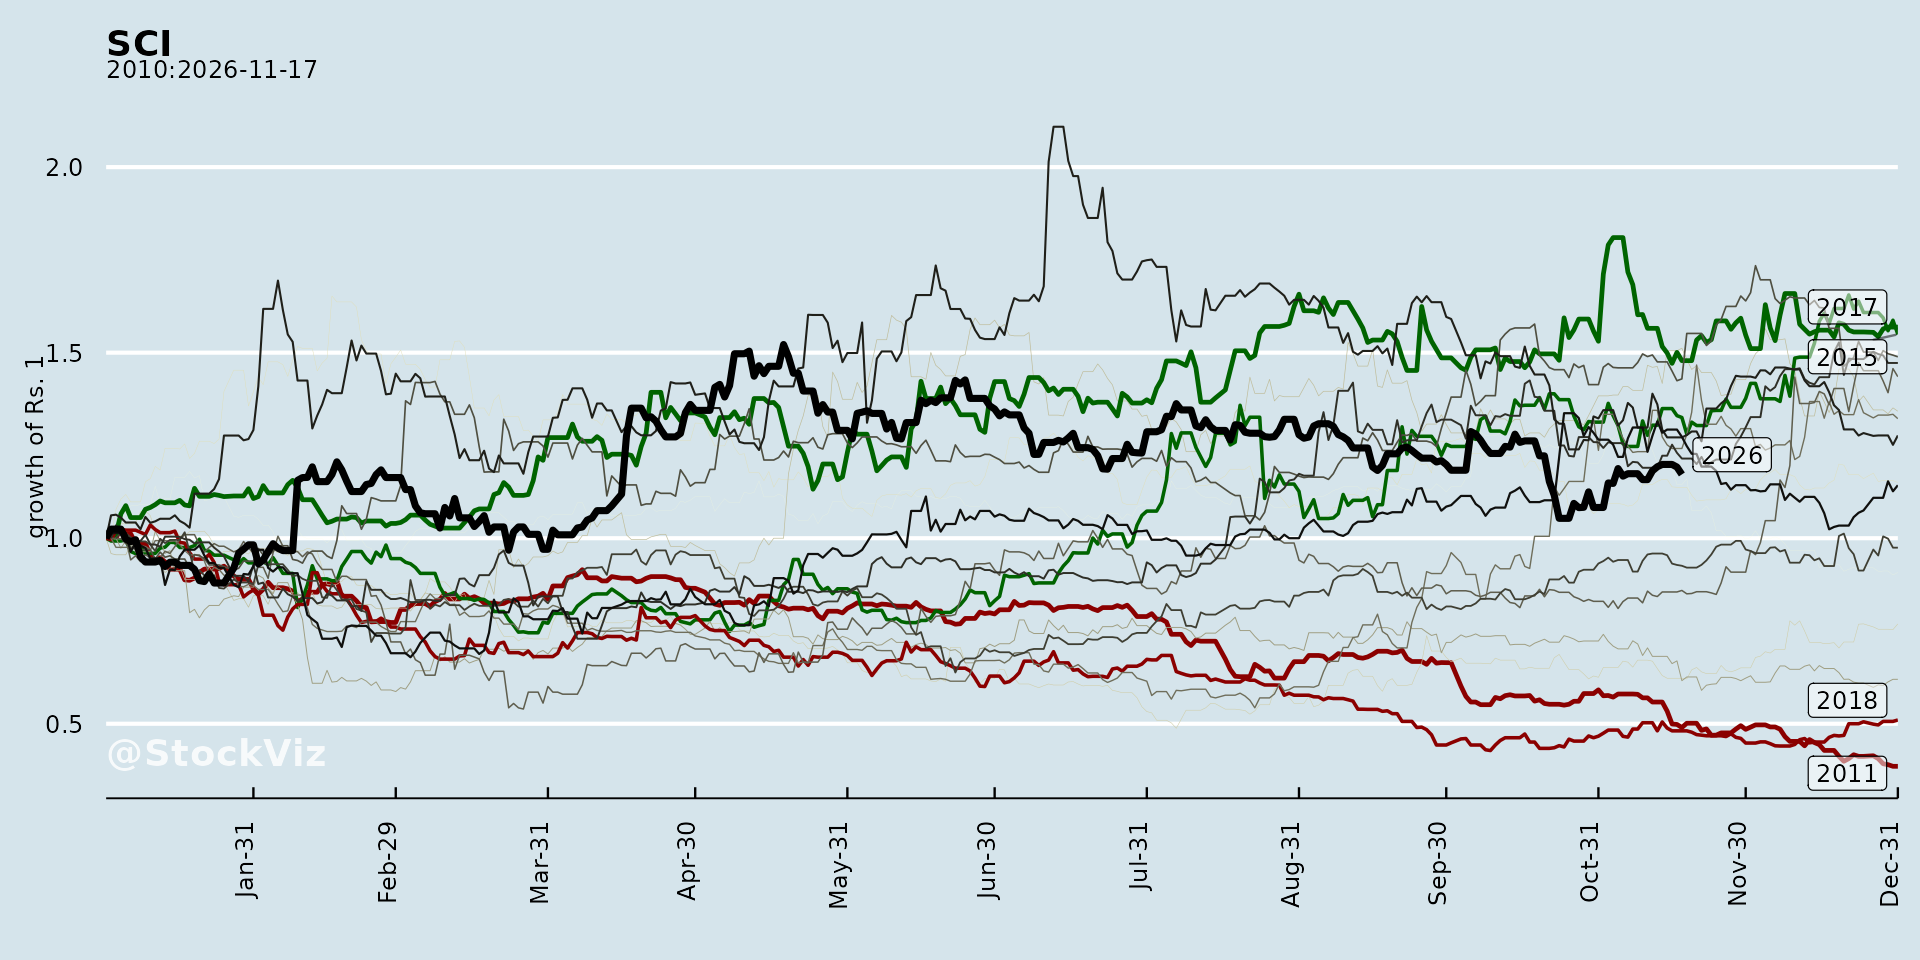
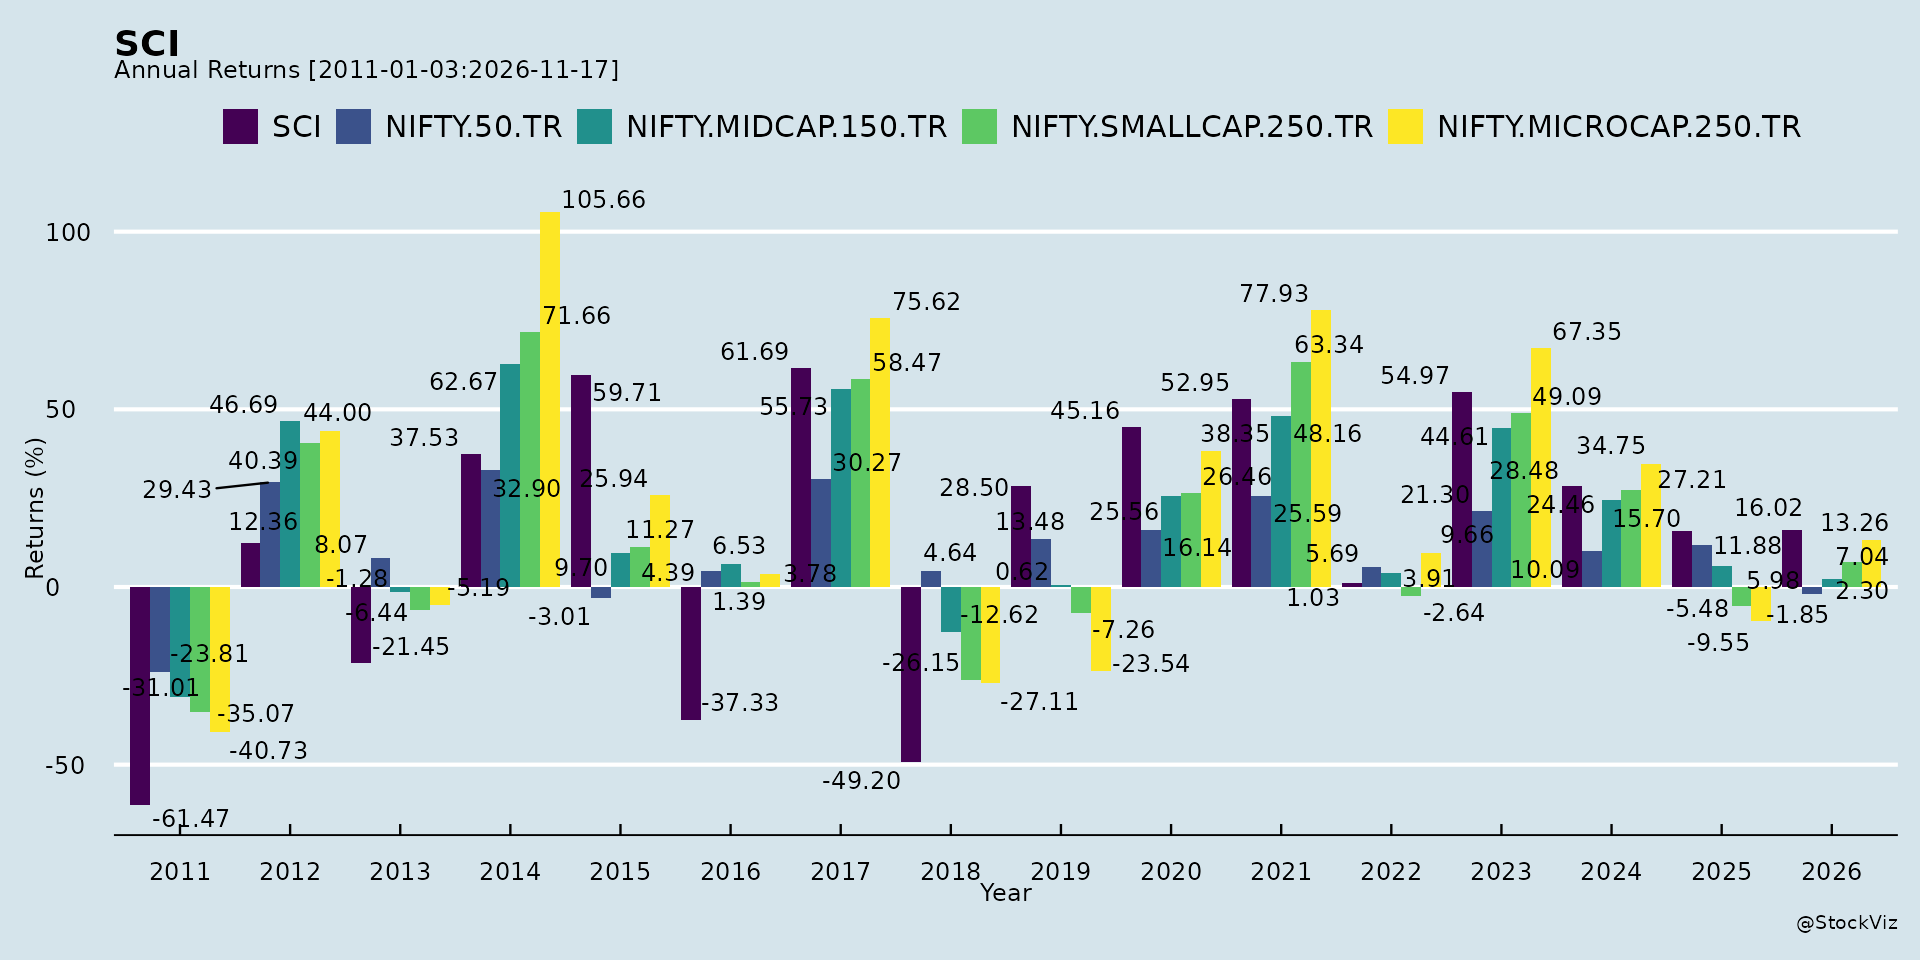
Annual Returns
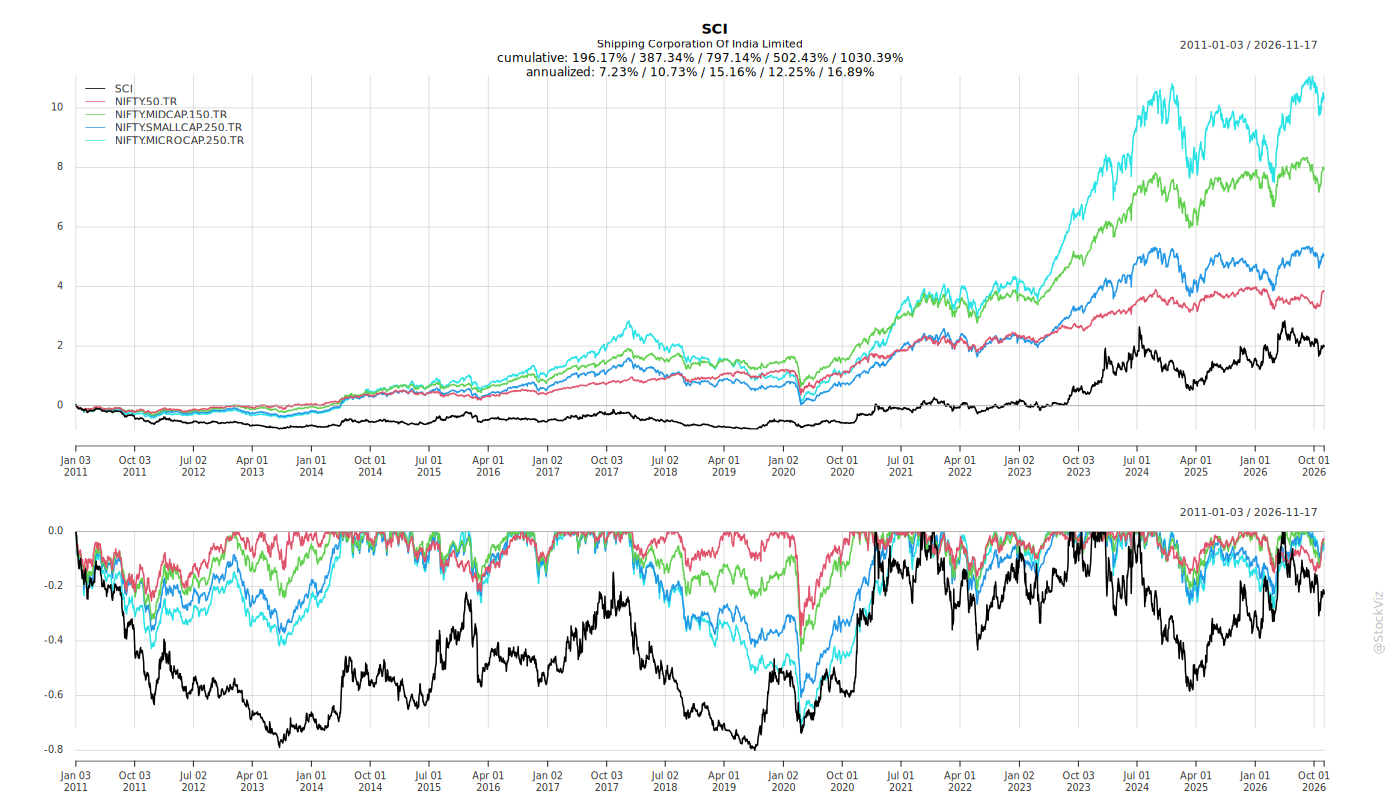
Cumulative Returns and Drawdowns
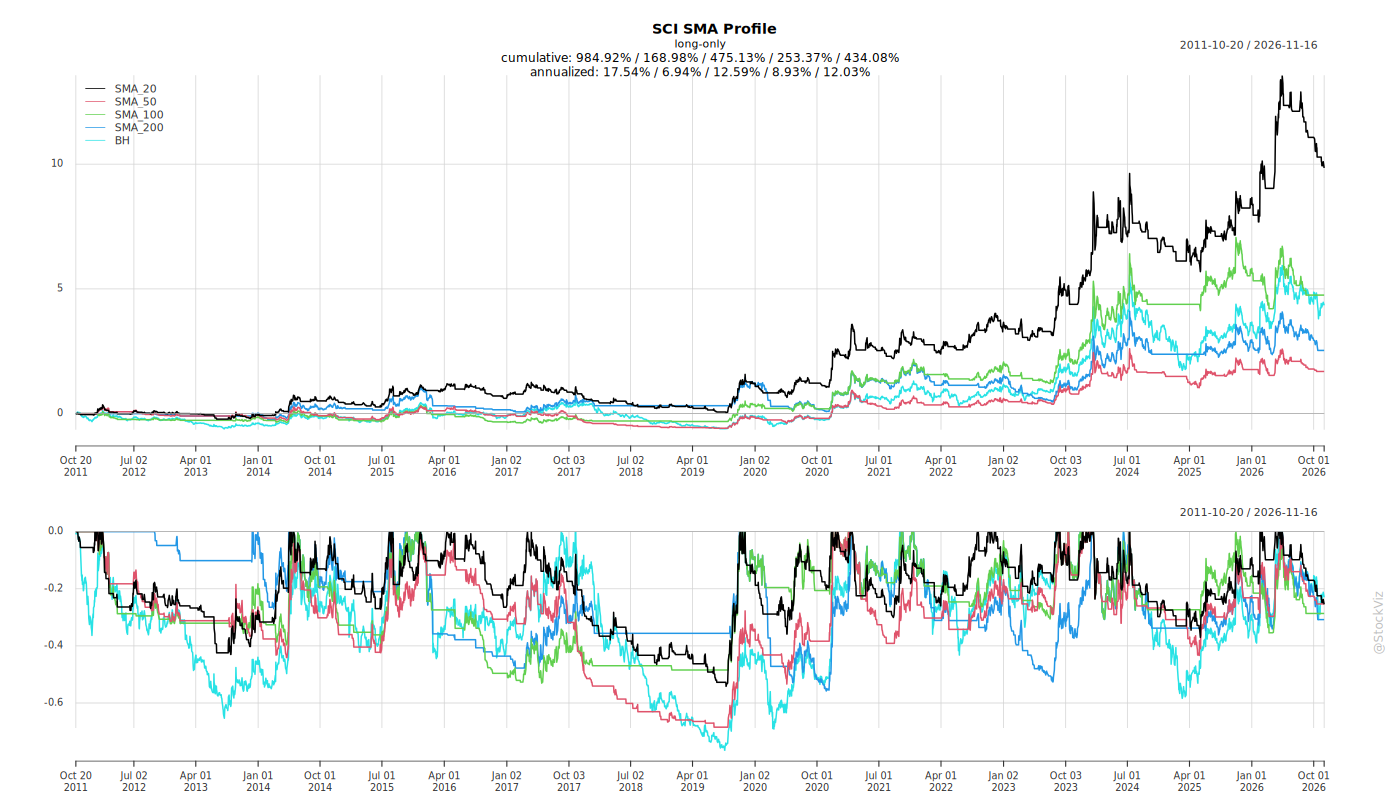
Fundamentals
Ownership
Margined
AI Summary
asof: 2026-09-17
The Shipping Corporation of India Limited — Recent Corporate Announcements
1. Headwinds and Challenges
Geopolitical disruption. Geopolitical developments in the Middle East have affected the operations of joint ventures ILT 1, ILT 2 and ILT 3. The auditors of these three joint ventures inserted a paragraph on material uncertainty relating to going concern in their respective independent review reports, though the company notes these joint ventures are not material to it. The company states that, based on going concern assessments performed by the joint venture companies, these entities have sufficient resources to continue operations and meet obligations as they fall due. Separately, the company identifies the Persian Gulf and Strait of Hormuz disruptions, heightened safety and security concerns in High Risk Areas, and elevated energy, logistics and insurance costs as key challenges.
Macroeconomic pressure. Global economic slowdown and inflation pressures are cited as headwinds, alongside potential oversupply in certain shipping segments due to heavy order books and vessel deliveries.
Operational constraints. The company flags a shortage of qualified seafarer officers and competent manpower for offshore vessels, and limited availability of shipyards on the Indian coast for dry-docking and repairs. It also notes intense competition from domestic private and international operators.
Accounting and reconciliation matters. The company continues to seek confirmations of balances for trade receivables, trade payables and deposits, with reconciliation ongoing; management does not expect any material difference affecting the financial results. Reconciliation of agent/vendor/customer balances is also ongoing, and management states the effect of changes in balances and the subsequent impact on foreign exchange gain/loss will not be material. The company is reconciling outstanding receivables relating to ongoing income tax litigation (shown as a tax asset) with assessment orders, orders giving effect (OGEs) and other documentation, and does not expect any material impact.
Volatility in shipping. The company notes the volatility of the shipping business in explaining that Performance Related Pay provisions are made only in the last quarter of the financial year.
2. Tailwinds and Growth Prospects
Domestic demand. India’s strong economic growth and favourable domestic demand are cited as opportunities, along with robust dry bulk trade driven by infrastructure development and manufacturing expansion, and high refinery utilisation supporting strong crude and product tanker demand.
Policy support. Government of India policy initiatives and schemes — including Shipbuilding and Maritime Reform schemes and the National Green Hydrogen Mission — are identified as growth prospects.
Green shipping and fleet expansion. The company points to expansion into green shipping through the acquisition of methanol dual-fuel vessels and Very Large Gas Carriers (VLGCs).
Strategic partnerships. Strategic MOUs with major oil PSUs and public entities for joint vessel operations are highlighted.
Fleet position. The total fleet stands at 58 vessels with 5.261 million DWT as of July 1, 2026.
3. Key Risks
- Geopolitical conflict risk, including Persian Gulf and Strait of Hormuz disruptions and High Risk Area safety and security concerns.
- Cost risk from elevated energy, logistics and insurance costs.
- Demand risk from global economic slowdown and inflation.
- Segment oversupply risk from heavy order books and vessel deliveries.
- Manpower risk from shortage of qualified seafarer officers and competent manpower for offshore vessels.
- Maintenance risk from limited Indian shipyard capacity for dry-docking and repairs.
- Competitive risk from domestic private and international operators.
- Going concern uncertainty at joint ventures ILT 1, ILT 2 and ILT 3, which the company states are not material to it.
- Balance confirmation, agent/vendor/customer reconciliation, and tax asset reconciliation matters, each assessed by management as not expected to have a material impact.
4. Management Guidance Versus Observed Business Performance
Guidance. Management expects global economic growth to moderate in 2026 before recovering in 2027, assuming a peaceful resolution of conflicts, and anticipates energy prices will gradually ease from mid-2026 onwards. For shipping segments, charter rates are expected to strengthen through 2026 for dry bulk, while product tanker fleets and LPG/LNG shipping markets are projected to see continued volatility due to supply dynamics and geopolitical factors. Management states it remains committed to aligning business strategy with evolving global realities, maintaining operational excellence, and pursuing vessel acquisitions at opportune times.
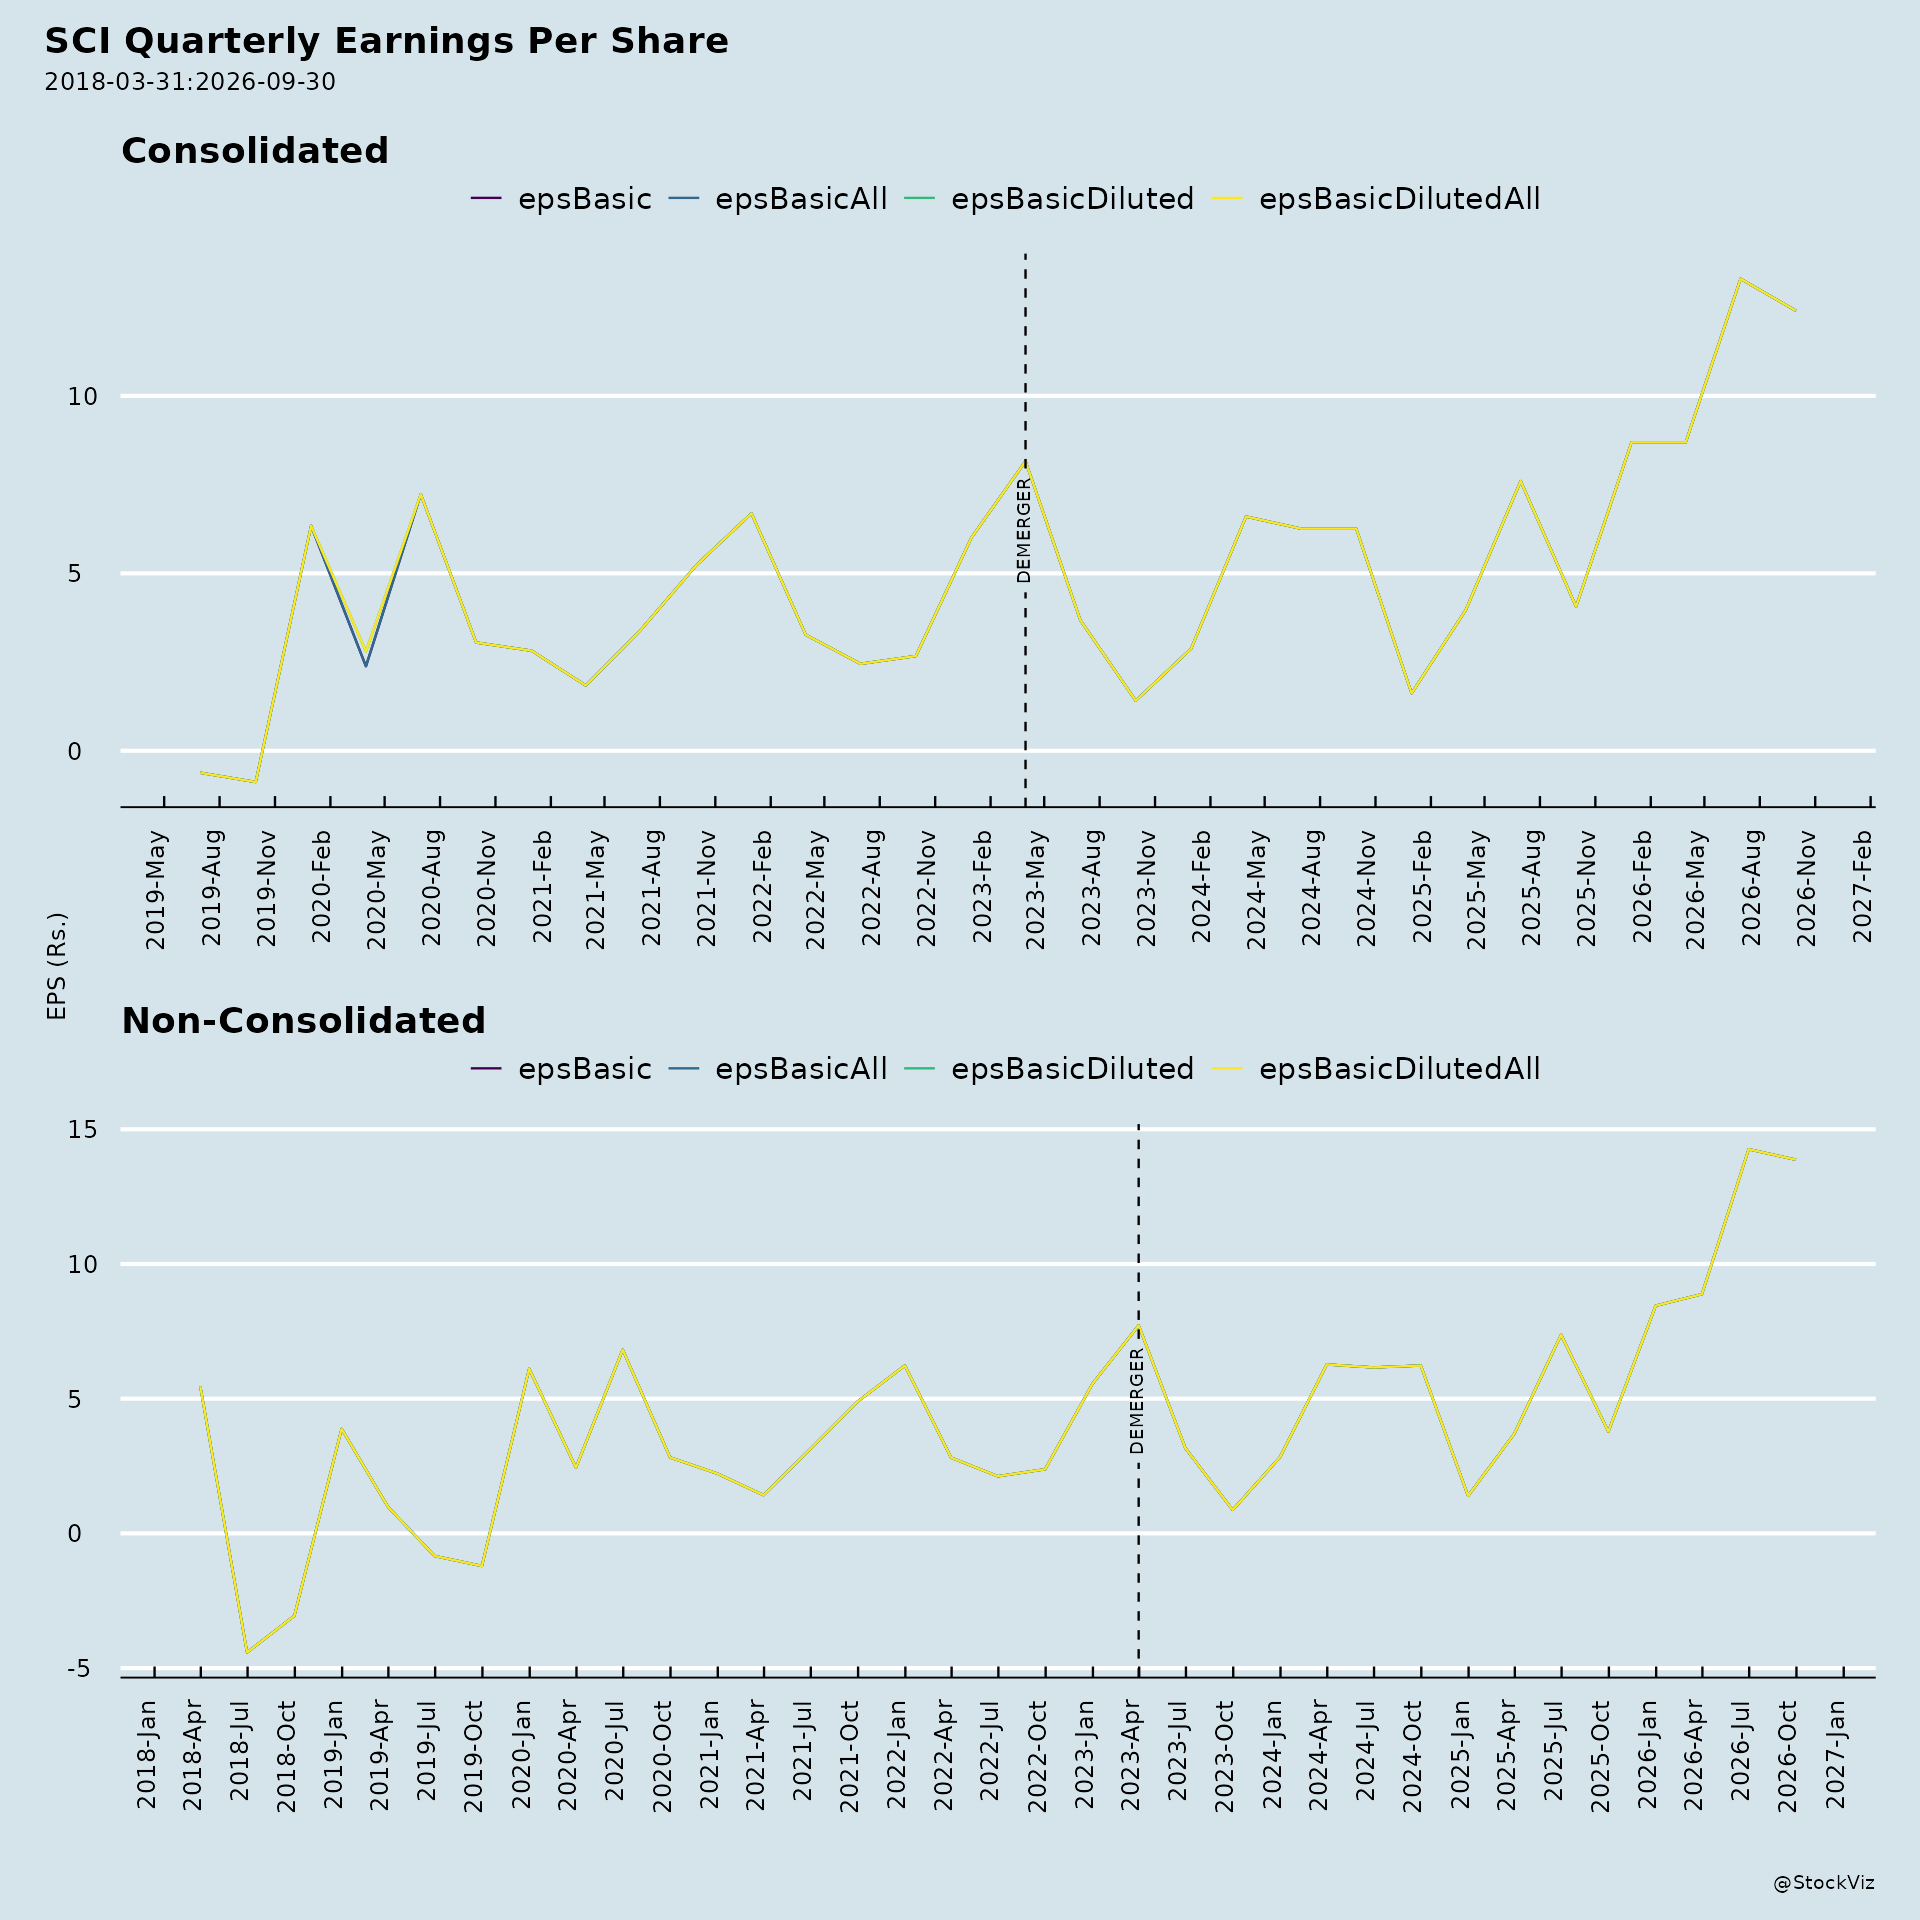
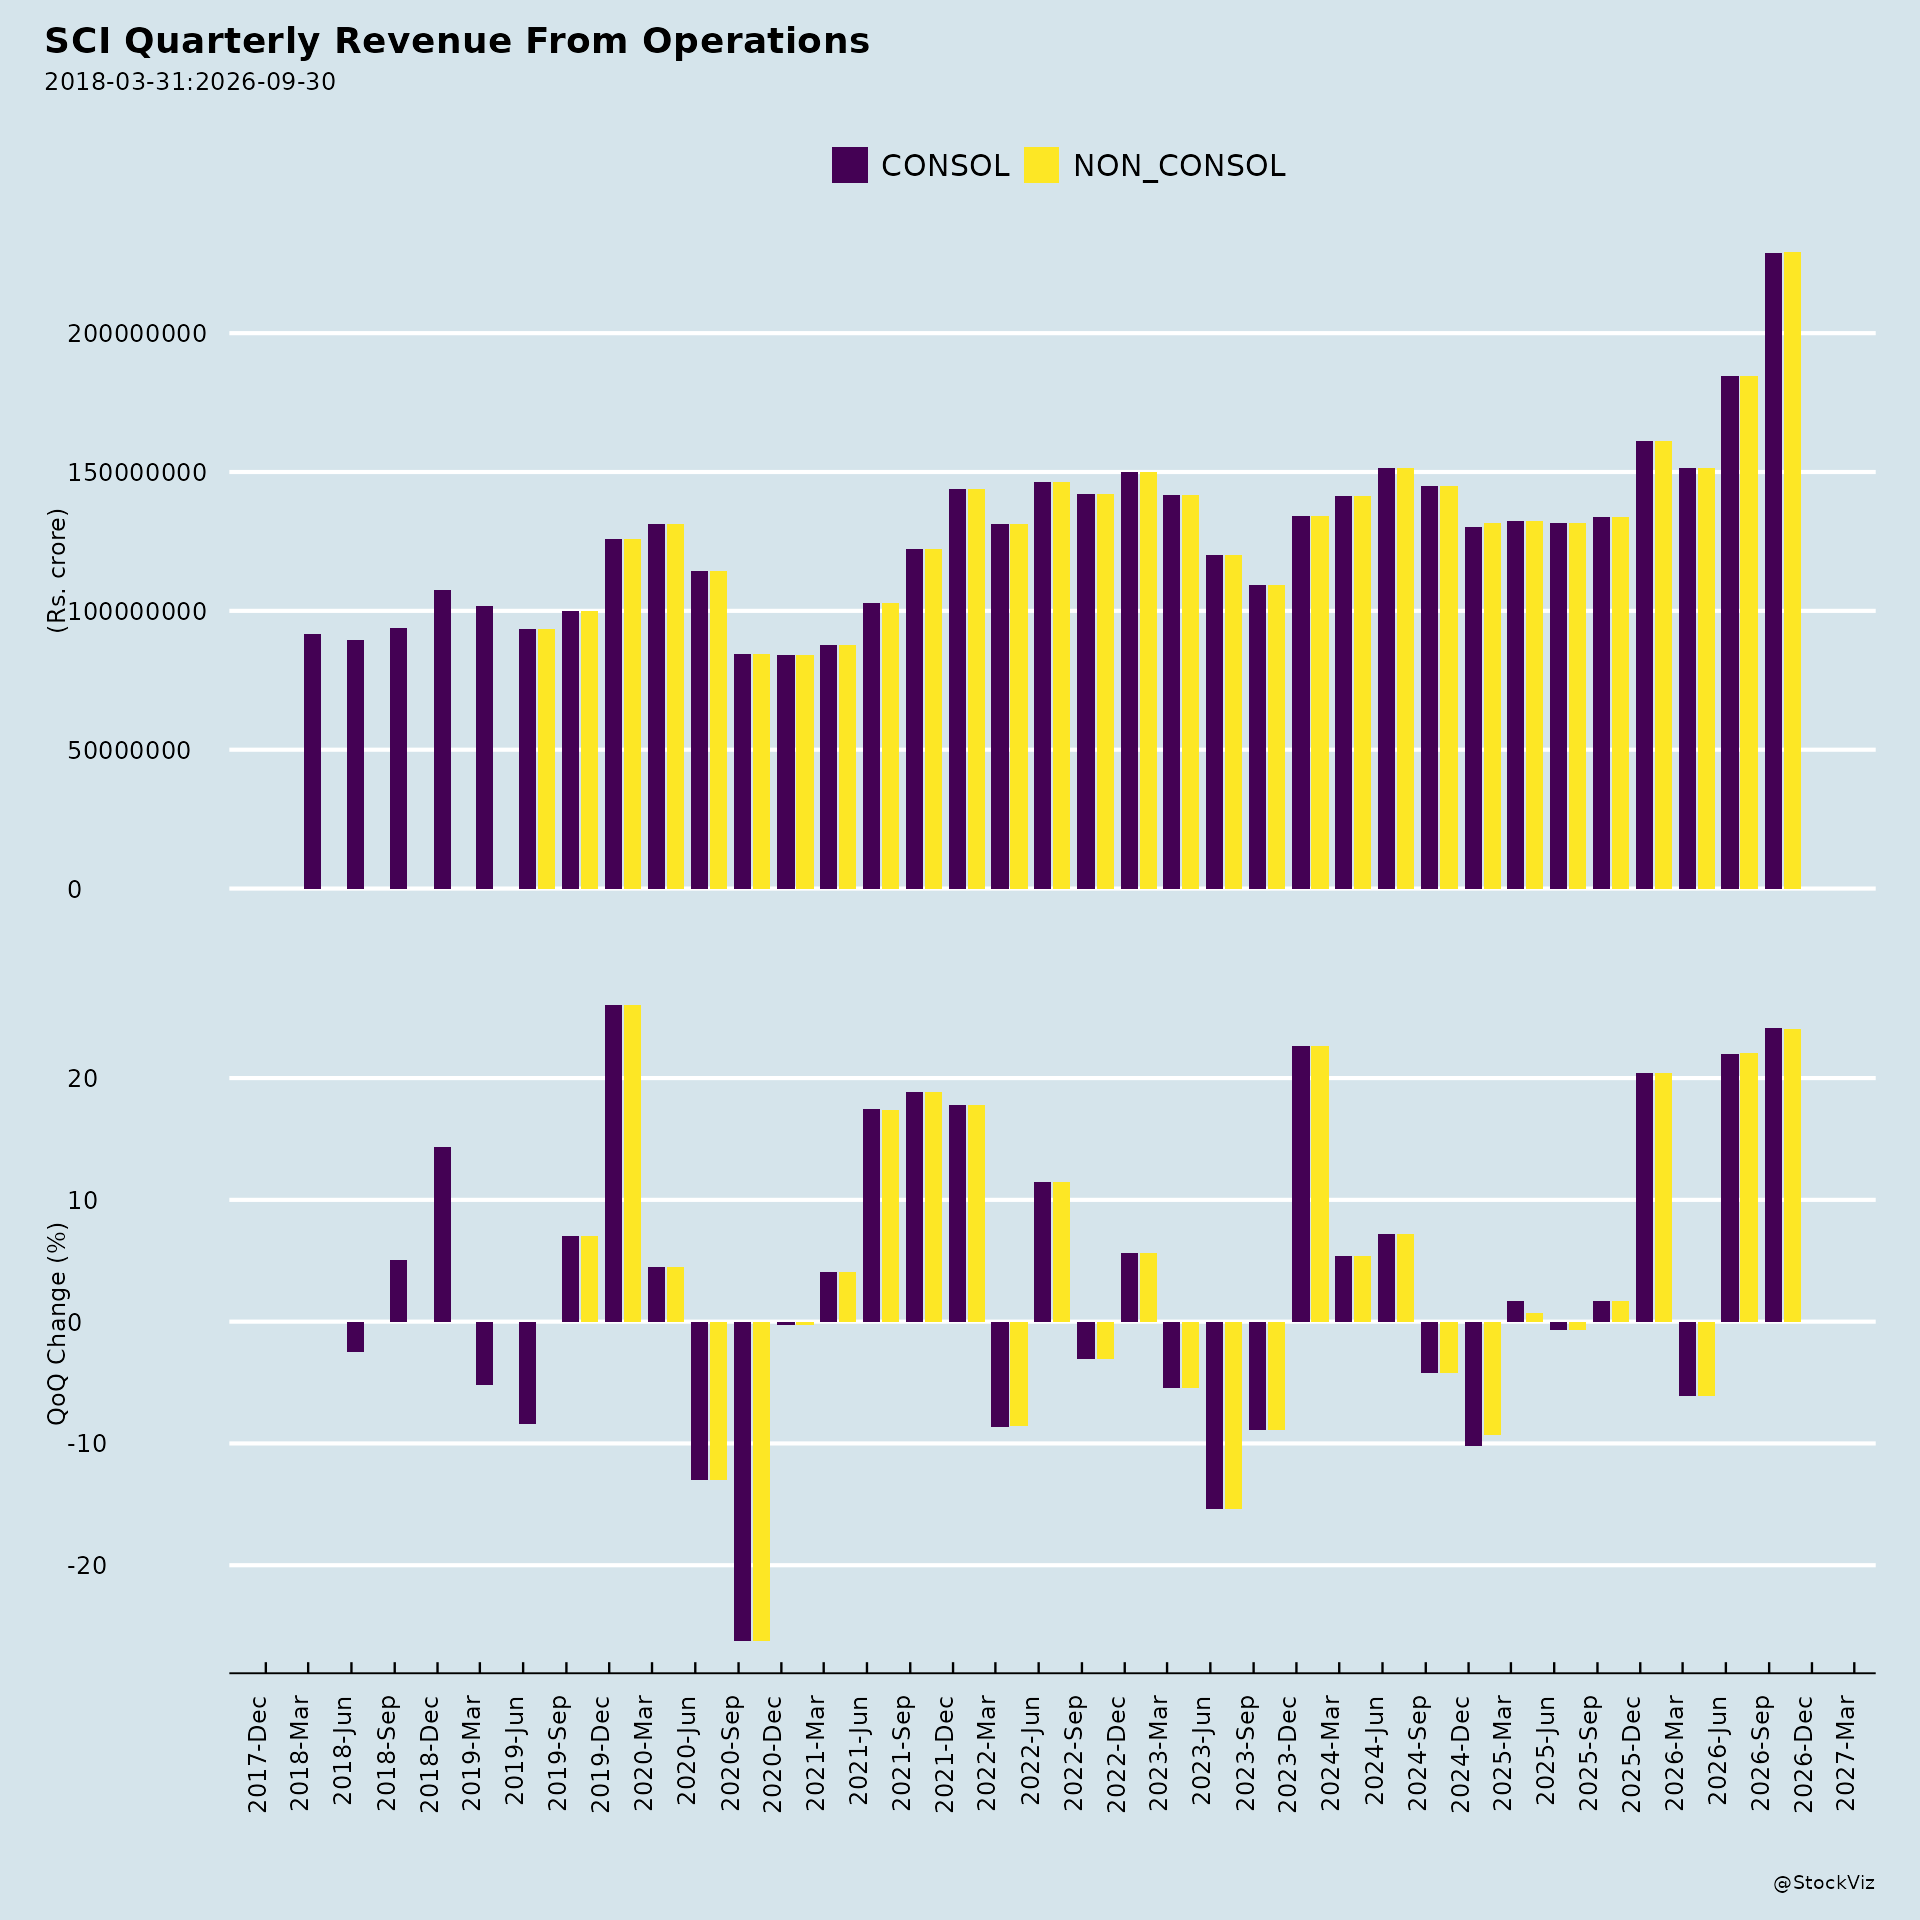
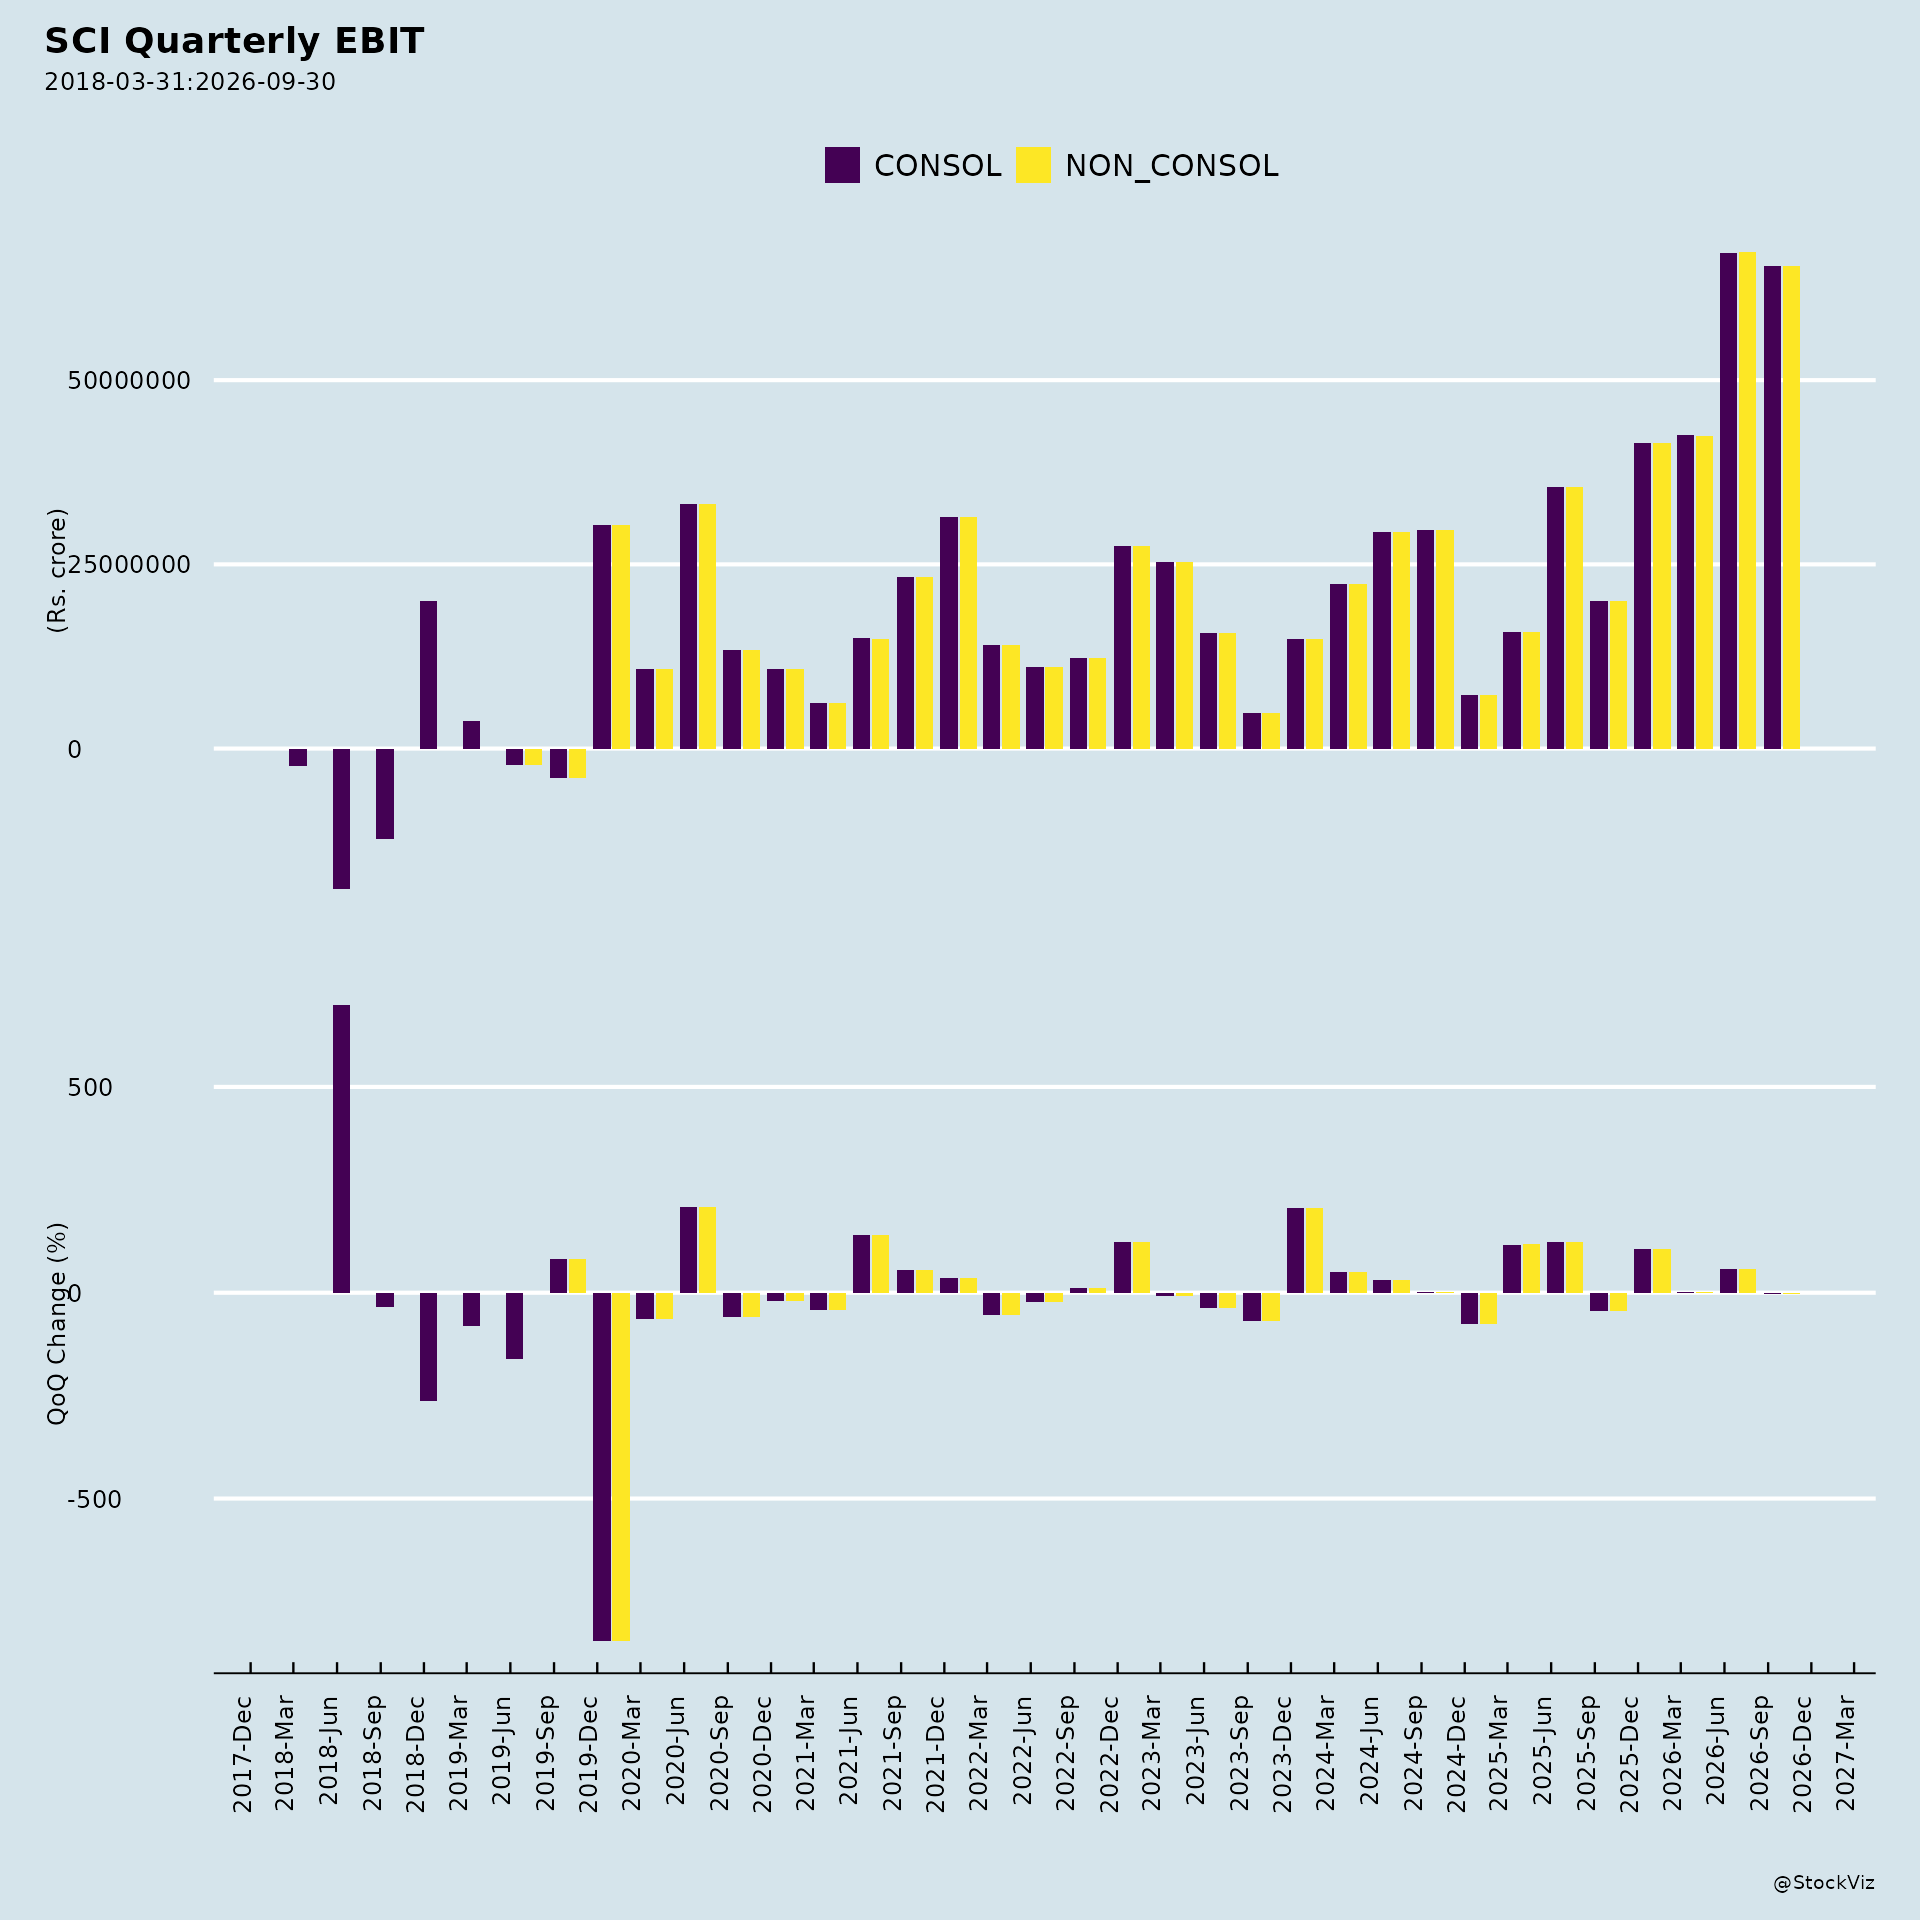
Observed performance. For the quarter ended 30.06.2026, standalone revenue from operations was ₹1,84,464 lakh, total income ₹1,95,248 lakh, and profit before tax ₹67,320 lakh, with profit for the period of ₹66,429 lakh and basic and diluted EPS of ₹14.26. Standalone segment results before tax and interest were: Liner ₹8,260 lakh, Bulk Carrier ₹4,318 lakh, Tanker ₹52,523 lakh, and Technical & Offshore ₹1,570 lakh. On a consolidated basis, revenue from operations was ₹1,84,656 lakh, total income ₹1,95,684 lakh, and profit before tax ₹62,831 lakh, with profit for the period of ₹61,934 lakh and basic and diluted EPS of ₹13.30. Consolidated share of net loss of associates and joint ventures accounted for using the equity method was ₹(4,504) lakh for the quarter.
For the year ended 31.03.2026, standalone revenue from operations was ₹5,77,813 lakh, profit before tax ₹1,39,589 lakh, profit for the period ₹1,32,625 lakh, and basic and diluted EPS ₹28.47. Consolidated revenue from operations was ₹5,77,979 lakh, profit before tax ₹1,42,281 lakh, profit for the period ₹1,35,292 lakh, and basic and diluted EPS ₹29.05. The company describes FY 2025-26 as having achieved its highest-ever consolidated Profit Before Tax of ₹1,423 Crores, standalone net PAT of ₹1,326.25 Crores, and consolidated net PAT of ₹1,352.92 Crores, with revenue from operations increasing to ₹5,778.13 Crores.
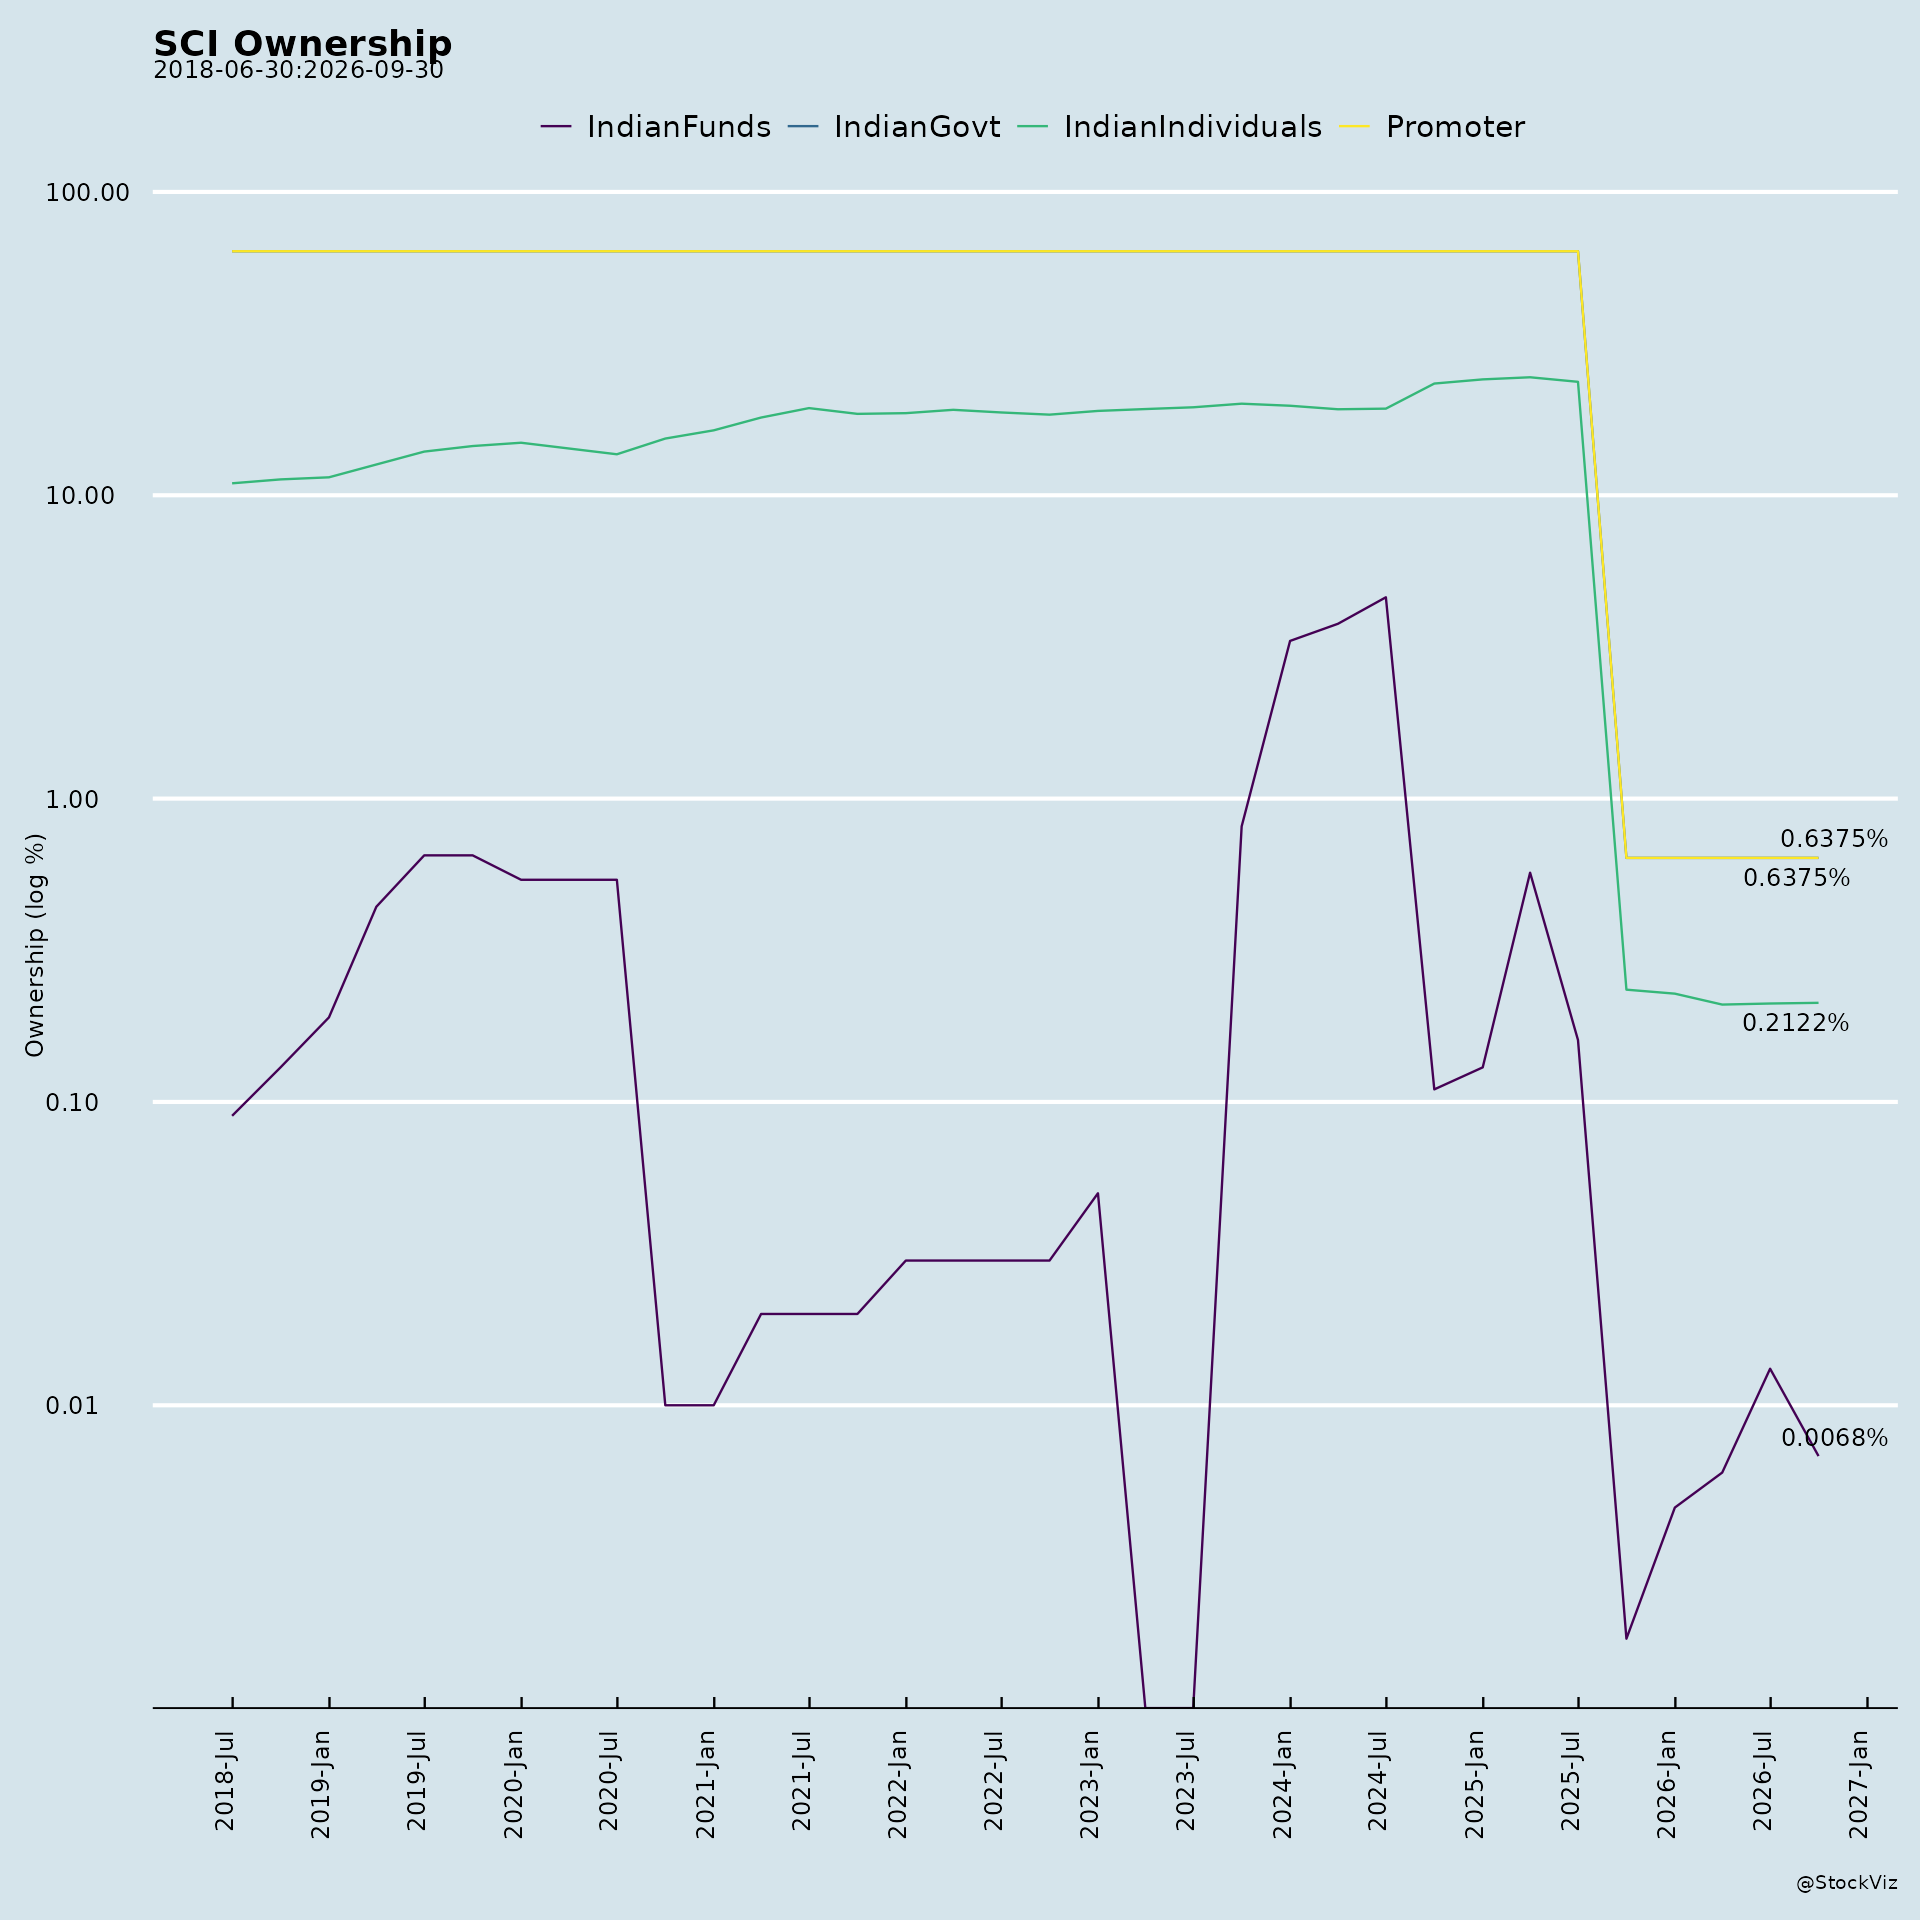
Strategic disinvestment. The proposed strategic disinvestment of SCI is being handled by the Department of Investment and Public Asset Management (DIPAM) with the engagement of a Transaction Advisor. The Preliminary Information Memorandum for inviting expression of interest was released on 22.12.2020. The Virtual Data Room is open and is being managed by the Transaction Advisor for the due diligence process by Qualified Interested Parties. The disinvestment process and procedural aspects remain in progress. Non-core assets have been transferred to Shipping Corporation of India Land and Assets Limited (SCILAL).
Annual General Meeting. The 76th Annual General Meeting is scheduled for Wednesday, September 23, 2026, at 1200 hours IST via Video Conferencing / Other Audio Visual Means. Shareholders who have not registered their email addresses are being provided web links to access the Annual Report for FY 2025-26 and are requested to update KYC details and email addresses through the RTA, M/s Alankit Assignments Limited.
CNBC-TV18: ratings, targets and commentary
No recorded CNBC-TV18 statements for this ticker.
Management comments
No recorded management comments with an explicit designation and affiliation for this ticker.
Copyright © 2023 SAS Data Analytics Pvt. Ltd. All rights reserved.