SANOFI
Equity Metrics
September 24, 2026
Sanofi India Limited
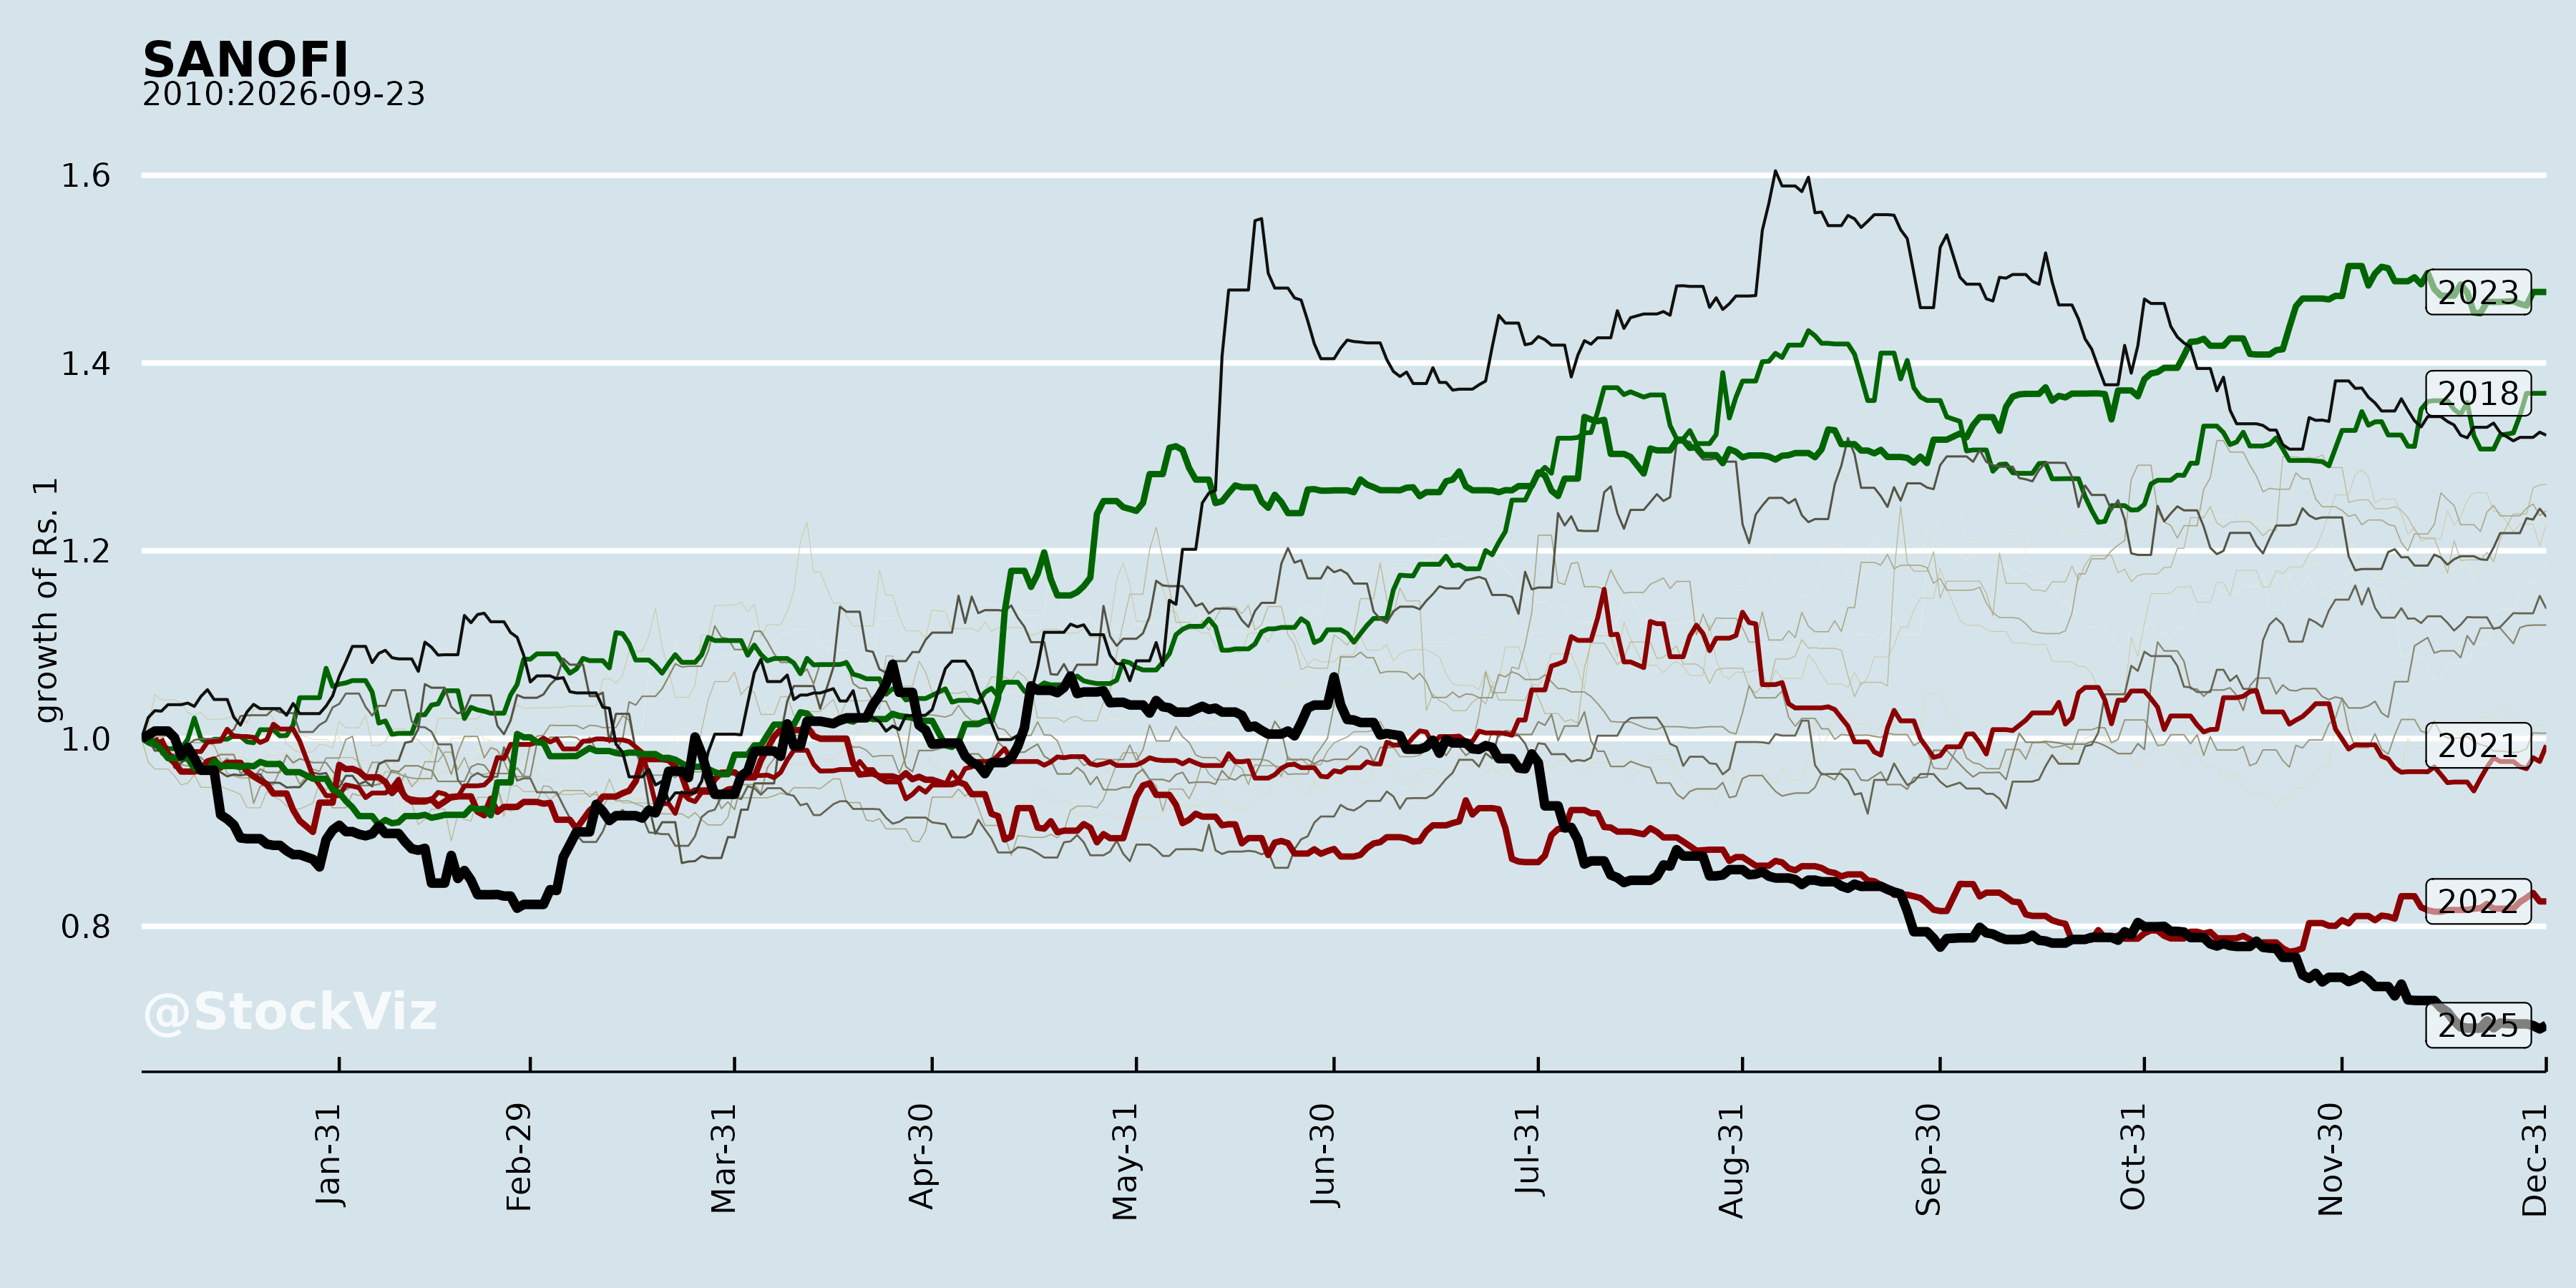
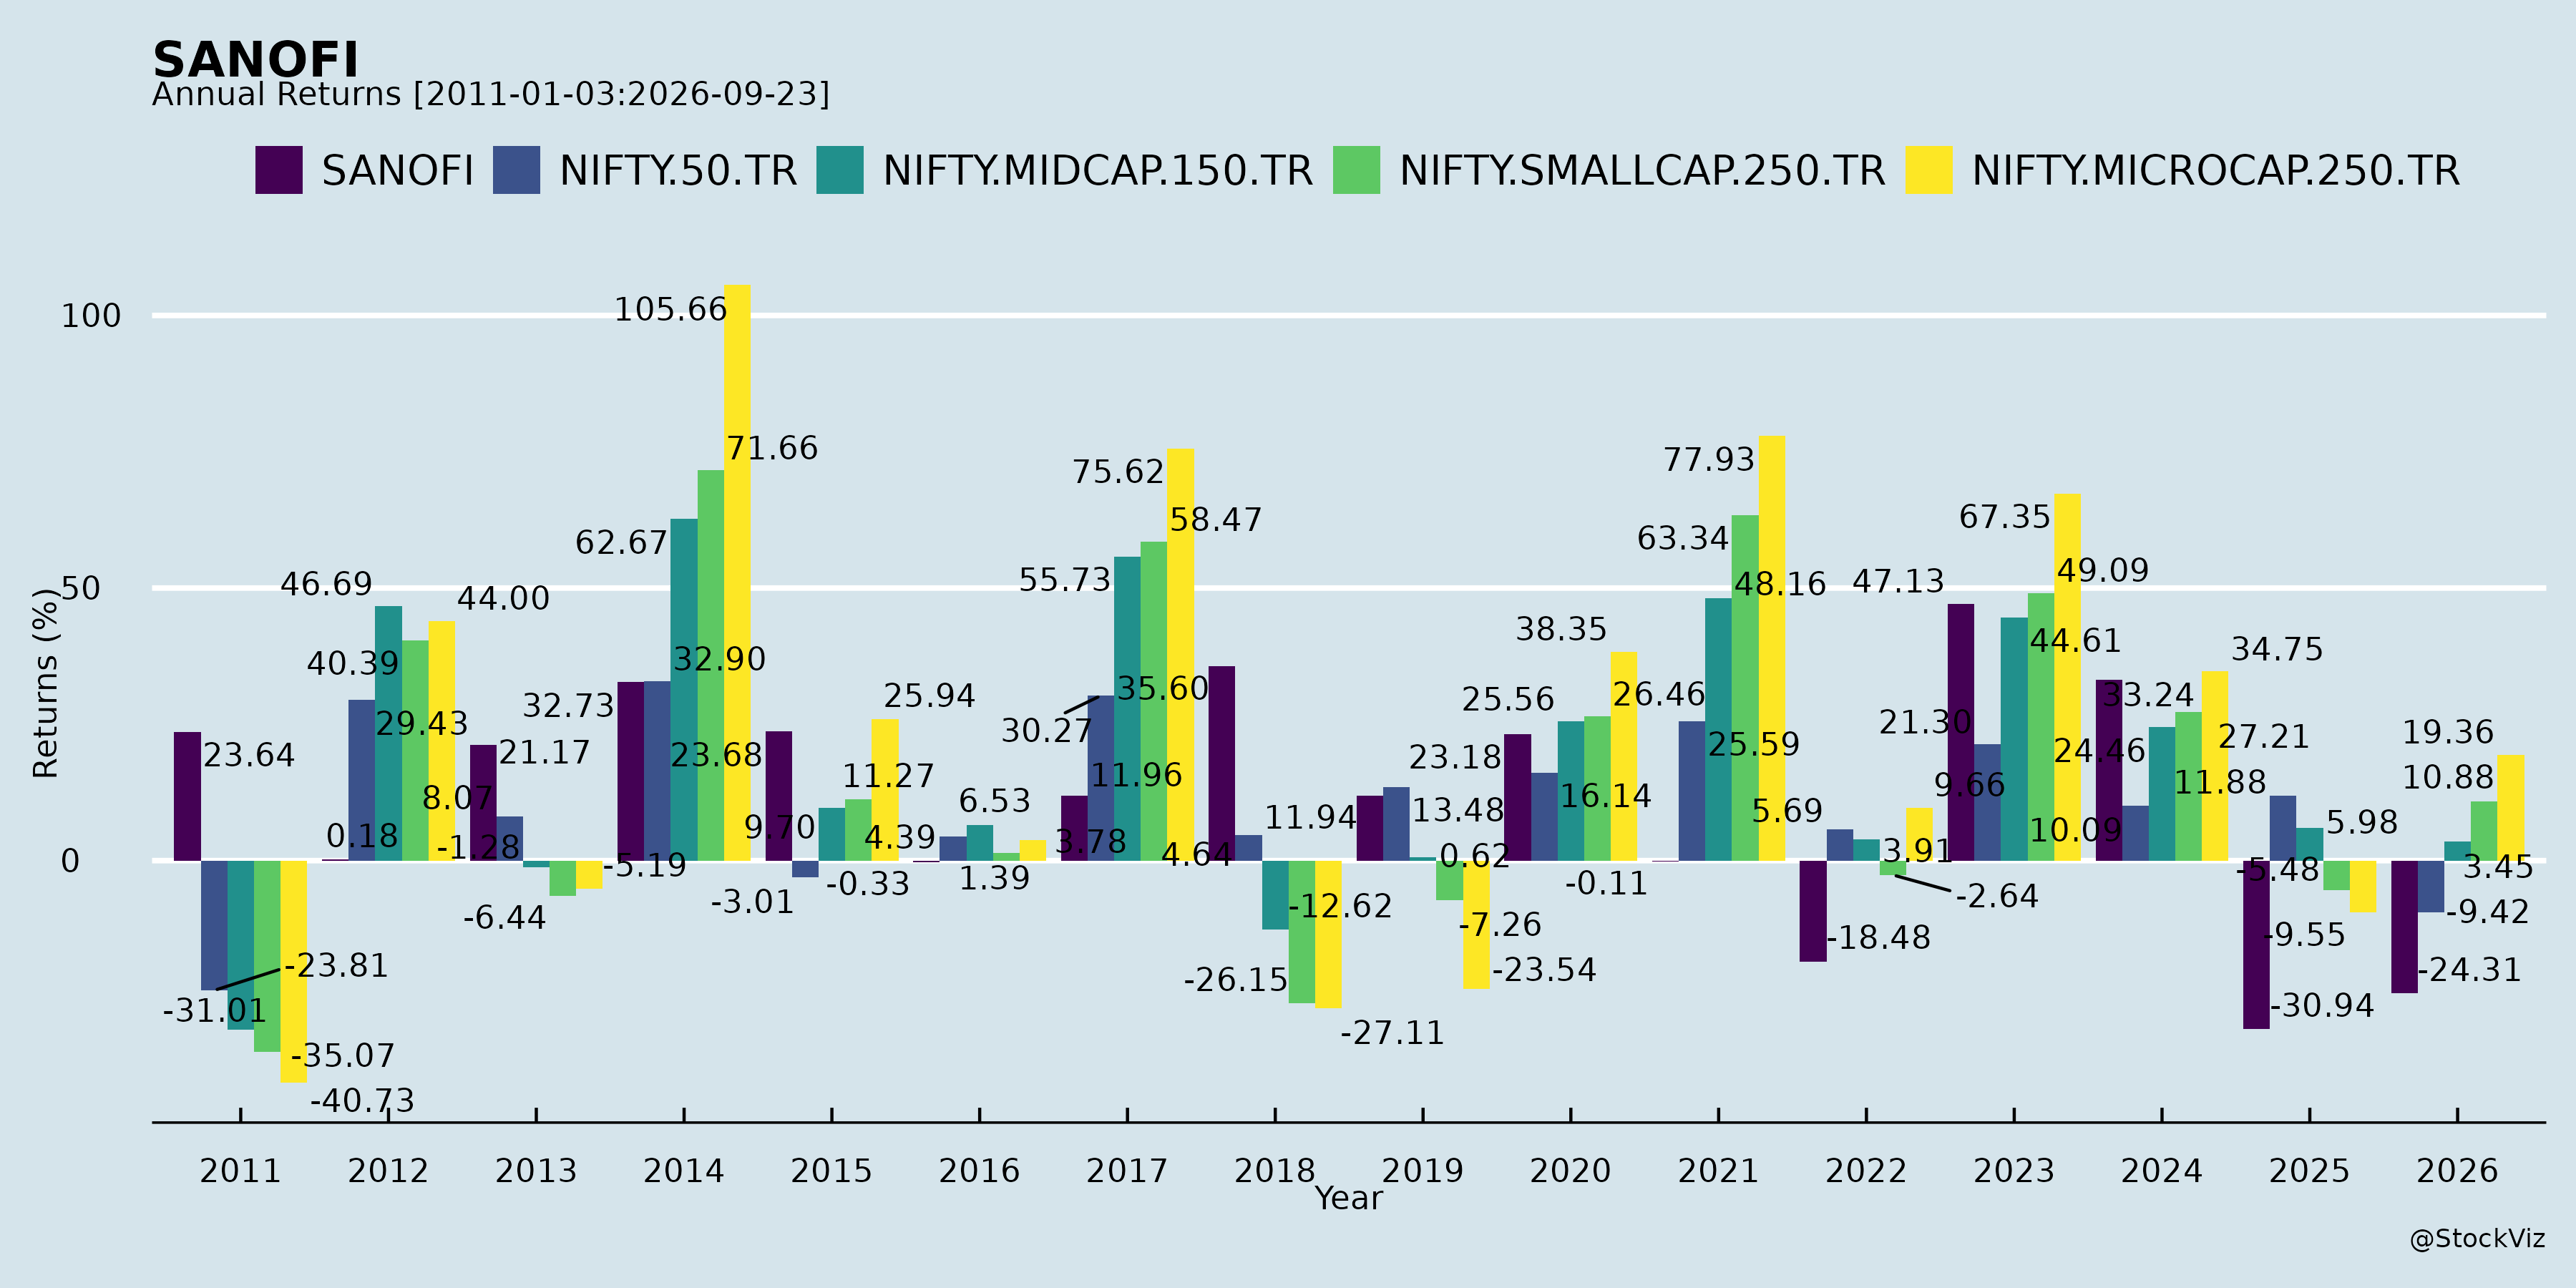
Annual Returns
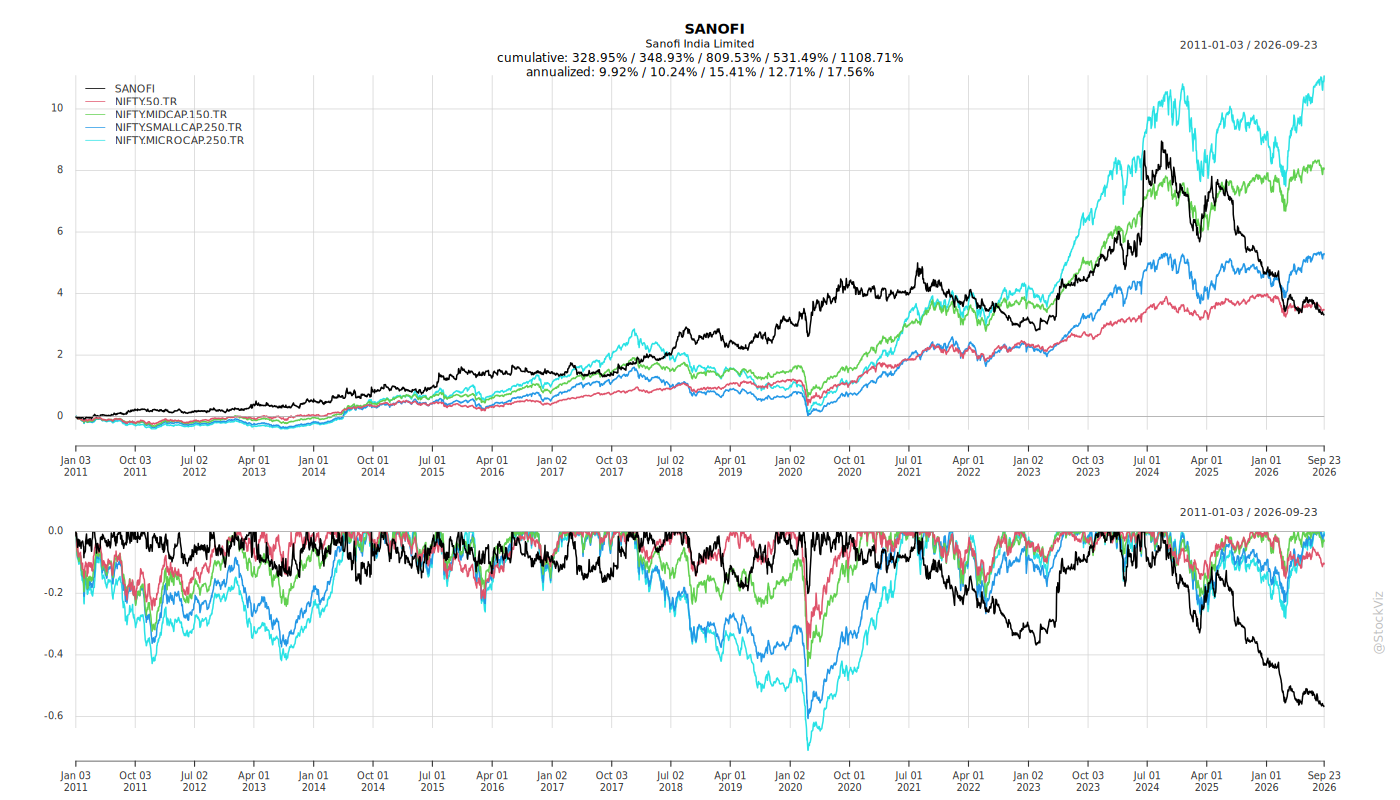
Cumulative Returns and Drawdowns
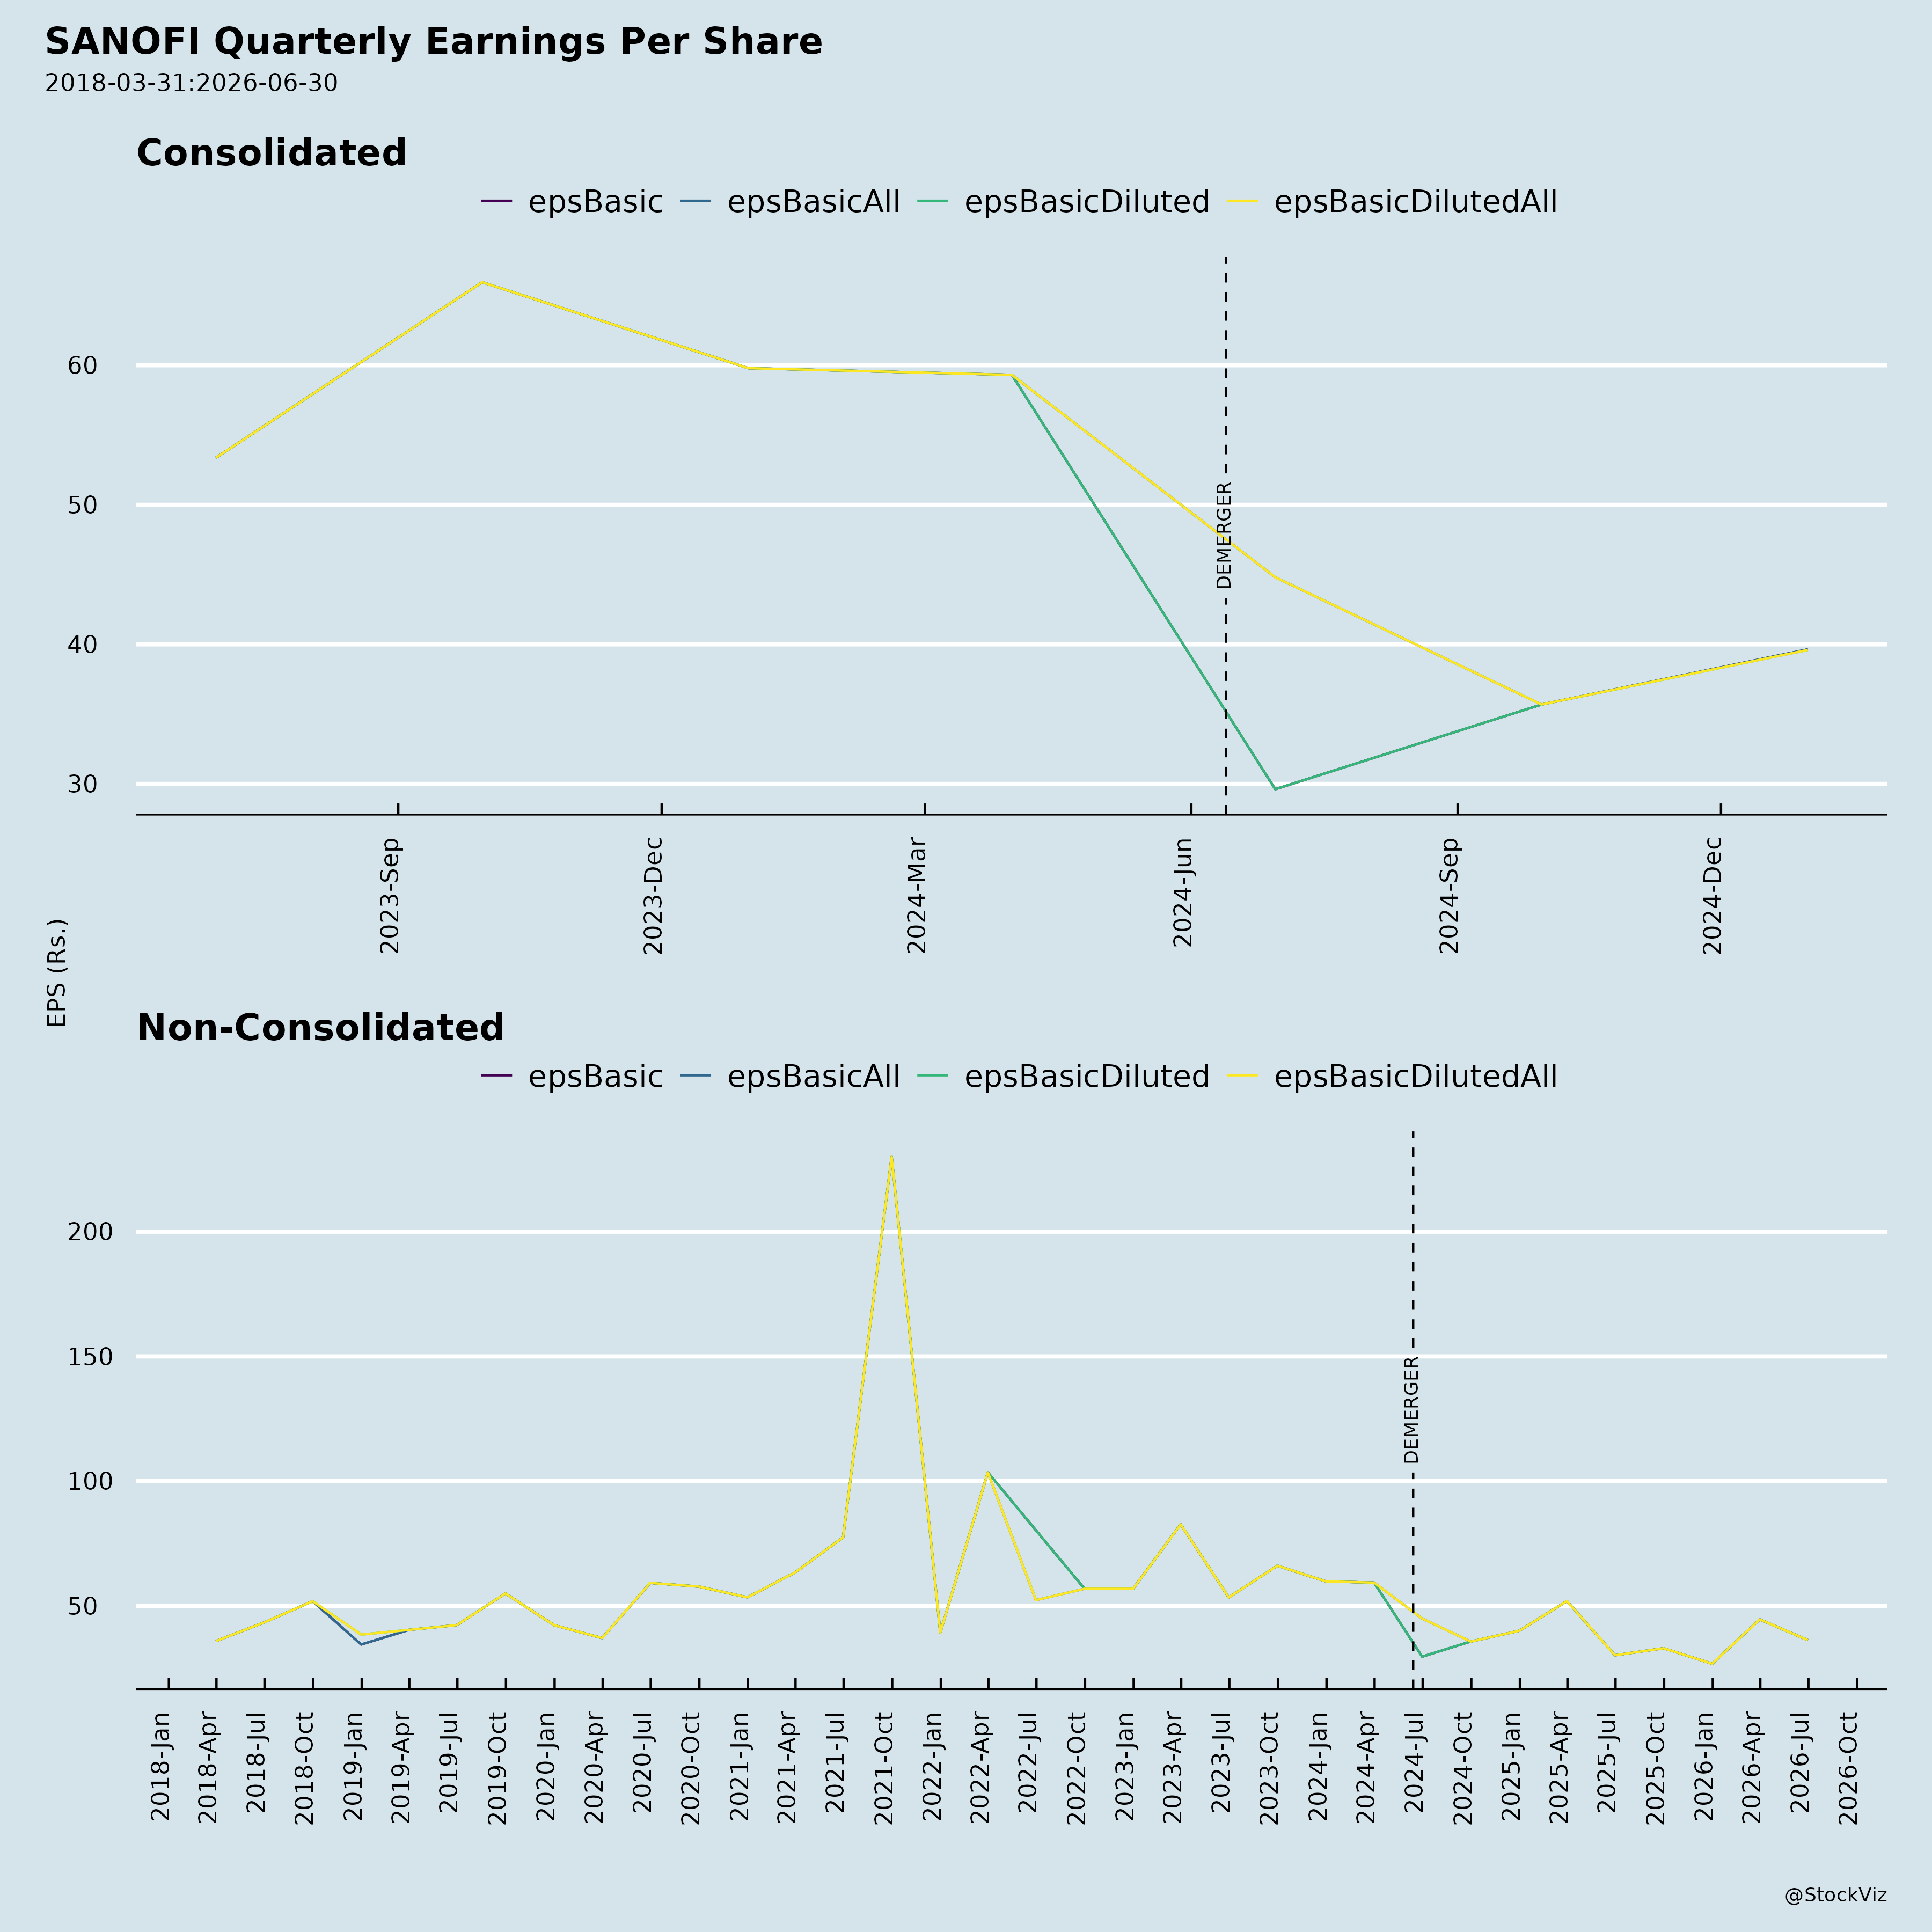
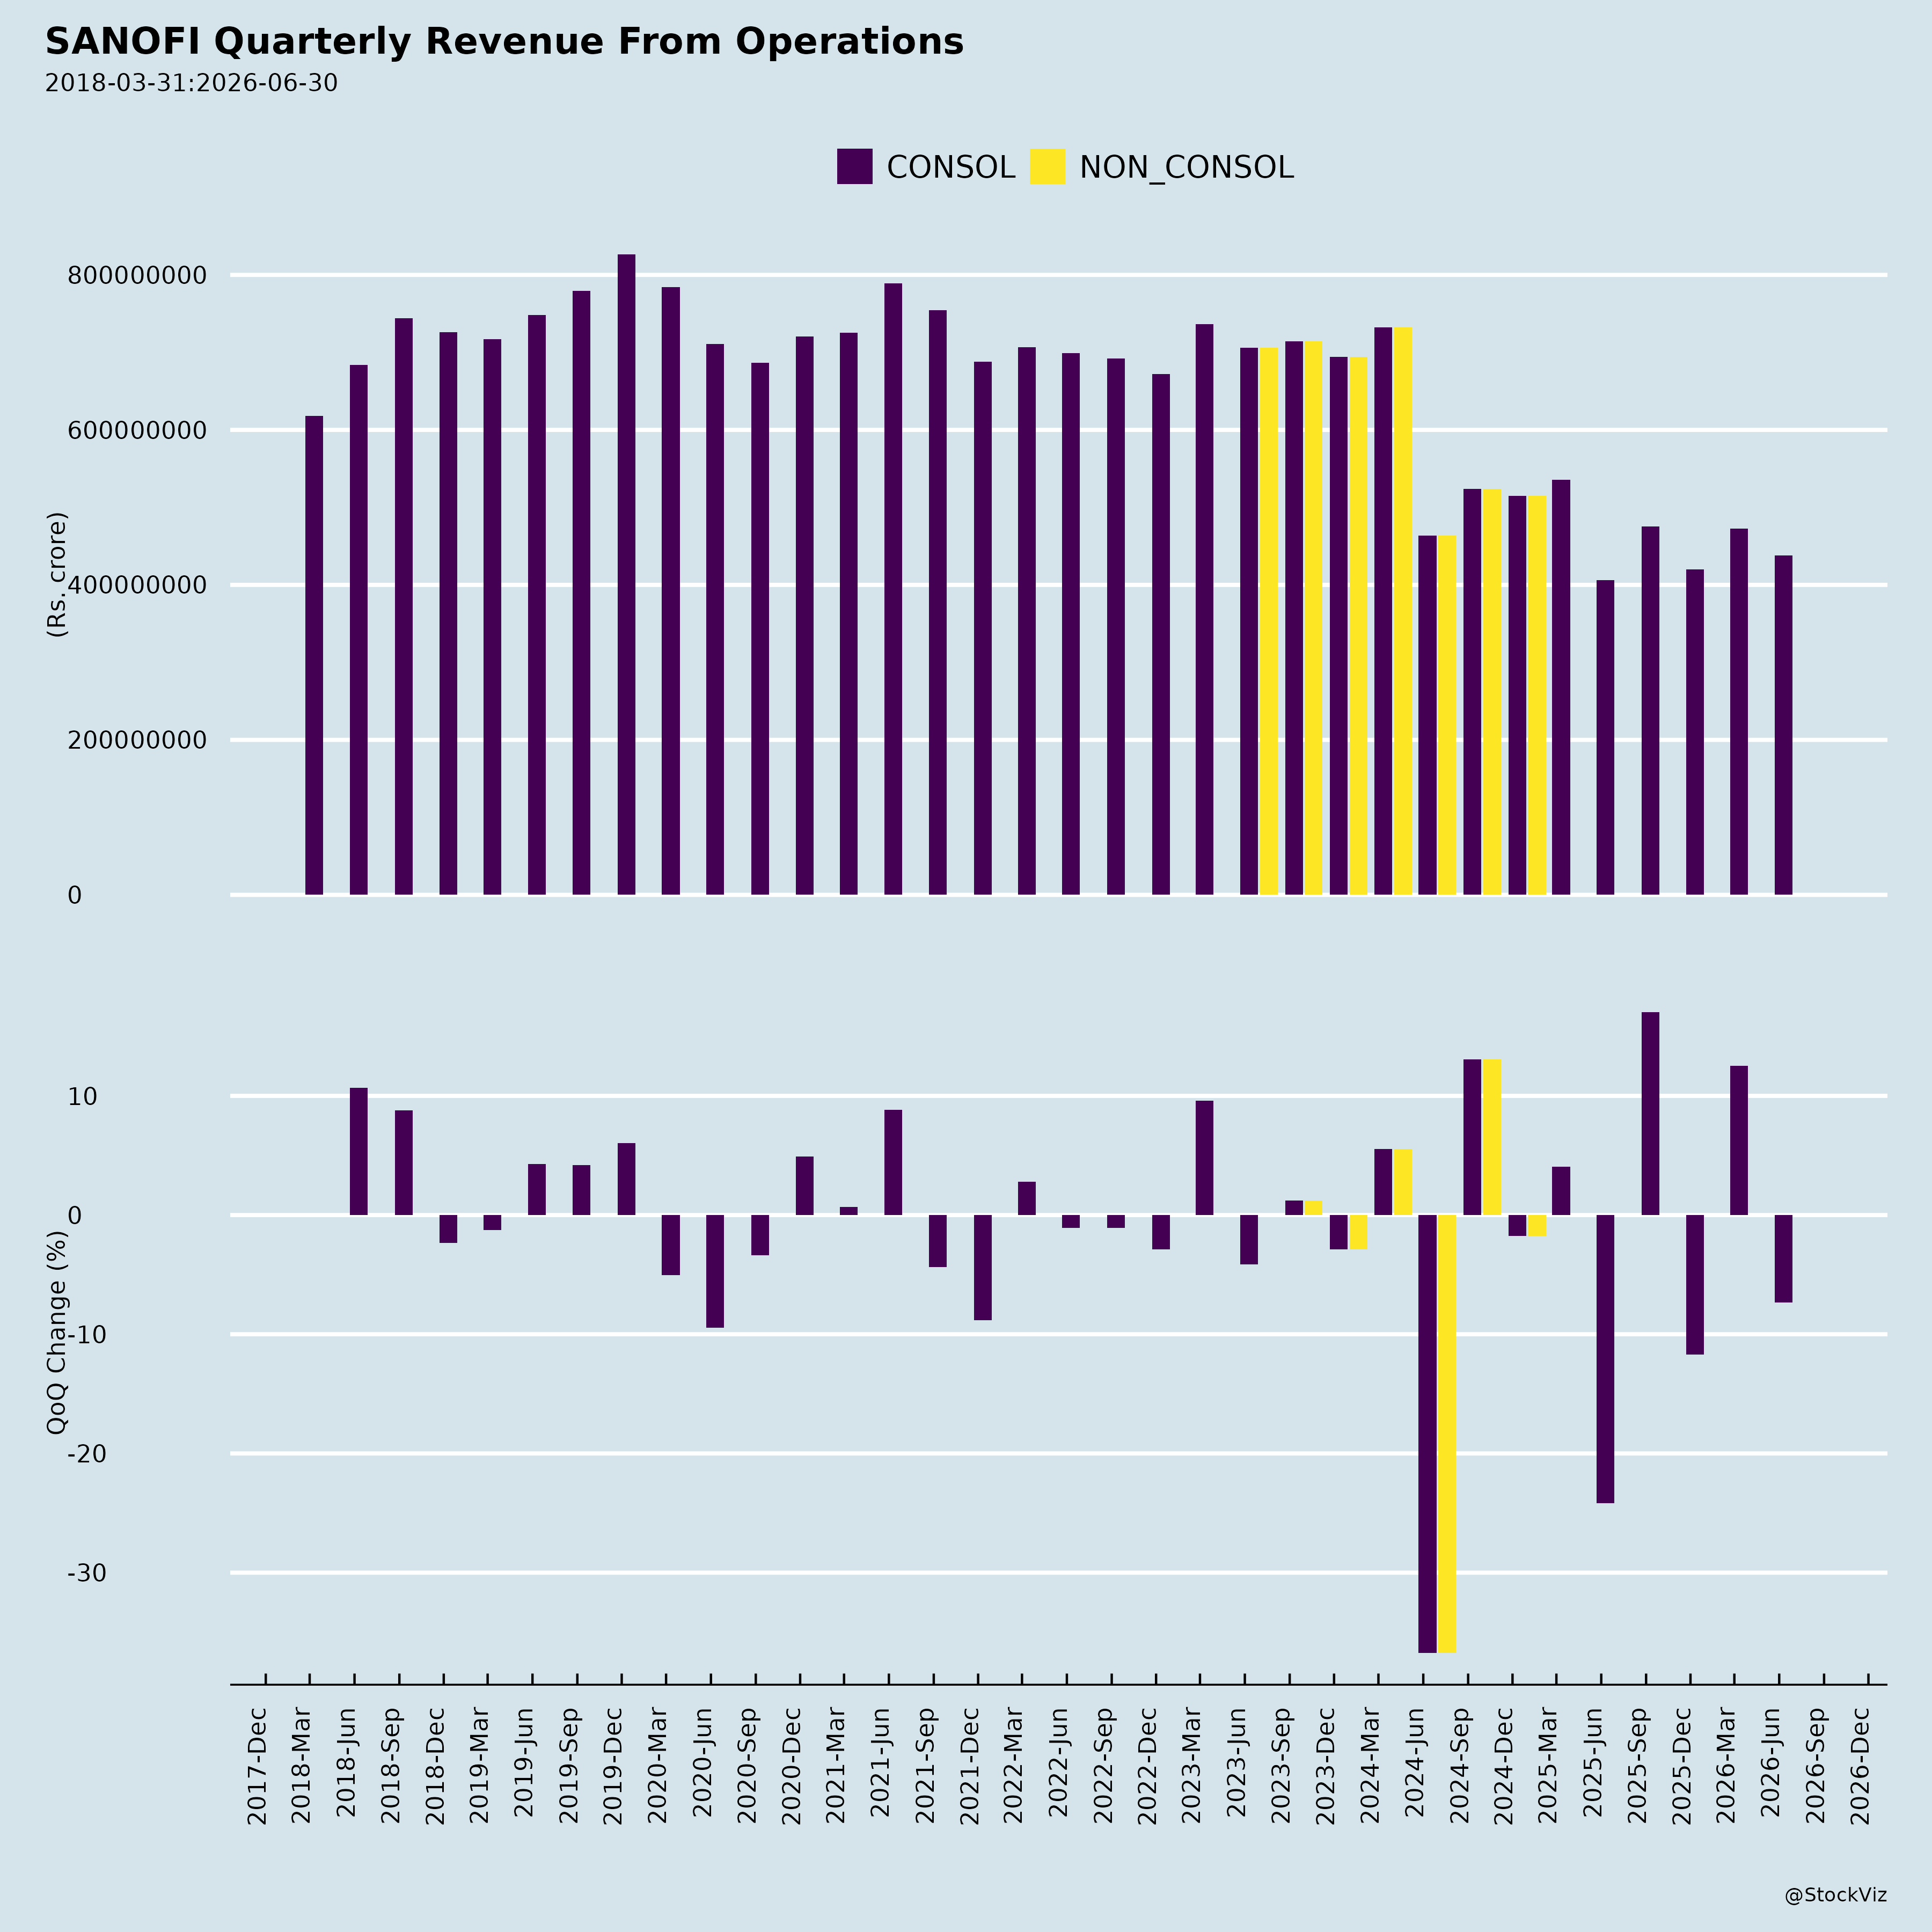
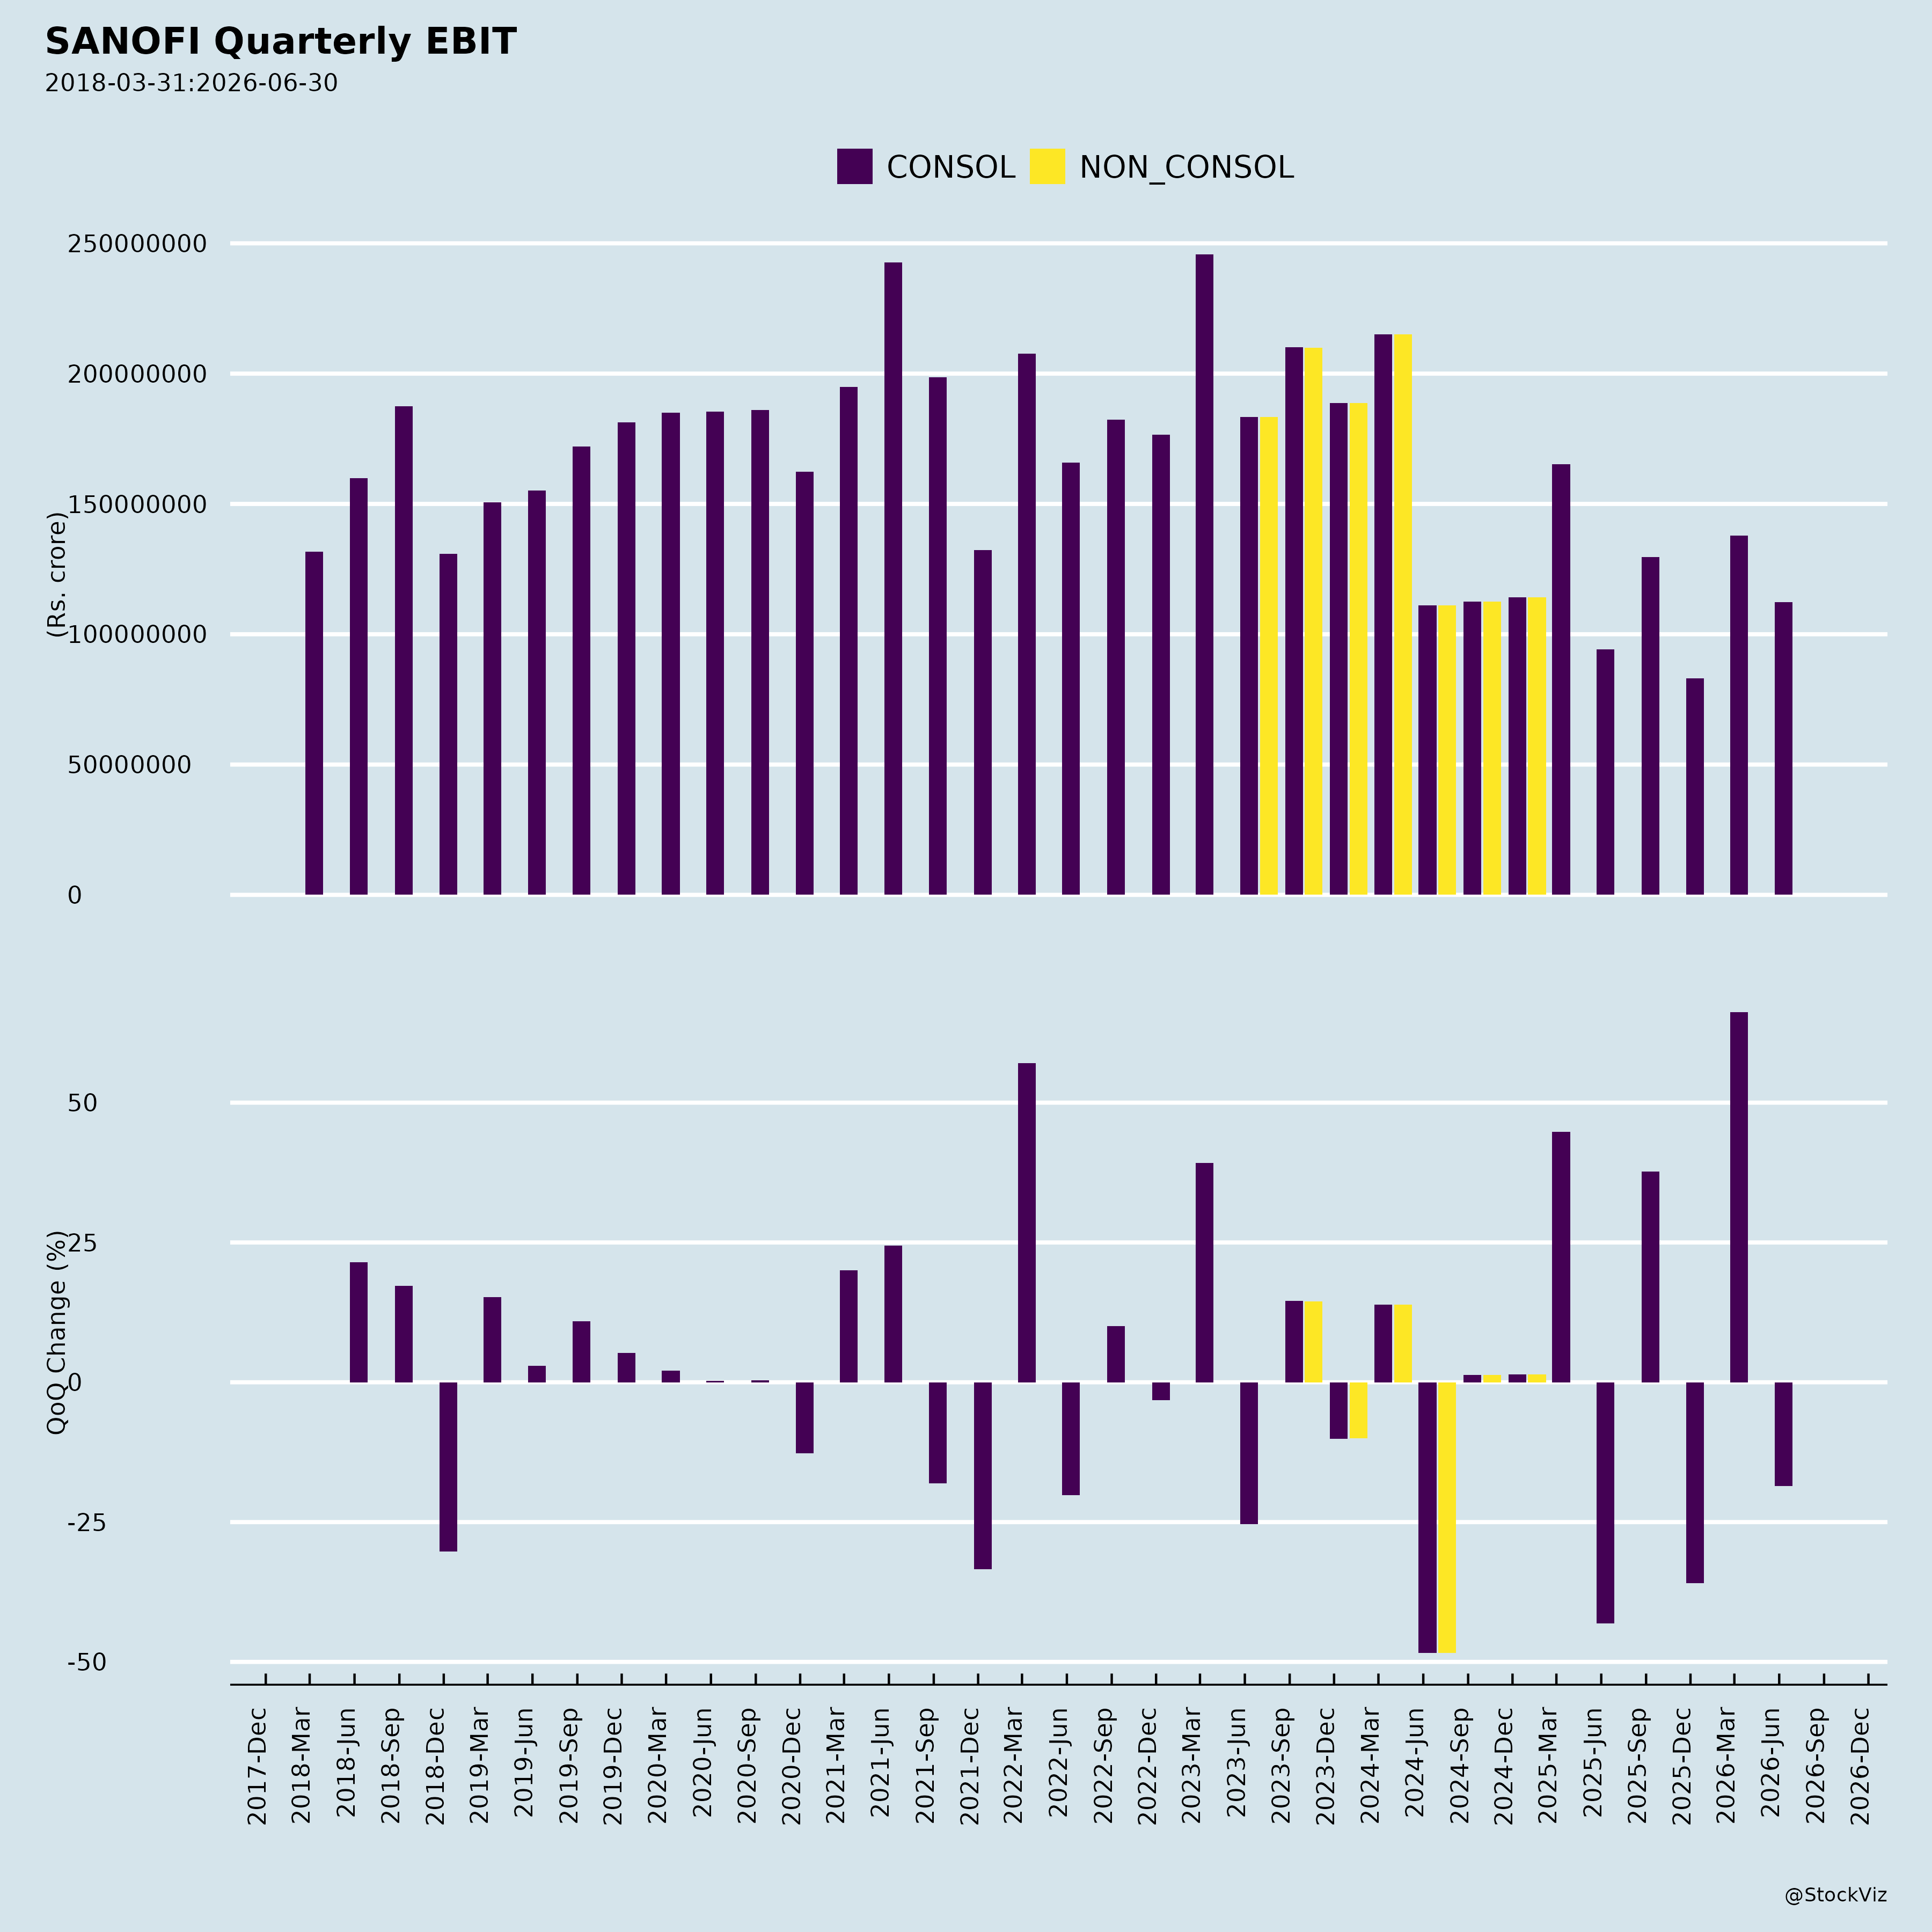
Fundamentals
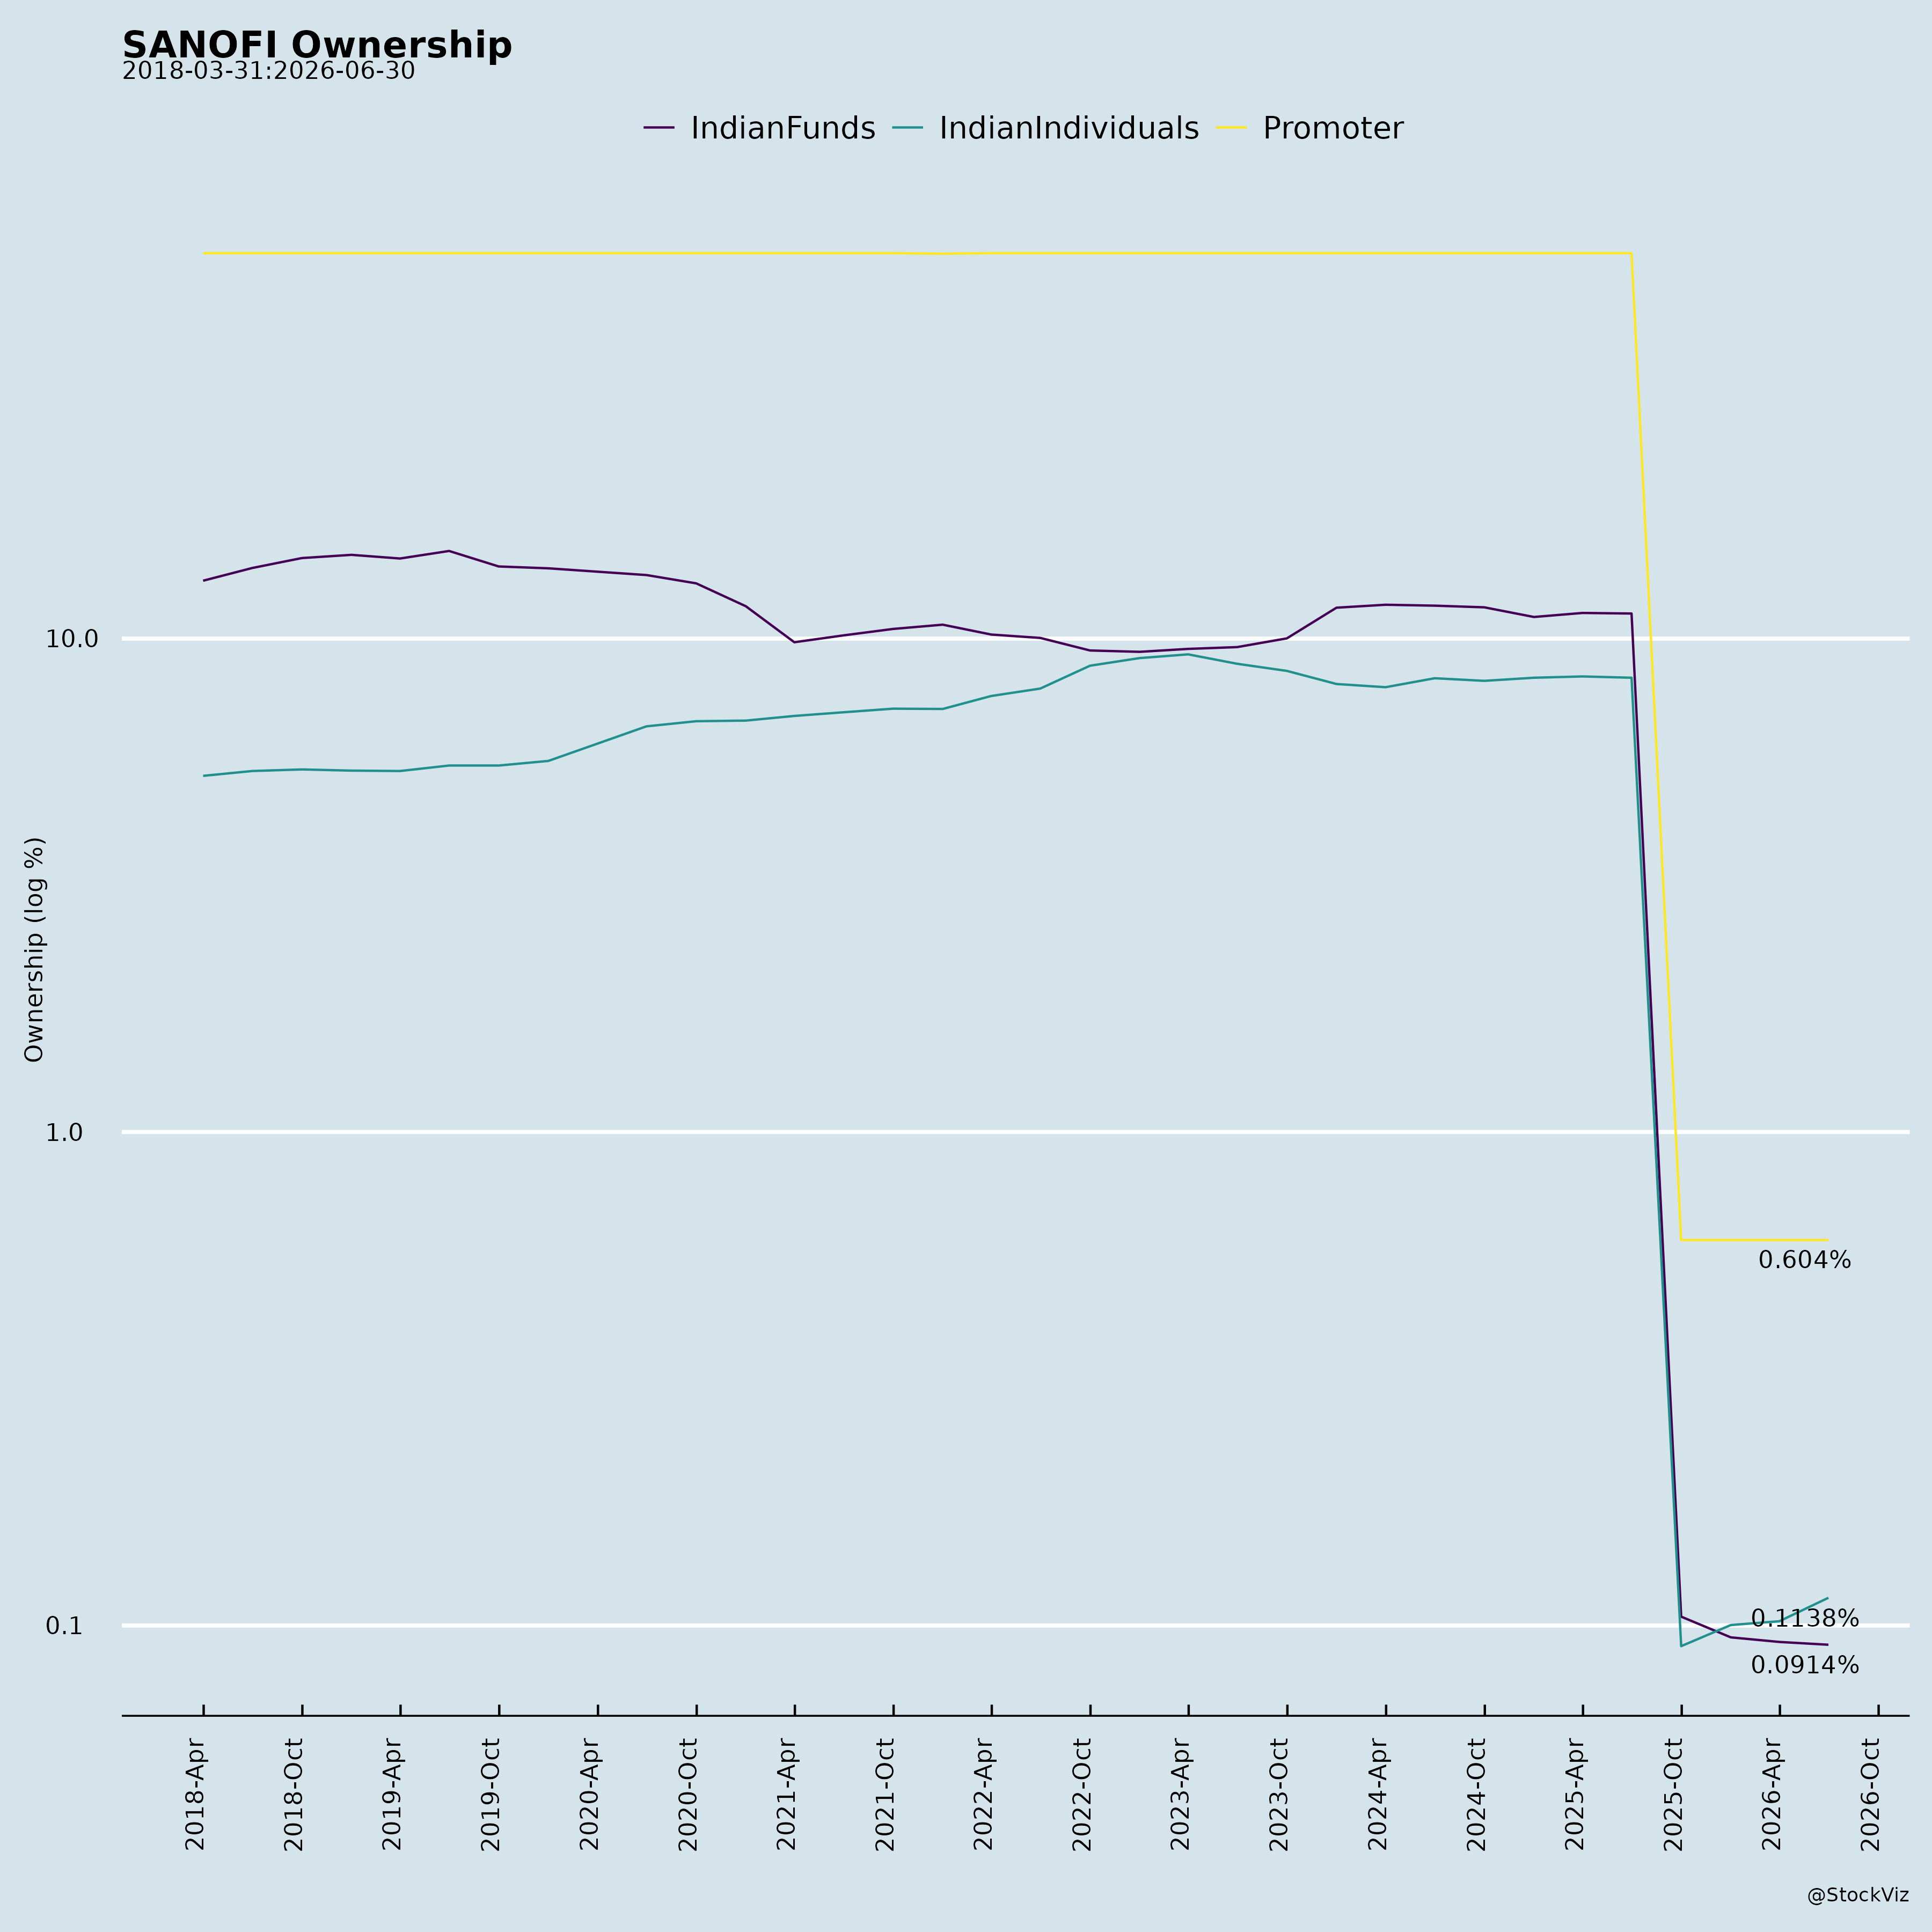
Ownership
Margined
AI Summary
asof: 2026-09-17
Sanofi India — Recent Corporate Announcements
1. Headwinds and Challenges
Partnership business growth remains subdued. The Cardiovascular, Oral Anti-Diabetes (OAD) and CNS partnership portfolio grew only 2% in Q2 2026. Management acknowledged this was below expectation and attributed the Q1 2026 and H1 2026 shortfall largely to one-offs in the prior-year transition period — specifically safety stock built with partners in Q1 2025 and sales-return agreements concluded during the transition. On the Q2 comparison, which management agreed was like-for-like, the 2% growth was described as not in line with industry. Management indicated it does not expect to reach industry growth in 2026, with 2027 being the period under evaluation. Aggressive competition in these genericised portfolios was cited as a continuing factor.
Export business pressure. Export sales declined 2% in Q2 2026 and were a drag on H1, with the Australia market specifically cited as facing heavy competition in mature products. The company is attempting to offset these losses through other markets (France, Italy, Turkey, Russia) and by specialising the Goa site, and is awaiting tender outcomes in South Africa.
H1 top-line contraction. Total income for H1 2026 was down 4% year-on-year, with total net sales down 2%, reflecting the significant Q1 2026 gap. Other operating income declined as certain services previously provided to consumer health are no longer being rendered.
Competitive intensity in insulin. A once-weekly basal insulin (Novo Nordisk’s Awiqli) has entered the market. Management views patient profiles for once-weekly versus once-daily basal analogs as distinct, but acknowledged it is too early to assess the impact and that a quarter of observation is needed.
Legal proceedings. A criminal complaint filed by the Central Bureau of Investigation relating to pharmaceutical supplies made to Bhabha Atomic Research Centre (BARC), Mysore between 2012 and 2015, alleging conspiracy with a BARC personnel to wrongfully influence procurement decisions, remains live. The Hon’ble Supreme Court of India dismissed the Company’s petition seeking quashing of the criminal proceedings on 7 September 2026. The Supreme Court has not recorded any finding of guilt and has not adjudicated on the merits; no penalty, conviction, or operational restriction has been imposed at this stage.
Leadership transition. Mr. Rachid Ayari is stepping down as Whole Time Director and Chief Financial Officer with effect from the close of business hours on 30 September 2026, and his name will be removed from the list of Key Managerial Personnel authorised to determine materiality of events and make disclosures to the stock exchanges.
2. Tailwinds and Growth Prospects
Diabetes franchise momentum. The insulin portfolio delivered 14% double-digit growth in Q2 2026, the second consecutive quarter of such growth, and 17% growth in H1 2026. Growth was powered by Lantus, Toujeo, Apidra and Soliqua. Sanofi retained leadership in the basal analog market with 58% value share and 61% volume share; the diabetes injectable segment value share was cited at 57.3%. Soliqua grew 16% quarter-on-quarter despite erosion in the GLP-1 market.
Public sector acceleration. The public sector business grew 70%, driven by new account openings for Toujeo and Soliqua under the CARE Accounts initiative, expanding into CGHS, ESI, Railway, State and Army channels.
Domestic sales growth. Domestic net sales grew 8% in Q2 2026, and total net sales grew 6%.
Profitability and margin expansion. Profit before tax and exceptional items rose 19% to INR 112 crores in Q2 2026 from INR 94 crores a year earlier, with PBT margin improving to 27% of net sales from 24%. Operating expenses (employee cost plus other expenses) declined 5% in Q2 and 15% in H1, reflecting cost discipline without impacting return-generating projects.
Cash generation. Cash grew 34%, and net cash inflow from operating activities was INR 2,114 million in H1 2026. Management described the balance sheet as healthy with no major risk.
Innovation and access initiatives. Real-world evidence publications for Toujeo and Soliqua, strengthening of Indian guideline positioning, work on novel devices and AI platforms for patient support, and digital outreach in tier 2 and tier 3 markets. On the CSR side, over 600,000 direct beneficiaries are targeted by end-2026, with a new MoU signed with NHM in Madhya Pradesh extending the KiDS and Mobile Medical Units programmes.
Pipeline optionality. Management stated it is evaluating parent pipeline assets for diabetes, and is working on business cases for innovative devices, Bluetooth devices and AI platforms. Discussions with the parent company will continue as the pipeline evolves.
Dividend expectations. Management indicated the payout is expected to be no lower than in the past, though the final decision and proposal rest with the Board.
3. Key Risks
- Continued below-market growth in the partnership portfolio, with recovery pushed to 2027 at the earliest.
- Competitive pressure in export markets, particularly Australia, and dependence on offsetting wins in other geographies and tender outcomes.
- Potential impact of once-weekly basal insulin entry on the insulin portfolio, the extent of which management says requires further observation.
- Aggressive competition in the genericised CV, CNS and OAD portfolios.
- Ongoing criminal proceedings following the Supreme Court’s dismissal of the quashing petition, with the Company assessing the judgment and formulating its next litigation strategy.
- Key managerial transition with the CFO and Whole Time Director stepping down effective 30 September 2026.
4. Management Guidance Versus Observed Performance
Diabetes growth. Management had committed to optimising and maximising the diabetes business unit, growing double-digit and above market. Observed: 14% growth in Q2 2026, the second consecutive quarter of double-digit growth, and 17% in H1 2026 — consistent with the stated commitment.
Partnership performance. The partnership was described as meeting expectations for market reach expansion, with continued return on investment from an expanded commercial footprint. Observed: 2% revenue growth in Q2 2026, which management itself acknowledged was below expectation and not in line with industry. Management guided that 2026 is unlikely to reach industry growth, with 2027 under evaluation.
Cost discipline. Management stated opex reduction would continue as a trend without impacting the top line. Observed: operating expenses declined 5% in Q2 and 15% in H1 2026, with PBT margin expanding from 24% to 27%.
H1 profitability. Management noted that excluding one-offs from last year and transition-period effects, both top line and bottom line would show growth. Observed: reported H1 PBT was down 4%, with the shortfall attributed to the Q1 2026 transition impact.
Dividend. Management expects the payout to be at minimum in line with last year, subject to Board decision.
GST refund. An application to grant GST refund without adjusting it against an outstanding demand of Rs. 75,63,190 was accepted, and a refund of Rs. 1,32,93,535 was sanctioned, with the order received on 12 August 2026. The Company stated there is no material impact on financial, operational or other activities.
Broker Narrative
The first report framed Sanofi as an India-focused restructuring story: cost rationalisation, CHC demerger, diabetes expansion and a manageable Lantus price cut. By the last report, the narrative had shifted to US growth (Revlimid/new launches), price hikes, raw-material softening and FX gains, while acknowledging domestic acute underperformance, regulatory/remediation issues, US price erosion and higher costs. The Buy rating never changed, but the optimism moved from domestic structural catalysts to external/market drivers.
Fears that came true
- The NLEM inclusion/Lantus price-ceiling risk materialised as a ~21% cut, and the subsequent Aug-2023 call ended in a -16% DISAPPOINTMENT.
- The early regulatory overhang broadened into the ‘regulatory issues and remediation processes’ cited in the last report, coinciding with the -38.4% and -43% DISAPPOINTMENT outcomes.
Optimism that failed
- The ‘India for India’ cost-rationalisation and broad-based growth tailwind faded: by the last report the acute portfolio was underperforming and R&D/other expenses had increased.
Broker Timeline
10 broker calls · 2023-05-11 to 2025-07-11
Copyright © 2023 SAS Data Analytics Pvt. Ltd. All rights reserved.