SAILIFE
Equity Metrics
November 18, 2026
Sai Life Sciences Limited
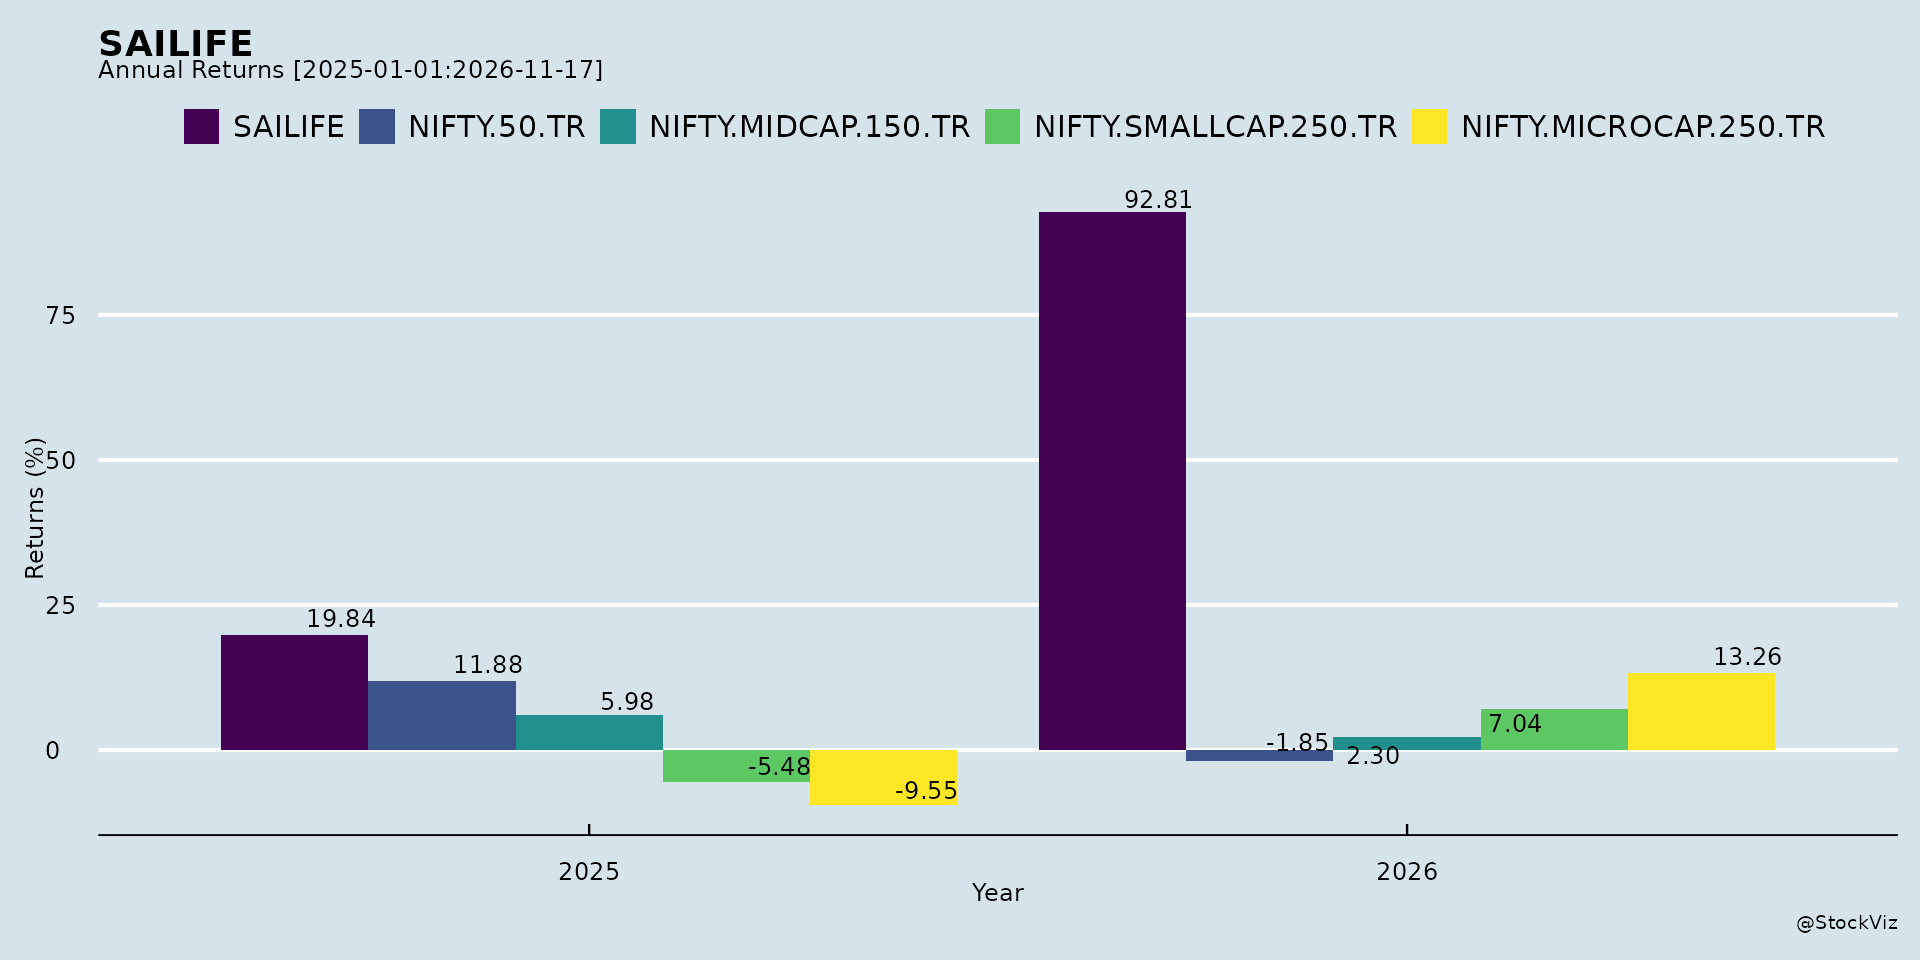
Annual Returns

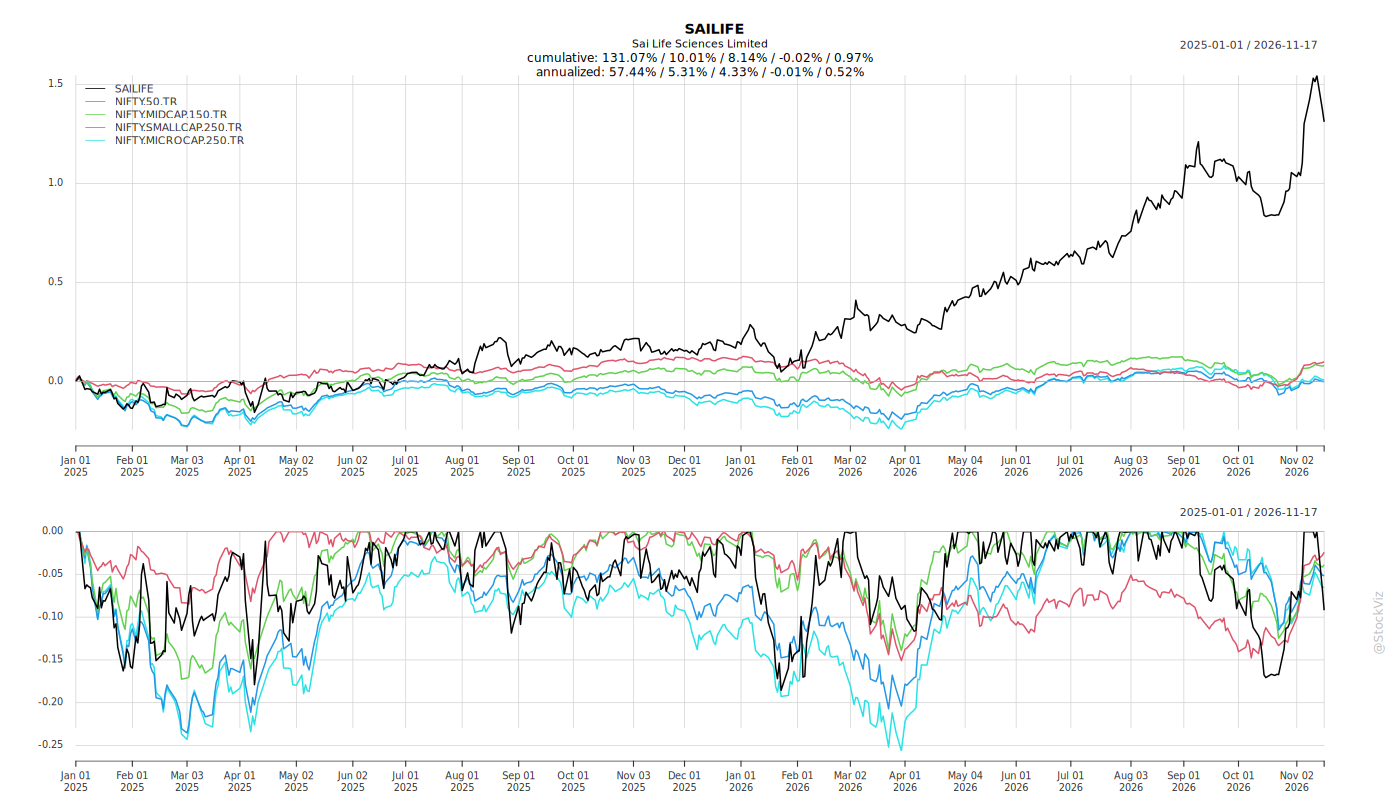
Cumulative Returns and Drawdowns
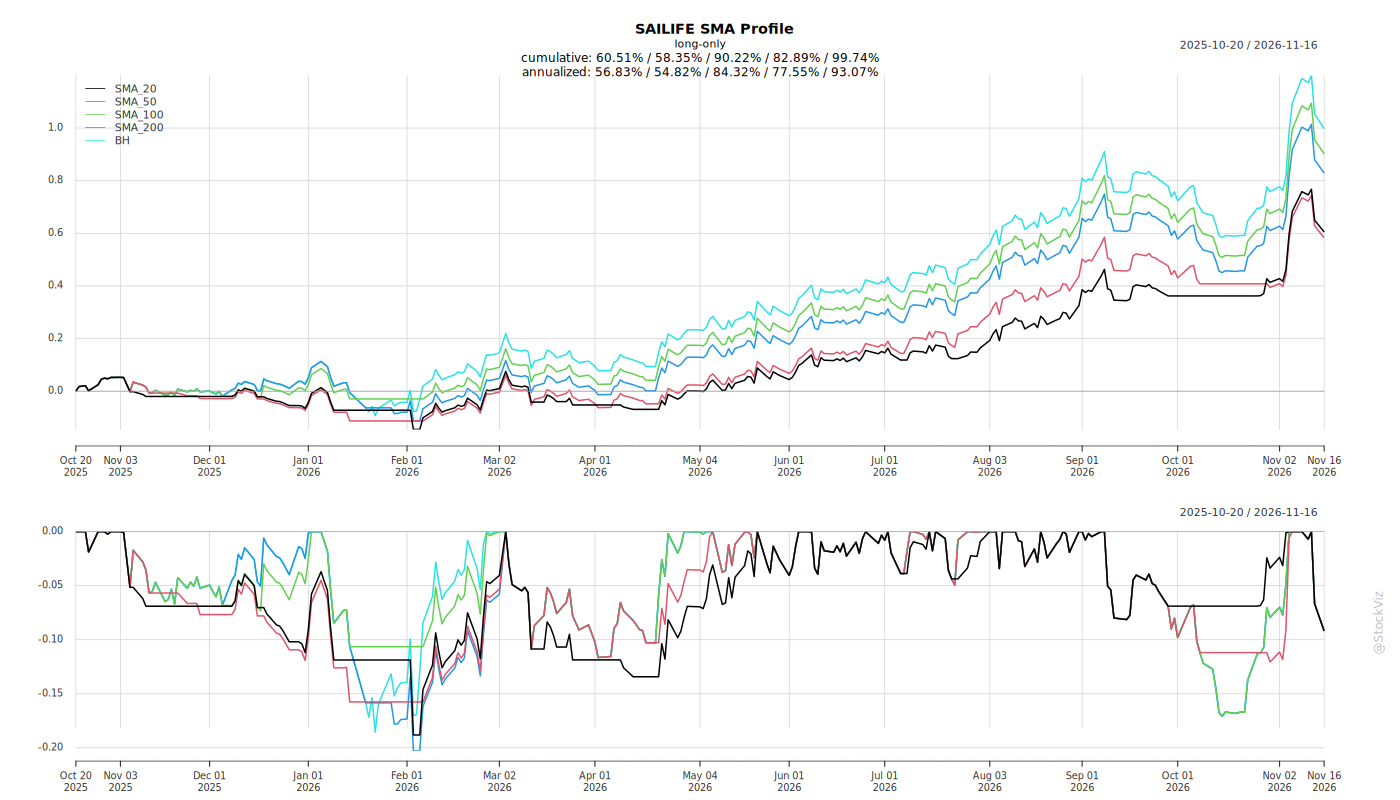
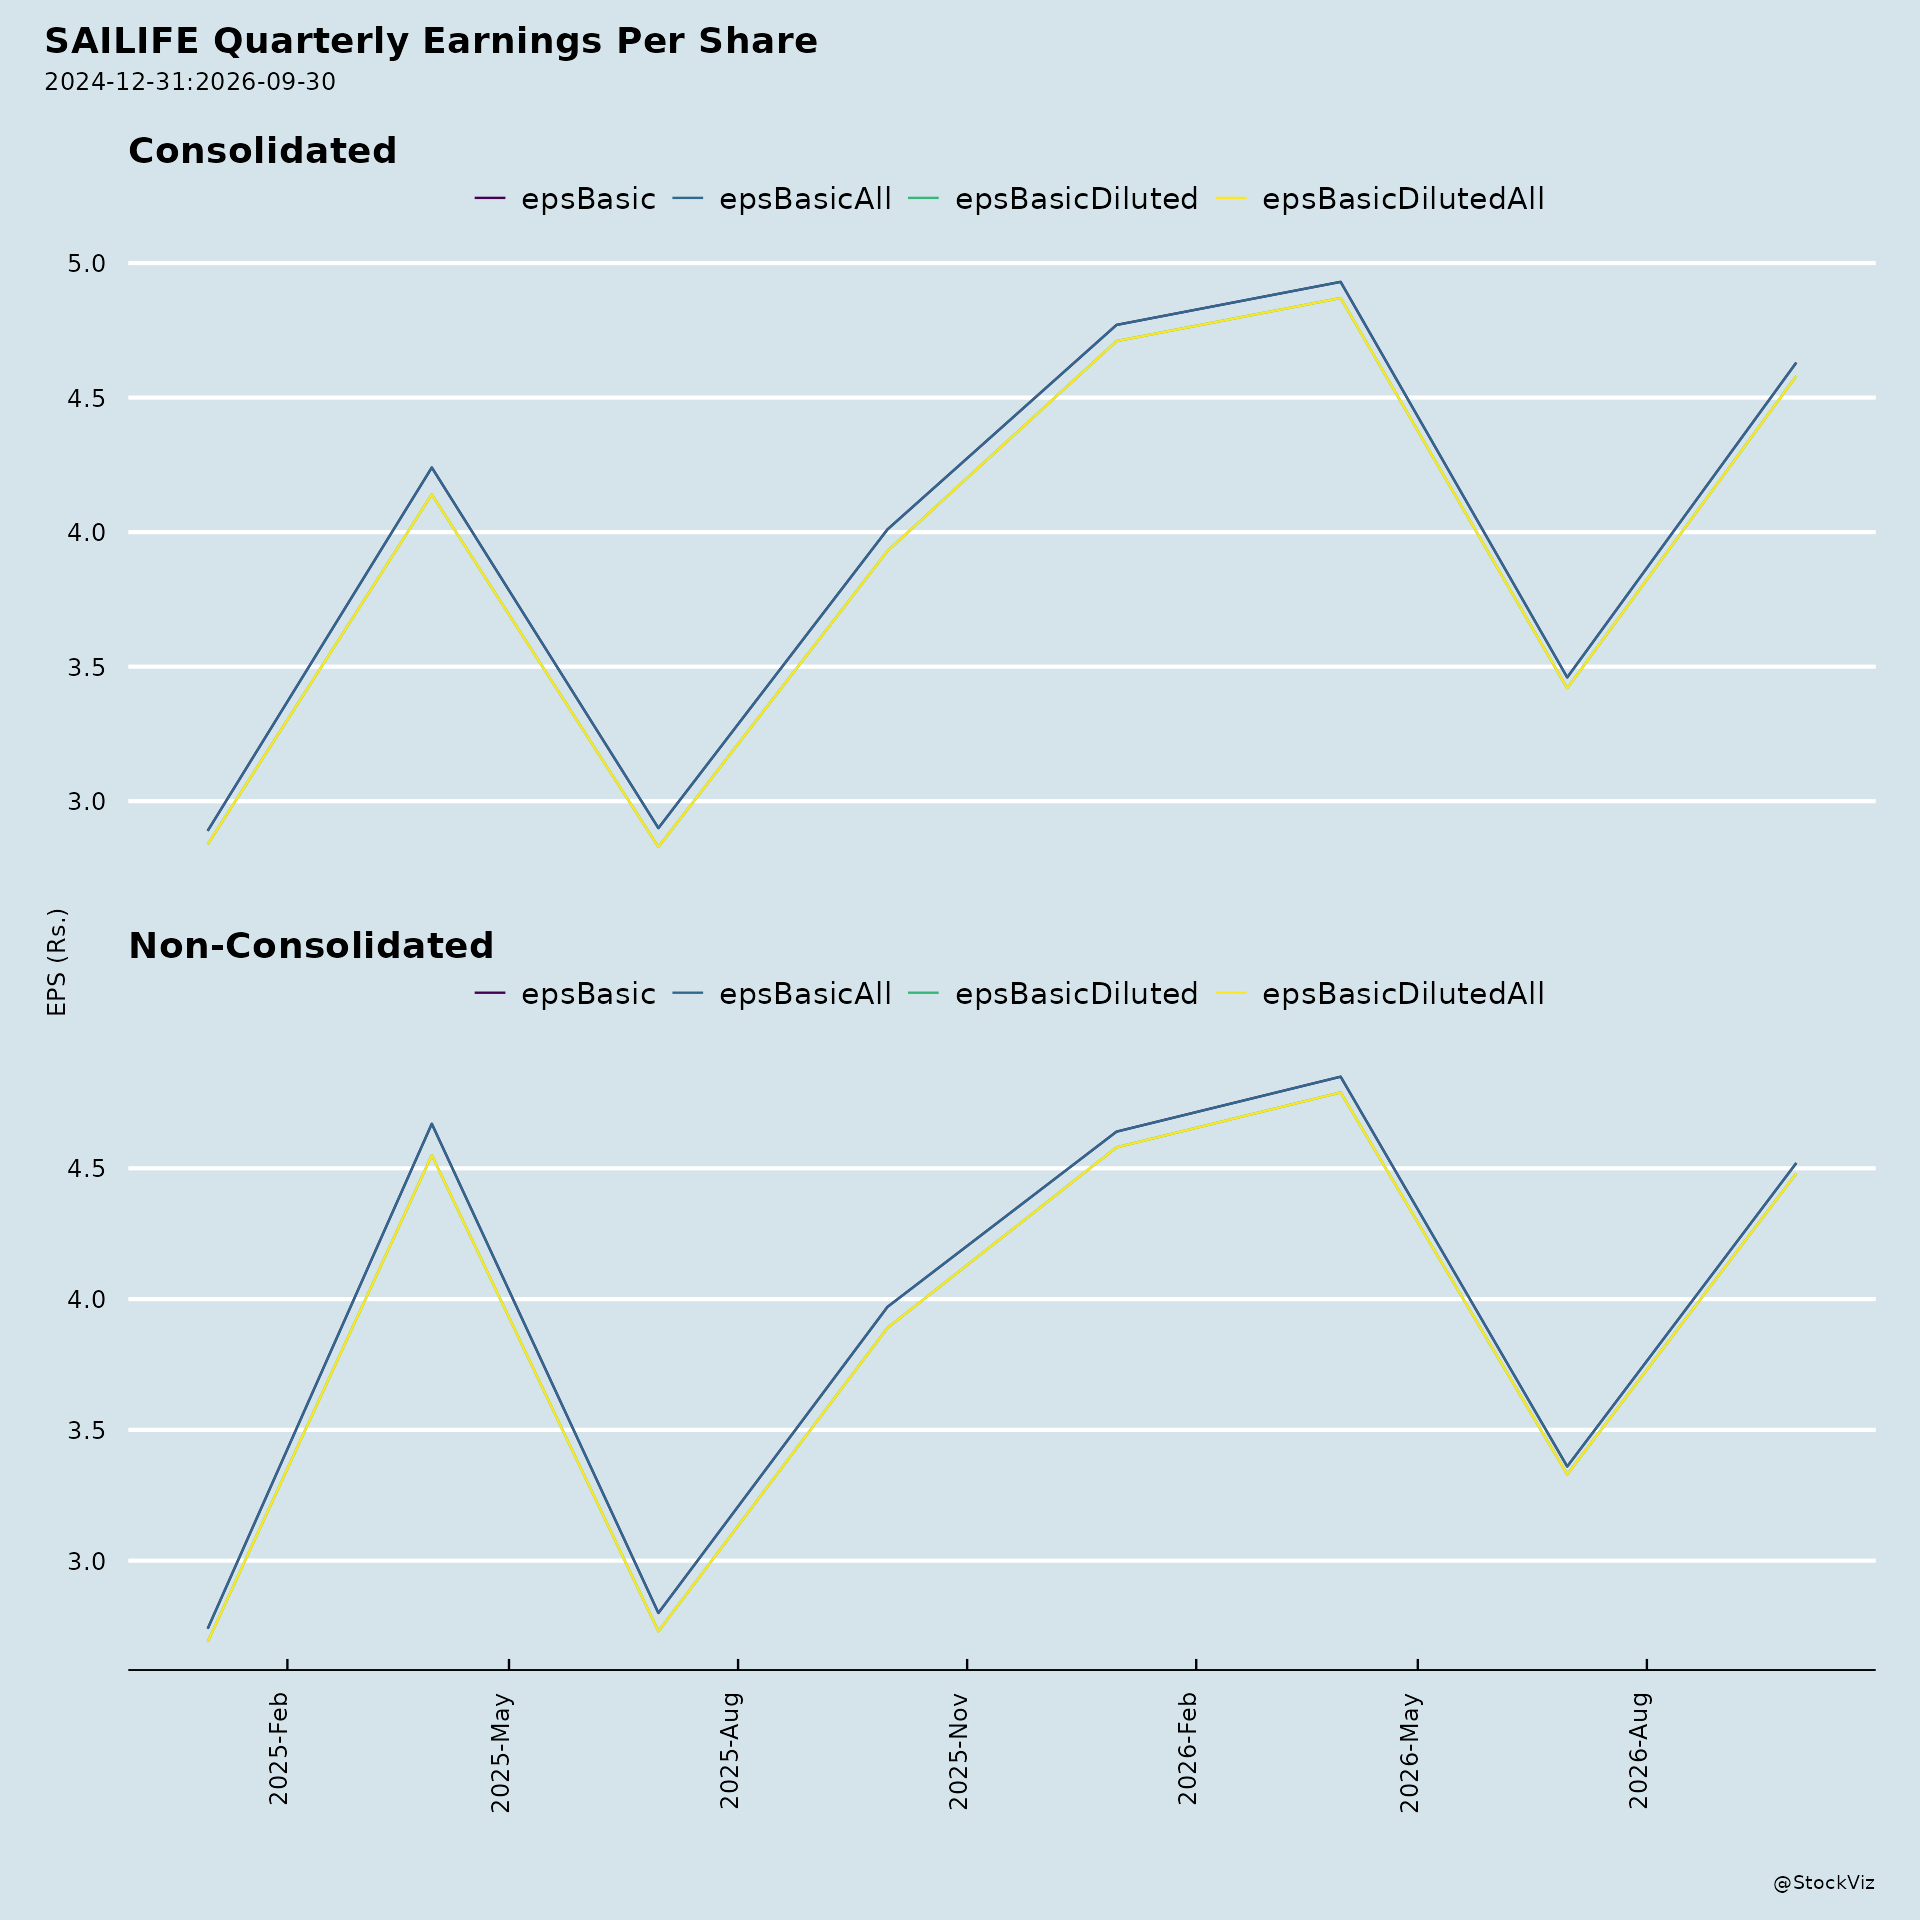
Fundamentals
Ownership
Margined
AI Summary
asof: 2026-09-16
Sai Life Sciences — Q1FY27 and Recent Announcements
1. Headwinds and Challenges
- The company operates in a single segment — Contract Research, Development and Manufacturing Services (CRDMO) — so performance is tied to demand from innovator pharmaceutical and biotech clients rather than diversified businesses.
- The Labour Codes notified by the Government of India on 21 November 2025 changed the definition of wages, increasing gratuity liability (past service cost) and compensated absences liability by Rs. 82.93 million for the quarter and nine months ended 31 December 2025. This was treated as an exceptional, non-recurring item. A reassessment in the quarter ended 31 March 2026, based on a revised remuneration structure, produced a credit of Rs. 2.92 million, leaving a net expense of Rs. 80.01 million for FY26. The company has stated that further clarification from the Government on other aspects of the Labour Codes will be evaluated and any differential impact accounted for in subsequent periods.
- Forward-looking statements in the company’s own disclosures flag risks and uncertainties including: general economic and business conditions in India; ability to successfully implement strategy; research and development efforts; growth and expansion plans; obtaining regulatory approvals; provisioning policies; technological changes; investment and business income; cash flow projections; exposure to market risks; changes in laws and regulations applicable to pharmaceuticals; increasing competition; and changes in political conditions in India.
- The analyst/institutional investor meeting schedule is subject to change due to exigencies on the part of participants or the company.
2. Tailwinds and Growth Prospects
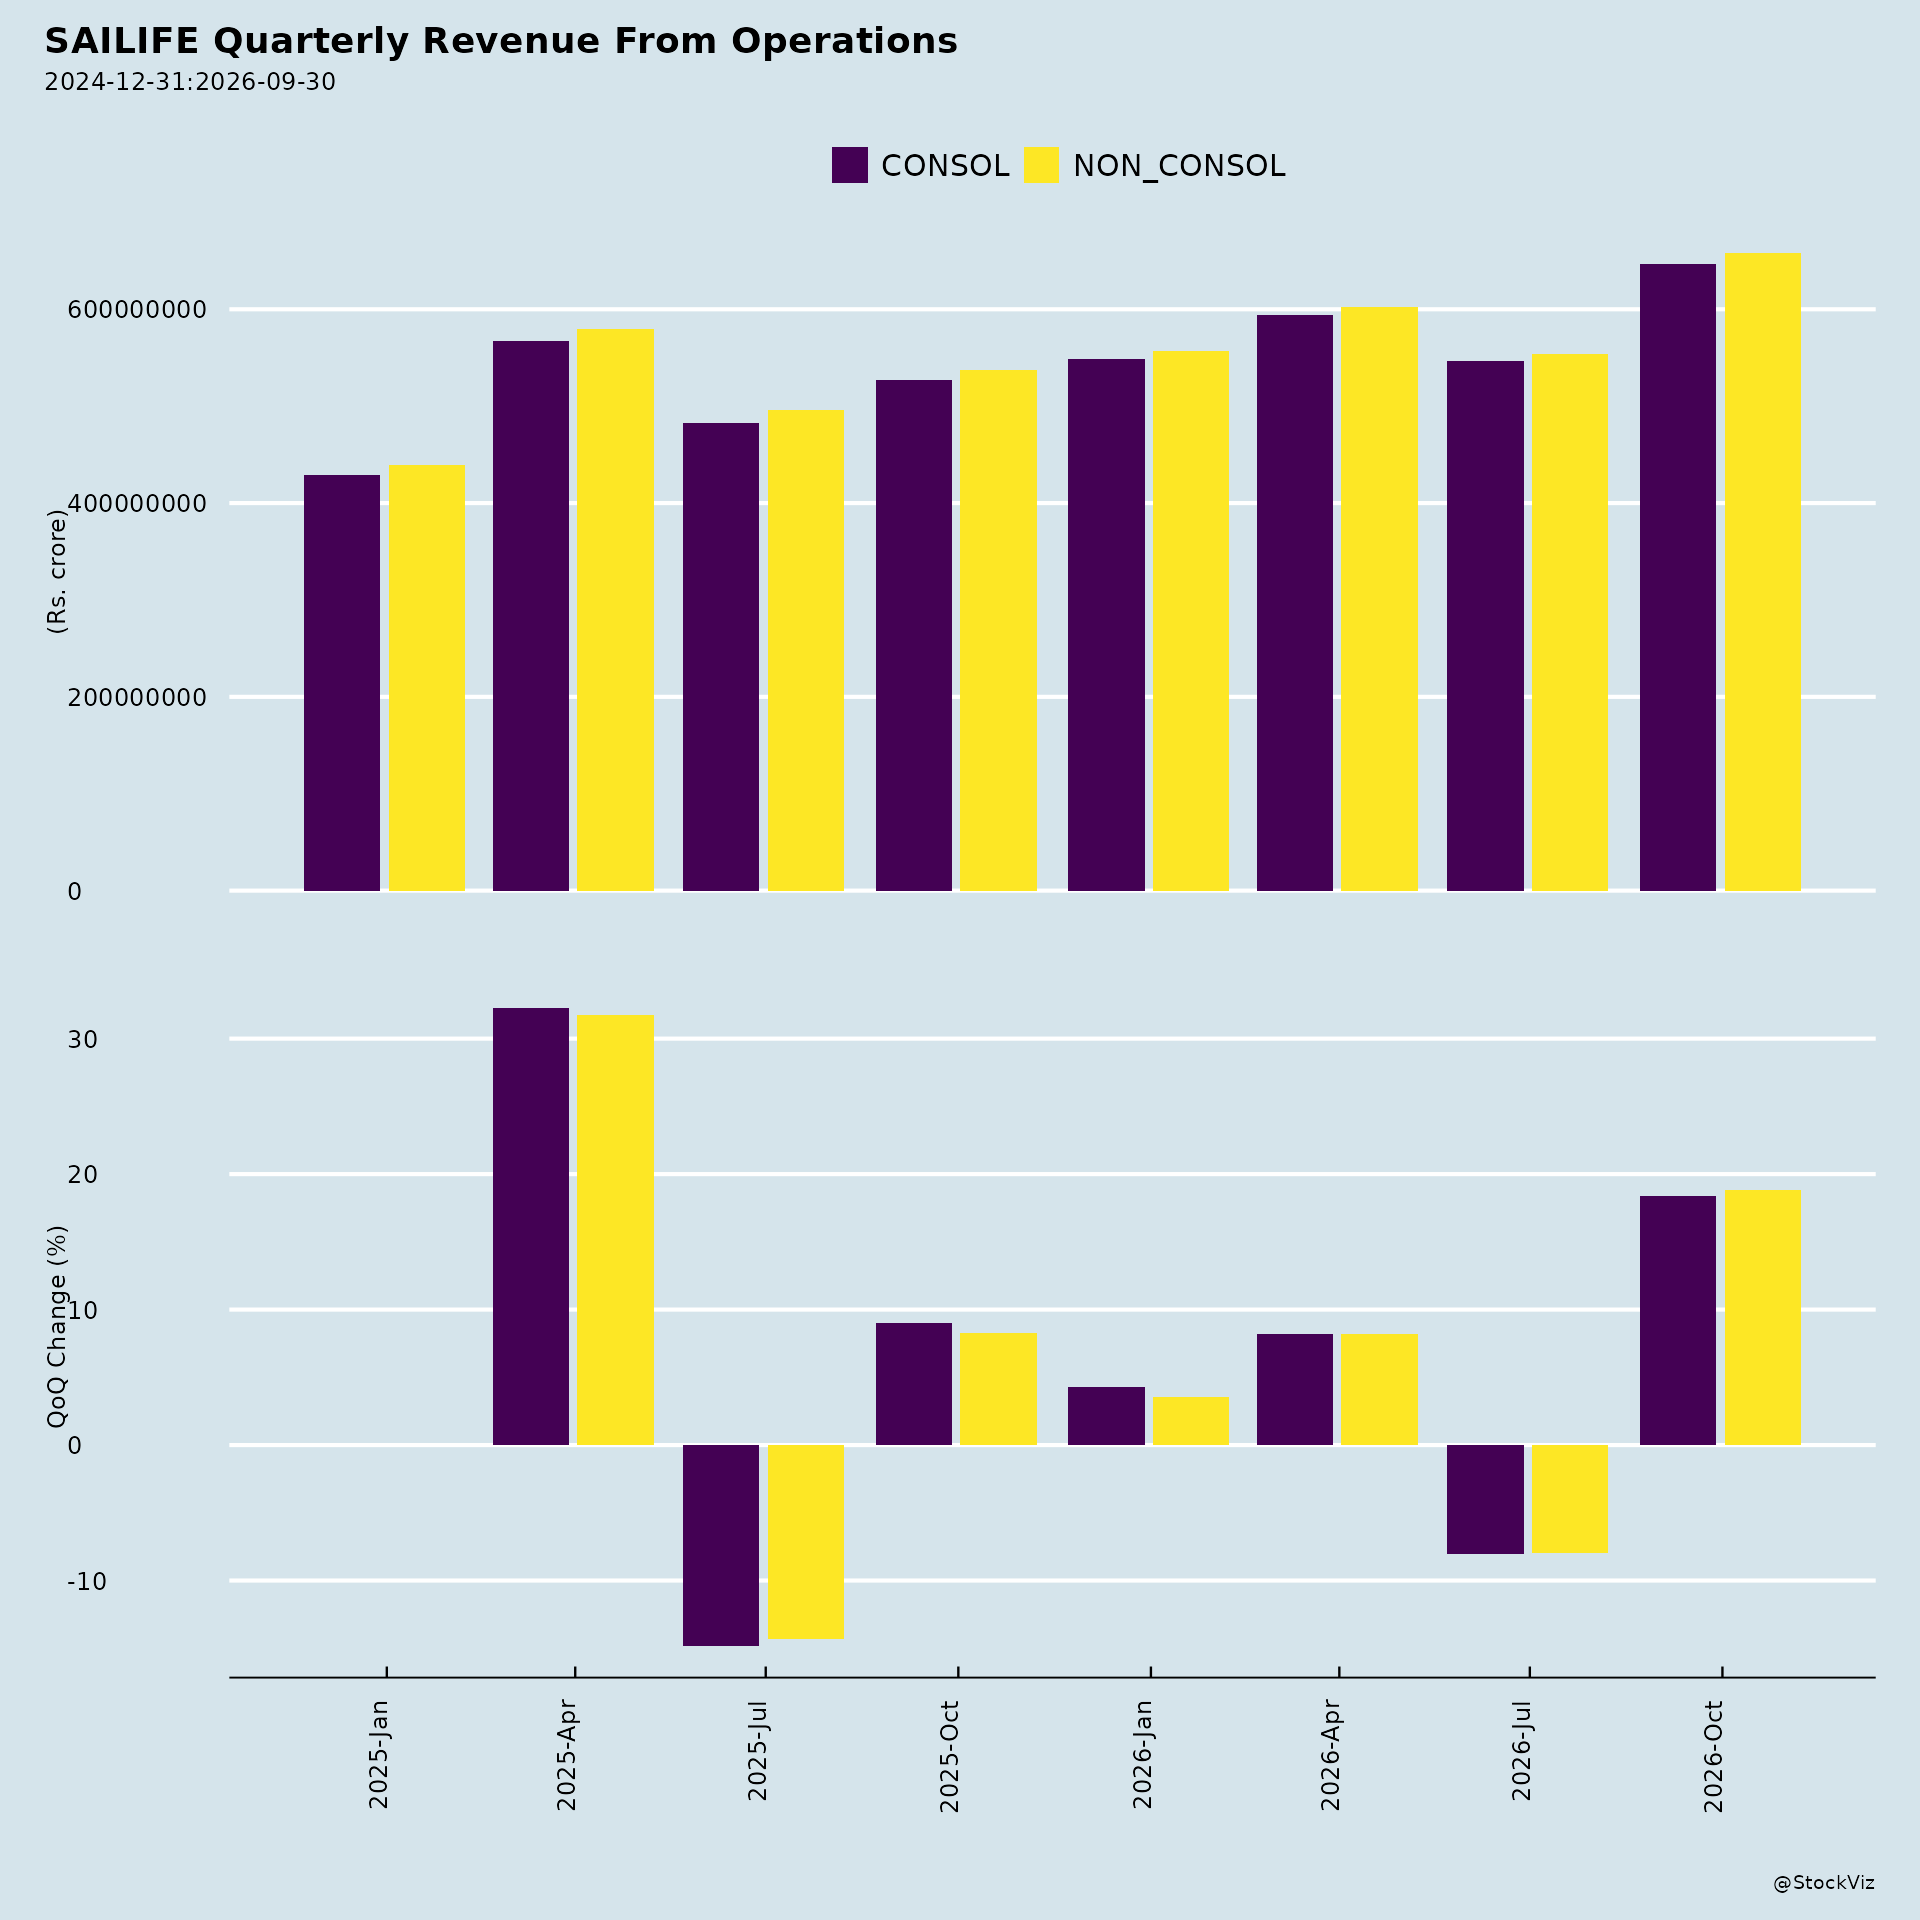
- Q1FY27 revenue from operations was ₹554 crore, up 12% year-on-year, with growth across both CRO and CDMO businesses. CRO grew 24% year-on-year.
- The CMC pipeline continues to strengthen, with 33 active commercial molecules and 14 late-phase molecules.
- Management describes an evolution in what large pharmaceutical companies seek from outsourcing partners — scientifically led partners who take greater ownership of integrated discovery and development programs rather than executing individual pieces of work. Sai Life believes its technology base, scientific talent and culture are key reasons large pharmaceutical companies are bringing significant work to it through strategic engagements, which management expects to create a healthy and sustained pipeline over multiple years.
- Encouraging traction is reported in the FTE-led engagement model.
- Growth prospects cited include expansion in CRO and CDMO businesses, expansion in new-age modalities such as peptides, ADCs and oligos, and digitization and automation initiatives.
- The company has expanded relationships with global pharmaceutical partners, added new commercial molecules, strengthened strategic collaborations, successfully undergone major regulatory inspections, and completed its IPO in December 2024.
- Consolidated revenue increased from ₹870 crore in FY2022 to ₹2,242 crore in FY2026; EBITDA rose from ₹131 crore to ₹661 crore; PAT rose from ₹6 crore to ₹349 crore, reflecting improvements in scale, profitability and operational excellence.
- The company reports over 300 active global clients, including 19 of the top 25 global pharma companies, 3,800+ total employees, world-class R&D and manufacturing facilities, and a 100% successful track record of regulatory inspections.
- During Q1FY27 the company operationalized a new 100,000 sq. ft. R&D facility at Genome Valley, Hyderabad, and achieved an EcoVadis Platinum Rating for sustainability, joining the top 1% of companies assessed worldwide.
3. Key Risks
- Risks and uncertainties explicitly noted in the company’s forward-looking statements: ability to successfully implement strategy, growth and expansion plans, obtain regulatory approvals, provisioning policies, technological changes, investment and business income, cash flow projections, and exposure to market risks.
- Broader factors cited: general economic and business conditions in India, research and development efforts, changes in laws and regulations applicable to pharmaceuticals, increasing competition, and changes in political conditions in India.
- The company cautions that forward-looking statements are not guarantees of future performance and that undue reliance should not be placed on them; it assumes no obligation to update forward-looking statements except as required by applicable securities laws.
- Potential further financial impact from the Labour Codes remains open, pending any additional Government clarification.
4. Management Guidance vs. Observed Performance
- Management has expressed confidence in sustaining long-term revenue growth guidance of 15–20% and an EBITDA range of 28–30%.
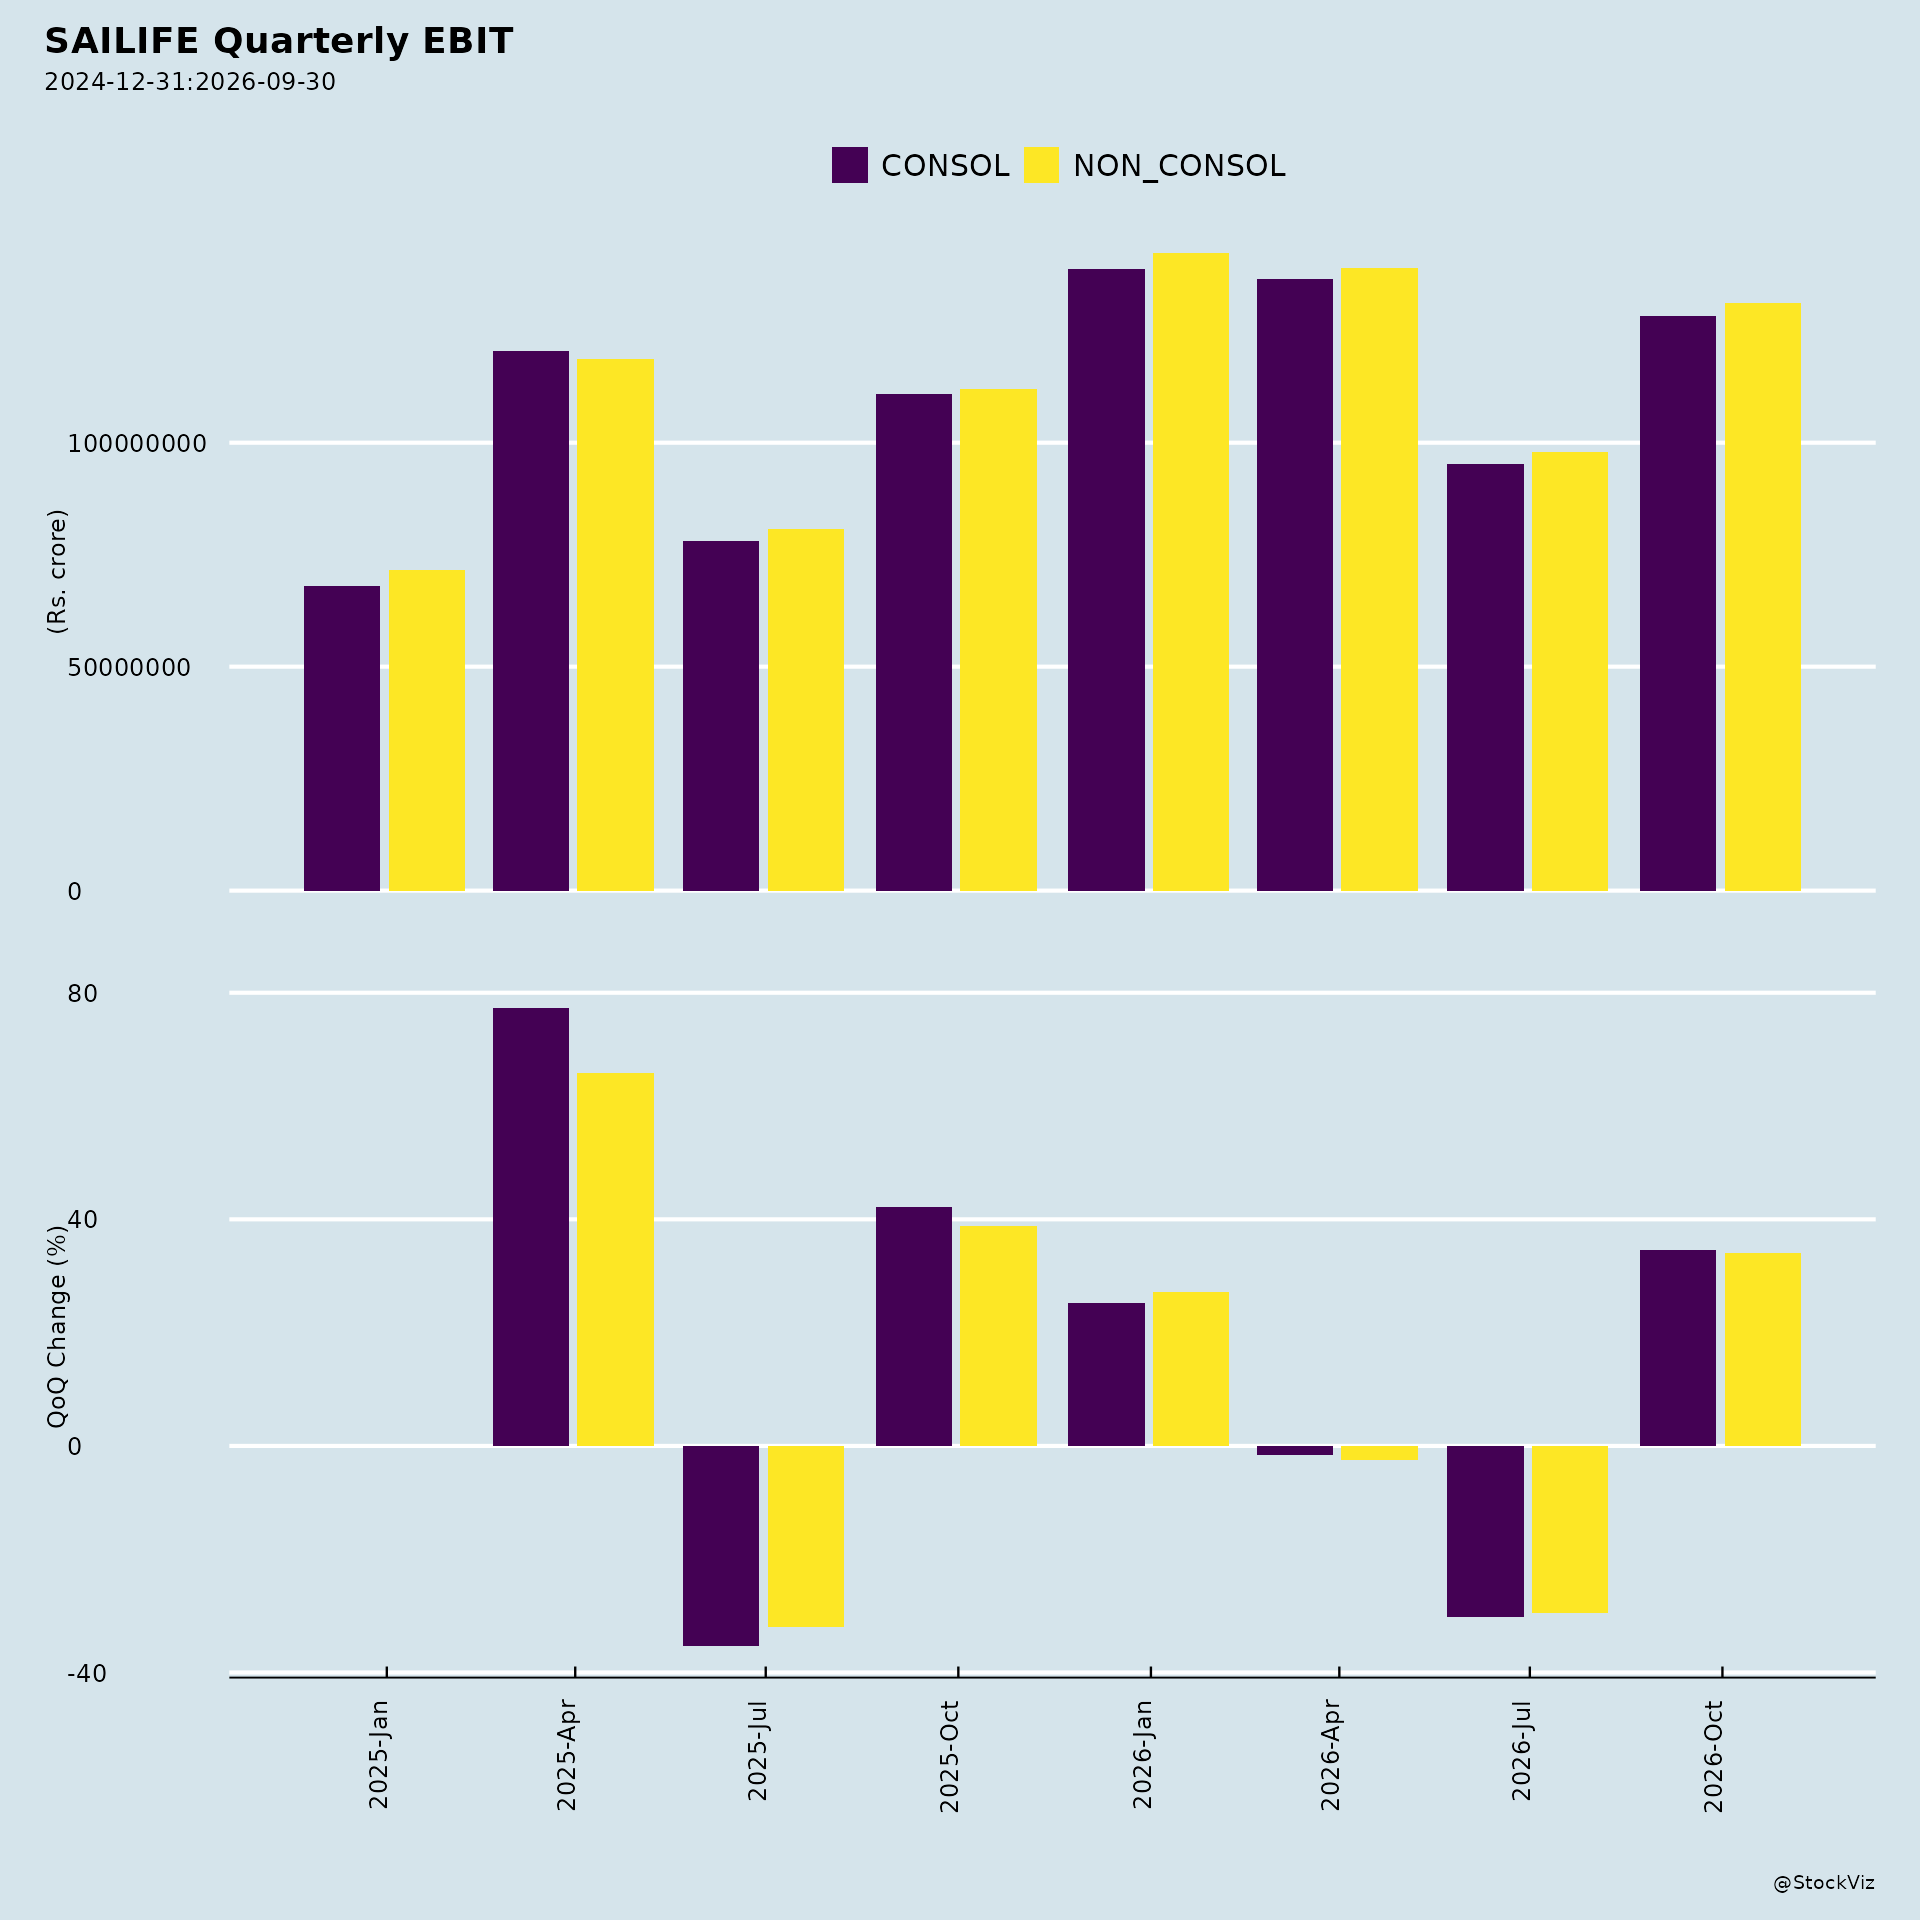
- Observed Q1FY27 performance: revenue from operations of ₹554 crore, up 12% year-on-year; EBITDA of ₹148 crore, up 18% year-on-year, with an EBITDA margin of 27%; PAT of ₹73 crore, up 22% year-on-year, with a PAT margin of 13%. Material margin was ₹409 crore, up 15% year-on-year.
- The Q1FY27 revenue growth of 12% is below the stated long-term revenue growth guidance range of 15–20%, while the reported EBITDA margin of 27% is slightly below the stated 28–30% range.
- On a consolidated basis, Q1FY27 revenue from operations was ₹5,542.85 million (₹554 crore), profit before exceptional items and tax was ₹979.74 million, and profit for the period was ₹732.85 million. Basic EPS was ₹3.46 and diluted EPS ₹3.42 (not annualised).
- On a standalone basis, Q1FY27 revenue from operations was ₹5,467.29 million, profit before tax was ₹953.34 million, and profit for the period was ₹713.39 million. Basic EPS was ₹3.36 and diluted EPS ₹3.33 (not annualised).
- The statutory auditors, Deloitte Haskins & Sells LLP, issued an unmodified conclusion on both the standalone and consolidated results for the quarter ended 30 June 2026.
- The Board meeting on 06 August 2026 commenced at 08:10 PM IST and concluded at 9:00 PM IST; an earnings call was scheduled for 4:00 PM IST on 07 August 2026.
- The 27th Annual General Meeting is scheduled for Thursday, 17 September 2026 at 10:30 A.M. IST via video conferencing/OAVM, with a cut-off date of 10 September 2026 for voting eligibility and remote e-voting from 9:00 a.m. IST on 14 September 2026 to 5:00 p.m. IST on 16 September 2026. Mr. Krishnamraju Kanumuri (DIN: 00064614), Managing Director and CEO, retires by rotation and offers himself for re-appointment.
- Officials of Sai Life Sciences will attend the Jefferies 5th India Forum on Friday, 18 September 2026, from 09:00 A.M. to 06:00 P.M. IST in Gurgaon for group/one-on-one in-person meetings, with discussions based strictly on publicly available information and without sharing unpublished price sensitive information.
Broker Timeline
1 broker calls · 2026-10-21 to 2026-10-21
CNBC-TV18: ratings, targets and commentary
No recorded CNBC-TV18 statements for this ticker.
Management comments
No recorded management comments with an explicit designation and affiliation for this ticker.
Copyright © 2023 SAS Data Analytics Pvt. Ltd. All rights reserved.