RVNL
Equity Metrics
November 18, 2026
Rail Vikas Nigam Limited
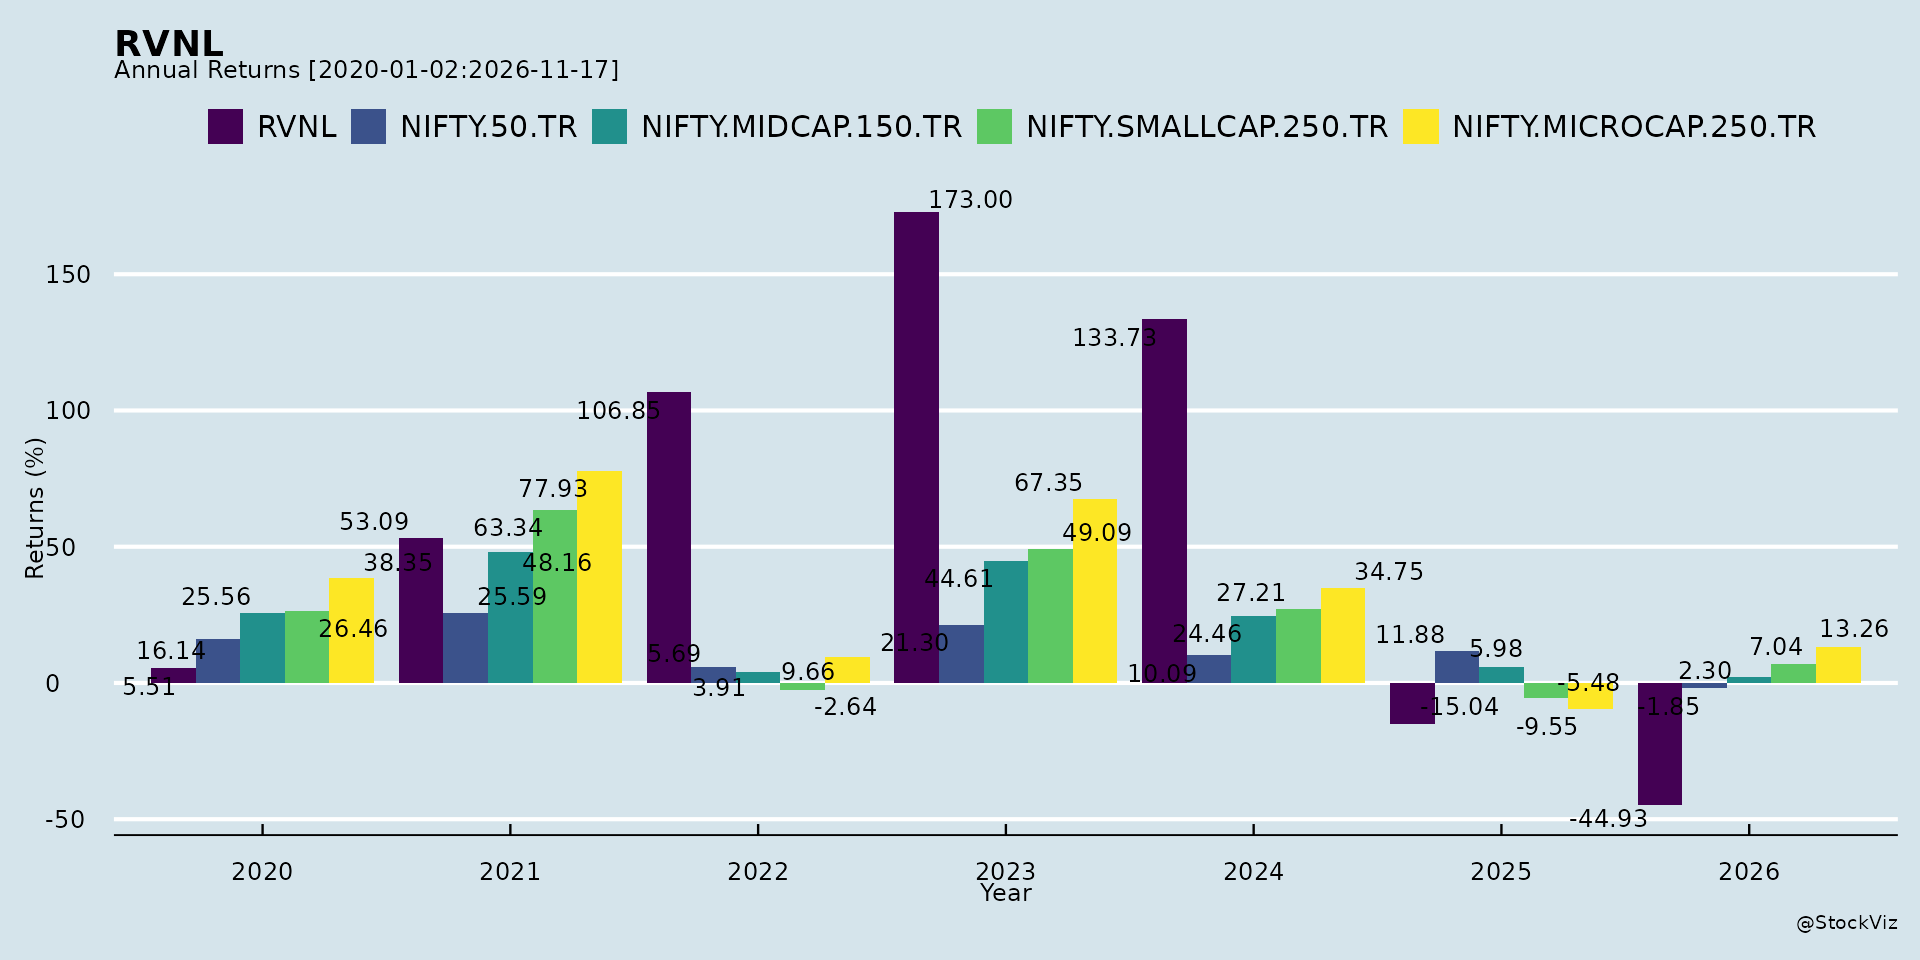
Annual Returns
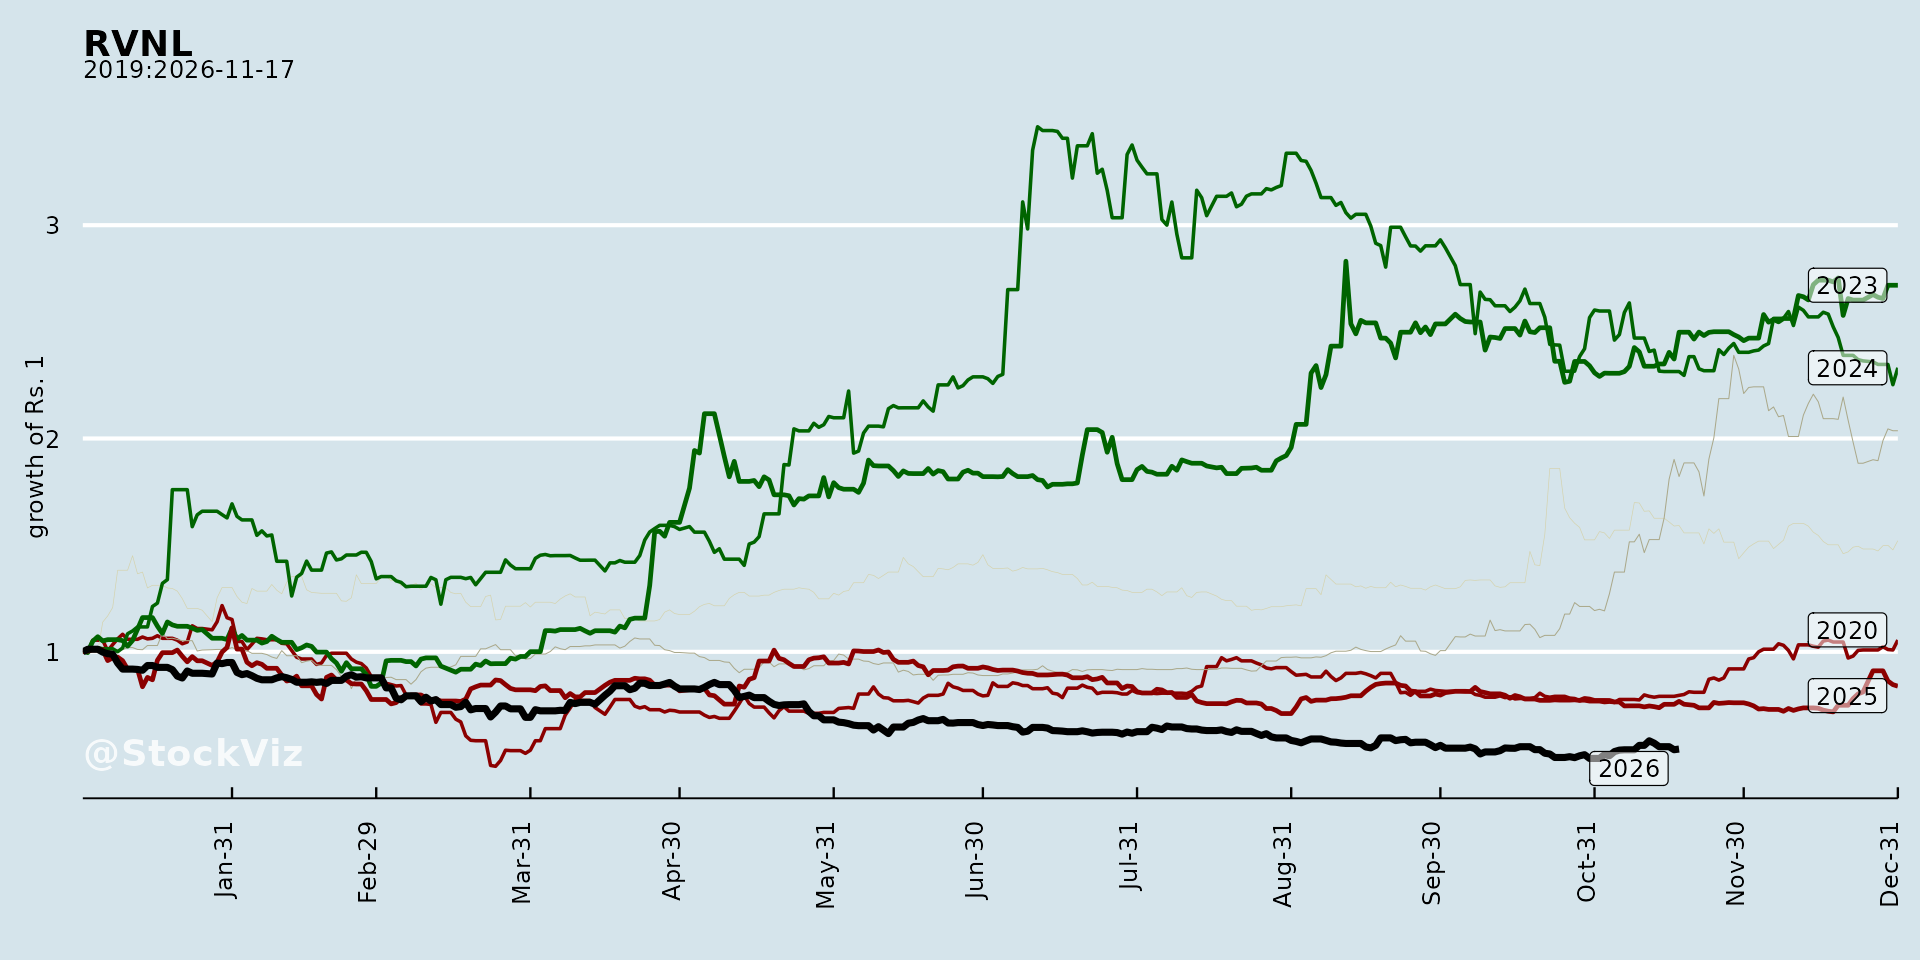
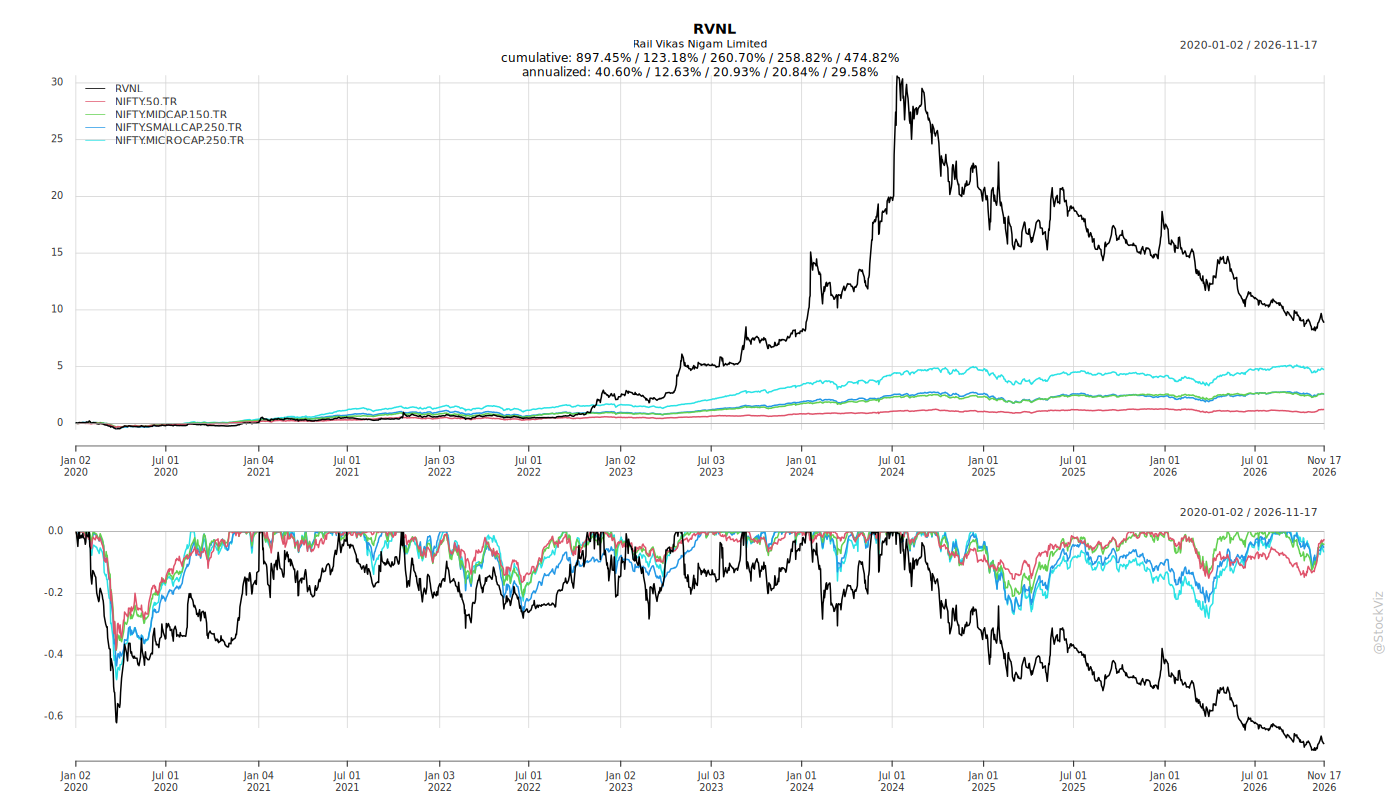
Cumulative Returns and Drawdowns
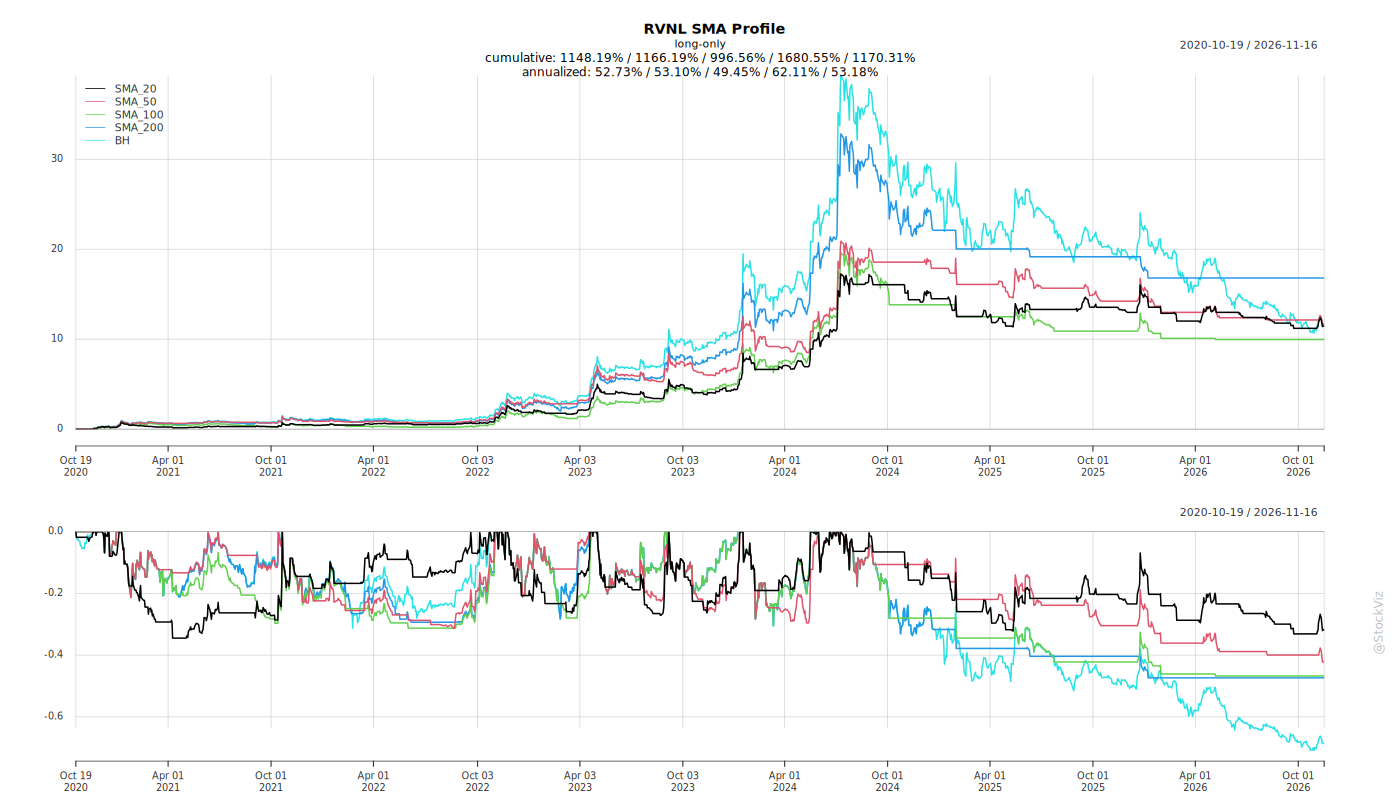
Fundamentals
Ownership
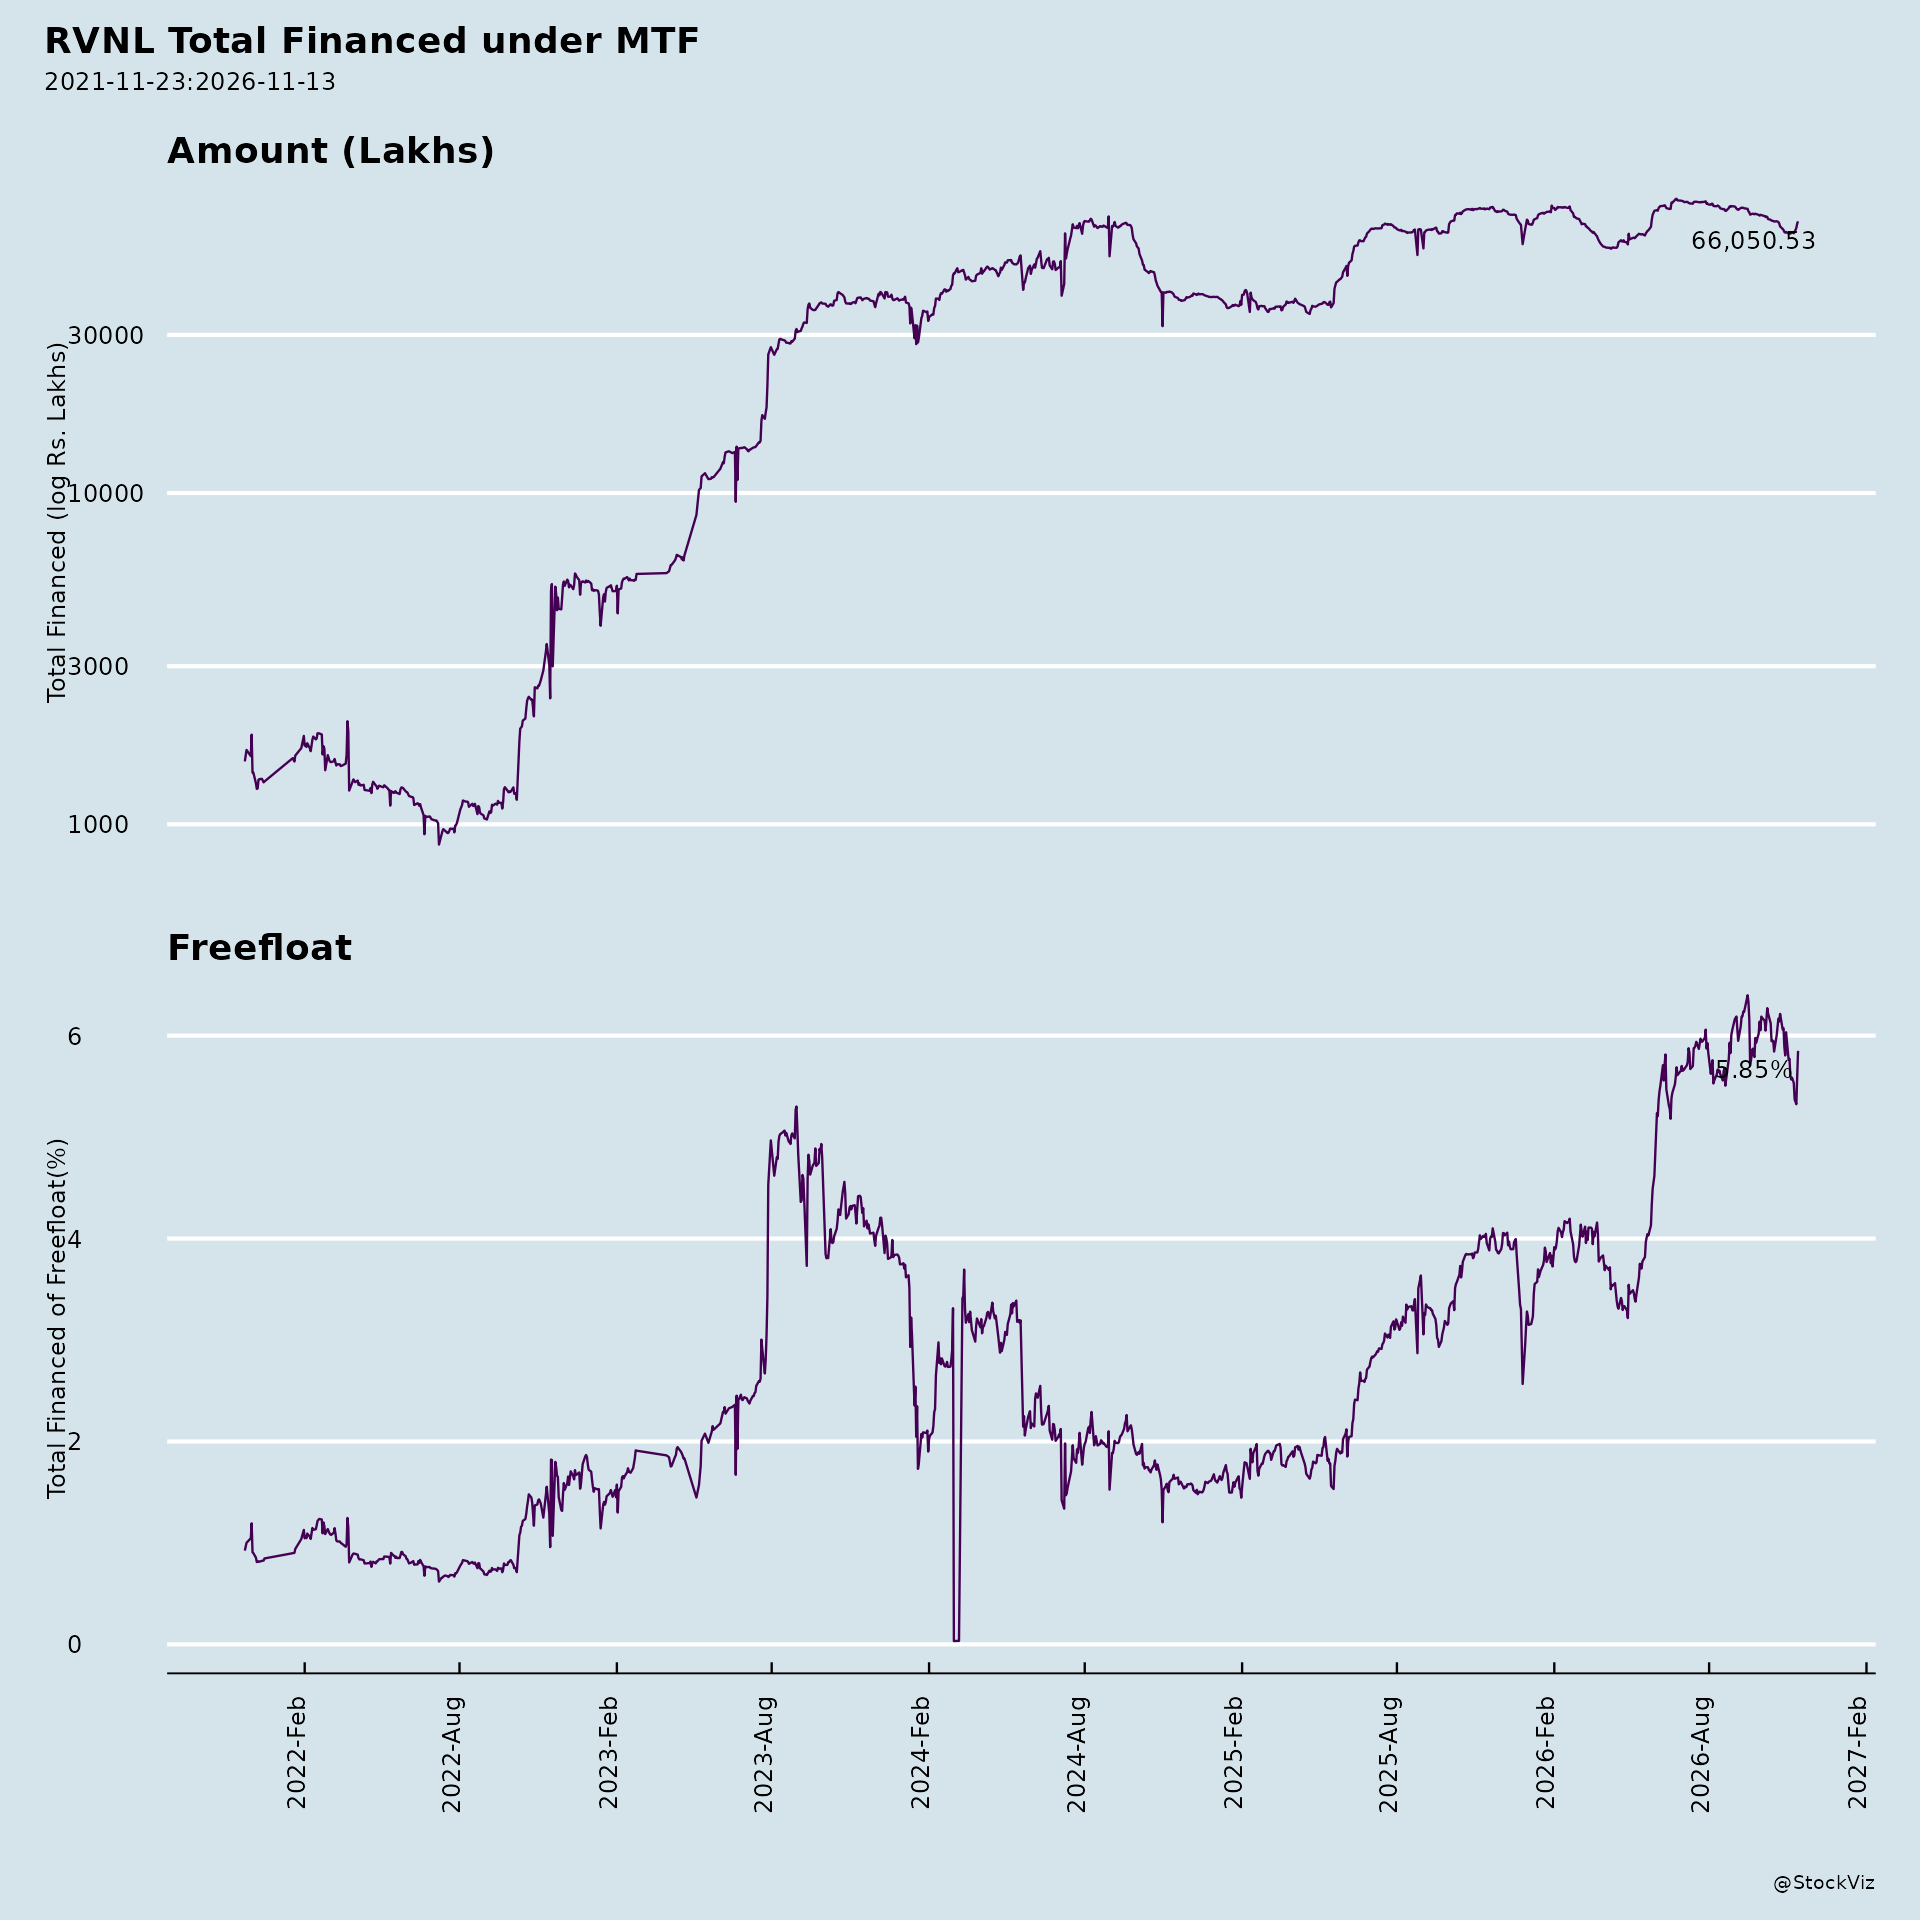
Margined
AI Summary
asof: 2026-09-16
RVNL: Recent Developments, Challenges and Growth Prospects
1. Headwinds and Challenges
Execution and project-specific issues. On the Q1 FY2026-27 earnings call (13.08.2026), management acknowledged that the BharatNet project (an INR 13,000 crore BSNL award covering 82,000 km of OFC infrastructure under the DB-1 model) initially faced execution problems. While work is now described as progressing in full swing in UP West and UP East, payment issues with BSNL are still being deliberated and resolved, with some payments received and others pending. On the implementation timeline, management indicated the duct and fiber work would take another six to eight months and would be extended.
Macro and operating constraints. Management cited the present geopolitical situation as a challenge faced during Q1, and flagged labor availability as a difficulty requiring extra effort to secure workers. Client payments were also described as a challenge, with regular follow-up being undertaken. On inflation, management noted that most contracts are covered by price variation clauses, though some impact is always present.
Receivables and legacy items. Railway outstanding was stated at approximately INR 2,500 crore, with monthly billing and payment typically received within 30 days. A separate disclosure notes pending finalisation of whether simple or compound interest applies prior to 30.09.2024 on delayed payments from JV company Krishnapatnam Railway Company Limited (KRCL), with INR 1,091.91 crore receivable as on 30th June 2026. Management stated that provisioning for onerous projects has already been made and no further loss provisions are anticipated.
Regulatory/compliance matter. RVNL received a fine of Rs. 9,66,420/- (inclusive of GST) from NSE for non-compliance with Regulations 17(1), 18(1) and 19(1)(2) concerning the composition of the Board and its committees for the quarter ended 30th June 2026. The company notes it is a Government company under Section 2(45) of the Companies Act, 2013, where the President of India and the Ministry of Railways exclusively hold the power to appoint all Directors, and RVNL has no role in these appointments.
Margin profile. Margins, while improved year-on-year, were described by management as remaining an important area of focus to be tracked closely.
2. Tailwinds and Growth Prospects
Order book and inflows. Order inflow for Q1 (April–June 2026) stood at INR 5,417 crore, and the total order book as on June 30, 2026 was INR 93,492 crore. The order book is led by railways at INR 58,000 crore, followed by S&P at INR 12,000 crore, ports/roads/highways at INR 3,651 crore, metros at INR 5,700 crore, power and transmission at INR 4,000 crore, and hydro and irrigation at INR 1,626 crore. Of the total order book, works in progress are about INR 40,000 crore.
New awards. RVNL received a Letter of Award from SJVN Thermal Private Limited for construction of a permanent siding with an aerial connection via track for the 1320 MW Buxar Thermal Power Project in Bihar, valued at Rs. 903,00,68,492/- (incl. GST), to be executed within 36 months. This is in the normal course of business and is not a related party transaction.
Diversification and new sectors. Management is targeting INR 20,000–25,000 crore of new work orders this year, with about INR 5,000–5,500 crore already received in Q1. Focus sectors for new orders are ports, hydro, highways and green energy. The company has secured approximately INR 6,500 crore of works from NMDC on a PMC basis and is in discussions with other state governments and PSUs for nomination-basis PMC work.
Flagship projects. The Vande Bharat sleeper train programme — an INR 14,400 crore project with a 35-year maintenance arrangement, executed by Kinet Railway Solutions Limited (an RVNL SPV) — is progressing steadily, with the first prototype trainset targeted for launch in December 2026 and delivery of 120 sets over five years, followed by 35 years of maintenance. The Rishikesh–Karnaprayag rail project (INR 37,000 crore, 125 km) has achieved 78% overall progress with about 97% tunnel excavation completed, targeted for completion by December 2029.
International opportunities. RVNL is bidding across Central Asia, the Middle East, Eastern Europe, Southeast Asia and Africa. Bids have been submitted in parts of Africa for power transmission lines, railway and road projects, and in Nepal for hydropower. An expression of interest has been submitted for the upcoming Tel Aviv Metro in Israel, and bids have been identified in Georgia and Serbia. Management expects overseas margins of 15–20%.
JV/subsidiary contribution. Subsidiaries contributed INR 126 crore to consolidated revenue and INR 12.70 crore to PAT, while share of profit from JVs and associates was INR 6.16 crore. Dividend income from JVs and subsidiaries was INR 12.07 crore in Q1. Employee productivity improved, with revenue from operations per employee rising from INR 4.29 crore to INR 4.97 crore QoQ.
Shareholder returns. All nine agenda items at the 23rd AGM held on August 25, 2026 were approved with requisite majority, including adoption of financial statements and a final dividend of Rs. 0.71 per share. Management stated dividend policy follows DIPAM guidelines — 30% of PAT or 4% of net worth, whichever is higher.
3. Key Risks
- Geopolitical exposure: Management acknowledged that the Middle East and Israel are volatile at present, though it expects stabilisation and notes these regions typically yield good margins. Risk assessment and risk premiums are stated to be built into quoting, with attention to manpower payments and insurance.
- Competitive bidding mix shift: As the business shifts toward competitive bidding, margins vary — 5–6% for domestic bidding works, 8–10% for management works, and about 7% for PSU PMC work. Management aims to keep bidding margins above 5–6% through selective, margin-focused bidding.
- Payment and receivables risk: Pending BSNL payments on BharatNet and the KRCL interest computation matter (INR 1,091.91 crore receivable) represent open items.
- Compliance/board composition risk: The NSE fine reflects ongoing board composition non-compliance, which the company attributes to the appointment process resting with the Ministry of Railways.
- Execution risks: Labor availability and weather conditions were cited as factors affecting execution pace, with management expecting execution to pick up as weather improves.
4. Management Guidance vs. Observed Performance
Guidance. Management targets around INR 20,000 crore of work orders this year (later referenced as INR 20,000–25,000 crore), top-line growth of about 15%, bottom-line growth of approximately 15–20%, EBITDA of 5–7% over three years, ROE of about 12–13%, and a 50-50 split between railway management works and bidding works in the order book over three years. No debt is currently envisaged, with bank working capital arrangements at around 5.5–5.9% available if needed, potentially for BharatNet.
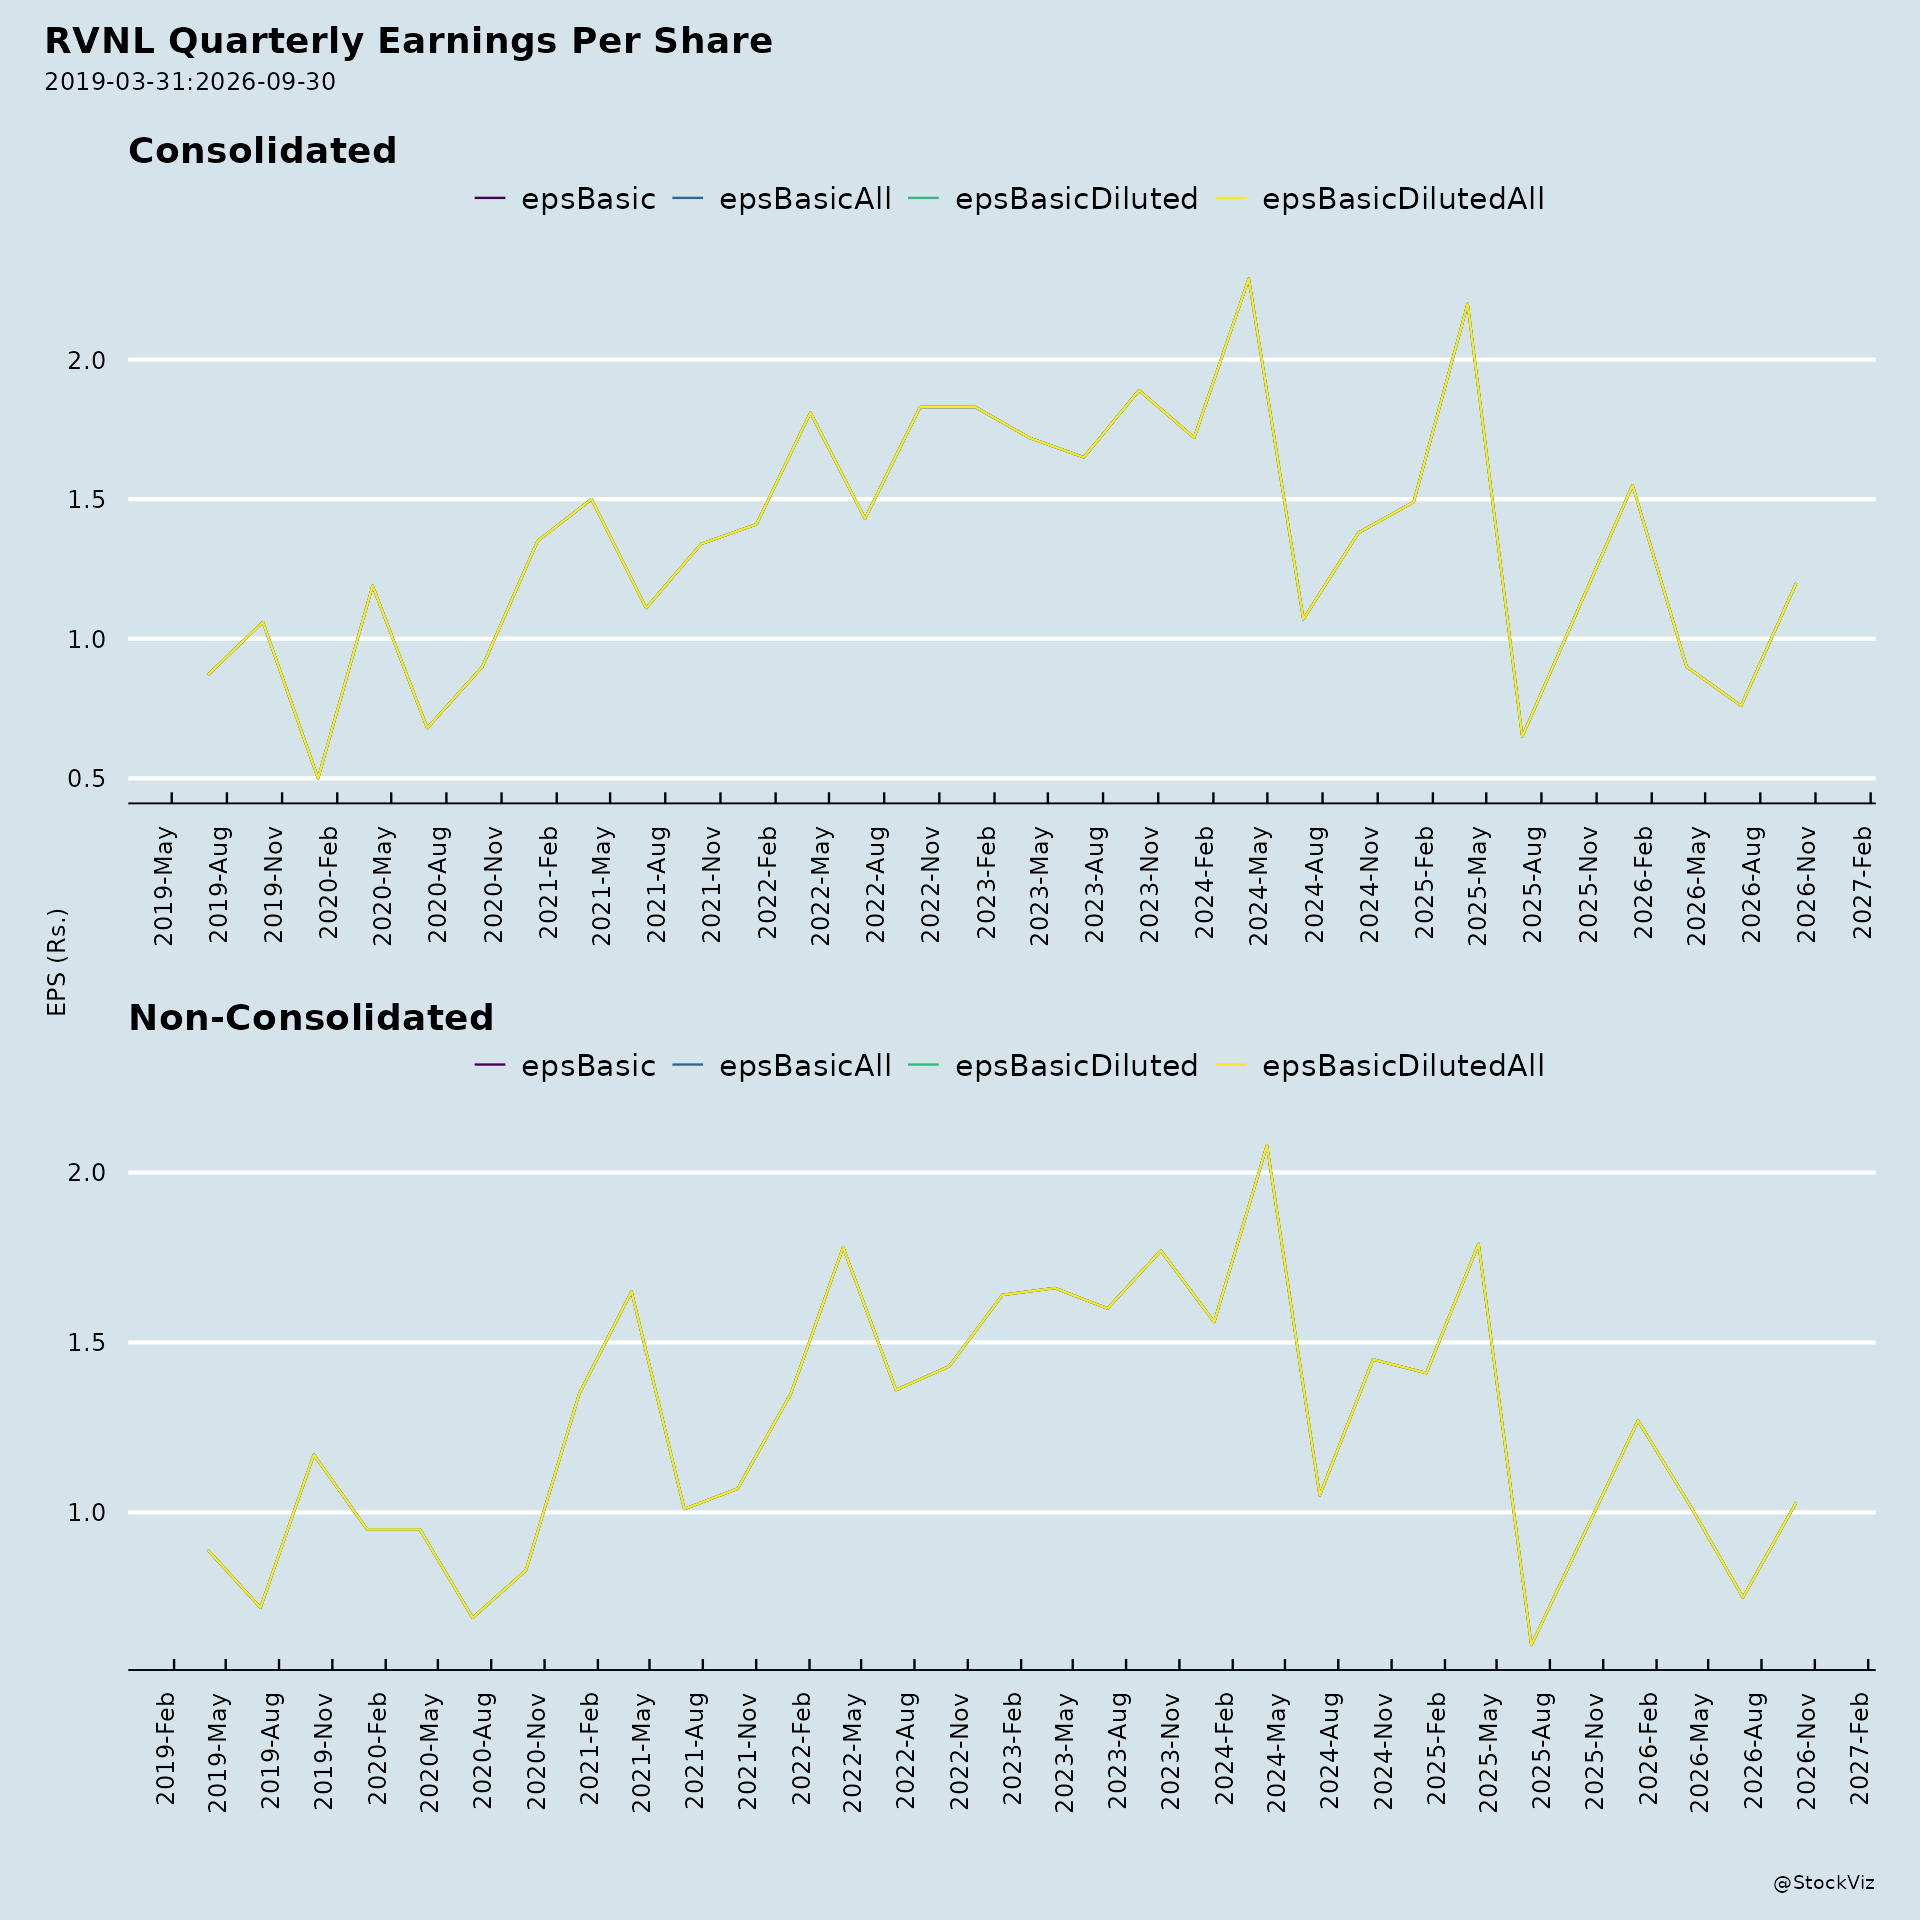
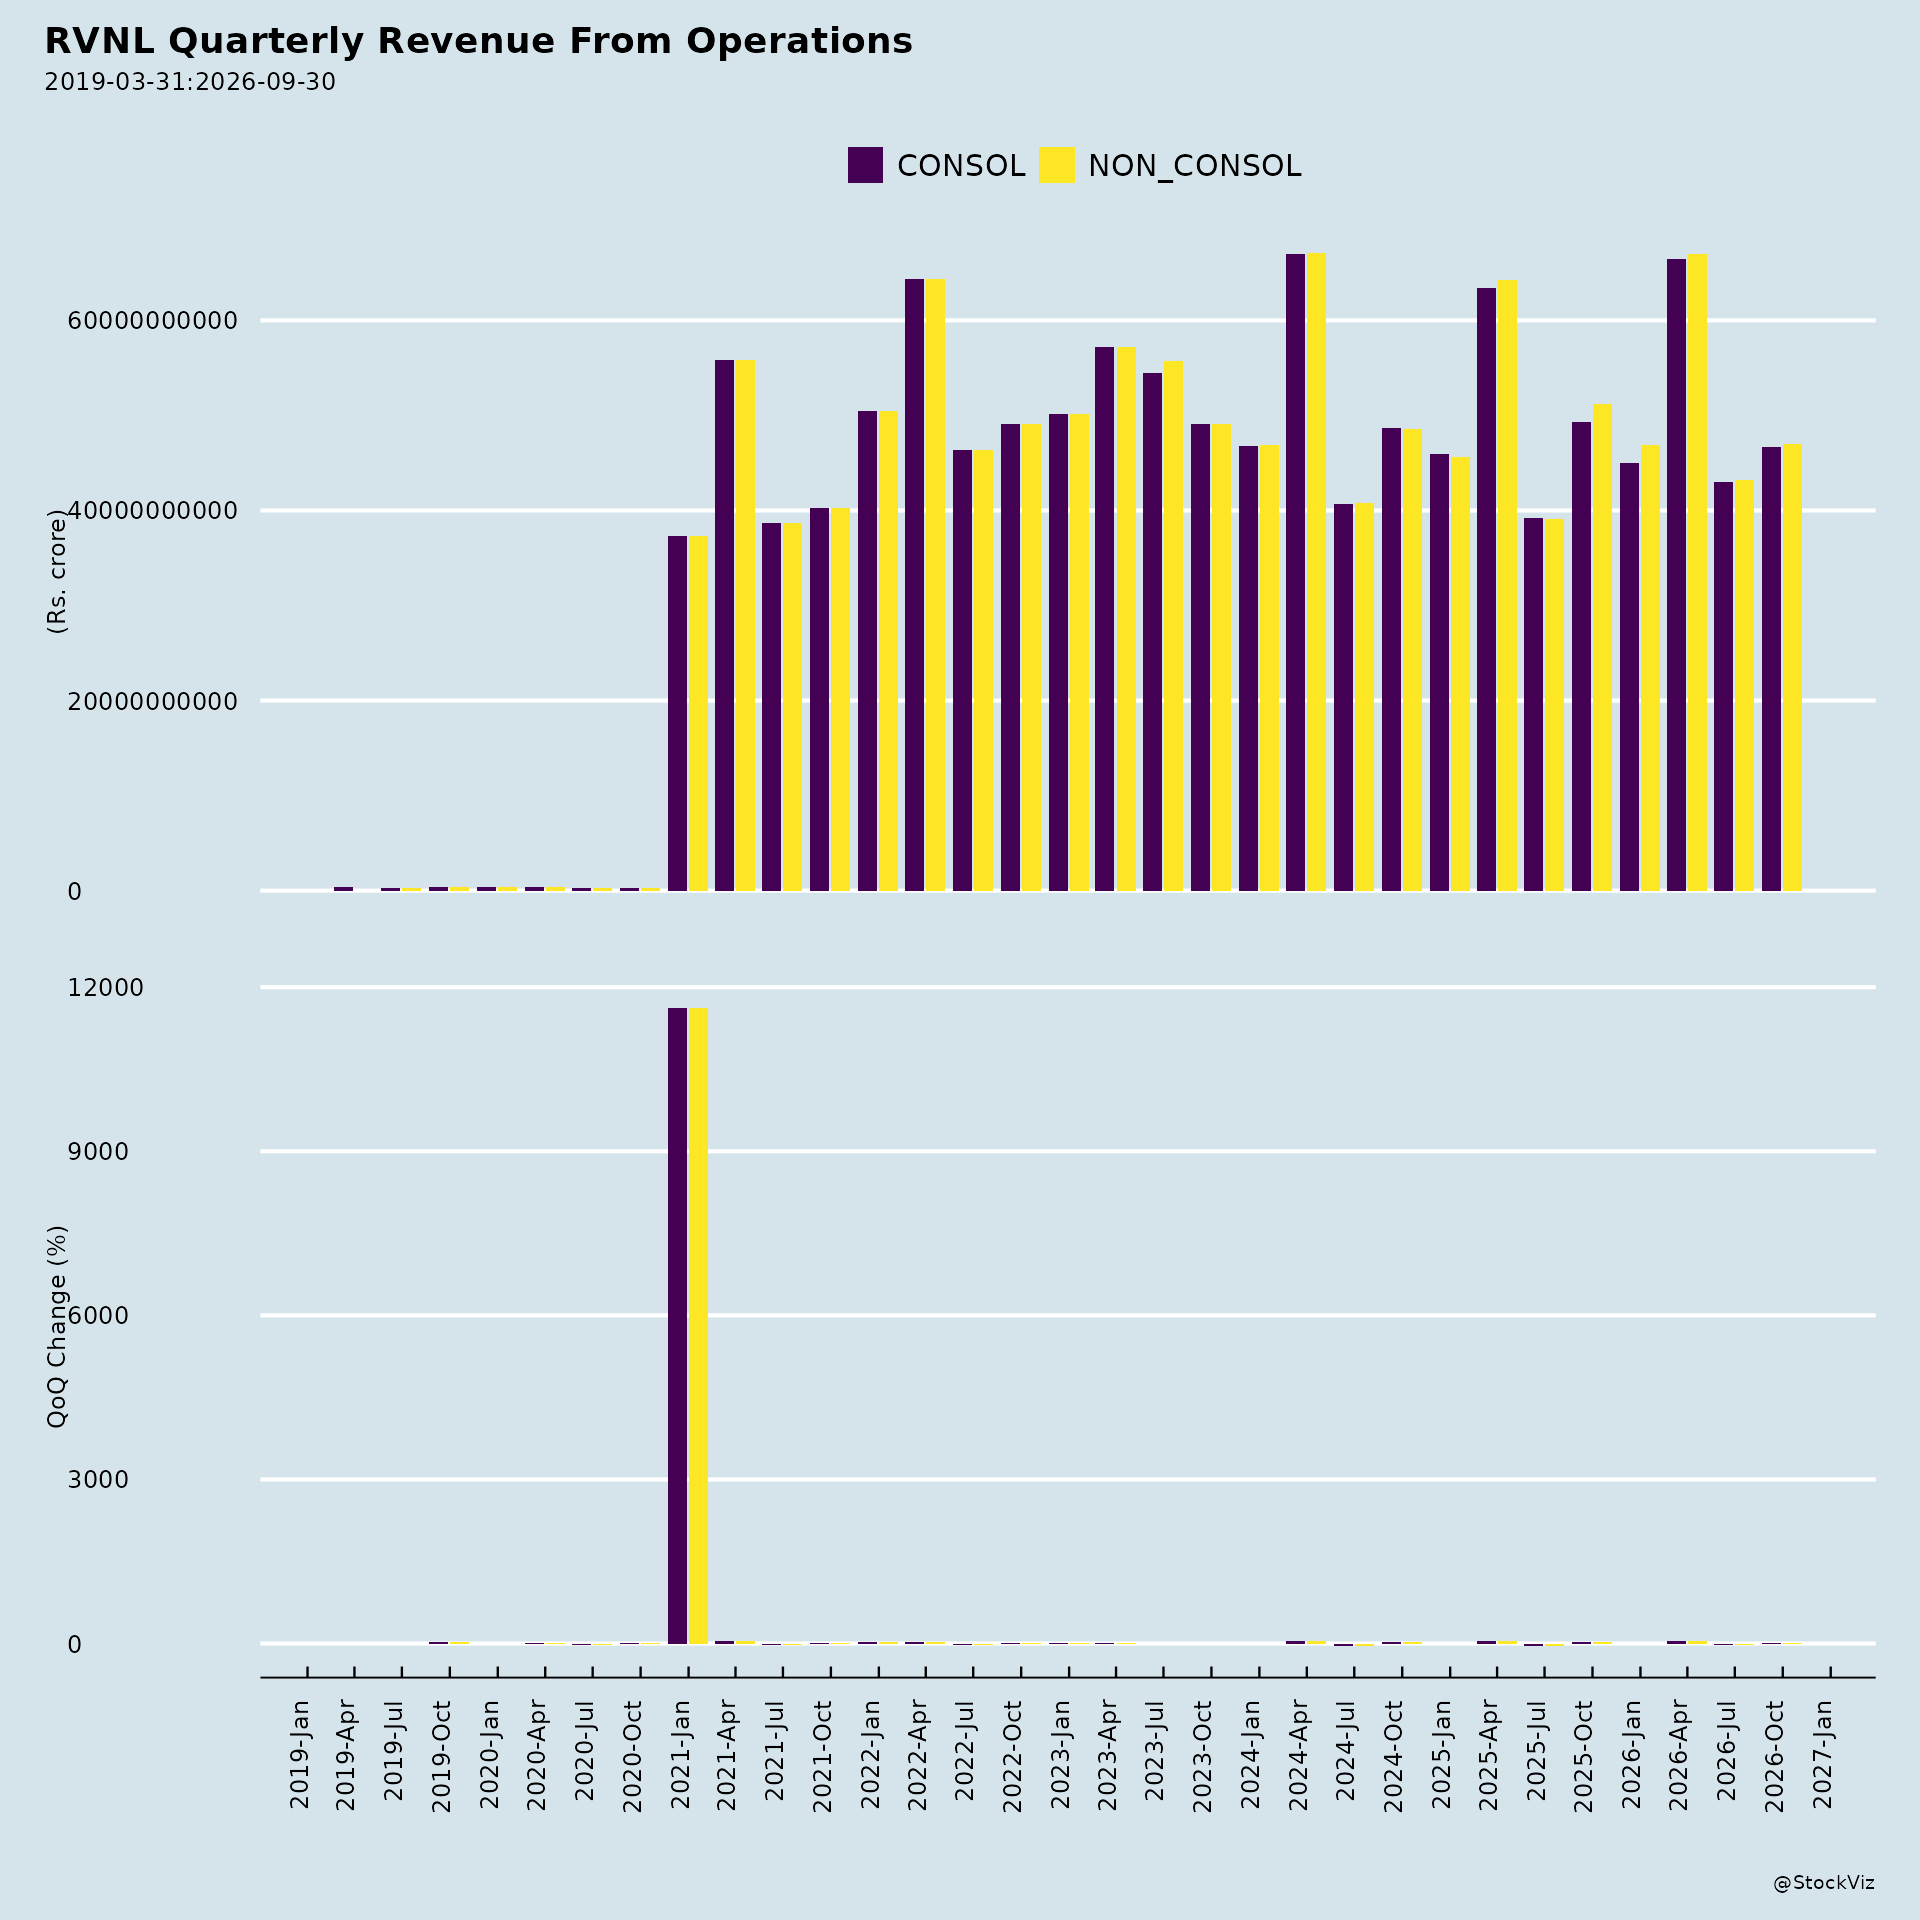
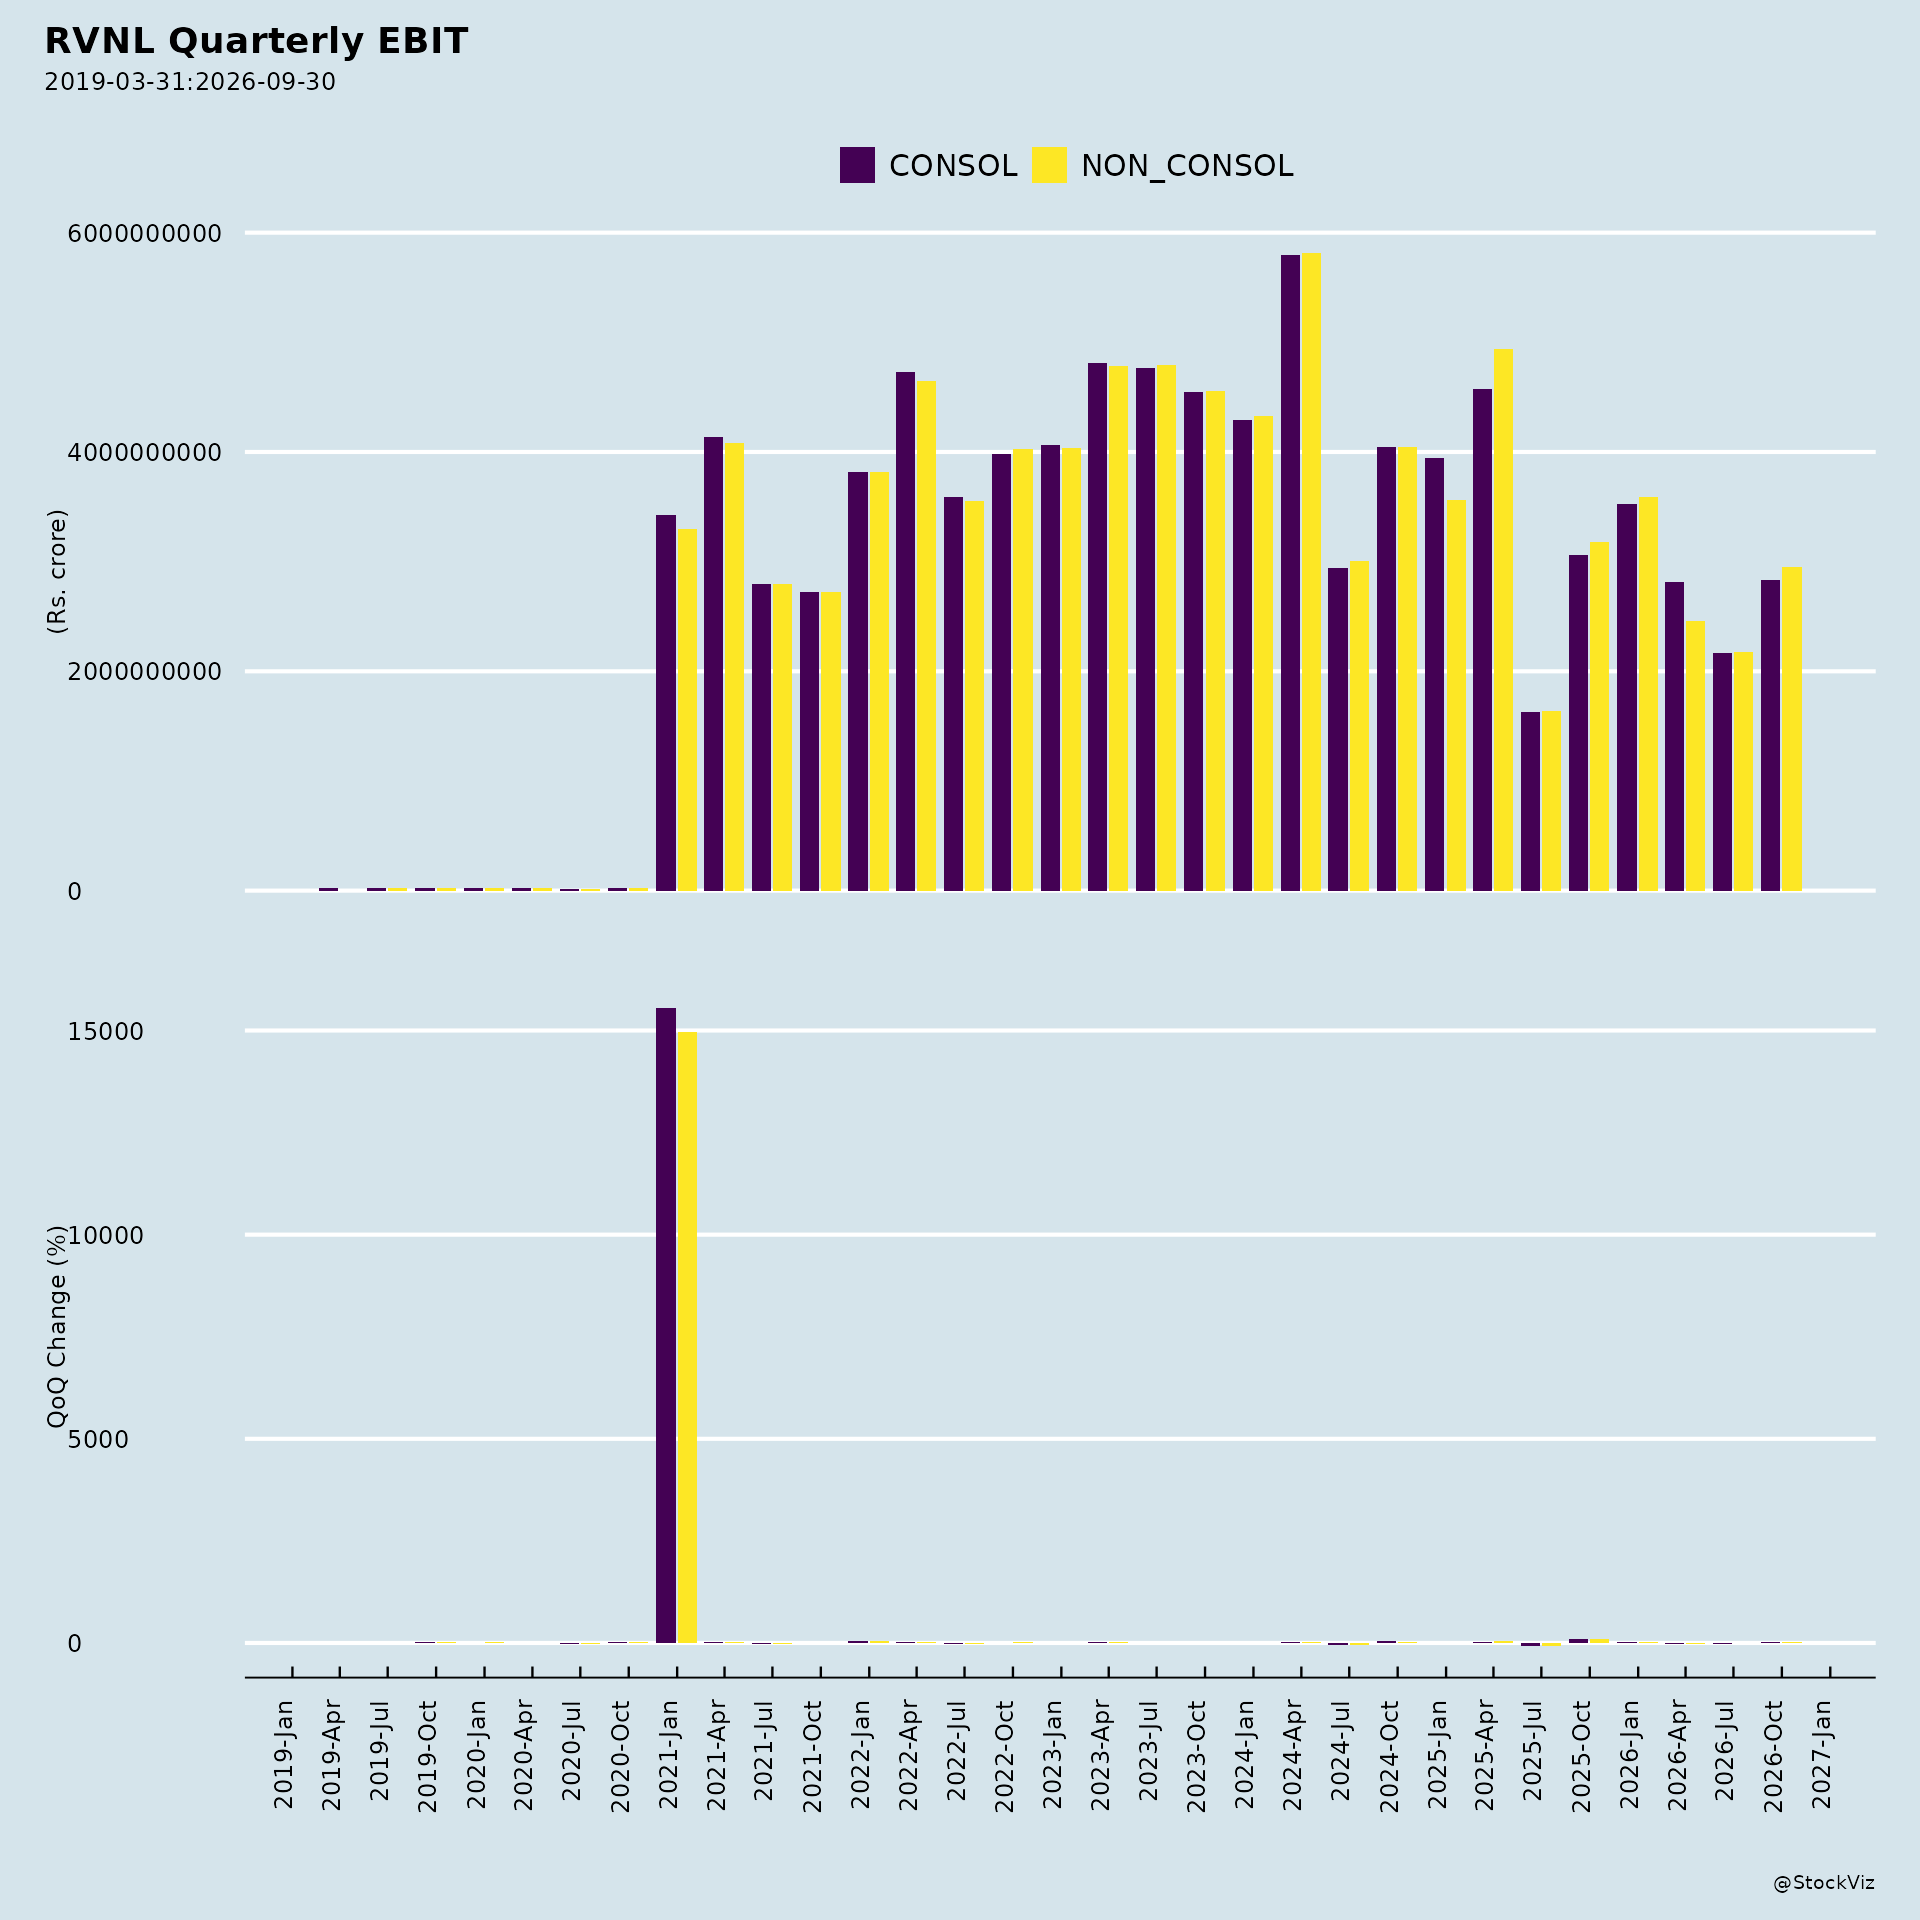
Observed Q1 FY2026-27 performance. Standalone turnover was INR 4,300 crore, up 9.62% YoY; consolidated turnover was INR 4,321 crore, up 10.55% YoY. Standalone EBITDA was INR 171 crore versus INR 81 crore in Q1 FY26 (up ~110%), with EBITDA margin at 3.99% versus 2.08%. Standalone PAT was INR 155 crore, up 21.72% YoY, and standalone EPS was INR 0.75, up 22.95% YoY. Consolidated EBITDA was INR 190 crore versus INR 64.91 crore, with margin at 4.41% versus 1.66%; consolidated PAT was INR 159.52 crore, up 18.73% YoY. Building works contributed 31.51% of total revenue from operations, up 16.63% from the previous year.
Assessment against guidance. Q1 bottom-line growth of about 19% YoY (as cited by management) is within the 15–20% guidance band, and management expressed confidence in maintaining momentum. Top-line growth of roughly 10% in Q1 is below the ~15% full-year guidance, with management attributing execution pickup to expected improvement in weather conditions in coming quarters. The Q1 EBITDA margin of 3.99% (standalone) and 4.41% (consolidated) is below the 5–7% three-year EBITDA aspiration, consistent with management’s statement that margins remain an area of focus. Revenue mix in Q1 was approximately 63% from management works and the remainder from bidding or PMC, against the stated three-year ambition of a 50-50 order book split.
Broker Narrative
The broker narrative evolved from early optimism centered on a Rs673bn order book providing ~3x TTM revenue visibility, margin expansion to 6.7% by FY25E, and Vande Bharat-driven TAM growth, toward a more cautious stance acknowledging execution challenges, working-capital build-up from multi-authority delays, and margin pressure from commodity and freight cost inflation. Themes of order visibility, sector diversification, and overseas expansion persisted, but the margin-expansion thesis was reversed into margin-risk caution, and the final Buy call carried little conviction given the -2.1% actual return.
Fears that came true
- EBITDA margin contraction flagged in the first report (~37bps to 6.1%) and ‘revenue growth could be marginal’ materialized as persistent underperformance including a -63.5% actual return in Aug 2024 and DISAPPOINTMENT outcomes in Nov 2025 and Sep 2026.
- Execution challenges involving multiple authorities, utility shifting, clearances, and frequent design changes causing delays and working-capital build-up flagged in the last report correlated with the DISAPPOINTMENT on the Sep 2026 Buy call (+32.7% predicted vs -2.1% actual).
- Potential FY27 margin pressure from higher commodity, freight, and insurance costs due to West Asia disruptions flagged in the last report confirmed the first report’s margin-contraction concern, as projected margin expansion to 6.7% never materialized.
Optimism that failed
- EBITDA margin was projected to expand to 6.4% in FY24E and 6.7% in FY25E, but instead faced continued contraction and near-term pressure as confirmed by the last report’s margin warnings.
- Winning 120 Vande Bharat train sets was expected to expand railway TAM by 15-16% and open rolling-stock manufacturing, but this did not prevent a -34.4% actual return in Nov 2025.
- Overseas projects offering better margins, advances, and payment cycles failed to offset domestic execution drag, contributing to the DISAPPOINTMENT outcome on the final Sep 2026 Buy call.
Broker Timeline
9 broker calls · 2023-11-10 to 2026-09-03
CNBC-TV18: ratings, targets and commentary
No recorded CNBC-TV18 statements for this ticker.
Management comments
No recorded management comments with an explicit designation and affiliation for this ticker.
Copyright © 2023 SAS Data Analytics Pvt. Ltd. All rights reserved.