RECLTD
Equity Metrics
November 18, 2026
REC Limited
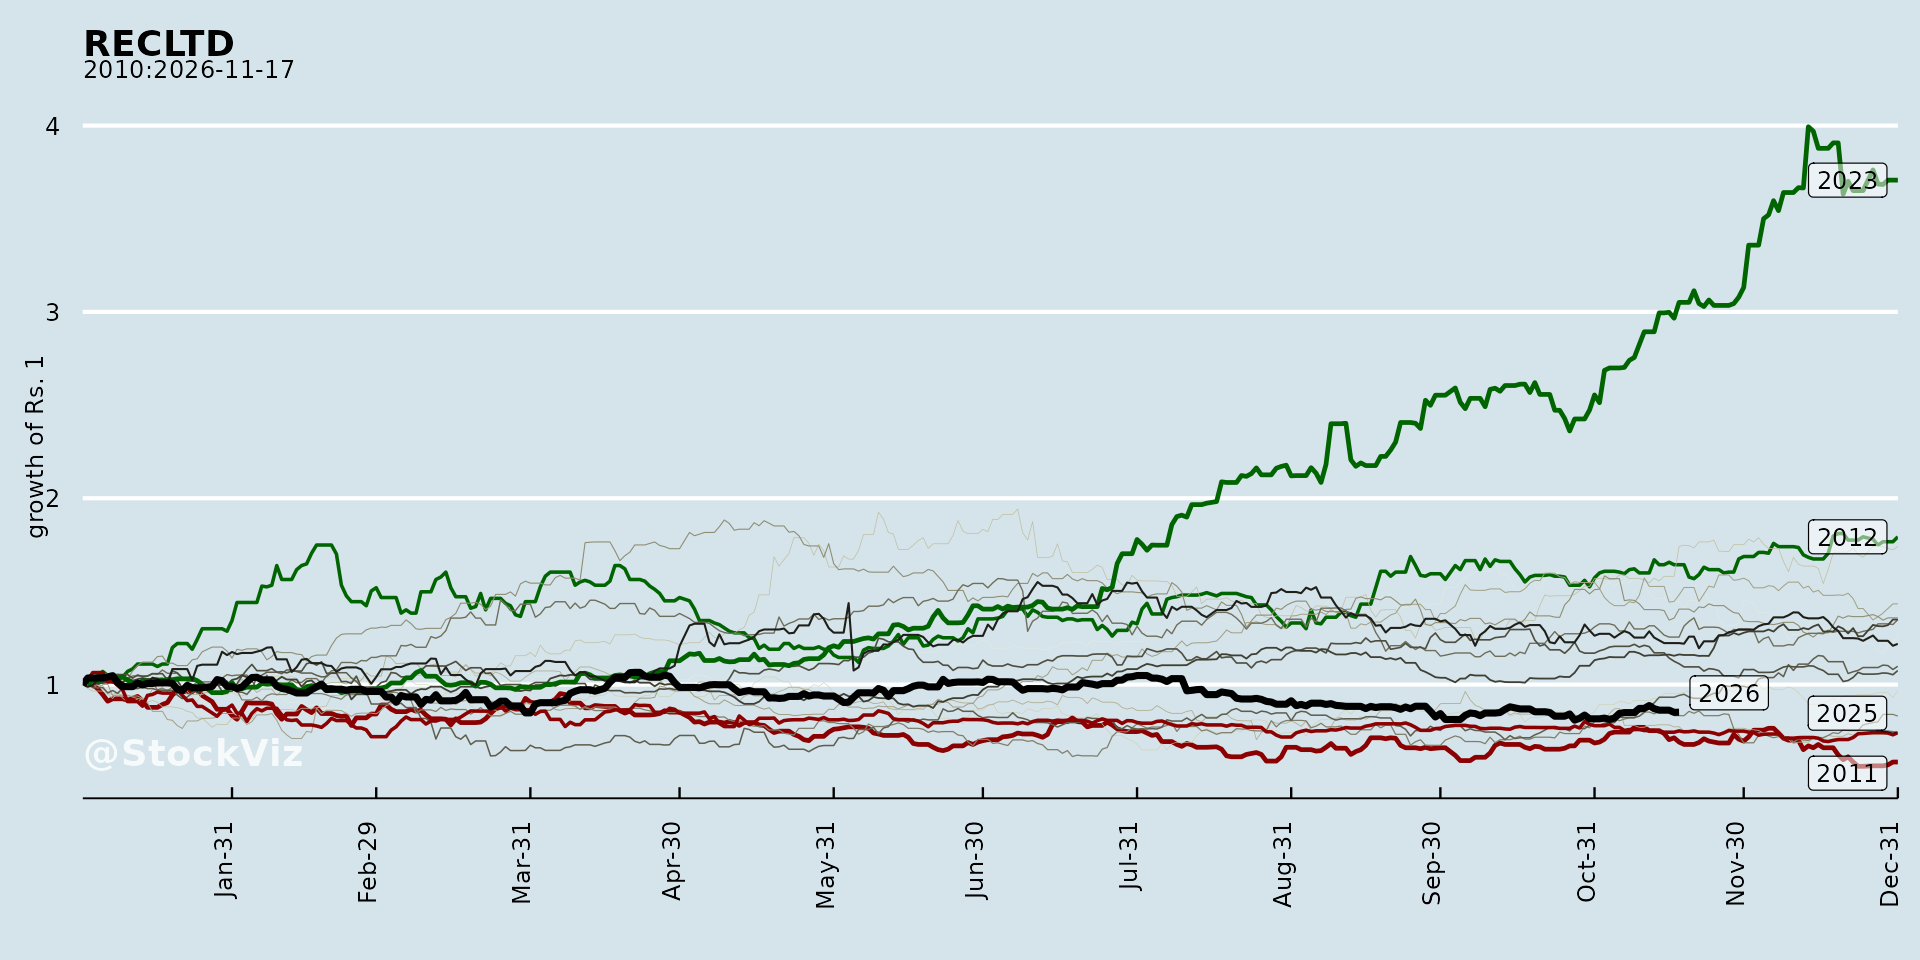
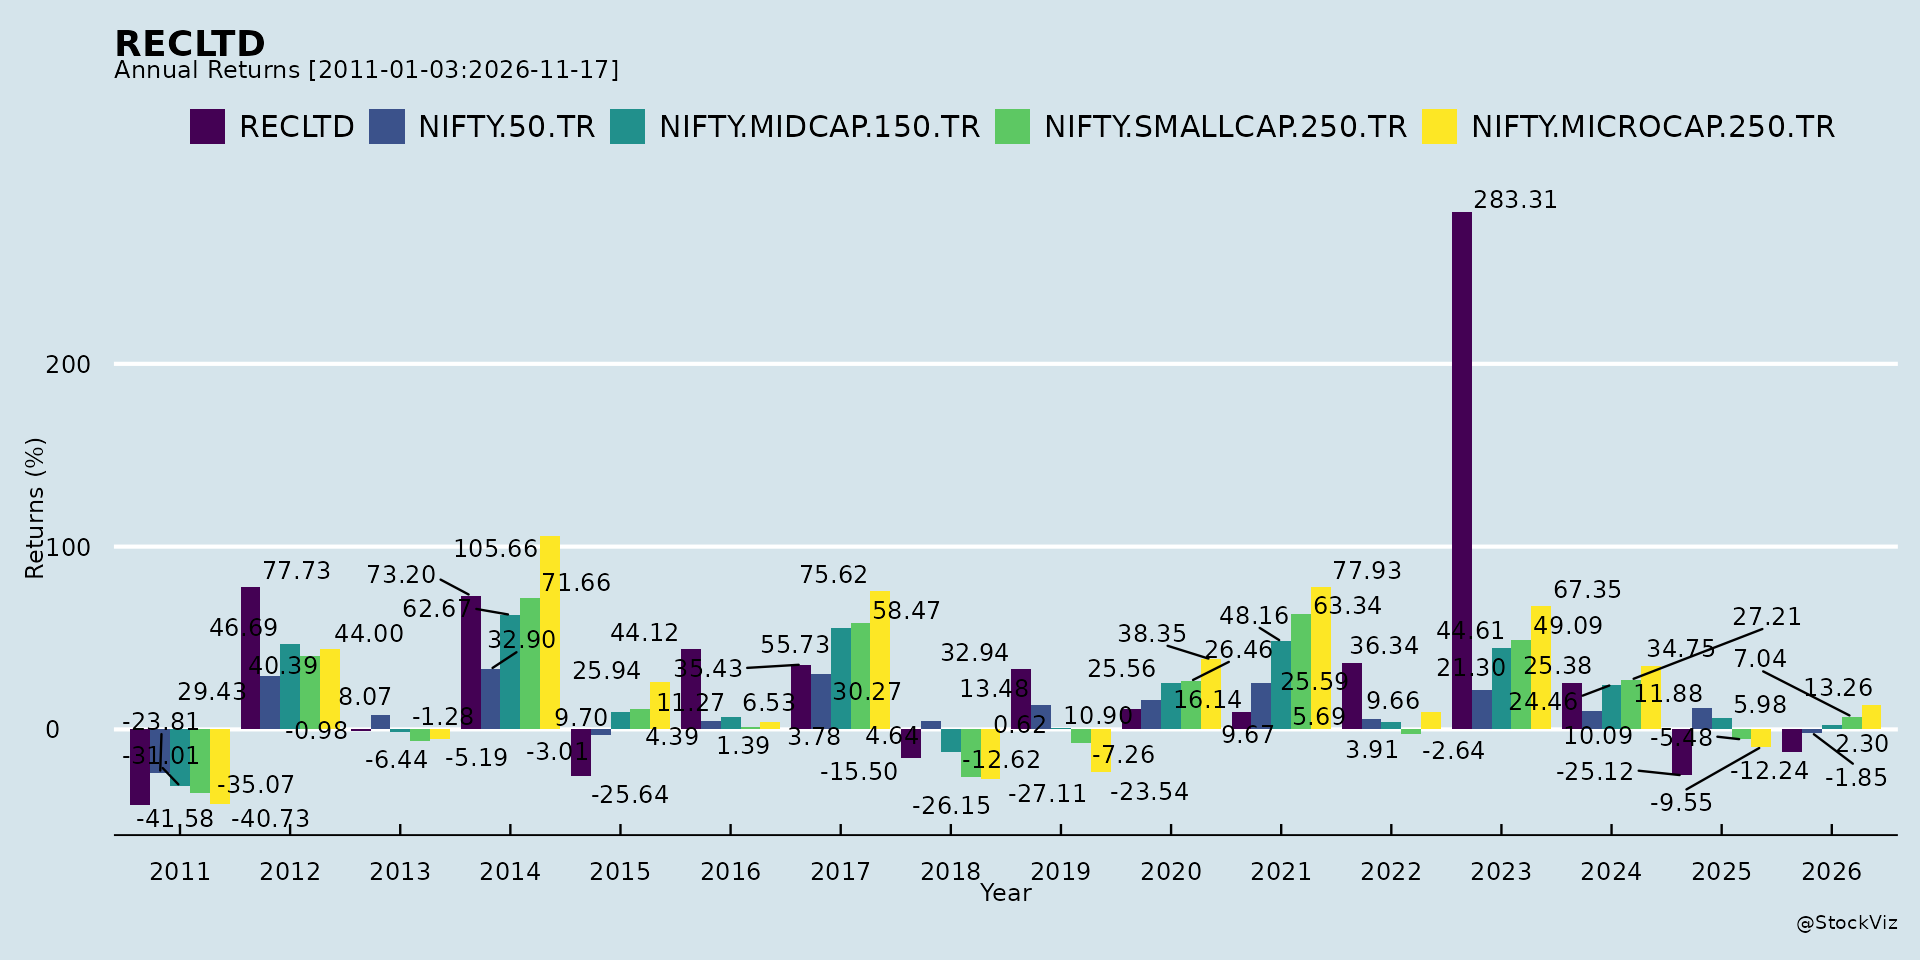
Annual Returns
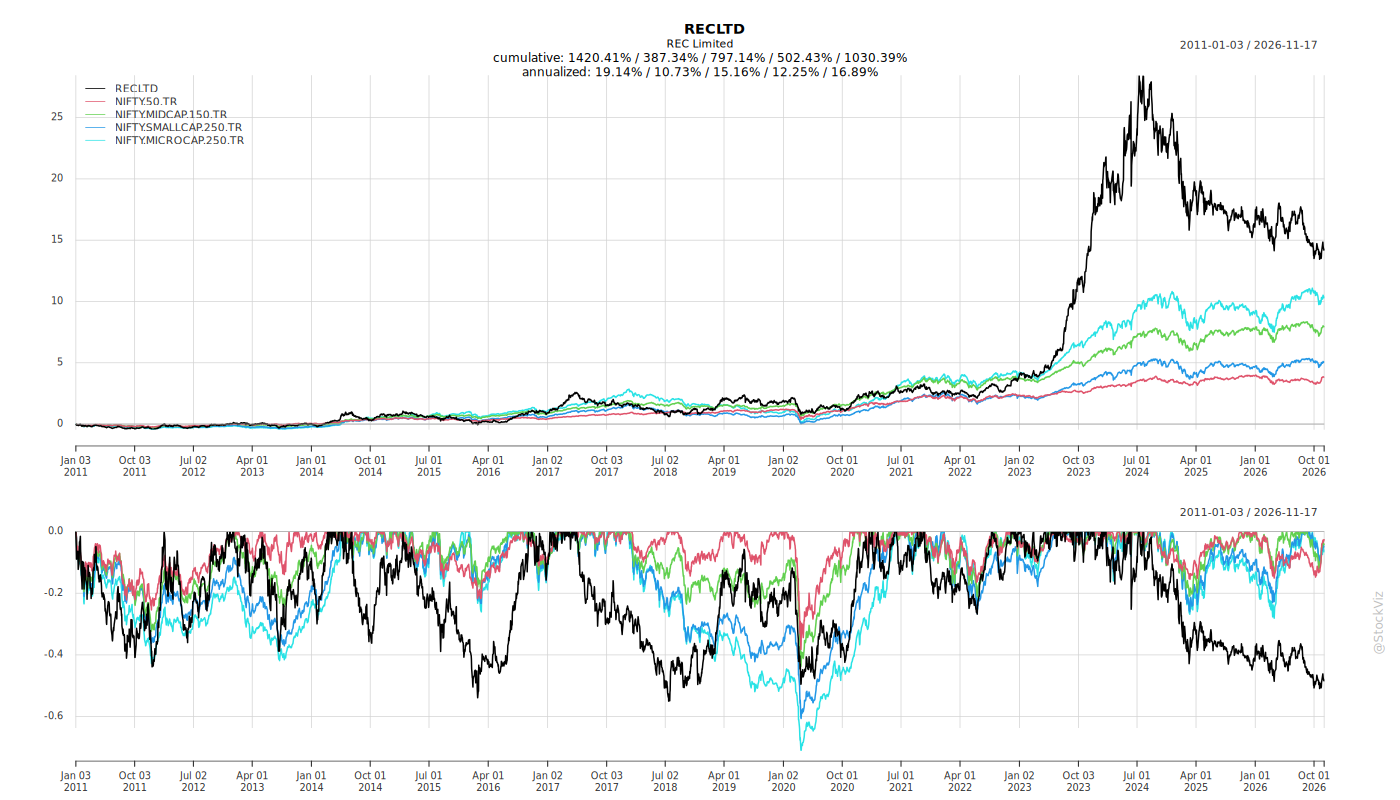
Cumulative Returns and Drawdowns
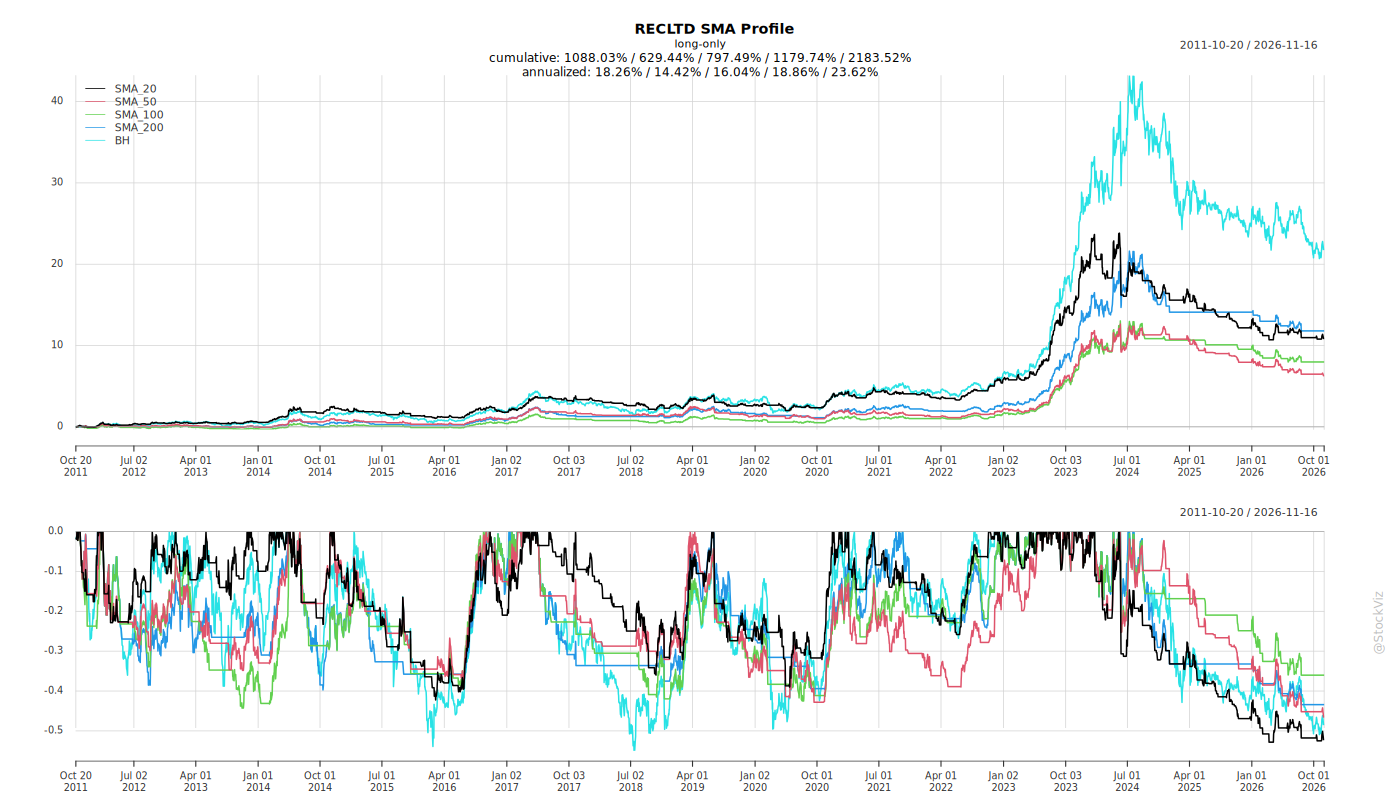
Fundamentals
Ownership
Margined
AI Summary
asof: 2026-09-16
REC Limited: Recent Corporate Announcements
Headwinds and Challenges
The supplied material does not identify any material headwinds or challenges for REC Limited.
Tailwinds and Growth Prospects
The supplied material does not identify any material tailwinds, opportunities, or growth prospects for REC Limited.
Key Risks
The supplied material does not identify any material risks for REC Limited.
Management Guidance Versus Observed Business Performance
The supplied material does not contain any management guidance or forward-looking statements. However, several concrete developments are disclosed:
Divestment of Musalgaon Power Transmission Limited: REC Power Development and Consultancy Limited (RECPDCL) transferred its entire shareholding in Musalgaon Power Transmission Limited — comprising 50,000 equity shares — along with all assets and liabilities to Maharashtra State Electricity Transmission Company Limited on September 9, 2026. This followed a tariff-based competitive bidding process. The consideration received was Rs 2,20,89,930. As a result, Musalgaon Power Transmission Limited ceased to be a subsidiary of RECPDCL and REC Limited.
57th Annual General Meeting: REC Limited held its 57th AGM on August 25, 2026, through video conferencing and other audio-visual means. All 11 resolutions set out in the AGM notice were approved by shareholders with the requisite majority. These included adoption of financial statements, declaration of dividends, appointment of various directors, statutory auditor remuneration, and approval for private placement of securities. The results were based on the scrutinizer report dated August 27, 2026, prepared by Shri Sachin Agarwal of M/s. Agarwal S. & Associates.
No forward-looking guidance or projections were provided in the supplied material against which observed performance could be compared.
Broker Narrative
The narrative evolved from a short-term technical thesis in the first report—focused on weekly trend reversal, short covering, and PE writer support at 500/460/450 levels—to a fundamental framing in the last report emphasizing loan growth, record disbursements, improving NPAs, and >20% RoE. While the tailwinds shifted from chart-based optimism to earnings and asset-quality metrics, the persistent headwind theme of competition-driven repayments and growth constraints remained throughout, and every Buy call ended in DISAPPOINTMENT except one where the predicted decline was merely less severe than actual.
Fears that came true
- The first report flagged a 10%+ correction and consolidation, which materialized as a -38.3% actual return in the initial period and continued negative returns through July 2025.
- Elevated repayments due to competition from banks and financial institutions were flagged and correlated with persistent DISAPPOINTMENT outcomes as the stock never recovered meaningfully.
- The risk that rate cuts pressure incremental loan yields materialized, with the stock failing to benefit despite eventual repo-rate cuts, contributing to sustained negative returns.
- Stressed-asset resolutions reducing YoY loan growth by ~1.3% came true and coincided with four DISAPPOINTMENT outcomes between October 2024 and May 2025.
- The warning of asset quality pressure, higher NPA/credit cost, and lower-than-expected growth aligned with five of six reports ending in DISAPPOINTMENT with negative actual returns.
Optimism that failed
- The claim that the weekly trend was turning upside and short covering was aggressive failed as the stock declined -38.3% immediately afterward and continued falling across subsequent periods.
- PE writer support at 500 with 460/450 strikes as strong support levels failed, as the stock kept falling below those levels amid selling pressure.
- Record disbursements of INR 595bn and sanctions above INR 1trn cited in the last report failed to translate into positive returns, ending in DISAPPOINTMENT with a -4.9% actual return.
- The expectation of steady margins, healthy asset quality, and >20% RoE for FY26E/FY27E did not prevent the stock from being rated DISAPPOINTMENT across all six reporting periods.
- Negative annualised credit cost of 43bps aided by ECL reversal did not sustain investor confidence, as the stock produced negative actual returns in the periods following the report.
Broker Timeline
6 broker calls · 2024-10-01 to 2025-07-25
CNBC-TV18: ratings, targets and commentary
No recorded CNBC-TV18 statements for this ticker.
Management comments
No recorded management comments with an explicit designation and affiliation for this ticker.
Copyright © 2023 SAS Data Analytics Pvt. Ltd. All rights reserved.