RBA
Equity Metrics
October 23, 2026
Restaurant Brands Asia Limited
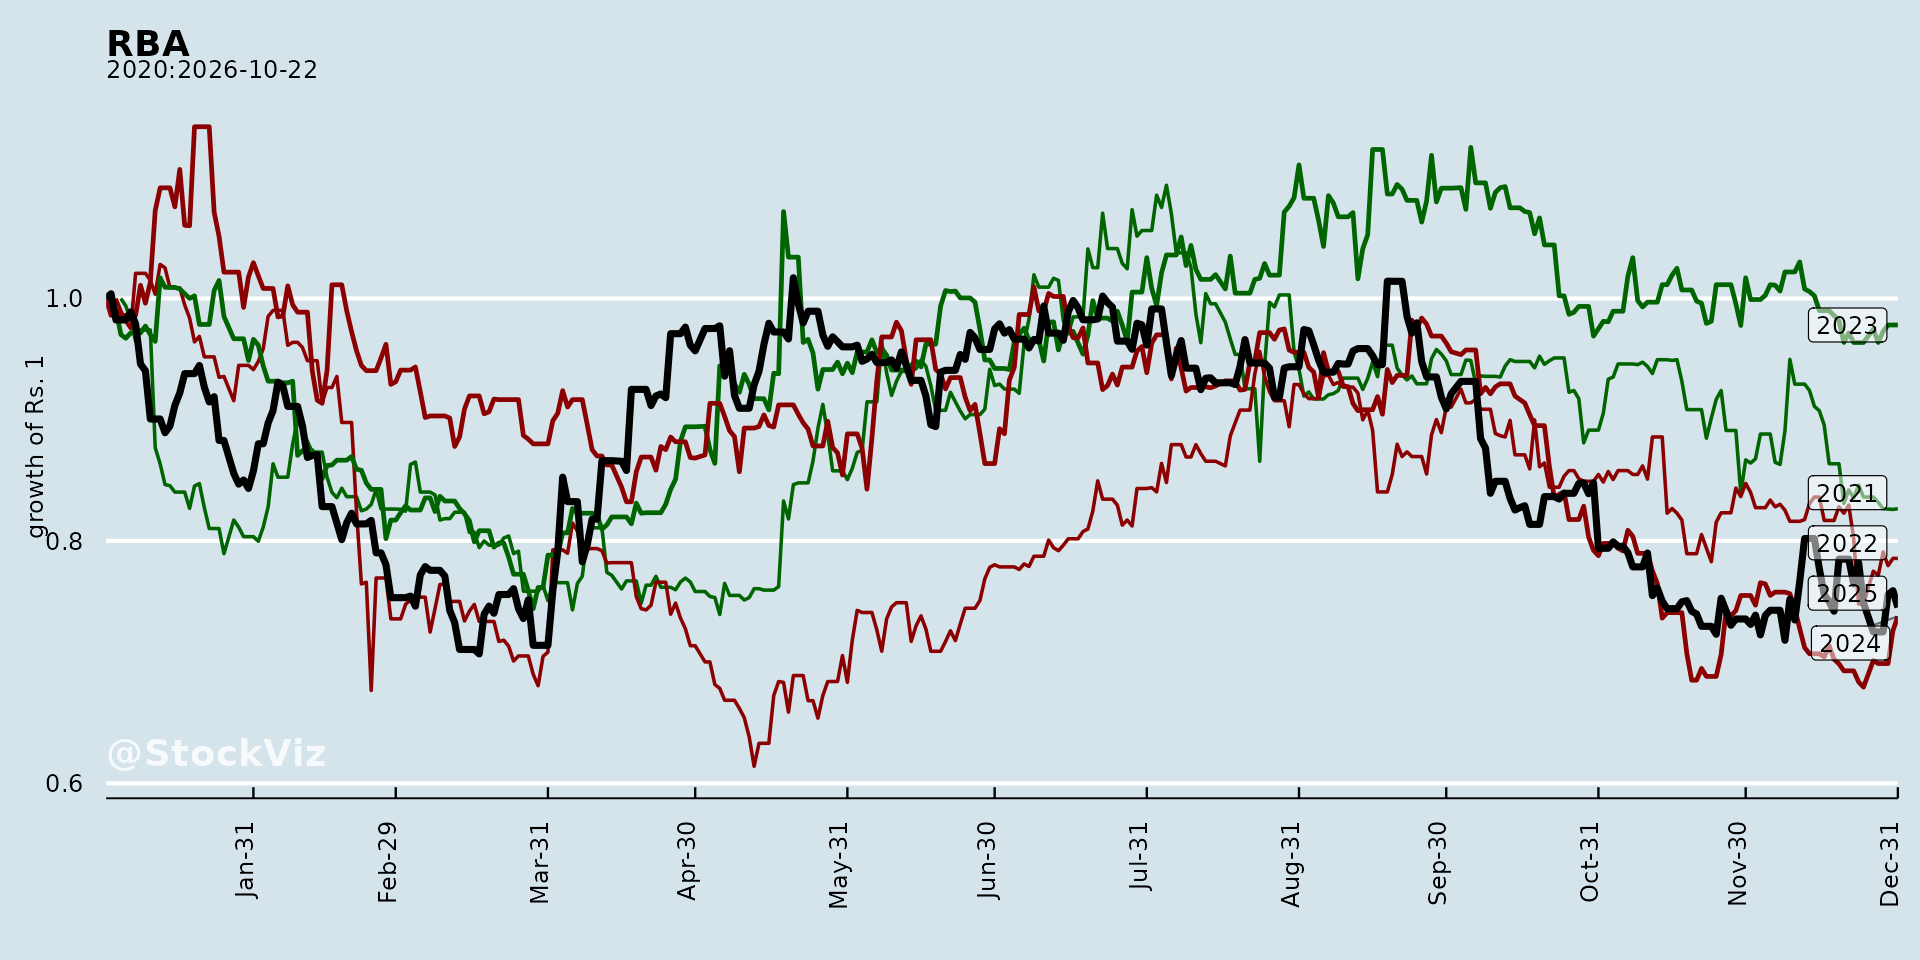
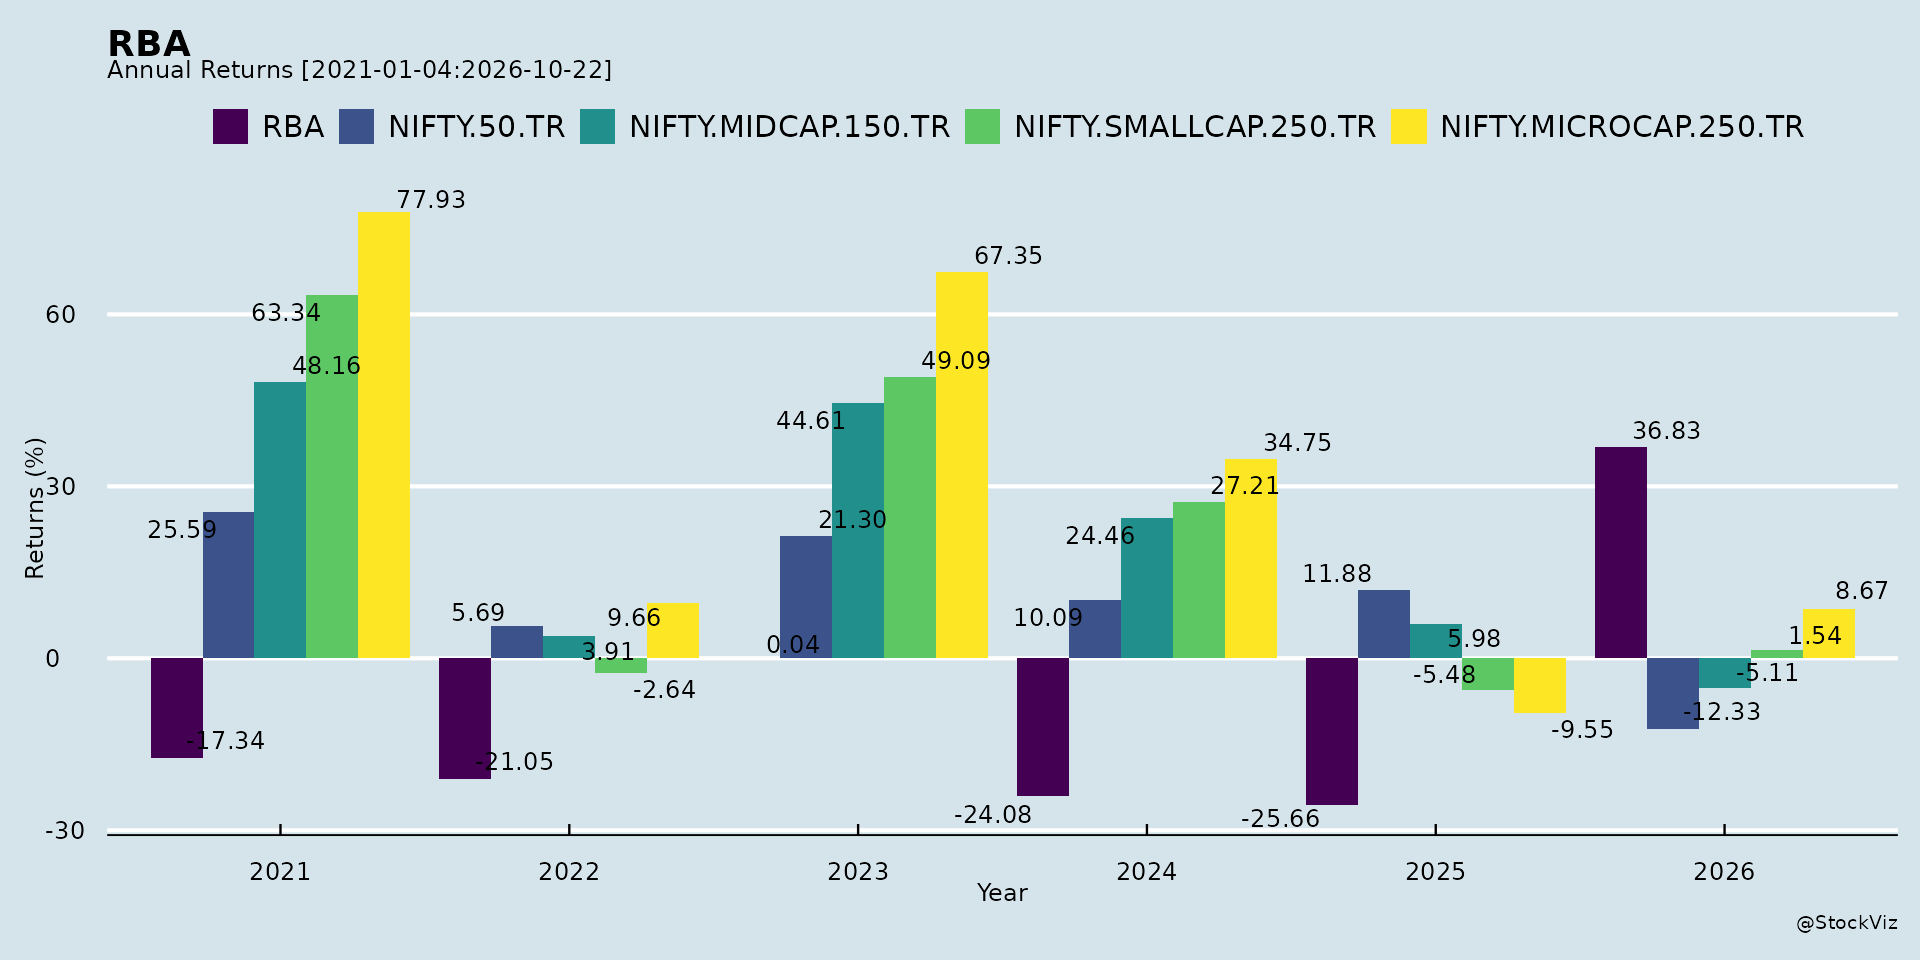
Annual Returns
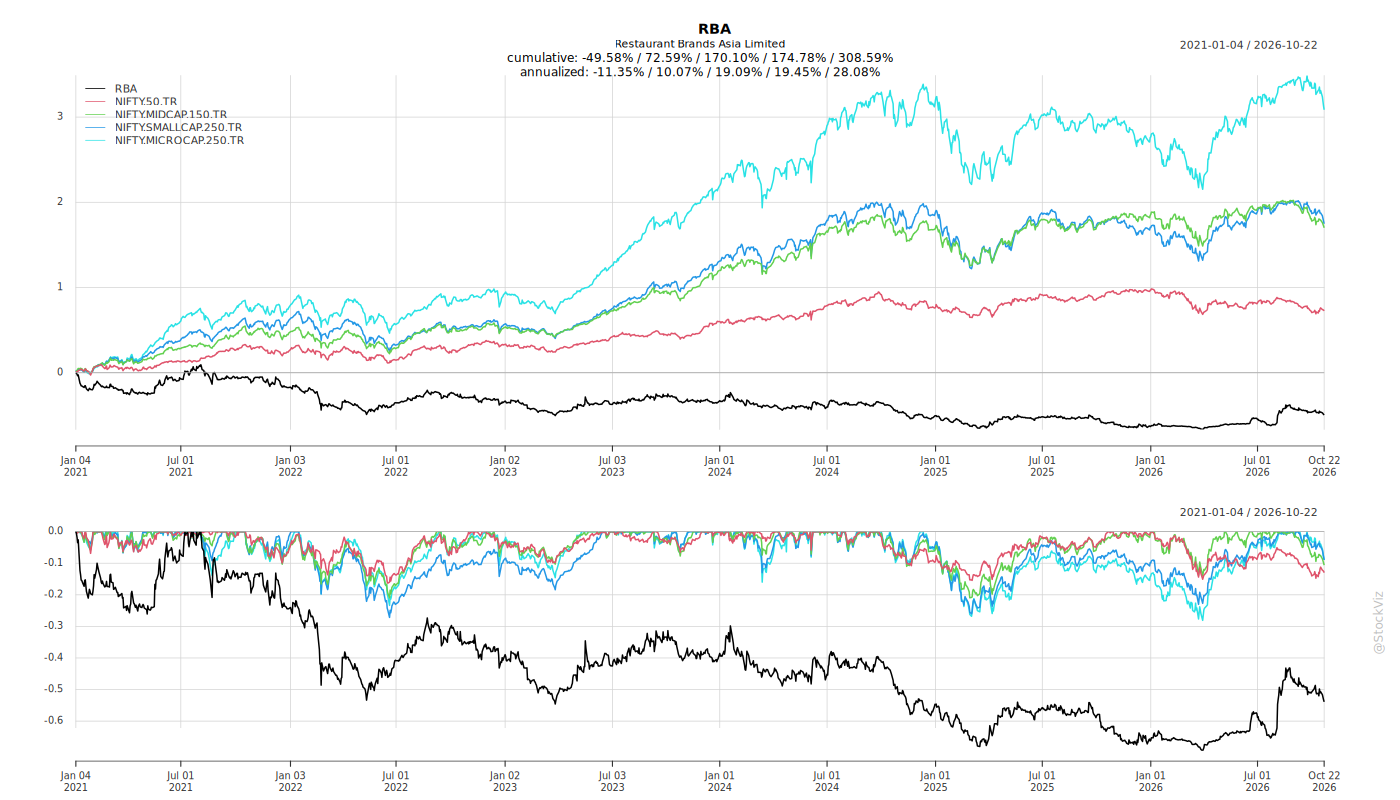
Cumulative Returns and Drawdowns
Fundamentals
Ownership
Margined
AI Summary
asof: 2026-09-17
Restaurant Brands Asia Limited — Recent Developments
1. Headwinds and Challenges
- Competitive and pricing pressure: The company identifies competitive intensity and the pricing environment in the market as material challenges, alongside economic conditions affecting demand and supply.
- Input and commodity costs: Changes in input costs and commodity price fluctuations are flagged as risks, as are currency rate fluctuations.
- Regulatory and tax environment: Government regulations and taxation, and significant changes in political stability in India and globally, are cited as challenges.
- Operating dependencies: The company cites its ability to maintain and manage key customer relationships and supply chain sources, and new or changed priorities of trade, as risk areas.
- External shocks: Climatic conditions, natural calamities, and litigation are identified as risks.
- Regulatory penalty: On September 03, 2026, the company received an order from the Additional District Magistrate, Agra (Case no. 784/2023) for violating Section 3(1)(zx) and Section 26(2)(ii) of the Food Safety and Standards Act, 2006, resulting in a penalty of Rs. 1,60,000. Management noted there is no material impact on the financial, operations, and other activities of the company.
- Indonesia subsidiary turnover decline: PT Sari Burger Indonesia’s standalone turnover declined across the last three financial years — IDR 1,109,225.52 million (FY24), IDR 965,168.88 million (FY25), and IDR 915,799.88 million (FY26) — and the subsidiary operates 137 outlets as of March 31, 2026.
2. Tailwinds and Growth Prospects
- Store network expansion: Burger King India opened its 600th restaurant in GTB Nagar, Delhi, on September 10, 2026, with 100+ restaurants across Delhi NCR and a presence across 140+ cities in India.
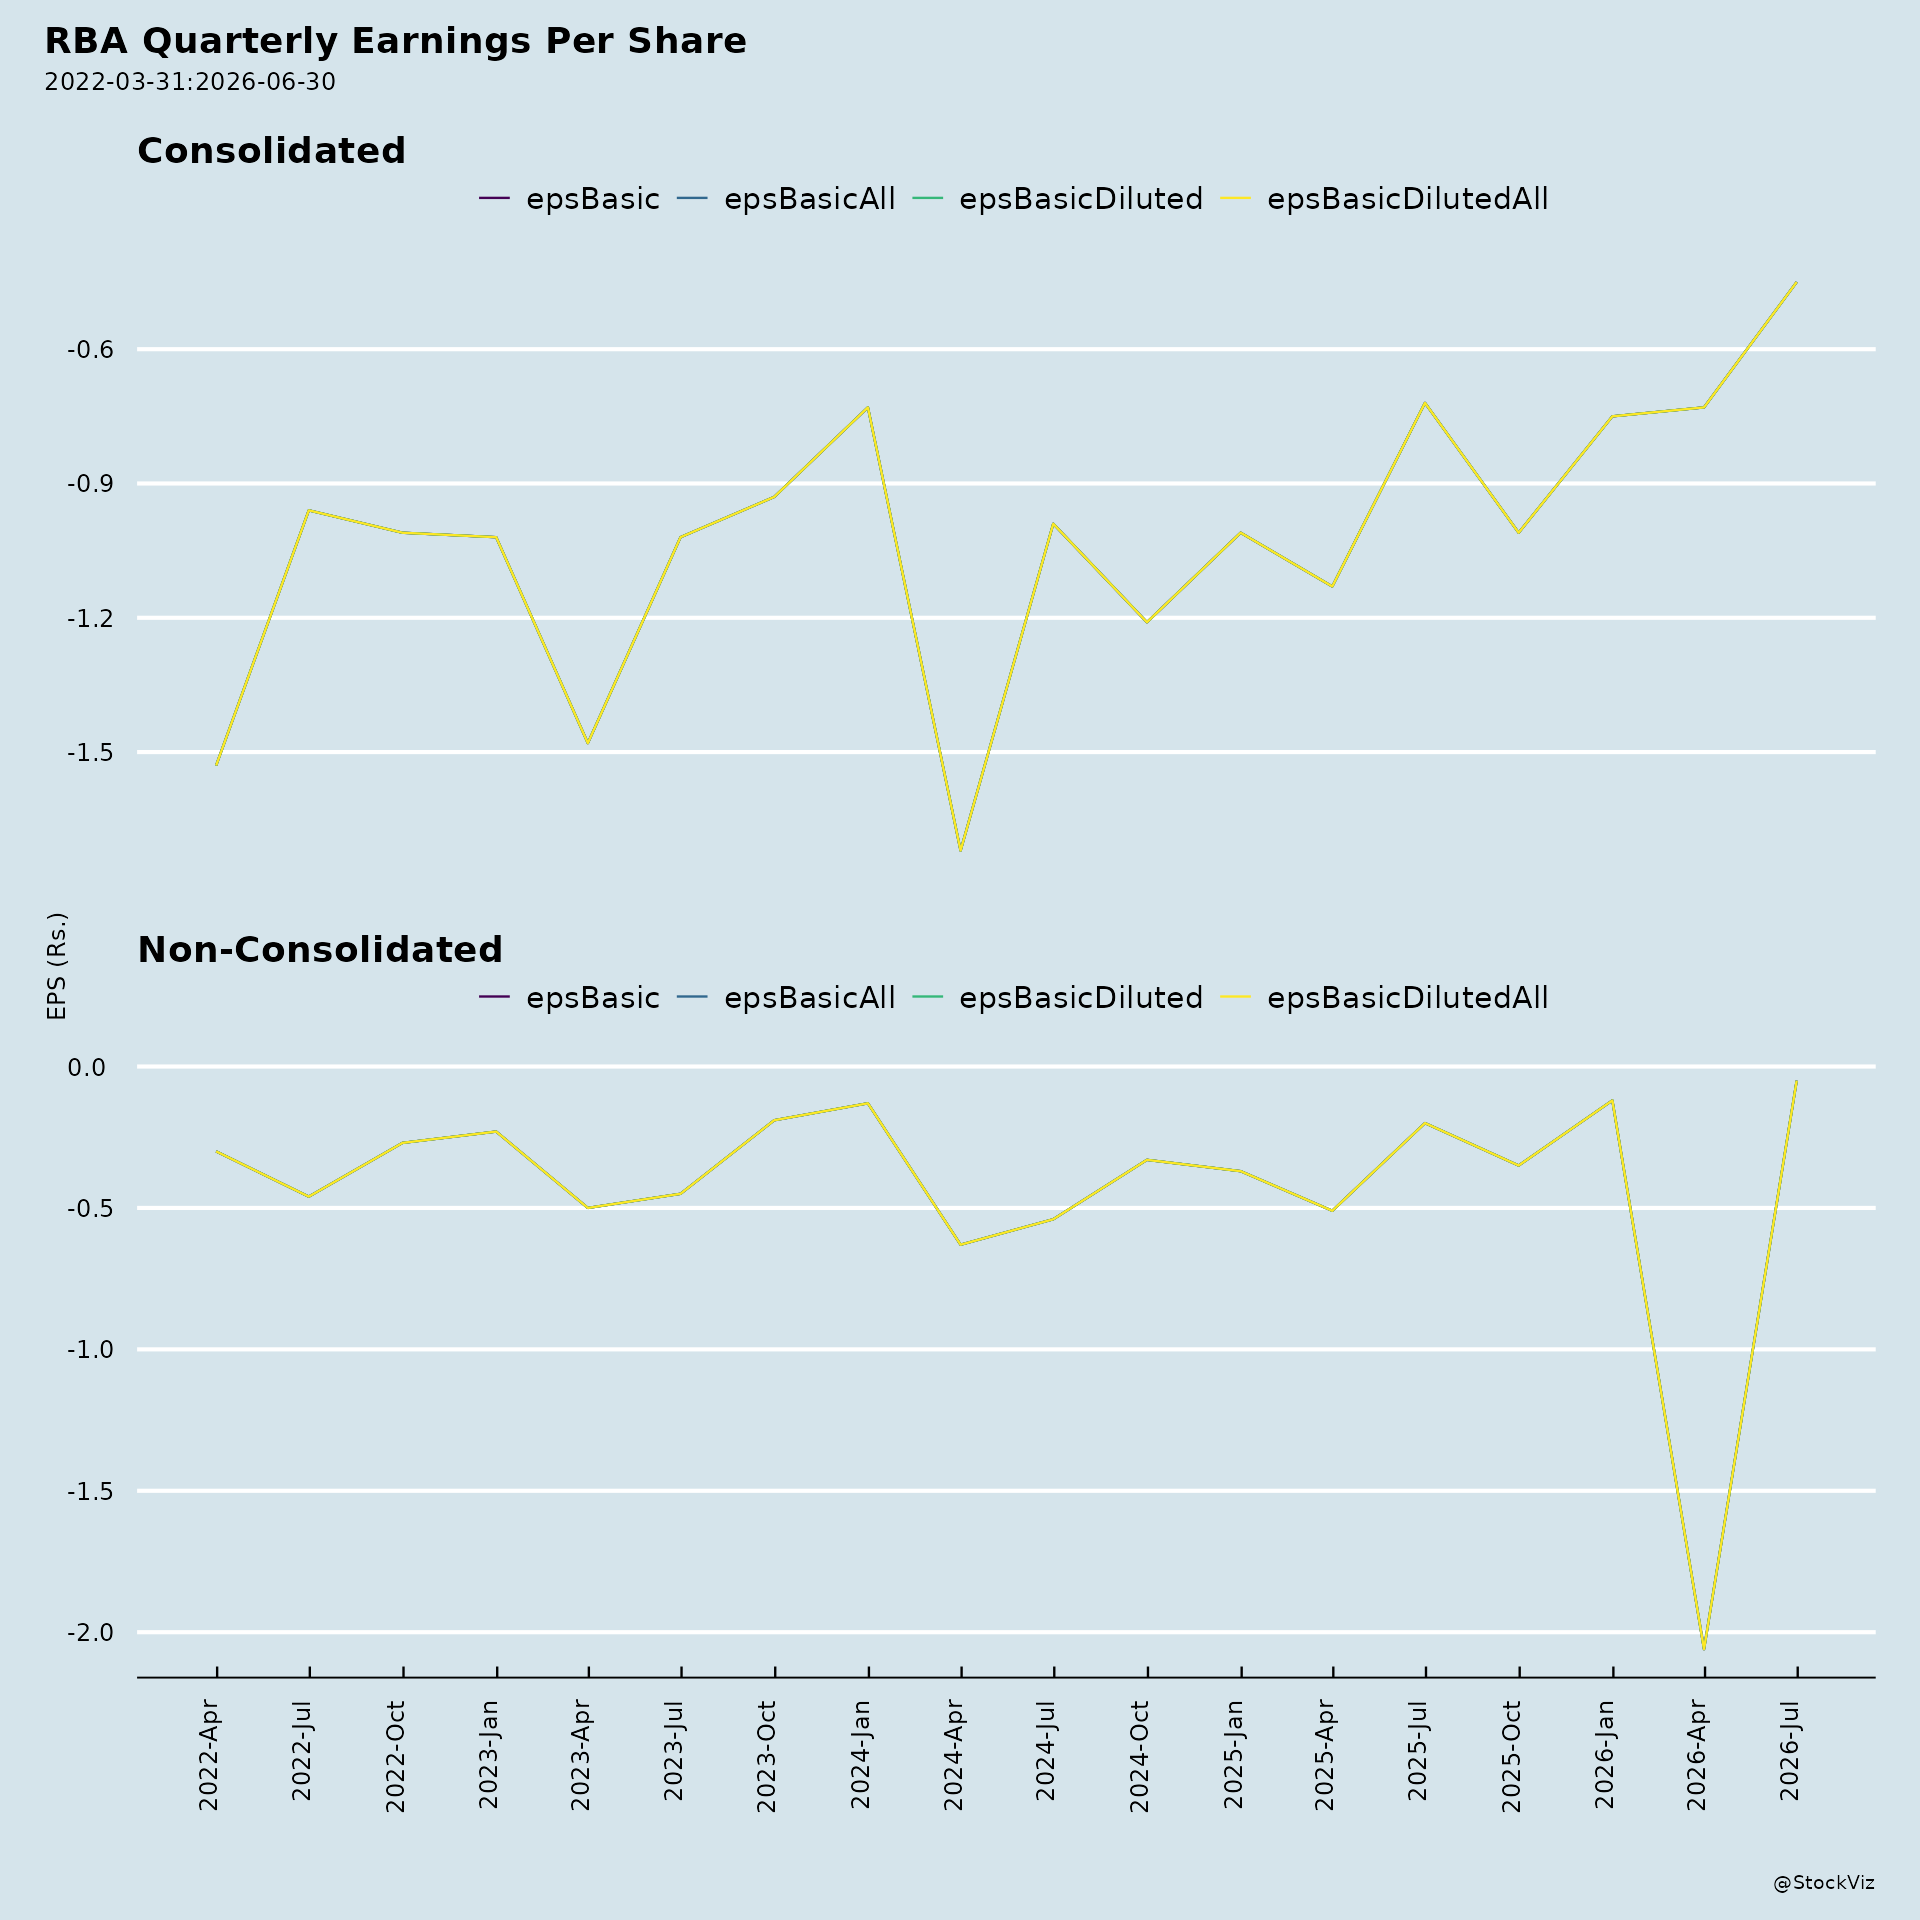
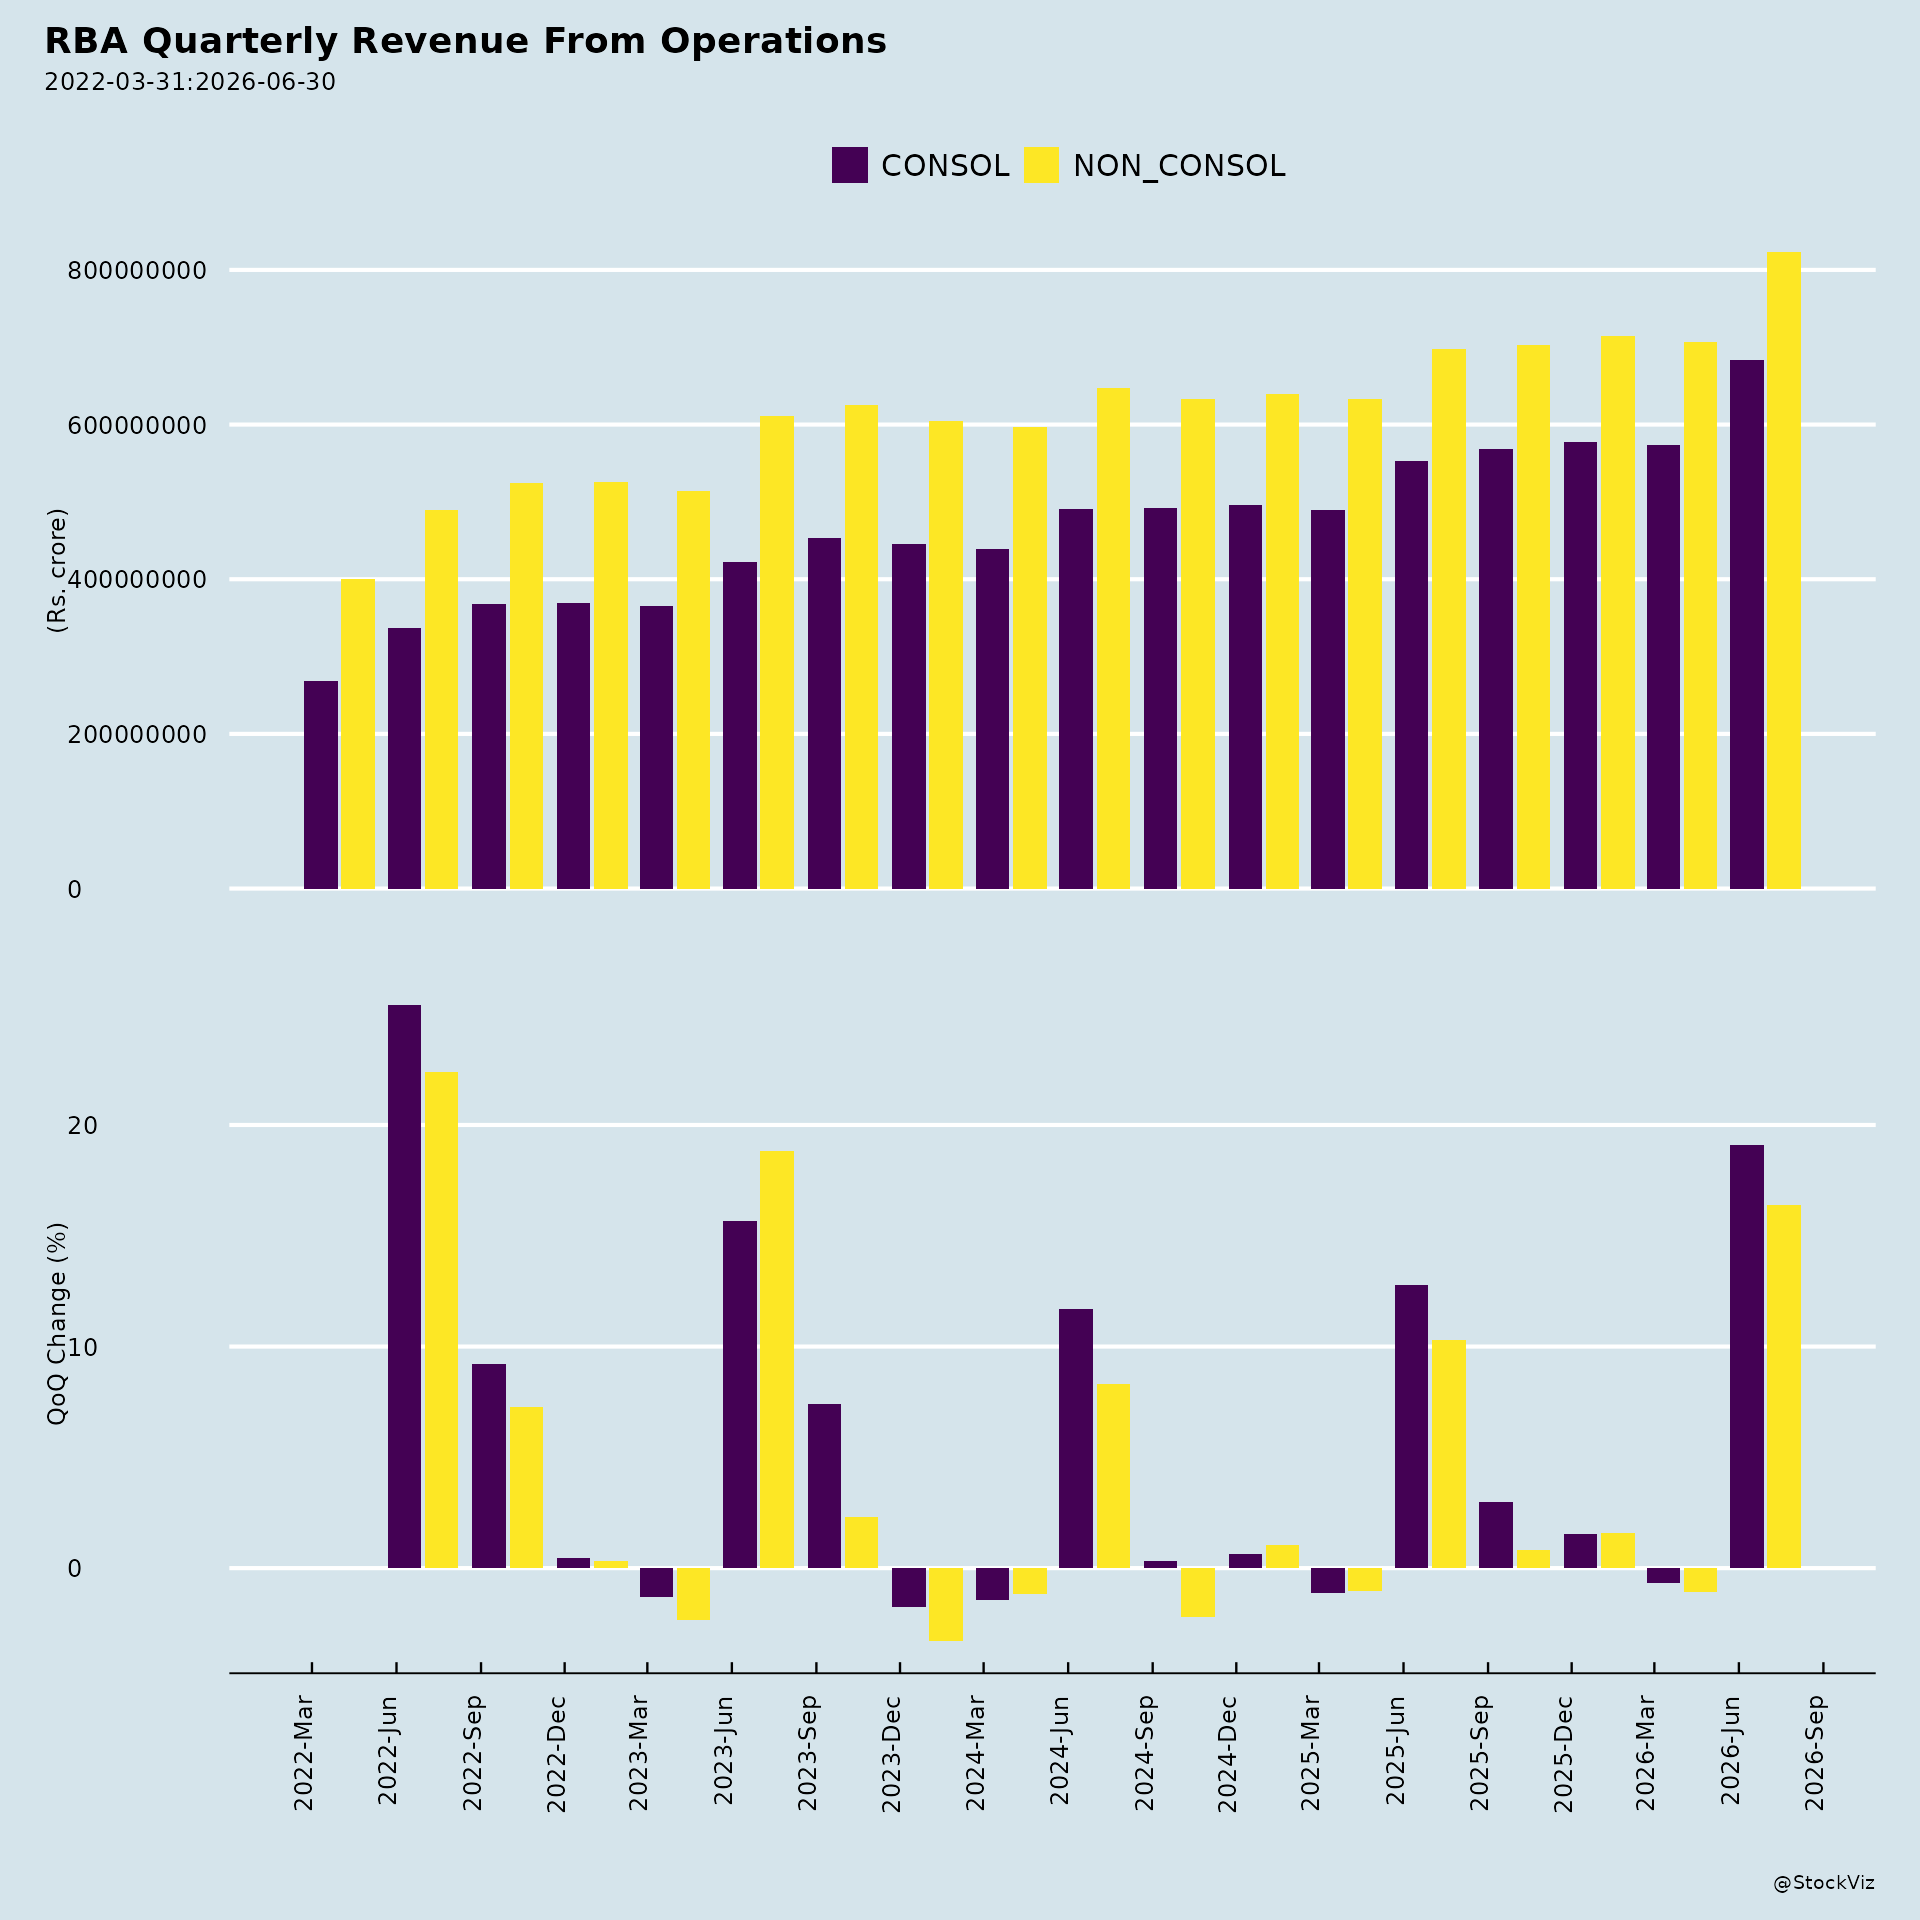
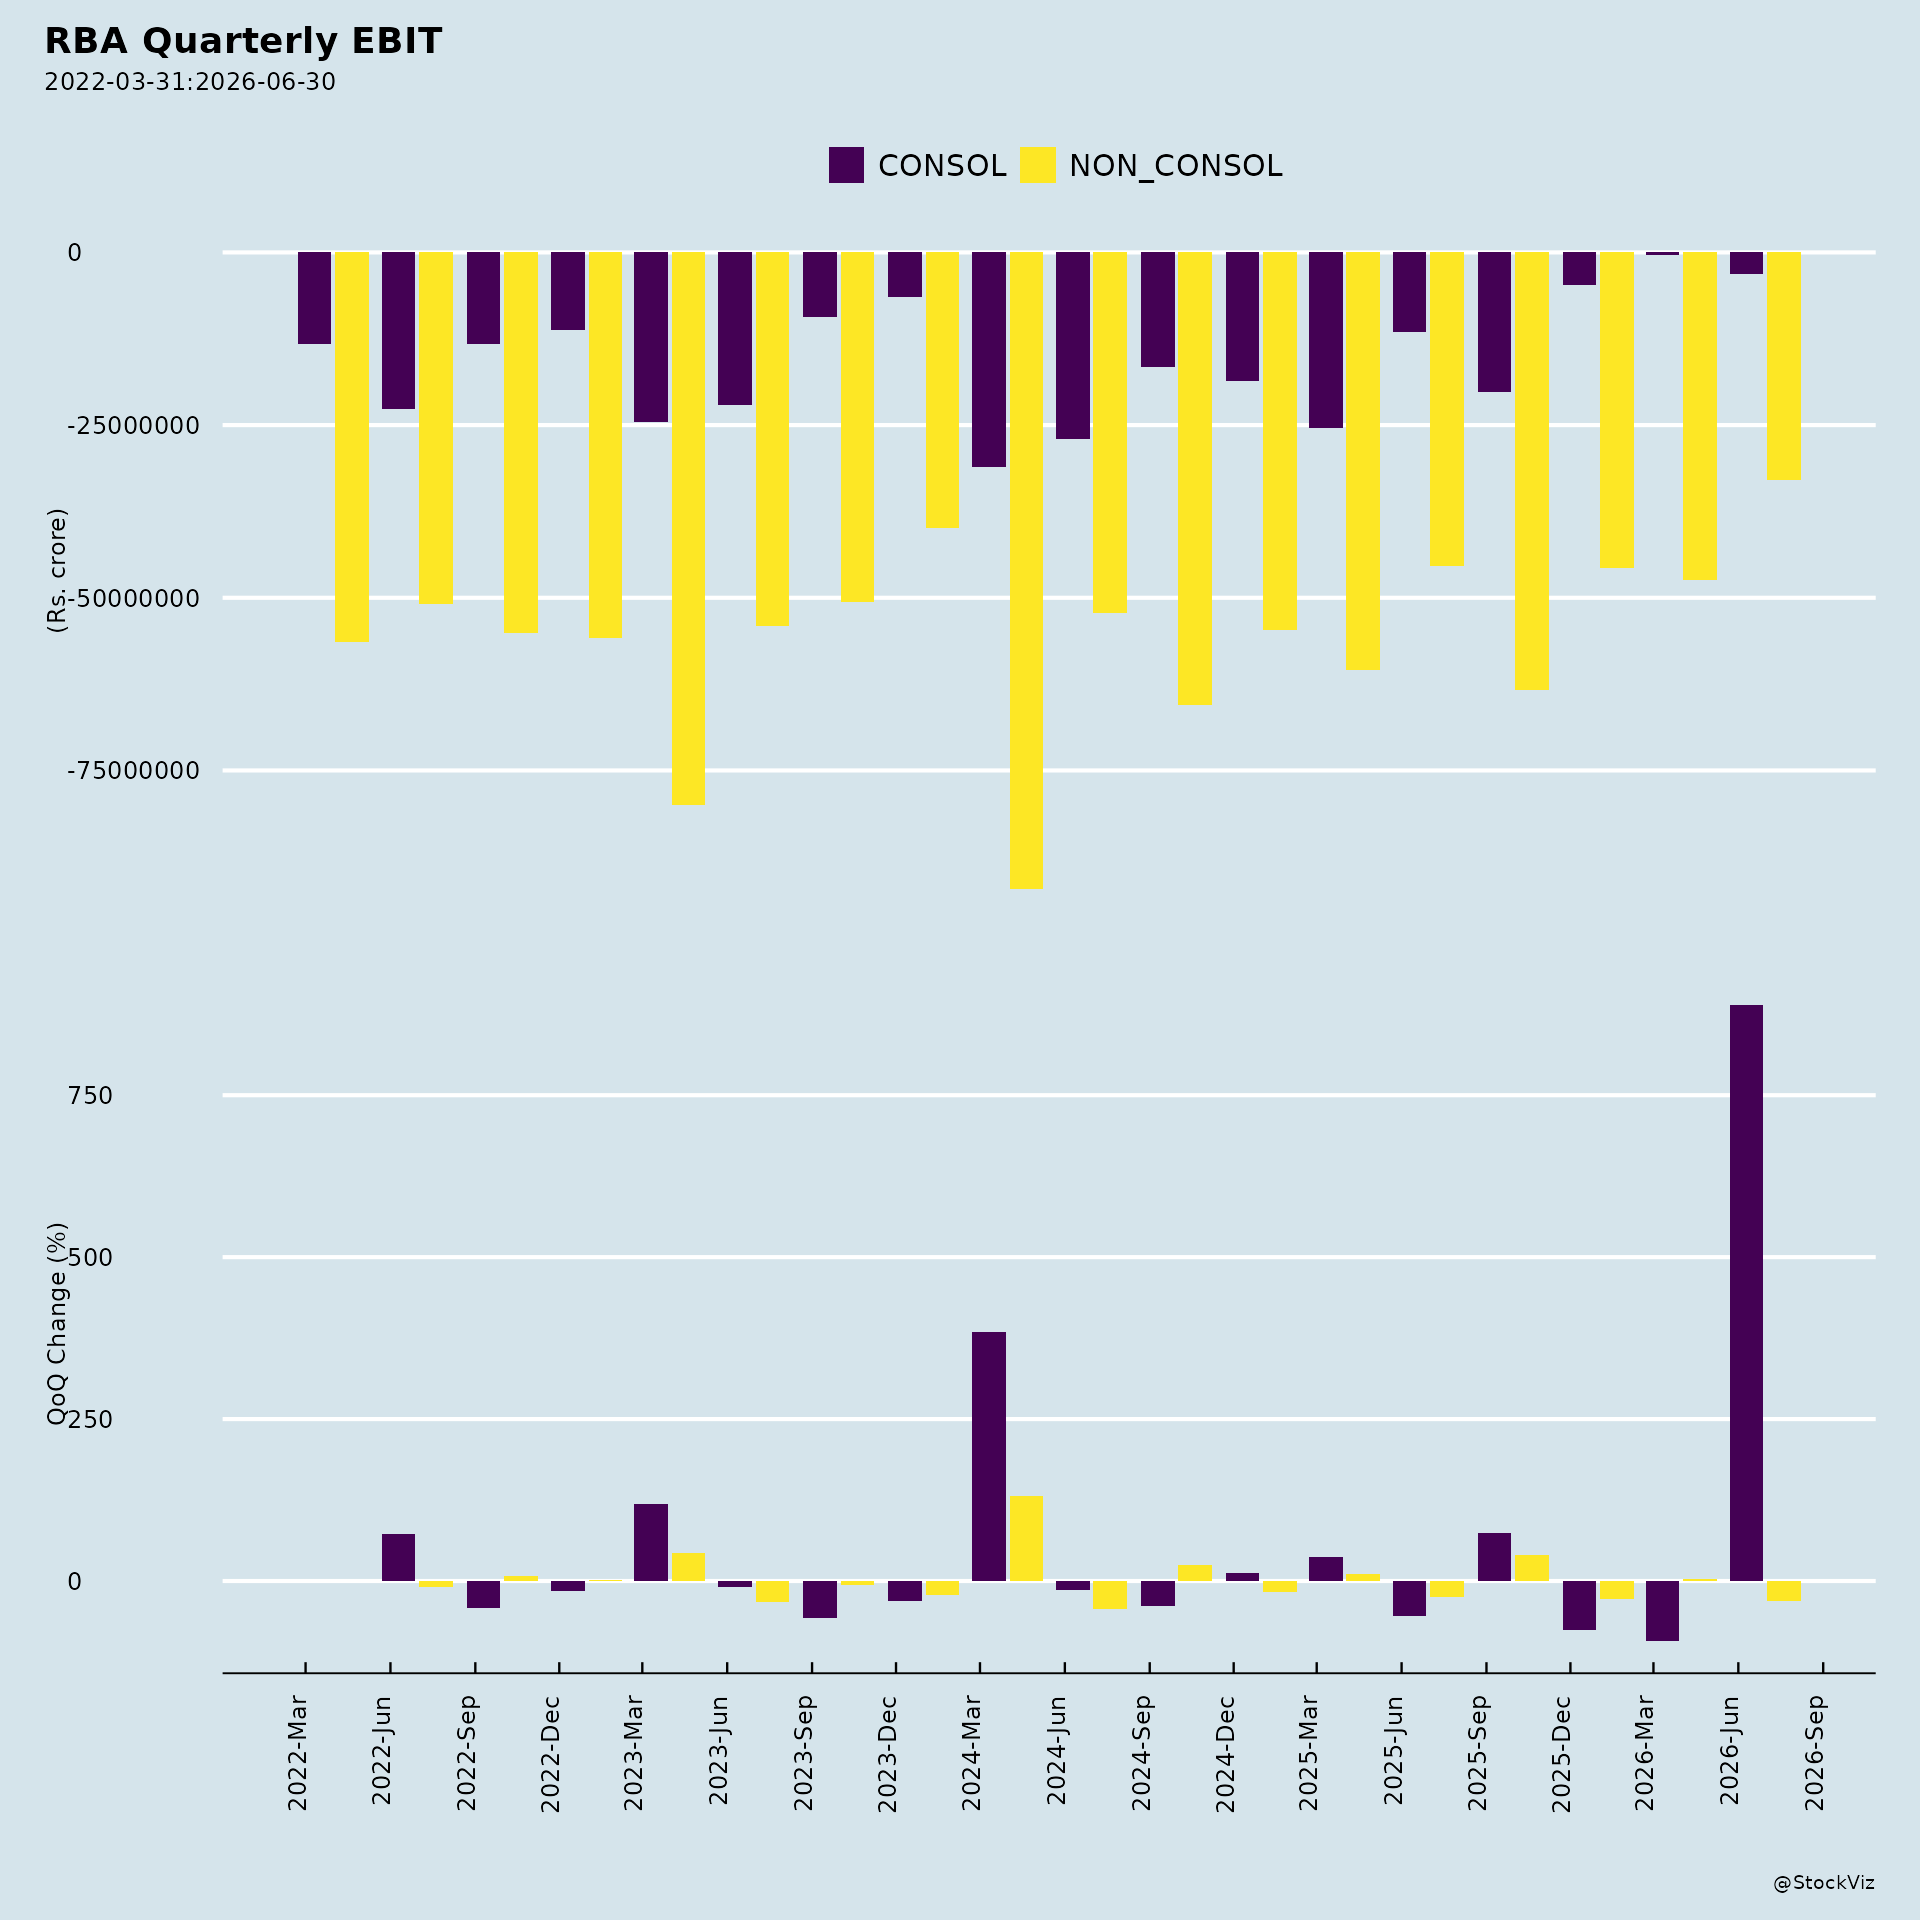
- Q1 FY27 performance: Same Store Sales Growth of 12.6% (highest in the last 15 quarters), revenue growth of 23.6% YoY, and Company EBITDA growing 2.3x to INR 52.7 Crs. India revenue from operations was INR 6,829 Mn, with a gross margin of 70.8%. Total store count reached 590 in India and 752 consolidated.
- Strategic initiatives: Scaling mindfully, building a strong network of supply partners, innovation, value propositions, adding the BK Café business, and rapid digital adoption. The Q1 FY27 document also cites menu strengthening, digital expansion, and value leadership initiatives.
- Franchise footprint: The company is the national master franchisee of the Burger King brand in India, and its subsidiaries are exclusive national master franchisees of Burger King and Popeyes in Indonesia.
- Capital infusion into Indonesia: On August 03, 2026, the Board approved investment in PT Sari Burger Indonesia by subscribing to up to 1,00,000 redeemable cumulative non-convertible preference shares at IDR 1,000,000 each, for an amount not exceeding IDR 100 billion, in one or more tranches, with proceeds used to meet the subsidiary’s business requirements. Completion is indicated up to December 31, 2026, with no change in equity shareholding and no voting rights attached to the preference shares.
3. Key Risks
- Earnings volatility: Risks and uncertainties regarding fluctuations in earnings.
- Demand/supply and macro: Economic conditions affecting demand and supply; significant changes in political stability in India and globally.
- Cost and currency: Change in input costs; commodity price fluctuations; currency rate fluctuations.
- Relationships and trade: Ability to maintain and manage key customer relationships and supply chain sources; new or changed priorities of trade.
- Regulatory, tax, and legal: Government regulations and taxation; litigation; the Agra FSSAI penalty order.
- External events: Climatic conditions and natural calamity.
- Forward-looking statement risk: Management states it cannot guarantee that forward-looking statements will be realized due to various external risk factors.
4. Management Guidance Versus Observed Business Performance
- Guidance framing: Management notes that statements relating to objectives, projections, outlook, expectations, and estimates constitute forward-looking statements, and that actual results may differ due to external risks and uncertainties. No unpublished price sensitive information is to be disclosed at the investor conferences (Ashwamedh – Elara India Dialogue 2026 on September 3, 2026; Anand Rathi G-200 Summit 2026 on September 21, 2026; Prabhudas Lilladher Mid & Small Cap Conference 2026 on September 28, 2026) beyond what is already public.
- Observed performance against stated initiatives: The Q1 FY27 disclosures report Same Store Sales Growth of 12.6% (highest in 15 quarters), revenue growth of 23.6% YoY, Company EBITDA growth of 2.3x to INR 52.7 Crs, gross margin of 70.8%, and store counts of 590 in India and 752 consolidated — consistent with the stated focus areas of menu strengthening, digital expansion, and value leadership.
- Milestone versus network targets: The 600th India restaurant opening on September 10, 2026, with 100+ outlets in Delhi NCR and presence in 140+ cities, follows the Q1 FY27 India store count of 590.
- Indonesia trajectory: The proposed preference share investment of up to IDR 100 billion is intended to meet BK Indonesia’s business requirements, against a backdrop of declining standalone turnover over FY24–FY26 and 137 outlets as of March 31, 2026.
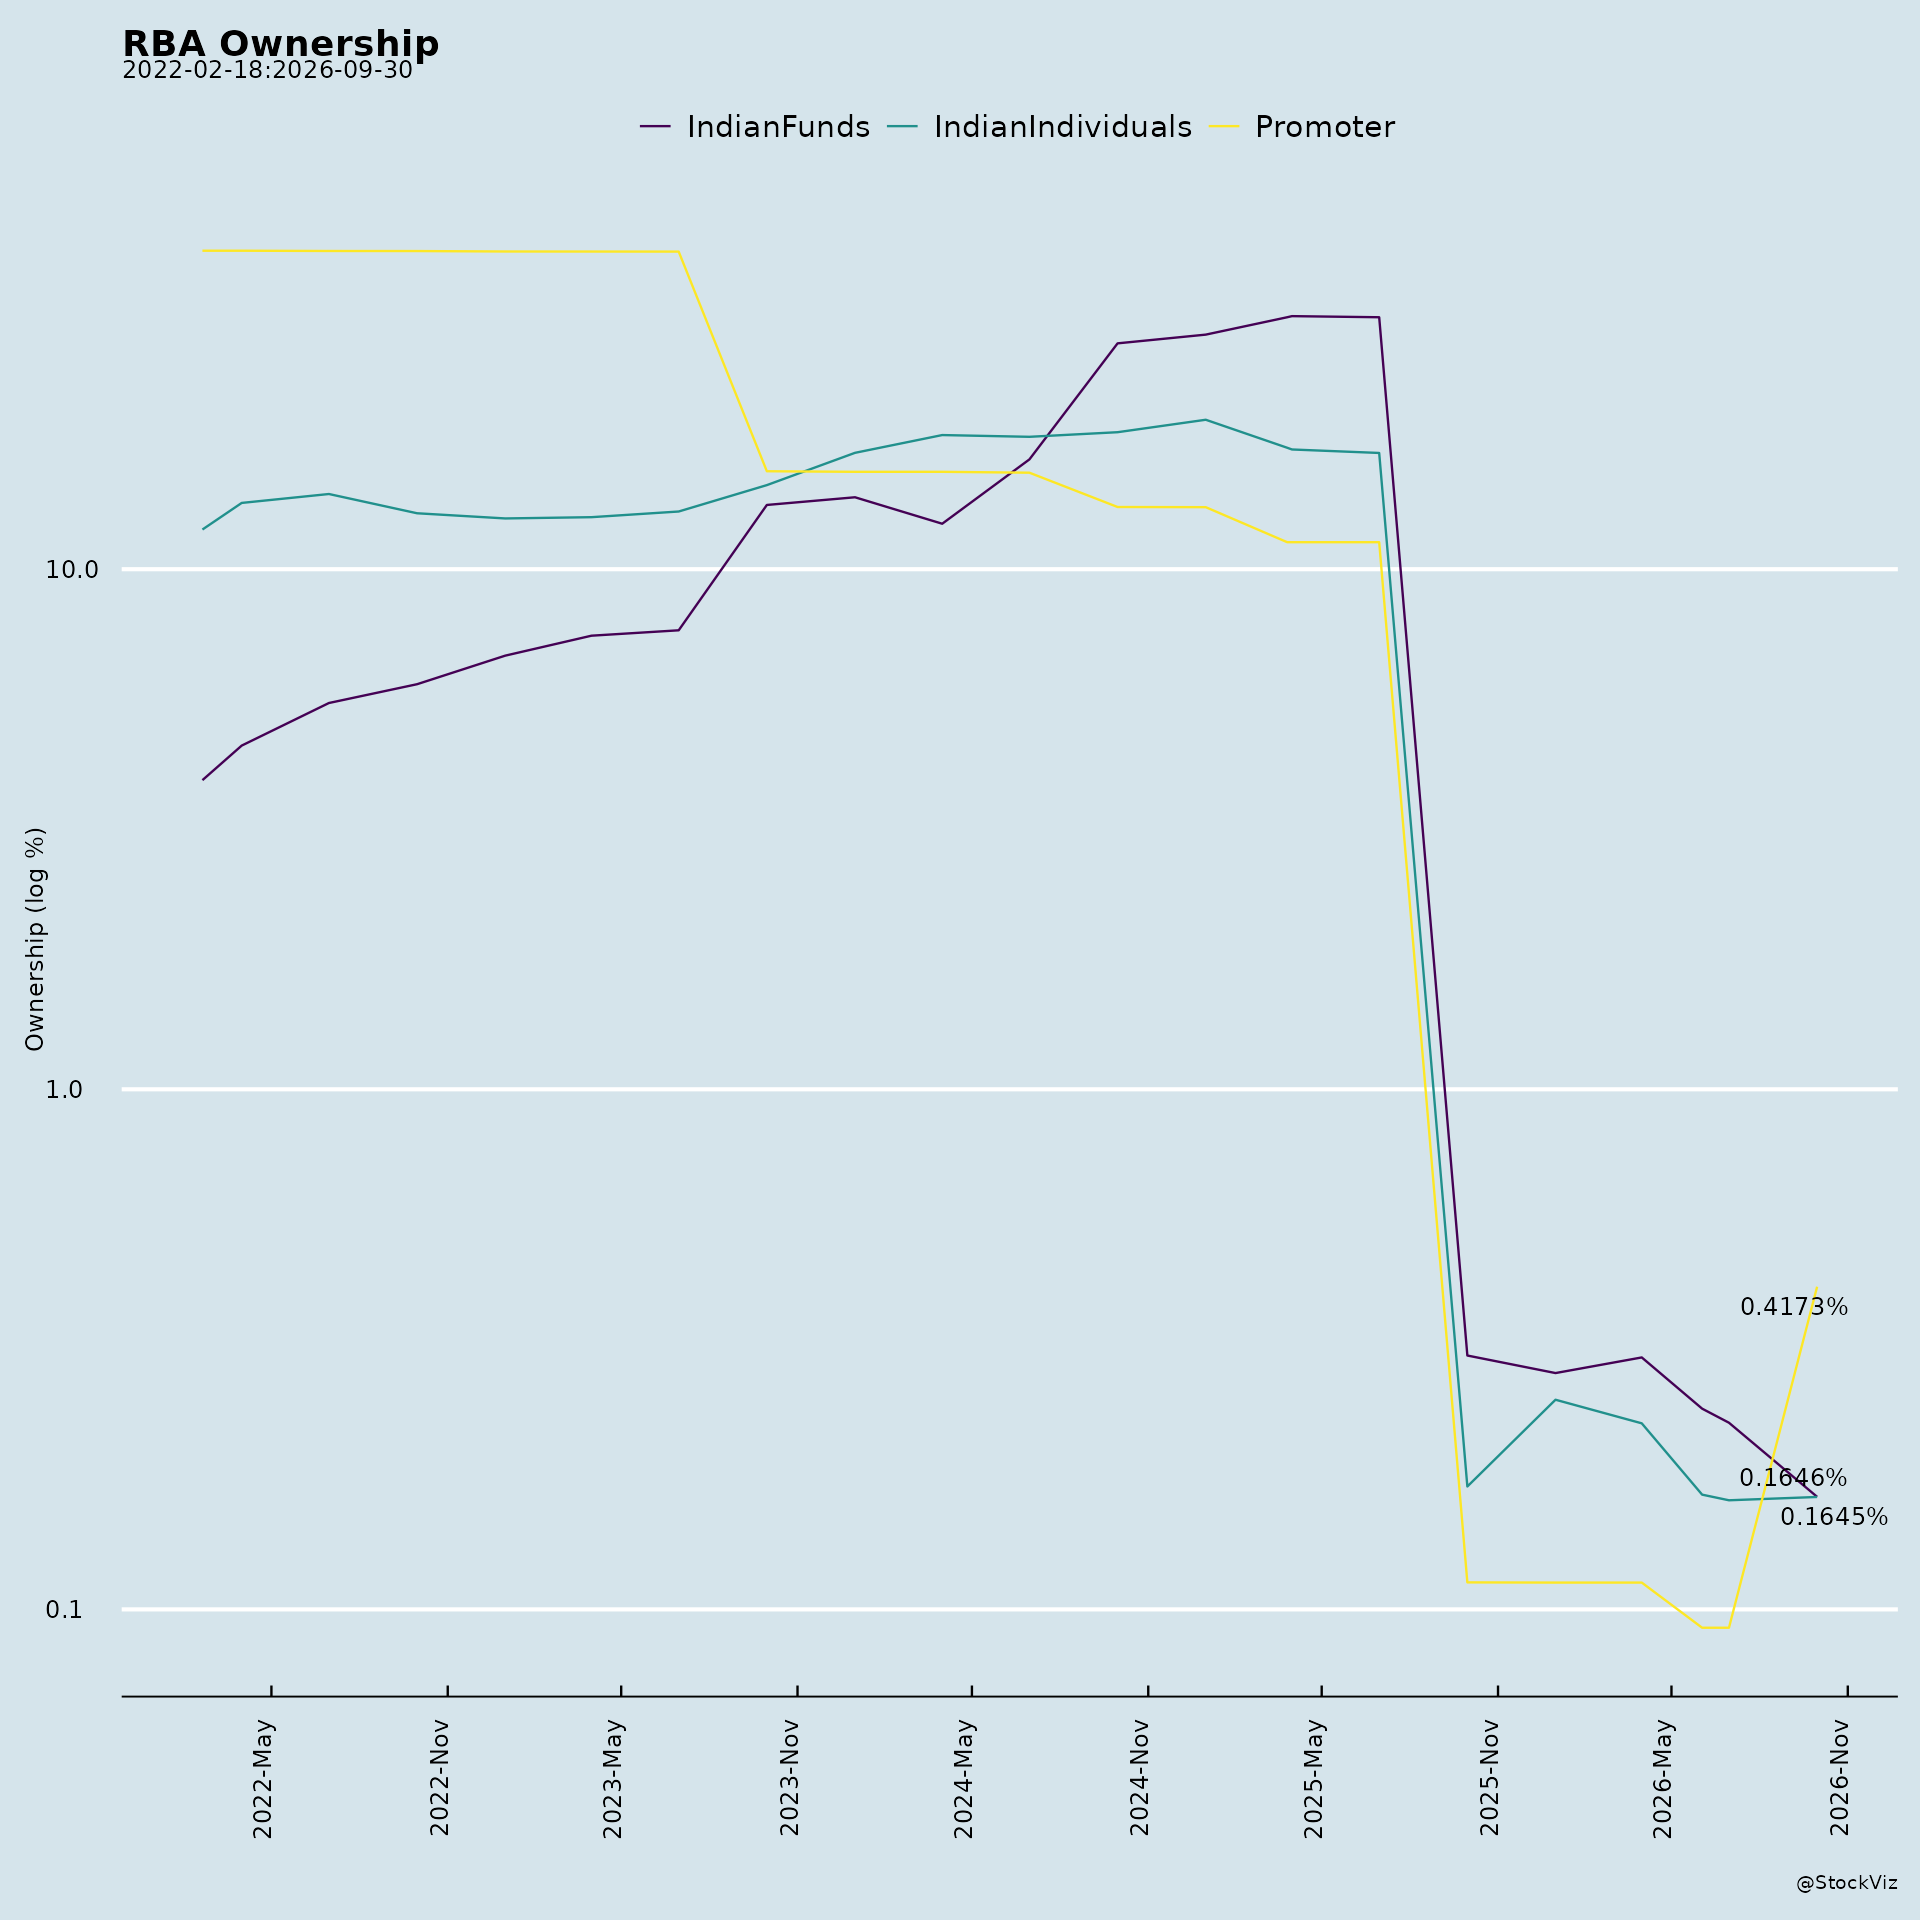
- Ownership transition: Following completion of the open offer on July 6, 2026, and acquisition of 6,56,23,090 equity shares from Seller 1 (plus 1 share from Seller 2 as nominee) as intimated July 7, 2026, the Acquirers and IATL acquired control and became promoters effective July 7, 2026; the Sellers ceased to be promoter/promoter group and were reclassified to public category under Regulation 31A. The preferential allotment on June 2, 2026 included 12,85,71,128 equity shares and 8,57,14,285 warrants to Acquirer 1, and 100 equity shares each to Acquirer 2, Acquirer 3, and Acquirer 4.
- Governance outcomes: At the 13th AGM on August 20, 2026, all four resolutions passed — adoption of audited standalone and consolidated financial statements for FY ended March 31, 2026 (99.9997% in favour); re-appointment of Mr. Rafael Odorizzi De Oliveira (94.289% in favour, with 15.7467% of public institution votes against); appointment of Mr. Madhusudan Bhagwandas Agrawal (99.9729% in favour); and appointment of Mr. Aayush Madhusudan Agrawal (99.973% in favour).
Broker Narrative
The broker narrative evolved from broad concerns about Indonesia’s macroeconomic slowdown and margin pressures to a sharp focus on India’s exceptional performance, while Indonesia remained a persistent drag. Early optimism about Popeyes’ traction in Indonesia faded, and the discussion shifted toward a potential exit from the Indonesia business.
Fears that came true
- Indonesia’s regional economic slowdown persisted, with BK Indonesia revenues declining 3.9% YoY and ongoing EBITDA losses.
- The earlier widening net losses continued, as adjusted PAT loss widened to Rs31.7mn due to a forex MTM loss on Indonesia investment.
Optimism that failed
- Indonesia Popeyes’ early traction did not sustain, as it saw muted traction amid intense competition from regional players.
Broker Timeline
25 broker calls · 2023-05-18 to 2026-08-04
Copyright © 2023 SAS Data Analytics Pvt. Ltd. All rights reserved.