RAMCOCEM
Equity Metrics
November 18, 2026
The Ramco Cements Limited
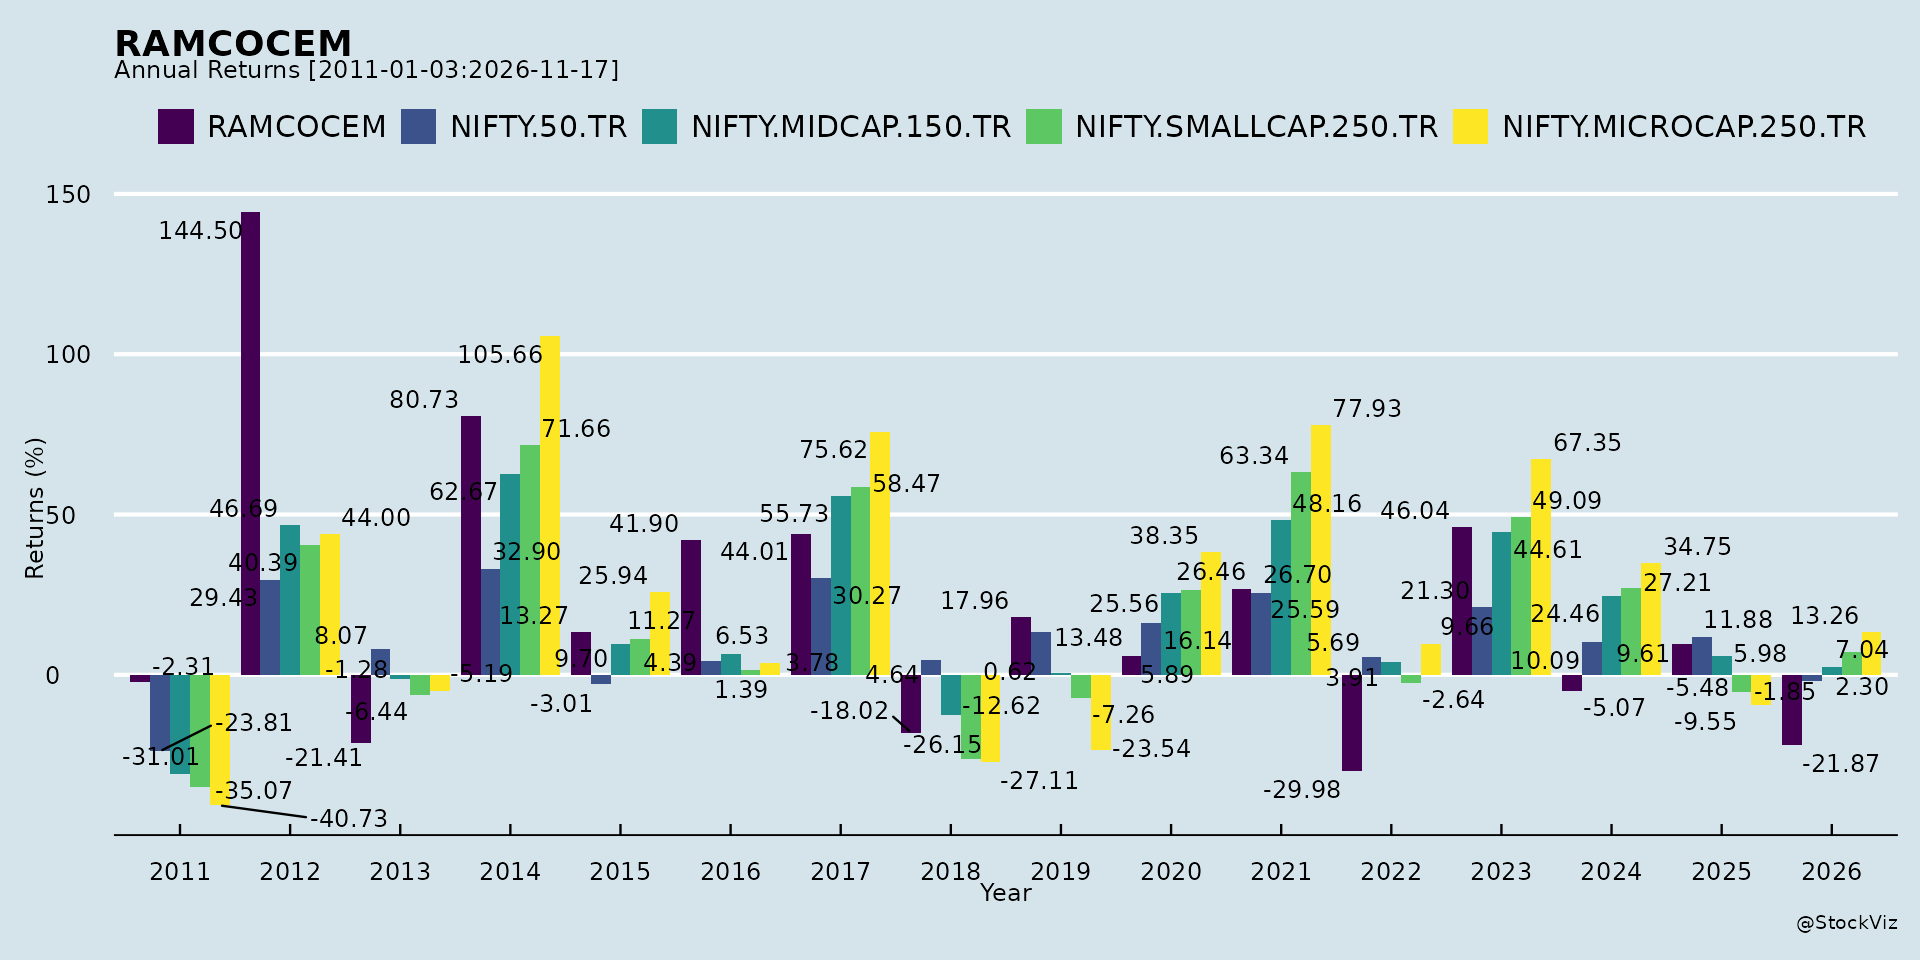
Annual Returns
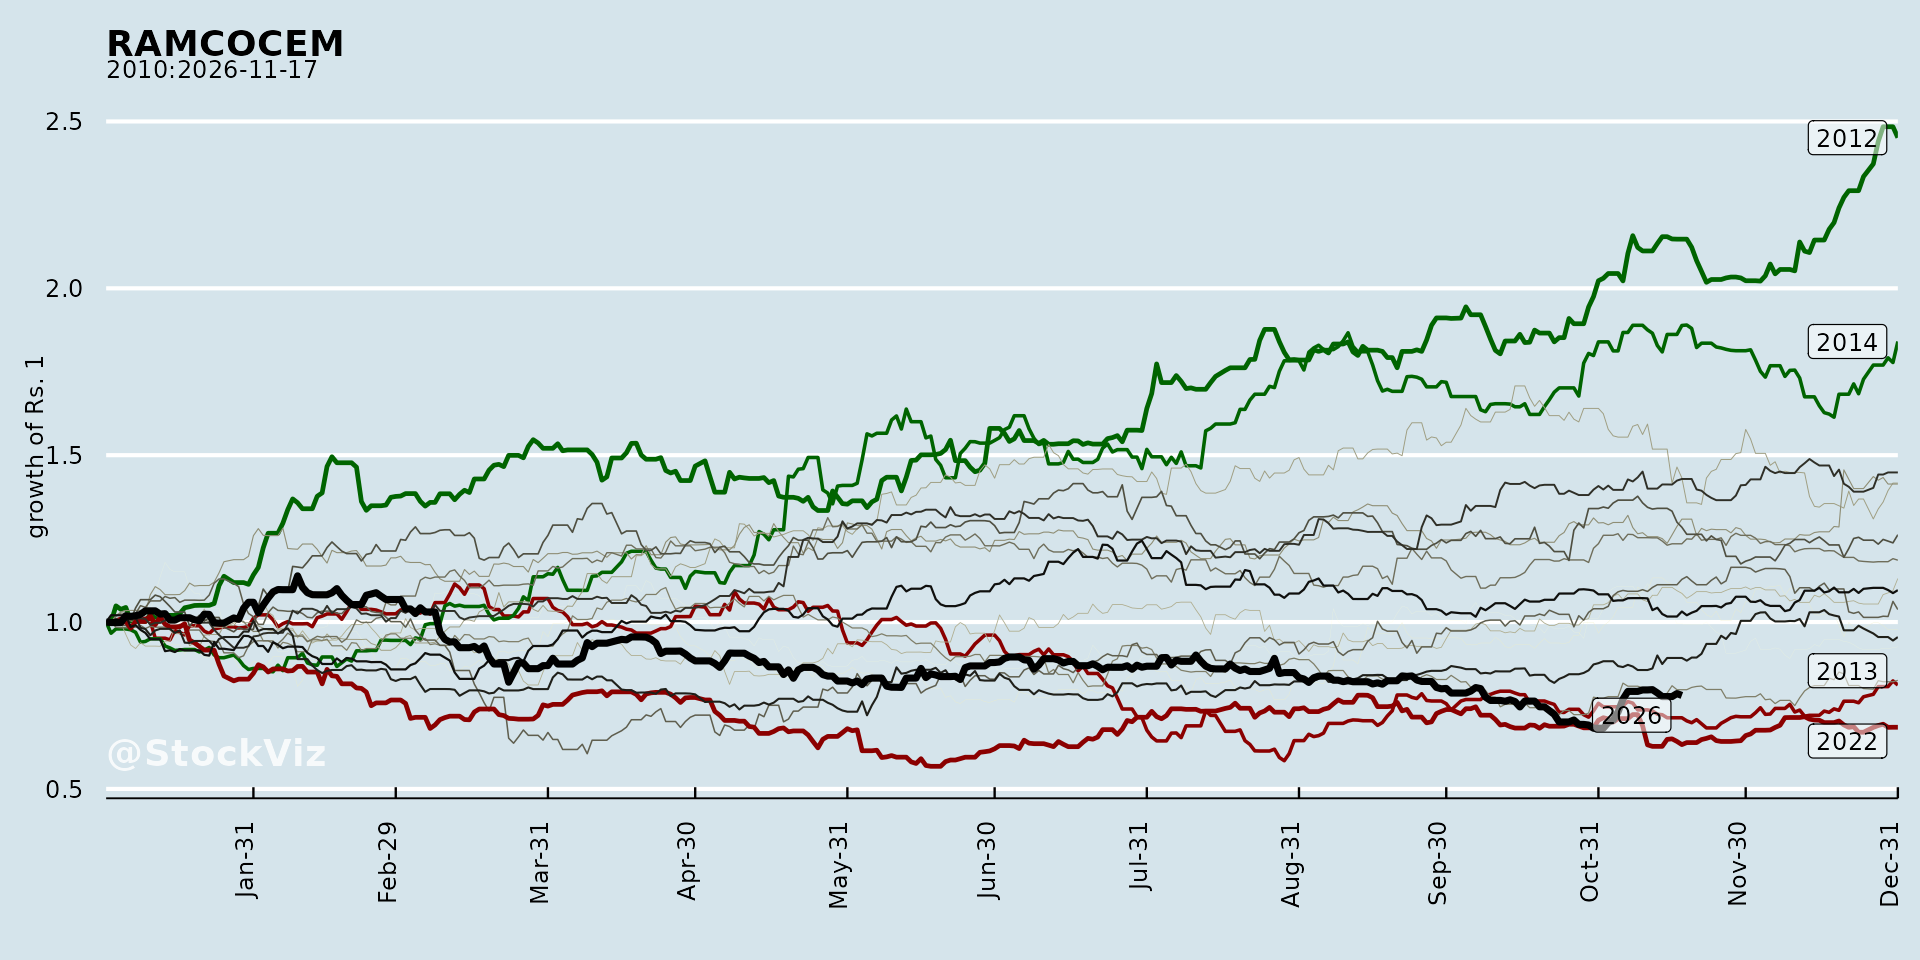
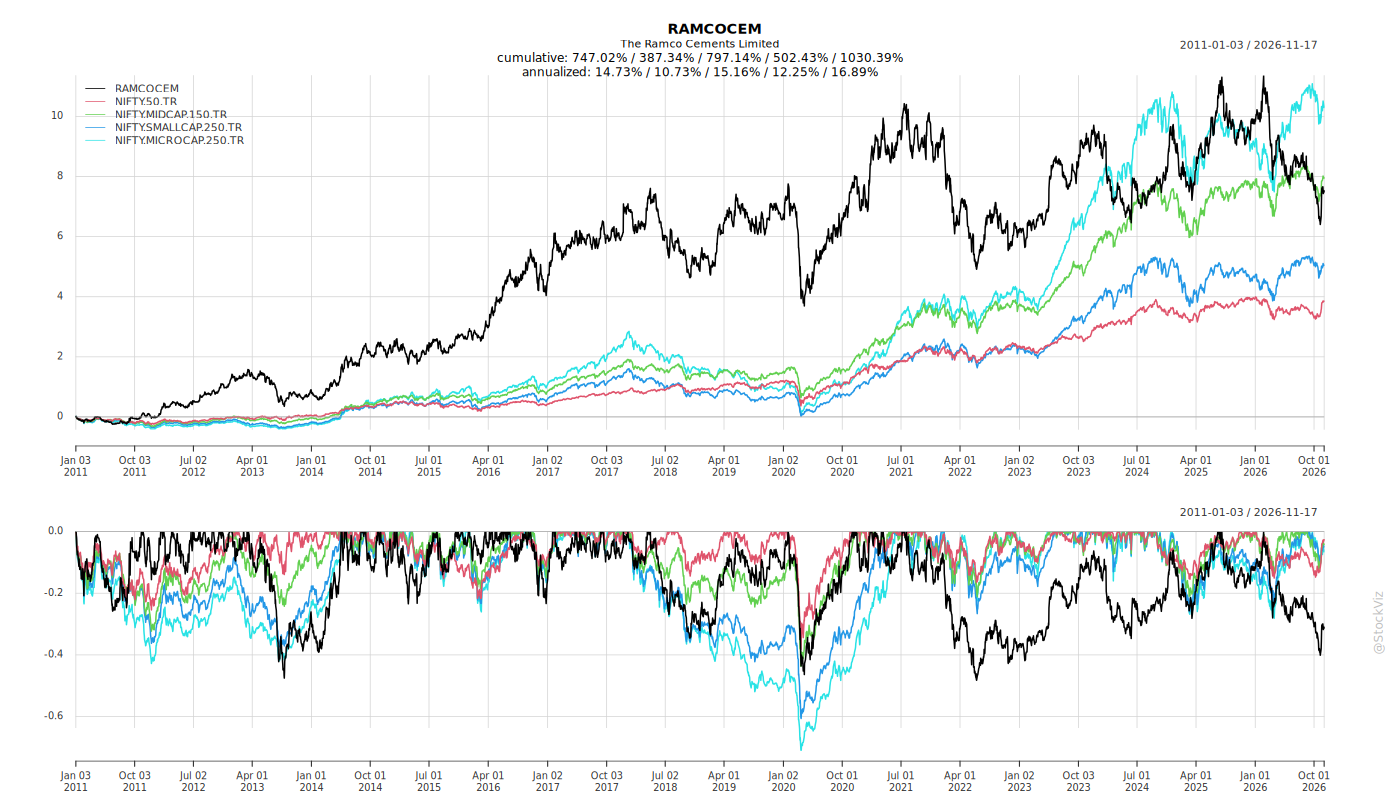
Cumulative Returns and Drawdowns
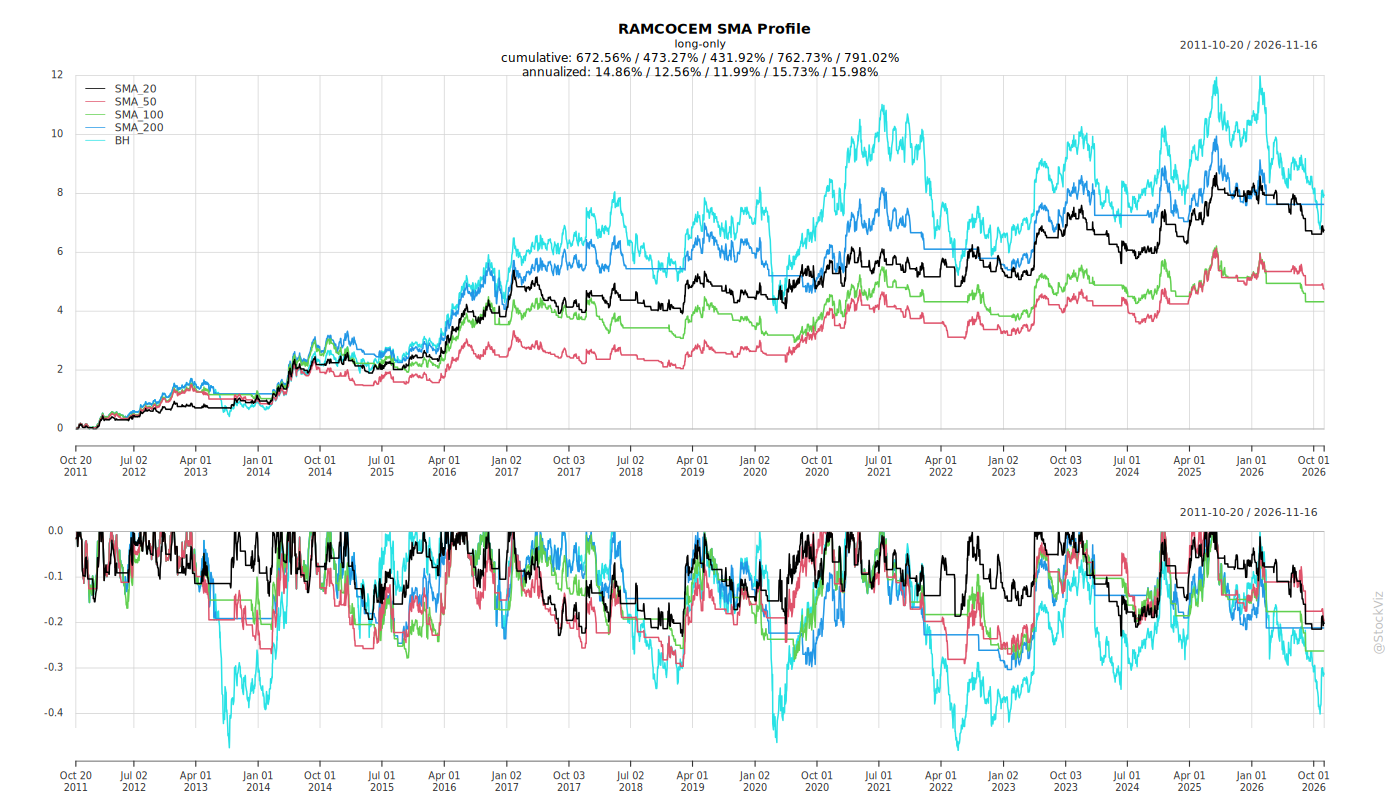
Fundamentals
Ownership
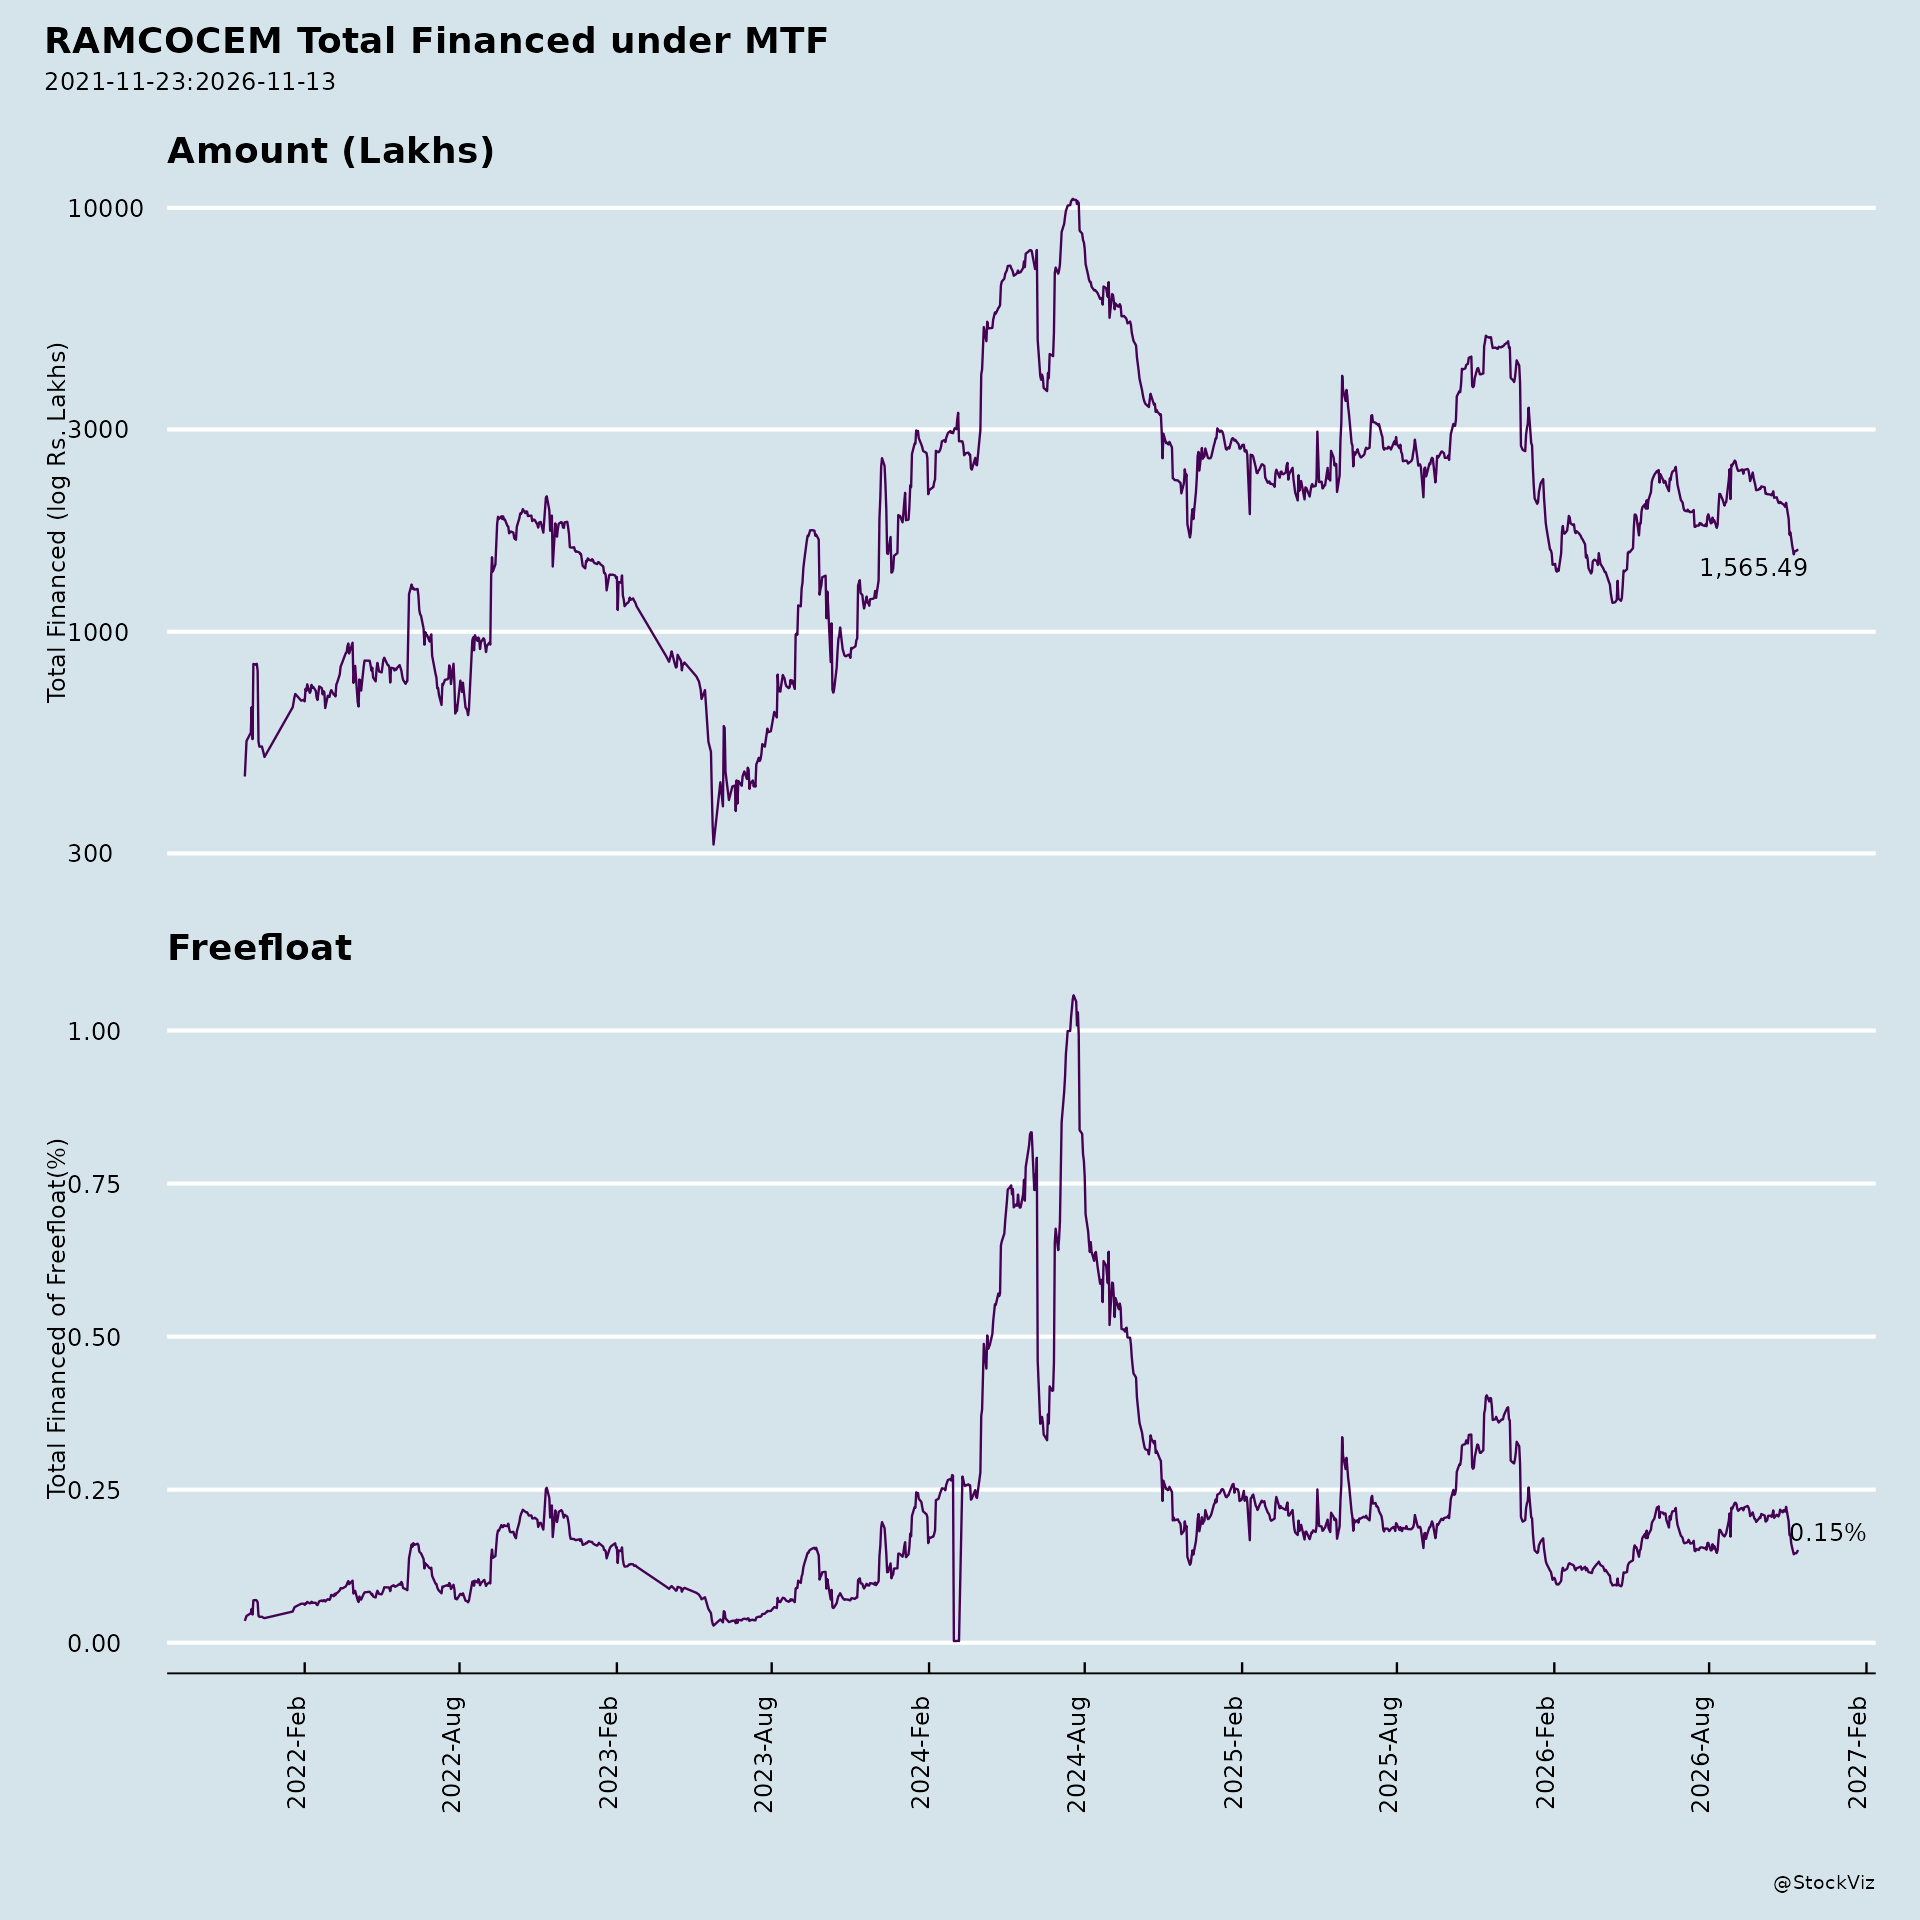
Margined
AI Summary
asof: 2026-09-16
RAMCOCEM: Recent Corporate Announcements Summary
1. Headwinds and Challenges
- Competition Commission of India (CCI) penalty: A penalty of Rs. 258.63 Crores was imposed by the CCI on 31-08-2016 over alleged cartelisation. The matter remains under legal appeal at the Supreme Court.
- Foreign operations: The company closed the operations of its foreign branch in Sri Lanka due to un-viability.
- Regulatory transition: The company continues to monitor the finalisation of State Rules and further clarifications relating to the Labour Codes, and will give effect to such changes in its books as and when required.
- Cancelled investor meeting: An investor meeting scheduled for 11th September 2026 with Motilal AMC at the Corporate Office in Chennai, organised by 360 ONE Capital Market Private Limited, was cancelled.
2. Tailwinds and Growth Prospects
- Mineral Bearing Land Tax cessation: Following the Mines and Minerals (Development and Regulation) Amendment Act, 2026 (MMDR), the company is no longer required to pay Rs. 160/- per tonne of limestone towards Mineral Bearing Land Tax in Tamil Nadu with effect from 22nd August 2026. Management expects this to reduce operating costs and favourably impact profitability and cash flows.
- Biodiversity recognition: The Pandalgudi limestone mine restoration received Advanced Certification from The Global Biodiversity Standard, making it the first site in Peninsular India to receive this recognition. The project inspired the Rajapalayam Masterplan and the declaration of Rajapalayam as one of four towns in Tamil Nadu on a fast track to carbon neutrality by 2041.
- Scale and footprint: Ramco Cements Limited, headquartered in Chennai, Tamil Nadu, was incorporated in 1957 and has an installed capacity of over 20 million tonnes per annum across more than ten manufacturing facilities in southern and eastern India.
3. Key Risks
- The CCI penalty of Rs. 258.63 Crores remains subject to an ongoing legal appeal at the Supreme Court, leaving the outcome unresolved.
- The Sri Lanka foreign branch was closed due to un-viability, reflecting challenges in that overseas operation.
- The company remains exposed to evolving regulatory requirements under the Labour Codes, with State Rules and Government clarifications still pending.
4. Management Guidance vs. Observed Business Performance
- Mineral Bearing Land Tax: Management stated that the cessation of the levy is expected to reduce operating costs and favourably impact profitability and cash flows. Observed performance shows the company had already paid Rs. 171.78 crores for 2025-2026 and Rs. 79.07 crores for 2026-2027 (till date) towards this tax, indicating the scale of the cost that will no longer be incurred from 22nd August 2026.
- Pandalgudi mine restoration: Management guidance indicates the restoration work is ongoing and expected to be completed by 2027. Observed progress includes over 500 acres of worked-out mines covered (with a 234-acre site assessed and certified) and over 430,000 native trees and shrubs from 150 species planted since 2018.
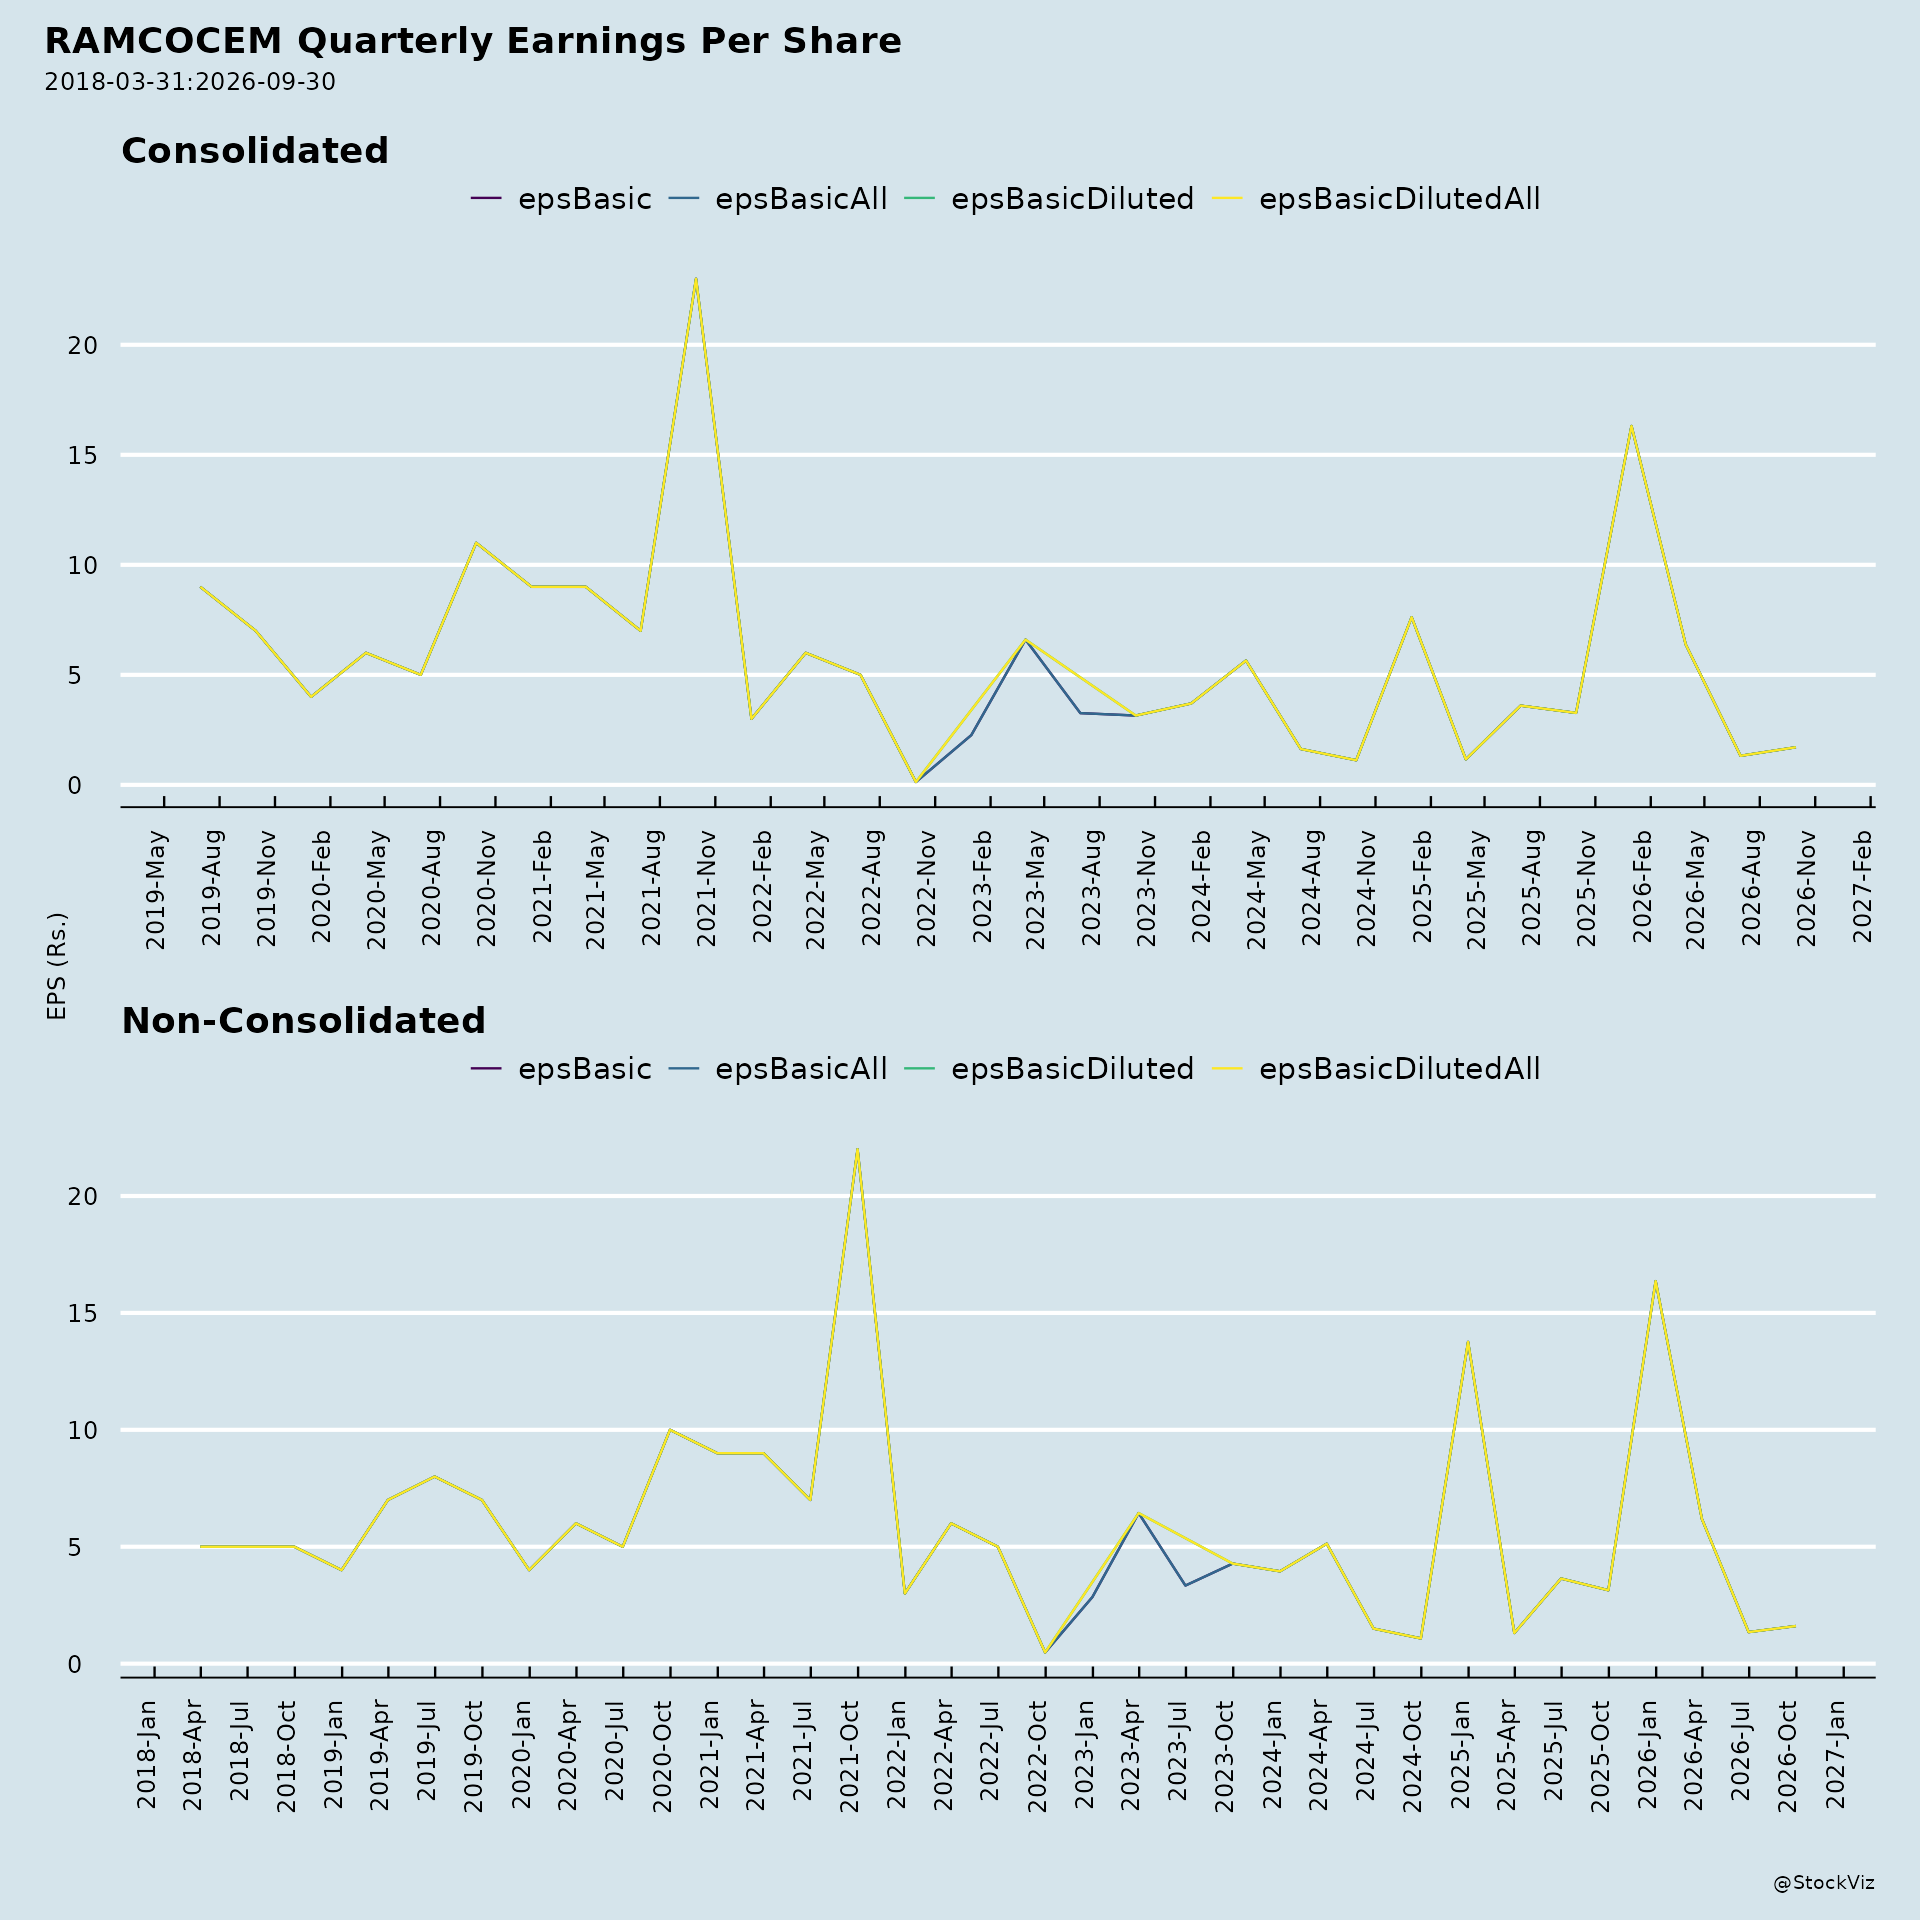
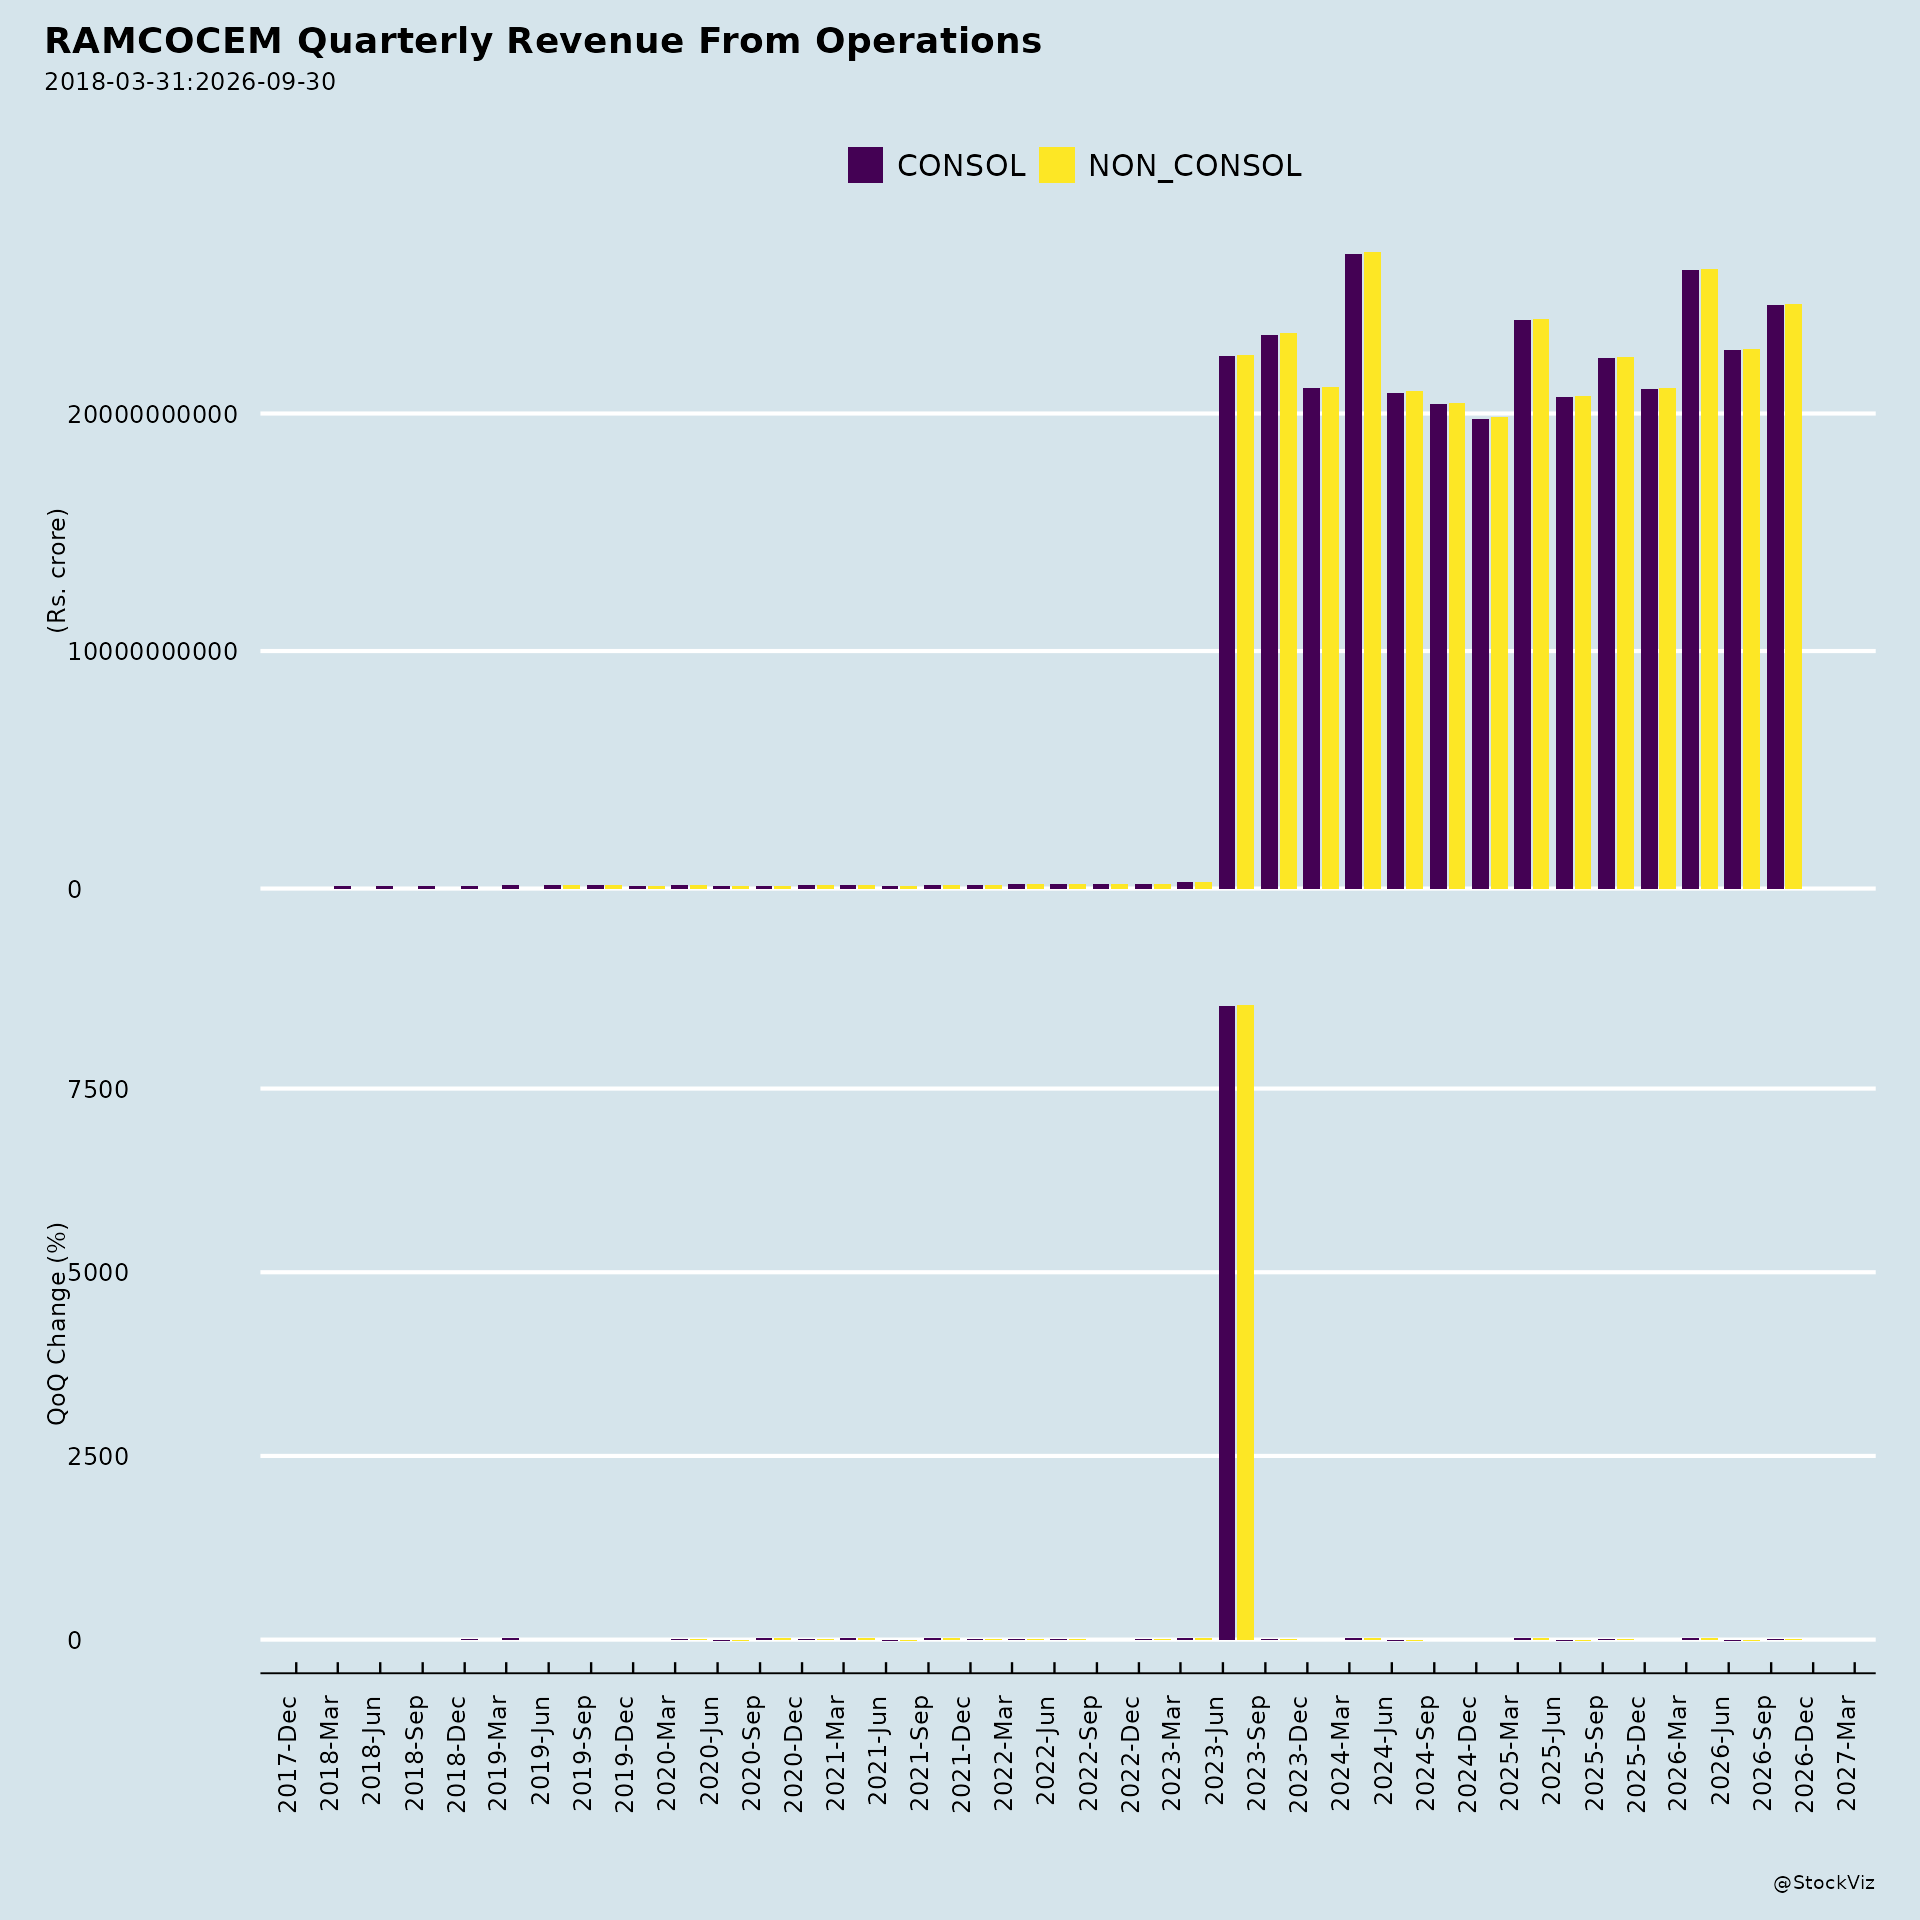
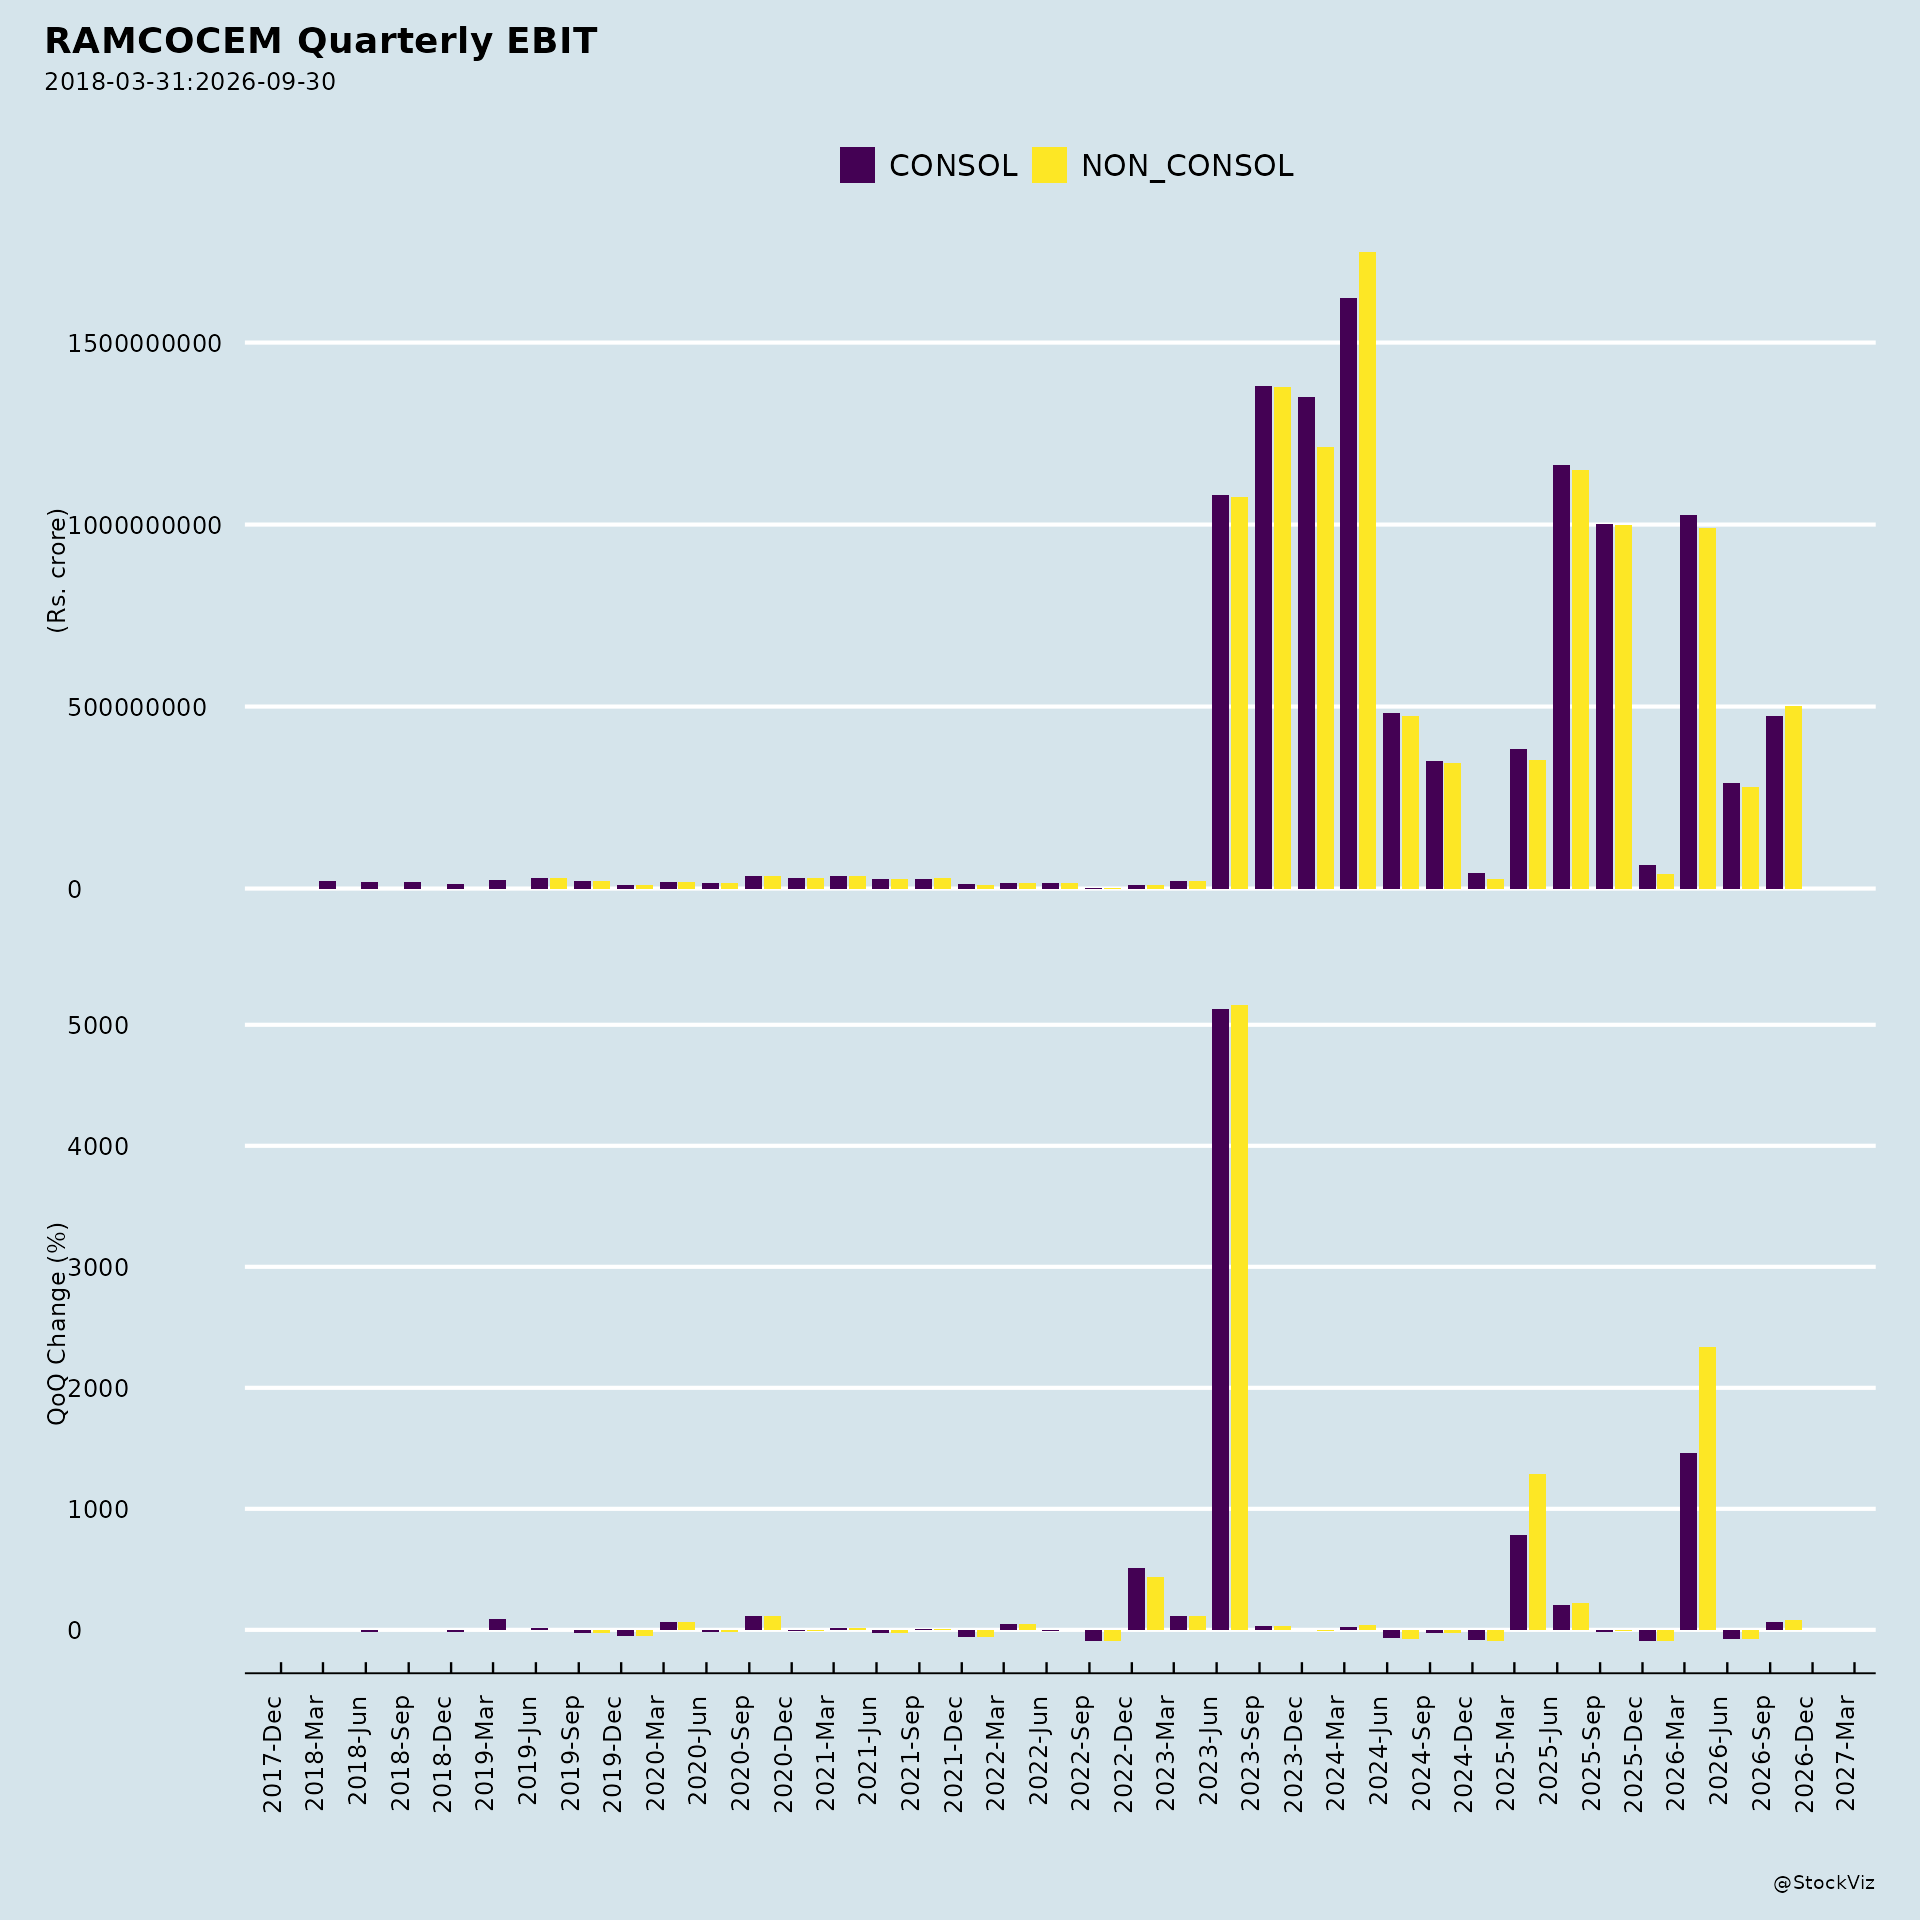
- Quarterly performance: For the quarter ended 30-06-2026, the company reported standalone total income of Rs. 2,276.18 Crores and net profit after tax of Rs. 31.86 Crores. Consolidated total income was Rs. 2,279.79 Crores with a net profit for the period of Rs. 31.24 Crores. The statutory auditors expressed an unmodified audit opinion.
- AGM outcomes: The 68th Annual General Meeting was held on August 20, 2026, via Video Conferencing. Actions included adoption of separate and consolidated audited financial statements for the year ended March 31, 2026, declaration of a dividend of Rs. 2.50 per share, reappointment of Shri P.R. Venketrama Raja as Director, and ratification of Rs. 7,50,000 remuneration for Cost Auditors M/s. Geeyes & Co. for the financial year 2026-27. All resolutions were passed with the requisite majority.
Broker Narrative
Both the first (Aug-2023) and last (Nov-2026) reports carry a Neutral call, but the narrative has shifted from cyclical optimism to structural margin worry: the early report paired volume/green-power enthusiasm with caveats on fuel costs, weak South/East pricing and rising interest expense, while the latest report concedes volumes and green energy (50% of power) did scale, yet shows profitability far worse than originally feared (EBITDA/t INR653, PAT down 53% YoY, net debt/EBITDA 3.1x). Themes that persisted across the three years are elevated power/fuel cost inflation, soft/flat East pricing, leverage and rich valuations; themes that changed are the addition of non-core asset monetization, construction chemicals and a 31mtpa capacity target as growth levers, plus a much more explicit focus on margin compression rather than EBITDA/t expansion.
Fears that came true
- Elevated Fuel & Input Costs: The early flag on high-cost fuel inventory never resolved, with blended fuel cost climbing to USD140/t (INR1.99/kcal) and opex/t up 6% YoY by 2QFY27, coinciding with repeated DISAPPOINTMENT outcomes through 2024-2025.
- Weak Realizations & Pricing: The flagged weakness in South/East cement prices persisted, with East trade prices still flat in the last report and a 2023 realization decline foreshadowing the muted +1% YoY realization reported later.
- Higher Debt & Interest Expenses: The concern over net debt (INR44.0b) and the 97% YoY interest surge carried through, with net debt at INR39.2b and net debt-to-EBITDA of 3.1x (TTM) in the final report.
- Lower-than-Estimated Performance / Earnings Revisions: The 1QFY24 PAT miss (41% below estimate) and EPS cuts proved the start of a persistent pattern, culminating in adj. PAT down ~53% YoY to INR347m and EBITDA/t down ~23% YoY.
- Margin Compression risk from flat East volume: Flat East volume flagged in 1QFY24 remained an issue, with East pricing still flat and OPM dipping 4.2pp YoY to ~13% by 2QFY27.
Optimism that failed
- Cost Reduction Trajectory: The expectation that fuel cost per kcal (INR2.03) would keep declining was reversed, with blended fuel consumption cost rising to INR1.99/kcal on USD140/t coal versus INR1.49/INR1.85 earlier periods.
- Opex Discipline: The early praise for Opex/t declining 1% YoY did not sustain, as Opex/t rose 6% YoY with variable cost/other/freight per ton up 10%/7%/2%.
- Upcoming Capacity Expansion as a growth driver: The Orissa GU Line-2 (0.9mt, 2HFY24) and Karnataka land acquisition did not deliver the anticipated earnings uplift, with the growth story instead re-based to Kolimigundla Line-2 and a 3.15mtpa clinker unit only by Dec’26.
- Premium product share as a margin cushion: The 27% premium share cited as a support in 1QFY24 did not prevent blended EBITDA/t from collapsing to INR653, even as premium share reached ~32% in the South.
Broker Timeline
56 broker calls · 2023-08-07 to 2026-11-05
CNBC-TV18: ratings, targets and commentary
No recorded CNBC-TV18 statements for this ticker.
Management comments
No recorded management comments with an explicit designation and affiliation for this ticker.
Copyright © 2023 SAS Data Analytics Pvt. Ltd. All rights reserved.