QPOWER
Equity Metrics
November 18, 2026
Quality Power Electrical Equipments Limited
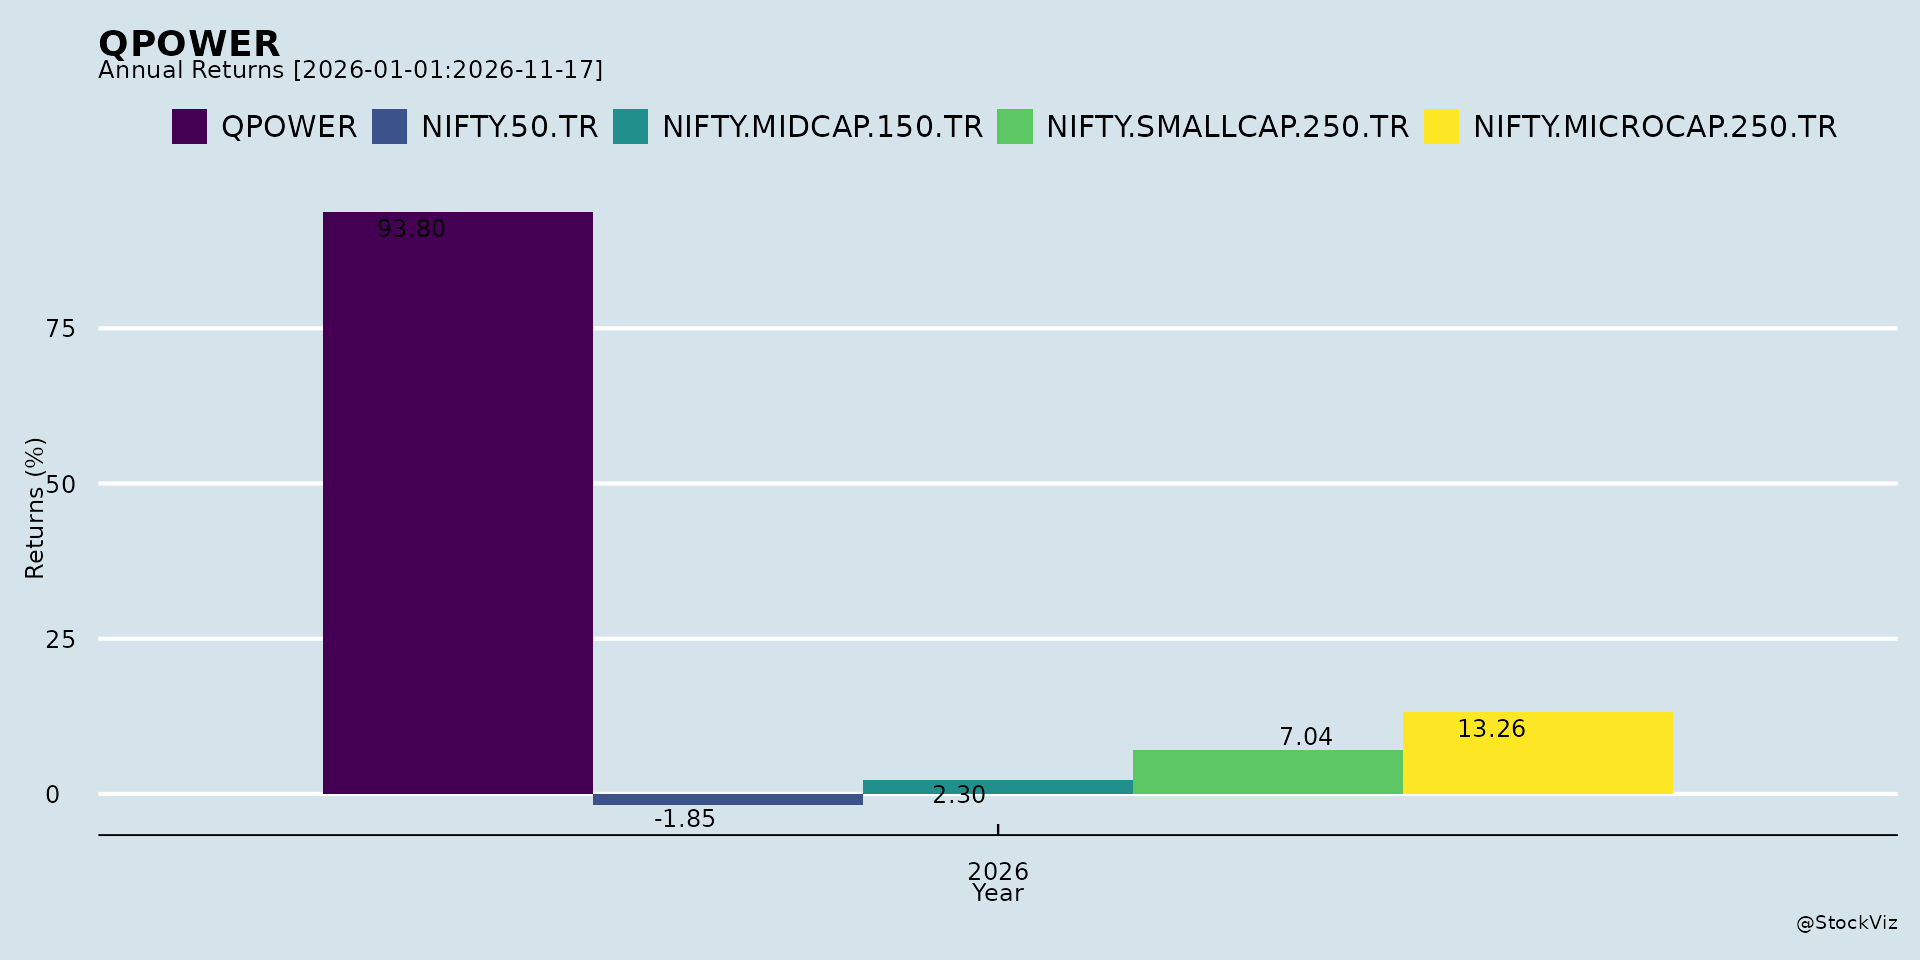
Annual Returns

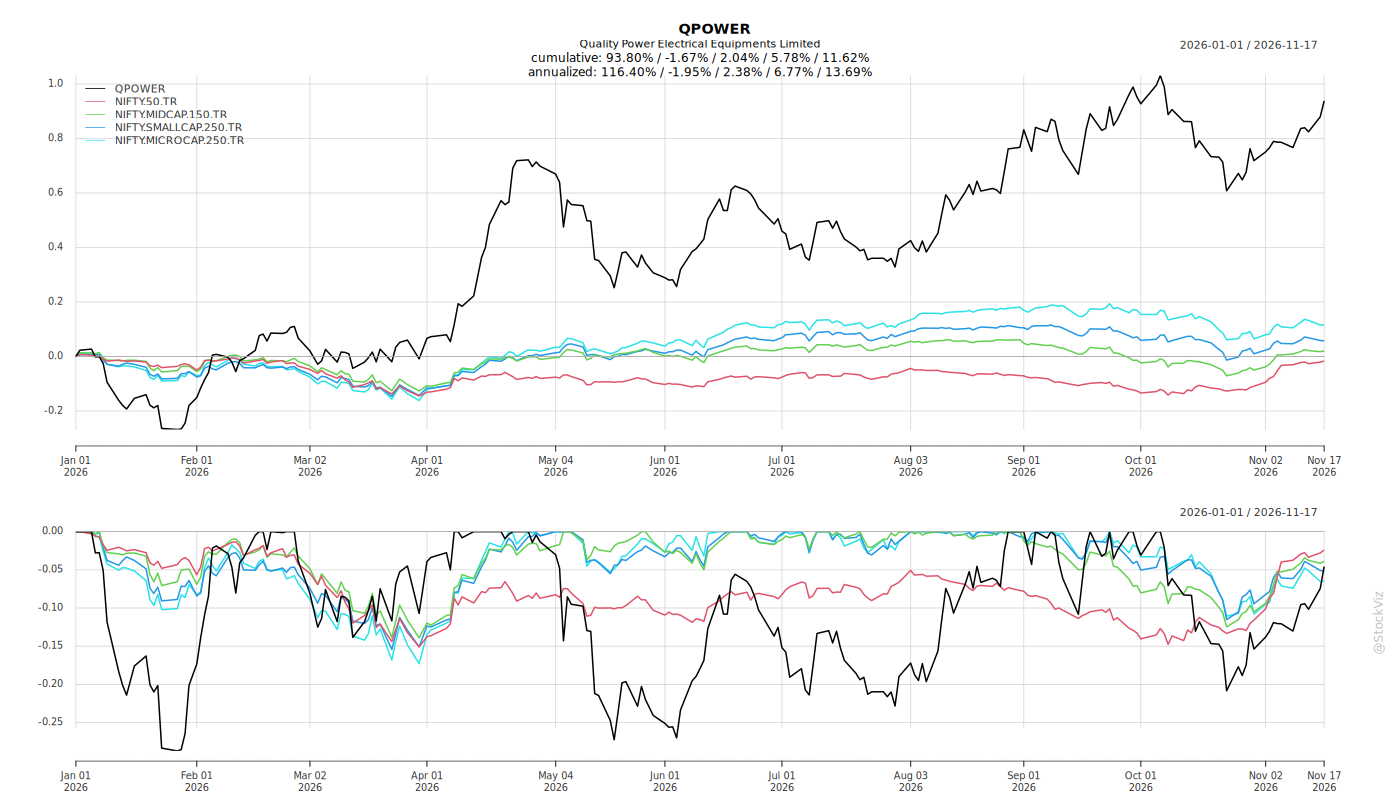
Cumulative Returns and Drawdowns
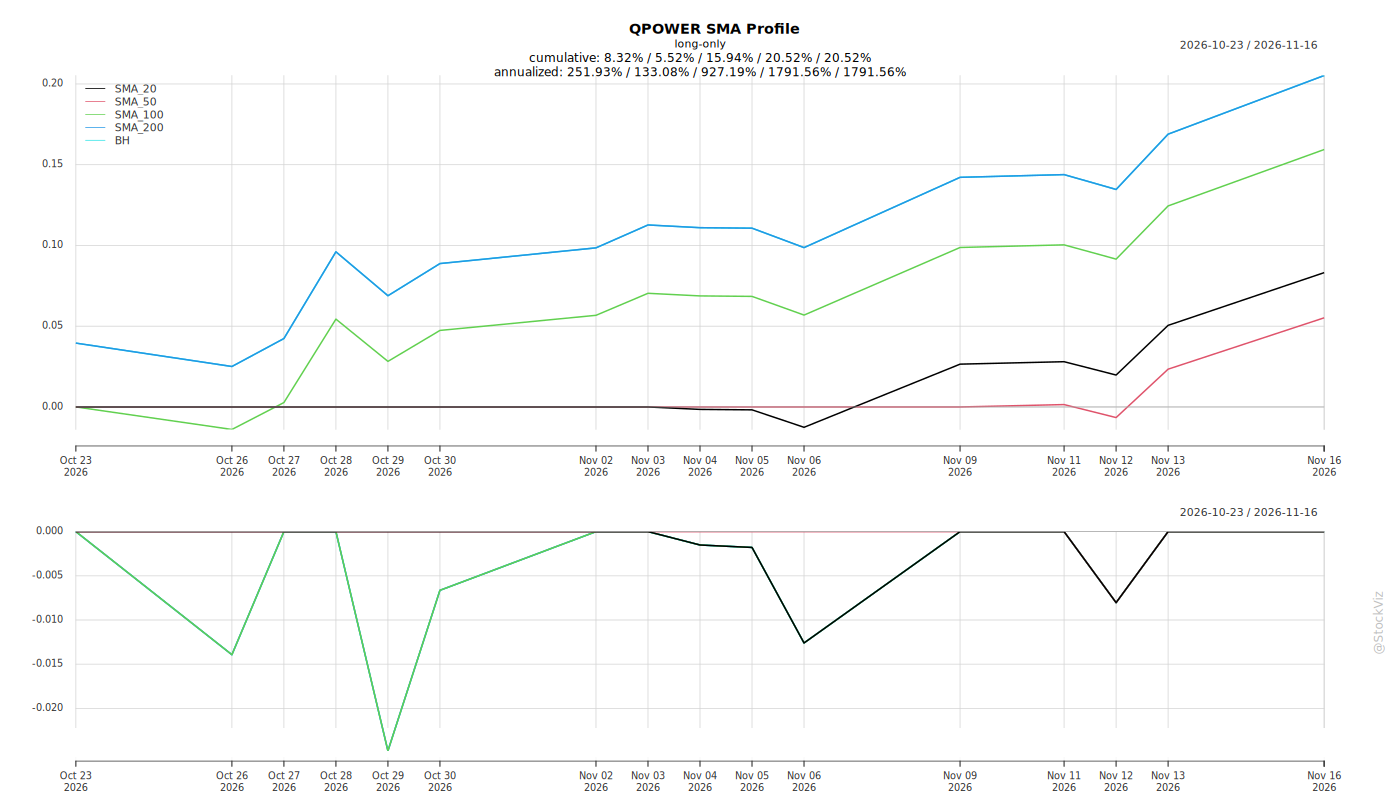
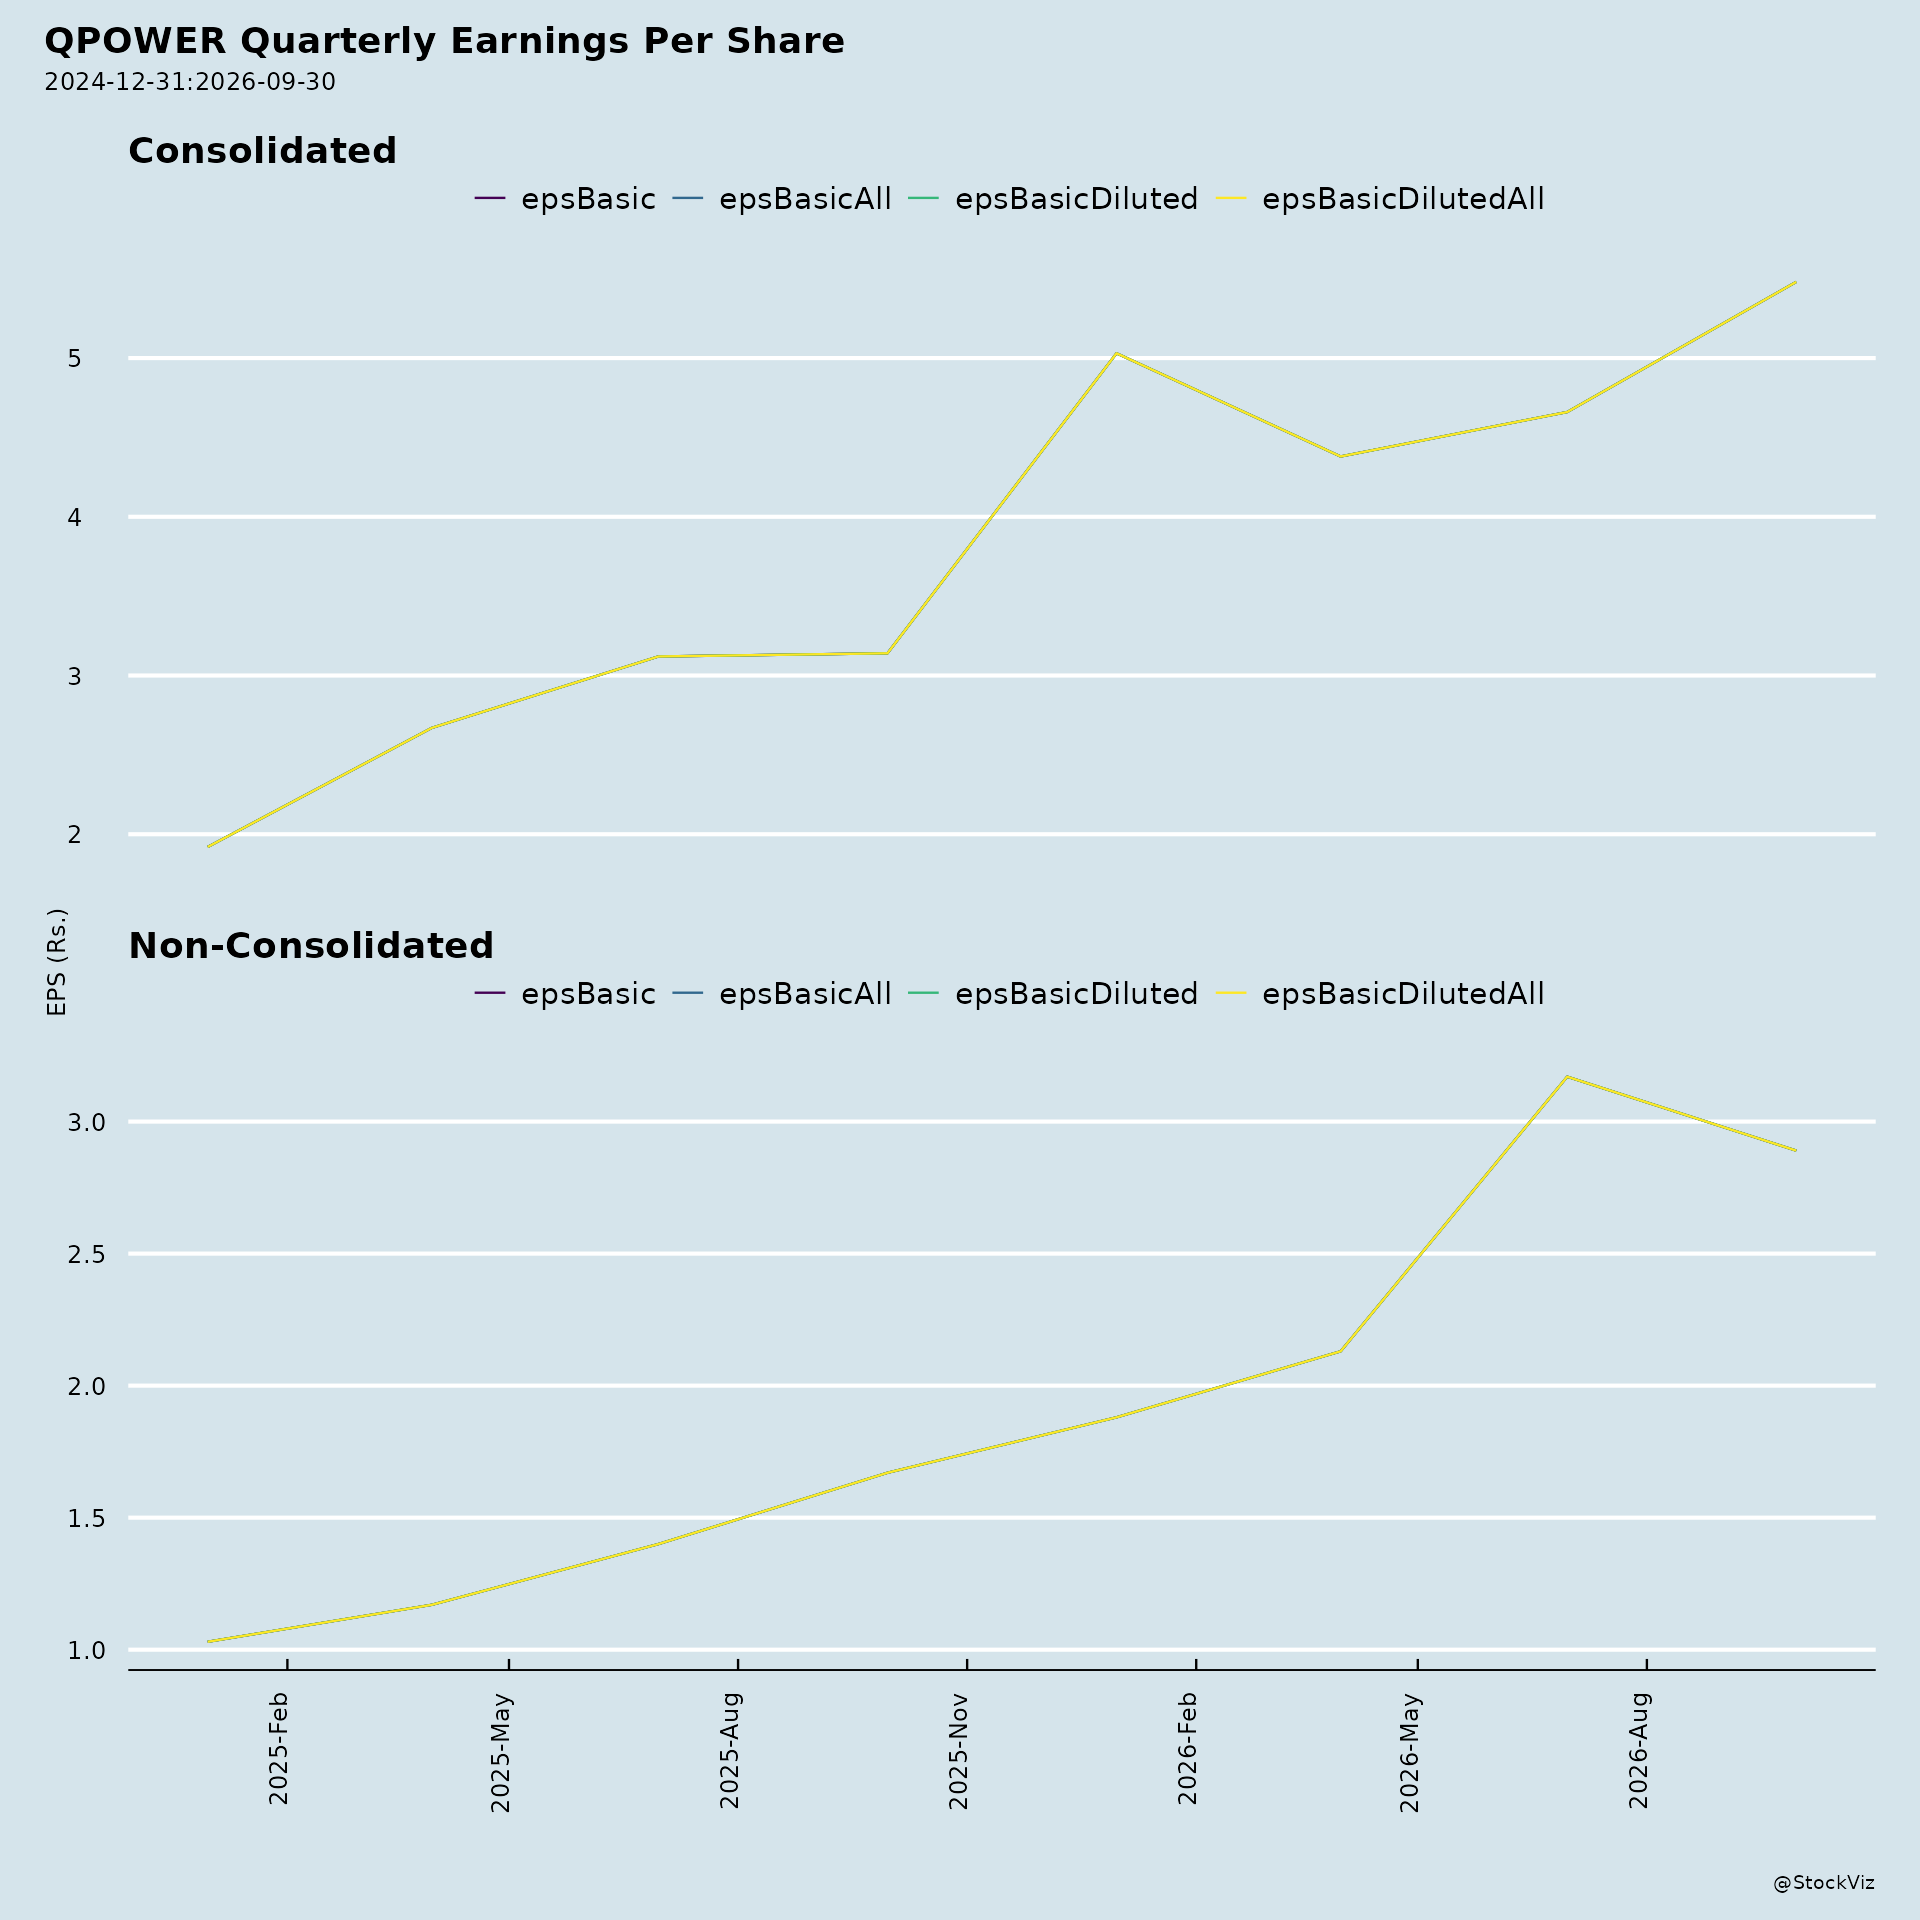
Fundamentals
Ownership
Margined
AI Summary
asof: 2026-09-17
QPOWER — Recent Corporate Announcements: Summary
1. Headwinds and Challenges
Raw material constraints and input pricing. Management states that raw material constraints — particularly electrical grade steel, copper and specialised insulation systems — continue to present a meaningful challenge, with input pricing remaining variable owing to geopolitical conditions across key sourcing corridors. Mitigation cited includes long-term supplier agreements, dual sourcing, vertical integration through the new Sangli facility, and contractual pass-through arrangements where commercially feasible.
Execution as the gating factor. The outlook section states that while the structural demand environment is robust, execution remains the gating factor.
Hyperinflationary accounting drag (Ind AS 29). Turkey is classified as a hyperinflationary economy, so the financial statements of Endoks Enerji are restated. This produced a non-cash net monetary loss of ₹78.21 million in Q1 FY2027, recognised within Other Expenses. It reduces reported EBITDA, PBT and PAT, is not deductible for tax (no tax credit), and management notes it is not comparable period-to-period. Reported PAT of ₹467 Mn versus adjusted PAT of ₹545 Mn reflects this charge; on a reported basis PAT declined 7.7% QoQ.
Seasonality. Total income was 17.2% lower QoQ, which the presentation attributes to seasonality.
Margin profile below prior full-year levels. FY2026 gross margin (43.3%) and EBITDA margin (23.5%) were below FY2025 (48.9% and 30.5% respectively), and FY2026 PAT margin (18.4%) was below FY2025 (25.6%).
Cash conversion trend. Cash flow from operations to EBITDA declined across FY23–FY26 (0.8x, 0.8x, 0.5x, 0.3x), even as operating cash flow rose in absolute terms.
Acquisition completion risk. The WSIL transaction has reached term sheet stage only; completion remains subject to confirmatory due diligence, definitive documentation, regulatory and shareholder approvals and other customary closing conditions, with no assurance it will complete on the terms described or at all. Valuation figures are indicative. Separately, the Board deferred consideration of the proposed preferential issue to WSIL shareholders, which will be taken up at a subsequent Board meeting.
2. Tailwinds and Growth Prospects
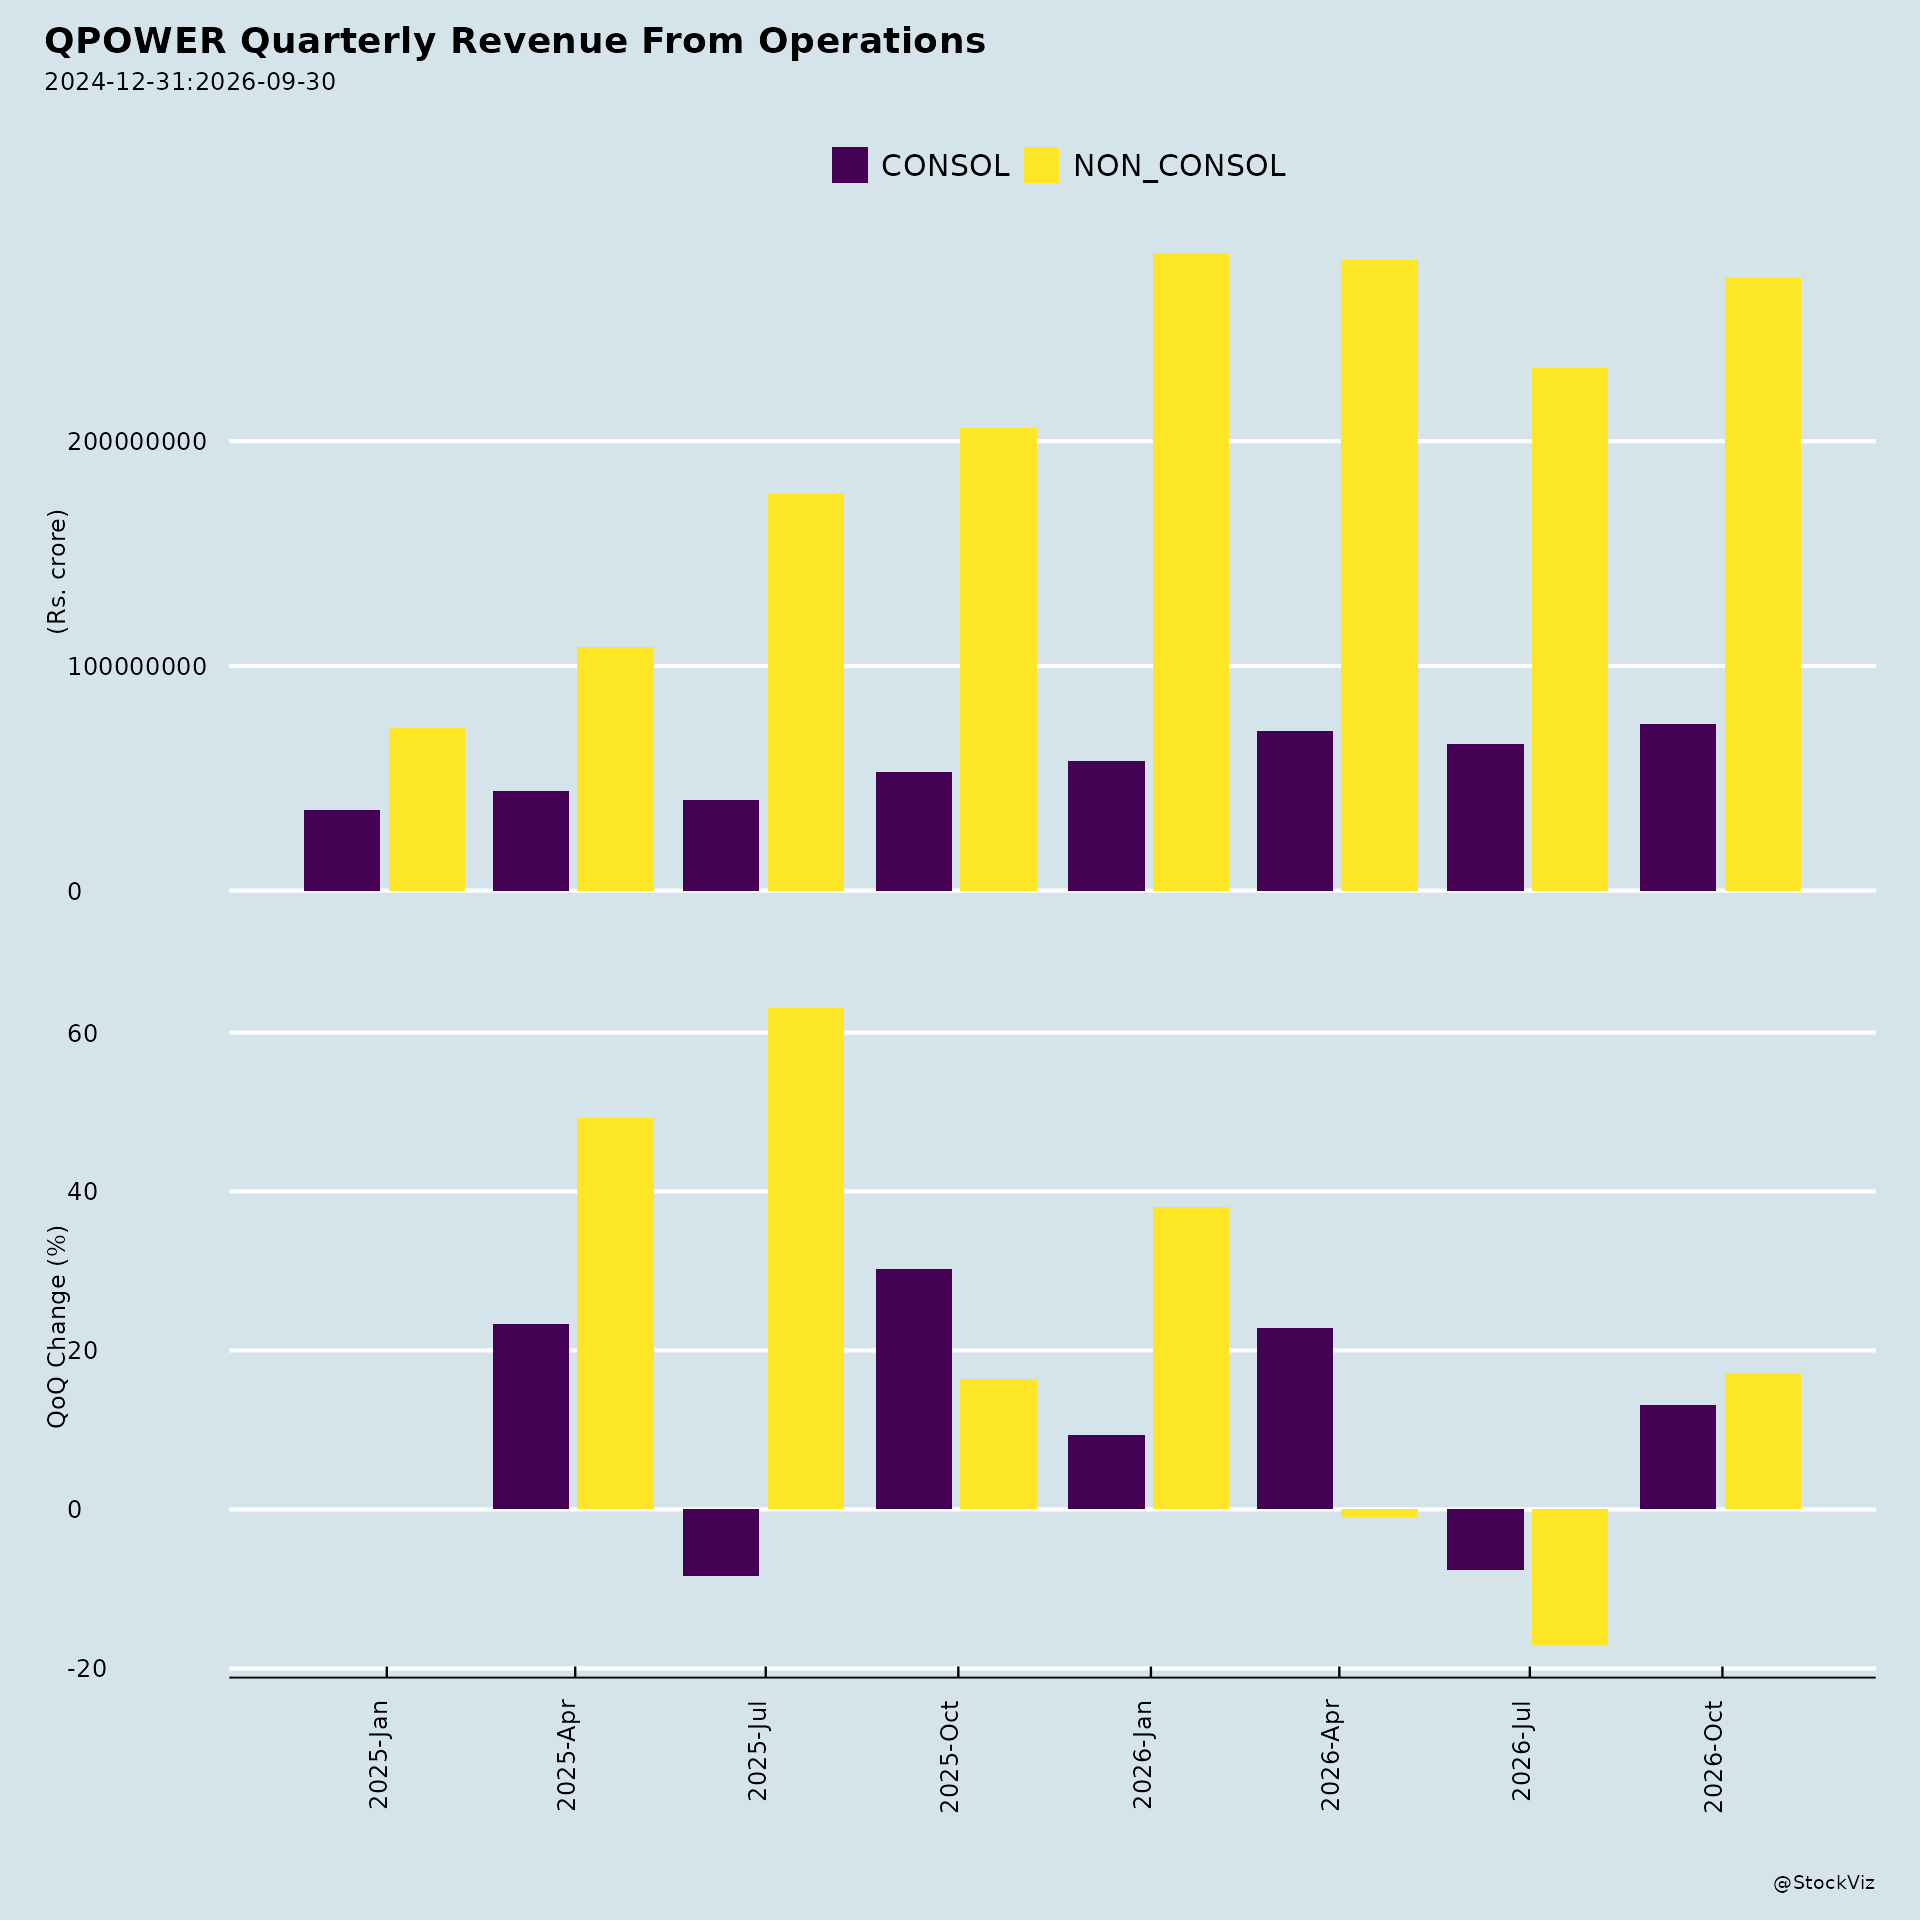
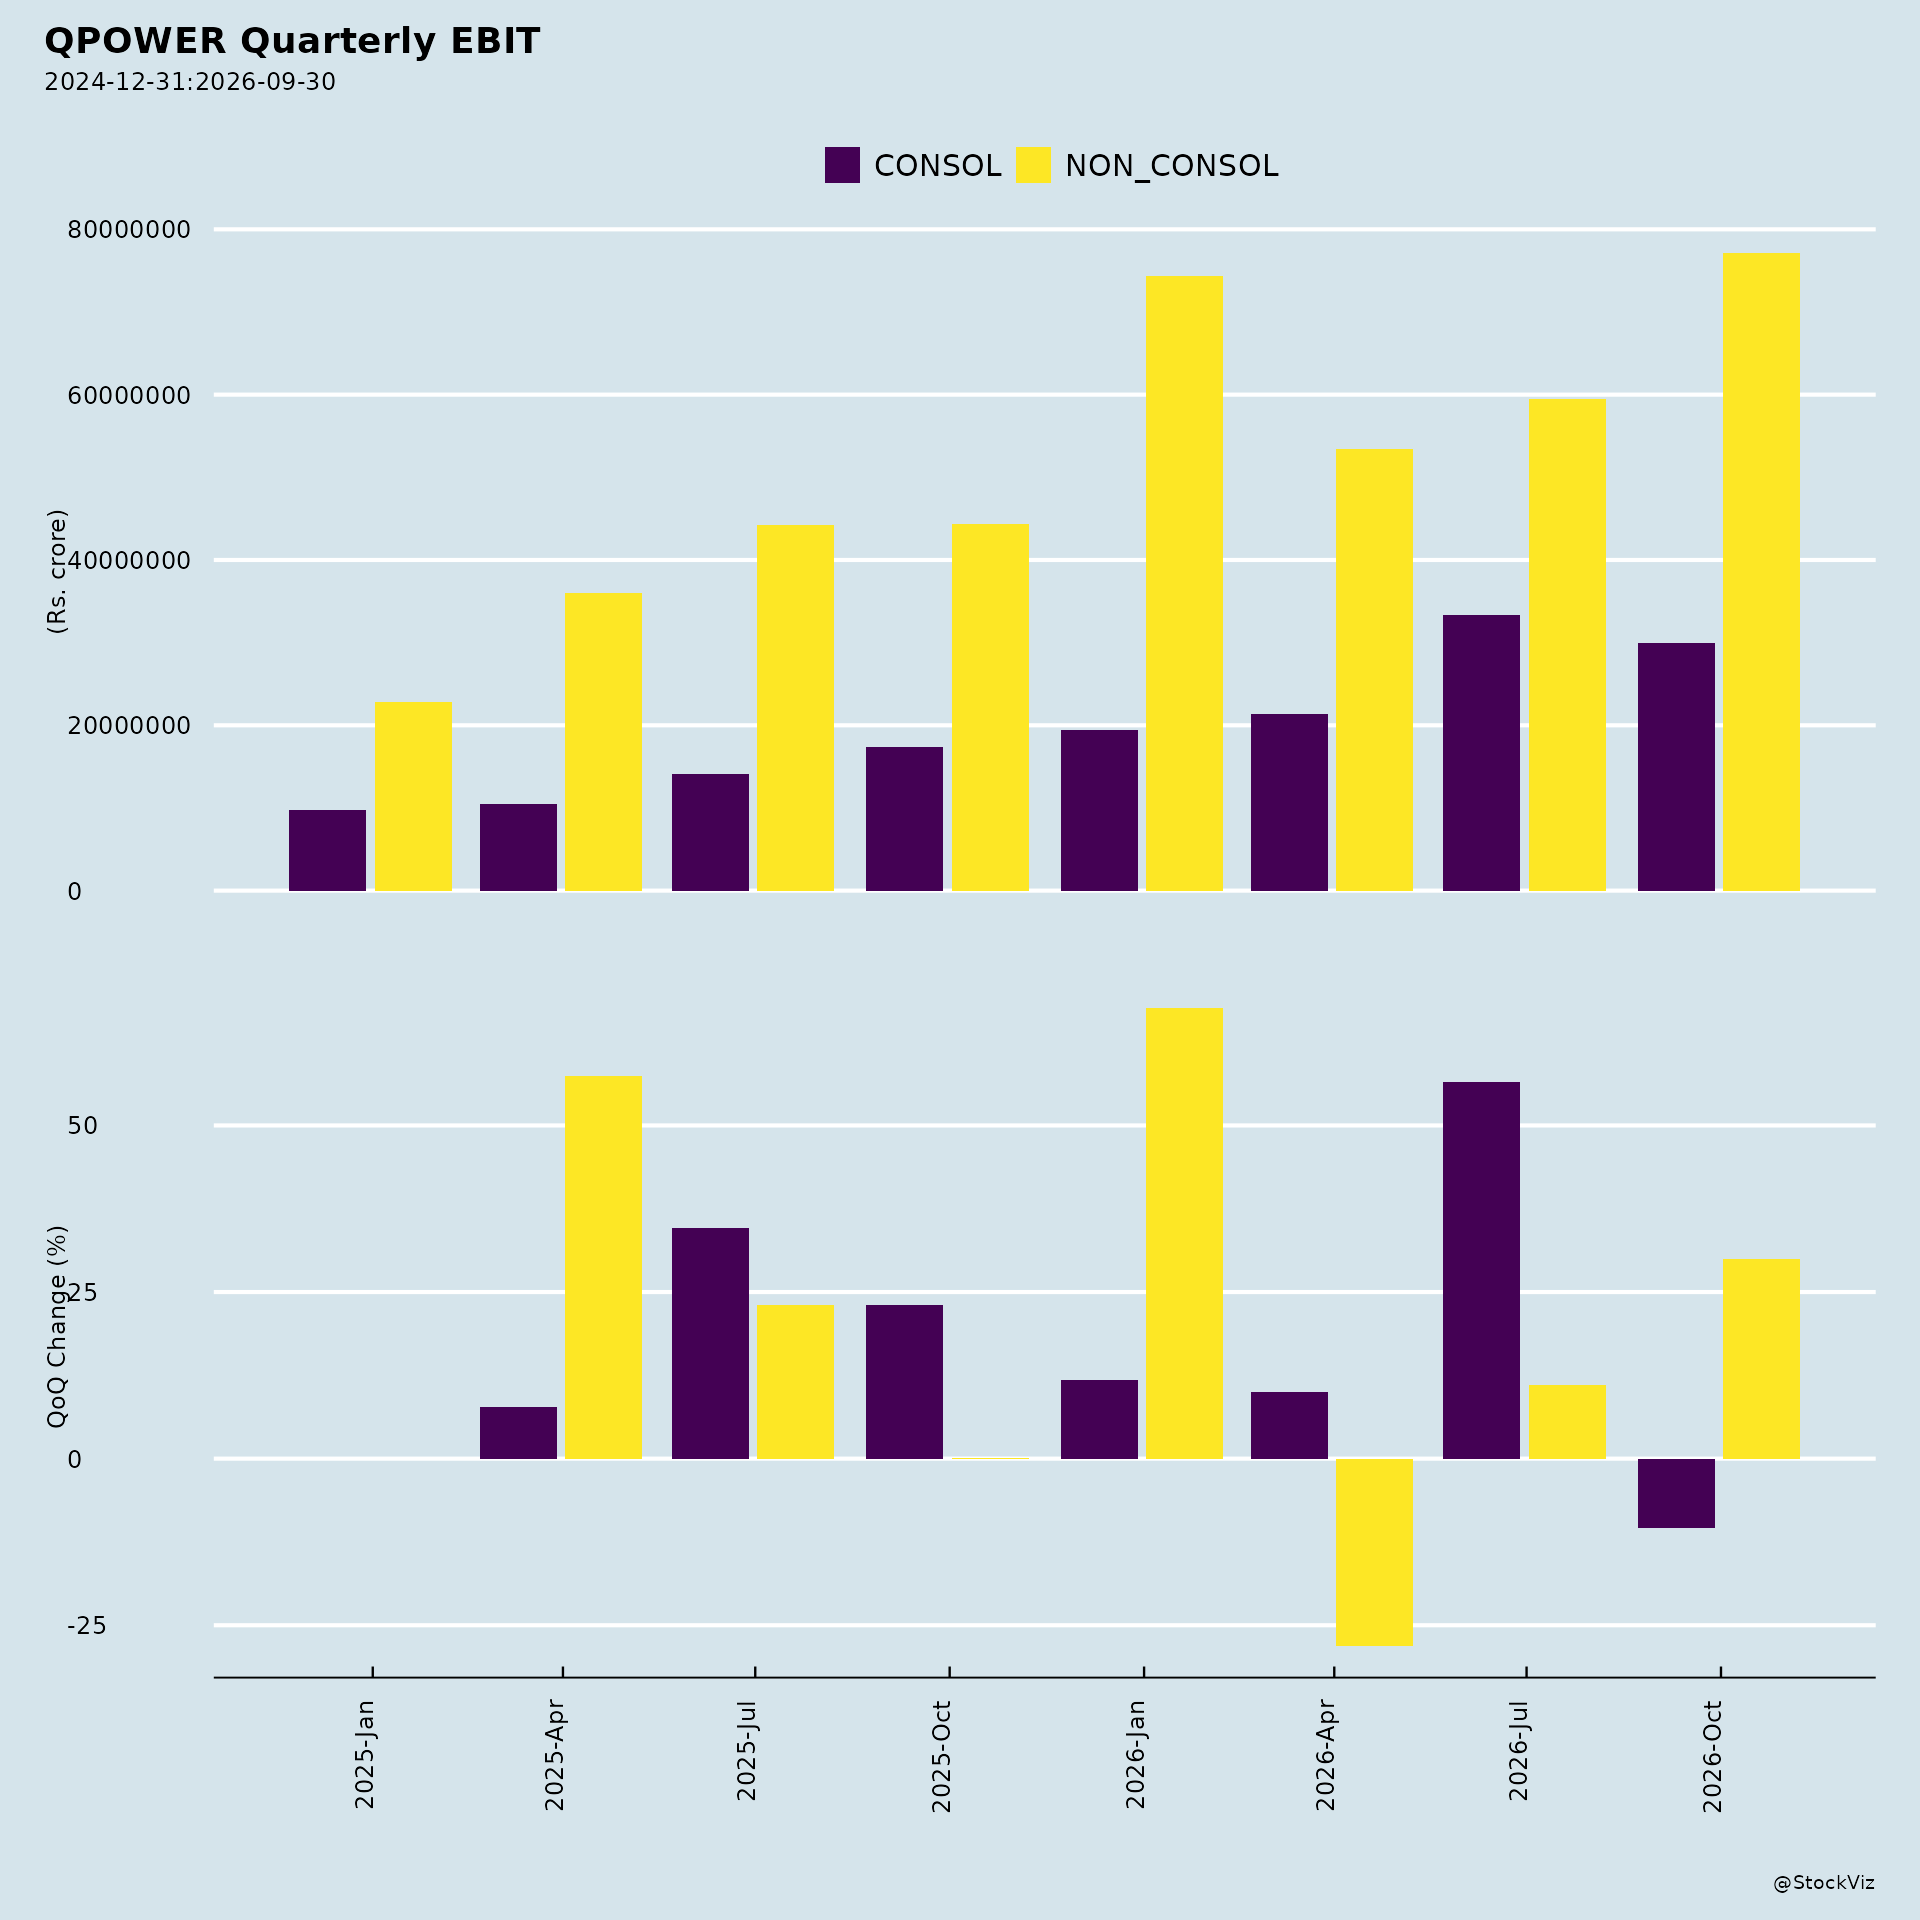
Q1 FY2027 performance. Total income of ₹2,564 Mn, up 32.1% YoY. Gross margin improved to 47.2% from 44.6% YoY as product mix shifted toward high voltage and power quality systems. Adjusted EBITDA of ₹725 Mn (28.3% margin) versus 24.9% in Q1 FY26 and 19.1% in Q4 FY26; adjusted PAT of ₹545 Mn, up 46.9% YoY and 7.7% QoQ.
Order book. ₹19,455 Mn as of 30 June 2026 (≈1.9x FY2026 consolidated revenue), split Endoks ₹8,010 Mn, Mehru ₹5,850 Mn, QP Equipments ₹5,530 Mn, Others ₹65 Mn, providing visibility into FY2028. Disclosed orders in the quarter totalled ₹104.9 crore: ₹48.3 crore of high voltage reactors for a US data centre project (execution ~12 months); ₹40.9 crore FACTS system and equipment order in Japan (execution by December 2027); ₹15.70 crore of 400 kV instrument transformer orders from Hitachi Energy India Limited (execution ~12 months).
Demand environment. Management cites multi-year-high tender activity across North America, Europe, the Middle East, Asia and India; breakthrough positions in HVDC (both LCC and VSC); qualifications and conversions on grid-scale BESS tenders in Europe; new FACTS wins across the Americas, Europe, the Middle East and Asia Pacific; and a first wave of orders for high voltage interconnect equipment serving hyperscale and AI data centre campuses in the United States.
Proposed WSIL acquisition. Term sheet executed June 2026 for 100% of Winwin Speciality Insulators Limited at an enterprise value of ~₹285 crore (total transaction value ~₹315 crore including ₹30 crore debt retained), structured as ₹142.5 crore equity swap via preferential issue and ₹142.5 crore cash. WSIL brings ceramic insulator capability to 1200 kV, polymeric insulators to 400 kV, ~18,000 MTPA installed capacity, a 47.7-acre Atchutapuram SEZ facility with access to Visakhapatnam and Gangavaram ports, exports to ~55 countries, and the 1961-origin WS Insulators brand. The presentation describes the proposed enterprise value as sitting below an indicative business value of ₹390 crore for the underlying land, buildings, plant and brand.
GIS participation. Grading capacitors for circuit breaker protection (Quality Power) and a co-development agreement between Mehru and Hyosung T&D India for gas insulated instrument transformers, designed, manufactured, tested and certified in India to IEC and IEEE standards.
BESS opportunity. Endoks’ two decades of converter experience (STATCOMs, SVCs, active harmonic filters) is positioned as a proven platform for battery power conversion systems, which share voltage source converter technology. Cited India context: 236 GWh storage requirement projected by CEA by 2031-32, ~102 GWh of BESS tenders issued in 2025, and ₹5,400 crore second tranche of viability gap funding approved in May 2026 for 30 GWh of standalone projects.
Capacity expansion. Sangli Global Coil Factory: machinery installation commenced, trial production expected August 2026 subject to regulatory clearances. HVDC CTC magnet wire facility: machinery installation scheduled from August 2026. Turkey: civil construction of new Endoks and Mehru facilities complete, interior fit-out underway; establishes advanced instrument transformer capability in Europe, with power conversion system operations expected to commence in Q3 FY2027.
Sukrut (50:50 JV). Backward integration into transformer tanks, fabrications, accessories and GIS components, against a global transformer capacity constraint with lead times of three to four years for large power transformers in several markets.
Balance sheet. Debt to equity below 0.21x throughout FY23–FY26 (0.05x in FY2026); ROCE 39.8% and ROE 26.6% in FY2026; operating cash flow increased in each of the last four years.
Shareholder returns. Interim dividend of ₹0.25 per equity share declared for FY2027; the AGM notice includes a dividend of ₹1/- per equity share for Non-Promoter shareholders.
3. Key Risks
- Raw material availability and pricing, including electrical grade steel, copper and specialised insulation systems, with variability linked to geopolitical conditions in sourcing corridors.
- Execution risk on order book conversion and capacity expansion timelines; management identifies execution as the gating factor.
- Acquisition risk on WSIL: due diligence, definitive documentation, regulatory and shareholder approvals, and closing conditions remain outstanding; valuation figures are indicative.
- Deferred preferential issue: the equity-swap component of the WSIL consideration was deferred by the Board and is subject to a subsequent Board meeting and approval.
- Macroeconomic and geopolitical conditions, customer capital expenditure cycles and project execution timelines, as flagged in the forward-looking statements.
- Ind AS 29 volatility: further net monetary losses may arise from Turkey’s hyperinflationary status, affecting reported (though not adjusted or cash) results.
- Regulatory clearances for trial production at Sangli.
- Competition, talent retention, contract overruns, government policies, fiscal deficits and regulations, as enumerated in the presentation’s risk factors.
4. Management Guidance Versus Observed Performance
Guidance and forward-looking statements provided:
- Order book of ₹19,455 Mn provides execution visibility into FY2028.
- Sangli Global Coil Factory expected to be commissioned for trial production during August 2026, subject to mandatory regulatory clearances.
- HVDC CTC magnet wire facility: machinery installation scheduled to commence in August 2026.
- Turkey expansion: power conversion system operations expected to commence in Q3 FY2027.
- US data centre reactor order execution expected over approximately twelve months; Japan FACTS order execution expected by December 2027; Mehru 400 kV instrument transformer orders execution over approximately twelve months.
- The deferred preferential issue proposal shall be taken up at a subsequent meeting of the Board, with disclosures made as and when approved.
- Management states it remains positive on the structural demand environment for grid modernisation, renewable integration, high voltage transmission and emerging power-intensive applications, while remaining focused on execution, capacity creation and supply chain management.
- The 25th AGM is scheduled for Tuesday, September 29, 2026 at 04:00 P.M. via video conferencing or other audio-visual means; the cut-off date for unregistered email addresses is August 28, 2026.
- A plant visit for investors and analysts is scheduled for Friday, 11th September 2026 at 10.30 A.M. at the WSIL plant.
Observed performance against prior stated positioning:
- Q1 FY2027 delivered 32.1% YoY revenue growth with adjusted EBITDA margin of 28.3% and adjusted PAT margin of 21.3%, both ahead of Q1 FY2026 (24.9% and 19.1%), which management attributes to richer product mix, higher gross margin and operating leverage.
- The quarter’s disclosed order wins (₹104.9 crore) were announced with value and execution period, consistent with the stated disclosure practice of announcing order wins with value and execution period, and the WSIL term sheet was disclosed at signing rather than at completion.
- FY2026 full-year margins (gross 43.3%, EBITDA 23.5%, PAT 18.4%) were below FY2025 levels (48.9%, 30.5%, 25.6%), while Q1 FY2027 margins recovered above the FY2026 full-year level.
- Cash flow from operations to EBITDA has declined from 0.8x in FY23 to 0.3x in FY26 even as absolute operating cash flow rose from ₹443 Mn to ₹803 Mn.
- The Board deferred the preferential issue to WSIL shareholders that formed part of the announced consideration structure, leaving the equity-swap component subject to a future Board decision.
Broker Timeline
1 broker calls · 2025-09-29 to 2025-09-29
CNBC-TV18: ratings, targets and commentary
No recorded CNBC-TV18 statements for this ticker.
Management comments
No recorded management comments with an explicit designation and affiliation for this ticker.
Copyright © 2023 SAS Data Analytics Pvt. Ltd. All rights reserved.