PRESTIGE
Equity Metrics
November 18, 2026
Prestige Estates Projects Limited
Residential Commercial Projects
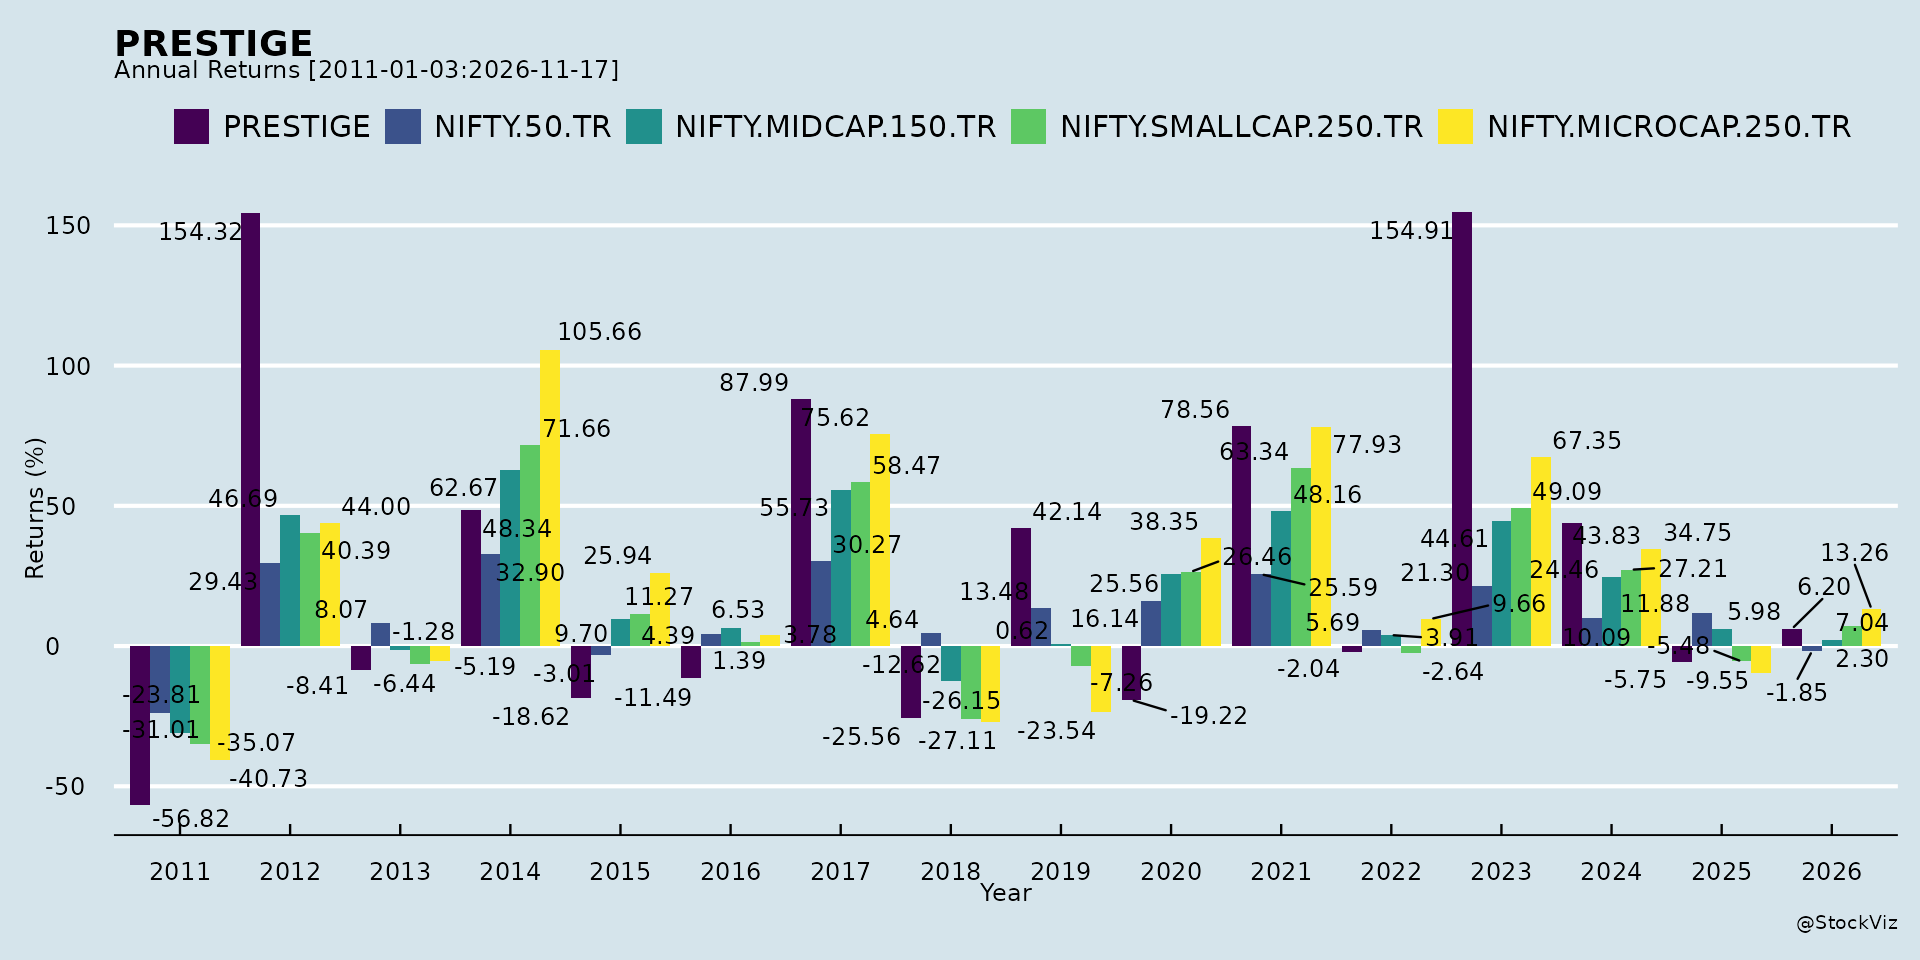
Annual Returns
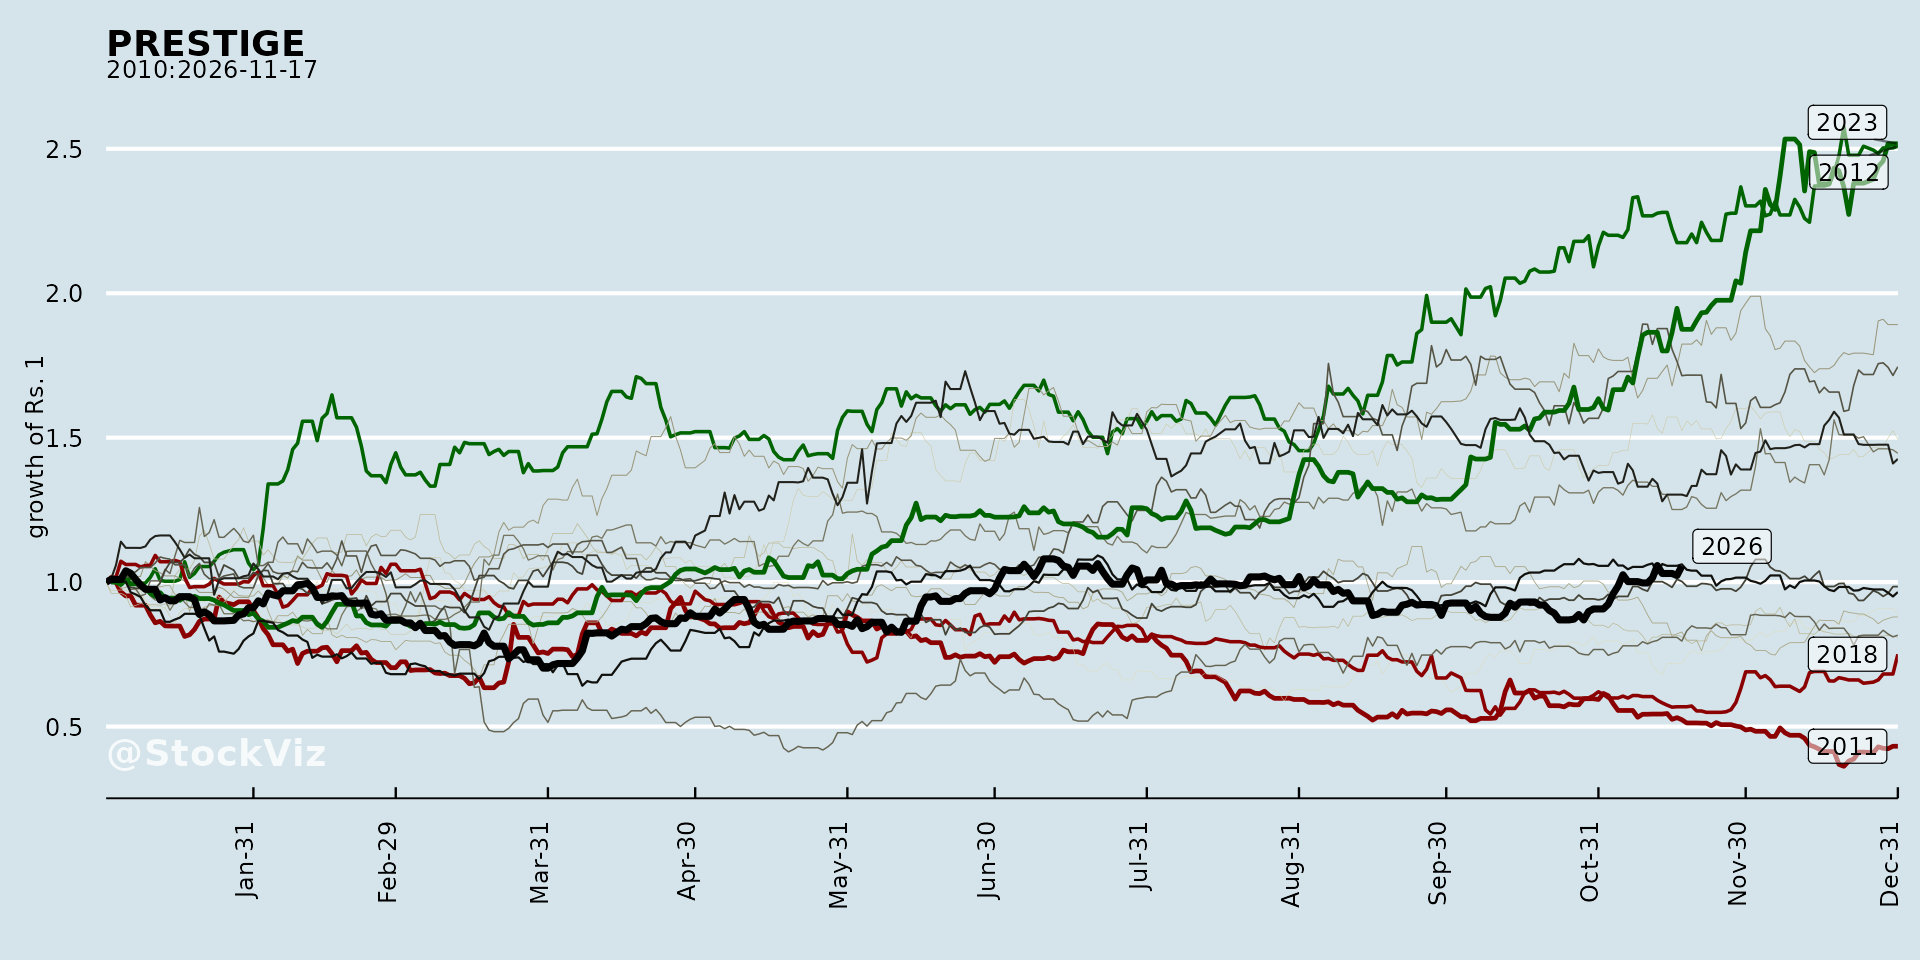
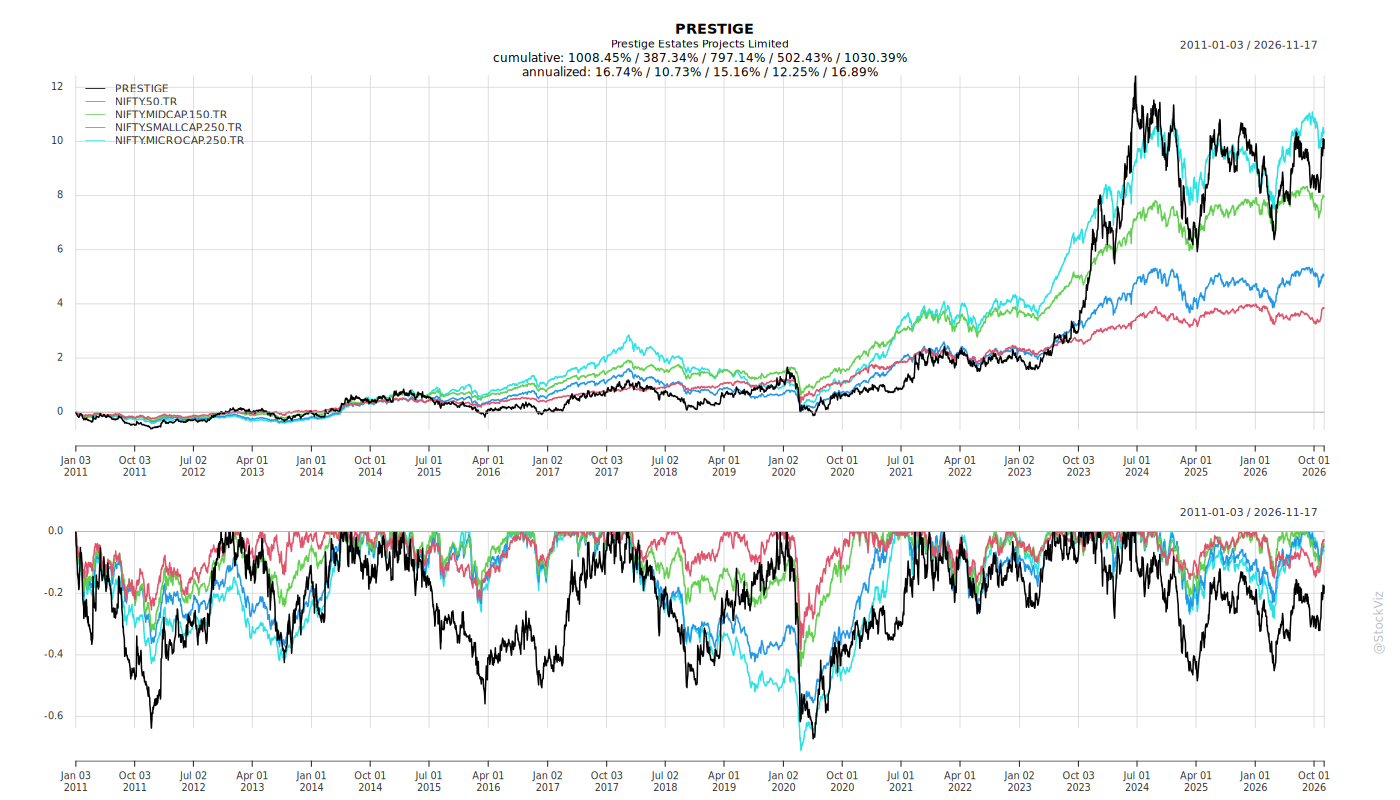
Cumulative Returns and Drawdowns
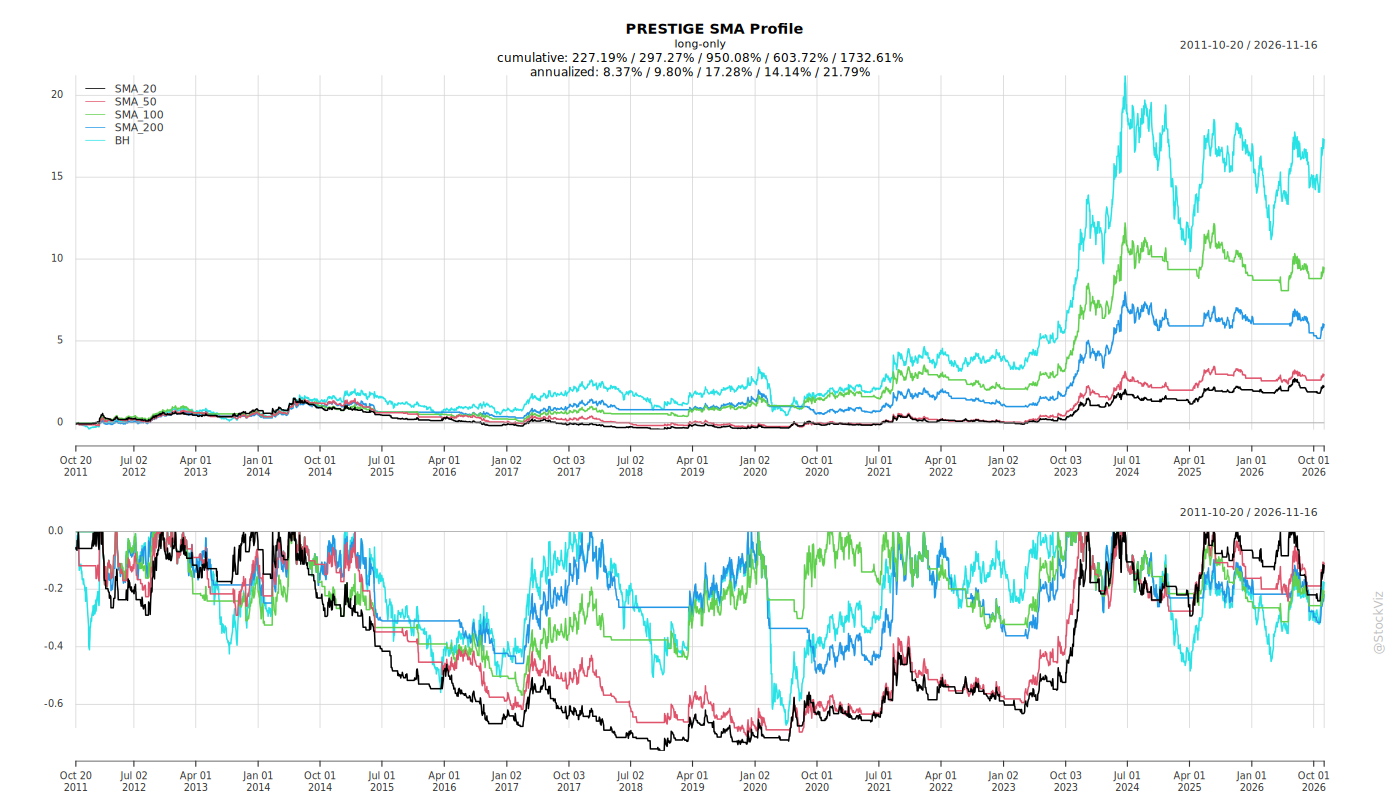
Fundamentals
Ownership
Margined
AI Summary
asof: 2026-09-16
Headwinds and Challenges
- Legal proceedings: A real estate project involving a land owner company has been ordered to be wound up by the Hon’ble High Court of Karnataka, and income tax search matters under section 132 of the Income Tax Act are ongoing.
- Geographic concentration in quarterly sales: Hyderabad accounted for 49% of Q1 FY27 residential sales, with Bengaluru at 27%, Mumbai 12%, NCR 7% and other markets 5%. Average realizations for the quarter primarily reflect this geographical mix, with Hyderabad accounting for nearly half of sales following the Prestige Golden Grove launch.
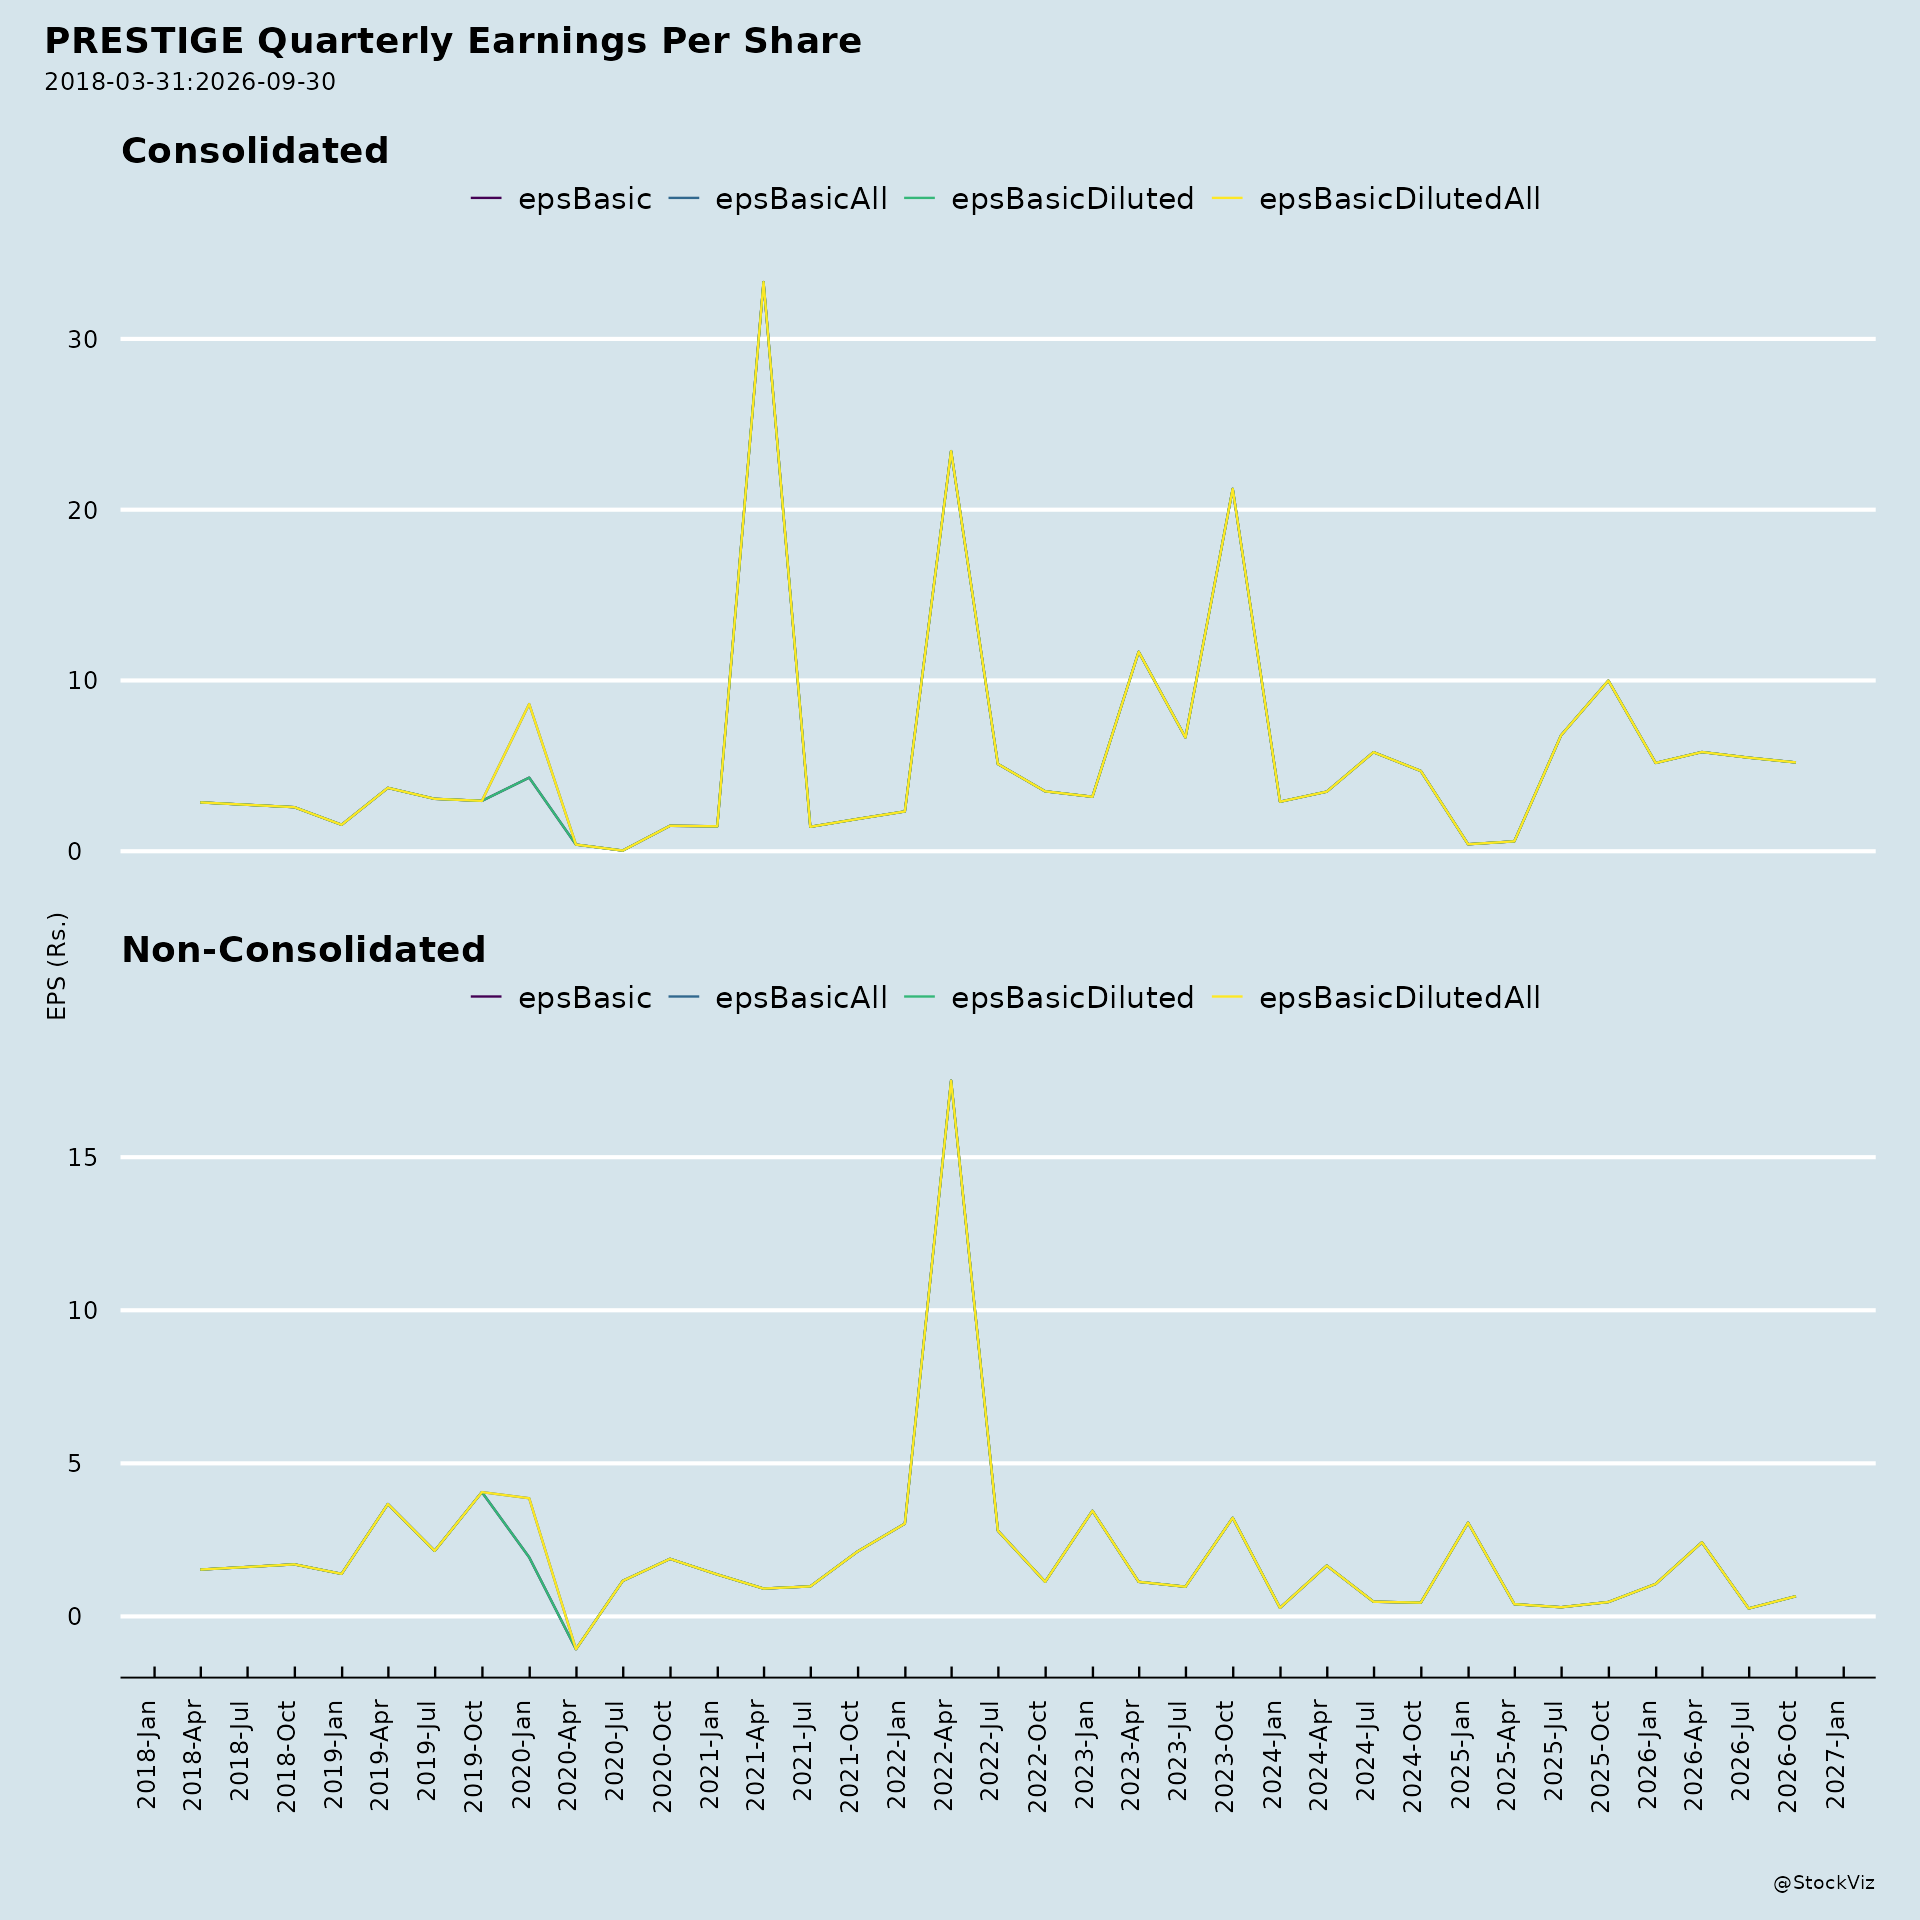
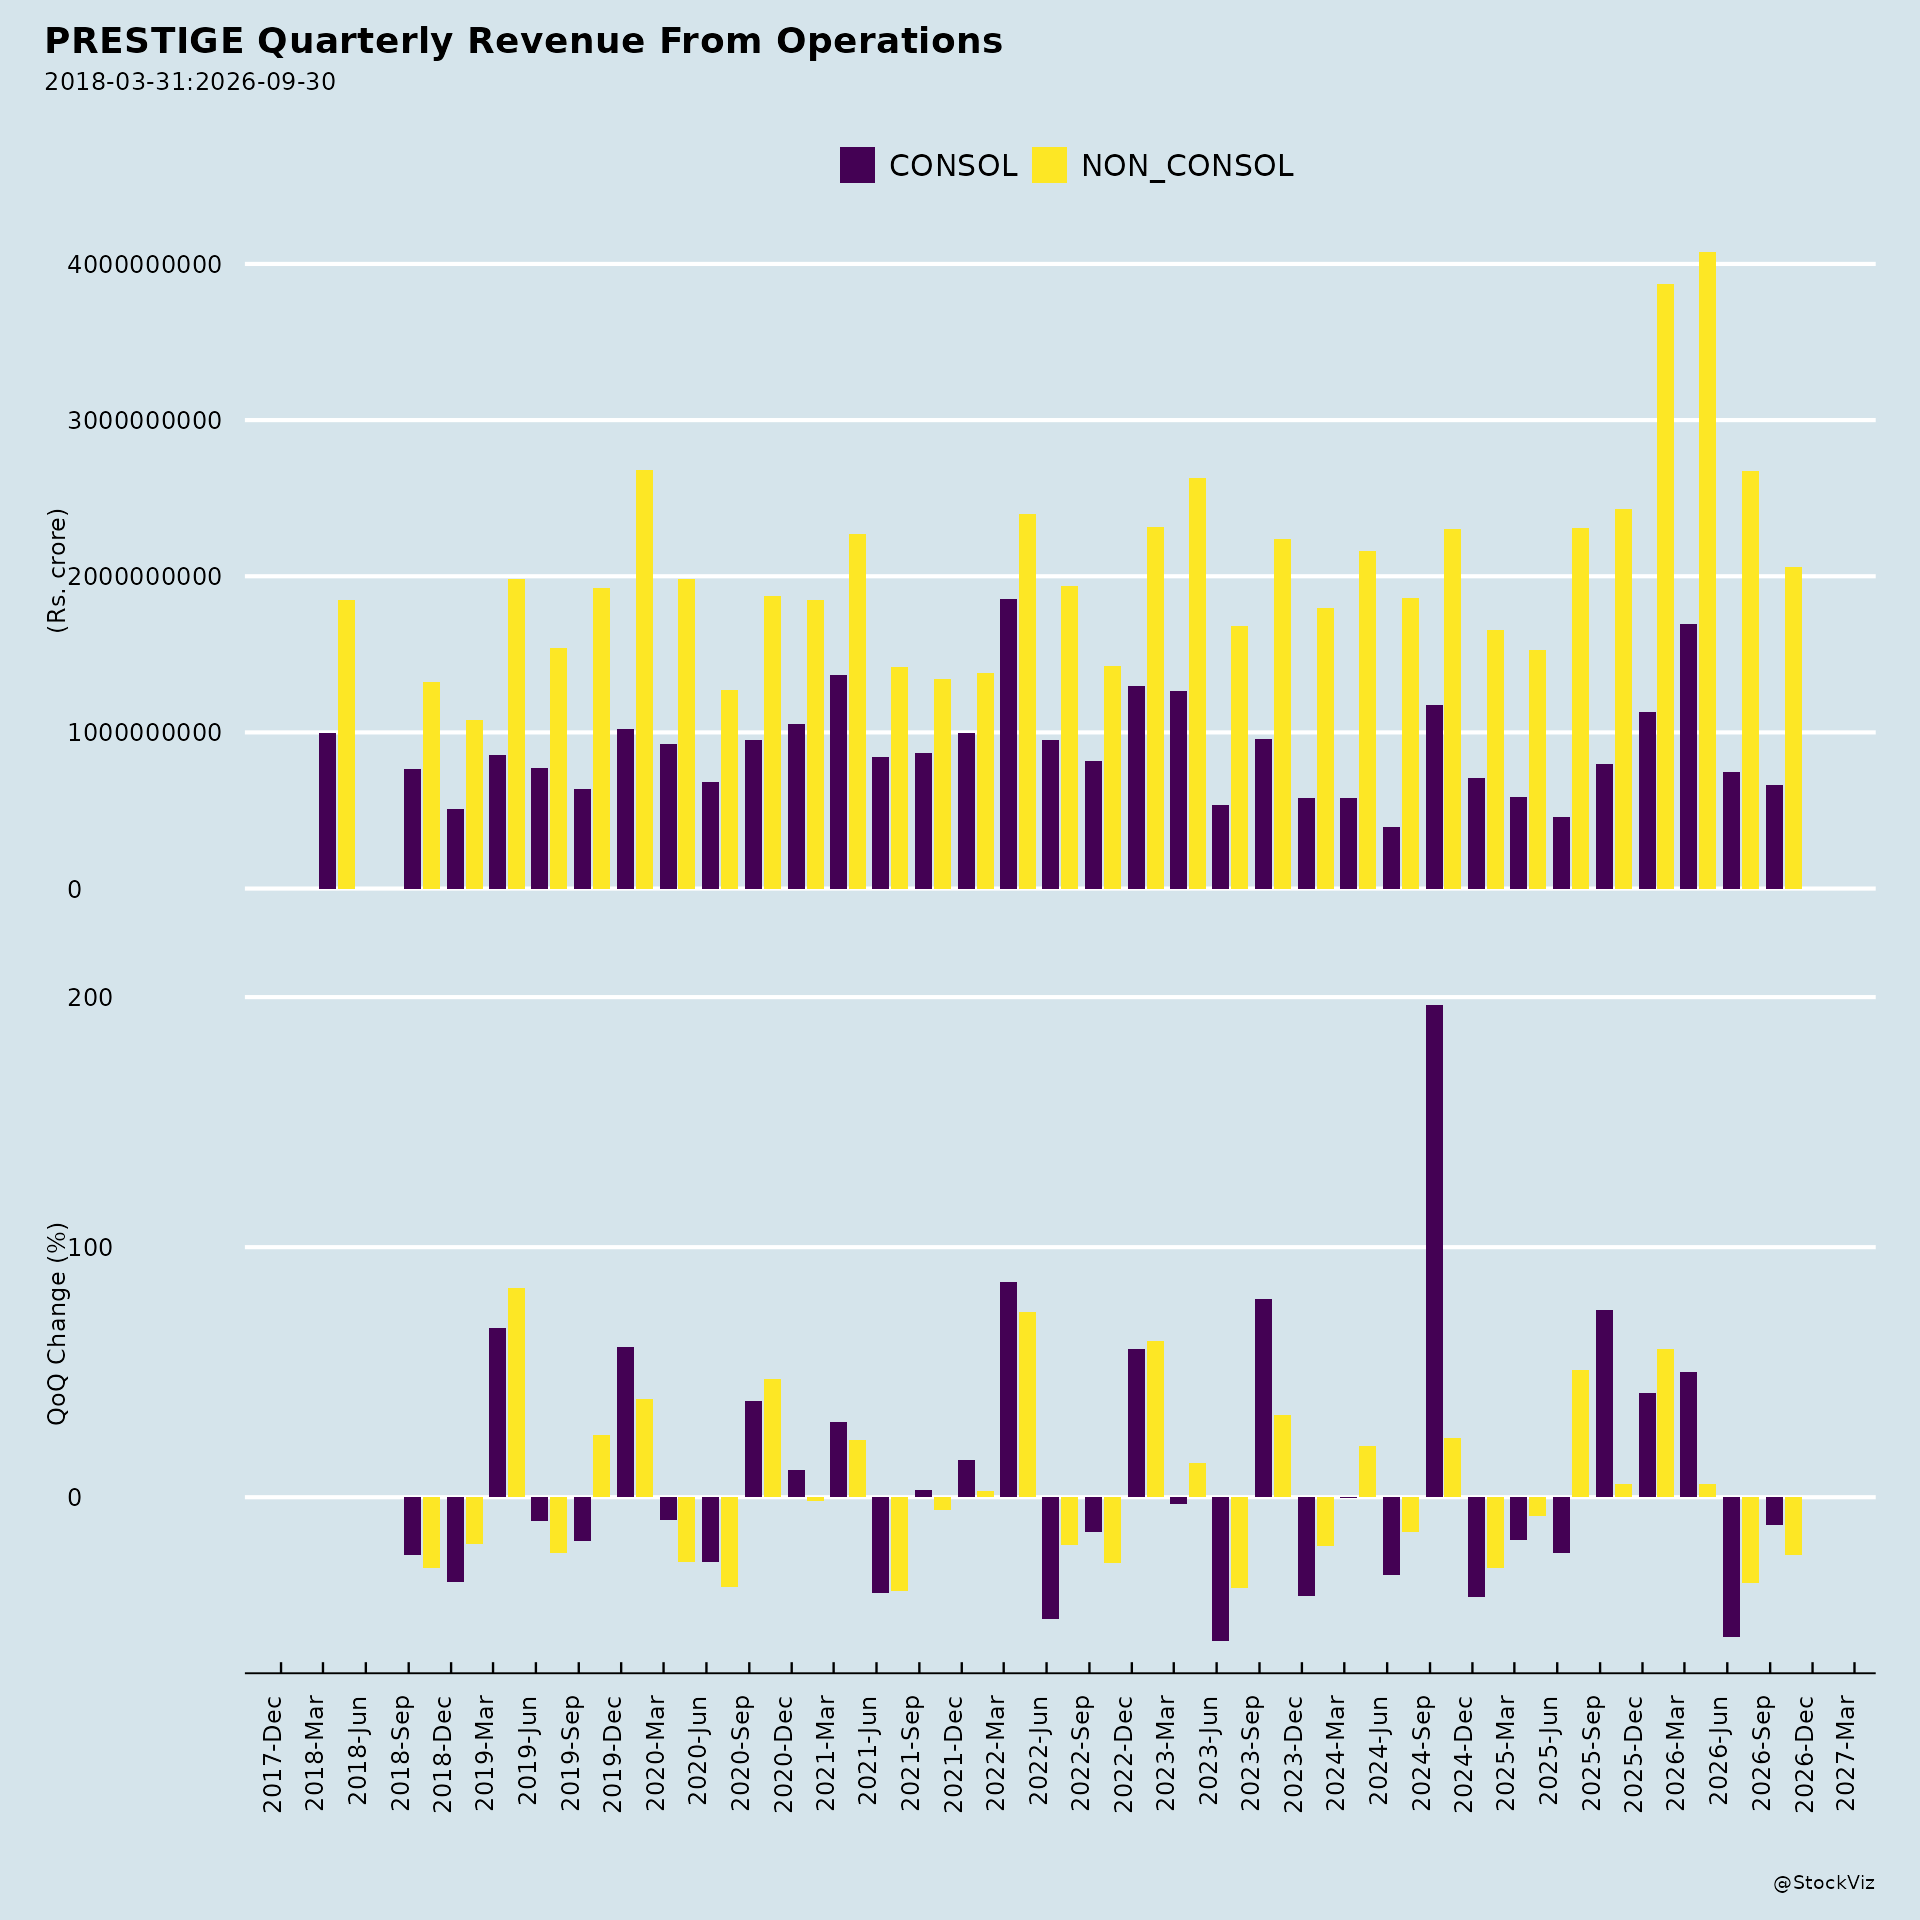
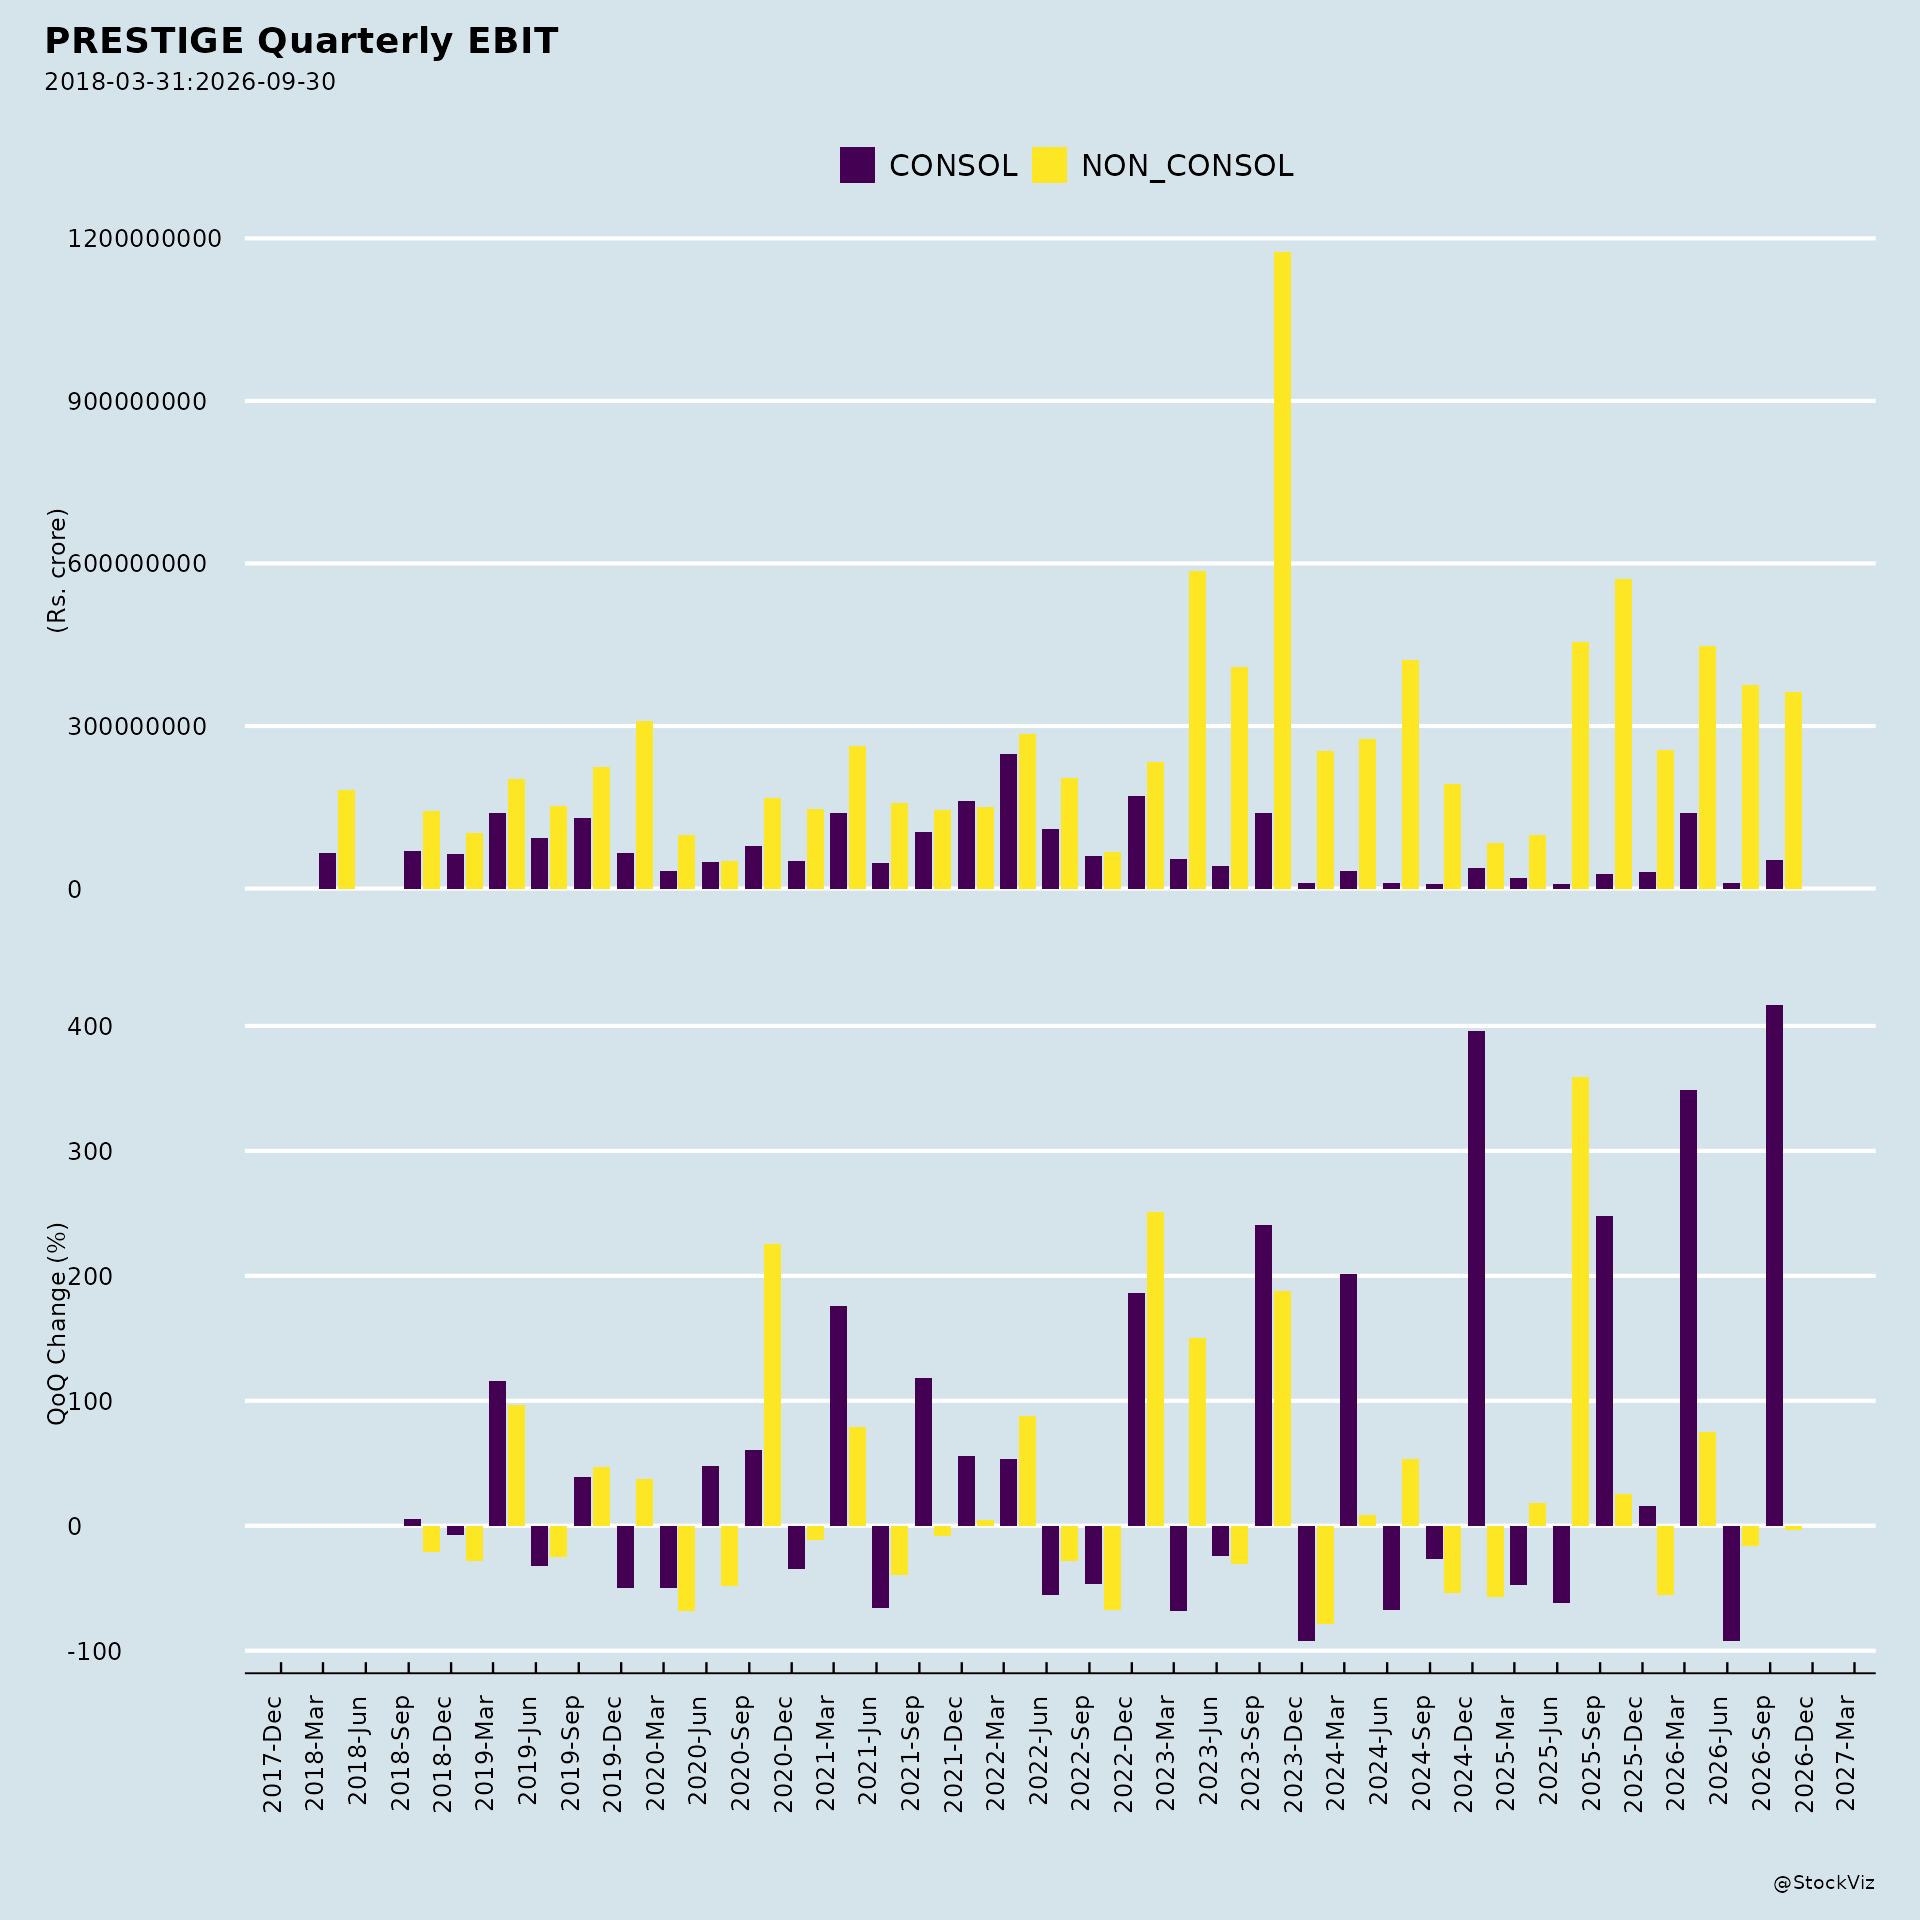
- Modest standalone profitability relative to consolidated: For the quarter ended June 30, 2026, standalone revenue from operations was Rs. 7,490 million with net profit of Rs. 114 million, while consolidated revenue was Rs. 26,751 million with net profit of Rs. 2,714 million.
Tailwinds and Growth Prospects
- Strong Q1 FY27 operational start: Residential pre-sales of ₹65,793 million, sales volume of 6.04 million sq ft and 3,337 units sold; collections of ₹48,022 million.
- Launch pipeline: Four projects launched in Q1 FY27 with combined developable area of 20.16 million sq ft and GDV of approximately ₹1,20,000 mn for residential projects — Prestige Golden Grove (Hyderabad, 14.3 mn sq ft), Prestige Gardenia Estates Ph II (Bengaluru plotted, 0.48 mn sq ft), Prestige ForestHills@TPCMulund - Ph2 (Mumbai, 2.45 mn sq ft) and Prestige Century Landmark (Bengaluru commercial, 2.93 mn sq ft).
- Festive season launch lineup: Management points to an exciting lineup of marquee launches across Mumbai, NCR, Bengaluru and Chennai during the festive season.
- NCR expansion: A 17.14-acre land parcel in Sector 109, Gurgaon was added to the residential portfolio, with saleable area of approximately 2.8 million sq ft and estimated GDV of approximately ₹5,600 crore. Management states it is steadily building scale and depth in NCR, with a strong portfolio of developments planned across NCR in FY27, and that the new project reflects confidence in the long-term potential of NCR. Robust residential demand, ongoing infrastructure development and the region’s increasingly important role in future growth are cited as supports.
- Annuity businesses performing well: Commercial gross leasing of 1.5 million sq ft in the quarter, with exit rentals of ₹7,560 mn as of June 2026. Retail gross turnover across malls of ₹7,370 million, up 18% year-on-year, with footfalls of 5.2 million and exit rentals of ₹2,776 mn as of June 2026. Hospitality delivered healthy operating performance with competitive ARRs and strong occupancy.
- Subsidiary IPO: Proposed initial public offering of wholly-owned subsidiary Prestige Hospitality Ventures Limited (PHVL), comprising an offer for sale of up to Rs. 10,000 million and a fresh issue of up to Rs. 17,000 million.
- Scale of platform: As of March 2026, the Group has delivered 316 projects spanning 212 million sq ft and has a pipeline of 135 projects across 227 million sq ft.
Key Risks
- The outcome and impact of the Karnataka High Court winding-up order relating to a land owner company involved in a real estate project.
- Income tax search matters under section 132 of the Income Tax Act.
- Dependence on a concentrated set of markets for quarterly sales, with Hyderabad contributing nearly half of Q1 FY27 sales and average realizations shaped by that mix.
- Execution and absorption risk on the large launch pipeline, including the festive season launches across Mumbai, NCR, Bengaluru and Chennai.
- Reliance on continued healthy residential demand, infrastructure development and NCR growth to support the planned portfolio.
Management Guidance Versus Observed Business Performance
- Guidance: Management stated it is steadily building scale and depth in the NCR region with a strong portfolio of developments planned across NCR in FY27, and that the Sector 109, Gurgaon project reflects confidence in the long-term potential of NCR. The Chairman and Managing Director stated that the company has an exciting lineup of marquee launches across Mumbai, NCR, Bengaluru and Chennai during the festive season, which is expected to further strengthen growth momentum, and expressed confidence in delivering a stellar performance for the year supported by healthy collections and resilient annuity businesses.
- Observed performance: Q1 FY27 began with pre-sales of ₹65,793 million, 6.04 million sq ft sold across 3,337 units, and collections of ₹48,022 million. Four projects were launched with 20.16 million sq ft of developable area, and three projects totalling 4.37 million sq ft were completed (Prestige Tech Forest, Prestige Sanctuary, Prestige Cityscape). Commercial leasing reached 1.5 million sq ft, retail GTO grew 18% year-on-year to ₹7,370 million with 5.2 million footfalls, and hospitality recorded healthy operating performance. The NCR share of quarterly sales was 7%, with the Sector 109 land addition representing the stated build-out of the NCR pipeline.
- Financial results and dividend: For the quarter ended June 30, 2026, standalone revenue from operations was Rs. 7,490 million with net profit of Rs. 114 million; consolidated revenue from operations was Rs. 26,751 million with consolidated net profit of Rs. 2,714 million. The board recommended a final dividend of Rs. 2.00 per share for the financial year ended March 31, 2026, which shareholders approved at the 29th AGM held on August 20, 2026.
- Shareholder approvals: At the AGM, seven resolutions were passed, including adoption of the audited standalone and consolidated financial statements for FY ended March 31, 2026, the final dividend of ₹2 per fully paid equity share for FY 2025-2026, re-appointment of Ms. Uzma Irfan as Director, ratification of remuneration to M/s P. Dwibedy & Co. as Cost Auditor for FY 2026-2027, re-designation of Ms. Uzma Irfan as Whole time Director (special resolution), and issue of Non-Convertible Debentures on a private placement basis (special resolution). Total votes polled represented 91.99% of shares outstanding, with 99.58% of votes in favour on the financial statement resolutions.
Broker Narrative
The 2023-06-01 call balanced supply-side fears (moderating supply, flattish realizations, absent launches driving weak bookings) against demand-side tailwinds (peaking rates, robust demand with meager inventory, strong launch pipelines). The thesis was strongly vindicated at first (+240.3% actual) but stalled through 2024-2025 with repeated negative actuals and six Buy DISAPPOINTMENTs. By the 2026-11-11 report the narrative had shifted from demand-versus-supply to execution: headwinds narrowed to approval/RERA delays while tailwinds emphasized delivered metrics (healthy pre-sales, strong collections, INR 460bn 2HFY27 pipeline, strong OCF, comfortable balance sheet), with the Buy call intact.
Fears that came true
- ‘Supply to moderate with flattish realization trends’ materialized as a prolonged flat-to-negative stretch from Apr-2024 to Dec-2025 (actuals of -10.3%, -10.2%, -10.1%, -3.0%, -6.5%, -5.3%, -0.4%) that produced six Buy-call DISAPPOINTMENT outcomes.
- The launch/booking fears — ‘lack of significant launches in certain regions’, ‘moderate new launches’ and ‘absence of new project launches leading to weak bookings for specific developers’ — were never fully laid to rest, with the final report still citing ‘Approval-related delays in a few upcoming projects’ and ‘regulatory approvals and RERA clearances remaining key constraints’.
Optimism that failed
- ‘Interest rates likely to peak out’ never translated into sustained support, as actual returns stayed negative or flat across 2024-2025 (e.g., -10.3% on 2024-04-02, -6.5% on 2025-05-30, -5.3% on 2025-11-01) despite the expected rate-cycle tailwind.
Broker Timeline
41 broker calls · 2023-06-01 to 2026-11-11
CNBC-TV18: ratings, targets and commentary
No recorded CNBC-TV18 statements for this ticker.
Management comments
No recorded management comments with an explicit designation and affiliation for this ticker.
Copyright © 2023 SAS Data Analytics Pvt. Ltd. All rights reserved.