POWERINDIA
Equity Metrics
November 18, 2026
Hitachi Energy India Limited
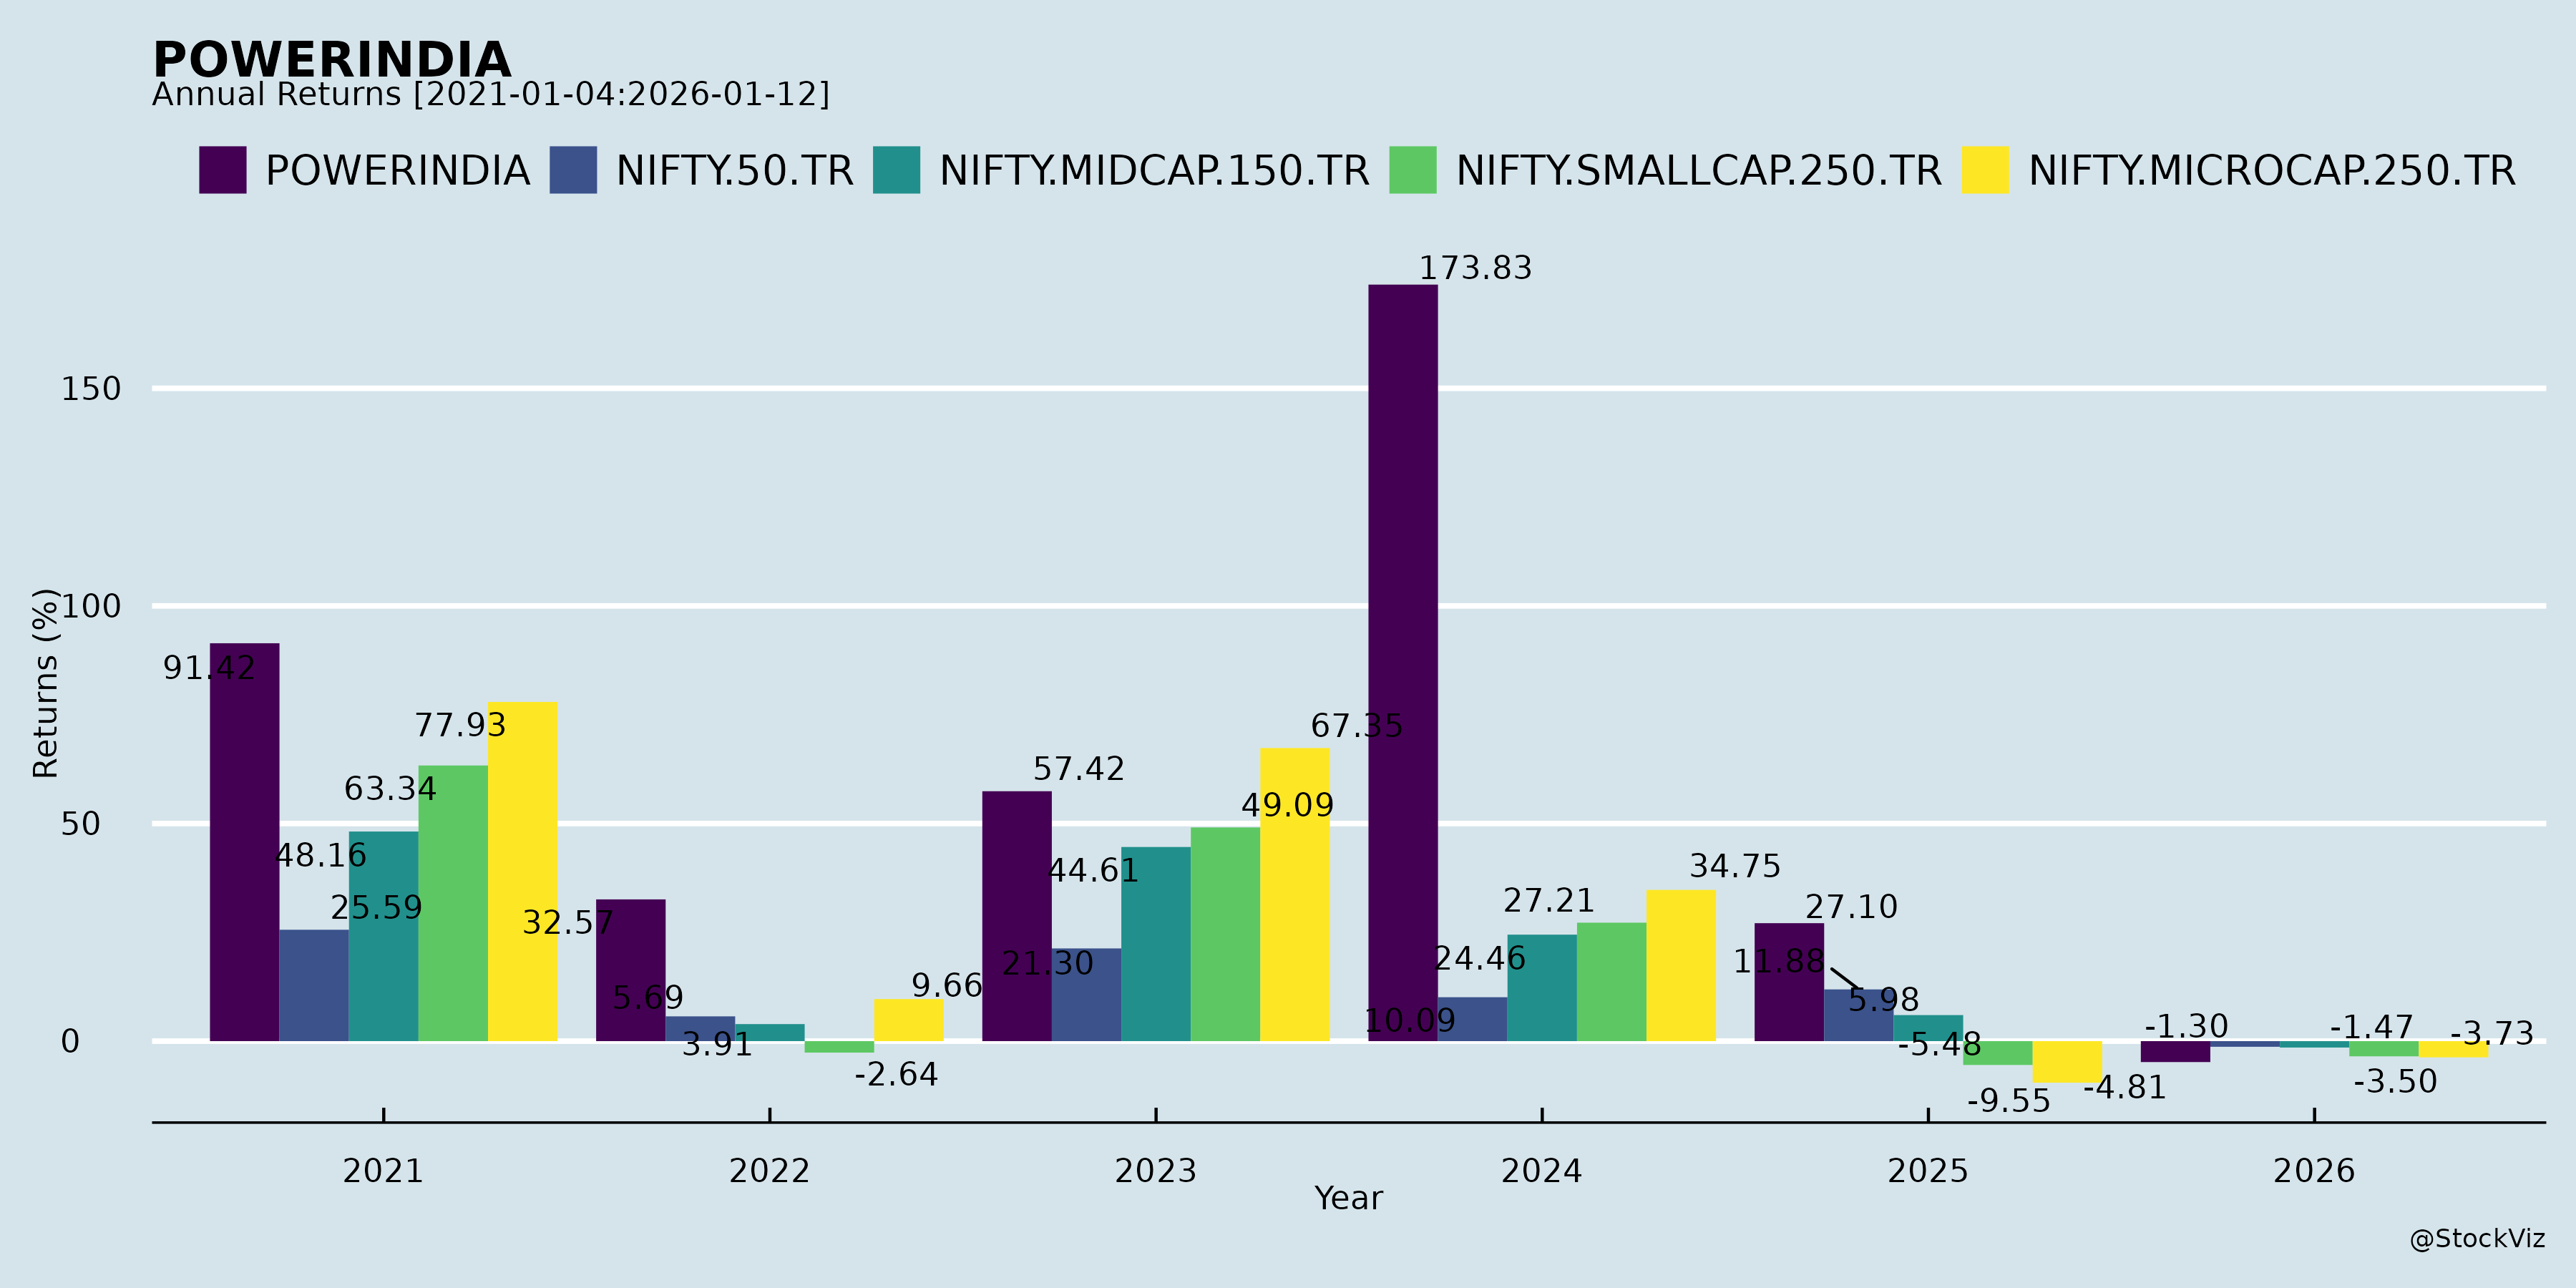
Annual Returns
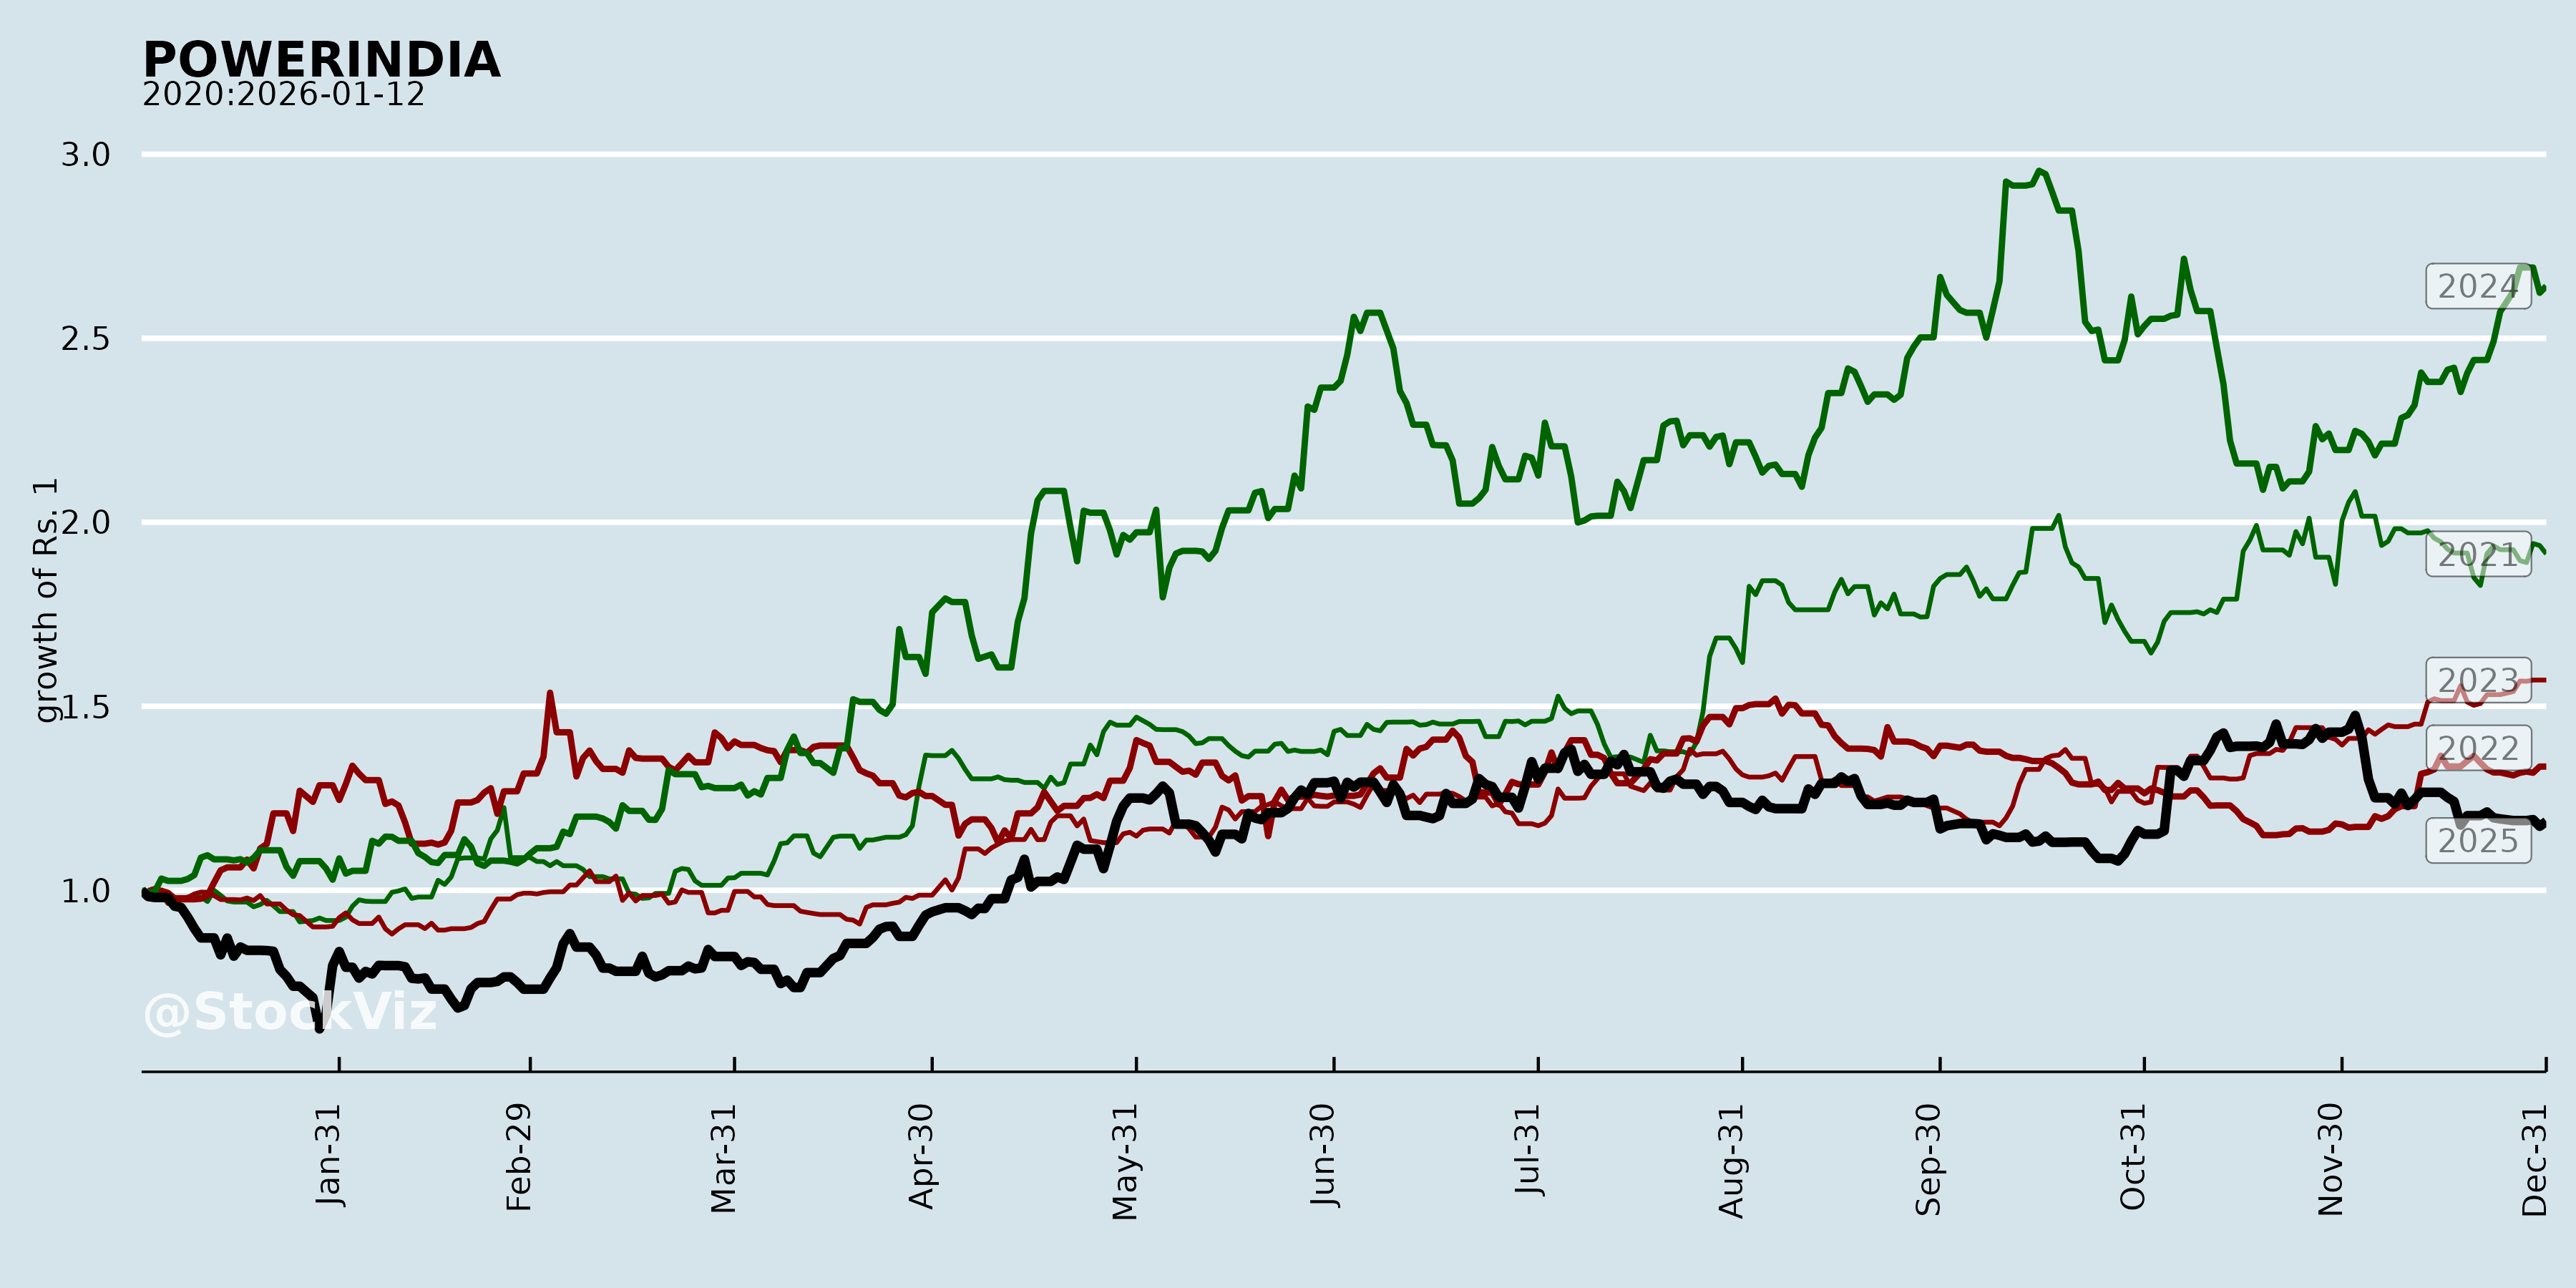
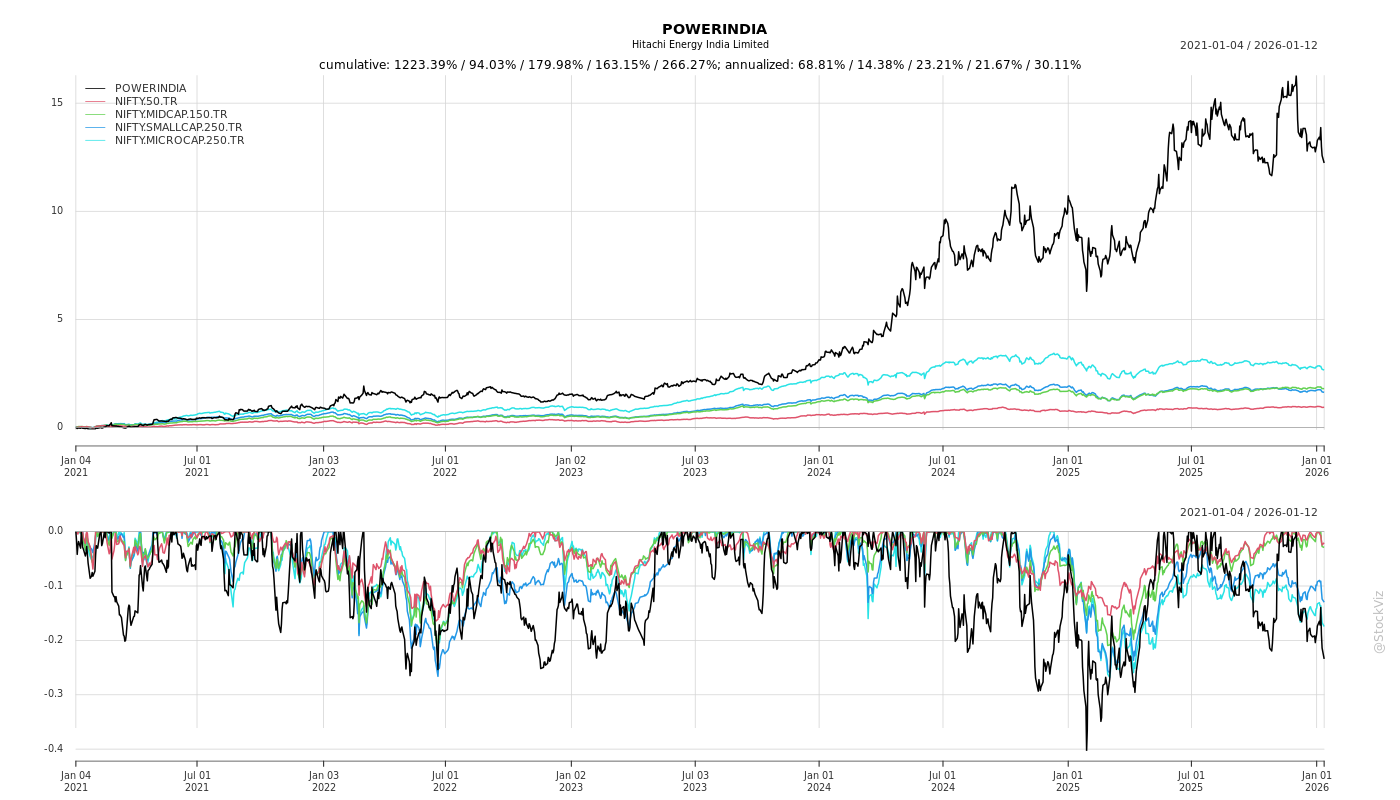
Cumulative Returns and Drawdowns
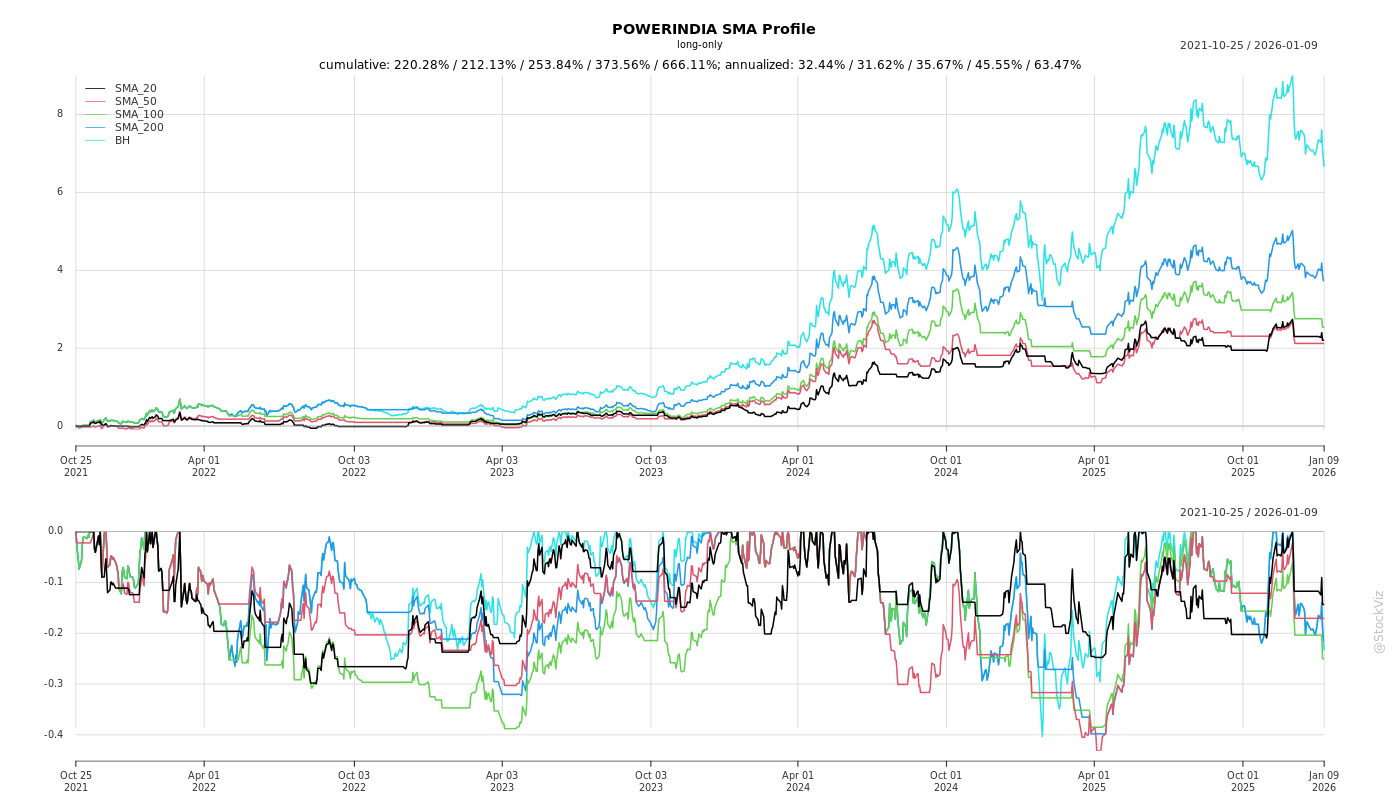
Fundamentals
Ownership
Margined

AI Summary
asof: 2026-09-14
Hitachi Energy India Limited — Recent Corporate Announcements
1. Headwinds and Challenges
- Geopolitical tension: Management states that a quick resolution of ongoing geopolitical tension is essential for world economic growth, and that prolongation of the current situation might hinder the pace of energy transition worldwide.
- Policy environment: Management notes that delivering on the renewable capacity target would require closer collaboration among all stakeholders and a level-playing-field policy to ensure equal opportunities for players, both domestic and global.
- Sequential softness: Revenue, PBT, PAT, and Operational EBITDA were all lower in Q1FY27 compared with Q4FY26, which the company attributes to a higher revenue base in the previous quarter.
- Foreign exchange and commodity timing differences: Operational EBITDA excludes, among other items, foreign exchange/commodity timing differences in income from operations; for the quarter ended June 30, 2026, this exclusion related to a loss of INR 36.37 crores.
2. Tailwinds and Growth Prospects
- Electrification demand: The company describes a surge in electrification driven by transport, manufacturing, digital infrastructure, and the clean energy industry, with India’s growing domestic power demand and structural advantages providing a significant opportunity for the energy sector.
- Order momentum: Q1FY27 orders totaled INR 5,096.5 crore, up 26.1% YoY and 39.7% QoQ (excluding HVDC orders in the respective quarters). Orders were led by HVDC, grid connection solutions, power quality equipment, and transformers, with data centers contributing significantly, followed by industries and renewables.
- Record backlog: The company reported its highest ever order backlog of INR 32,222.1 crore, which it states provides revenue visibility for several quarters.
- Energy storage milestone: The company secured its first BESS order for a 165 MW / 330 MWh project in Andhra Pradesh. With government focus on capacity expansion and grid assimilation, the company expects growth momentum in the energy storage segment to continue.
- Exports: The export segment continued to grow, accounting for 33.6% of total orders (without HVDC) booked in the quarter, with orders from Europe, North America, and South Asia for grid integration and power quality products.
- Services: Service orders came from utilities, discoms, industry, and transport for bay extension, switchyard commissioning, maintenance, and lifecycle services.
- Emerging segments: The new fiscal year opens opportunities in AI data centers, smart grids, BESS, and electric vehicle infrastructure. The target of 900 GW of non-fossil fuel installed capacity by FY36 is expected to grow renewable energy opportunities manifold and calls for a robust energy manufacturing ecosystem.
- Capacity expansion: Construction began in June 2026 on the company’s 20th manufacturing unit at Karjan, Vadodara, to strengthen execution capabilities and supply chain robustness.
- Related party transaction limits: Shareholder approval is being sought via Postal Ballot for material related party transactions during FY 2026-27 with Hitachi Energy Sweden AB (up to INR 2,800 crore), Hitachi Energy USA Inc (up to INR 1,900 crore), and Hitachi Energy Ltd., Switzerland (up to INR 1,300 crore). Management expects higher procurement of critical products and components and increased transaction volumes during FY 2026-27 to support the expanding order backlog and export operations.
- ESG rating improvement: The company’s overall ESG rating improved to ‘CRISIL ESG 69’ for 2026 from ‘CRISIL ESG 61’ for 2025, assigned independently by Crisil ESG Ratings & Analytics Ltd using publicly available information, with the report received by the company on September 01, 2026.
3. Key Risks
- Geopolitical risk: Prolonged geopolitical tension could hinder the pace of the global energy transition, as flagged in the Q1FY27 outlook.
- Policy risk: The absence of a level-playing-field policy could affect equal opportunities for domestic and global players, per management’s outlook.
- Related party concentration: The proposed FY 2026-27 transactions with Hitachi Energy Sweden AB, Hitachi Energy USA Inc, and Hitachi Energy Ltd., Switzerland represent significant enabling ceilings subject to shareholder approval through Postal Ballot.
- Foreign exchange and commodity exposure: Timing differences in foreign exchange and commodity items affected income from operations in Q1FY27 (a loss of INR 36.37 crores excluded from Operational EBITDA).
4. Management Guidance Versus Observed Business Performance
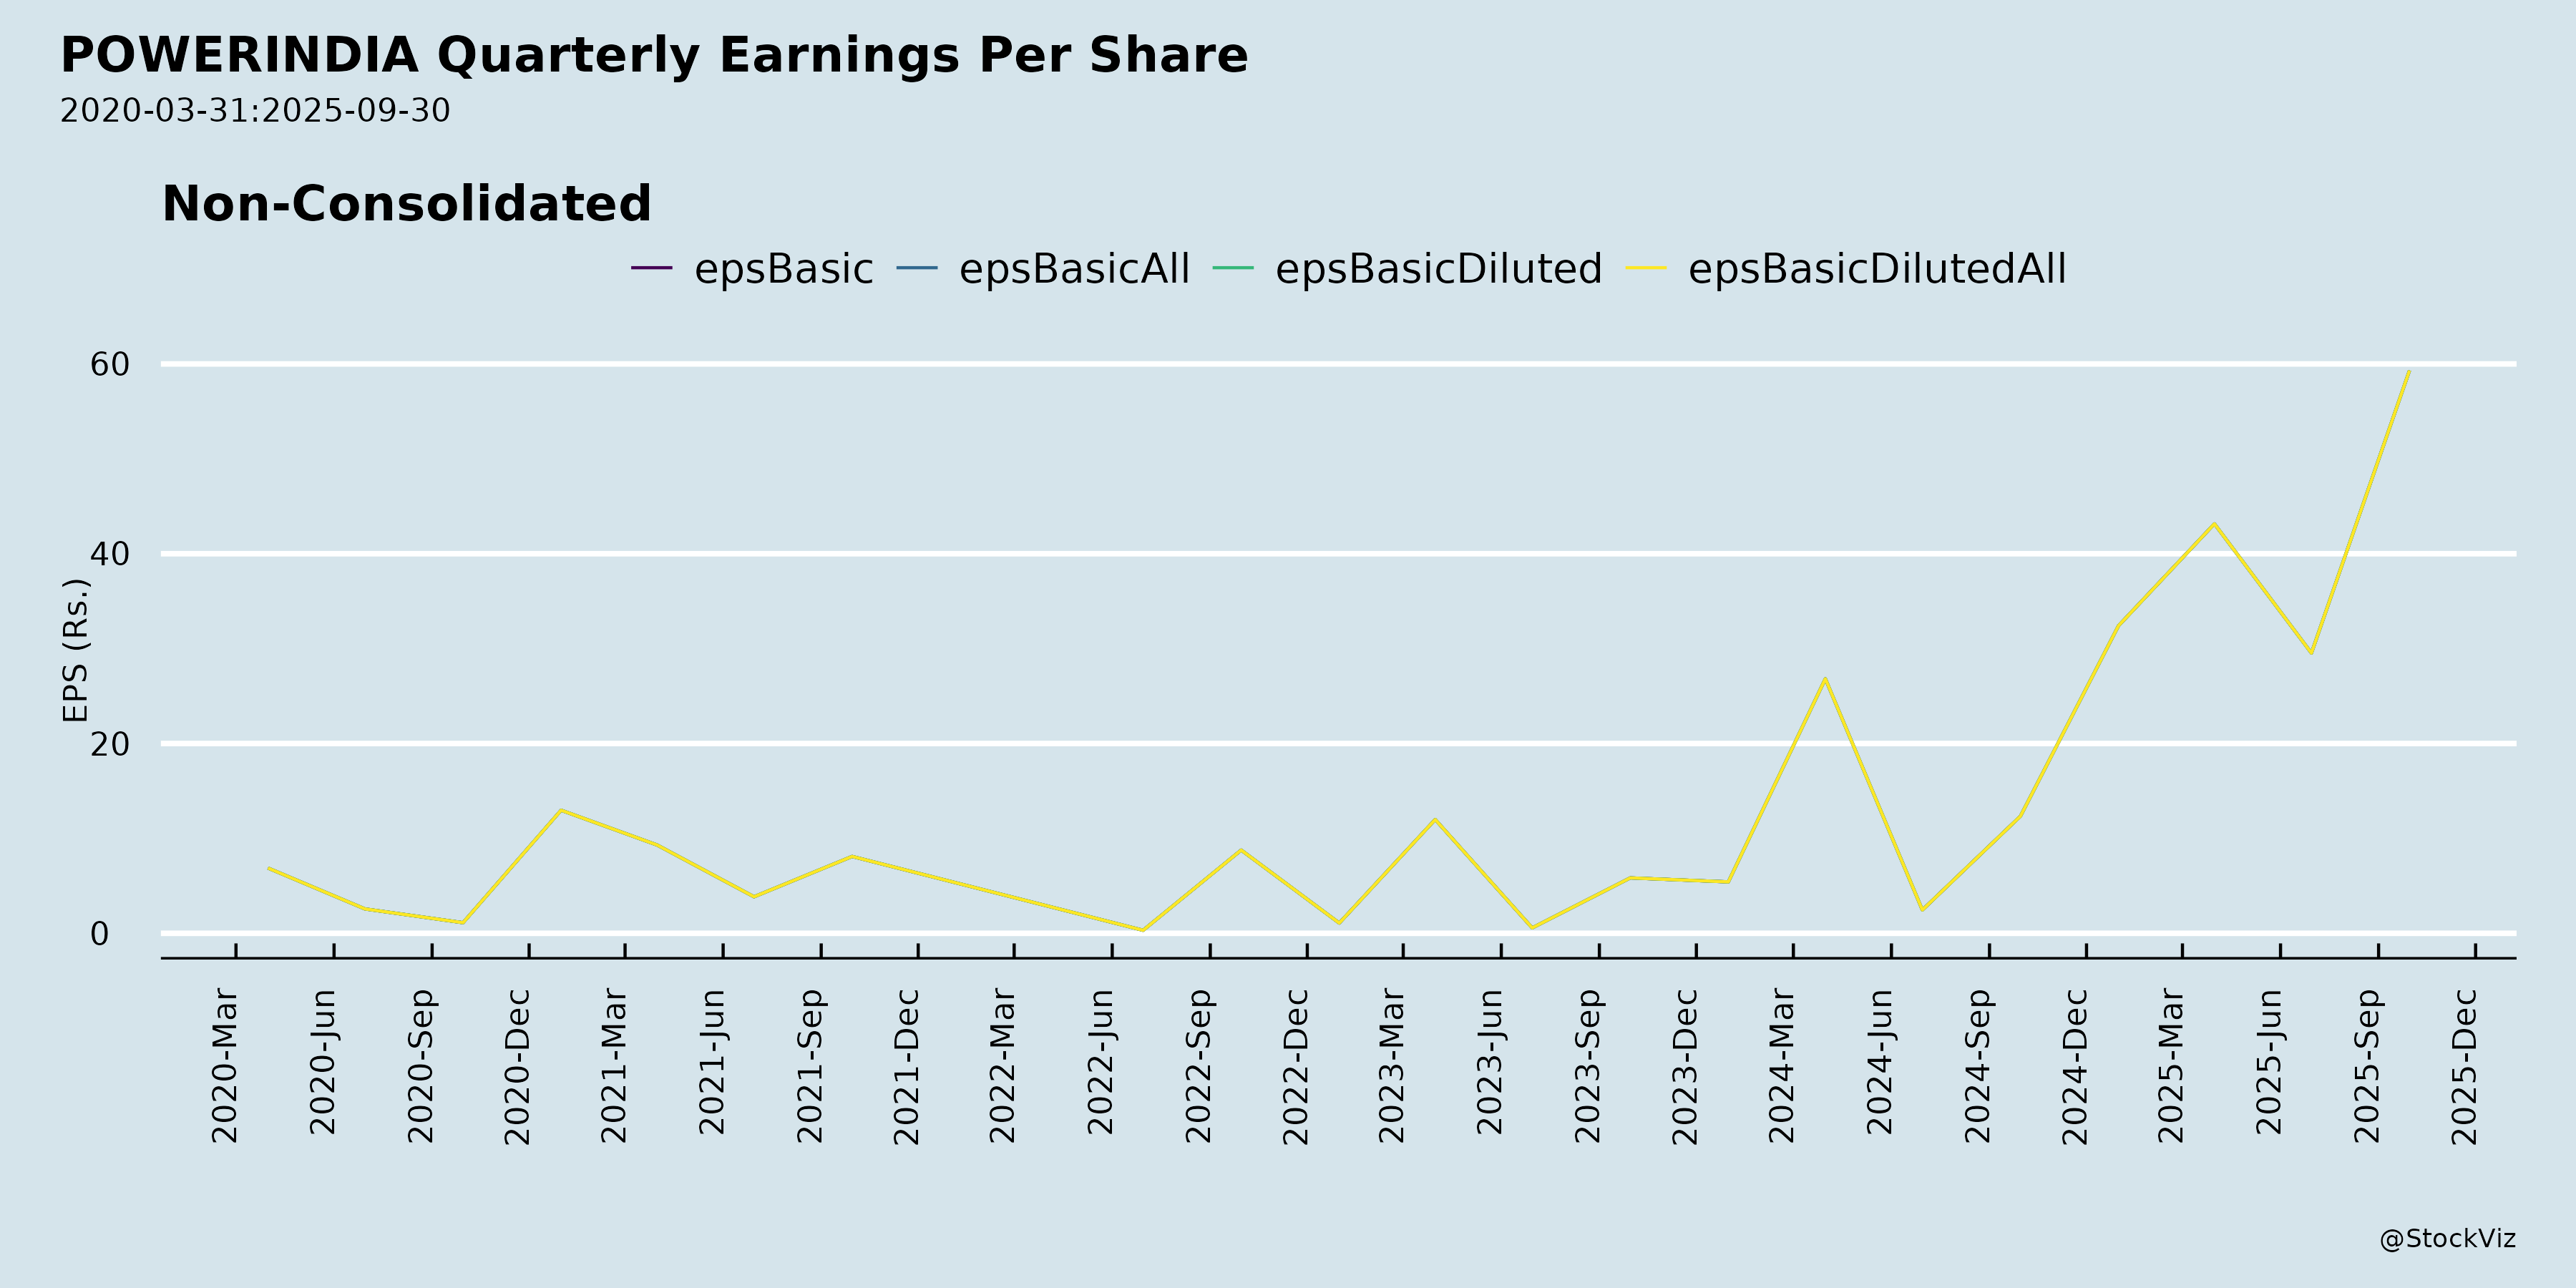
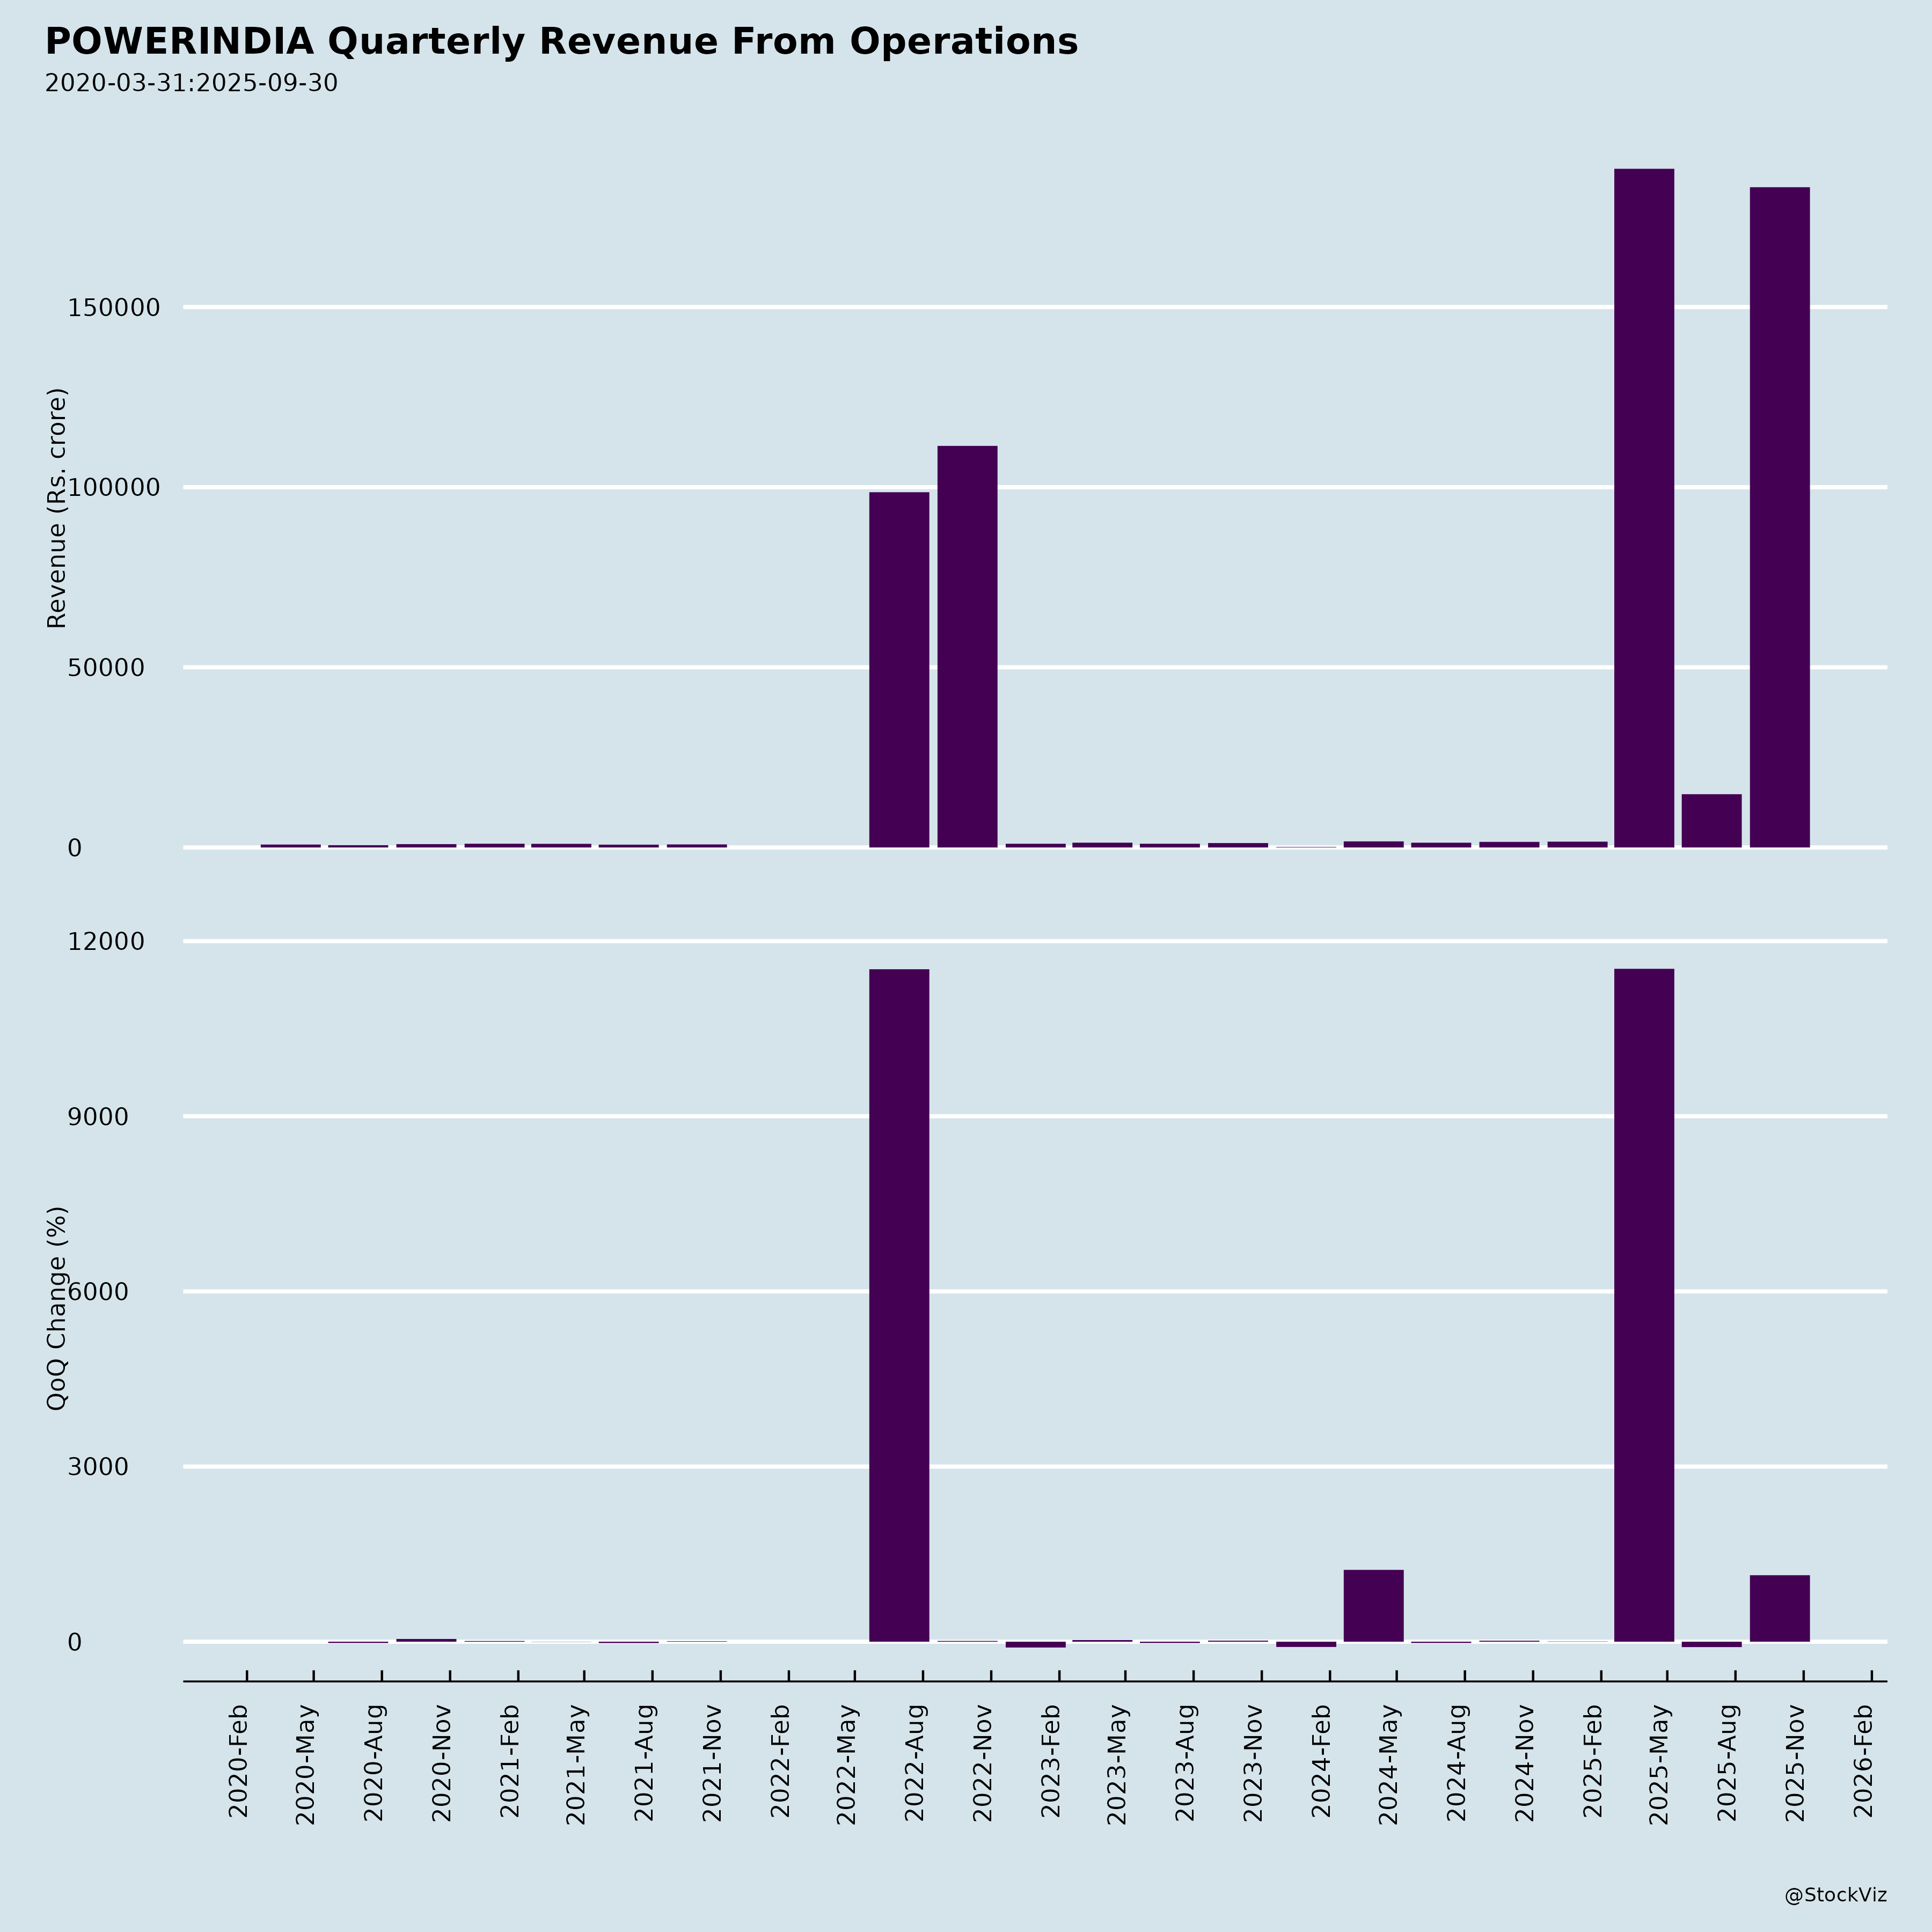
- Order backlog and execution: Management states the highest ever order backlog of INR 32,222.1 crore provides revenue visibility for several quarters. Observed performance in Q1FY27 showed revenue growth of 68.6% YoY to INR 2,493.7 crore, driven by strong, timely execution of order backlog across all businesses.
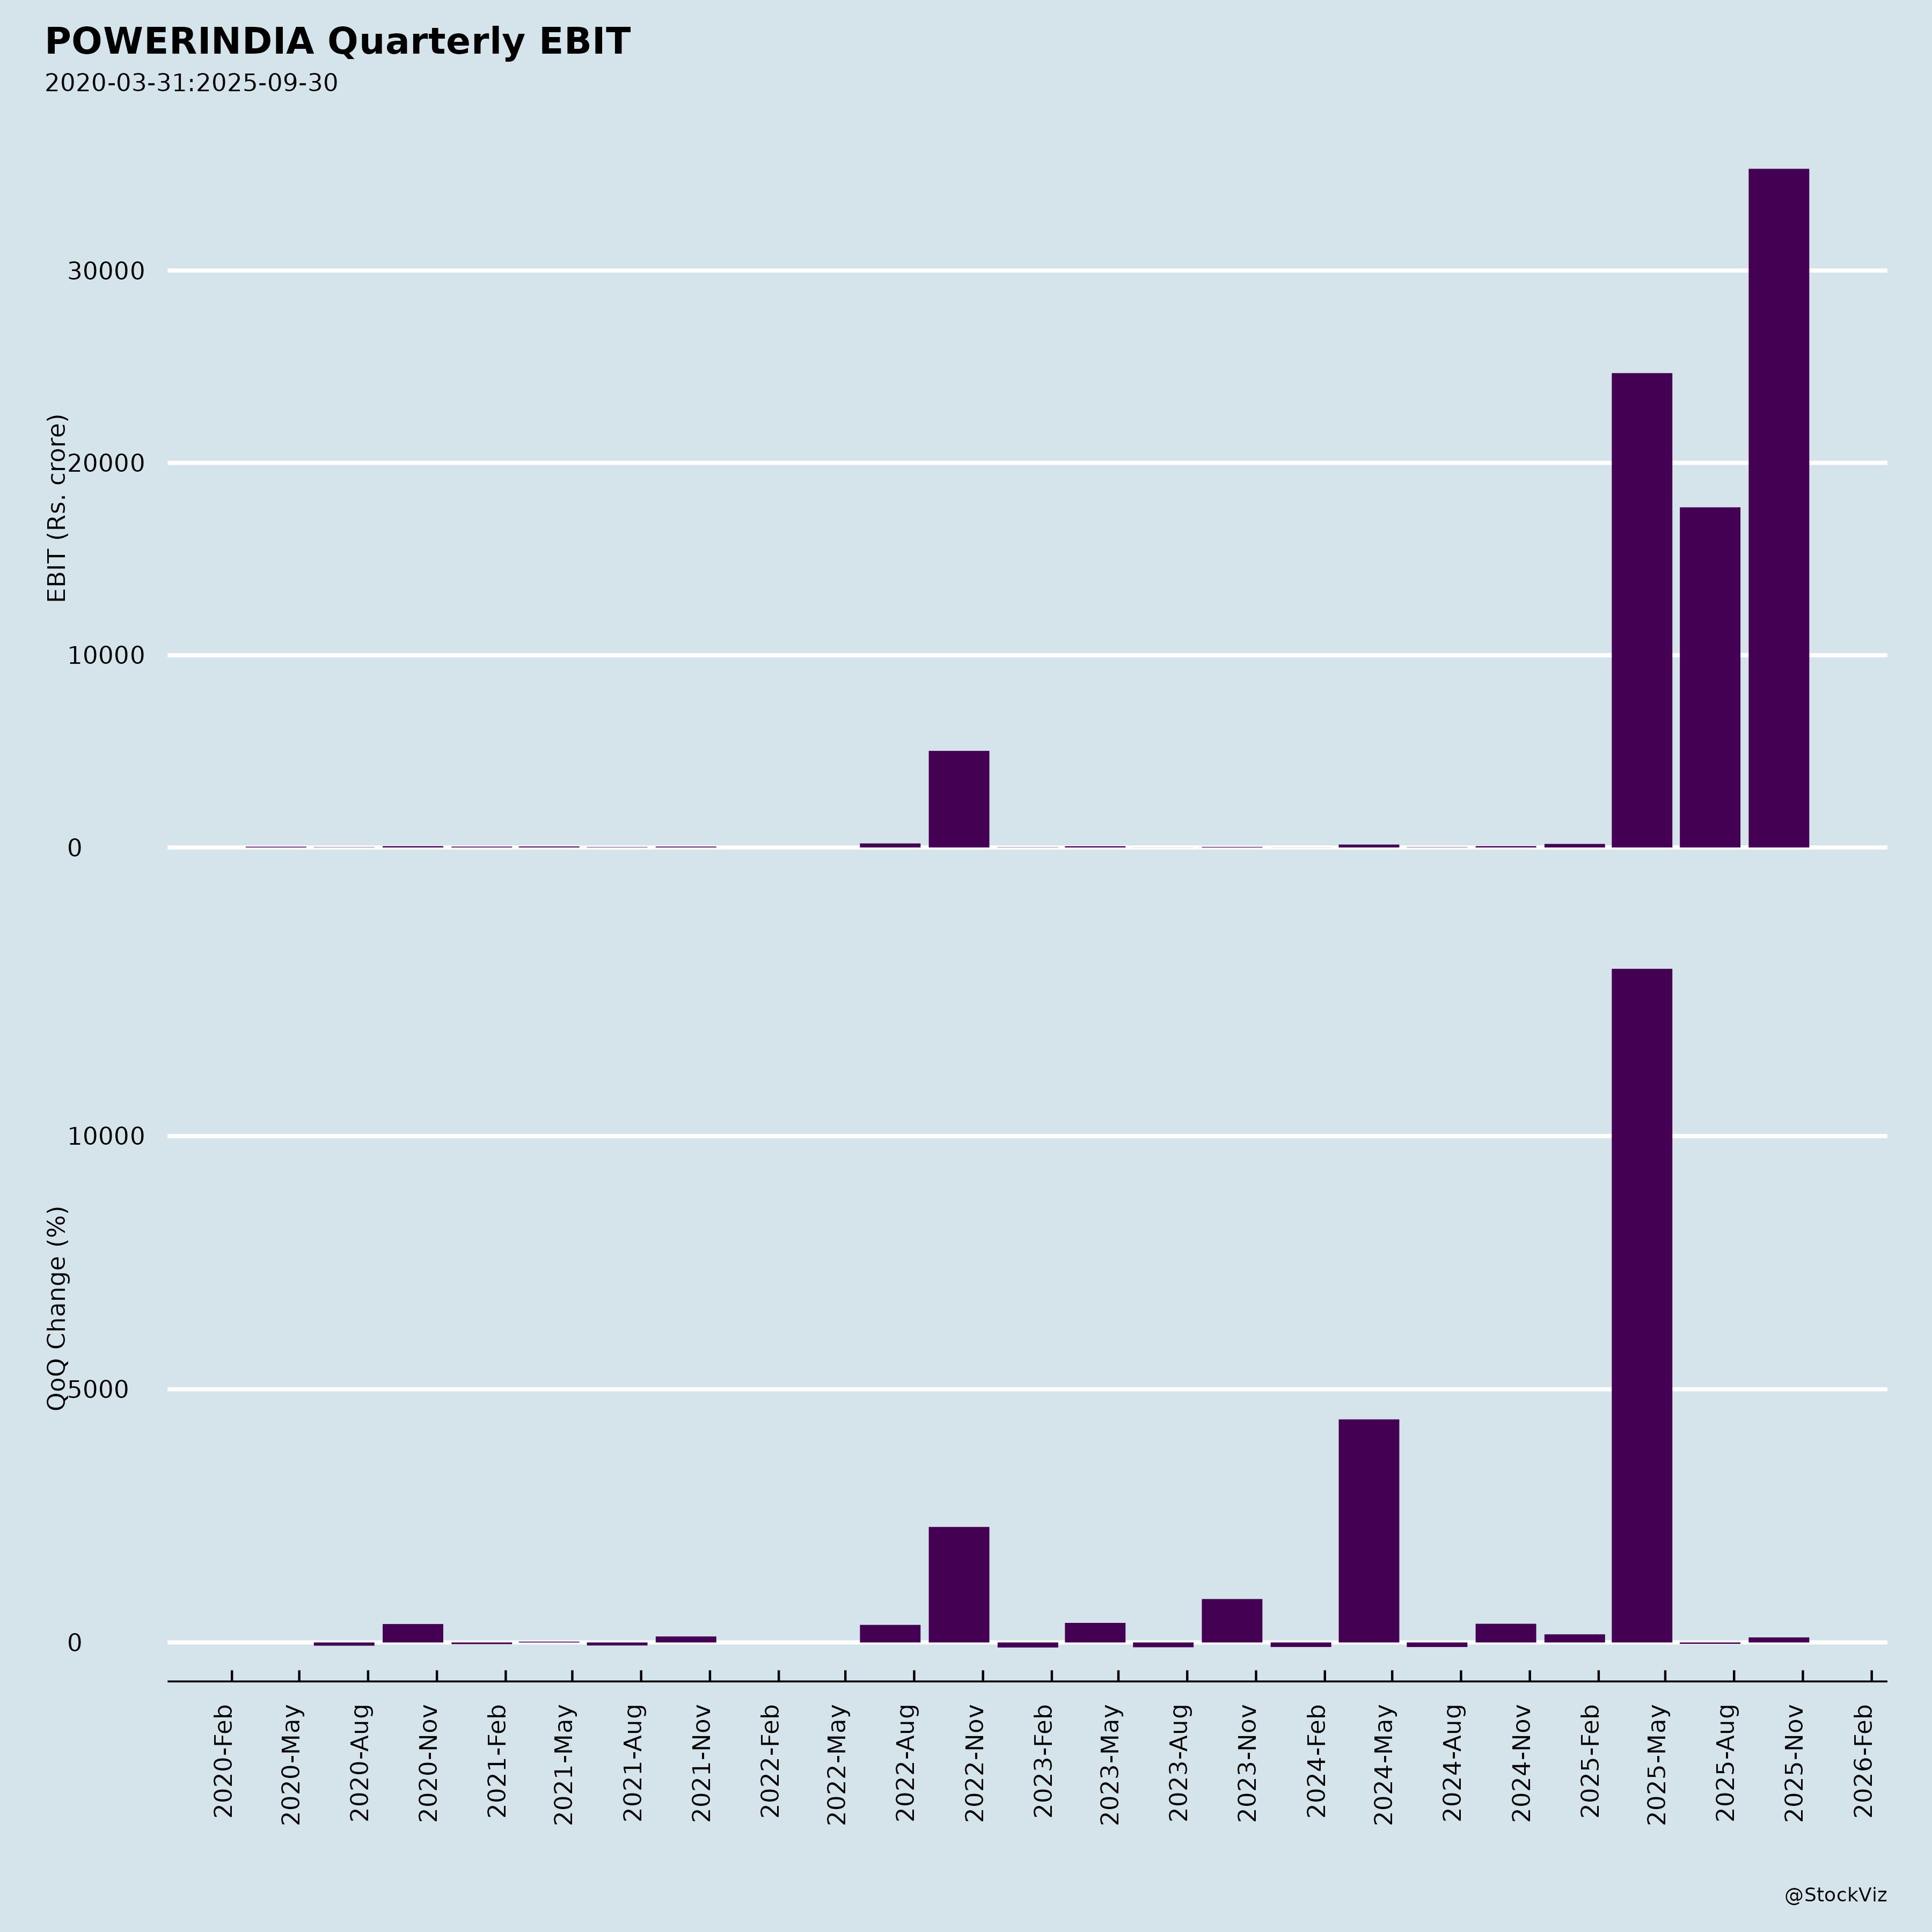
- Margins and efficiency: Management attributes healthy margin growth to efficient execution of a favorable product mix, strong operational efficiencies, and growing export contribution. Observed Q1FY27 Operational EBITDA was INR 399.9 crore at a 16.0% margin, with PBT up 120.2% YoY and PAT up 123.5% YoY.
- Procurement and transaction volumes: Management expects higher procurement of critical products and components and increased transaction volumes during FY 2026-27 to support the expanding order backlog and export operations. Management also notes the proposed related party transaction limits represent enabling ceilings and should not be construed as a commitment that the entire approved value will necessarily be consummated.
- Capacity build-out: Management states construction of the 20th manufacturing unit at Karjan, Vadodara, began in June 2026, reflecting commitment to energy security and the ‘Make in India’ vision.
- Investor engagement: The company will meet analysts and investors at the Jefferies India Conference 2026 in Gurgaon on September 16, 2026, in an in-person group setting, with discussions referring only to publicly available documents and no unpublished price-sensitive information shared. A separate analysts/investors presentation for Citi’s 2026 India Industrials Access Day in Singapore and Hong Kong on August 12–13, 2026 was hosted on the company’s website.
- Governance updates: The Board on August 07, 2026 approved amendments to the Code of Conduct for Prevention of Insider Trading and the Code of Practices and Procedures for Fair Disclosure of Unpublished Price Sensitive Information. Remote e-voting on the Postal Ballot for related party transaction approvals is available from September 13, 2026 to October 12, 2026.
Broker Narrative
The structural bull case on government capex, transmission/HVDC build-out, exports and services persisted from the first to the last report, ending back at Buy despite interim Sell/Neutral calls along the way. The margin narrative changed: early confidence that a raw-material price correction would support margins gave way to last-report warnings of elevated commodity costs, HVDC execution dragging gross margins, and a 90% YoY OCF decline on working capital. Early fears of export weakness and inflow sustainability were replaced by an export-margin-premium (300-400bp) and services-monetization story, with strong base and export orders offsetting weak new HVDC ordering. The stock’s huge gains through 2025 vindicated the bulls, while the 2026 drawdowns (-12.2% to -15.8% around the Neutral/Reduce calls) marked the first stretch where the flagged cost and order risks showed up in returns.
Fears that came true
- The early warning that a steep rise in raw material prices could hurt gross margins materialized, as the last report cites elevated commodity/raw material prices keeping material costs under pressure and HVDC execution weighing on gross margins, coinciding with the stock’s negative actual returns in mid-2026 (-12.2% on 2026-05-26, -15.8% on 2026-05-27, -3.1%/-6.5% in Aug-2026) when Reduce/Neutral calls were published.
- The early risk that sequentially slowing order inflows might not be sustainable resurfaced in the last report as ‘weaknesses in new HVDC ordering’ that needed strong base and export orders to offset, emerging during the 2026 period when actual returns turned negative.
Optimism that failed
- The tailwind that a ‘correction in raw material prices supports margins, especially for fixed-price contracts’ failed, as the last report states commodity and raw material prices are expected to remain elevated, keeping material costs under pressure and HVDC execution weighing on the gross margin profile.
- The tailwind that the ‘structural order-inflow trend remains positive, with strong demand acting as a catalyst’ was undercut by the last report’s disclosure of weaknesses in new HVDC ordering, forcing reliance on base and export orders to sustain growth.
Broker Timeline
32 broker calls · 2023-12-10 to 2026-11-12
CNBC-TV18: ratings, targets and commentary
Extracted from CNBC-TV18 posts; ratings and targets are as published, not current consensus. OCR may contain errors. Speaker attribution is retained; not all speakers are brokers. These statements are separate from the Broker Narrative and Broker Timeline and have no calculated performance or outcomes.
Ratings and targets
| Published / source (IST) | Speaker / affiliation | Rating / target | Commentary |
|---|---|---|---|
| 2026-11-13 |
PL Capital
Amit Anwani
|
Buy
|
Jal Jeevan Mission has been an issue for many cos but for L&T it's a small portion. Q2 was better than expected for L&T. Order book for Hitachi Energy is very strong. Expect to see a reversal in Hitachi Energy share price. Strong commentary from Hitachi Energy management. |
Management comments
No recorded management comments with an explicit designation and affiliation for this ticker.
Copyright © 2023 SAS Data Analytics Pvt. Ltd. All rights reserved.