POLICYBZR
Equity Metrics
November 18, 2026
PB Fintech Limited
Financial Technology (Fintech)
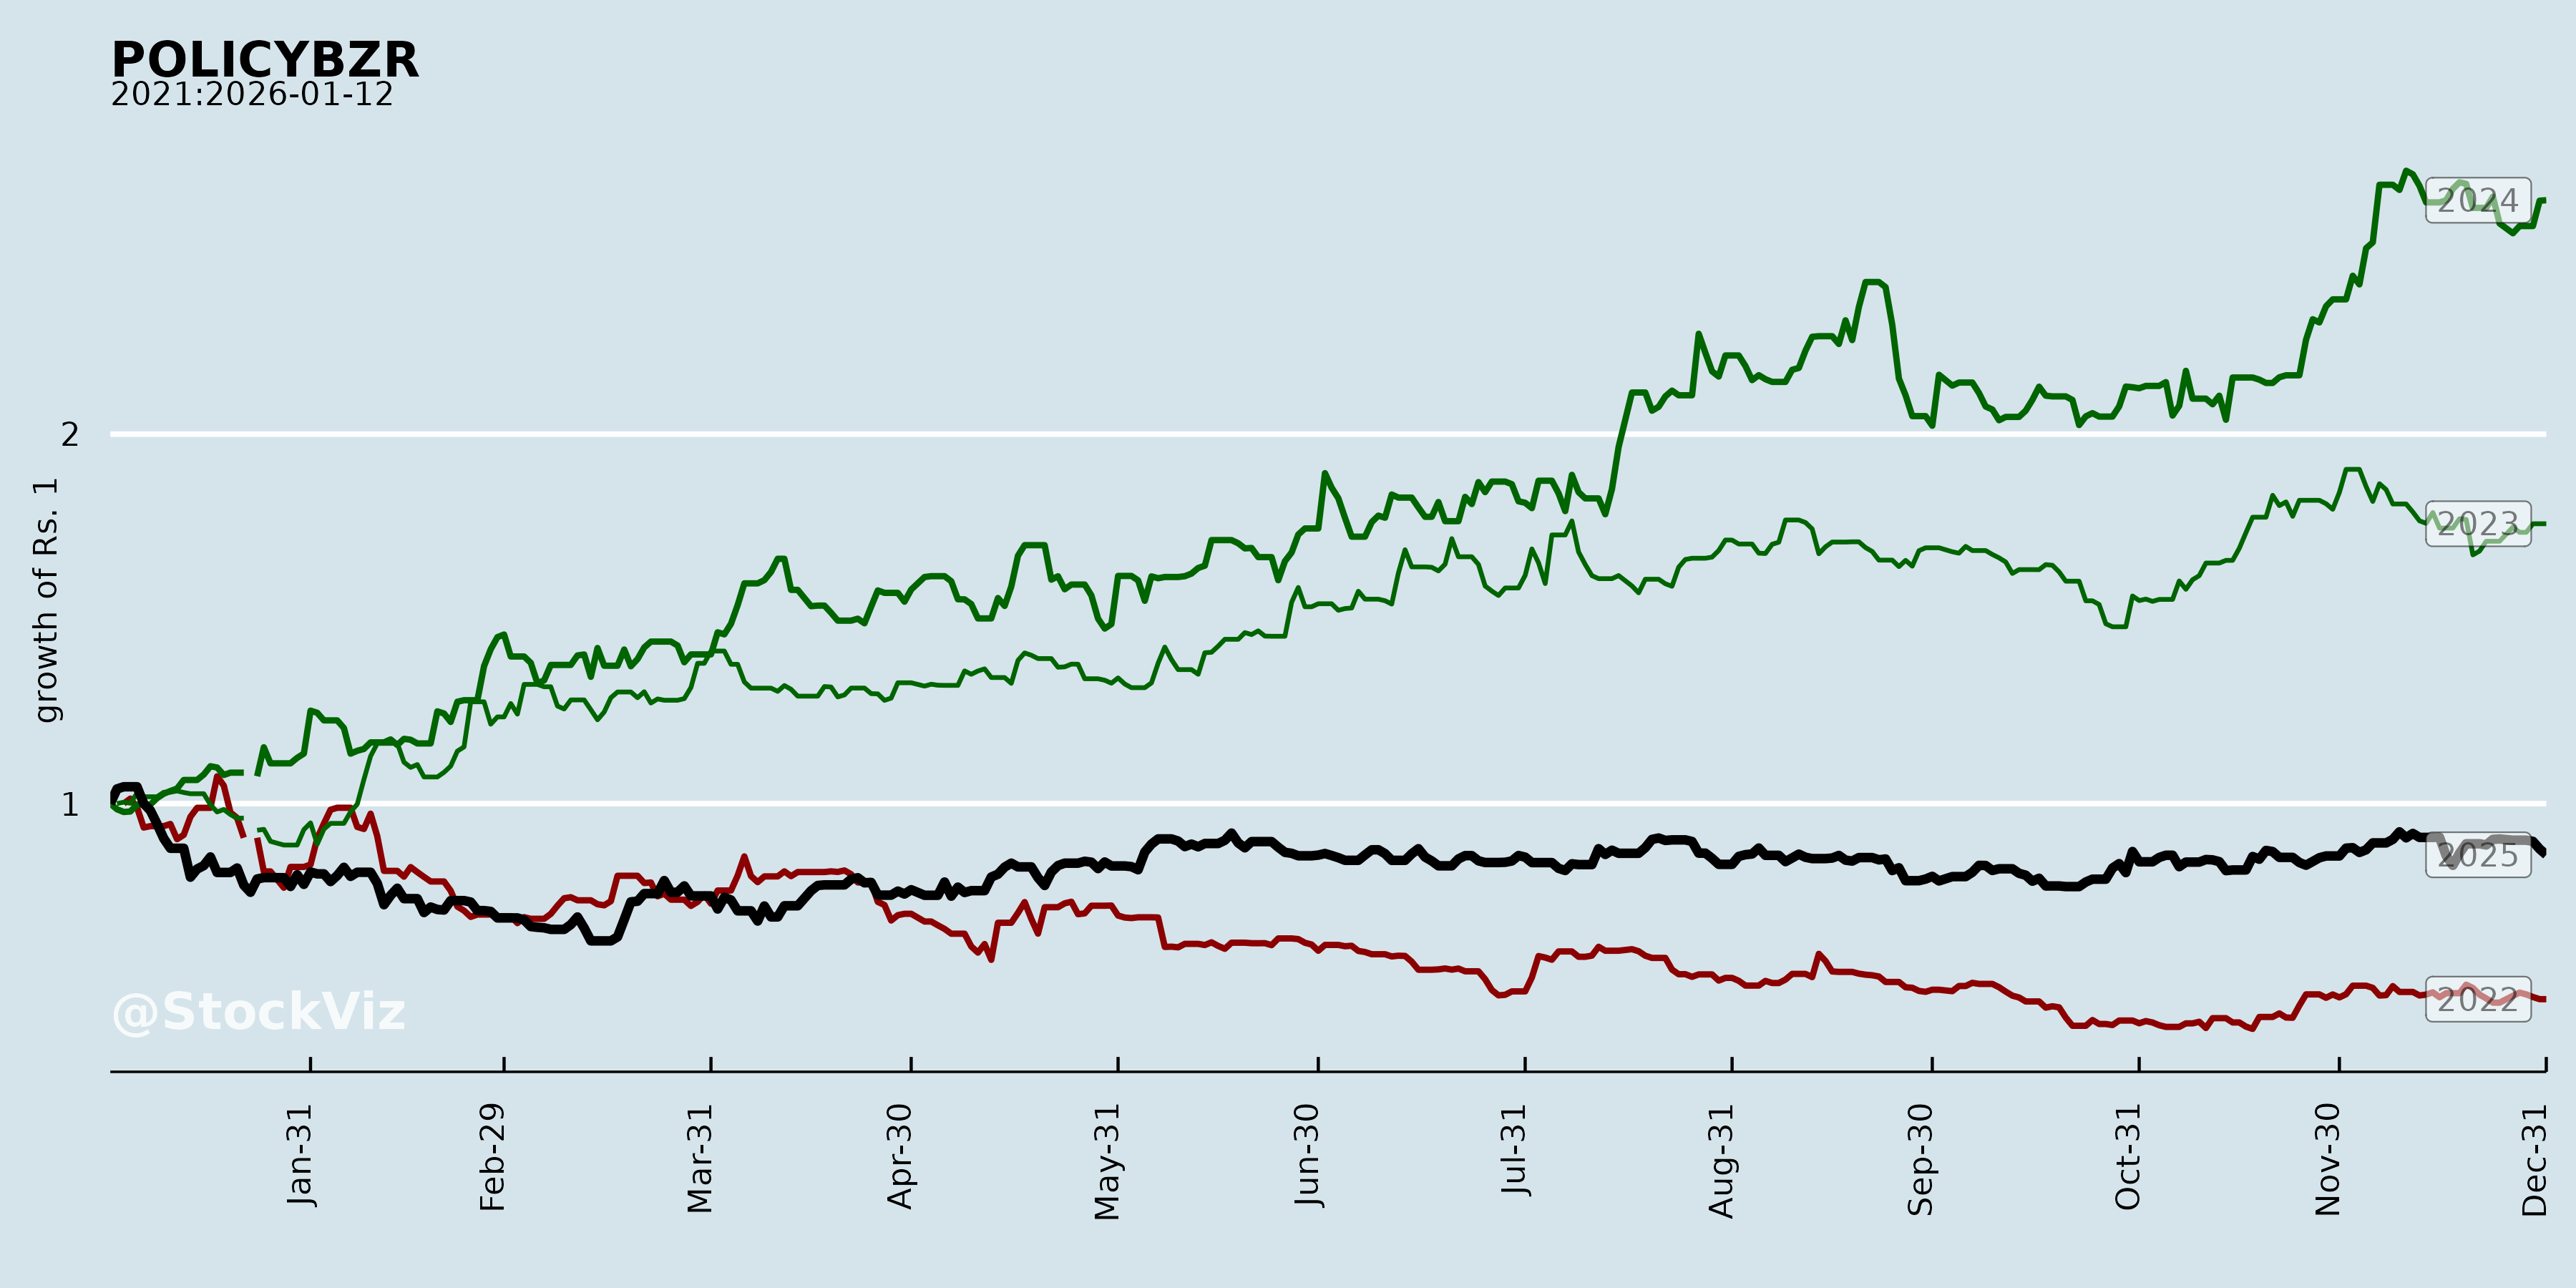
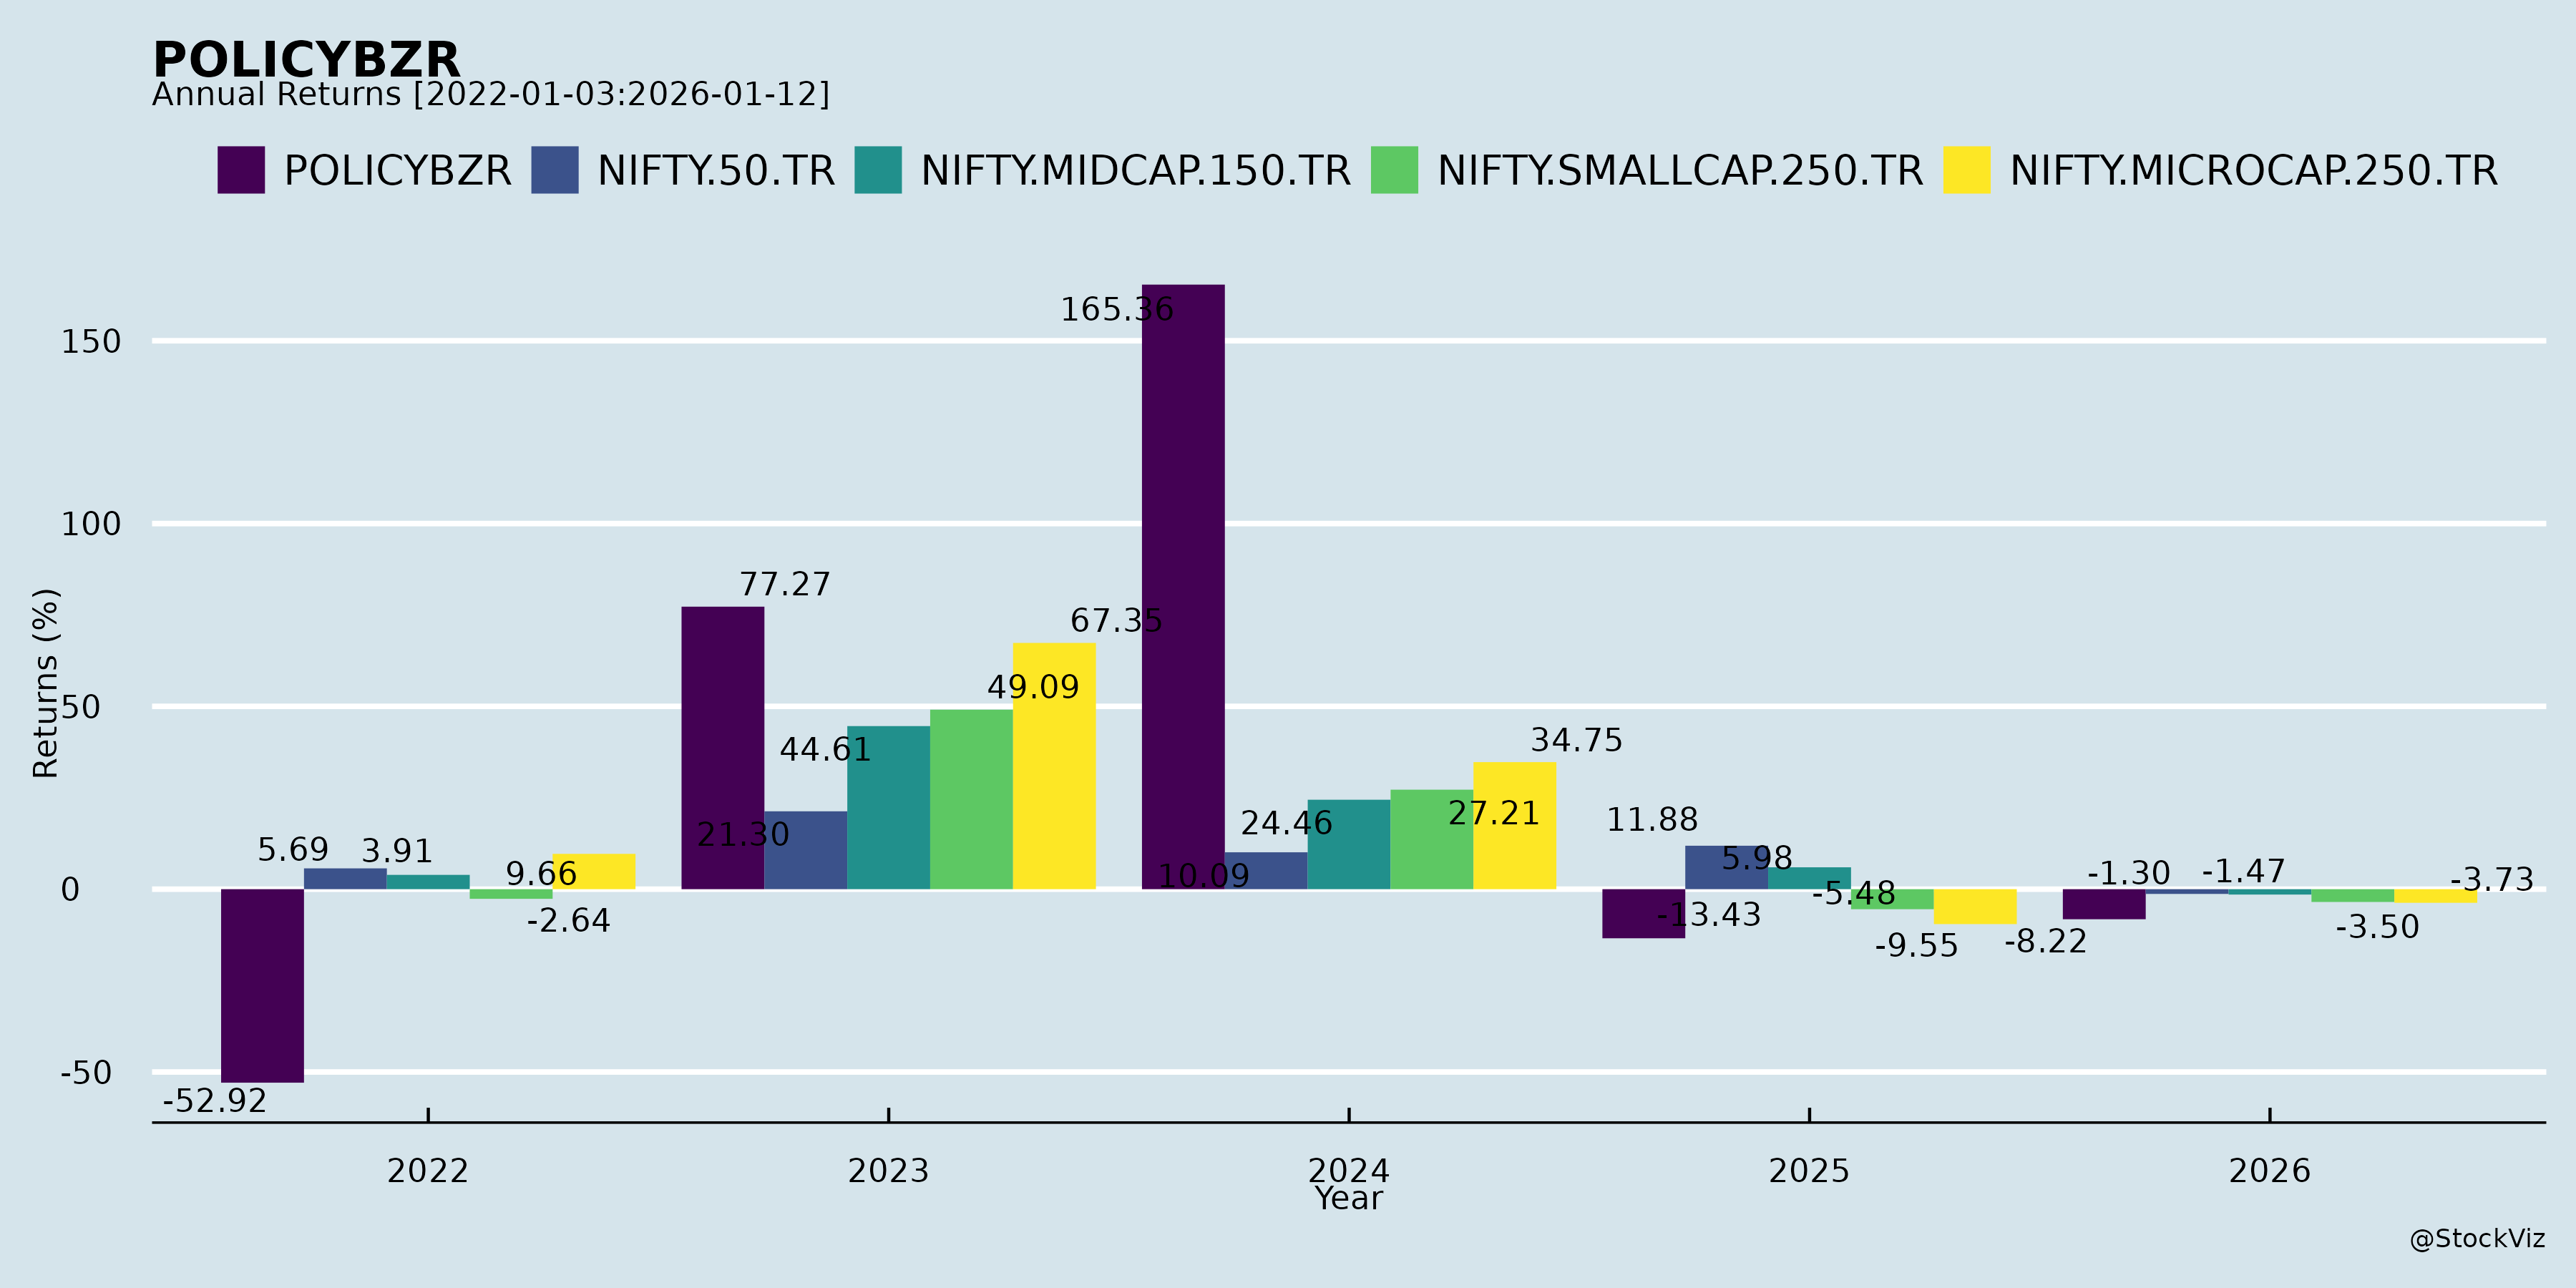
Annual Returns
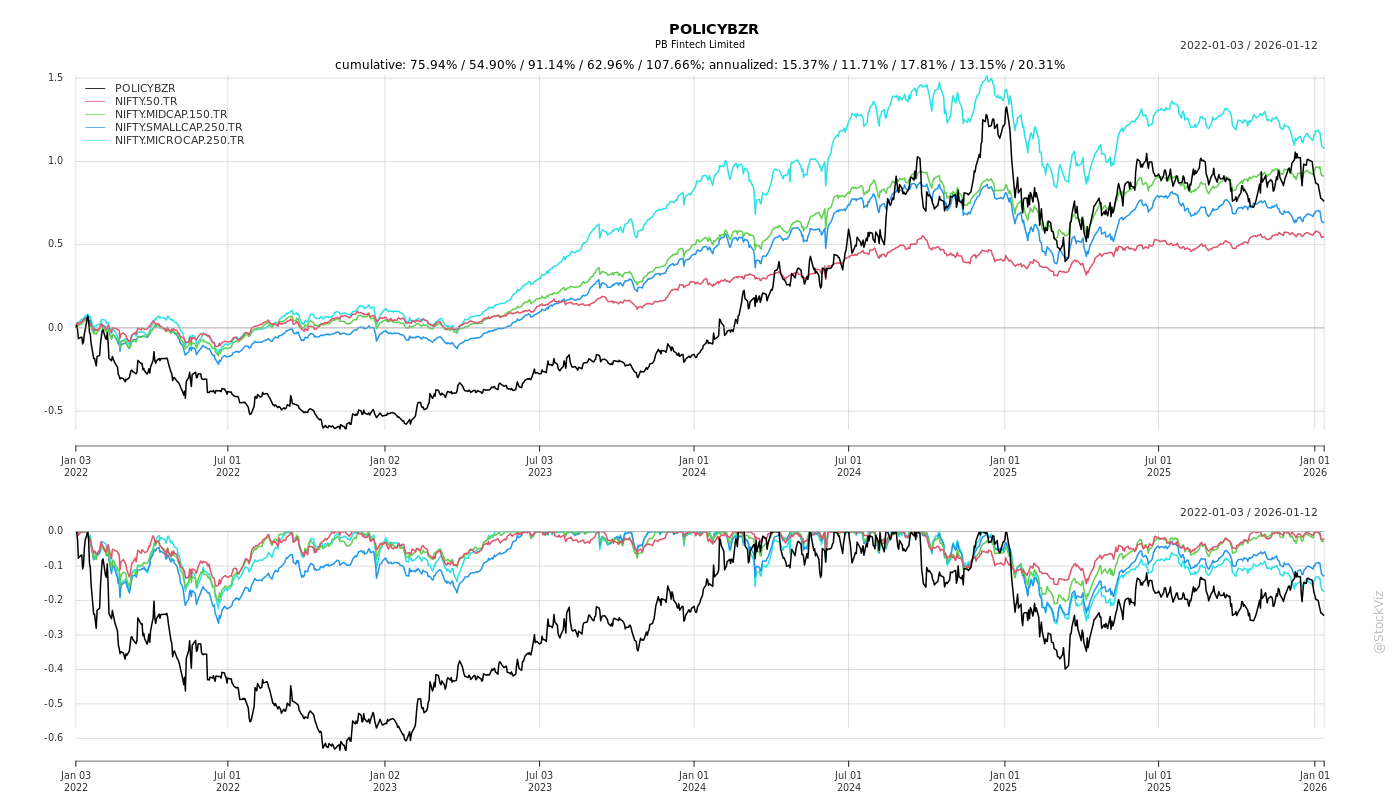
Cumulative Returns and Drawdowns

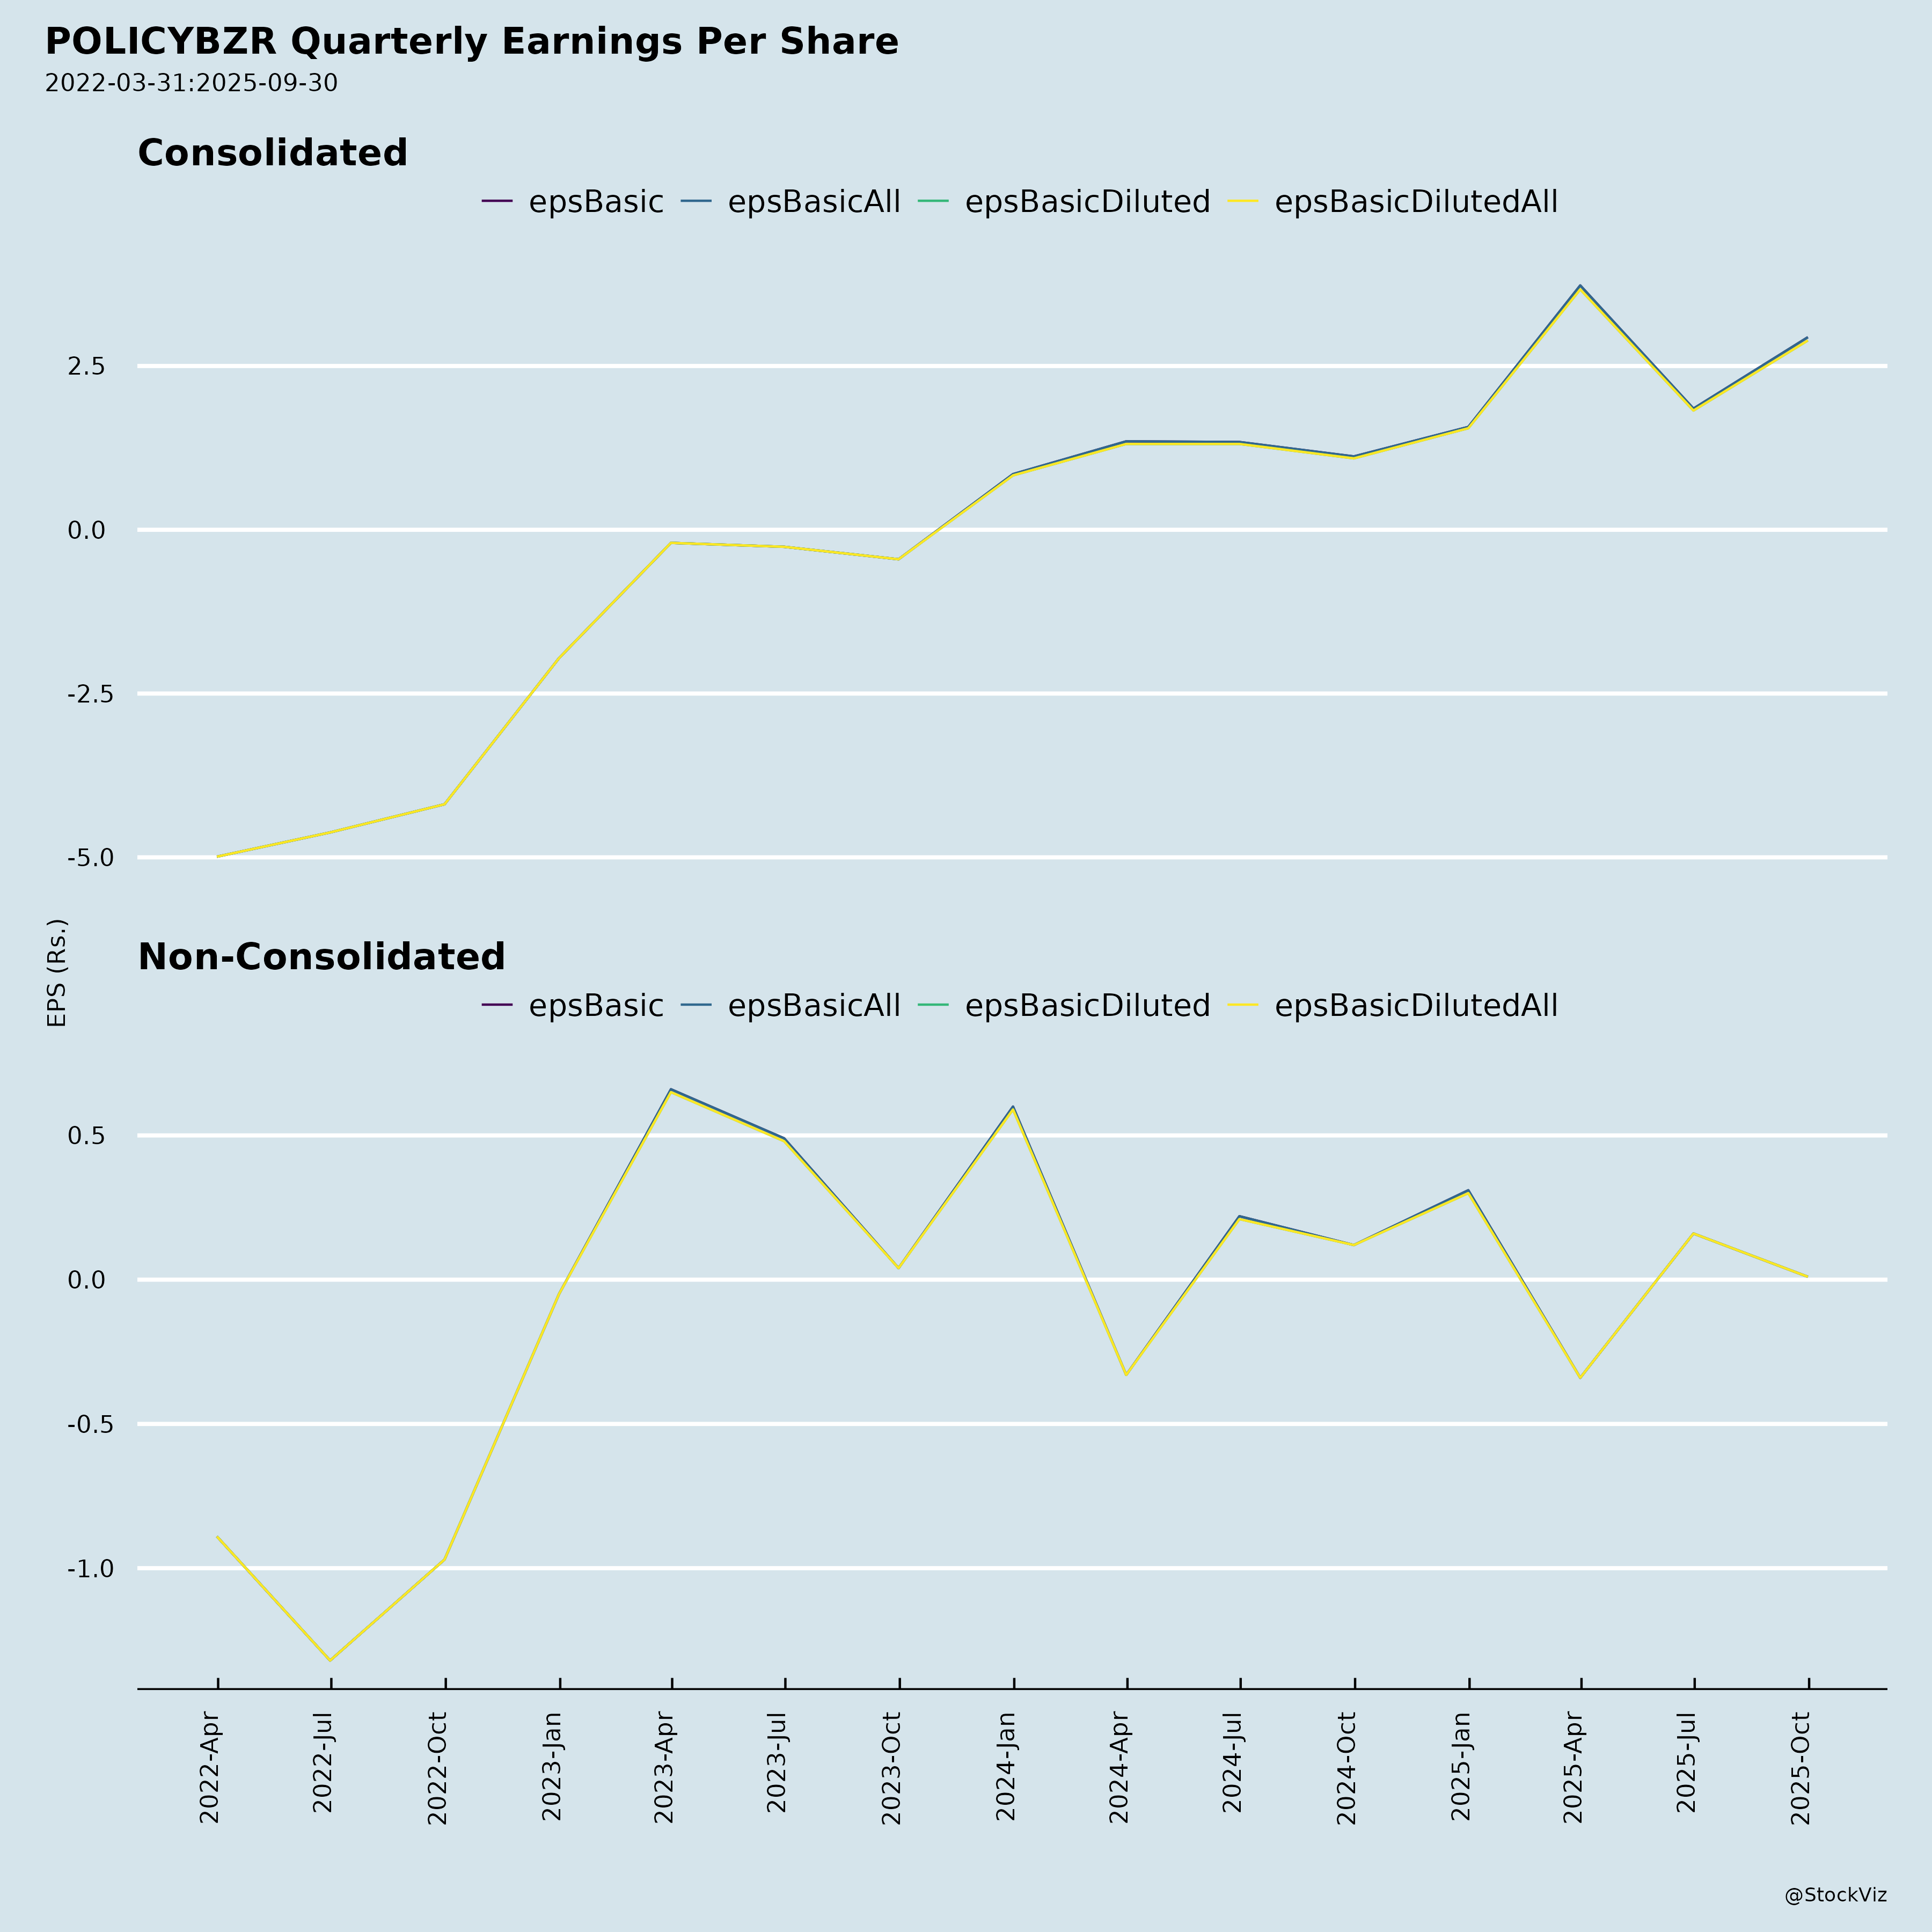
Fundamentals
Ownership
Margined
AI Summary
asof: 2026-09-16
PB Fintech (POLICYBZR) — Recent Corporate Announcements: Summary
1. Headwinds and Challenges
- Regulatory and compliance exposure: The company operates under regulatory uncertainty and compliance requirements across its jurisdictions, including orders and penalties from bodies such as IRDAI.
- Cybersecurity and data privacy: It handles large volumes of customer information, exposing it to cybersecurity and data privacy threats.
- Competitive pressure: The digital financial services and insurance aggregation sectors are competitive.
- Operational fraud risk: Historical employee–vendor kickback instances have been identified in subsidiaries.
- Macroeconomic sensitivity: External factors such as disposable incomes, interest rates, and insurance/credit demand can affect the business.
- Credit card issuance remains subdued: Within Paisabazaar, core disbursal growth is led by unsecured credit while cards remain subdued, and new initiatives are pivoting to retail.
- New Initiatives still loss-making at EBITDA level: For Q1FY27, New Initiatives reported Adjusted EBITDA of negative ₹36 Cr (negative 5% margin), though this improved from negative 6% a year earlier.
- PB Connect re-strategizing: The company is re-strategizing PB Connect within its lending disbursal operations.
- Savings-linked growth drag: Core New Insurance Premium including Savings grew 39% YoY in Q1FY27, below the 48% growth excluding Savings, indicating the Savings category dilutes overall new premium growth.
- Governance transition: Ms. Lilian Jessie Paul completed her first term as a Non-Executive Independent Director on June 18, 2026, requiring reconstitution of the CSR and Stakeholders Relationship Committees effective August 05, 2026.
2. Tailwinds and Growth Prospects
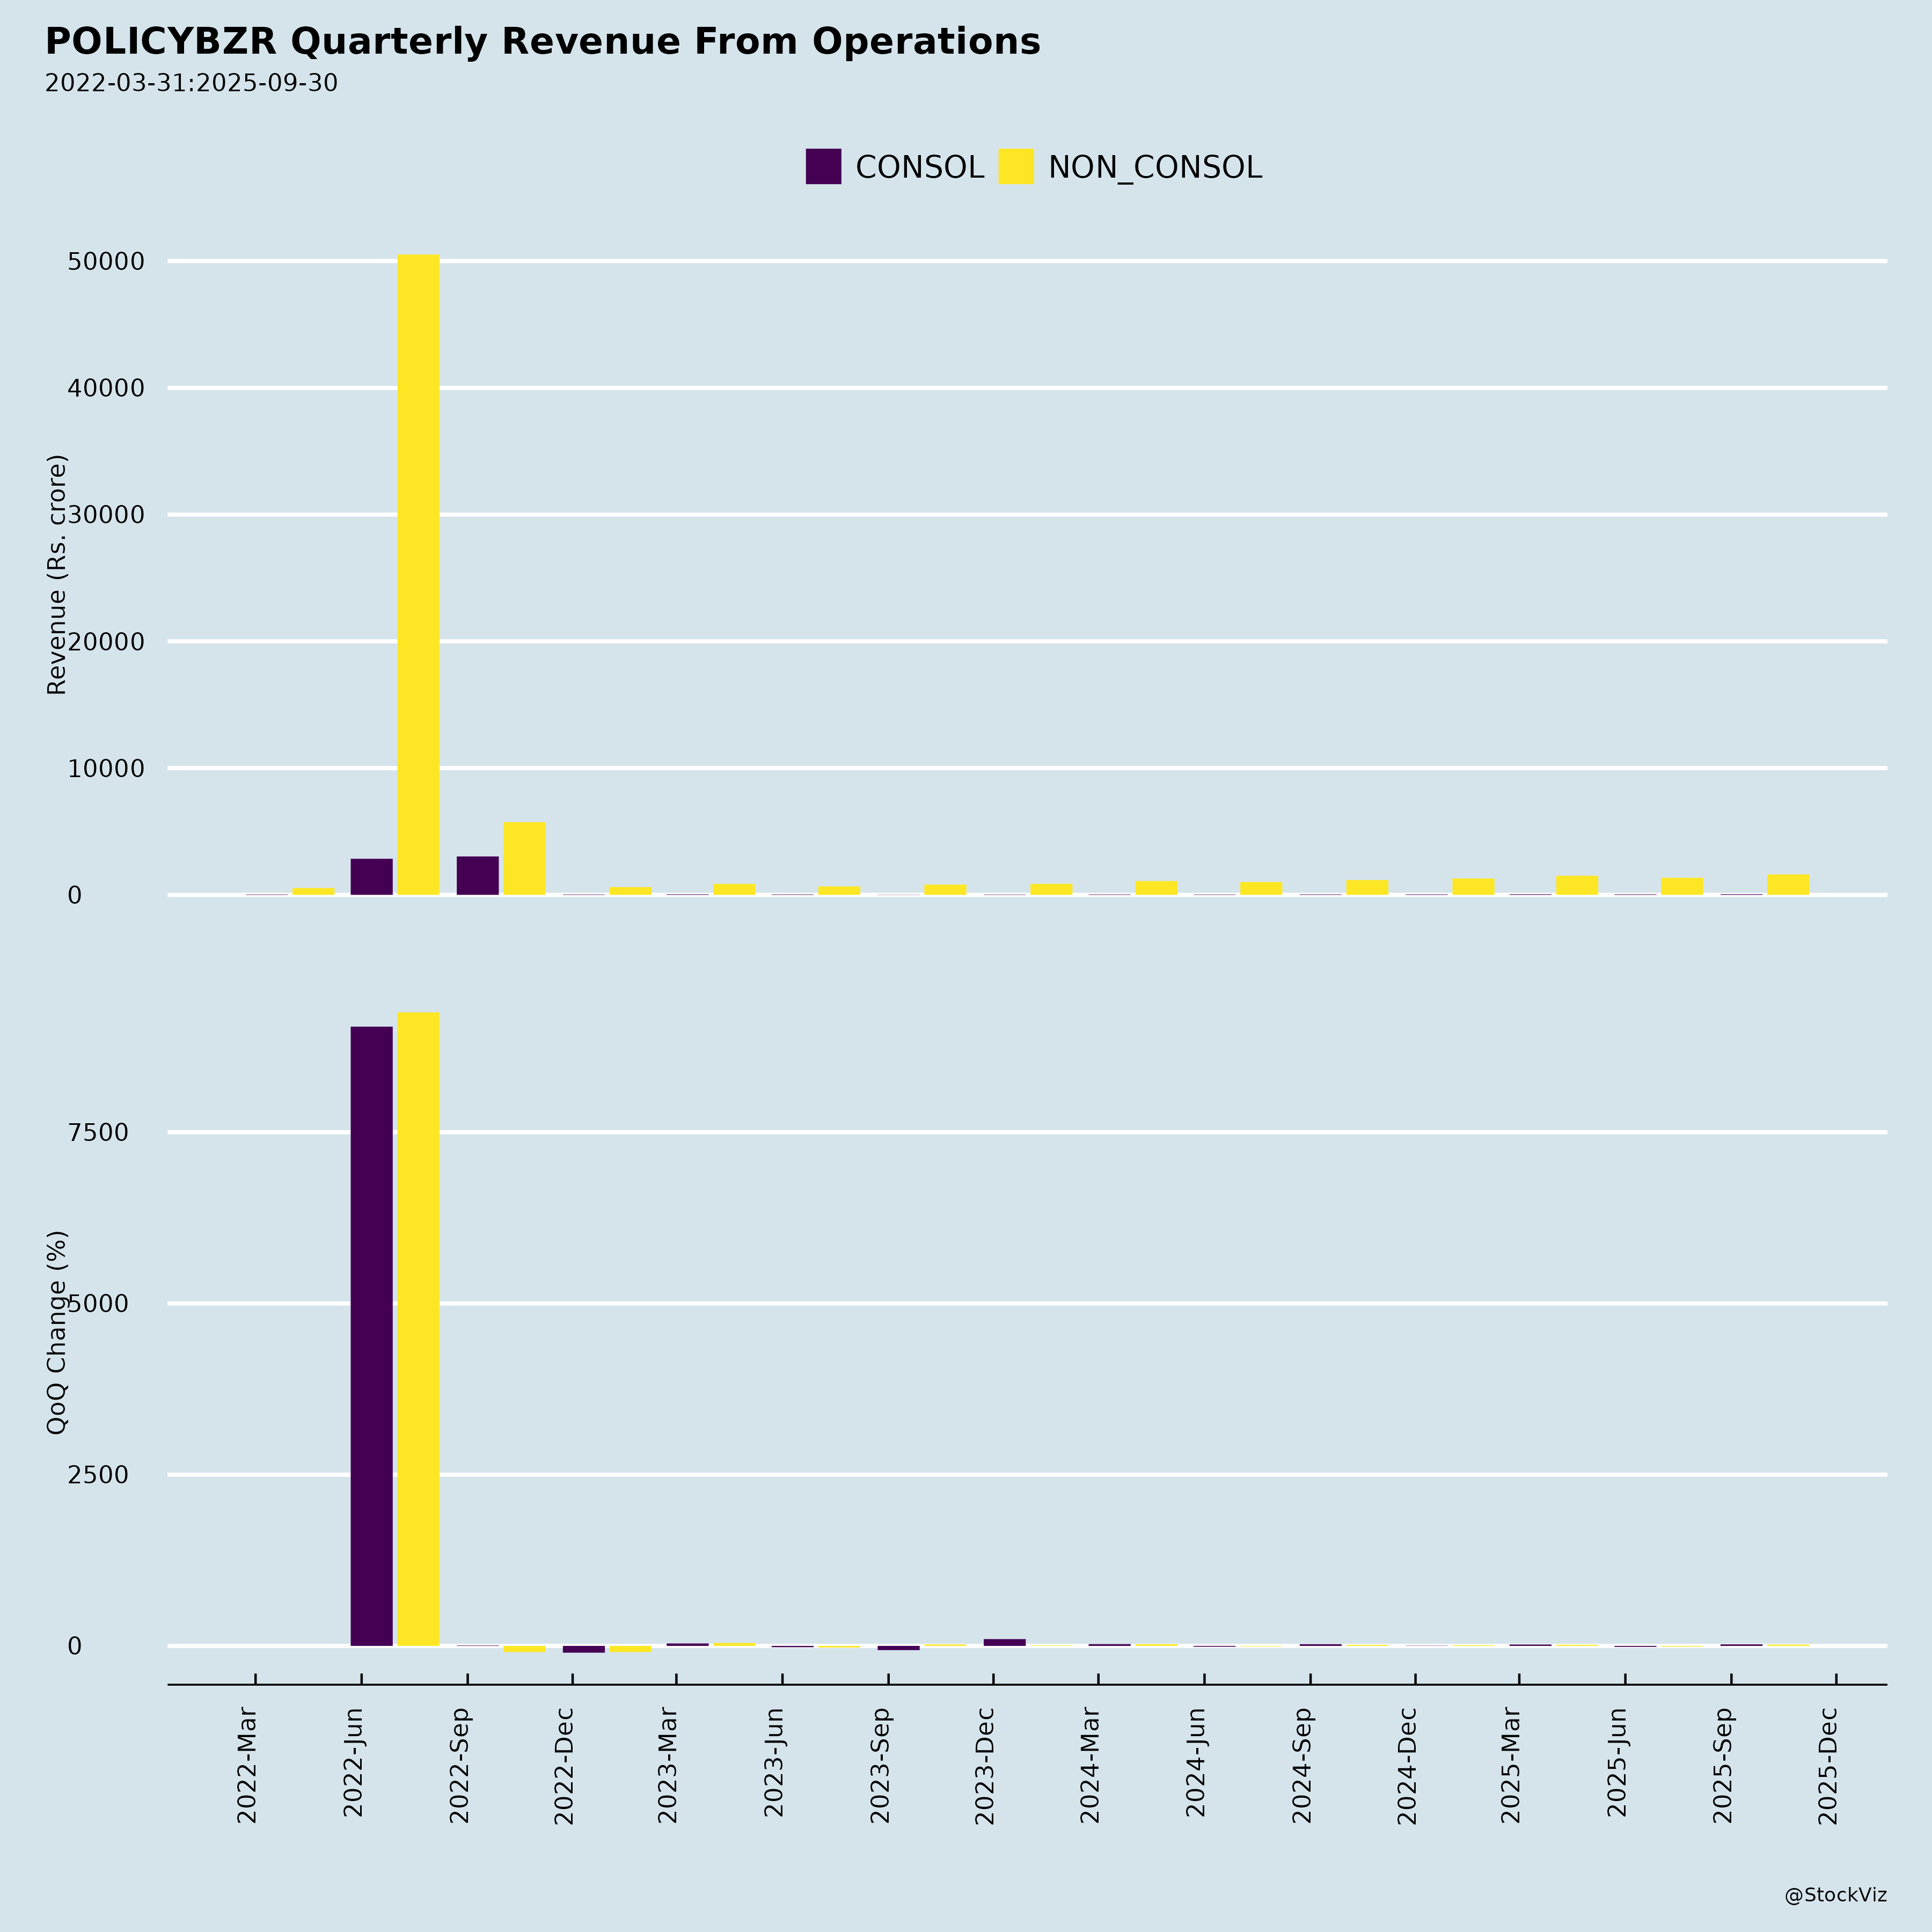
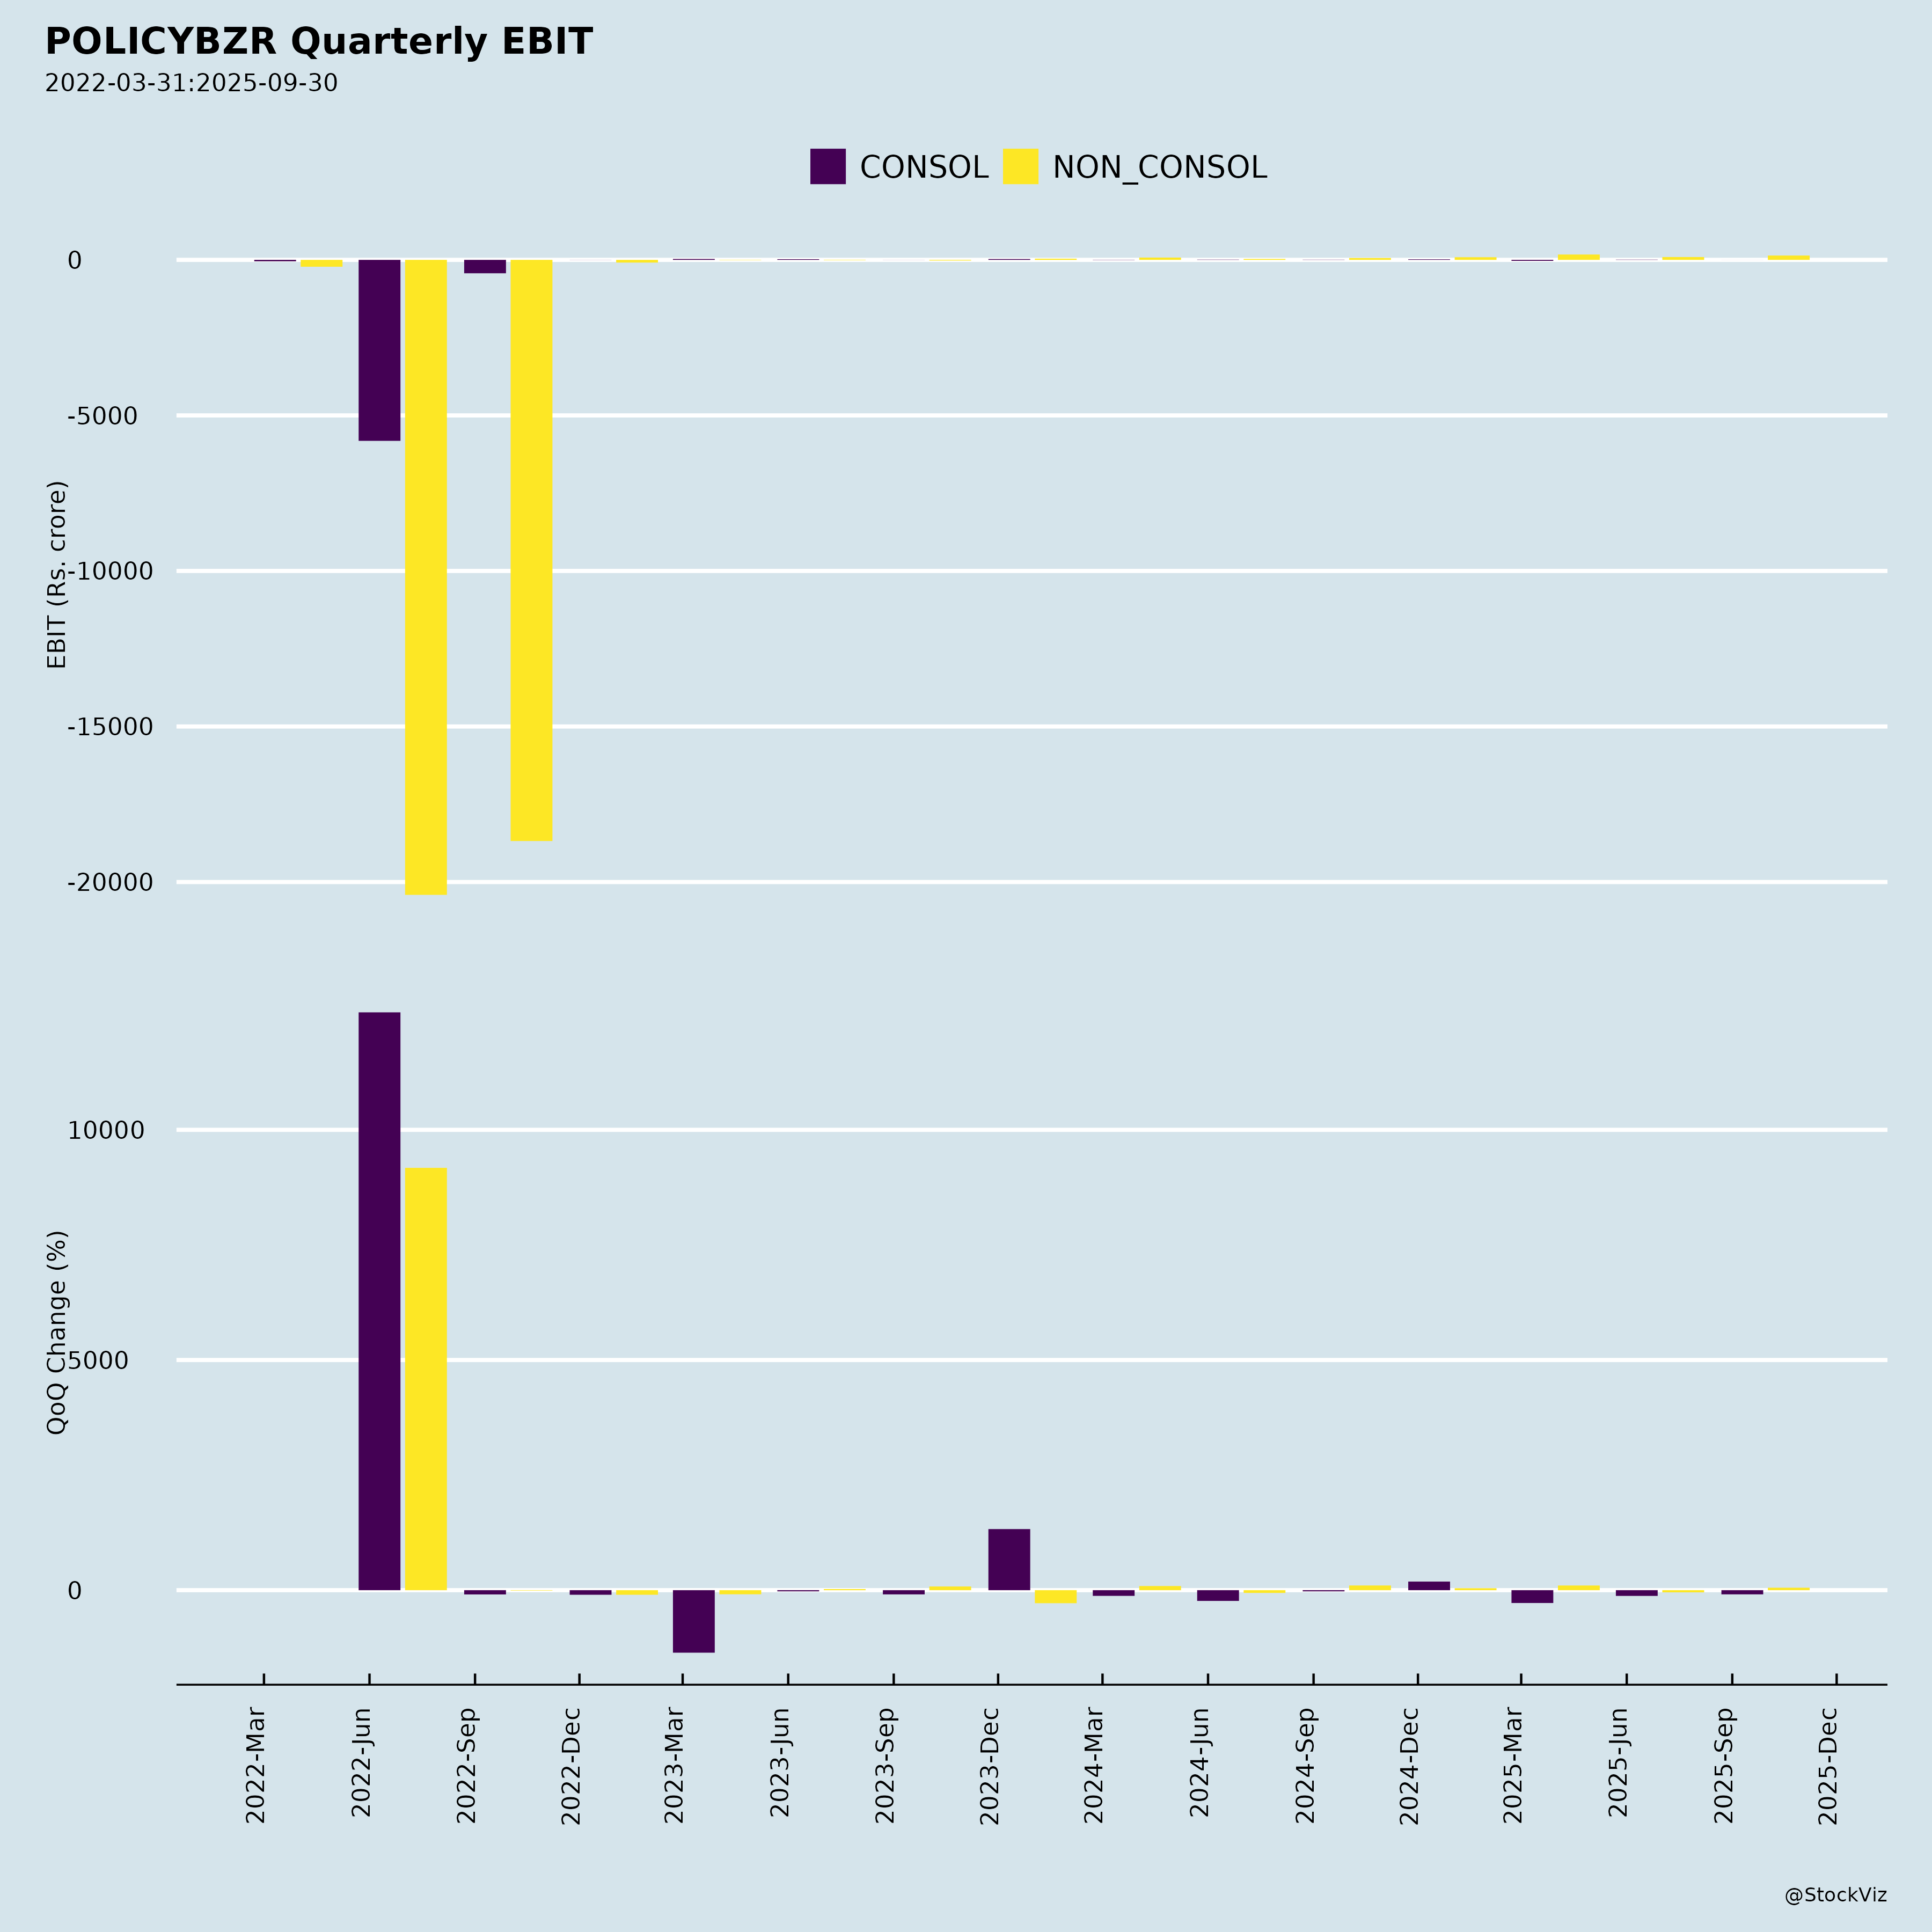
- Q1FY27 performance (quarter ended June 30, 2026): Total Insurance Premium grew 41% YoY to ₹8,372 Cr; new protection (Health + Term) premium grew 53% YoY; operating revenue grew 40% YoY to ₹1,888 Cr; PAT grew 92% YoY to ₹163 Cr with PAT margin rising from 6% to 9%.
- Renewal/trail revenue annuity: Core renewal/trail revenue on a 12-month rolling basis reached ₹1,003 Cr, up from ₹725 Cr a year earlier (38% growth), with the insurance segment growing 55% YoY; quarterly core insurance renewal revenue is at an ARR of ₹999 Cr, up 48% YoY. Management describes this as a key driver of long-term profit growth.
- Consistent core new business growth: Core New Insurance Premium (excluding Savings) has grown above 34% YoY for 13 consecutive quarters; Q1FY27 growth was 48% YoY.
- Credit business momentum: Core credit revenue was ₹127 Cr, up 25% YoY, with core disbursal at ₹2,776 Cr, up 33% YoY; both have grown for four consecutive quarters.
- PB Partners scale-up: 500k+ registered advisors, active partners at 1.13 lacs (up 55% YoY), presence in ~19k pin codes covering 99% of India’s pin codes; Q1FY27 premium grew 46% YoY to ₹1,637 Cr (ex-GST) and revenue grew 47% to ₹561 Cr; Tier 2 and Tier 3 markets contributed 78% of GWP.
- UAE business: Q1FY27 insurance premium grew 31% YoY, with a mix shifting toward health and life; the business was profitable in FY26 and remained profitable in Q1FY27.
- India macro and structural opportunity: Growing middle class, favorable demographics (median age ~29 years), rising digital penetration (UPI, Aadhaar, Account Aggregator, DigiLocker, e-KYC, BBPS), and significant under-penetration in life insurance, general insurance, retail lending, and credit cards relative to global benchmarks.
- Regulatory tailwinds: The Sabka Bima Sabki Raksha Act and GST exemptions on life and health insurance premiums are cited as growth drivers.
- AI-driven operating leverage: AI is embedded across sales, service, risk, and claims — including 100% call transcription across 9 Indian languages, ~10 crore monthly customer interactions, and reported +20% advisor conversion improvement and +10% average ticket size uplift.
- New verticals: Expansion into pension solutions (Pensionbazaar), motor ownership journeys (PB Wheels), reinsurance broking, payments/account aggregation, bonds, FDs, and mutual funds (daily SIP platform launching August 2026).
- Financial strength: Asset-light, debt-free model with cash and investments of ₹5,109 crore; FY2025-26 consolidated revenue from operations of ₹6,794 crore (up 37% YoY), Adjusted EBITDA of ₹725 crore, PAT of ₹670 crore, total insurance premium of ₹29,934 crore (up 42%), and Paisabazaar credit disbursals of ₹30,740 crore.
3. Key Risks
- Regulatory actions, orders, and penalties (including from IRDAI) across operating jurisdictions.
- Cybersecurity breaches and data privacy incidents involving large customer data volumes.
- Competitive intensity in digital financial services and insurance aggregation.
- Operational fraud, including historical employee–vendor kickback instances in subsidiaries.
- Macroeconomic pressures on disposable incomes, interest rates, and demand for insurance and credit.
- Execution risk in scaling loss-making New Initiatives and in re-strategizing PB Connect.
- Dependence on renewal/trail revenue economics and continued growth in protection and credit segments.
4. Management Guidance Versus Observed Business Performance
- Growth trajectory: Management highlights that revenue grew at a 51% CAGR from ₹238 Cr in Q1FY22 to ₹1,888 Cr in Q1FY27, and PAT margin improved from -47% in Q1FY22 to 9% in Q1FY27 — consistent with the stated long-term profit growth thesis anchored on renewal revenue.
- Core new business: Management states core new insurance premium (excluding Savings) has grown above 34% YoY for 13 consecutive quarters; Q1FY27 delivered 48% YoY, matching this claim.
- Renewal revenue: Management describes renewal/trail revenue as a key long-term profit driver; observed 12-month rolling renewal revenue rose to ₹1,003 Cr (38% YoY), with insurance renewal revenue up 55% YoY.
- New Initiatives efficiency: Management notes quarterly adjusted EBITDA margin improved from -6% to -5% YoY with 7% contribution margin; observed Q1FY27 New Initiatives Adjusted EBITDA was negative ₹36 Cr (negative 5% margin) versus negative ₹31 Cr (negative 6%) in Q1FY26.
- Credit business: Management states core credit disbursal and revenue are growing for the last four consecutive quarters; observed Q1FY27 core credit revenue of ₹127 Cr (up 25% YoY) and core disbursal of ₹2,776 Cr (up 33% YoY).
- UAE profitability: Management states the UAE business was profitable in FY26 and remains profitable in Q1FY27; observed Q1FY27 UAE premium growth of 31% YoY.
- Forward-looking strategy — “Evolution by Design”: Management’s stated focus is transitioning from a transaction-led platform to a lifecycle ecosystem, maintaining underwriting and risk discipline over short-term volume growth, scaling new verticals (pension, PB Wheels, reinsurance broking, payments/account aggregation), and embedding AI across discovery, risk, service, and claims.
- Investor communications: Management will attend the Jefferies India Forum 2026 on September 16, 2026, in Gurugram at 10:00 A.M. IST, with no unpublished price sensitive information to be shared. The 18th AGM will be held on Monday, September 28, 2026, at 11:00 A.M. IST via video conference/audio-visual means; shareholders with unregistered email addresses as of August 28, 2026 are being notified physically to access the AGM notice and FY 2025-26 Annual Report online.
Broker Narrative
The narrative evolved from micro-level operational anxieties—new initiative losses, take rate drops, savings softness, and sequential contraction—toward macro-level regulatory threats, specifically commission compression hitting core online insurance revenue by 30%. Early tailwinds like robust core growth and high-margin renewal compounding were later overshadowed by regulatory headwinds, while optimism shifted to cost savings and new revenue streams. The arc moved from Add to Neutral as structural margin pressures replaced execution risks.
Fears that came true
- Valuation concerns (~40x FY27E multiple) materialized into sharp corrections, with actual returns reaching -47.4% and -36.8%.
- Increased new initiative losses (INR 150mn, -10.1% margin) aligned with sustained negative returns like -32.0% and -31.5%.
- Drop in new business take rates (30.5% vs 39%) preceded DISAPPOINTMENT outcomes for bullish calls, e.g., Buy +14.8% predicted vs -36.8% actual.
- Sequential business contraction (core -12% QoQ, PoSP decline) correlated with later losses such as -23.0% and -28.0%.
Optimism that failed
- Robust core growth (~30% YoY) failed as regulatory tightening delivered a 30% hit to FY28 core online insurance revenue.
- Core margin expansion (45.3%) was reversed by commission caps that compressed online insurance margins.
- High-margin renewal compounding (85% EBITDA margin) could not prevent the stock from falling 30-50% and the broker turning Neutral.
- Paisabazaar profitability (7% margin, 20% target) was overshadowed by the need for new revenue streams like services and reinsurance broking.
Broker Timeline
21 broker calls · 2023-08-09 to 2026-09-24
CNBC-TV18: ratings, targets and commentary
No recorded CNBC-TV18 statements for this ticker.
Management comments
No recorded management comments with an explicit designation and affiliation for this ticker.
Copyright © 2023 SAS Data Analytics Pvt. Ltd. All rights reserved.