PNB
Equity Metrics
October 23, 2026
Punjab National Bank
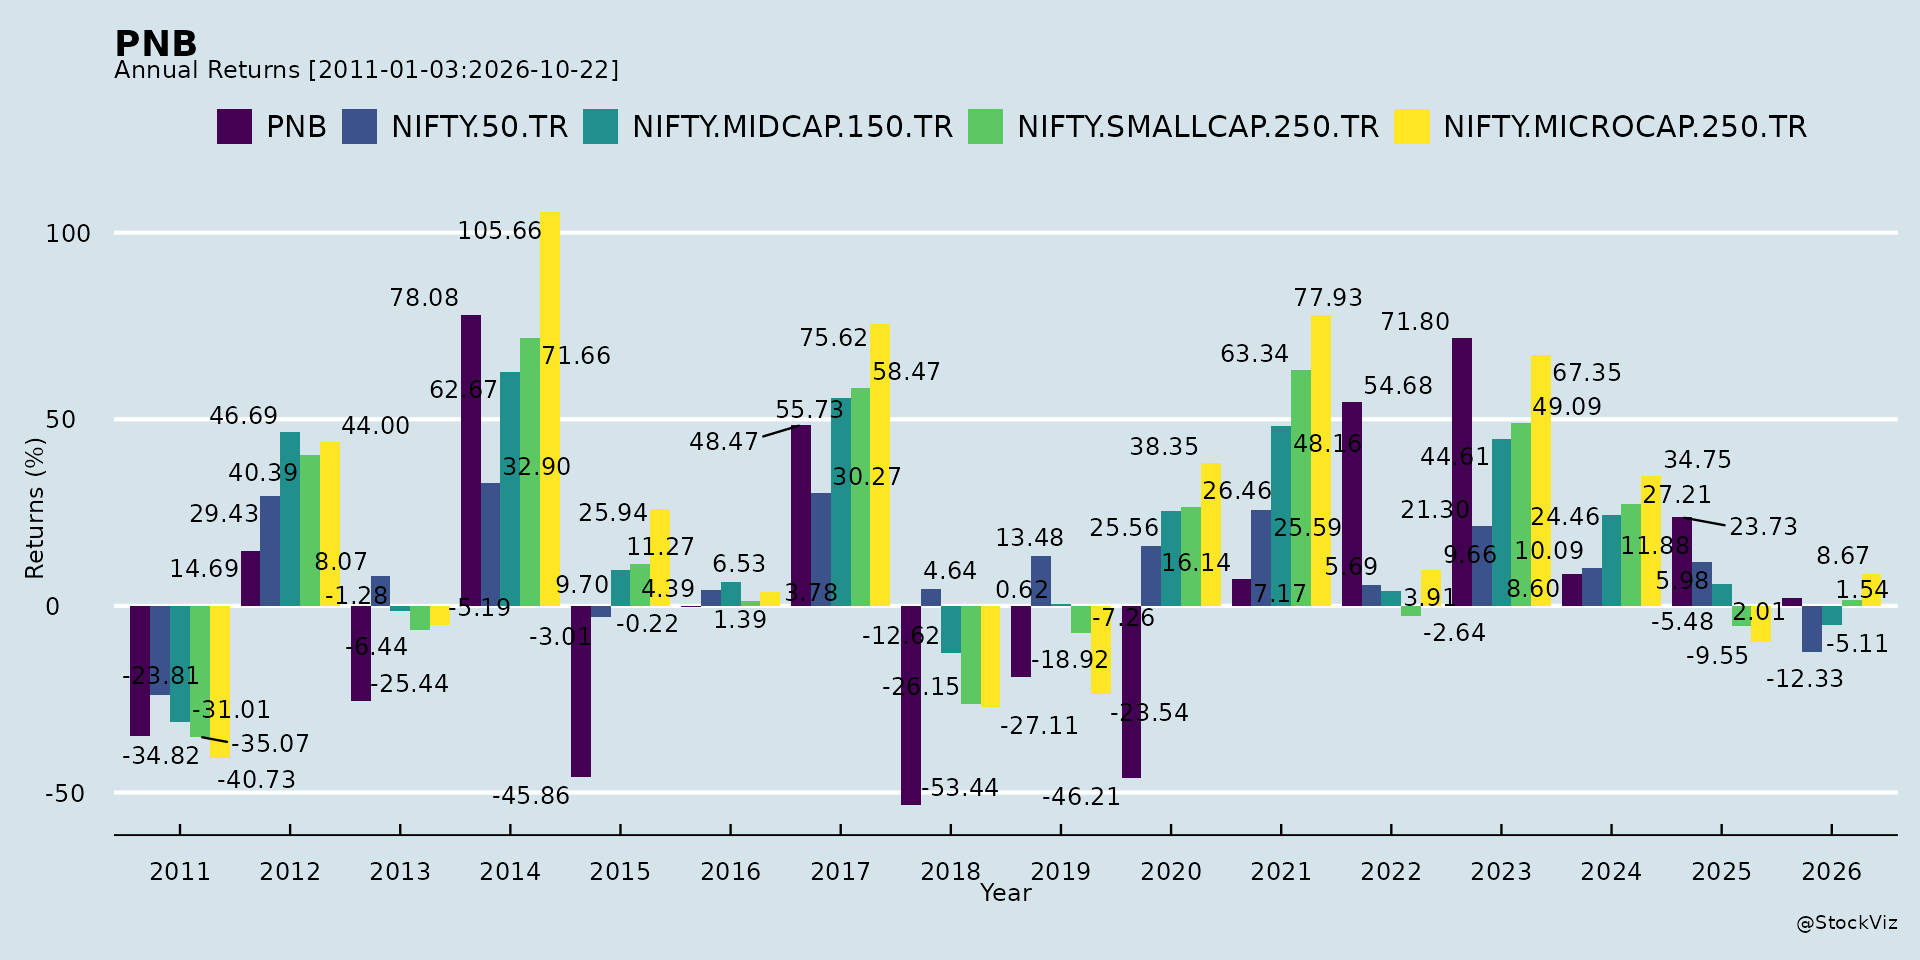
Annual Returns
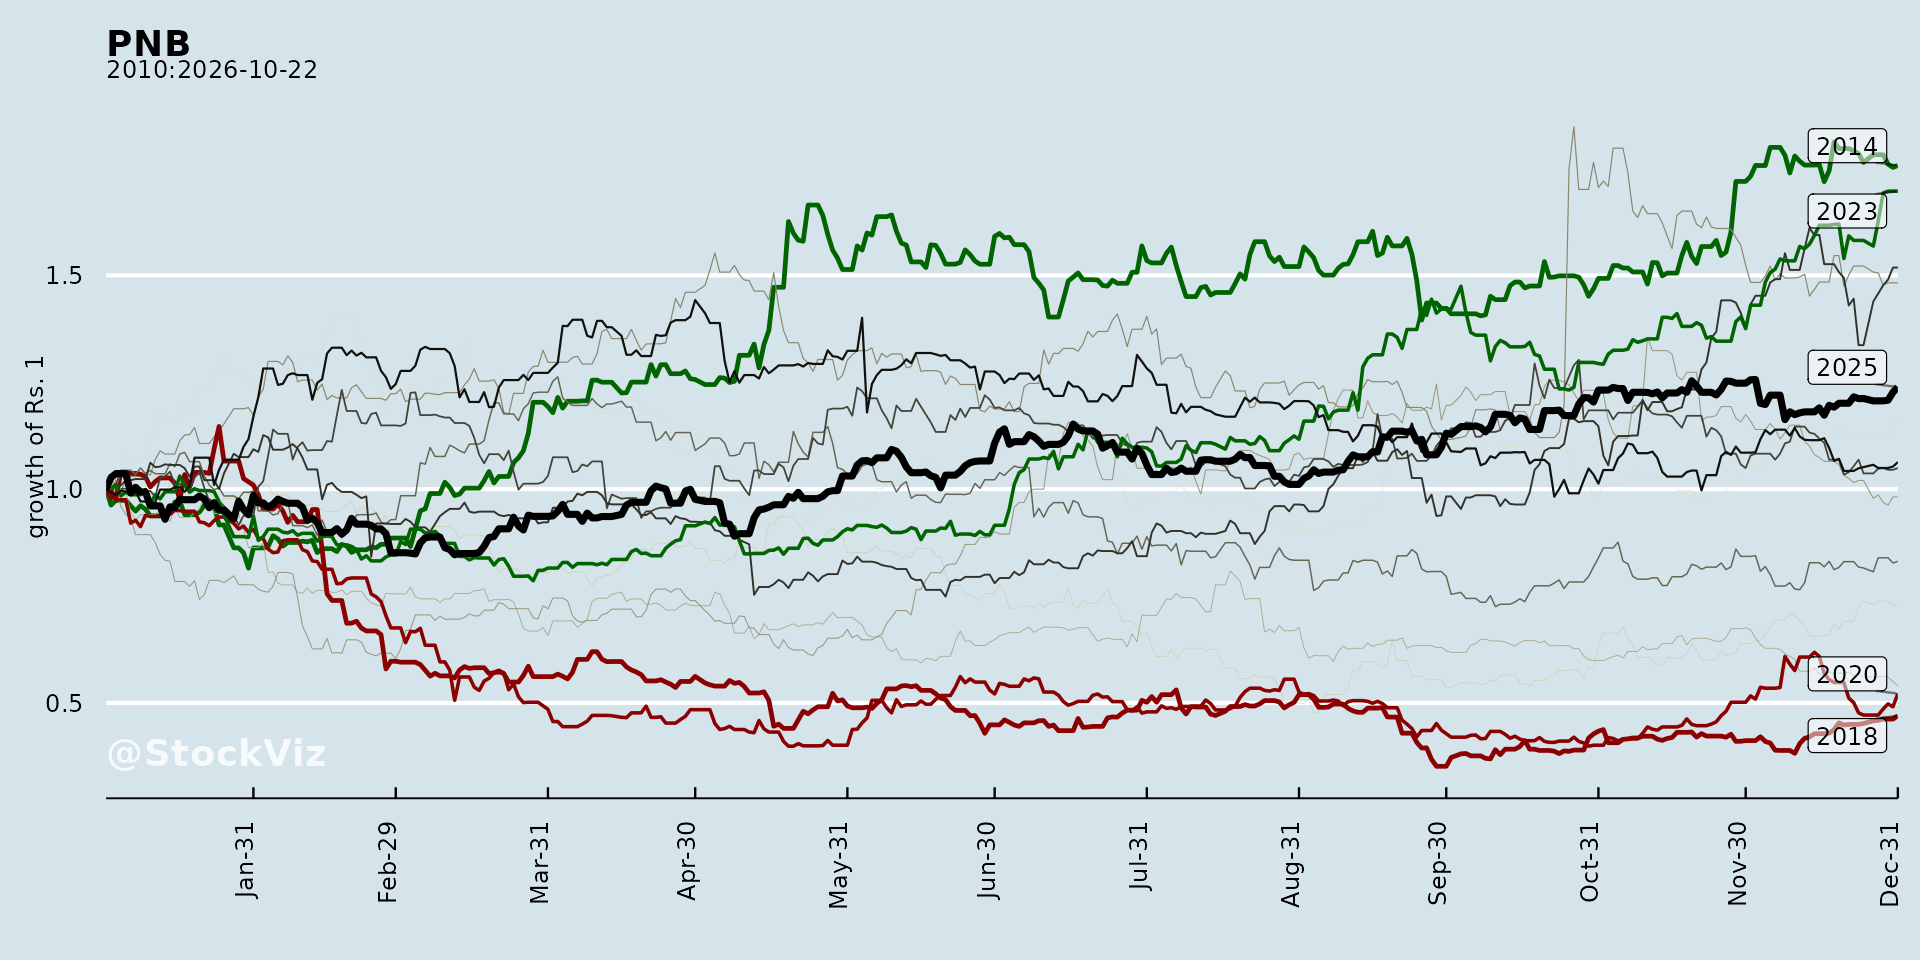
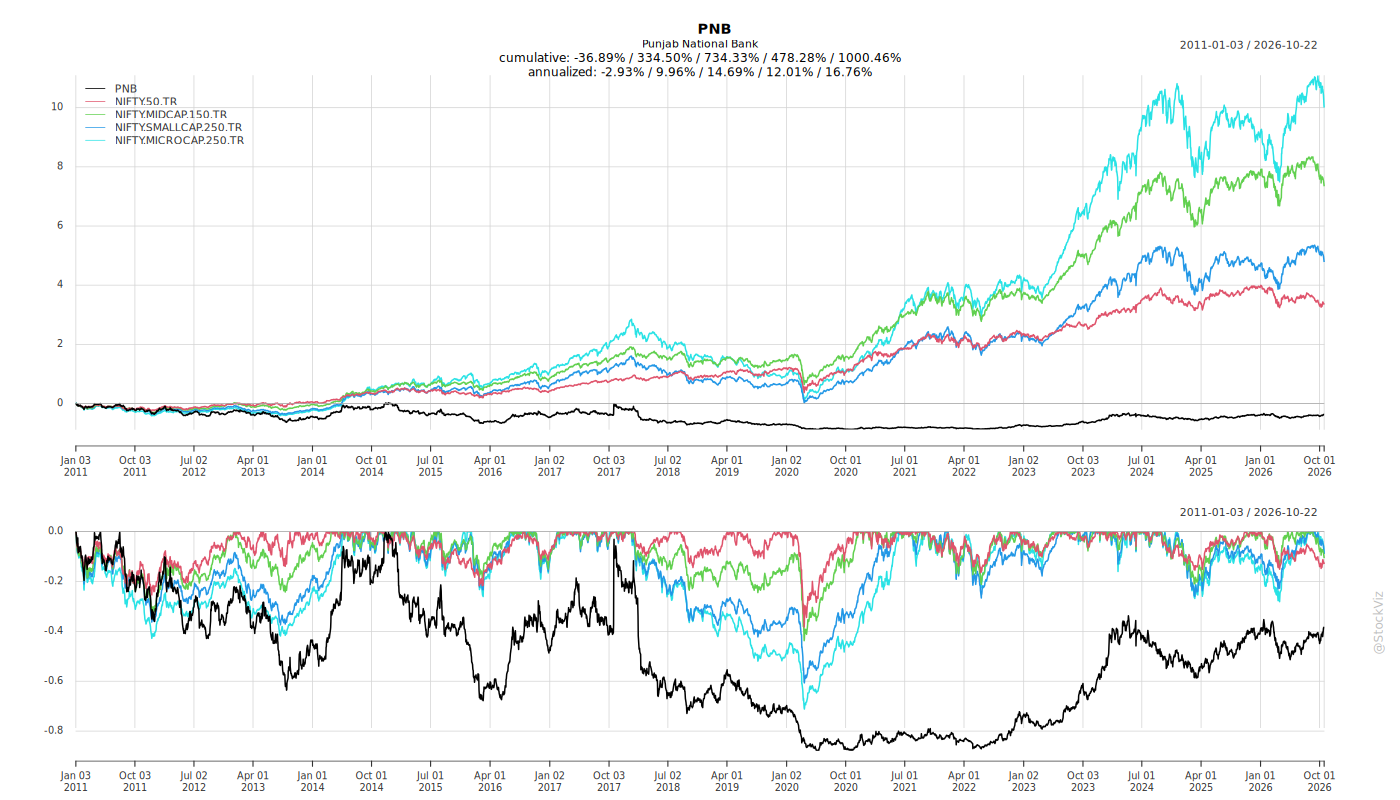
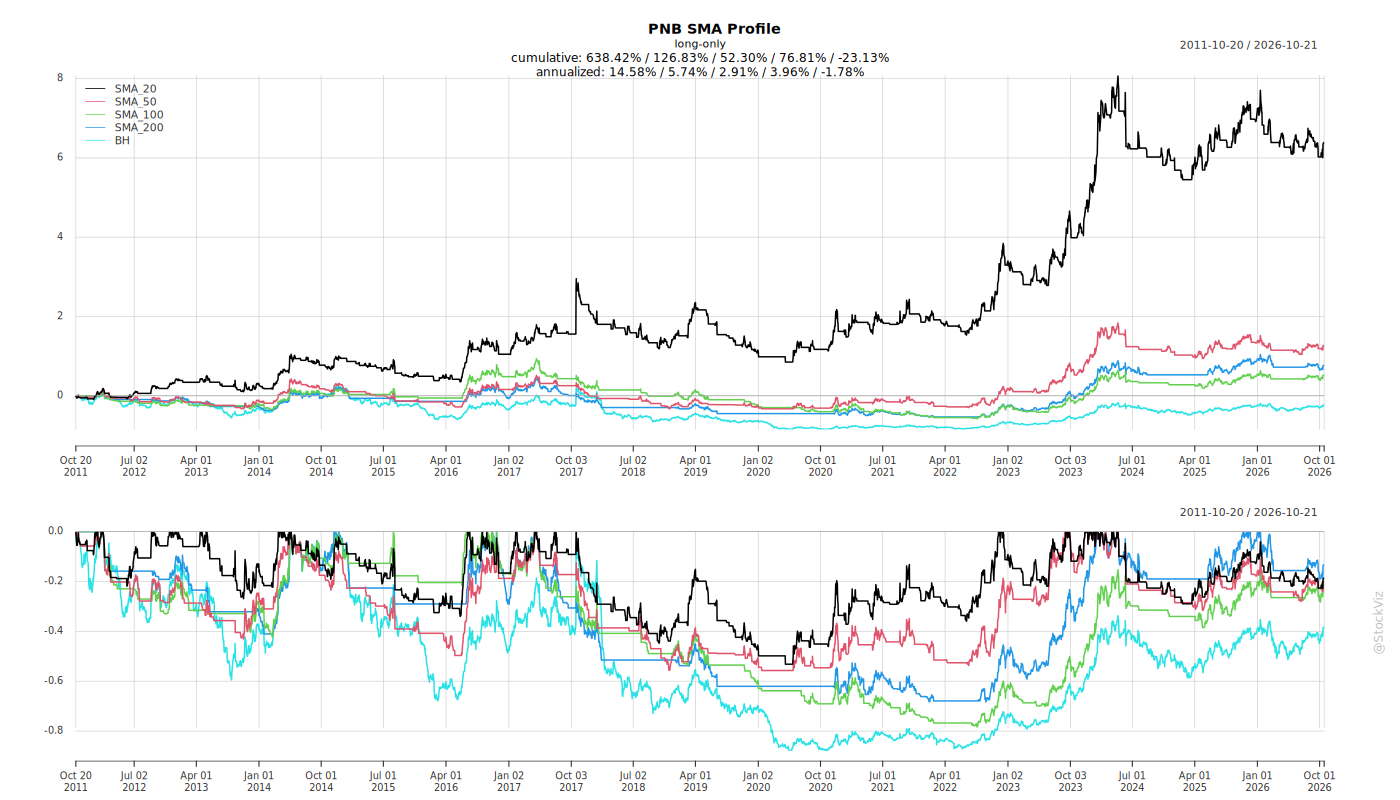
Cumulative Returns and Drawdowns
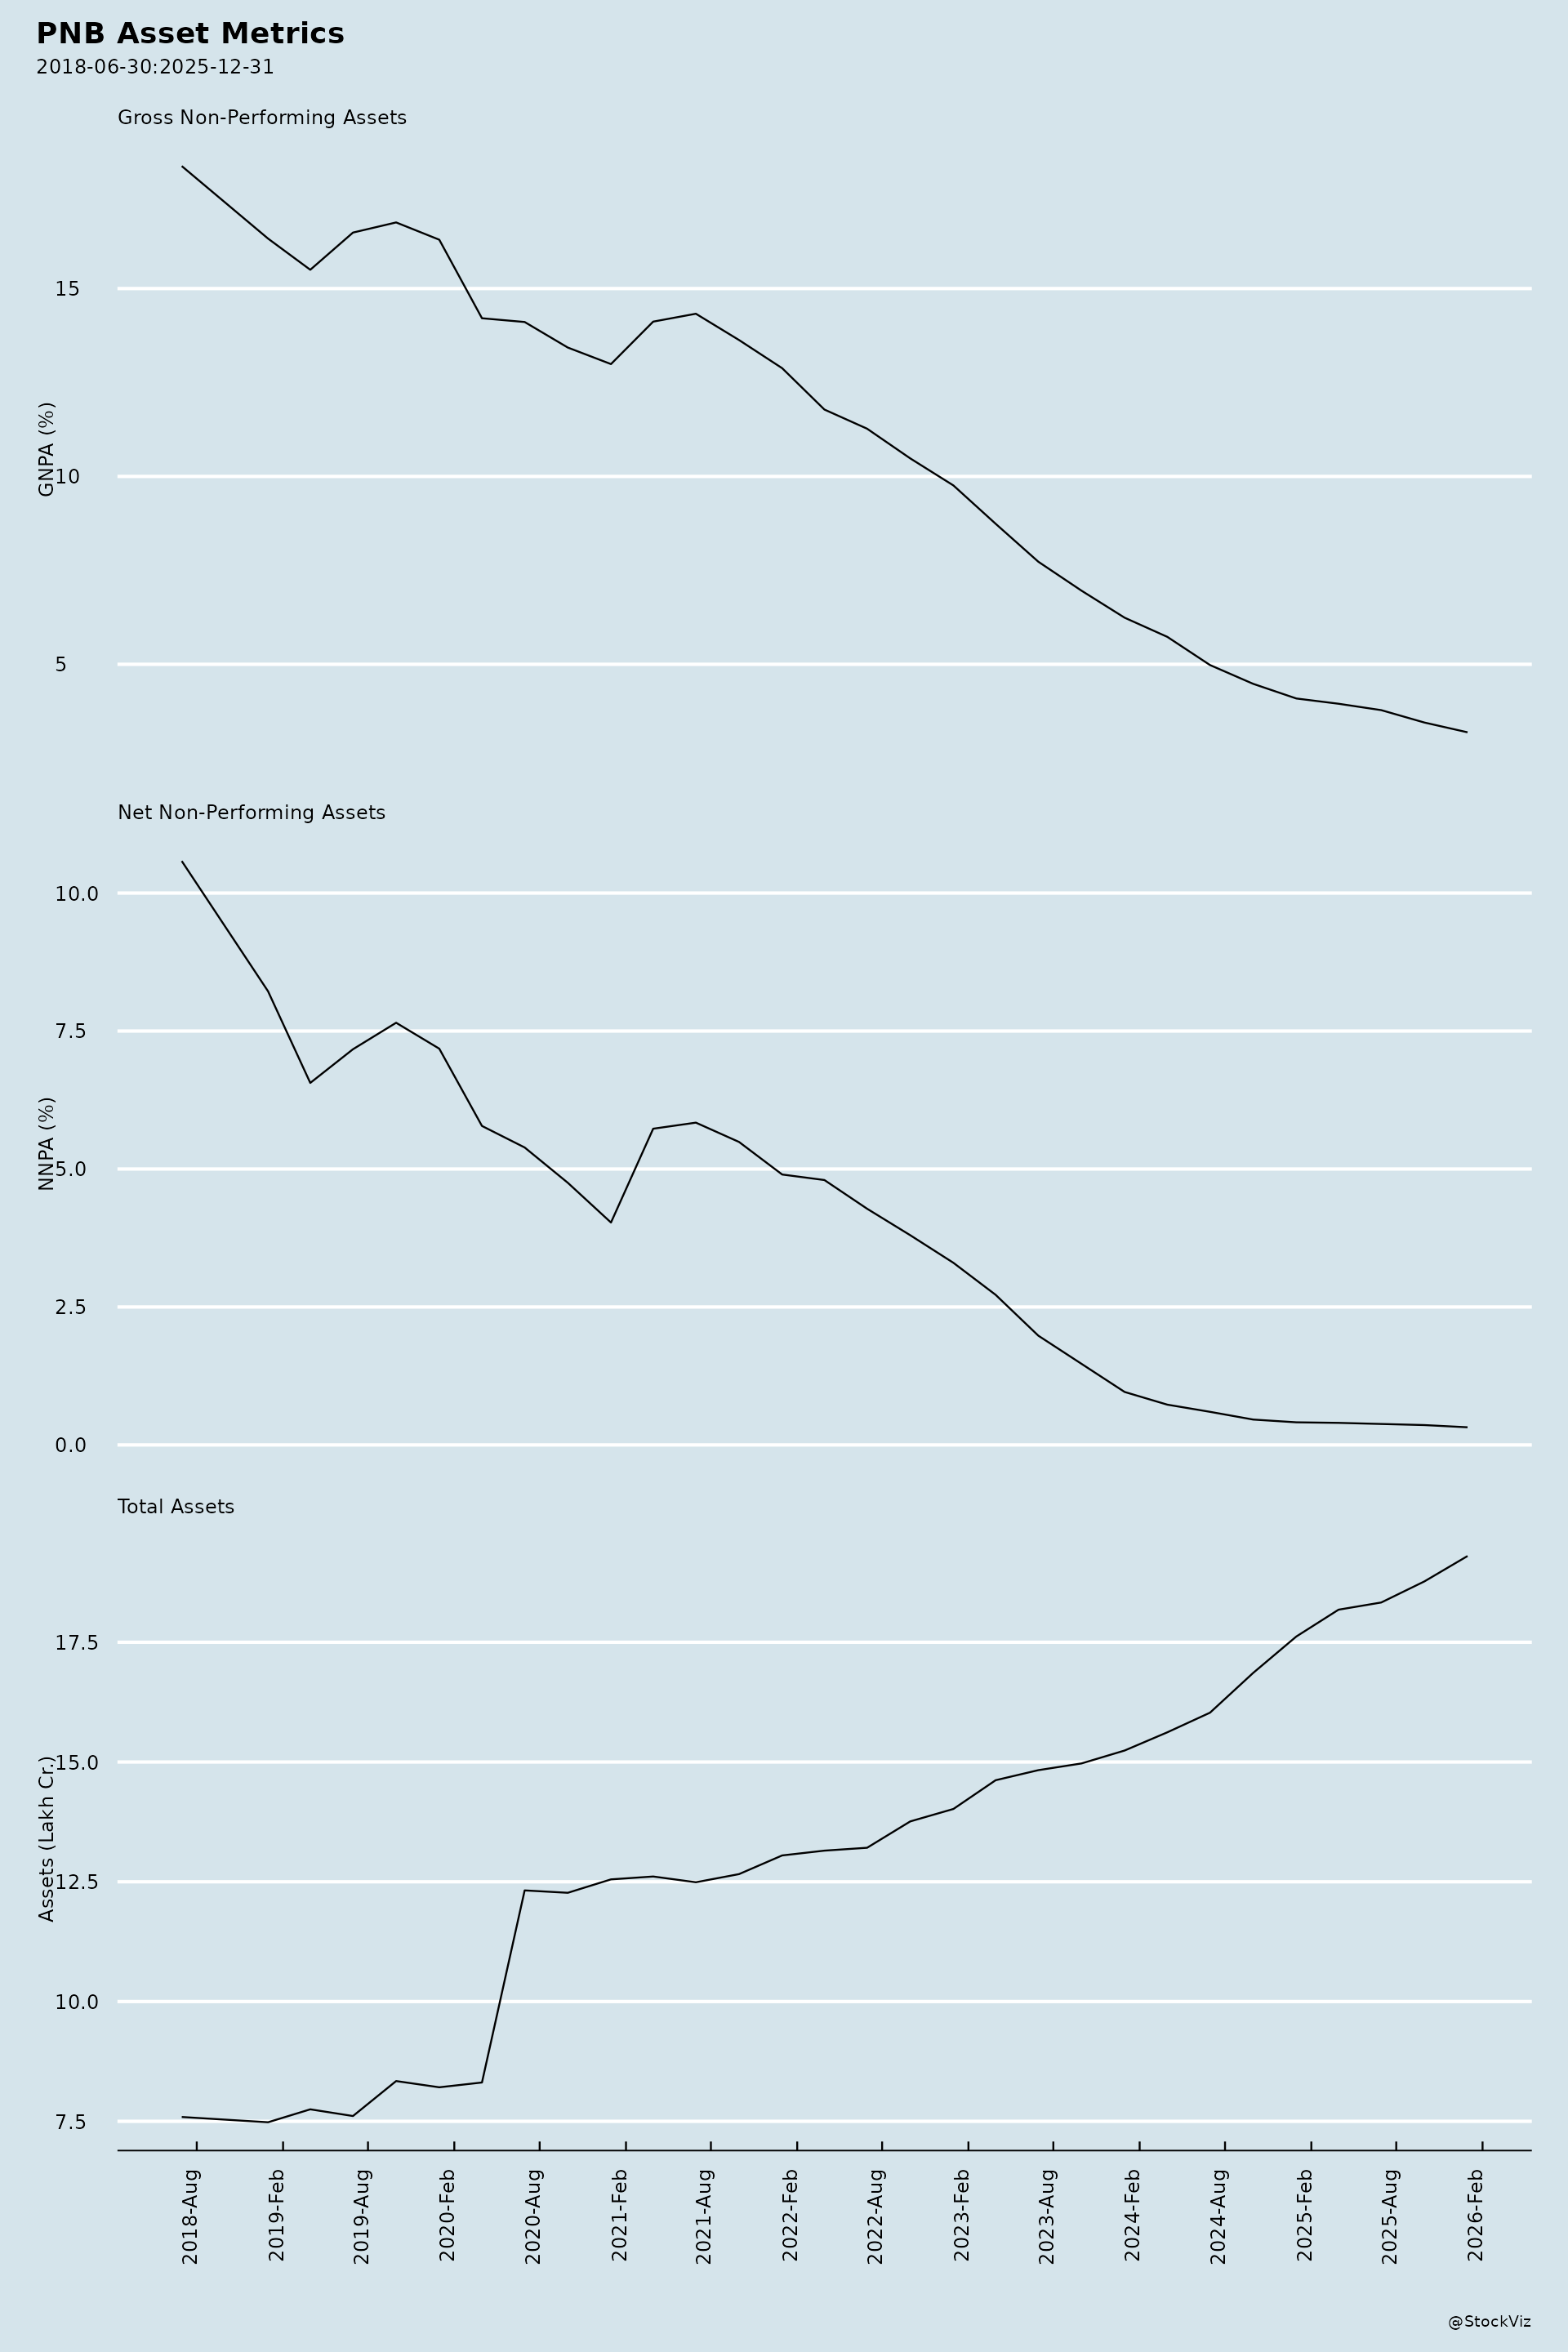
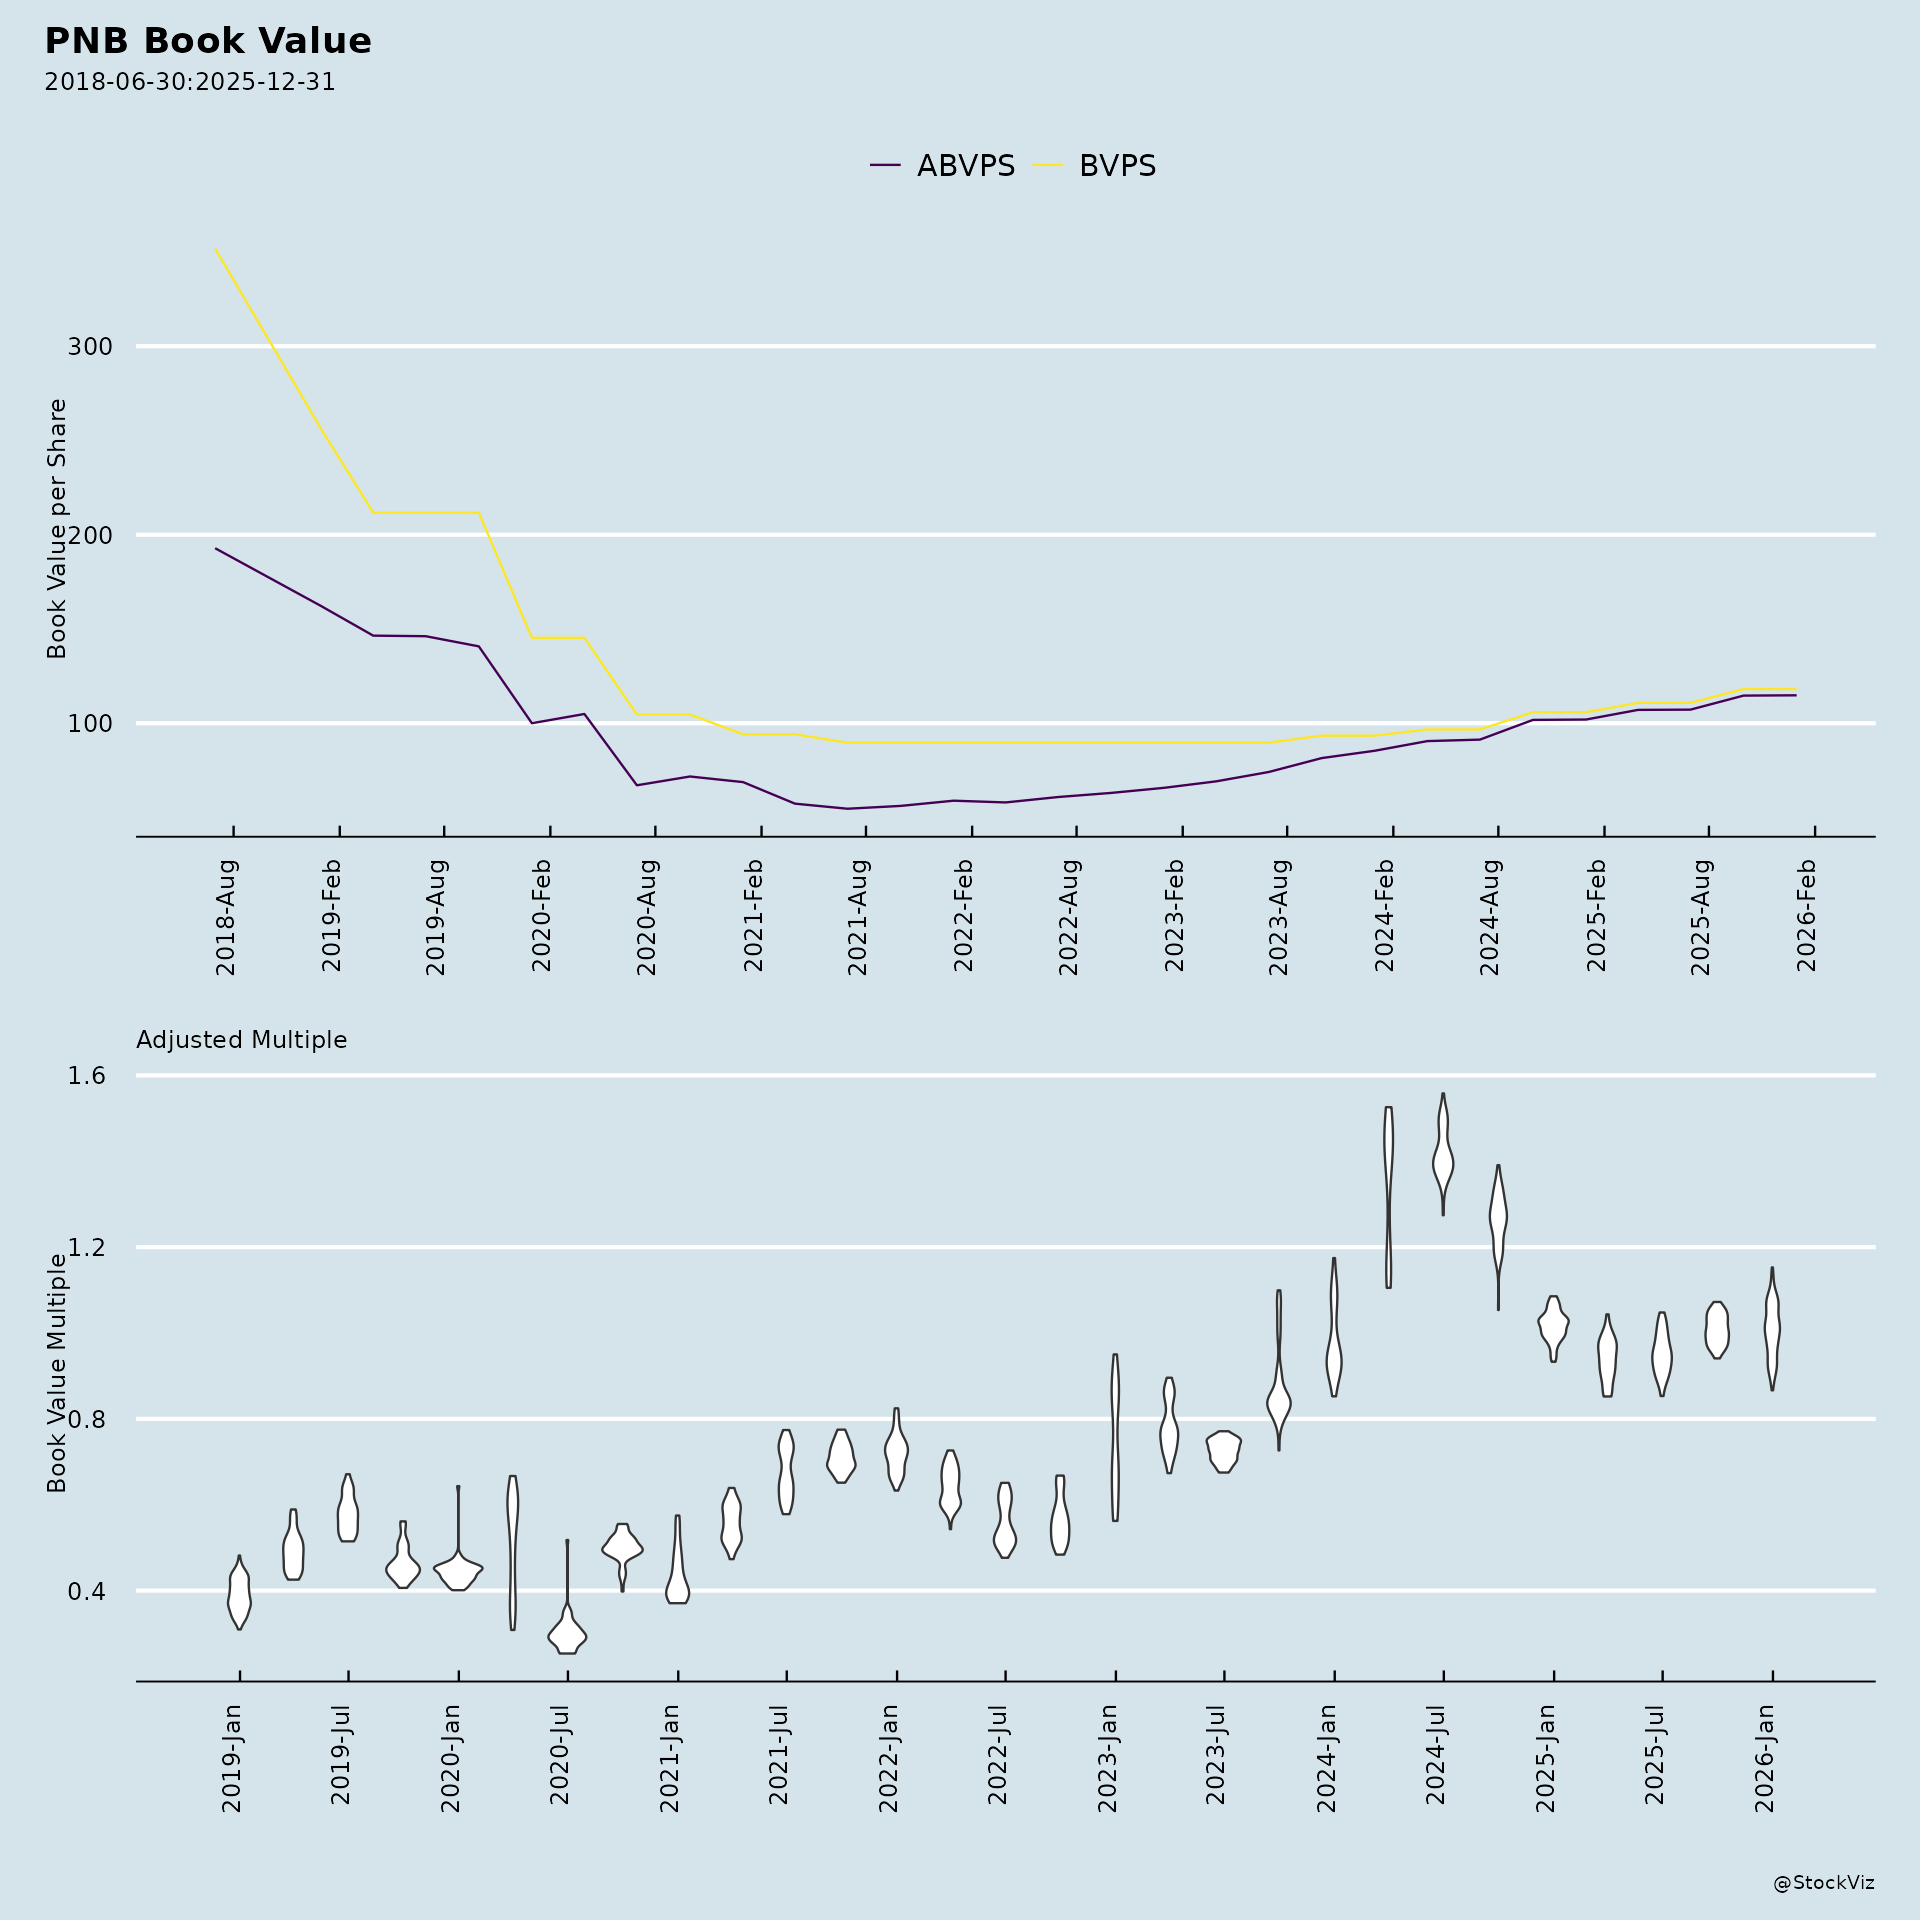
Fundamentals
Ownership
Margined
AI Summary
asof: 2026-09-14
PNB: Recent Corporate Announcements — Summary
1. Headwinds and Challenges
- Global growth and trade uncertainty: slower global growth and trade frictions are cited as external pressures.
- Geopolitical uncertainties: the West Asia conflict and trade restrictions feature among the identified risks.
- Crude oil volatility: volatile crude prices are linked to current account deficit and imported inflation concerns.
- Inflationary pressures: the El-Nino effect and lower Kharif sowing are flagged as domestic inflation risks.
- Regulatory action: the Reserve Bank of India imposed a monetary penalty of ₹4,33,900 on the bank on August 20, 2026 for non-compliance with operational guidelines of Currency Chests under RBI Master Directions.
- Governance transition: a Government of India Nominee Director, Shri Divesh Sehara (IAS, 2005 Batch, Bihar Cadre, Joint Secretary, Ministry of Finance, Department of Financial Services), was appointed to the Board effective 10th September 2026.
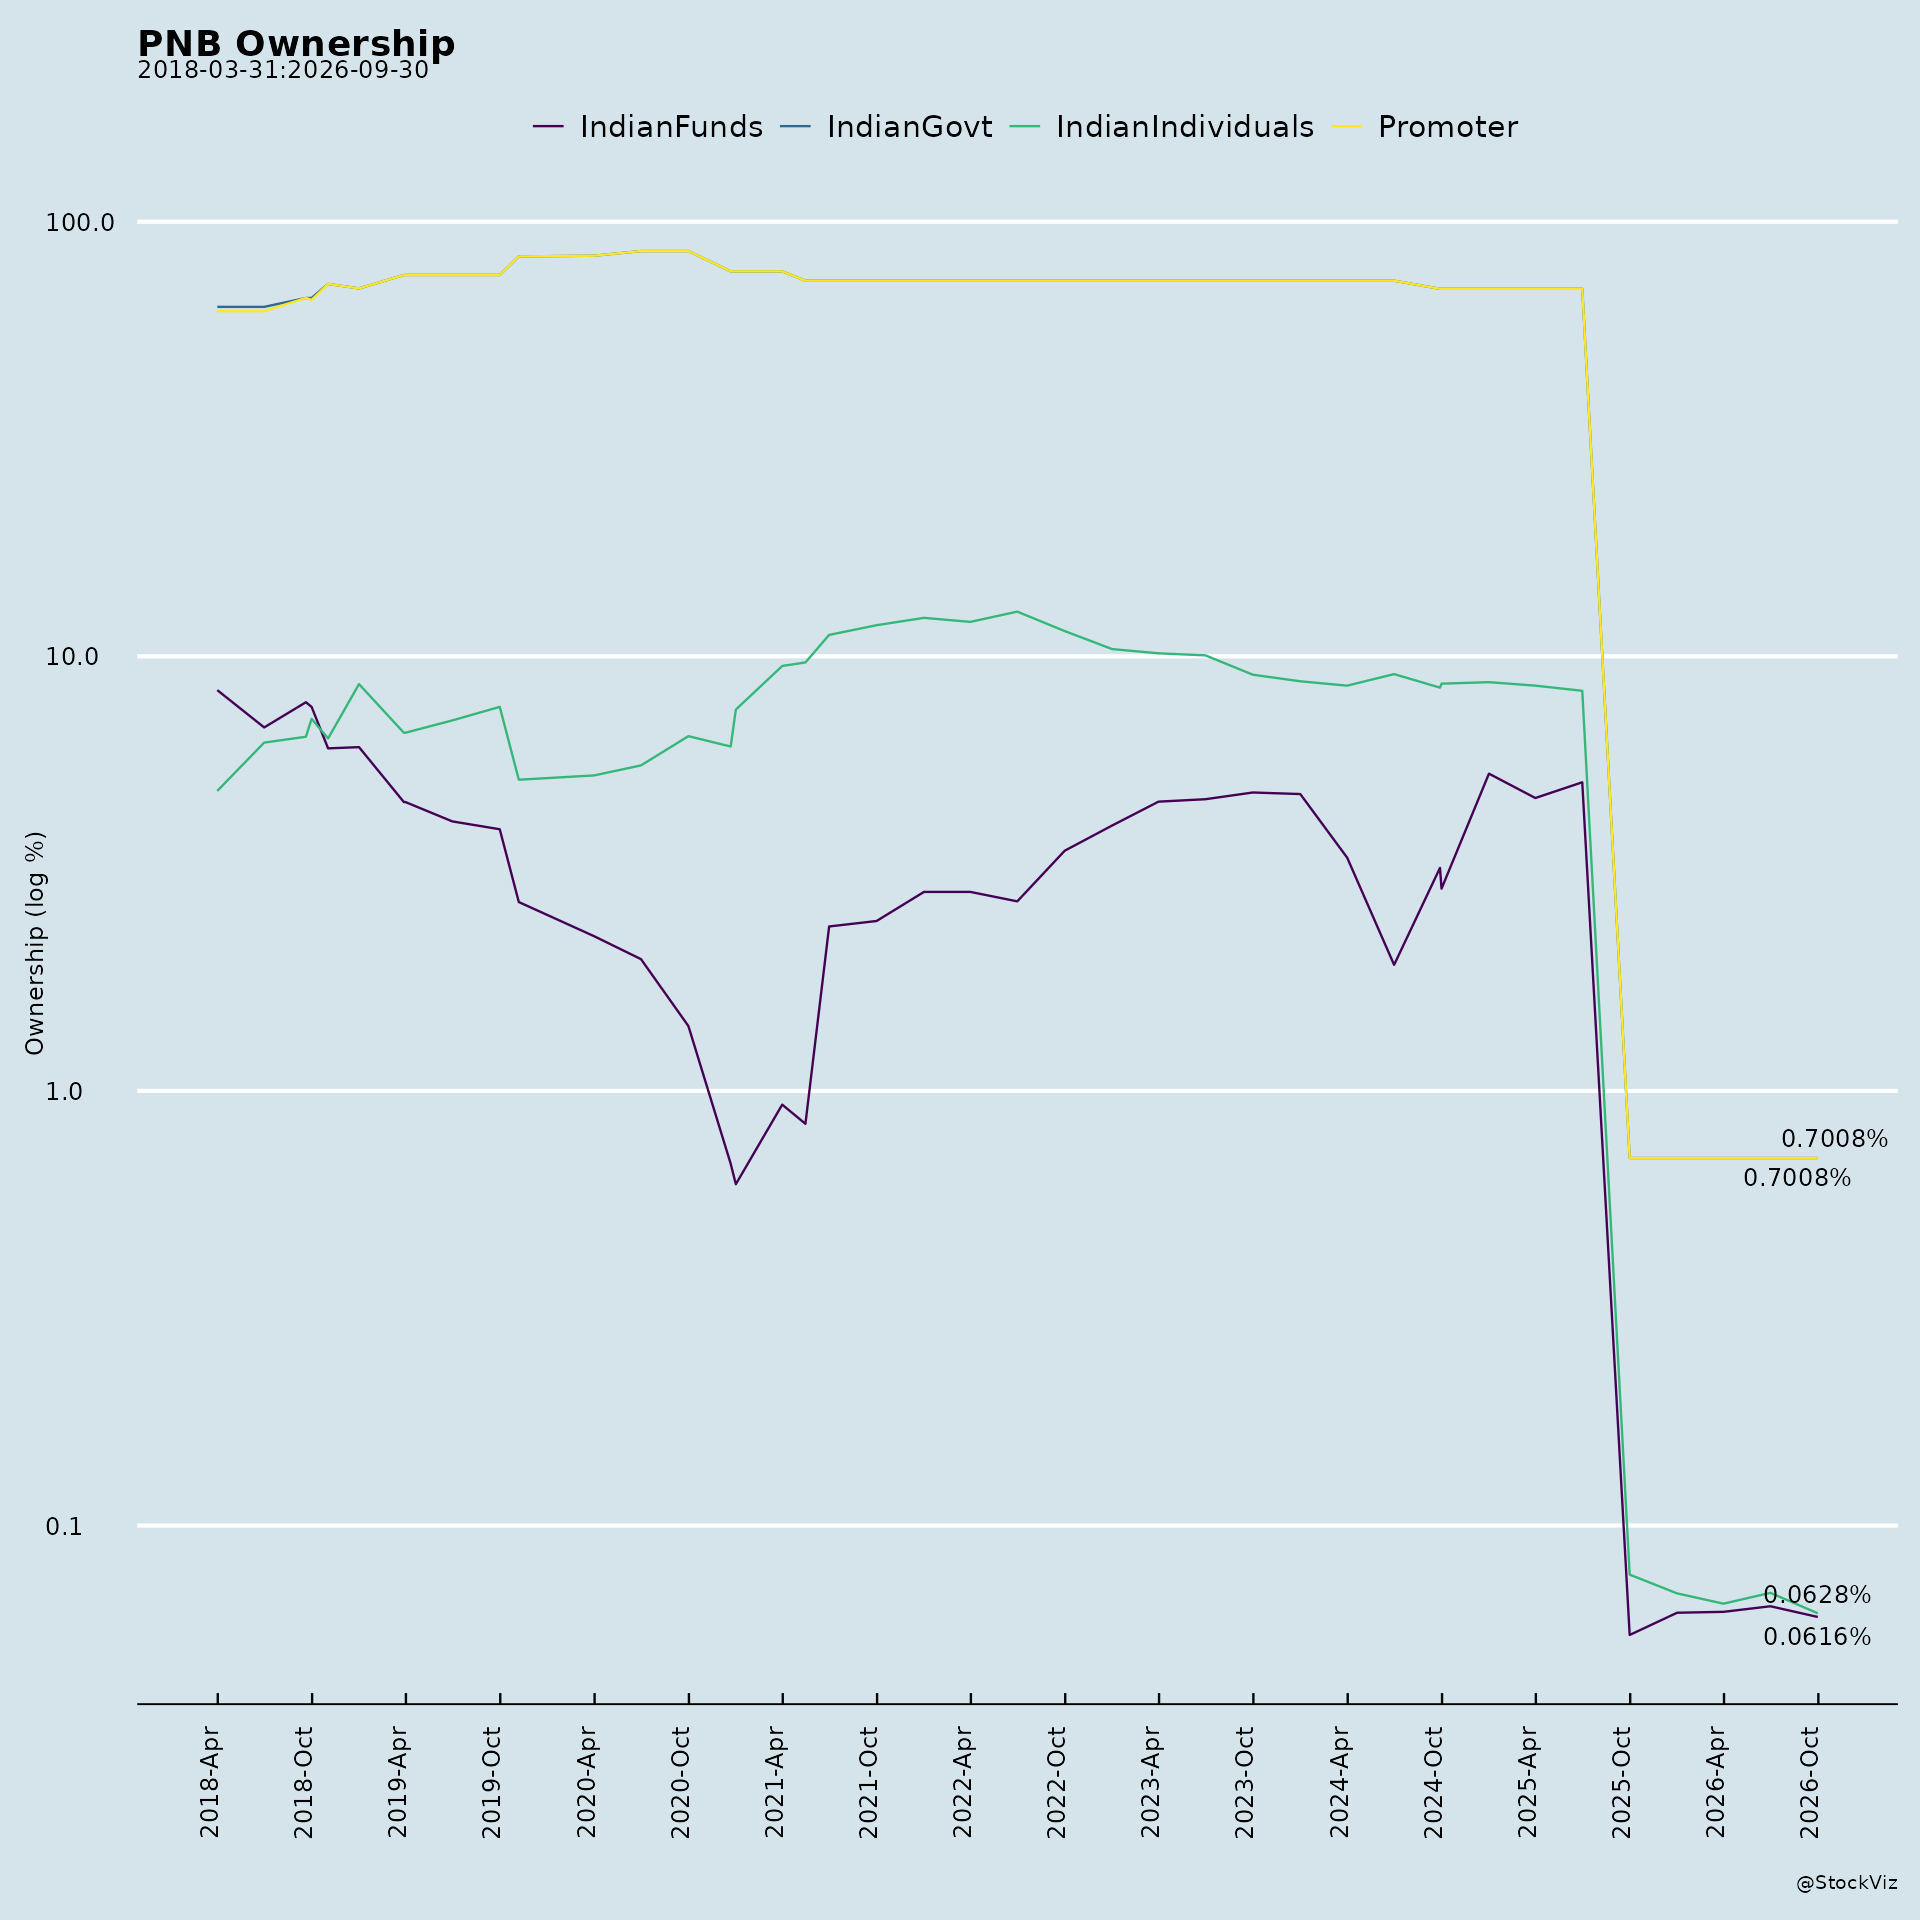
- Shareholder representation process: an Extraordinary General Meeting is scheduled for 25th September 2026 to elect one director from among shareholders other than the Central Government, with public shareholding at 29.92% as of the notice date.
2. Tailwinds and Growth Prospects
- Resilient Indian economy: growth momentum supported by policy credibility, structural reforms, and digital transformation.
- Consumption drivers: rural demand recovery and tax relief cited as robust consumption supports.
- External strength: strong forex reserves of $707 billion as of August 7, 2026.
- Infrastructure and services: continued strength in infrastructure investment and services.
- Banking sector momentum: credit growth at a nine-quarter high in June 2026 with stable asset quality.
- Business expansion: global business grew 10.2% Y-o-Y to ₹29.98 Lakh Crore as on June 2026; global deposits rose 8.5% Y-o-Y to ₹17.24 Lakh Crore; global advances rose 12.7% Y-o-Y to ₹12,73,132 Crore.
- Retail and priority sector traction: core retail advances up 17.5% Y-o-Y; housing loans up 11.9% to ₹1,32,840 Crore; vehicle loans up 34.4% to ₹36,599 Crore; agriculture PS advances up 16.4% to ₹1,61,668 Crore; MSME advances up 19.8% to ₹2,03,025 Crore.
- Deposit franchise: savings deposits up 7.2% to ₹5,33,798 Crore; current deposits up 12.3% to ₹79,318 Crore; CASA deposits up 7.8% to ₹6,13,116 Crore, with CASA share at 36.7%.
- Digital adoption: digital transactions up 24% Y-o-Y to 365 Crore; PNB One activated users up 19% to 270 Lakh; WhatsApp Banking users up 100% to 140 Lakh; CBDC users at 17.22 Lakh with 153.06 Lakh transactions.
- New funding avenue: Board approval on July 29, 2026 for a Medium-Term Note Programme up to USD 1.5 billion, with bond issuance through PNB IFSC Banking Unit GIFT City.
- Recognition: awards including the Golden Peacock National Training Award 2026, APY Annual Awards Excellence Achiever for FY 2025-26, Platinum Award for Treasury Transformation and Platinum Award for Product Innovation (Krishi Tatkal Rinn) at the Infosys Finacle Innovation Awards 2026, and a Climate Finance category win at the Viksit Bharat “Ambassador for Change” Awards 2026.
3. Key Risks
- Asset quality: GNPA at 2.78% and NNPA at 0.28% as on June 2026, though both improved Y-o-Y and sequentially; slippage ratio at 0.68% for Q1 FY27.
- Regulatory compliance: the RBI penalty for Currency Chest operational non-compliance highlights compliance risk.
- Macro-financial: crude oil volatility feeding the current account deficit and imported inflation; El-Nino and lower Kharif sowing affecting inflation and rural demand.
- External environment: slower global growth, trade frictions, and geopolitical conflict.
- Capital and provisioning: CRAR at 18.13% as on June 2026; PCR (incl. TWO) at 97.23%.
4. Management Guidance vs. Observed Performance
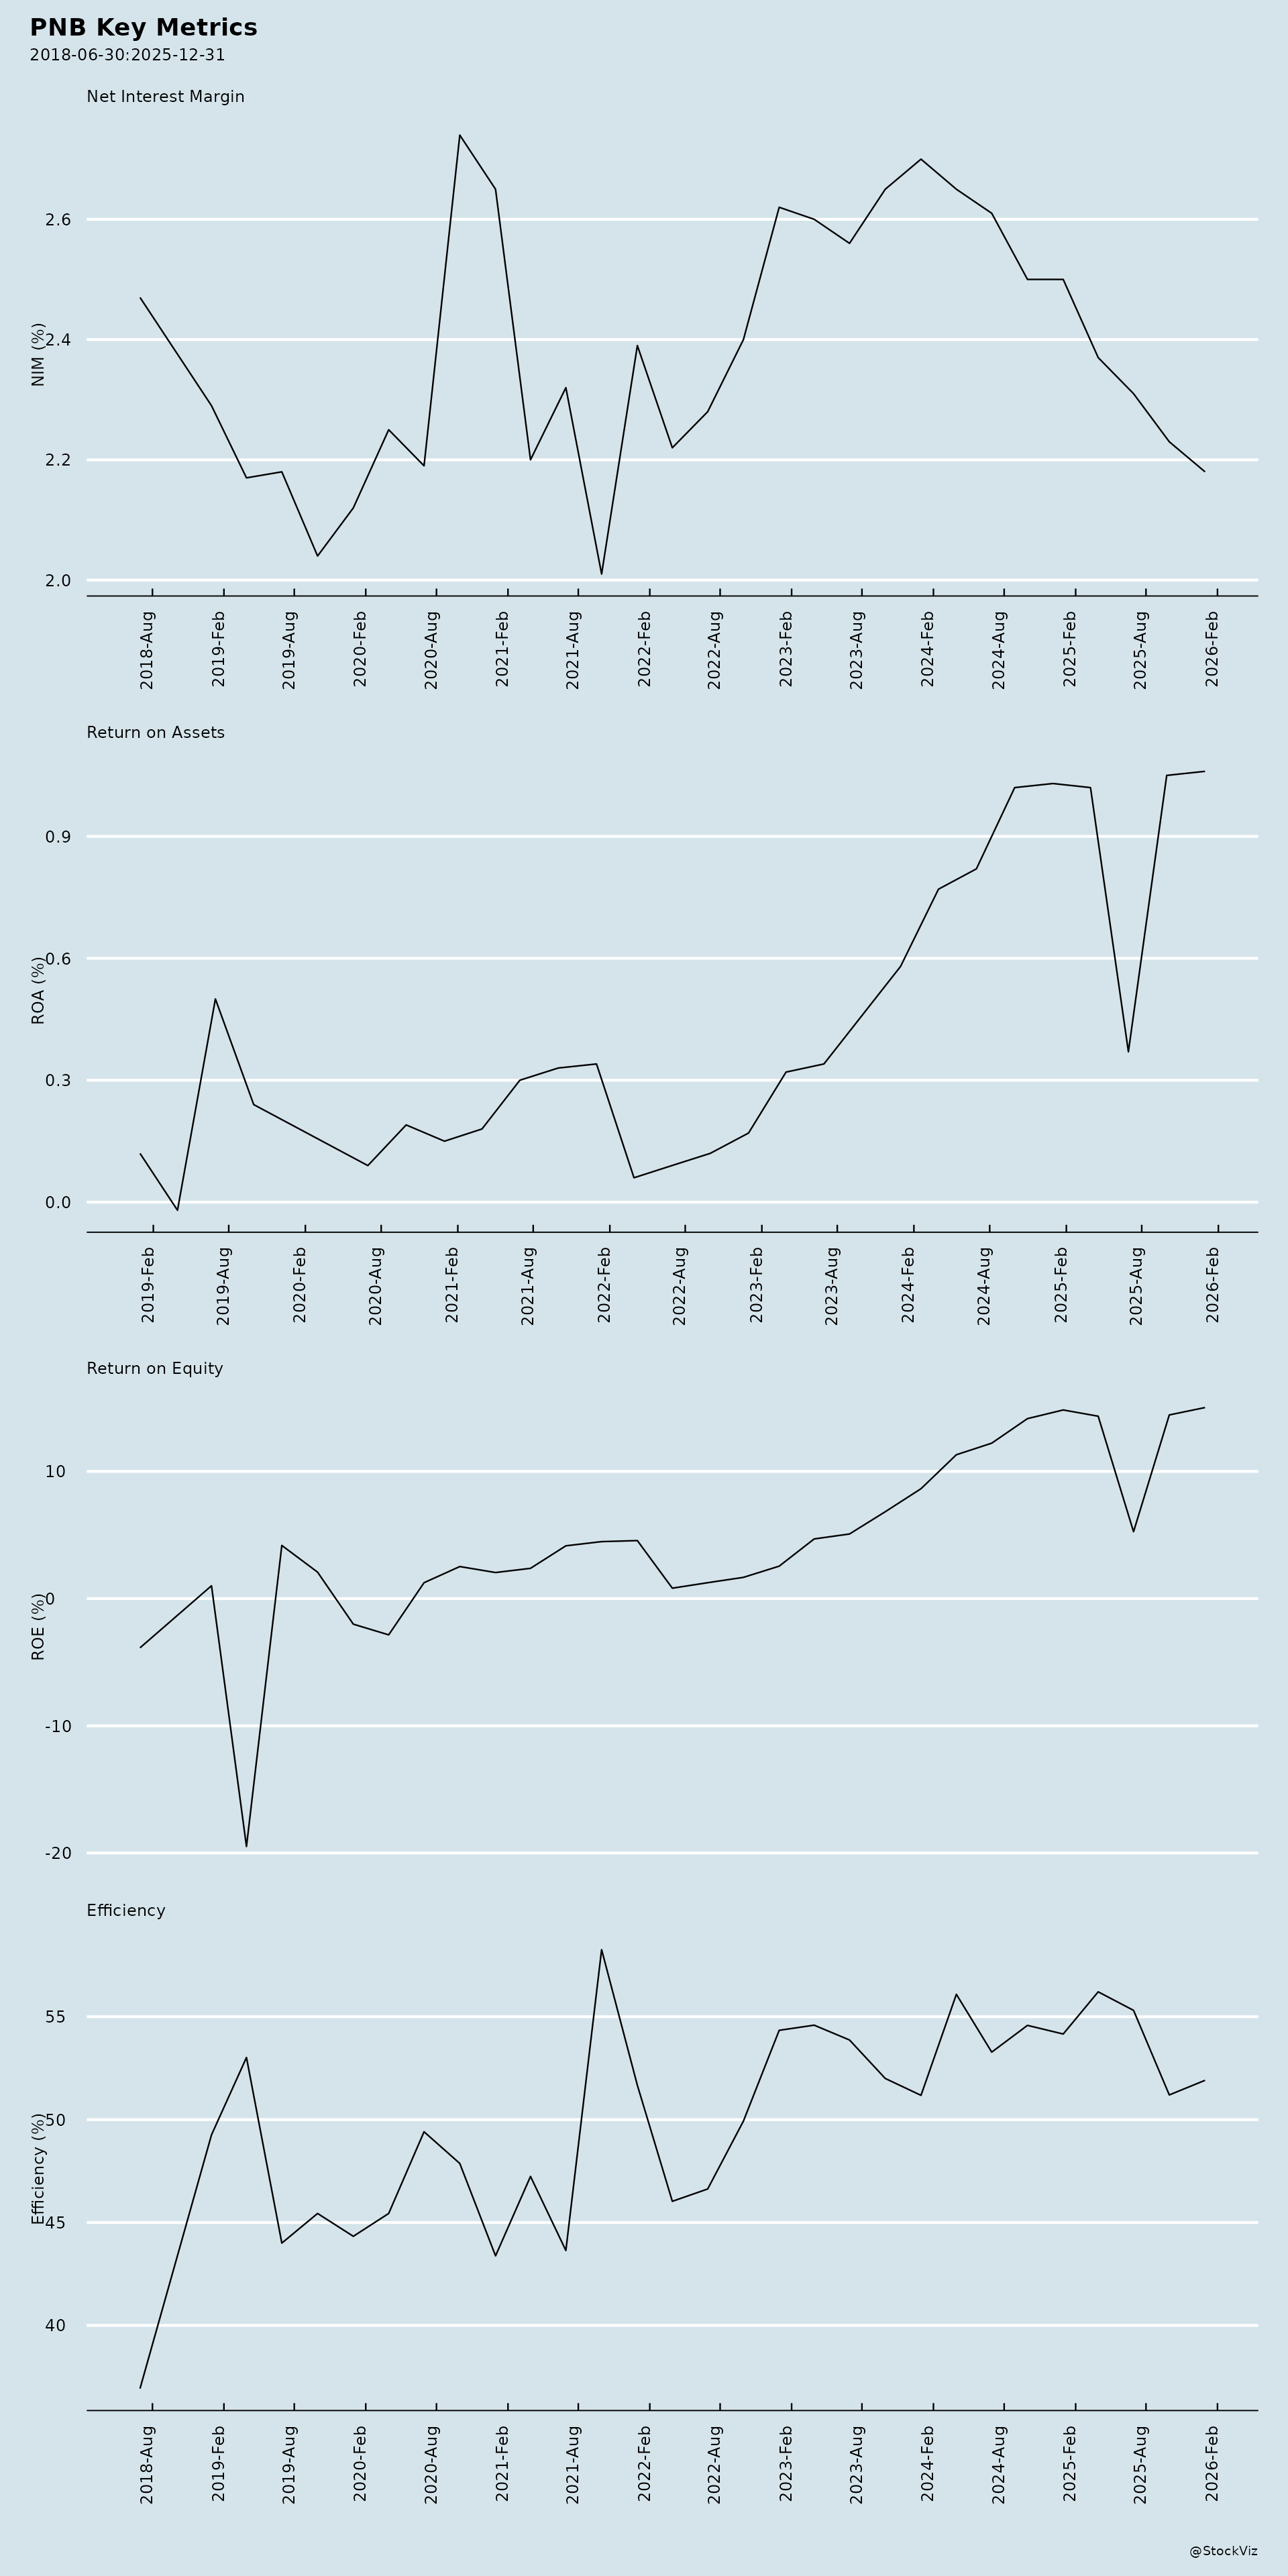
FY27 guidance provided by management: - Credit growth (Y-o-Y): 12%–13% - Deposit growth (Y-o-Y): 9%–10% - CASA share: 38% - Operating profit growth (Y-o-Y): 9%–10% - Net interest income growth (Y-o-Y): 7% - NIM: 2.60%–2.70% - Gross NPA: below 2.50% - Net NPA: below 0.3% - PCR (incl. TWO): more than 96% - Credit cost: below 0.4% - Total recovery amount: > $1,373 Mn - RoA: above 1% - Slippage ratio (annualized): below 0.9%
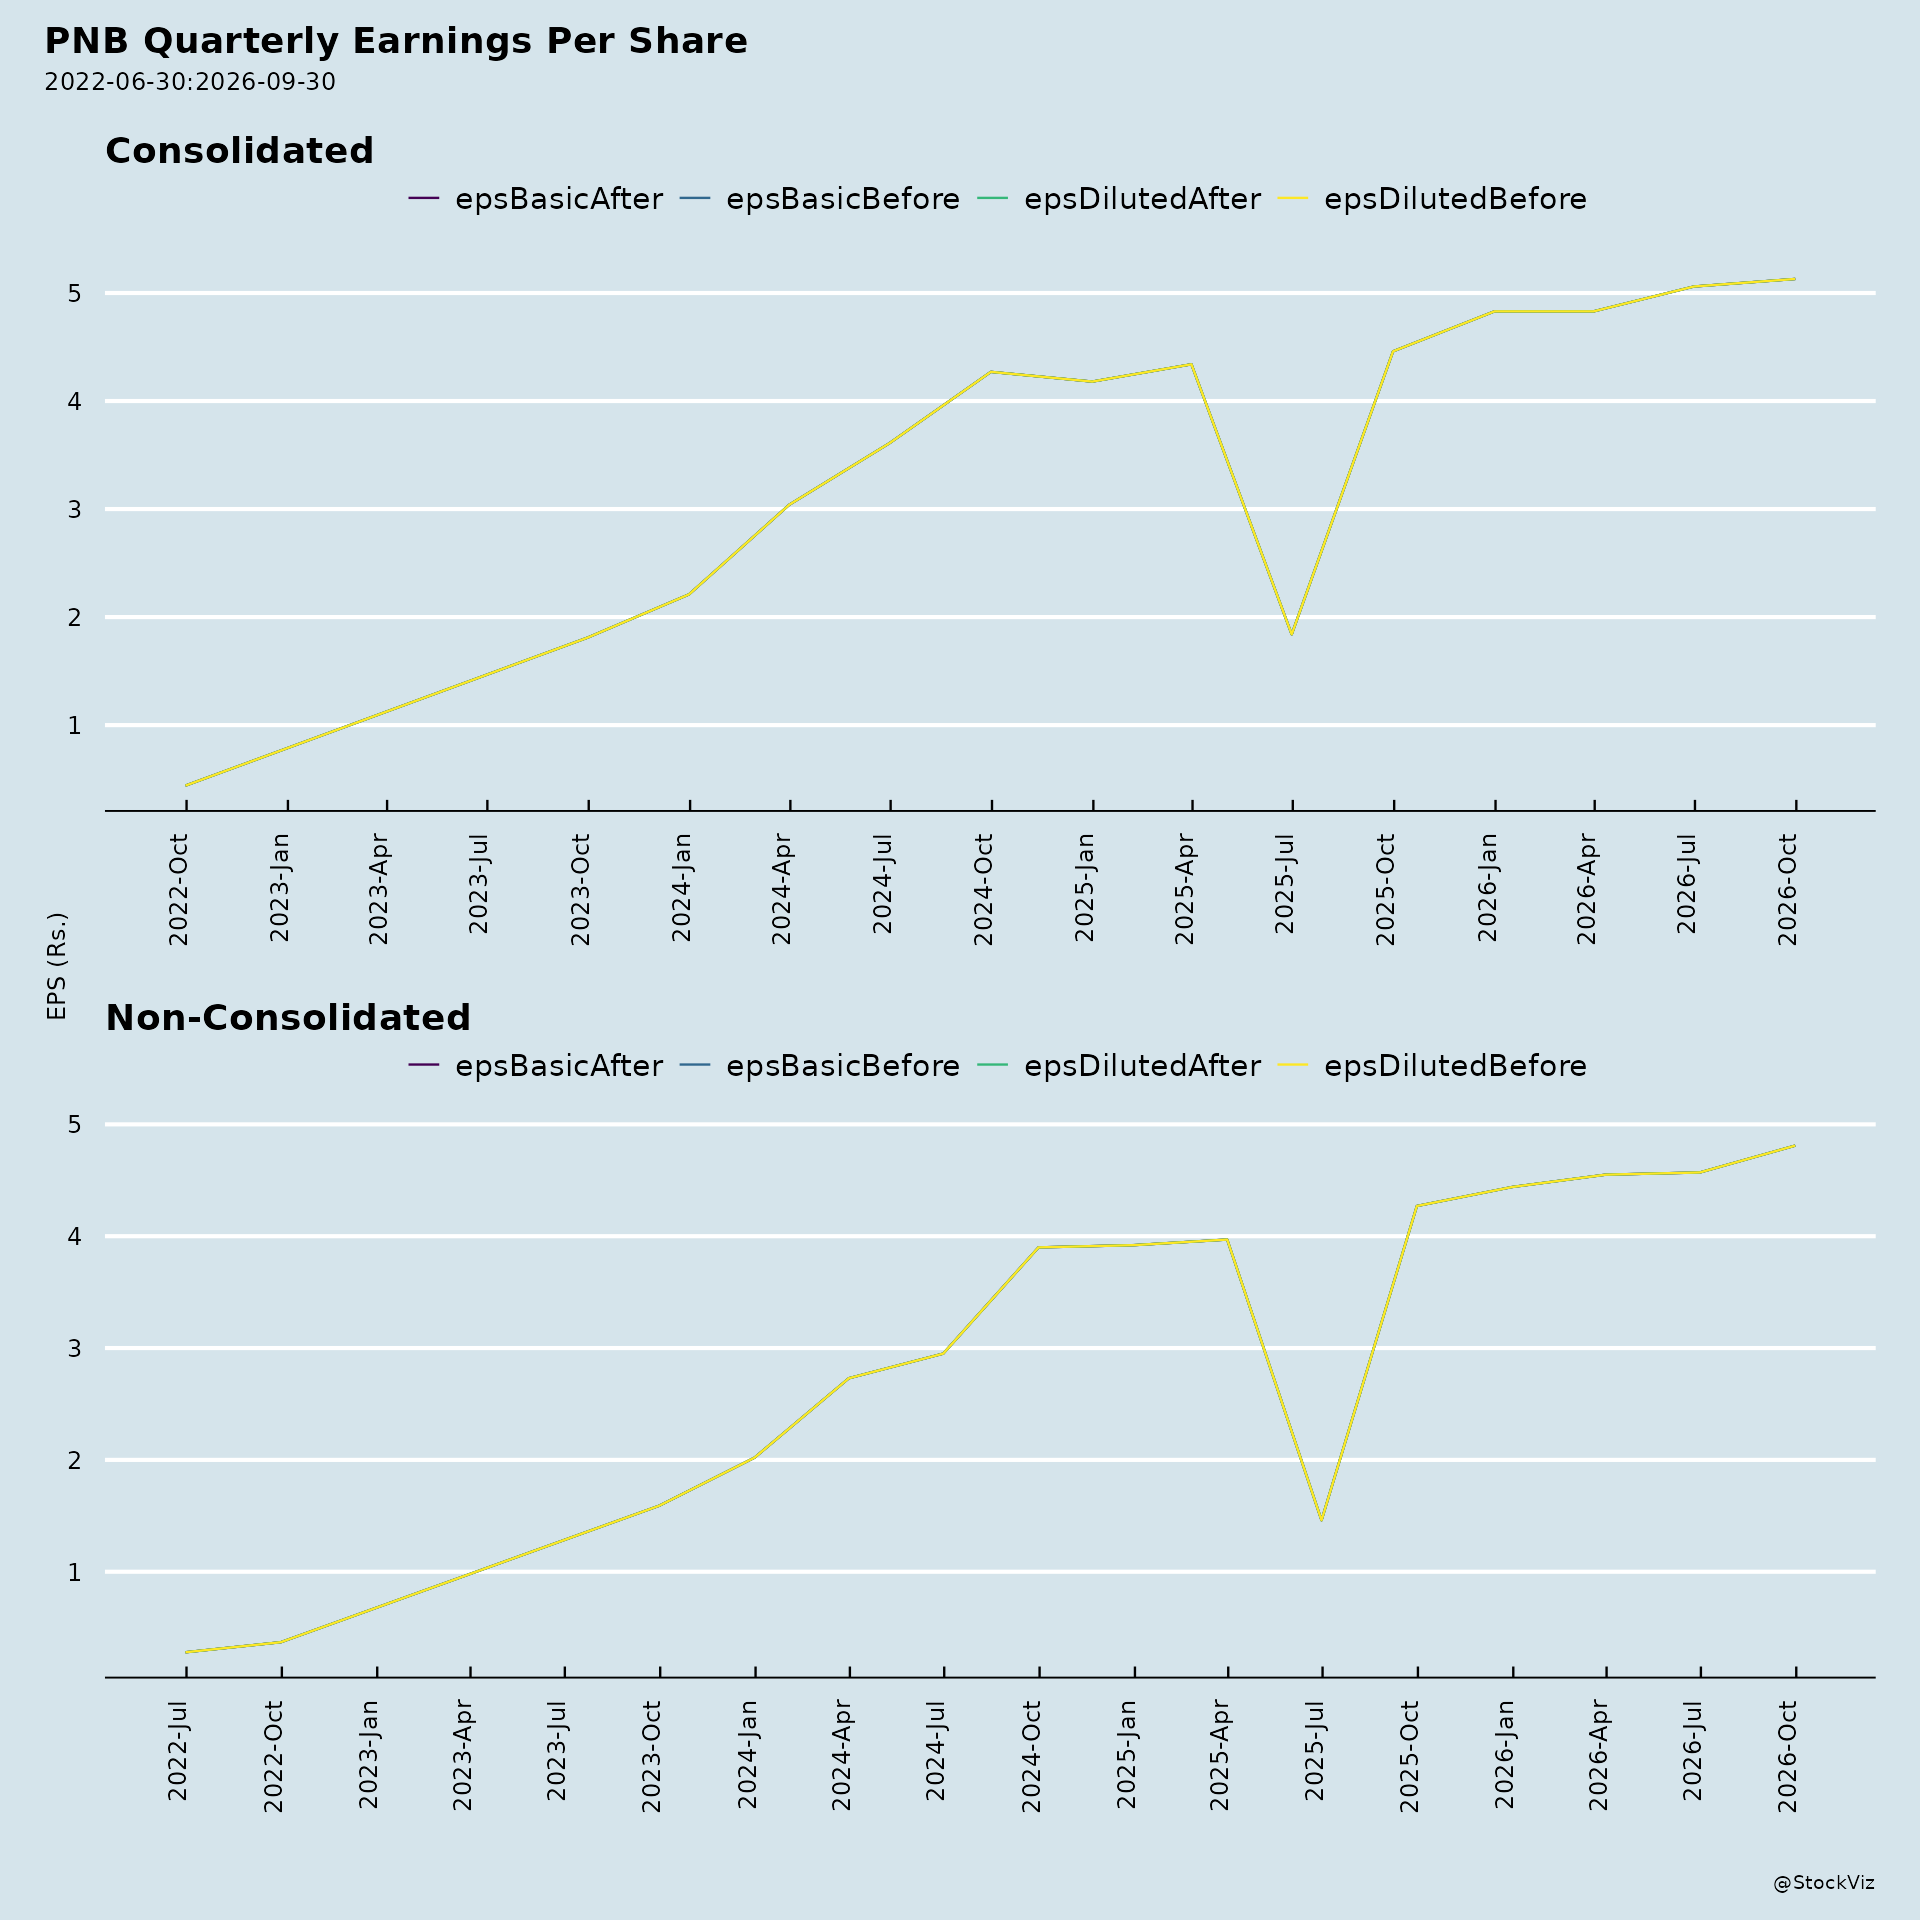
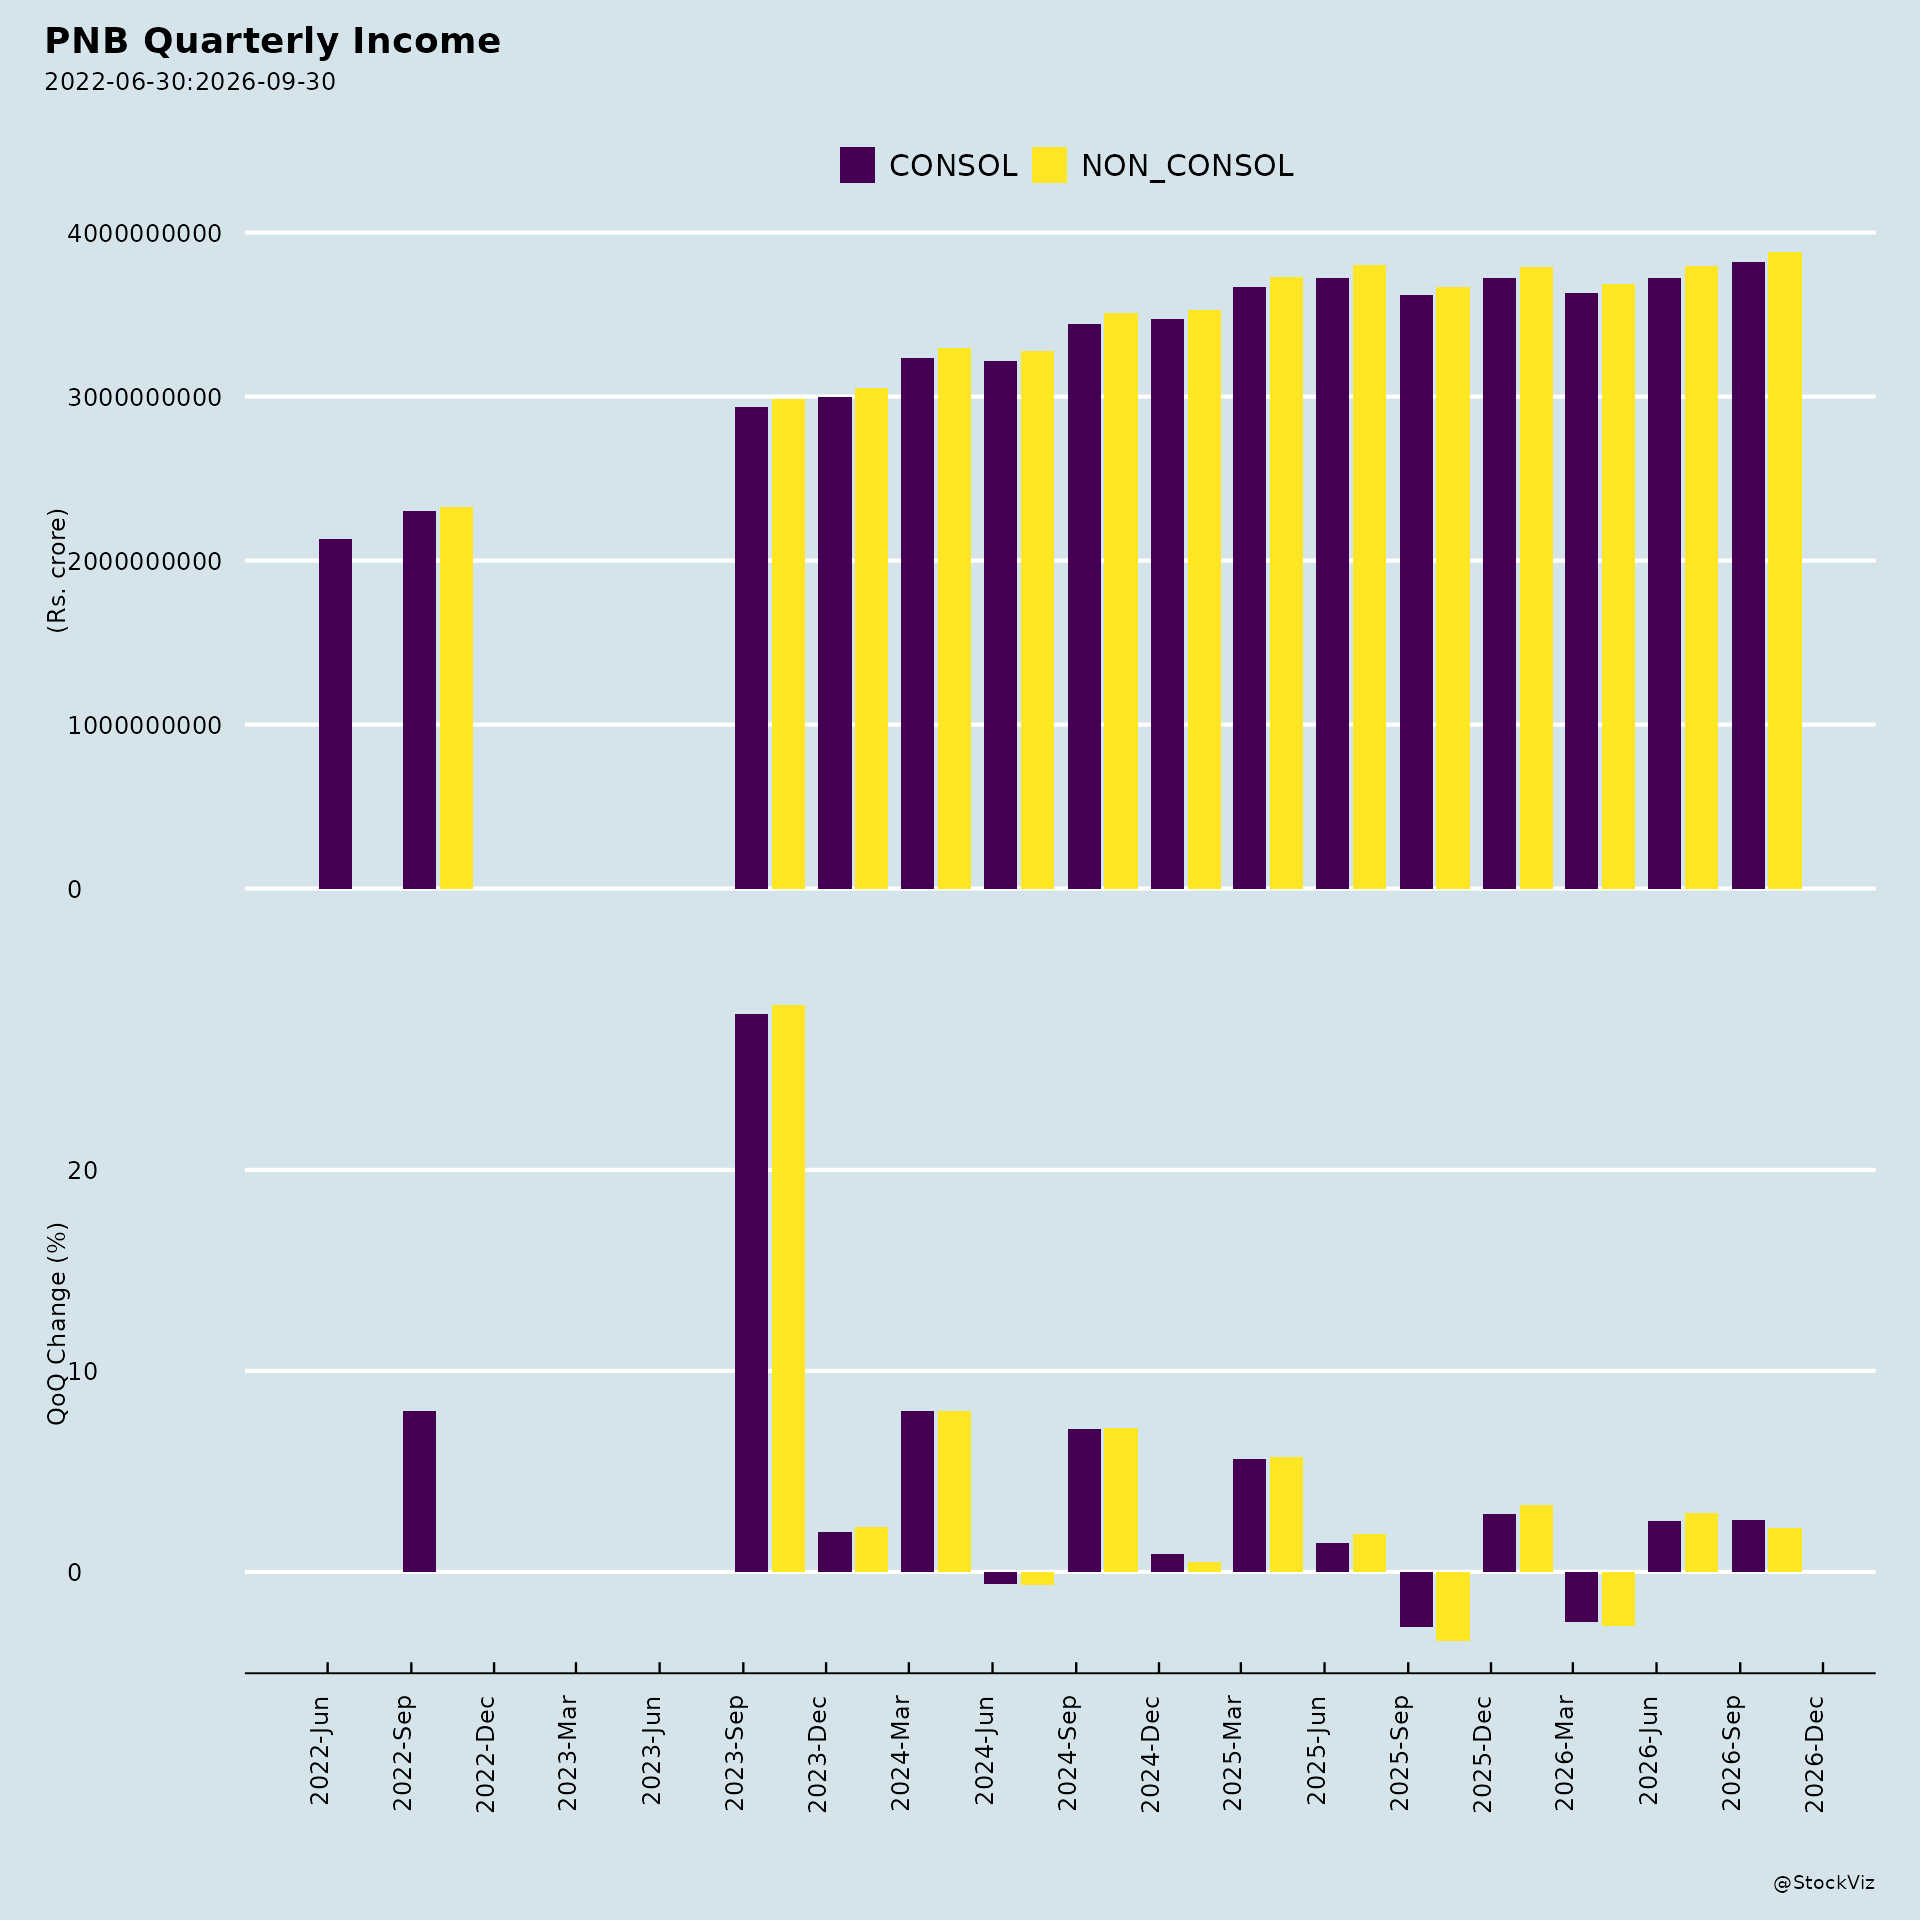
Observed performance (Q1 FY27, quarter ended 30 June 2026): - Net profit up 213.6% Y-o-Y to ₹5,253 Crore (Q1 FY26: ₹1,675 Crore). - RoA at 1.04%, up 67 bps Y-o-Y — above the “above 1%” guidance. - Global NIM at 2.50% in Q1 FY27, up from 2.47% in Q4 FY26 — below the 2.60%–2.70% guidance range. - CRAR at 18.13% as on June 2026 vs 17.50% as on June 2025. - Book value per share (tangible) at ₹108.58 in June 2026 vs ₹92.64 in June 2025. - CD ratio at 73.8% as on June 2026 vs 71.1% in June 2025. - GNPA at 2.78% and NNPA at 0.28% — within the guided thresholds of below 2.50% and below 0.3% respectively. - Slippage ratio at 0.68% for Q1 FY27 — below the guided annualized ceiling of 0.9%. - Operating profit at ₹7,519 Crore for Q1 FY27, up 6.2% Y-o-Y from ₹7,081 Crore. - Net interest income up 2.1% Y-o-Y to ₹10,798 Crore. - Total interest income at ₹32,897 Crore for Q1 FY27, up 2.3% Q-o-Q from ₹32,157 Crore in Q4 FY26. - Interest income on advances at ₹23,061 Crore, up 6.4% Y-o-Y. - Fee-based income at ₹2,339 Crore for Q1 FY27, up 19.6% Q-o-Q from ₹1,956 Crore in Q4 FY26. - Business per employee at ₹29.71 Crore (June 2026) vs ₹27.30 Crore (June 2025); business per branch at ₹278.28 Crore vs ₹257.39 Crore. - Net profit per employee at ₹21.71 Lakhs and per branch at ₹203.37 Lakhs for Q1 FY27. - Distribution network: 54,248 touch points, 10,359 domestic branches, 2 international branches, 10,605 ATMs, and 33,284 BCs. - Financial inclusion: PMJDY accounts at 573.46 Crore as on June 2026 vs 539 Crore as on June 2025; PMJJBY enrollments at 95.72 Lakh, PMSBY at 357.00 Lakh, and APY at 59.77 Lakh as on 30.06.2026. - Investor engagement: representatives participated in one-to-one and group physical meetings at the Ashwamedh – Elara India Dialogue 2026 on 1st September 2026 in Mumbai, sharing only publicly available information.
Broker Narrative
The narrative shifted from a cautious Neutral (2023) worried about rising deposit costs, margin compression and wage-driven opex to a Buy (2026) as funding costs fell, NIM expanded and opex relief emerged from lower PSLC/AS-15 costs. Retail/SME/RAM credit growth and controlled slippages remained consistent bullish themes throughout. The biggest reversal was on treasury: initially cited as a tailwind from falling bond yields, by 1QFY27 treasury profits had collapsed 52% YoY and became a headwind. New concerns about ECL transition, CASA erosion and early-stage SMA-2 stress replaced the original cost-of-deposit fears.
Fears that came true
- The early warning on higher funding costs/bulk deposit mix materialized as CASA contracted to 36.7% by 1QFY27, and this funding pressure was associated with the May-2024 DISAPPOINTMENT (-23.8% actual return).
- The flagged stagnation in loan yields showed up in low-yielding corporate advances being run off and NII growth of just 2.1% YoY in 1QFY27, a period also preceded by negative actual returns in mid-2024 (e.g., -14.8% in June-2024).
Optimism that failed
- The early optimism on healthy treasury performance from moderating bond yields failed: treasury profits fell 52% YoY to INR 7.7b, dragging total other income down 17.7% YoY.
- The expected deposit-accretion tailwind from the INR 2,000 note discontinuance did not provide a durable CASA improvement, as CASA dipped 29 bps YoY to 36.7% by 1QFY27.
Broker Timeline
30 broker calls · 2023-06-01 to 2026-07-19
Copyright © 2023 SAS Data Analytics Pvt. Ltd. All rights reserved.