PIIND
Equity Metrics
November 18, 2026
PI Industries Limited
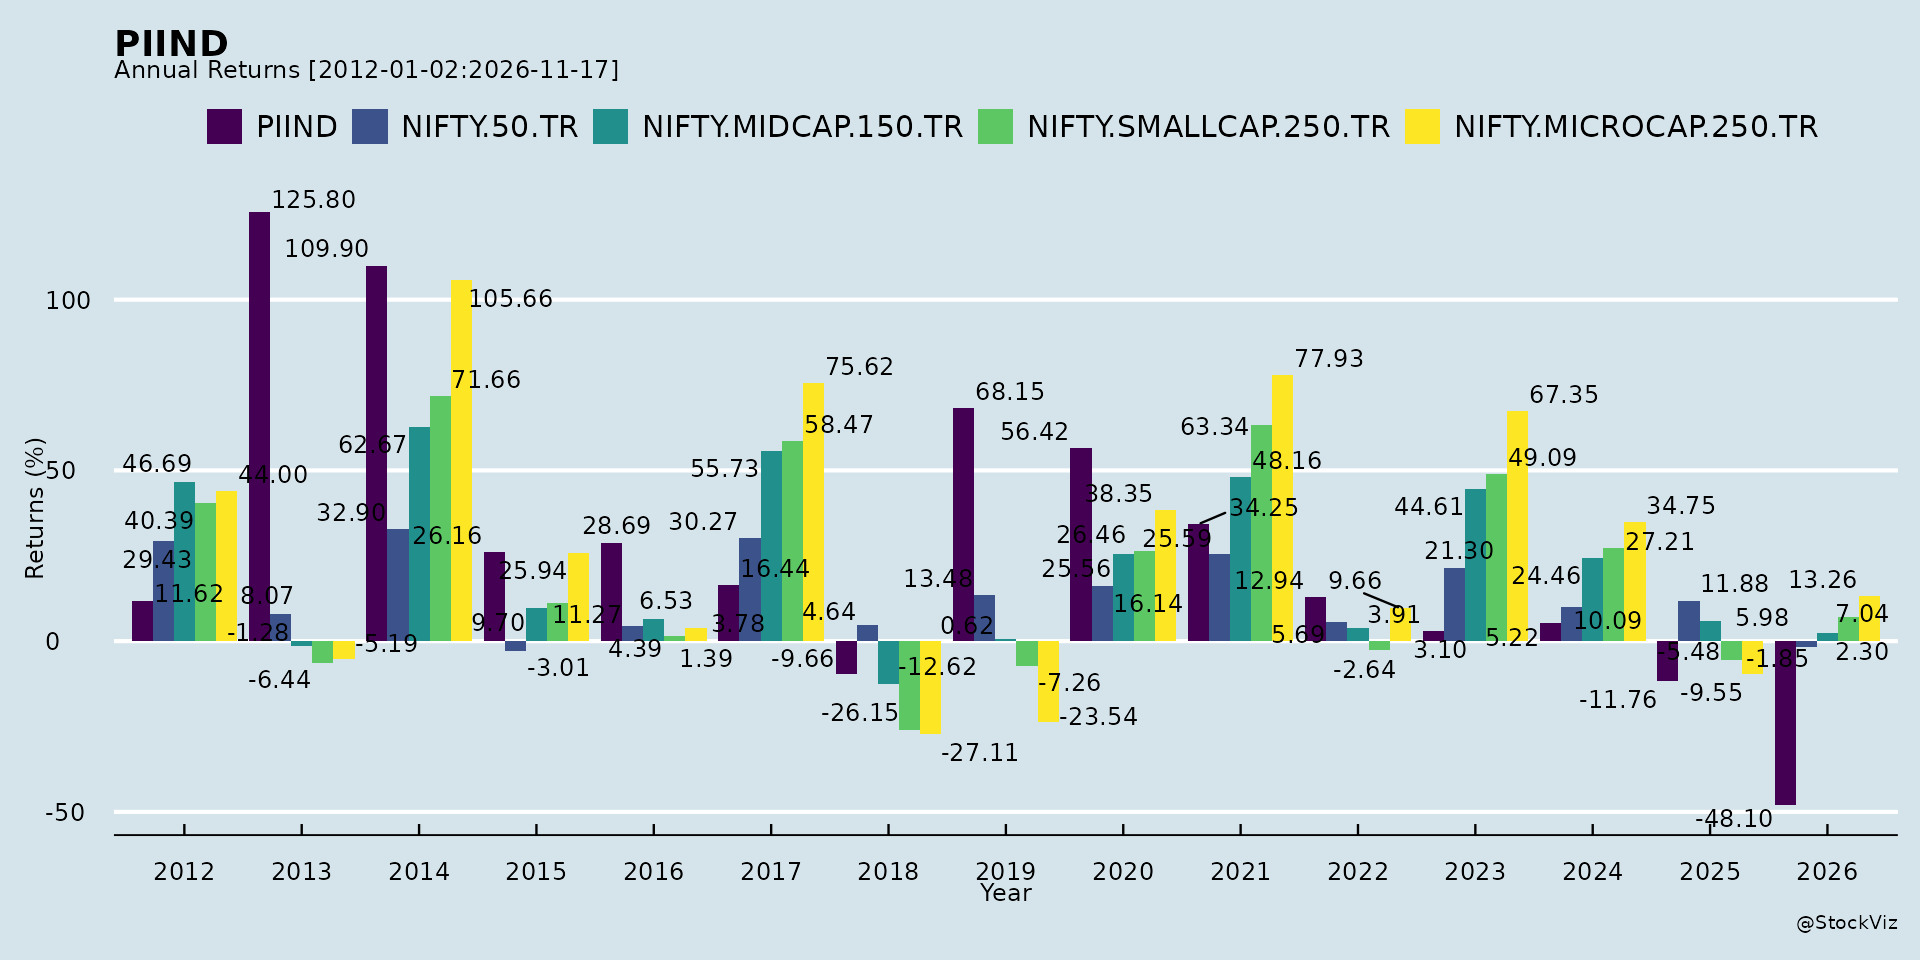
Annual Returns
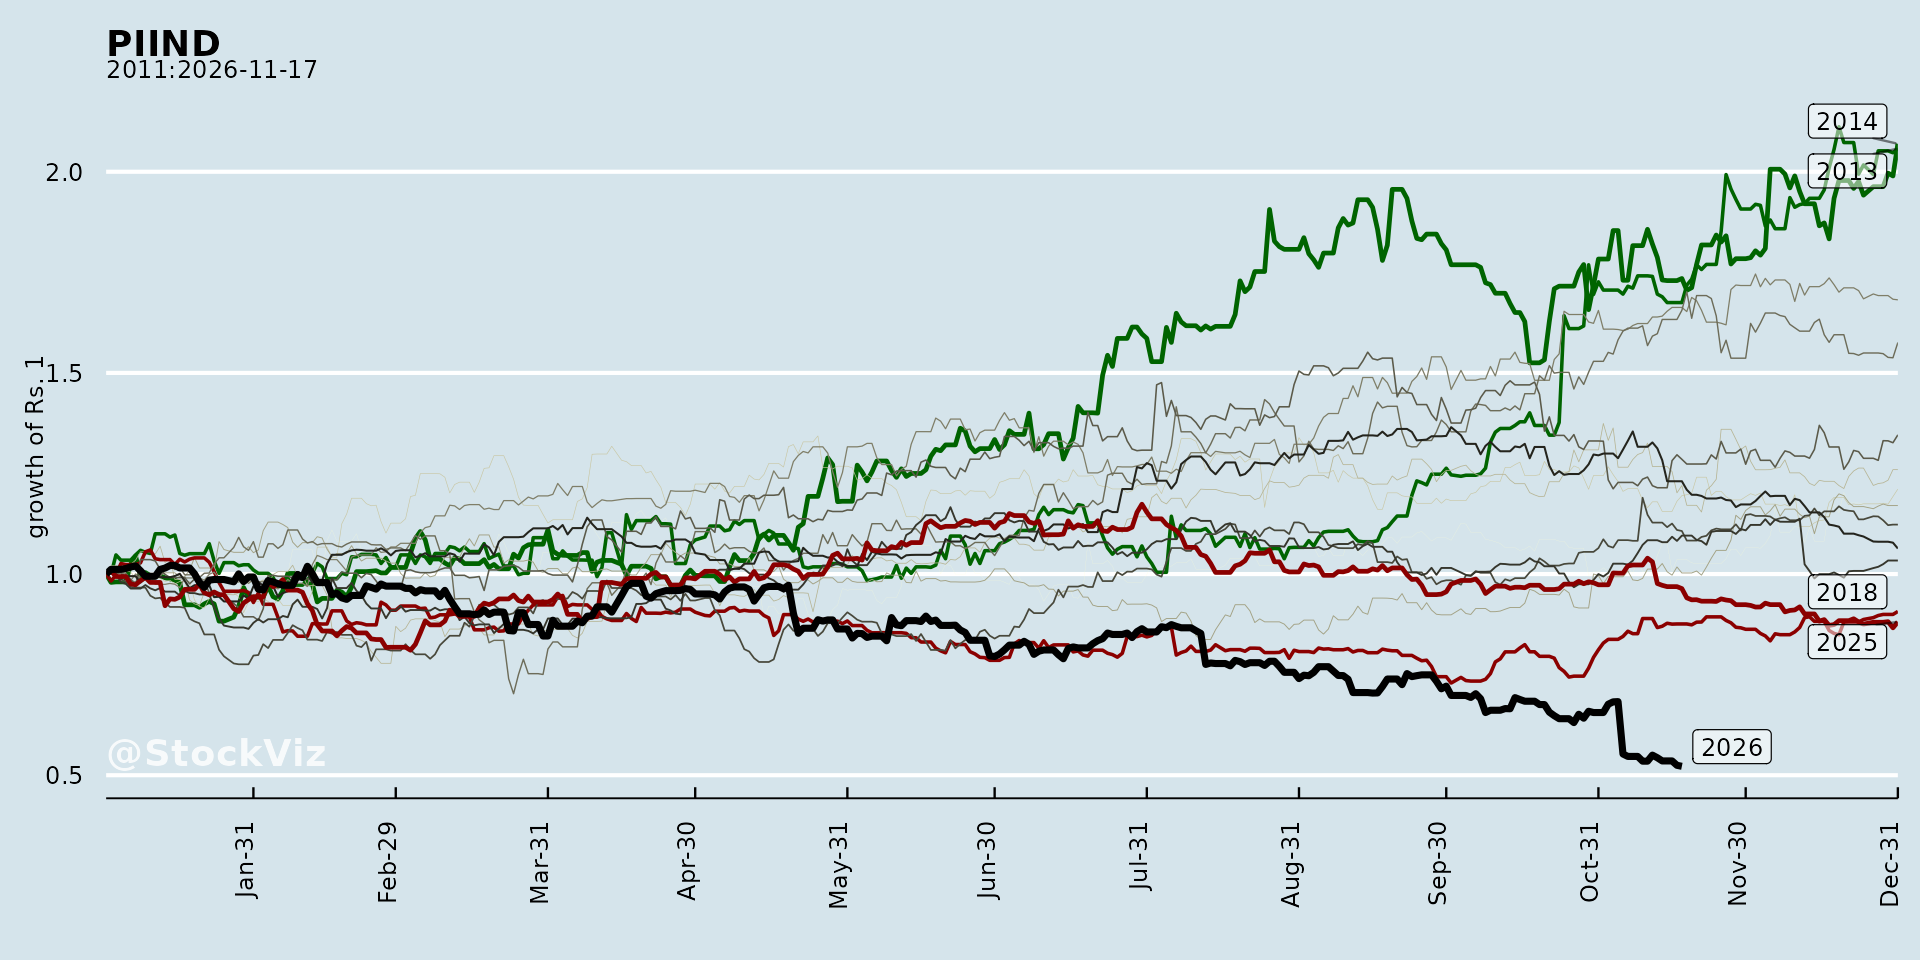
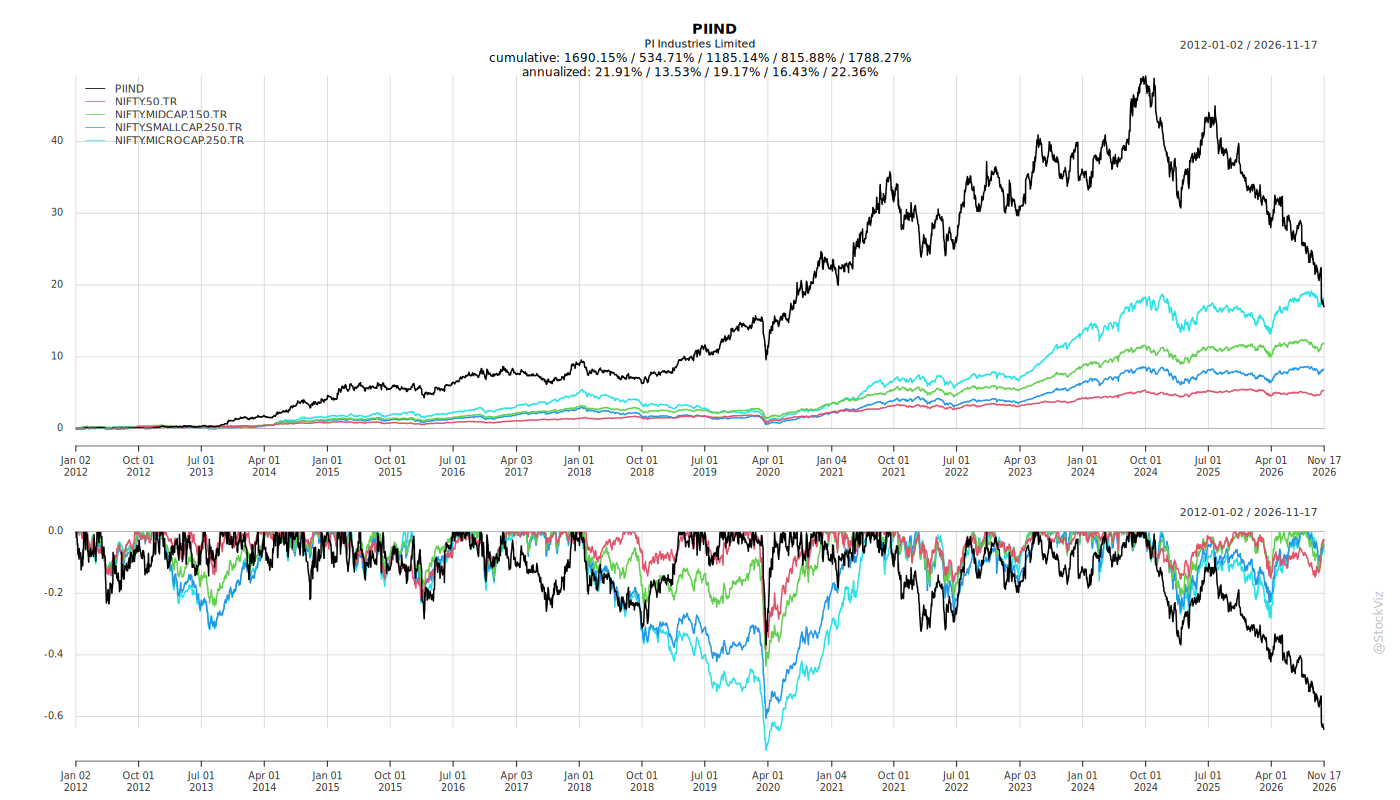
Cumulative Returns and Drawdowns
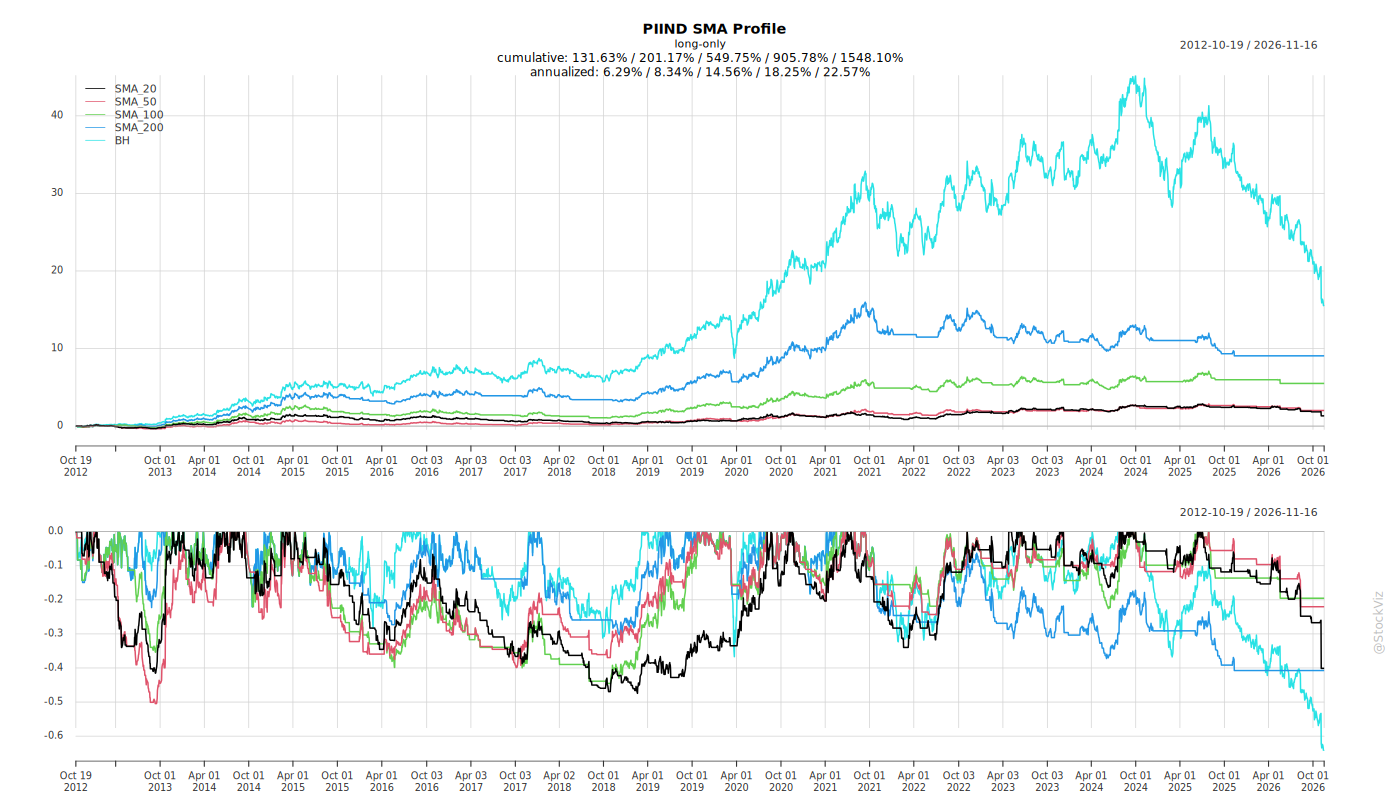
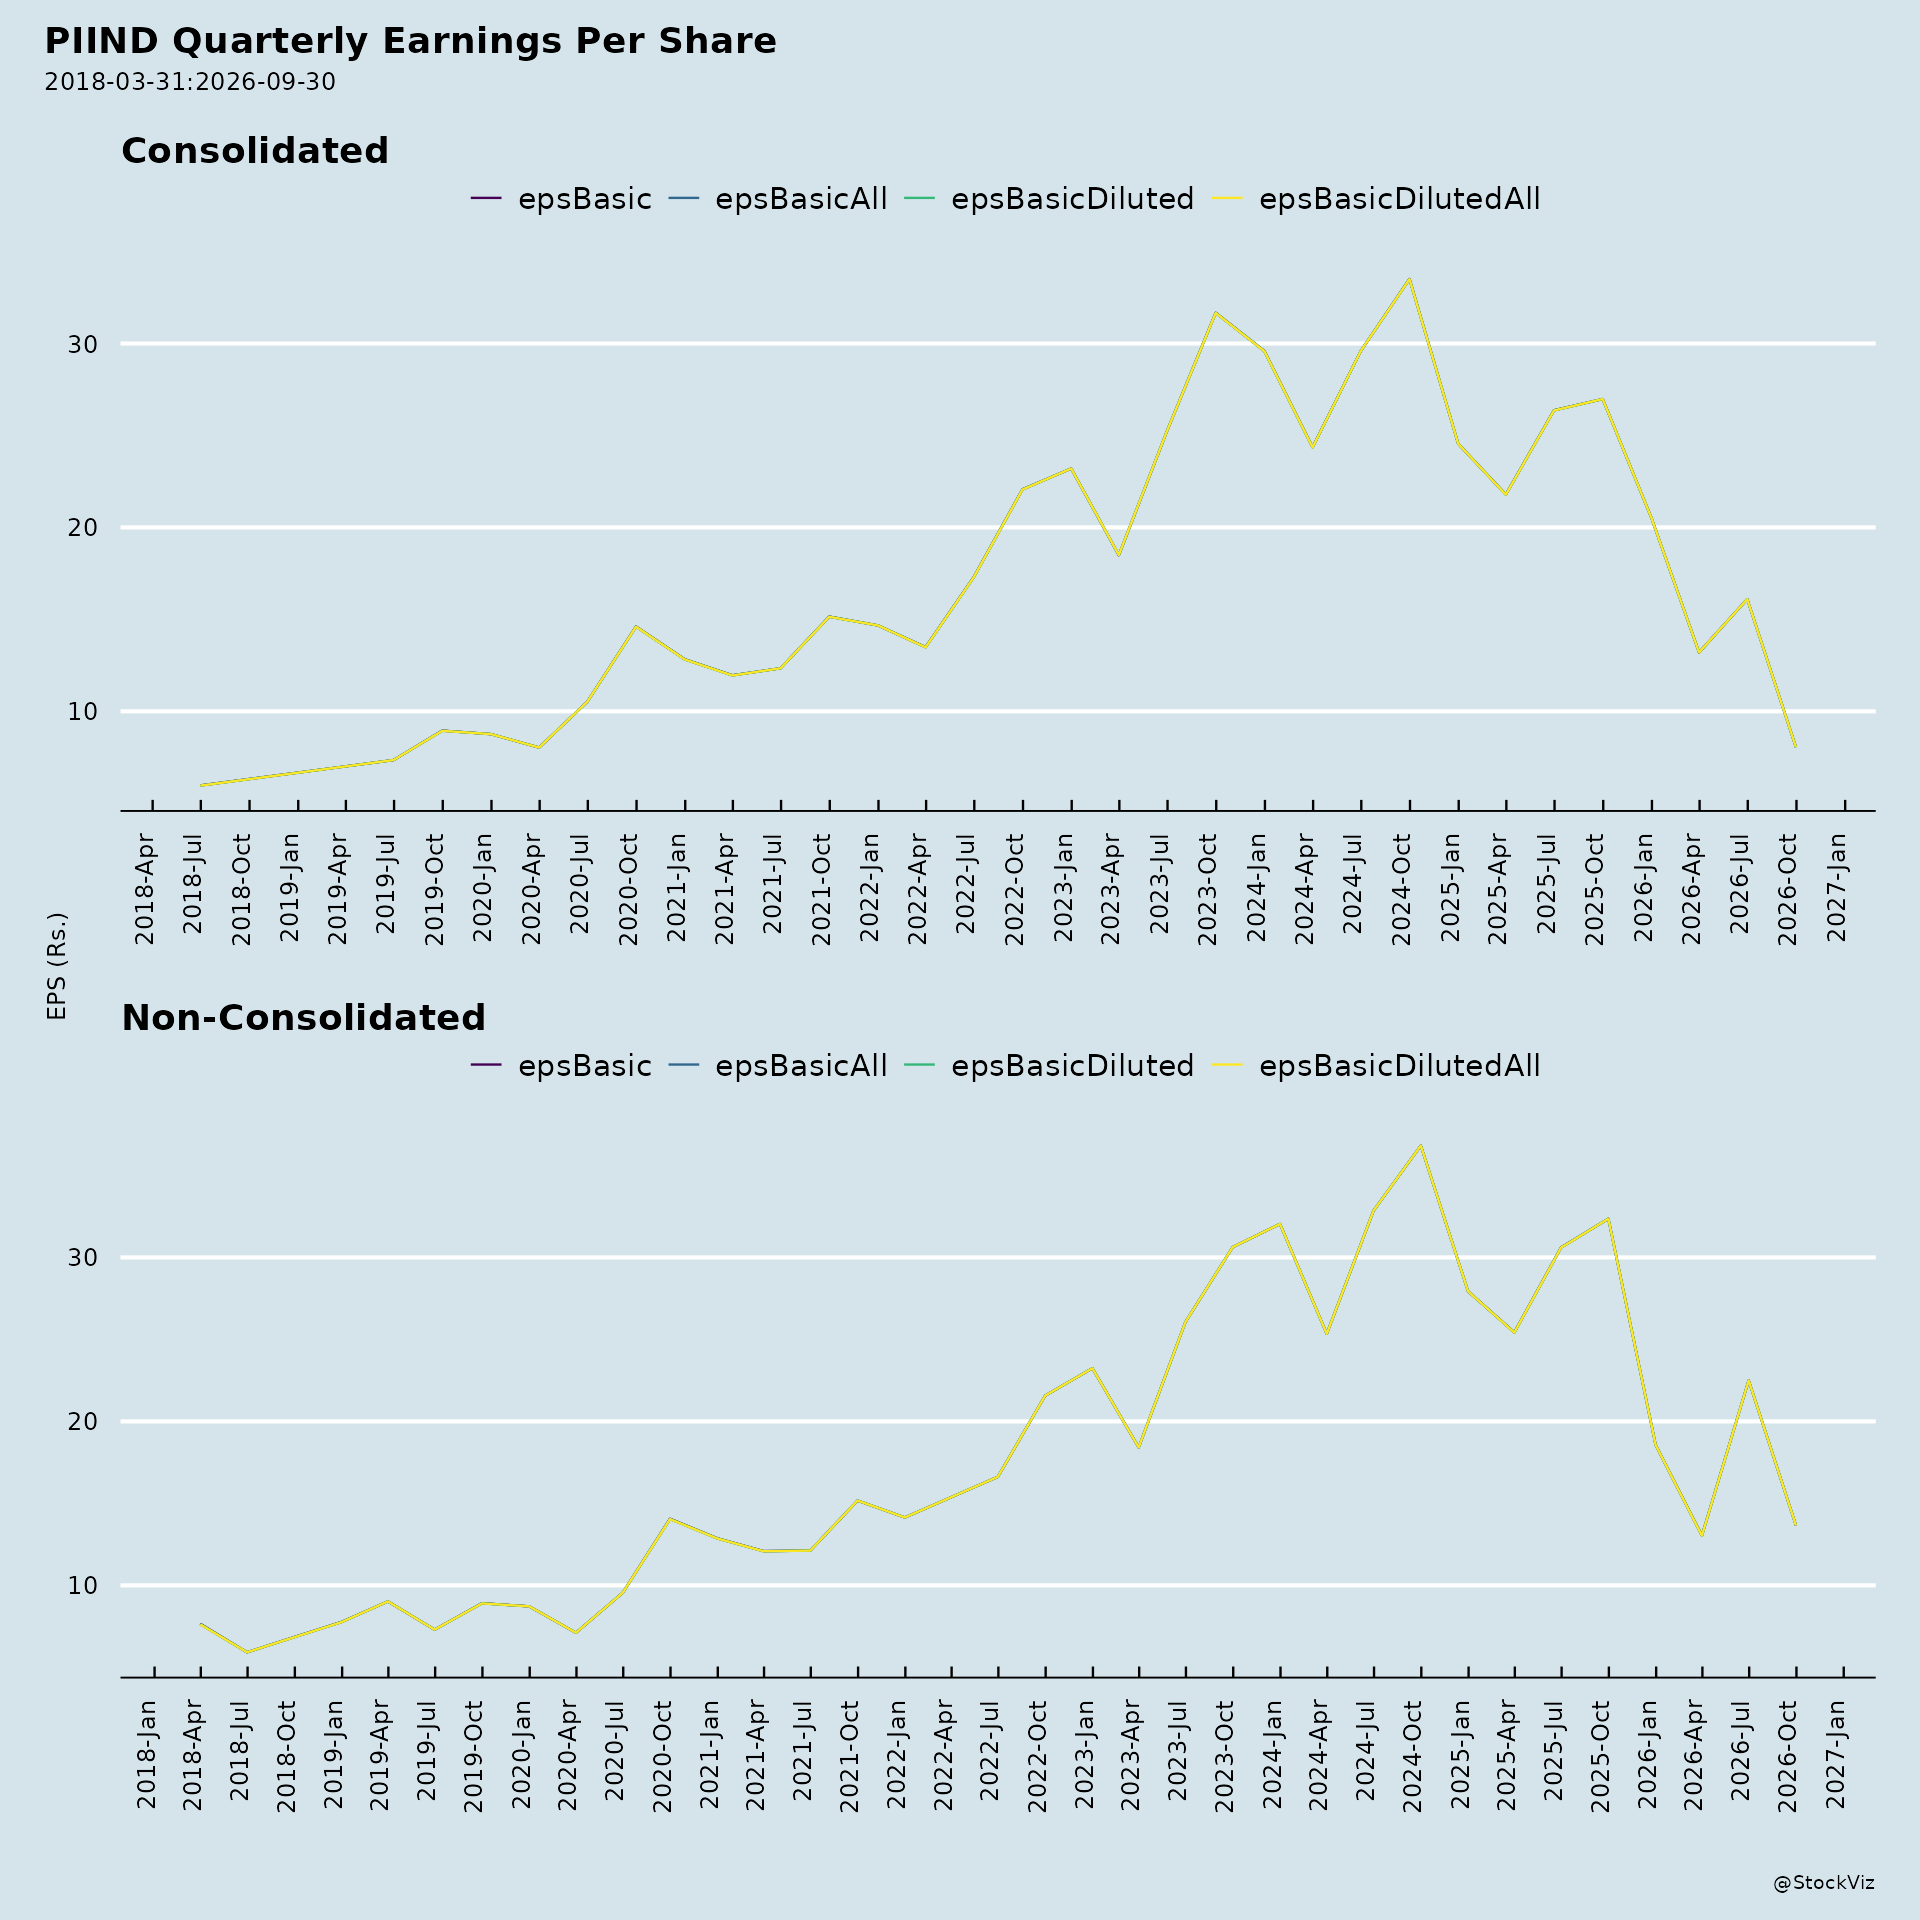
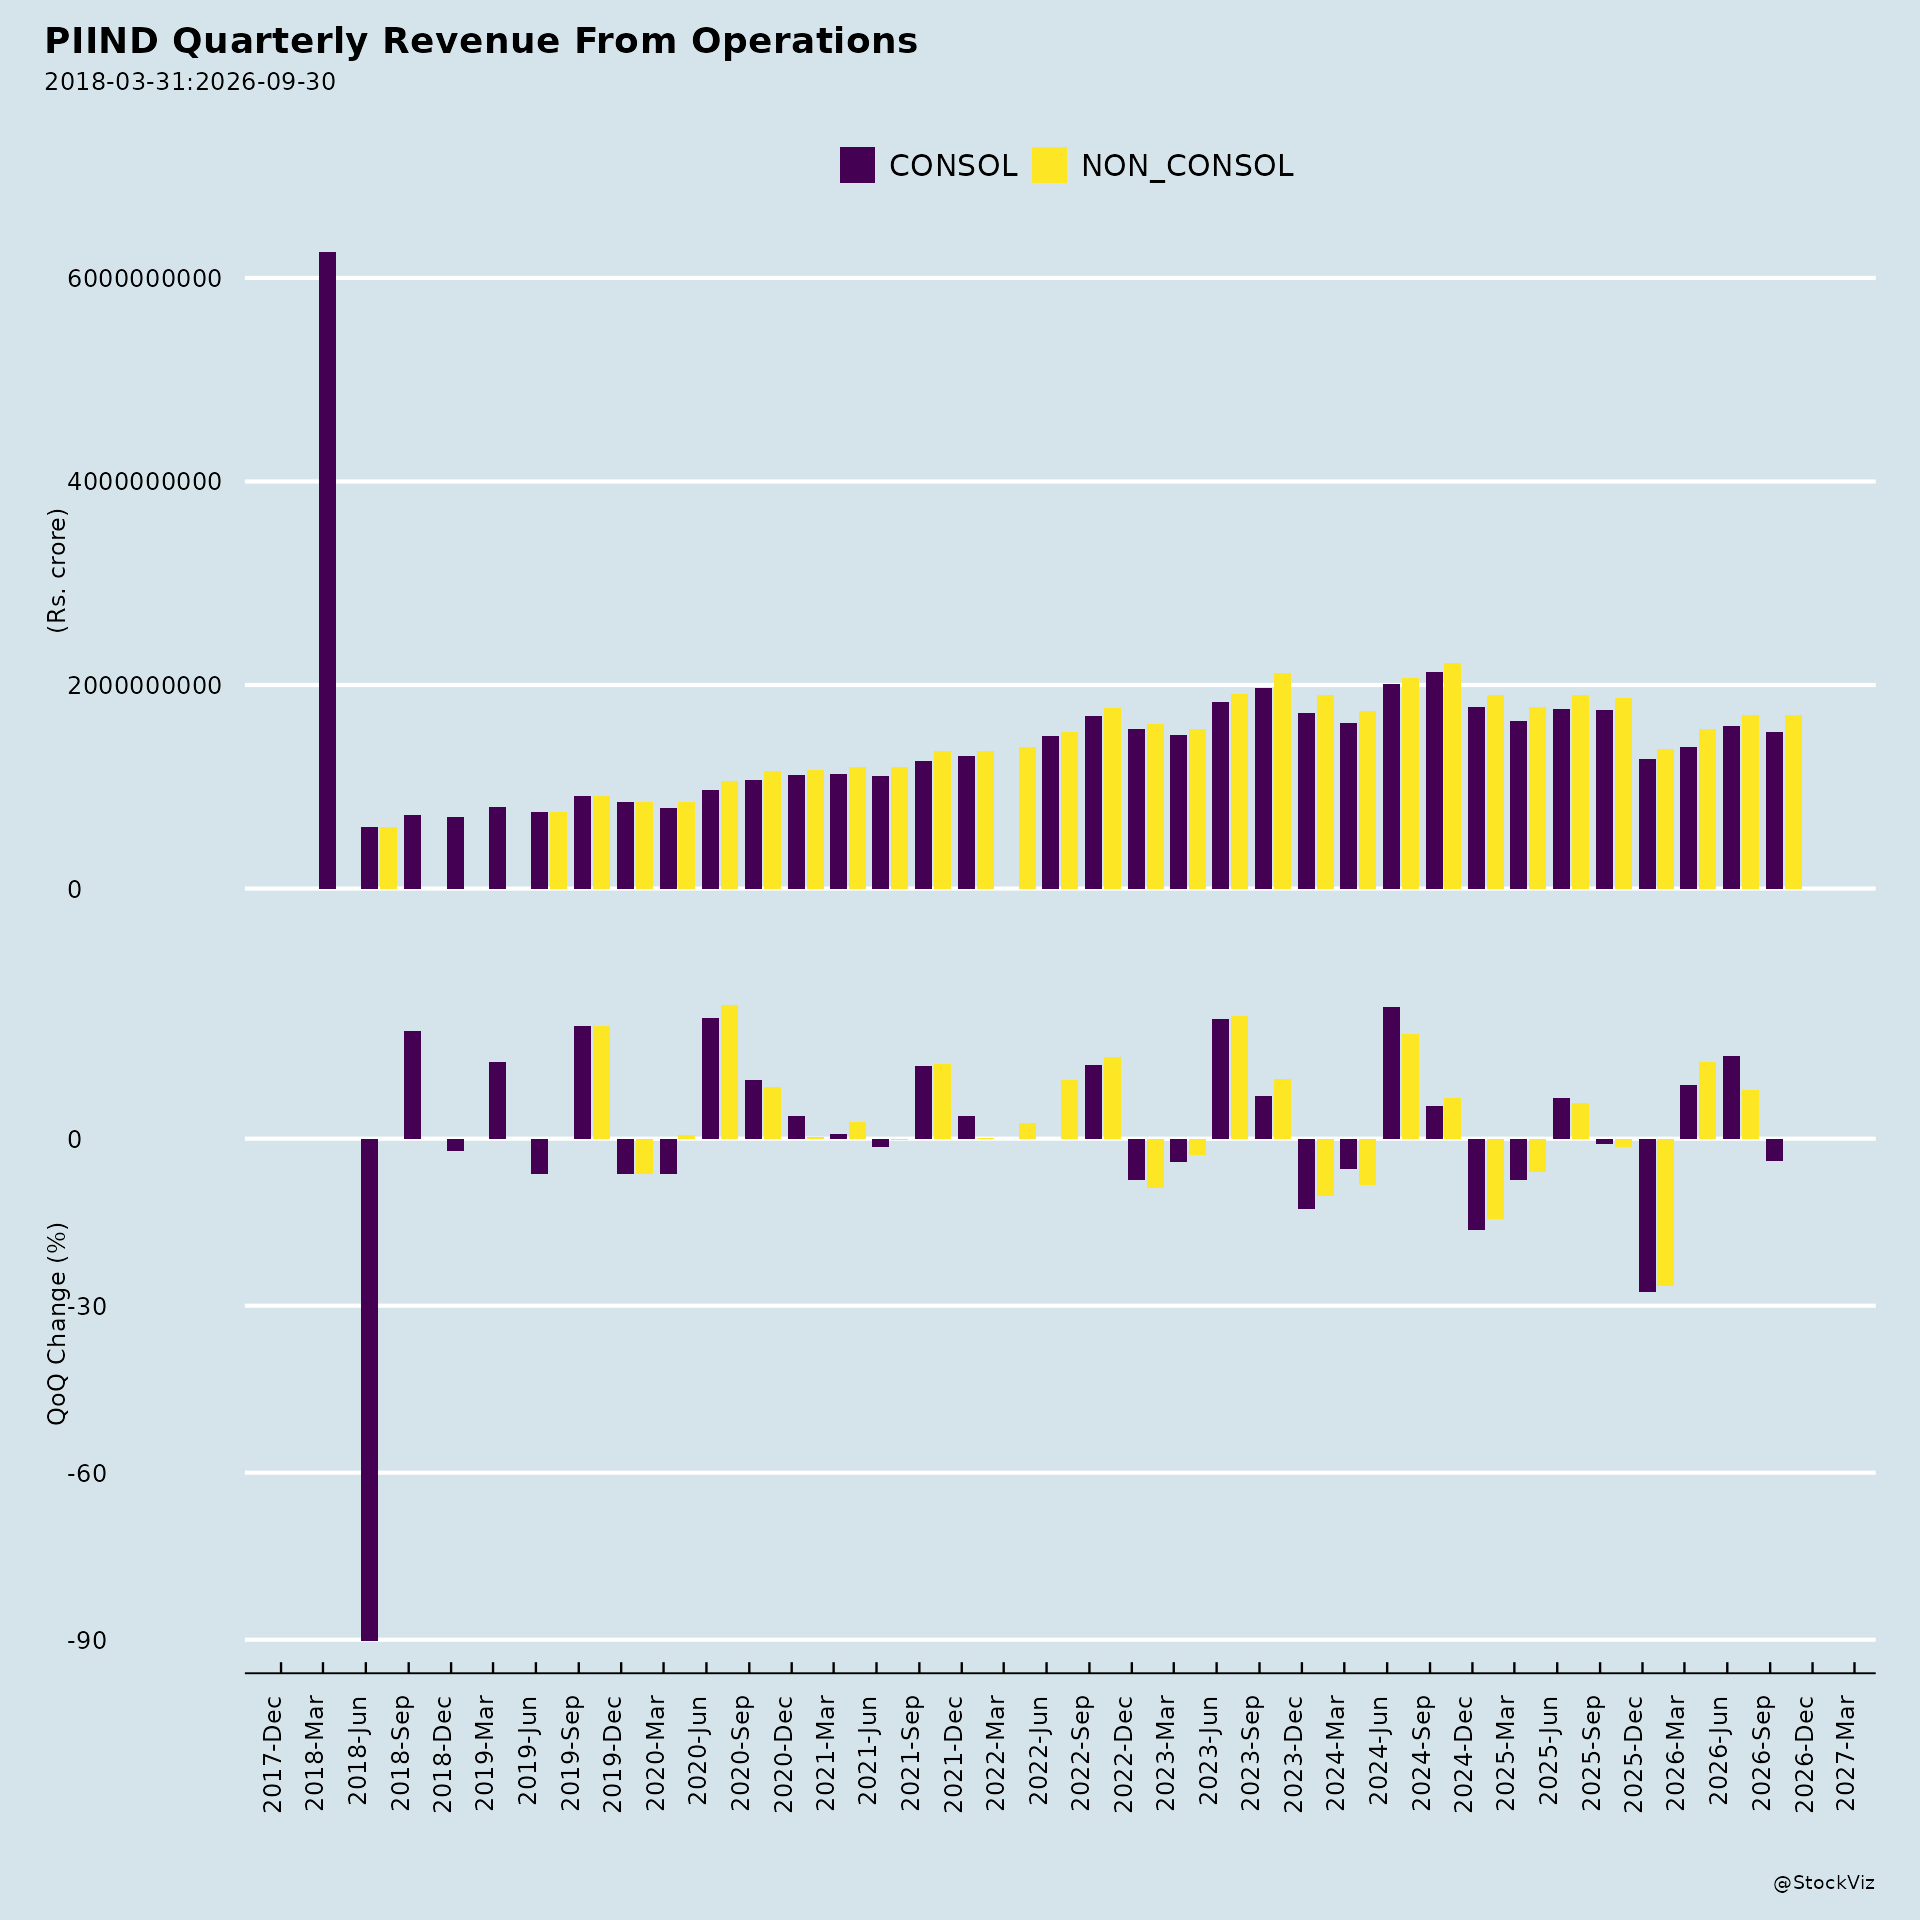
Fundamentals
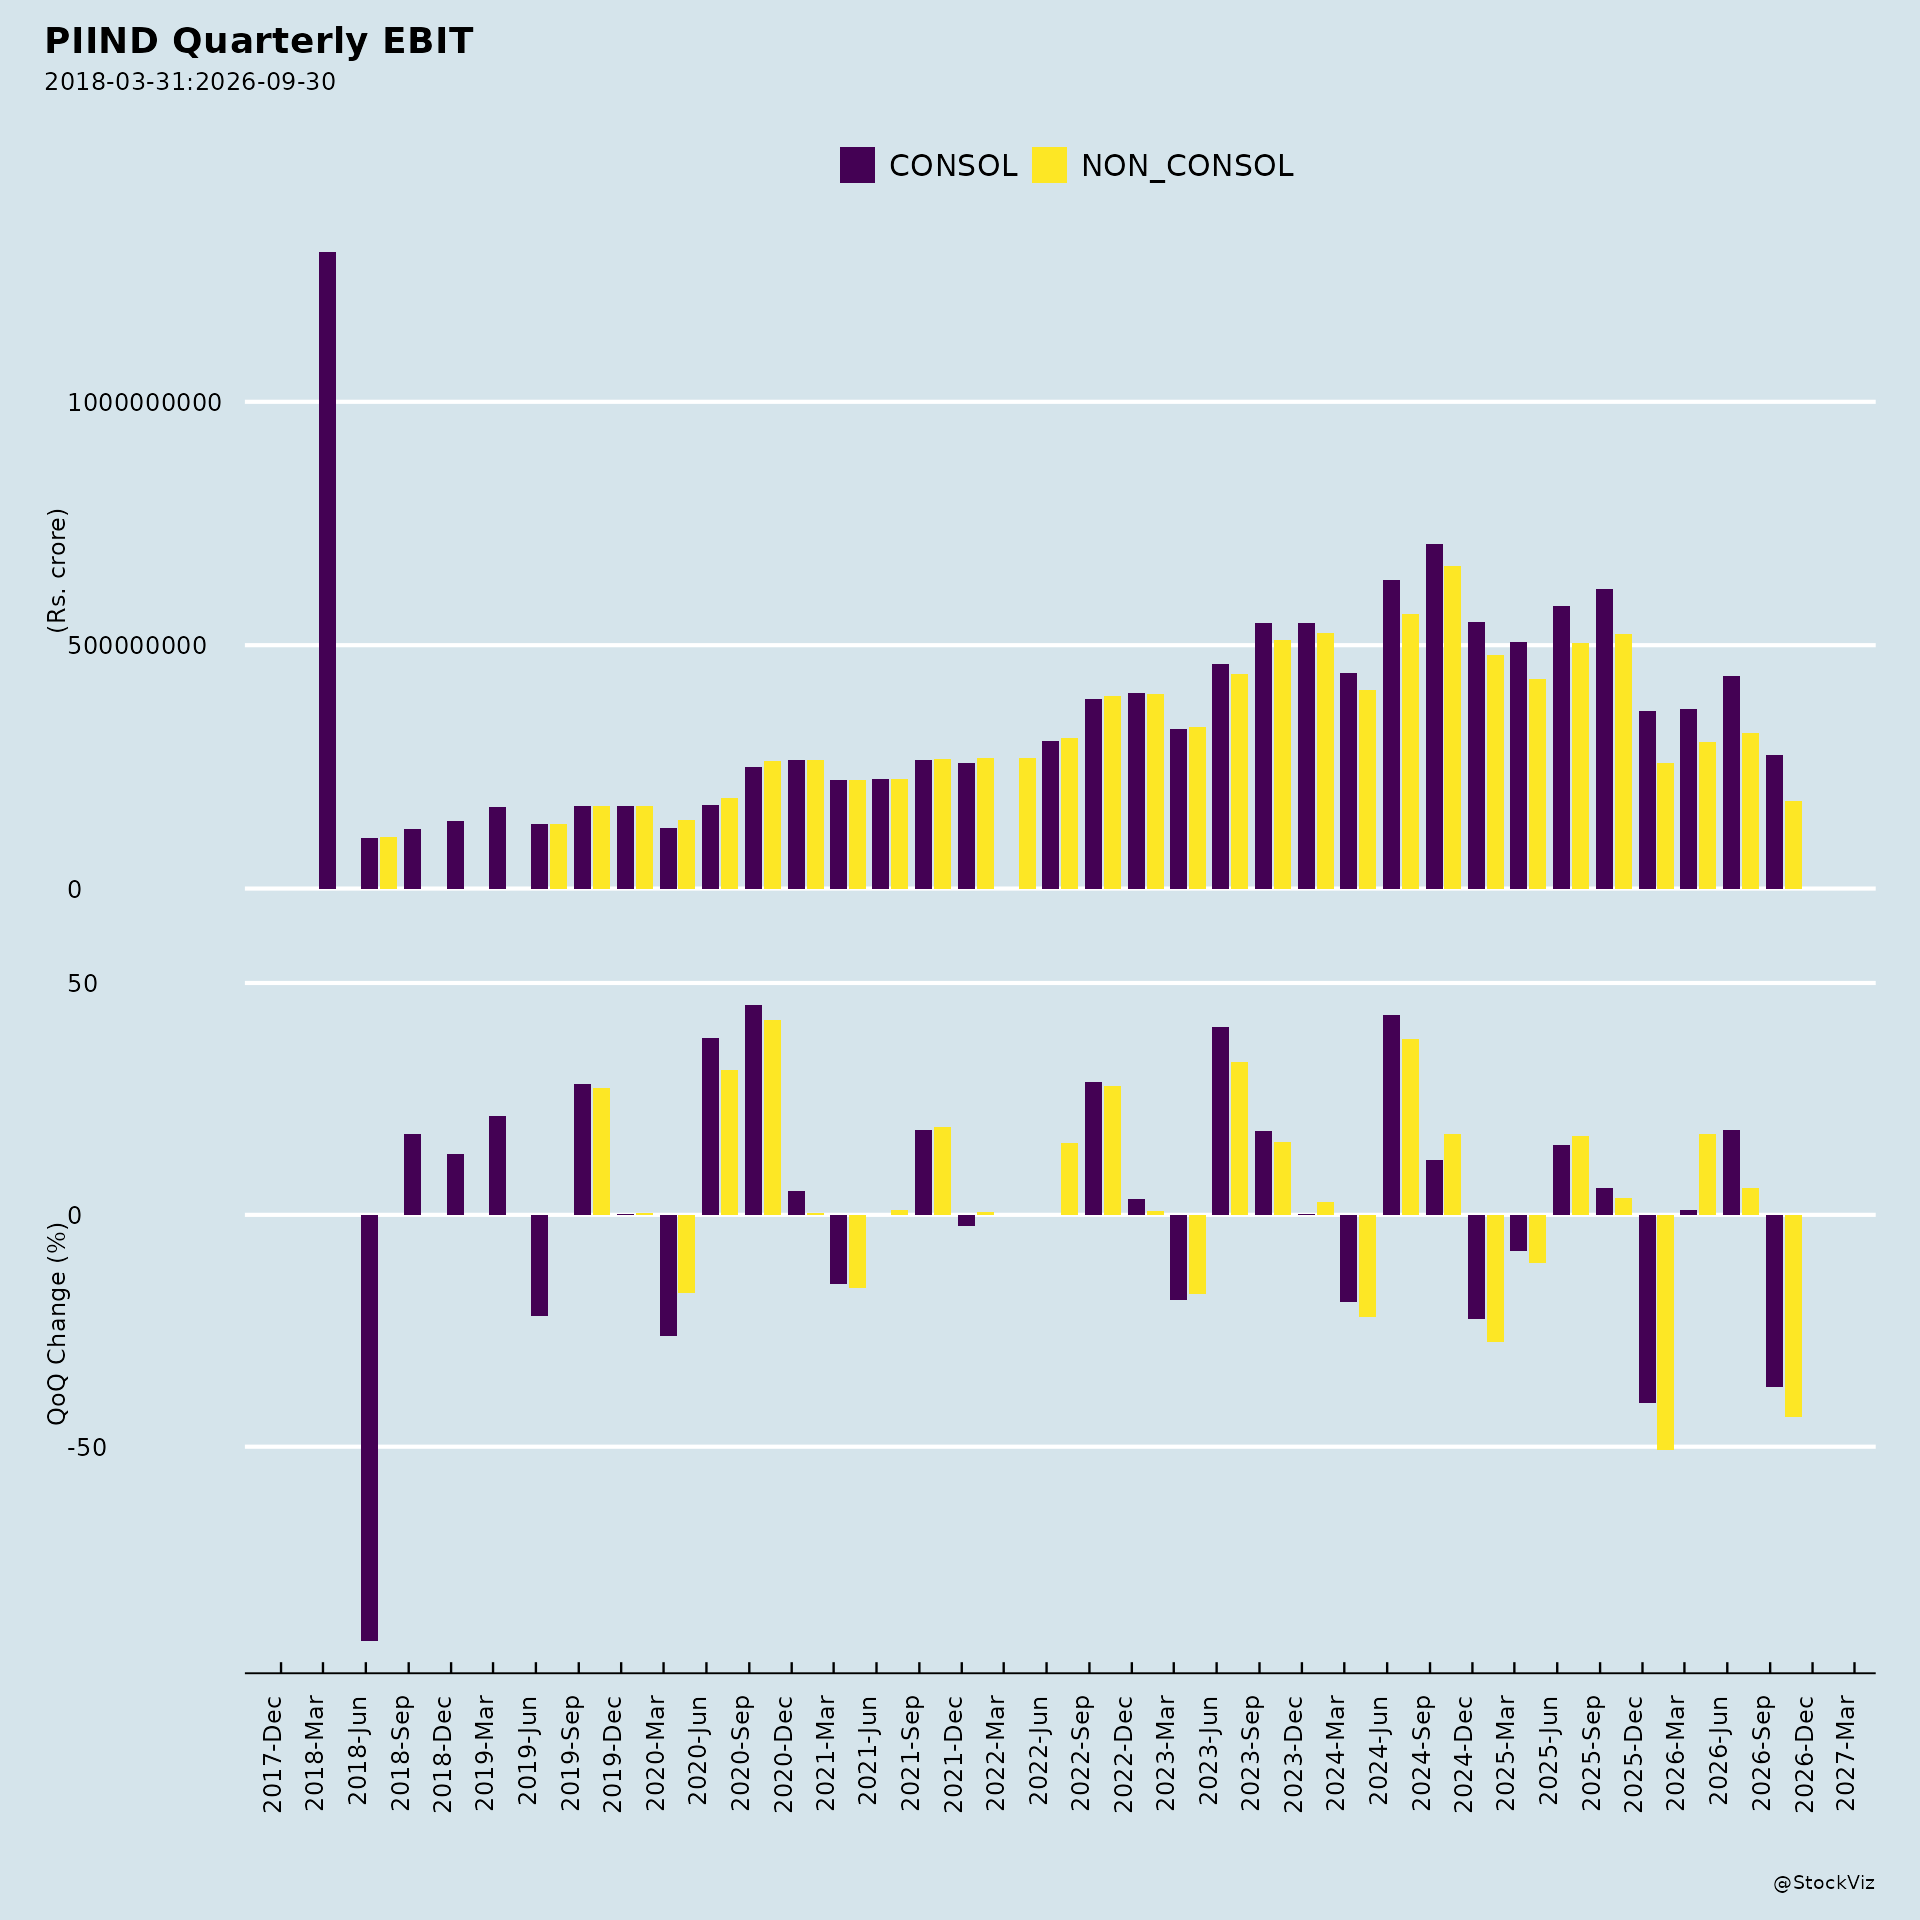
Ownership
Margined
AI Summary
asof: 2026-09-16
PI Industries (PIIND) — 79th AGM Voting Analysis
1. Headwinds and Challenges
- Director re-appointment drew significant institutional dissent. Resolution 3, the re-appointment of Mr. Rafael Del Rio Donoso as a director retiring by rotation, passed but with 12,425,320 votes against — 9.06% of votes polled. Public institutions opposed it heavily: 12,423,965 votes against, or 18.74% of their votes polled.
- Remuneration for Mr. Rafael Del Rio Donoso faced the strongest opposition. Resolution 6, covering remuneration payable to him as a Non-Executive Non-Independent Director, saw 21,443,079 votes against — 15.63% of votes polled. Public institutions cast 21,441,695 votes against, representing 32.32% of their votes polled.
- Independent director re-appointments also attracted notable negative votes. Resolution 9 (re-appointment of Ms. Pia Singh) recorded 13,077,512 votes against, or 9.53% of votes polled, with public institutions opposing at 19.71% of their votes. Resolution 8 (re-appointment of Mr. Shobinder Duggal) saw 725,858 votes against, or 0.53% of votes polled, with 1.11% of public institutional votes against.
- The special resolution for Dr. Atul Kumar Gupta’s appointment as Whole Time Director was not unanimous. Resolution 7 passed with 1,346,215 votes against, or 0.98% of votes polled; public institutions opposed at 2.03% of their votes.
- Even routine resolutions saw minor dissent. Resolution 2 (dividend confirmation/declaration) had 36,103 votes against, and Resolution 5 (cost auditor remuneration ratification) had 1,086 votes against.
2. Tailwinds and Growth Prospects
- All nine resolutions were passed with the requisite majority, as confirmed by the Scrutinizer’s Report dated August 14, 2026, issued by Mr. Ashish Kumar Friends, Practicing Company Secretary, A.K Friends and Company.
- Strong shareholder participation. Total votes polled across resolutions ranged from 89.86% to 90.41% of outstanding shares, indicating broad engagement.
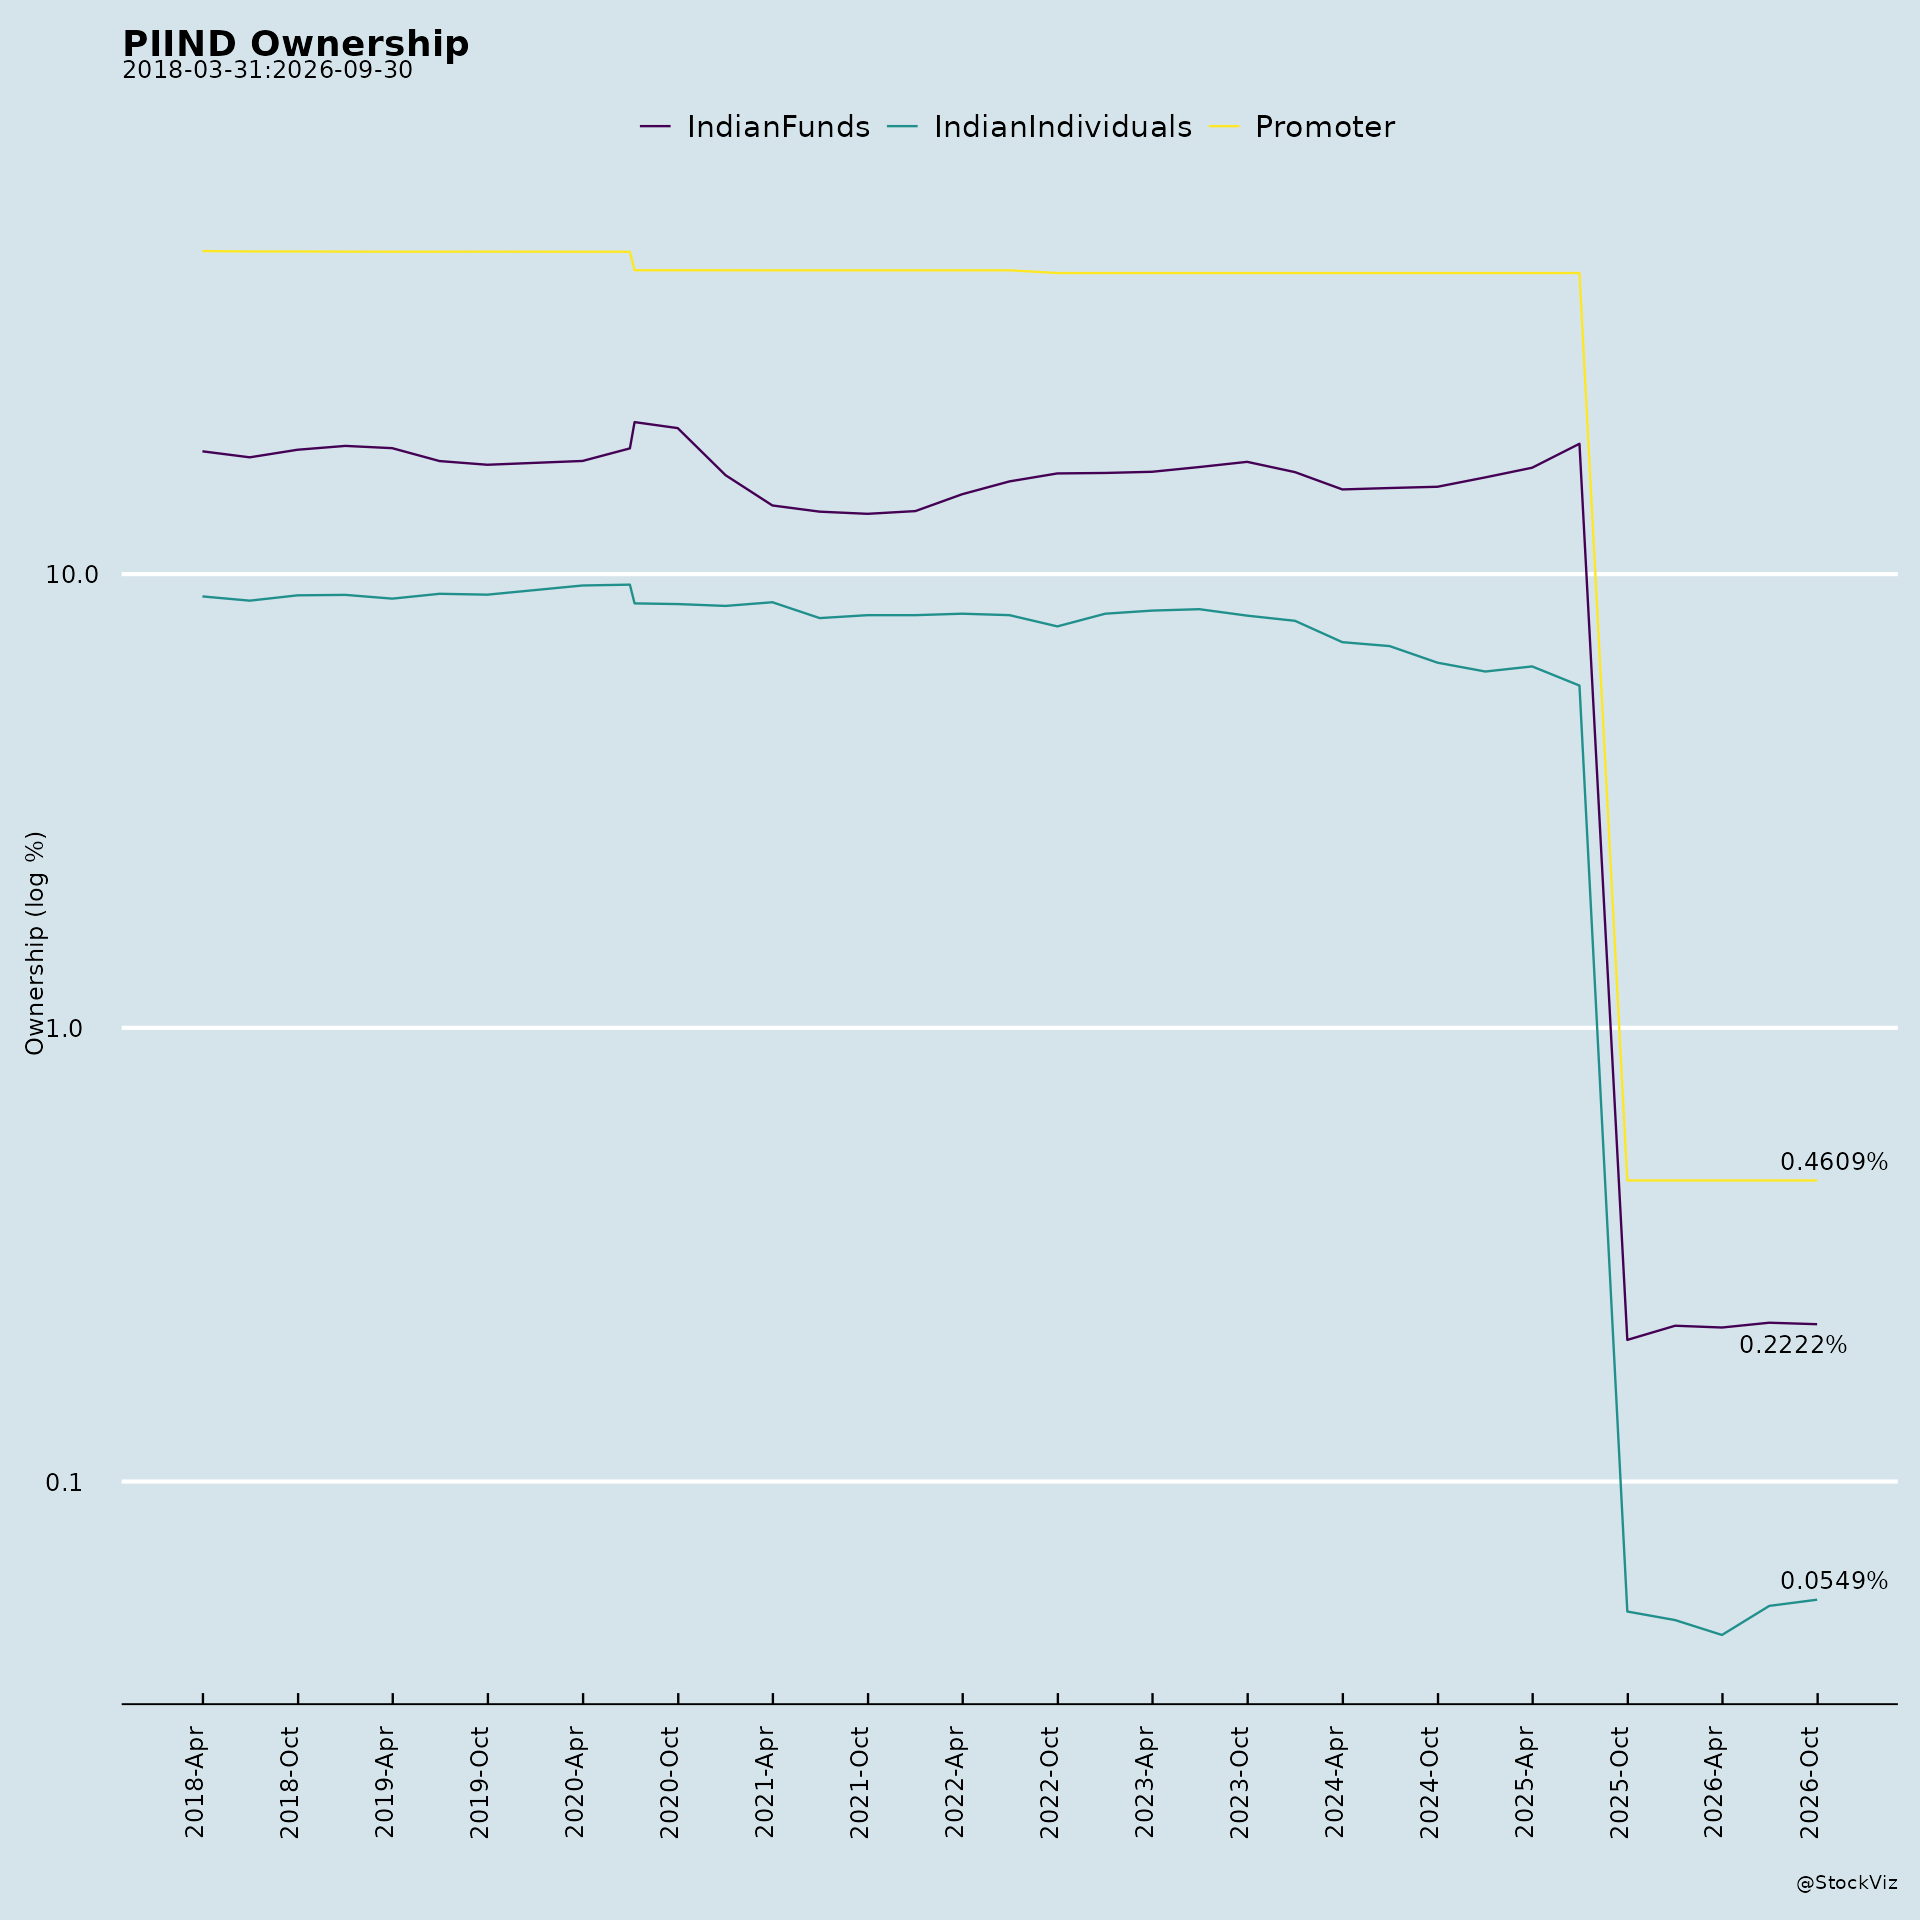
- Promoter and promoter group support was unanimous. On every resolution, 69,920,474 promoter votes were polled, all in favour, with zero against.
- Dividend resolutions received near-total backing. Resolution 2, confirming an interim dividend of Rs. 5.00 per equity share and declaring a final dividend of Rs. 10.00 per equity share (face value Re. 1.00 each), passed with 99.97% of votes in favour.
- Board continuity and leadership appointments were endorsed. Mr. Rafael Del Rio Donoso was re-appointed (Resolution 3), Dr. Atul Kumar Gupta was appointed as Director and Whole Time Director (Resolution 7), and Mr. Shobinder Duggal (Resolution 8) and Ms. Pia Singh (Resolution 9) were re-appointed as Independent Directors.
- Governance housekeeping was completed. Resolution 4 approved non-filling of the vacancy caused by retirement of Mr. Arvind Singhal as Non-Executive Non-Independent Director, and Resolution 5 ratified cost auditor remuneration for FY 2026-27.
3. Key Risks
- Concentration of promoter voting power. Promoter and promoter group held 69,920,474 shares, and their 100% in-favour votes were decisive in passing all resolutions, including those where public institutional opposition was material.
- Institutional investor dissatisfaction. The high against-votes from public institutions on Resolutions 3, 6, 8, and 9 signal governance or remuneration-related concerns among institutional shareholders.
- Related-party/remuneration sensitivity. The remuneration resolution for Mr. Rafael Del Rio Donoso (Resolution 6) attracted the largest protest vote (15.63% overall, 32.32% of public institutional votes), indicating sensitivity around non-executive director compensation.
- Board composition changes. The retirement of Mr. Arvind Singhal and the decision not to fill the vacancy (Resolution 4) alters board composition.
4. Management Guidance Versus Observed Business Performance
The supplied material does not contain management guidance or business performance data. It covers only the voting results and Scrutinizer’s Report of the 79th AGM held on Friday, August 14, 2026, at 10.30 A.M. (IST) through Video Conference/Other Audio-Visual Means. The resolutions relate to adoption of financial statements for the year ended March 31, 2026, dividend confirmation/declaration, director appointments and re-appointments, cost auditor remuneration ratification, and non-filling of a director vacancy. No forward-looking guidance or operational/financial performance metrics are provided in the source material.
Broker Narrative
The narrative moved from an overwhelmingly Buy/Accumulate stance in 2023-24, built on CSM growth, a patented-molecule moat and pharma diversification, to a defensive Hold by August 2026 as CSM/agchem and pharma revenues contracted. Weather/monsoon risk, input-cost margin pressure and generic-market stress persisted as recurring concerns from the first report to the last. The key change was the erosion of the ‘patented/innovator moat’ thesis: pyroxasulfone off-patent and genericization replaced pipeline optimism as the central challenge.
Fears that came true
- The weather/monsoon risk materialized, with later reports citing heat waves, delayed sowing and high inventory hurting domestic core agchem.
- Input-cost pressure materialized, as domestic agri margins remained under pressure due to higher input costs.
- Generic-market stress materialized, with global agrochemical genericization and pyroxasulfone going off patent hurting CSM growth.
- Export/CSM weakness materialized, as CSM segment revenue fell 12.7% YoY due to soft commodity prices and genericization.
Optimism that failed
- The strong CSM growth/pipeline optimism failed: projected 20% CSM CAGR and a ~USD 1.8bn order book did not prevent a 12.7% YoY CSM revenue decline.
- Pharma diversification optimism failed: expected pharma revenue contribution did not provide stability, as pharma revenue contracted 25% YoY due to order book phasing.
- The patented/innovator-moat optimism failed: the portfolio was not immune to generic headwinds, with pyroxasulfone off-patent concentration becoming a growth challenge.
- The domestic traction/guidance optimism failed: the 18-20% FY24 ex-pharma revenue growth view was undermined by heat waves, delayed sowing and high inventory, with later branded agchem growth only 2% YoY.
Broker Timeline
24 broker calls · 2023-05-22 to 2026-08-12
CNBC-TV18: ratings, targets and commentary
No recorded CNBC-TV18 statements for this ticker.
Management comments
No recorded management comments with an explicit designation and affiliation for this ticker.
Copyright © 2023 SAS Data Analytics Pvt. Ltd. All rights reserved.