PIDILITIND
Equity Metrics
September 24, 2026
Pidilite Industries Limited
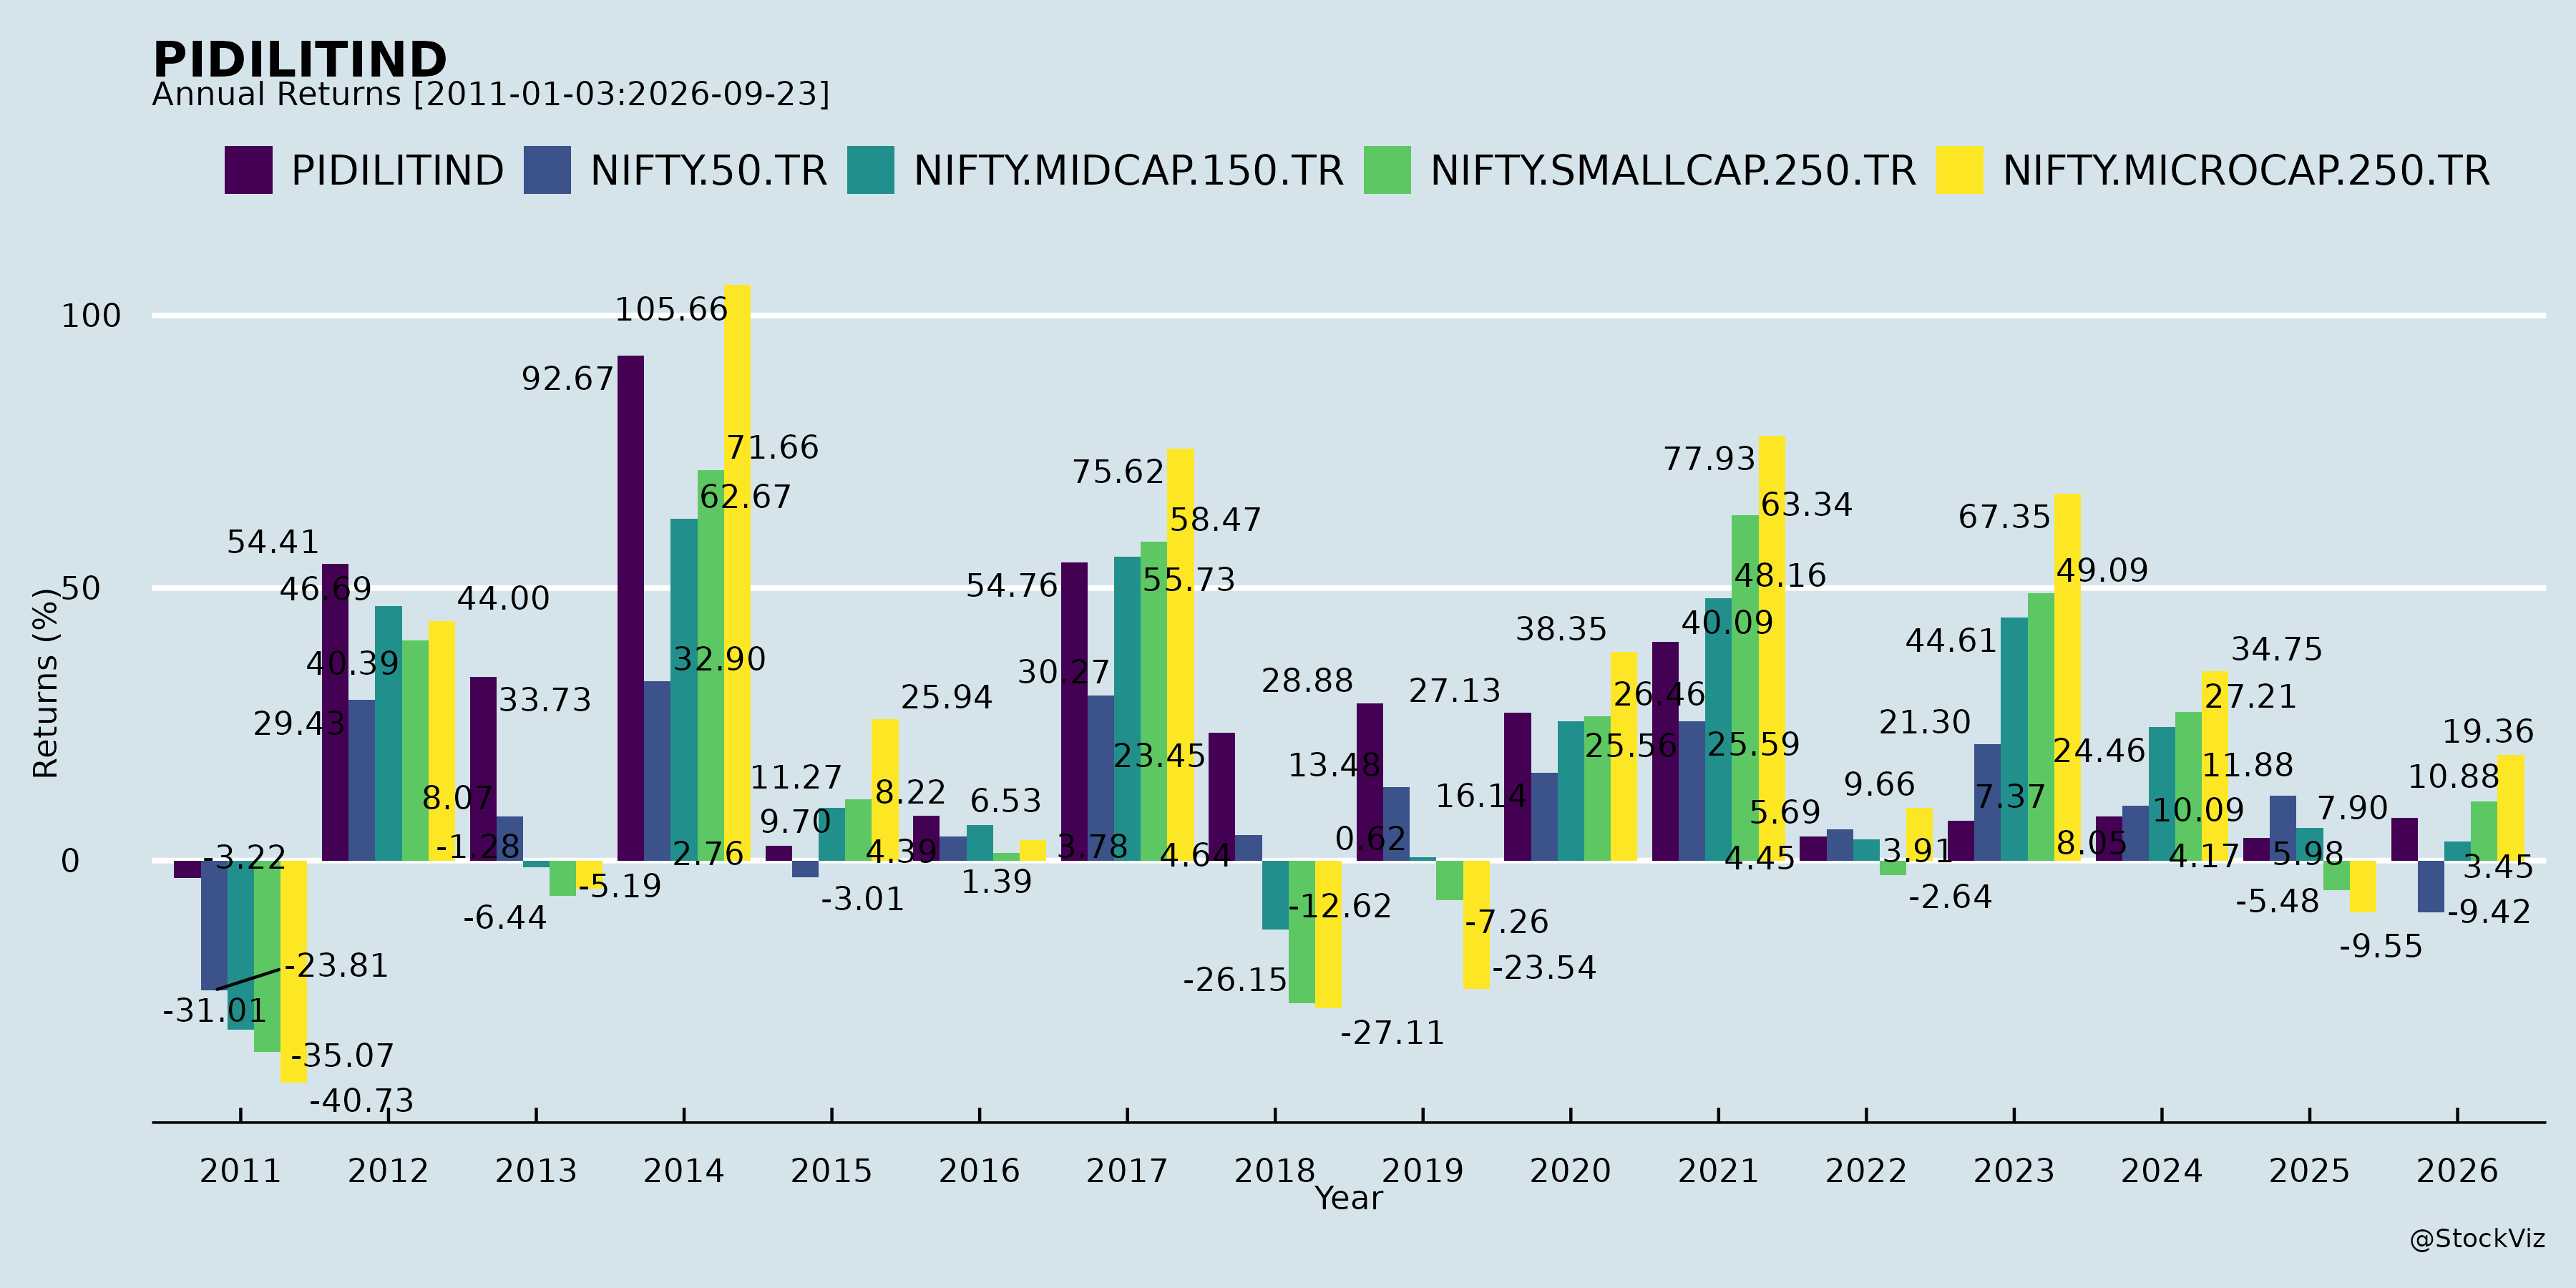
Annual Returns
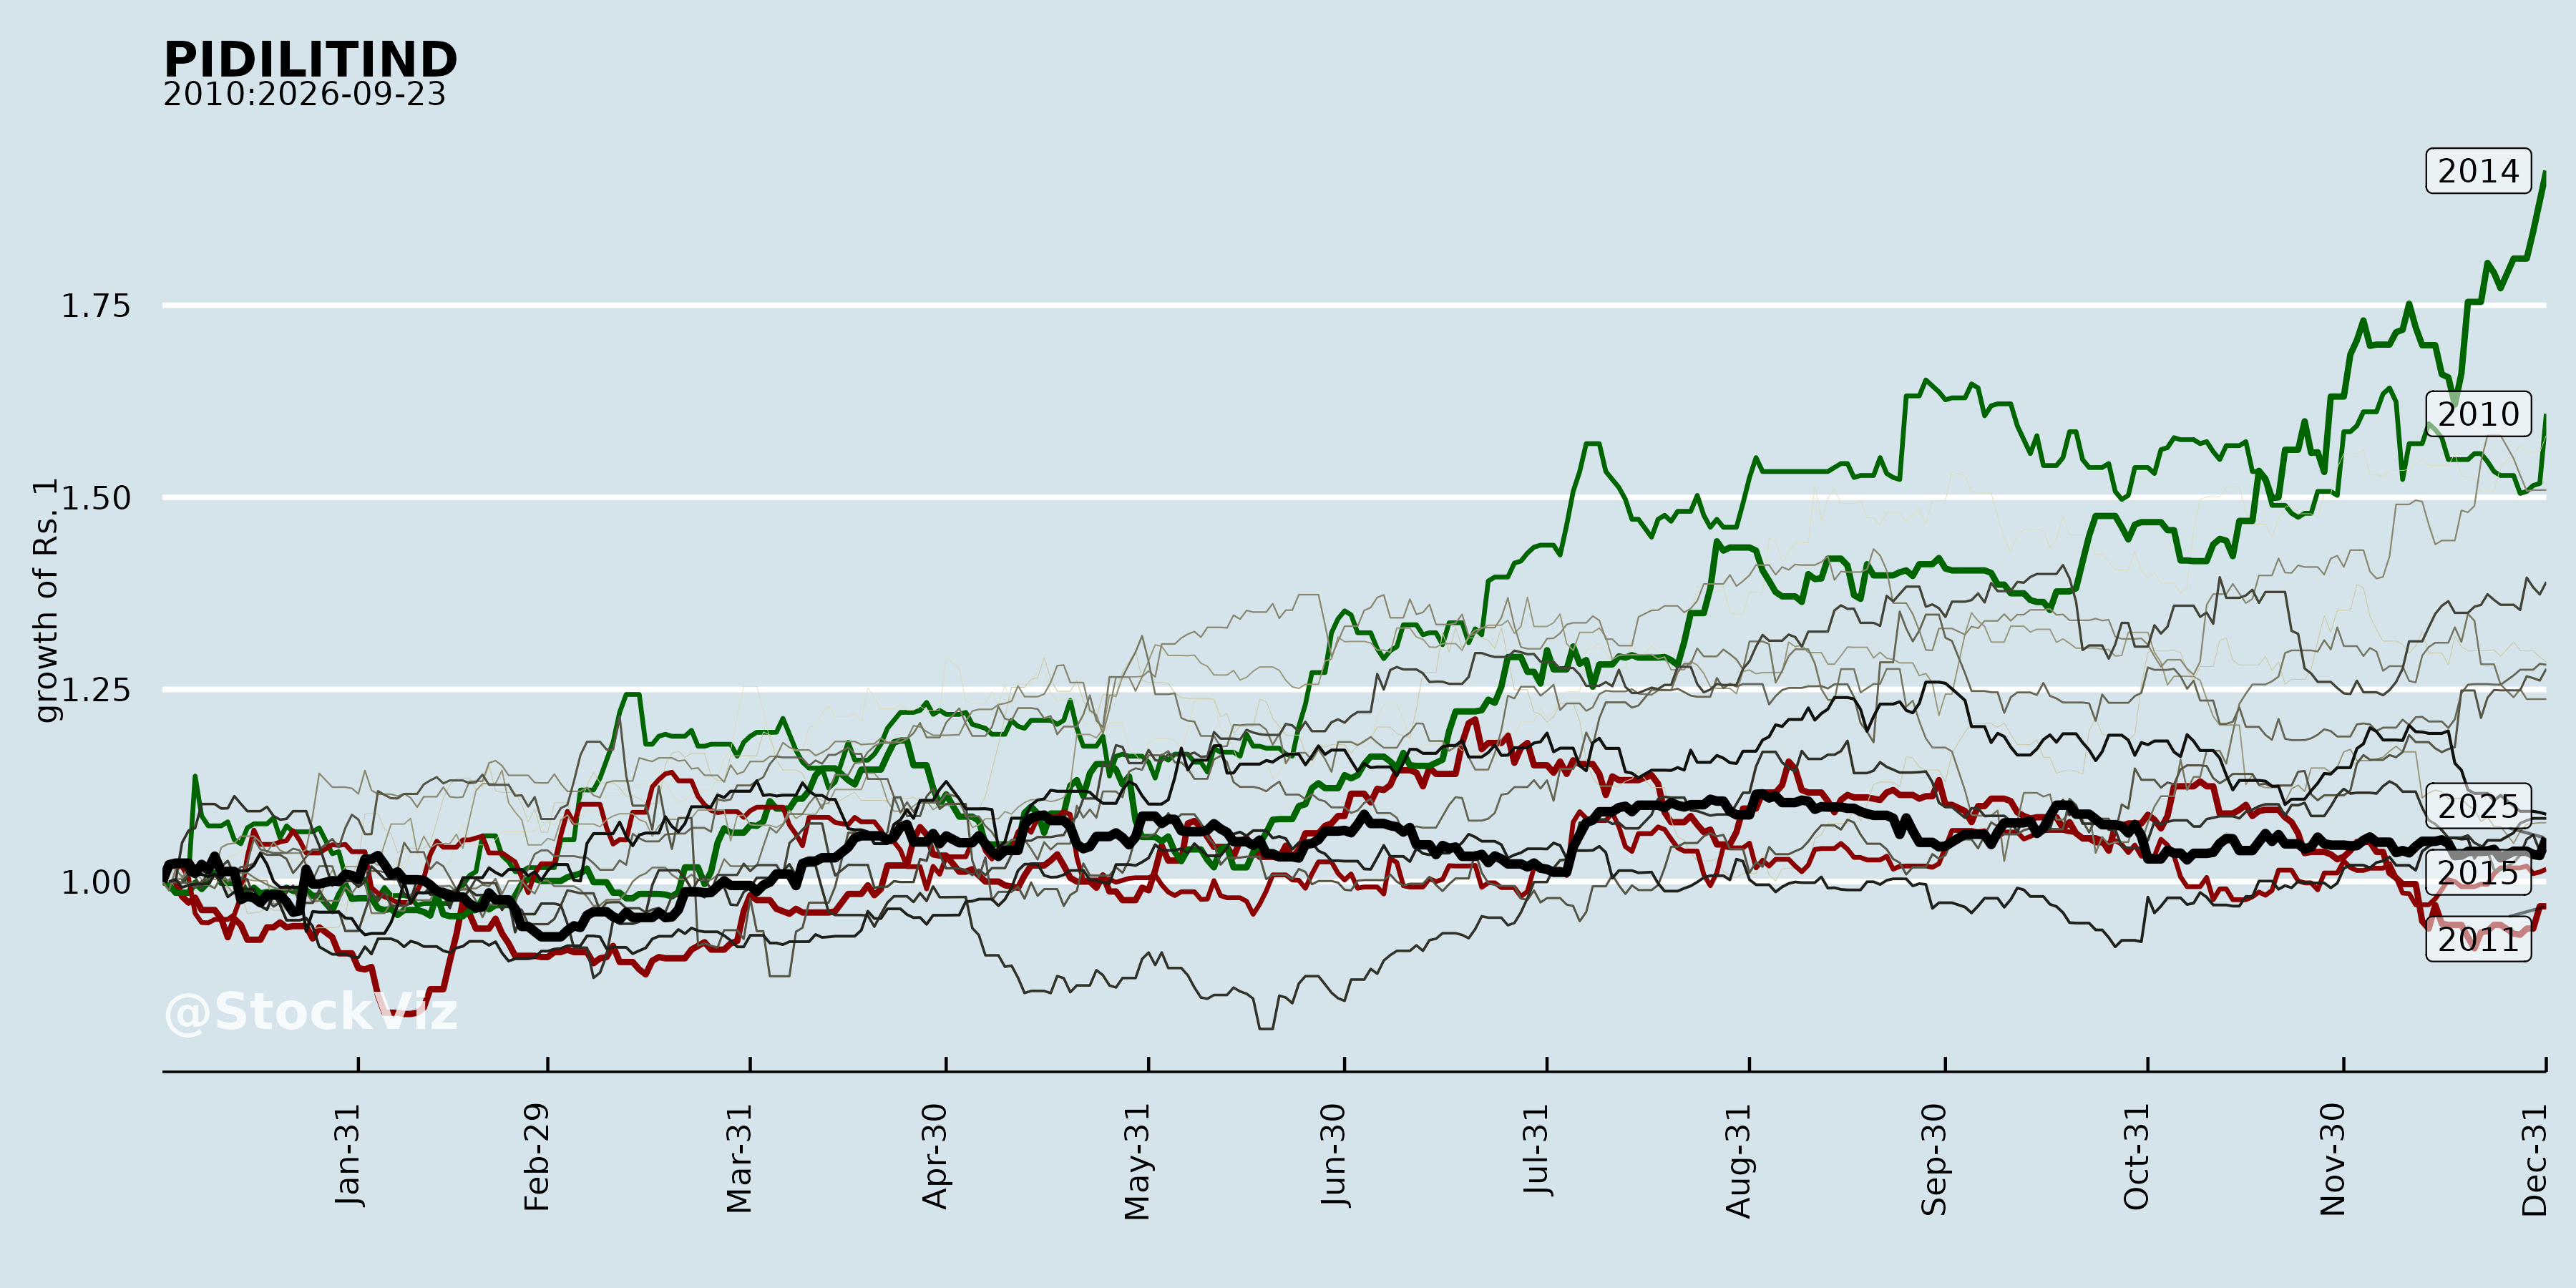
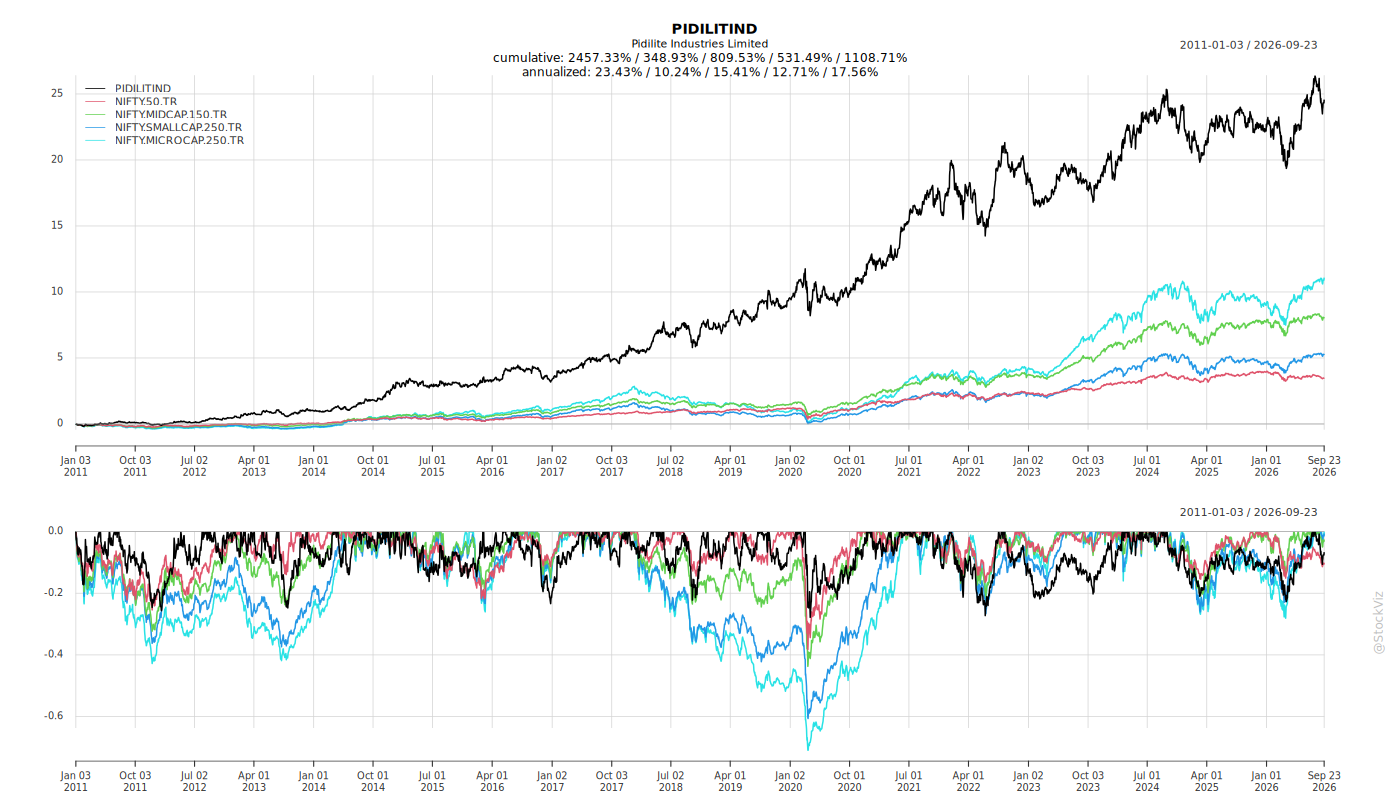
Cumulative Returns and Drawdowns
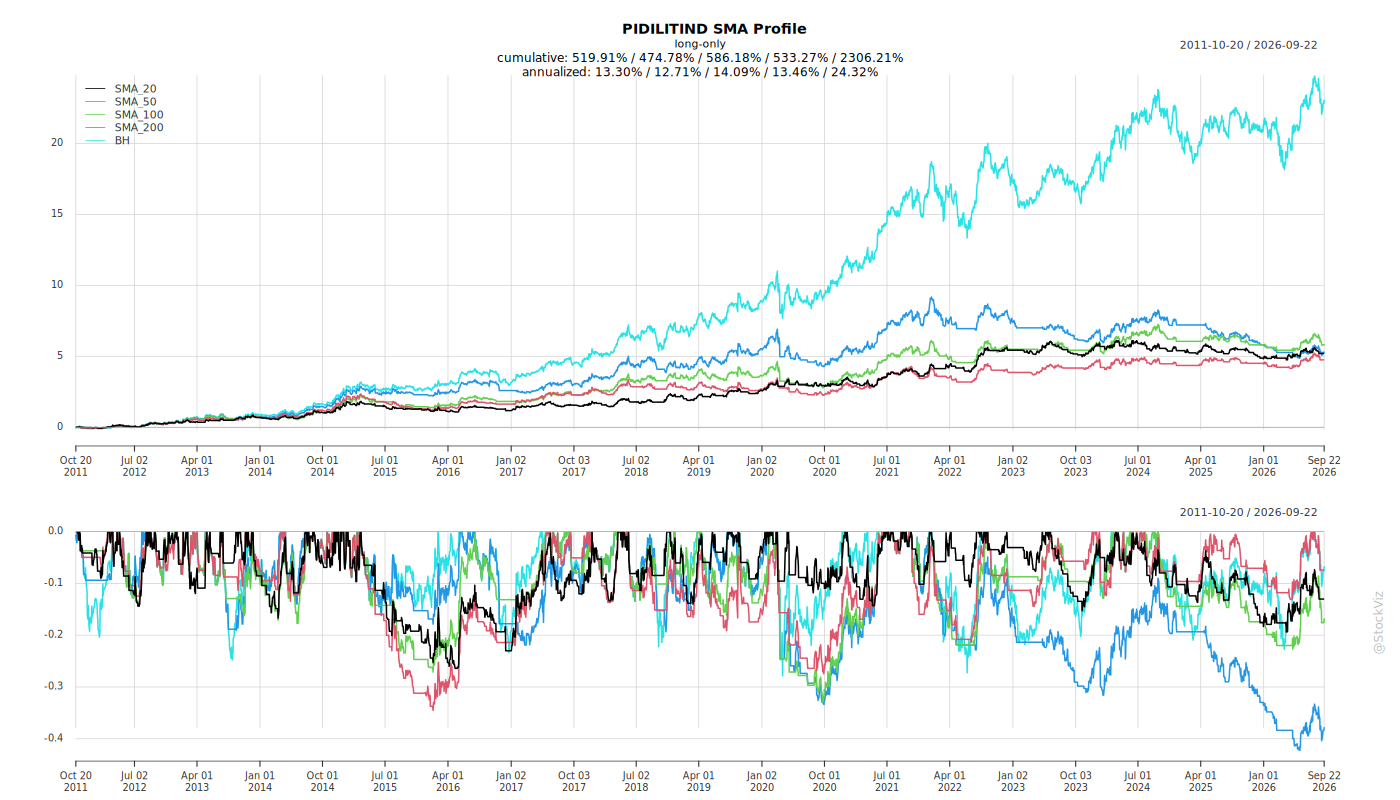
Fundamentals
Ownership
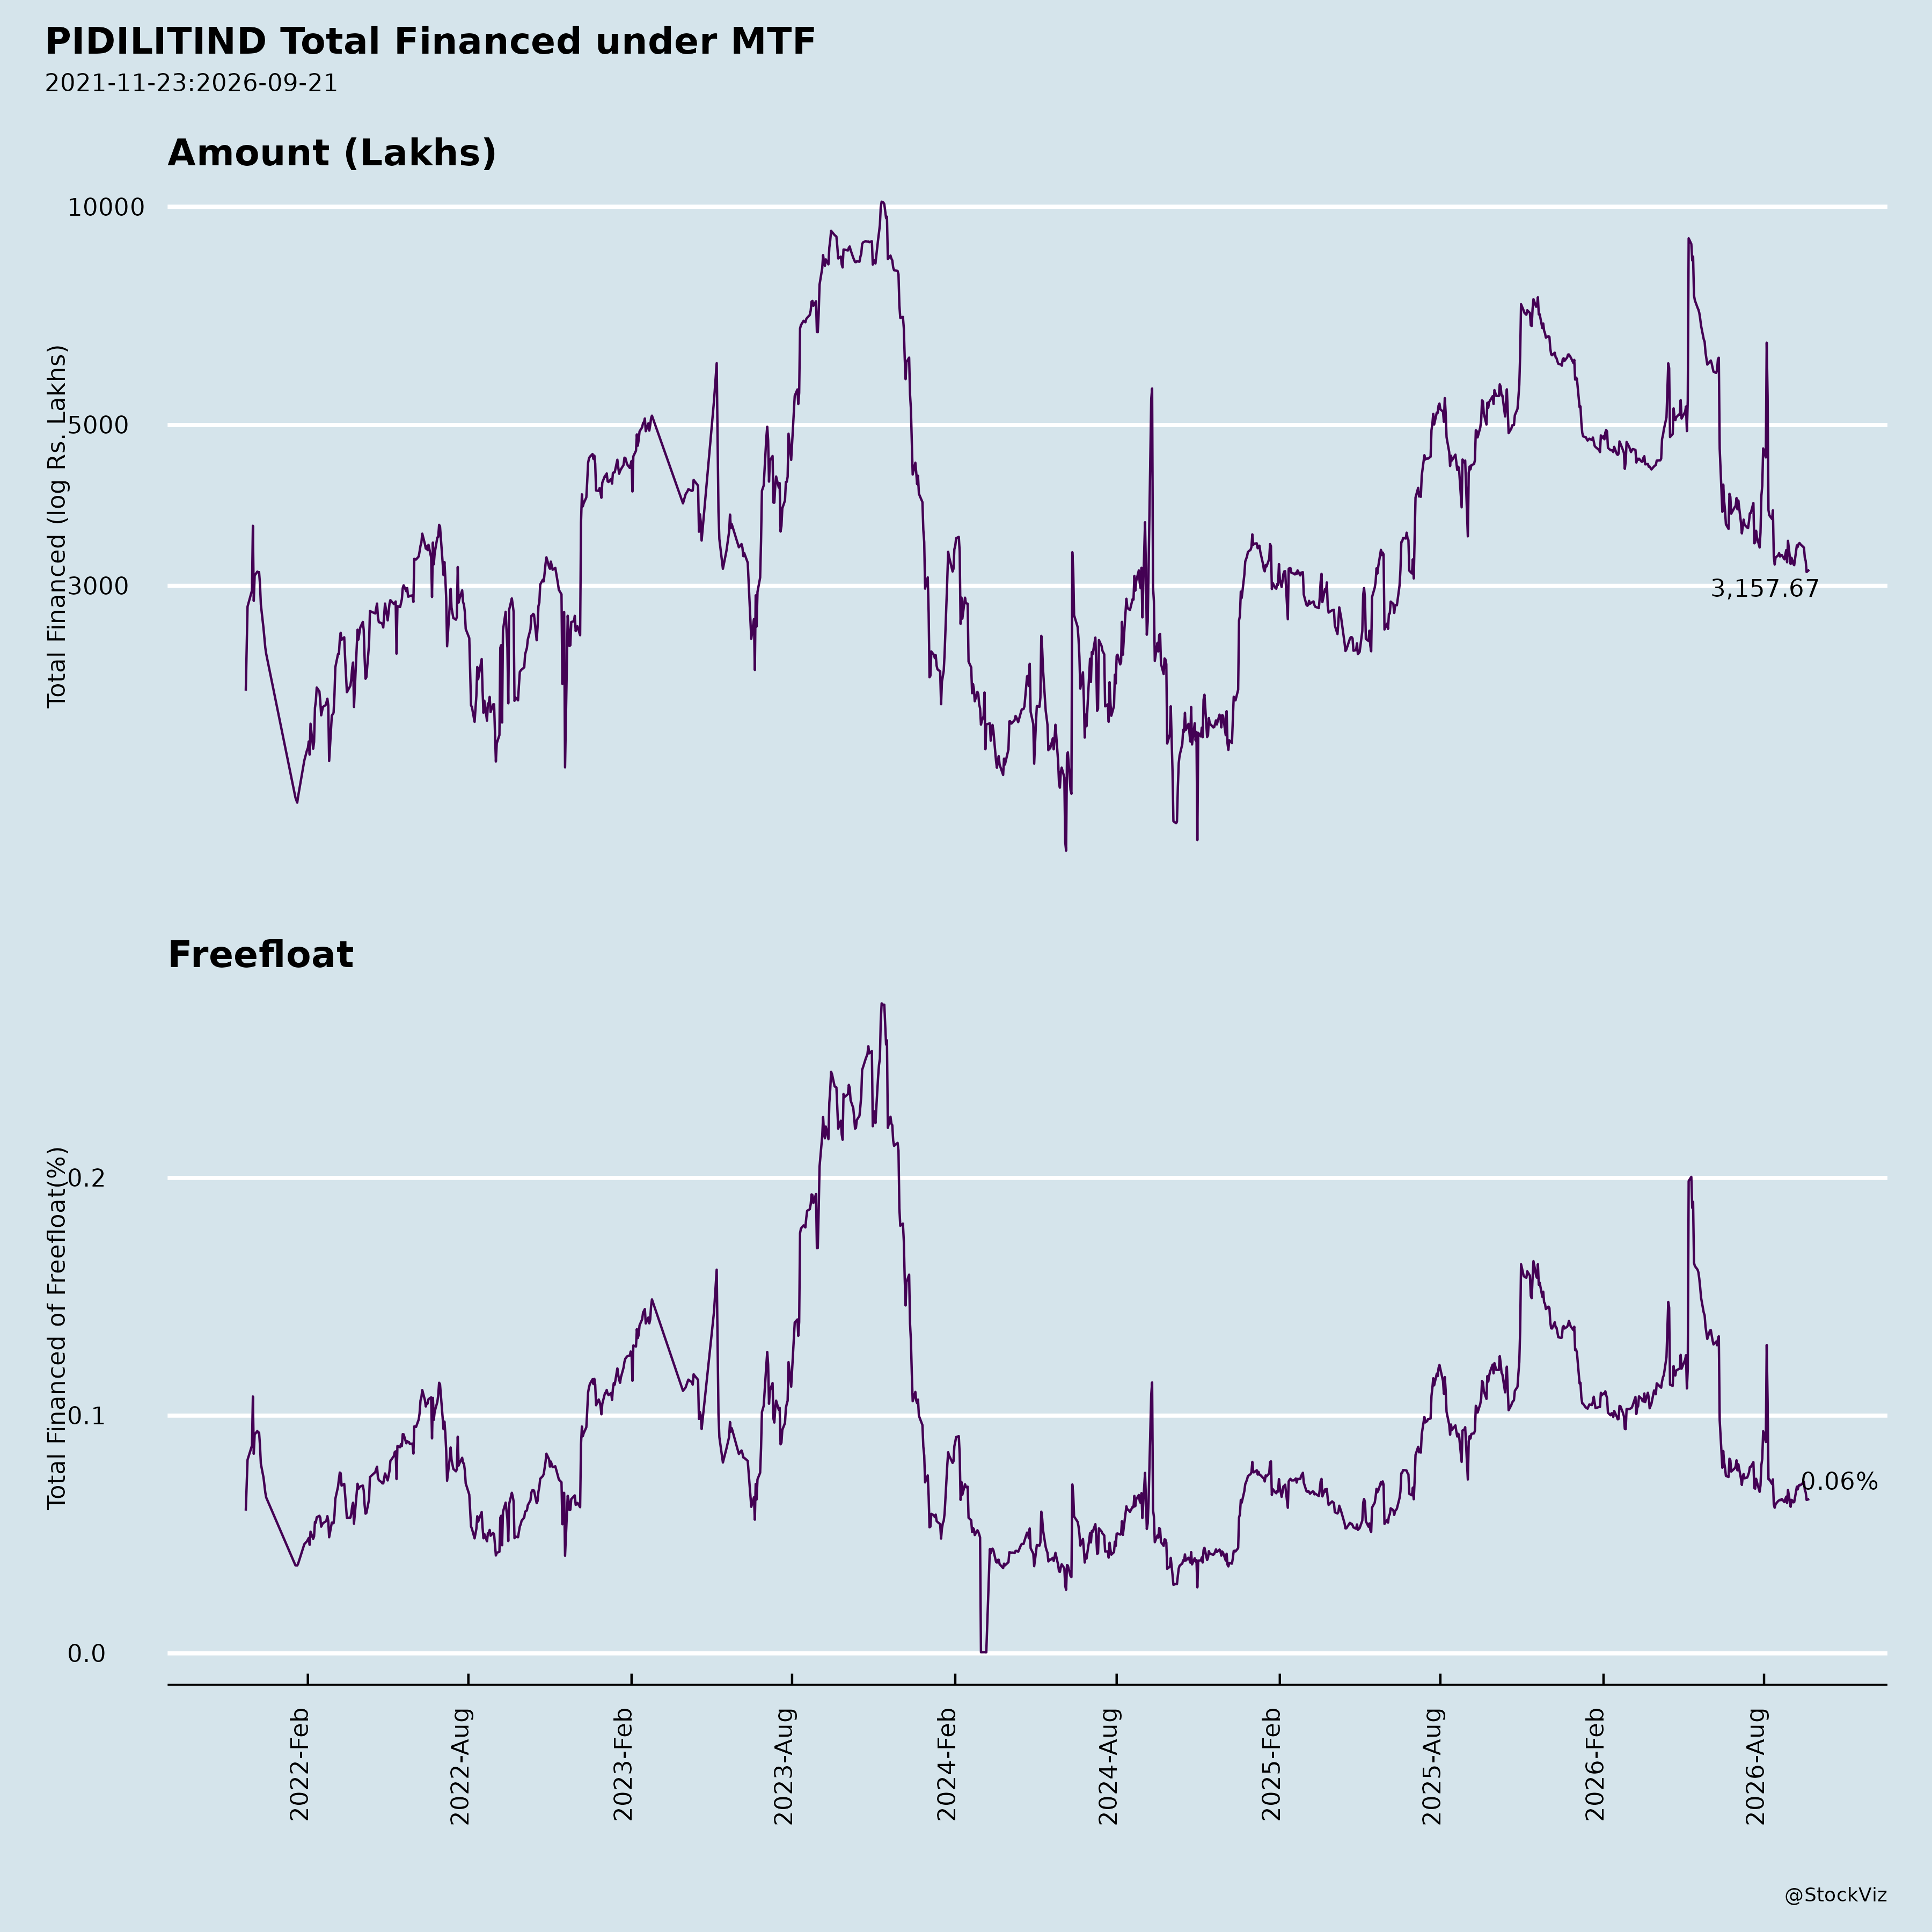
Margined
AI Summary
asof: 2026-09-14
Pidilite Industries – Recent Corporate Announcements
1. Headwinds and Challenges
- Input cost inflation linked to the West Asia crisis. In the Q1 FY27 results press release dated 4 August 2026, Pidilite reported that gross margin contracted due to the inflationary impact of the West Asia crisis. On a standalone basis, gross margin came in at 52.5%, down ~90 bps from 53.4% in Q1 FY26. On a consolidated basis, gross margin was 53.3%, down ~70 bps from 54% a year earlier.
- Price increases taken to offset rising input costs. The company stated that price increases were taken across all categories to offset the increase in input costs, indicating cost pressure across the portfolio.
- External volatility being monitored. Management noted it continues to monitor raw material inflation, freight costs, and global supply chain disruptions.
- Subsidiary wind-down. Nina Percept (Bangladesh) Private Limited (NPBPL), a wholly-owned step-down subsidiary, was voluntarily liquidated with effect from 19 August 2026, with the stated reason being a lack of business opportunities causing the subsidiary to remain inoperative since incorporation.
- GST penalties. Two separate GST orders were
disclosed:
- An Order in Original dated 30 June 2026 (received via post on 21 July 2026) from the Assistant Commissioner of CGST & C. Ex. Division-III, Indore, Madhya Pradesh, imposing a penalty of Rs. 46,98,047/- for F.Y. 2020-21 to 2022-23.
- An Order-in-Original dated 31 August 2026 (received via email the same day) from the Superintendent of Central GST & C. Excise, Fatuha Range, Bihar, imposing a penalty of Rs. 10,42,207/- for F.Y. 2020-21.
- In both cases the company stated there is no material impact on financials, operations, or other activities, and that the orders are appealable.
2. Tailwinds and Growth Prospects
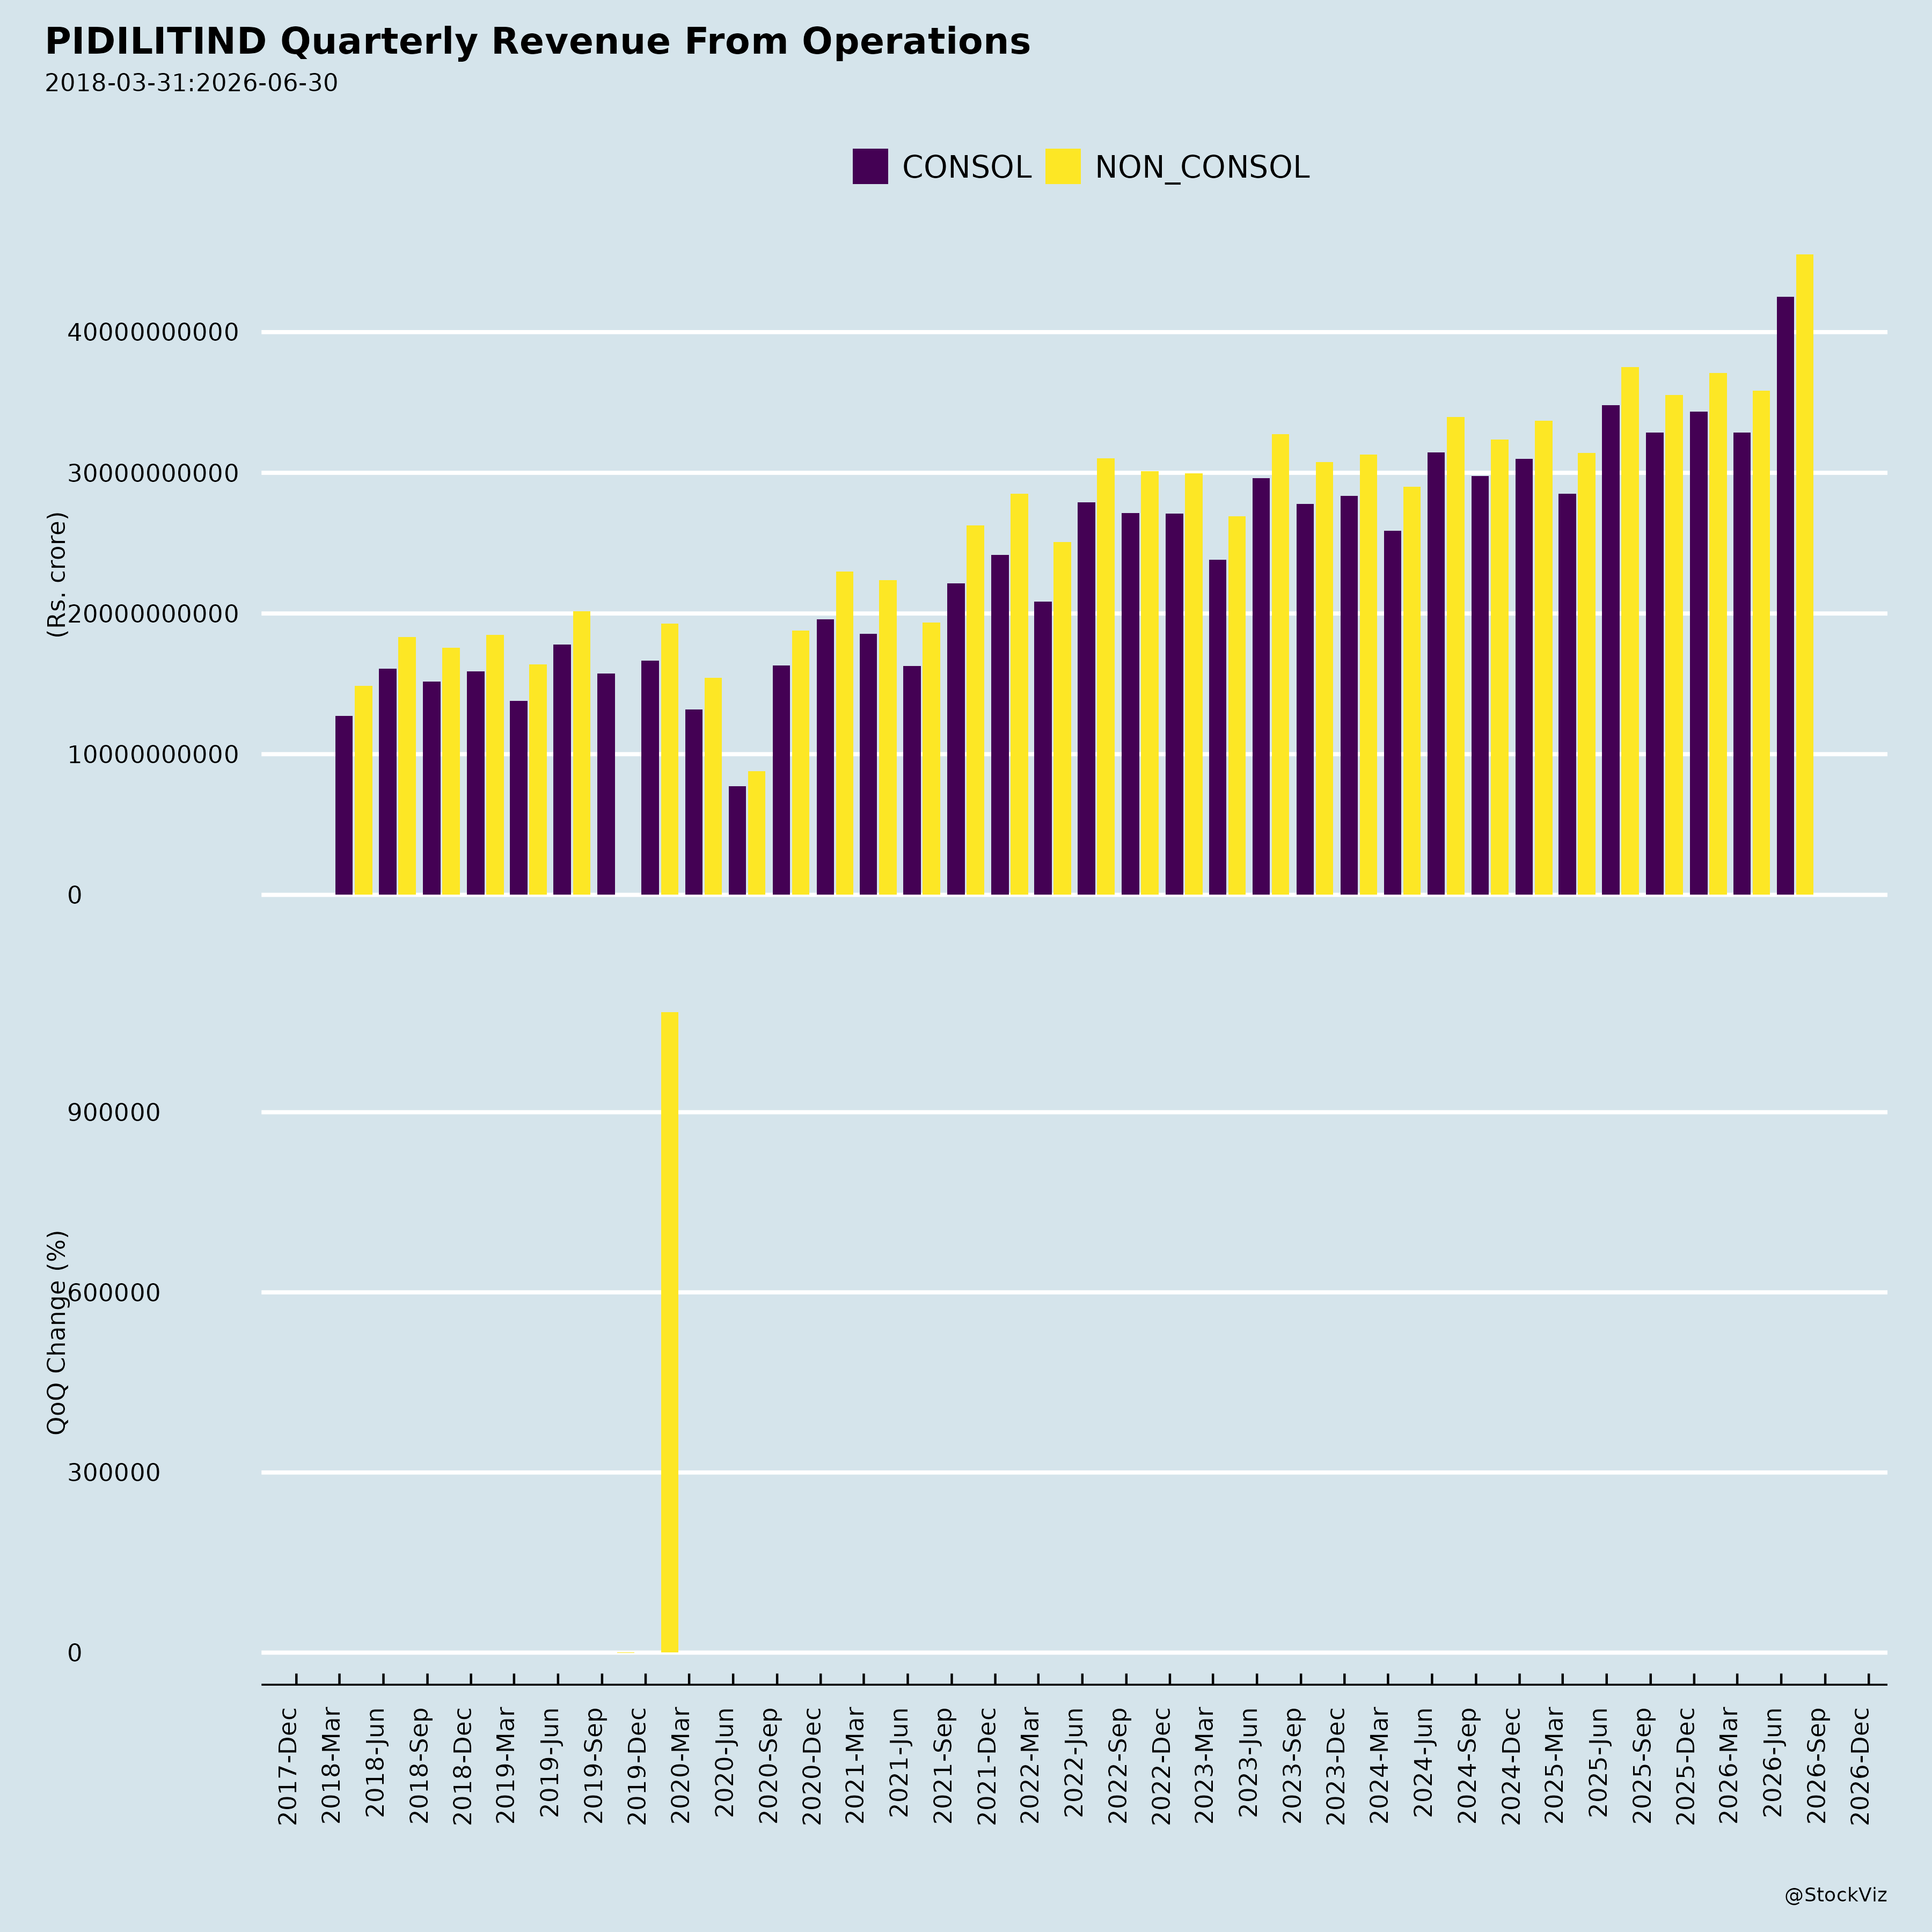
- Strong Q1 FY27 revenue growth. For the quarter ended 30 June 2026, consolidated net sales grew 21.3% to Rs 4,541 crores, with underlying volume growth (UVG) of 11.3%. Standalone net sales grew 22.2% to Rs 4,237 crores, also with UVG of 11.3%.
- Broad-based segment growth (standalone). Consumer & Bazaar (C&B) revenue grew 22.5% with UVG of 12.2%; Business to Business (B2B) revenue grew 16.0% with UVG of 7.3%.
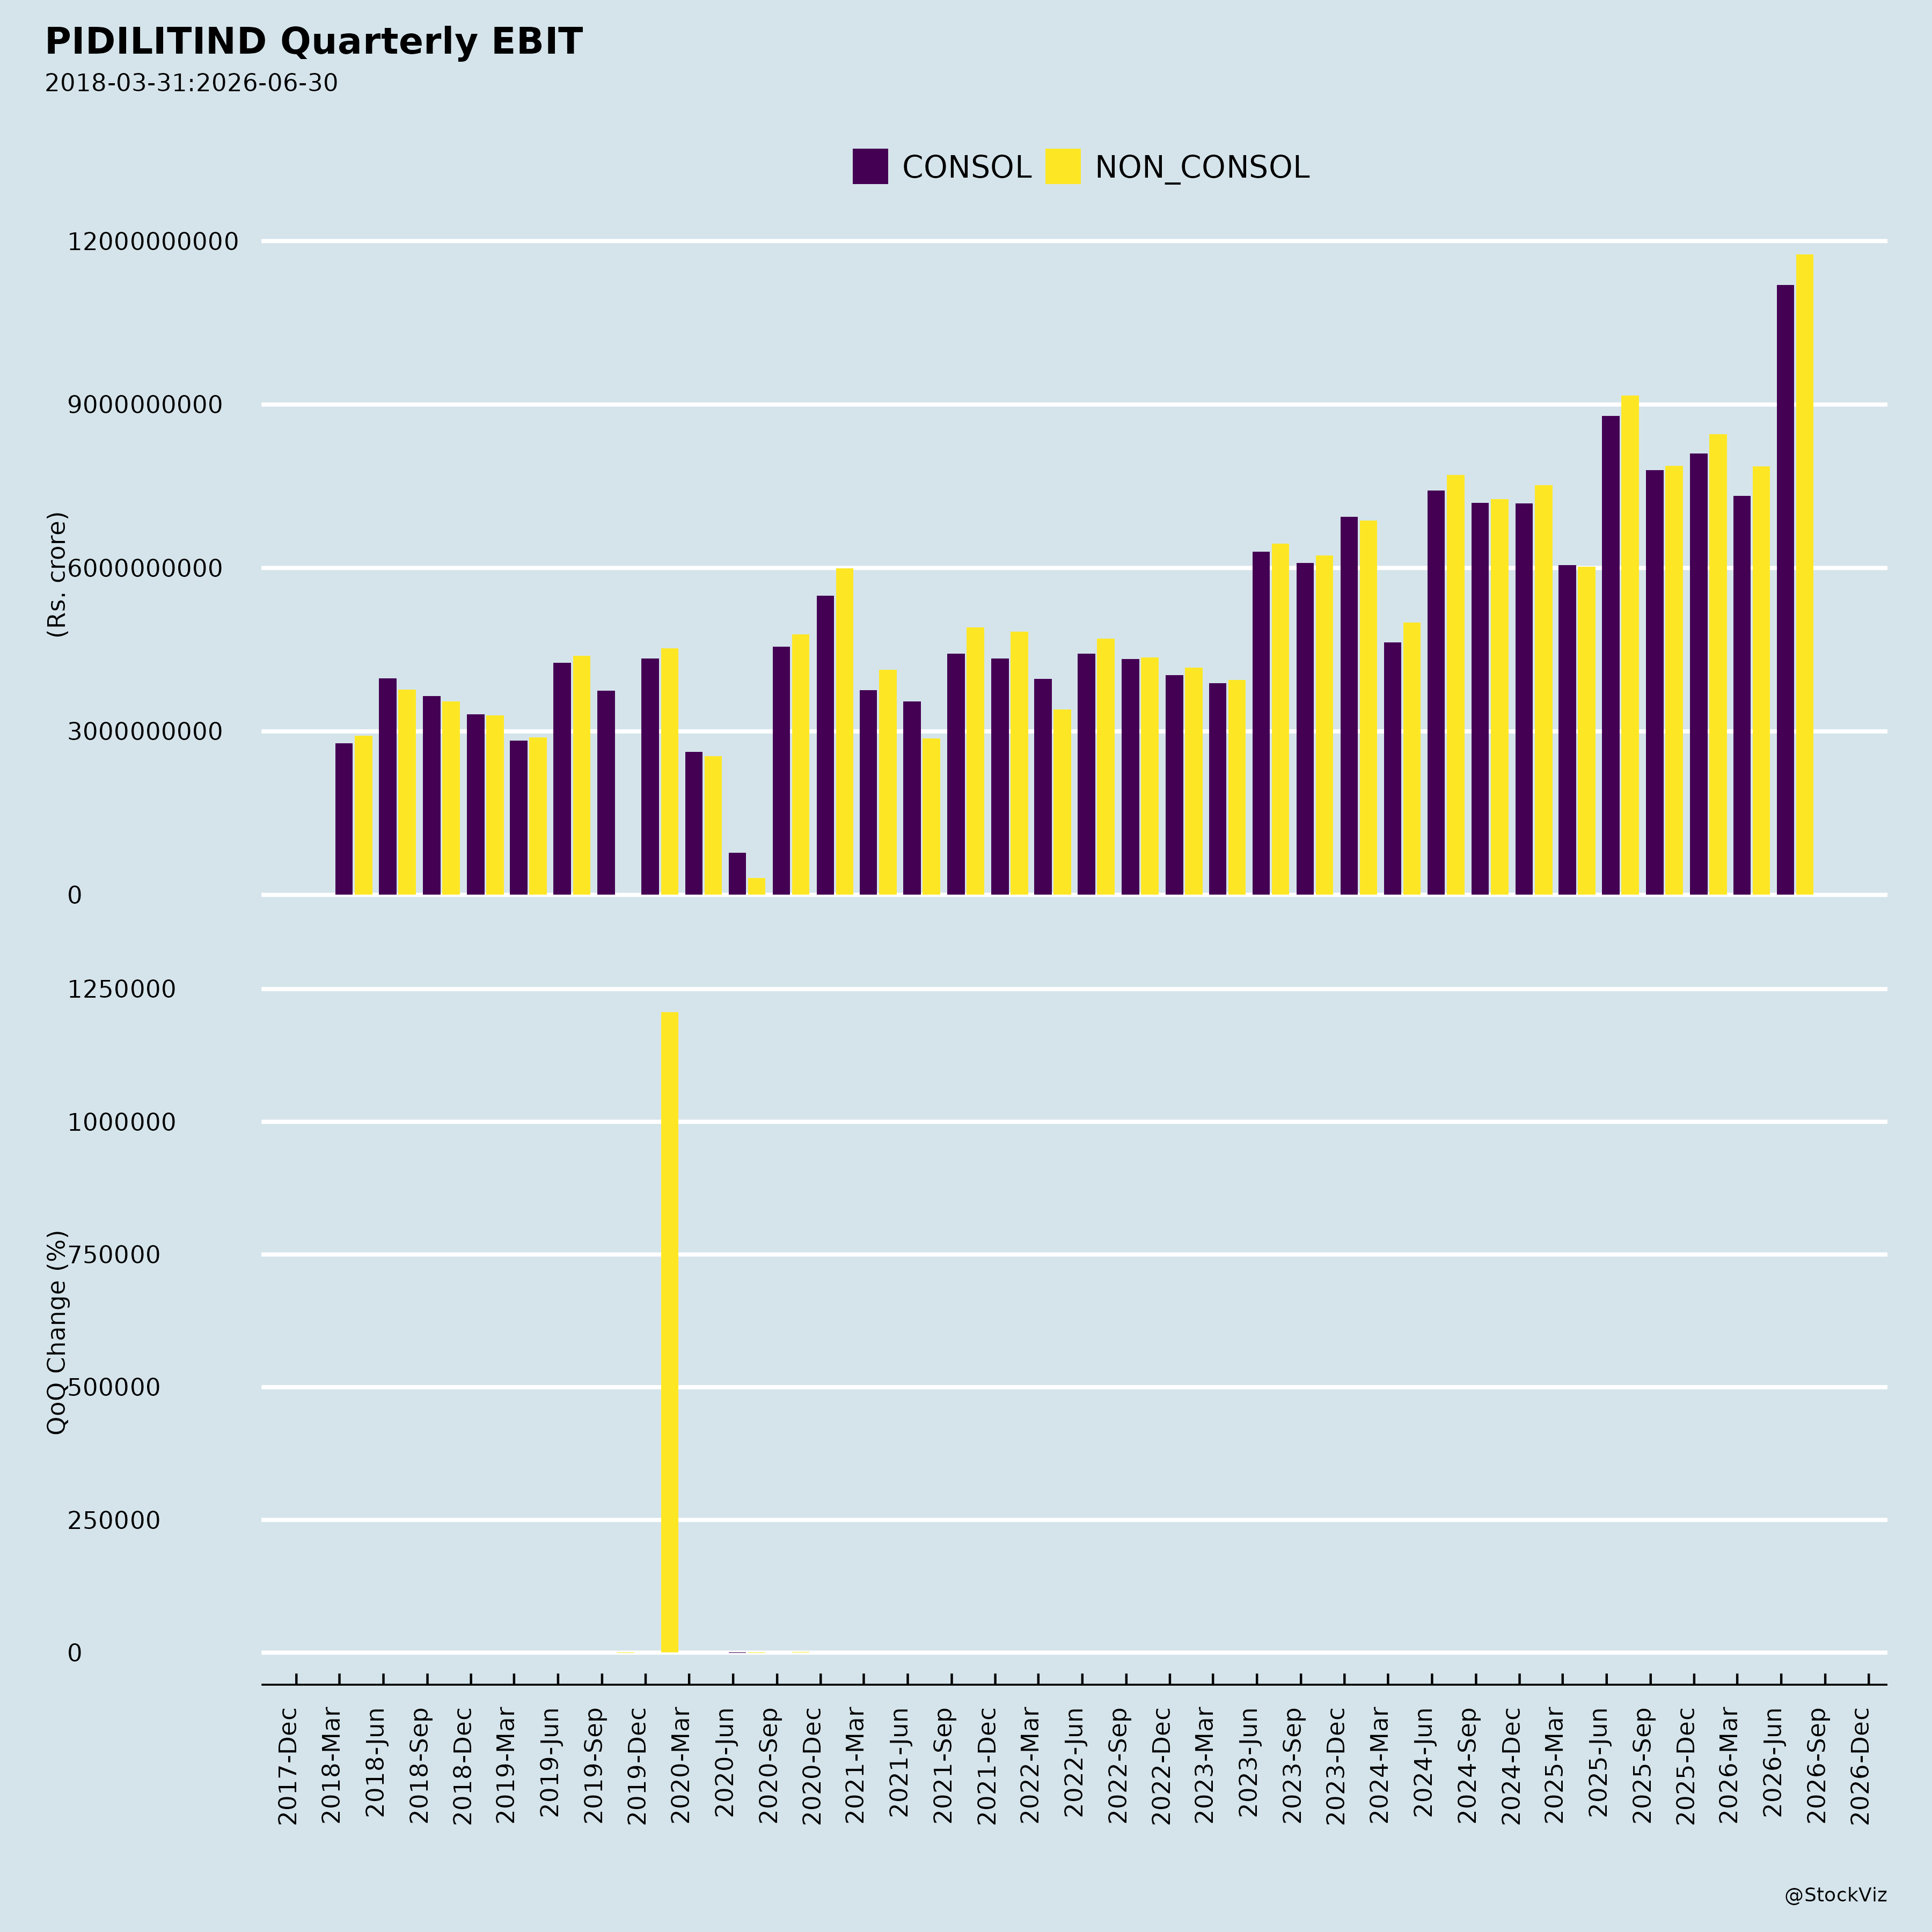
- Margin expansion. Standalone EBITDA margin improved to 26.4% from 25.6% (~80 bps), with EBITDA up 26.2% to Rs 1,121 crores. Consolidated EBITDA margin improved to 26.3% from 25.1% (~120 bps), with EBITDA up 26.9% to Rs 1,194 crores.
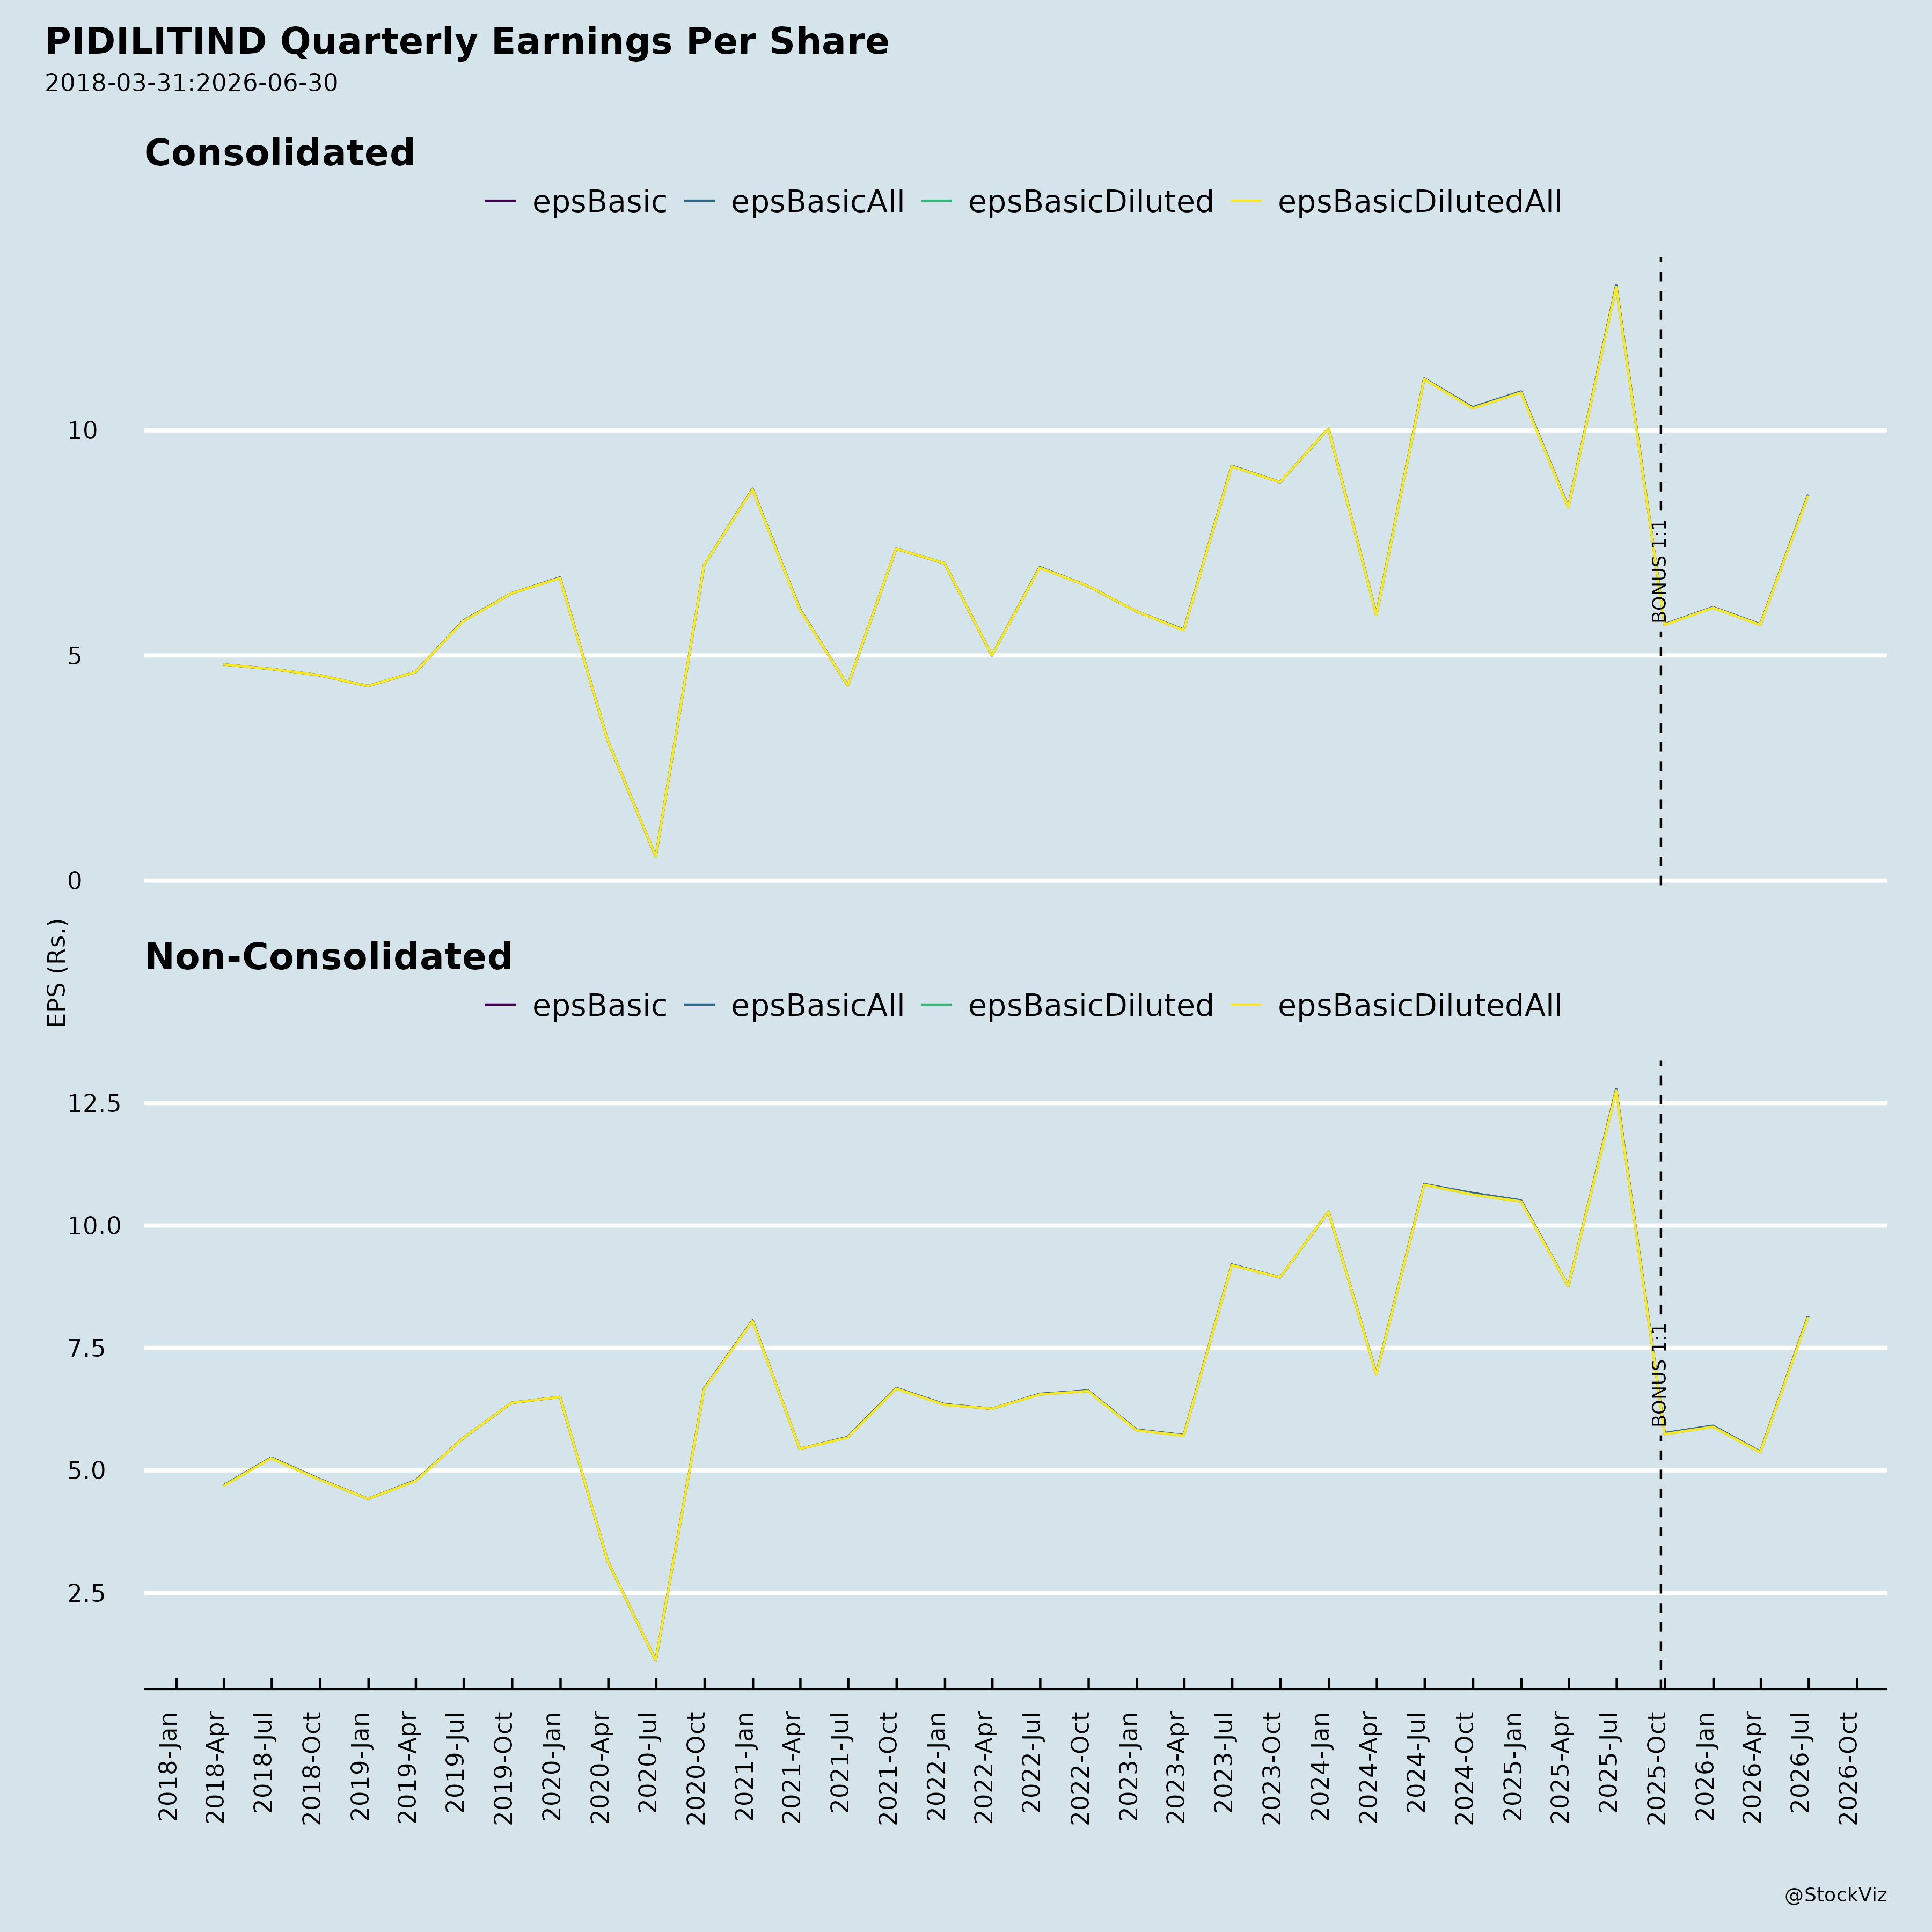
- Profit growth. Standalone Profit After Tax rose 27.7% to Rs 830 crores; consolidated Profit After Tax rose 30.3% to Rs 884 crores.
- Resilient domestic demand. Management described domestic demand as continuing to be resilient, supported by healthy performance in urban and rurban markets.
- Continued investment. The company highlighted investments in brand building and business development during the quarter, aimed at strengthening brands and expanding market presence, alongside innovation, people, and supply chain capabilities.
3. Key Risks
- Raw material inflation, freight costs, and global supply chain disruptions, which management explicitly said it continues to monitor.
- Geopolitical impact, which was among the topics raised by members at the 57th AGM held on 4 August 2026, alongside questions on company operations.
- Gross margin compression risk from inflationary pressures, as reflected in the year-on-year gross margin contraction in Q1 FY27.
- Tax/regulatory exposure, as illustrated by the two GST penalty orders (Indore and Fatuha Range, Bihar), both of which the company is reviewing and evaluating for appeal.
- Subsidiary-level business viability risk, as illustrated by the liquidation of NPBPL due to lack of business opportunities.
4. Management Guidance Versus Observed Business Performance
- Management commentary (4 August 2026): Mr. Sudhanshu Vats, Managing Director, stated that FY27 commenced on a strong footing with broad-based growth across both C&B and B2B segments; that domestic demand continues to be resilient; that disciplined execution enabled the company to manage volatility while balancing investments with prudent cost management; and that the company remains confident its proactive measures will mitigate risks while sustaining growth momentum.
- Observed performance against that commentary: The Q1 FY27 results for the quarter ended 30 June 2026 show consolidated revenue growth of 21.3% and UVG of 11.3%, with growth in both segments (C&B +22.5%, B2B +16.0% standalone), consistent with the described broad-based growth. Margins expanded year-on-year at both standalone and consolidated levels despite gross margin contraction, consistent with the stated balancing of investments and cost management. The company also acted on price increases across all categories to offset input cost increases.
- Forward-looking statements: Management said it continues to monitor external factors such as raw material inflation, freight costs, and global supply chain disruptions, and expressed confidence that proactive measures will mitigate risks while sustaining growth momentum. No specific numerical guidance was provided in the supplied material.
- Other scheduled engagement: An analyst/institutional investor meeting with Aberdeen Asset Management is scheduled for 08 September 2026, 01:00 pm to 02:00 pm in Mumbai (physical meeting with a single institution), with dates subject to change due to exigencies on the part of investors or the company.
Broker Narrative
The narrative shifted from caution over B2B/export weakness, Araldite disruption, and moderate international growth to a stronger demand and innovation-led outlook, while margin concerns persisted via VAM volatility and geopolitical inflation. Early fears of international moderation reversed into robust international growth, but the hoped-for B2B recovery did not materialise as exports stayed negative. Overall, the broker view remained Accumulate/Buy with increasing emphasis on premium and innovation-driven growth.
Fears that came true
- The flagged risk of export-dependent B2B weakness persisted, as exports UVG fell -8.4% in the last report, correlating with a -1.0% actual return.
- The early fear of inflation and global uncertainty materialised through West Asia war-driven gross margin contraction and high-cost inventory, despite international growth beating expectations.
Optimism that failed
- The expectation that B2B business would strengthen with construction activities did not materialise, as exports remained negative (UVG -8.4%).
Broker Timeline
22 broker calls · 2023-05-09 to 2026-08-05
Copyright © 2023 SAS Data Analytics Pvt. Ltd. All rights reserved.