PFOCUS
Equity Metrics
November 18, 2026
Prime Focus Limited
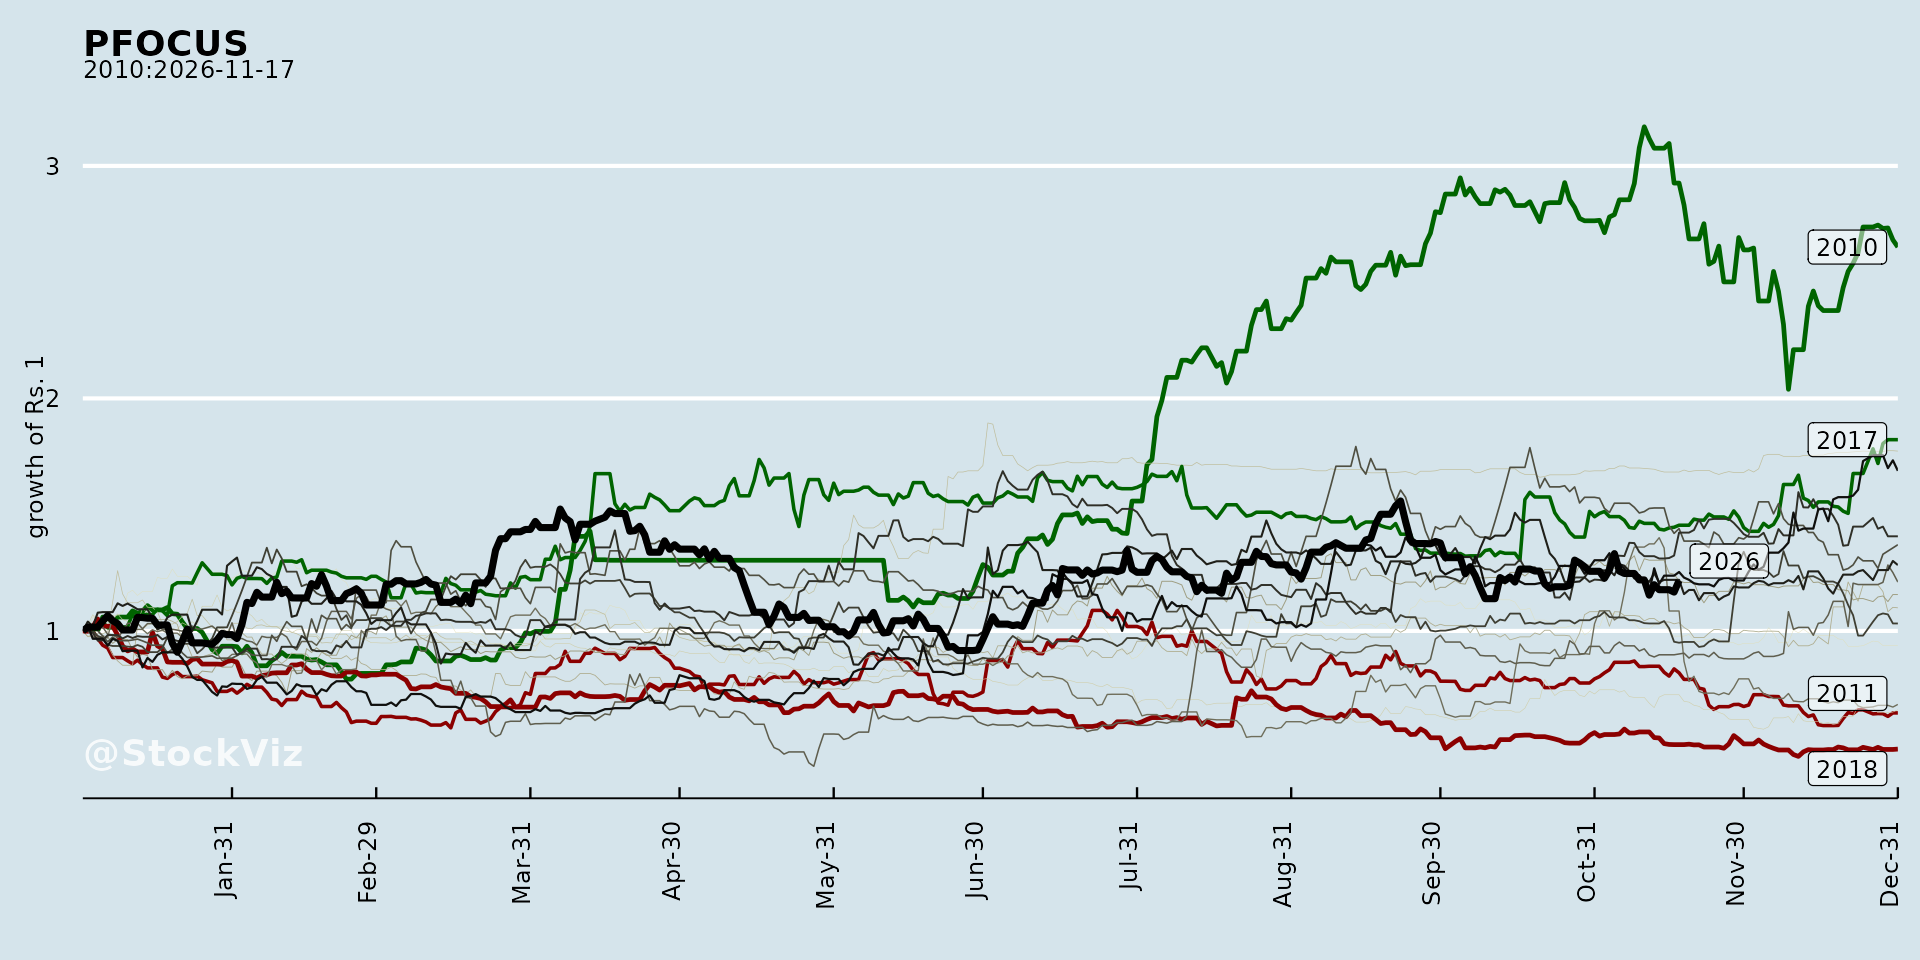
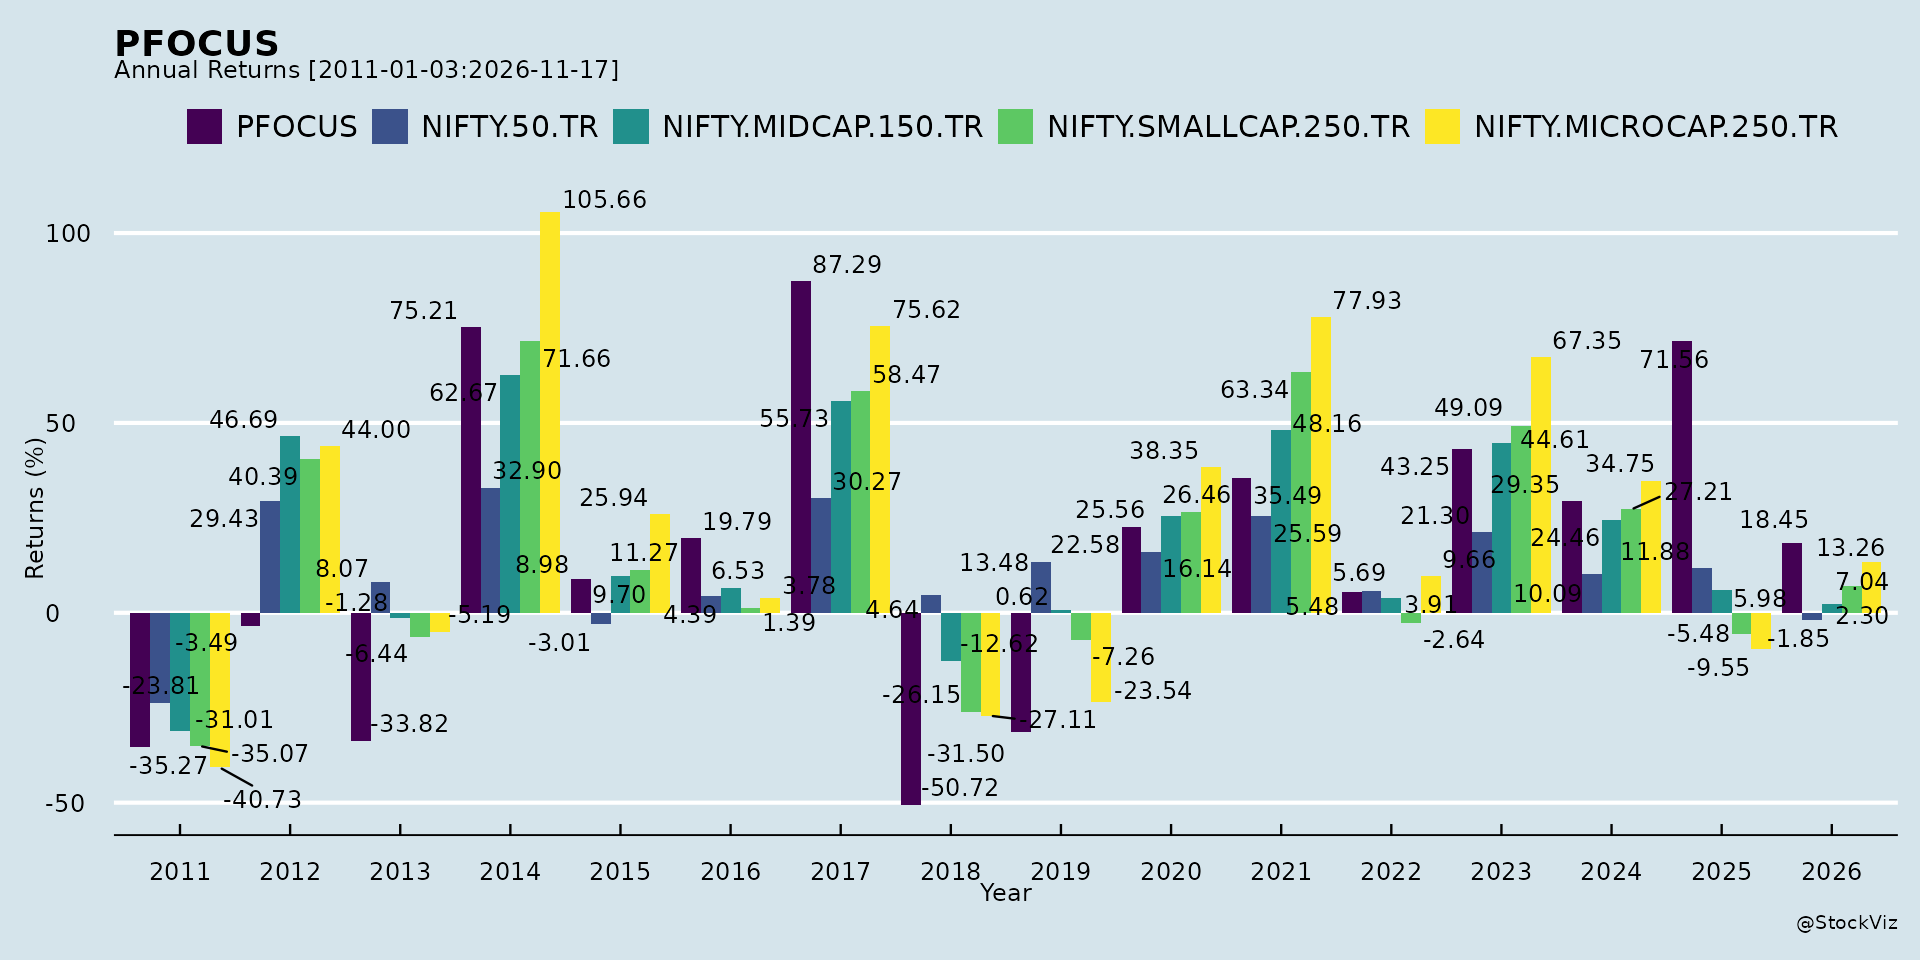
Annual Returns
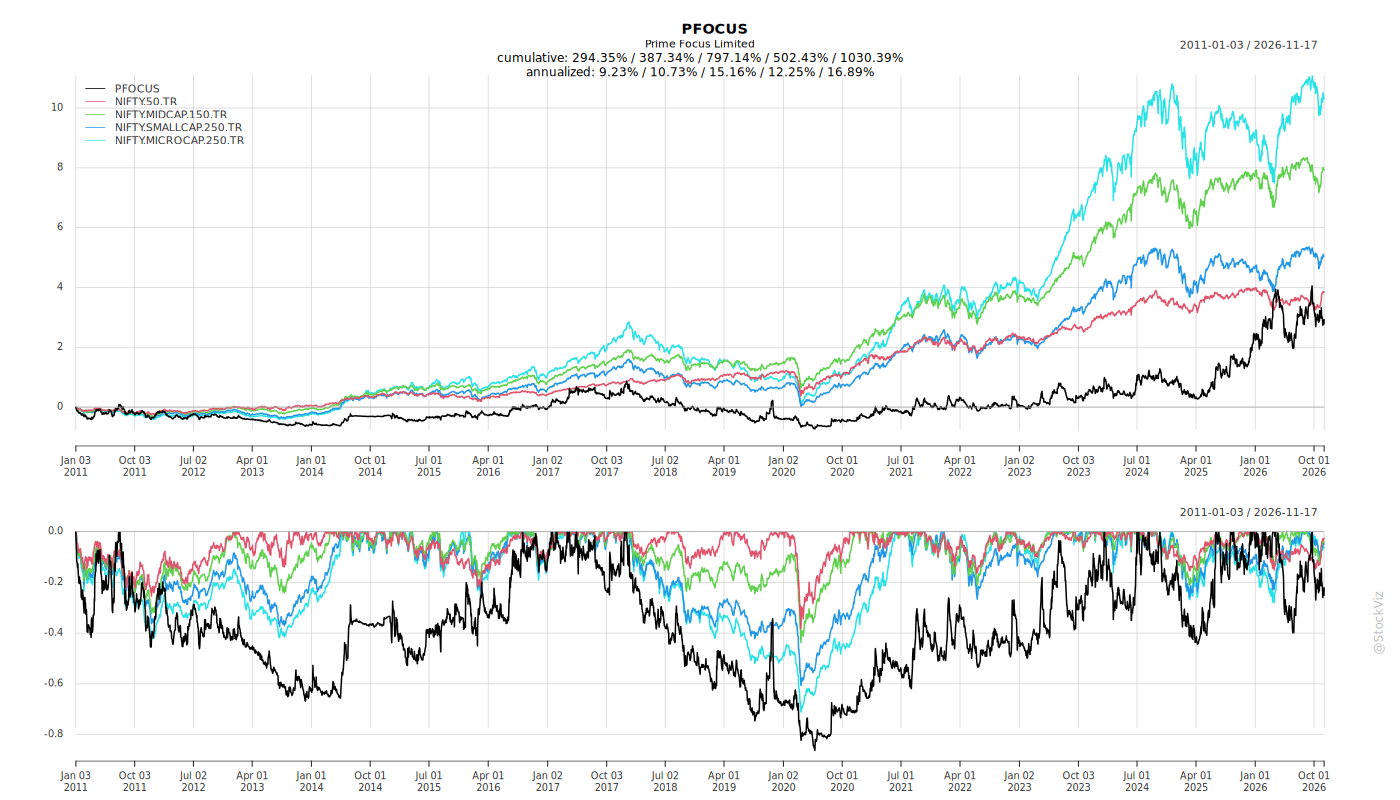
Cumulative Returns and Drawdowns
Fundamentals
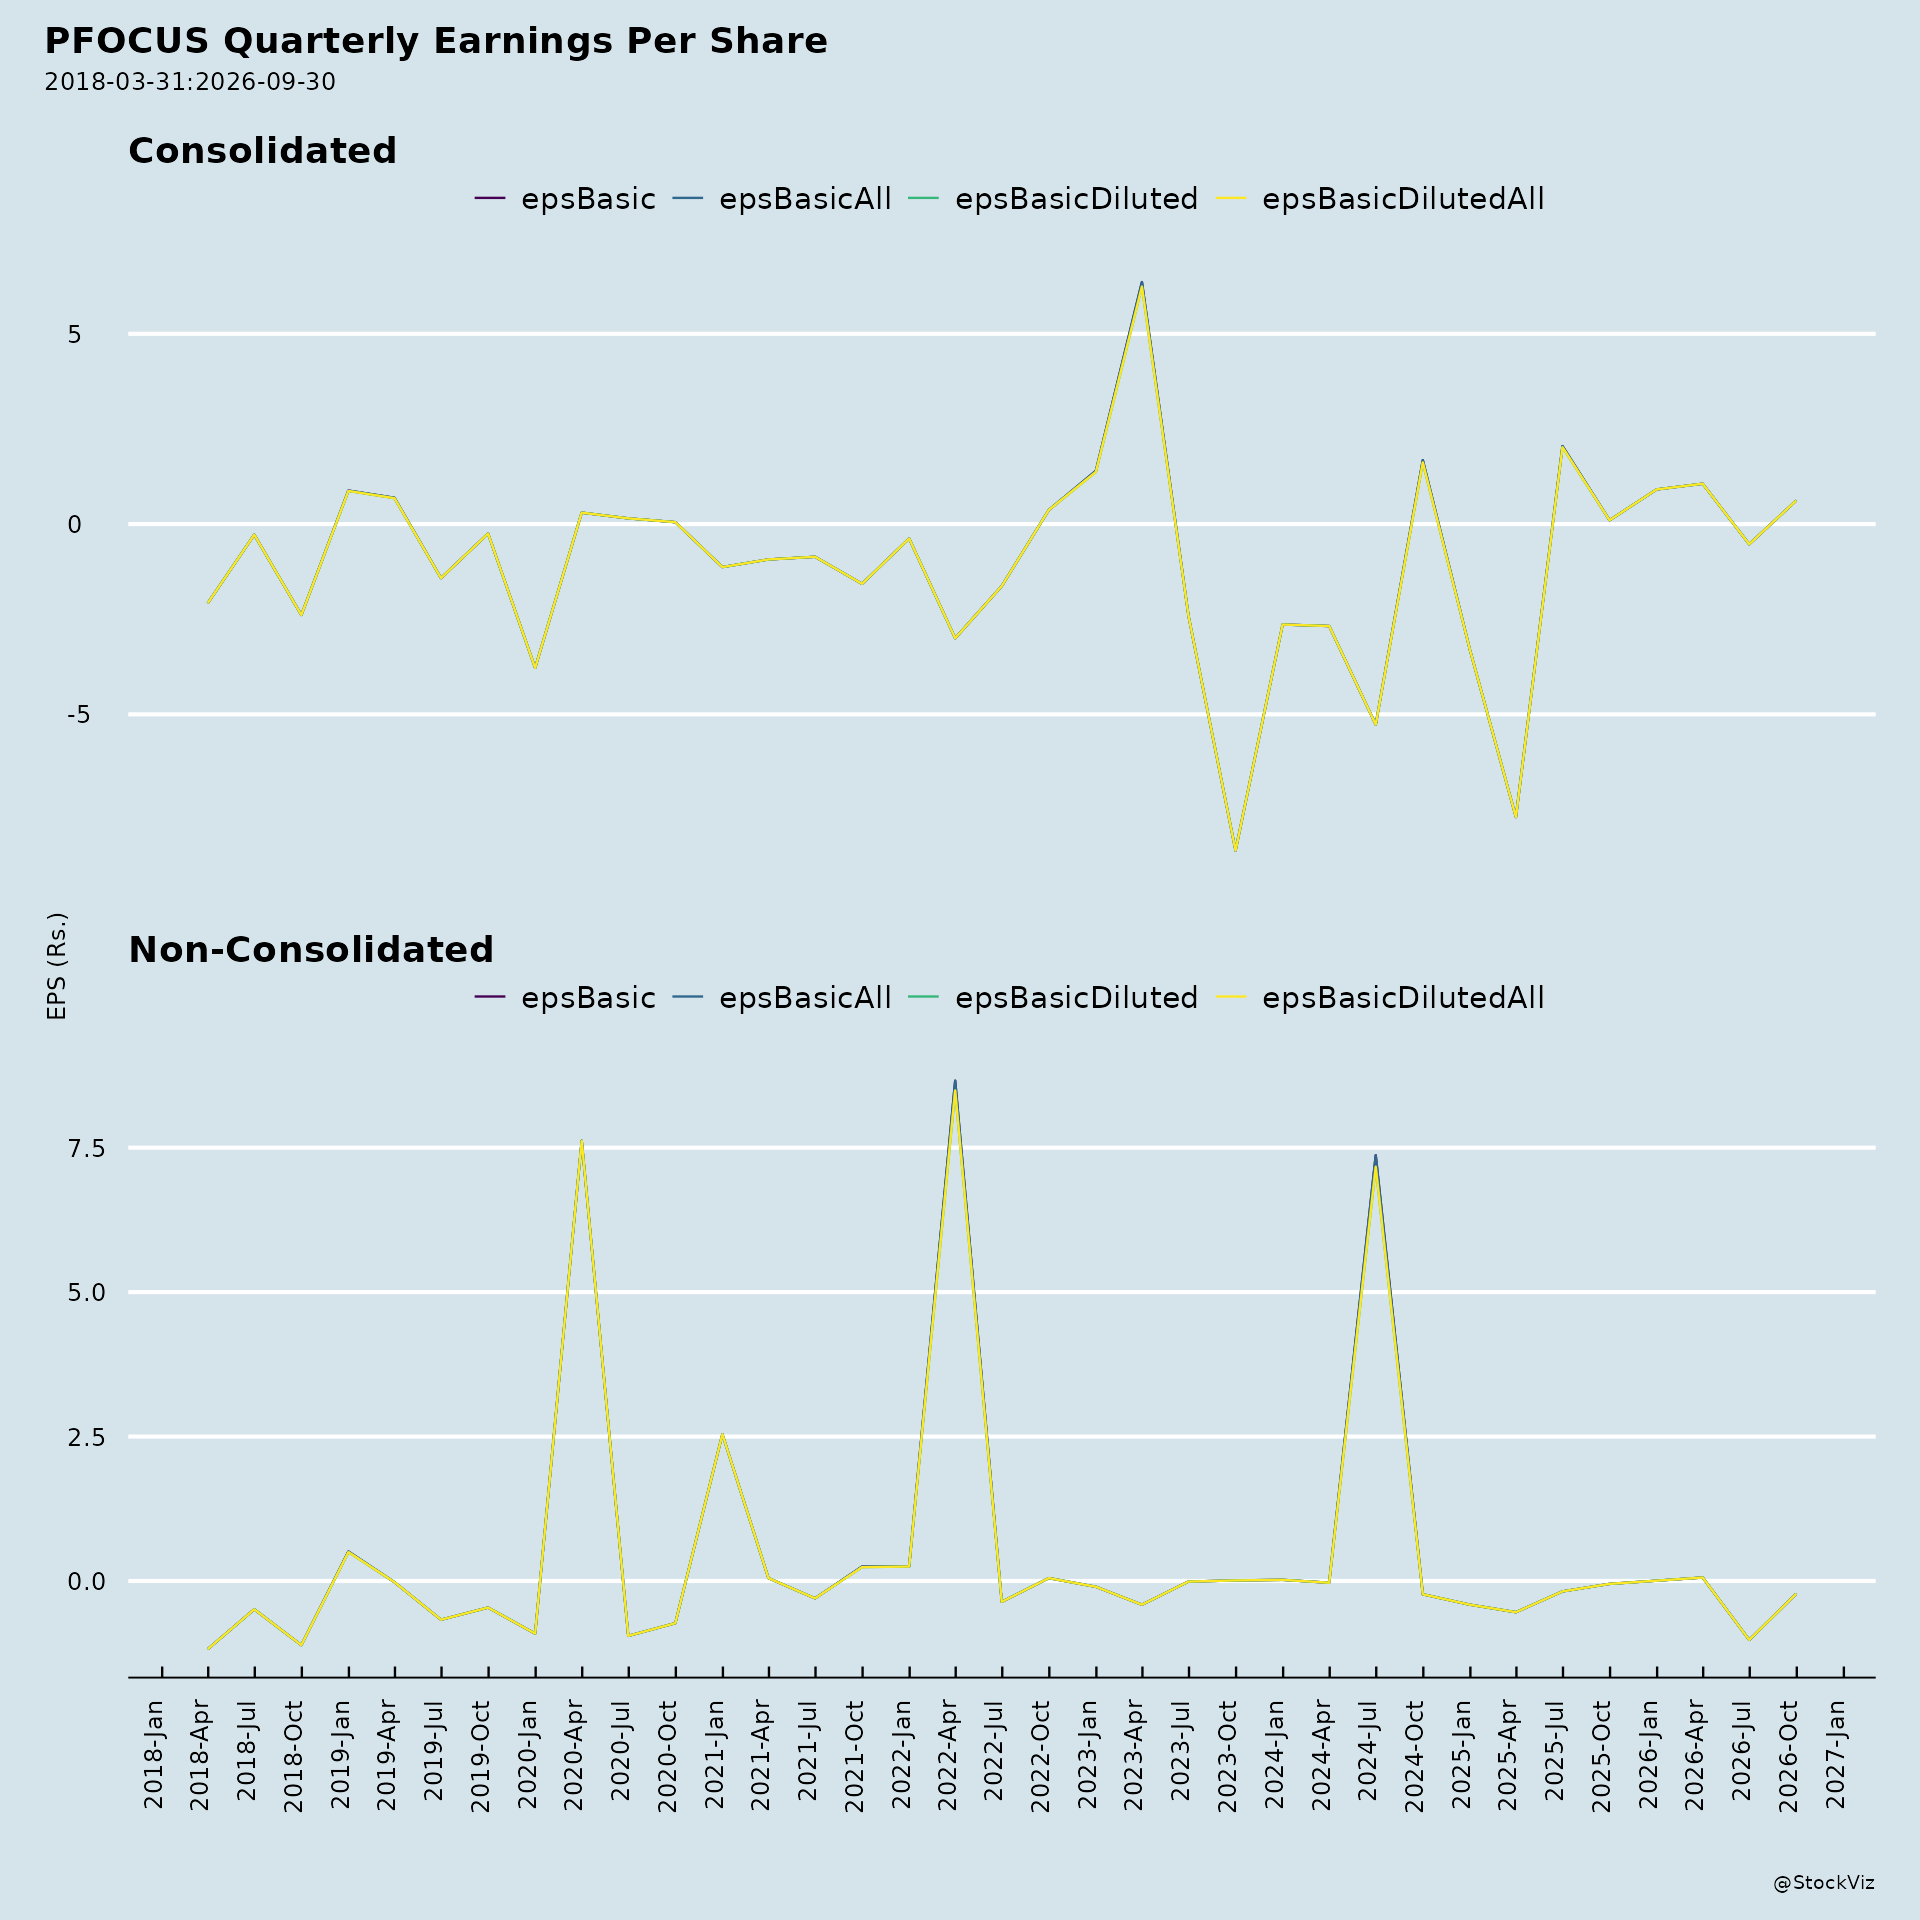
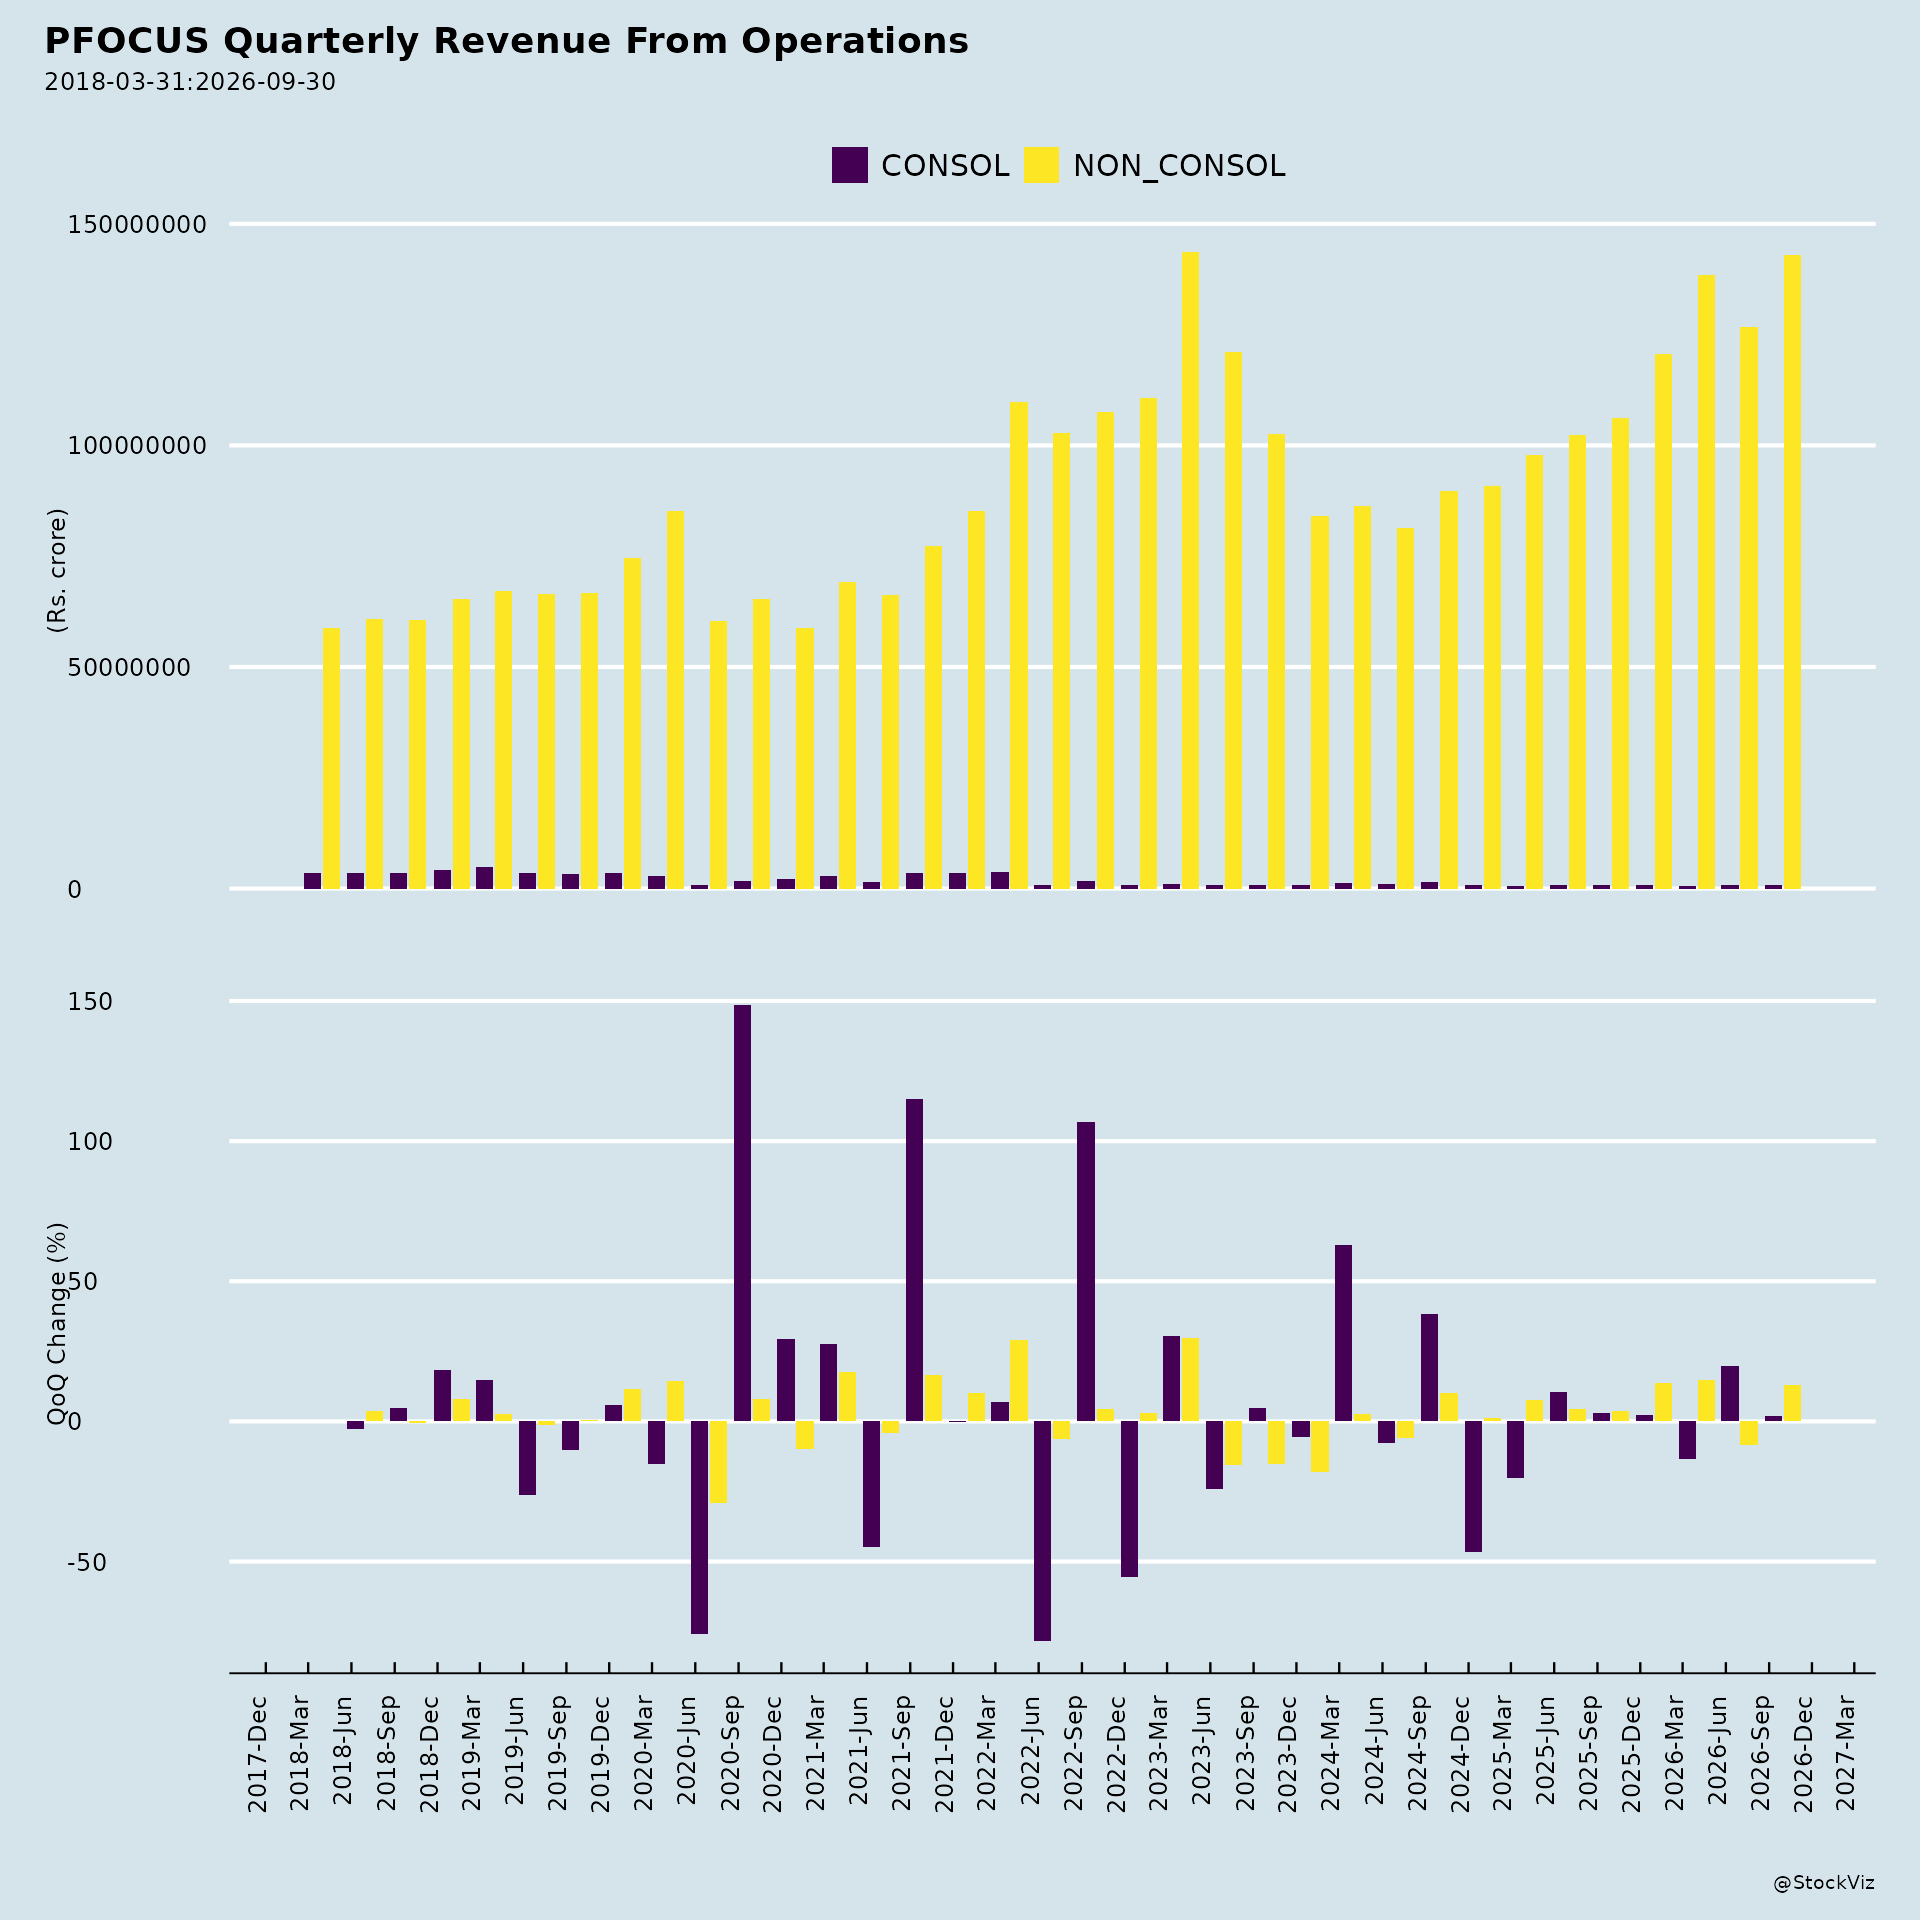
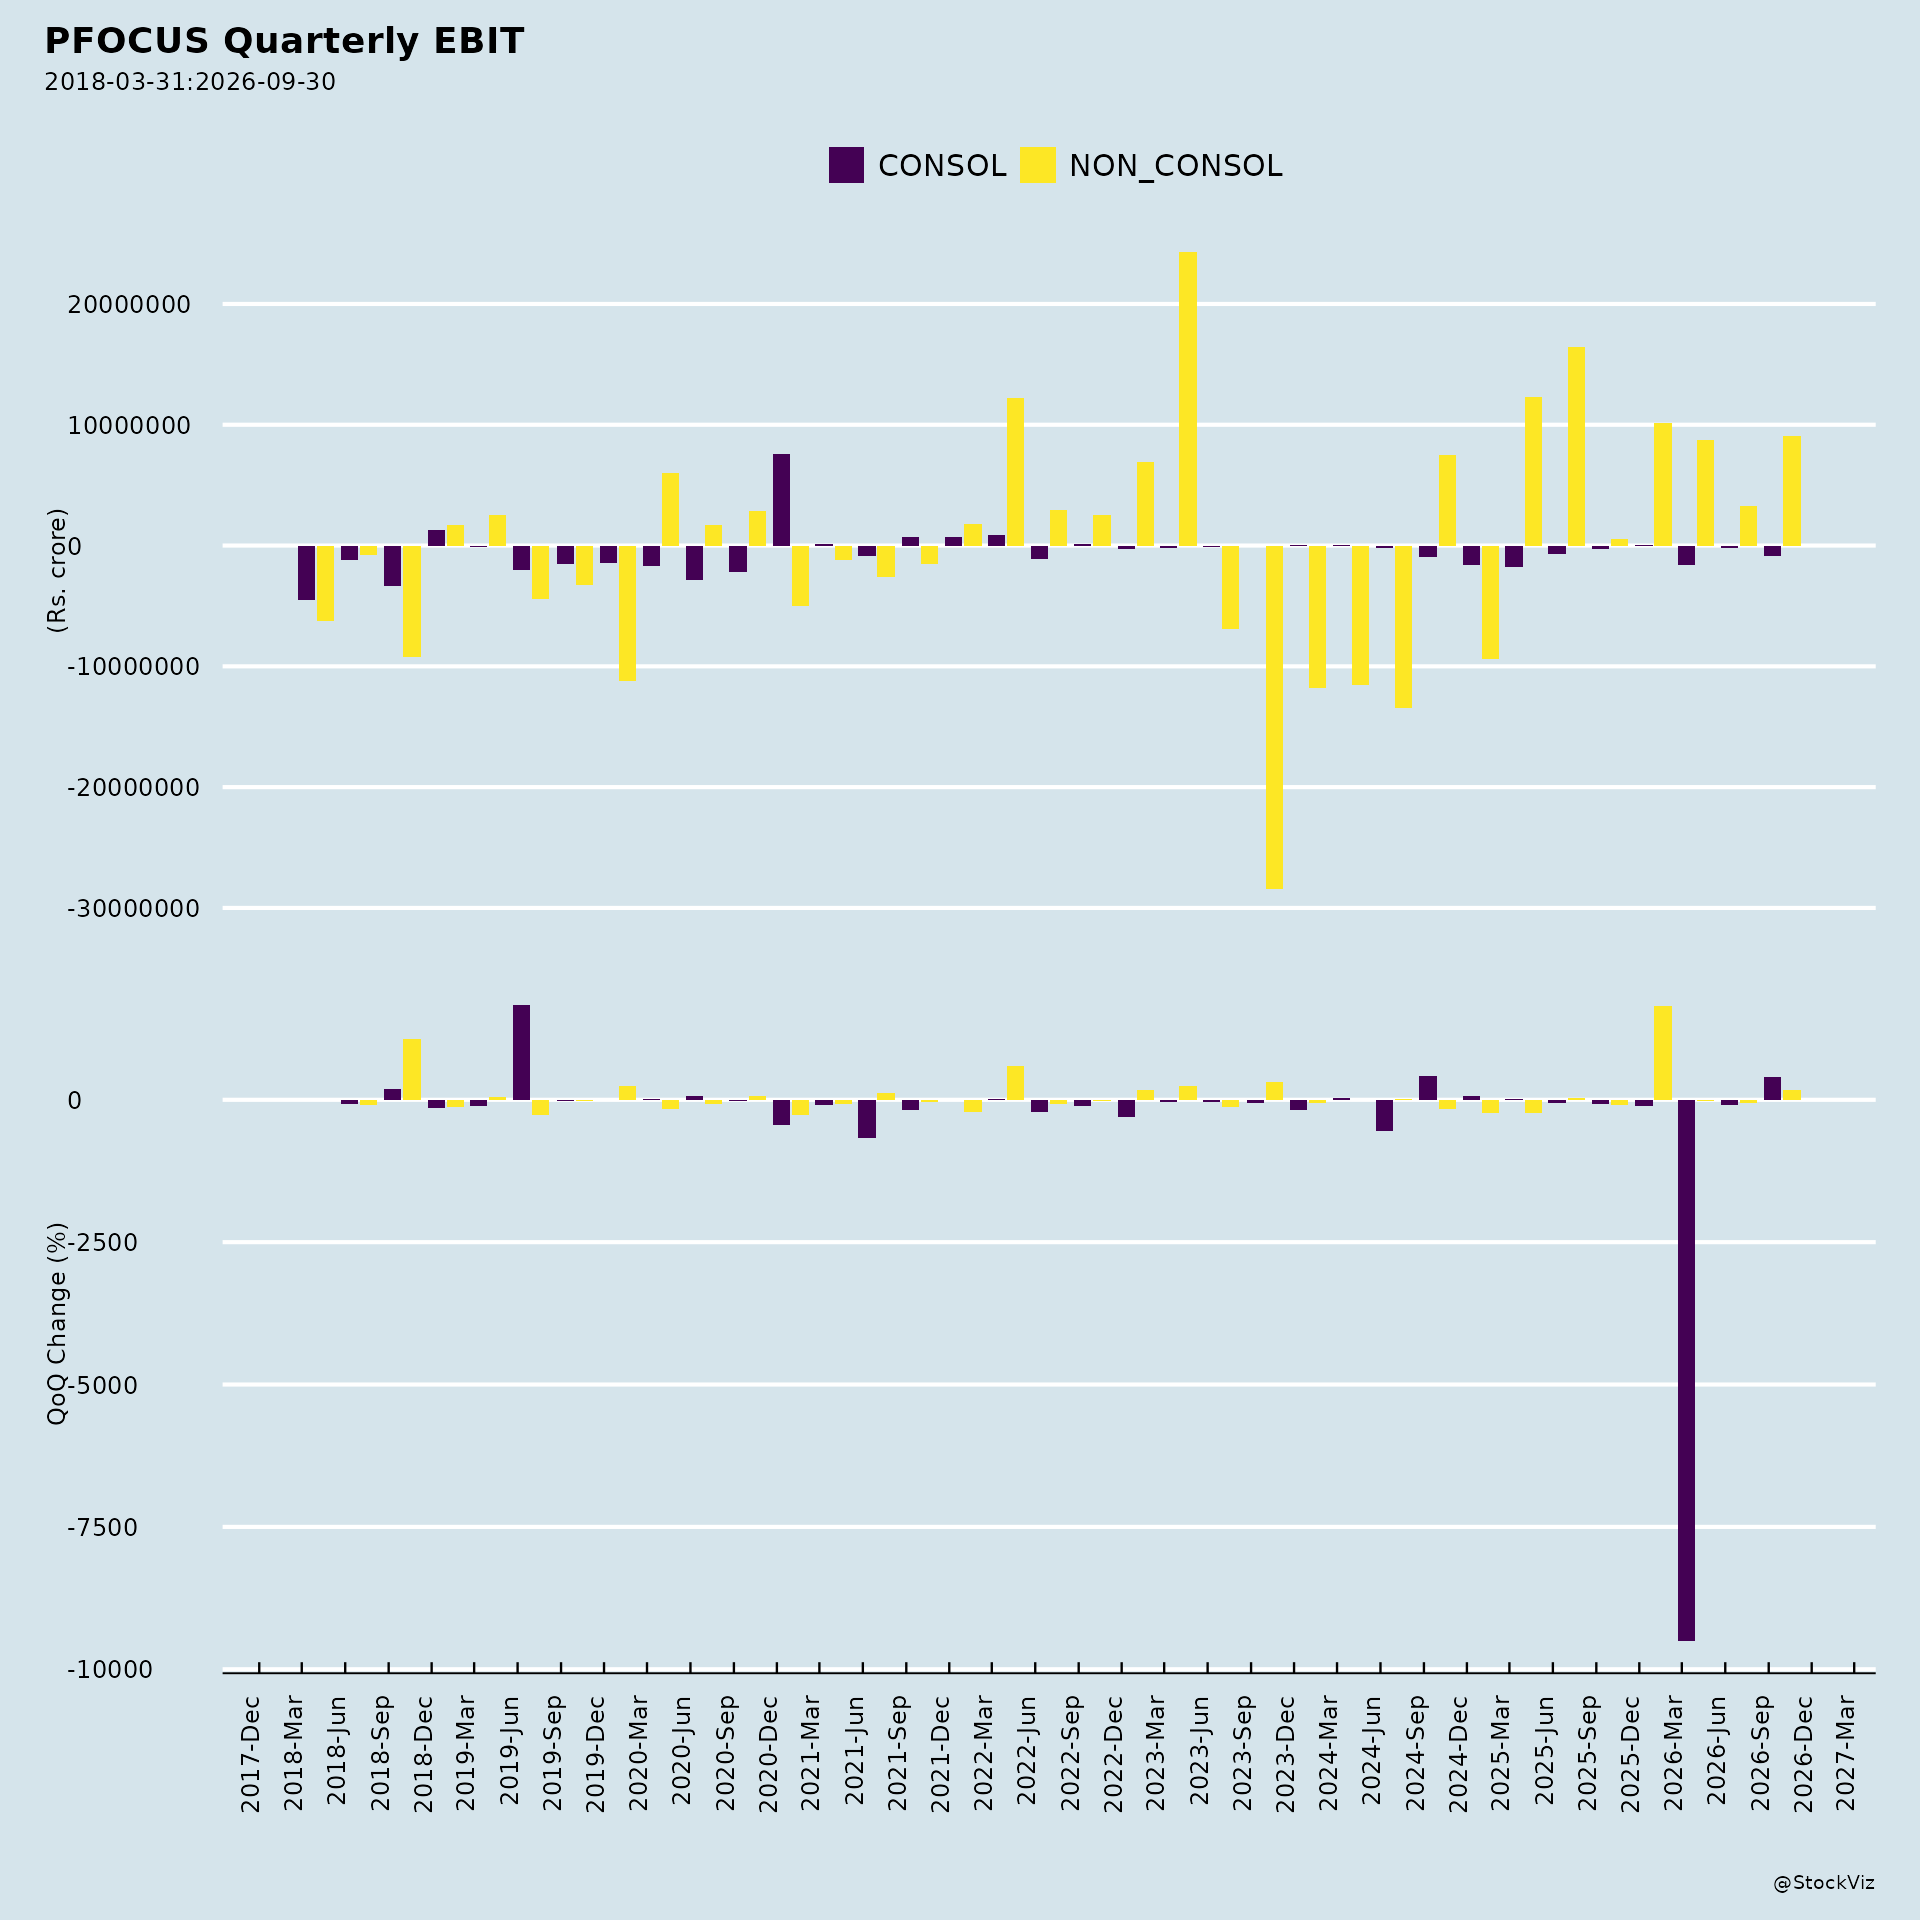
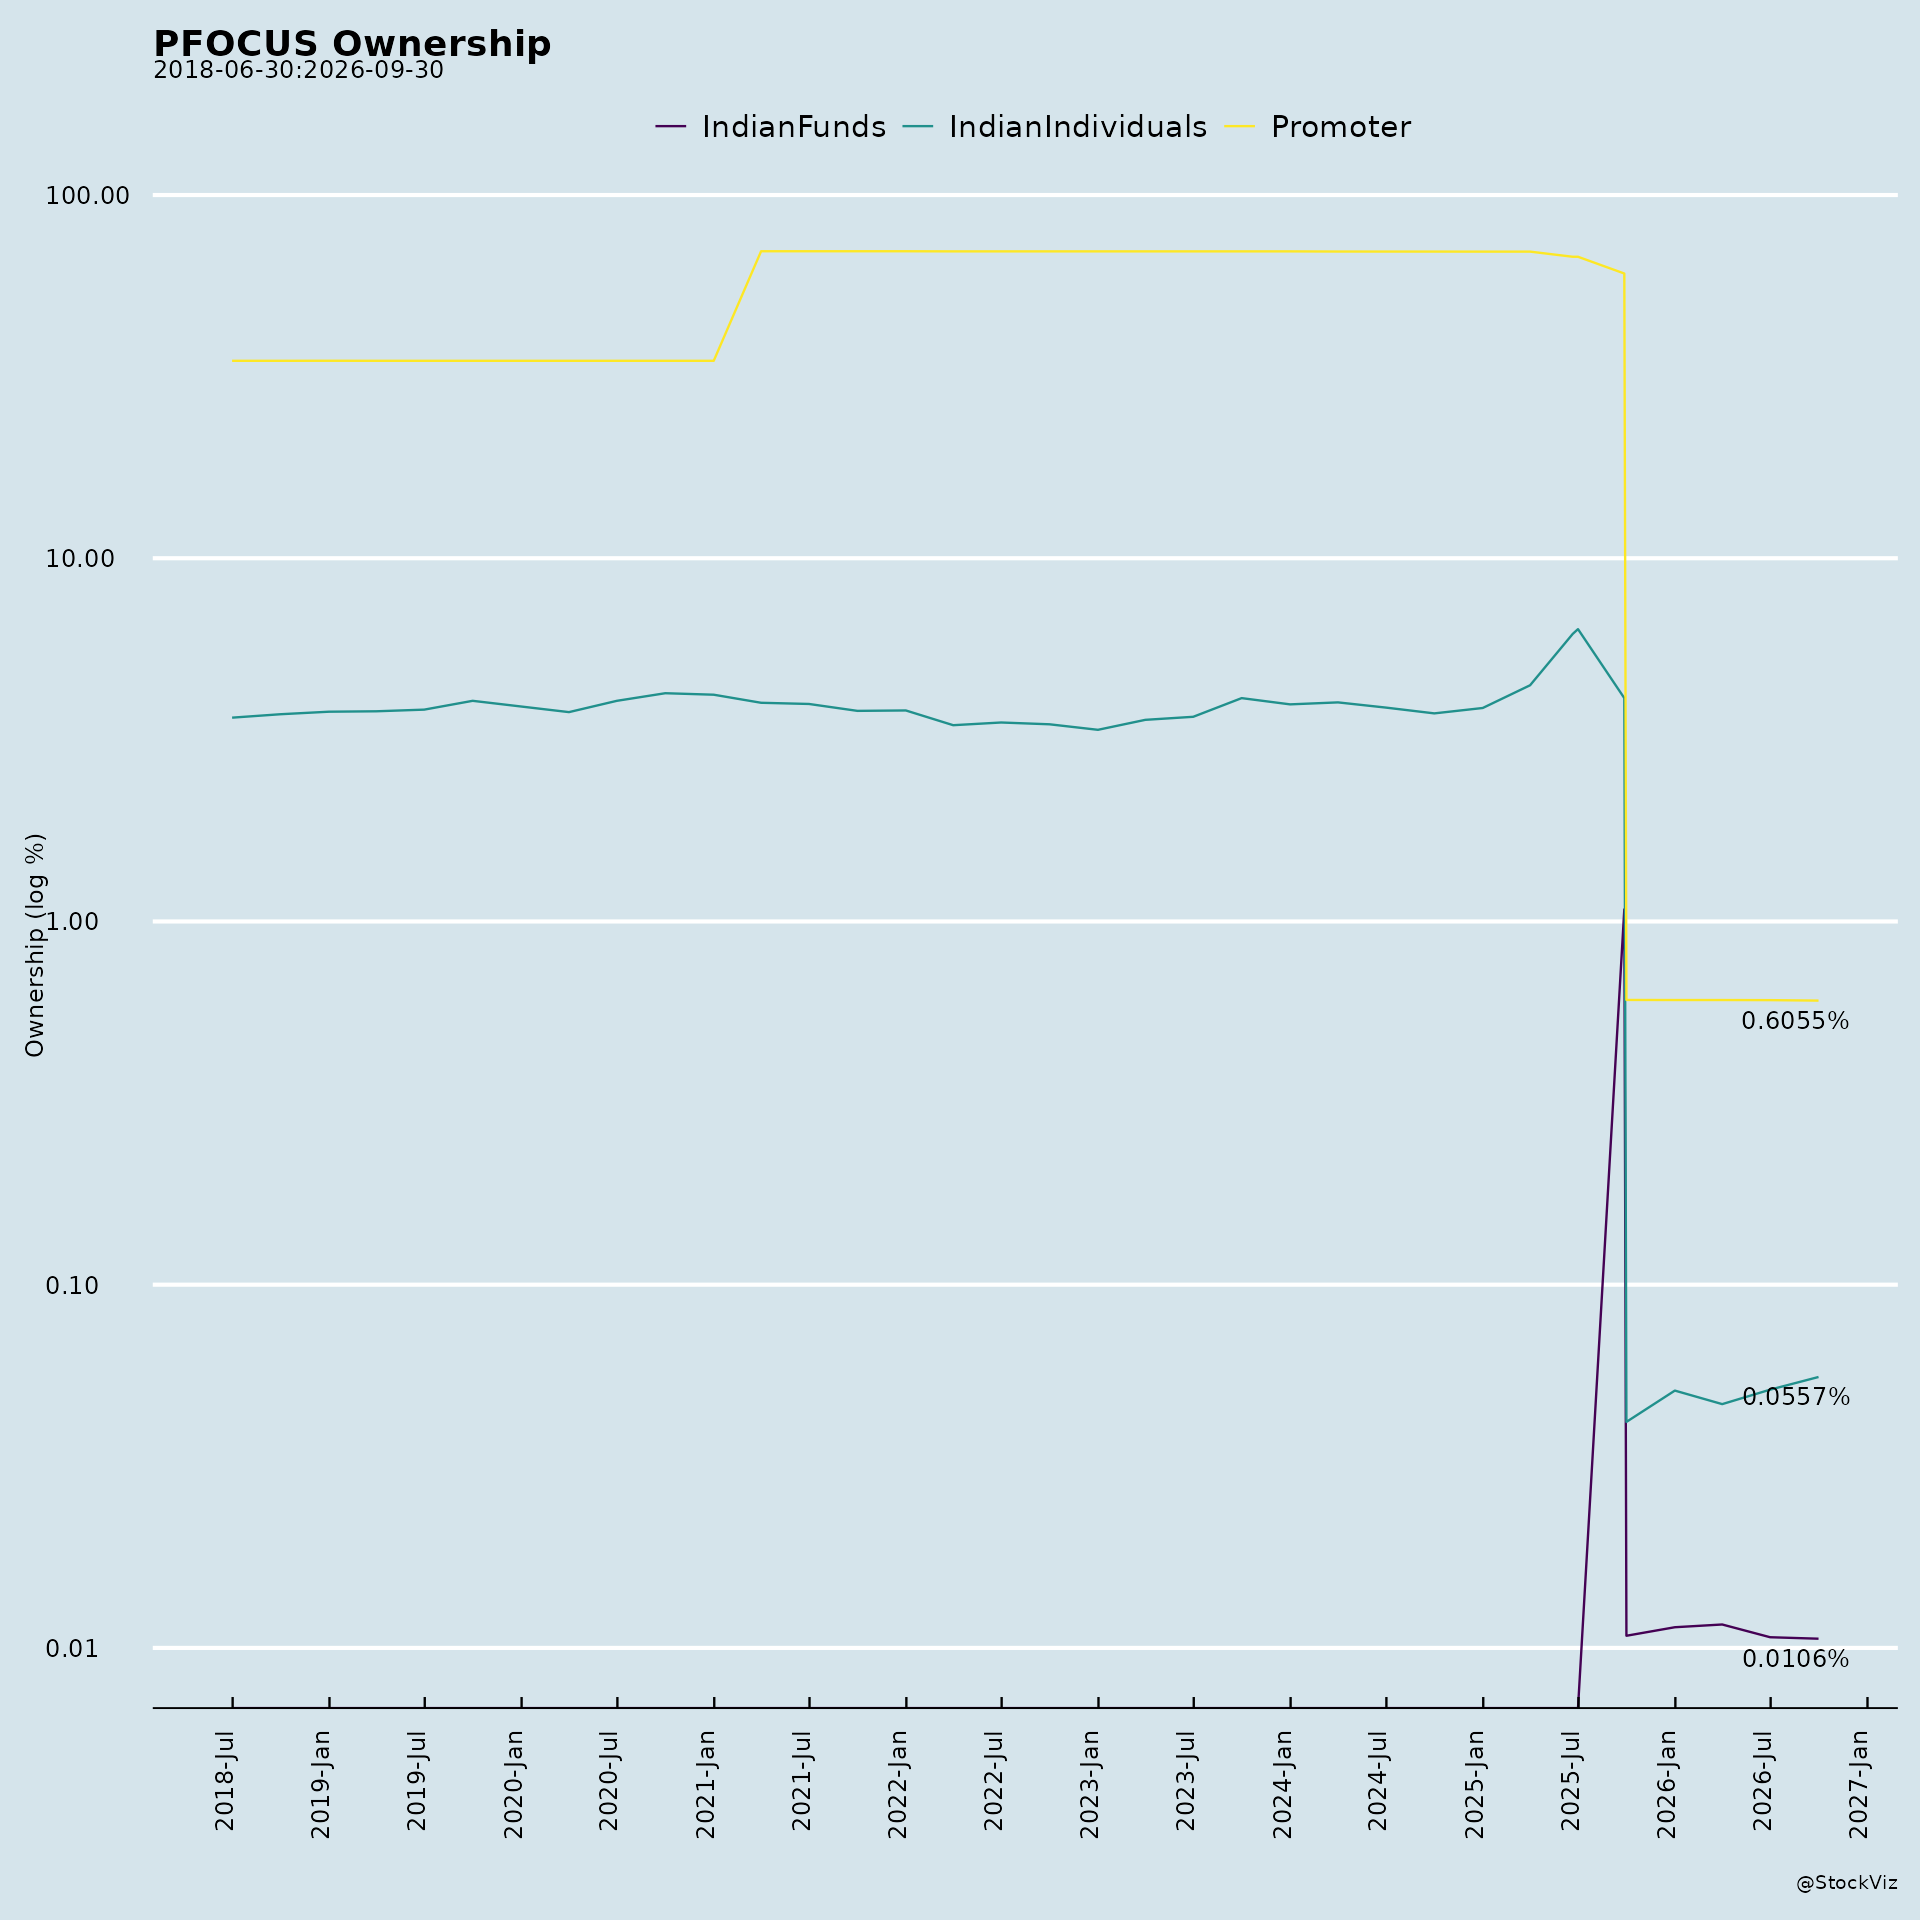
Ownership
Margined
AI Summary
asof: 2026-09-16
PFOCUS: Recent Corporate Announcements Summary
1. Headwinds and Challenges
Margin and pricing pressure: Platform consolidation across OTT and digital ecosystems, pricing pressure, and tighter scrutiny of return on investment are pressuring margins.
Cost inflation: Rising production and operating costs across technology, sets, post-production, logistics, VFX, hospitality, and marketing.
Regulatory complexity: New labour codes and evolving compliance frameworks are increasing operational complexity.
Industry-level risks: Changing consumer preferences, regulations, and potential supply chain disruptions or industry strikes.
Competition: Intense domestic and international competition, accelerated by rapid advancements in Artificial Intelligence.
Talent: Employee attrition, skilled talent shortages, and limited training institutes create talent retention risk.
Cybersecurity: Data breaches, ransomware attacks, and phishing attempts.
Legal matter: An NCLT petition filed by RASPL regarding a loan agreement was admitted in May 2026. The NCLAT granted a stay and required a deposit of INR 353.80 crores, which the Company has complied with.
2. Tailwinds and Growth Prospects
Digital expansion: Continued growth of OTT platforms, connected TV, digital advertising, retail media, and gaming.
Content demand: Growing consumer demand for original, culturally relevant, and regional content.
Global outsourcing: Expanding opportunities as studios outsource specialised activities such as VFX, animation, and post-production.
AI-led production: Production efficiency, automated workflows, and enhanced content creation.
New experience formats: Growth in live and immersive experiences and integrated media technology solutions.
Strategic initiatives: Focus on artificial intelligence through the unified enterprise AI platform BRAHMA AI, and high-profile upcoming co-production projects such as Ramayana.
Fundraise and capital base: The Board approved raising funds not exceeding INR 3,000 Crore via permissible securities (equity shares, debt securities, QIP, ADR/GDR, preferential issue, or rights issue) and agreed to increase authorised share capital from Rs. 85,00,00,000 to Rs. 100,00,00,000, subject to member and regulatory approvals.
3. Key Risks
- Margin pressure from platform consolidation, pricing pressure, and tighter ROI scrutiny.
- Cost inflation across production and operating expense lines.
- Regulatory pressures from new labour codes and evolving compliance frameworks.
- Changing consumer preferences, regulations, and potential supply chain disruptions or industry strikes.
- Competition from domestic and international players, intensified by AI advancements.
- Talent retention risk from attrition, skilled talent shortages, and limited training institutes.
- Cybersecurity risks including data breaches, ransomware, and phishing.
- Legal/regulatory risk from the RASPL NCLT petition admitted in May 2026, currently stayed by NCLAT subject to a complied deposit of INR 353.80 crores.
4. Management Guidance vs. Observed Business Performance
Guidance and forward-looking statements: - Global economic growth is projected to remain largely stable, with India continuing as one of the fastest-growing major economies. - Global M&E industry expected to grow at a CAGR of 3.4% between 2025 and 2030, reaching US$ 4.2 trillion by 2030. - Indian M&E industry expected to grow at an over-7% CAGR between 2025 and 2028, reaching approximately INR 3.3 trillion by 2028. - Focus on expanding global delivery and studio footprint, deepening partnerships with studios and OTT platforms, and driving operational efficiency through automation and cloud adoption, anchored in the three-pillar architecture of DNEG, BRAHMA AI, and Prime Focus Studios.
Observed performance (FY 2025-26): - Consolidated total income from operations: INR 4,675.81 crores. - Net profit after tax after minority interest: INR 218.74 crores. - Standalone income from operations: INR 27.86 crores, with a net loss after tax of INR 2.75 crores. - Adjusted EBITDA: INR 1,423 crores at a 30.4% margin. - Net debt: INR 4,374 crores as of March 31, 2026.
Governance and capital actions: - The 29th AGM is scheduled for Wednesday, September 30, 2026, at 12:30 P.M. (IST) via Video Conferencing / Other Audio Visual Means. - Physical letters containing weblinks to the Annual Report for FY 2025-26 and the AGM Notice were dispatched to members whose email addresses were not registered as of the cut-off date of Friday, August 28, 2026. - The proposed fundraise of up to INR 3,000 Crore and increase in authorised share capital are subject to member and regulatory approvals.
Broker Timeline
1 broker calls · 2026-09-06 to 2026-09-06
CNBC-TV18: ratings, targets and commentary
No recorded CNBC-TV18 statements for this ticker.
Management comments
No recorded management comments with an explicit designation and affiliation for this ticker.
Copyright © 2023 SAS Data Analytics Pvt. Ltd. All rights reserved.