PFC
Equity Metrics
October 23, 2026
Power Finance Corporation Limited
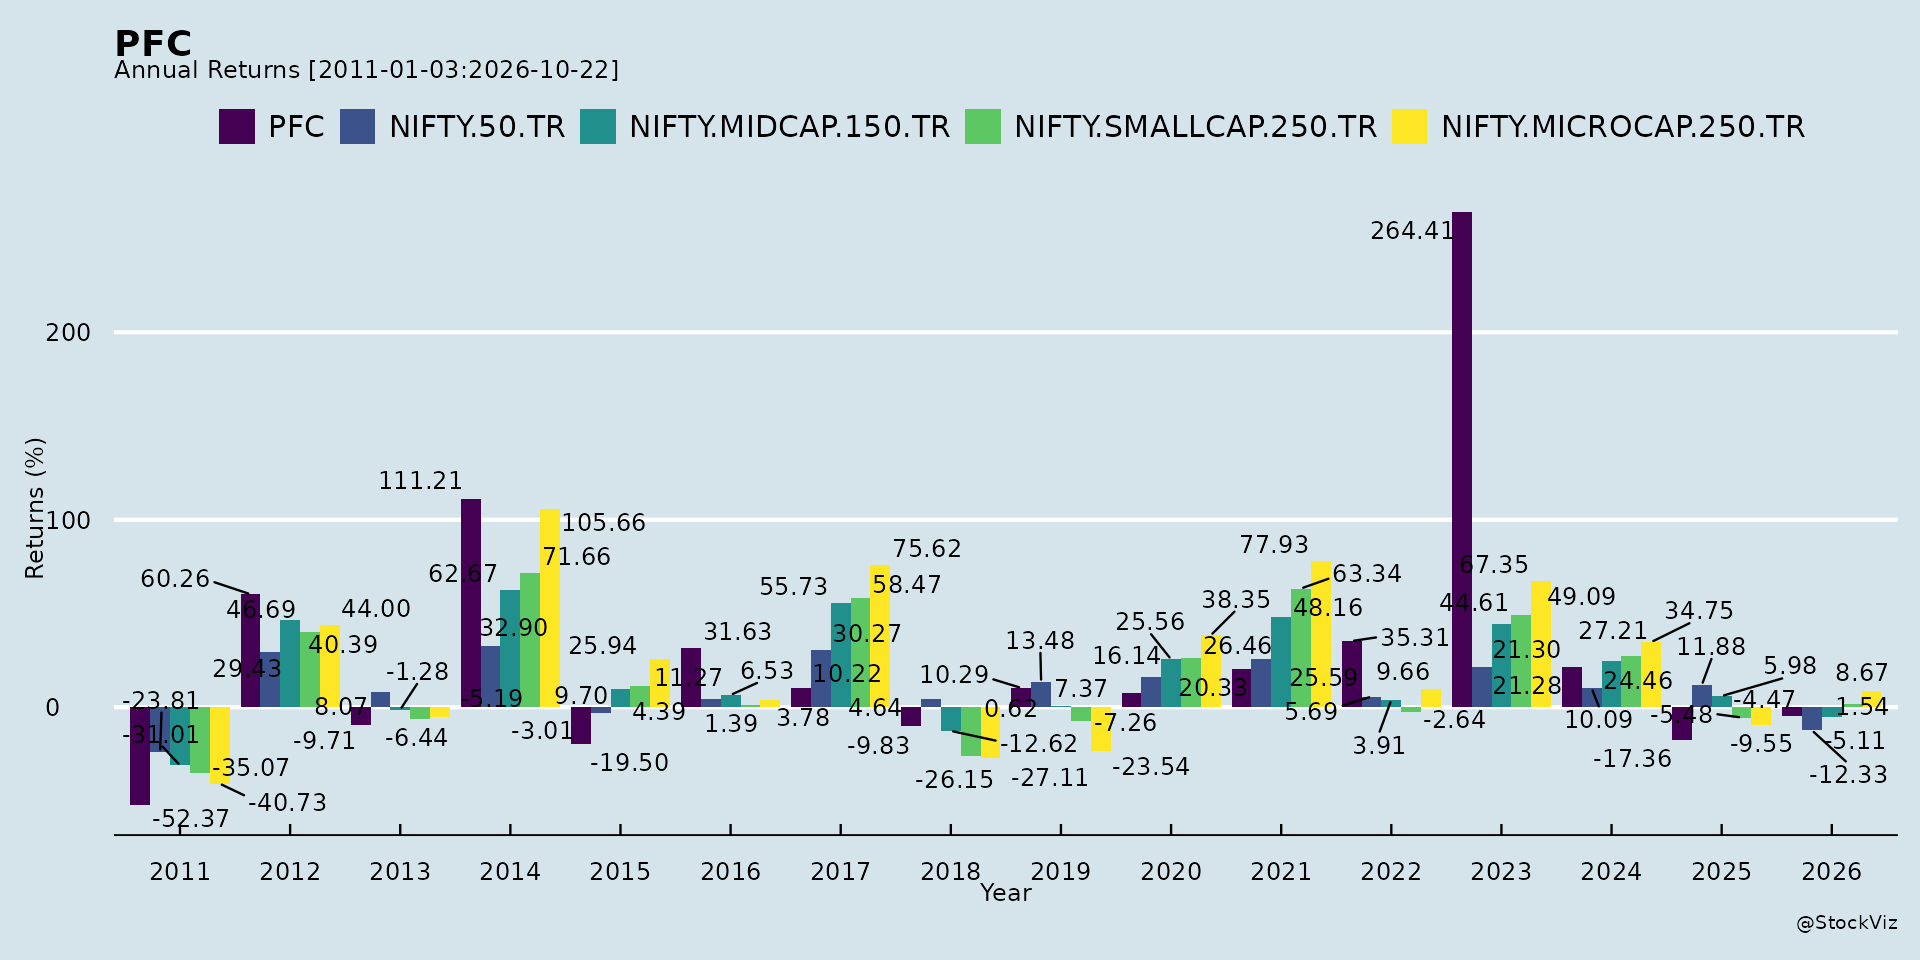
Annual Returns
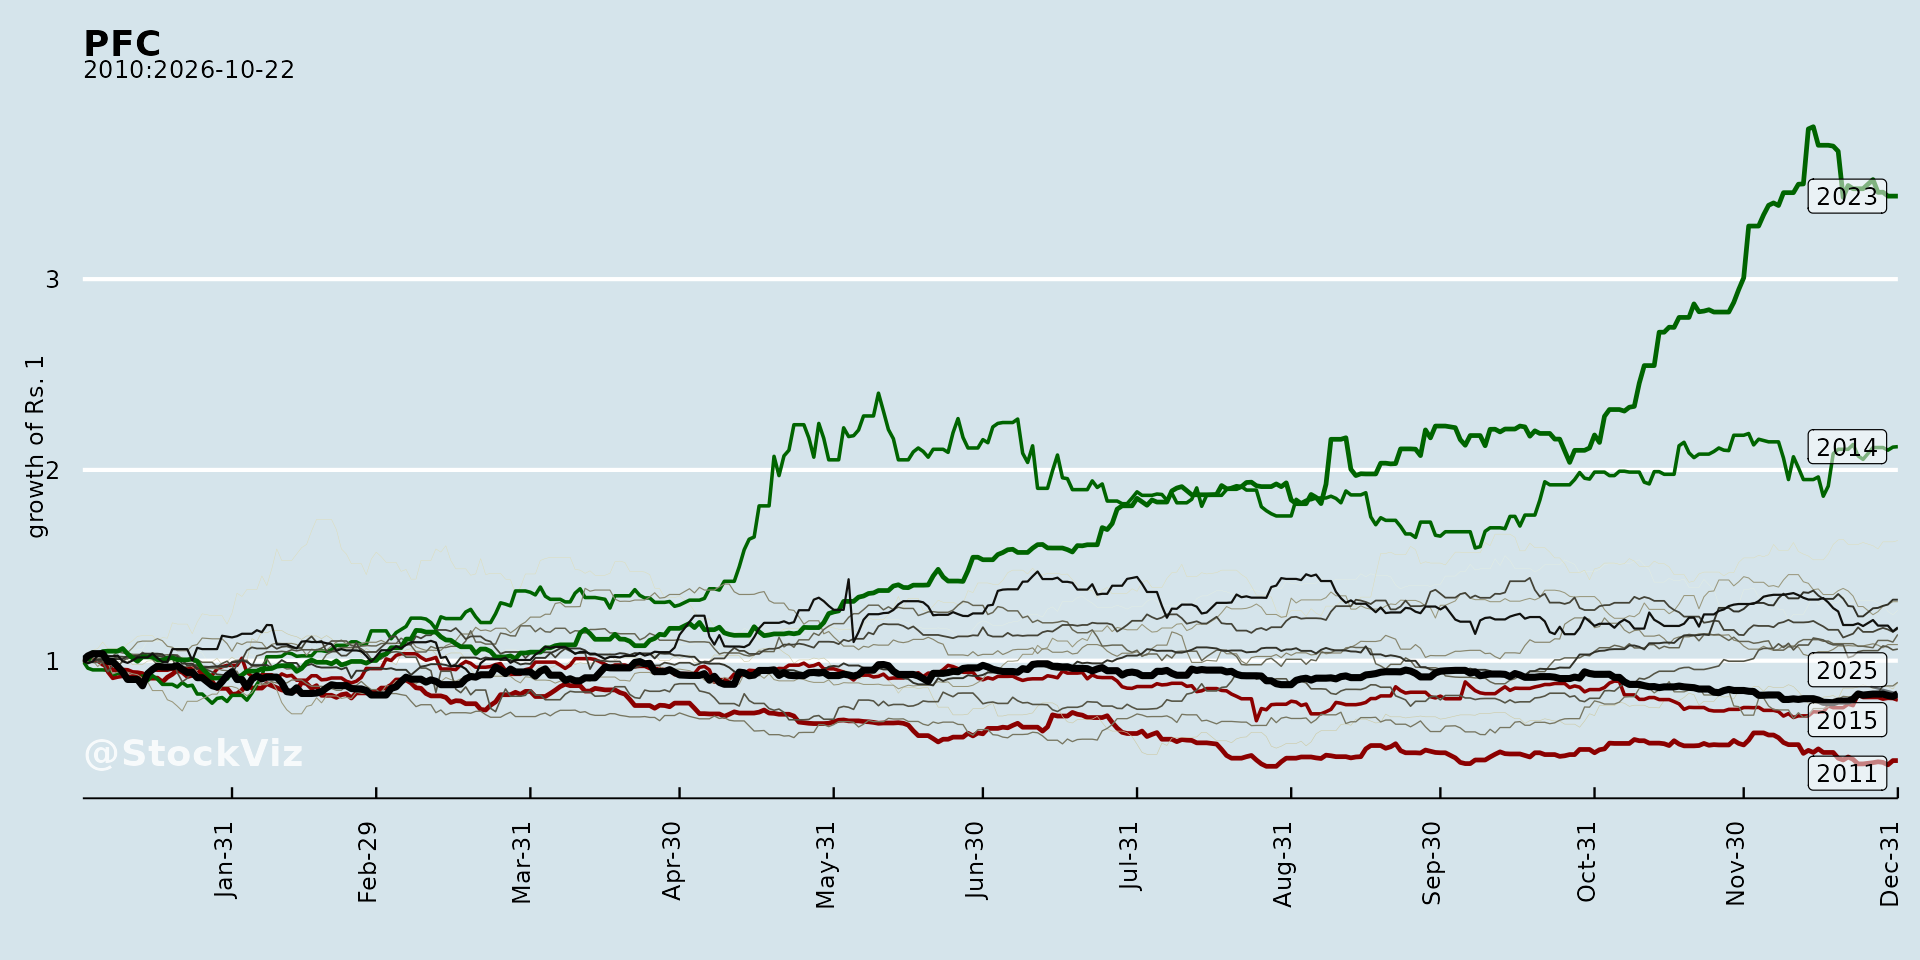
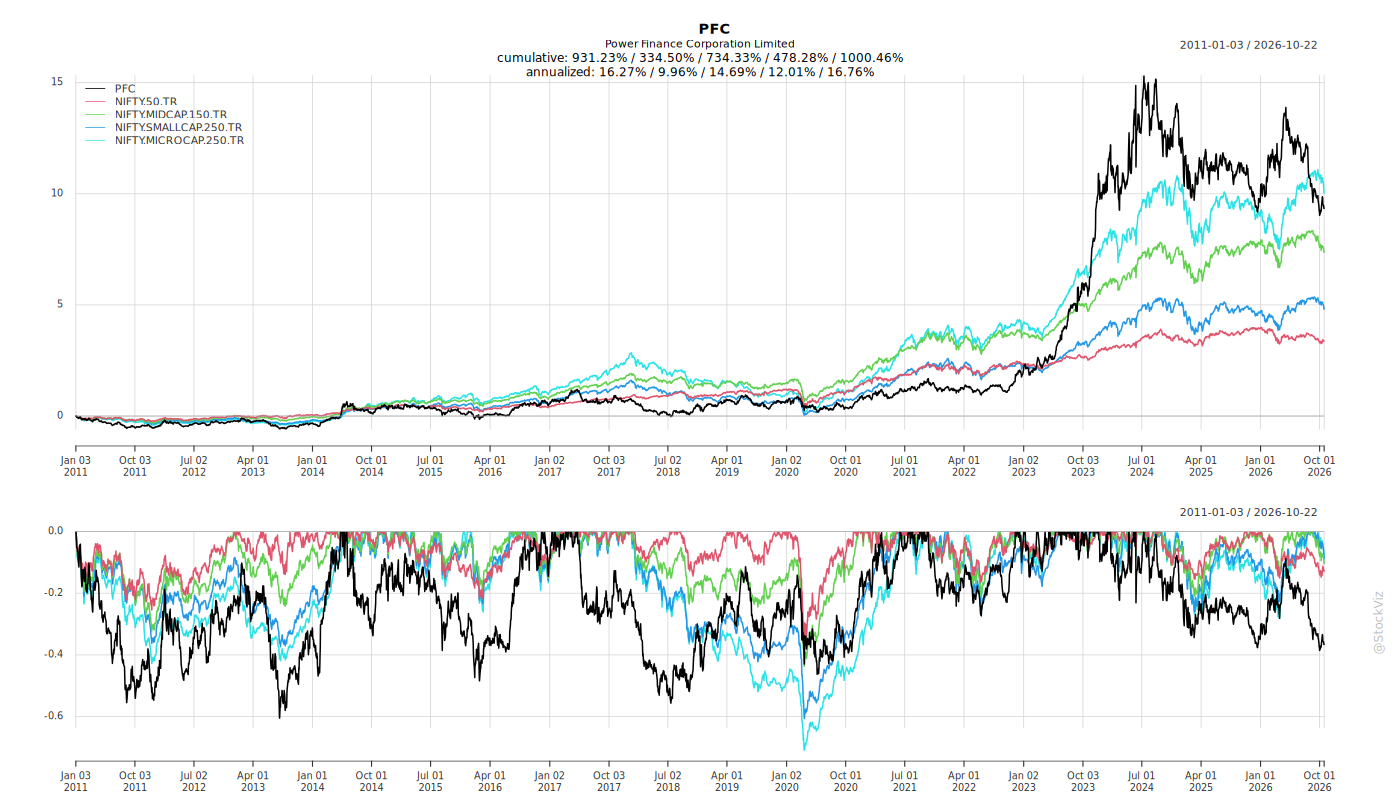
Cumulative Returns and Drawdowns
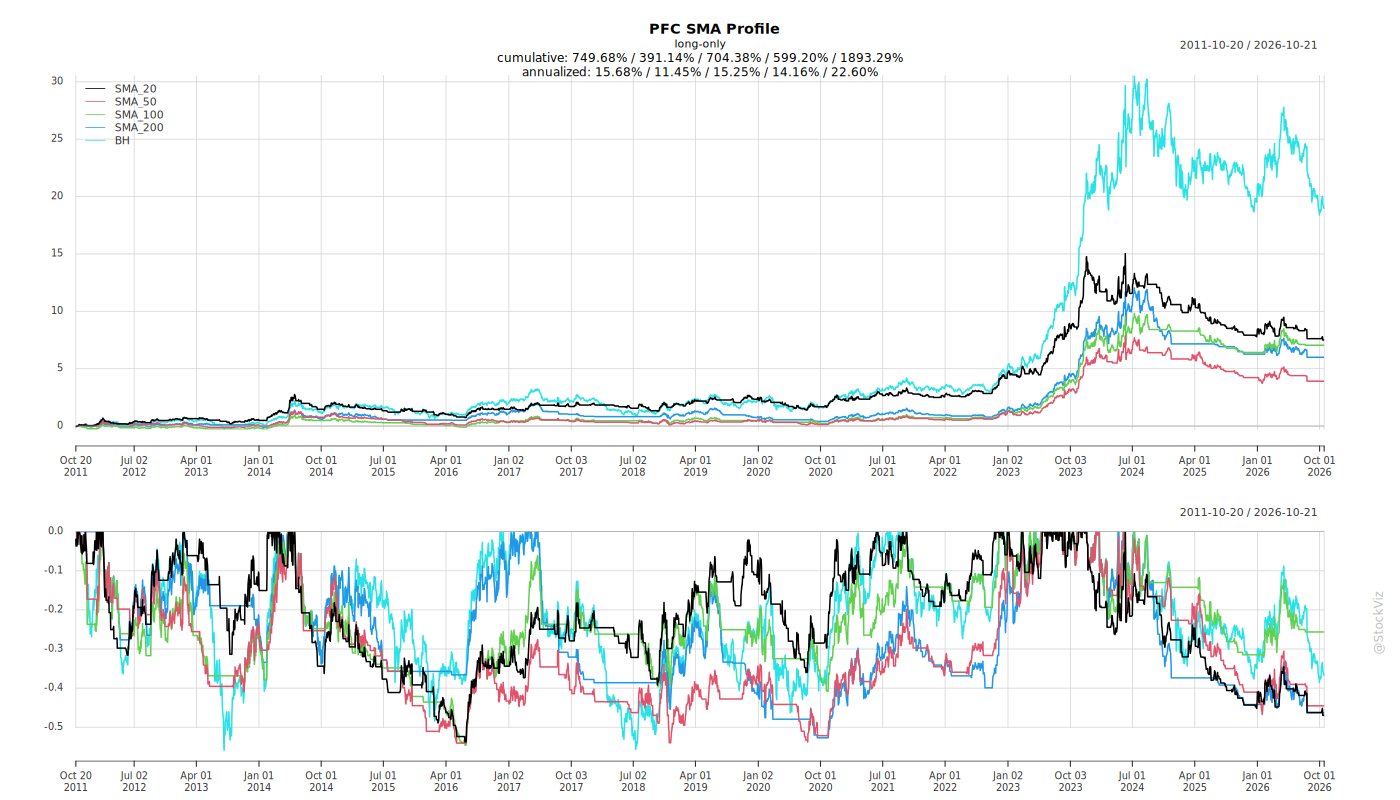
Fundamentals
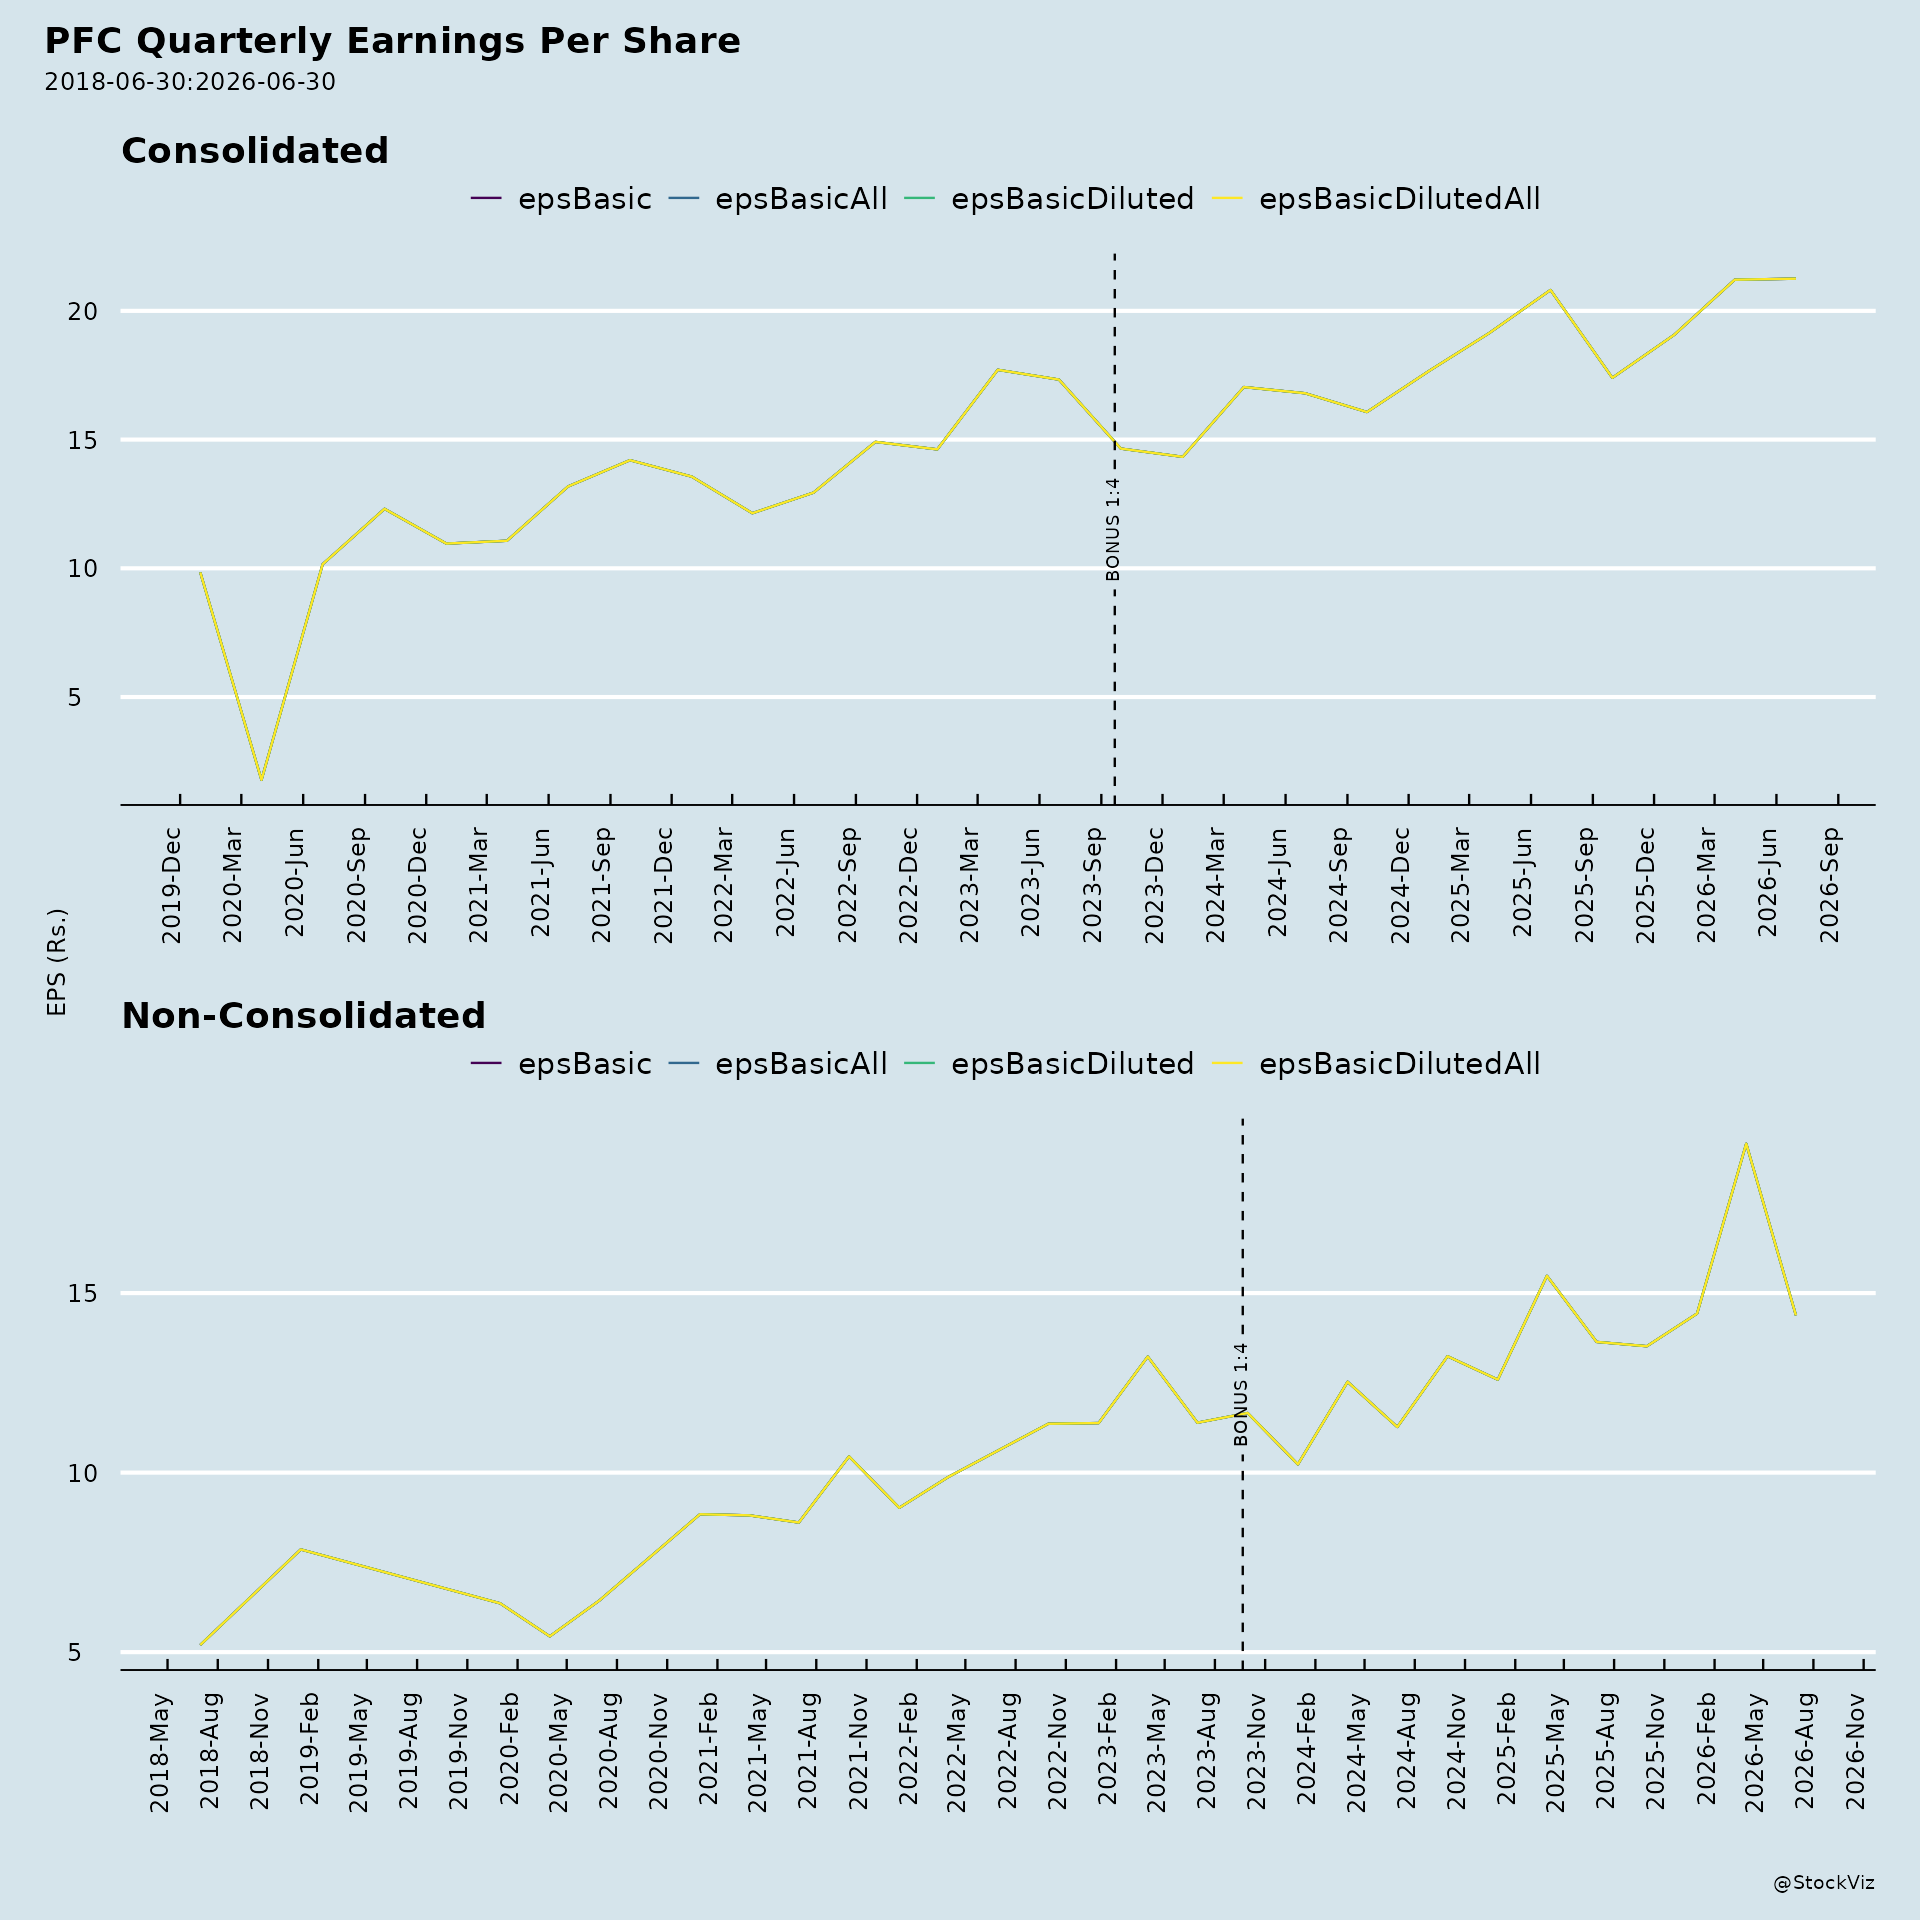
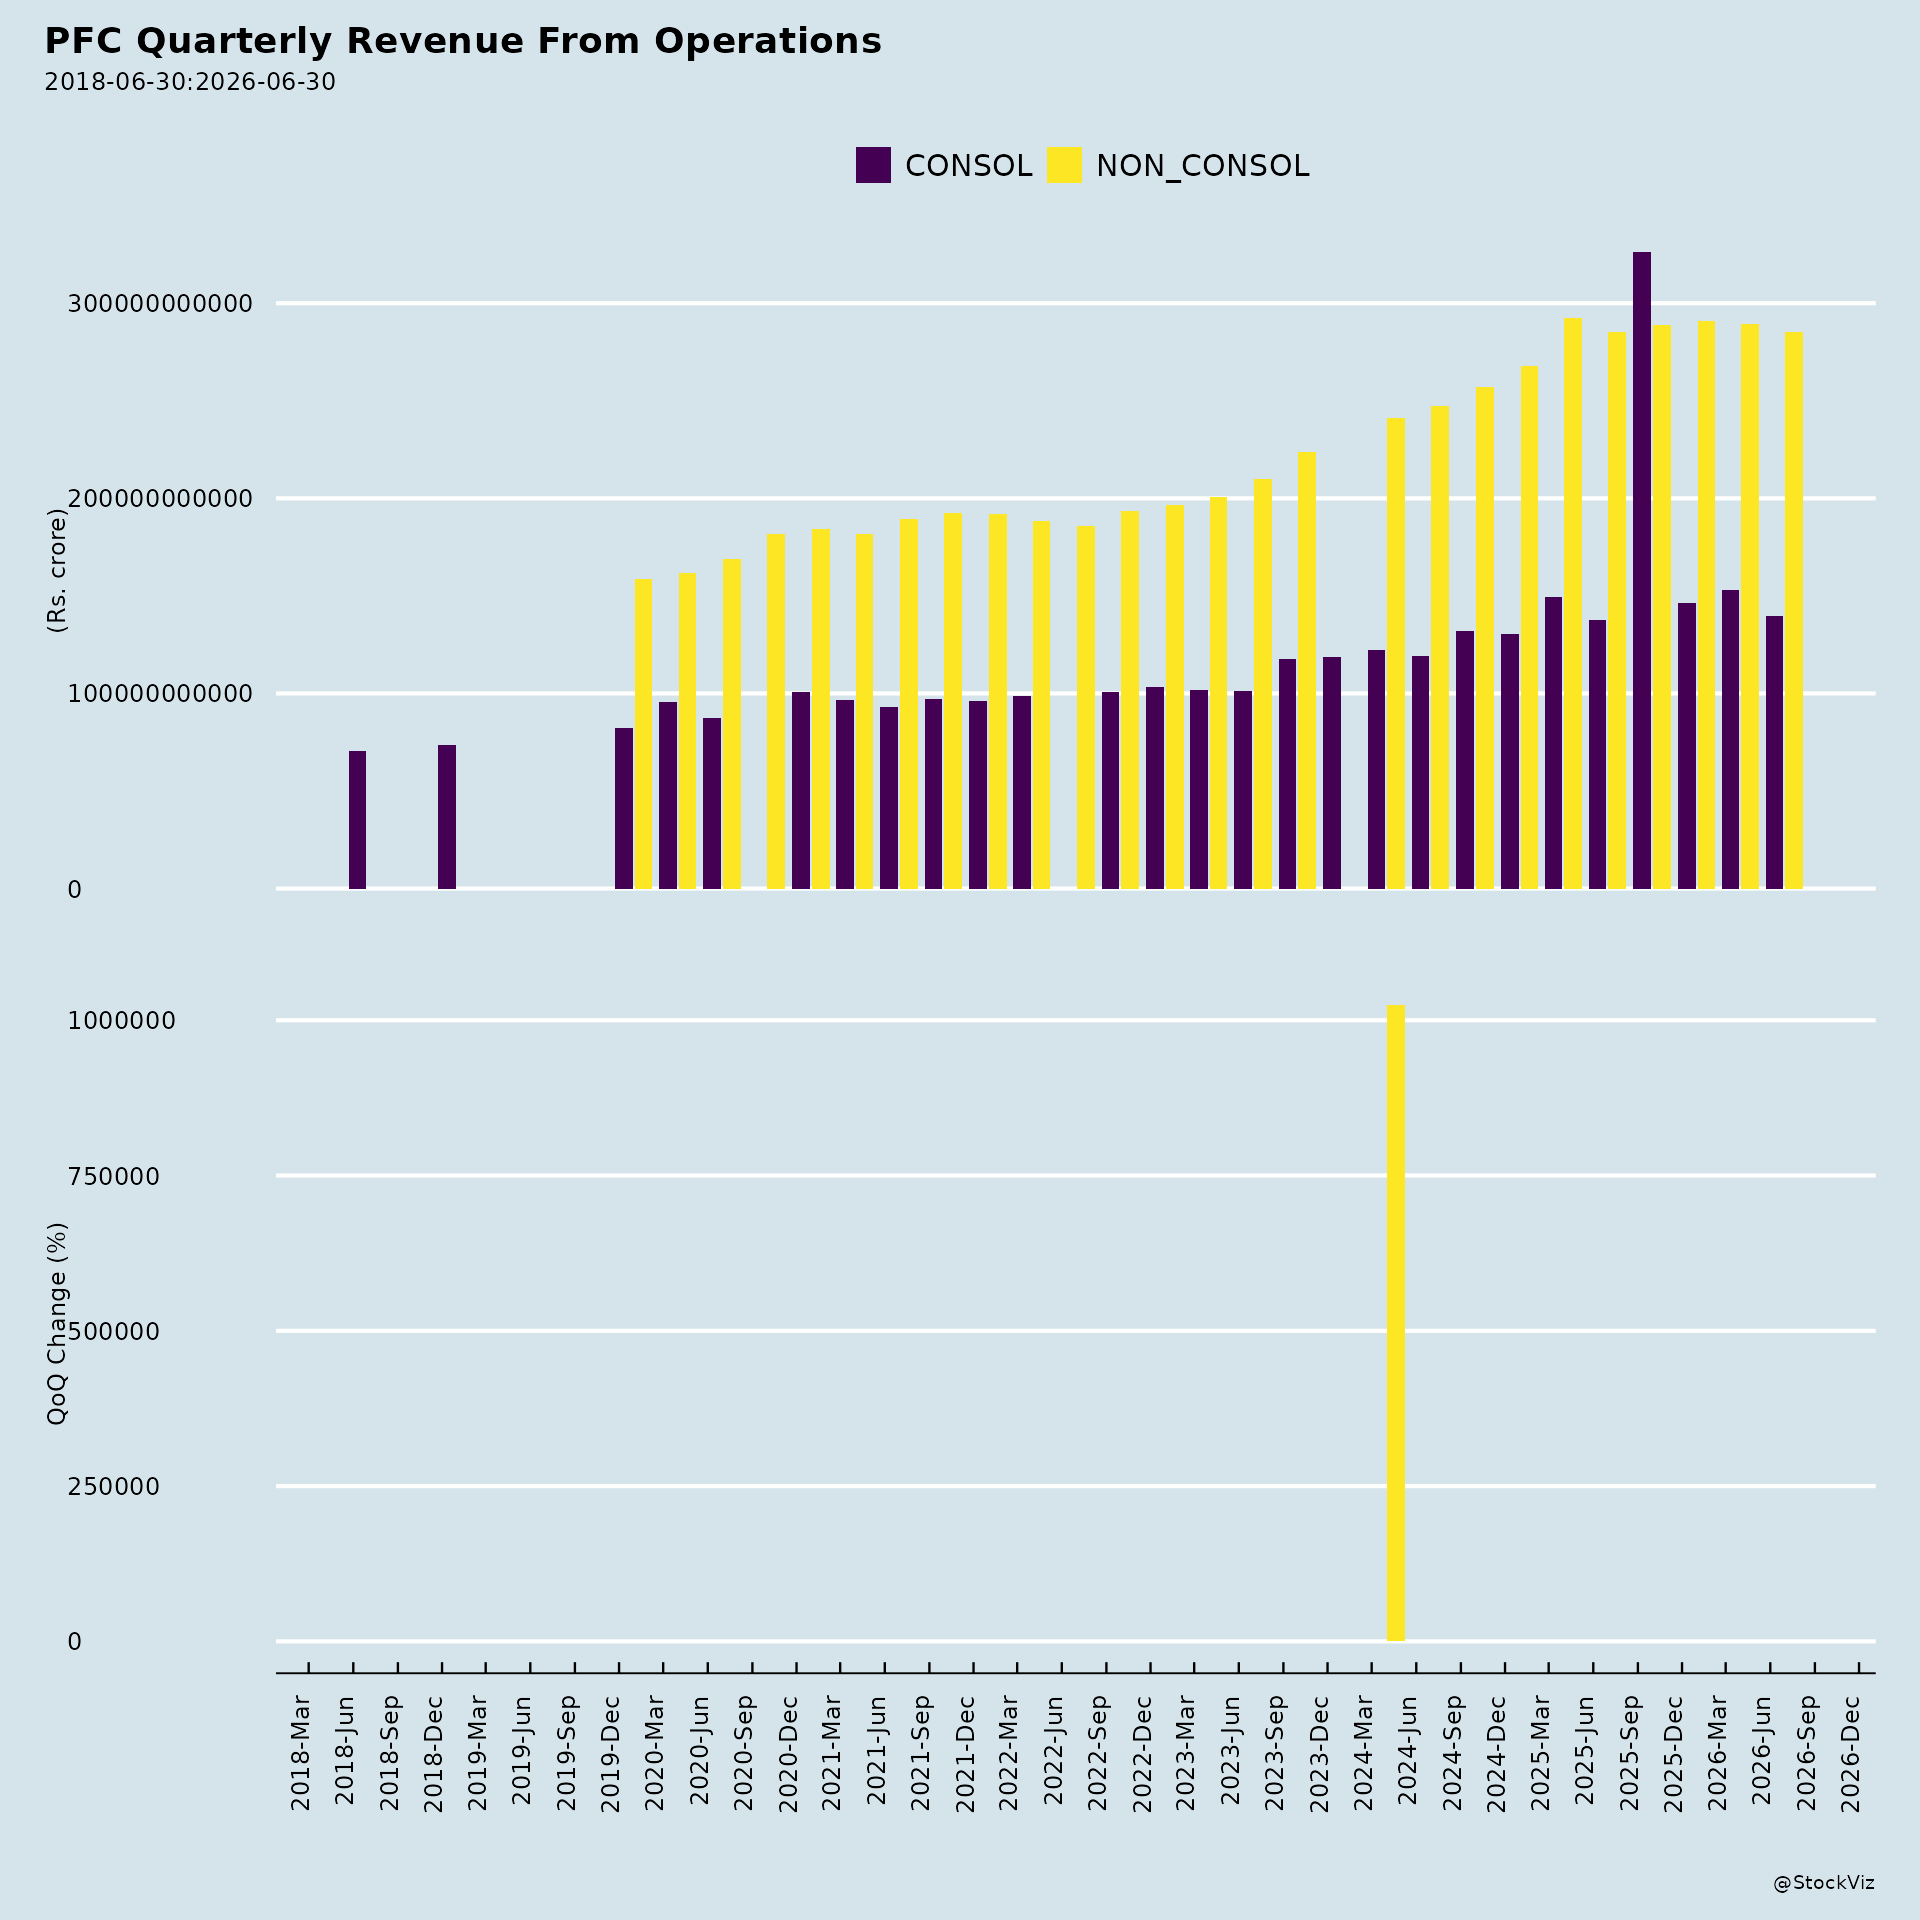
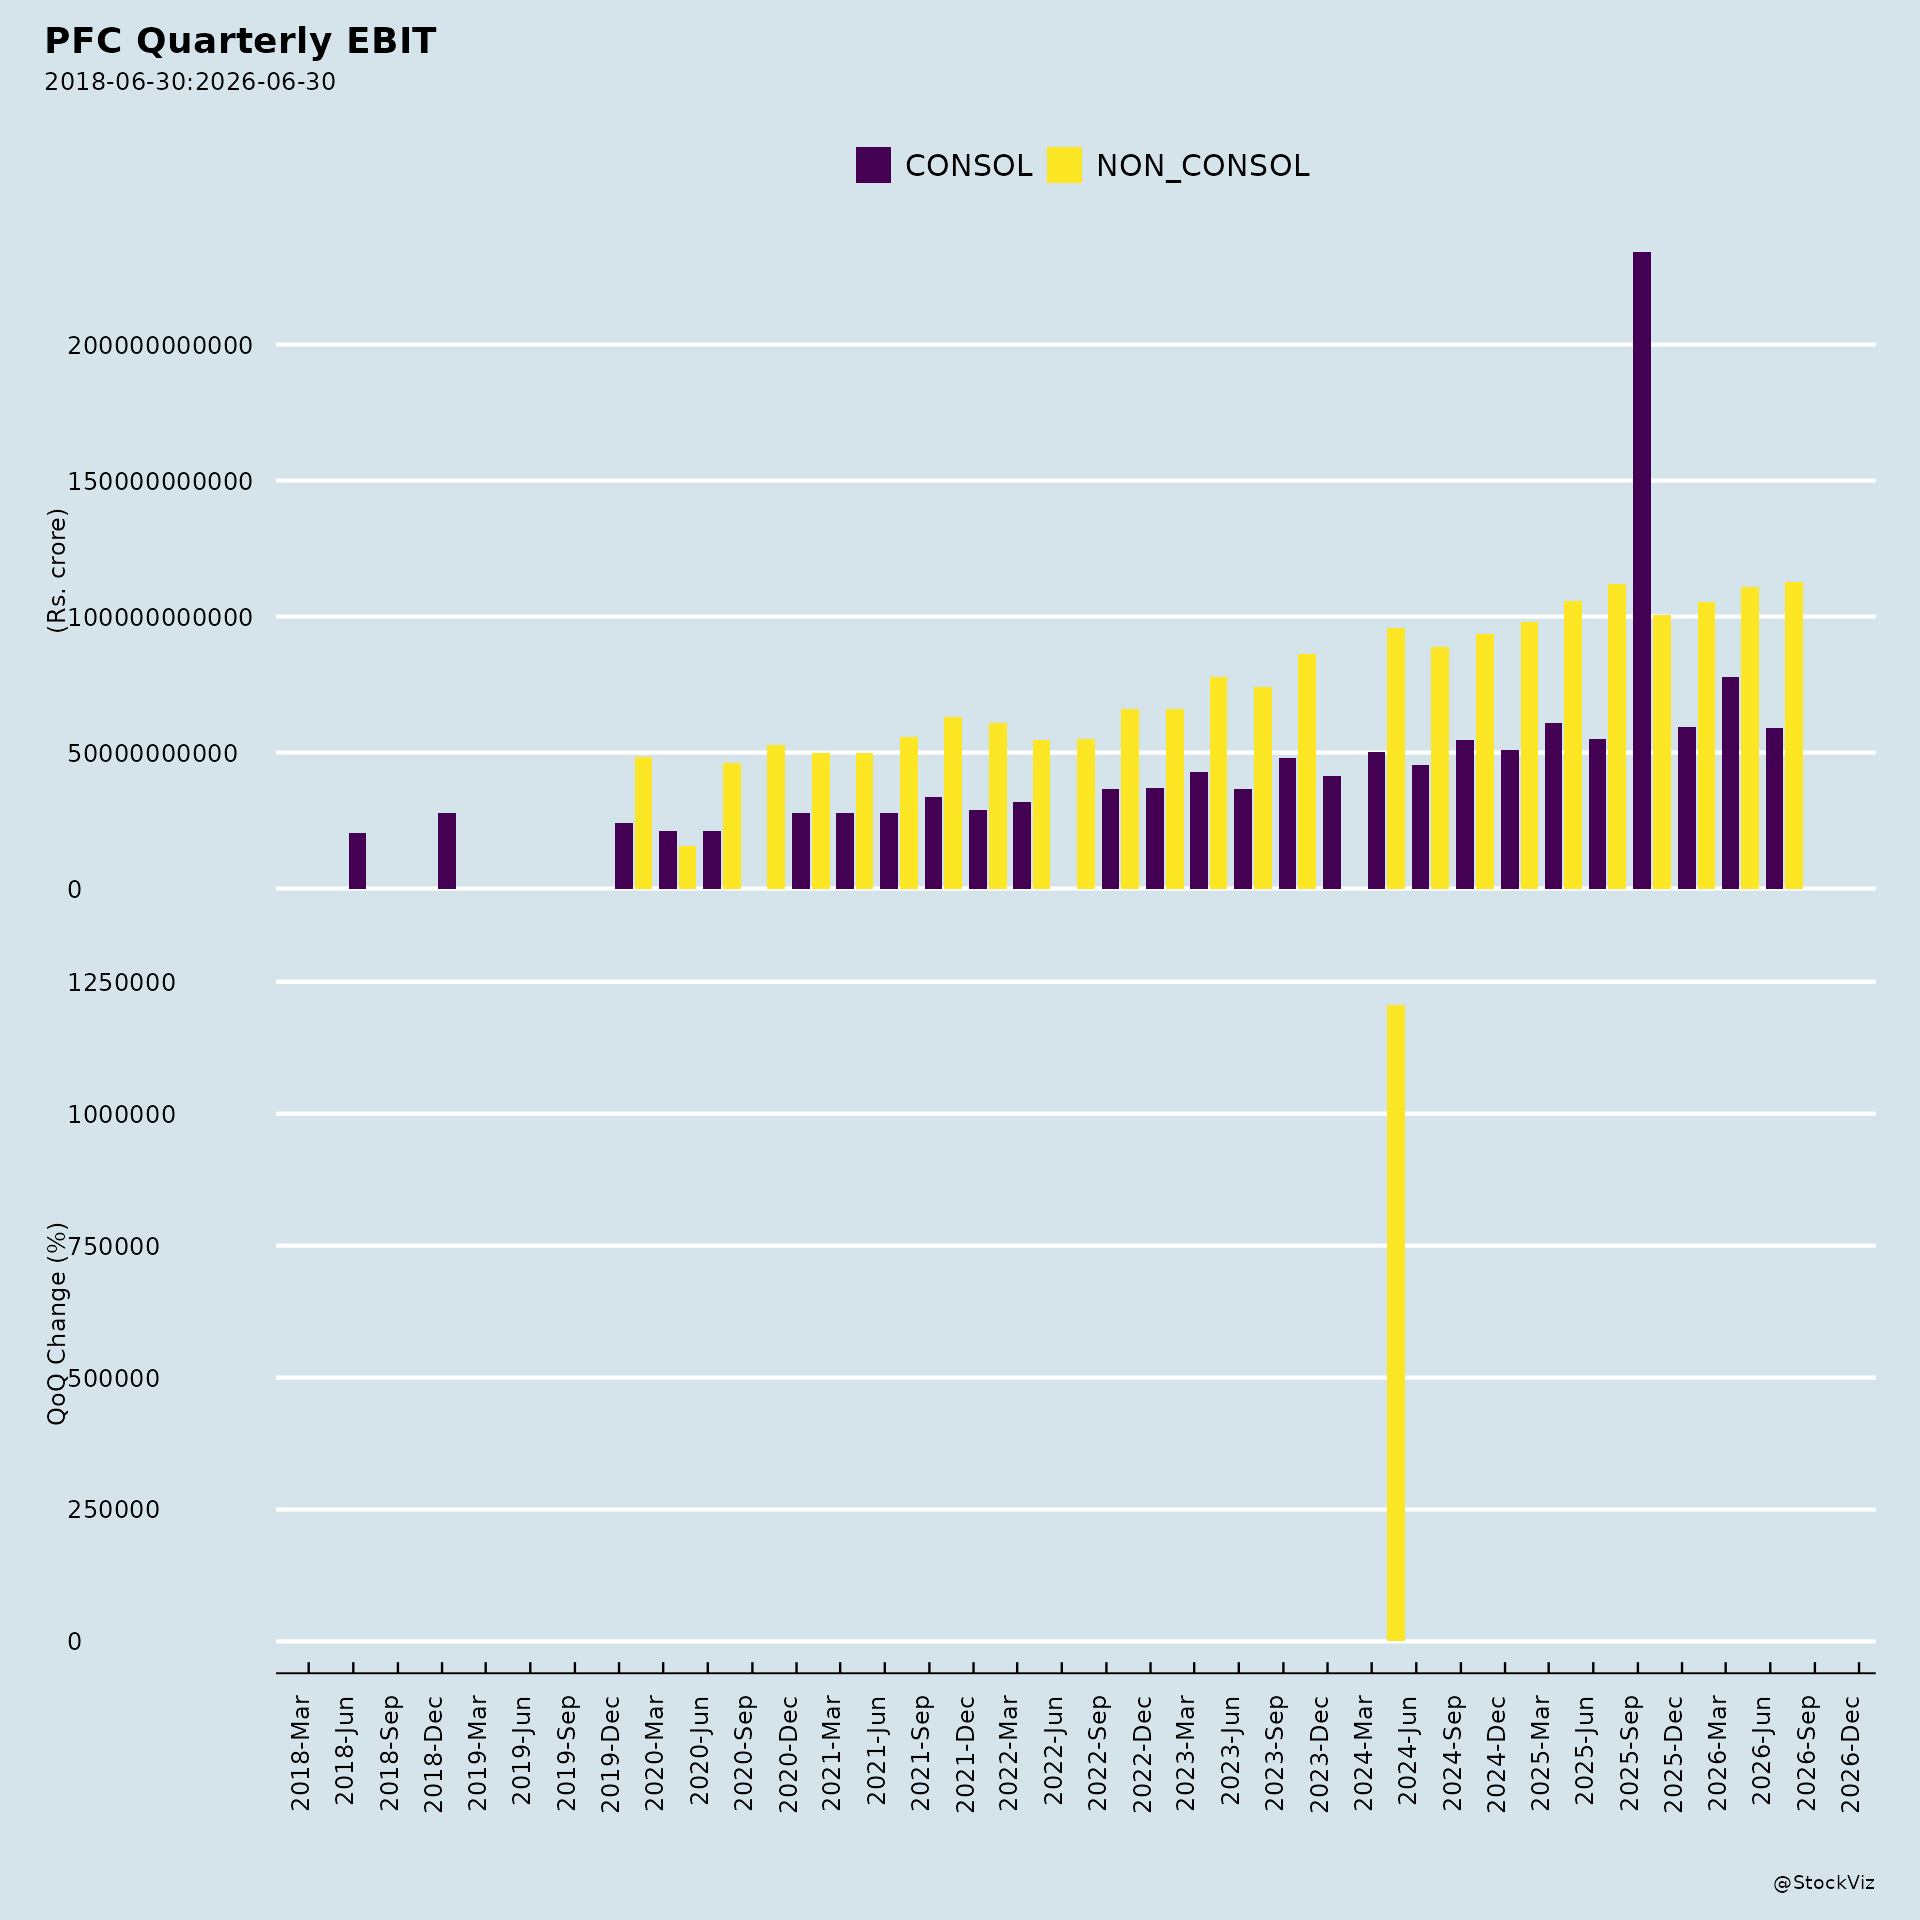
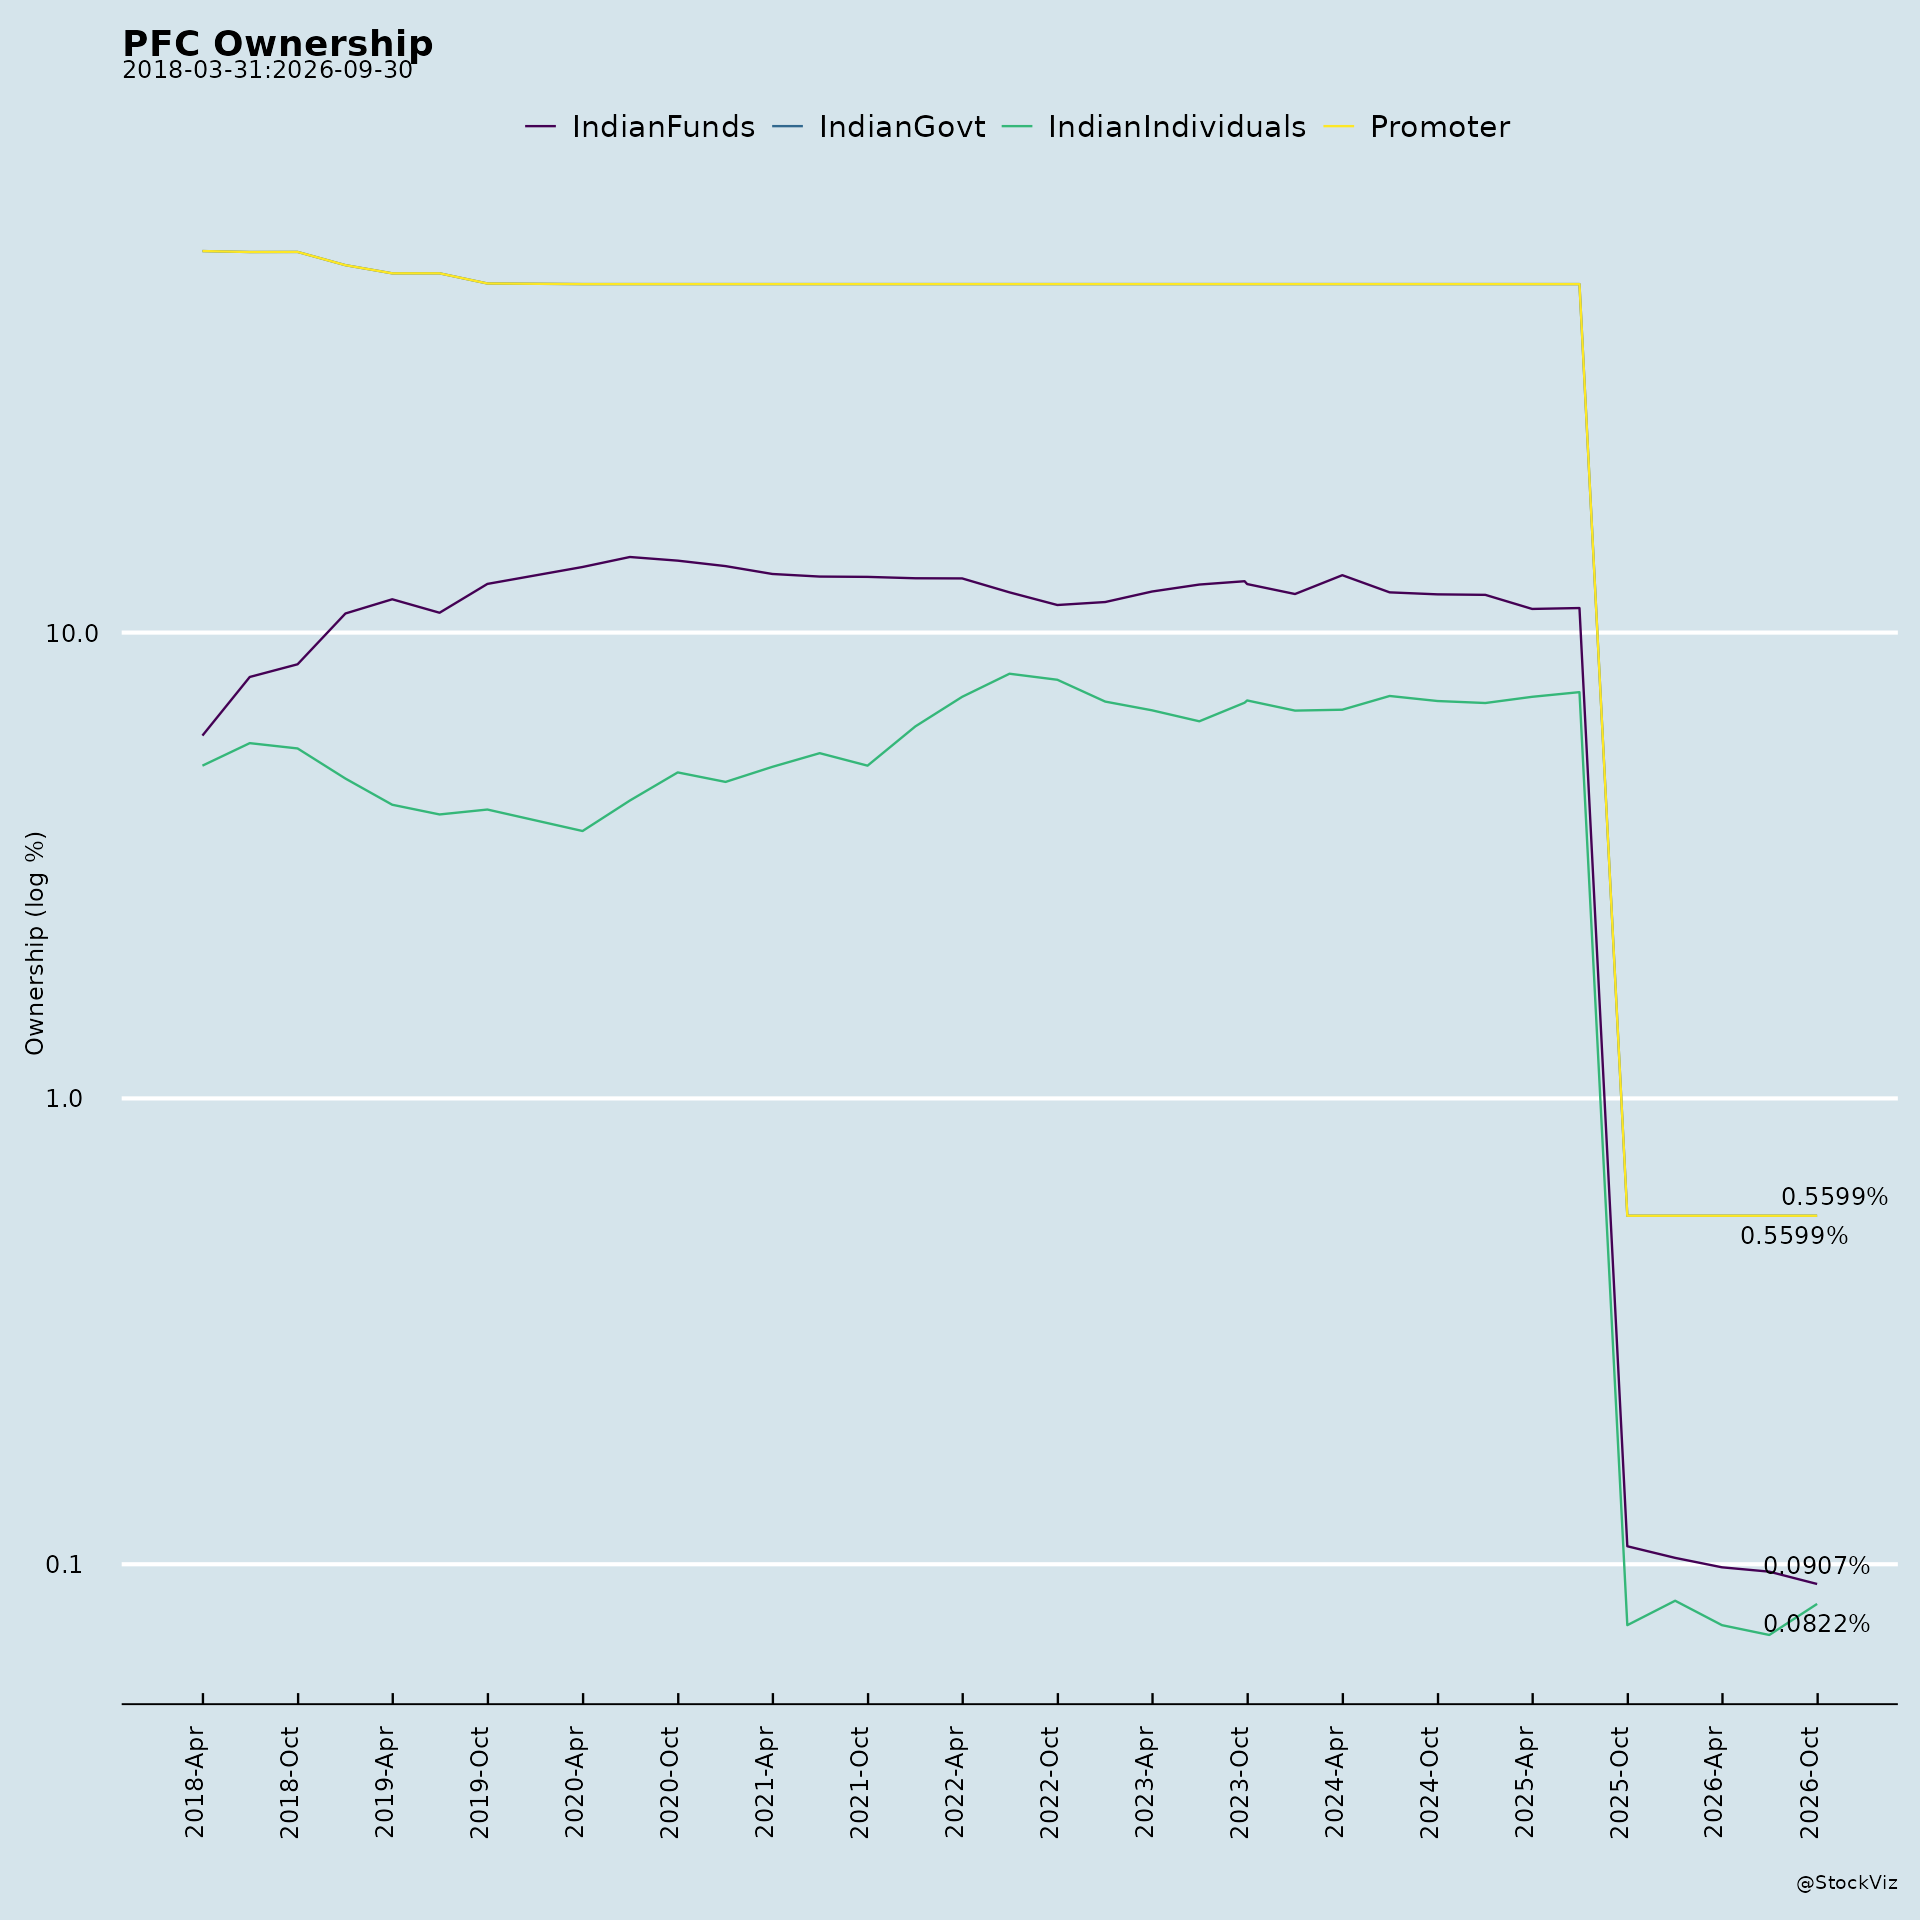
Ownership
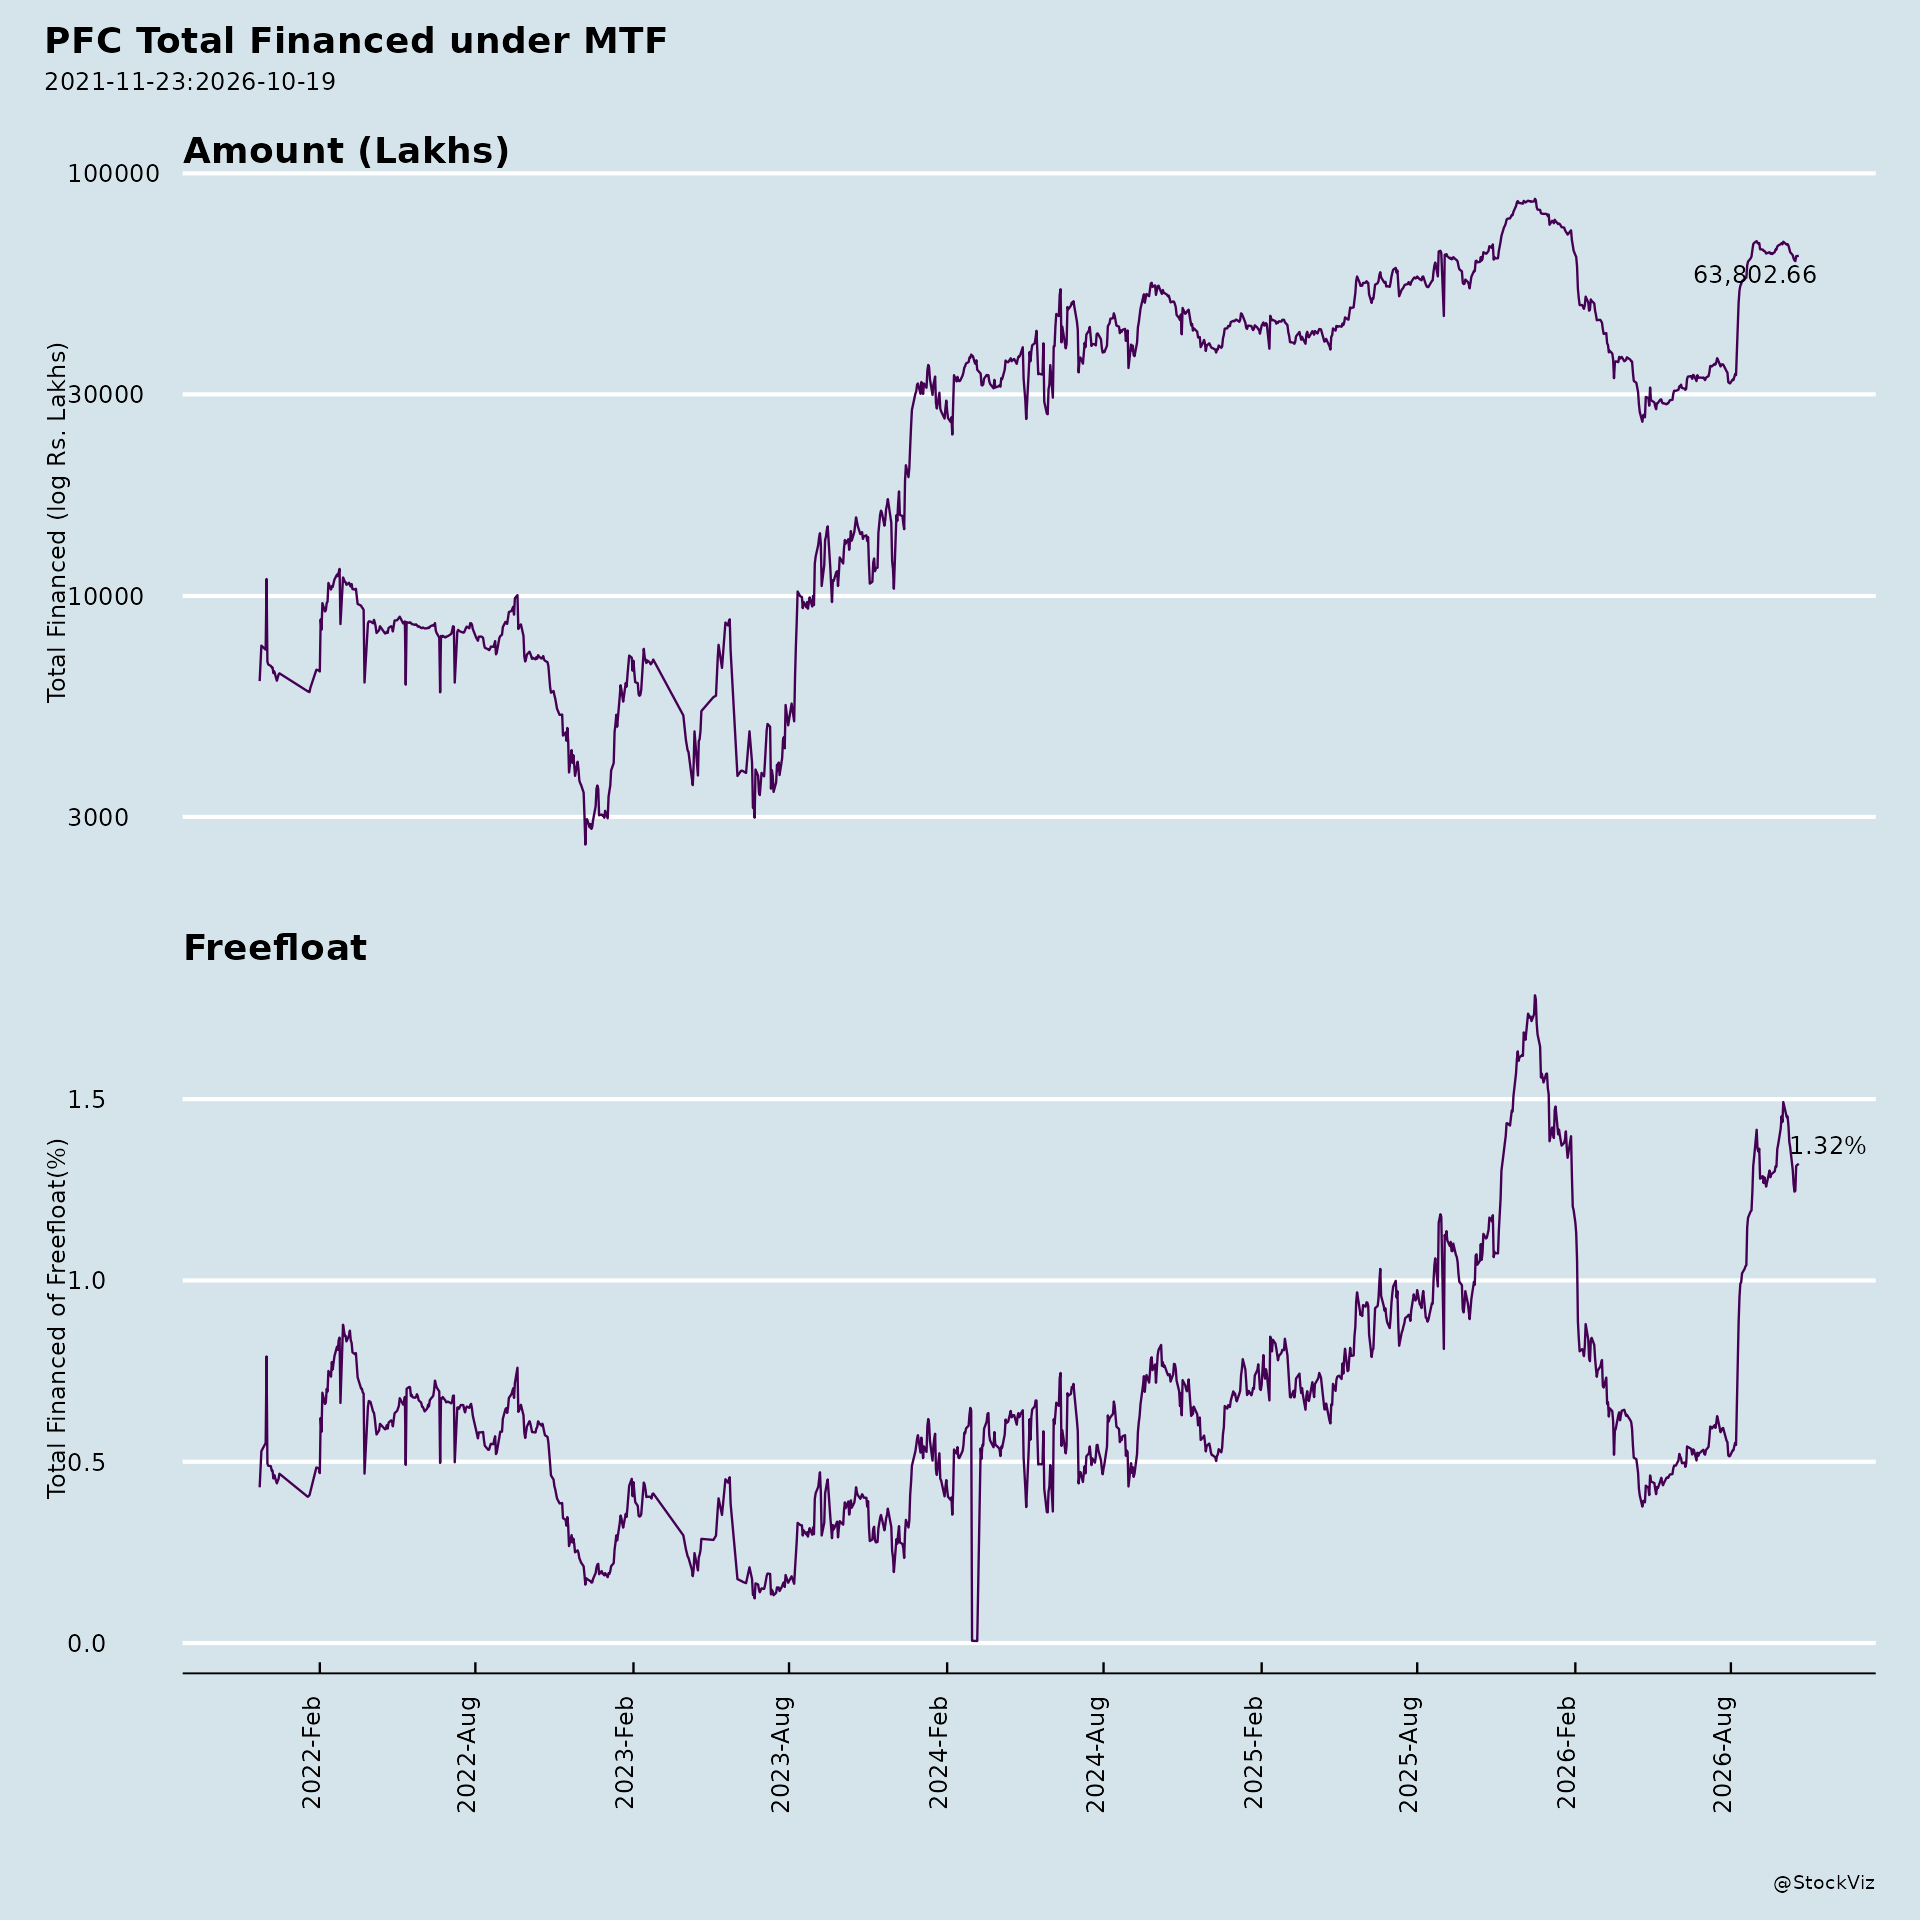
Margined
AI Summary
asof: 2026-09-14
PFC — Recent Corporate Announcements: Summary
1. Headwinds and Challenges
The supplied material does not identify specific headwinds or challenges. The only items that could be read as constraints or obligations are procedural and financial in nature:
- The interim dividend of Rs. 3.90 per equity share (39% on face value of Rs. 10 each) is subject to deduction of tax at source, with dividend income taxable in the hands of shareholders.
- The company must complete payment of the interim dividend on or before 06.09.2026, with 27.08.2026 fixed as the Record Date.
- The 40th AGM included an item for enhancement of the borrowing limit, indicating a need for shareholder approval to expand borrowing capacity.
No operational, sectoral, or financial headwinds are described in the source material.
2. Tailwinds and Growth Prospects
The material sets out several forward-looking opportunities:
- Energy transition financing: Financing India’s energy transition is identified as a growth prospect.
- Renewable energy: Initiatives in renewable energy are cited as an opportunity.
- Distribution reforms: Power distribution reforms are listed among growth areas.
- Sustainable finance: Sustainable finance is identified as a prospect.
- Proposed PFC-REC merger: The merger is described as having strategic significance, with management discussing its strategic importance and a future roadmap.
- Fifth Decade priorities: Management highlighted priorities for PFC’s Fifth Decade, framed around supporting India’s journey to Viksit Bharat 2047.
- Prudent growth and risk management: These are cited as part of the company’s growth prospects.
3. Key Risks
The supplied material does not describe specific risks. The items with risk-adjacent content are:
- The proposed PFC-REC merger, which is referenced as a strategic initiative with a future roadmap but without detail on execution or integration risk.
- The enhancement of the borrowing limit, which implies reliance on continued access to debt funding, though no risk is stated.
- Tax deduction at source on dividends, which affects shareholder returns but is not framed as a risk.
No credit, market, regulatory, or operational risks are identified in the source material.
4. Management Guidance vs. Observed Business Performance
Guidance and forward-looking statements provided:
- Priorities for the Fifth Decade supporting India’s journey to Viksit Bharat 2047.
- Strategic significance of the proposed PFC-REC merger, along with a future roadmap.
- Focus on ESG rating and borrowing strategy.
- Growth prospects tied to energy transition, renewable energy, distribution reforms, and sustainable finance.
- Prudent growth and risk management as ongoing priorities.
Observed business performance and corporate actions:
- The Board, in its meeting on 07.08.2026, approved unaudited standalone and consolidated financial results for the quarter ended 30.06.2026, along with special purpose condensed interim financial statements, accompanied by a Limited Review Report from the joint statutory auditors (Thakur Vaidyanath Aiyar & Co. and Mehra Goel & Co. LLP).
- The Board declared an interim dividend of Rs. 3.90 per equity share (39%) for FY 2026-27, with a Record Date of 27.08.2026 and payment on or before 06.09.2026.
- The 40th AGM was held on Monday, 31.08.2026, via video conferencing, with 159 shareholders holding 1,84,78,93,469 shares attending.
- All business items and resolutions proposed for the 40th AGM were approved with the requisite majority. These covered adoption of standalone and consolidated audited financial statements for FY ended 31.03.2026, confirmation of the interim dividend, declaration of the final dividend, appointment and remuneration of directors and statutory auditors, and enhancement of the borrowing limit.
The source material does not provide financial figures from the quarterly results or AGM outcomes that would allow a direct comparison between management’s forward-looking statements and actual performance. The only observable performance-linked actions are the declaration of the interim dividend, the approval of audited FY2025-26 financial statements, and the shareholder-approved enhancement of the borrowing limit.
Broker Narrative
The first report in 2024 flagged no headwinds or tailwinds, reflecting an unqualified bullish stance that ended in a -21.7% DISAPPOINTMENT. By the last report in 2026, the narrative had matured to acknowledge serious headwinds—collapsing disbursements, competitive pressure from banks, yield compression, and PFC-REC merger execution risks—while still citing tailwinds such as credit cost reversals, stable spreads, merger-driven scale, and energy storage initiatives, though the persistent negative actual returns across nearly all reports suggest these tailwinds have not translated into stock performance.
Fears that came true
- Competitive pressure from banks on commissioned projects led to disproportionate prepayments, materializing as yield compression to 9.56% and contributing to repeated DISAPPOINTMENT outcomes with deeply negative returns.
- Lower-than-expected loan growth due to higher repayments materialized as the loan book grew only 4% YoY with disbursements falling ~44% YoY, correlating with sustained negative actual returns across multiple reports.
- The risk of delays or hiccups in the PFC-REC merger process remains a live concern given the complex execution and regulatory approval requirements still ahead.
Optimism that failed
- Management’s ~10% loan growth target for FY27 failed to materialize as disbursements fell ~50% QoQ to INR 202bn in Q1FY27.
- The strong sanctioned-but-undisbursed pipeline did not translate into actual disbursements, with Q1FY27 disbursements down sharply both QoQ and YoY.
- The expectation that ECL-driven provision reversals from 18 discom rating upgrades and a benign credit cycle would drive sustained outperformance failed, as the stock posted negative returns in nearly every reporting period despite these tailwinds.
Broker Timeline
18 broker calls · 2024-06-23 to 2026-08-10
Copyright © 2023 SAS Data Analytics Pvt. Ltd. All rights reserved.