OPTIEMUS
Equity Metrics
September 24, 2026
Optiemus Infracom Limited
Telecom - Equipment & Accessories
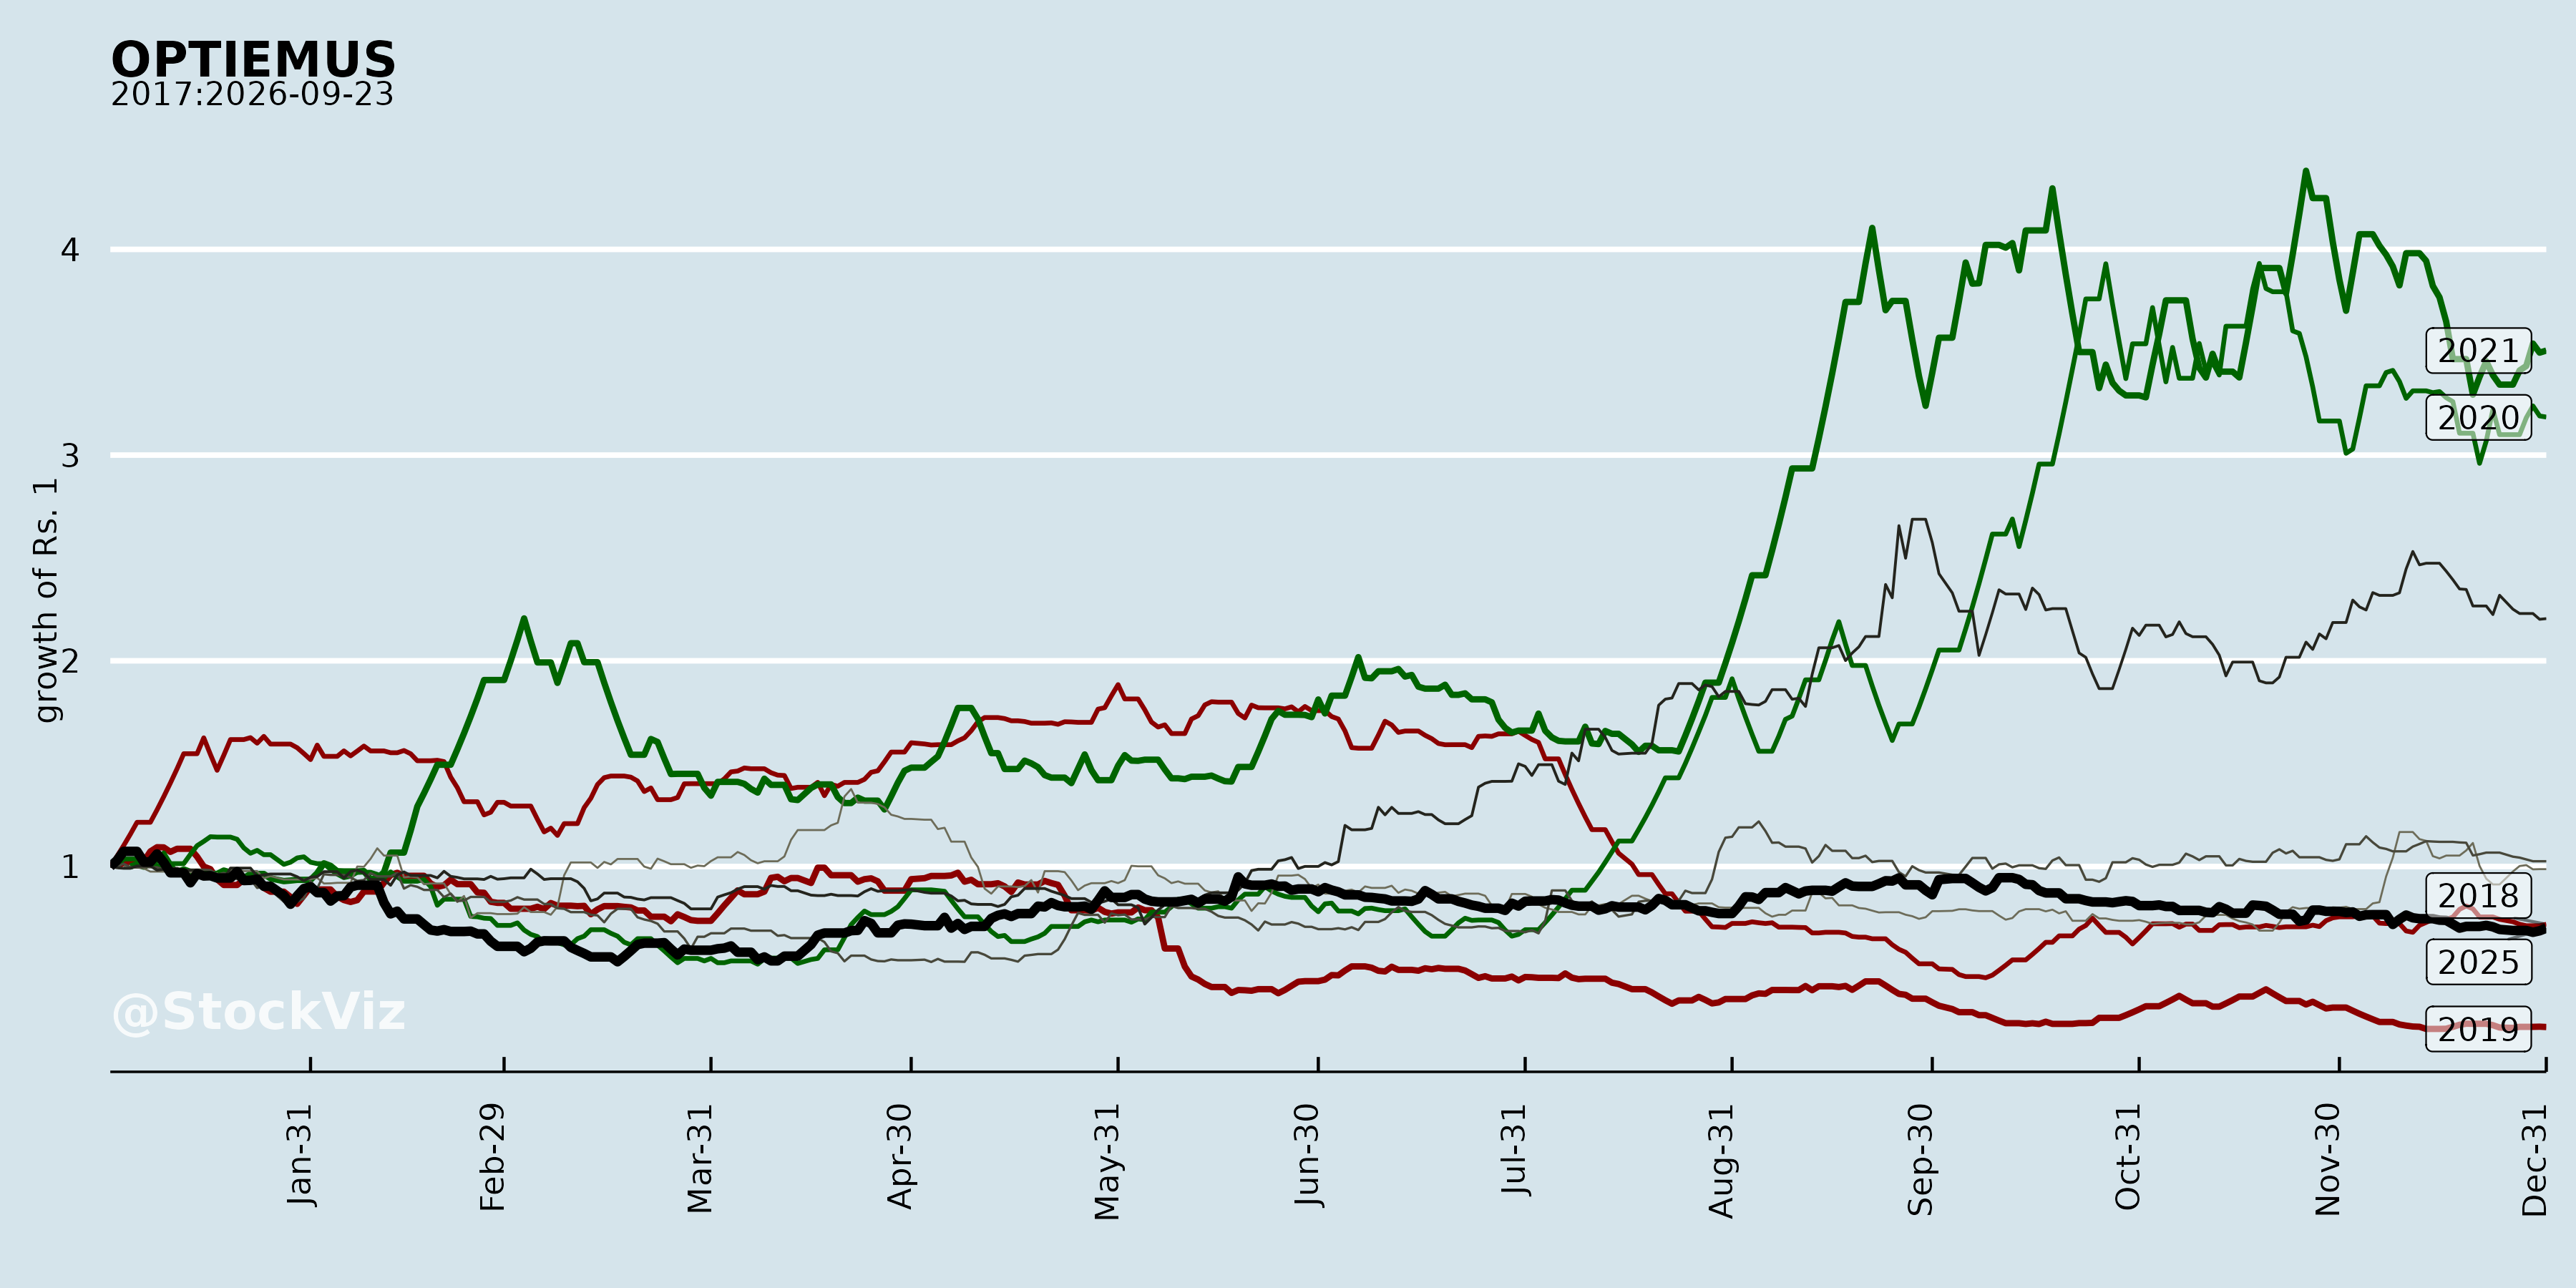
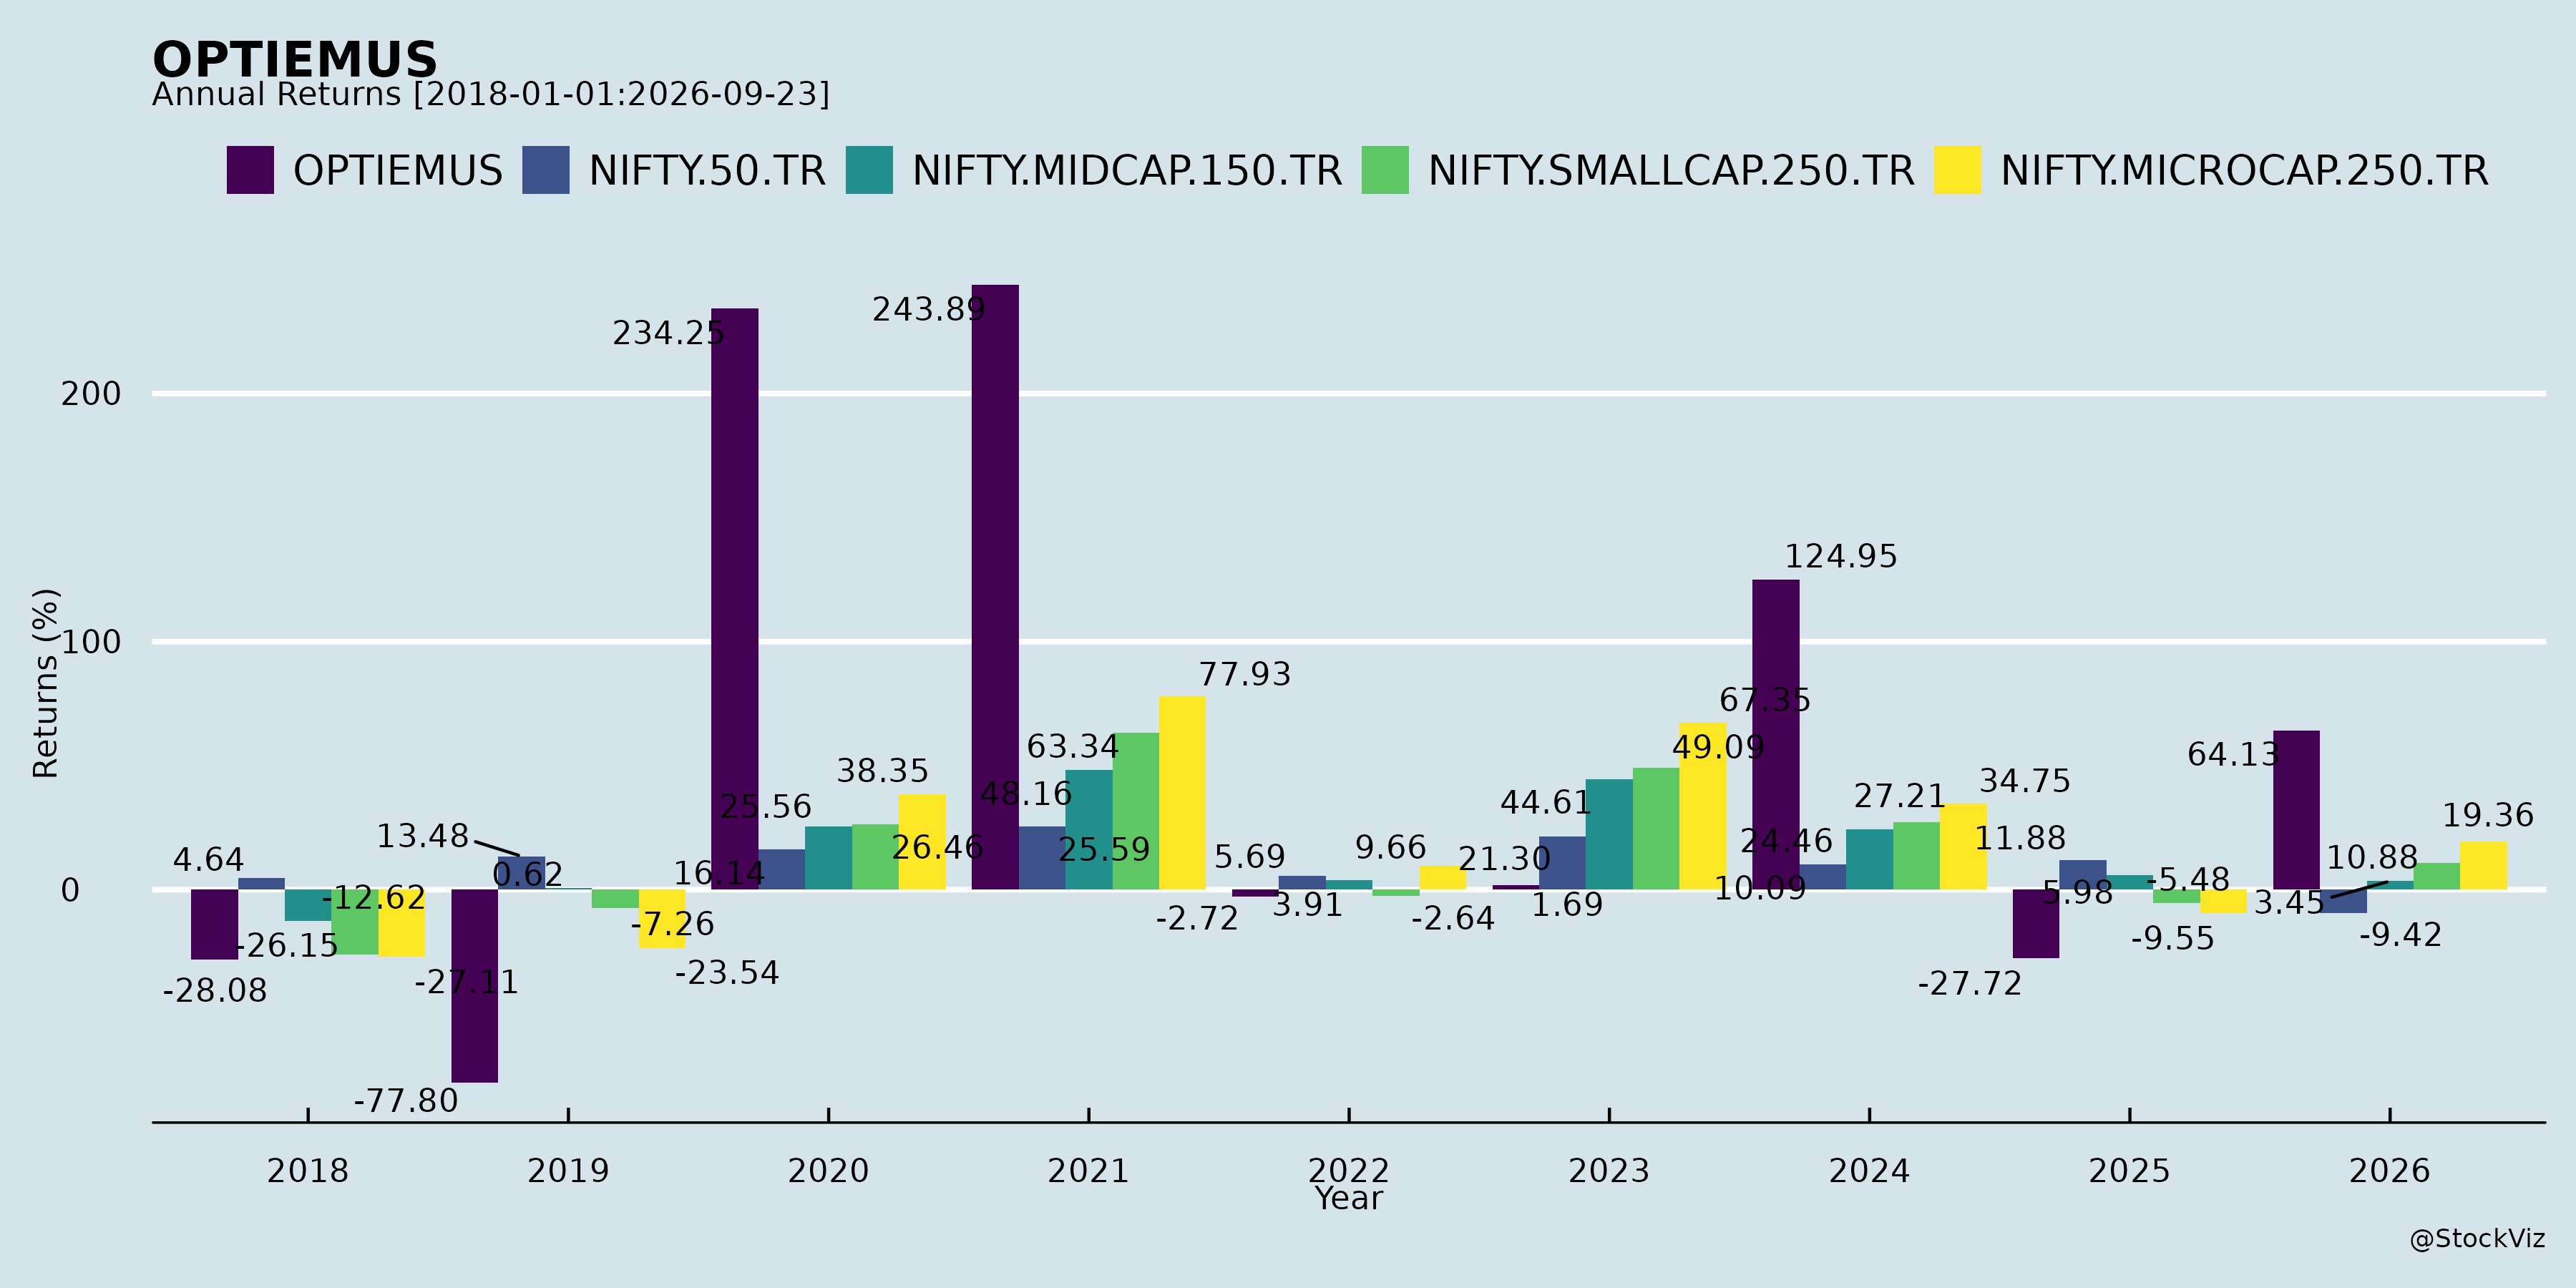
Annual Returns
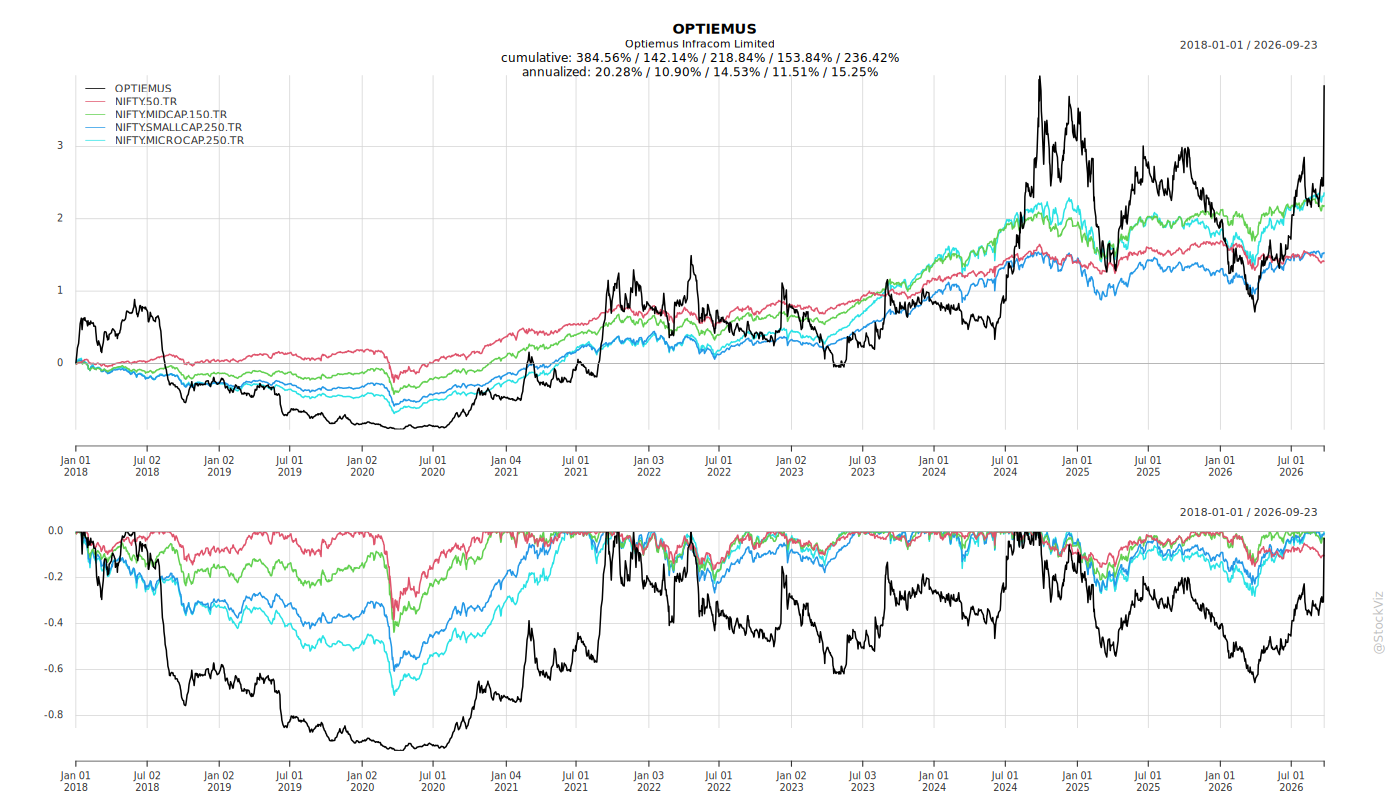
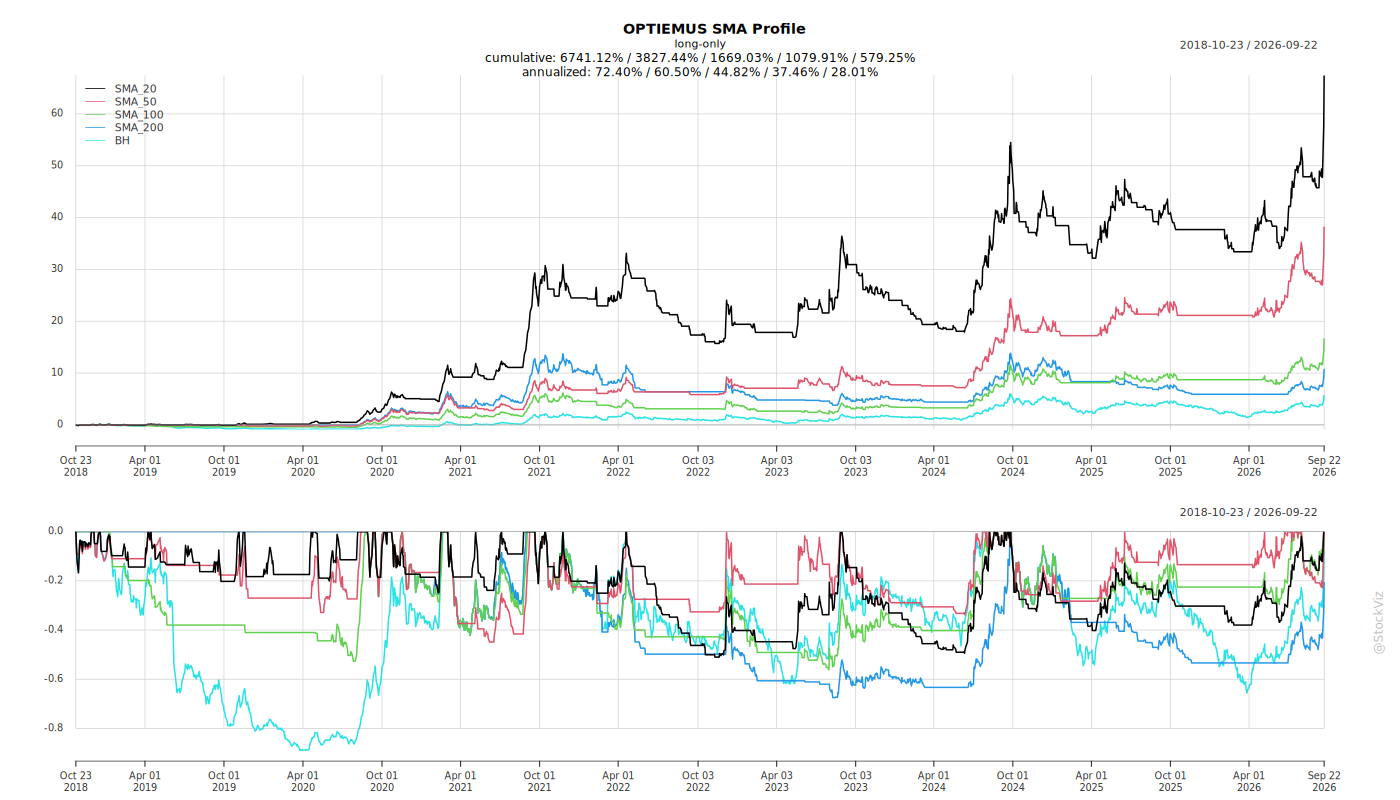
Cumulative Returns and Drawdowns
Fundamentals
Ownership
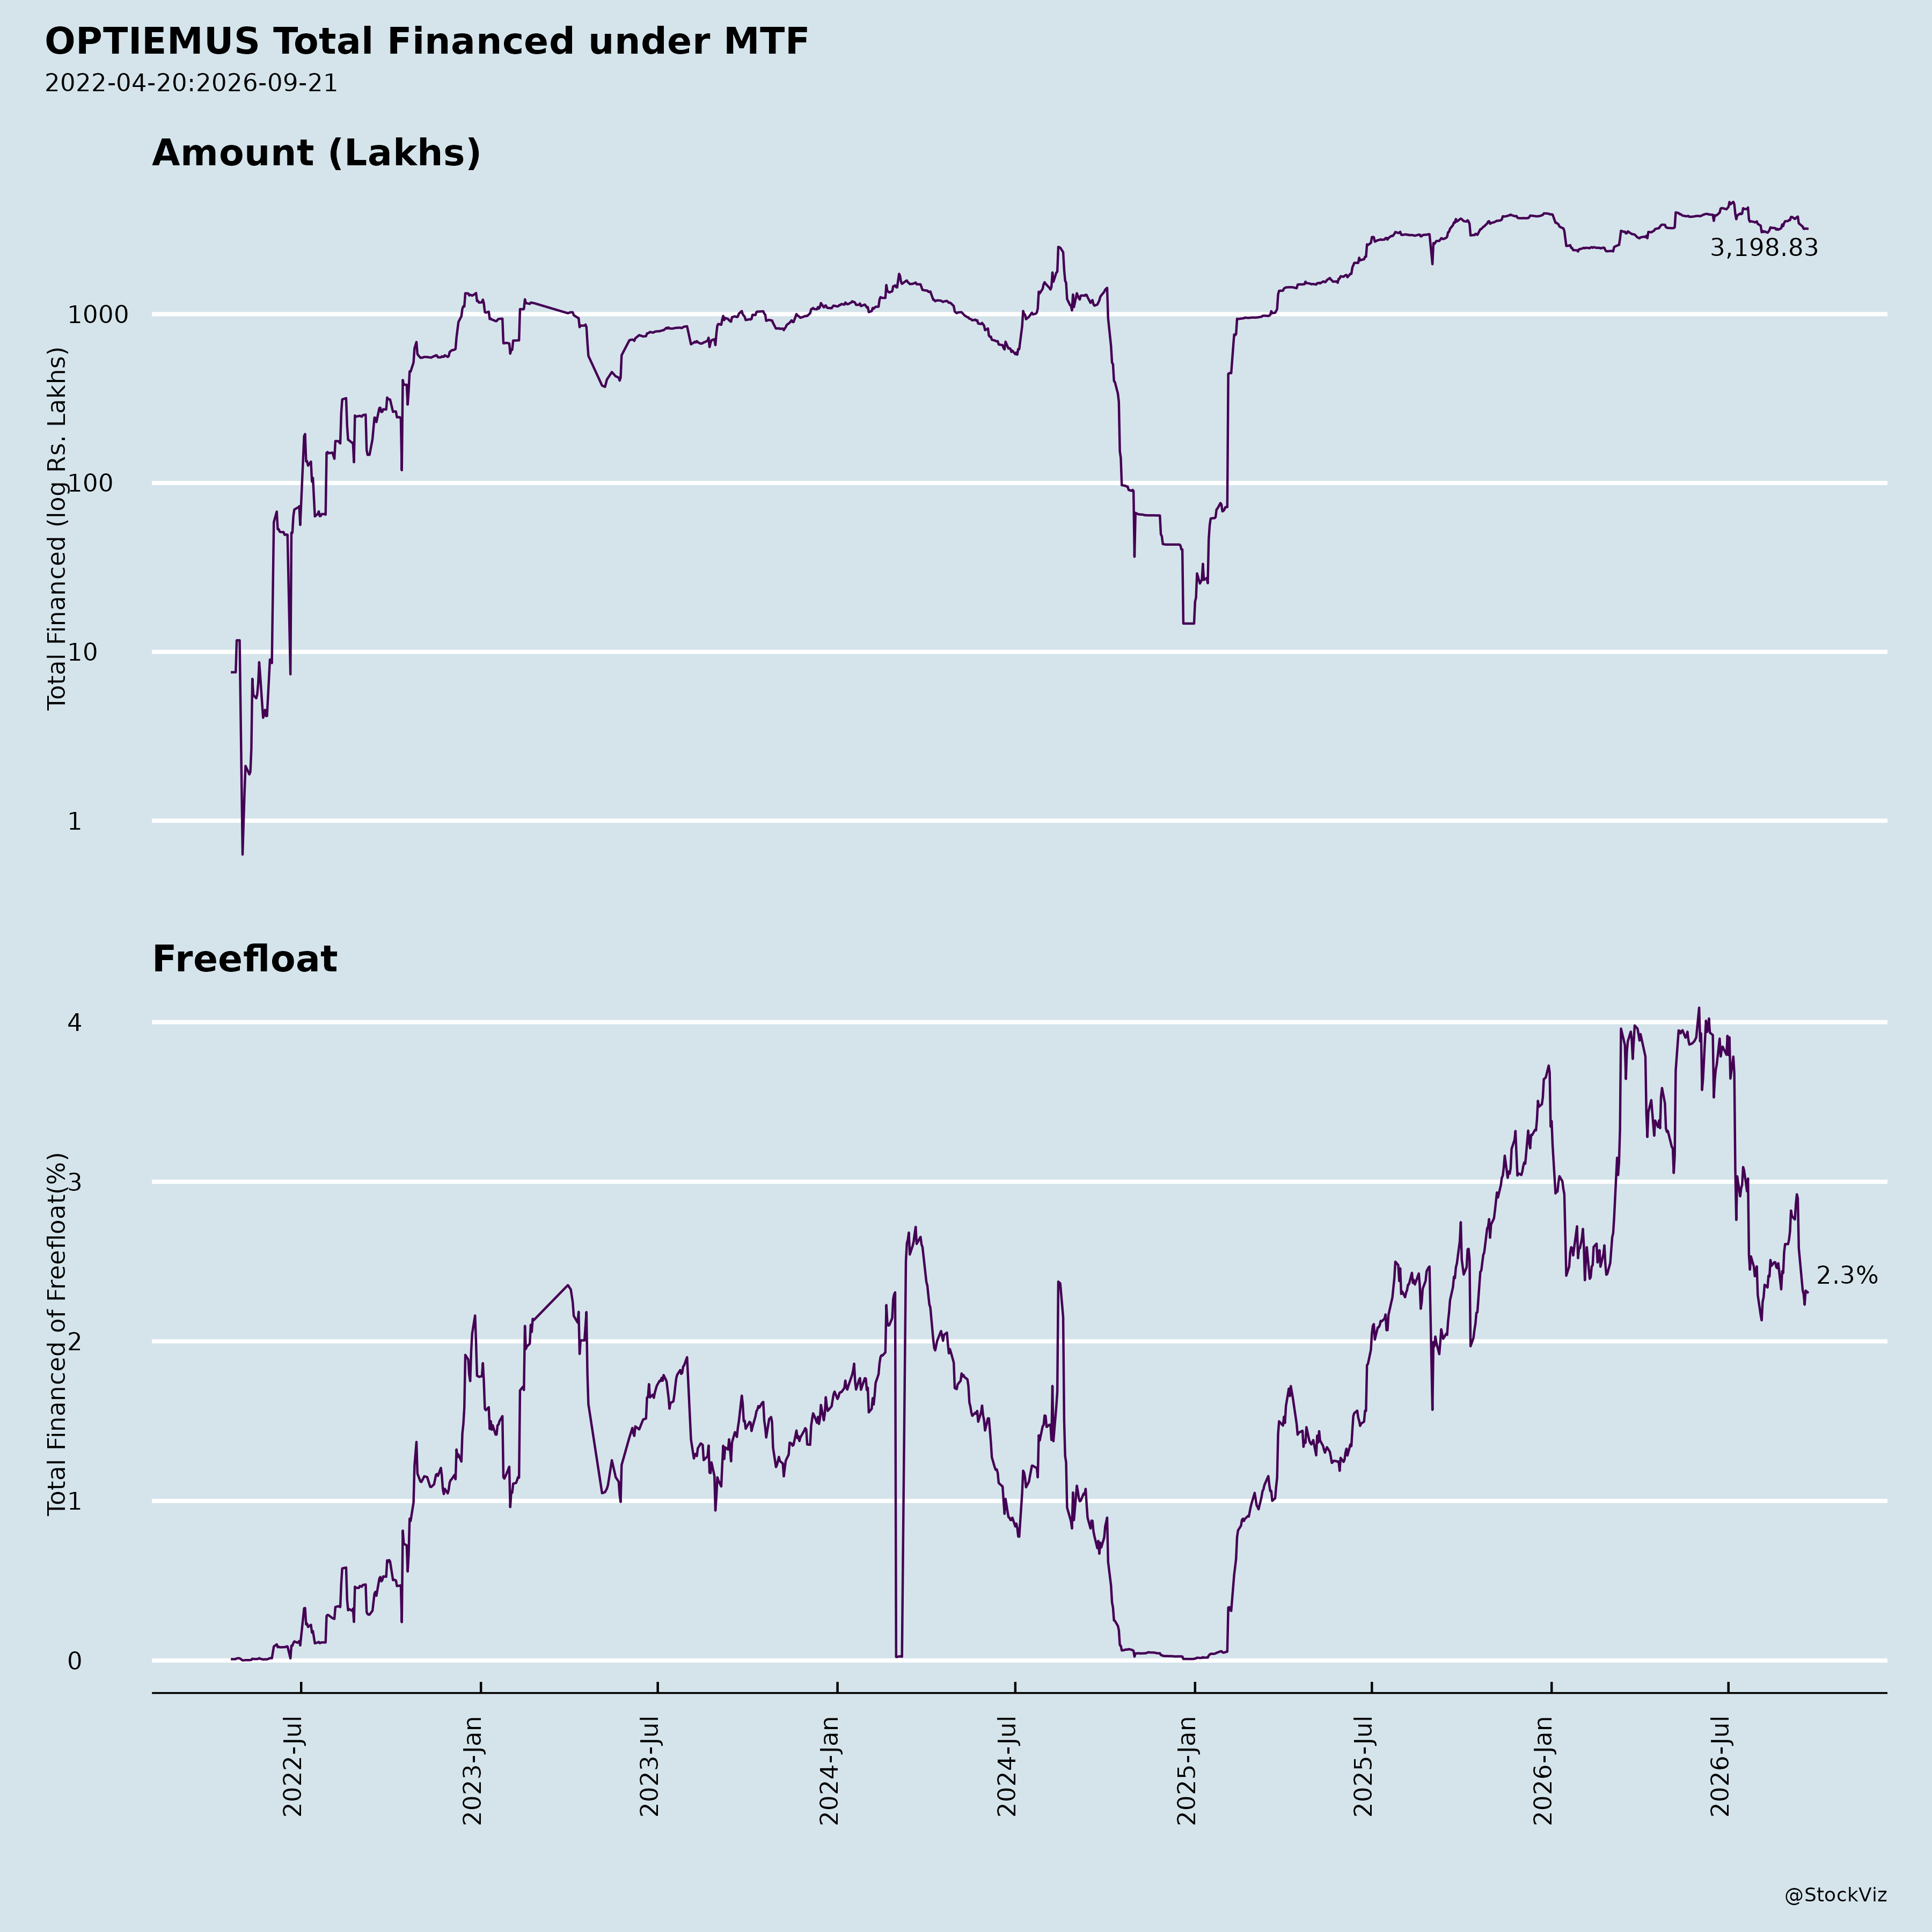
Margined
AI Summary
asof: 2026-09-17
Optiemus Infracom — Recent Corporate Announcements
1. Headwinds and Challenges
- Margin compression from revenue mix. Q1 FY27 EBITDA margin stood at 4.68% versus 6.80% in Q1 FY26, a decline of about 2.1 percentage points. Management attributes this to a revenue shift toward high-volume mobile manufacturing. PBT margin fell from 4.3% to 3.2% and PAT margin from 3.3% to 2.4% over the same comparison.
- Incubation drag from new businesses. Drones and Cover Glass incubation expenses reduced Q1 FY27 PAT by ₹245 Lakhs; adjusting for these, core operating PAT was ₹2,363 Lakhs.
- Macro and operating risks cited in the annual report. Persistent inflationary pressures, geopolitical uncertainties, evolving trade dynamics, global supply chain disruptions, foreign exchange volatility, pricing pressures, technology obsolescence, intense market competition, cybersecurity threats, and dependence on global supply chains.
- Prior portfolio volatility. The EMS narrative notes that the company exited volatile local-brand contracts and onboarded premium customers to ensure consistent volumes, indicating past exposure to unstable contract relationships.
- No dividend. The Board did not recommend any dividend for FY 2025-26.
2. Tailwinds and Growth Prospects
- AI+ smartphone EMS partnership. Billing began March/April 2026 and scaled through Q1 FY27, contributing ~₹500+ crore in the quarter — described as the largest single-program ramp in OEL’s history. Unit 3 (Noida) came online in Q1 FY27, adding 6 million units of installed annual capacity.
- MPMS / PLI 2.0. Cabinet-approved ₹62,500 crore scheme for FY27–FY31, with up to 9.5% stackable incentives for Indian brands (5.0% base domestic manufacturing + 1.5% component localization + 3.0% design & R&D for Indian brands only). Management expects this to support margin expansion and position the company to onboard other Indian brands.
- Screen protector B2C category. Mandatory BIS certification expected by January 2027, with an announcement anticipated within 30 days of the Q1 FY27 presentation. The category is framed around ~60 crore smartphone users in India, ~2 pieces/year average usage, a ~₹20,000 crore import-only market, and ~₹40,000 crore potential by 2030. Dual brands planned: RhinoTech (premium) and OptiGuard (economy), with in-house dual-stage chemical tempering at Noida.
- Second B2C category launch in Q3 FY27, aligned with the stated vision of building a proprietary B2C product portfolio.
- Cover glass JV with Corning International (70:30). India’s first finished cover-glass plant in Tamil Nadu; OEM audits and on-site visits by leading global brands underway, with customer onboarding expected over the next 3–4 quarters (Q4 FY27 / Q1 FY28).
- Drones (Optiemus Unmanned Systems, wholly-owned subsidiary). High-altitude defense systems and precision-agriculture platforms; service contracts being pitched to state governments and defense bodies. Positioned as medium-term option value not factored into guidance.
- Quectel partnership (announced June 29, 2026). OEL will locally manufacture Quectel’s automotive, 5G, 4G, Cat-1 and other cellular modules at its Noida facilities, supporting IoT, automotive, telecom, energy, smart mobility, industrial automation, telematics, and smart infrastructure applications.
- Policy and demand environment. Make in India, Digital India, PLI schemes, Semicon India Programme, rising smartphone penetration, 5G rollout, AI-enabled devices, IoT, cloud computing, and growing demand for domestic electronics manufacturing.
- Capital support for drones. Acquisition of 56,00,000 equity shares in Optiemus Unmanned Systems Private Limited for ₹5,60,00,000 in cash, to fund working capital, business operations, and capital expenditure, and to strengthen the balance sheet and diversify risk. Expected completion within 90 days.
- Other income. Q1 FY27 other income of ₹1,091 Lakhs, primarily from government policy incentives, expected to be recurring.
3. Key Risks
- Margin trajectory. The shift toward high-volume mobile manufacturing has already compressed margins; management expects improvement in coming quarters, but this depends on execution and mix.
- Dependence on a small number of large programs and partners. The AI+ smartphone ramp is a major revenue contributor; the loss or slowdown of such programs would be material.
- Execution and timing risk on new categories. Screen protector launch is tied to BIS notification timing; the second B2C category is scheduled for Q3 FY27; cover glass customer onboarding is expected over 3–4 quarters. Slippage in any of these would affect the outlook.
- Regulatory and policy dependence. PLI 2.0 incentives, BIS implementation, and government policy incentives (which drive other income) are external factors.
- Global supply chain and FX exposure, as flagged in the annual report.
- Competition and technology obsolescence in electronics manufacturing and consumer categories.
- Cybersecurity threats, as flagged in the annual report.
- Incubation losses from Drones and Cover Glass continuing to weigh on reported PAT until those businesses scale.
4. Management Guidance vs. Observed Performance
- Q1 FY27 beat guidance. Management states that “disciplined execution in Q1 FY27 drove performance ahead of guidance,” with the AI+ EMS partnership contributing ~₹500+ crore in the quarter.
- FY27 revenue target: ~₹3,600 crore, described as roughly 2x FY26 revenue, anchored by strong Q1 execution and forward visibility. This excludes contributions from screen protectors, cover glass, and the new B2C product launch.
- FY28–FY29: 30%+ annual revenue growth, with a stated target of ₹6,000 crore revenue by FY29. This outlook also excludes screen protector, cover glass, and the Q3 FY27 B2C launch, which management describes as upside.
- Observed Q1 FY27 consolidated performance (₹ in
Lakhs):
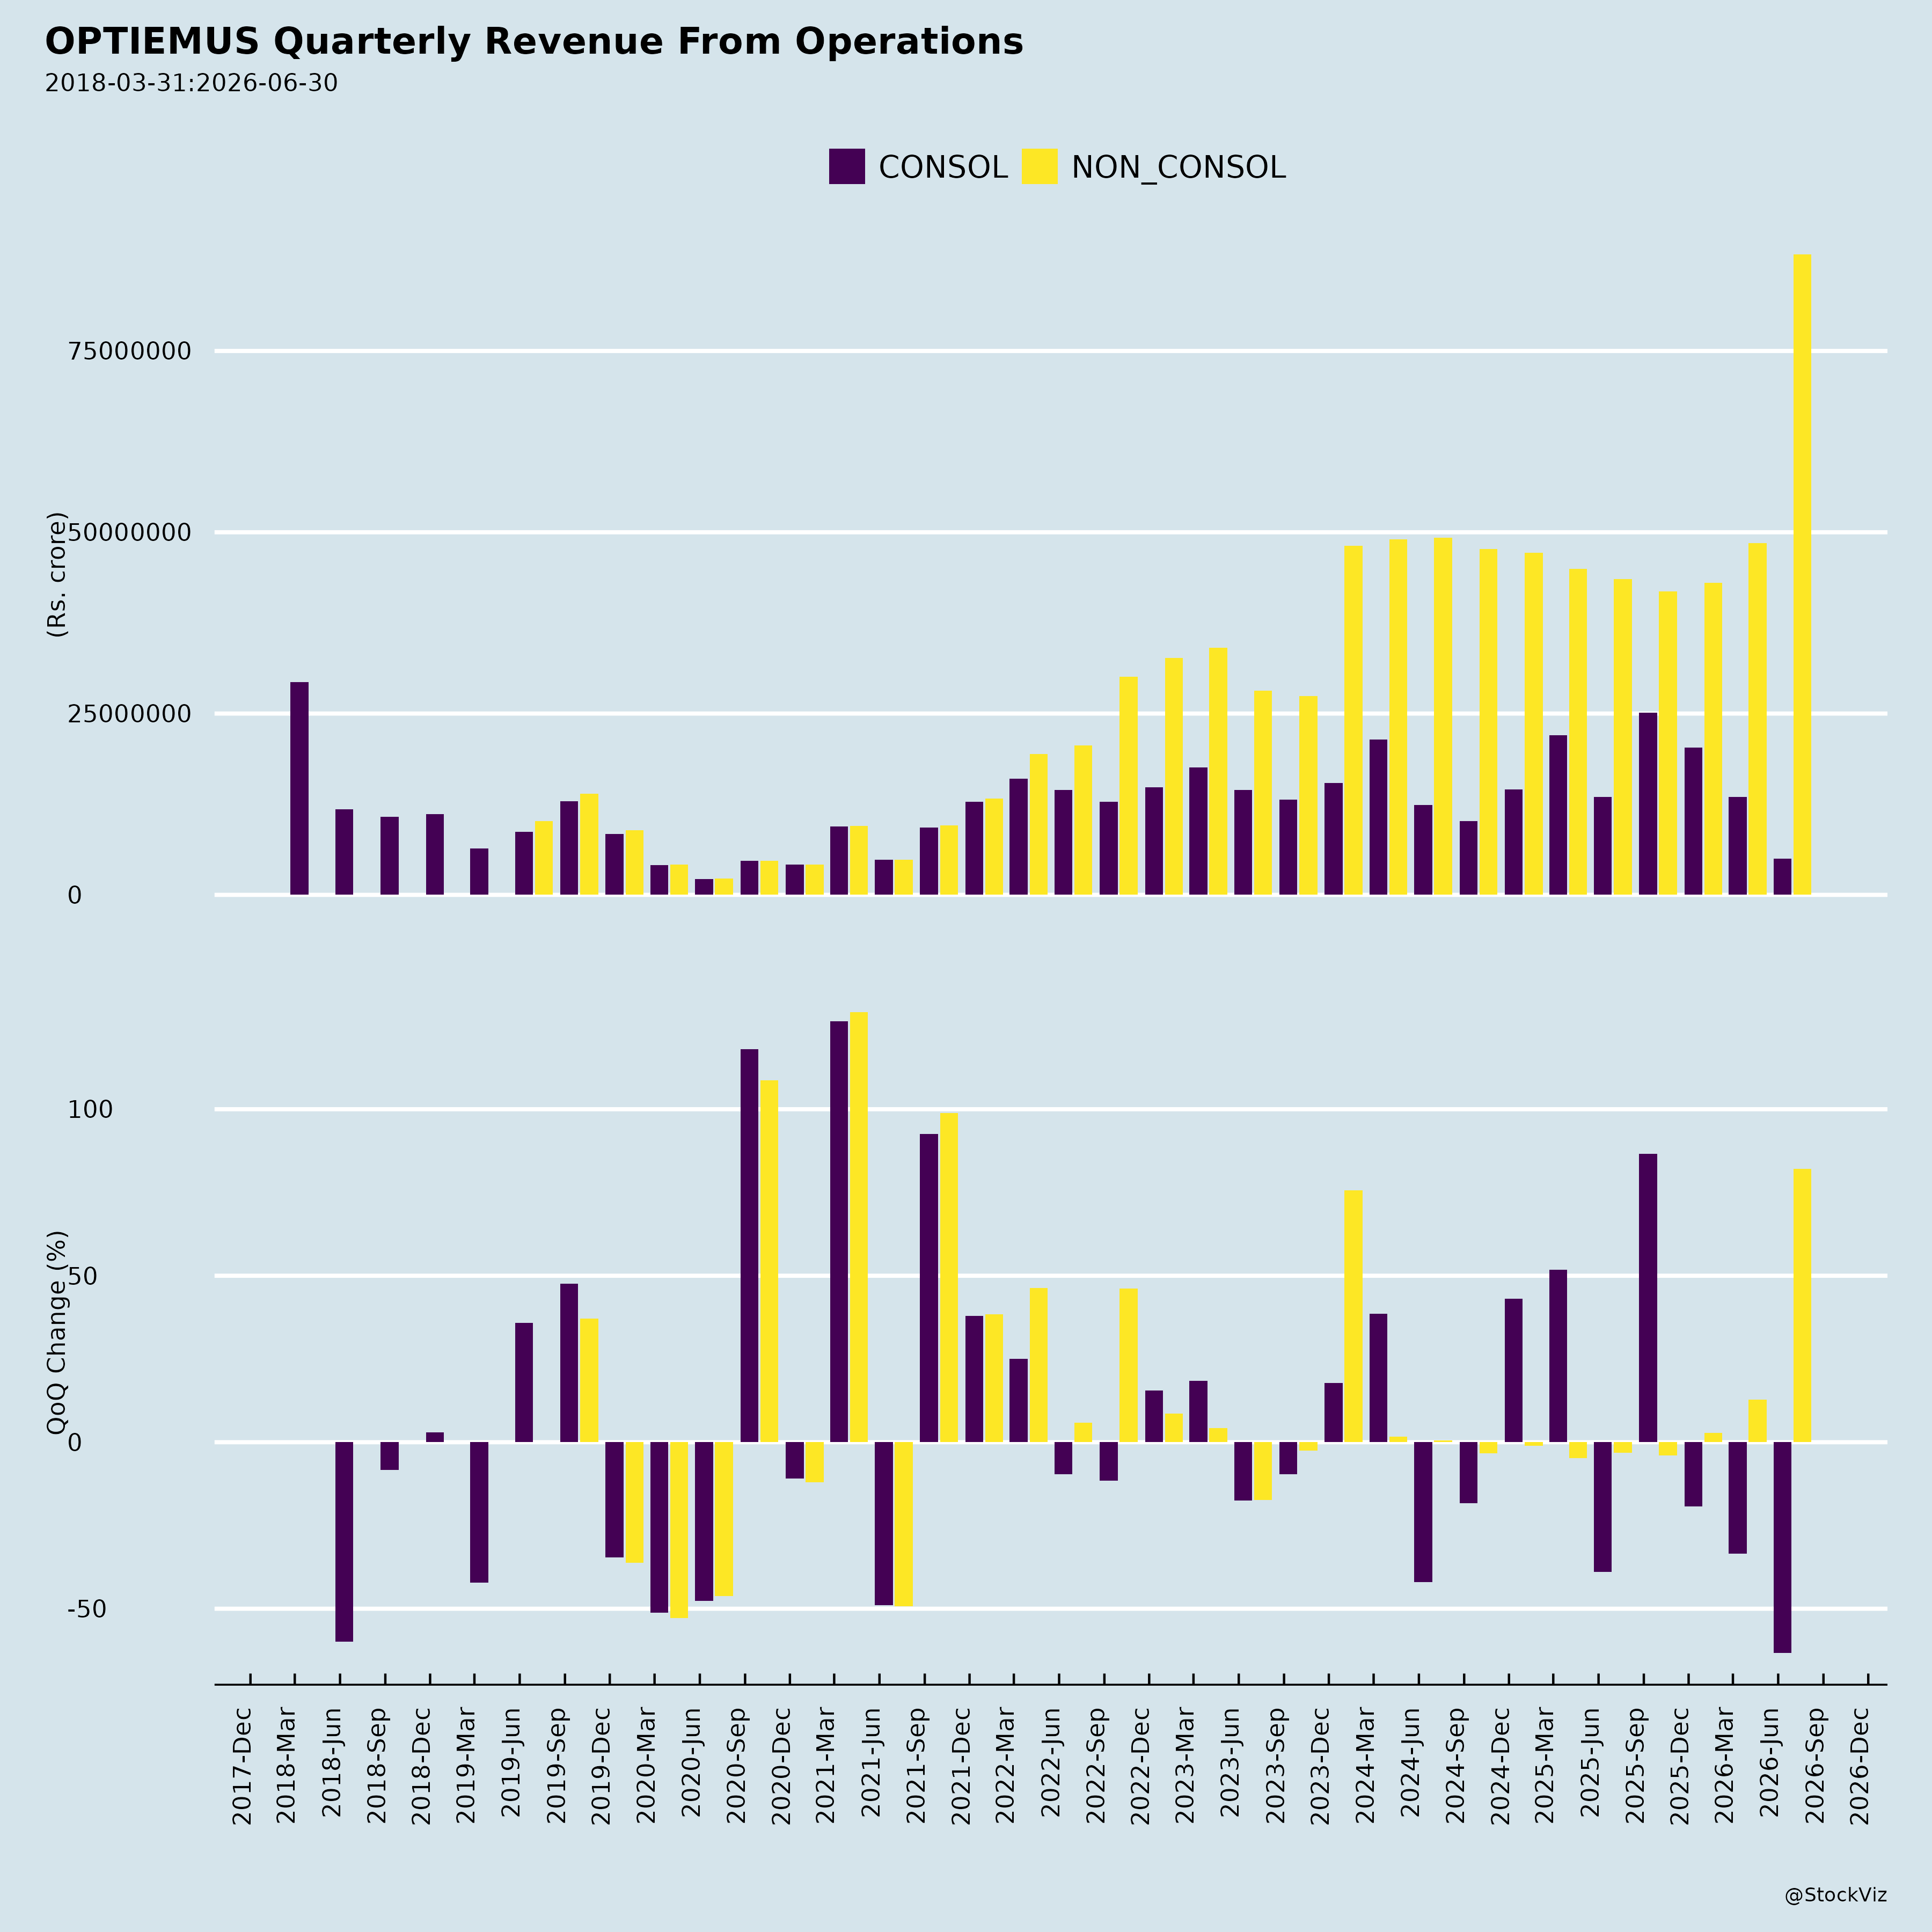
- Operating Revenue: 88,299 vs 43,535 in Q1 FY26 (+103% YoY)
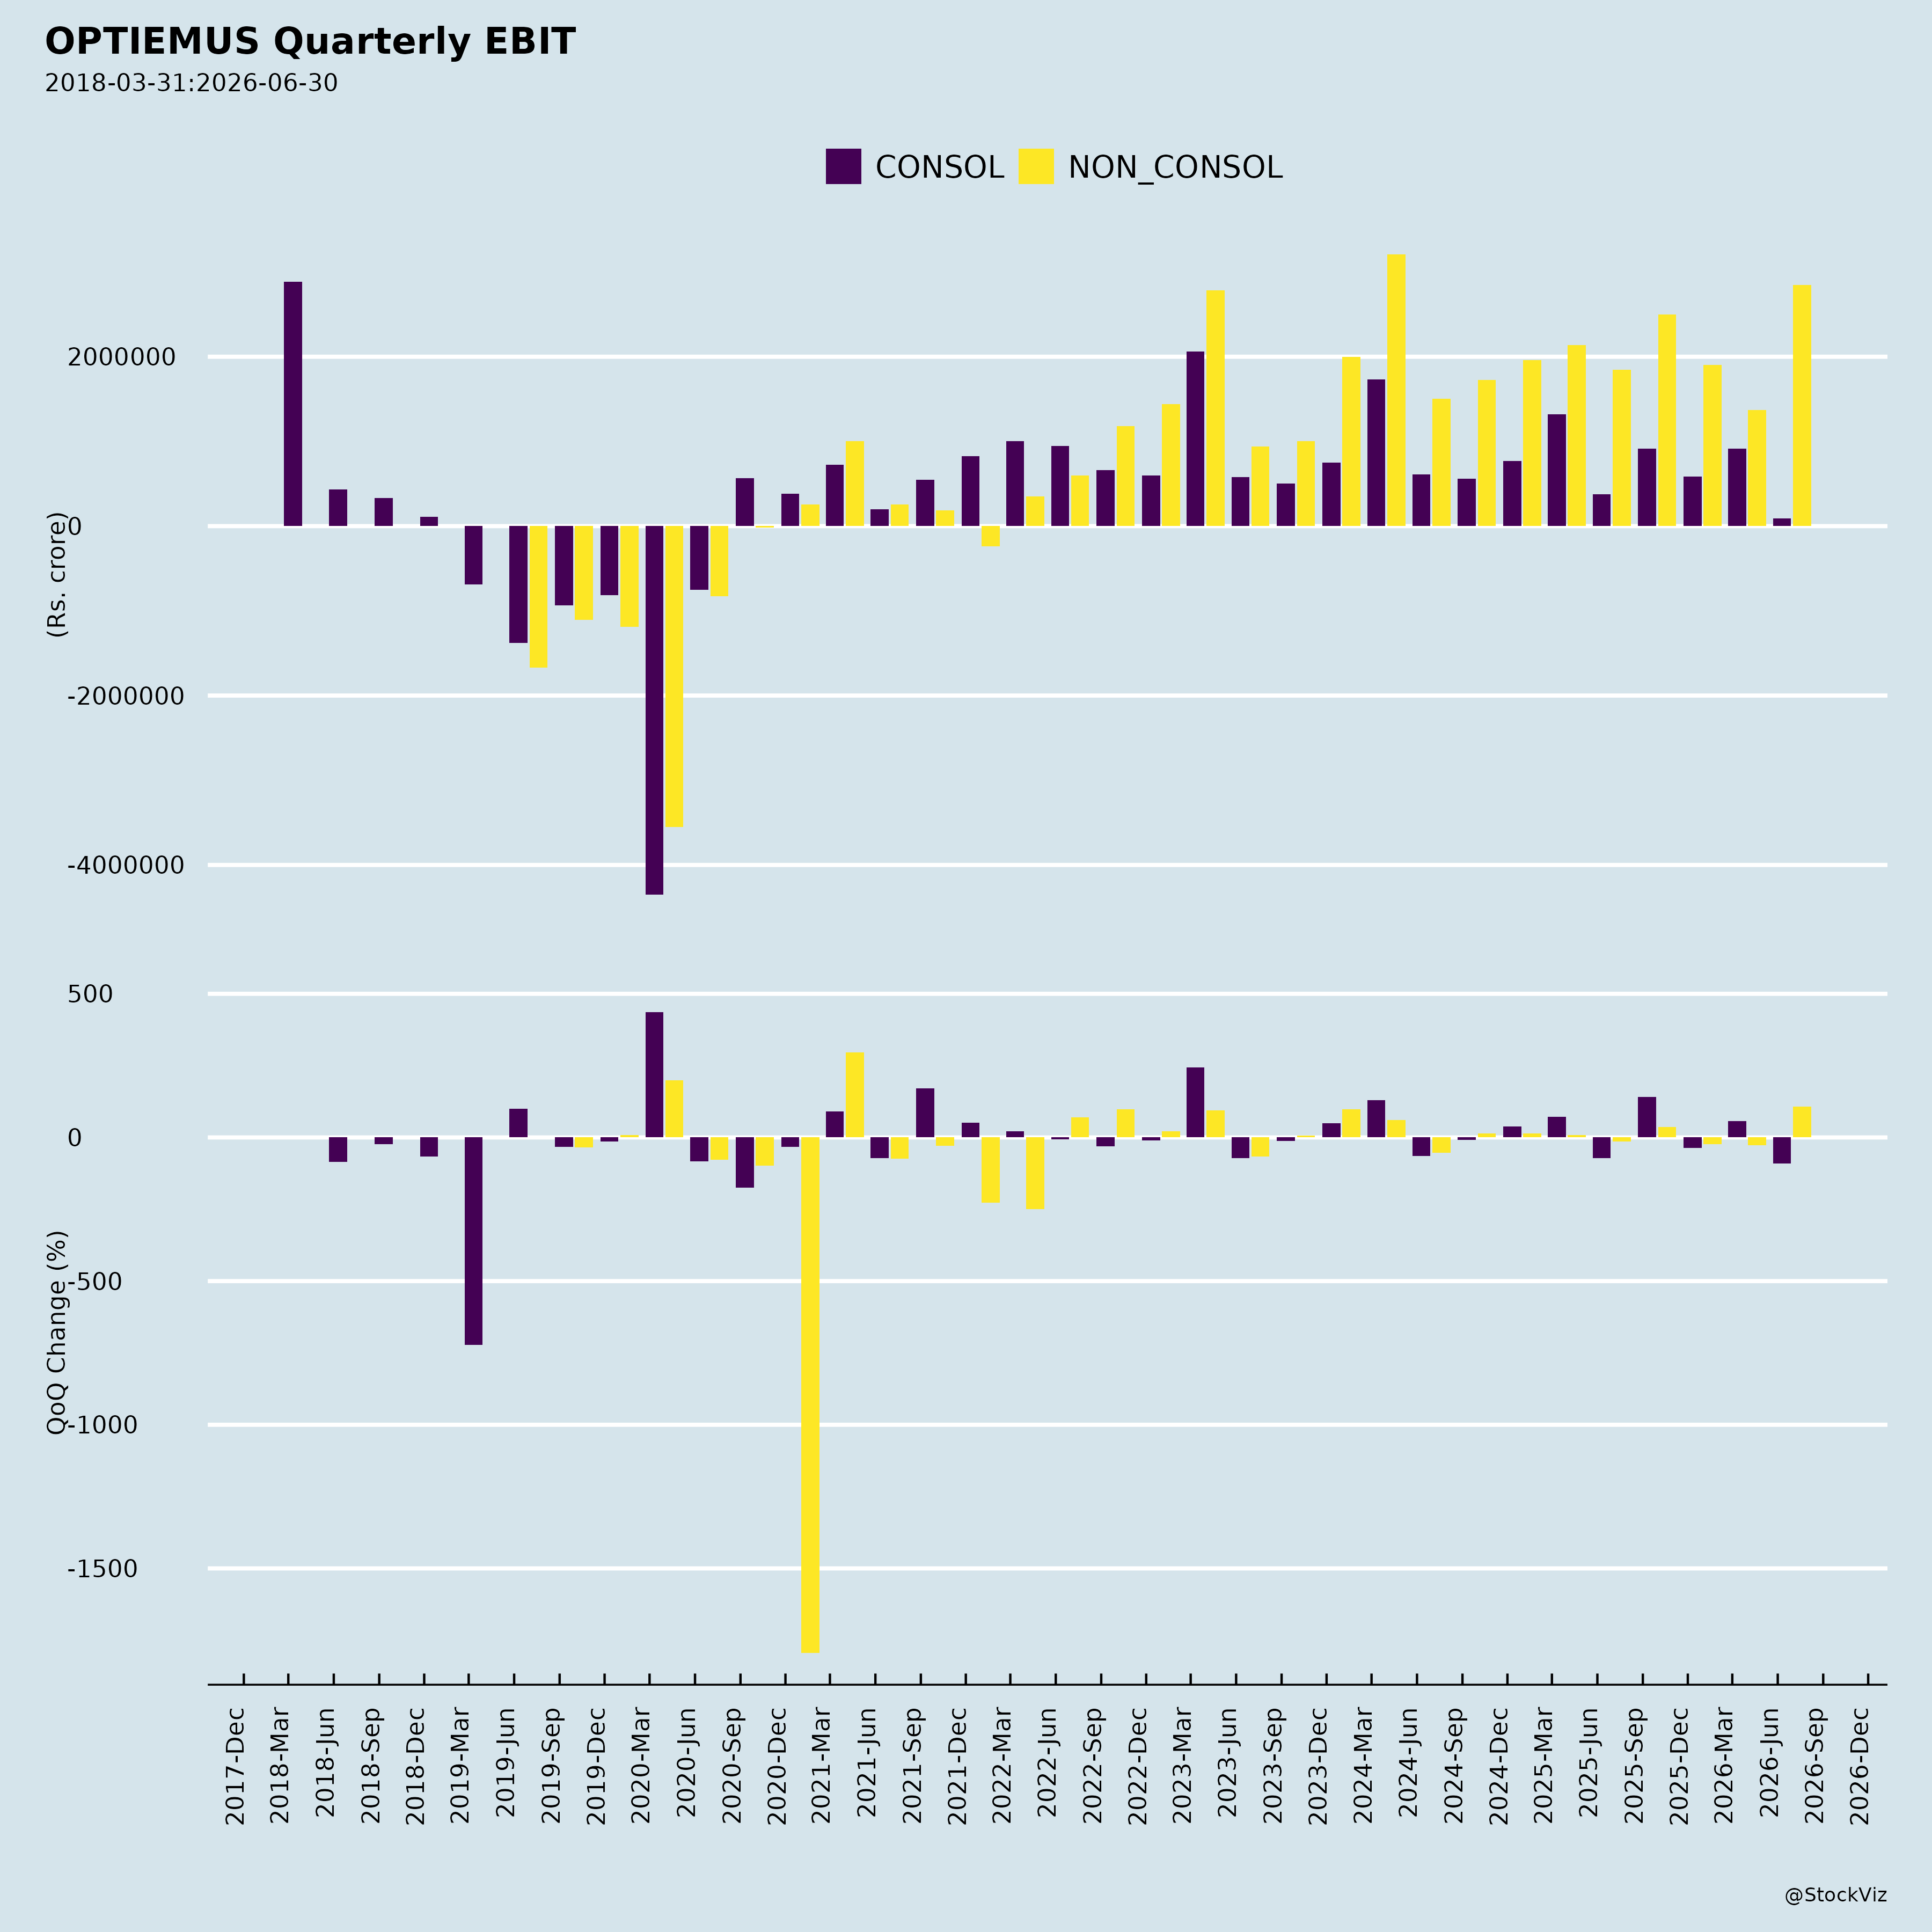
- EBITDA: 4,132 vs 2,958 (+40% YoY)
- PBT: 2,824 vs 1,884 (+50% YoY)
- PAT: 2,118 vs 1,453 (+46% YoY)
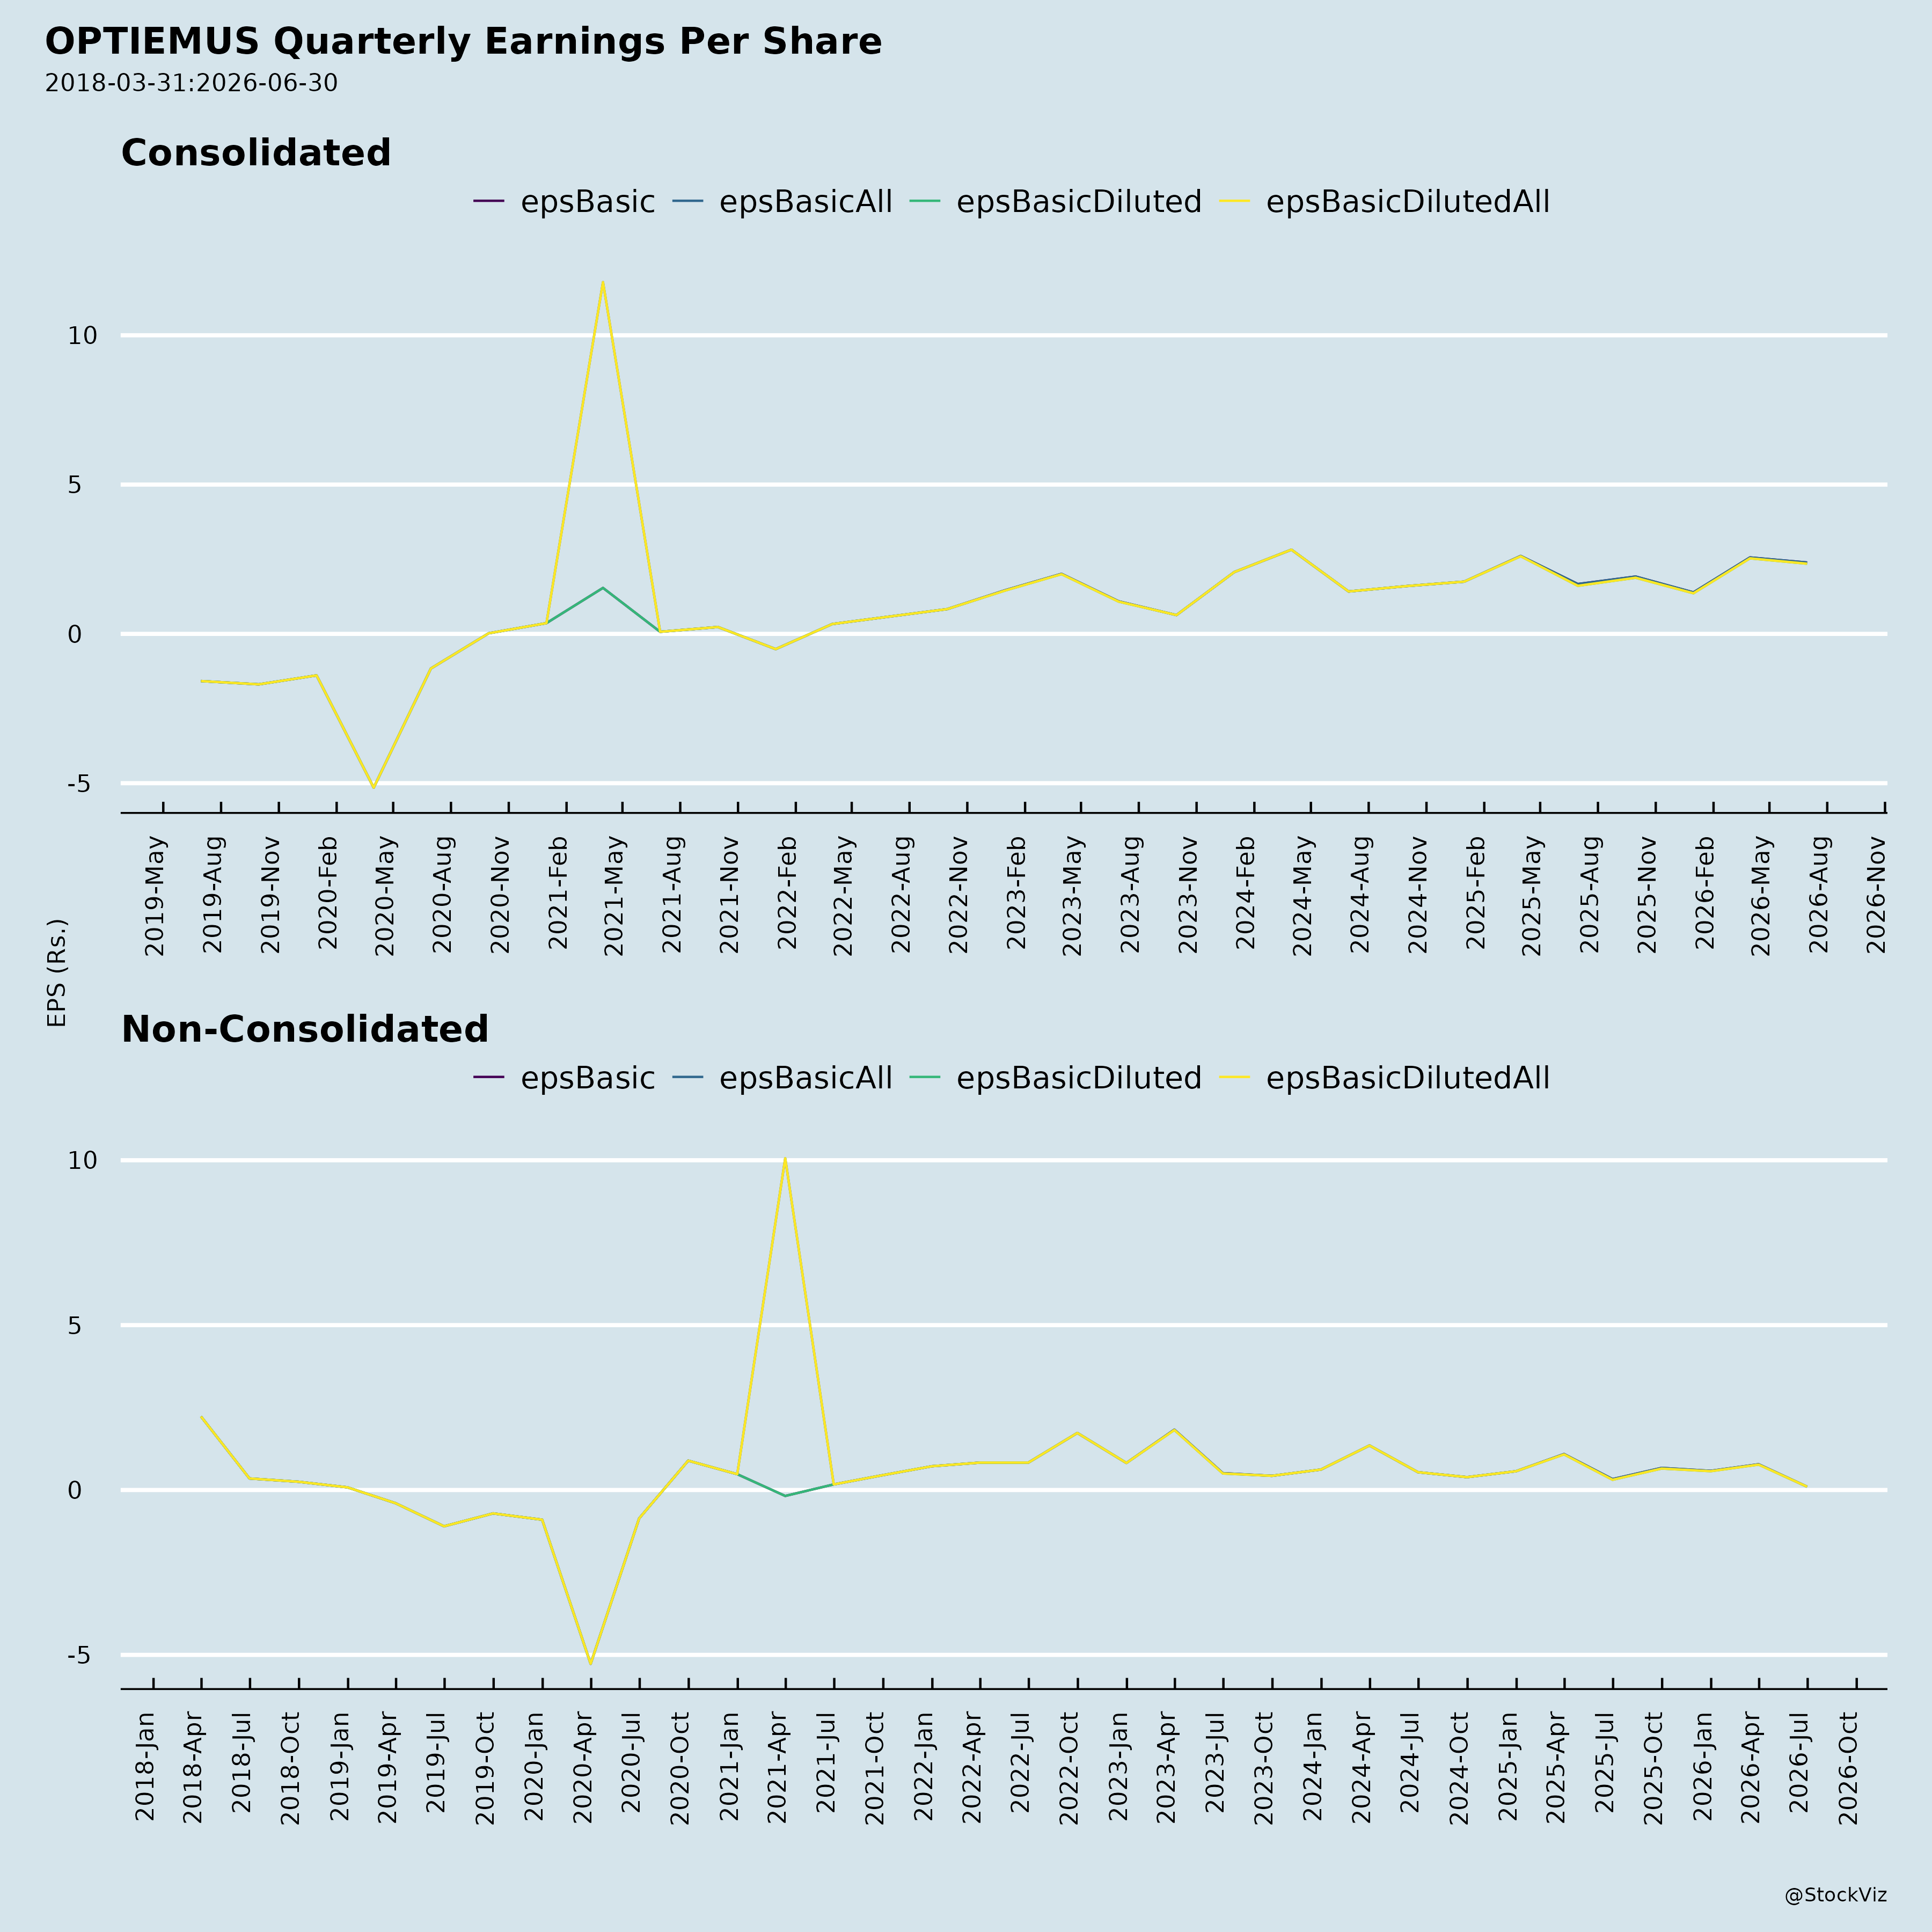
- Diluted EPS: 2.35 vs 1.61 (+46% YoY)
- EBITDA %: 4.7% vs 6.8%; PBT %: 3.2% vs 4.3%; PAT %: 2.4% vs 3.3%
- FY26 consolidated actuals (₹ in Lakhs): Operating Revenue 1,76,862; EBITDA 12,365 (7.0%); PBT 9,067 (5.1%); PAT 6,601 (3.7%); Diluted EPS 7.39.
- Margin guidance. Management expects EBITDA margins to improve in coming quarters following the commissioning of Noida Unit 3 (6 million units annual installed capacity added in Q1 FY27).
- Annual report outlook. The company aims to continue strengthening core wholesale trading operations, support manufacturing of subsidiaries, and pursue opportunities through the right products, partnerships, and capabilities to build sustainable businesses and create long-term value for stakeholders.
- AGM and governance dates. The 33rd AGM is scheduled for Monday, September 28, 2026, at 11:30 A.M. IST via VC/OAVM. Remote e-voting runs from Friday, September 25, 2026, 09:00 A.M. to Sunday, September 27, 2026, 05:00 P.M., with a cut-off date of Monday, September 21, 2026. The Register of Members and Share Transfer Books will be closed from Tuesday, September 22, 2026, to Monday, September 28, 2026. Mr. Gauri Shankar and Mr. Rakesh Kumar Srivastava were re-appointed as Independent Directors for a second five-year term from April 01, 2027, to March 31, 2032.
Copyright © 2023 SAS Data Analytics Pvt. Ltd. All rights reserved.