ONGC
Equity Metrics
November 18, 2026
Oil & Natural Gas Corporation Limited
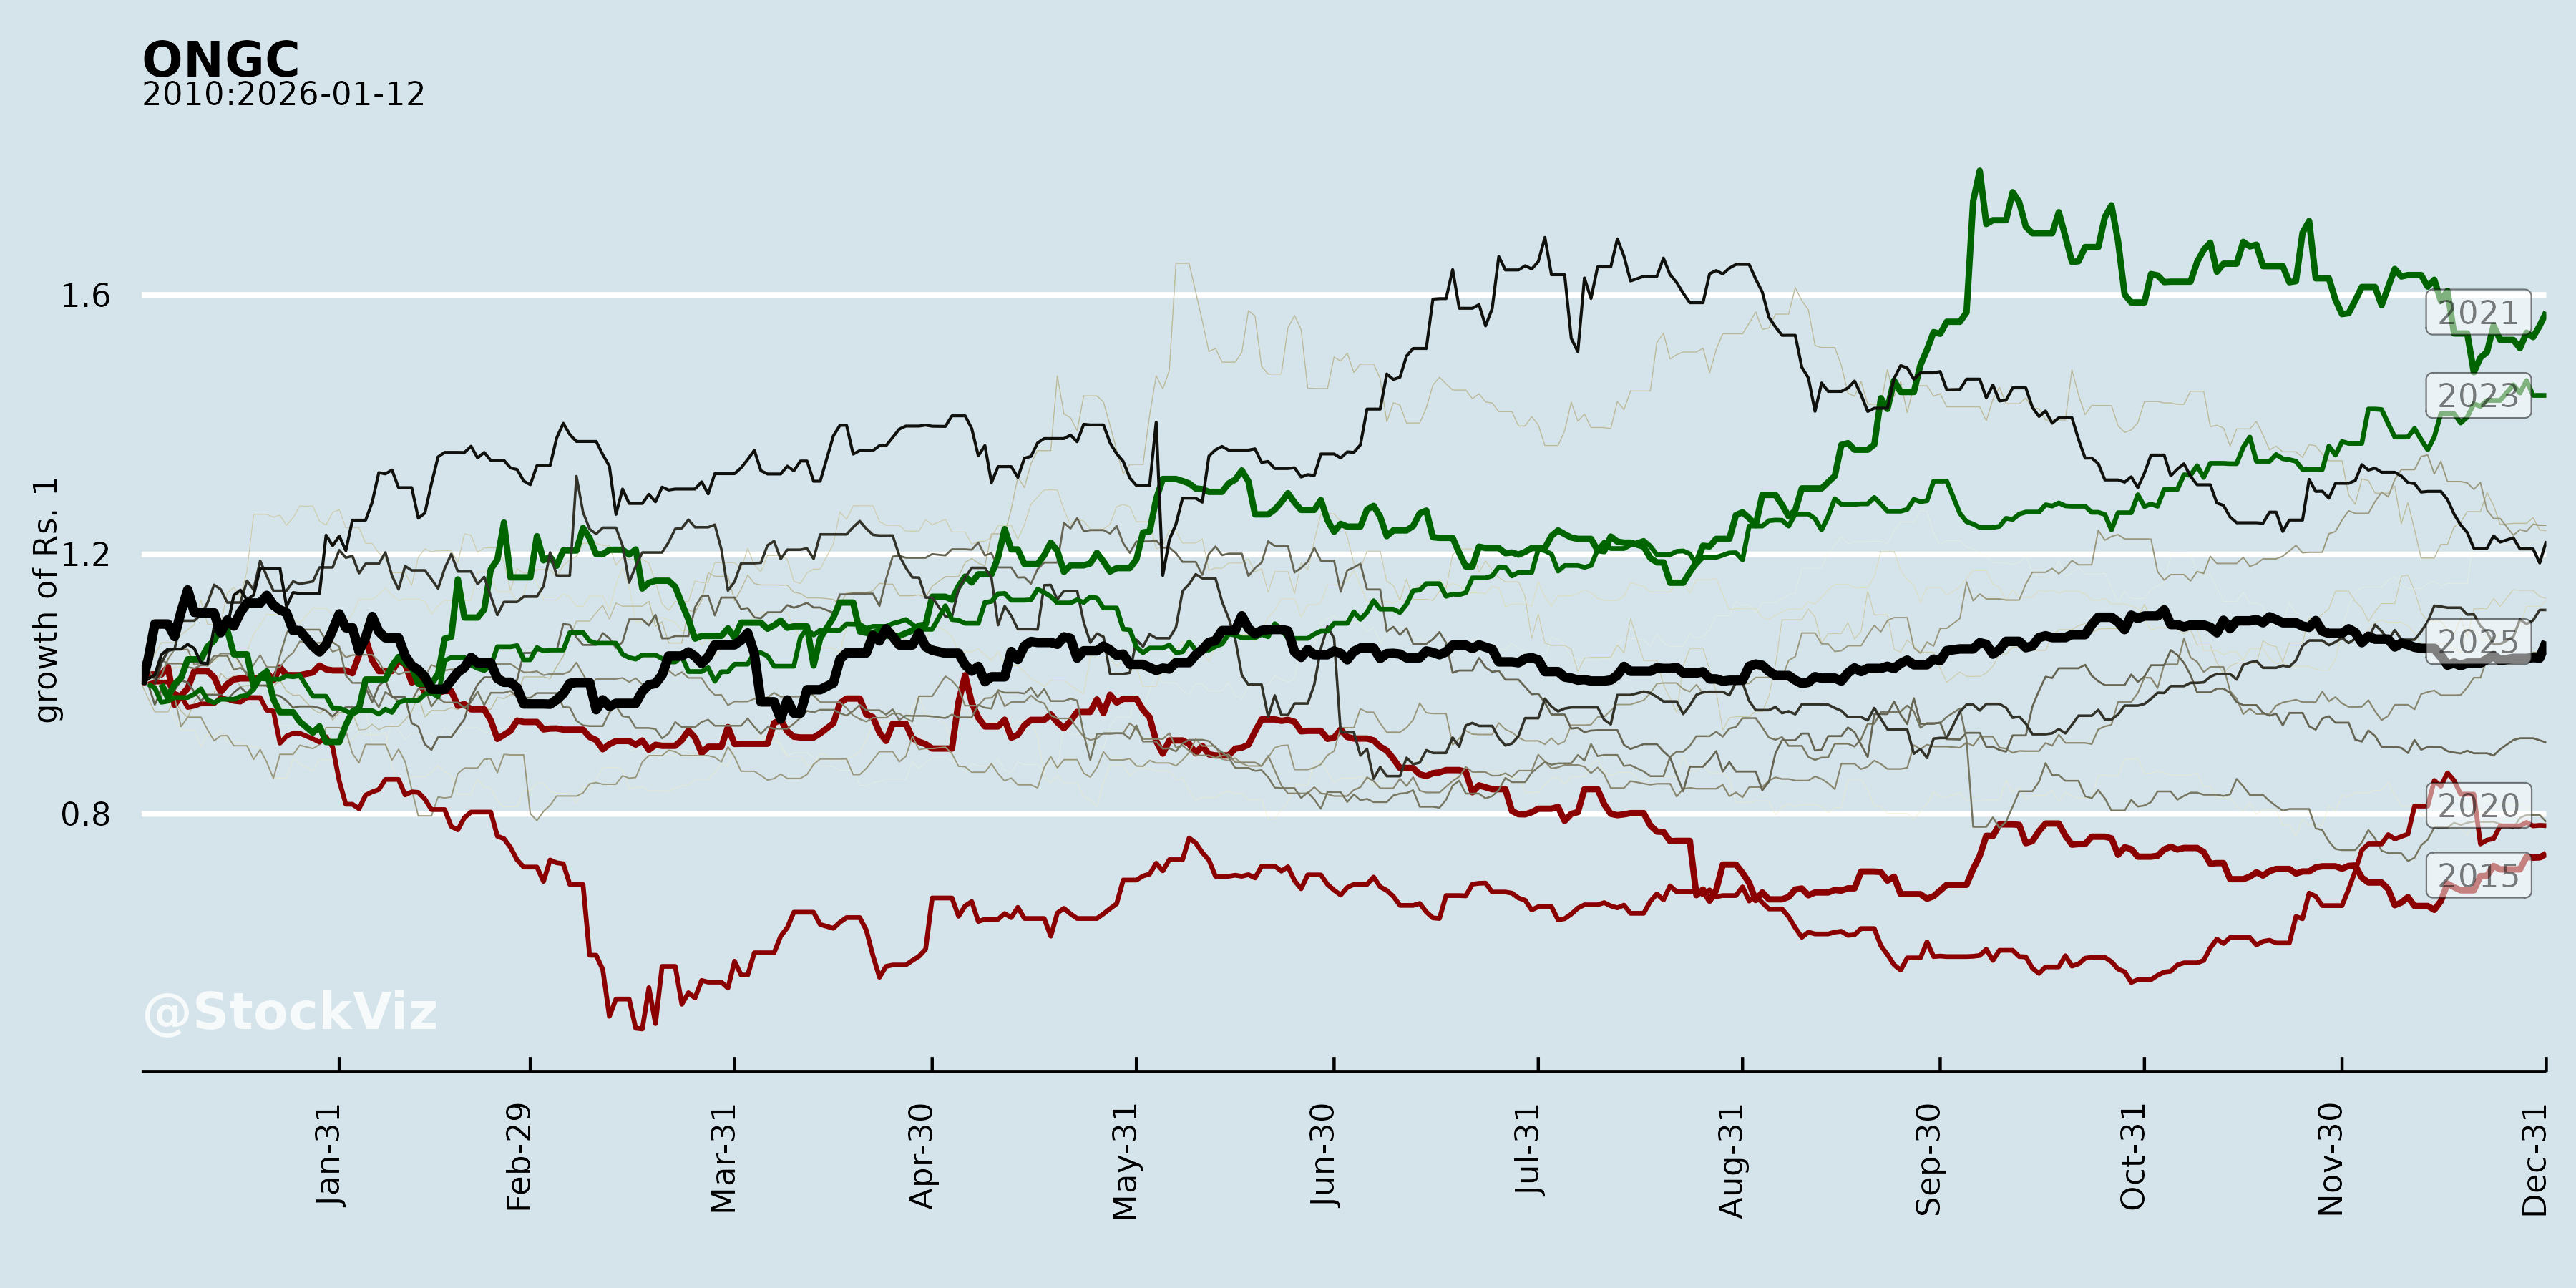
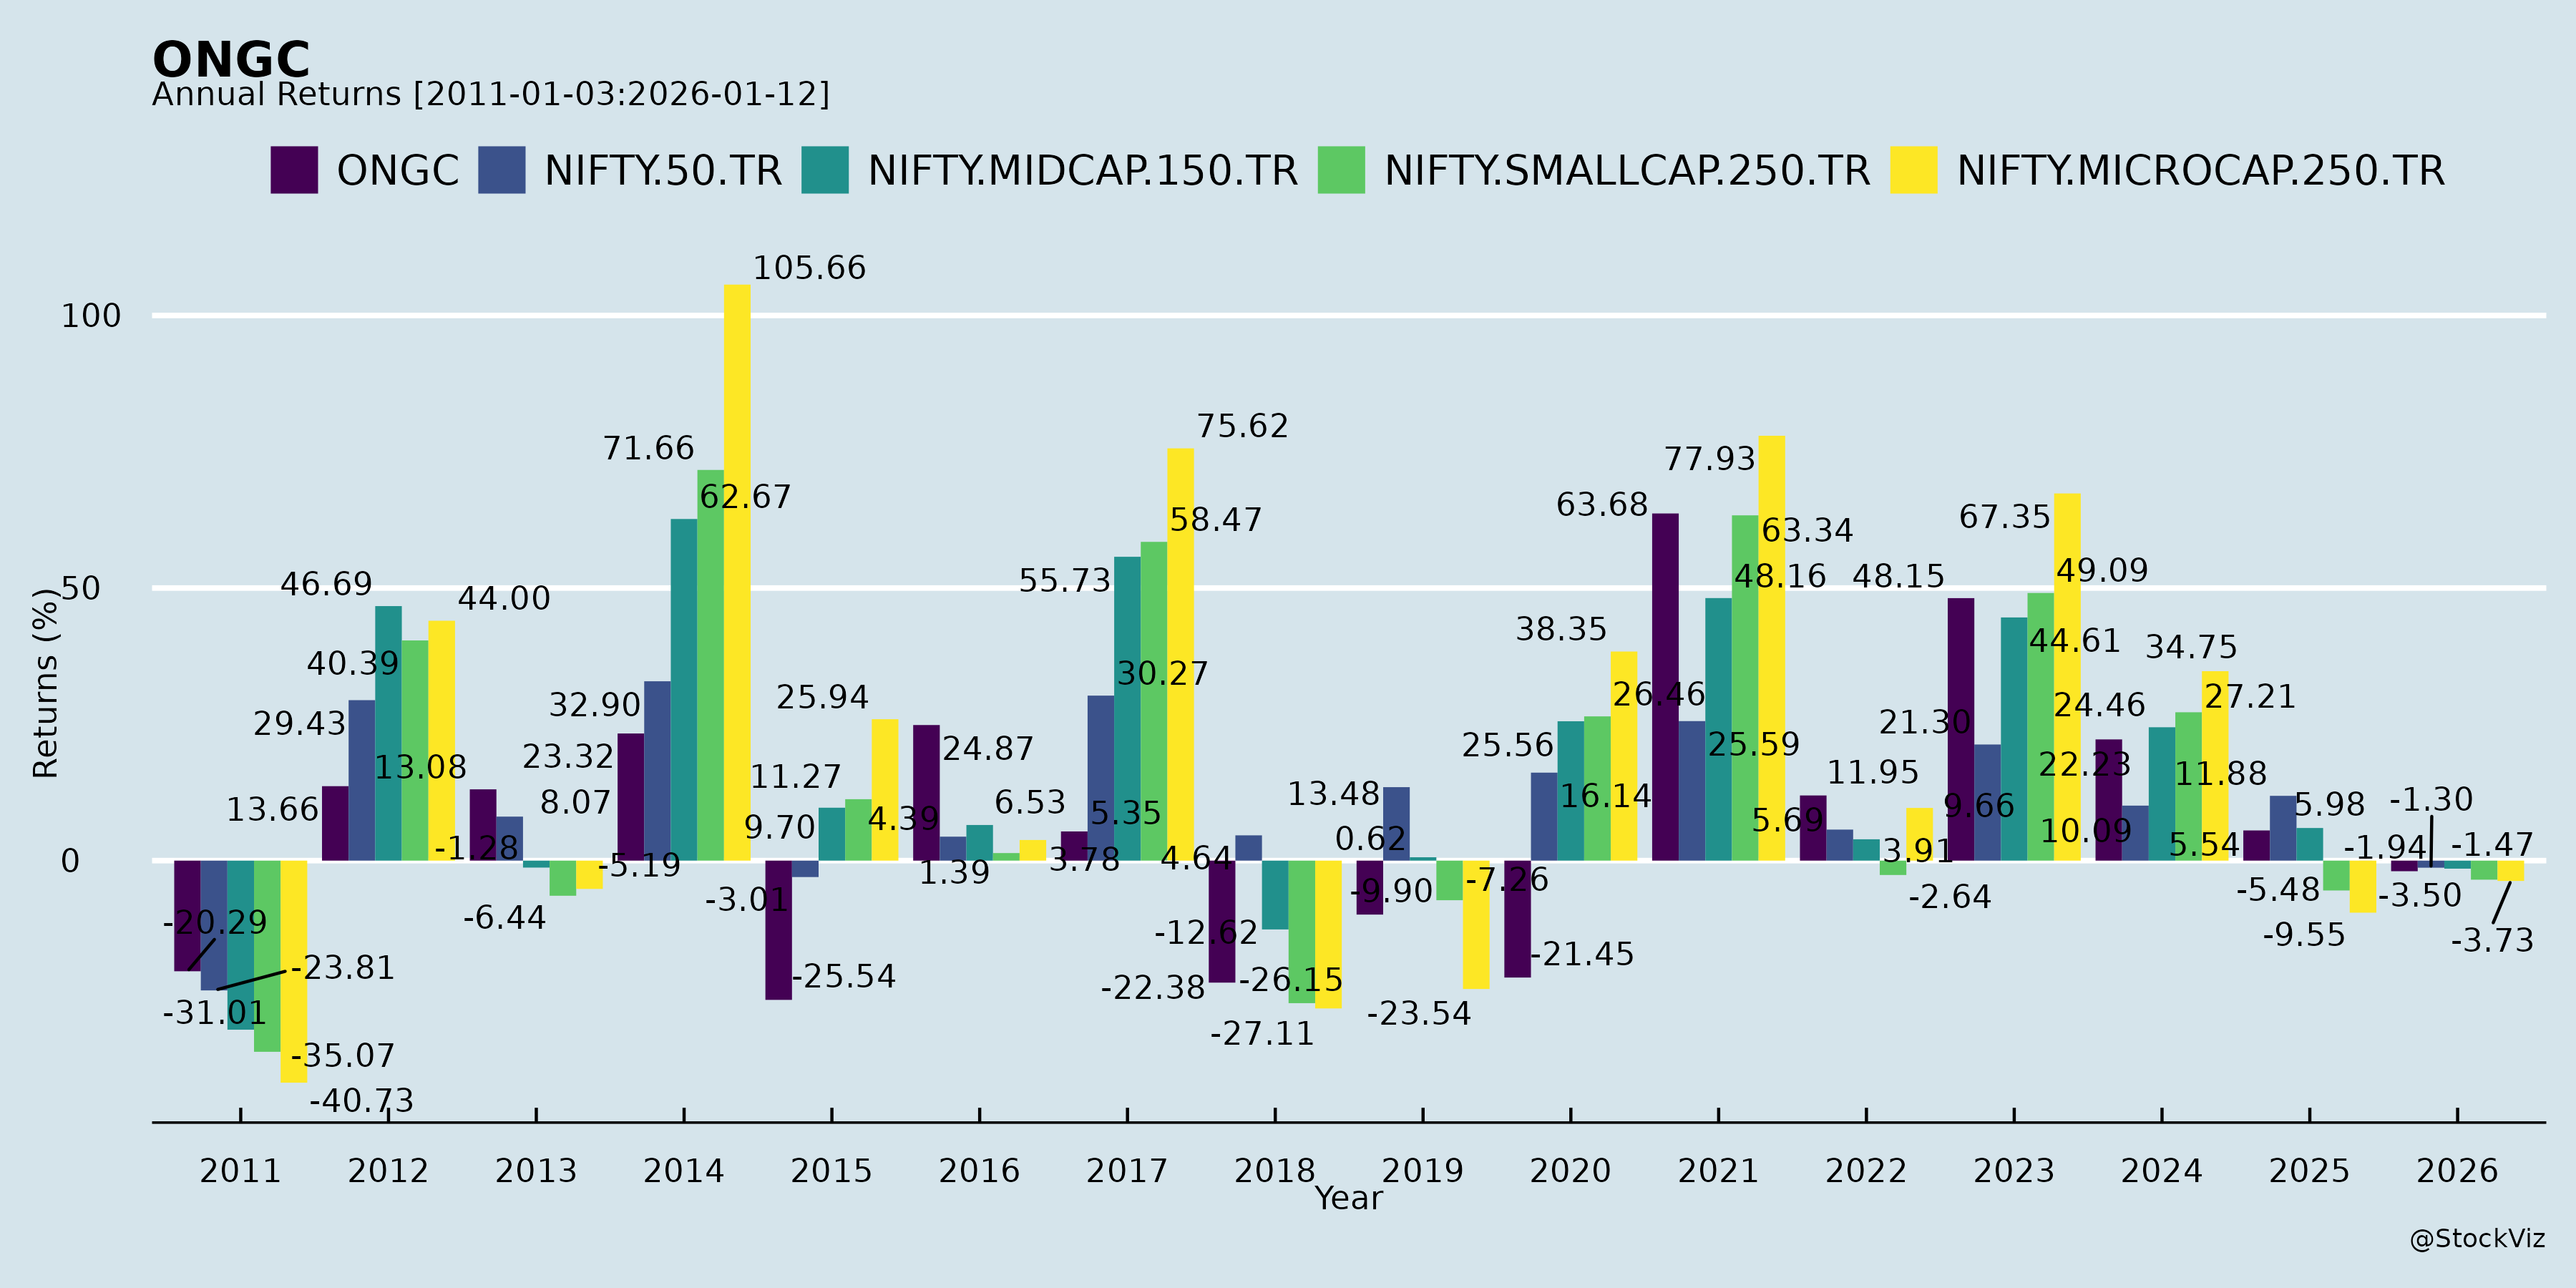
Annual Returns
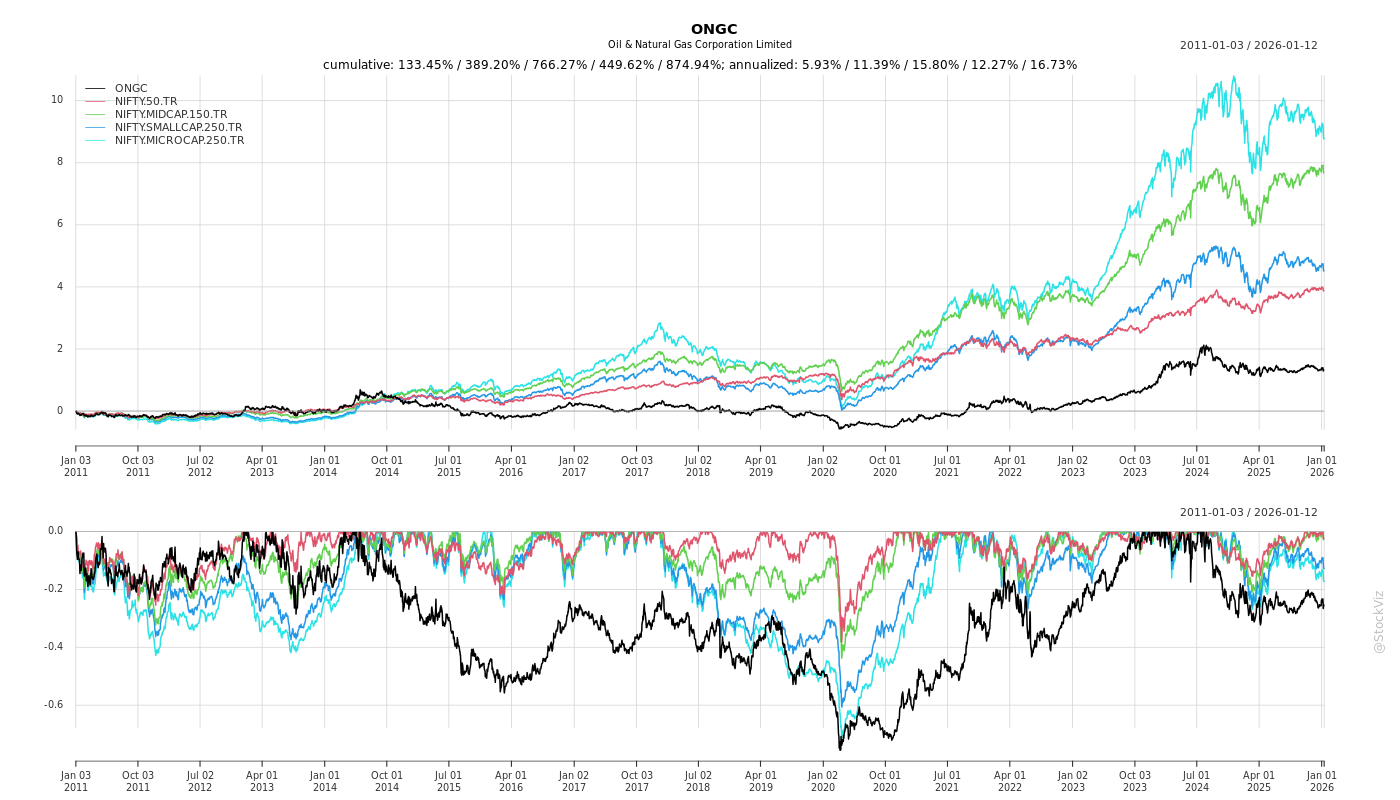
Cumulative Returns and Drawdowns
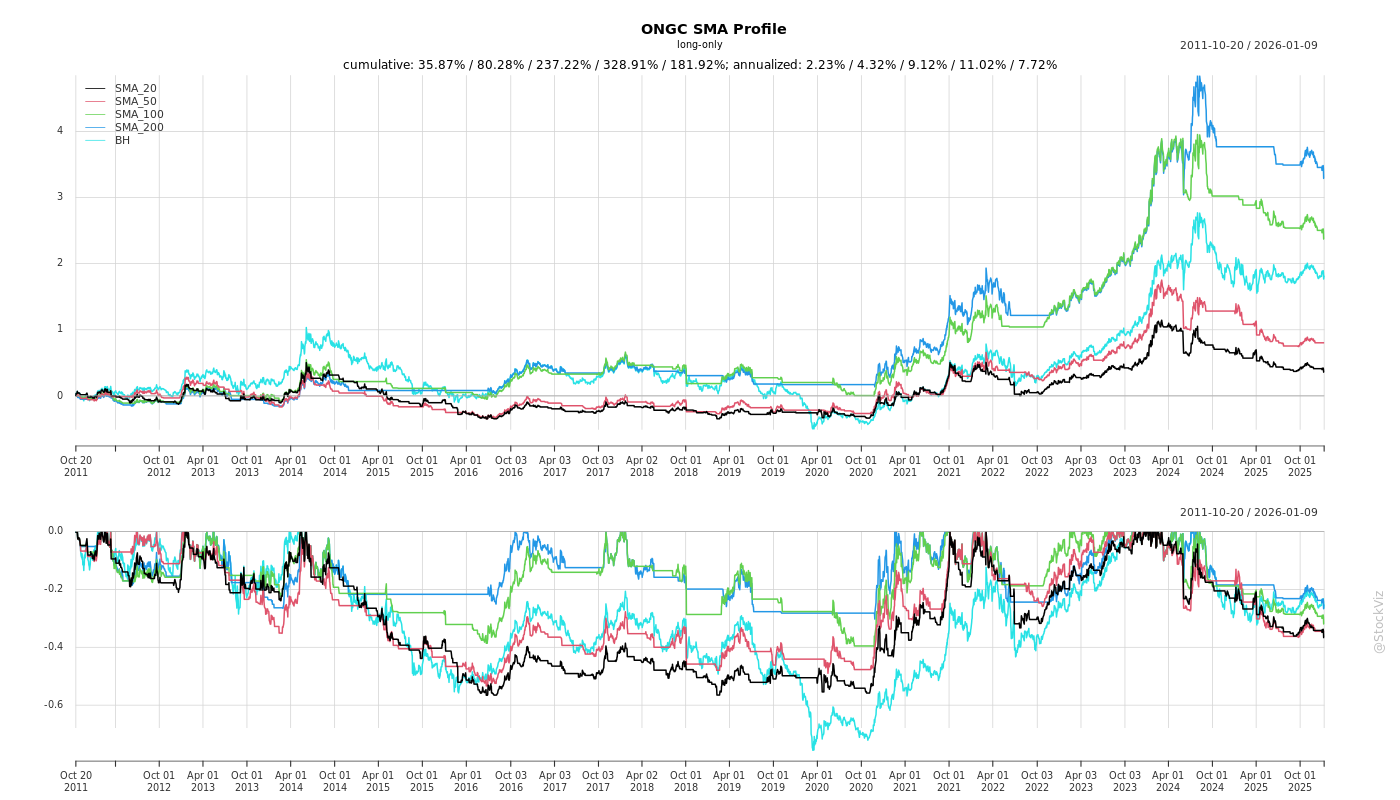
Fundamentals
Ownership
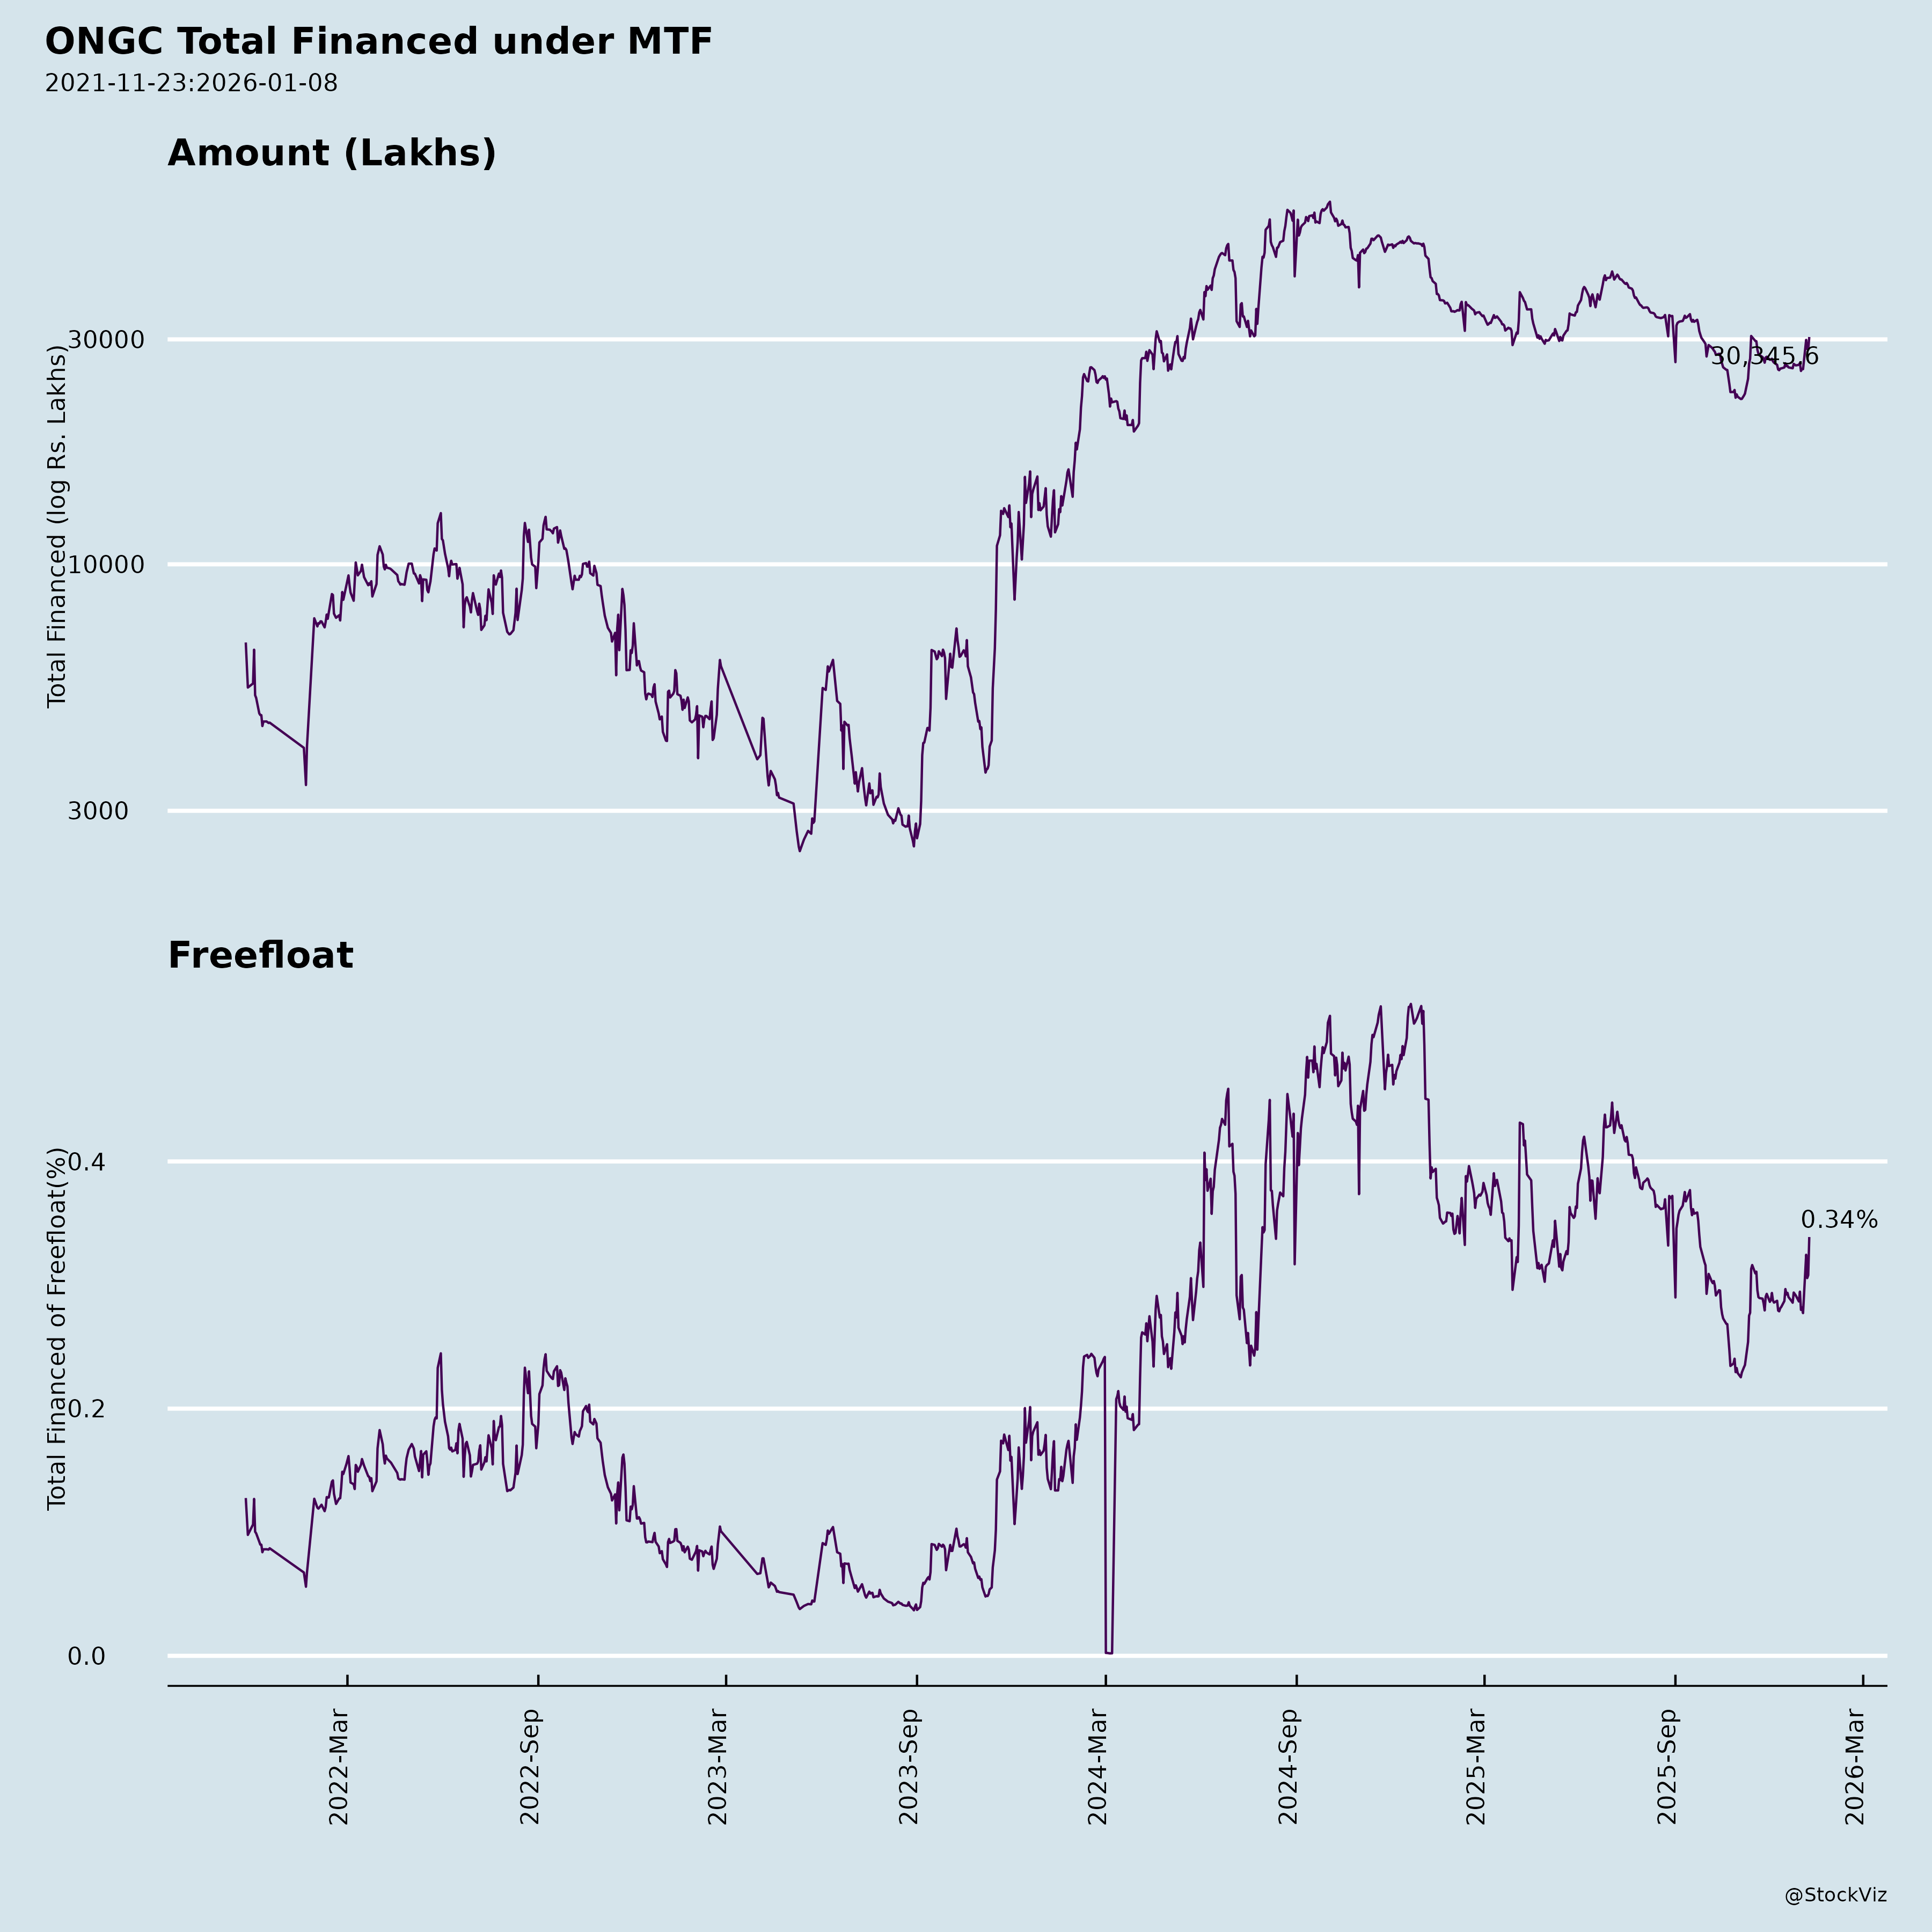
Margined
AI Summary
asof: 2026-09-14
Headwinds and Challenges
- Governance gap on the Board: The tenure of Independent Directors on the Board of ONGC completed on March 27, 2026. As a result, the Board did not have Independent Directors as required under SEBI (LODR) Regulations, 2015, the Companies Act, 2013 and DPE guidelines. Consequently, the Audit Committee could not be reconstituted and no Audit Committee meeting could be held; the standalone and consolidated financial results for the quarter ended June 30, 2026 were reviewed and approved directly by the Board at its meeting on August 04, 2026. The statutory auditors flagged this as an Emphasis of Matter in both the standalone and consolidated limited review reports.
- Legacy PMT JV arbitration exposure: ONGC holds 40% participating interest in the Panna-Mukta and Mid & South Tapti (PMT) fields, whose PSCs expired on December 21, 2019. Based on the October 12, 2016 Final Partial Award, DGH raised a demand on the Contractors; ONGC’s 40% share amounts to USD 1,624.05 million, equivalent to ₹15,365 Crore as on June 30, 2026 (₹15,225 Crore as on March 31, 2026). The JV partners have contested the demand as premature. The matter has moved through the English Commercial Court, the Arbitral Tribunal, and the Delhi High Court, with the Government’s appeal before a division bench ruled maintainable and the hearing pending. Arbitration on an increase in the Cost Recovery Limit, which may reduce the liability, is also pending. No provision has been accounted; the demand is treated as a contingent liability.
- Service Tax/GST on royalty: ONGC has received demand orders relating to levy of Service Tax/GST on royalty paid for crude oil and natural gas and has challenged them before various judicial forums; the matter is pending before the Supreme Court of India. The Company has recognized a provision of ₹20,450 Crore as at June 30, 2026 (₹19,645 Crore as at March 31, 2026), including ₹805 Crore recognized during the current year, and has deposited ₹19,392 Crore under protest up to June 30, 2026 (₹18,647 Crore up to March 31, 2026). Other JV partners’ share of ₹6,934 Crore (₹6,683 Crore as at March 31, 2026) has not been provided for and is disclosed as a contingent liability, backed by a legal opinion from the Additional Solicitor General of India. Disputed demands relating to penalty and other matters of ₹2,200 Crore (₹2,187 Crore as at March 31, 2026) are also disclosed as contingent liabilities.
- CB-OS/2 block dispute: The Government decided on September 19, 2025 not to extend the PSC for the Pre-NELP JV block CB-OS/2 (ONGC 50%, Vedanta Limited 40% as operator, Invenire Petrodyne Limited 10%) and directed ONGC to take over operations. Vedanta did not hand over operations in September 2025 and filed a writ petition; the Delhi High Court directed status quo. The High Court dismissed Vedanta’s petition on July 22, 2026, and ONGC took over operations and control effectively from that date and applied for a Petroleum Lease on July 28, 2026. Vedanta challenged the order before a Division Bench on July 22, 2026 and the matter is under adjudication. ONGC recognized an impairment of ₹40 crore against the carrying value of assets in the block on a conservative basis and has accounted for its interest as an unincorporated joint venture till June 30, 2026.
- Terminal Excise Duty refund dispute: DGFT Delhi rejected ONGC’s claims for refund of excise duties other than Basic Excise Duty on February 25, 2025. ONGC filed a writ petition before the Delhi High Court on May 23, 2025; the matter is listed for further hearing on October 07, 2026. ₹2,088 Crore as on June 30, 2026 (unchanged from March 31, 2026) is carried as recoverable, considered good.
- Subsidiary plant shutdown: At subsidiary OPaL, the PP plant was shut down due to a technical issue from August 14, 2025 to October 20, 2025. The OEM’s interim report is under study; the final report will be shared with the insurer, and any insurance settlement will be accounted for when finalized or received.
- ESG assessment: ONGC received an ESG Risk Assessment Report with an overall score of 44 (Inadequate) from ESGRisk.ai, an agency it neither engaged nor consulted. Management considers this score low and not commensurate with its decarbonization initiatives, governance structure, and BRSR disclosures.
- Sector and compliance profile: The company operates in a carbon-intensive sector with substantial emissions, environmental compliance incidents, limited female representation on the Board and senior management, and various penalties and litigation regarding service tax, GST, penalties, and environmental non-compliance.
- Disclosure timing: The schedule of the Analyst/Investor Meet with Motilal Oswal’s 22nd Annual Global Group Meetings (Mumbai, August 18, 2026) was disclosed on August 14, 2026 with a delay, as the date and schedule of group meetings was finalized that day.
Tailwinds and Growth Prospects
- North East gas connectivity: ONGC commissioned gas evacuation facilities at Khoraghat GGS-1 in Golaghat district, Assam, on August 18, 2026, enabling surplus associated natural gas from the Upper Assam Shelf to be processed and evacuated through the North East Gas Grid (NEGG) developed by Indradhanush Gas Grid Limited (IGGL). The development complements the commissioning of the Dergaon–Dimapur Pipeline, which connected Nagaland to the North East Gas Grid and the National Gas Grid. The connectivity will facilitate utilisation of nearly 1 lakh Standard Cubic Metres (SCM) of gas per day from ONGC’s Jorhat asset.
- Additional hook-up facilities: ONGC is developing hook-up facilities at Jantapathar and Kasomarigaon to connect additional producing fields of the Jorhat Asset with the North East Gas Grid. These projects are expected to further augment gas availability, reduce flaring and strengthen the gas-based economy of the region.
- Regional demand creation: Improved gas availability is expected to create opportunities for households, industry, transport and power, while supporting economic and infrastructure development of Assam and the wider North-East. The infrastructure advances the vision of developing the North-East as a key growth engine of India and a more integrated gas-based economy.
- CB-OS/2 operational control: Following the Delhi High Court order of July 22, 2026, ONGC took over operations and control of the CB-OS/2 block and applied for a Petroleum Lease on July 28, 2026.
- ESG-related initiatives: Increased female representation on the board with a target of 25% or higher, increased renewable energy consumption across operations, improved gender diversity across the workforce, and strengthened occupational health and safety management practices.
- Shareholder returns: At the 33rd Annual General Meeting held on August 31, 2026, all 11 business items were passed with the requisite majority, including declaration of a final dividend of Rs. 1 per equity share for the financial year 2025-26.
Key Risks
- Contingent liabilities from arbitration and tax disputes: The PMT JV demand of ₹15,365 Crore as on June 30, 2026 remains a contingent liability pending finality by the Arbitration Tribunal; the ultimate outcome of the litigation and its consequential impact cannot presently be determined. The Service Tax/GST on royalty matter is pending before the Supreme Court, with ₹20,450 Crore provided and ₹6,934 Crore (other JV partners’ share) plus ₹2,200 Crore (penalty and other matters) disclosed as contingent liabilities.
- Litigation over CB-OS/2: Vedanta’s challenge before the Division Bench of the Delhi High Court is under adjudication; the ultimate outcome and consequential impact cannot presently be determined.
- Recoverability of TED refund: The ₹2,088 Crore Terminal Excise Duty refund is contested, with DGFT having rejected the claims and the writ petition pending before the Delhi High Court, listed for hearing on October 07, 2026.
- Reliance on management-certified and unreviewed information: The standalone and consolidated results include ONGC’s proportionate share in 216 blocks under NELP/HELP/DSF/OALP and JO accounts, of which 27 blocks were not reviewed by the auditors and were certified by management; these contributed proportionate revenue of ₹1,376.32 Crore and profit/(loss) (net) including other comprehensive income of ₹515.26 Crore for the quarter ended June 30, 2026. The consolidated statement also includes unreviewed information for 1 subsidiary and 1 controlled trust (total revenue ₹83.63 crore, total profit/(loss) (net) ₹48.74 crore, total comprehensive income ₹48.23 crore) and for 2 joint ventures and 3 associates (Group’s share of total profit/(loss) (net) ₹127.18 crore, total comprehensive income ₹127.70 crore), all certified by the management of the respective entities.
- Reliance on technical/commercial evaluation by management: The auditors placed reliance on management’s technical/commercial evaluation for categorization of wells, allocation of costs, production profile, proved/probable hydrocarbon reserves and depletion, impairment, decommissioning cost liability, project completion timelines, and NELP/HELP and nominated block liability for underperformance against the agreed Minimum Work Programme.
- Governance and ESG profile: The absence of Independent Directors on the Board as of the results approval date, the ESG Risk Assessment score of 44 (Inadequate), carbon-intensive operations, environmental compliance incidents, limited female representation on the Board and senior management, and various penalties and litigation are identified risk factors.
- Subsidiary operational risk: The OPaL PP plant shutdown from August 14, 2025 to October 20, 2025 and the pending final OEM report and insurance claim assessment, including possible business interruption.
Management Guidance Versus Observed Business Performance
- Gas evacuation and connectivity: Management states that the Khoraghat GGS-1 commissioning (August 18, 2026) will facilitate utilisation of nearly 1 lakh SCM of gas per day from the Jorhat asset, and that the Jantapathar and Kasomarigaon hook-up facilities will further augment gas availability and reduce flaring. These are forward-looking statements; the source material does not provide subsequent production data to verify them.
- CB-OS/2: Management states that ONGC took effective control of the block from July 22, 2026 and applied for a Petroleum Lease on July 28, 2026. Observed performance in the reported results reflects accounting for the interest as an unincorporated joint venture till June 30, 2026 and a conservative impairment of ₹40 crore against the carrying value of assets in the block.
- ESG score: Management considers the ESGRisk.ai score of 44 (Inadequate) low and not commensurate with its decarbonization initiatives, governance structure, and BRSR disclosures. The source material does not provide a subsequent revised score or third-party validation.
- Dividend: The final dividend of Rs. 1 per equity share for FY 2025-26 was declared at the AGM on August 31, 2026, with all 11 business items passed with the requisite majority.
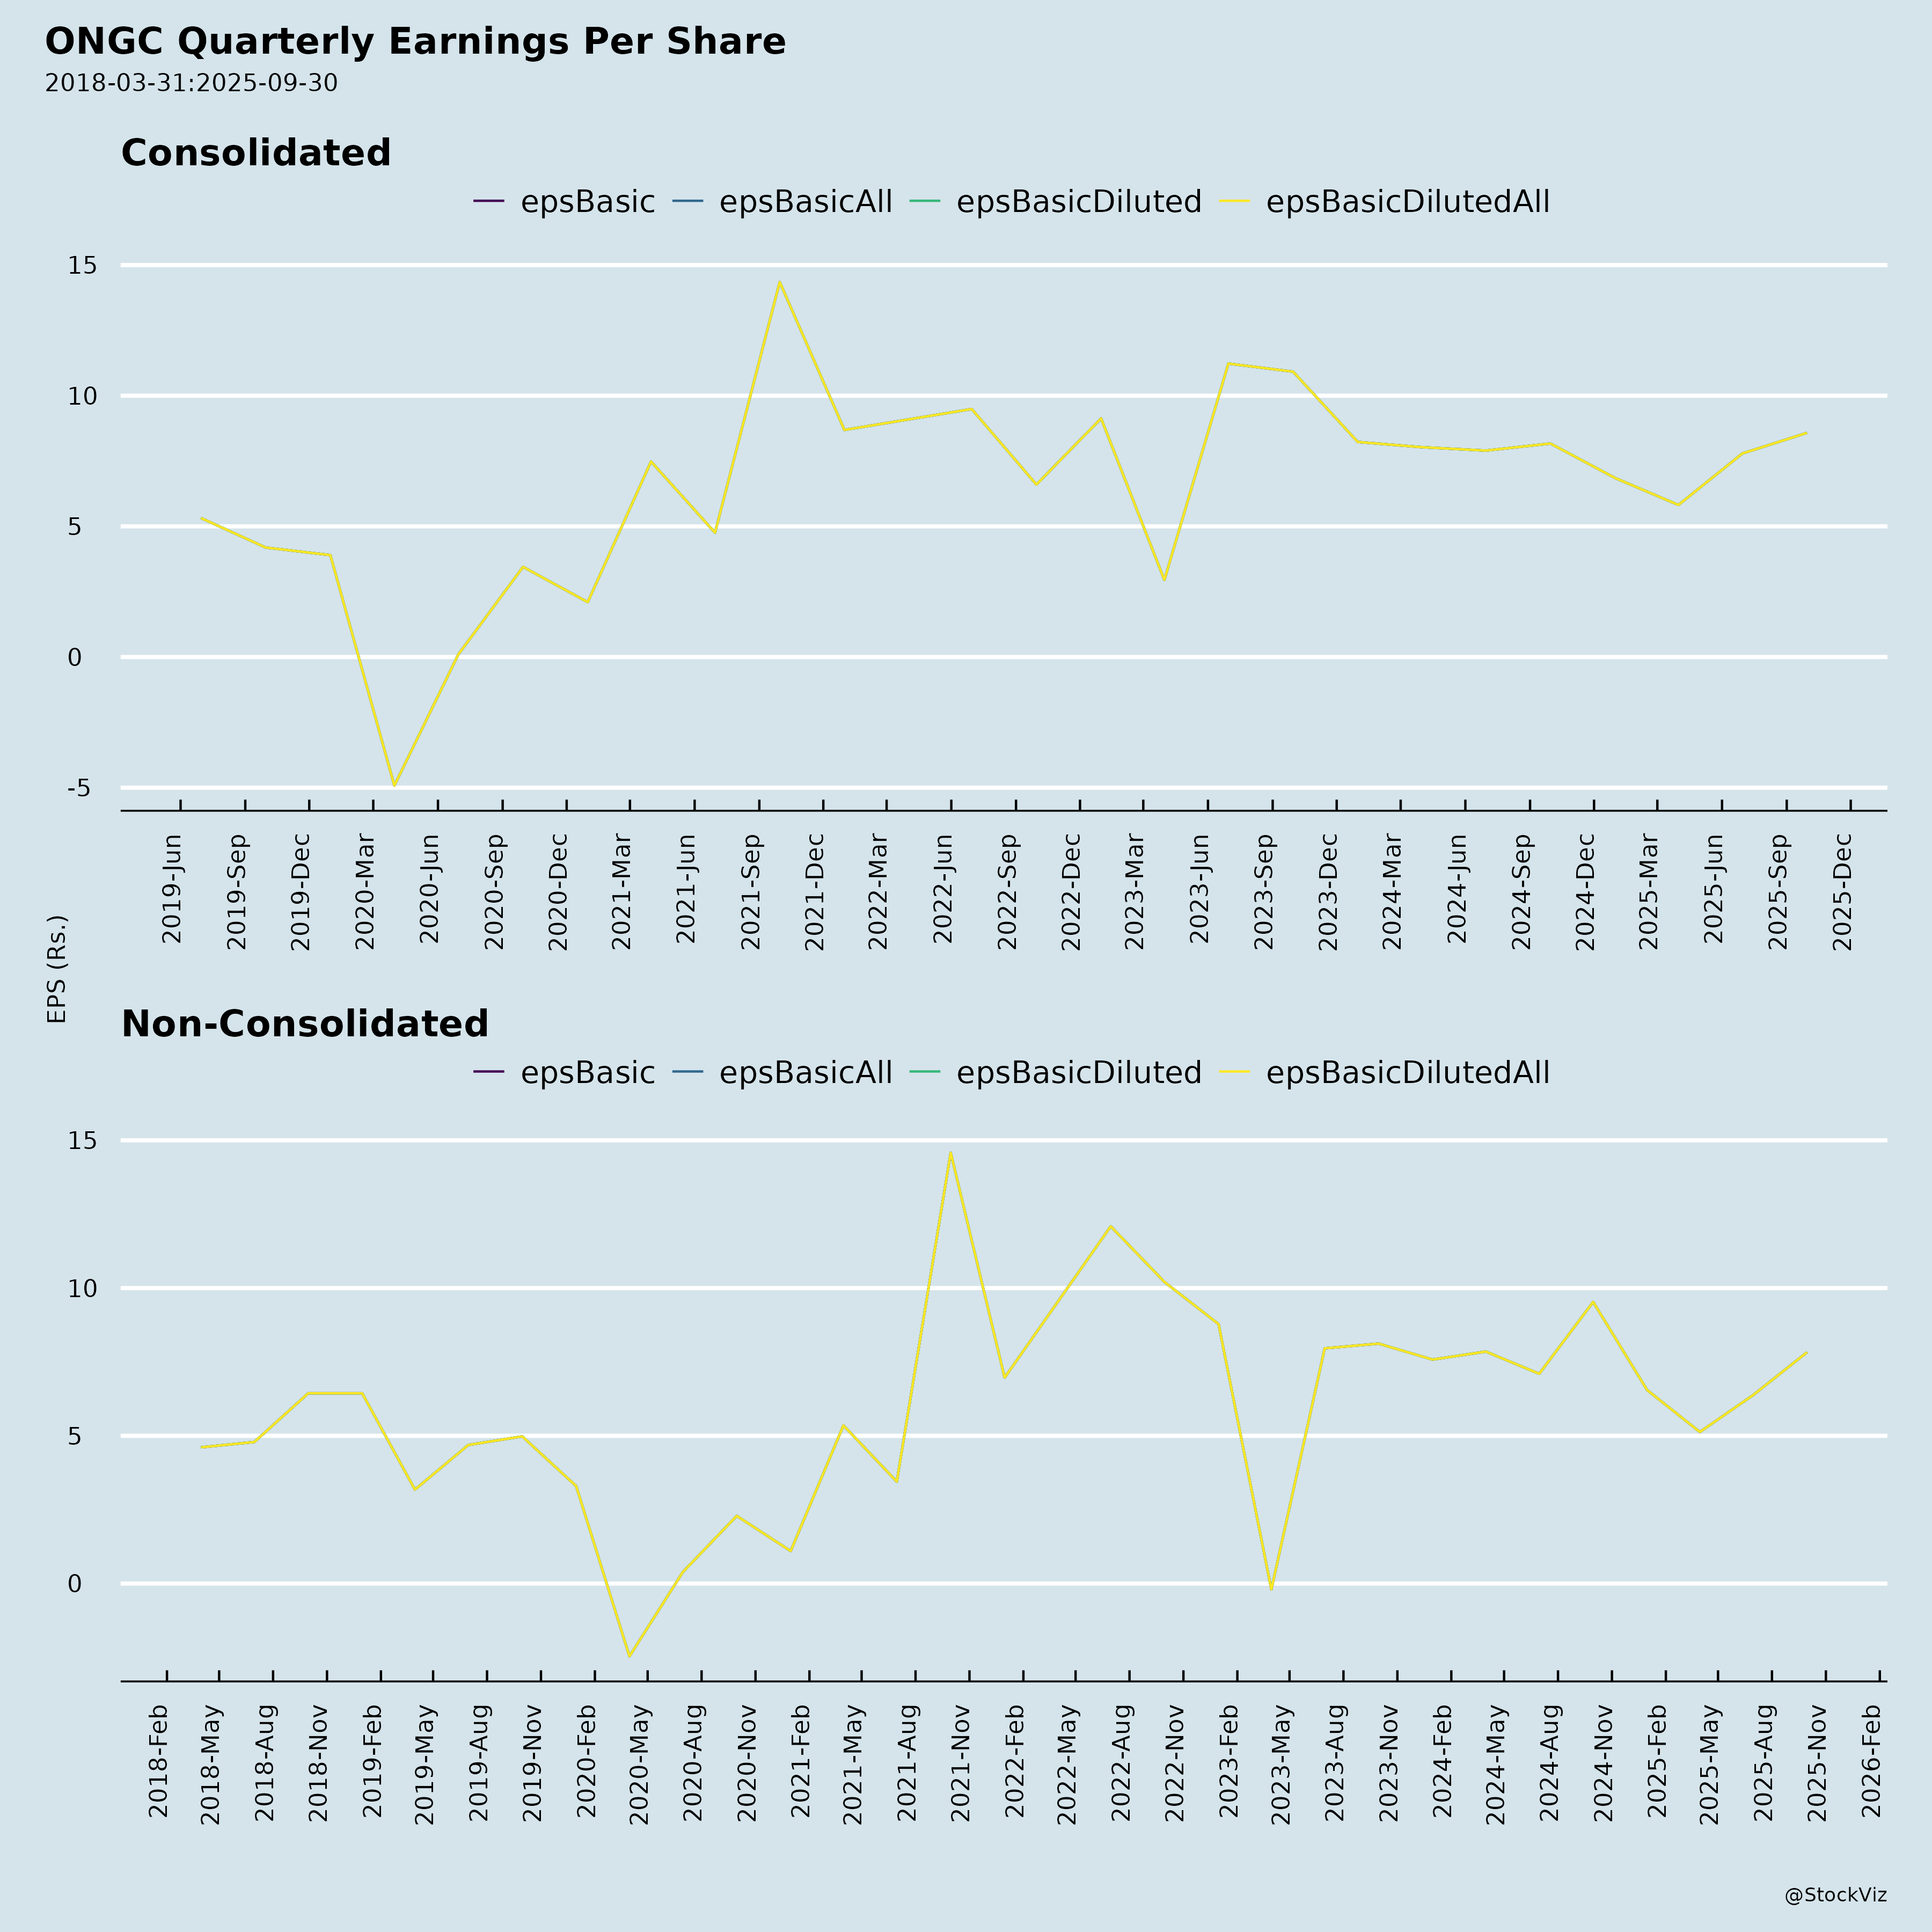
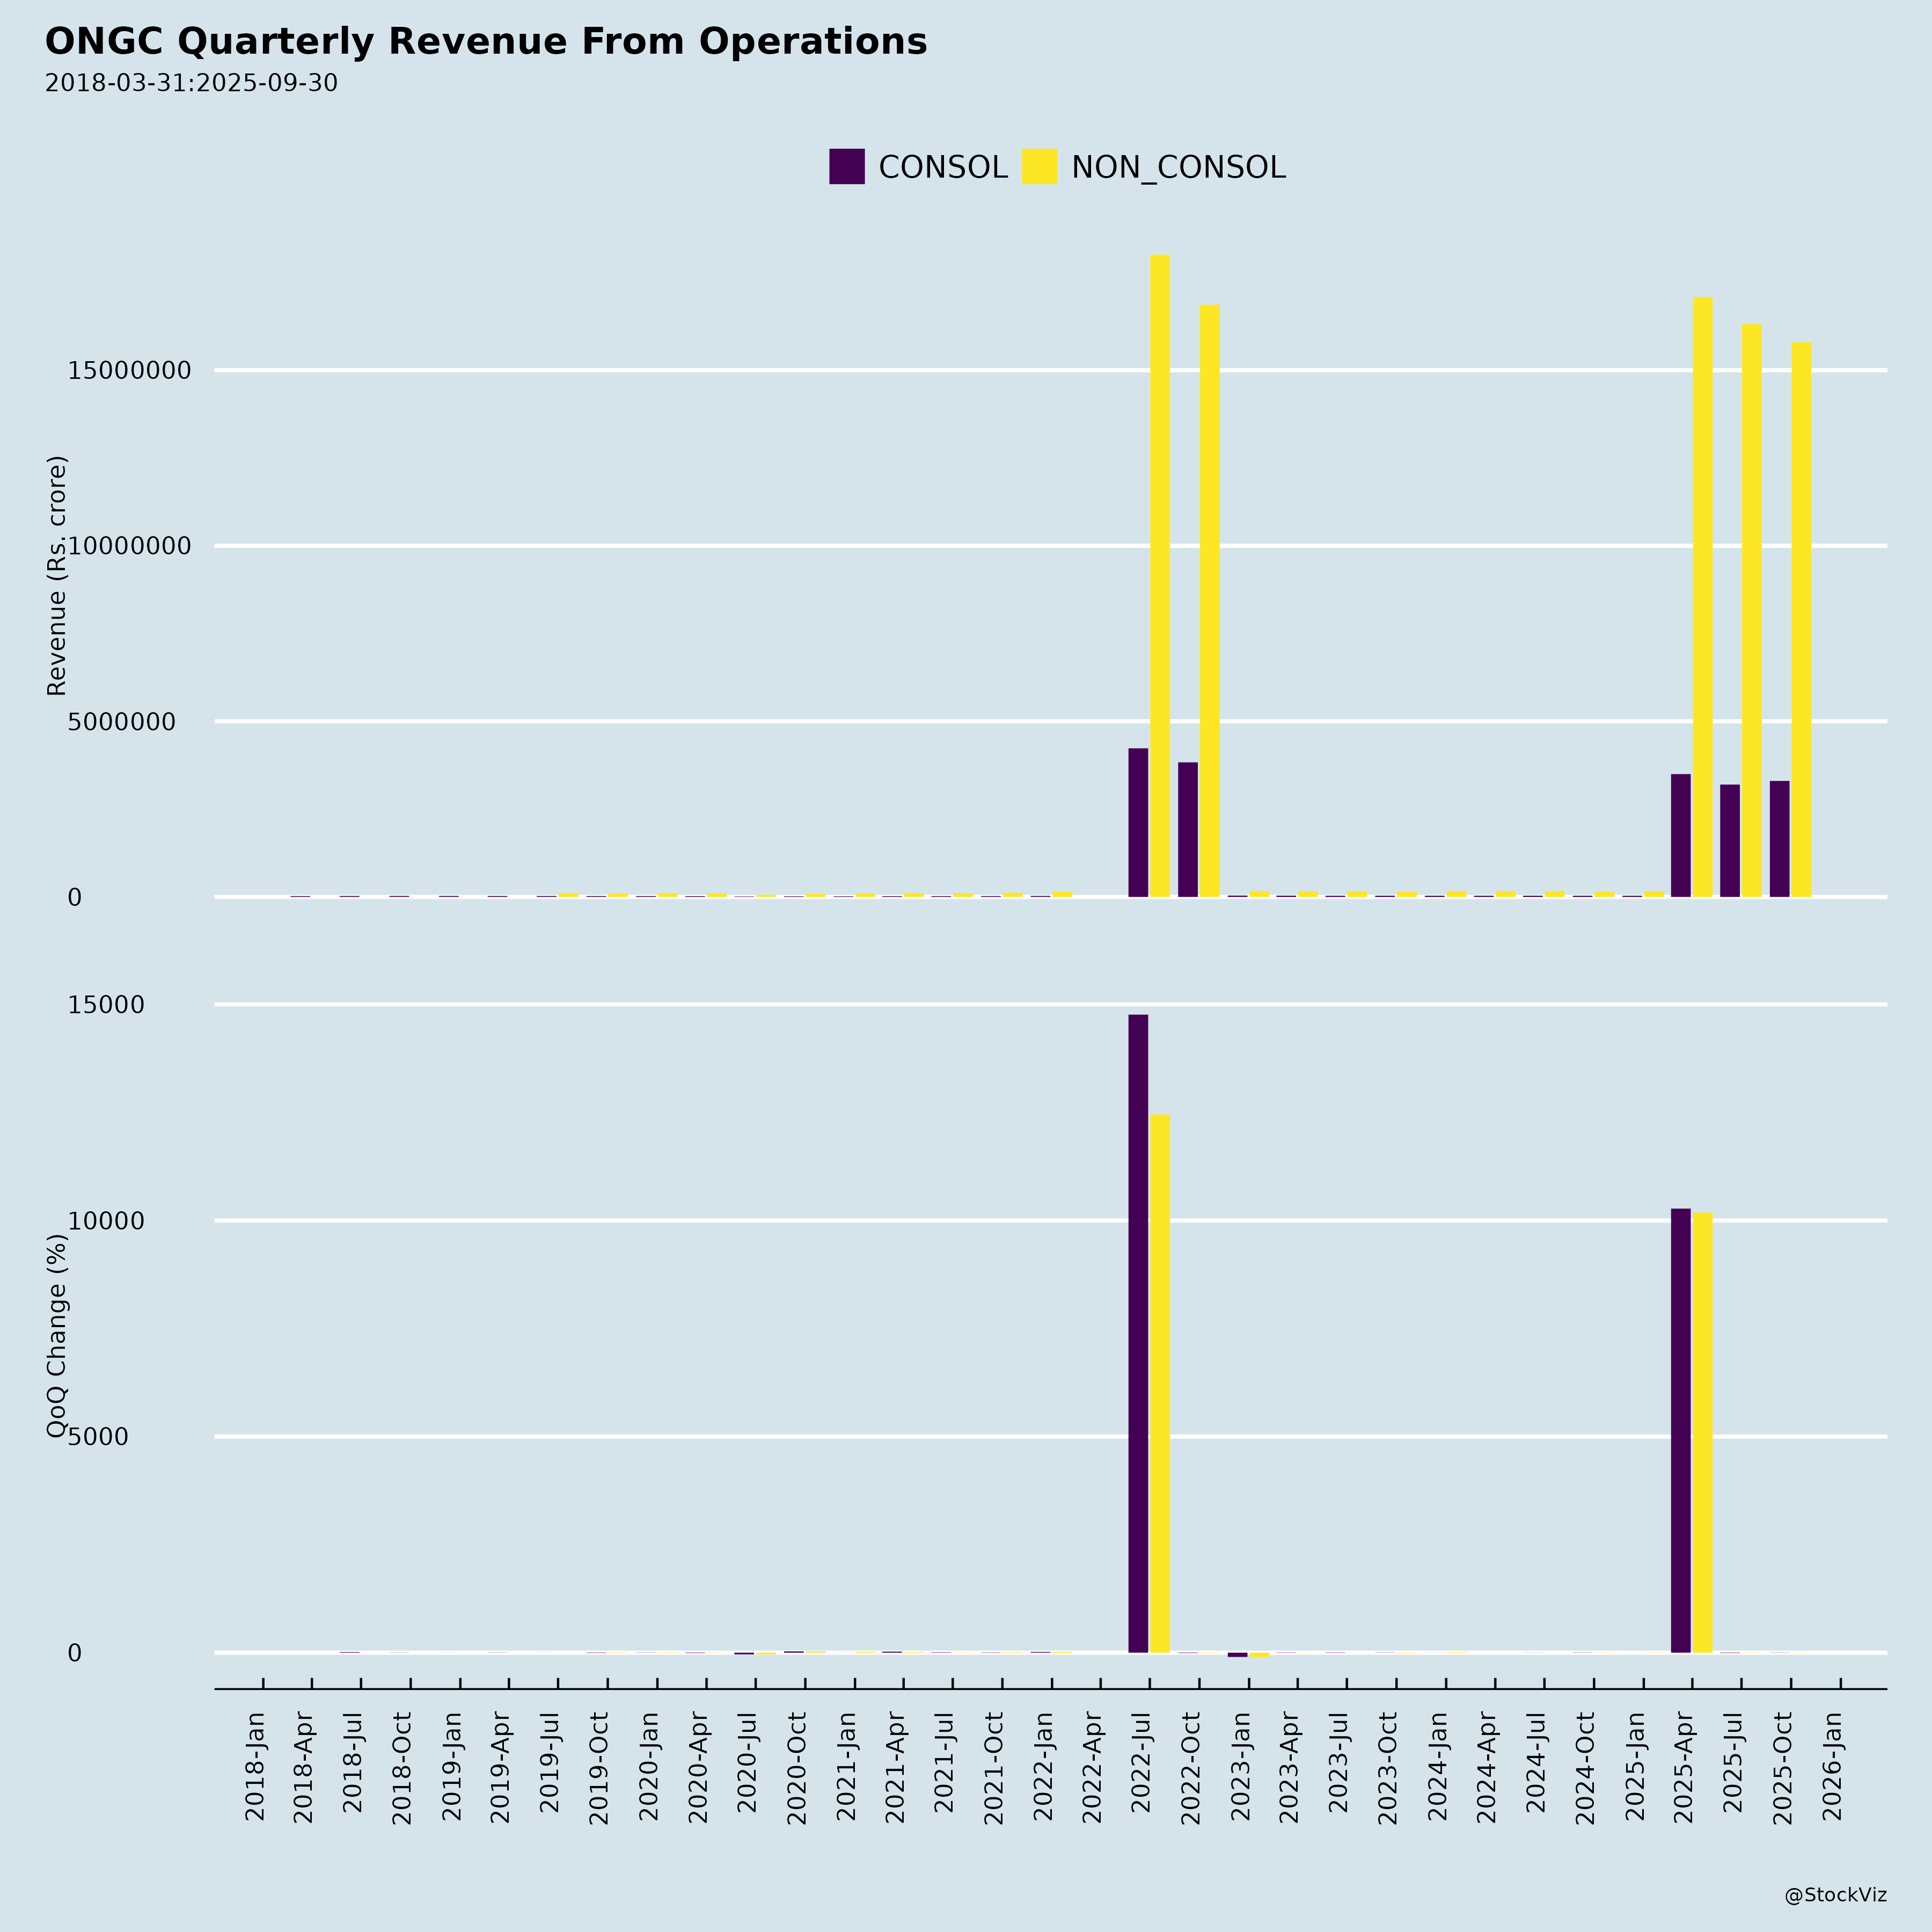
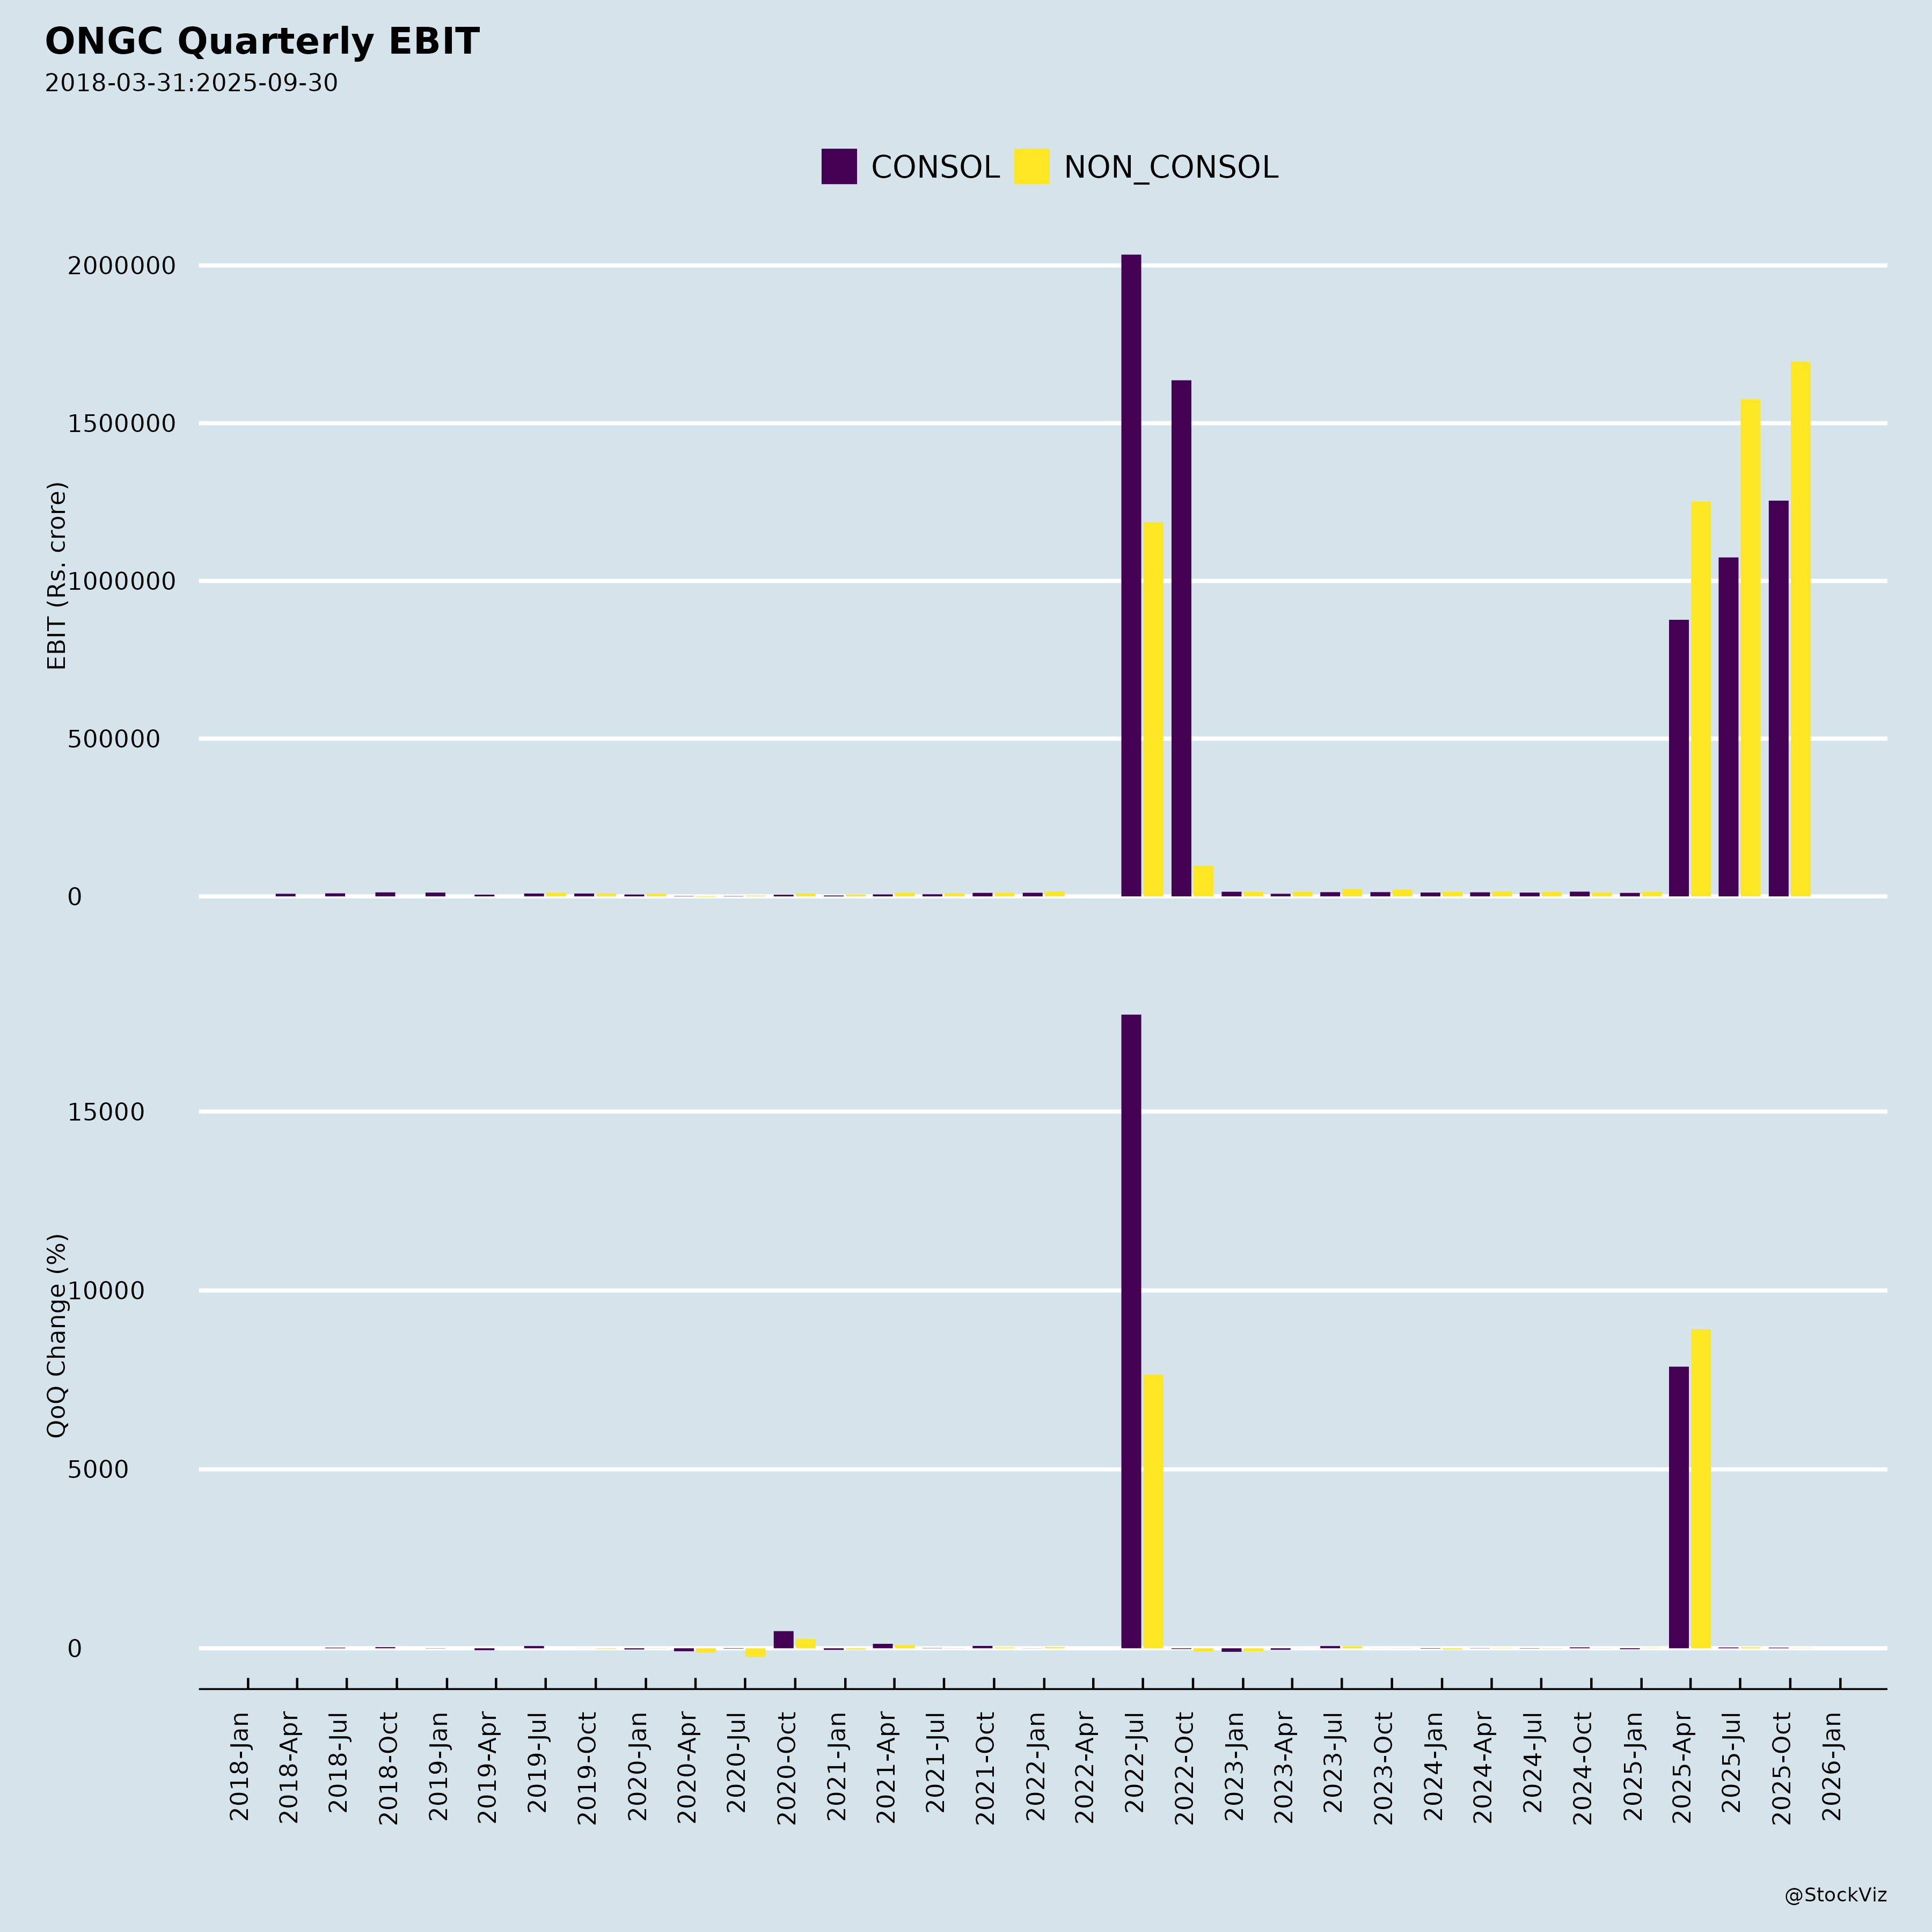
- Financial performance for the quarter ended June 30, 2026 (standalone): Revenue from operations was ₹46,460.45 Crore, total income ₹48,321.65 Crore, profit before tax ₹22,848.02 Crore, profit for the period ₹17,033.81 Crore, and total comprehensive income ₹18,663.13 Crore. Earnings per share (basic and diluted, not annualised) was ₹13.54. Operating margin was 51.51% and net profit margin 36.66%.
- Financial performance for the quarter ended June 30, 2026 (consolidated): Revenue from operations was ₹204,987.35 Crore, total income ₹207,775.93 Crore, profit before tax ₹7,012.45 Crore, profit for the period ₹6,554.44 Crore, and total comprehensive income ₹8,543.19 Crore. Earnings per share (basic and diluted, not annualised) was ₹9.46. Operating margin was 4.58% and net profit margin 3.20%. Profit for the period attributable to owners of the Company was ₹11,898.93 Crore, with non-controlling interests at ₹(5,344.49) Crore.
- Segment performance (standalone, quarter ended June 30, 2026): Offshore revenue was ₹33,337.24 Crore and onshore ₹13,123.21 Crore; offshore segment result was ₹19,182.50 Crore and onshore ₹3,936.56 Crore.
- Segment performance (consolidated, quarter ended June 30, 2026): E&P offshore revenue was ₹33,337.24 Crore, E&P onshore ₹13,072.91 Crore, refining & marketing ₹186,884.38 Crore, petrochemicals ₹3,857.87 Crore, and others ₹3,346.20 Crore. Segment result for refining & marketing was ₹(16,154.95) Crore and petrochemicals ₹(453.76) Crore.
- Balance sheet and coverage metrics (standalone, June 30, 2026): Net worth ₹350,433.56 Crore, outstanding debt ₹6,106.74 Crore, debt equity ratio 0.02, debt service coverage ratio 512.17, interest service coverage ratio 206.91, current ratio 2.25, total debts to total assets 0.01.
- Balance sheet and coverage metrics (consolidated, June 30, 2026): Net worth ₹418,808.61 Crore, outstanding debt ₹162,969.34 Crore, debt equity ratio 0.39, debt service coverage ratio 1.41, interest service coverage ratio 4.69, current ratio 0.86, total debts to total assets 0.20.
- NCD disclosures: ONGC had ₹10,000 million unsecured Non-Convertible Debentures as on June 30, 2026; security cover certificates are not applicable as these are unsecured NCDs. Four series of NCDs aggregating to ₹4,140 Crore were issued during FY 2020-21 (outstanding ₹1,000 Crore as on June 30, 2026), with funds fully utilised for the intended purpose during the same year and “NIL” deviation statements filed on November 13, 2020 and June 24, 2021; no statement of deviation was submitted for the quarter ended June 30, 2026. There were no outstanding secured debentures as on June 30, 2026.
Broker Narrative
The broker narrative shifted from a financial-services growth thesis (NII/PPoP expansion, pristine asset quality at PCR ~83%, Retail/SME/Business Banking opportunities) in the first report to an oil-and-gas operational story (crude and gas realisations, deepwater reservoir challenges, Western Offshore redevelopment, Sakhalin revival, Samudra Manthan mission) in the last report, with the earlier optimism largely giving way to caution around production risks and liability exposures. The Buy consensus persisted across both reports, but the underlying drivers changed entirely from balance-sheet and franchise themes to commodity-price and reservoir-operational themes.
Fears that came true
- Economic slowdown impacting loan/growth materialized through widespread DISAPPOINTMENT outcomes with deeply negative actual returns from mid-2024 onward (e.g., -25.1%, -14.7%, -13.2%).
- KG-98/2 reservoir complexity materialized as production was explicitly impaired by reservoir-related challenges at the deepwater block, correlating with multiple DISAPPOINTMENT and PENDING outcomes.
- HPCL under-recoveries and PMT arbitration liability were flagged as downside risks and coincided with a period of persistent negative actual returns and repeated broker downgrades or DISAPPOINTMENT calls.
Optimism that failed
- Healthy NII/Core PPoP growth and industry-best PCR of ~83% failed to materialize as positive returns, with most Buy calls from 2024 onward resulting in DISAPPOINTMENT outcomes.
- Strong growth opportunities in Retail, SME, and Business Banking failed to drive the predicted outperformance, as actual returns turned sharply negative across multiple reports despite the bullish framing.
- Stable margin expansion to 4.9% and a high-yielding/low-cost franchise narrative did not sustain, evidenced by the last report’s Buy call delivering only a FLAT +0.9% actual return.
- Higher crude and gas realisations cited as a tailwind in the last report failed to produce positive outcomes, with actual returns remaining flat or negative and several subsequent DISAPPOINTMENT calls.
Broker Timeline
62 broker calls · 2023-05-05 to 2026-08-31
CNBC-TV18: ratings, targets and commentary
Extracted from CNBC-TV18 posts; ratings and targets are as published, not current consensus. OCR may contain errors. Speaker attribution is retained; not all speakers are brokers. These statements are separate from the Broker Narrative and Broker Timeline and have no calculated performance or outcomes.
Ratings and targets
| Published / source (IST) | Speaker / affiliation | Rating / target | Commentary |
|---|---|---|---|
| 2026-11-09 |
CLSA
|
Outperform
Target: INR 405
Horizon: FY27-28
|
High conviction outperform call on ONGC with target price at ₹405/sh. Q2 standalone PAT was 5% below estimates due to impairment losses and a one-off provision; EBITDA and core PBT beat estimates by 7% and 4%. Declared interim dividend of ₹8/sh, implying 3.5% yield. KG-98/2 and Daman upside should drive FY27-28 volume growth. See 76% upside based on $82/bbl Brent in FY28. |
Management comments
No recorded management comments with an explicit designation and affiliation for this ticker.
Copyright © 2023 SAS Data Analytics Pvt. Ltd. All rights reserved.