OLECTRA
Equity Metrics
November 18, 2026
Olectra Greentech Limited
Passenger Cars & Utility Vehicles
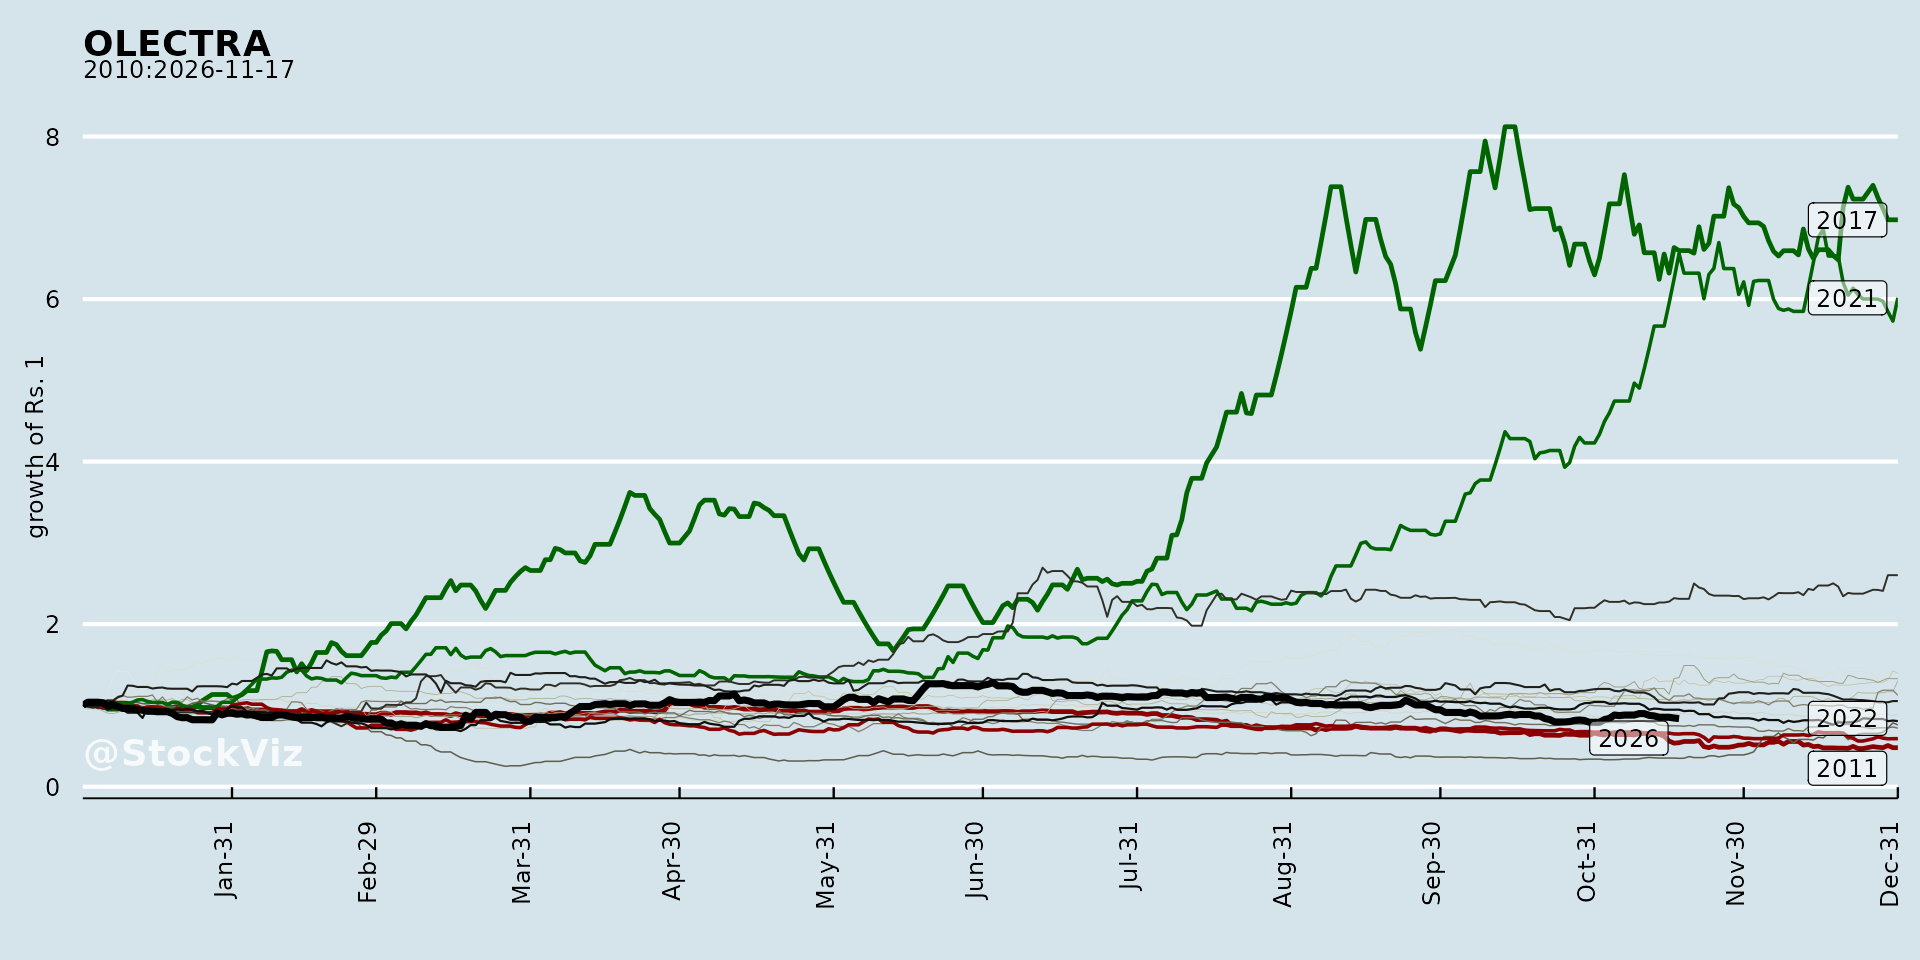
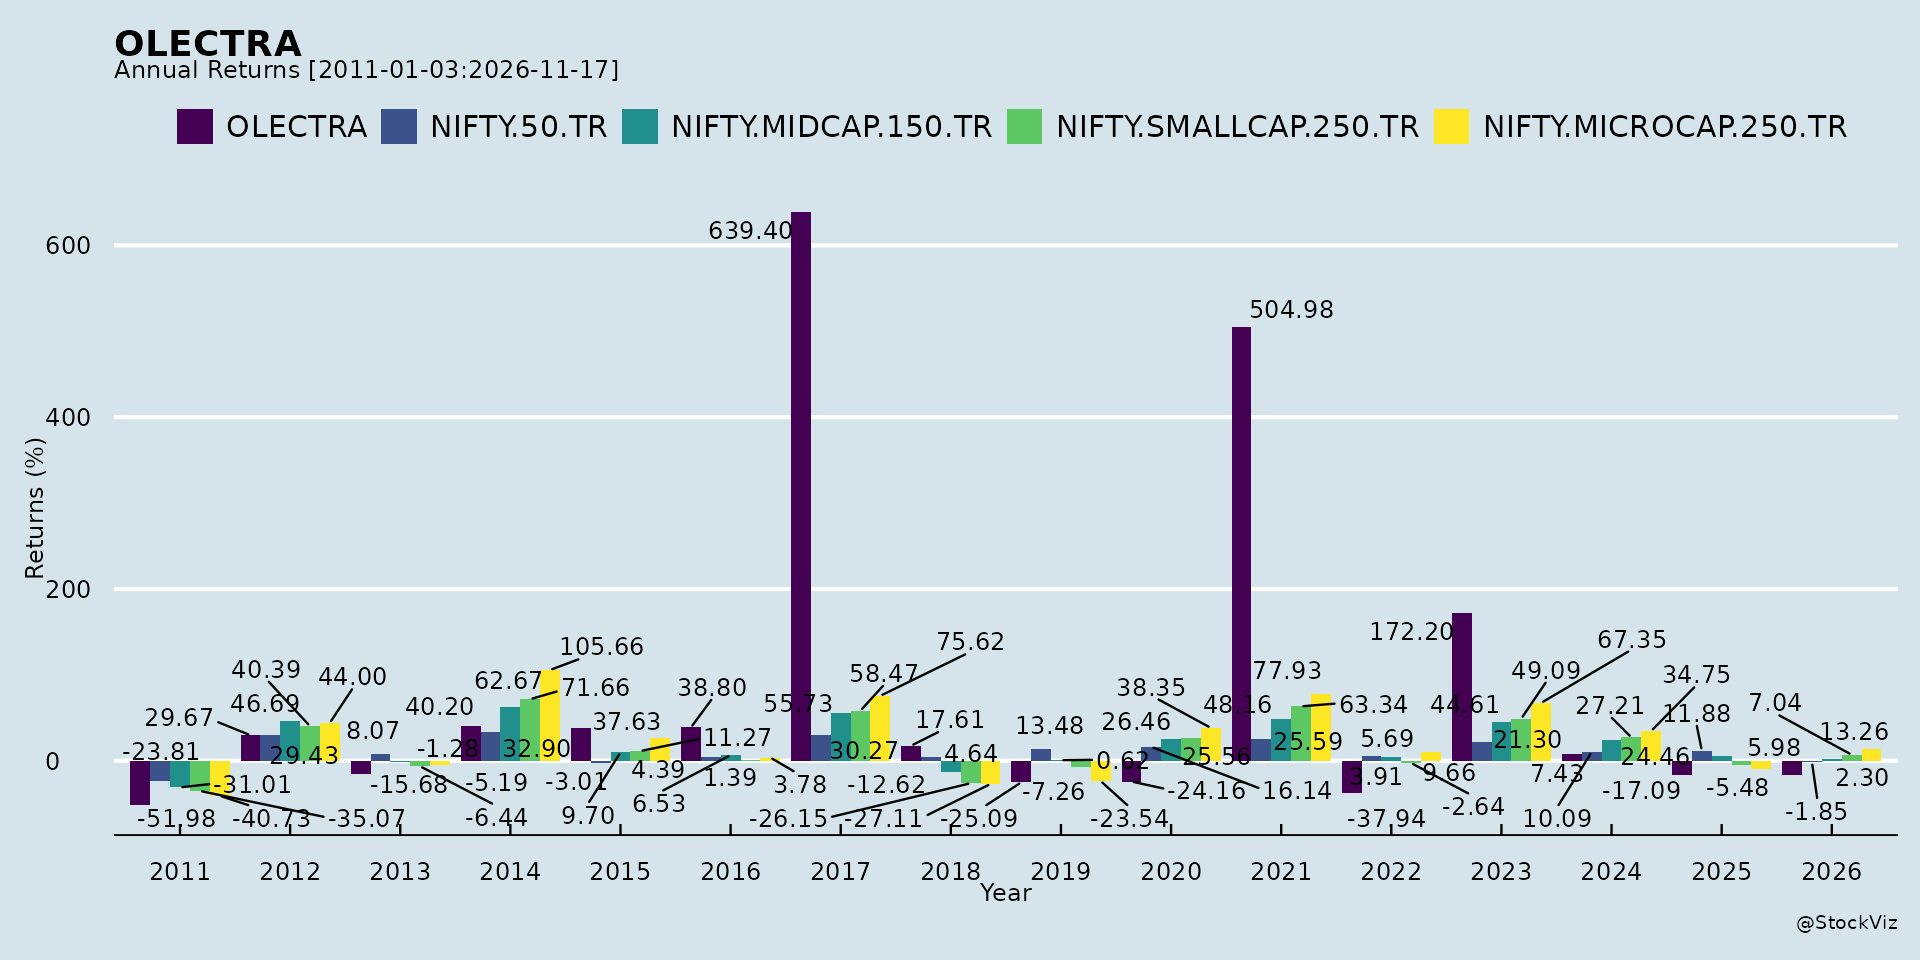
Annual Returns
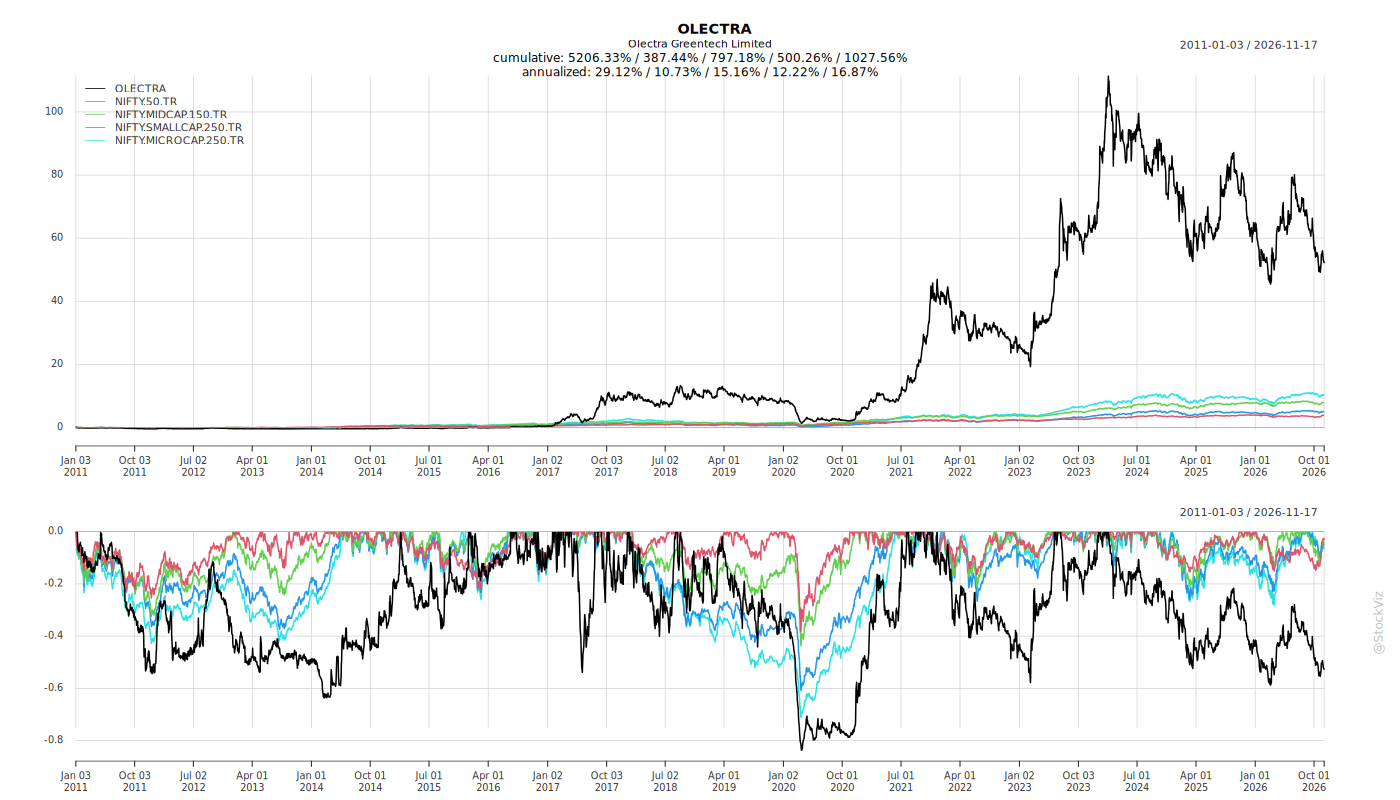
Cumulative Returns and Drawdowns
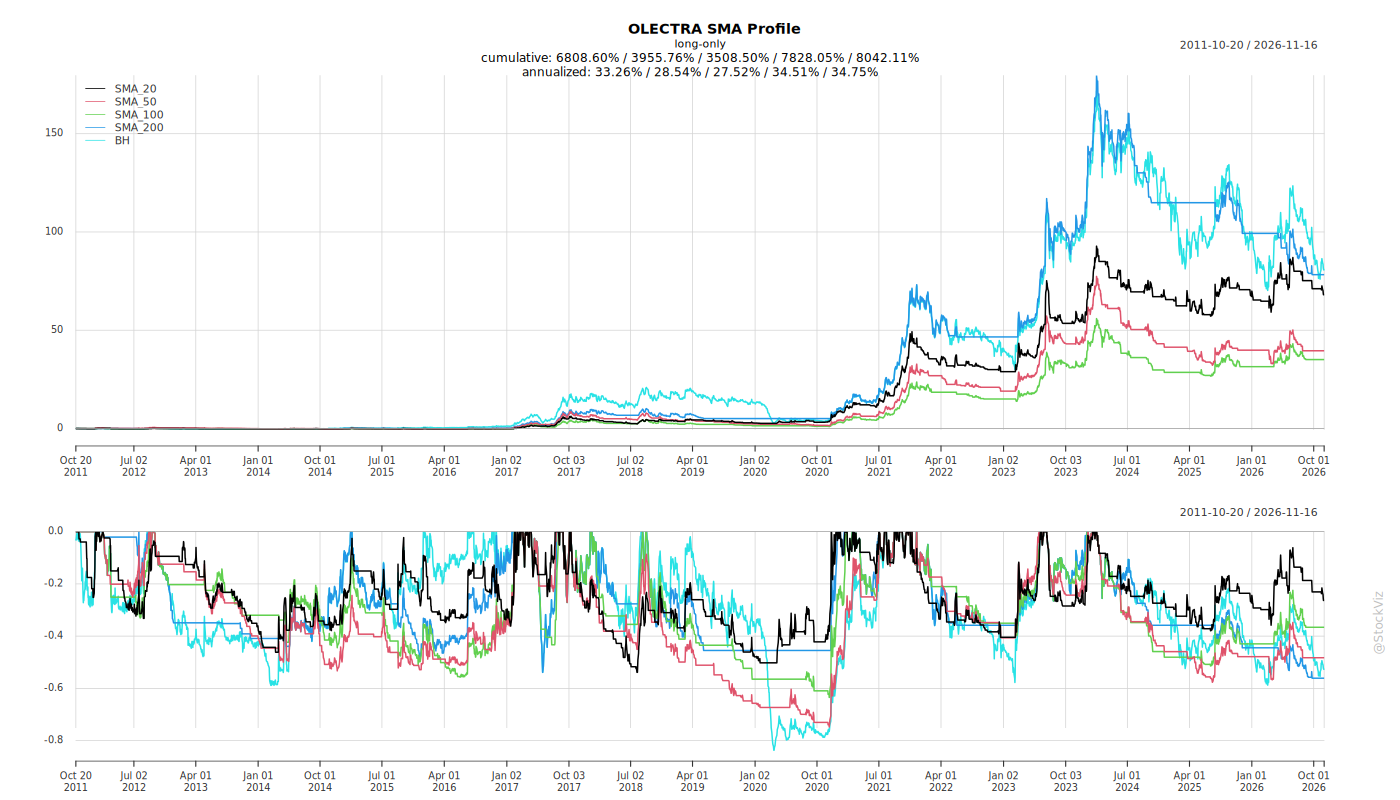
Fundamentals
Ownership
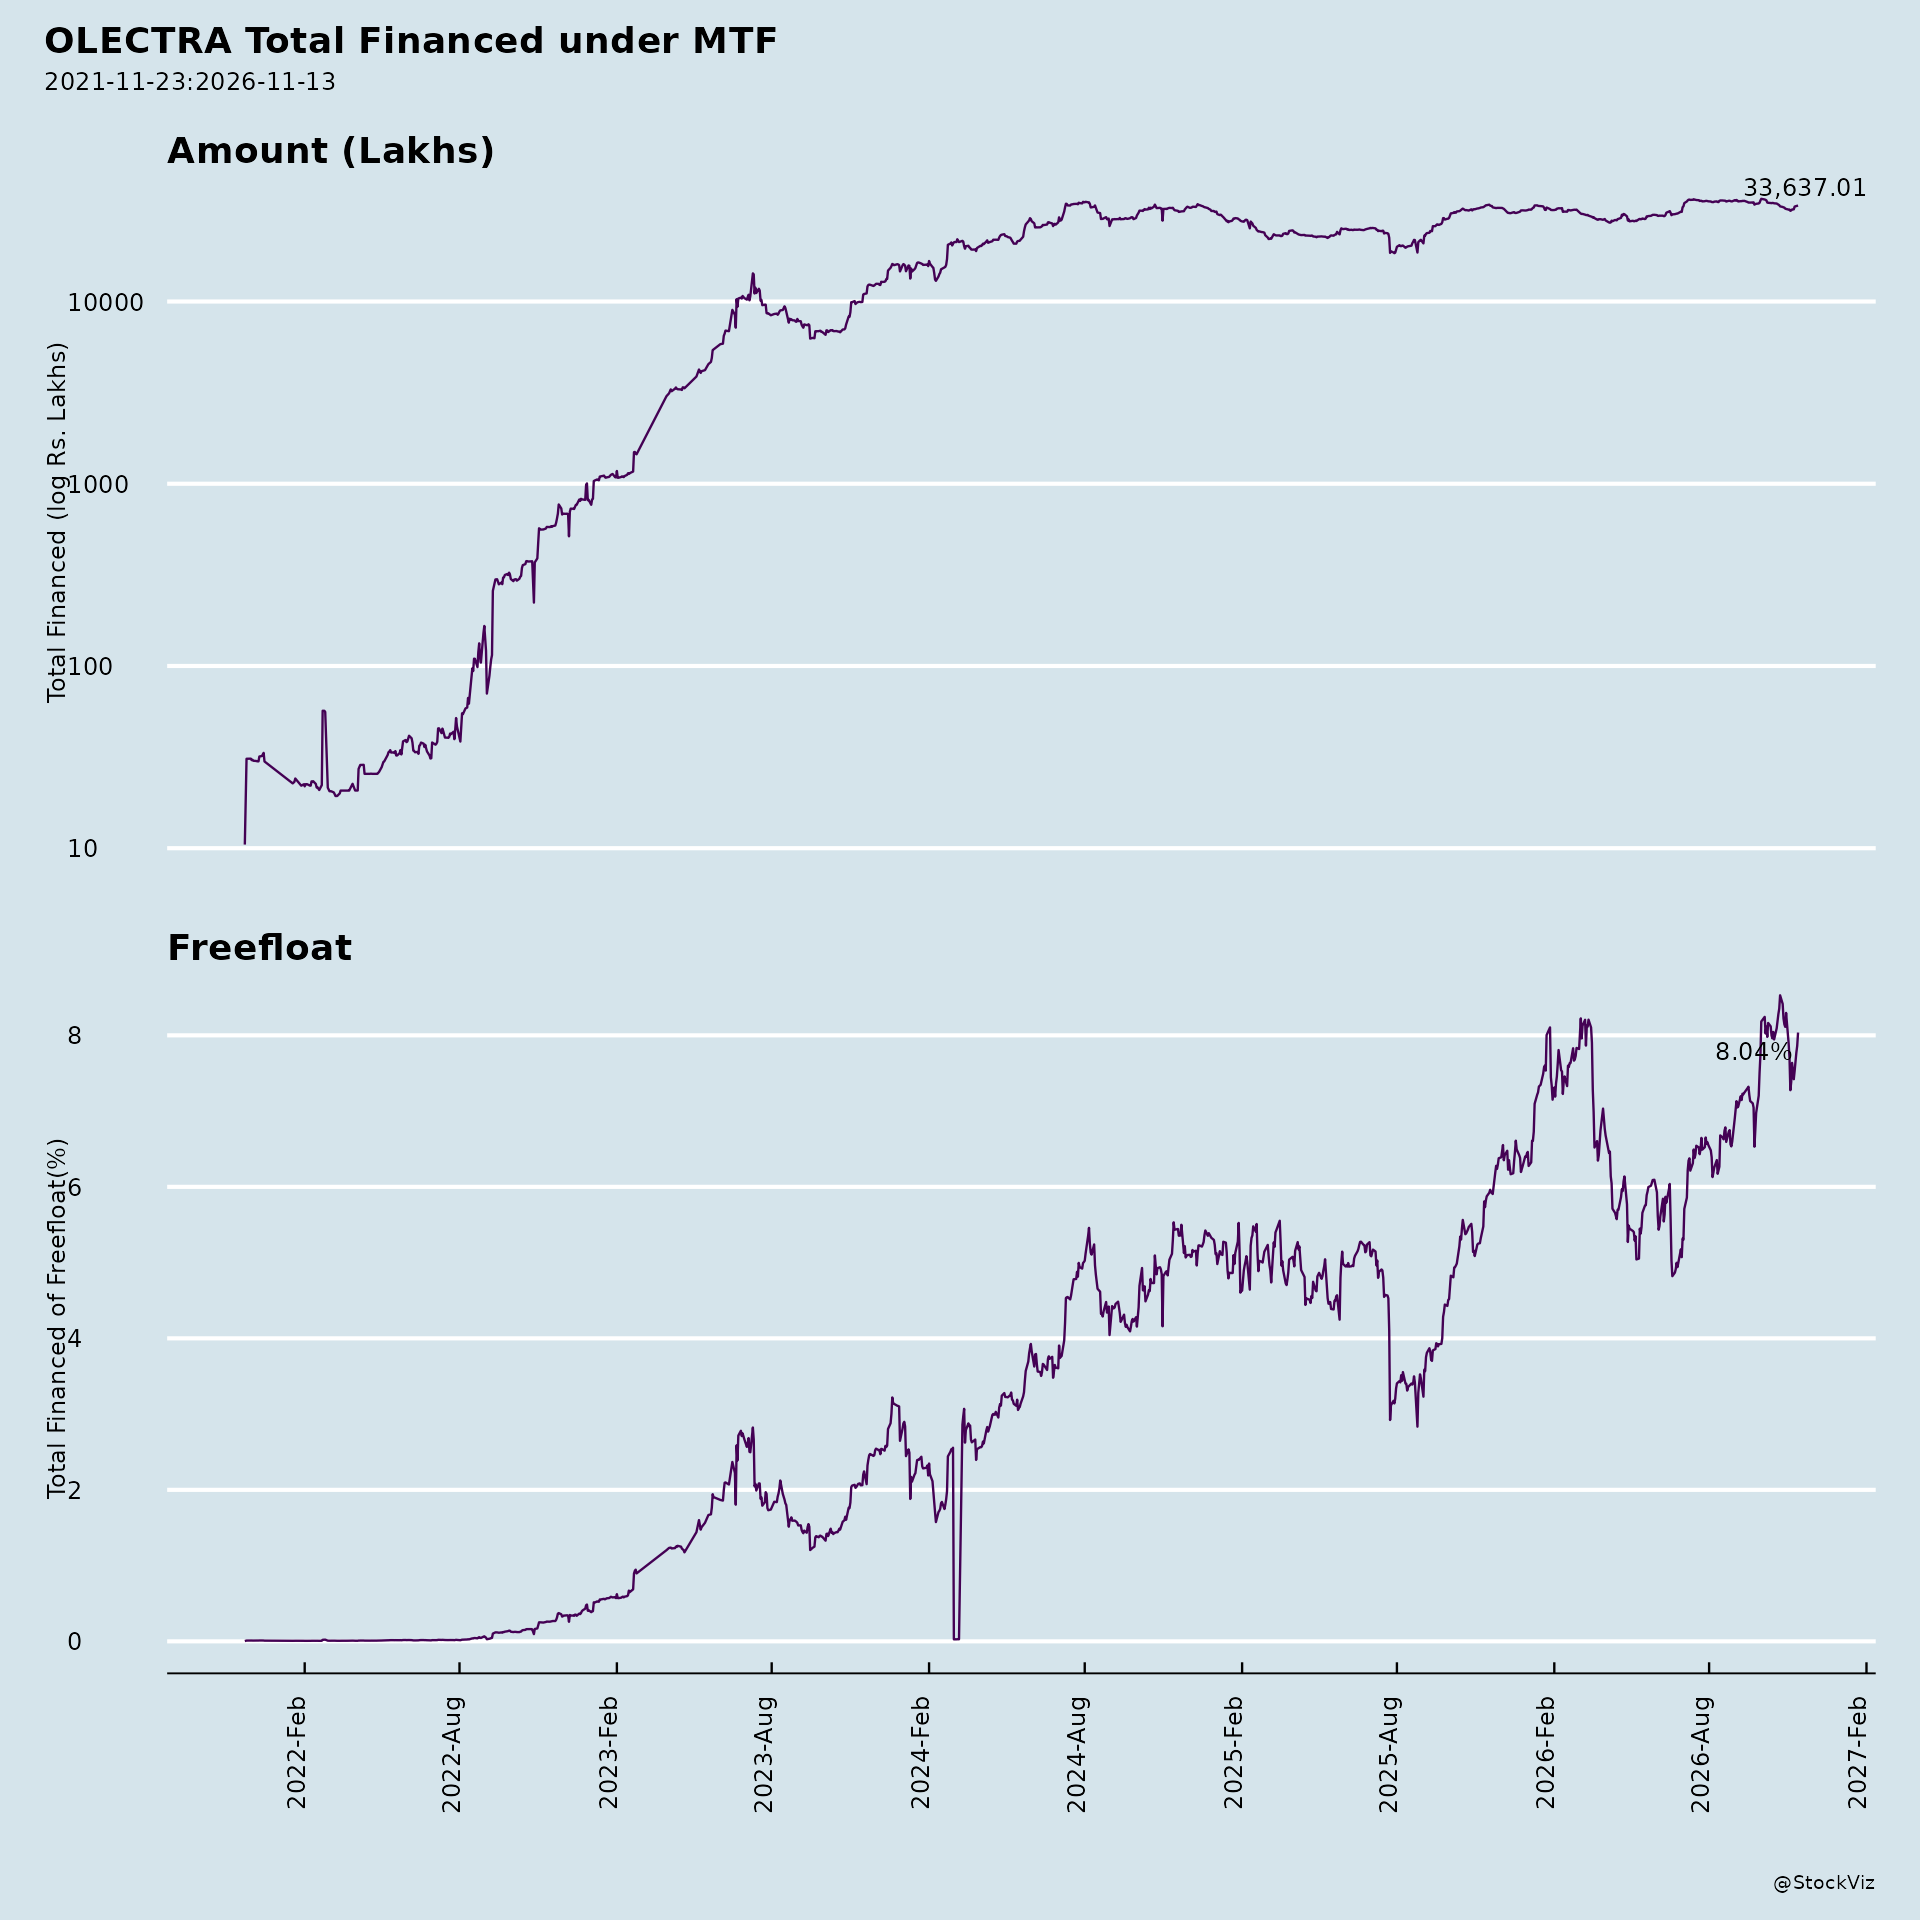
Margined
AI Summary
asof: 2026-09-17
Headwinds and Challenges
- The business is capital-intensive, requiring sustained investment in manufacturing capacity and working capital.
- Payments from State Transport Undertakings (STUs) under the GCC model can be delayed, tying up cash.
- Pricing is competitive and tender-driven, which can pressure margins.
- The company depends on supply chains for critical components such as battery cells and semiconductors.
- Availability of specialized skilled talent is a constraint.
- Competition is intensifying from both domestic and global players.
- Raw material prices — such as silicone rubber and FRP — are volatile.
- Government transmission project executions can be delayed, affecting the Energy Division.
- Geopolitical uncertainties and global market volatility pose external risks.
Tailwinds and Growth Prospects
- Electric bus adoption is rising, supported by government initiatives including PM E-DRIVE, PM e-Bus Sewa, FAME-II, and viability gap funding.
- Rapid urbanization and public transport electrification are expanding the addressable market.
- Improving total cost of ownership (TCO) economics favor electric buses.
- Addressable markets are expanding into private intercity transportation, corporate mobility, airport shuttles, and Tier-2/Tier-3 cities.
- Large STU fleet replacement opportunities remain.
- Growth in power transmission and railway electrification is driving insulator demand for the Energy Division.
- Ongoing R&D and product portfolio expansion include electric trucks and tippers.
- Export market expansion is a further opportunity.
Key Risks
- Capital-intensive requirements and delayed STU payments under the GCC model could strain liquidity.
- Competitive, tender-driven pricing could erode profitability.
- Supply chain dependencies on battery cells and semiconductors could disrupt production.
- Intensifying competition from domestic and global players could affect market share.
- Raw material price volatility (silicone rubber, FRP) could impact costs.
- Delays in government transmission project executions could affect the Energy Division.
- Geopolitical uncertainties and global market volatility add external risk.
Management Guidance vs. Observed Business Performance
- Management anticipates accelerated industry growth as EV bus adoption crosses the 10–15% threshold.
- Strategic plans include launching a new electric bus platform designed to meet PM E-Drive requirements in Q3 FY27.
- Management targets a commercial launch of an indigenous electric truck platform in Q4 FY27, with a production target of approximately 2,500 electric vehicles by FY27.
- Plans also include expanding manufacturing capacities, scaling deliveries, and continuing disciplined capital allocation to maintain industry leadership.
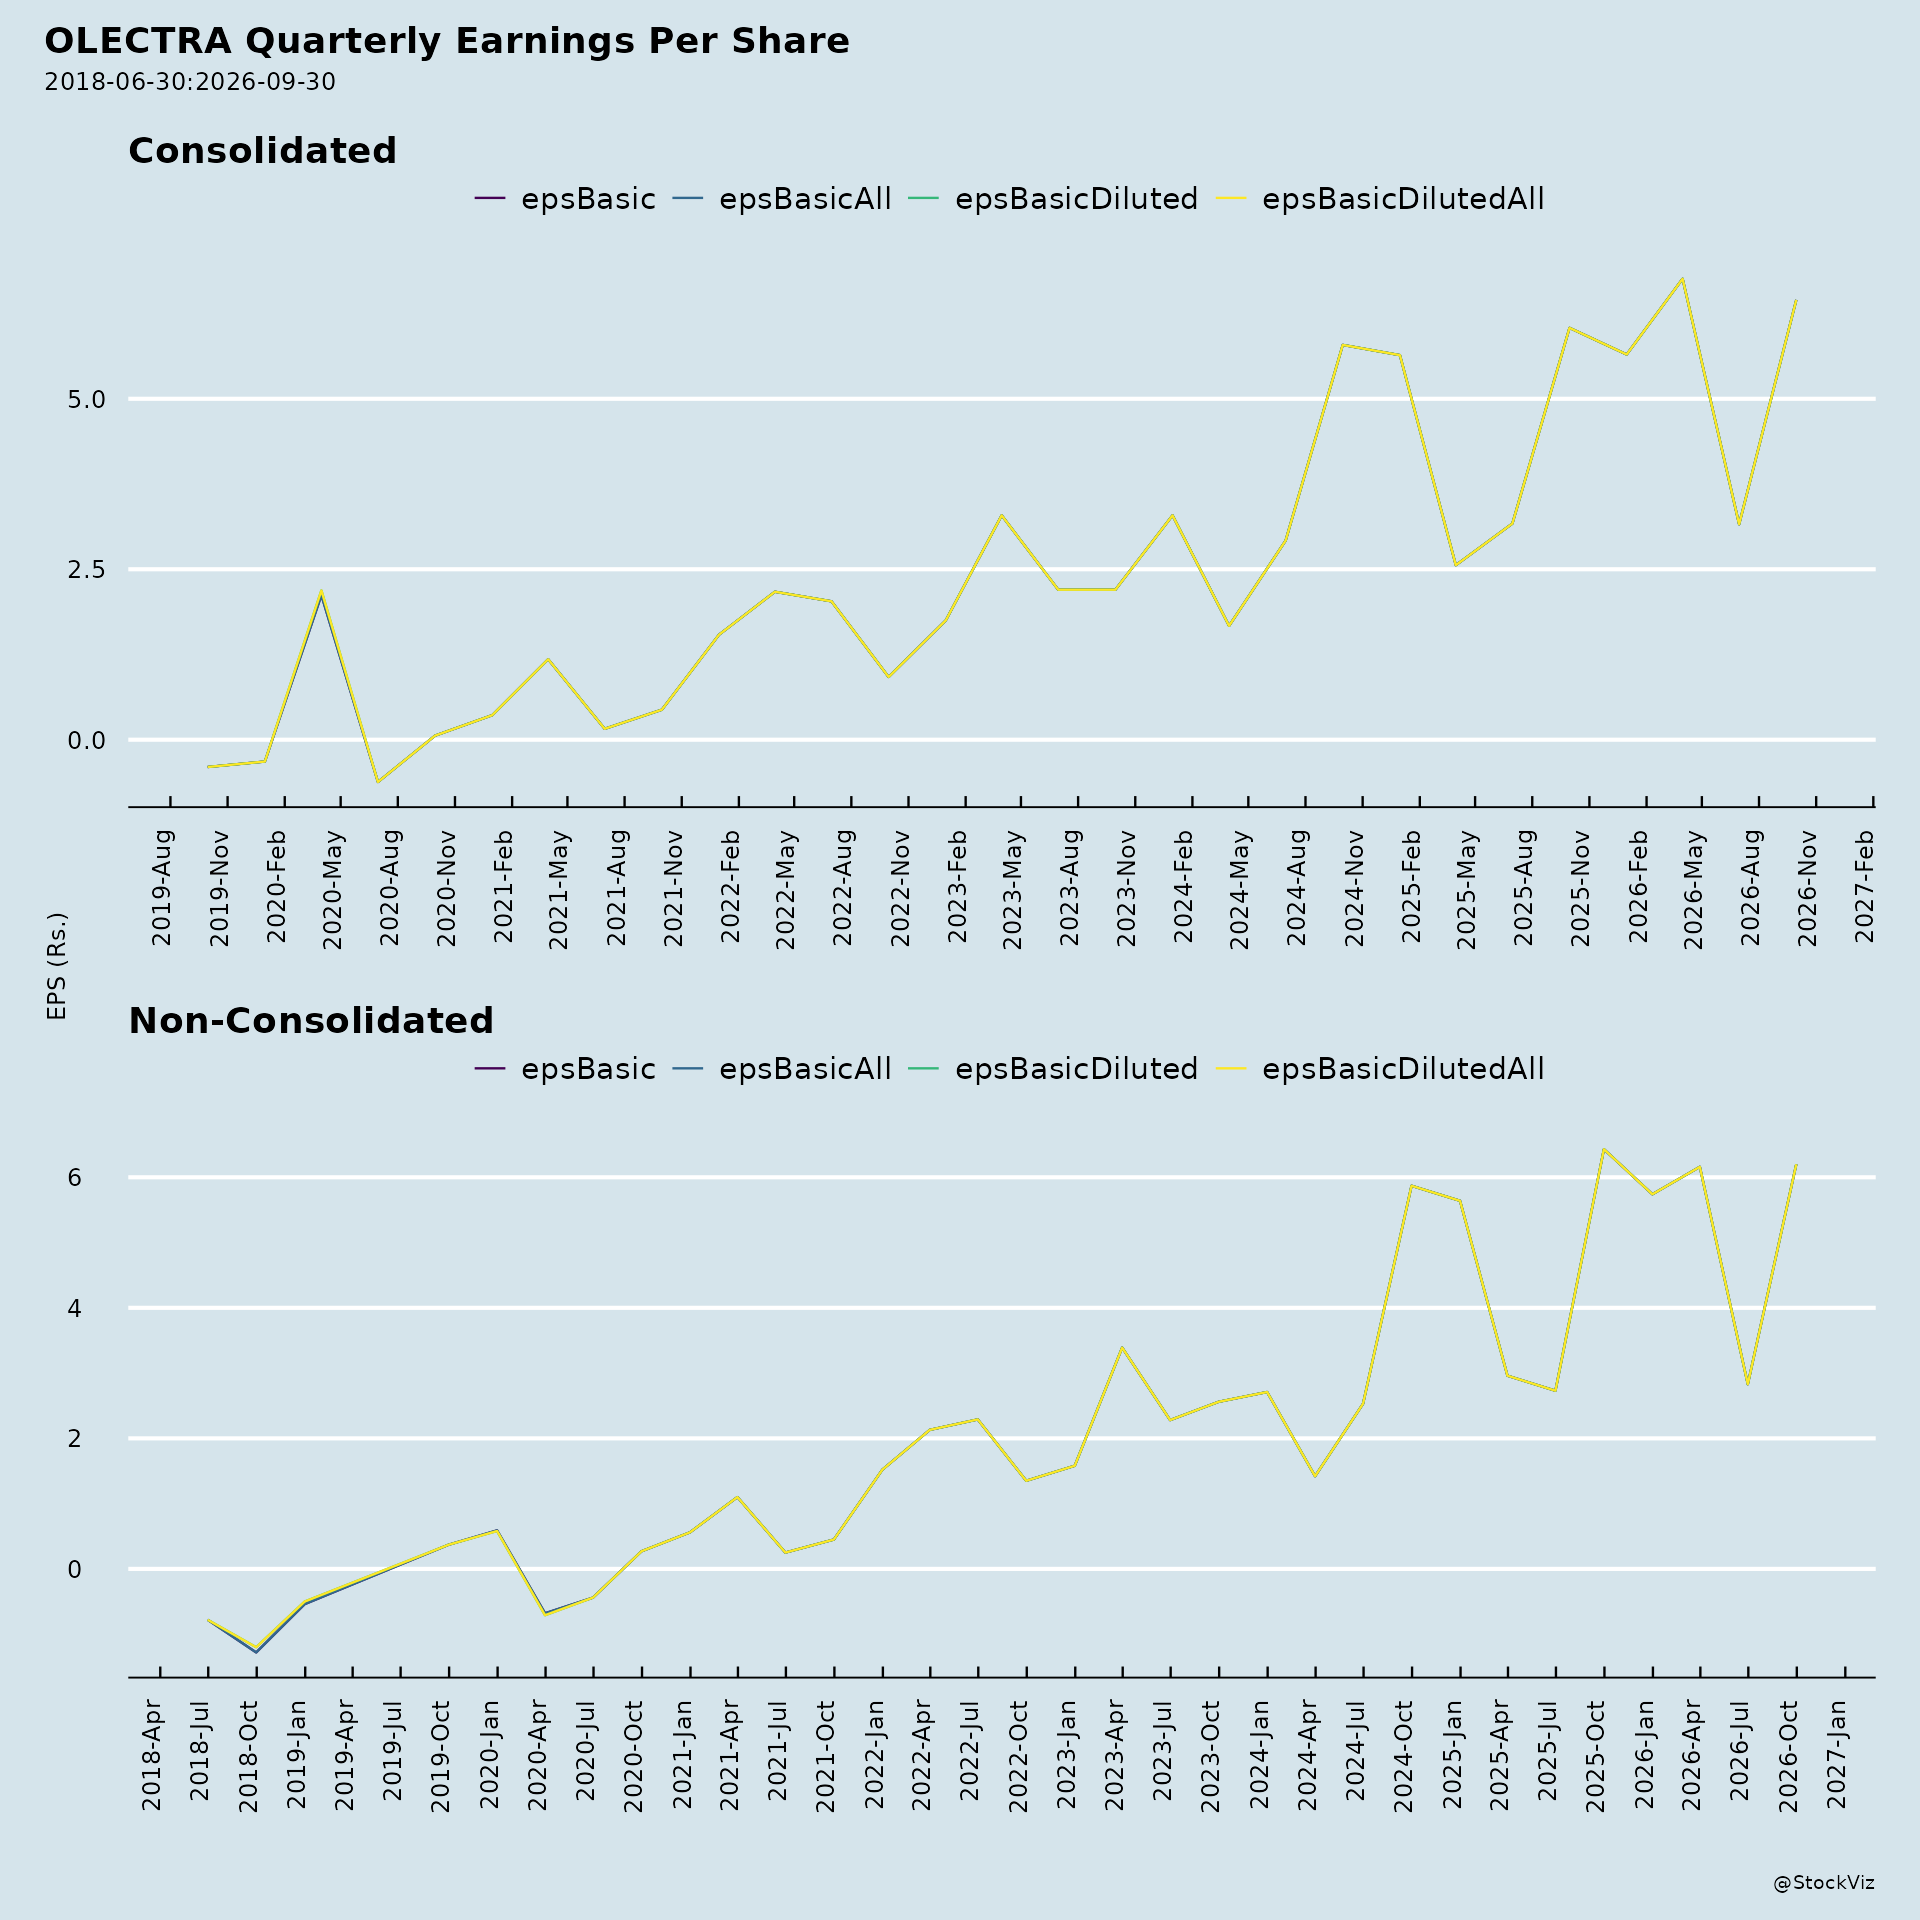
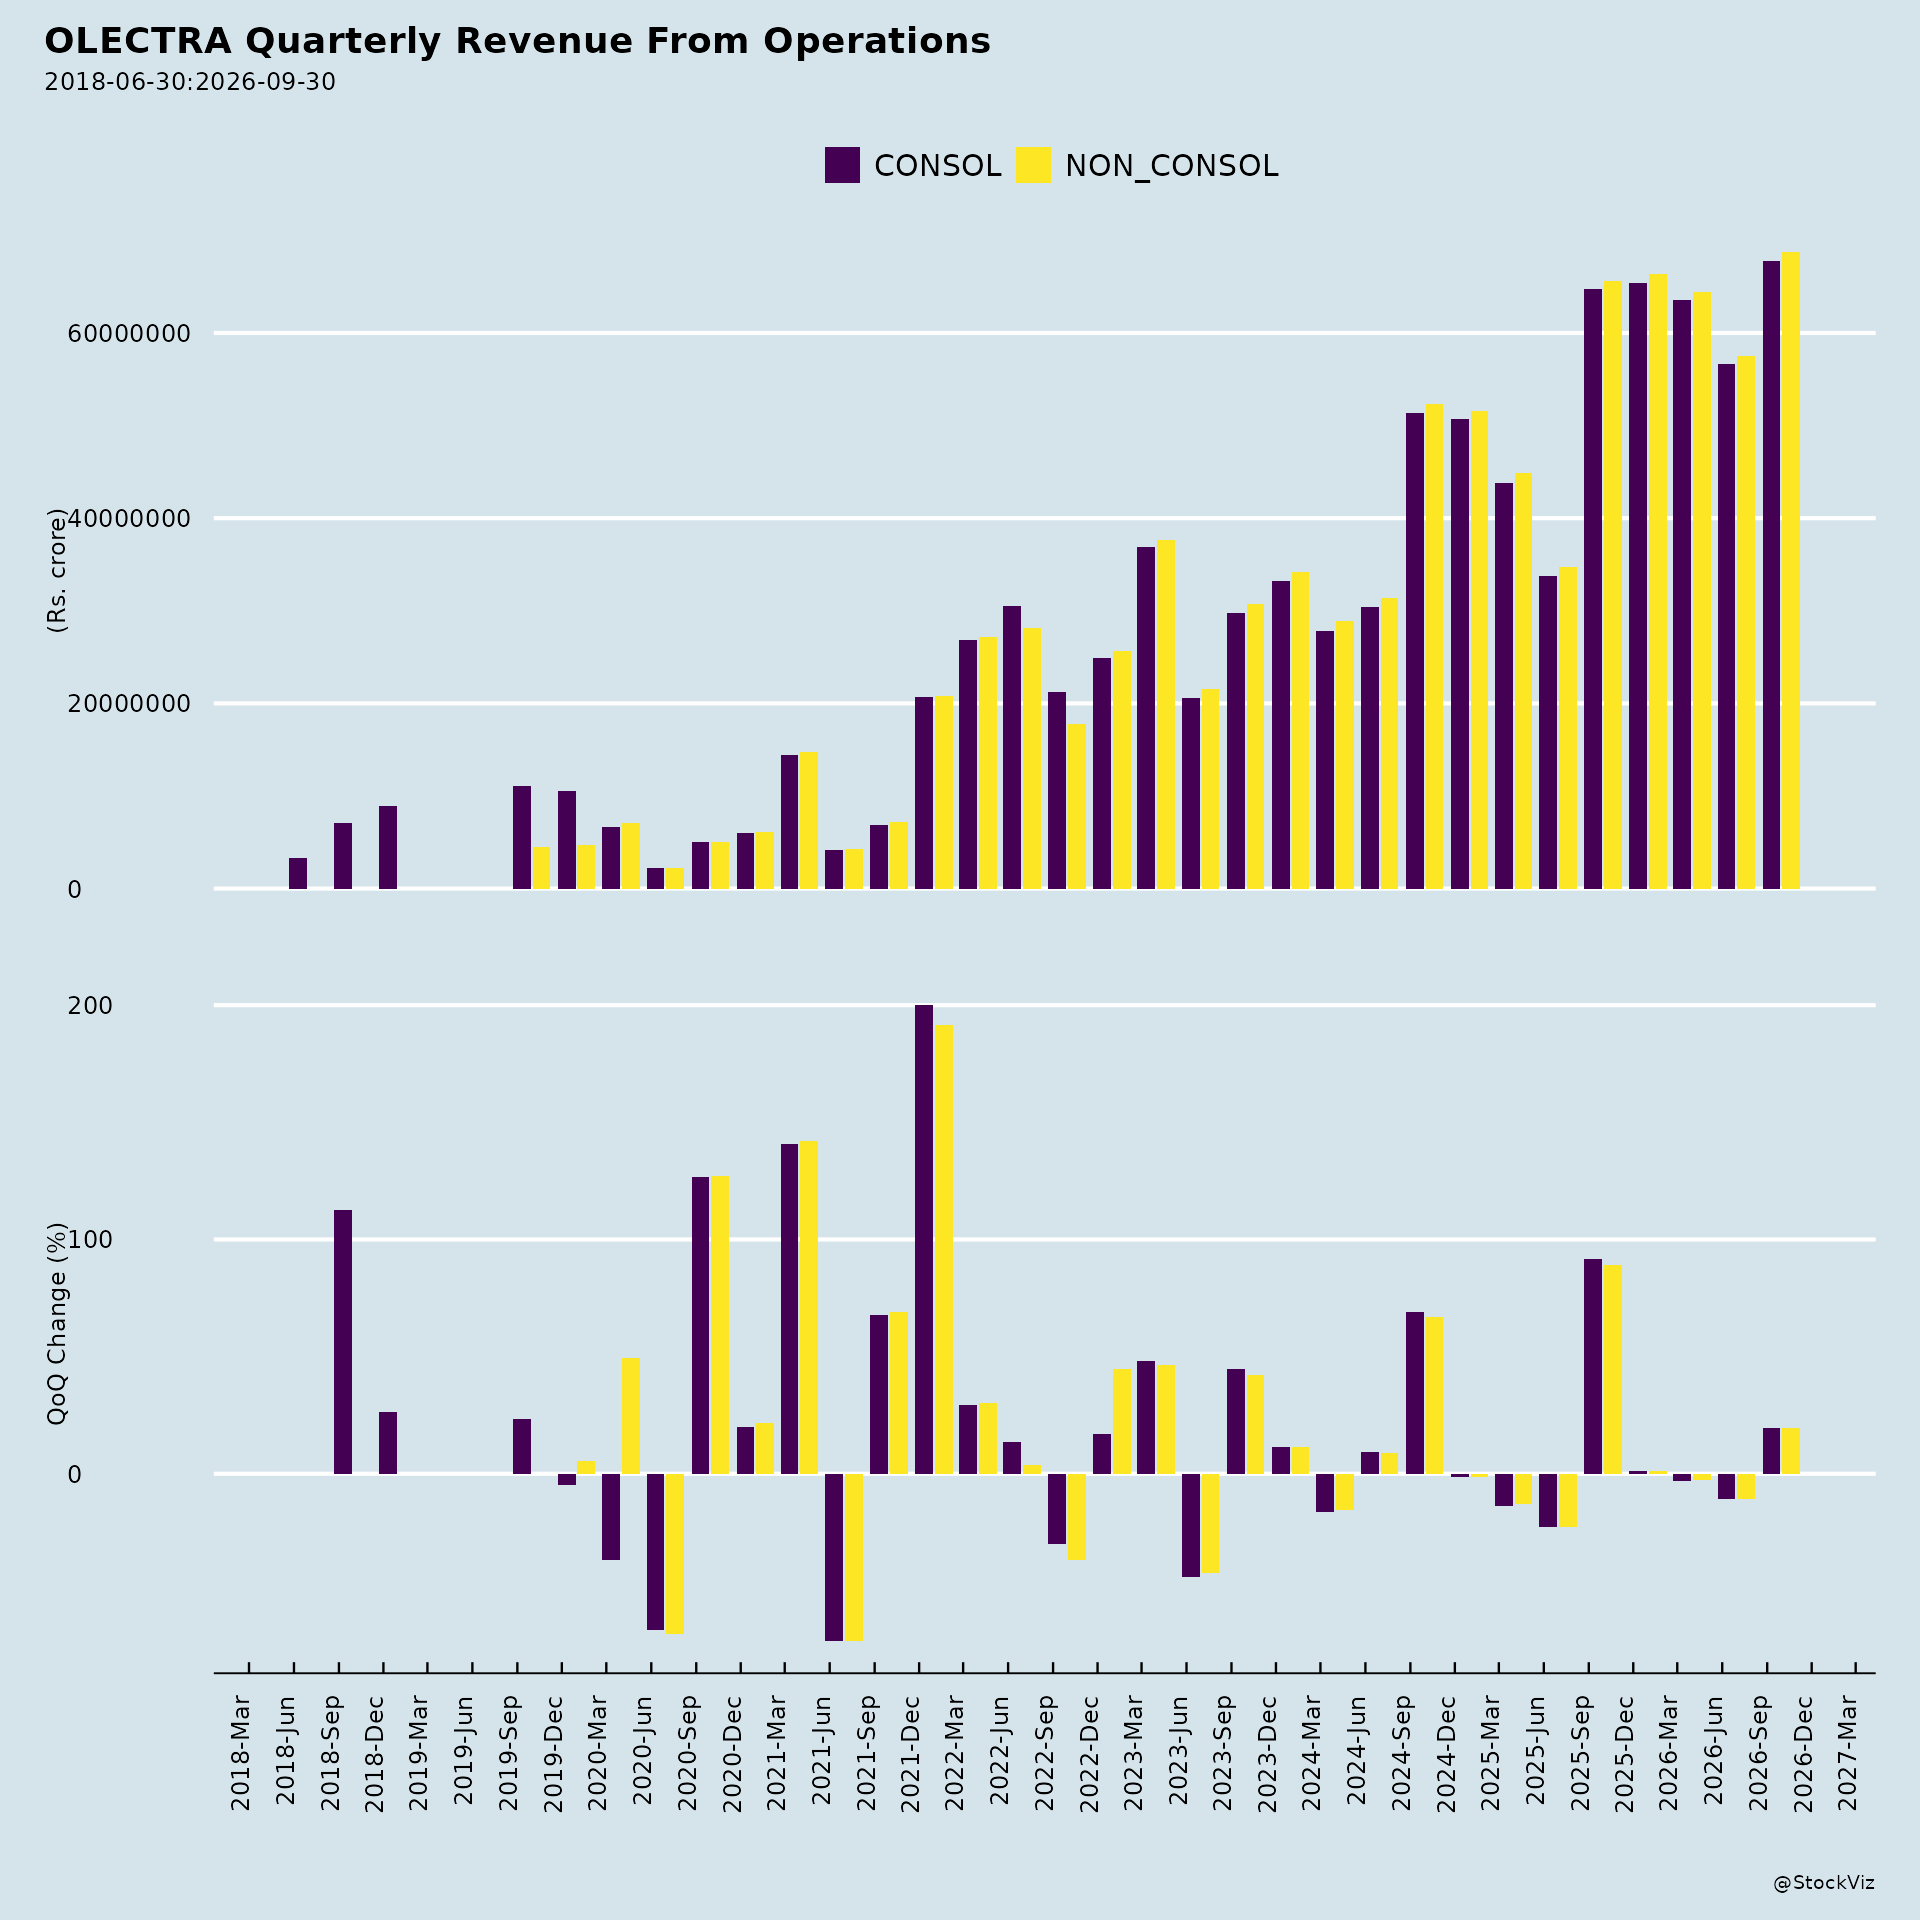
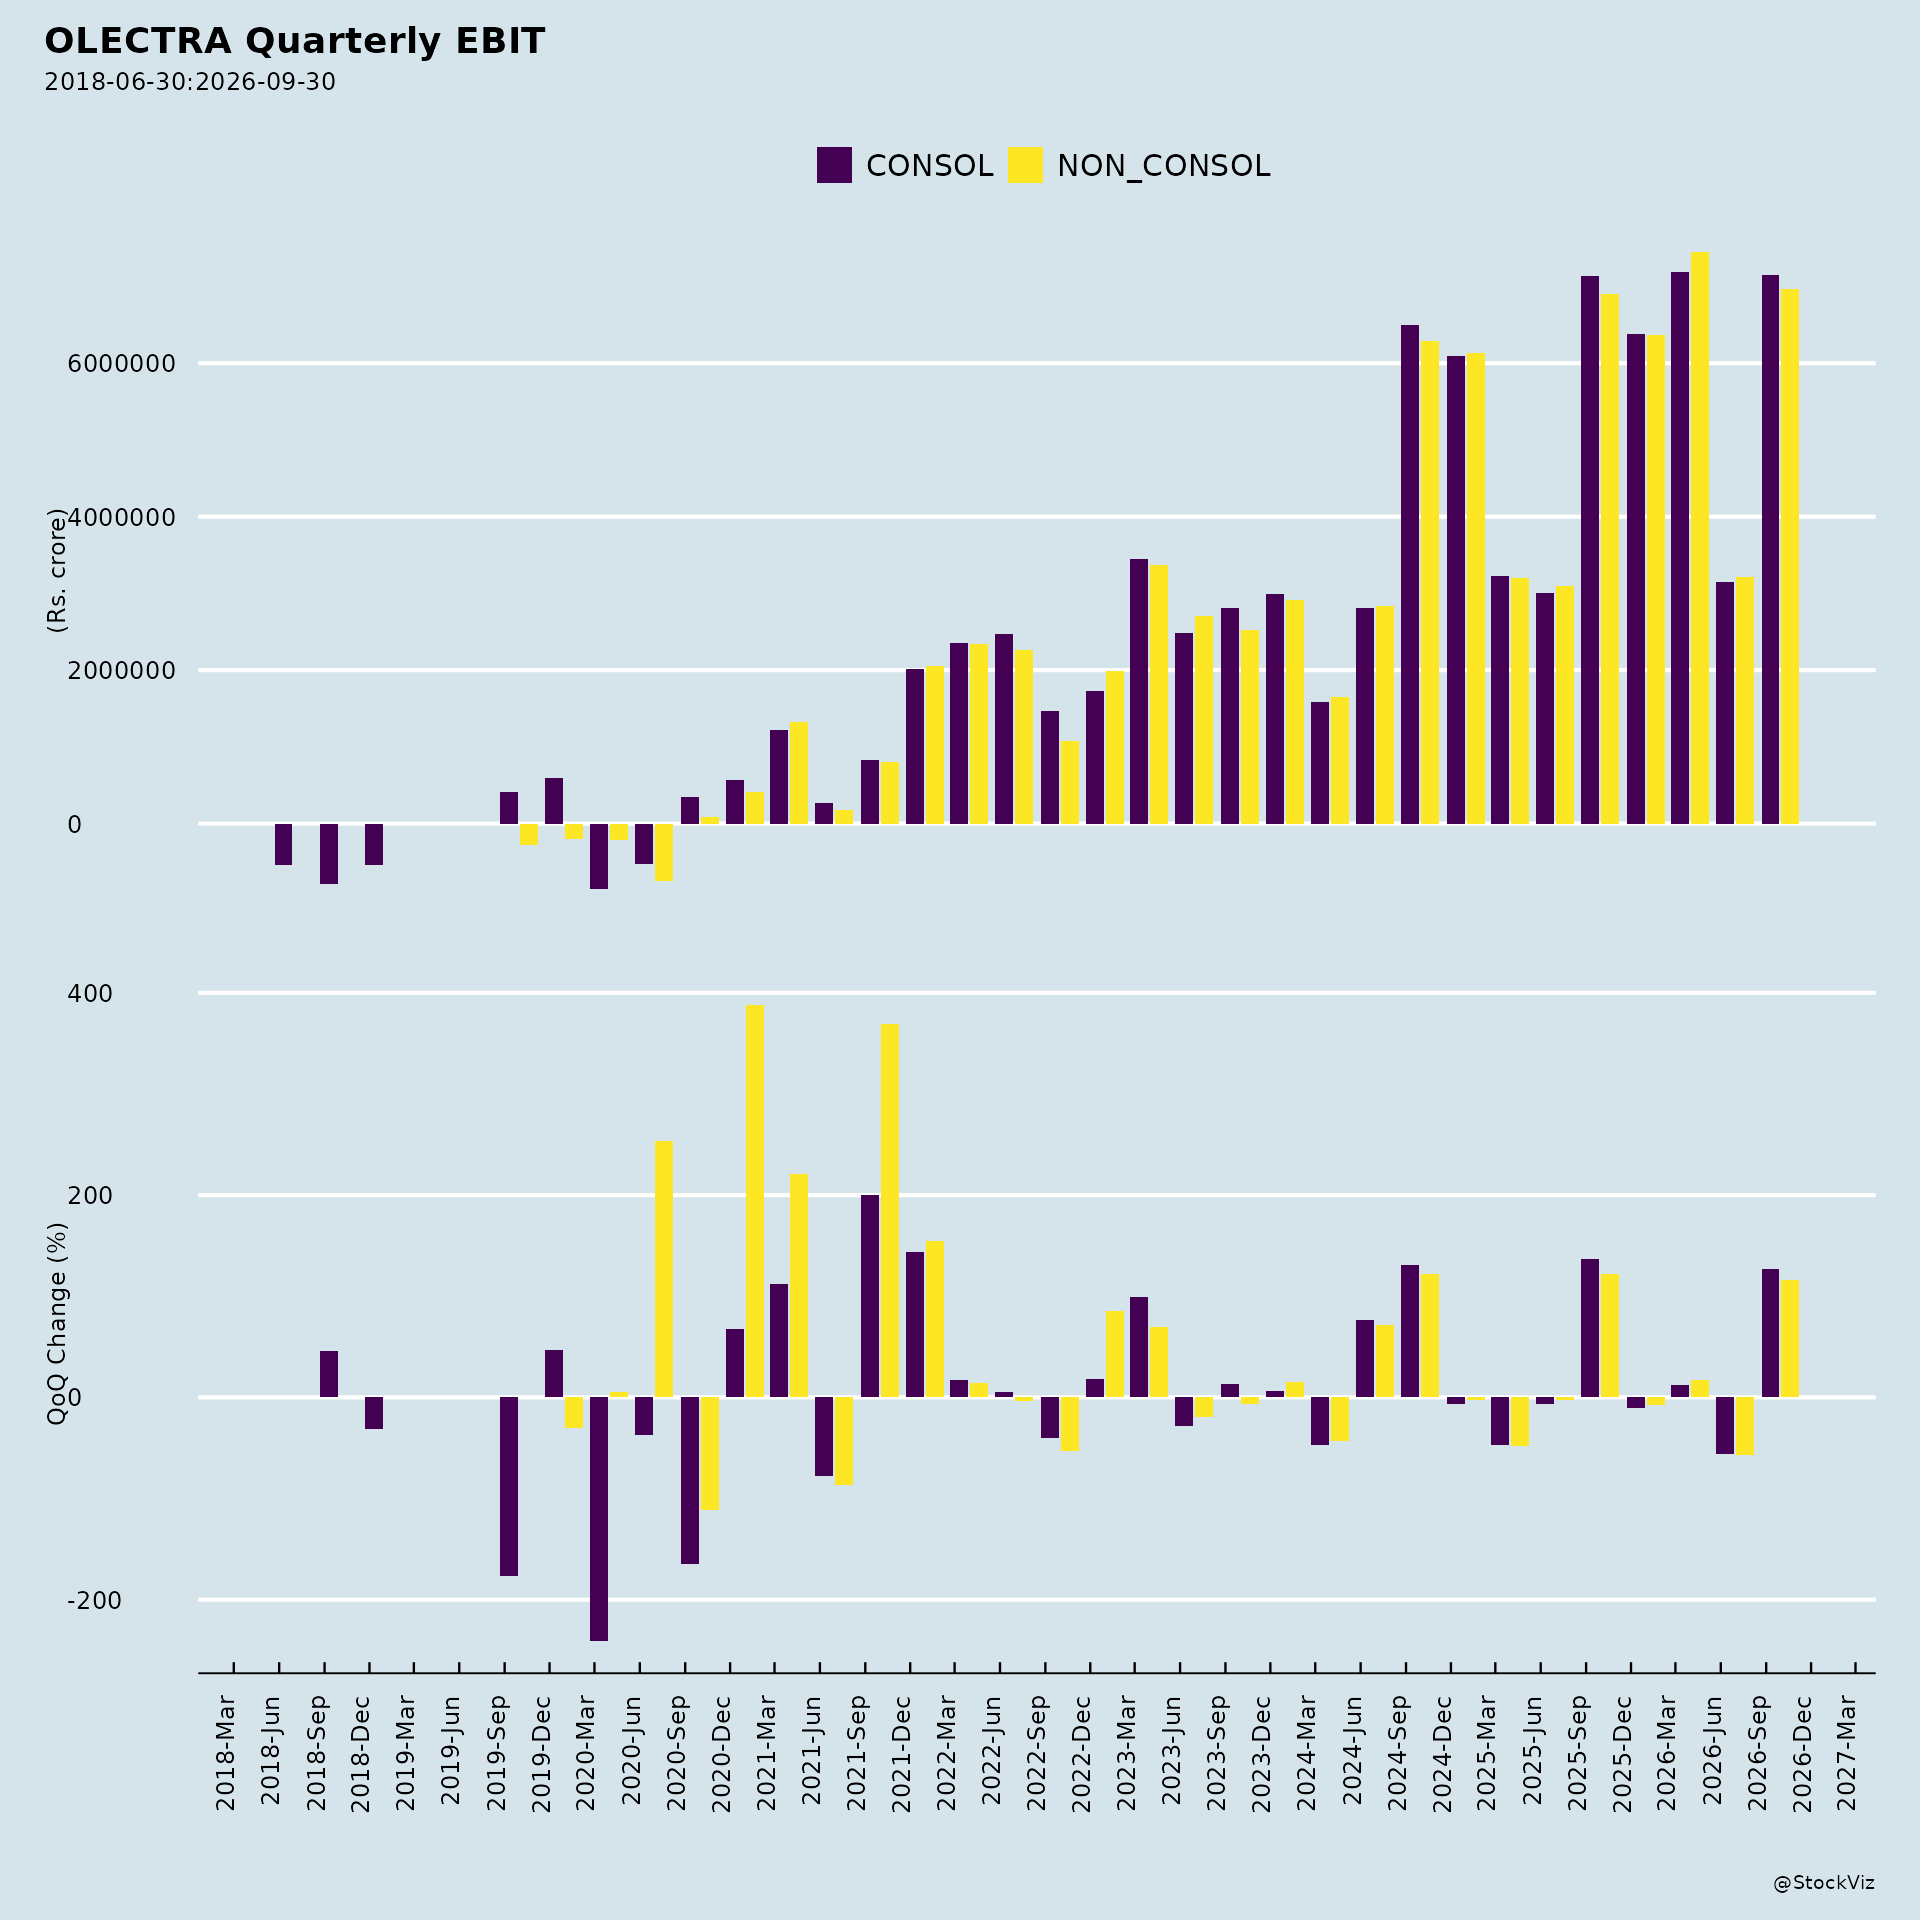
- Observed performance for the first quarter ended June 30, 2026: standalone revenue from operations was ₹56,664.40 lakhs, with net profit after tax of ₹2,319.43 lakhs; consolidated revenue from operations was ₹57,550.64 lakhs, with net profit after tax of ₹2,666.32 lakhs.
- For FY26 (year ended March 31, 2026), consolidated revenue reached ₹2,312.17 crores (a 28% increase), adjusted EBITDA was ₹352.28 crores, PAT increased to ₹179.53 crores, vehicle deliveries grew 32% to 1,280 units, and the order book stood at around 10,000 buses.
- The Seetharampur greenfield manufacturing facility phase-1 commenced commercial operation.
- A final dividend of 15% (₹0.60 per equity share) was recommended.
- The company reported a market share of over 20% in India’s electric bus market.
- A conference call with investors was held on 17th August, 2026, regarding the unaudited financial results for the first quarter ended 30th June, 2026, and the transcript was made available on the company website.
CNBC-TV18: ratings, targets and commentary
No recorded CNBC-TV18 statements for this ticker.
Management comments
No recorded management comments with an explicit designation and affiliation for this ticker.
Copyright © 2023 SAS Data Analytics Pvt. Ltd. All rights reserved.