OFSS
Equity Metrics
October 23, 2026
Oracle Financial Services Software Limited
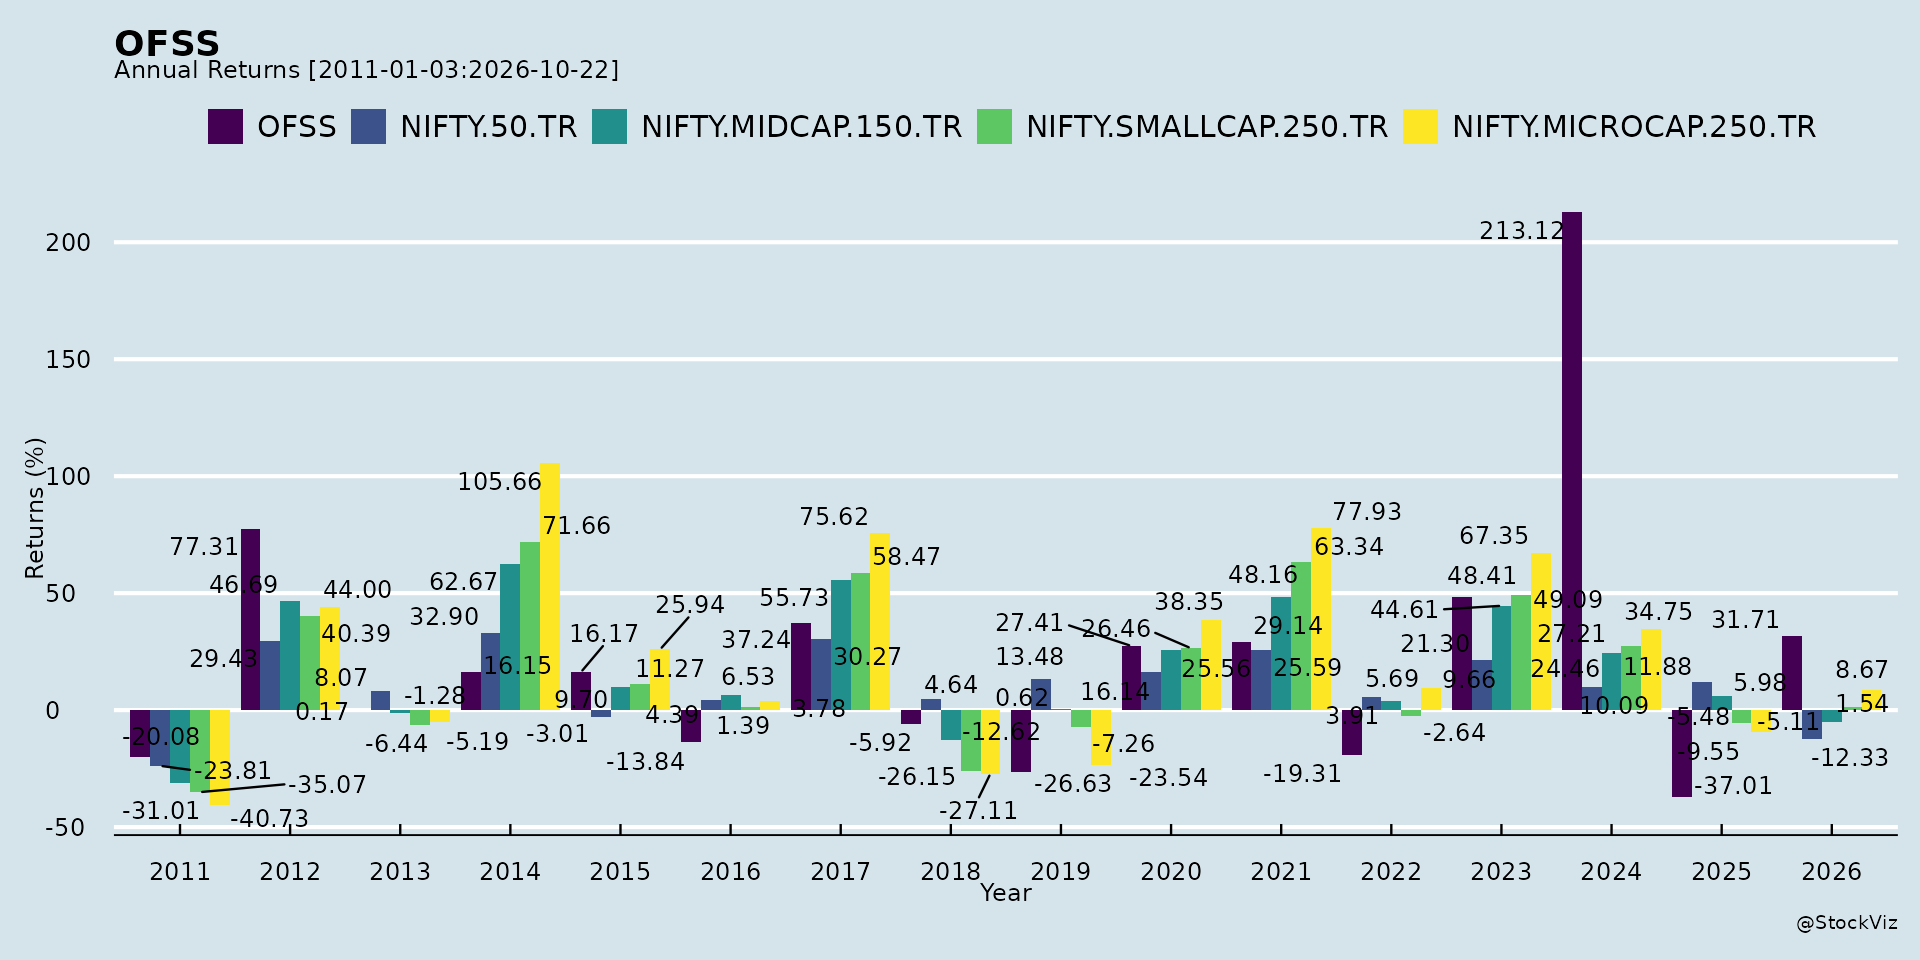
Annual Returns
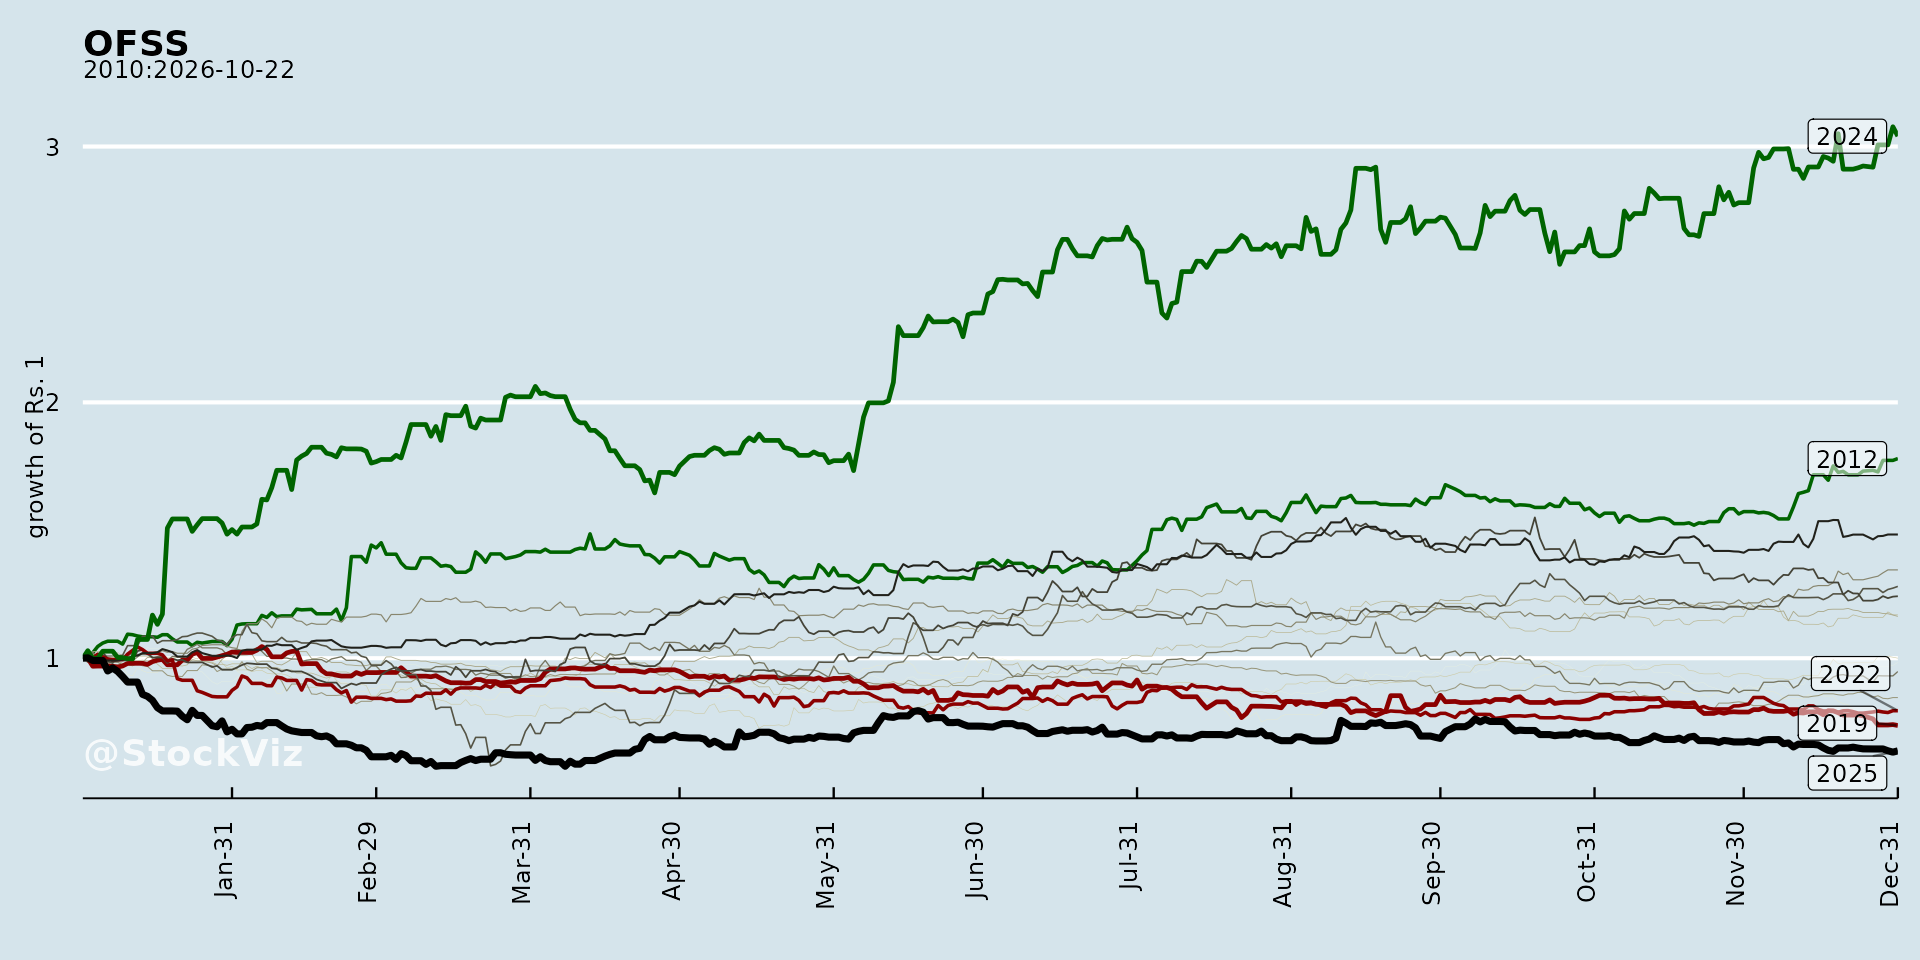
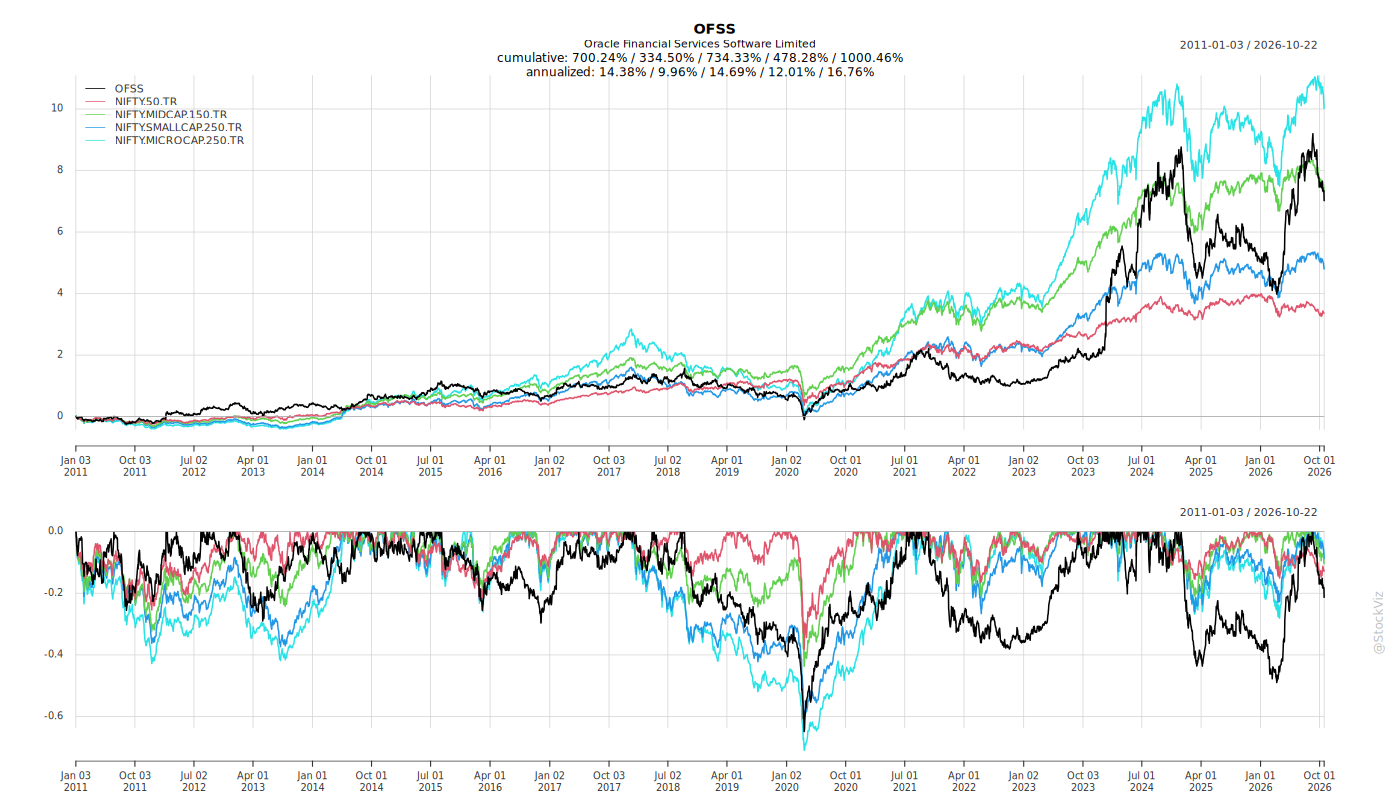
Cumulative Returns and Drawdowns
Fundamentals
Ownership
Margined
AI Summary
asof: 2026-09-14
OFSS Q1 FY2026-27: Results, Leadership Transition, and Governance Developments
1. Headwinds and Challenges
Services segment weakness. The Services business posted revenue of Rs. 189 Crore, up only 6% year-on-year, and its segment result fell 29% year-on-year (from Rs. 542 million to Rs. 383 million). Sequentially, Services revenue declined 3% and its segment result fell 42% (from Rs. 663 million to Rs. 383 million). This contrasts sharply with the Products business, which grew 75% year-on-year.
Europe sequential decline. Europe revenue fell 22% quarter-on-quarter (from Rs. 4,018 million to Rs. 3,149 million), even though it grew 27% year-on-year.
Elevated employee costs, including severance. Consolidated employee benefit expenses rose to Rs. 10,753 million from Rs. 8,390 million a year earlier. This included employee severance expenses of Rs. 1,782 million in the quarter. Standalone employee benefit expenses included severance of Rs. 1,151 million. The company also recorded a provision of Rs. 268 million (consolidated) for employee benefits related to The New Labour Code notified on November 21, 2025.
Unallocable expenses rising. Unallocable expenses increased 54% year-on-year and 111% sequentially, to Rs. 725 million.
Leadership transition. Mr. Makarand Padalkar resigned as Managing Director & CEO effective end of day July 23, 2026, and ceased to be Chairperson/member of respective Board committees. Mr. Avadhut Ketkar, previously CFO, was appointed MD & CEO effective July 24, 2026 for three consecutive years up to July 23, 2029, subject to shareholder approval. Mr. Manish Bhandari, previously Chief Accounting Officer, was appointed CFO effective July 24, 2026. Mr. Andrew Mark Morawski was appointed an Additional Director (Non-Executive, Non-Independent) effective July 22, 2026, subject to shareholder approval.
Concentration in the Americas. Americas revenue rose to 55% of total revenue (from 38% a year earlier), increasing dependence on a single geography.
Forward-looking statement risk. The company’s safe harbor statement notes that statements relating to future plans and prospects are subject to material risks and uncertainties, and that many factors could cause actual results to differ materially.
2. Tailwinds and Growth Prospects
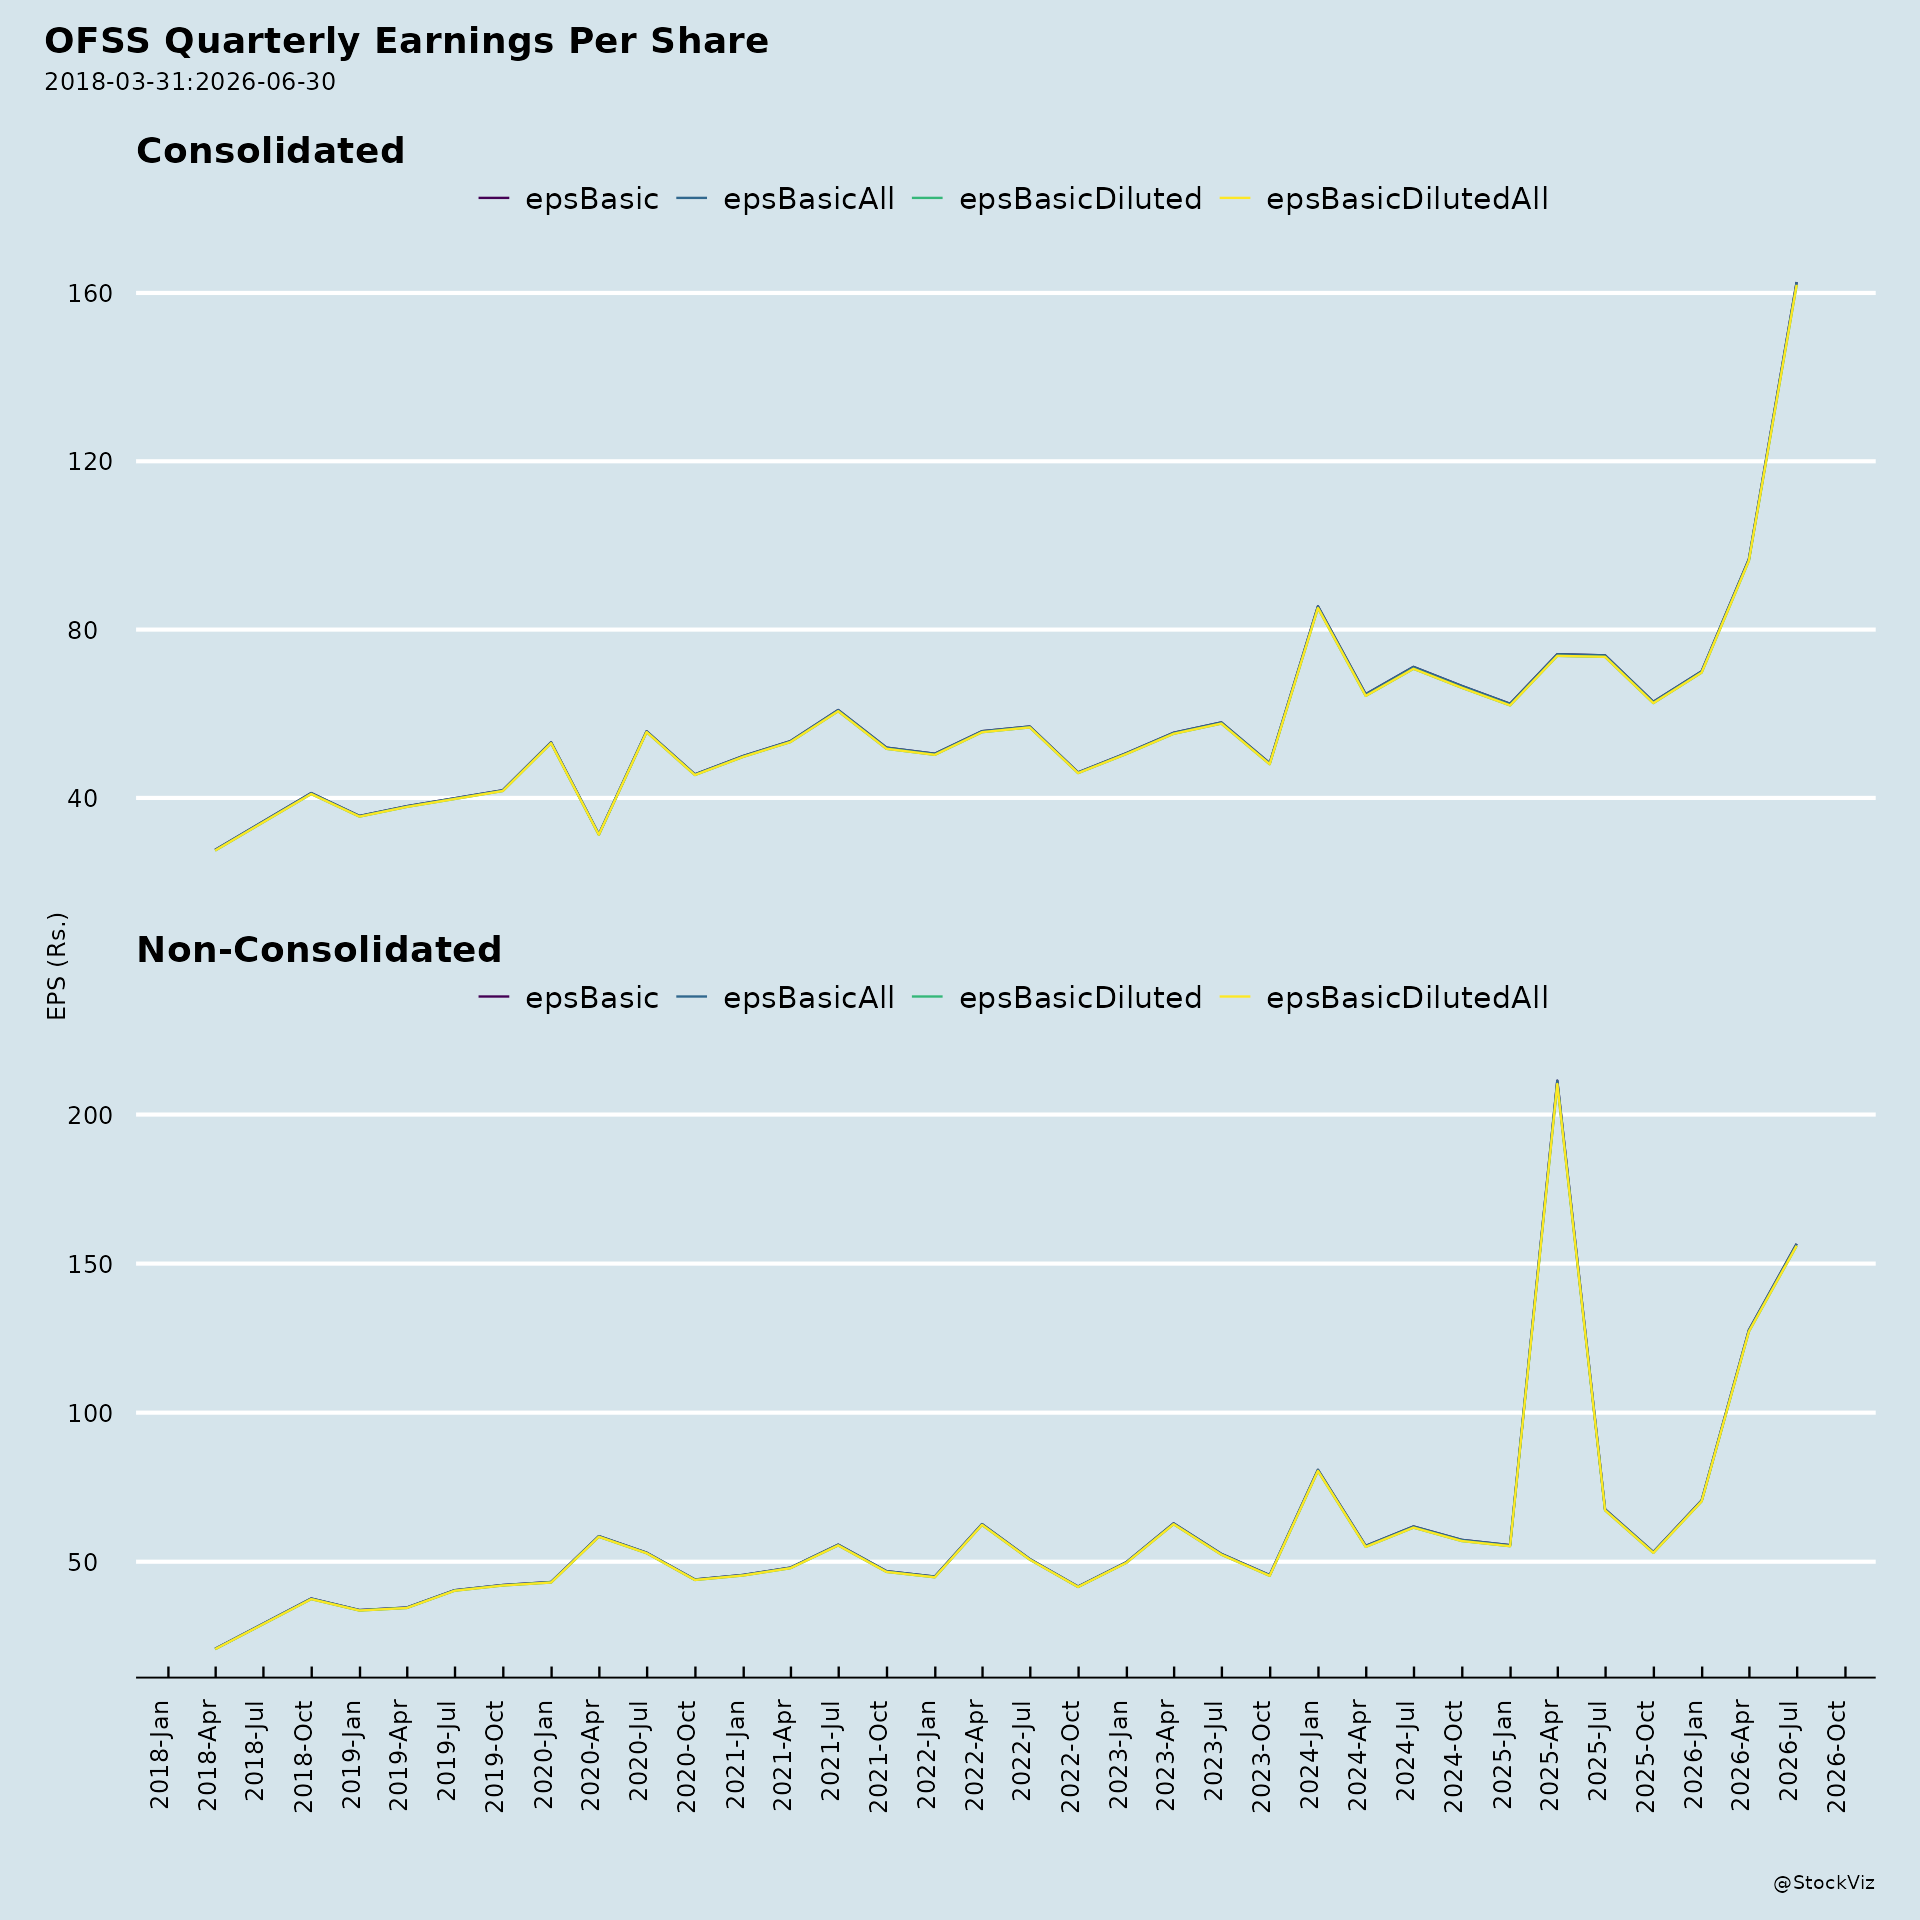
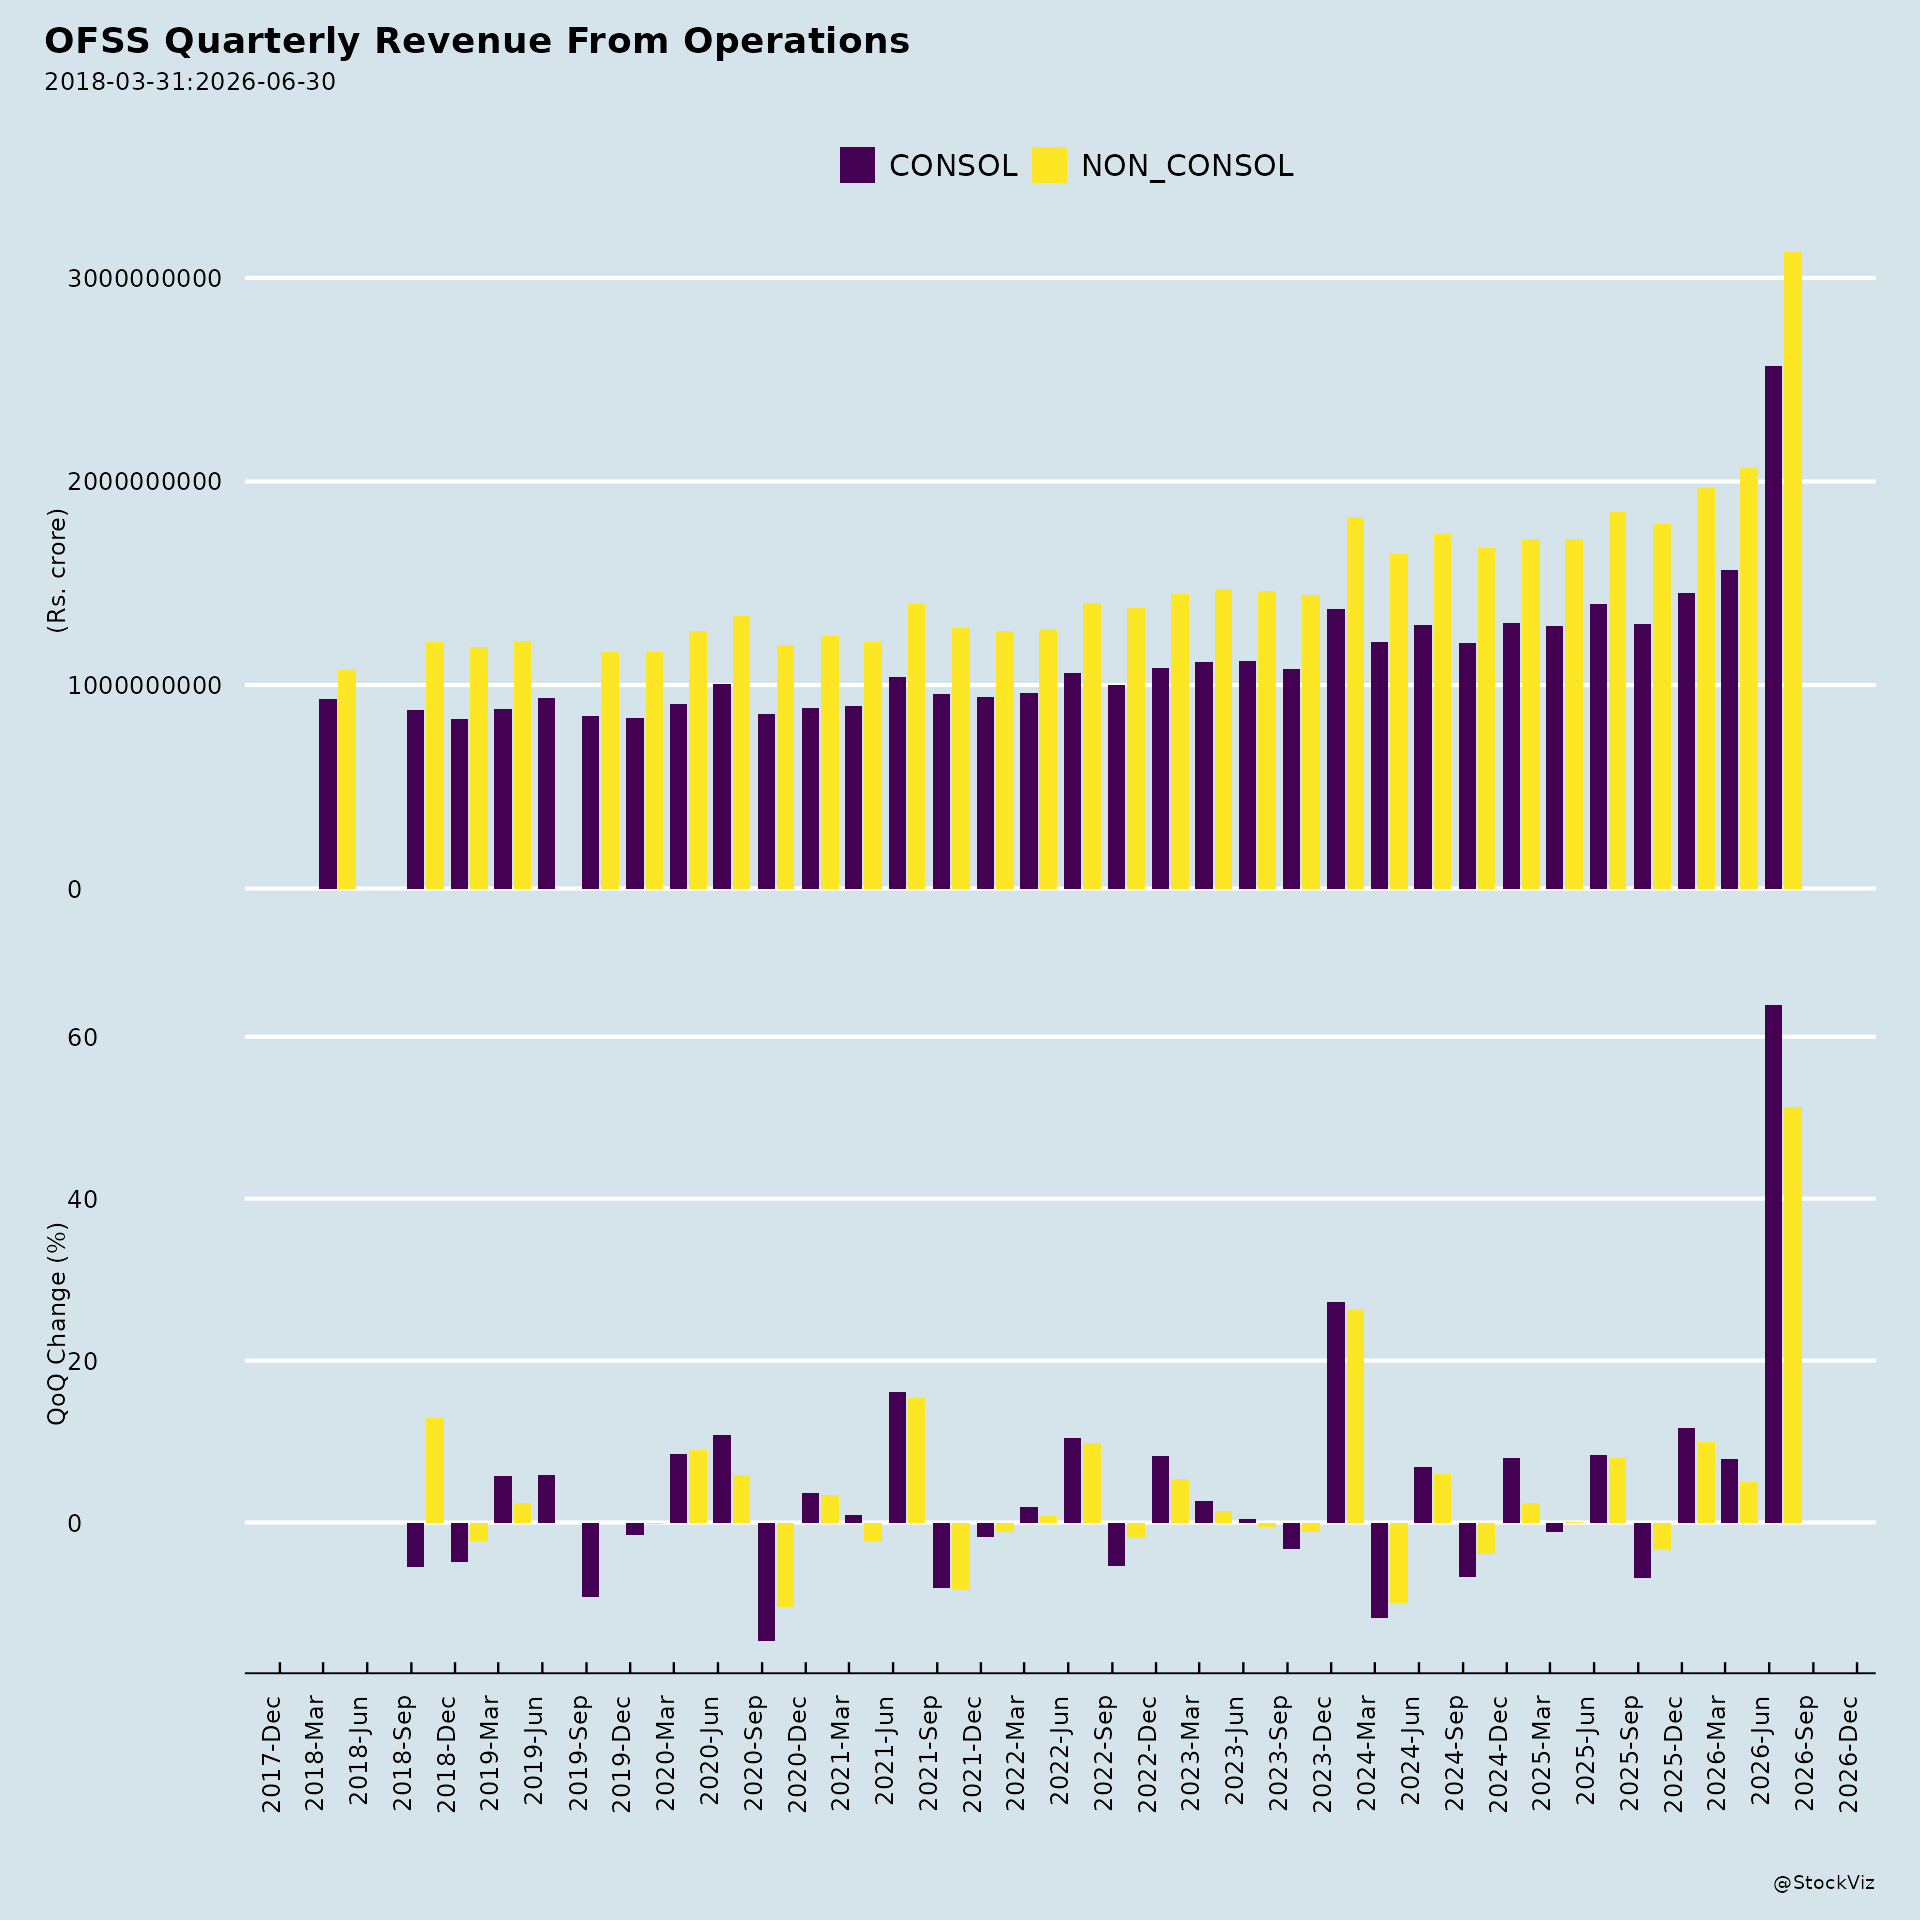
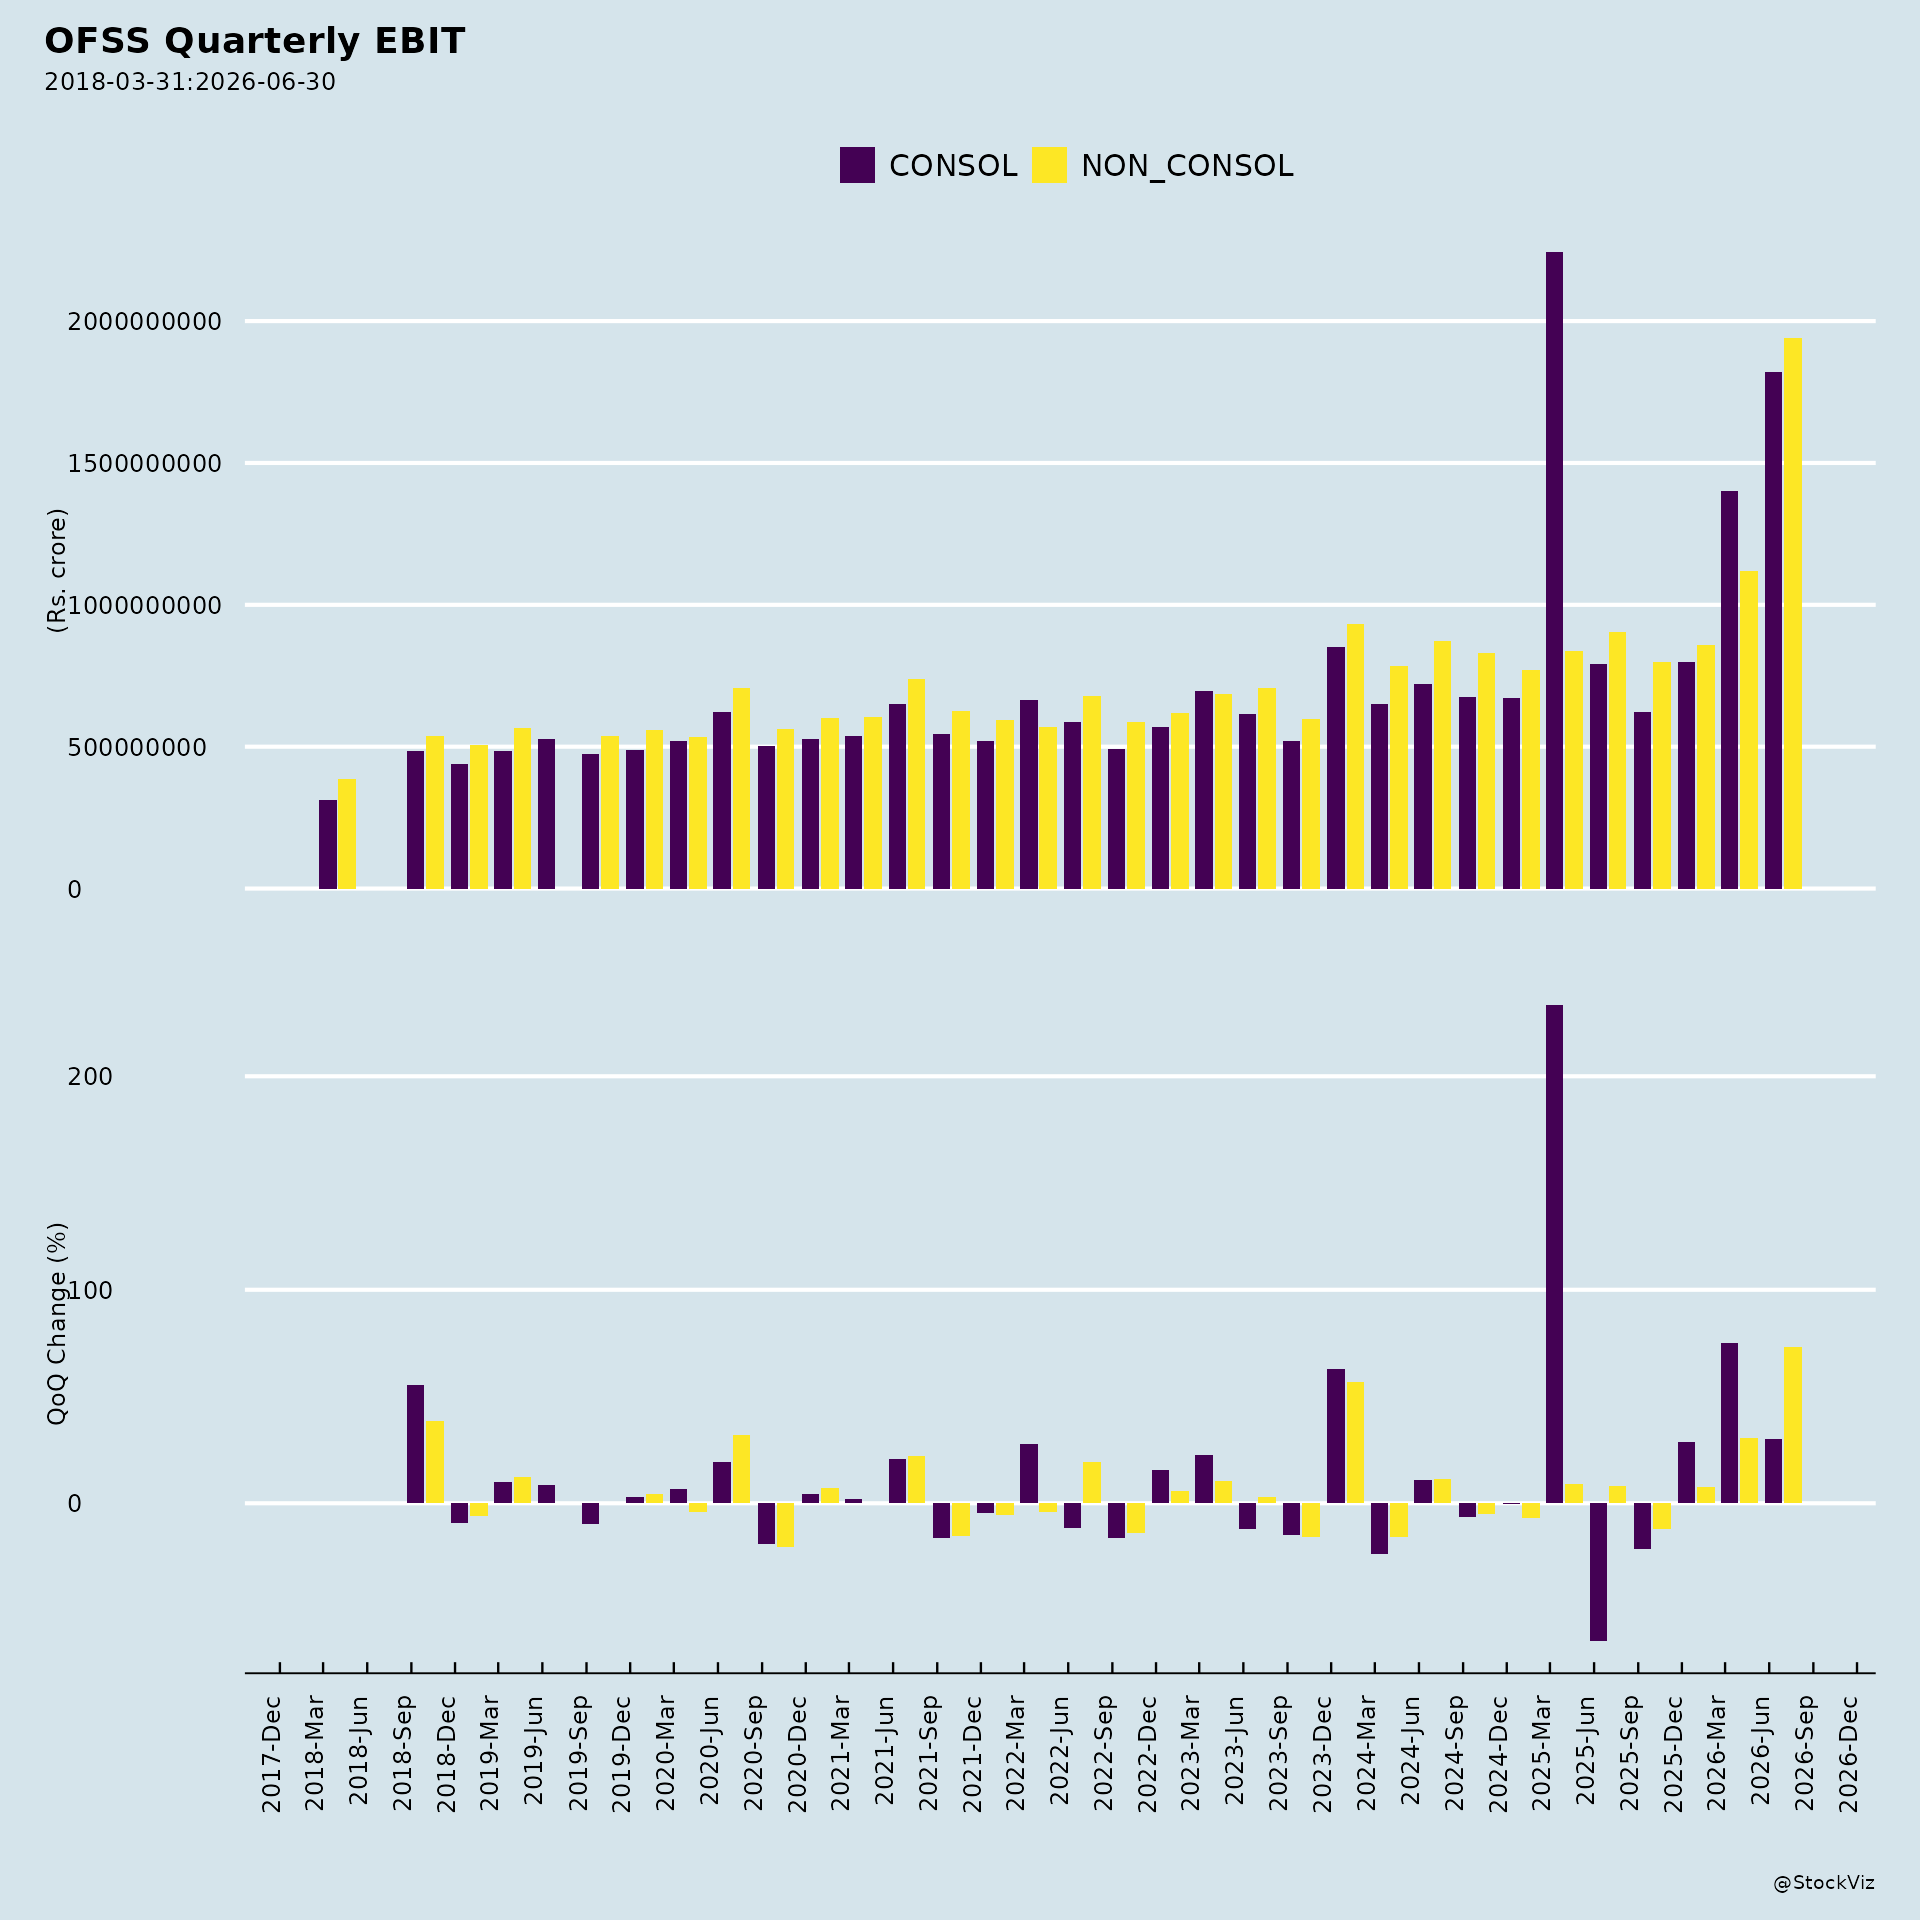
Exceptional revenue and profit growth. Consolidated revenue was Rs. 3,125 Crore, up 69% year-on-year and 51% sequentially. Operating income was Rs. 1,861 Crore, up 123% year-on-year. Net income was Rs. 1,416 Crore, up 121% year-on-year. Diluted EPS was Rs. 161.92, up 120% year-on-year.
Landmark customer agreement. During the quarter, the company entered into an agreement with an existing customer for licensing of software products, transfer of personnel, and provision of transition services, recognizing license revenue of Rs. 9,353 million and other income of Rs. 191 million. Management described this as a “landmark agreement” with a leading global bank and a “historic” quarter.
Products momentum. Products revenue was Rs. 2,936 Crore, up 75% year-on-year. License & Cloud Fees grew 418% year-on-year and 307% sequentially, rising to 44% of revenues from 14% a year earlier. Products segment result rose 129% year-on-year.
Remaining Performance Obligation. RPO was Rs. 7,345 Crore, up 16%, indicating a growing backlog.
Broad-based global wins. Business highlights include: a large U.S. vacation ownership company adopting Lending and Leasing Cloud Service; a Mexican company implementing Analytical Applications; a U.S. company substantially increasing licensed account volume for Lending and Leasing; a Japanese bank adopting Accounting Foundation and Analytical Applications Cloud Service; a U.S. bank signing a strategic agreement for FLEXCUBE Banking with perpetual licenses and transfer of personnel; J&T Banka in the Czech Republic going live with the full suite of Financial Crime and Compliance Management Cloud Services; a South African bank renewing Accounting Foundation Cloud Service; a UAE digital bank selecting Analytical Applications; a UAE bank subscribing to Financial Crime and Compliance Cloud Services; multiple Indian banks expanding relationships; ABB Bank in Azerbaijan implementing Oracle Banking applications; a Kosovo bank signing for core banking and payments; a Brunei bank upgrading Oracle Banking applications; a Saudi Arabian bank renewing Oracle Banking applications; and banks in Ethiopia and Jordan expanding Oracle Banking investments.
AI-first strategy. Management attributed continued success to modernization of products as part of an AI-first strategy and focus on solutions addressing critical business priorities of financial institutions.
Deployment flexibility. Management emphasized providing customers flexibility in deployment options alongside modern cloud and AI-enabled solutions.
Geographic diversification. Growth was broad-based year-on-year: Americas up 141%, Asia Pacific up 36%, Europe up 27%, Middle East and Africa up 20%, and India up 4%.
3. Key Risks
Dependence on a single large transaction. The quarter’s results were significantly influenced by one agreement with an existing customer, contributing Rs. 9,353 million in license revenue and Rs. 191 million in other income. The sustainability of this contribution beyond the quarter is not addressed in the material.
Services segment profitability erosion. The Services segment result declined both year-on-year and sequentially, with margins compressing (segment result as a percentage of Services revenue fell to approximately 20% from 30% a year earlier).
Geographic concentration. Americas accounted for 55% of revenue, up from 38%, concentrating exposure to that region.
Leadership continuity risk. The CEO transition, with the outgoing CEO continuing for a few months to assist transition, and simultaneous CFO change, represent a period of executive turnover.
Regulatory and labour law changes. The New Labour Code required immediate recognition of past service cost, with provisions recorded in the quarter and prior year.
Forward-looking uncertainty. The safe harbor statement explicitly flags material risks and uncertainties that could cause actual results to differ from expectations.
Shareholder approval pending. The appointments of Mr. Ketkar as MD & CEO and Mr. Morawski as Director are subject to shareholder approval via postal ballot, with e-voting from September 3, 2026 to October 2, 2026, and results to be communicated on or before October 6, 2026.
4. Management Guidance Versus Observed Business Performance
Management commentary. Mr. Padalkar described the quarter as “historic,” citing the landmark agreement with a leading global bank and a broader portfolio of wins. He stated the company’s “growth pipeline is highly secure” and expressed confidence in the company’s future and its ability to “scale even greater heights.” Mr. Ketkar stated that “all our operating parameters continue to be healthy” and that the company remains focused on providing customers flexibility in deployment options with modern cloud and AI-enabled solutions.
Observed performance. The reported results show strong consolidated growth: revenue up 69%, operating income up 123%, and net income up 121% year-on-year. Products revenue grew 75% and RPO grew 16%. However, the Services segment showed weakness, with revenue up only 6% year-on-year and segment result down 29% year-on-year and 42% sequentially. Europe declined 22% sequentially. Employee benefit expenses rose significantly, including severance costs. The quarter’s performance was materially boosted by a single large customer agreement.
Forward-looking statements. The only explicit forward-looking statements in the material are management’s qualitative expressions of confidence in the growth pipeline and future scaling, and the safe harbor statement noting that future plans and prospects are subject to material risks and uncertainties. No specific financial guidance figures for future periods are provided in the material.
Broker Narrative
The narrative evolved from a cautiously positive Buy in 2023, which flagged margin contraction, PAT decline, customer concentration, weaker operating cash flow, and SaaS-transition revenue friction, to a strongly confident Buy in 2026 with no major operational headwinds. The persistent themes were product/cloud momentum, robust deal activity, and a strong balance sheet/dividend profile. The key change was that margin worries reversed into significant EBITDA margin expansion of 660 bps to 51.1%, while RPO growth and a USD 100 Mn deal win signaled stronger revenue visibility rather than SaaS-related friction.
Broker Timeline
15 broker calls · 2023-06-30 to 2026-04-23
Copyright © 2023 SAS Data Analytics Pvt. Ltd. All rights reserved.