OBEROIRLTY
Equity Metrics
November 18, 2026
Oberoi Realty Limited
Residential Commercial Projects
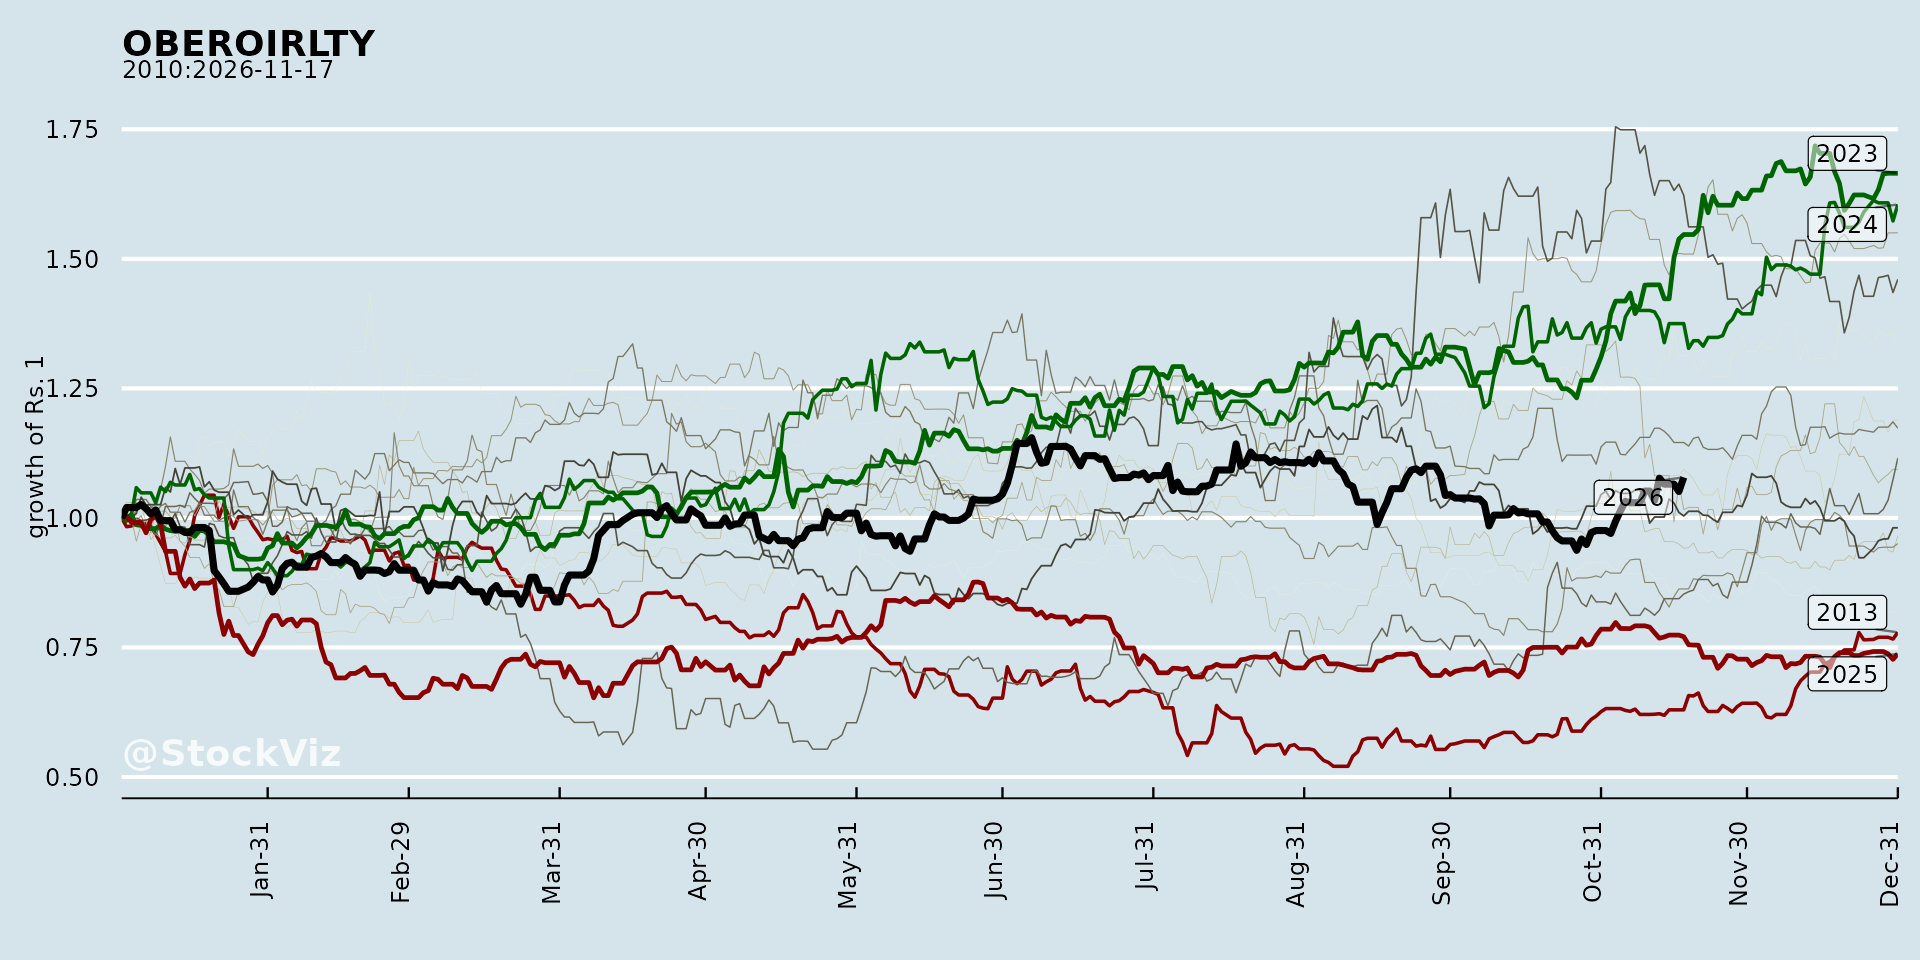
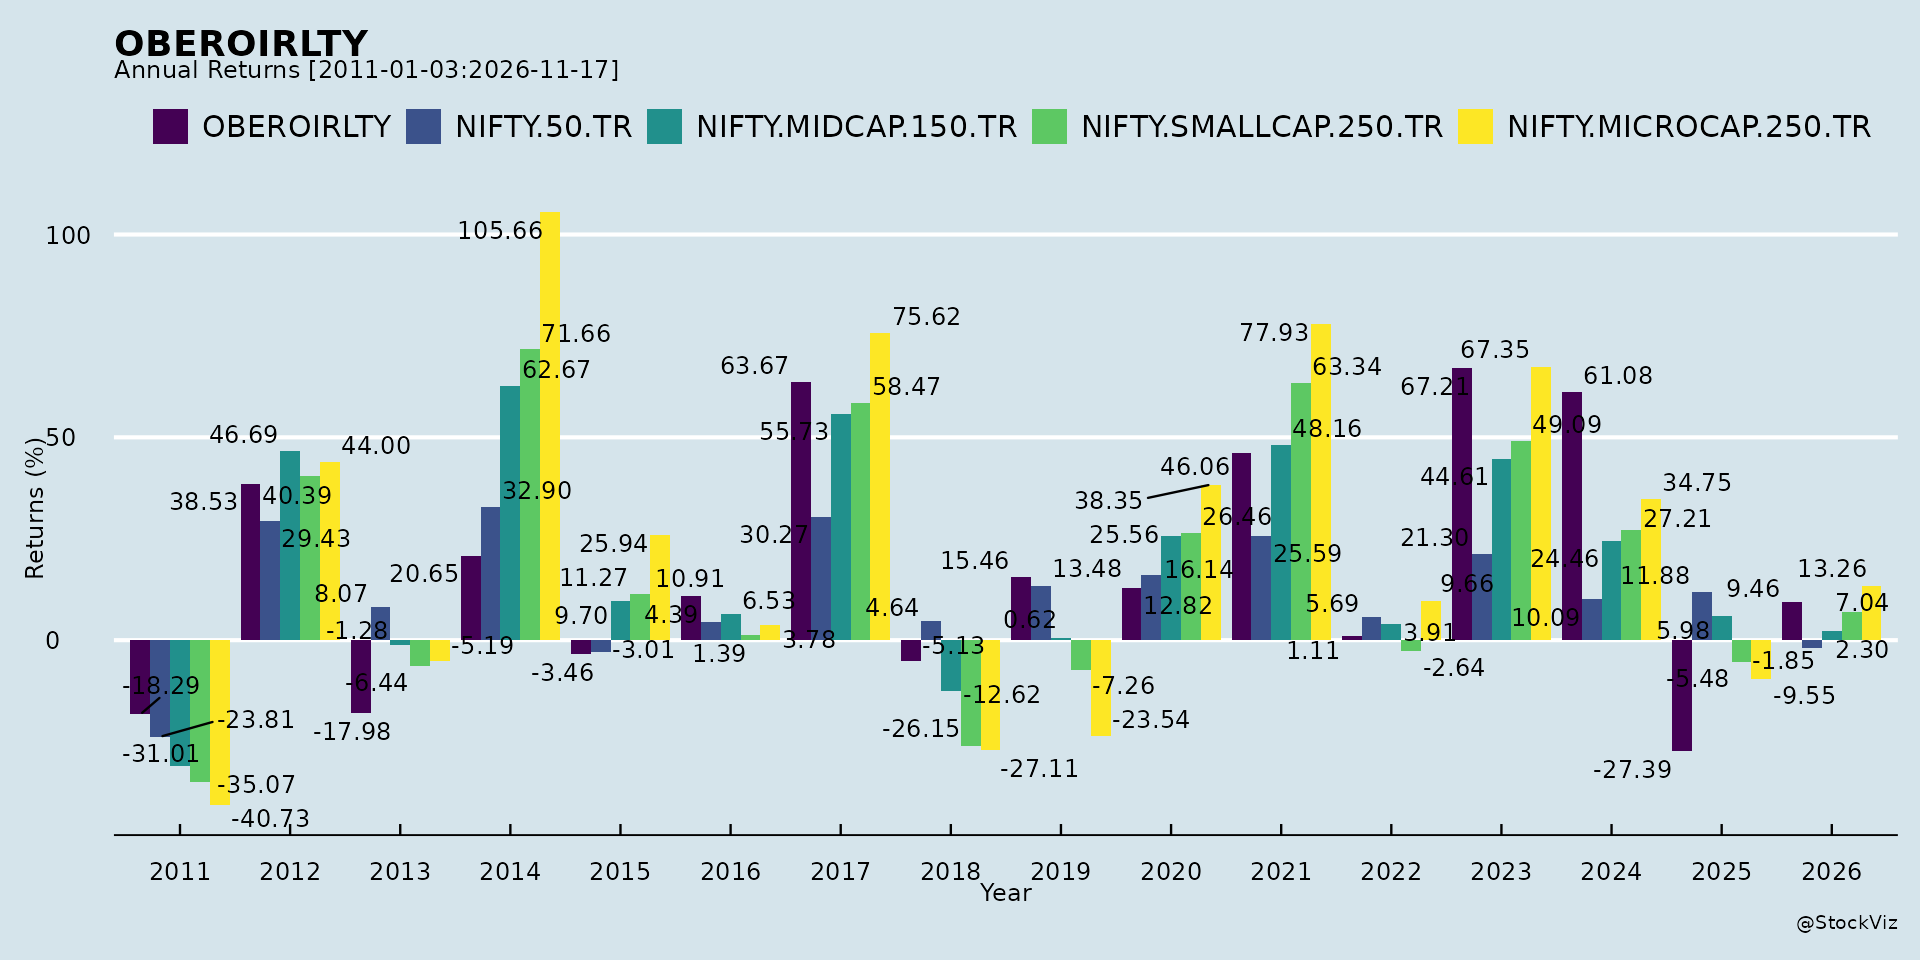
Annual Returns
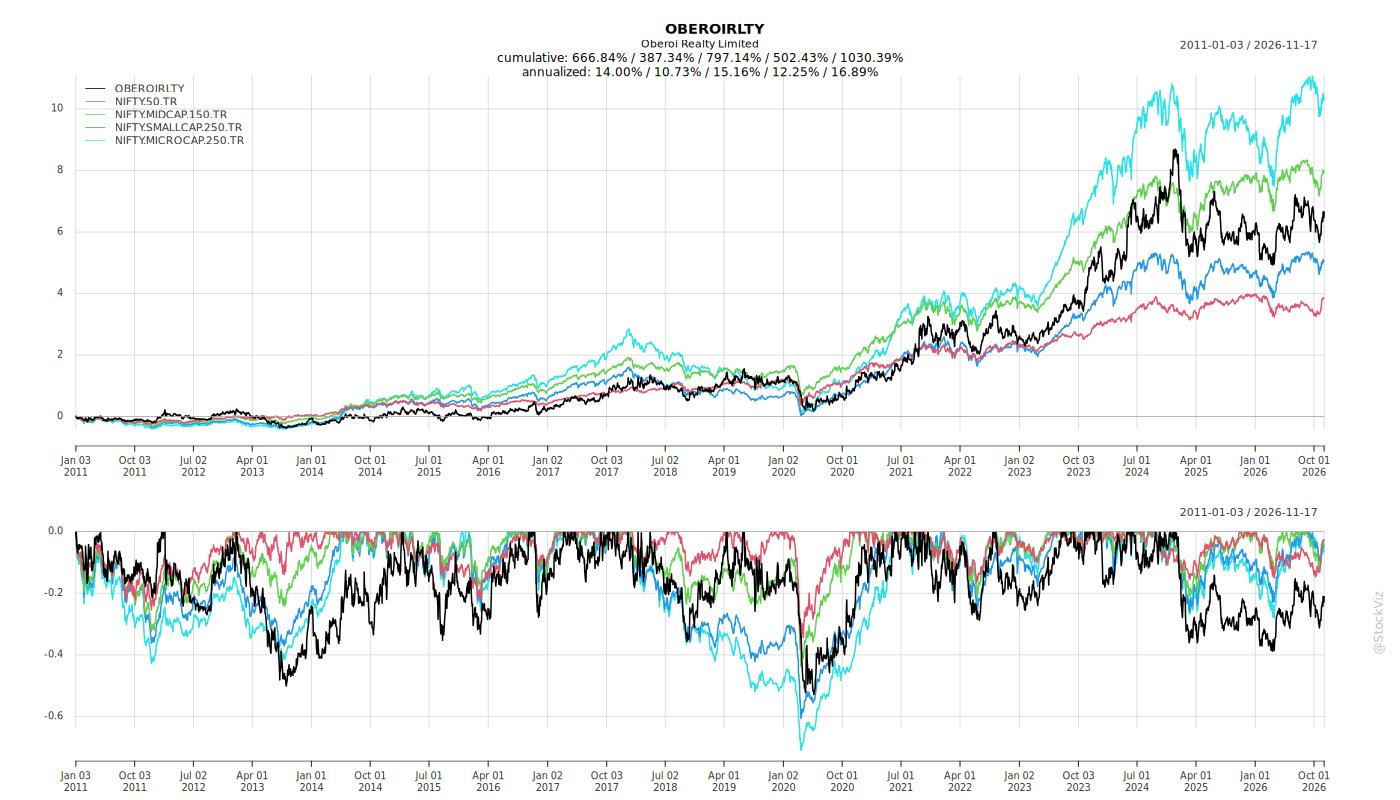
Cumulative Returns and Drawdowns
Fundamentals
Ownership
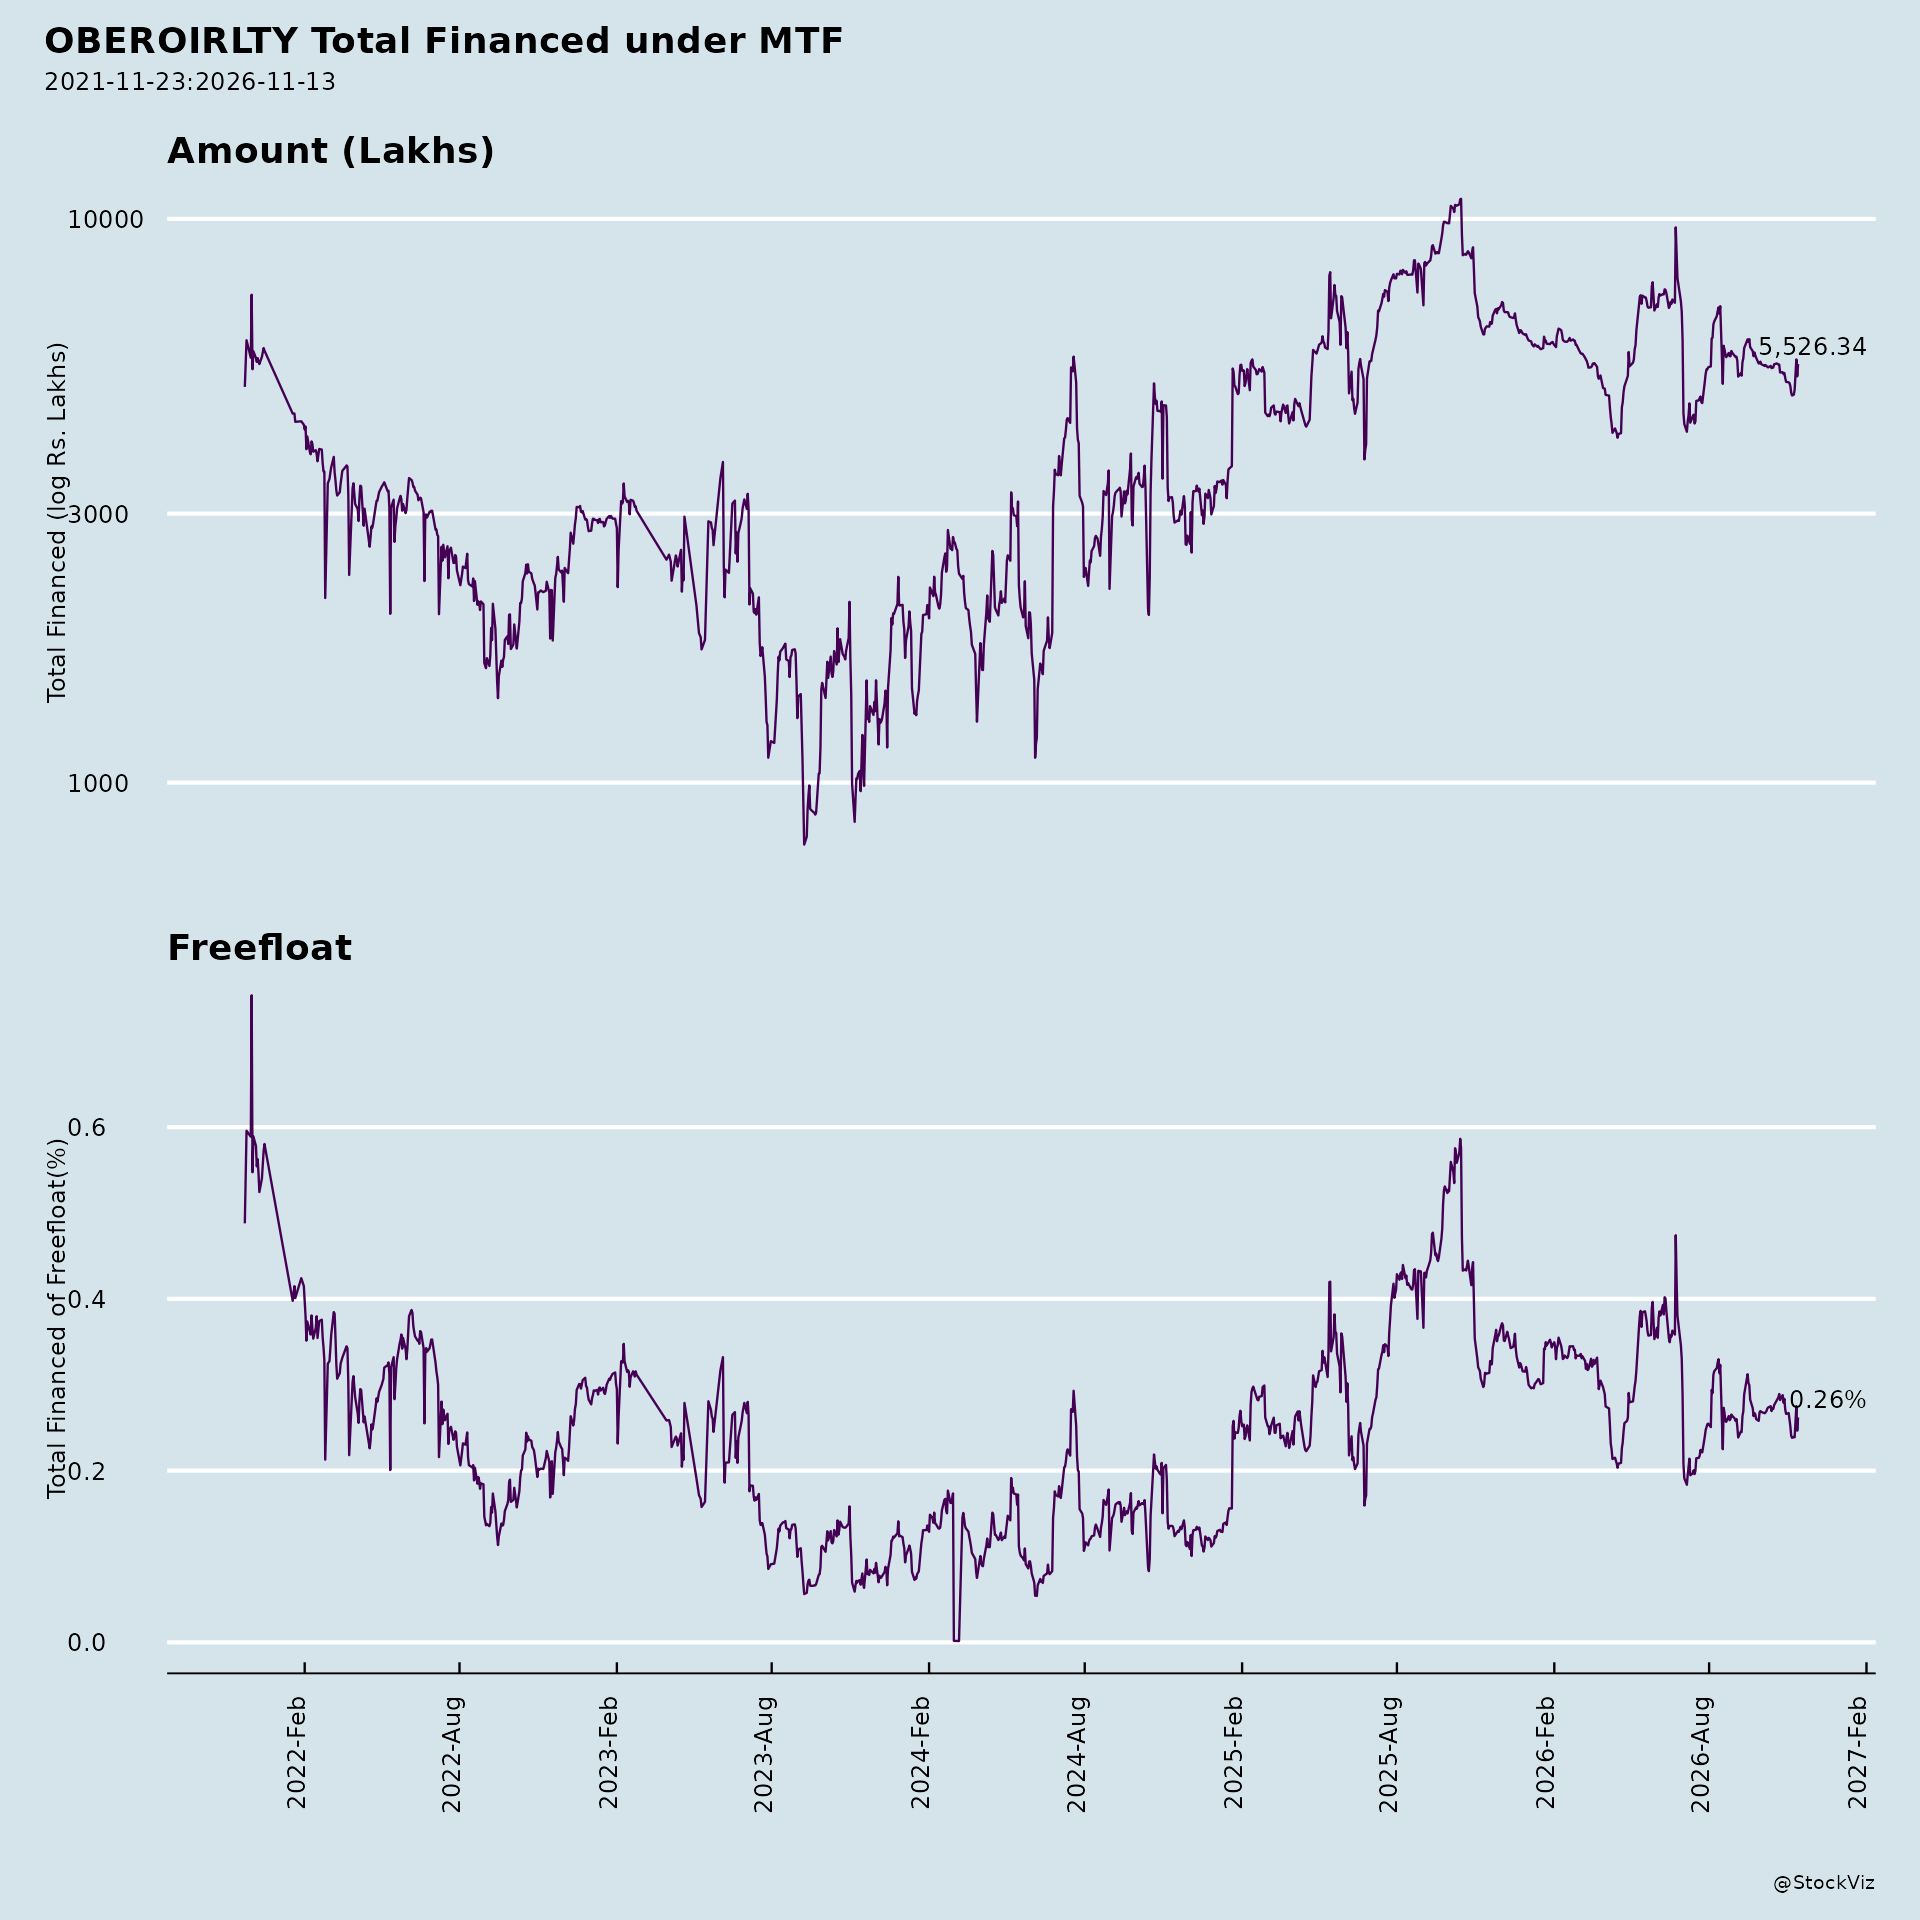
Margined
AI Summary
asof: 2026-09-16
Oberoi Realty — Recent Corporate Announcements: Summary
1. Headwinds and Challenges
Litigation over the Gurugram project (Project ‘Three Sixty North’) - A Writ Petition was filed by Advance India Projects Limited (AIPL) against the Director, Department of Town and Country Planning Haryana (DTCP) and others before the Hon’ble Punjab and Haryana High Court, Chandigarh. - By an order dated July 7, 2026, the High Court imposed a restriction on further allotments and further creation of third-party rights in relation to the project. - AIPL’s representation dated April 29, 2026 sought cancellation of Licence No. 69 of 2025 (dated May 12, 2025), the parent licences, and the order dated June 17, 2025 approving the change of developer in favour of Oberoi Realty Ltd.
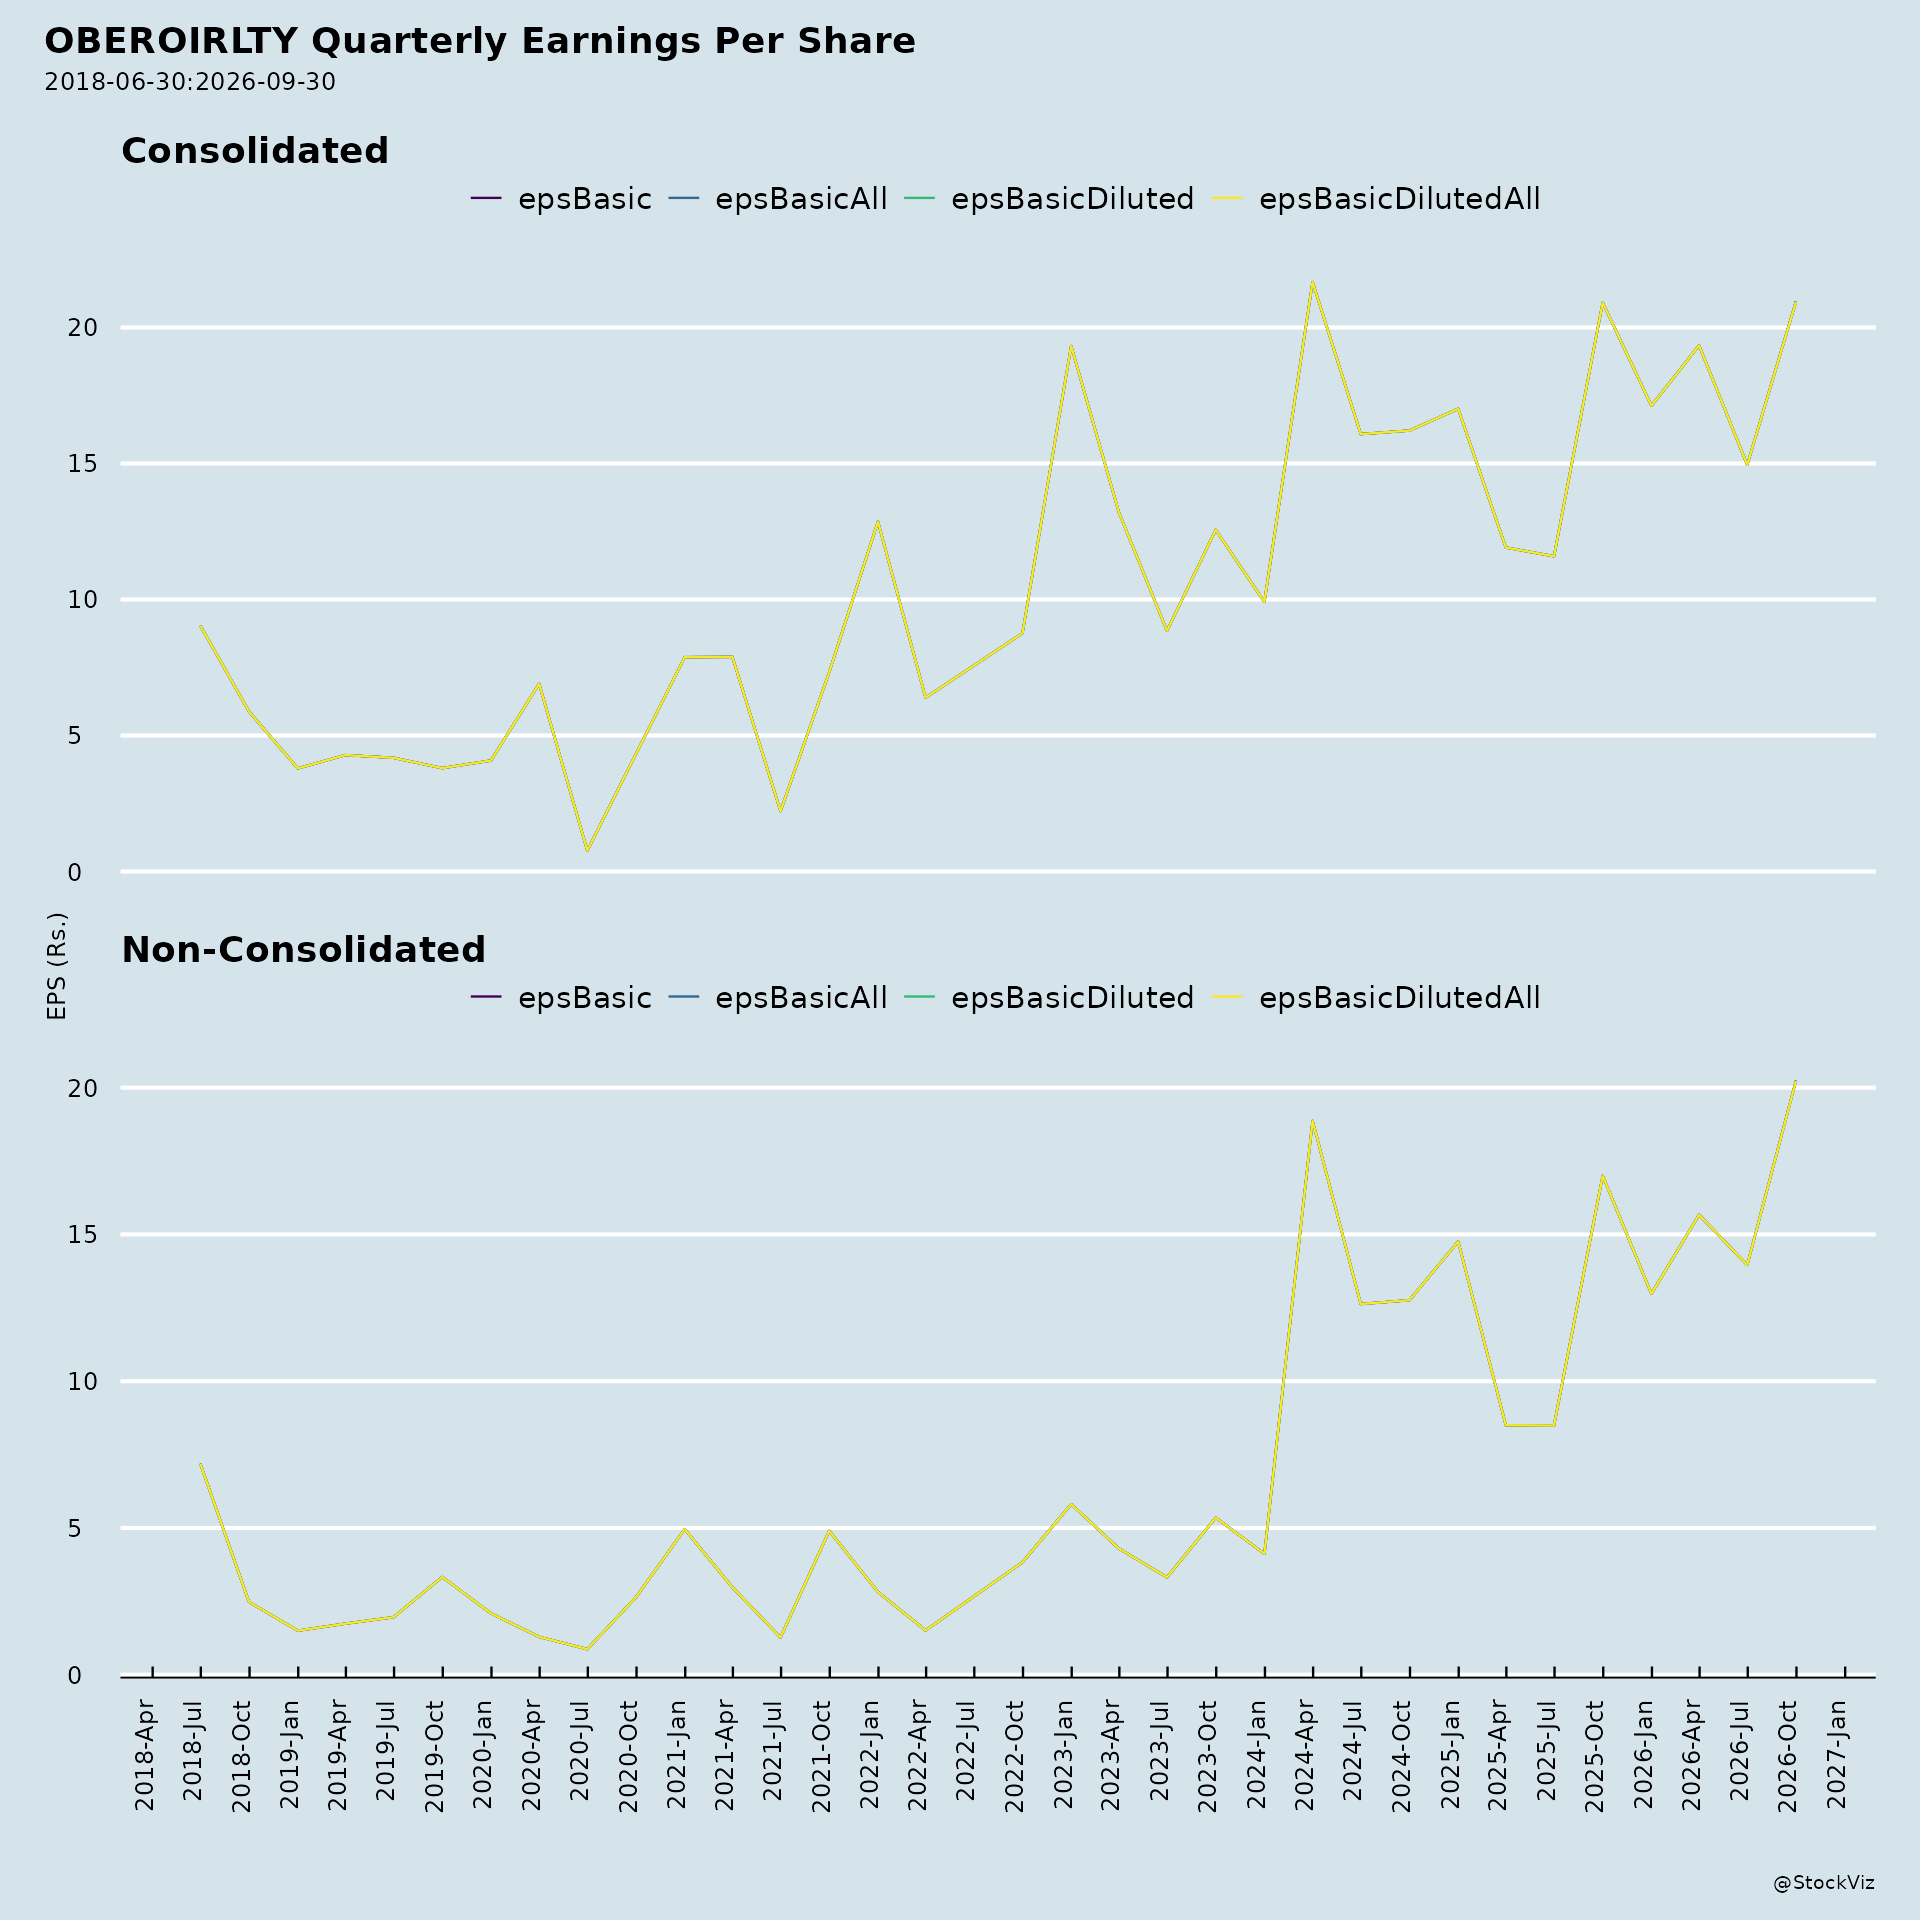
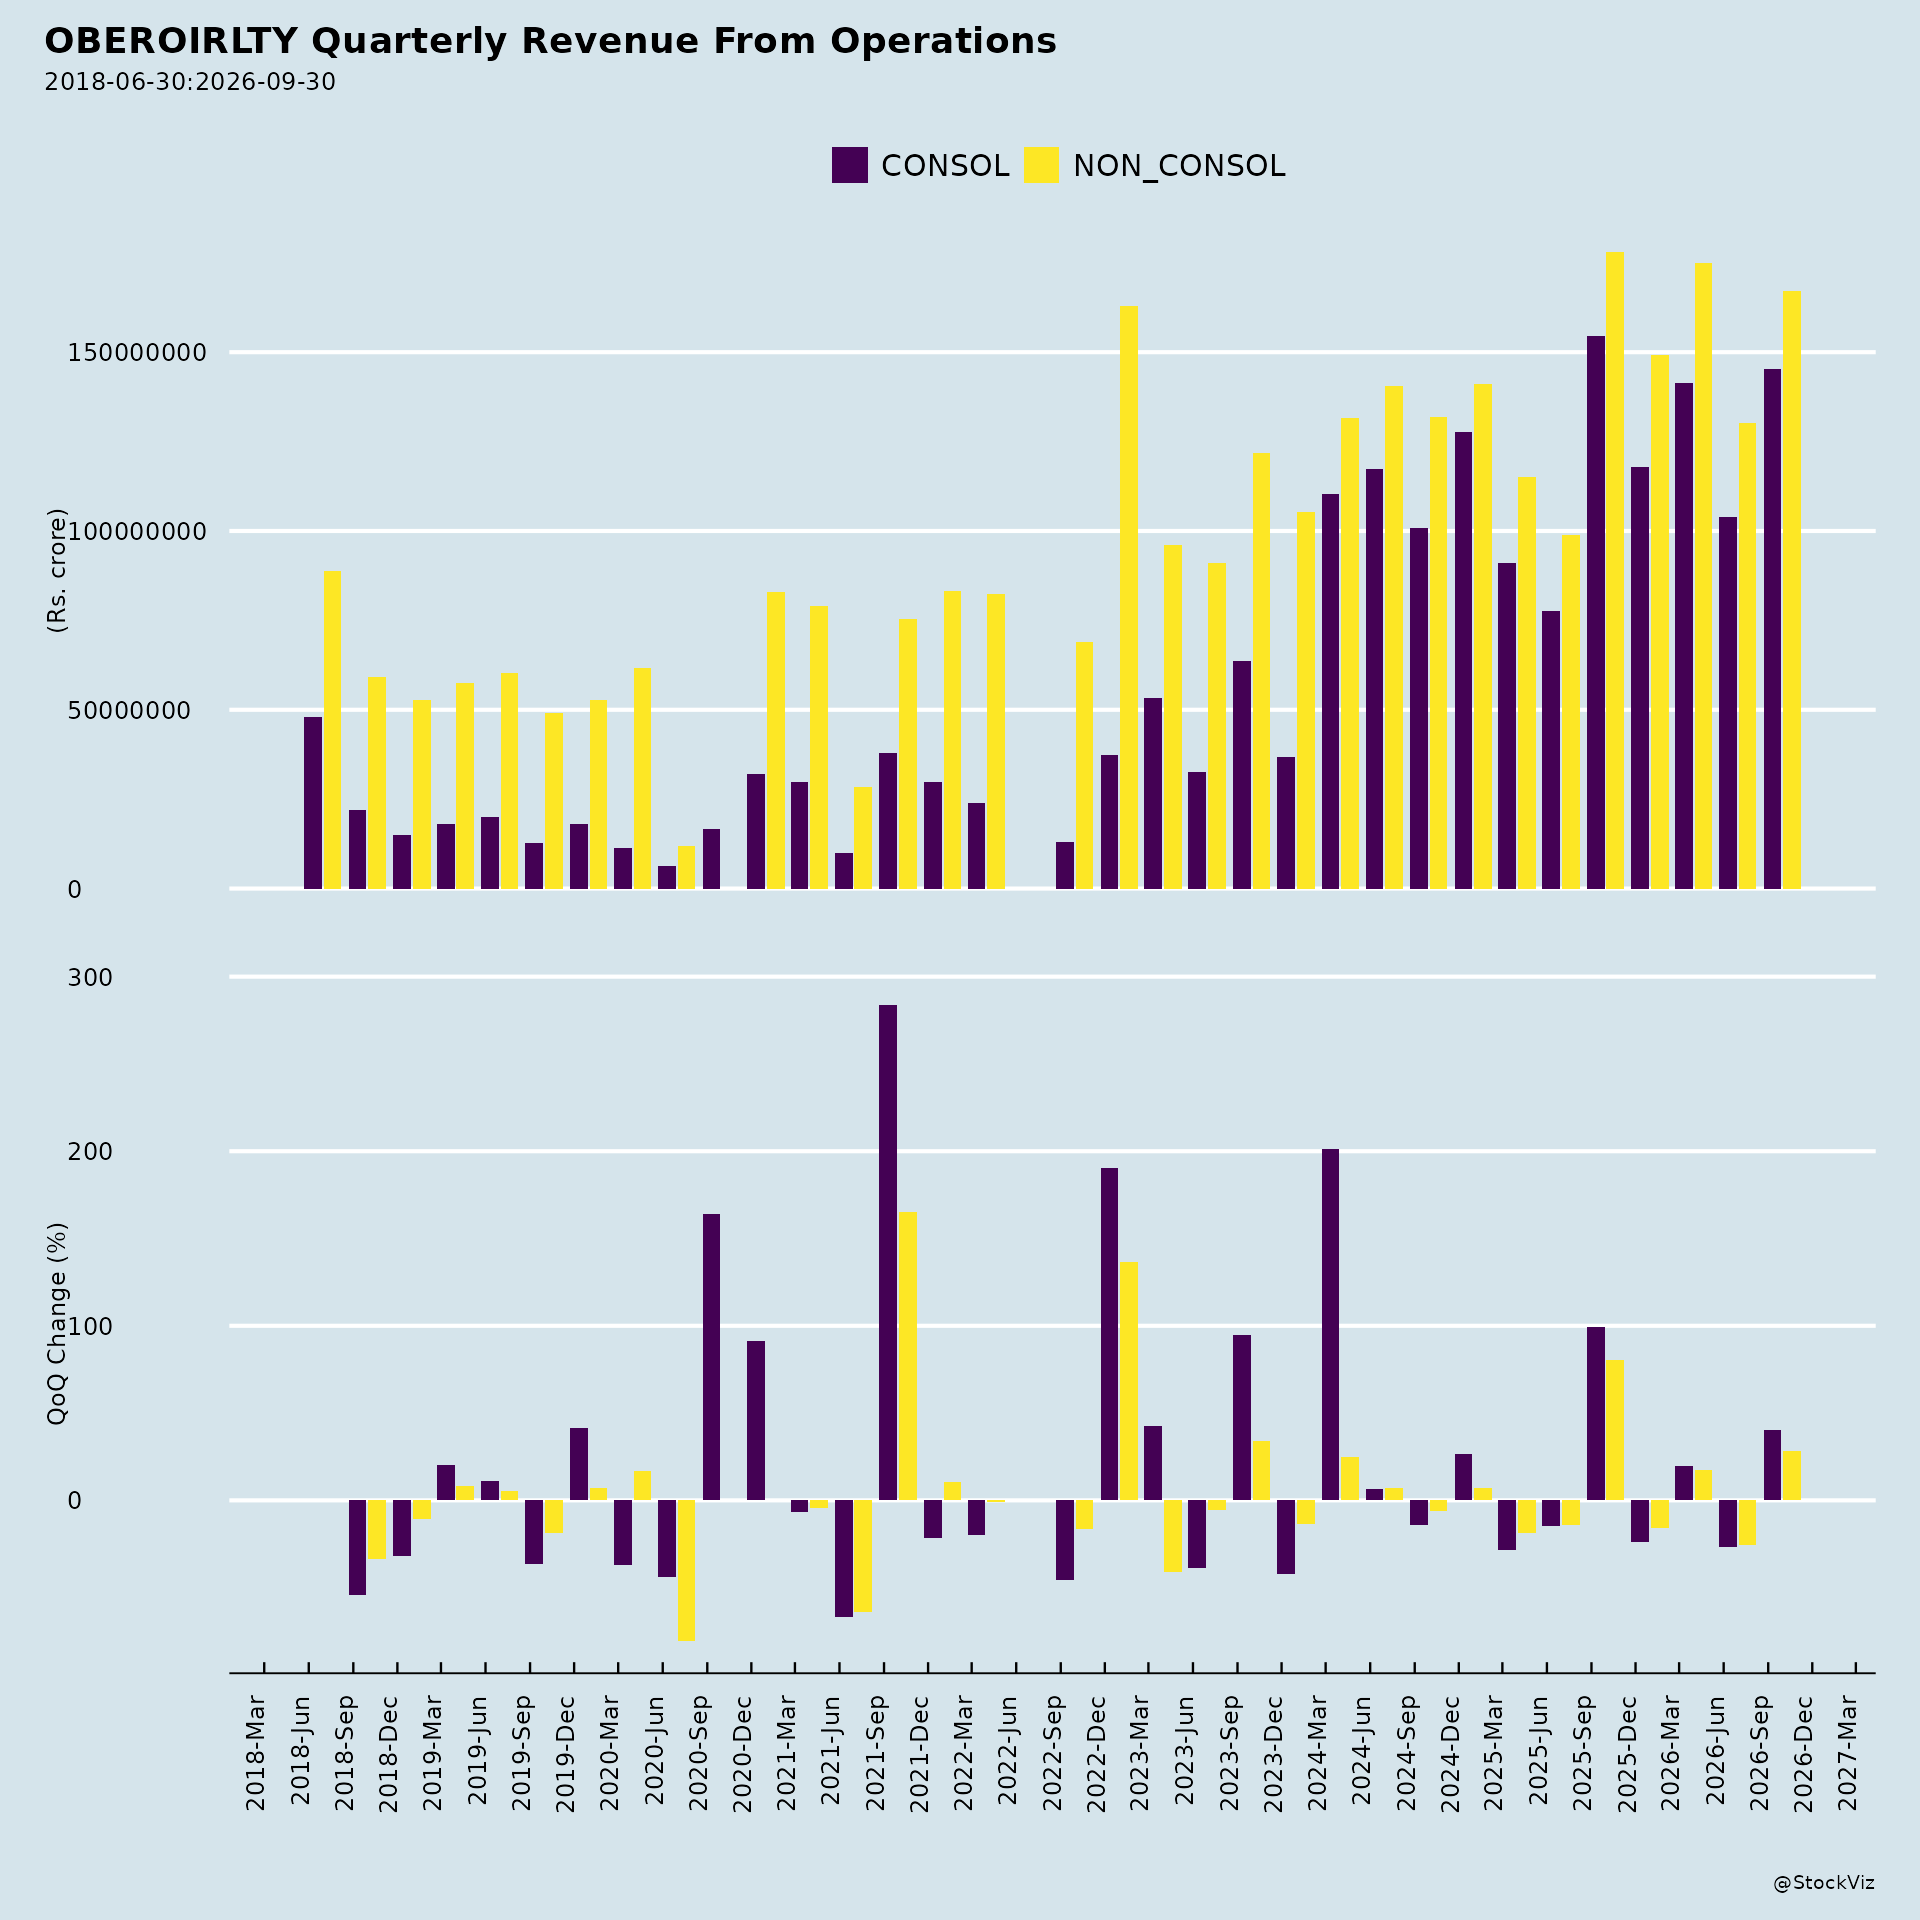
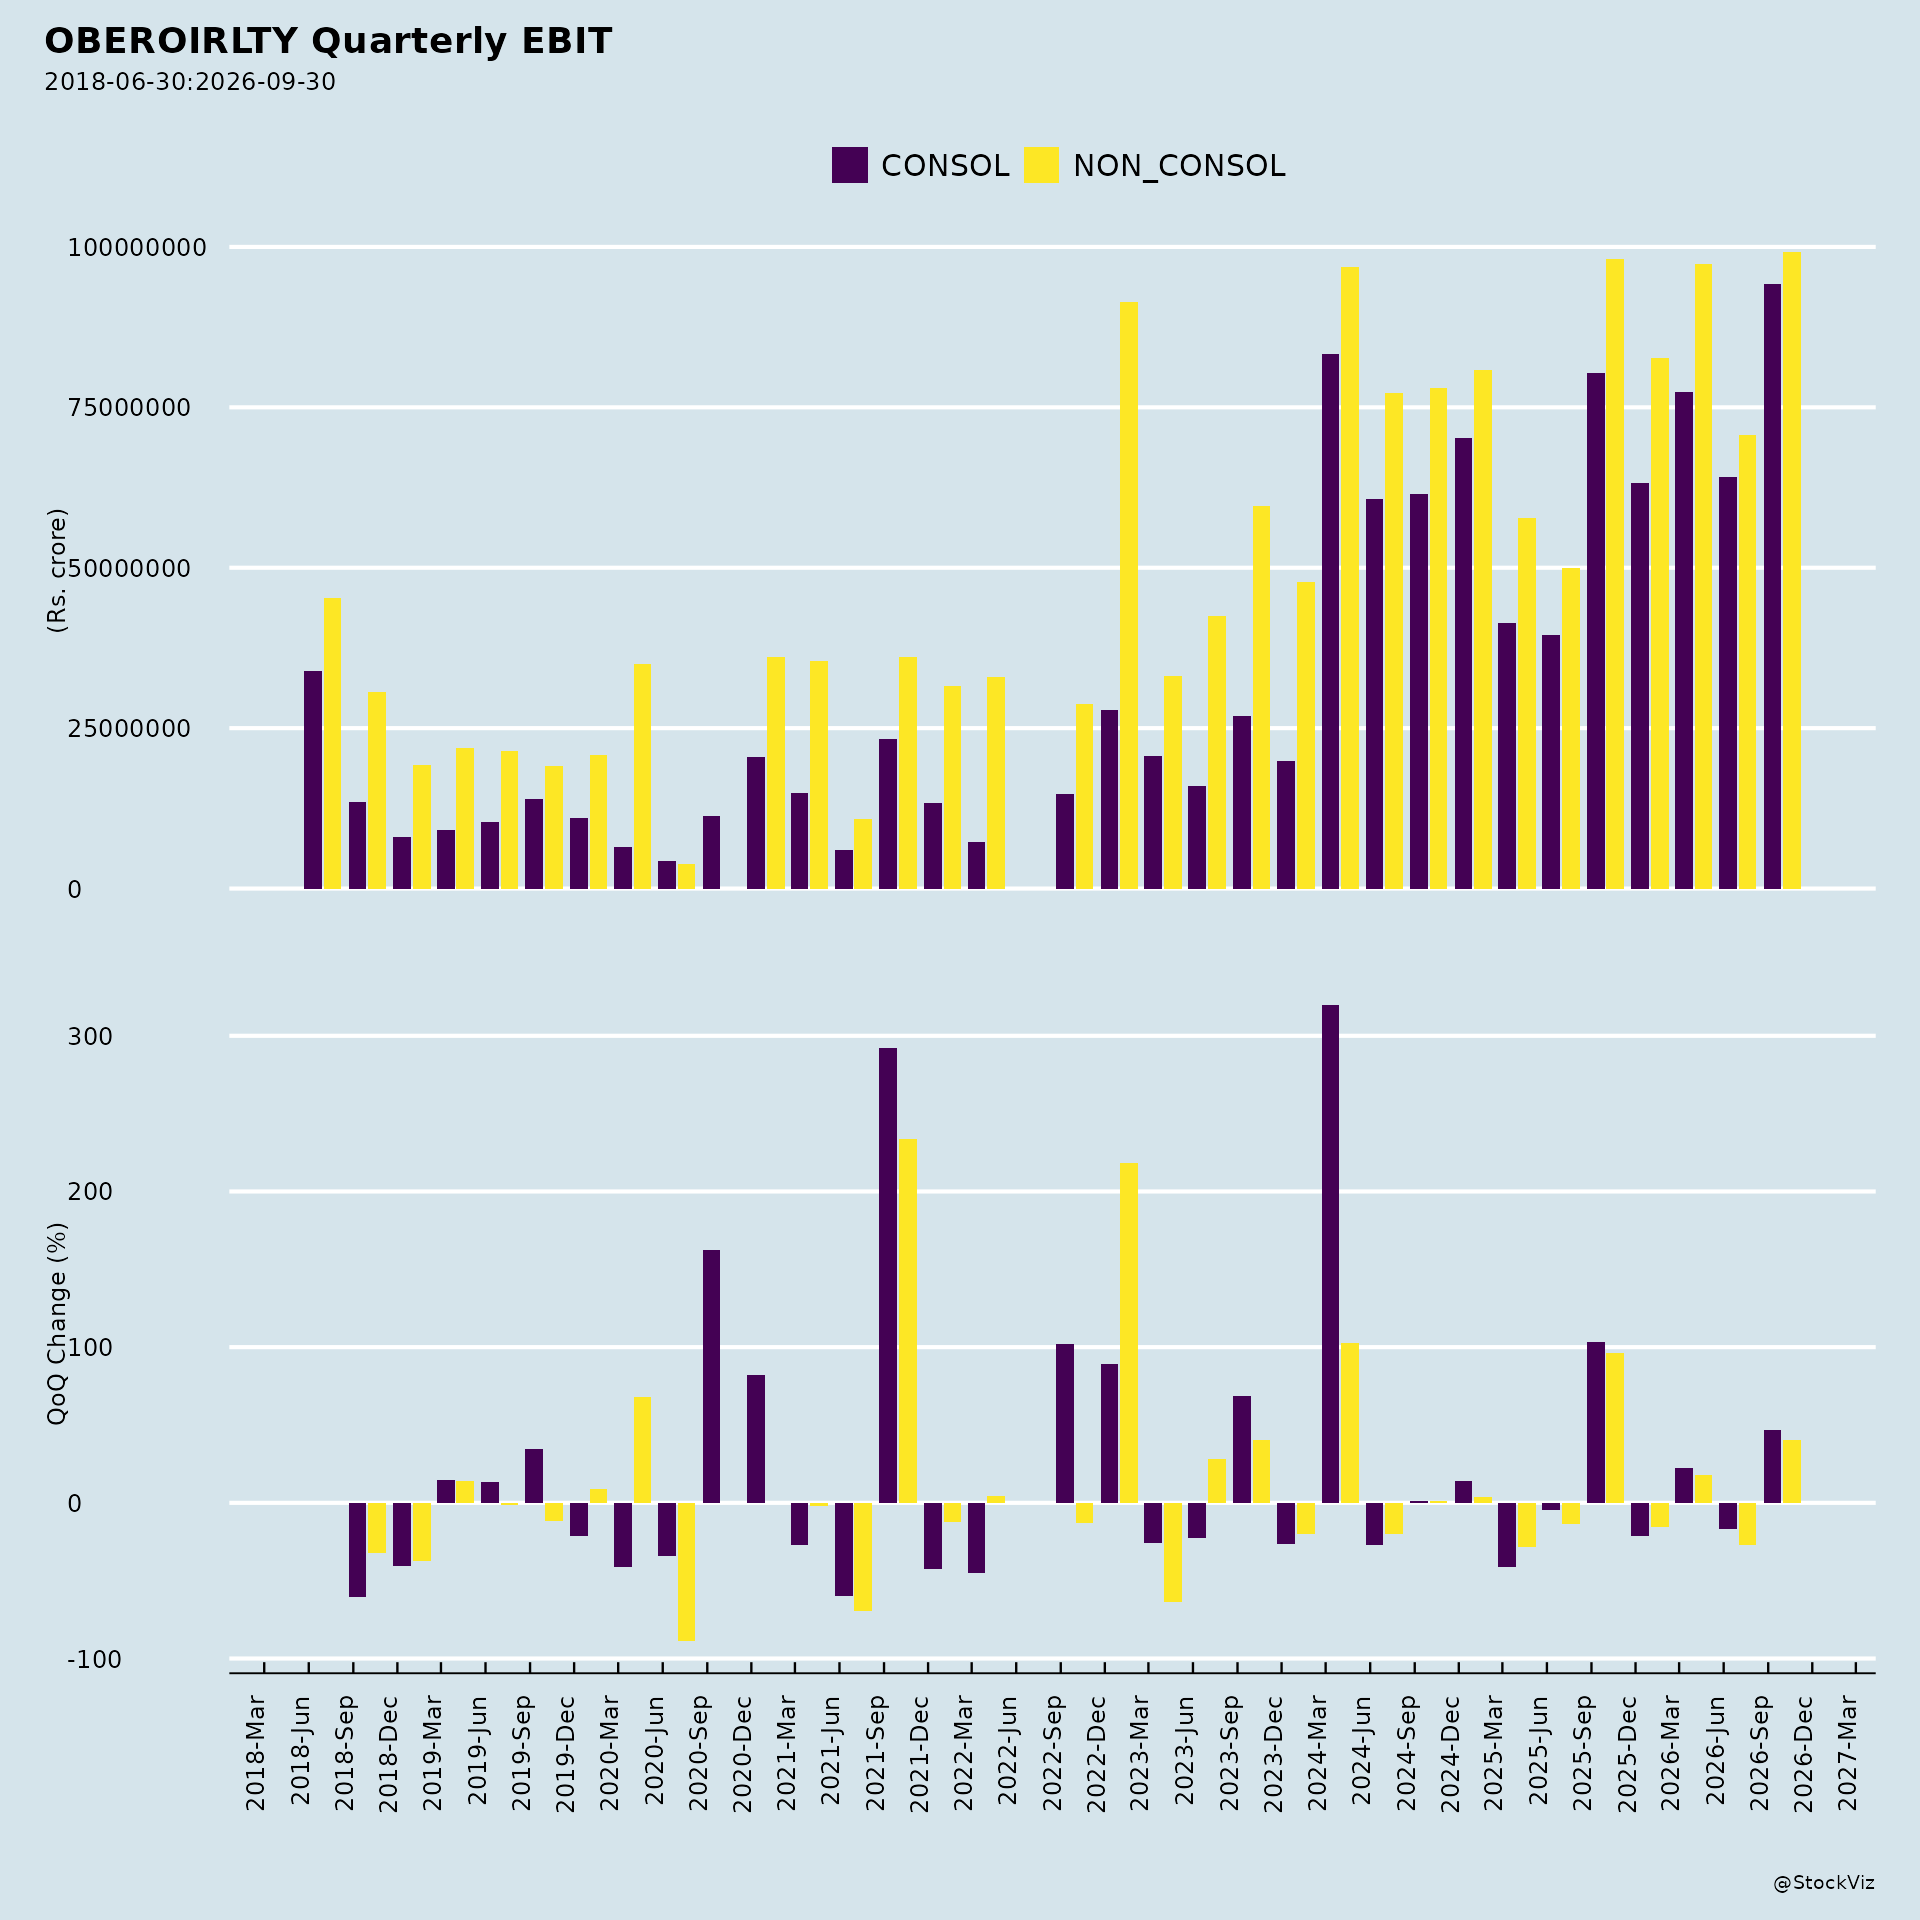
Quarter-on-quarter moderation in earnings - Consolidated revenue for Q1FY27 was Rs. 1,361.69 crore, compared with Rs. 1,82,371 lakh (Rs. 1,823.71 crore) in the quarter ended March 31, 2026. - Consolidated Profit Before Tax for Q1FY27 was Rs. 711.64 crore, against Rs. 96,294 lakh (Rs. 962.94 crore) in the preceding quarter. - Consolidated Profit After Tax for Q1FY27 was Rs. 544.71 crore, against Rs. 70,328 lakh (Rs. 703.28 crore) in Q4FY26. - The company notes that the nature of accounting for the real estate business is such that quarterly/yearly results may not be strictly comparable to earlier periods.
Cost and leverage-related movements - Consolidated finance cost rose to Rs. 5,243 lakh in Q1FY27 from Rs. 2,710 lakh in Q4FY26. - Consolidated inventory turnover (days) increased to 2,020 days in Q1FY27 from 1,396 days in Q4FY26; standalone inventory turnover rose to 2,545 days from 1,621 days. - Consolidated debt service coverage ratio declined to 1.61 in Q1FY27 from 2.14 in Q4FY26; standalone declined to 1.46 from 1.71. - Consolidated debtors turnover (days) increased to 23 from 14; standalone to 27 from 13.
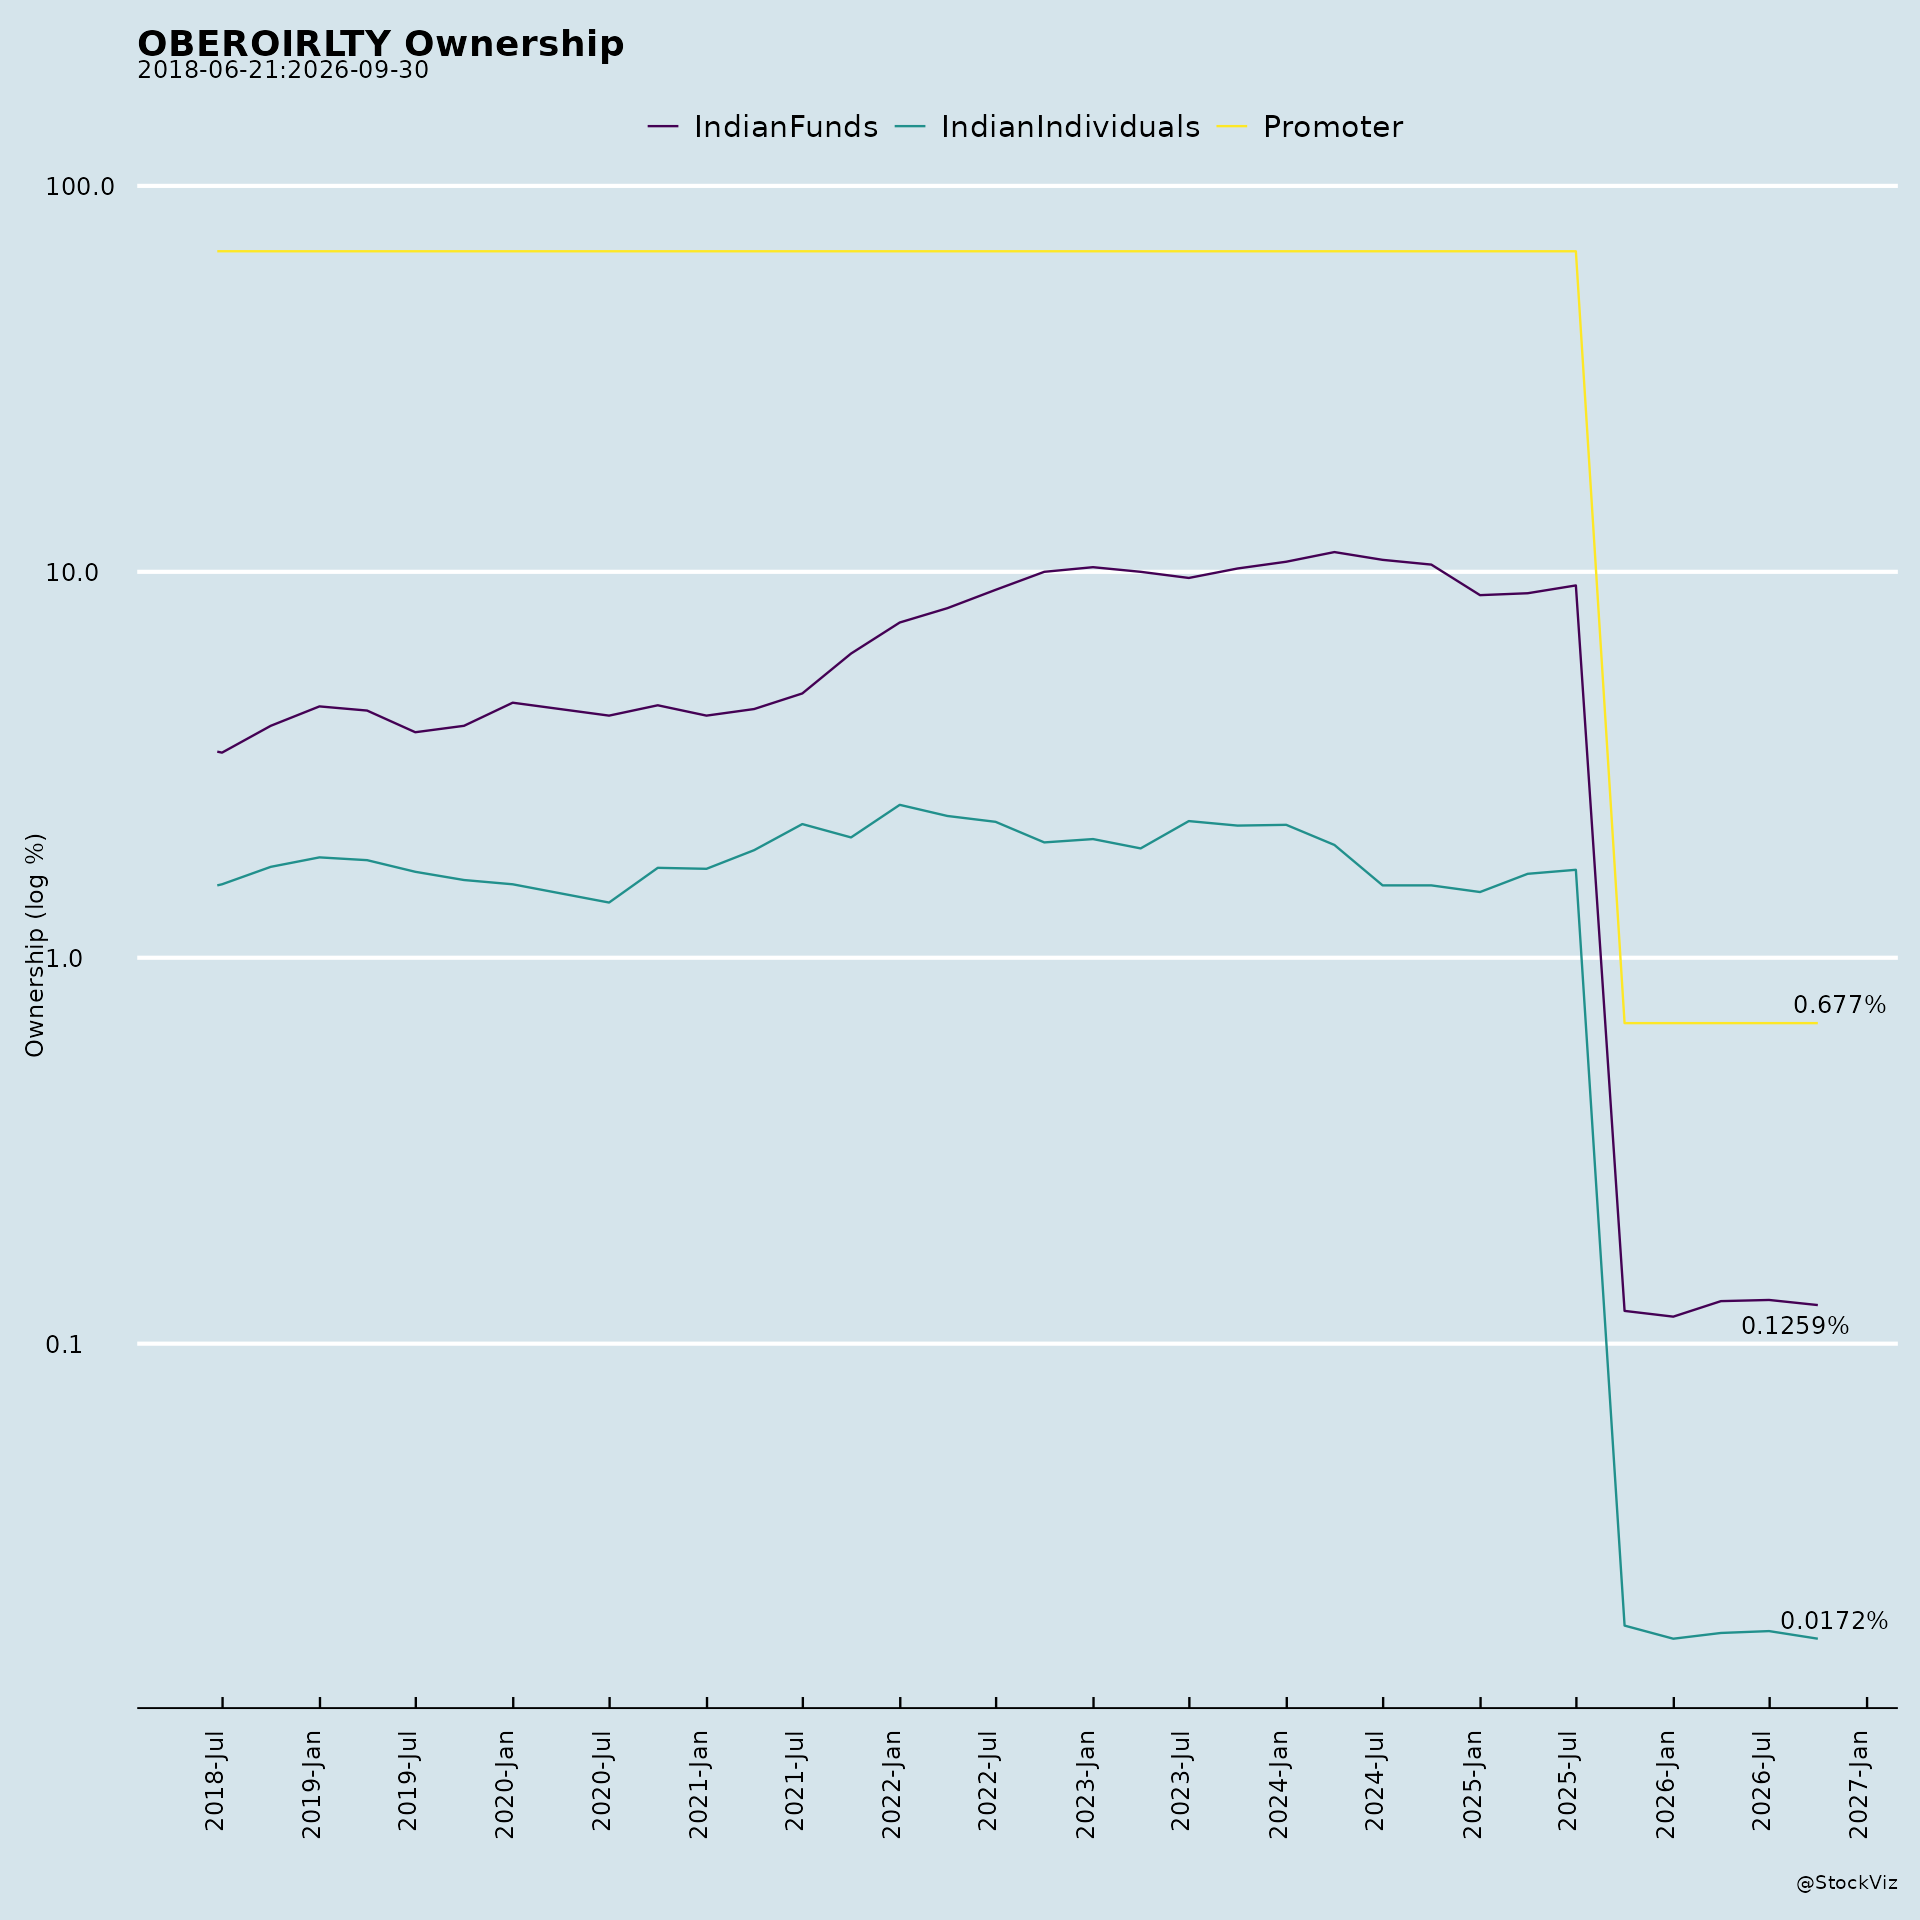
Governance-related dissent at the AGM - At the 28th AGM held on June 25, 2026, Resolution 3 (re-appointment of Mr. Vikas Oberoi as a Director retiring by rotation) saw 6,892,776 votes against (2.0177% of votes polled), with Public Institutions recording 6,892,597 votes against (7.2268% of their votes polled). - Resolution 5 (approval of issue of equity shares and/or convertible securities by way of qualified institutions placement) saw 2,869,282 votes against from Public Institutions (3.0082% of their votes polled).
2. Tailwinds and Growth Prospects
Resolution of the Gurugram litigation - By order dated August 13, 2026 (received by email on August 17, 2026), the DTCP held that Licence No. 69 of 2025 dated May 12, 2025 and the order dated June 17, 2025 approving the change of developer in favour of Oberoi Realty Ltd. are legally intact and do not require any action under the provisions of Act No. 8 of 1975. - The DTCP rejected and filed AIPL’s representation dated April 29, 2026 as being without merit. - Consequently, the restriction imposed by the High Court on further allotments and further creation of third-party rights vide its order dated July 7, 2026 ceased to be operative.
NCR foray and launch pipeline - Mr. Vikas Oberoi stated that the recent launch of the company’s first development in the NCR marked the beginning of a new chapter, following four decades of building the business in the Mumbai Metropolitan Region. - The company describes a robust pipeline of upcoming launches, with focus on international standards of design, execution and quality.
Diversified portfolio performance - Residential, commercial, retail and hospitality businesses continued to perform steadily during the quarter. - Segment revenue for real estate was Rs. 1,25,402 lakh in Q1FY27 (against Rs. 94,491 lakh in Q1FY26); hospitality segment revenue was Rs. 4,687 lakh (against Rs. 4,264 lakh). - Hospitality segment results improved to Rs. 1,698 lakh in Q1FY27 from Rs. 1,476 lakh in Q1FY26.
Growth-oriented corporate actions - The Board approved a qualified institutions placement (QIP) enabling resolution at the AGM (Resolution 5), which passed with 97.9823% of votes polled in favour. - Centerstage Realty Private Limited was incorporated as a wholly owned subsidiary on June 2, 2026, and Oberoi Realty subscribed to Rs. 26,850 lakh of its equity share capital on June 9, 2026. - The Resolution Plan for Hotel Horizon Private Limited (HHPL) was implemented on May 7, 2026, following NCLT approval dated January 29, 2026; Oberoi Realty holds 49.999% and infused Rs. 45,950 lakh as an unsecured loan. - The scheme of amalgamation of Nirmal Lifestyle Realty Private Limited with the company was made effective April 14, 2026 (appointed date November 7, 2024).
Recognition - Oberoi Mall received the Most Admired Shopping Centre of the Year for Mixed Land Use Development award at the MAPIC India Awards 2026. - Sky City Mall received the Most Admired Shopping Centre — Marketing & Promotion Activities (Metro West) award at the MAPIC India Awards 2026. - Prego at The Westin Mumbai Garden City was featured in the IHC London & IIHM Hospitality Honours List 2026.
3. Key Risks
- Regulatory and legal risk: The Gurugram project was subject to a High Court restriction and a challenge to its licence and change-of-developer approval; while the DTCP order dated August 13, 2026 resolved the matter at that level, the underlying dispute illustrates exposure to regulatory and third-party challenges on project approvals.
- Project approval dependency: The change of developer approval (June 17, 2025) and Licence No. 69 of 2025 were central to the company’s rights in the project, and their validity was contested.
- Comparability and timing risk in real estate accounting: The company states that results of a quarter/year may not be strictly comparable to earlier periods due to the nature of real estate business accounting.
- Leverage and coverage metrics: Debt service coverage ratio declined on both consolidated (1.61 vs 2.14) and standalone (1.46 vs 1.71) bases quarter-on-quarter; finance costs increased.
- Working capital intensity: Inventory turnover days lengthened (consolidated 2,020 vs 1,396; standalone 2,545 vs 1,621), and debtors turnover days increased.
- Forward-looking statement risk: The company’s own forward-looking statement notes risks and uncertainties including regulatory changes, local political or economic developments, and technological risks that could cause actual results to differ materially.
- Dilution risk: The QIP resolution approved at the AGM permits issuance of equity shares and/or convertible securities, which could dilute existing shareholders.
- Shareholder dissent: Notable minority opposition on the re-appointment of the Chairman & Managing Director and on the QIP resolution at the AGM.
4. Management Guidance Versus Observed Business Performance
Management commentary (July 17, 2026) - Mr. Vikas Oberoi stated that India continues to stand out as one of the strongest long-term growth stories globally, and the company remains optimistic about opportunities for premium housing. - He stated that customers place greater emphasis on brand and product as aspirations evolve. - He stated that residential, commercial, retail and hospitality businesses continued to perform steadily, reflecting the strength of the diversified portfolio. - He stated that the NCR launch marked the beginning of an exciting new chapter, and that with a robust pipeline of upcoming launches, the company remains focused on bringing international standards of design, execution and quality to every development while creating lasting value for stakeholders.
Observed performance in Q1FY27 (quarter ended June 30, 2026) - Consolidated revenue: Rs. 1,361.69 crore, against Rs. 1,073.98 crore in Q1FY26. - Consolidated EBIDTA: Rs. 794.94 crore, against Rs. 606.77 crore in Q1FY26. - Consolidated PBT: Rs. 711.64 crore, against Rs. 506.96 crore in Q1FY26. - Consolidated PAT: Rs. 544.71 crore, against Rs. 421.00 crore in Q1FY26. - Standalone revenue from operations: Rs. 1,03,827 lakh, against Rs. 77,534 lakh in Q1FY26 (restated for merger). - Standalone PBT: Rs. 64,151 lakh, against Rs. 39,559 lakh in Q1FY26 (restated). - Standalone PAT: Rs. 50,763 lakh, against Rs. 30,884 lakh in Q1FY26 (restated). - Segment performance: real estate revenue Rs. 1,25,402 lakh (vs Rs. 94,491 lakh in Q1FY26); hospitality revenue Rs. 4,687 lakh (vs Rs. 4,264 lakh); hospitality segment results Rs. 1,698 lakh (vs Rs. 1,476 lakh). - Net profit margin (consolidated): 39.92% in Q1FY27, against 39.22% in Q1FY26. - Operating margin (standalone): 56.65% in Q1FY27, against 53.52% for the year ended March 31, 2026. - The Board declared an interim dividend of Rs. 2 per equity share (20% of face value) for FY2026-27 at its meeting on July 17, 2026. - The company redeemed Rs. 8,300 lakh of Series 1 NCDs and Rs. 8,500 lakh of Series 2 NCDs during the quarter. - Employee stock options: 18,38,837 options approved under the Oberoi Realty Employee Stock Option Scheme, 2025 at an exercise price of Rs. 1,650 per option, vesting in a staggered manner over seven years with a four-year exercise period; an ESOP expense of Rs. 505 lakh was recognised for the quarter. - The security cover of at least 1.5 times on the non-convertible debentures was maintained as on June 30, 2026.
Guidance versus performance alignment - The management’s statement that businesses “continued to perform steadily” is consistent with year-on-year growth across consolidated revenue, EBIDTA, PBT and PAT, and with growth in both real estate and hospitality segment revenues and results. - The management’s emphasis on the NCR launch as a new chapter is consistent with the Gurugram project update, where the DTCP order dated August 13, 2026 confirmed the licence and change-of-developer approval and lifted the High Court’s restriction on further allotments and third-party rights. - The management’s reference to a “robust pipeline of upcoming launches” is not accompanied in the supplied material by specific launch dates, project counts, or pre-sales guidance figures; no quantitative launch guidance is provided against which observed performance can be compared. - The management’s optimism on premium housing demand is not accompanied by specific demand or pricing guidance in the supplied material. - The company’s forward-looking statement explicitly notes that actual results could differ materially from forward-looking statements due to regulatory changes, local political or economic developments, technological risks, and other factors.
Broker Narrative
The broker narrative shifted from FY23 fears over weak presales, compressing residential margins, and rising leverage to a 2026 thesis centered on NCR expansion, large-scale project launches, and annuity/hotel cash flow growth. Launch execution risk and residential demand sensitivity persisted throughout, while the leverage headwind reversed into an expected net cash position of INR 5bn by Mar’27E. The last report remains cautiously bullish but still flags an MMR/NCR slowdown and falling annuity occupancies.
Fears that came true
- Weak presales velocity and limited FY23 launches materialized as a slowdown in MMR and NCR residential markets by the last report, a period marked by multiple negative actual returns and DISAPPOINTMENT outcomes.
- Temporary retail margin pressure at Oberoi Mall broadened into a fall in annuity rentals and occupancies, which the last report lists as a headwind alongside several negative actual returns.
Optimism that failed
- The projected 4x growth in cumulative office and retail rental revenues to Rs 12.2bn by FY25 from Commerz 3 and Borivali Mall failed to materialize, as the last report instead flags a fall in annuity rentals and occupancies.
- The launch-heavy FY24 pipeline and 15–25% QoQ ASP increase optimism did not sustain in MMR, giving way to the last report’s flagged slowdown in MMR and NCR residential markets.
Broker Timeline
50 broker calls · 2023-05-17 to 2026-10-22
CNBC-TV18: ratings, targets and commentary
No recorded CNBC-TV18 statements for this ticker.
Management comments
No recorded management comments with an explicit designation and affiliation for this ticker.
Copyright © 2023 SAS Data Analytics Pvt. Ltd. All rights reserved.