NYKAA
Equity Metrics
November 18, 2026
FSN E-Commerce Ventures Limited
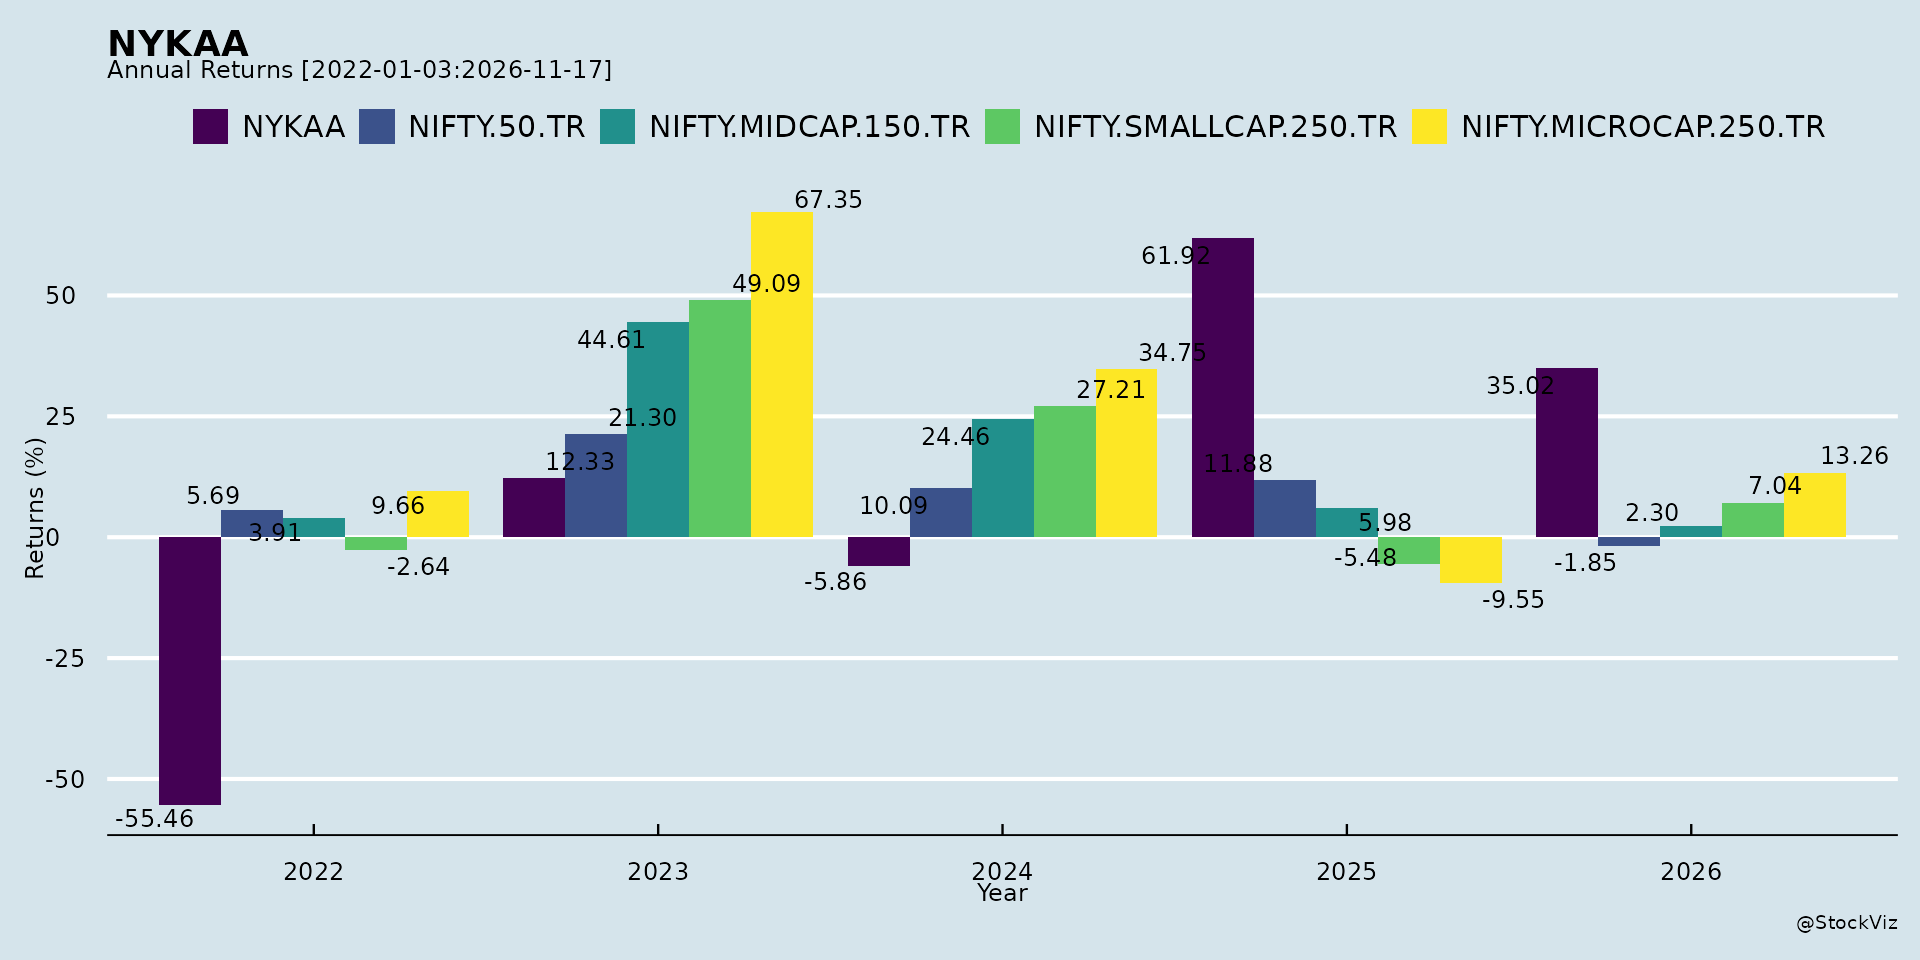
Annual Returns
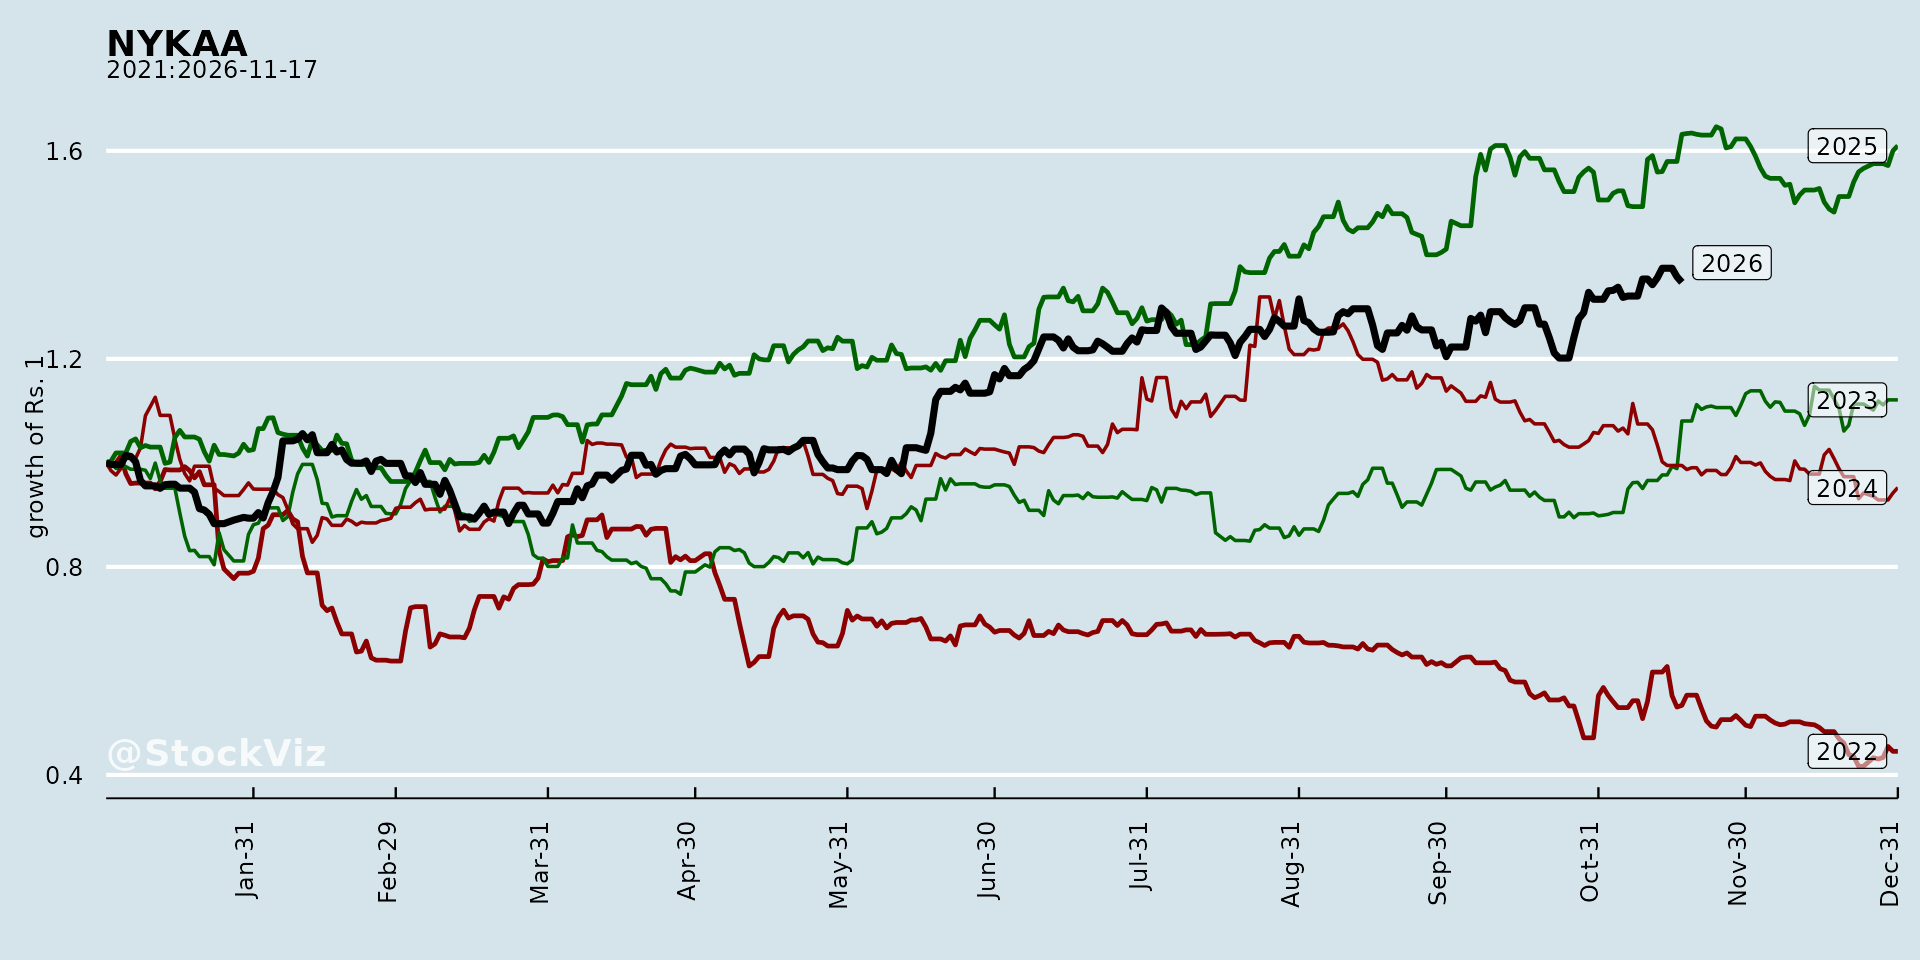
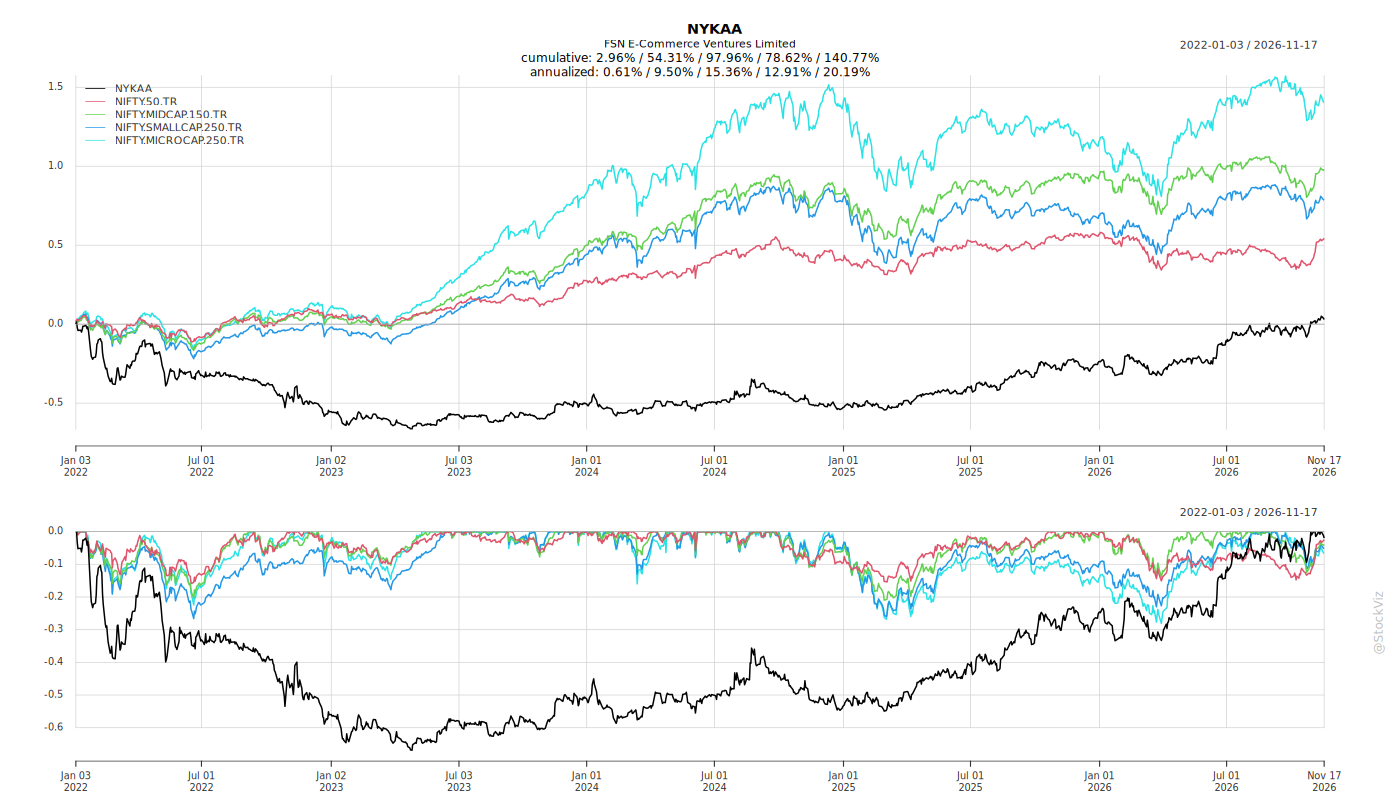
Cumulative Returns and Drawdowns
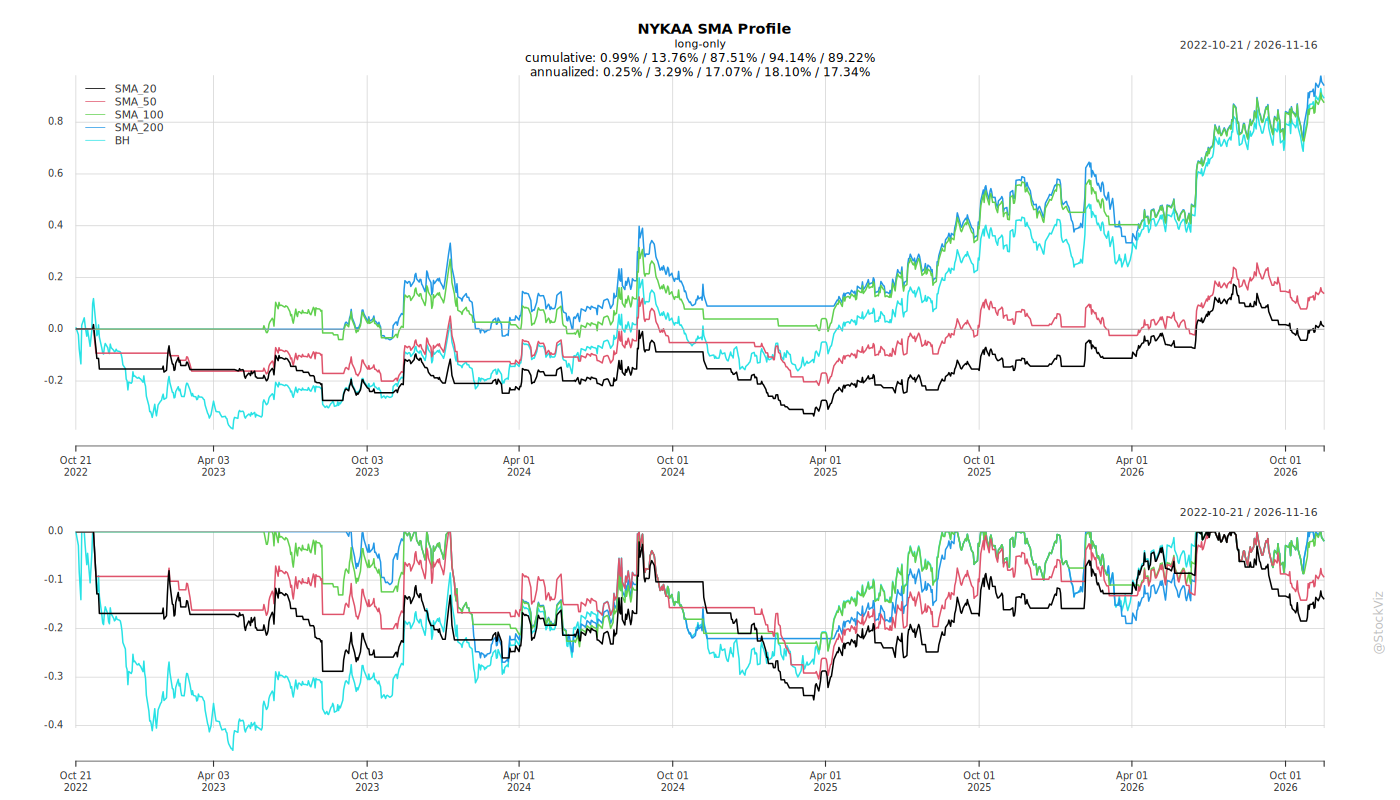
Fundamentals
Ownership
Margined
AI Summary
asof: 2026-09-14
Nykaa Q1 FY27: Growth, Profitability, and the Road Ahead
1. Headwinds and Challenges
GST-led MRP impact on Superstore. A part of the Superstore portfolio was affected by GST-led MRP reductions, which management expects to normalise over the coming quarters. This created a gap between NSV growth (28%) and GMV growth in the eB2B business. Management indicated the GST impact will start normalising from Q3 onwards, at which point NSV and GMV growth should converge.
GCC geopolitical headwinds. Nysaa, Nykaa’s Middle East omnichannel beauty offering, continues to be impacted by geopolitical headwinds in the region. Further improvement depends on external factors beyond the business’s control, though the May festive season supported a modest improvement in performance.
Fulfillment cost pressure. Fulfillment expenses increased 42 basis points, driven by continued investment in infrastructure expansion and the point-to-point fulfillment cost of Nykaa Now orders. A one-off impact from the new labour code also raised fulfillment costs in the Superstore business.
Warehouse inventory theft. Inventory theft at one of the subsidiary’s warehouses resulted in an expense of Rs. 10.38 crore during the year ended March 31, 2026.
Seasonality and order volume. Beauty order volumes dipped 1% quarter-on-quarter (17.5 million to 17.3 million). Management attributed this to normal seasonal patterns, noting Q3 is typically the strongest quarter due to festive demand and flagship sales, and encouraged year-on-year comparison, which showed approximately 20% growth.
Festive timing shift. Some festive dates are expected to fall in Q3, with a possibility that some benefit accrues in Q4 if dates are pushed later. Management noted most dates appear to be falling in Q3.
2. Tailwinds and Growth Prospects
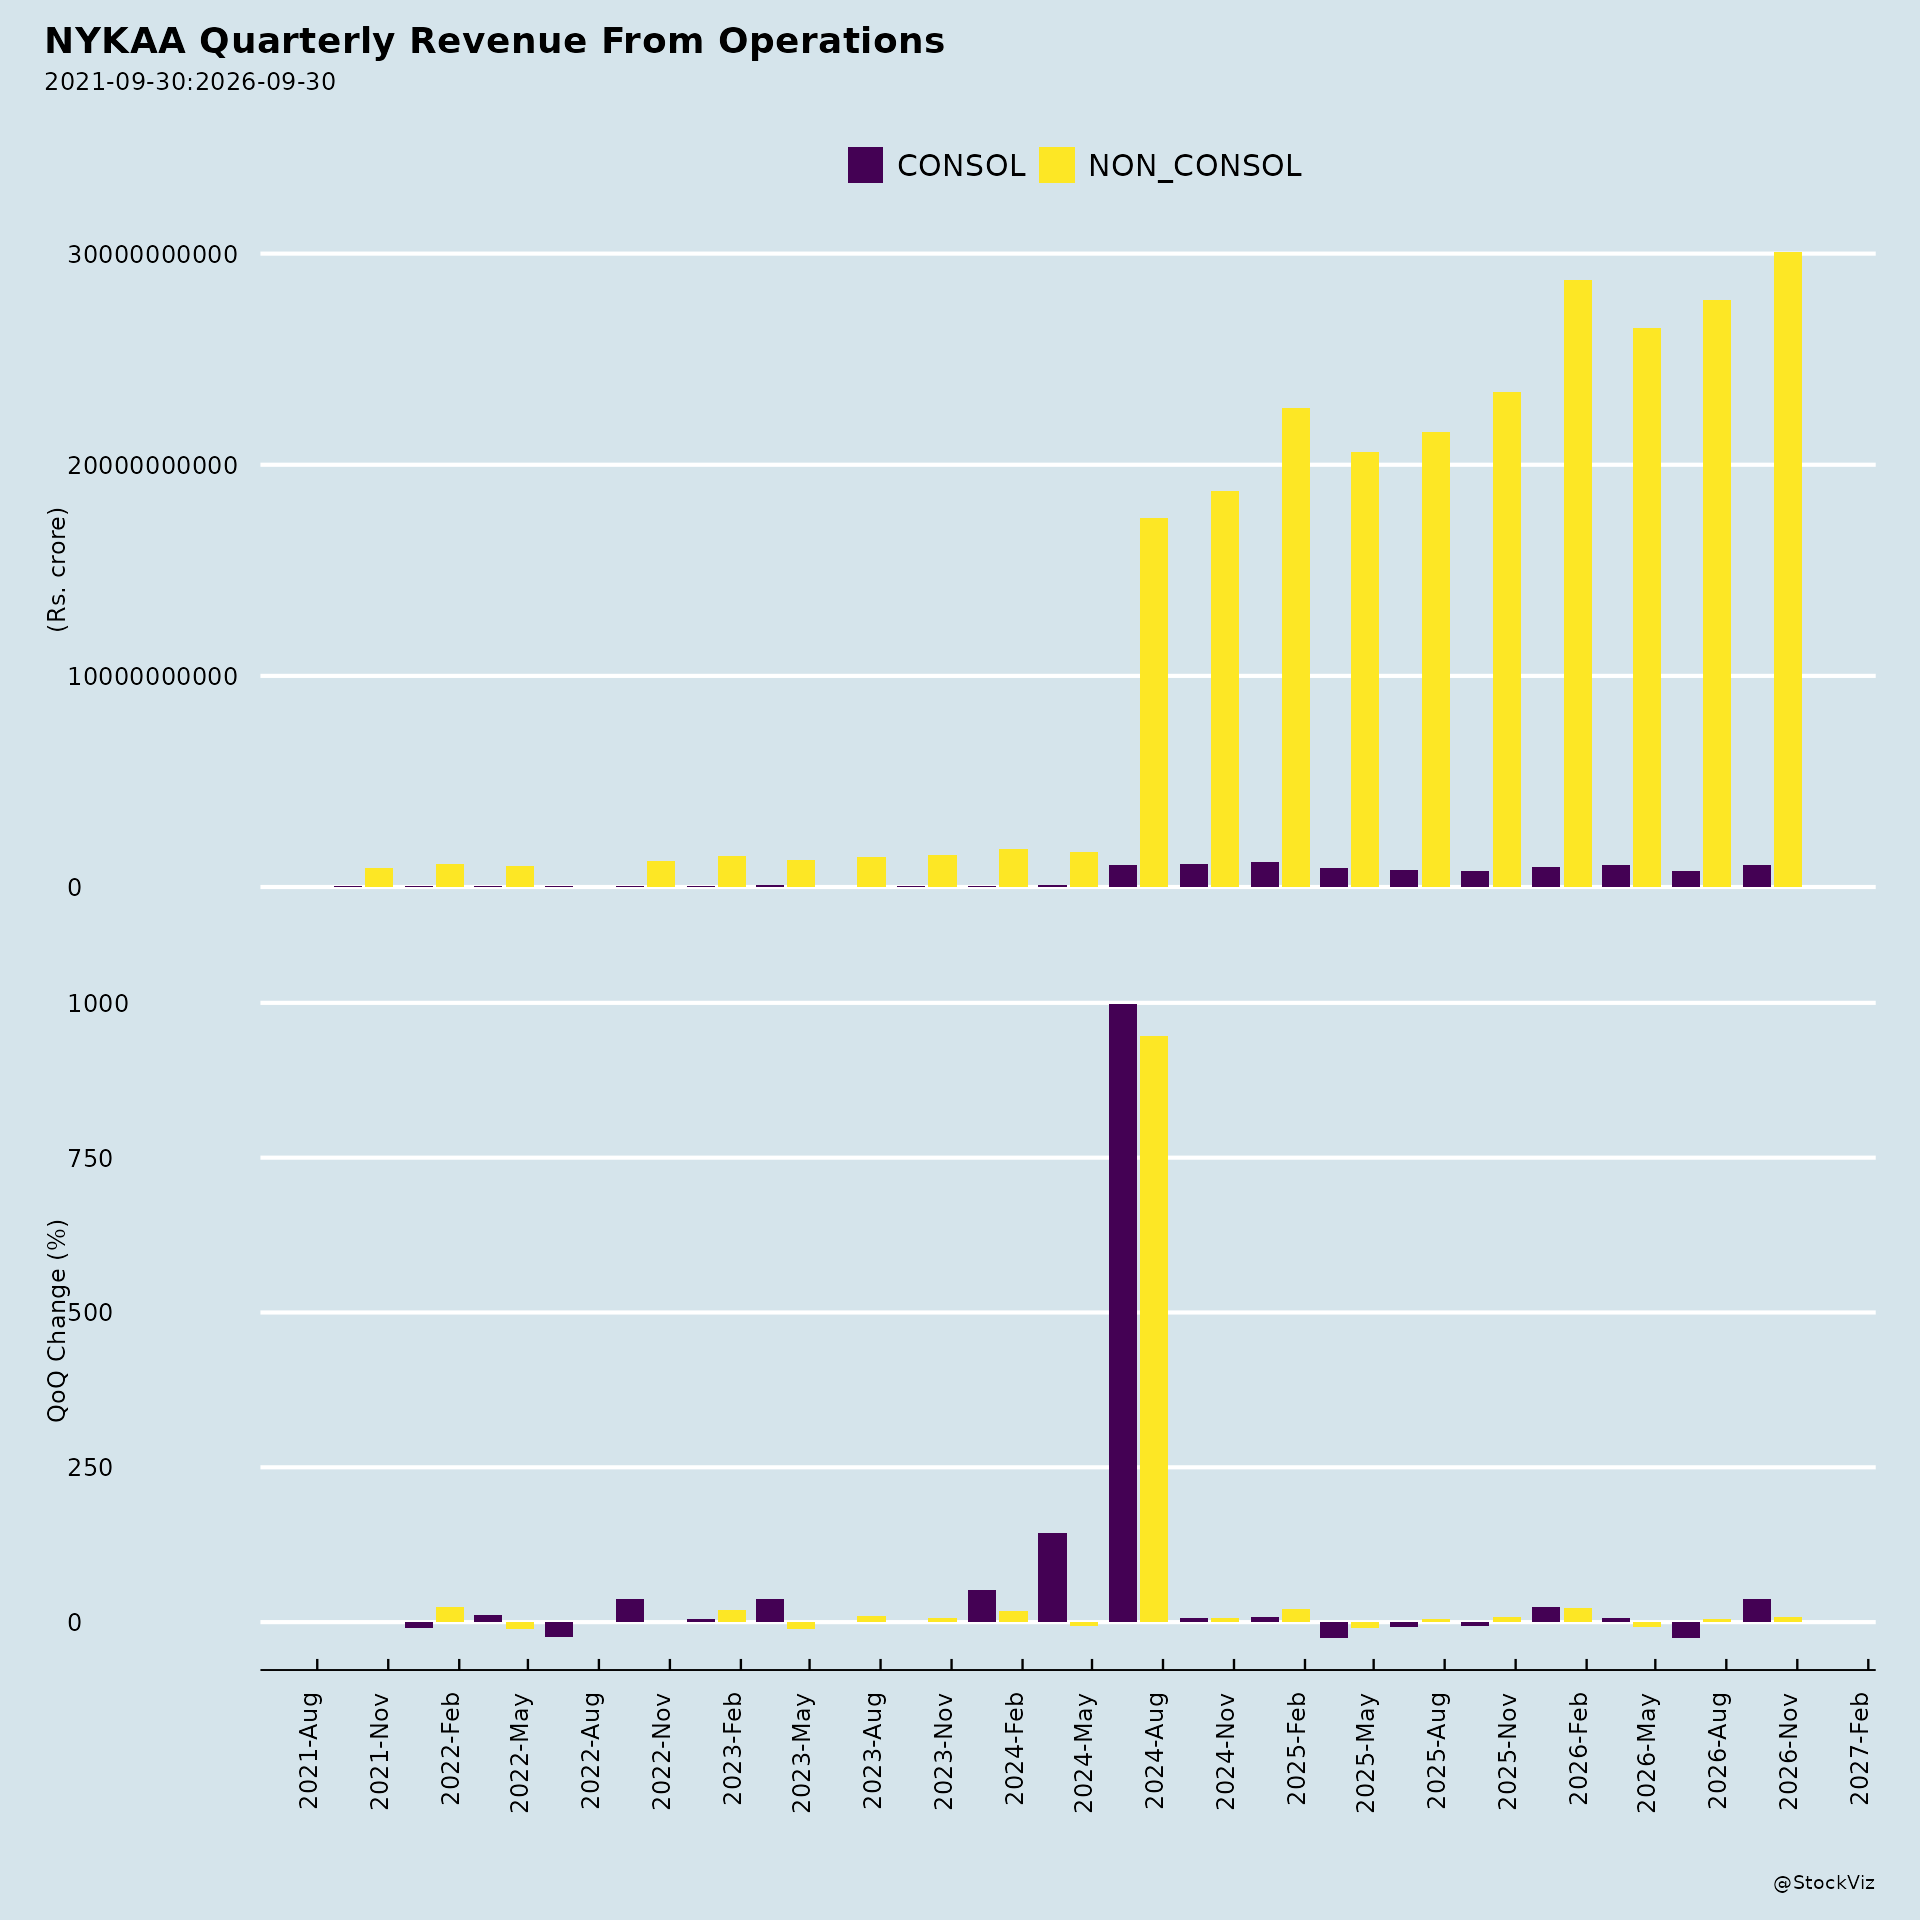
Accelerating growth across verticals. Consolidated GMV grew 34% year-on-year to Rs. 5,590 crore, and net revenue grew 29% to Rs. 2,782 crore. Beauty NSV growth stood at 29%, accelerating from mid-20s growth in prior quarters. Fashion delivered a standout quarter with NSV growth of 54% versus 20% a year ago.
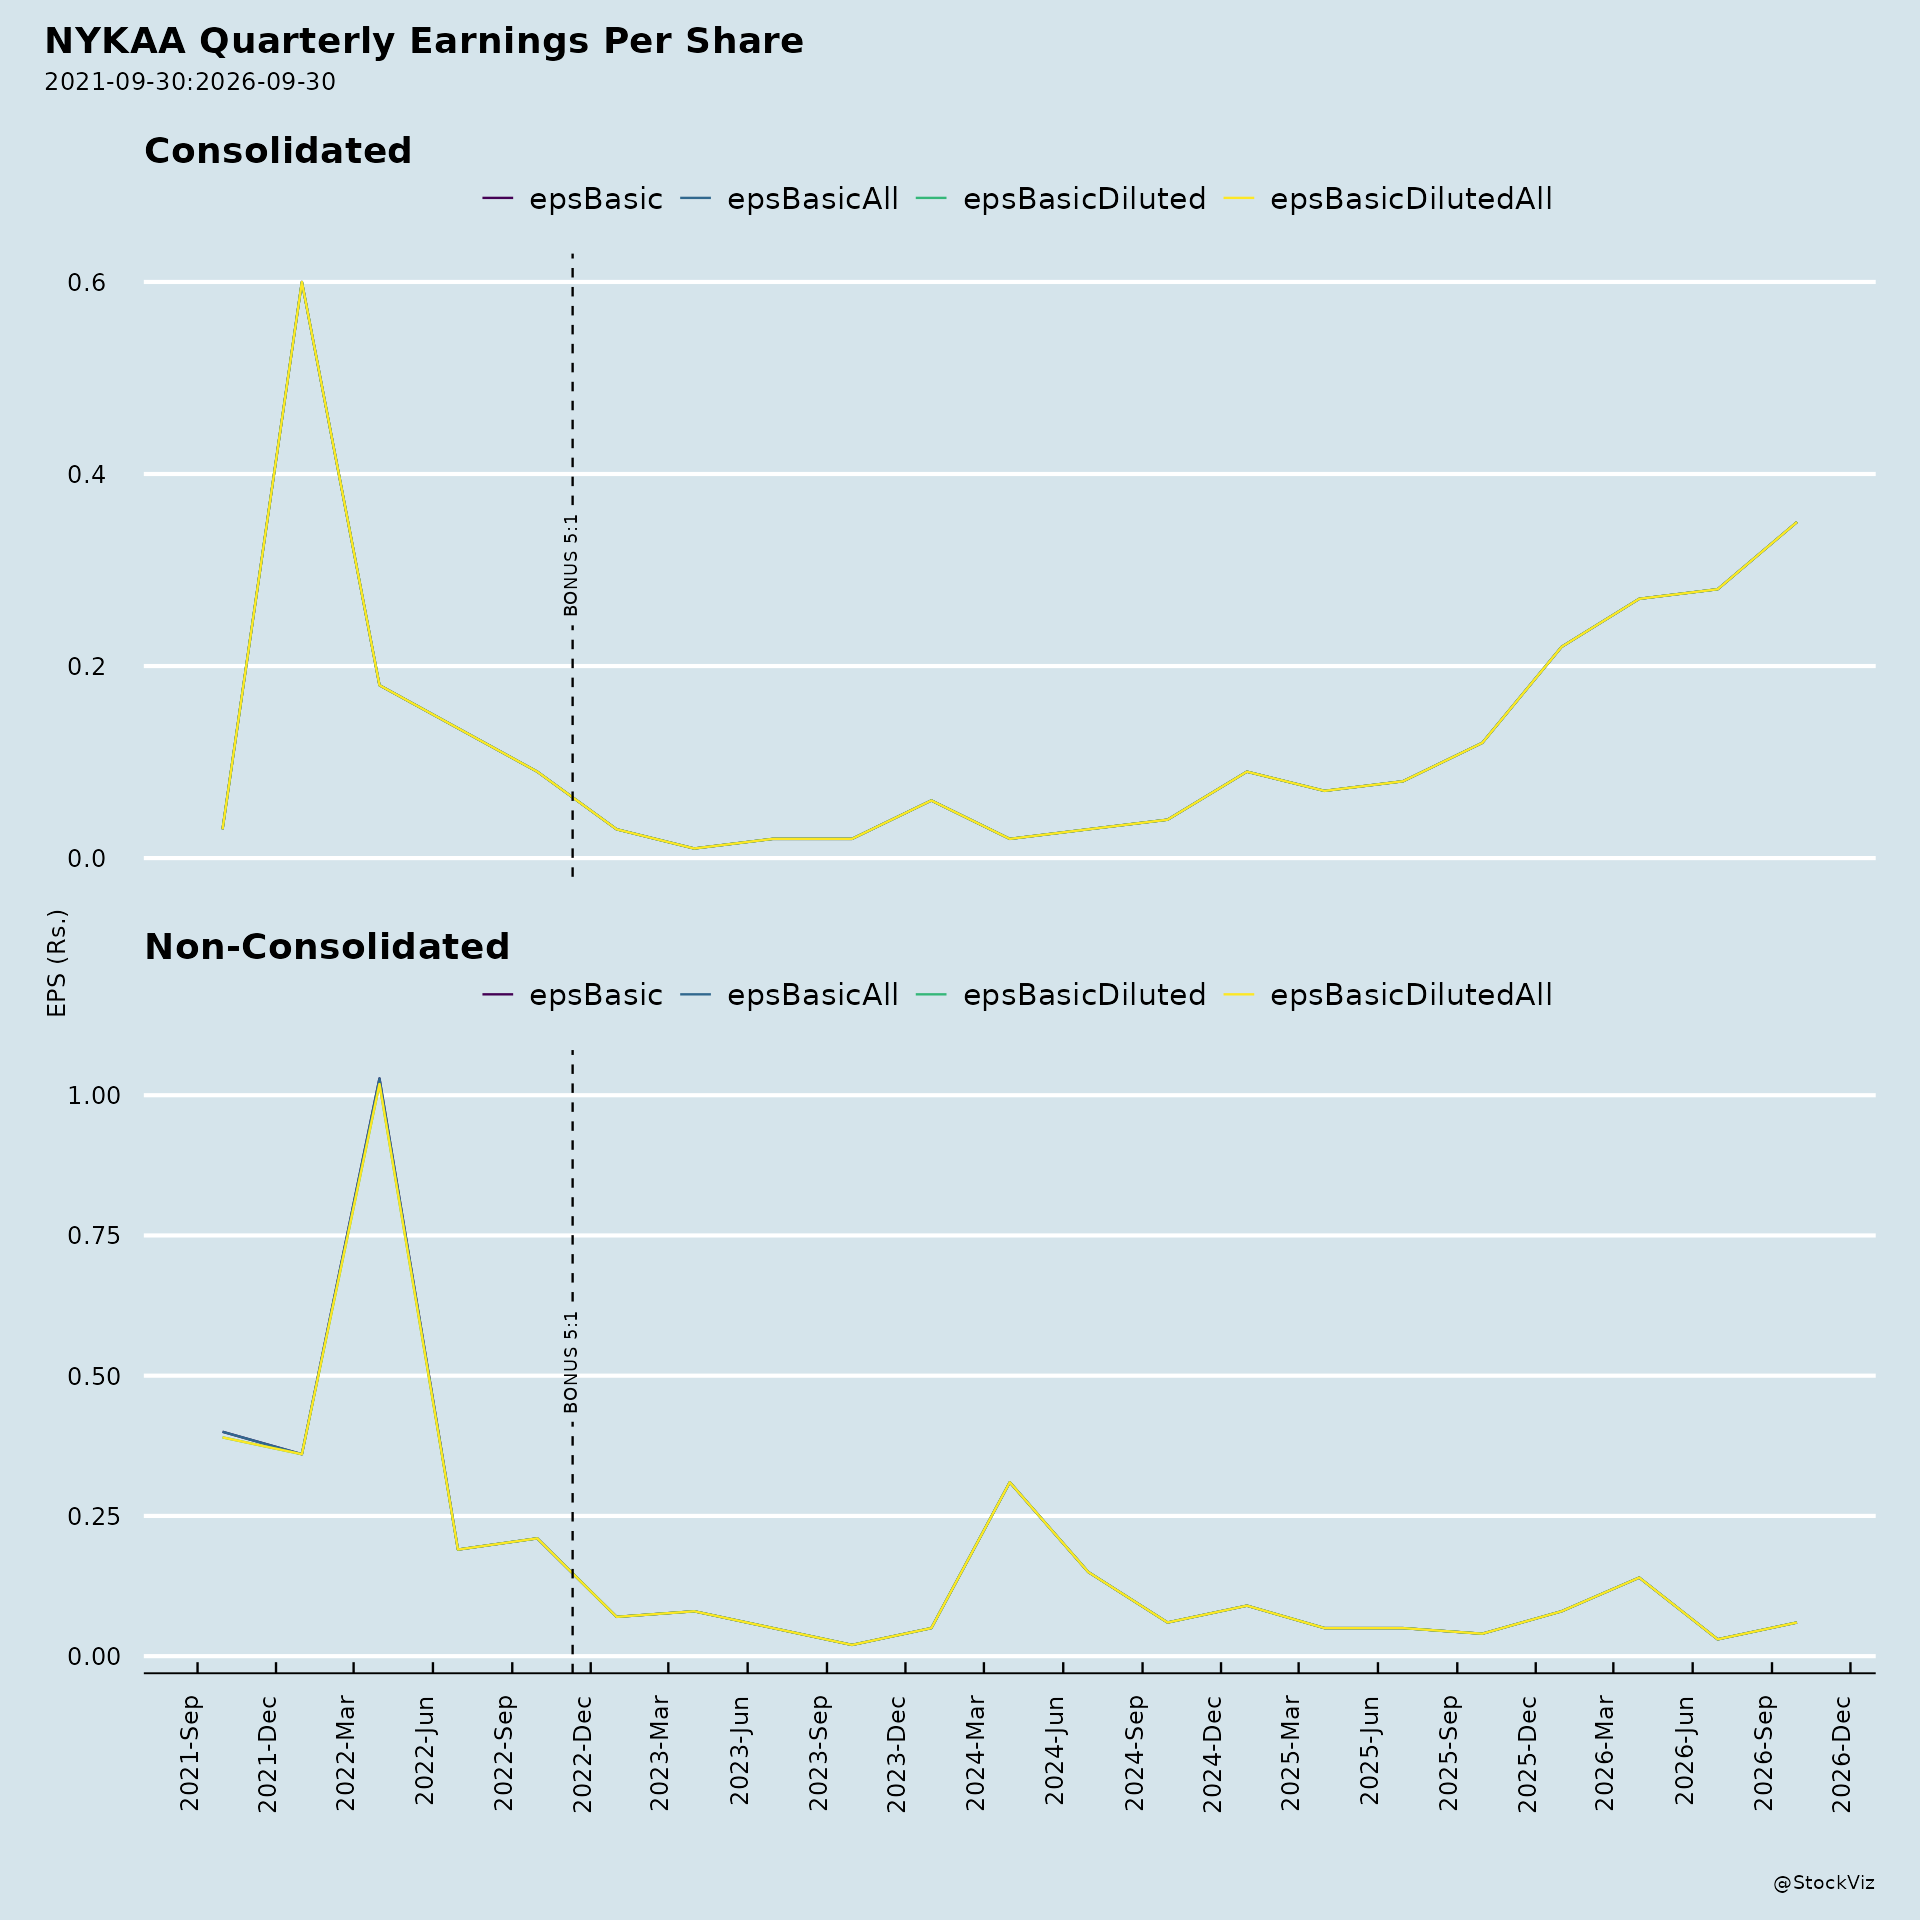
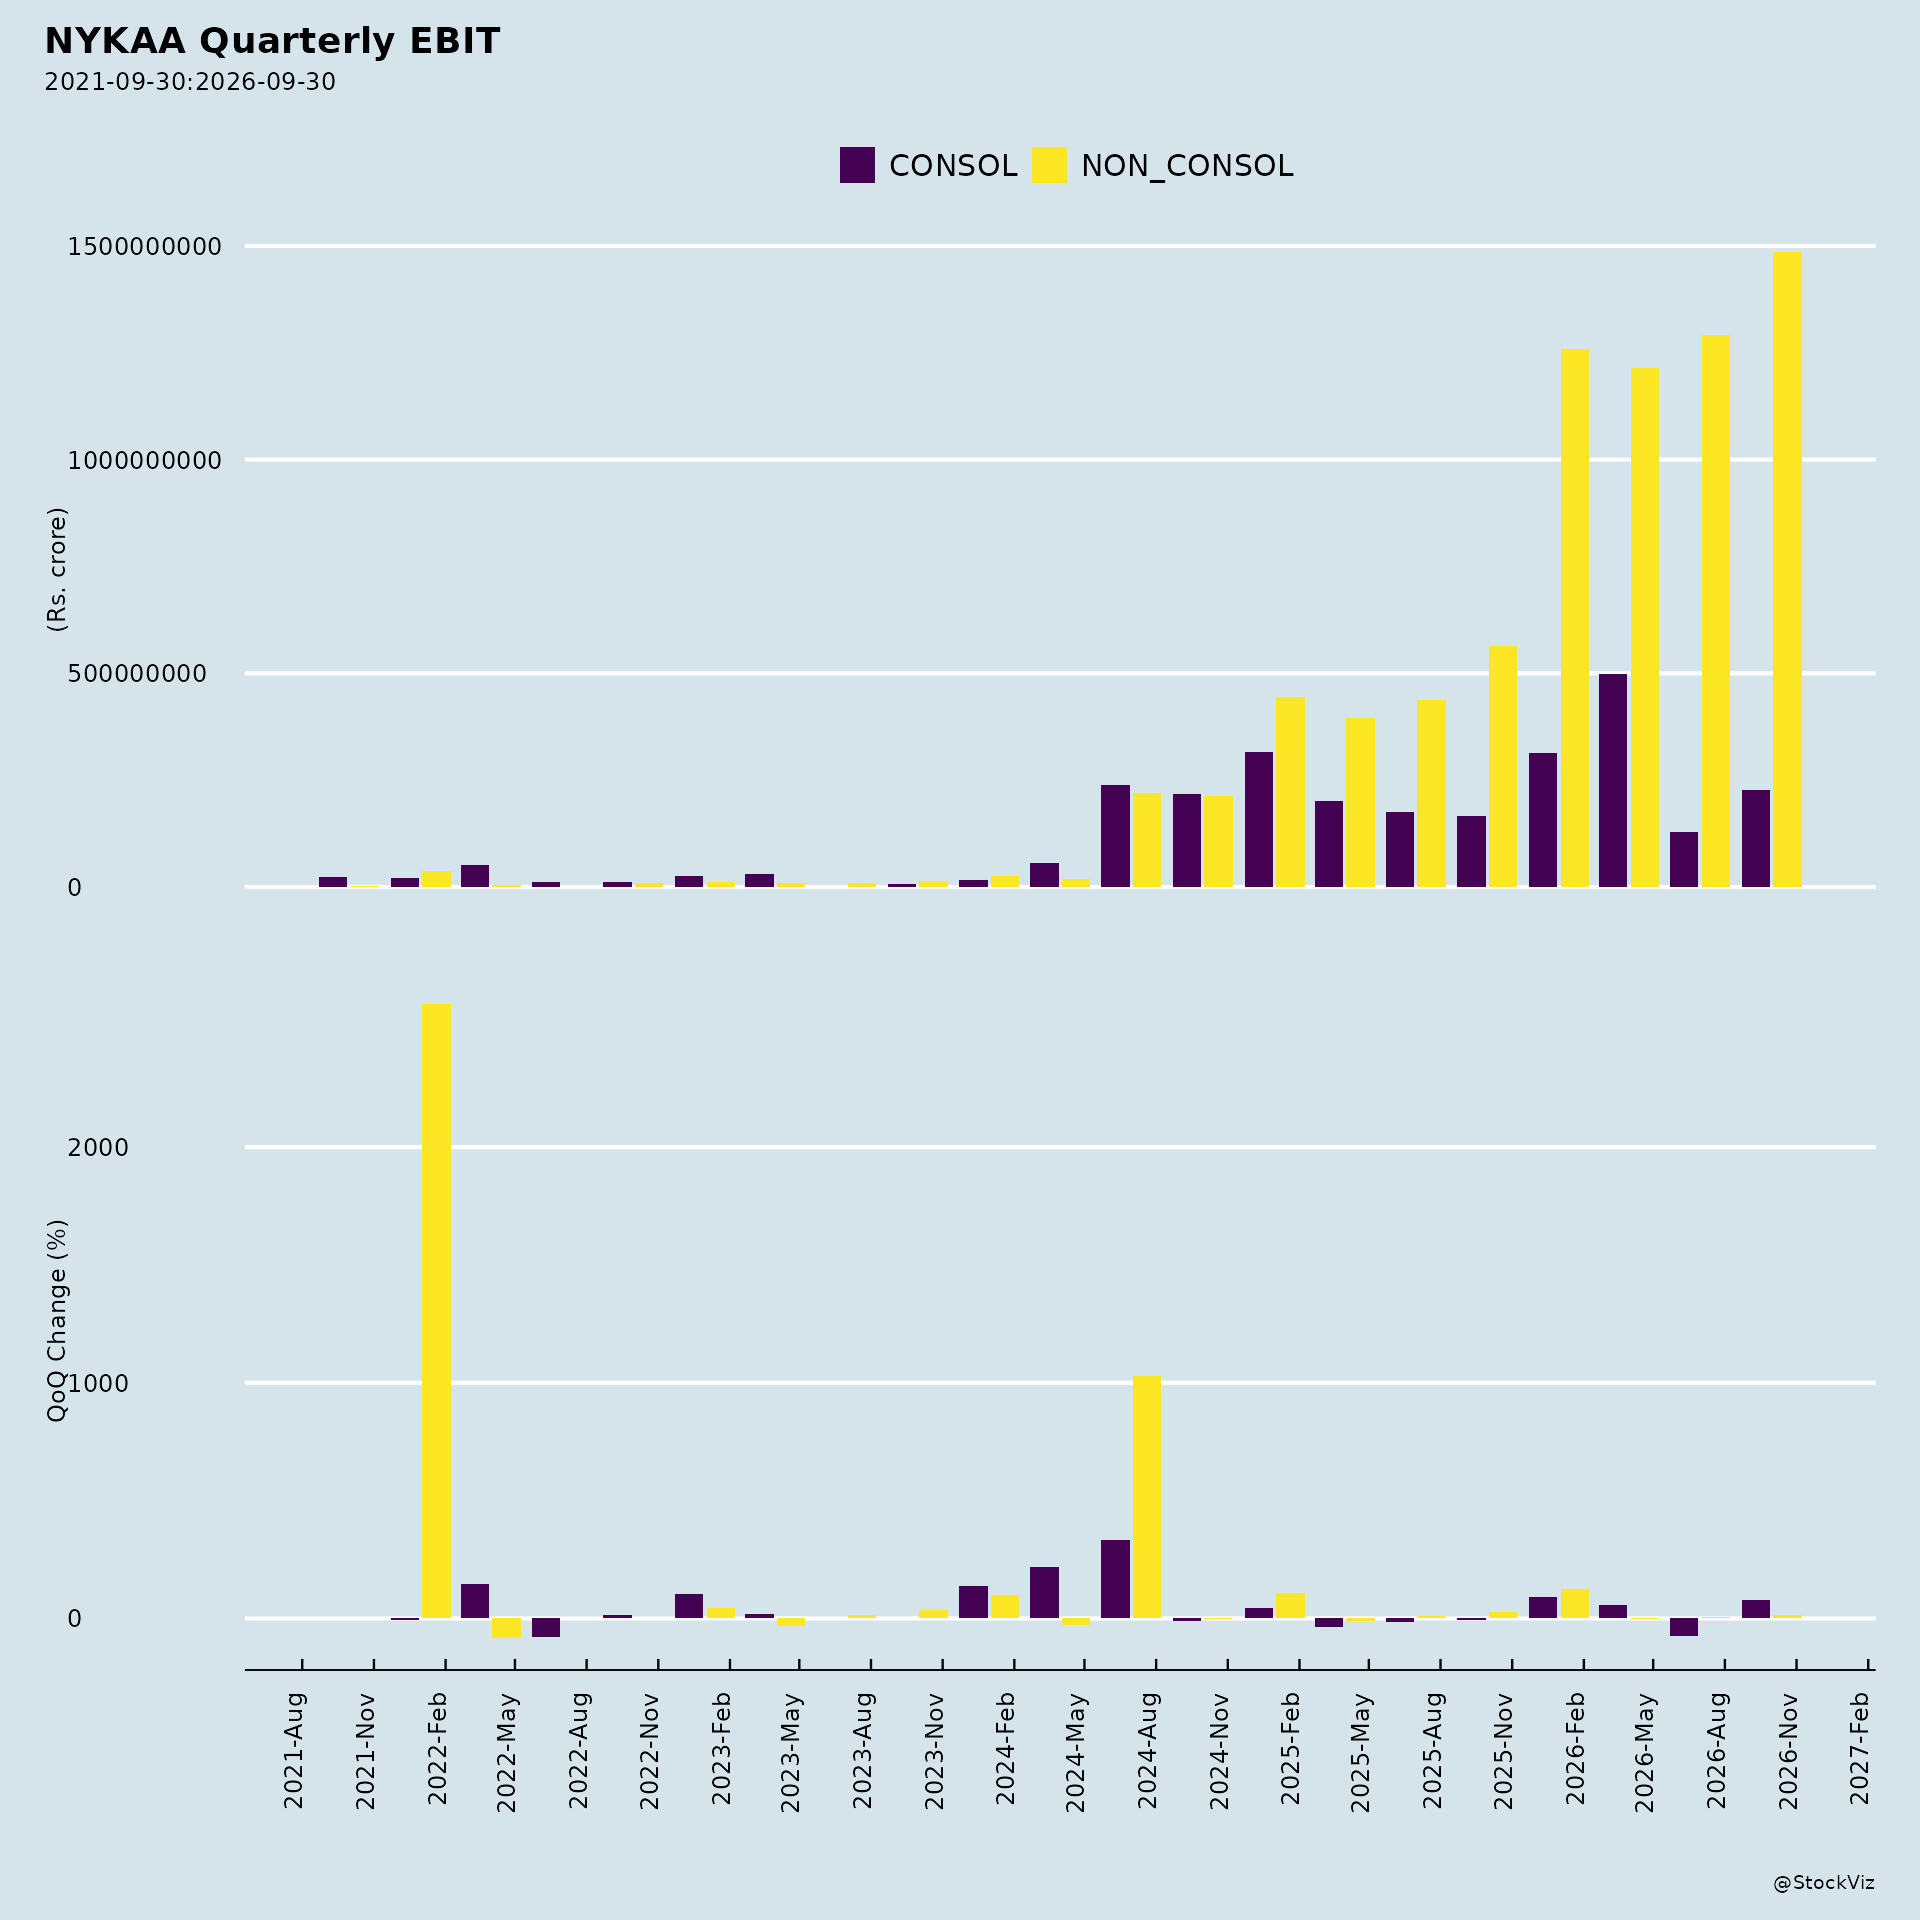
Profitability expansion. EBITDA grew 68% year-on-year to Rs. 236 crore, with margins expanding to 8.5% from 6.5%. PAT grew 226% to Rs. 80 crore. Beauty EBITDA margin reached 10.3%, while Fashion moved from negative 6.2% EBITDA margin in Q1 FY26 to 0.1% in Q1 FY27, with the fashion business remaining profitable after Q4.
Nykaa Now expansion. The quick delivery platform expanded from 3 cities with limited assortment in Q1 FY26 to 13 cities with over 1,000 brands, delivering within 30–60 minutes. Management plans to reach 25+ cities by the end of FY27. Early read suggests the proposition is not EBITDA-dilutive, with increased purchase frequency and AOVs consistent with mainline orders.
Brand partnerships and launches. Rare Beauty launched in June 2026 and quickly became a top 5 premium brand on the platform. Other launches included SK-II, K18, Judydoll, and Dr. Reju-All. Nike is now among the top 3 brands on the fashion platform, with over 1.5 million app installs within six months of the D2C partnership launch.
Retail network expansion. Nykaa operates 324 stores across 105 cities, with total retail space up 29% year-on-year to approximately 3.3 lakh sq. ft. The largest-ever Nykaa Luxe store opened at Ambience Mall, Vasant Kunj, spanning over 5,000 sq. ft. Same-store sales growth was double-digit, and 50% of stores are in Tier 2 cities and beyond.
House of Nykaa scaling. The portfolio achieved an annualized GMV run rate of approximately Rs. 3,758 crore, growing 39% year-on-year, with NSV of Rs. 550 crore (36% growth). The portfolio now includes 13 brands, with Dot & Key at a Rs. 1,300 crore annualized NSV run rate, Kay Beauty at Rs. 300 crore, and Nykaa Cosmetics at Rs. 270 crore.
Aminu acquisition. Nykaa acquired a 51% majority stake in Aminu Wellness Private Limited, a premium dermocosmetic skincare brand, for consideration of up to Rs. 32 crore. Aminu reported Rs. 19 crore in FY26 net revenue, grew 8x over three years, and is profitable. The acquisition is expected to close by September 15, 2026, subject to regulatory approvals. The remaining 49% will be acquired over the next few years on pre-agreed terms.
Earth Rhythm stake increase. The company increased its shareholding in Earth Rhythm Private Limited by an additional 24.2%, with corresponding shares credited to the company’s demat account.
AI-led initiatives. Virtual Closet, launched May 26, 2026, has powered over 200,000 virtual avatars and achieved 2x higher conversion among users. AskNykaa serves as a conversational search engine, and Nynaa, the AI voice assistant, resolves nearly half of customer calls at human quality.
Superstore growth. The eB2B platform serves 1,200+ cities with over 523,000 registered retailers, up 30% year-on-year. NSV grew 28%, driven by network expansion and higher AOV from existing retailers. EBITDA improved by more than 300 basis points.
Customer base expansion. Over 60 million cumulative consumers have ever bought from Nykaa, a 33% year-on-year growth. Beauty annual unique transacting customers crossed 20 million. Fashion cumulative customers reached 12 million, growing 34% year-on-year, with customer acquisition costs down 30% over two years.
3. Key Risks
Dependence on external factors in GCC. Nysaa’s performance improvement depends on geopolitical conditions beyond the business’s control.
Execution risk in Nykaa Now expansion. The plan to reach 25+ cities by FY27 involves increased fulfillment costs, though management currently views the proposition as accretive from an LTV perspective.
Inventory and fulfillment cost management. Fulfillment expenses rose 42 basis points, and the new labour code created a one-off impact. Managing these costs while expanding quick delivery and infrastructure remains a focus area.
Seasonality and festive timing. A portion of business depends on festive demand, which is concentrated in Q3. Shifts in festive timing could affect quarterly comparisons.
Integration and scaling of acquisitions. The Aminu acquisition involves integrating a founder-run business and executing on pre-agreed terms for acquiring the remaining stake over the next few years.
Competitive intensity in quick commerce. Nykaa Now competes with horizontal quick commerce platforms, though management differentiates through wider beauty assortment and authenticity.
4. Management Guidance vs. Observed Performance
Superstore growth guidance. Management had guided to 35%+ CAGR for Superstore. Observed NSV growth was 28%, with GMV lower due to GST-led MRP impact. Management attributed the gap to the GST impact, which is expected to normalise from Q3, and outlined three levers to reach guidance: expanding retailer network, adding wellness categories, and leveraging data science. Management stated they expect to be on guidance by FY2030.
Fashion growth guidance. Management reiterated guidance of 3 to 3.5x growth over a 4- to 5-year period, shared at the Investor Day. Observed Q1 FY27 NSV growth was 54%, with management noting the numbers largely reflect underlying platform growth, and expressing confidence in continued healthy growth irrespective of adding partners like Nike.
Nykaa Now EBITDA impact. Management’s hypothesis was that Nykaa Now would not be dilutive and would increase purchase frequency. Observed performance showed no EBITDA margin dilution despite Nykaa Now reaching meaningful scale in metros, with EBITDA improvement in the quarter. Management noted AOVs for Nykaa Now orders are not meaningfully different from mainline orders.
Aminu acquisition timeline. Management guided the acquisition to close by September 15, 2026, subject to regulatory approvals and closing conditions. The transaction was announced August 4, 2026.
Marketing efficiency. Management noted marketing costs have been protected at similar levels while pushing customer acquisition. Observed performance showed marketing efficiency improvement of 42 basis points in Beauty, and a 534 basis points improvement in Fashion’s marketing and S&D expenses to 22.9%, driven by lower CAC and better customer retention.
Capital efficiency. Management highlighted prudent capital utilization. Observed performance showed fixed asset turnover improved to 10.7x from 9.9x in FY26, working capital days sustained under 30, and ROCE improved to 26.8% from 21.2% in FY26.
Broker Narrative
The same fears persisted and sharpened: the first report’s risks of “further slowdown in discretionary spending”, “slower fashion growth relative to BPC … adverse mix” and “competition” reappear in the last report as “Demand slowdown in discretionary space”, “Slower-than-expected profitability in Fashion” and “Intense competition across platforms and D2C brands”, now joined by “Higher customer acquisition cost”/“High sales & marketing intensity” plus new authenticity, cosmetics ingredient/supply-chain-compliance and urban-concentration risks. The bull case narrowed from a broad multi-name e-commerce/B2B tailwind (Zomato, IndiaMART, Just Dial, Nazara, Matrimony, Delhivery PTL) to Nykaa-specific drivers — BPC premiumisation, >42mn users, House of Nykaa brands, ~338 stores, Superstore eB2B and AI-led self-serve — with Fashion recast from early mix-drag to “turnaround to breakeven”. Yet every actual return is positive (up to +115.5%) and all Reduce/Sell calls are DISAPPOINTMENTs, so the early headwinds never produced a negative price outcome and the BPC/online-share/B2B tailwinds carried into the last report.
Broker Timeline
24 broker calls · 2023-07-10 to 2026-10-19
CNBC-TV18: ratings, targets and commentary
No recorded CNBC-TV18 statements for this ticker.
Management comments
No recorded management comments with an explicit designation and affiliation for this ticker.
Copyright © 2023 SAS Data Analytics Pvt. Ltd. All rights reserved.