NUVAMA
Equity Metrics
September 24, 2026
Nuvama Wealth Management Limited
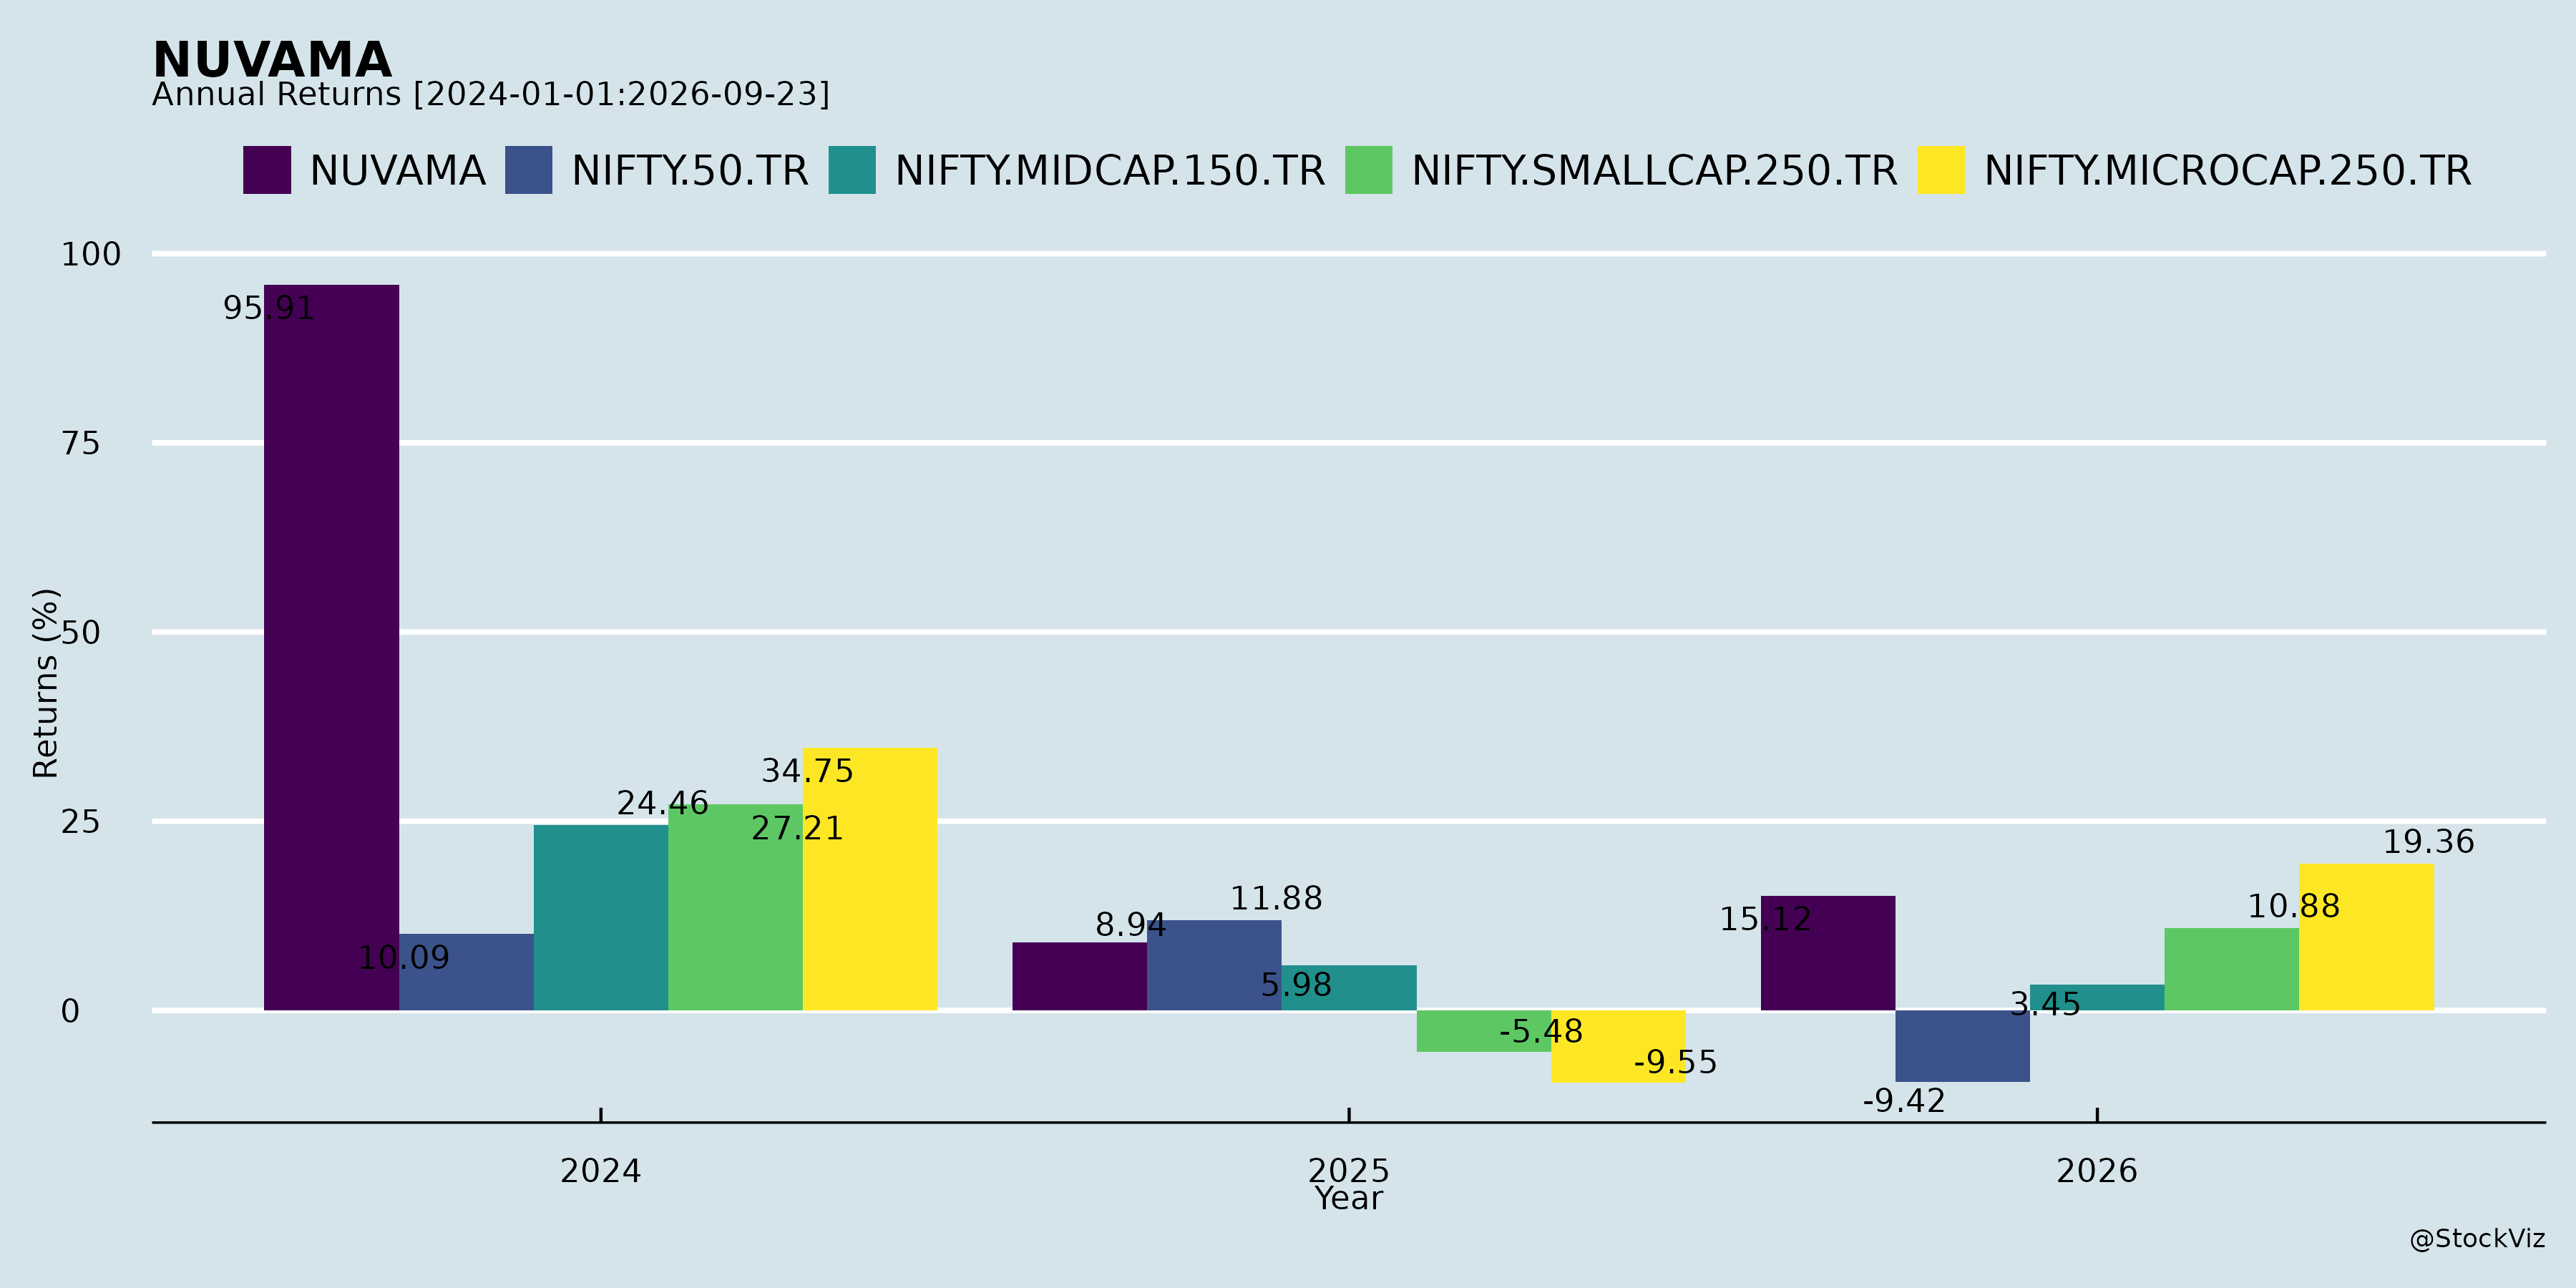
Annual Returns

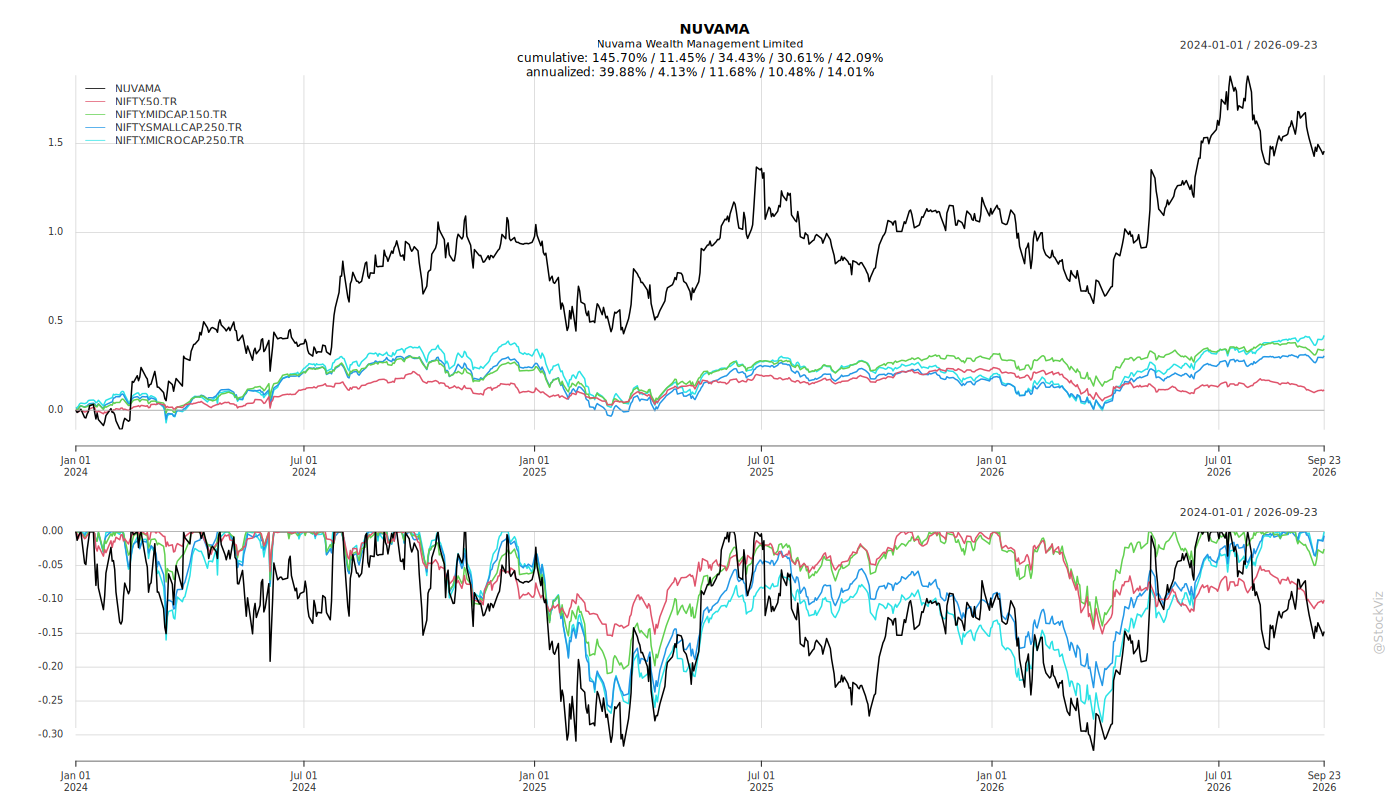
Cumulative Returns and Drawdowns
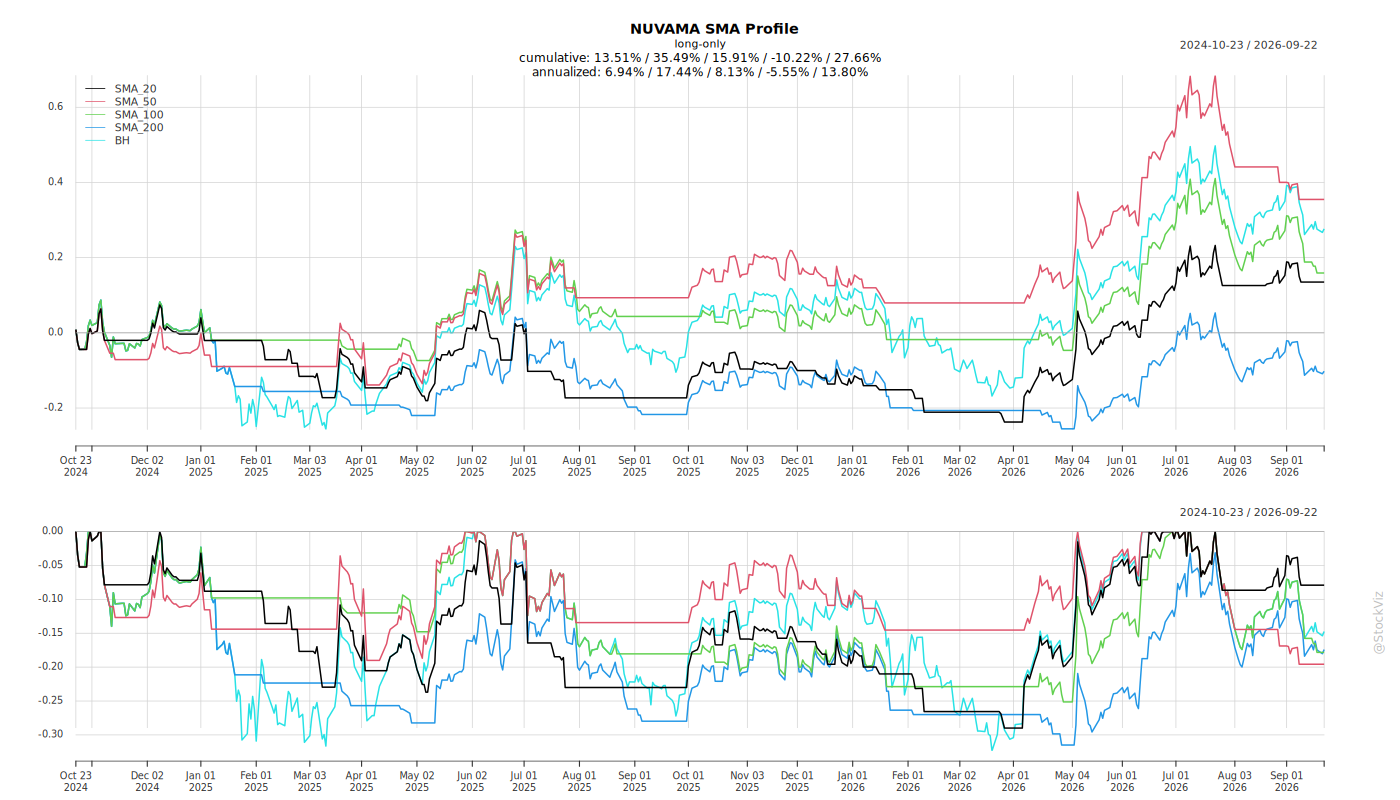
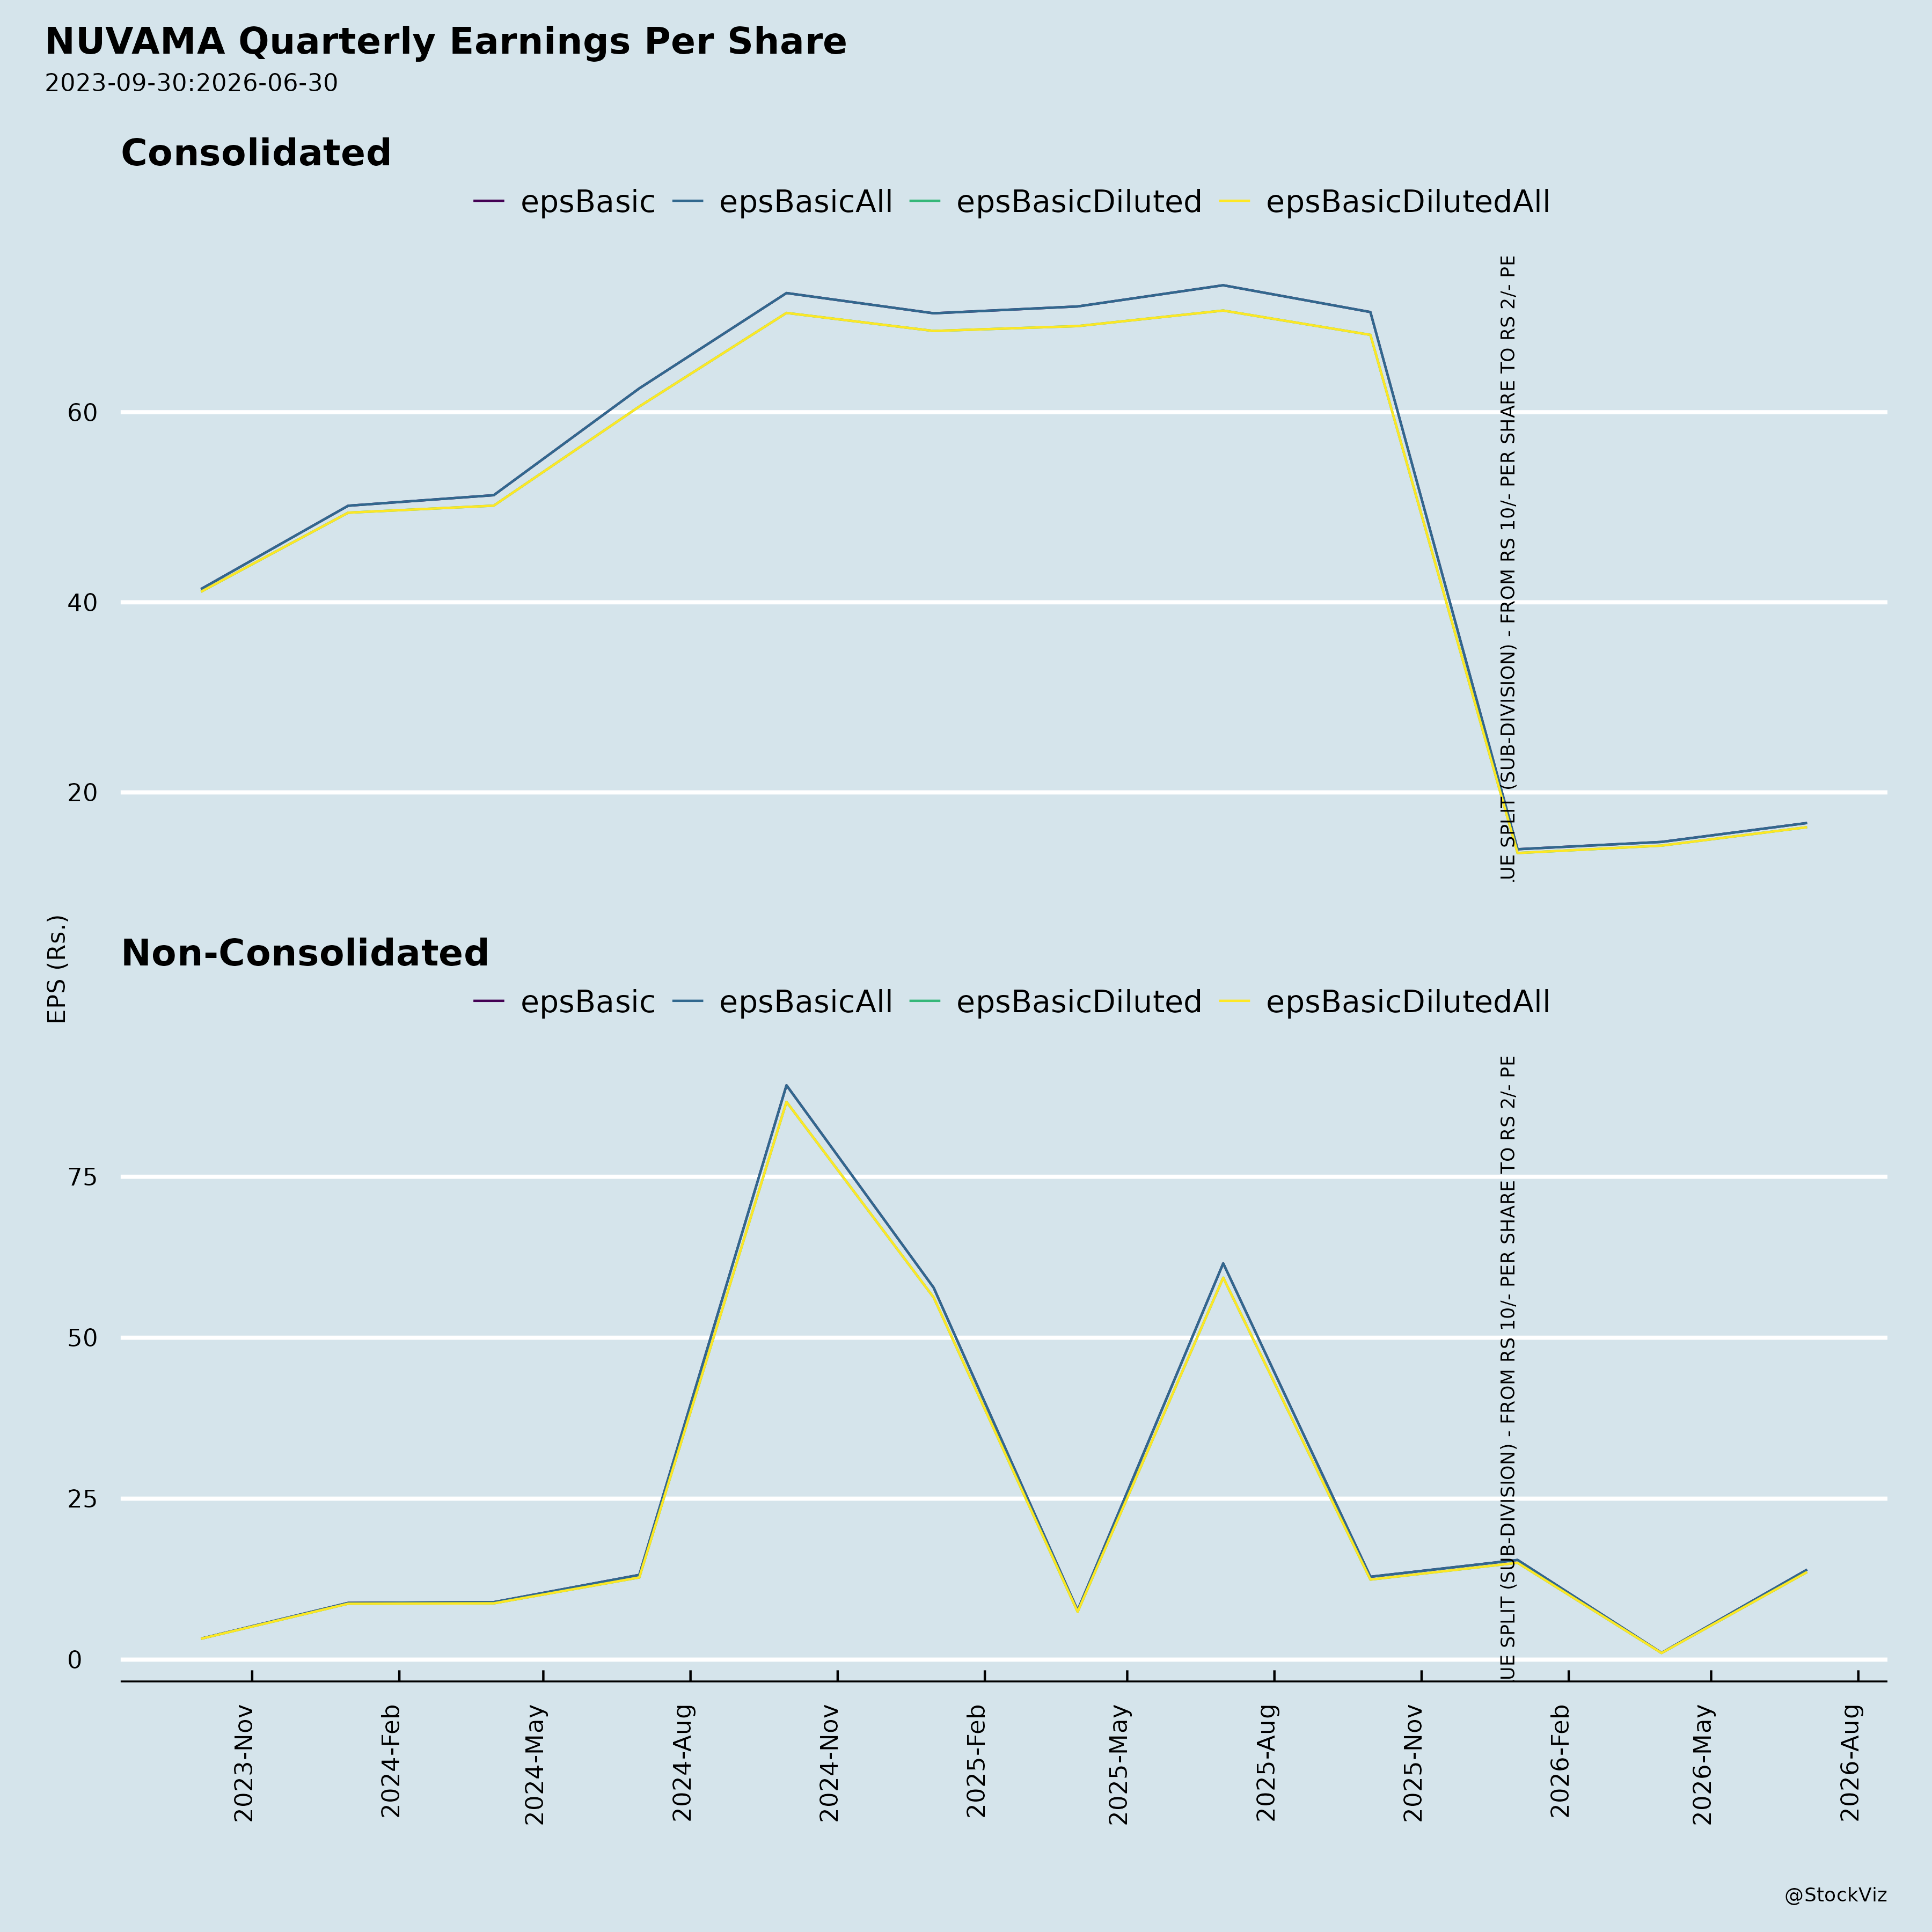
Fundamentals
Ownership
Margined
AI Summary
asof: 2026-09-16
Nuvama Wealth Management: Recent Announcements Summary
Headwinds and Challenges
Nuvama operates against a backdrop of heightened global uncertainty. The company flags tariff-led and trade protectionism developments, geopolitical tensions including conflicts involving the US, Iran, and Israel, supply chain disruptions, volatile capital flows, and market corrections as external pressures. Domestically, it notes moderate corporate earnings growth in certain sectors and increasing competitive intensity across the wealth management industry.
On the regulatory and legal front, Nuvama Clearing Services Limited (NCSL) and V-Rise Securities Private Limited have faced legal proceedings and regulatory matters concerning margin shortfalls, along with investigations by the Economic Offence Wing (EOW) relating to Anugrah Stock and Broking Private Limited, including unencumbered asset undertaking requirements.
Tailwinds and Growth Prospects
The company points to India as one of the fastest-growing major economies globally, with structural growth drivers including rising formalisation, digital adoption, infrastructure investments, and increasing participation in financial markets. India is projected to add over USD 2 trillion in financial wealth by 2030, supported by rising affluence, wealth succession, and formalisation of family offices.
Specific growth actions include the acquisition of an additional 26% equity stake in Pickright Technologies Private Limited, making it a wholly owned subsidiary, and an investment not exceeding Rs. 100 crores in Nuvama Asset Management Limited (NAML), which has received SEBI approval to act as an Asset Management Company for Nuvama Mutual Fund. The Board also approved raising funds via Non-convertible Debentures not exceeding Rs. 500 crores.
Key Risks
Beyond the geopolitical, trade, and market risks noted above, the legal and regulatory proceedings involving NCSL and V-Rise Securities—including the EOW investigation tied to Anugrah Stock and Broking—represent ongoing matters requiring attention. Competitive intensity in wealth management poses a risk to franchise positioning and pricing.
Management Guidance vs. Observed Performance
For FY 2026, total revenue reached Rs 3,122 crore, operating PAT was Rs 1,049 crore, and client assets surpassed Rs 4.5 lakh crore, with return on equity of 28.1%, a cost-to-income ratio of 56%, and dividend payout of approximately 49%. The company completed a sub-division of equity shares from a face value of Rs 10 to Rs 2 each during the year.
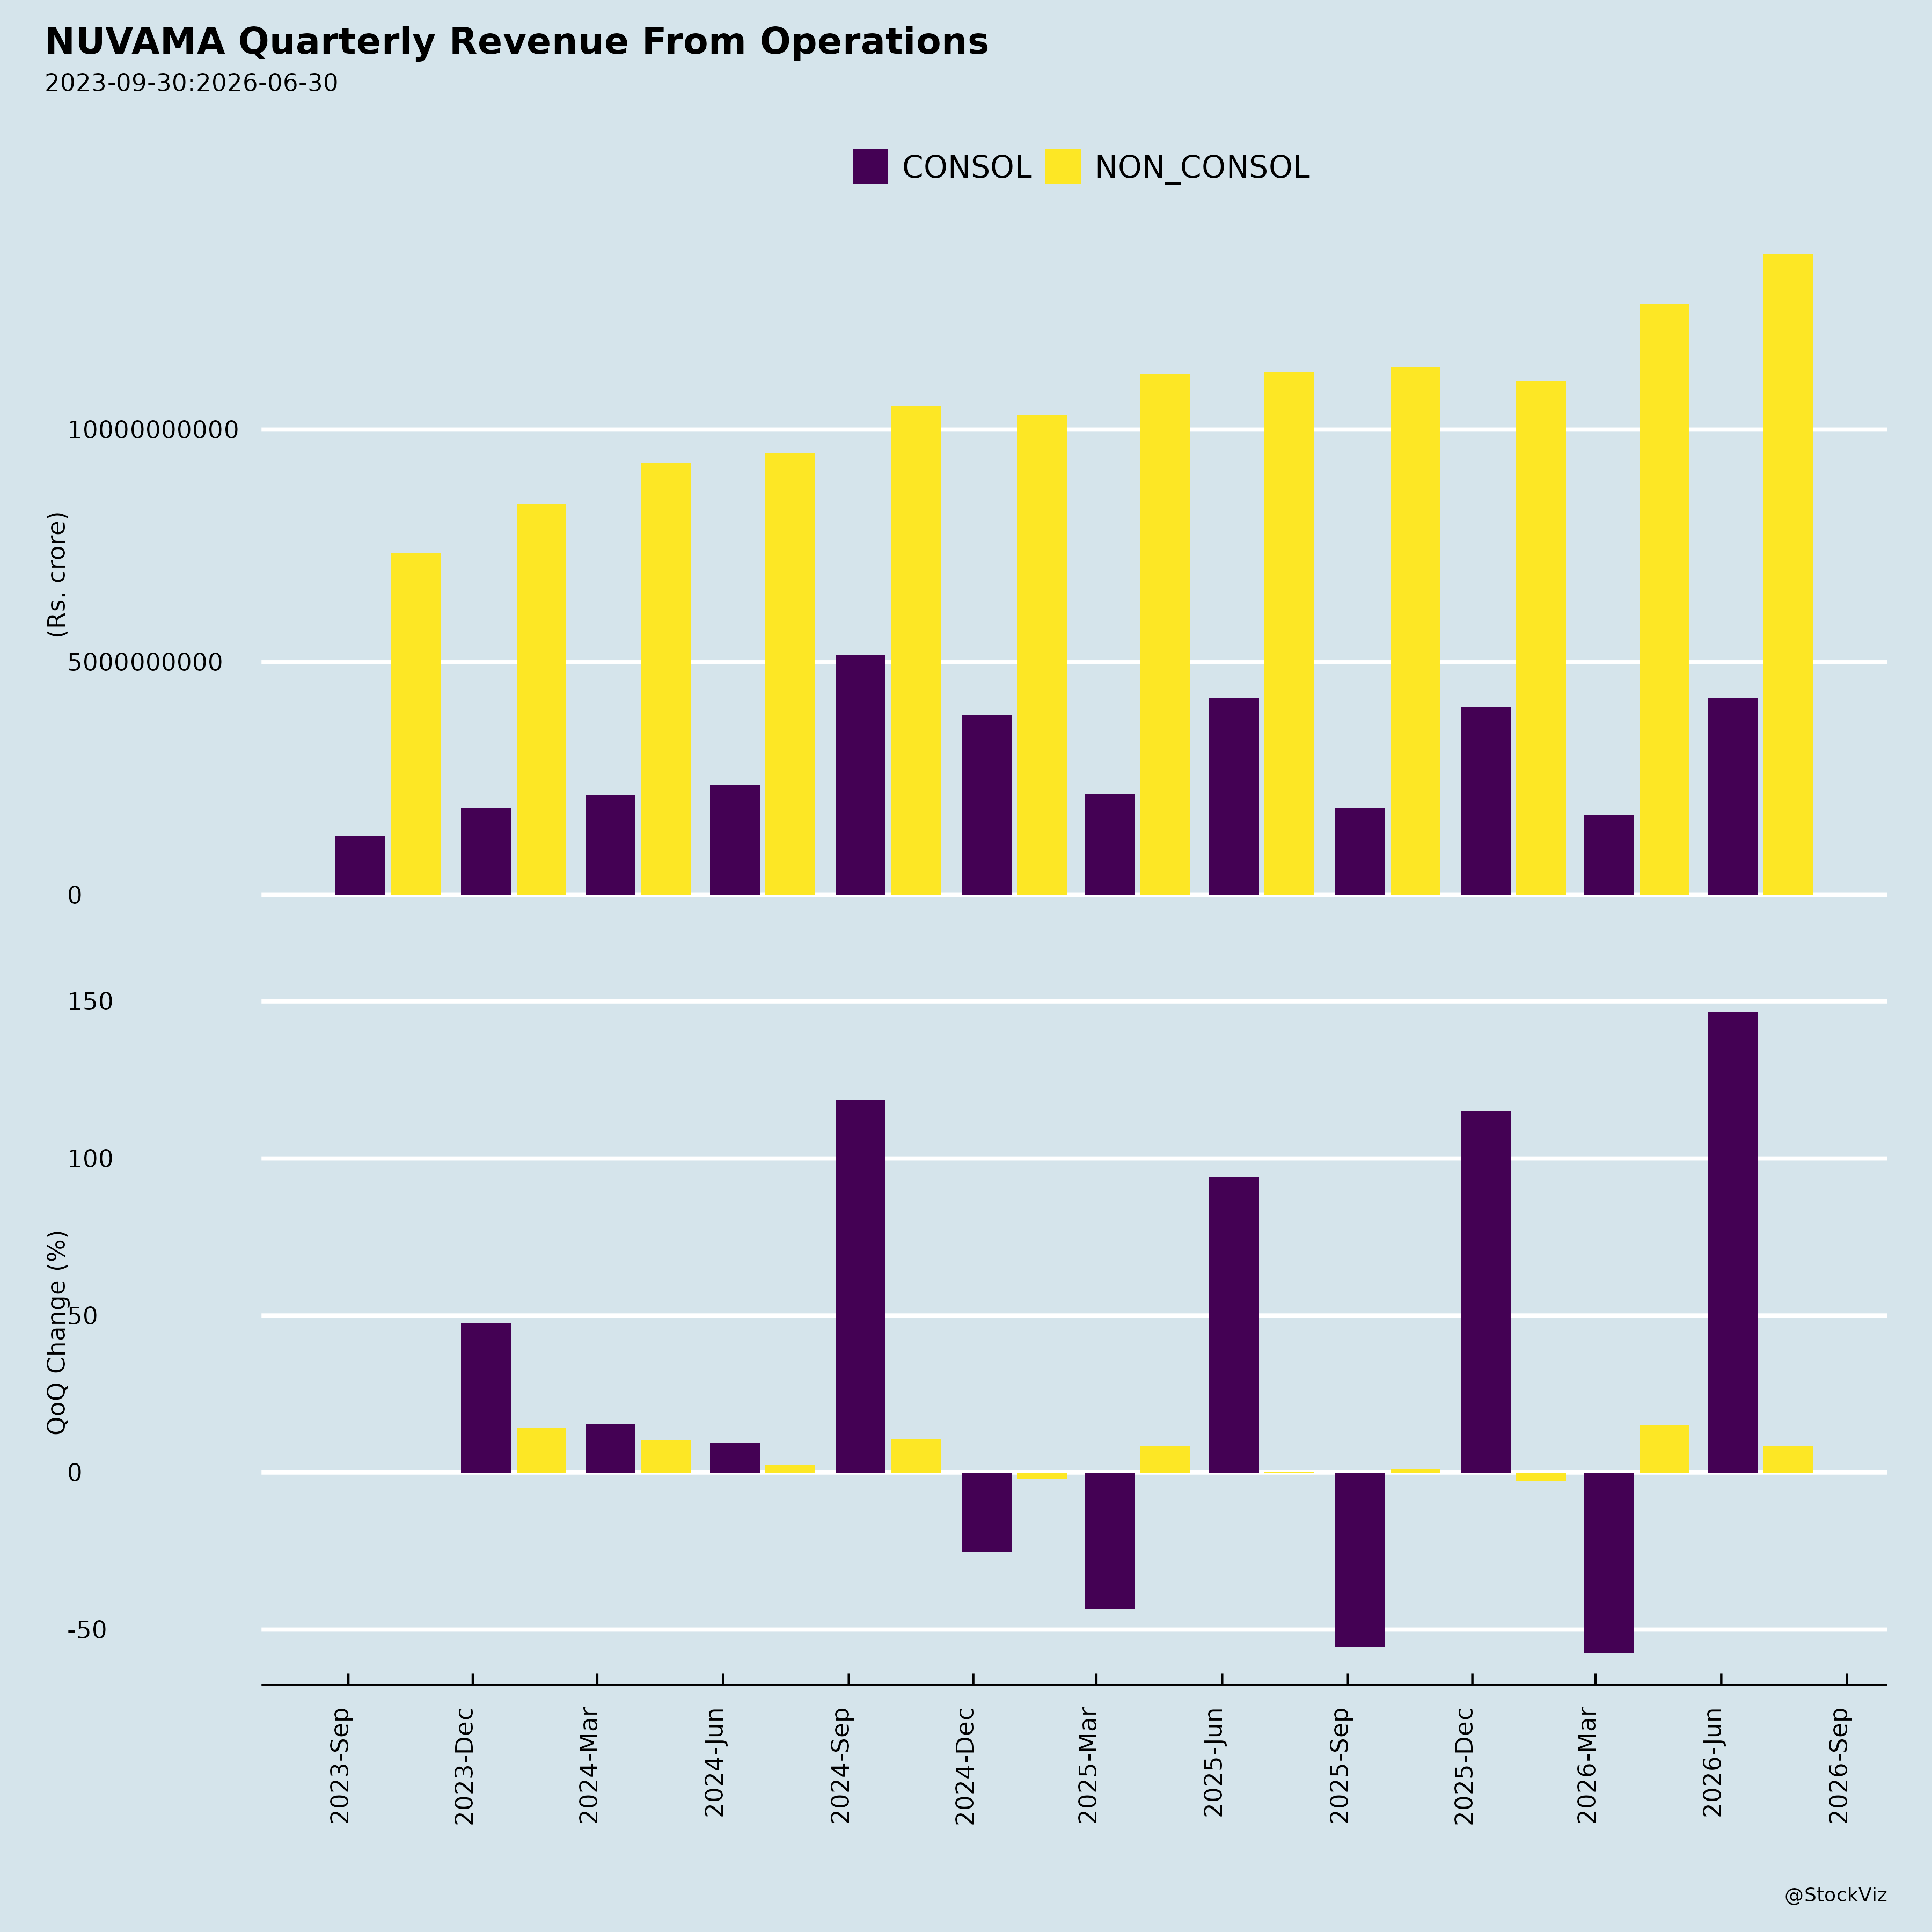
For the quarter ended June 30, 2026, consolidated total income was Rs. 1,381.96 crores with net profit after tax of Rs. 305.64 crores; standalone total income was Rs. 430.87 crores with net profit of Rs. 254.70 crores.
Management’s stated forward focus is on scaling sustainably, deepening focus asset pools across ARR and MPIS solutions, investing in talent and technology, and maintaining operating efficiency. Priorities include scaling the Wealth Management franchise, expanding asset management strategies including private credit and SIFs, strengthening asset services via RTA and trustee services, and growing the fixed-income franchise and market share in capital markets. Management anticipates completing the Pickright acquisition tentatively within 2 months from the date of intimation and the NAML investment tentatively within 1 year from the date of intimation.
Other Developments
The Nomination and Remuneration Committee approved the grant of 79,38,556 Employee Stock Appreciation Rights (ESARs) under the ‘Nuvama Wealth Management Limited Employee Stock Appreciation Rights Scheme 2026’. Of these, 73,93,366 ESARs vest on a graded basis over five years, and 5,45,190 ESARs vest in equal annual tranches over four years, exercisable within two years from the date of vesting. The Board re-appointed Mr. Birendra Kumar and Ms. Anisha Motwani as Independent Directors.
Representatives of Nuvama are participating in the UBS India Summit 2026 on September 11, 2026, the J.P. Morgan India Conference on September 21, 2026, and the Nuvama Emerging India CEO Forum on September 28, 2026, all involving in-person group and one-on-one meetings in Mumbai. The company may discuss the Investor Presentation for the quarter ended June 30, 2026, and no unpublished price-sensitive information shall be shared or discussed. The schedule of meetings is subject to change due to exigencies.
Broker Narrative
The narrative shifted from broad structural tailwinds like demographic dividends and low market penetration to immediate operational and margin pressures. Early regulatory fears regarding SEBI’s F&O rules and telescopic TERs persisted as the primary headwinds, while new concerns like rising employee costs and declining retention rates emerged. Growth optimism pivoted from theoretical penetration metrics to tangible execution milestones like asset services hitting all-time highs and offshore breakevens, though the expected capital markets recovery remained elusive.
Fears that came true
- SEBI’s F&O regulations intermittently hitting volumes materialized as flat capital markets IB/IE revenue and a 19% YoY decline in segment operating PBT, contributing to the 2026-08-01 call’s disappointing +0.1% actual return.
- Telescopic TER structures and tightened commissions pressured AMC yields, which materialized in INR4.3b net outflows and an INR77m operating loss at the AMC, aligning with the 2026-06-11 call’s disappointing +19.5% actual return.
- Margin-segregation and peak-margin norms caused volume disruptions that persisted, leading to declining wealth and asset services retention and the 2026-08-01 call’s near-flat +0.1% actual return.
Optimism that failed
- Growth in new product avenues like AIFs, PMS, and passives failed to deliver immediate profitability, as investments in new verticals and mutual fund platform build-up resulted in quarterly losses expected to peak at INR350-360m, aligning with the 2026-06-11 call’s disappointing +19.5% actual return.
- The expectation that a robust IPO pipeline and pent-up issuance demand would support IB/IE recovery failed to materialize in the near term, as capital markets IB/IE revenue was flat YoY and segment operating PBT declined 19% YoY, contributing to the 2026-08-01 call’s disappointing +0.1% actual return.
Broker Timeline
15 broker calls · 2024-12-06 to 2026-08-01
Copyright © 2023 SAS Data Analytics Pvt. Ltd. All rights reserved.