NMDC
Equity Metrics
September 24, 2026
NMDC Limited
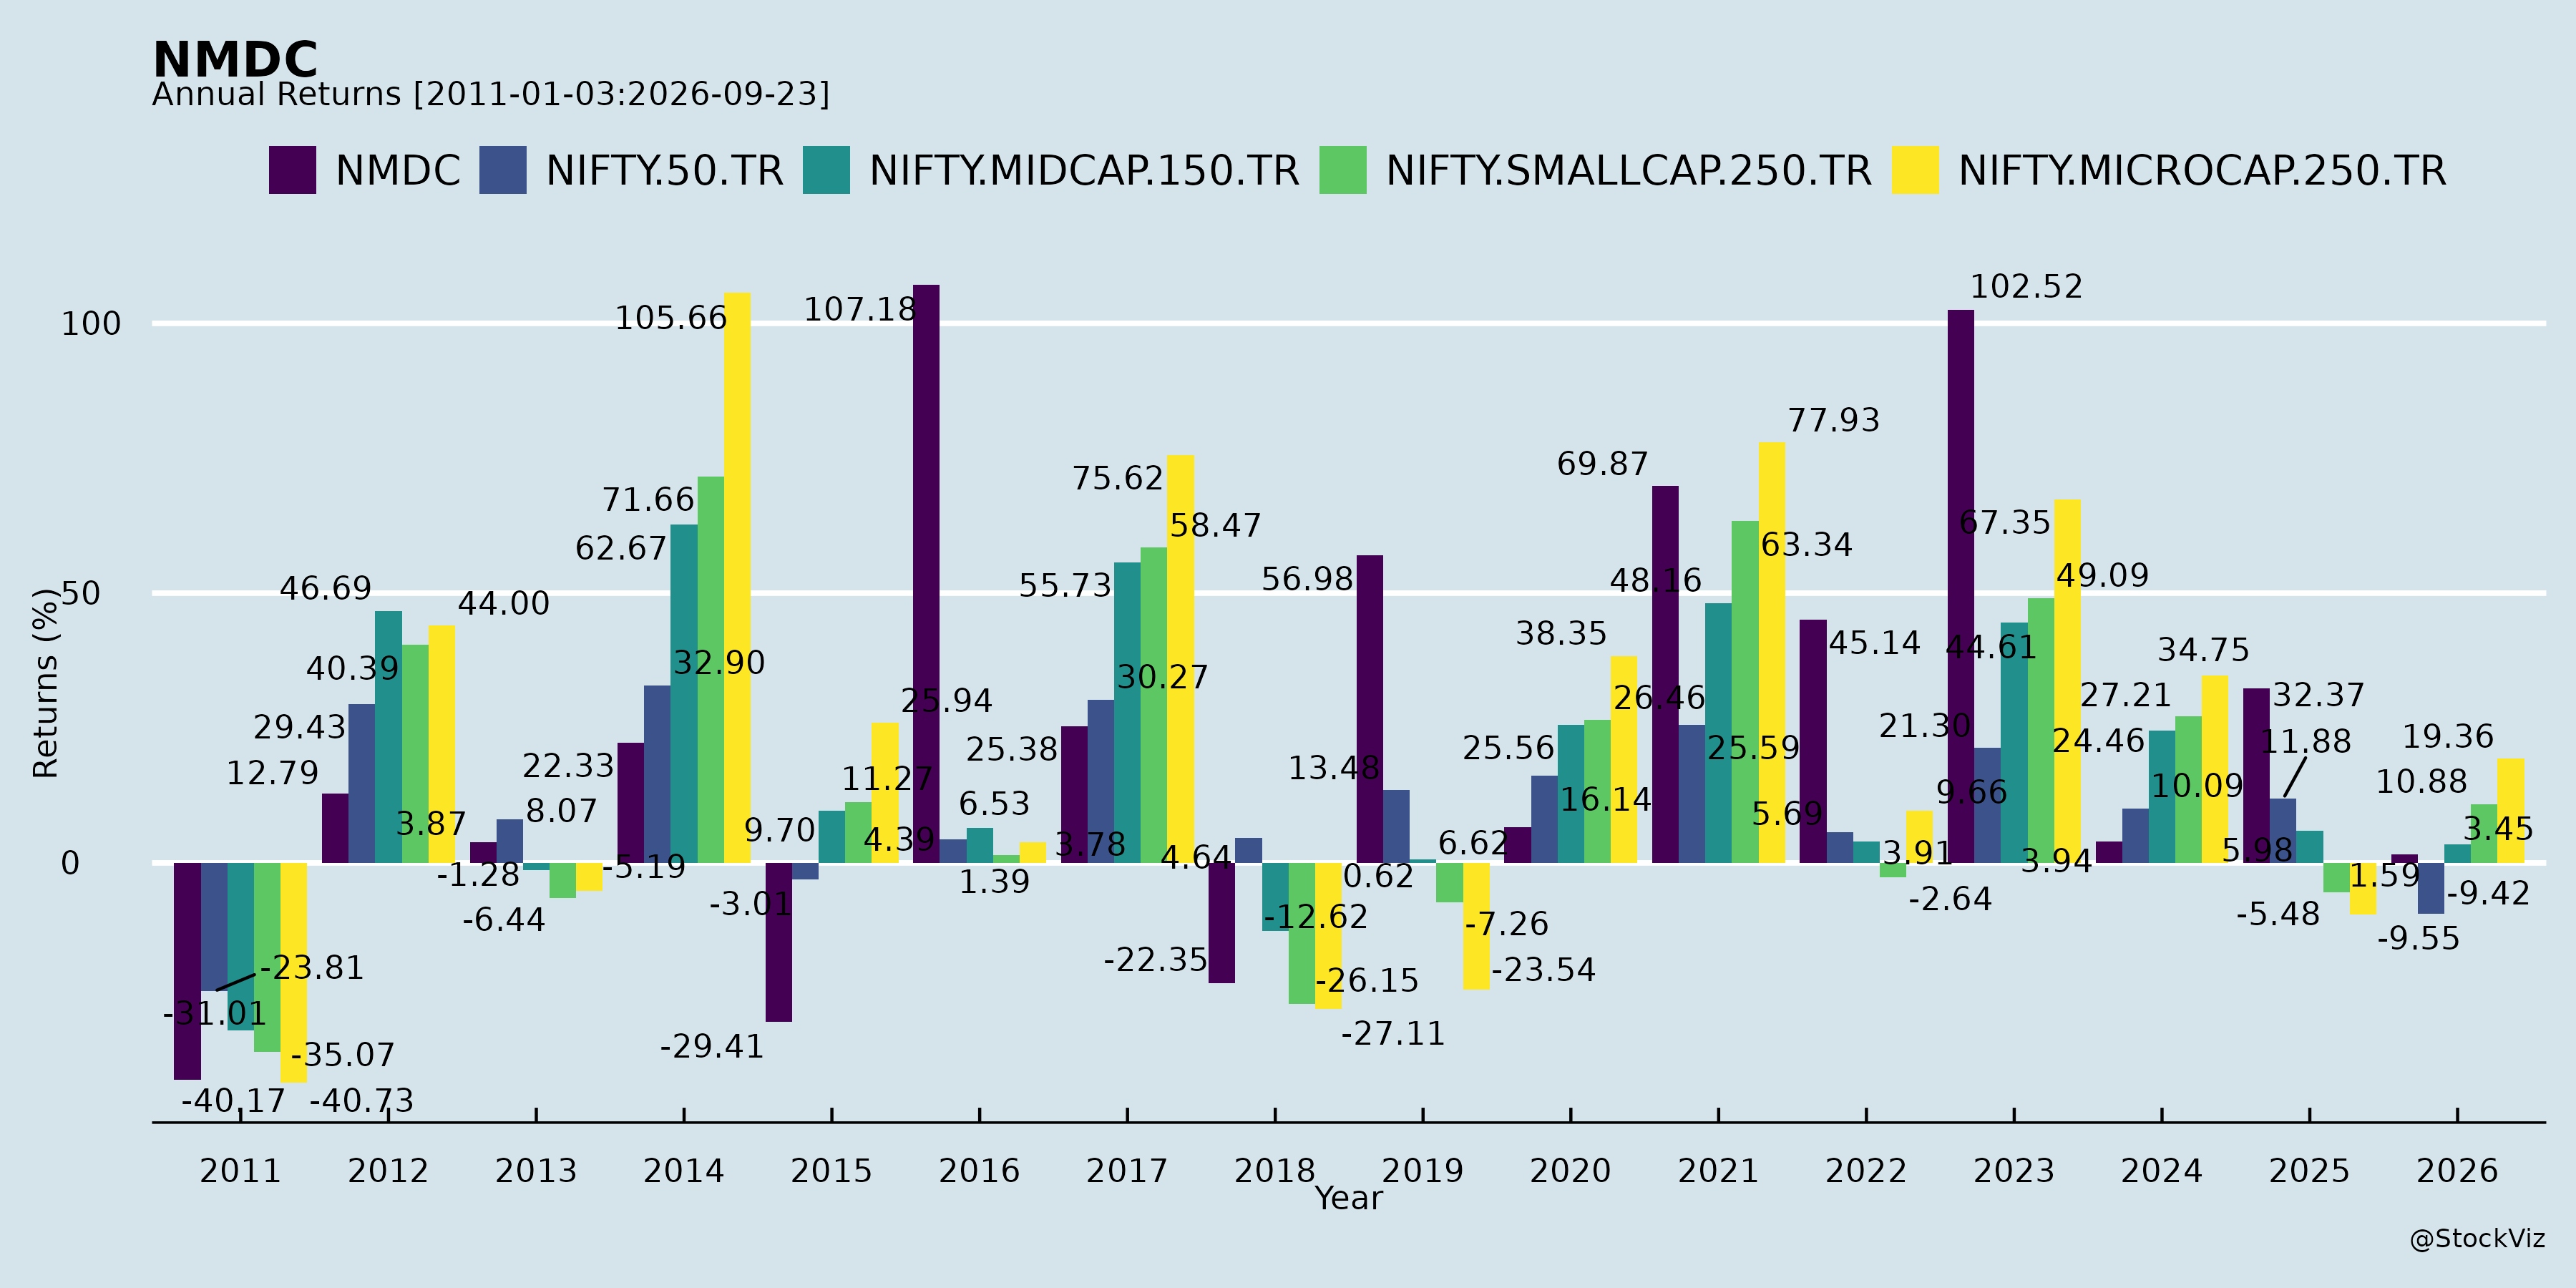
Annual Returns
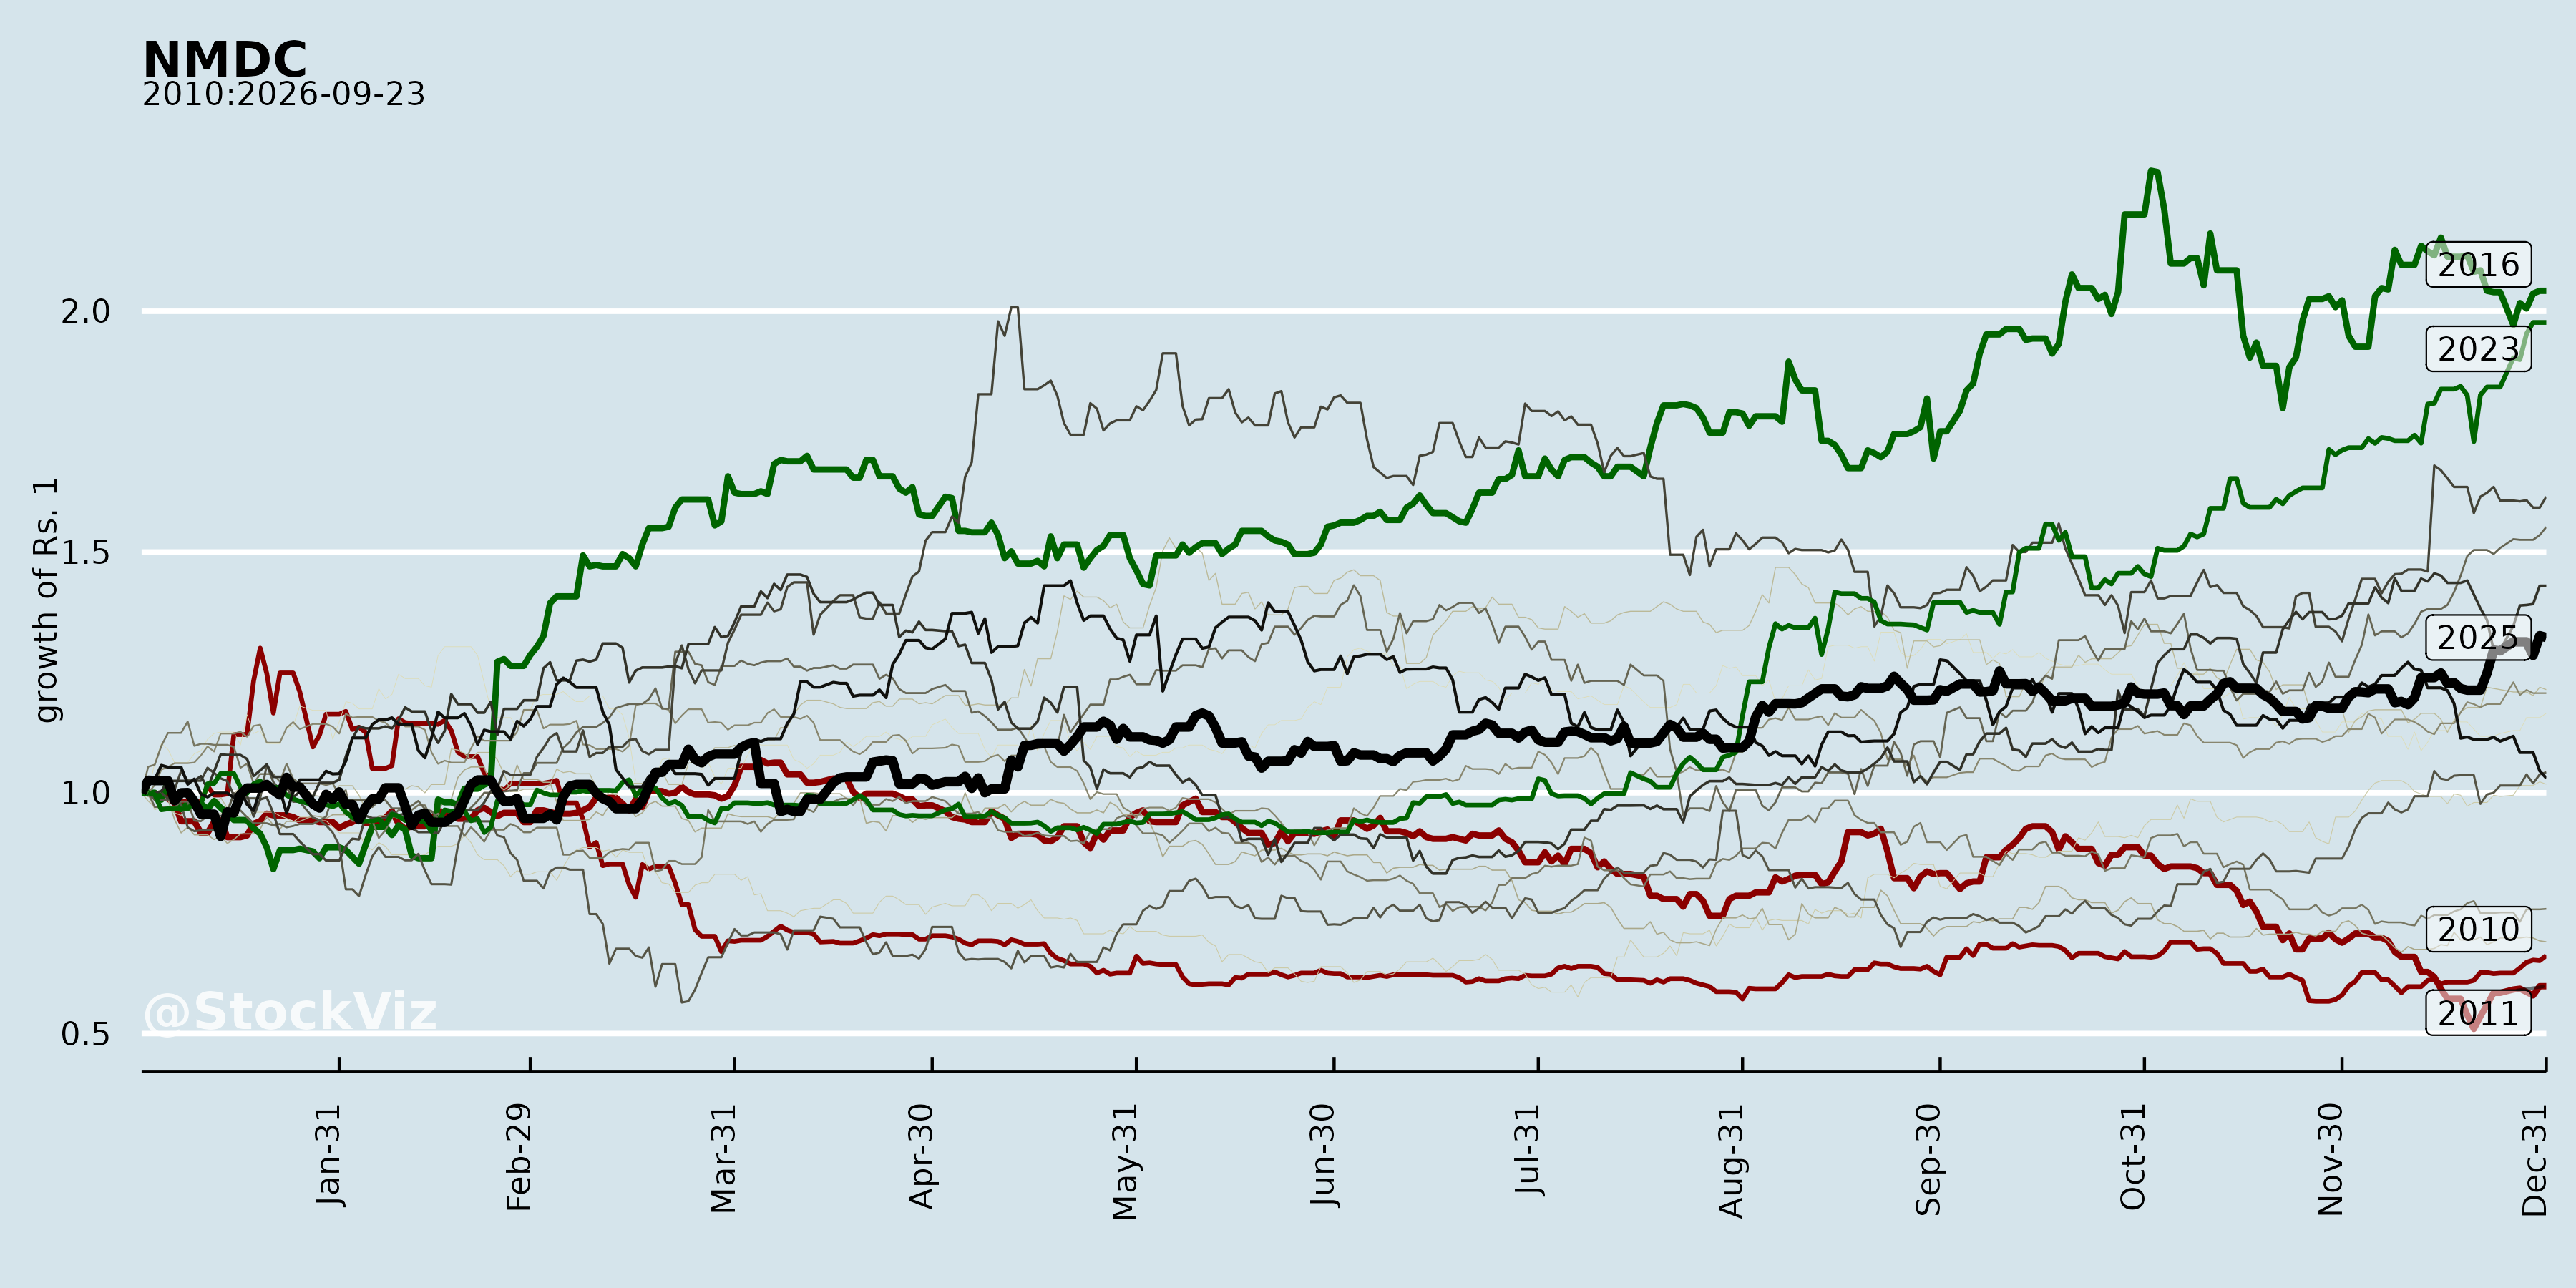
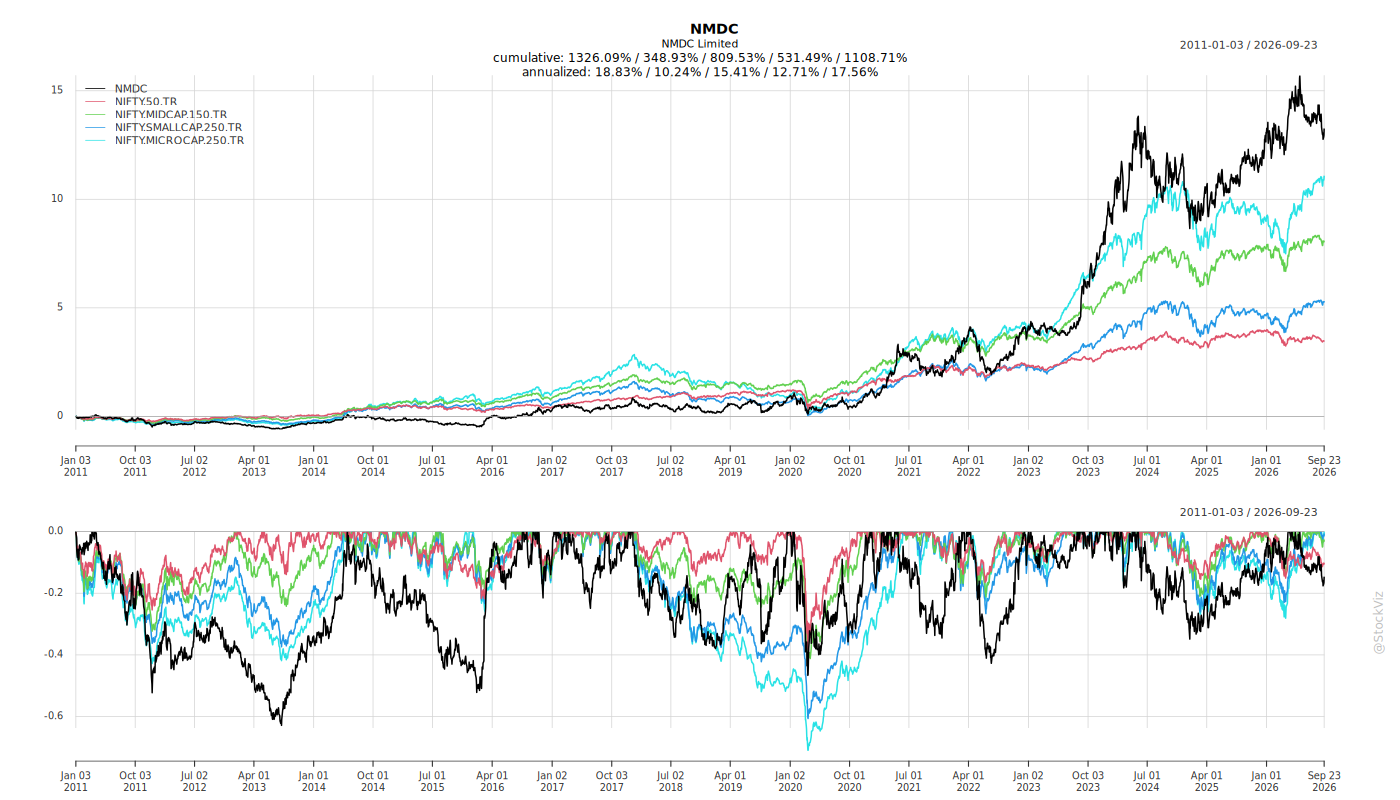
Cumulative Returns and Drawdowns
Fundamentals
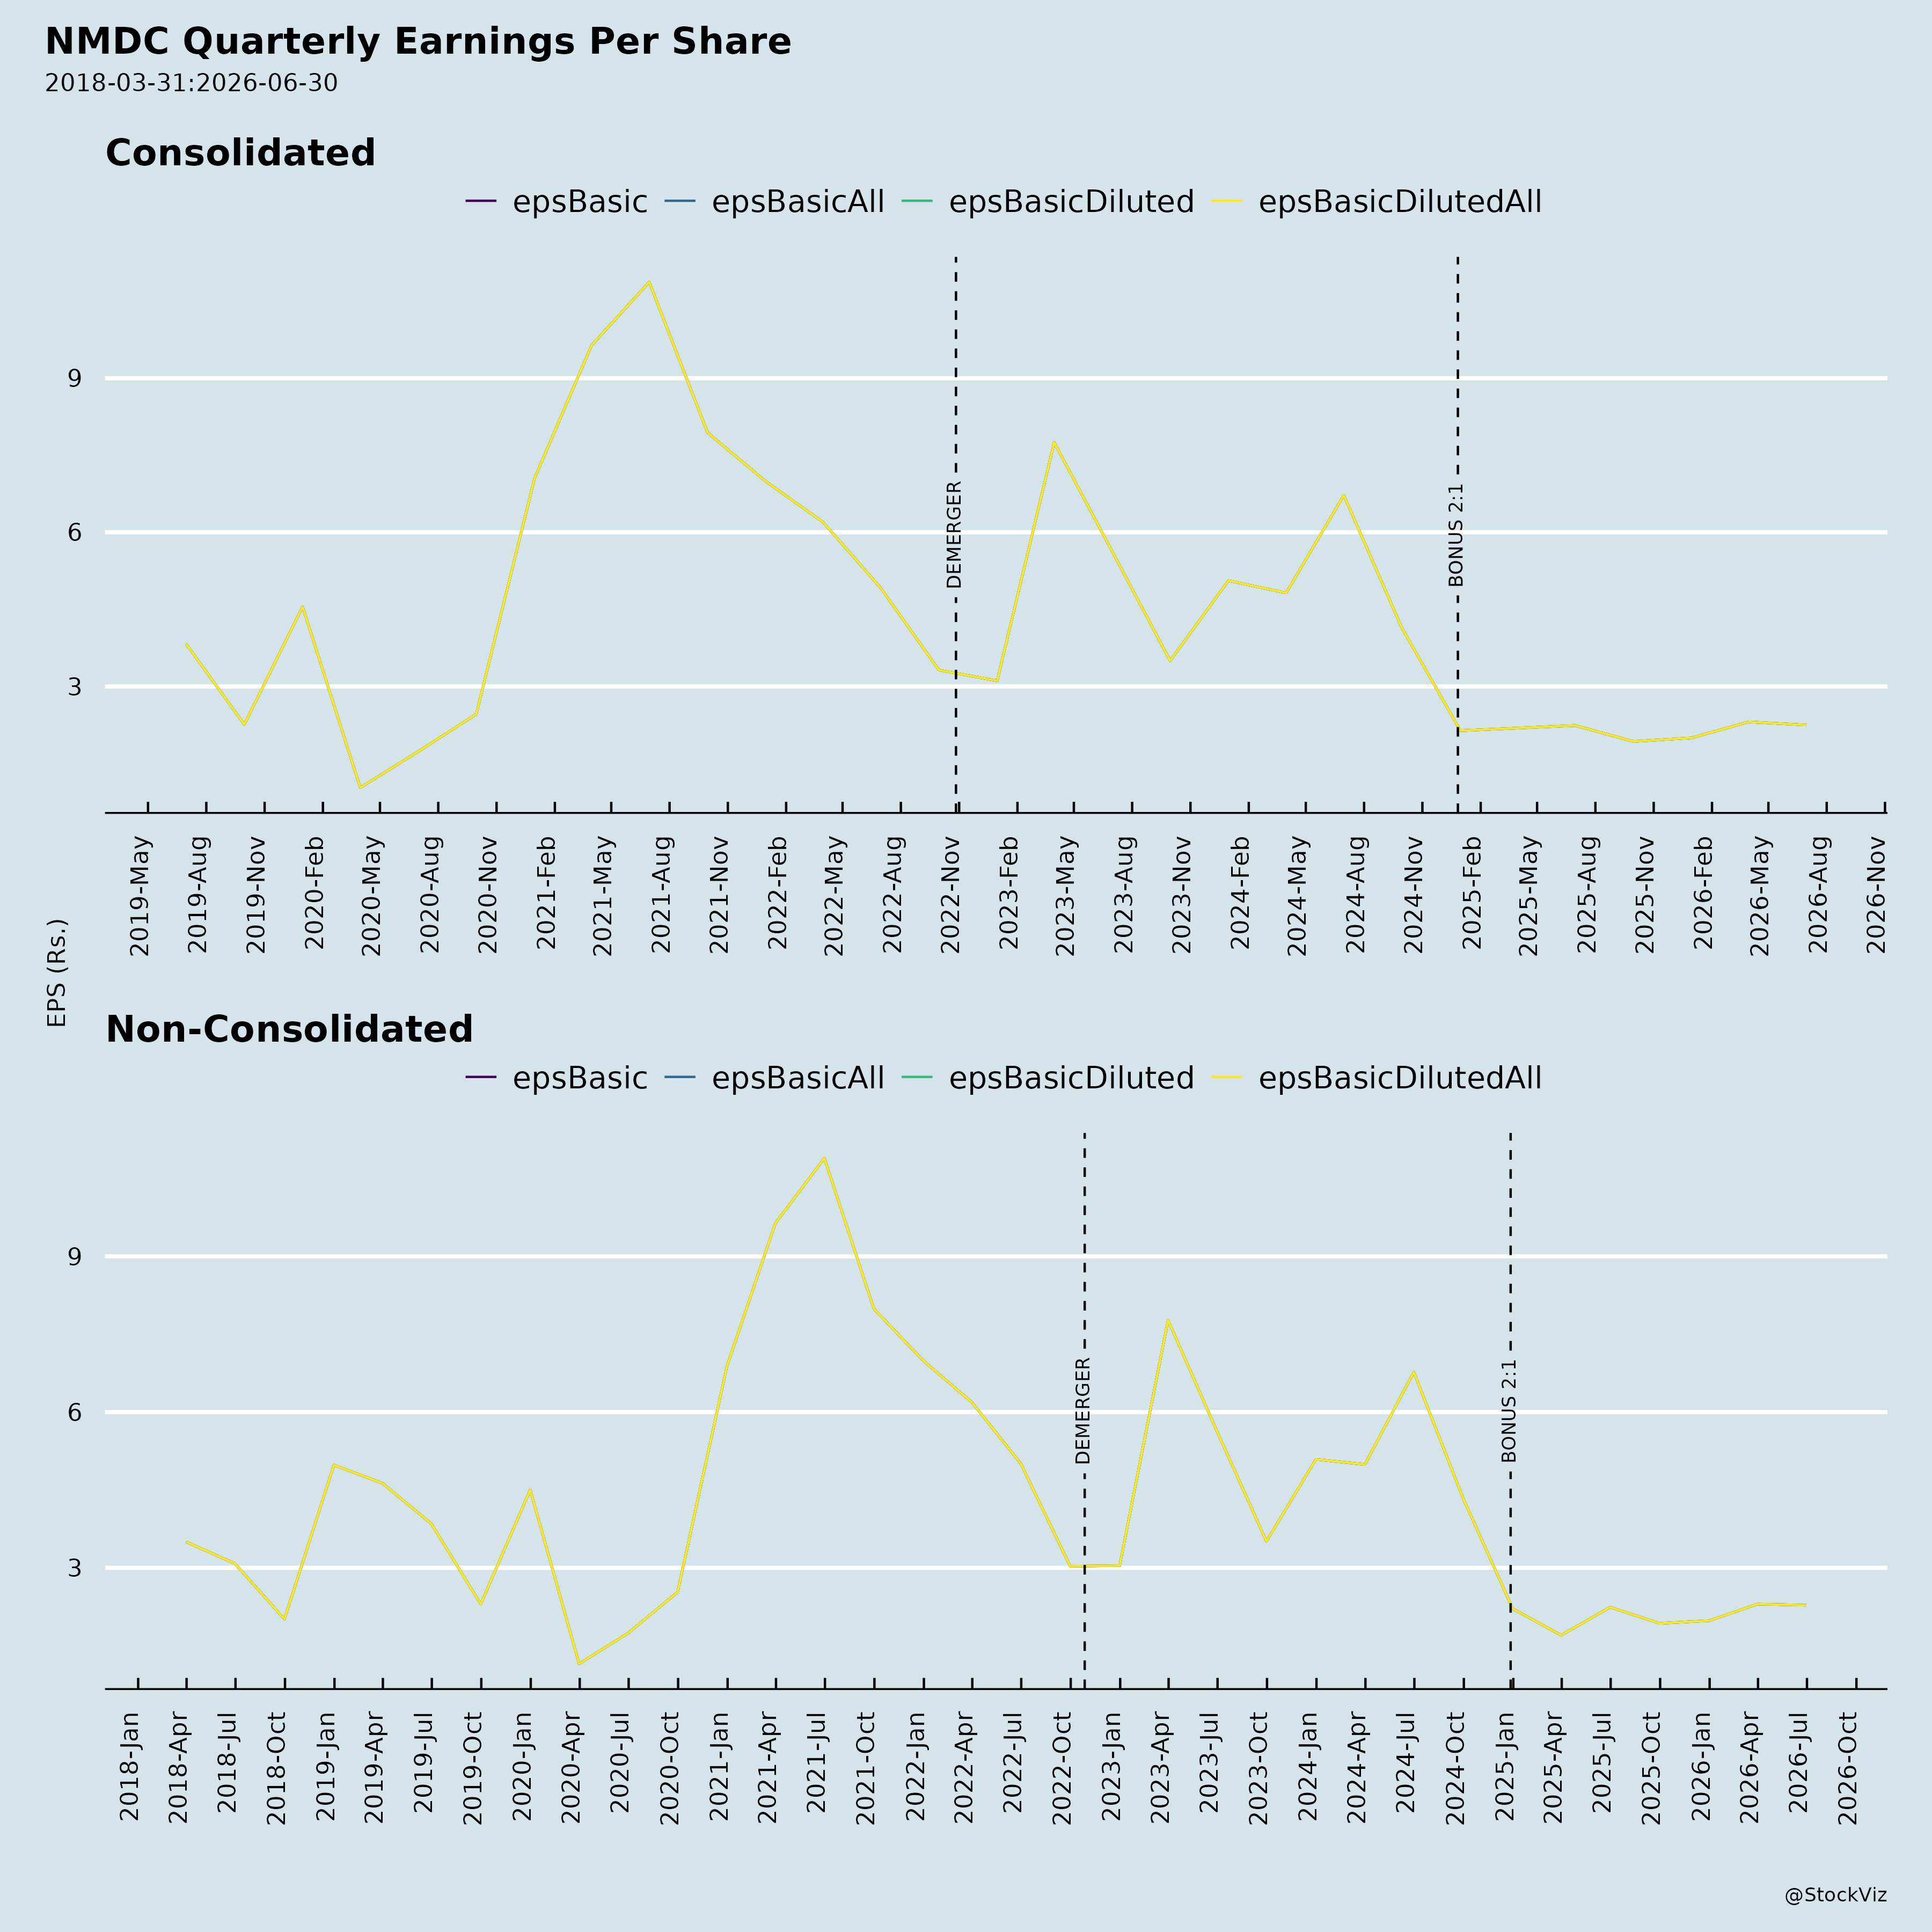
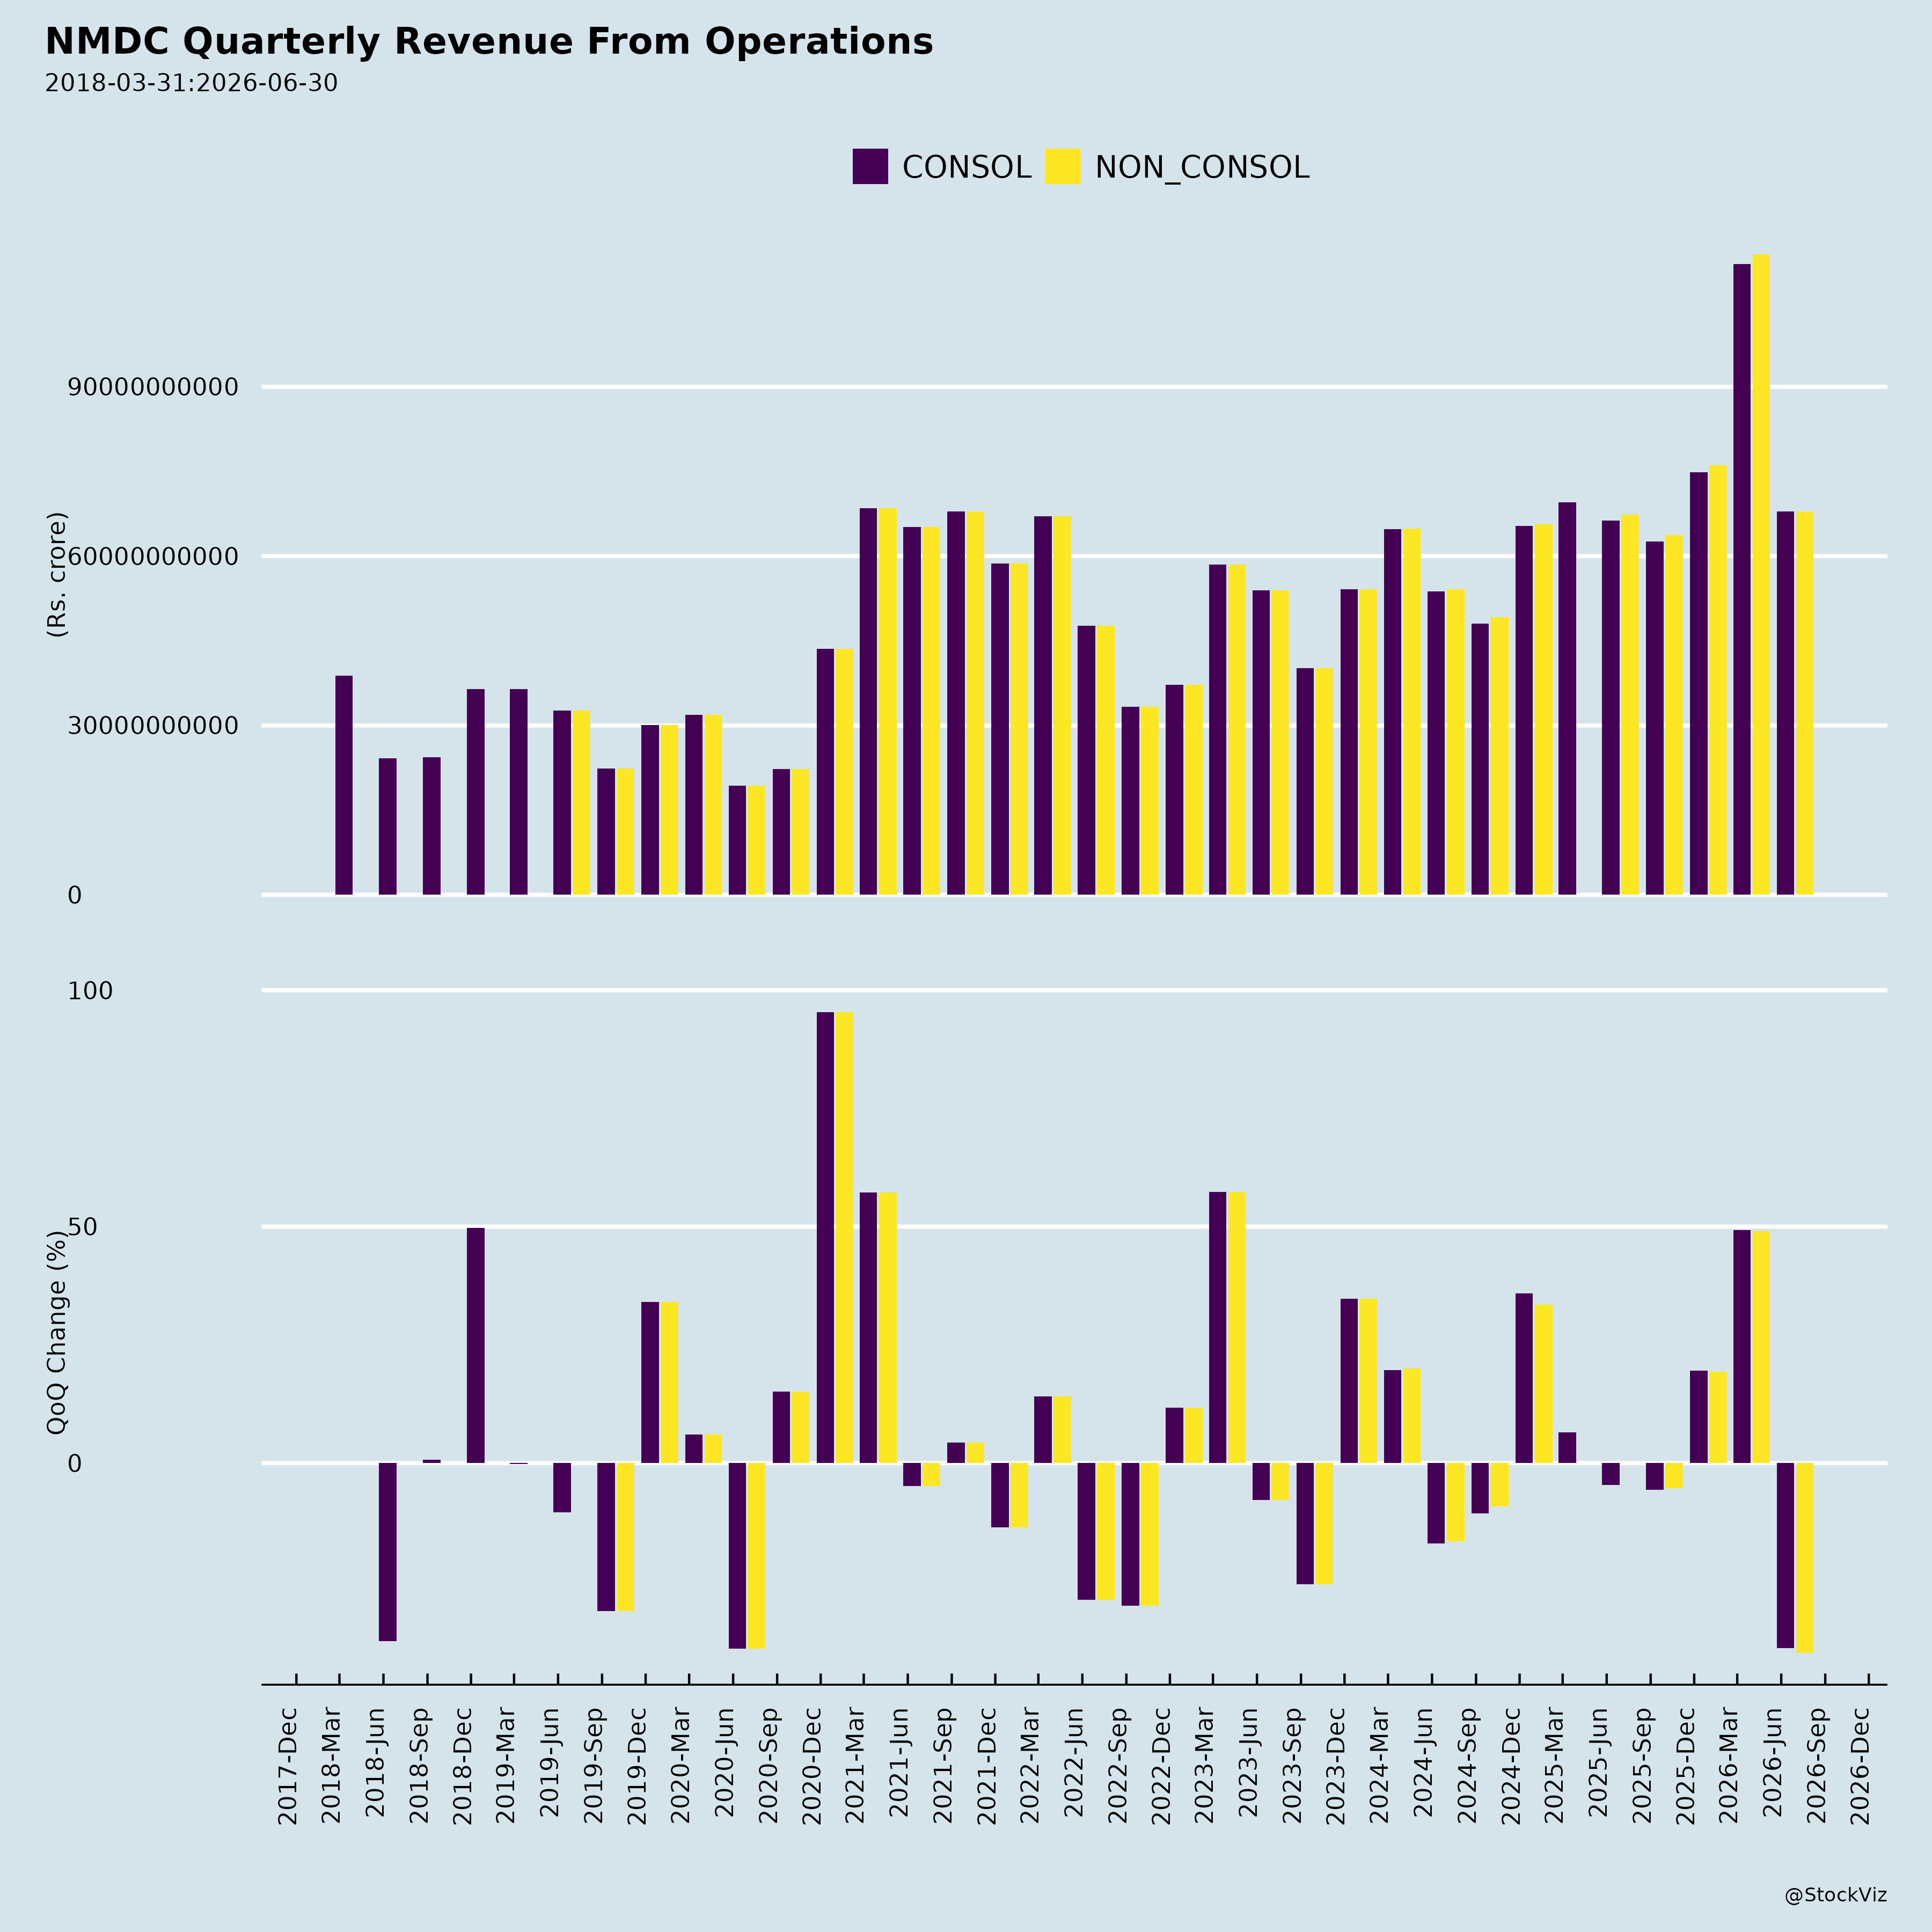
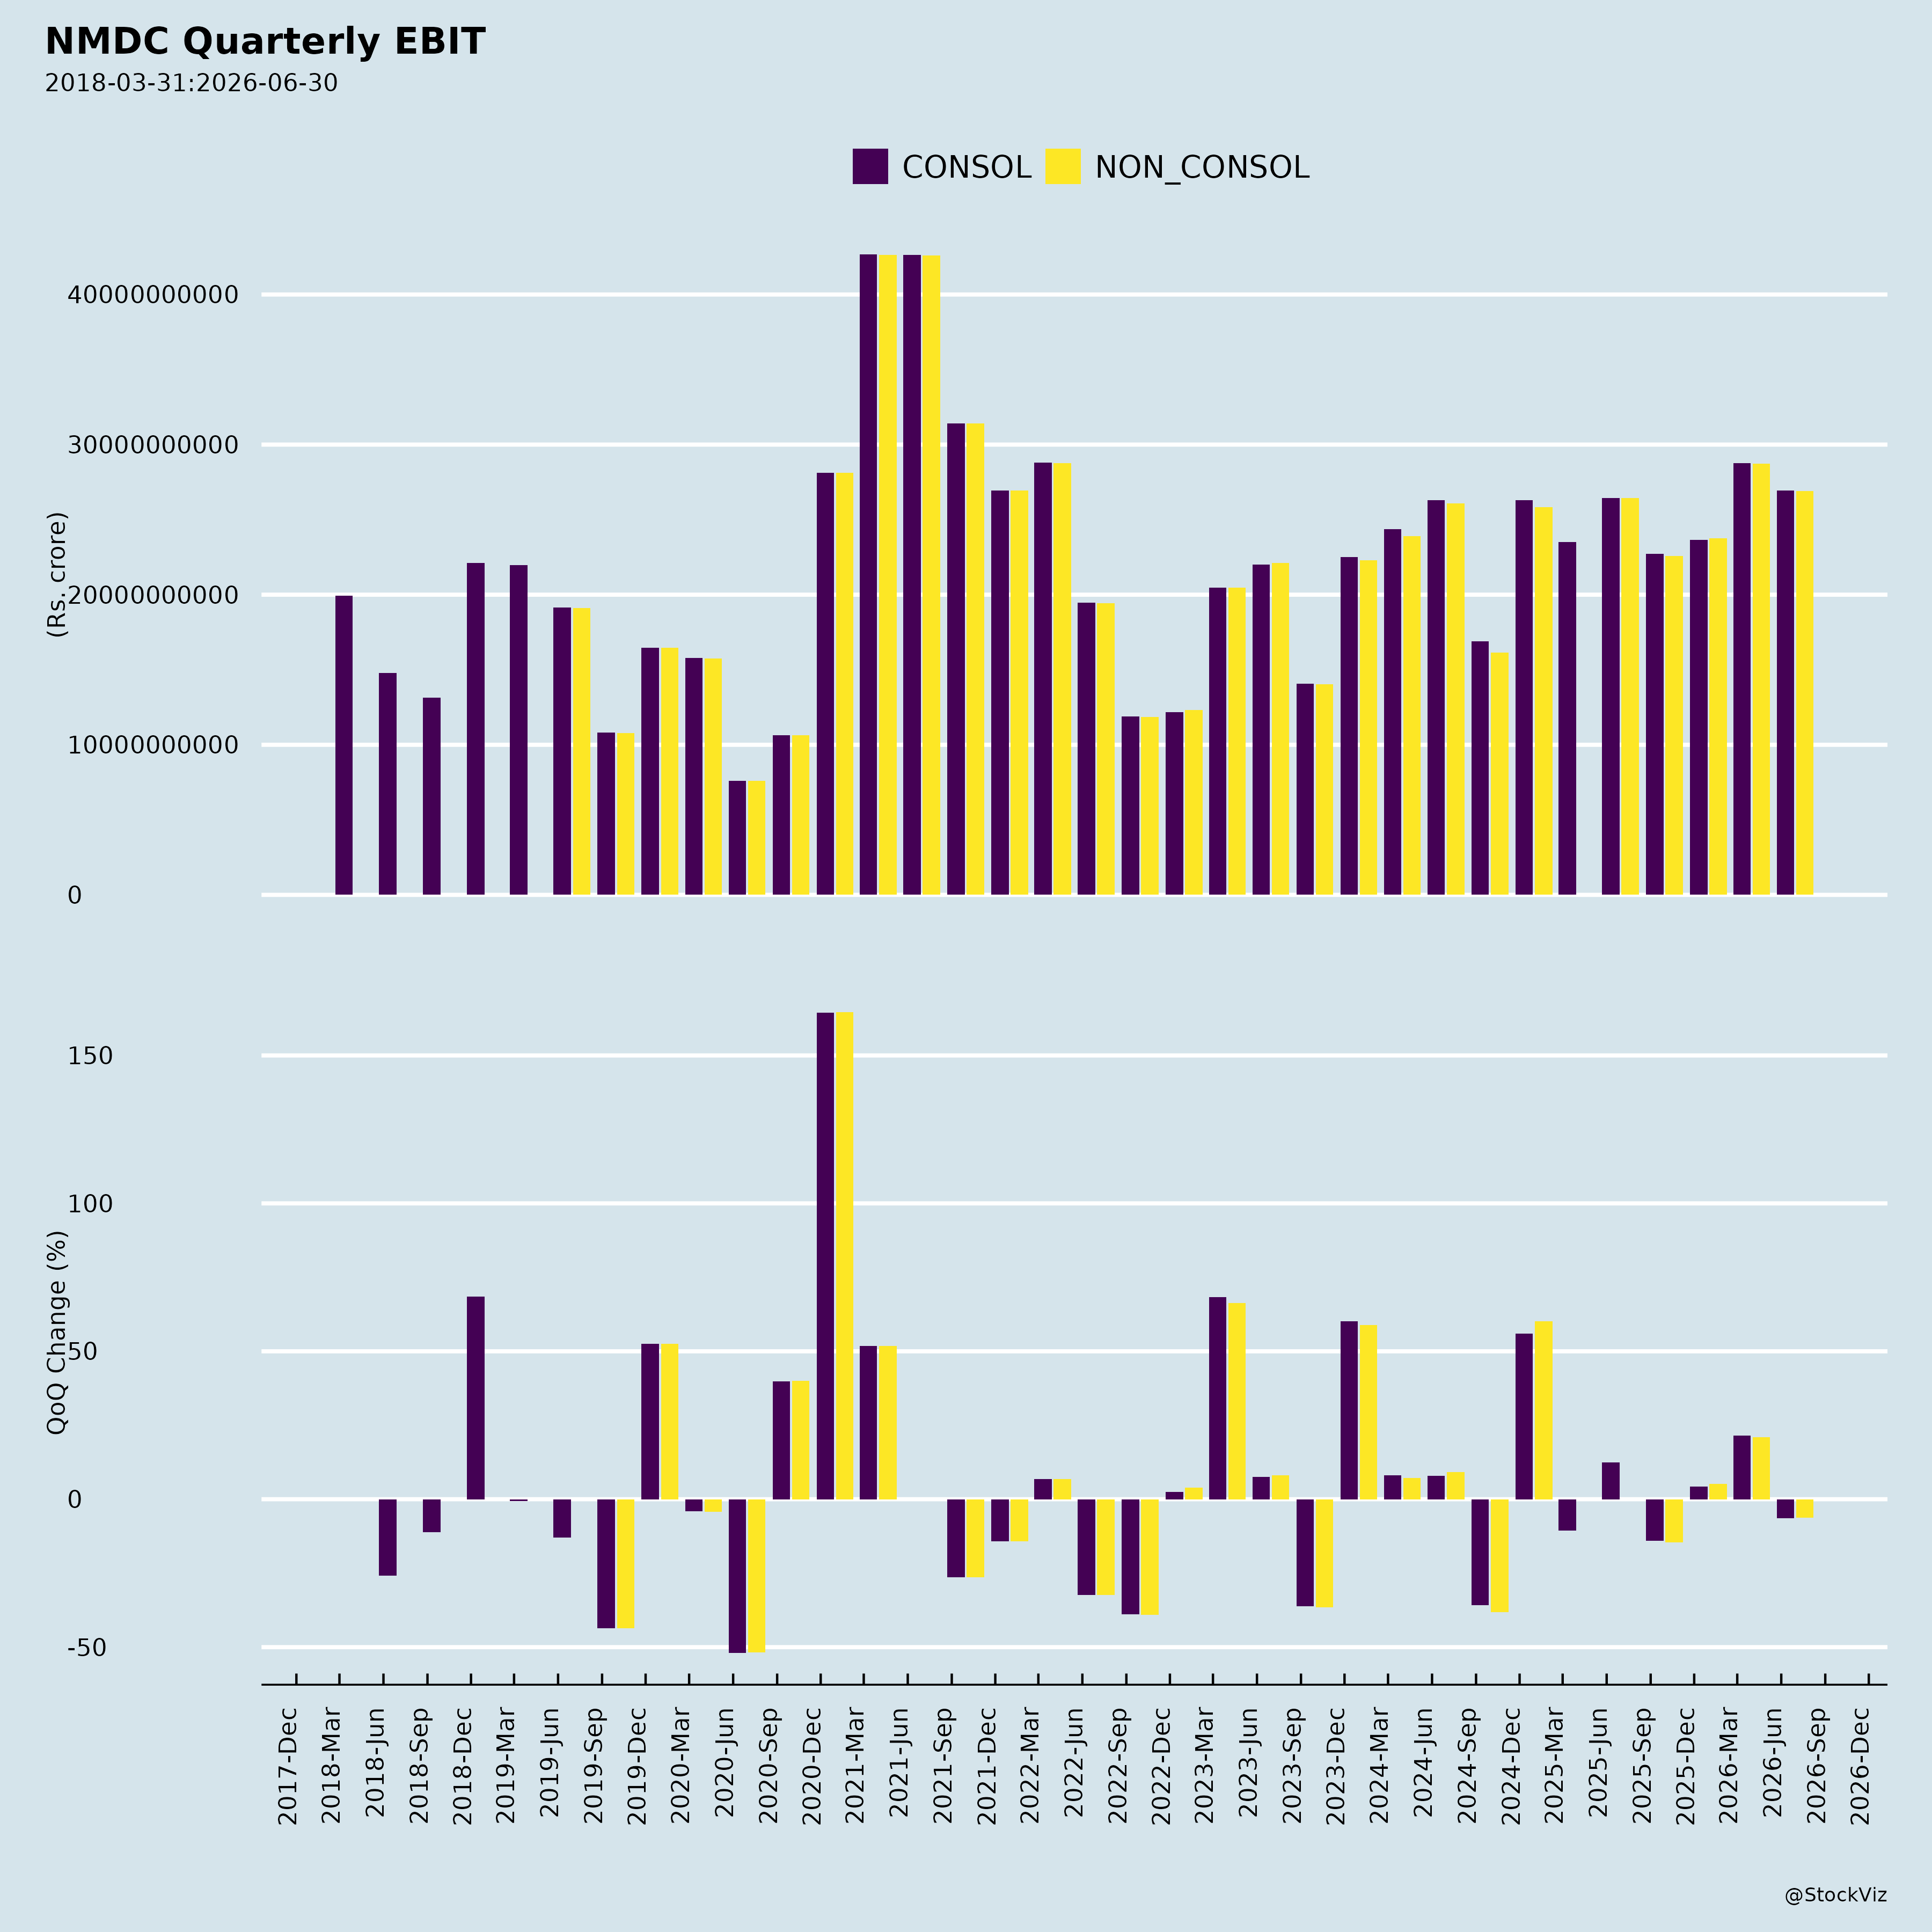
Ownership
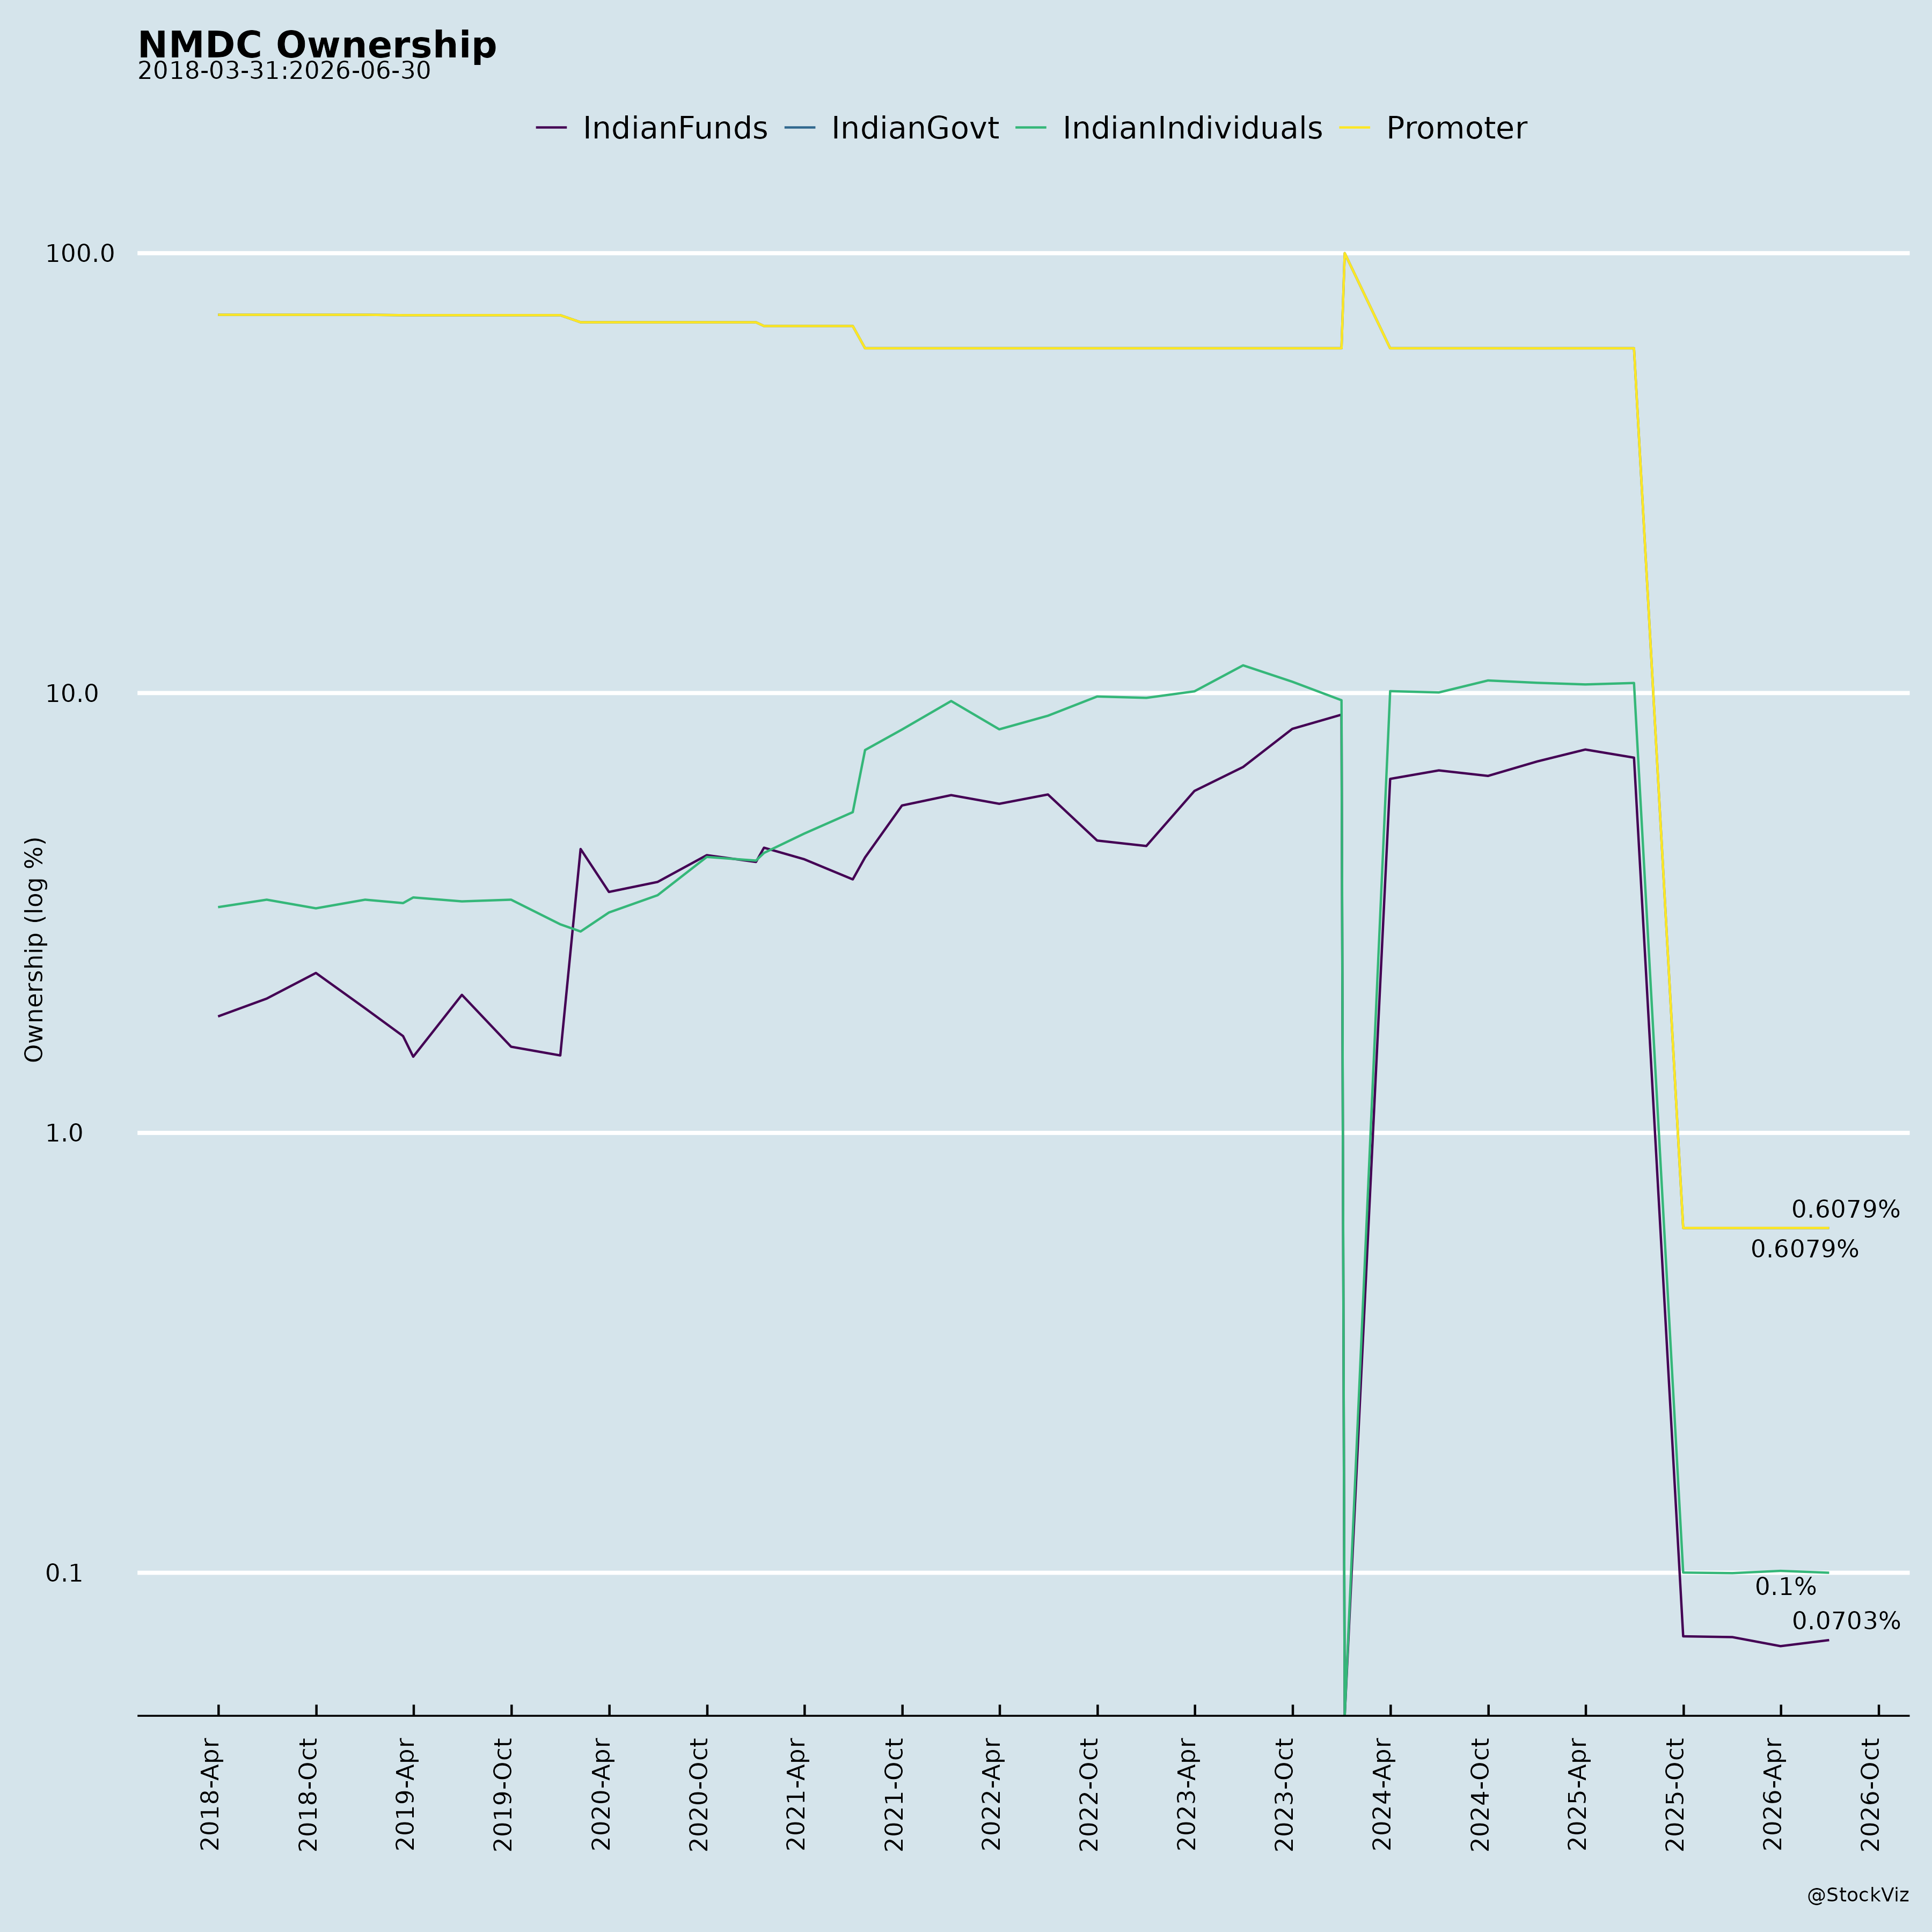
Margined
AI Summary
asof: 2026-09-16
Headwinds and Challenges
Karnataka mineral tax exposure. The Karnataka Legislature passed the Karnataka (Mineral Rights and Mineral Bearing Land) Tax Bill, 2024 in December 2024. As of the reporting date it remains pending enactment, awaiting the assent of the President of India, and the Governor of Karnataka referred it for Presidential assent with reservations on its legality. If enacted in its current form, which proposes retrospective applicability of tax on mineral rights and mineral-bearing lands, NMDC estimates a liability of approximately ₹15,785.72 crores as on the reporting date. This has been treated as a contingent liability. The company notes that under its Long-Term Agreements and Auction Notices, future statutory duties, levies or taxes are contractually recoverable from customers/bidders, and it will assess enforceability of those recourse provisions upon enactment.
Recoverables from NMDC Steel Limited (NSL). Following the demerger of NMDC Iron & Steel Plant into NSL (scheme sanctioned by the MCA on October 6, 2022, effective October 13, 2022, appointed date April 1, 2021), NMDC incurred ₹2,502.64 crores on behalf of NSL with no specific repayment schedule in the scheme. NSL has repaid ₹901.25 crores, leaving ₹1,601.39 crores outstanding as on June 30, 2026; NSL provided a repayment schedule during the quarter. Other NSL balances outstanding are ₹4,499.20 crores (iron ore trade receivables), ₹167.53 crores (employee-related services) and ₹179.83 crores (advance for HR products). An expected credit loss of ₹136.19 crores reflecting the time value of money has been recognised.
Recoverables from RINL. Trade receivables from Rashtriya Ispat Nigam Limited, mainly for iron ore and pellets supplies, amount to ₹4,712.47 crores as at June 30, 2026. An expected credit loss of ₹298.48 crores has been recognised.
KIADB land advance for KVSL. NMDC paid ₹639.61 crores to KIADB towards the cost of 2,857.54 acres allotted to its wholly owned subsidiary Karnataka Vijayanagar Steel Limited for a 3 MTPA integrated steel plant. The land was allotted on a lease-cum-sale basis by letter dated July 13, 2017, with possession certificates for 2,843.98 acres issued January 11, 2018 and revised August 1, 2018. The land is in KVSL’s possession but the lease agreement is yet to be executed. Allotment conditions required construction to commence within 9 months and production within 5 years of possession. KVSL has sought an extension of the lease period to 99 years, under review by the Government of Karnataka; KIADB has in principle agreed to a 10-year lease in place of the earlier 2-year period. A Business Management Consultant was engaged to evaluate alternate business models, an internal committee was formed to review the report, and legal opinions were obtained on the impact of surrendering the land. In a review meeting between NMDC and the Ministry of Steel on July 08, 2026, NMDC was directed to explore setting up facilities for value added products; the KVSL Board on July 30, 2026 directed KVSL management to take further necessary action. ₹95.94 crores (15% of ₹639.61 crores) is included in contingent liabilities, and the amount is classified as a non-current asset.
Common Cause judgment compensation demand. Show Cause Notices dated July 31, 2018 from the District Collector, South Bastar, Dantewada demanded ₹7,241.35 crores as compensation based on the Supreme Court’s Common Cause judgment relating to Odisha iron ore mines; NMDC contests its applicability to Chhattisgarh operations. Revised notices on September 26, 2019 reduced the demand to ₹1,623.44 crores, followed by demand notices dated November 15, 2019 directing deposit within 15 days (₹1,131.97 crores for Bacheli and ₹491.47 crores for Kirandul). With Chhattisgarh mining leases due for renewal from March 31, 2020, NMDC deposited ₹600 crores under protest and filed a writ petition before the High Court of Bilaspur and a revision application before the Mines Tribunal. The High Court on February 19, 2020 directed no coercive action till March 12, 2020. The matter was last listed September 24, 2025 and adjourned; before the Mines Tribunal it was last listed November 13, 2025 and adjourned. The ₹600 crores paid under protest is disclosed under Other Non-Current Assets and the ₹1,623.44 crores demand is a contingent liability.
Railway Transit Pass penalty. A show-cause notice dated August 29, 2024 from the District Collector, South Bastar, Dantewada alleged mineral dispatches from 01.04.2024 to 25.08.2024 without timely Railway Transit Passes, resulting in a penalty of ₹1,620.50 crores. NMDC states it pays royalty in advance and there is no resultant loss to the exchequer. It filed Writ Petition No. 4747/2024 in the High Court of Chhattisgarh at Bilaspur. At the last listing on June 30, 2026, the High Court granted two weeks to the State Government and Railway Authorities to file returns and a further two weeks to NMDC for its rejoinder. The State Government’s reply is received; the Railway Authorities’ reply is awaited; NMDC has finalised its rejoinder and is filing it. The next hearing is September 30, 2026. The penalty is a contingent liability.
Legacy Iron Ore Limited (LIOL). NMDC’s total investment in this Western Australia-focused subsidiary is ₹443.34 crores as on June 30, 2026. LIOL’s net worth as on June 30, 2026 is ₹187.06 crores and it holds a cash reserve of ₹28.92 crores (AUD 4.38 million). Based on LIOL’s share price as of June 30, 2026, the market value of the investment was ₹295.29 crores, below the carrying value. An independent assessment during the year ended March 31, 2026 concluded recoverable value exceeded carrying value, indicating no impairment; management sees no significant developments since then and investments are carried at cost.
Bastar Railway (BRPL) excess compensation. BRPL paid compensation for private land acquisition; excess compensation of ₹85.63 crores was identified per the Jagdalpur District Collector’s report dated April 30, 2019 and the enquiry committee report dated August 23, 2019. Of this, ₹83.63 crores pertains to two individuals who have filed litigation before the Supreme Court; the matter is sub judice.
HR coil segment. The HR Coil & Sheets segment recorded a segment result of negative ₹0.06 crores for the quarter ended June 30, 2026, versus ₹19.00 crores in the quarter ended March 31, 2026 and ₹0.17 crores in the quarter ended June 30, 2025. Segment revenue for HR Coil & Sheets was nil in the June 2026 quarter, with a note stating that pending necessary approvals there was no transaction in respect of HR Coils during the quarter.
Tailwinds and Growth Prospects
Iron ore production and sales momentum. Provisional data for July 2026 show monthly production of 4.06 MT versus 3.09 MT in July 2025, and cumulative production up to July 2026 of 19.16 MT versus 15.09 MT up to July 2025. Cumulative sales up to July 2026 were 15.15 MT versus 14.98 MT a year earlier. Chhattisgarh drove the increase: monthly production 2.55 MT versus 1.89 MT, cumulative production 13.78 MT versus 10.08 MT, and cumulative sales 11.79 MT versus 10.29 MT. Karnataka monthly production was 1.51 MT versus 1.20 MT and cumulative production 5.38 MT versus 5.01 MT, though Karnataka monthly sales fell to 0.90 MT from 1.31 MT and cumulative sales to 3.36 MT from 4.69 MT.
Iron ore pricing. NMDC fixed prices of iron ore with effect from 09.09.2026: Lump Ore (65.5%, 10-40mm) at ₹5,400 per ton and Fines (64%, -10mm) at ₹4,500 per ton. These are FOR prices exclusive of Royalty, DMF, NMEDT, Cess, Forest Permit Fee, transit fee, GST, environmental Cess and other taxes.
NMDC-CMDC joint venture approvals. NMDC subscribed to 30,46,46,939 shares amounting to ₹304.65 crores (51%) in a rights issue by NMDC-CMDC Limited to fund statutory clearances including EC and FC for Deposit-4 and Deposit-13. Total investment in NMDC-CMDC as on June 30, 2026 is ₹402.99 crores. The mining lease deed for Deposit-4 was executed and registered on January 21, 2026, and major statutory approvals including Environmental Clearance, Forest Clearance, Mine Plan approval, Consent to Establish and Consent to Operate for initial capacity were obtained. Land acquisition and infrastructure development including road construction and mine evacuation facilities are in progress, and initial mining activities commenced after statutory approvals. For Deposit-13, Forest Clearance was transferred to NMDC-CMDC on June 02, 2026 by MoEFCC; MoEFCC consented to the revised CA Land on July 13, 2026; the Forest Department issued the Forest Land diversion order on July 15, 2026. The Ministry of Mines order dated September 22, 2025 relaxed operation of Section 4A(4) of the MMDR Act up to September 21, 2026, extending time for operationalisation of Deposit 13. Initial mining activities commenced from July 23, 2026.
Bastar Railway project takeover. The Ministry of Railways granted in-principle approval for taking over the BRPL project. Railway Board letter No. 2015/Infra/12/3PT dated 20.02.2026 conveyed approval for termination of the Concession Agreement between SECR and BRPL on mutually agreeable terms with financial settlement guidelines. Expenditure towards land acquisition, litigation and forest survey is to be reimbursed to BRPL after physical verification and confirmation of clear title in the name of Railways; administrative expenditure until termination is to be borne by BRPL and SECR is to take over pending court cases. The Office of Dy. Chief Engineer/III/Construction, by letter dated June 12, 2026, sought action on verification and transfer of land acquired, and IRCON was informed. NMDC’s total investment in BRPL as on June 30, 2026 is ₹152.67 crores, carried at cost, and the company expects full recovery of project cost incurred by BRPL pending verification, settlement and formal takeover.
RINL revival support. On January 17, 2025, the Cabinet Committee on Economic Affairs approved a revival plan for RINL with a Government of India financial package of ₹11,440 crores. Lenders approved a significant financial plan to support RINL’s recovery, and the Ministry of Steel is pursuing measures to enhance RINL’s operational and financial sustainability. Management is confident the entire outstanding receivable will be fully recoverable.
NSL scale-up. Management cites increased capacity and consequent scale-up of NSL operations from FY 2024-25 onwards as the basis for confidence in ultimate recovery of all outstanding amounts.
RINL land lease for facilities. During FY 2024-25, NMDC entered into an MoU with RINL on September 4, 2024 for a long-term lease of approximately 1,167 acres for establishing various facilities: 30 years at a nominal annual ground rent of Re. 1, with an upfront premium of ₹1,502 crores and a security deposit of ₹90.12 crores. A Right of Use asset was recognised effective September 4, 2024 under Ind AS 116. The lease agreement was registered on May 1, 2025. As of the reporting date the security deposit of ₹90.12 crores is yet to be paid and unpaid upfront premium of ₹503.11 crores is considered under lease liability.
LIOL project advancement. LIOL entered a joint venture with Hancock Prospecting Pty Ltd to develop magnetite iron ore assets at the Mt. Bevan Project, advancing through feasibility studies. At Mt. Celia it continues exploration and drilling to find additional mineral resources and upgrade inferred resources to higher-confidence categories, and is obtaining a pre-feasibility study report for a heap leach and gold recovery plant.
Key Risks
- The Karnataka mineral tax Bill, if enacted as drafted, could give rise to a liability of approximately ₹15,785.72 crores, with recovery from customers/bidders dependent on enforceability of contractual recourse provisions.
- Recoverability of ₹1,601.39 crores from NSL arising from the demerger, plus ₹4,846.56 crores of trade and other receivables from NSL, depends on NSL’s continued scale-up and the repayment schedule provided.
- Recoverability of ₹4,712.47 crores from RINL depends on continued government support and the approved revival plan.
- The KVSL land matter depends on the outcome of discussions with the Government of Karnataka and KIADB, with ₹95.94 crores in contingent liabilities and the ₹639.61 crores advance classified as a non-current asset.
- The ₹1,623.44 crores Common Cause compensation demand and the ₹1,620.50 crores RTP penalty are sub judice, with outcomes dependent on pending proceedings.
- LIOL’s market value of investment (₹295.29 crores) is below its carrying value; no impairment was recognised based on an independent assessment as at March 31, 2026.
- BRPL’s ₹85.63 crores excess compensation matter, of which ₹83.63 crores relates to two individuals, is pending before the Supreme Court.
- The HR Coil & Sheets segment had no revenue in the June 2026 quarter pending necessary approvals.
Management Guidance Versus Observed Business Performance
- NSL recovery: Management is confident of ultimate recovery of all NSL amounts, citing increased capacity and scale-up of NSL operations from FY 2024-25 onwards. Observed: NSL repaid ₹901.25 crores of the ₹2,502.64 crores incurred on its behalf and provided a repayment schedule during the quarter; ₹1,601.39 crores remains outstanding and is presented under Current Assets – Other Financial Assets. An expected credit loss of ₹136.19 crores was recognised.
- RINL recovery: Management is confident the entire outstanding receivable will be fully recoverable, citing the CCEA revival plan of January 17, 2025, lender support and Ministry of Steel measures. Observed: ₹4,712.47 crores remains outstanding as at June 30, 2026, with an expected credit loss of ₹298.48 crores recognised.
- KVSL: Management states the financial impact depends on the final outcome of discussions with the Government of Karnataka and KIADB, pending the KVSL Board’s decision. Observed: the lease agreement is still not executed, the extension request is under review, and NMDC was directed by the Ministry of Steel on July 08, 2026 to explore value-added product facilities, with the KVSL Board deliberating on July 30, 2026.
- NMDC-CMDC: Management carries the investment at cost in view of project developments. Observed: Deposit-4 lease deed executed and registered January 21, 2026 with major statutory approvals obtained and initial mining commenced; Deposit-13 clearances progressed through June–July 2026 and initial mining commenced July 23, 2026.
- BRPL: Management expects full recovery of project cost incurred by BRPL, pending land verification by the joint committee of SECR, BRPL and IRCON, finalisation of financial settlement and formal takeover by the Ministry of Railways. Observed: the Railway Board approval letter is dated 20.02.2026 and the Dy. Chief Engineer’s letter seeking verification and transfer action is dated June 12, 2026.
- LIOL: Management views no significant developments since the March 31, 2026 impairment assessment affecting the conclusion that recoverable value exceeds carrying value. Observed: the investment’s market value based on LIOL’s share price was ₹295.29 crores as at June 30, 2026, below the carrying value of ₹443.34 crores.
- Production and sales: Cumulative iron ore production up to July 2026 rose to 19.16 MT from 15.09 MT a year earlier, while cumulative sales rose only to 15.15 MT from 14.98 MT, with Karnataka cumulative sales declining to 3.36 MT from 4.69 MT.
Broker Narrative
The broker narrative shifted from broad market-level optimism about Nifty momentum and technical upside in 2021 to stock-specific fundamental concerns about commodity pricing and capital allocation by 2026. The long-term structural growth story—NMDC’s iron ore dominance, rising steel demand, and production targets—persisted across all reports, while near-term framing evolved from fear of a Nifty correction to worries about range-bound iron ore prices and elevated capex dragging earnings. Early emphasis on RSI-driven momentum and higher tops gave way to later focus on diversification into critical minerals and coal blocks as growth catalysts.
Fears that came true
- The latest report’s flagged headwind of elevated capex spends weighing on earnings correlates with the near-flat to negative 2026 actual returns (e.g., -9.0% in June 2026 and -4.8% in May 2026), indicating the concern is materializing.
- Early concerns about limited near-term upside and potential market consolidation echoed in several DISAPPOINTMENT outcomes, such as May 2024 (-11.3% actual vs. +16.3% predicted) and June 2026 (-9.0% actual), where upside failed to materialize.
Optimism that failed
- The optimism about rising iron ore demand and ambitious 100 MT production targets translating into near-term stock gains has not yet materialized, as 2026 reports show flat-to-negative actual returns despite the bullish long-term framing.
Broker Timeline
59 broker calls · 2021-06-07 to 2026-08-17
Copyright © 2023 SAS Data Analytics Pvt. Ltd. All rights reserved.