NH
Equity Metrics
October 23, 2026
Narayana Hrudayalaya Ltd.
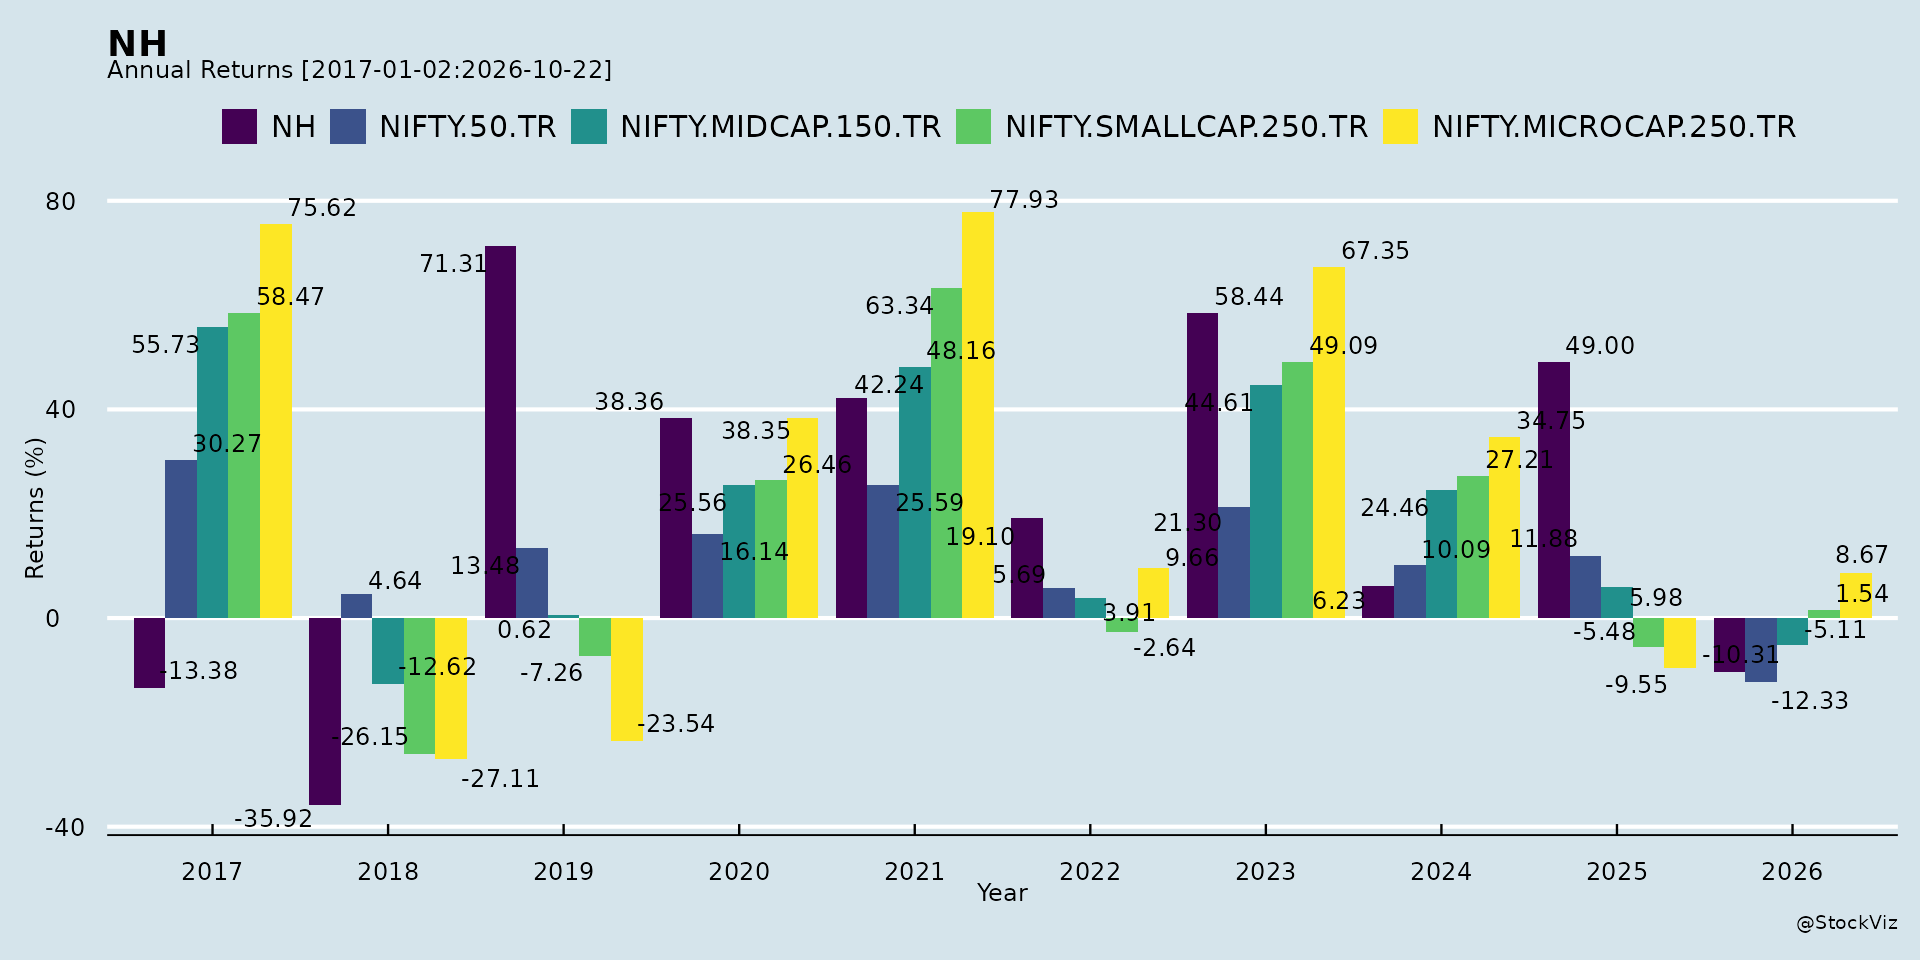
Annual Returns
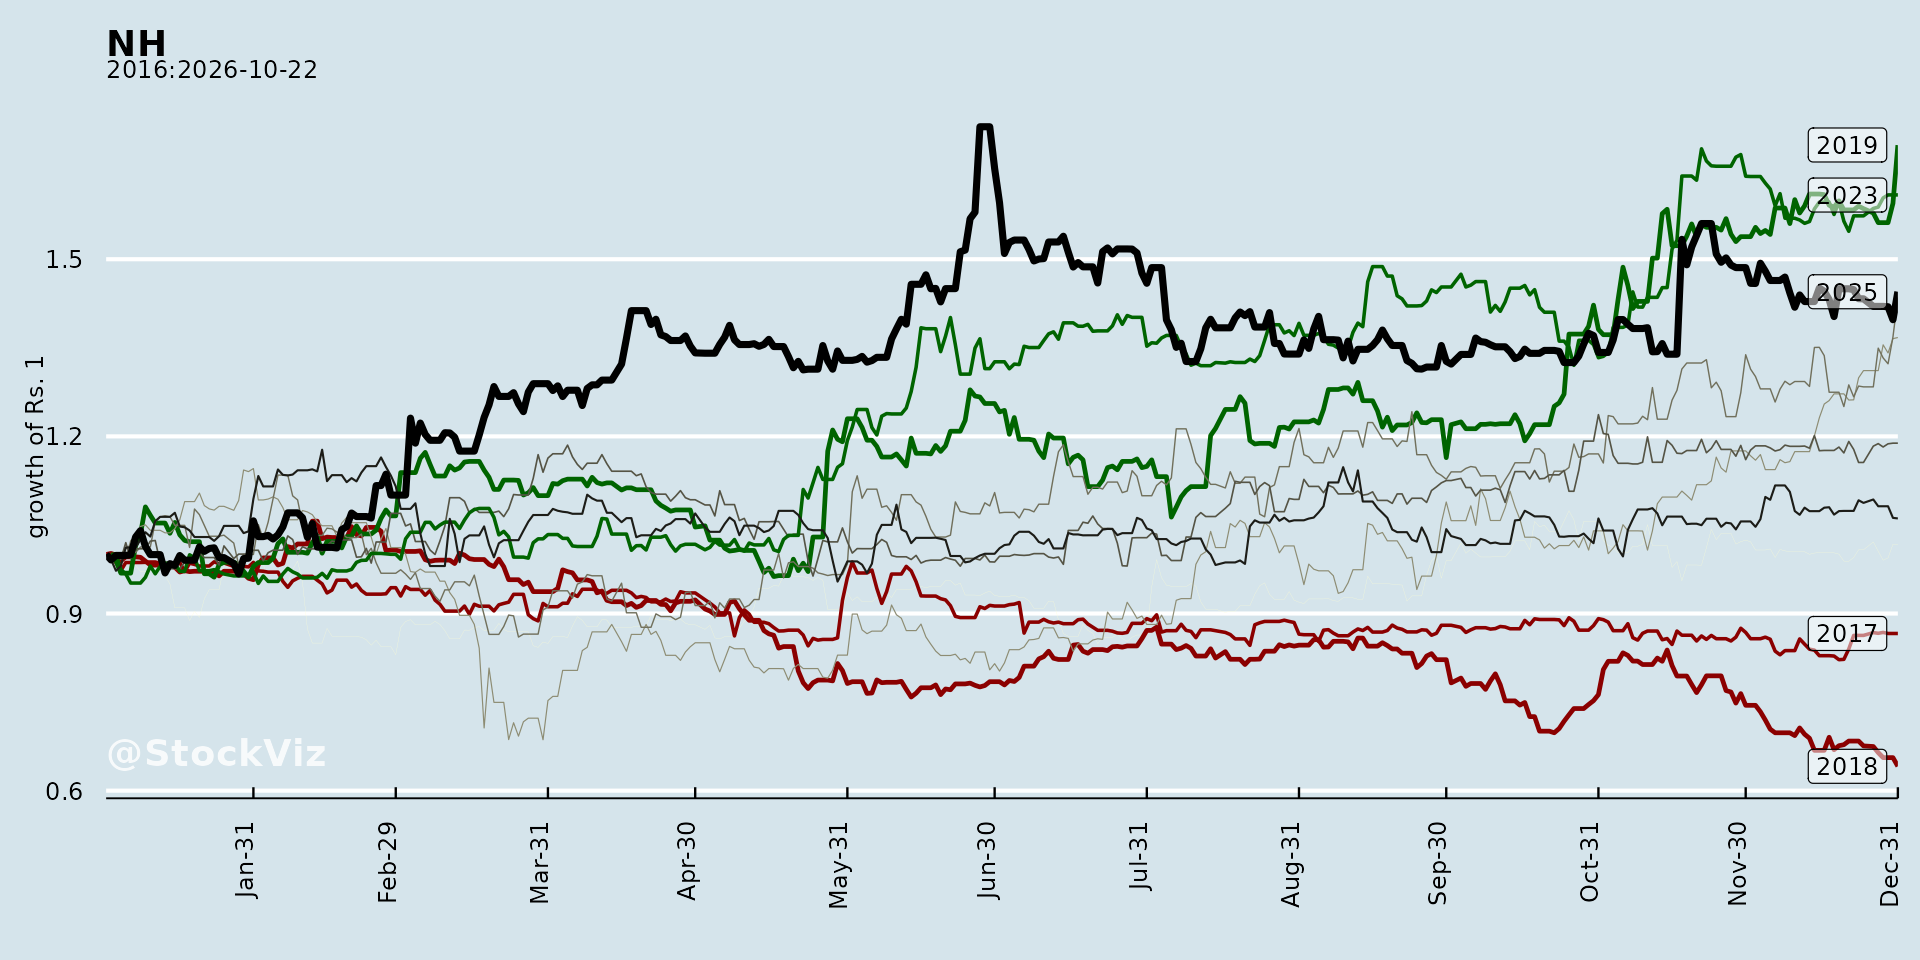
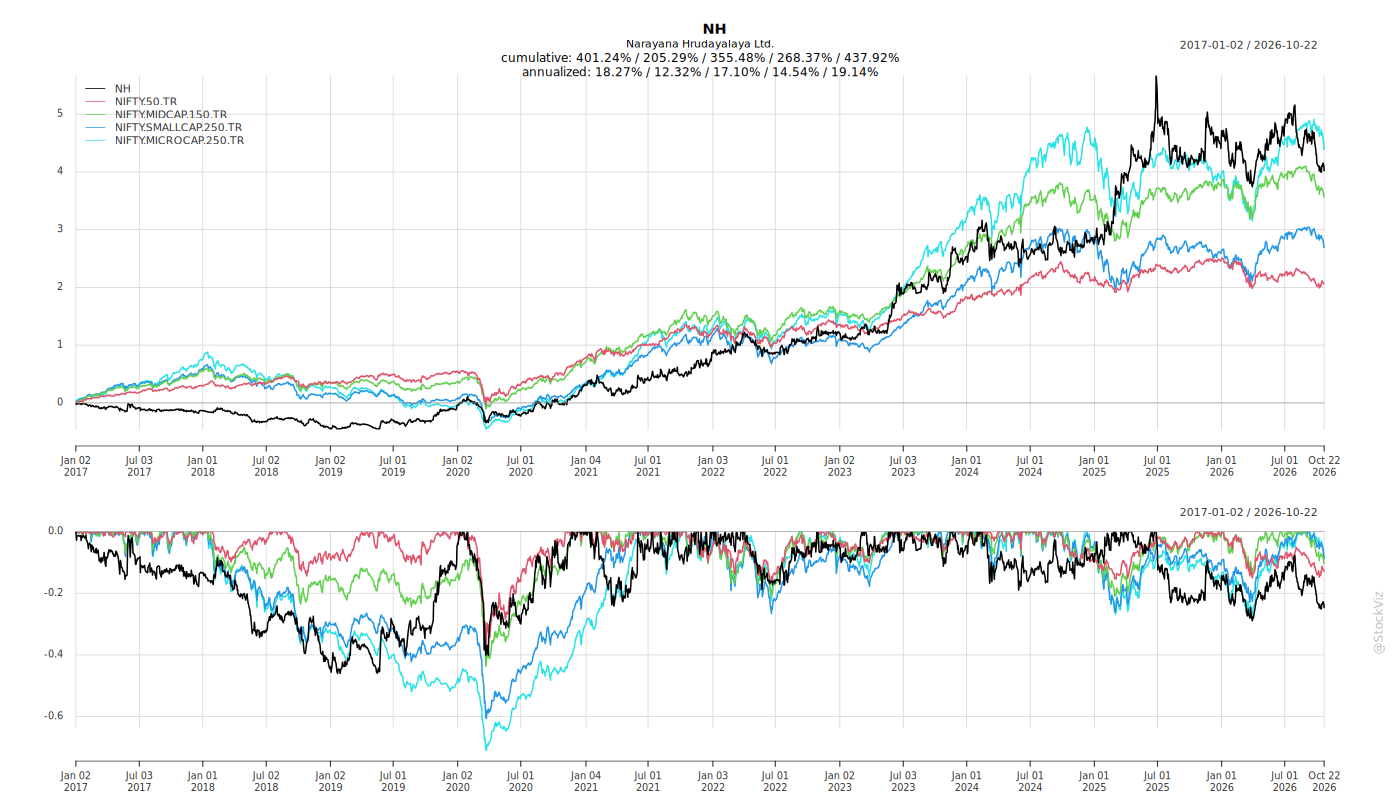
Cumulative Returns and Drawdowns
Fundamentals
Ownership
Margined
AI Summary
asof: 2026-09-16
Narayana Hrudayalaya (NH): Recent Corporate Announcements Analysis
1. Headwinds and Challenges
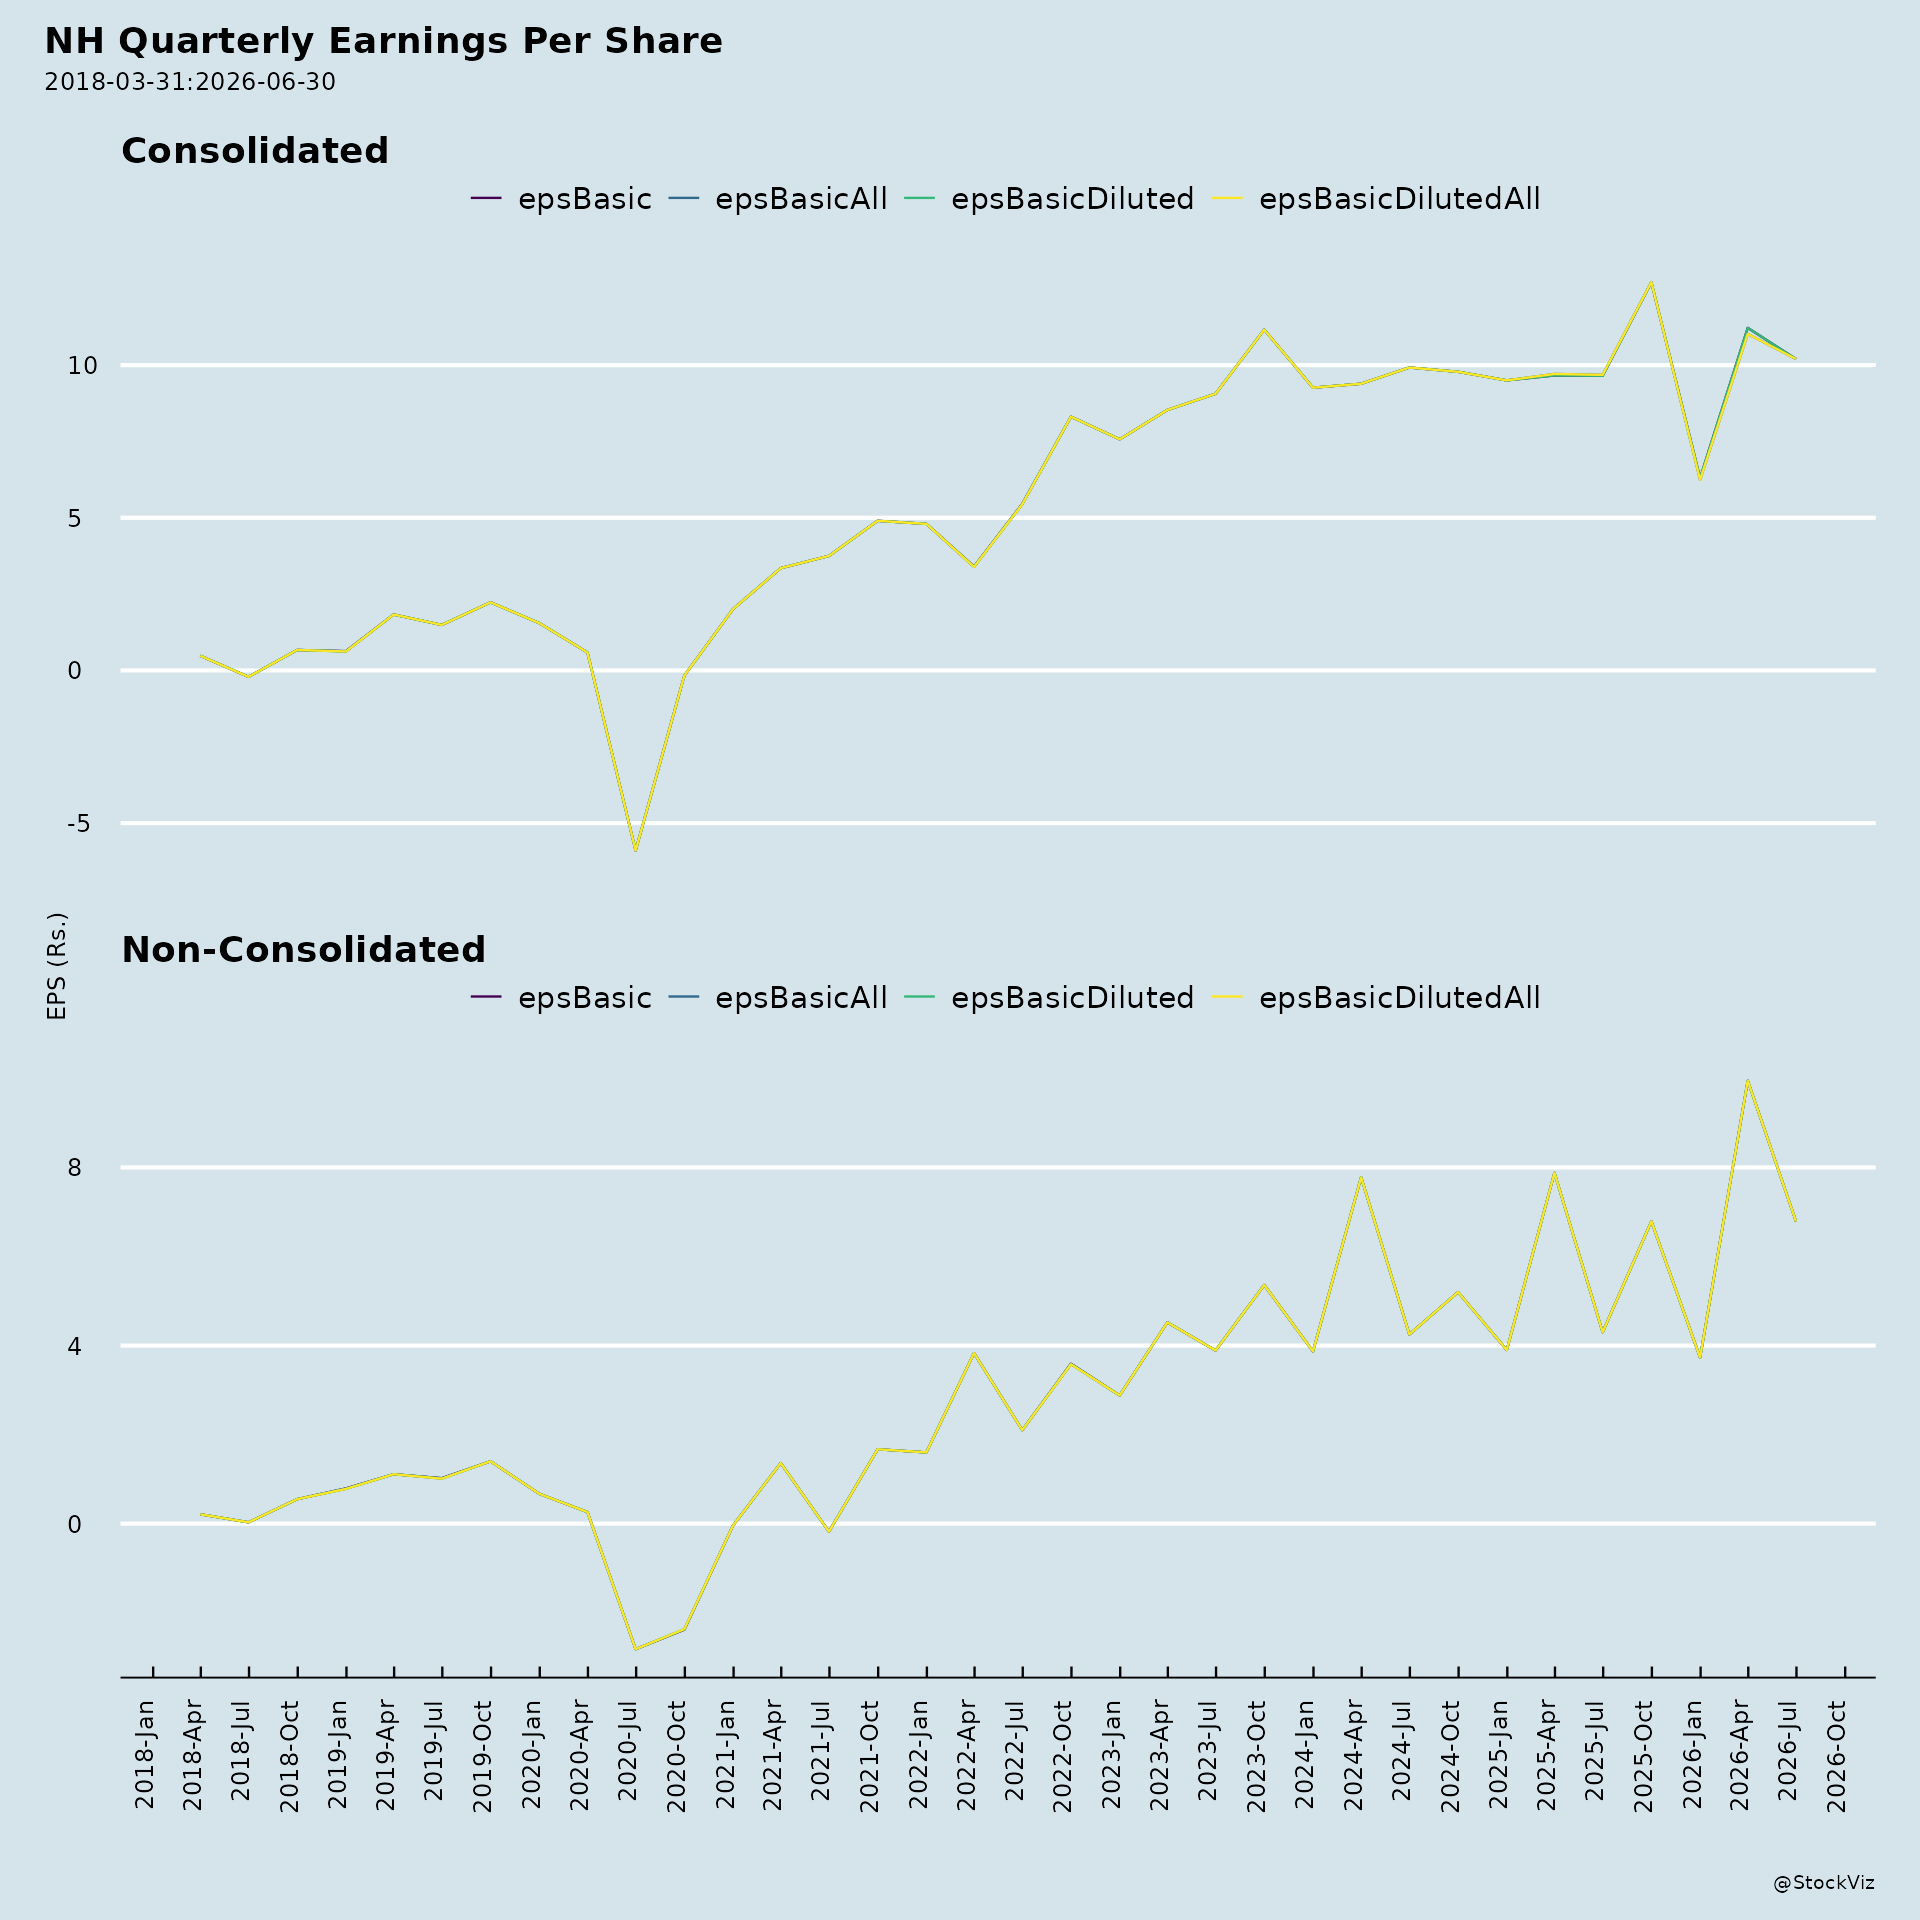
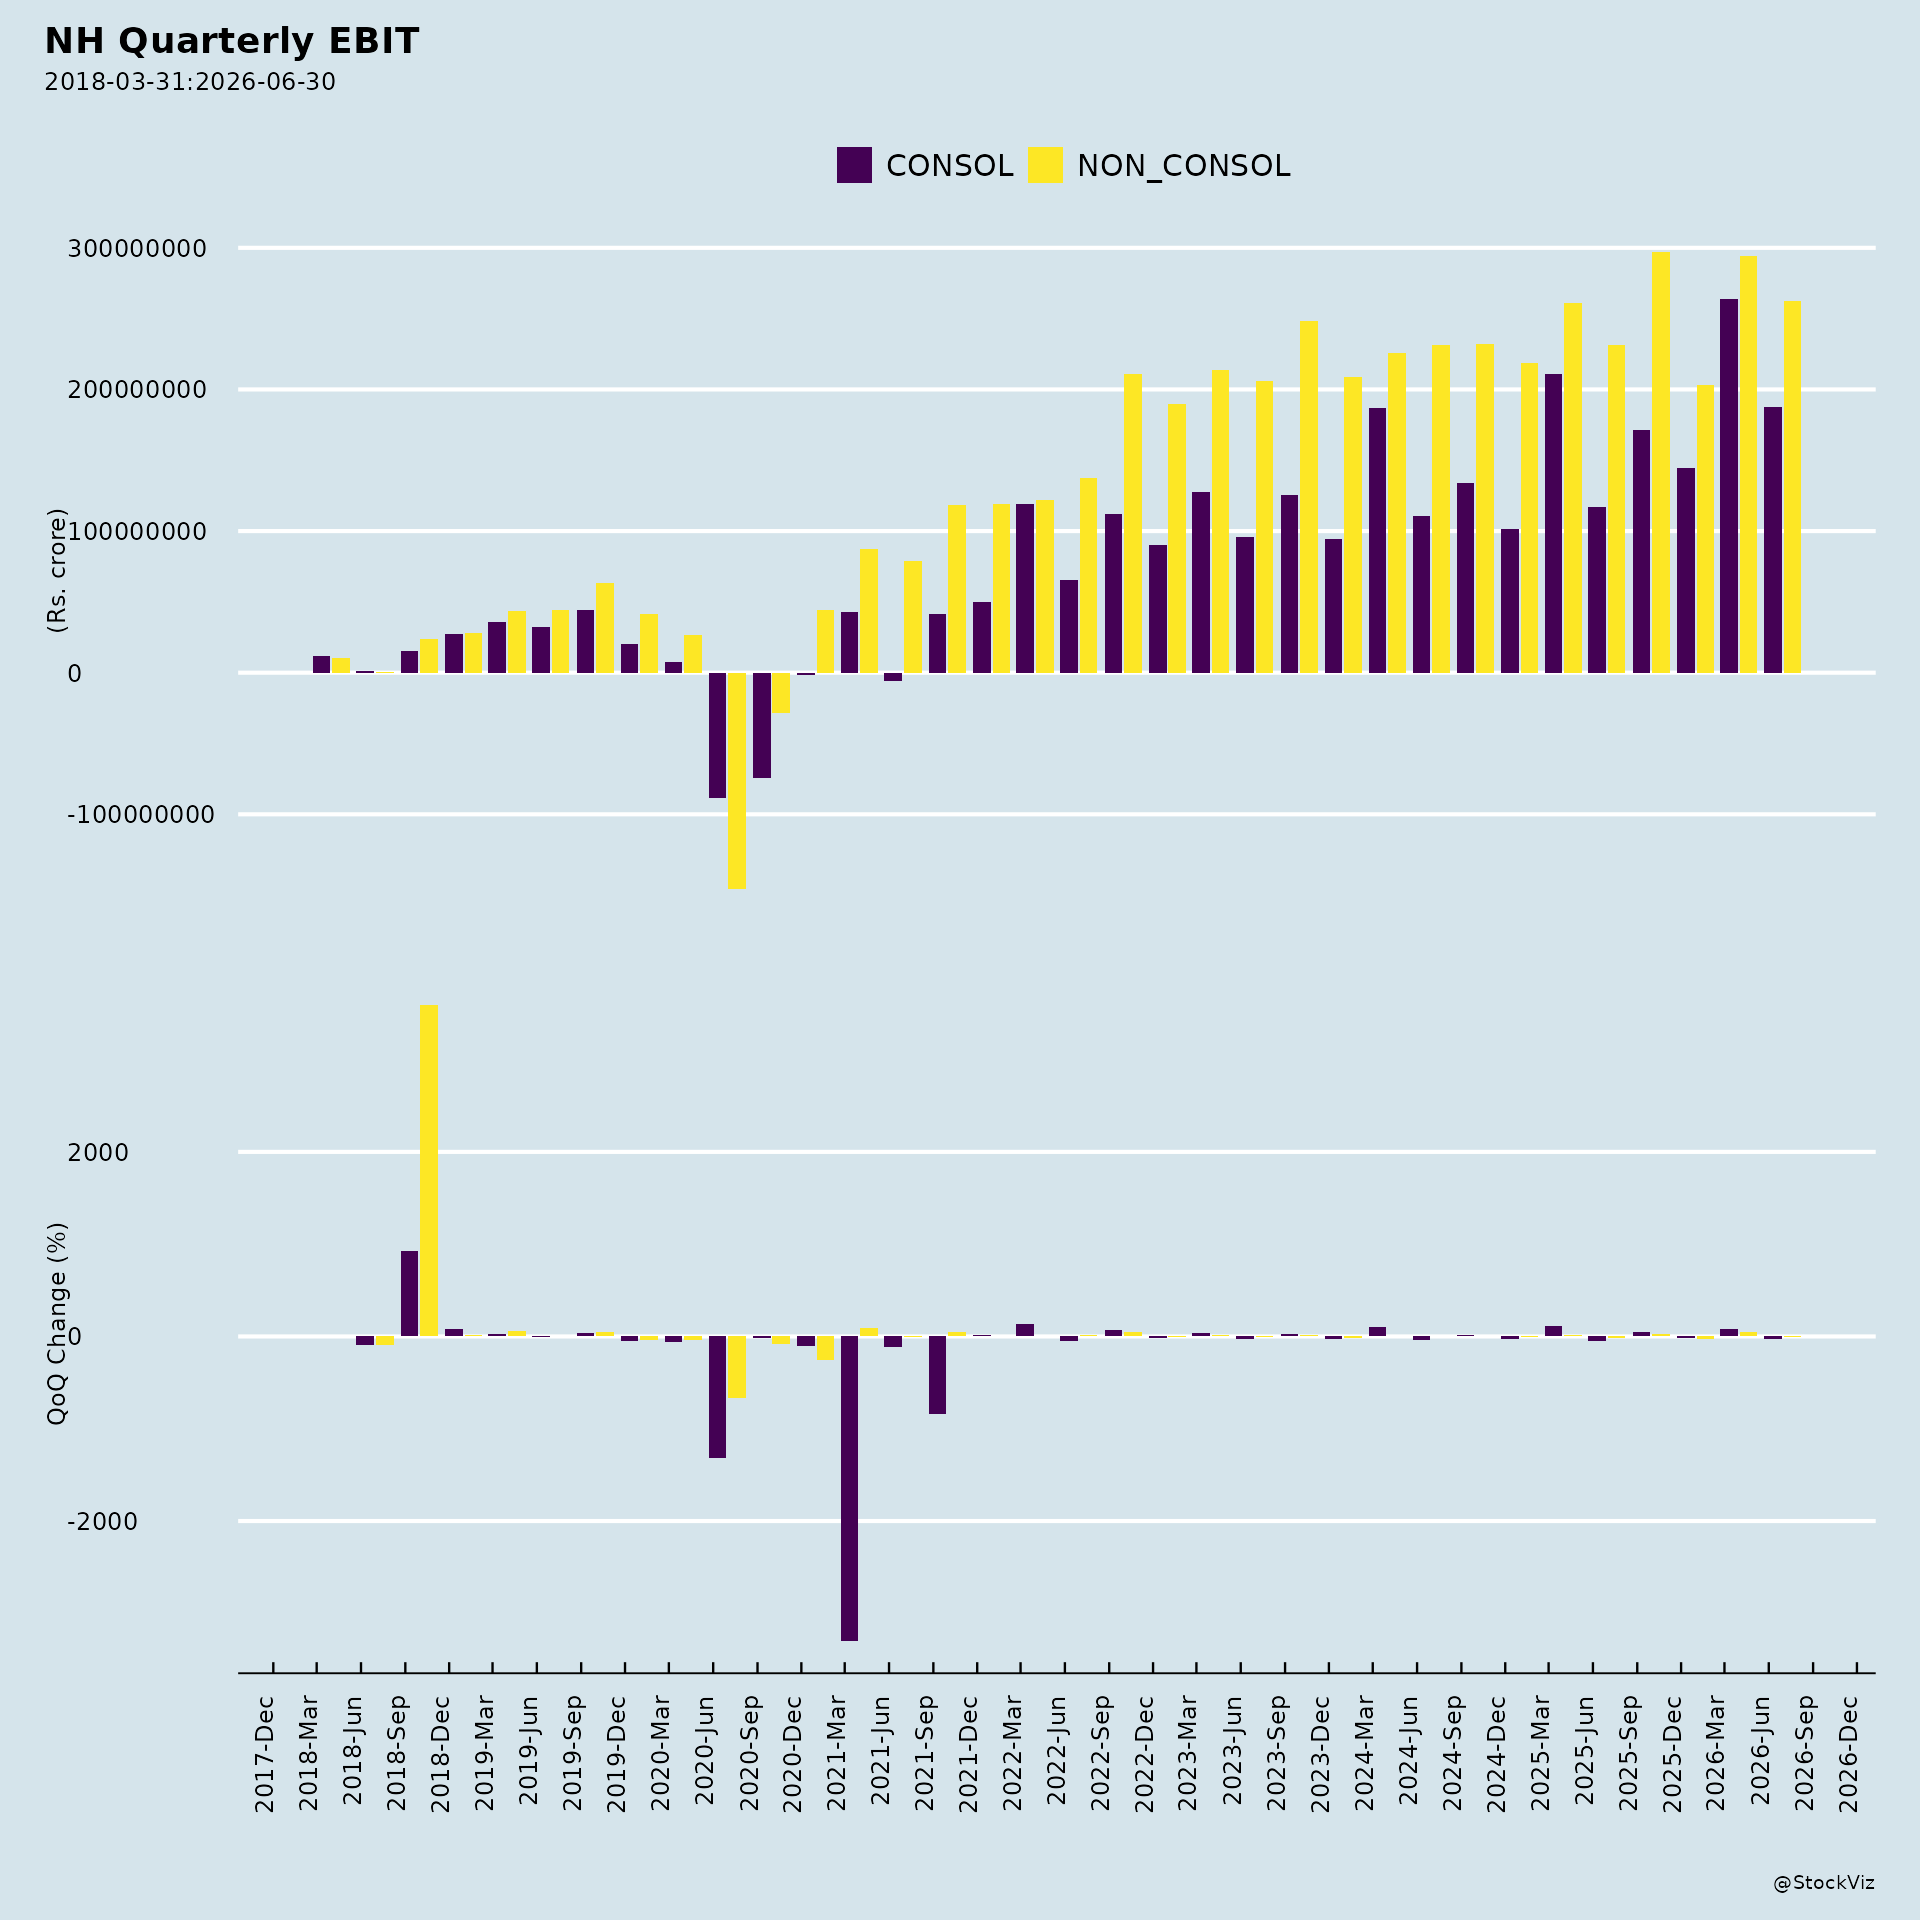
Margin compression despite revenue growth. In Q1 FY27 (quarter ended June 30, 2026), consolidated operating revenue grew 78.0% YoY to ₹26,836 Mn, but consolidated EBITDA margin fell to 18.8% from 23.9% in Q1 FY26. Consolidated PAT grew only 5.7% YoY to ₹2,073 Mn, with PAT margin declining to 7.7% from 13.0%. On a sequential basis, consolidated EBITDA declined 6.4% QoQ and PAT declined 9.2% QoQ.
Seasonally weaker quarter in India. Management noted that Q1 is a seasonally weaker quarter, though India still delivered 17.0% YoY revenue growth.
Insurance segment losses. The “Others” (Insurance) segment reported a loss of ₹624.61 Mn in Q1 FY27, compared with a loss of ₹240.46 Mn in Q1 FY26 and ₹599.70 Mn in Q4 FY26.
Elevated leverage and foreign currency exposure. As of June 30, 2026, total borrowings less cash, bank balances and investments stood at ₹19,671 Mn, with a net debt-to-equity ratio of 0.42. Debt worth US$115 Mn and GBP £150 Mn is foreign currency denominated. Consolidated debt-equity ratio rose to 1.24 from 0.58 a year earlier, and the interest service coverage ratio declined to 4.00 from 6.11 YoY.
Rising employee costs. Consolidated employee benefits expense rose to ₹7,248.38 Mn in Q1 FY27 from ₹2,955.23 Mn in Q1 FY26, reflecting the enlarged group following the UK acquisition.
Regulatory and compliance burden. The BRSR identifies regulatory issues and compliance, corporate governance obligations, business conduct and compliance, data security and privacy, health and safety, process safety and quality, business continuity, and water stress as material risks. Customer complaints (regular complaints in hospitals) rose to 3,413 in FY2025-26 from 2,561 in FY2024-25, and 22 patient litigations were filed during the year, with 1 pending at year-end.
Pending regulatory approvals for schemes. The merger of Meridian Medical Research & Hospital Ltd (MMRHL) into NH and the demerger of clinical services from NH Integrated Care Private Limited (NHIC) into NH both await final NCLT orders, with no impact on Q1 FY27 results.
Discontinued operations. The Shri Mata Vaishno Devi Narayana Superspeciality Hospital business was transferred to Shri Mata Vaishno Devi Charitable Society effective April 1, 2026, and is treated as discontinued operations. A write-down of approximately ₹62.06 million was recorded in the previous year.
2. Tailwinds and Growth Prospects
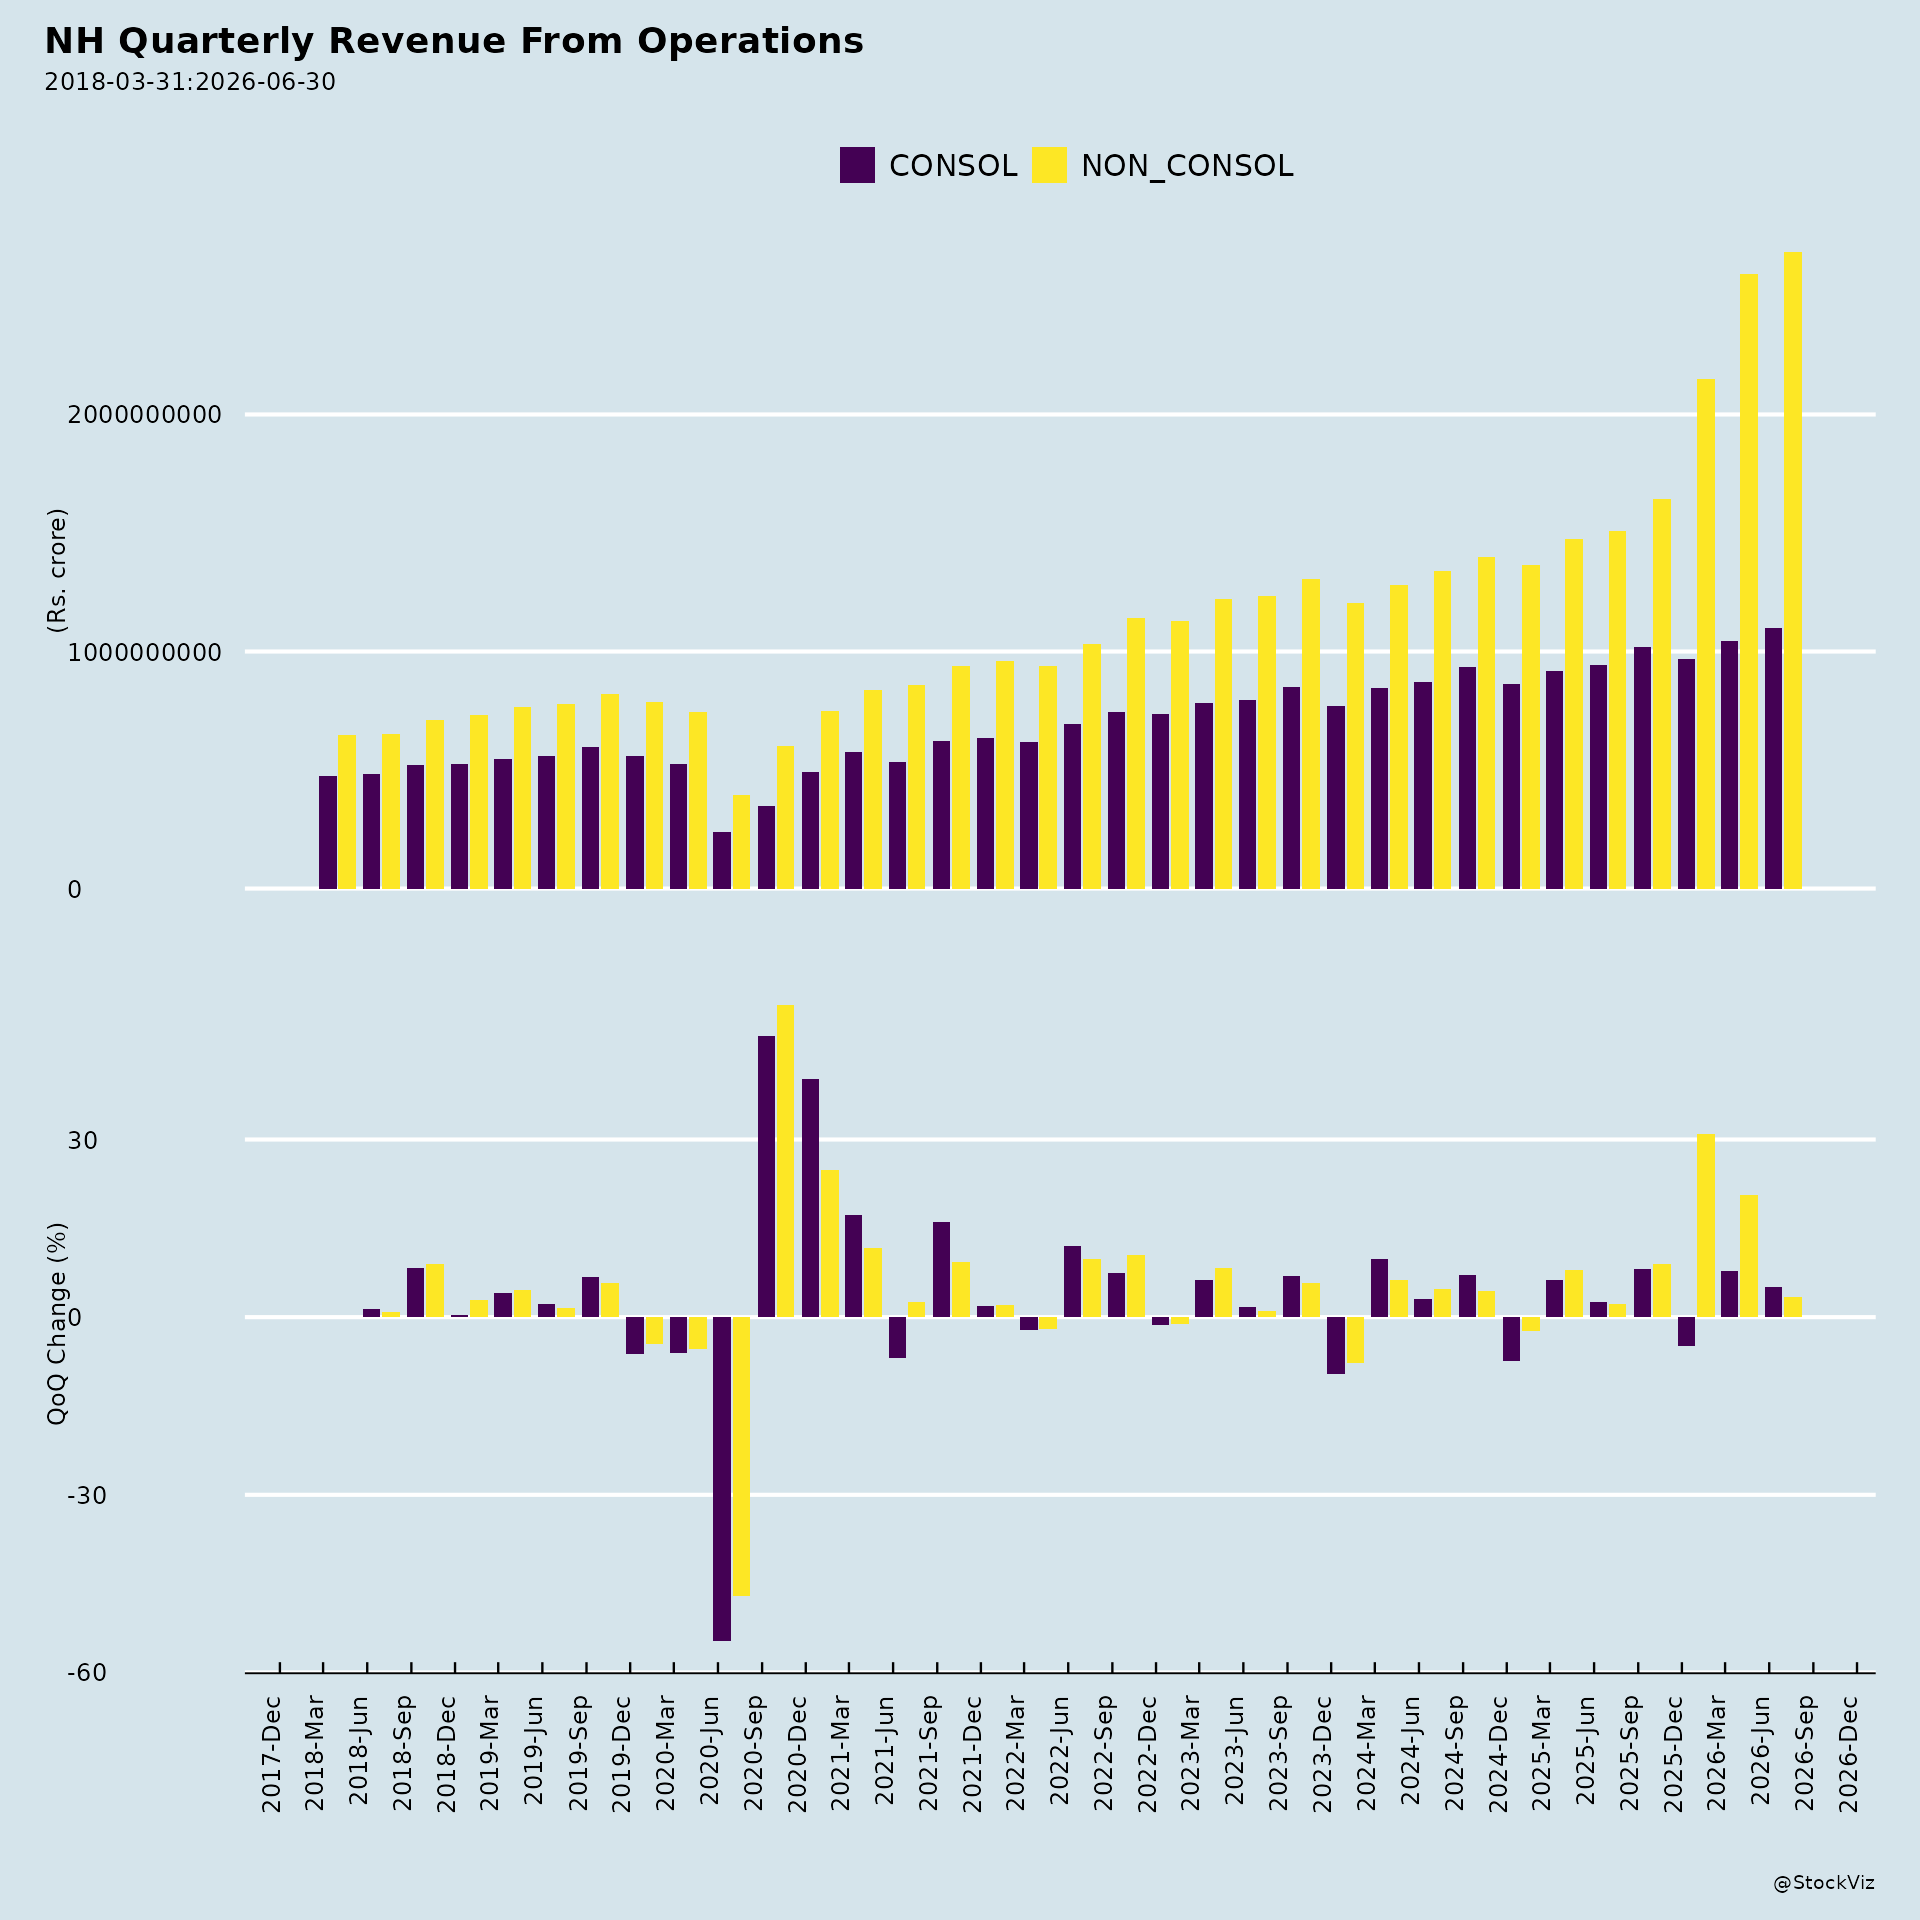
Strong consolidated revenue growth. Q1 FY27 consolidated operating revenue was ₹26,836 Mn, up 78.0% YoY and 3.5% QoQ, driven by all geographies.
India business momentum. India operating revenue was ₹13,247 Mn in Q1 FY27, up 17.0% YoY and 5.9% QoQ, attributed to higher patient footfall, focus on high-end and complex procedures, and strong underlying customer demand. The expanding Integrated Care ecosystem—clinics and insurance—is reinforcing momentum and strengthening the funnel into the hospital network.
Cayman business performance. Cayman operating revenue was ₹5,514 Mn, up 38.9% YoY (down 1.8% QoQ), supported by the One Health insurance platform, which management states has strengthened patient access and affordability.
UK business stability. UK operating revenue was ₹8,257 Mn in Q1 FY27, up 2.1% QoQ. The business is in its third quarter under NH, with integration progressing and separation from its erstwhile parent approaching completion. Management expressed confidence in its growth potential.
Clinical capability expansion. Narayana Institute of Cardiac Sciences, Bangalore performed 2,137 cardiac surgeries in Q1 FY27 and 19 Pulse Field Ablation procedures in June 2026 for Atrial Fibrillation since launch in India. Narayana Hospital, Gurugram operationalized the CUVIS Ortho Robotic System and a Thulium Laser System. A wide spectrum of robotic surgery was performed across units, including robotic CBD exploration, robot-assisted hiatus and ventral hernia repair, robotic simple prostatectomy, and robotic cytoreductive surgery.
Access to healthcare as an opportunity. The BRSR identifies access to healthcare as a material opportunity, with positive financial implications expected from expanding the breadth of operational activities.
Energy efficiency opportunity. Energy-efficient initiatives aligned with ESG objectives are expected to reduce energy expenses and enhance profitability.
Network scale. NH operates 55 healthcare facilities across India with overseas presence in the Cayman Islands and the United Kingdom, with over 5,900 operational beds and capacity of over 6,200 beds.
3. Key Risks
Health and safety risk. Potential financial implications related to legal disputes, with mitigation through certifications, policies, and codes of conduct applicable to employees, patients, and other stakeholders.
Process safety and quality risk. Potential revenue risk from concerns related to safety standards and service quality, mitigated through a three-layer NHL Governance Framework and JCI and NABH accreditations.
Corporate governance and business conduct risk. Failure to comply with laws and regulations may lead to adverse rulings and negative consequences, mitigated through well-defined policies, dedicated committees, and a diverse board.
Business continuity risk. Possible interruptions from disasters, mitigated through detailed disaster management plans.
Data security and privacy risk. Risk of losing sensitive data impacting patient information, organizational operations, and internal procedures, mitigated through an organization-wide policy overseen by the board and committees.
Regulatory issues and compliance risk. Risk of negative outcomes from non-compliance with healthcare regulations, mitigated through robust policies and procedures with KPIs monitored regularly.
Water stress risk. Water scarcity negatively affects hospital operations, leading to increased costs for water procurement, mitigated through treated domestic wastewater reuse for non-contact applications and rainwater harvesting.
Foreign currency exposure. Debt denominated in US dollars and GBP exposes the group to exchange rate movements. Cayman and UK numbers are converted at 94.71 for YTD FY27 versus 88.31 for FY26, and UK numbers at 1.34 GBP/USD for YTD FY27.
Insurance segment drag. The insurance segment continues to report losses, with the “Others” segment result at negative ₹624.61 Mn in Q1 FY27.
4. Management Guidance Versus Observed Business Performance
Management commentary on Q1 FY27. Dr. Emmanuel Rupert, Managing Director and Group CEO, stated that the first quarter of FY27 started on a strong note with all geographies delivering robust performance. He noted that despite Q1 being seasonally weaker, India delivered robust growth driven by higher patient footfall, focus on high-end and complex procedures, and strong underlying customer demand. He stated that the Cayman business continues to perform well, supported by the One Health insurance platform. He described the UK business as stable, with integration progressing well and separation from its erstwhile parent approaching completion, and expressed confidence in its growth potential. He stated confidence in delivering on expectations for the year.
Observed performance versus commentary. Consolidated revenue growth of 78.0% YoY and India growth of 17.0% YoY are consistent with the described strong note. However, consolidated EBITDA margin declined to 18.8% from 23.9%, and PAT margin declined to 7.7% from 13.0%, indicating that profitability did not keep pace with revenue growth. The insurance segment loss widened YoY. The UK business, described as stable, contributed ₹8,257 Mn in revenue with 2.1% QoQ growth. Cayman revenue grew 38.9% YoY but declined 1.8% QoQ.
Guidance on schemes. Management expects final NCLT orders for both the MMRHL merger and the NHIC demerger in due course, with no impact on Q1 FY27 results. The MMRHL scheme has an appointed date of April 1, 2024, and the NHIC scheme has an appointed date of April 1, 2025.
Investor engagement. NH scheduled a one-on-one meeting with FSSA Investment Managers on August 20, 2026, and hosted a Q1 FY27 earnings conference call on August 3, 2026, with the transcript to be uploaded on the company website.
Broker Narrative
The broker maintained a Buy rating throughout, but the story narrowed over time: the first report framed India new-unit turnarounds, Cayman cash generation, and the NHIC integrated-care model as broad growth drivers, while the last report leans almost entirely on India hospital execution and margin/ARPOB expansion. Persistent themes include capex/bed additions, India margin expansion, and Cayman repricing, but early confidence in Cayman’s margin-accretive strength and NHIC’s demand-creation value has been replaced by explicit acknowledgement of Cayman/CIHL insurance losses, widening India insurance/clinic losses, UK operational shocks, and project delays.
Fears that came true
- The early concern that the new Cayman unit would be margin-dilutive materialized, as the last report notes Cayman seasonal weakness, modest revenue growth, and continued CIHL insurance losses, accompanying DISAPPOINTMENT outcomes.
- The early caution that NHIC would not be remunerative initially materialized, with India insurance and clinics losses jumping sharply QoQ from INR180mn to INR330mn.
Optimism that failed
- The expectation that Cayman would remain a strong, margin-accretive cash generator failed to hold, as insurance losses persisted despite ex-insurance volume growth.
- The optimism that the NHIC asset-light integrated-care model would create long-term patient demand has not paid off operationally, with its insurance and clinic losses widening sharply.
- The planned throughput expansion via aggressive capex has been delayed, with Rajarhat, Central/South Bangalore, and some asset-light partner-model projects pushed back due to licensing approvals.
Broker Timeline
25 broker calls · 2023-06-16 to 2026-08-04
Copyright © 2023 SAS Data Analytics Pvt. Ltd. All rights reserved.