MBEL
Equity Metrics
September 24, 2026
M & B Engineering Limited
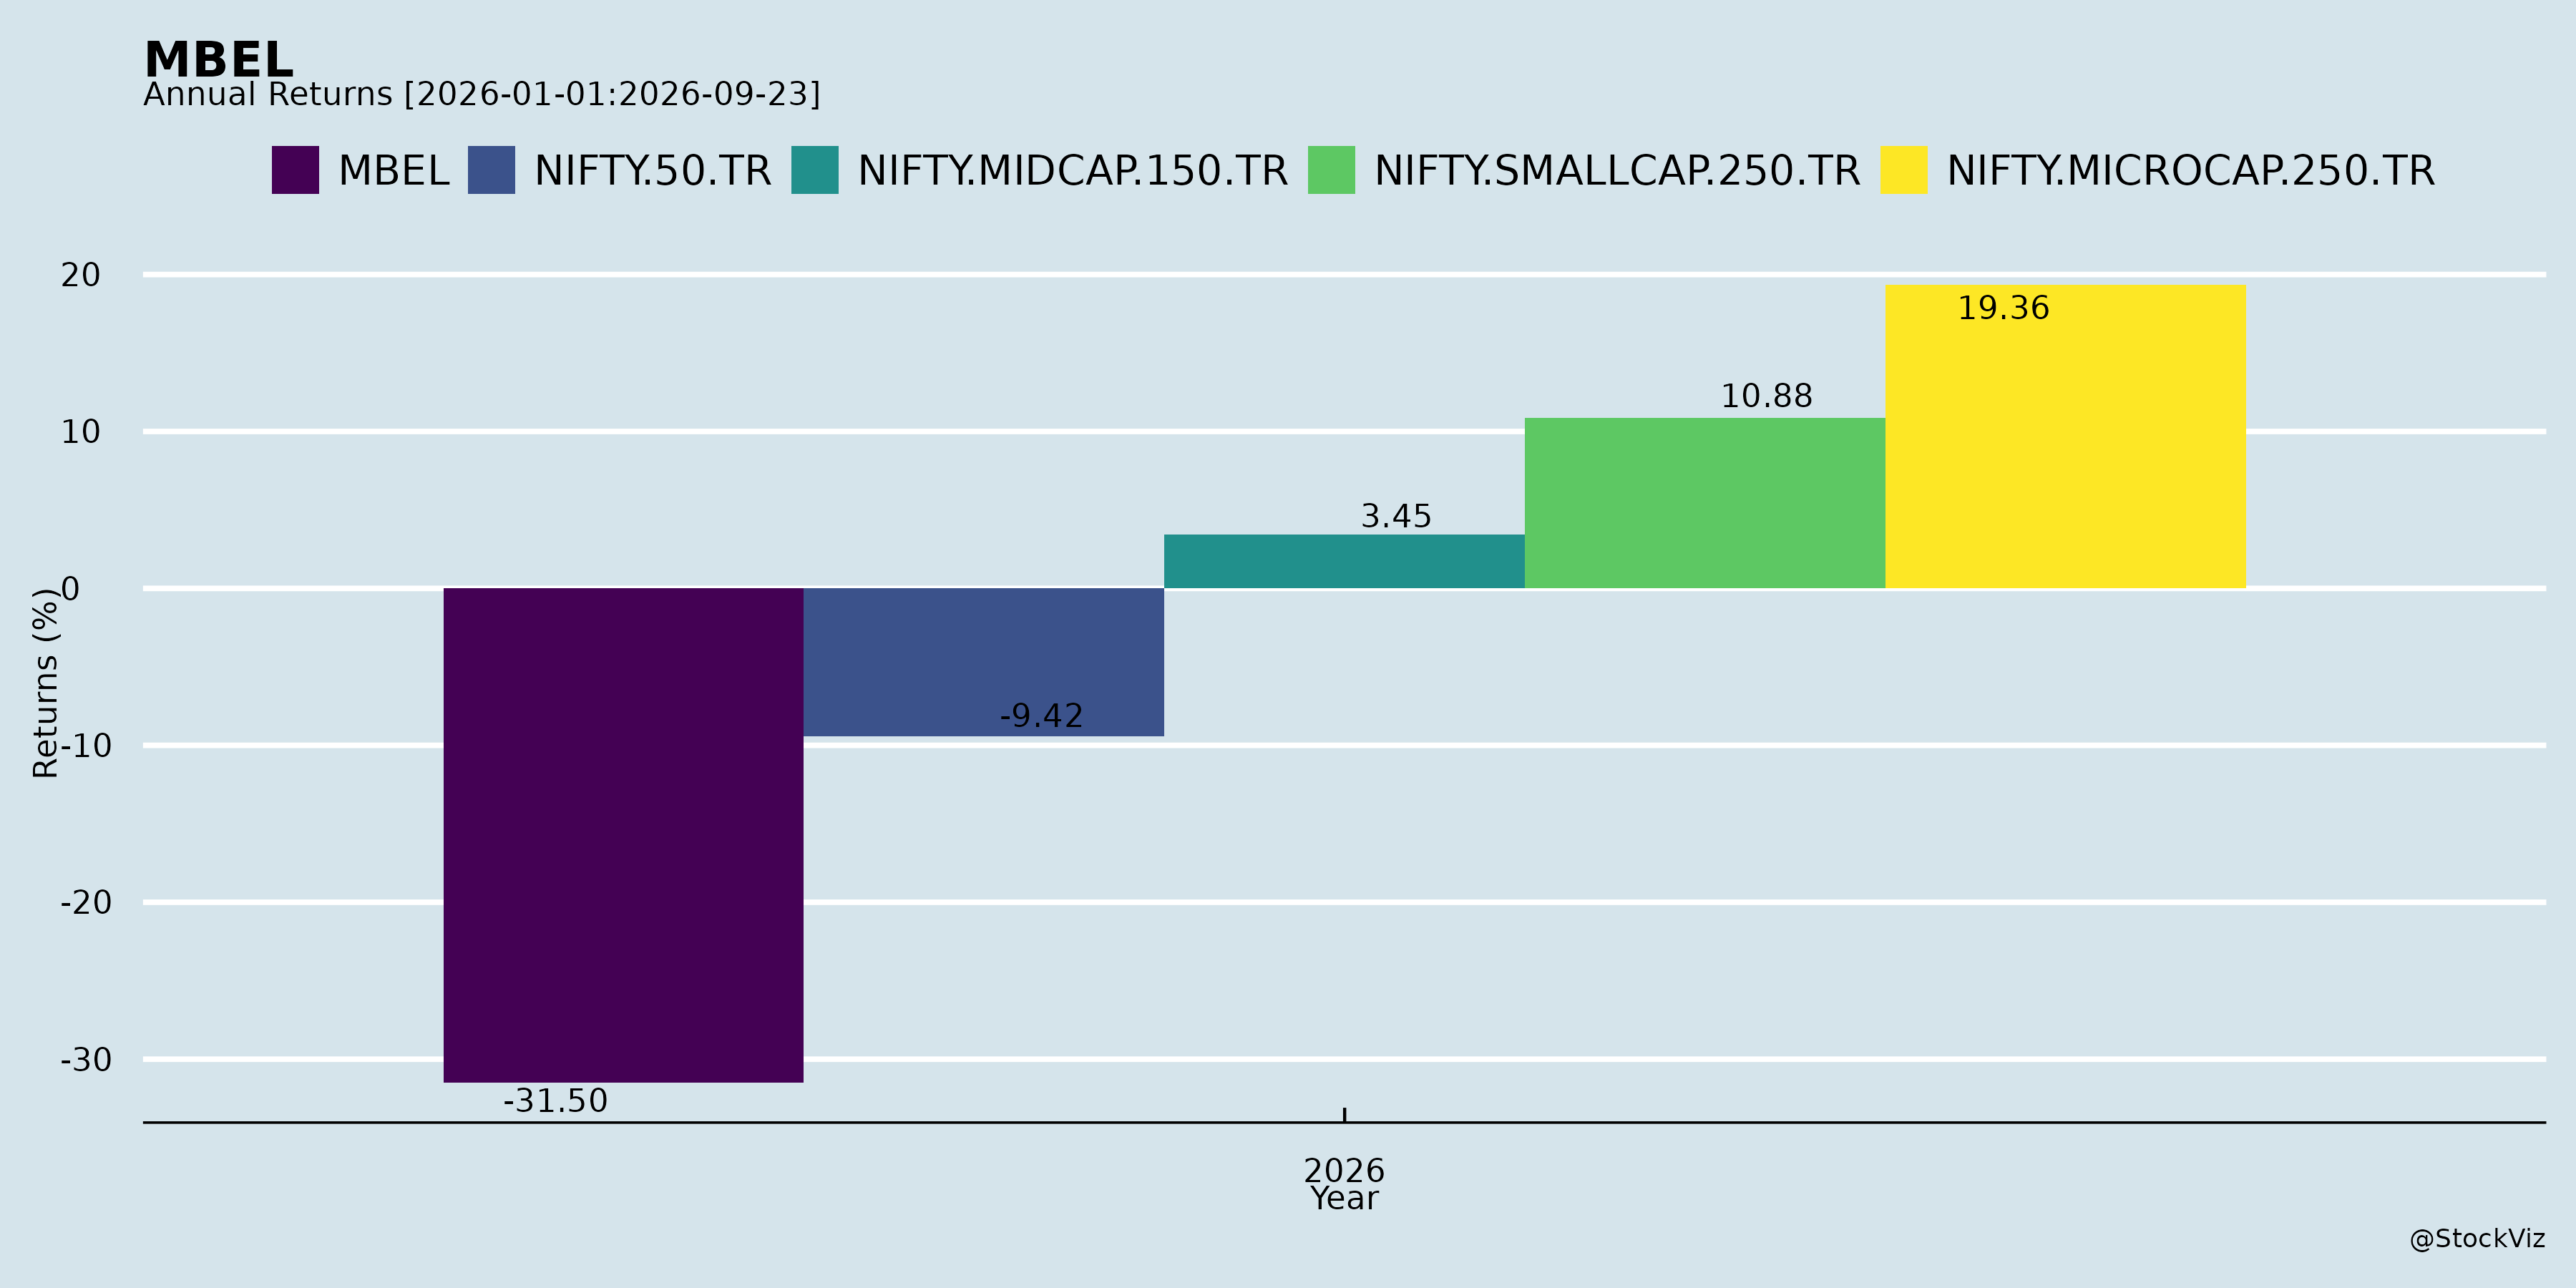
Annual Returns

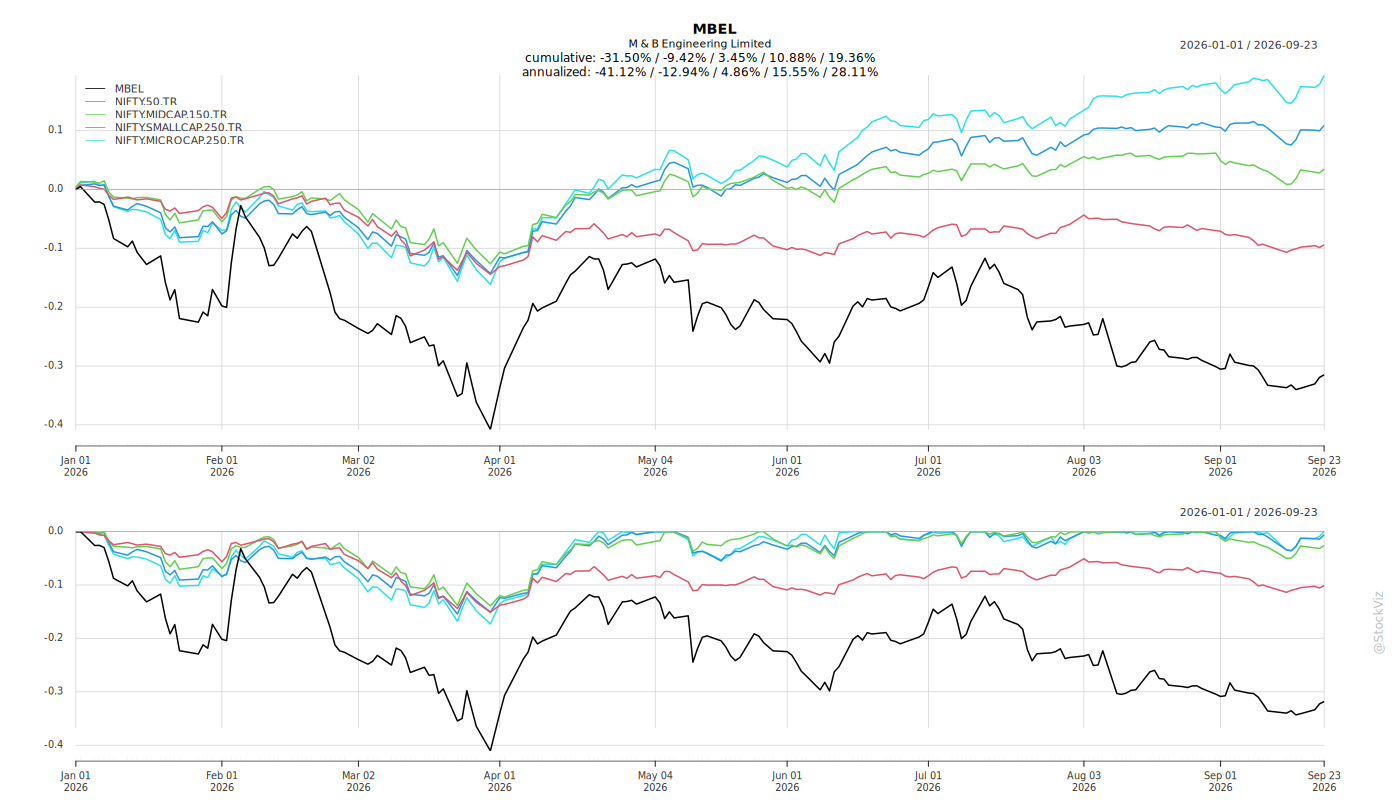
Cumulative Returns and Drawdowns
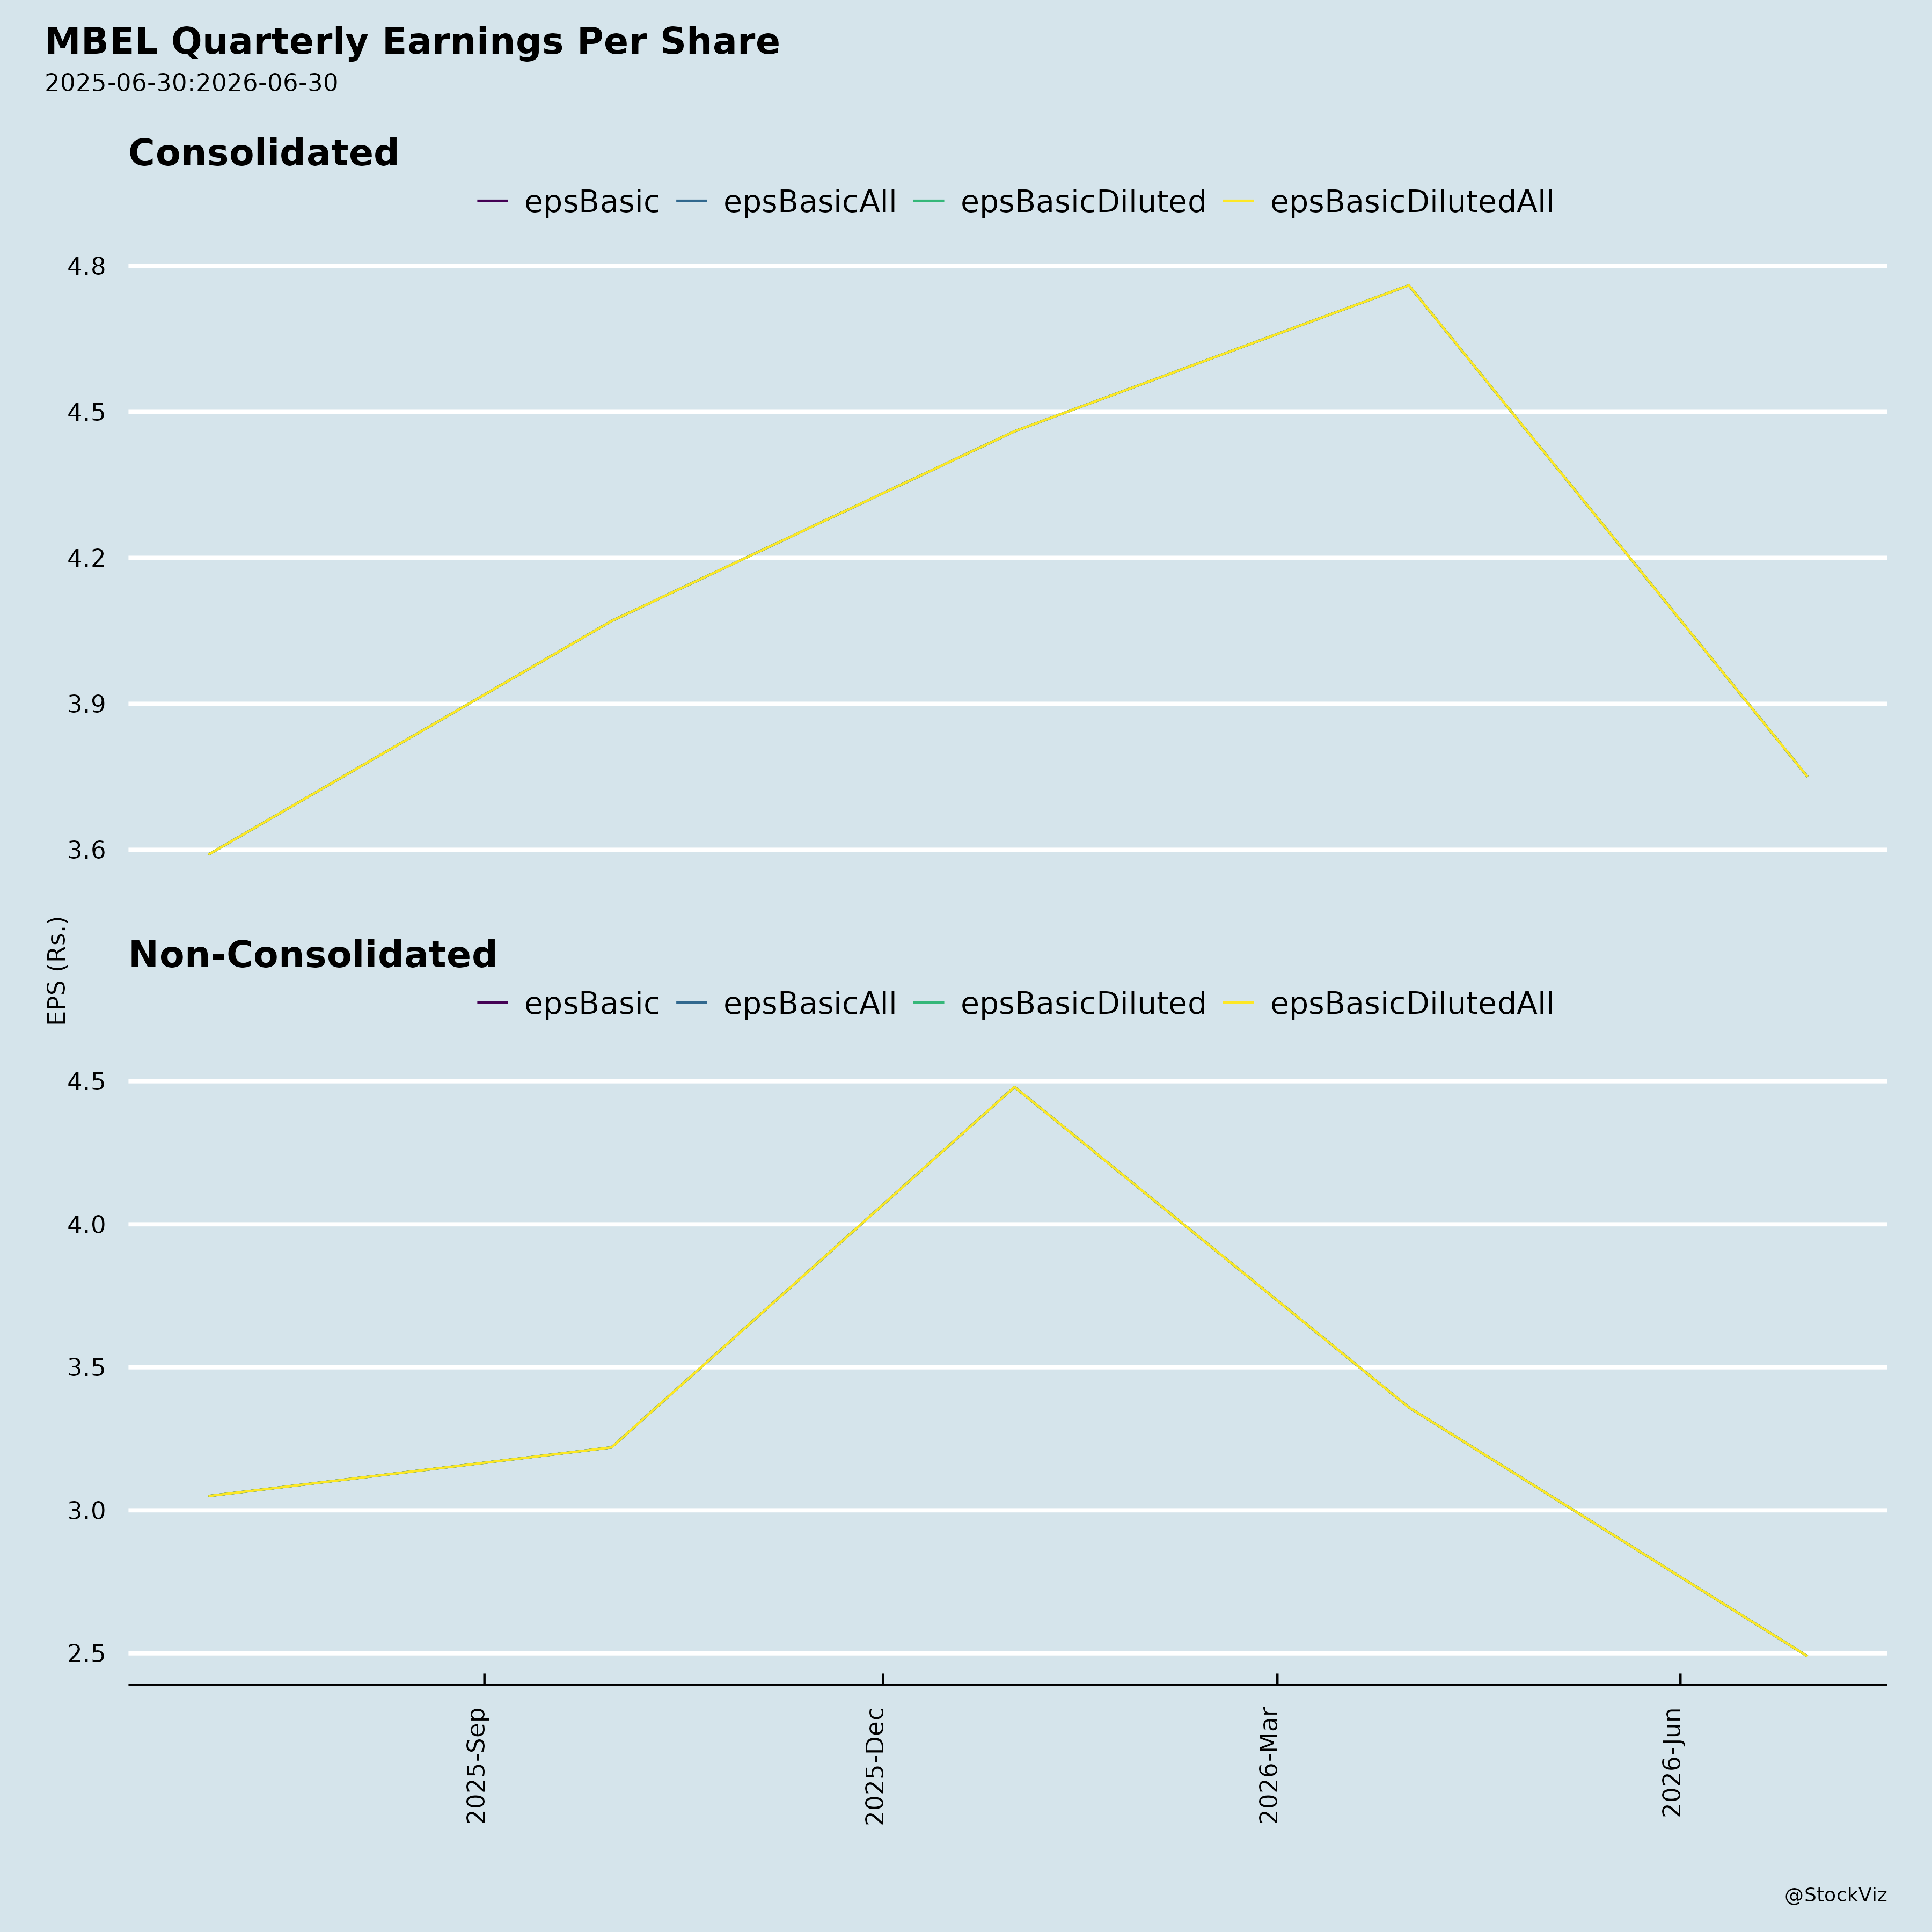
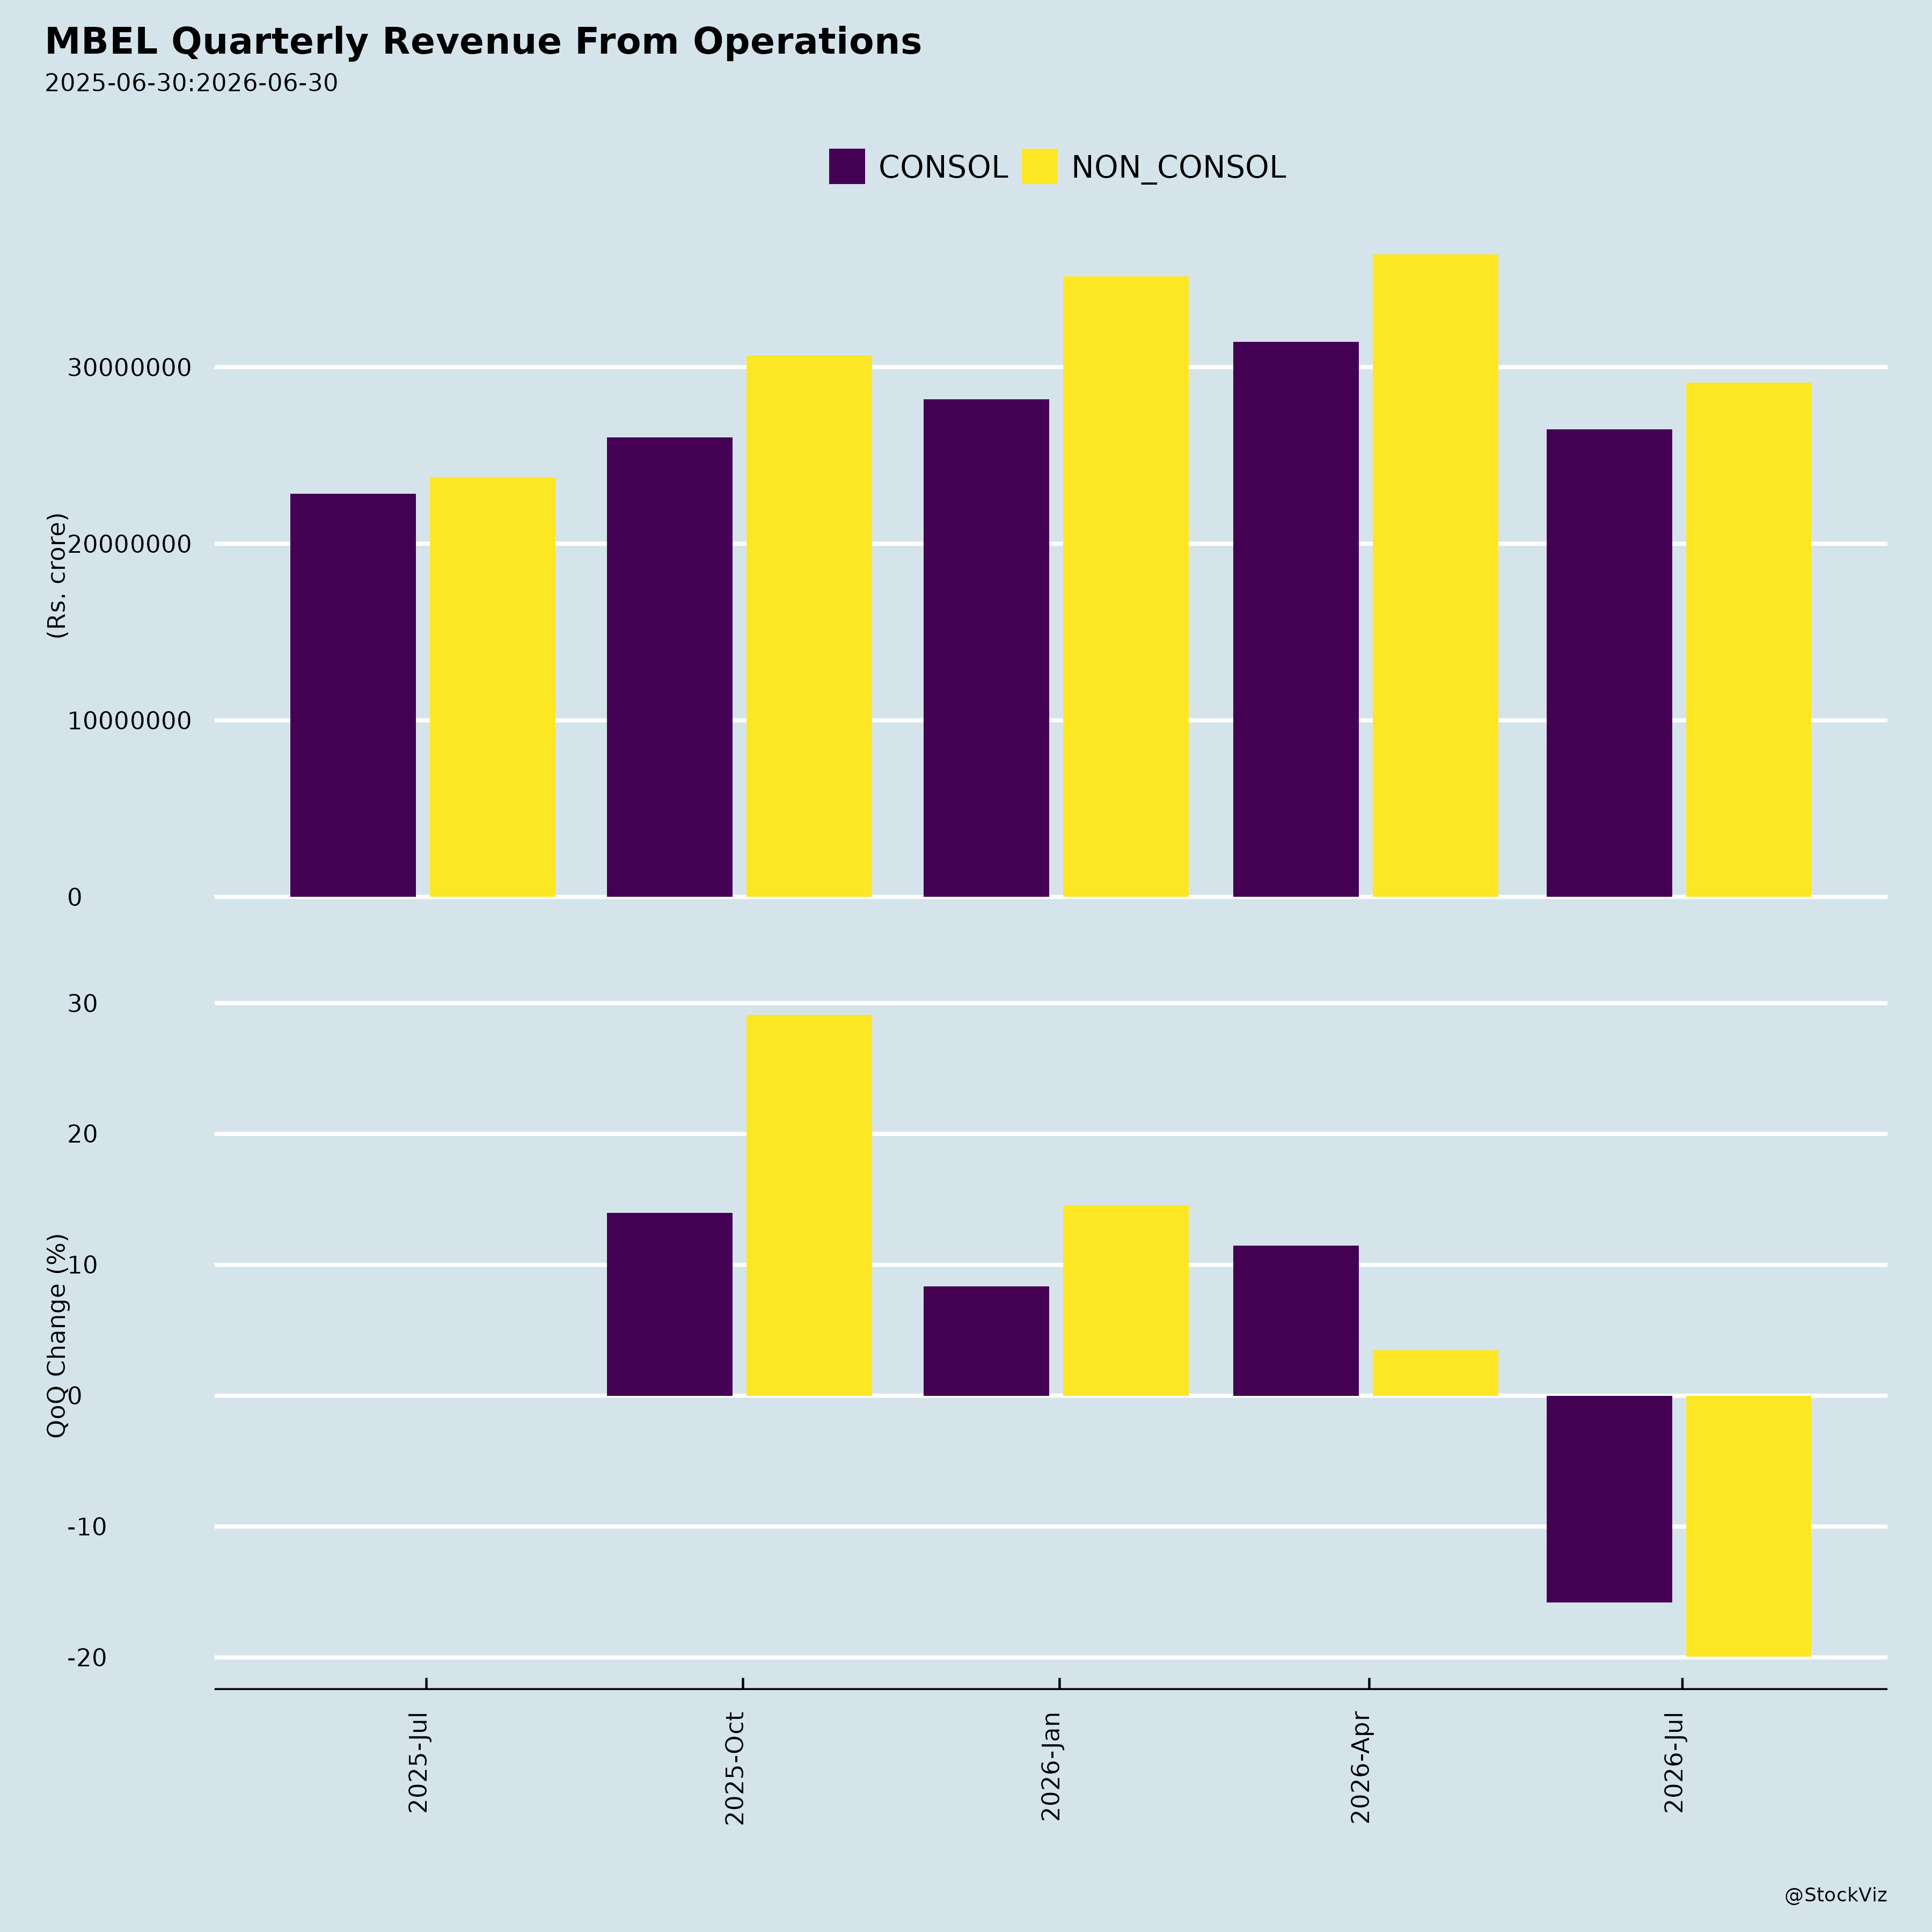
Fundamentals
Ownership
Margined
AI Summary
asof: 2026-09-18
M&B Engineering Limited — Recent Corporate Announcements
1. Headwinds and Challenges
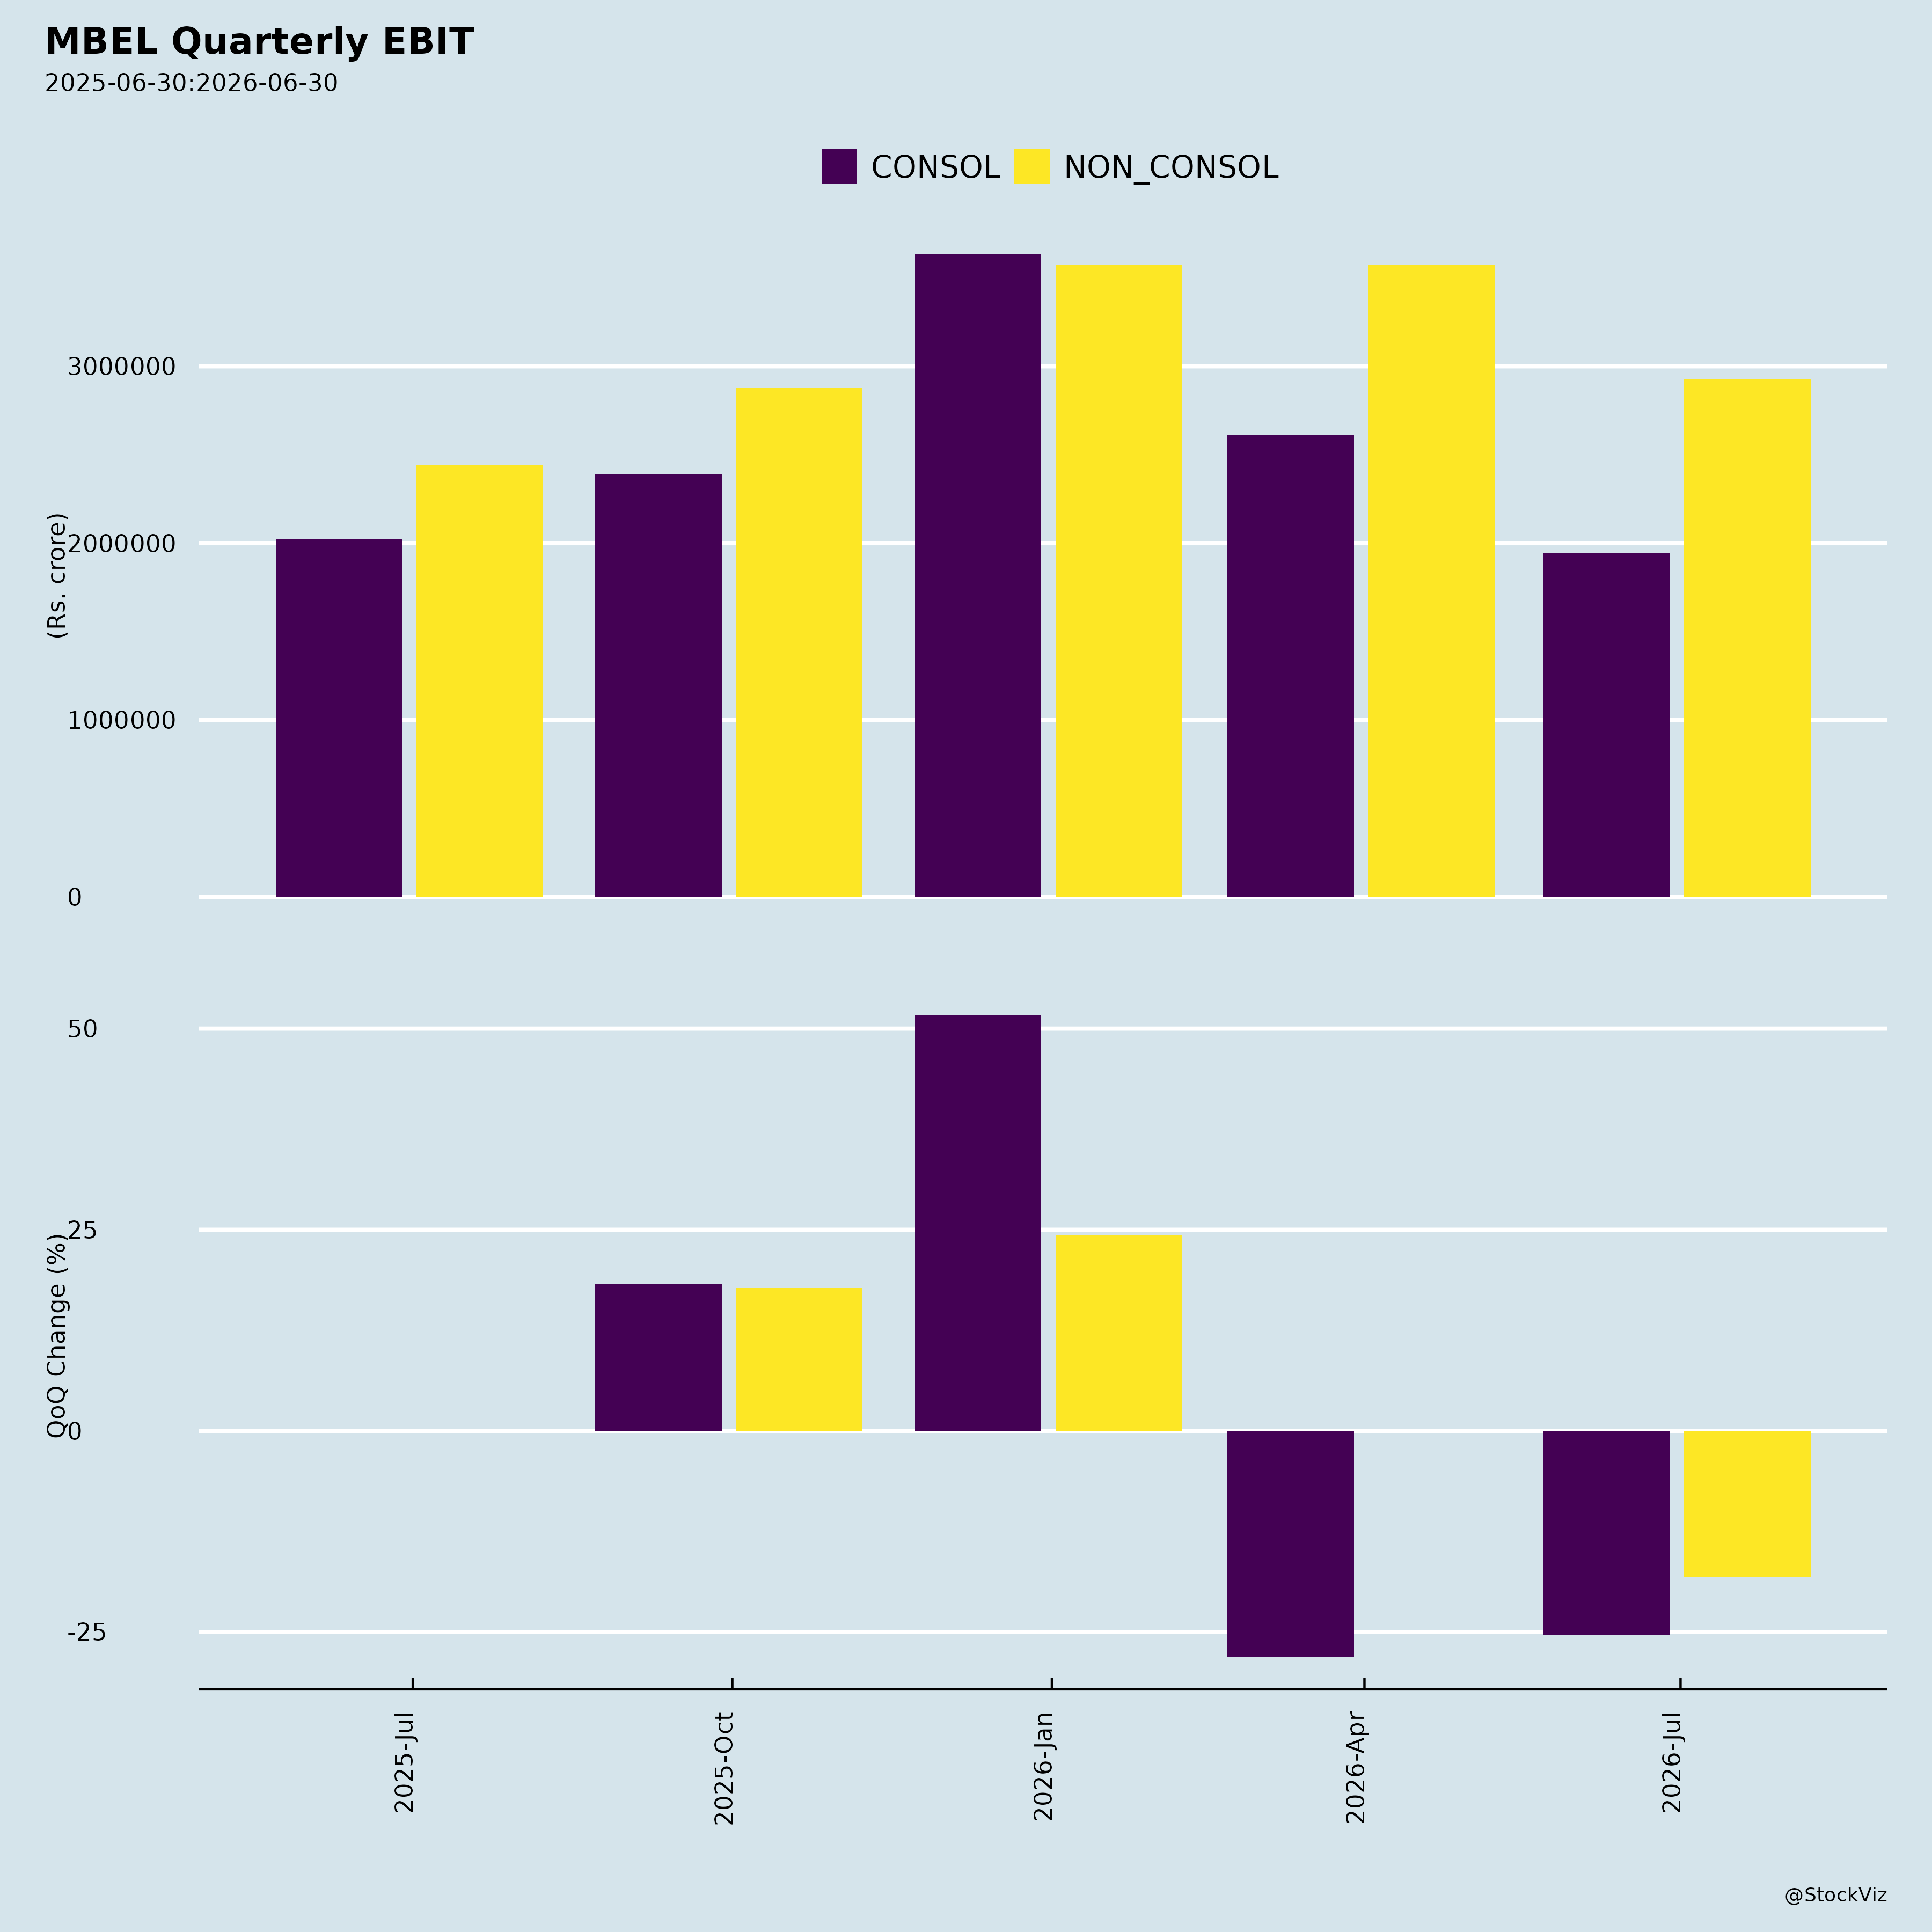
- EBITDA margin compression: In Q1FY27, EBITDA grew only 6.2% YoY (₹33.68 crore to ₹35.76 crore) despite revenue growth of 22.5%, and EBITDA margin fell to 12.28% from 14.17% in Q1FY26. Management commentary attributes the revenue growth to healthy execution across both divisions, but the margin decline is evident in the reported numbers.
- Operating EBITDA below reported EBITDA: The investor presentation notes reported EBITDA of ₹36 crore versus operating EBITDA of ₹33 crore, with operating EBITDA margin at 11.4% — lower than the reported 12.3%.
- Export revenue concentration and volatility: Q1FY27 export revenue was ₹28 crore (10% of total revenue), a sharp increase from ₹2.99 crore in Q1FY26. While this represents growth, the small base and lumpy nature of export orders (₹278 crore of the order book, with bulk to be shipped during the current fiscal) introduce execution and timing risk.
- Working capital intensity: Changes in working capital consumed ₹70.39 crore in FY25 and ₹17.10 crore in FY26. Trade receivables rose from ₹192.36 crore in FY25 to ₹239.14 crore in FY26, and inventories increased from ₹322.38 crore to ₹349.01 crore over the same period.
- Capital expenditure execution risk: The company is undertaking multiple simultaneous expansions — Sanand brownfield (commissioning October 2026), Cheyyar brownfield (completion planned Q3 FY28), and a ₹30 crore heavy structural steel line (operative by Q1FY28). Delays or cost overruns could affect guidance.
- IPO proceeds underutilized: As of June 30, 2026, only 56.57% of net IPO proceeds had been utilized. Capital expenditure deployment was just 17.49% (₹23.75 crore of ₹135.78 crore), leaving ₹112.03 crore pending.
- Foreign exchange exposure: The company reported net exchange fluctuations of ₹1.12 crore gain in Q1FY27, but FY26 saw a net exchange loss of ₹6.04 crore, indicating sensitivity to currency movements.
- Dependence on cyclical end-user industries: Revenue is concentrated in warehousing and logistics (25.2% of FY26 revenue), general engineering and manufacturing (14.2%), and infrastructure (11.3%) — sectors sensitive to economic cycles and industrial capex trends.
2. Tailwinds and Growth Prospects
- Strong order book: Orders on hand stood at ₹1,053 crore as on June 30, 2026, up 24.9% YoY. Phenix accounted for ₹837 crore (79.5%) and Proflex ₹216 crore (20.5%). Export orders within Phenix were ₹278 crore.
- Revenue growth momentum: Q1FY27 revenue from operations grew 22.5% YoY to ₹291.10 crore. Proflex contributed ₹77 crore (26% of total, up 25% YoY) and Phenix ₹214 crore (74%, up 22% YoY).
- Capacity expansion: Sanand PEB capacity is being expanded from 72,000 MTPA to 92,000 MTPA (commissioning October 2026). Cheyyar is adding 20,000 TPA PEB capacity (completion Q3 FY28). A ₹30 crore investment in a fully automated heavy structural steel processing line will expand capacity from 12,000 tonnes to 22,000 tonnes (operative Q1FY28). Post-completion, total PEB and structural steel capacity will reach 1,54,000 tonnes per annum.
- Proflex expansion: Two new mobile manufacturing units were commissioned, taking the total to 17 and increasing Proflex installed capacity to 21 lakh square meters per annum.
- Certifications enabling export growth: The Cheyyar facility received AISC certification, enabling service to west coast US customers via the Pacific route from next fiscal. The Sanand facility received EU Certification, enabling pursuit of UK and European markets. Sanand is described as India’s only PEB manufacturing unit with both AISC and Canadian Welding Bureau certifications.
- Export momentum: Export revenue reached ₹28 crore in Q1FY27, with export orders at ₹278 crore in the order book.
- Favourable industry outlook: The global PEB market is projected to reach USD 32–35 billion by 2029 (CAGR ~10%), while the Indian market is expected to reach INR 330–345 billion by 2030. The global self-supported roofing market is projected to reach USD 0.87–0.92 billion by 2029.
- Emerging opportunities: Management identifies renewables, cold storage, warehousing, railways, and agriculture as growth drivers. The heavy structural steel line targets data centers, high-rise buildings, and complex industrial structures.
- Repeat customer base: Repeat customers contributed 54.07% of FY26 consolidated operating revenue, with relationships exceeding 15 years with some customers.
- Dividend: A final dividend of ₹1.00 per equity share was approved at the 44th AGM held on September 17, 2026.
3. Key Risks
- Margin sustainability: The decline in EBITDA margin from 14.17% to 12.28% YoY in Q1FY27 raises questions about pricing power and cost management amid rapid growth.
- Execution risk on expansions: Multiple simultaneous capex projects (Sanand, Cheyyar, heavy structural steel line) carry risks of delay, cost escalation, or underutilization.
- Working capital and cash flow: Despite positive operating cash flow of ₹89.93 crore in FY26 (adjusted), the company has historically seen volatile working capital movements. The clarification regarding the FY26 operating cash flow adjustment (from negative ₹30.88 crore to positive ₹89.93 crore due to IPO fund reclassification) highlights the importance of understanding cash flow composition.
- Export market concentration: While exports are growing, they remain a small portion of revenue (10% in Q1FY27) and are subject to geopolitical, logistical, and currency risks.
- Dependence on key sectors: Concentration in warehousing, general engineering, and infrastructure exposes the company to cyclical downturns in these sectors.
- Regulatory and compliance risks: As a listed entity, the company is subject to SEBI regulations. The ESOP allotment of 12,503 shares at ₹196.50 per share (August 10, 2026) and the associated disclosures indicate ongoing compliance requirements.
- Competition: The PEB and self-supported roofing markets have organized players, and the company’s ability to maintain its leadership position depends on continued capacity expansion and certification advantages.
4. Management Guidance vs. Observed Business Performance
| Guidance / Forward-Looking Statement | Source and Date | Observed Performance / Evidence |
|---|---|---|
| Revenue growth of over 25% in FY27 | Management commentary, Q1FY27 press release and investor presentation, August 10, 2026 | Q1FY27 revenue grew 22.5% YoY. FY26 revenue grew 27.4% YoY (₹988.55 crore to ₹1,259.72 crore). |
| Sanand brownfield capex commissioning in October 2026, taking PEB capacity from 72,000 MTPA to 92,000 MTPA | Investor presentation, August 10, 2026 | Not yet commissioned as of the presentation date. |
| Cheyyar brownfield expansion of 20,000 TPA PEB capacity, completion planned Q3 FY28 | Investor presentation, August 10, 2026 | Implementation to commence during current fiscal; not yet complete. |
| ₹30 crore investment in heavy structural steel processing line, operative by Q1FY28 | Investor presentation, August 10, 2026 | Board approval obtained; not yet operative. |
| Export orders of ₹278 crore, bulk to be shipped during current fiscal | Investor presentation, August 10, 2026 | Q1FY27 export revenue was ₹28 crore. |
| AISC certification for Cheyyar to enable west coast US customers from next fiscal | Investor presentation, August 10, 2026 | Certification received; revenue impact not yet observed. |
| EU Certification for Sanand facility to enable UK and European market opportunities | AGM document, September 17, 2026 | Certification received; revenue impact not yet observed. |
| All eight resolutions at 44th AGM passed with 100.00% approval, including final dividend of ₹1.00 per equity share | AGM document, September 17, 2026 | Resolutions duly passed. |
| Commitment to maintaining highest standards of quality, regulatory compliance, and manufacturing excellence | AGM document, September 17, 2026 | Ongoing operational focus. |
Key observations on guidance vs. performance:
- Management’s FY27 revenue growth guidance of over 25% is supported by Q1FY27 growth of 22.5% and a strong order book of ₹1,053 crore (up 24.9% YoY). However, achieving over 25% for the full year would require acceleration from the Q1 pace.
- The margin trajectory is a divergence from guidance: while management expresses confidence in growth, the EBITDA margin decline in Q1FY27 (12.3% vs. 14.2% YoY) contrasts with the prior year’s full-year margin of 12.5% (FY26) and 13.6% (FY25).
- Capacity expansion guidance is specific and time-bound, with Sanand commissioning targeted for October 2026 and the heavy structural steel line for Q1FY28. These are near-term milestones that can be tracked against actual progress.
- Export growth guidance is supported by certifications (AISC for Cheyyar, EU for Sanand) and a growing export order book, but actual export revenue realization remains to be seen.
- The company’s track record shows FY26 revenue growth of 27.4% and PAT growth of 20.2%, which provides context for evaluating FY27 guidance.
Copyright © 2023 SAS Data Analytics Pvt. Ltd. All rights reserved.