MANKIND
Equity Metrics
September 24, 2026
Mankind Pharma Limited
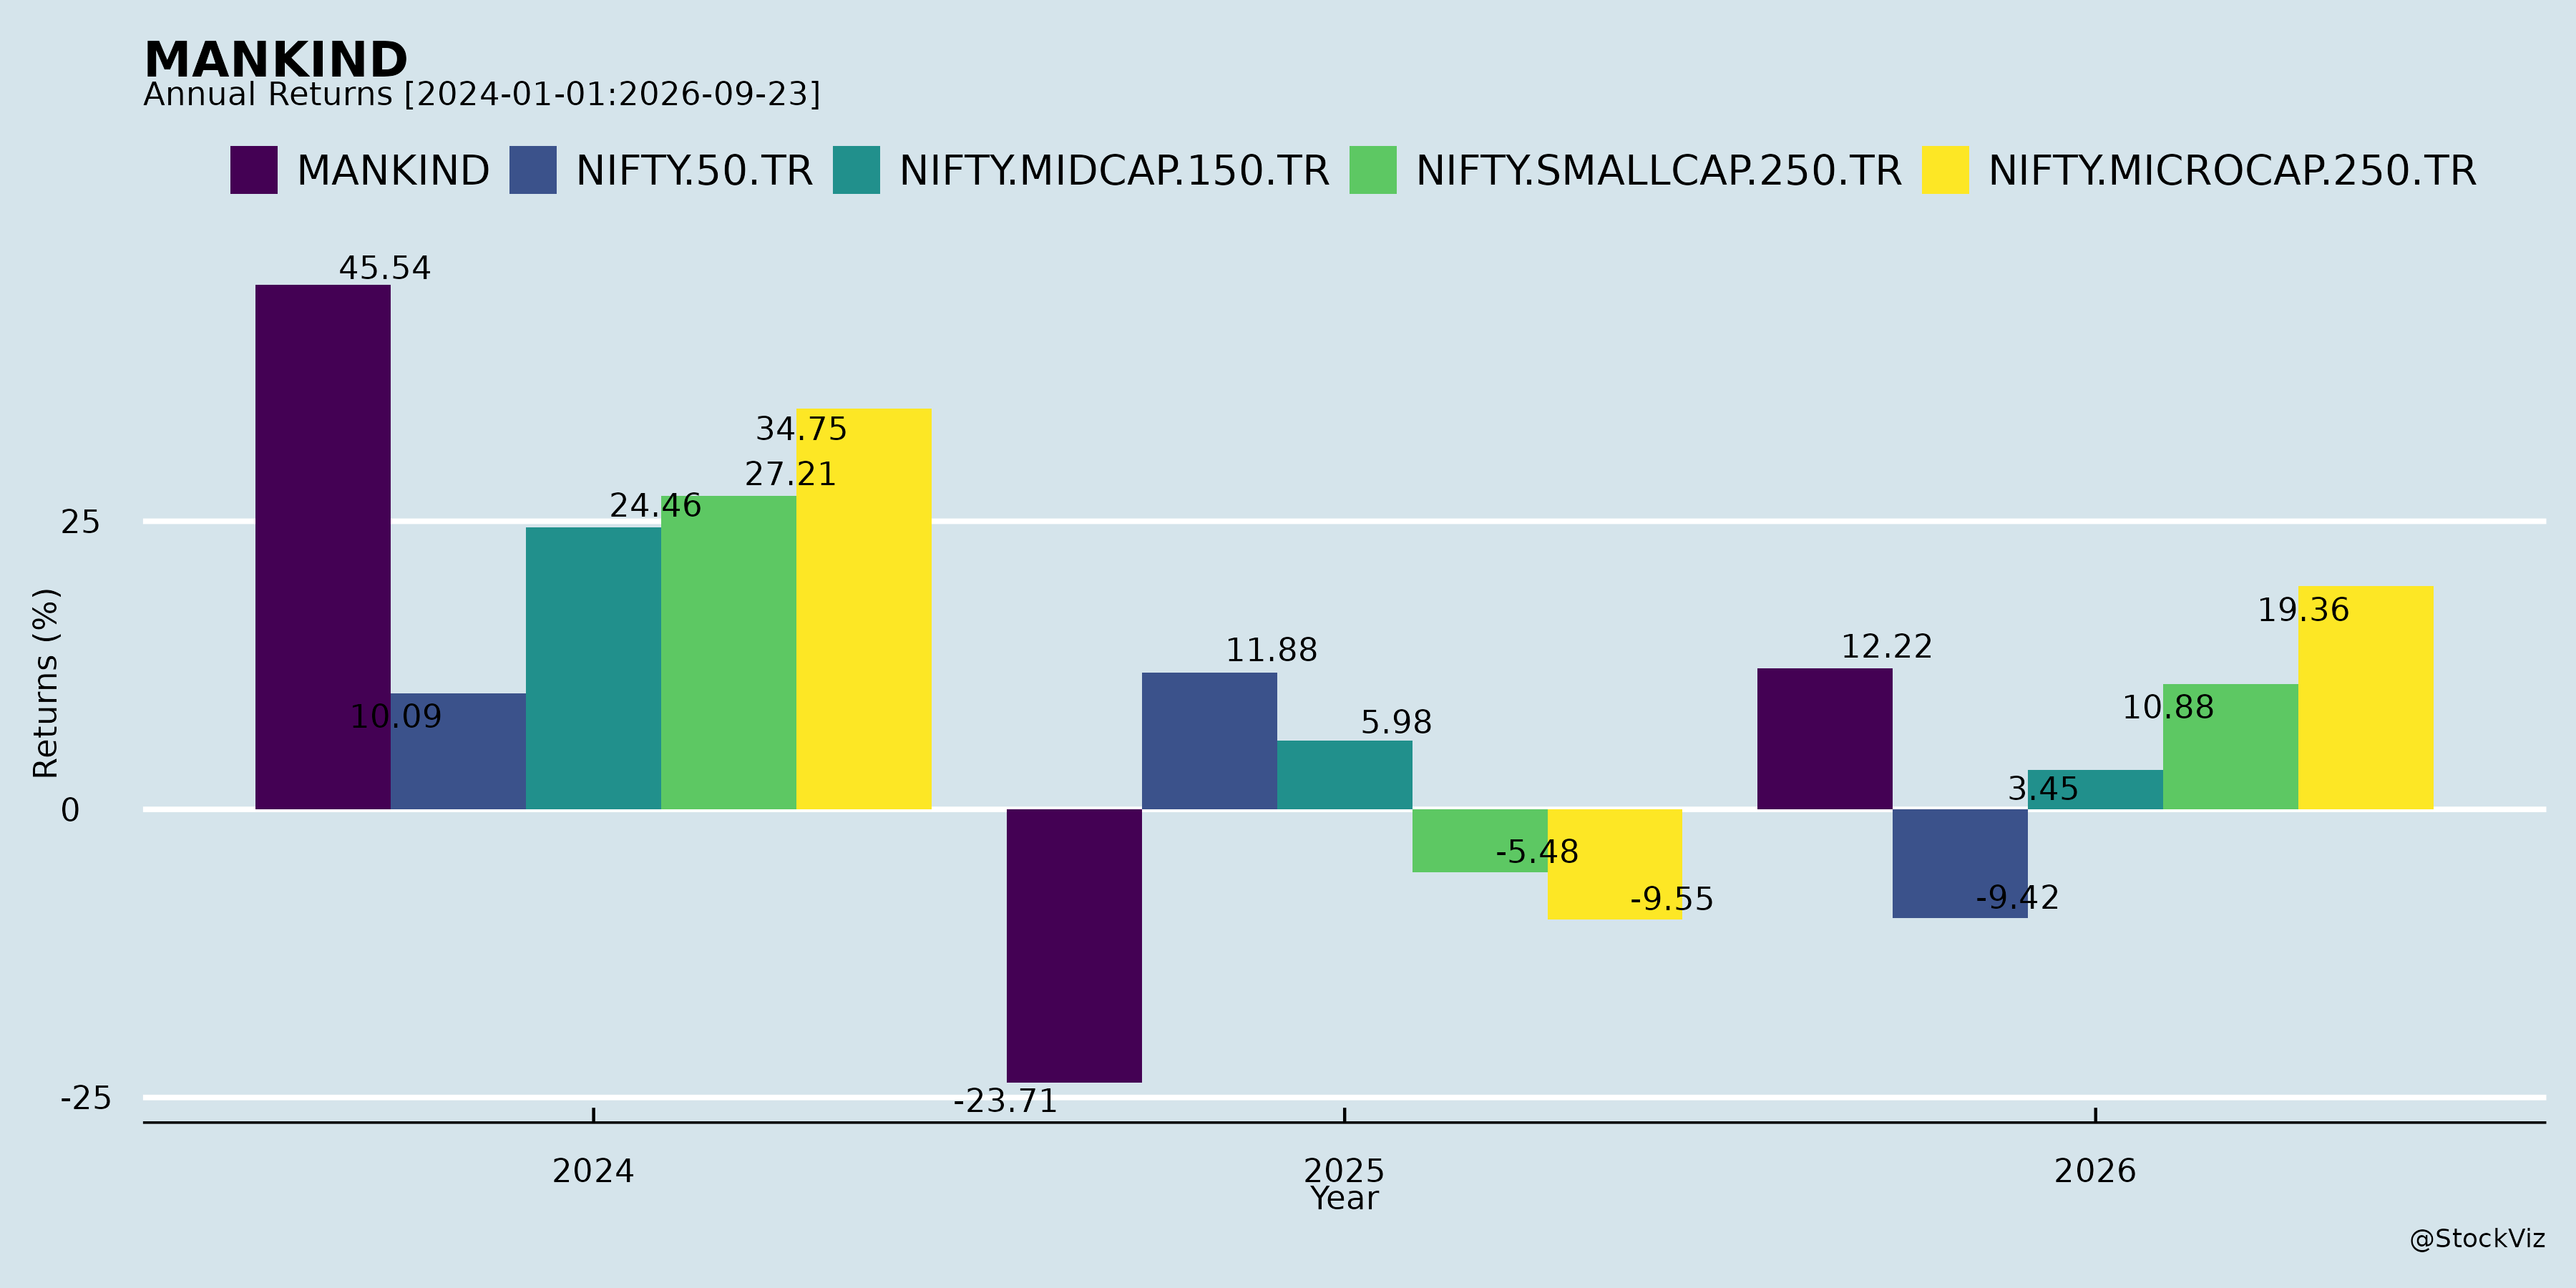
Annual Returns

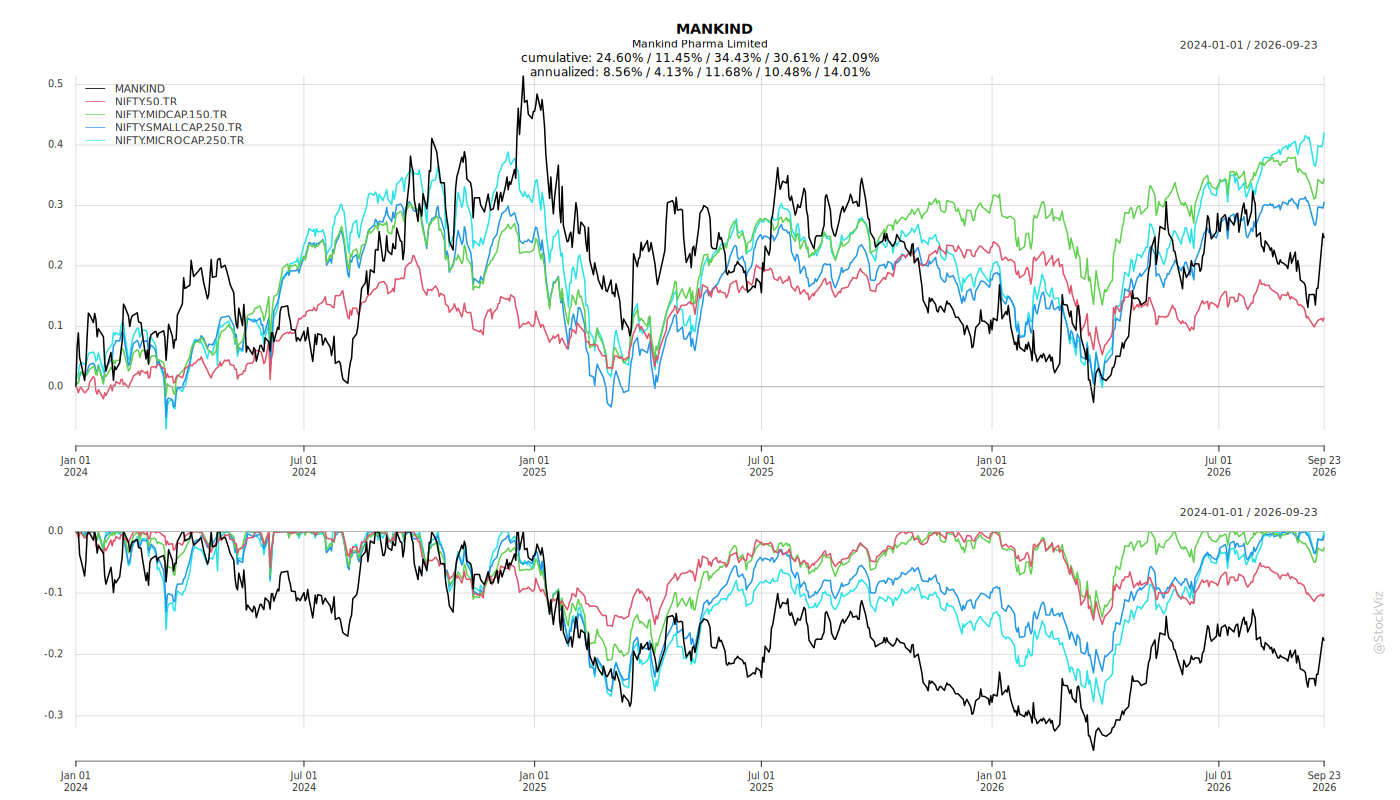
Cumulative Returns and Drawdowns
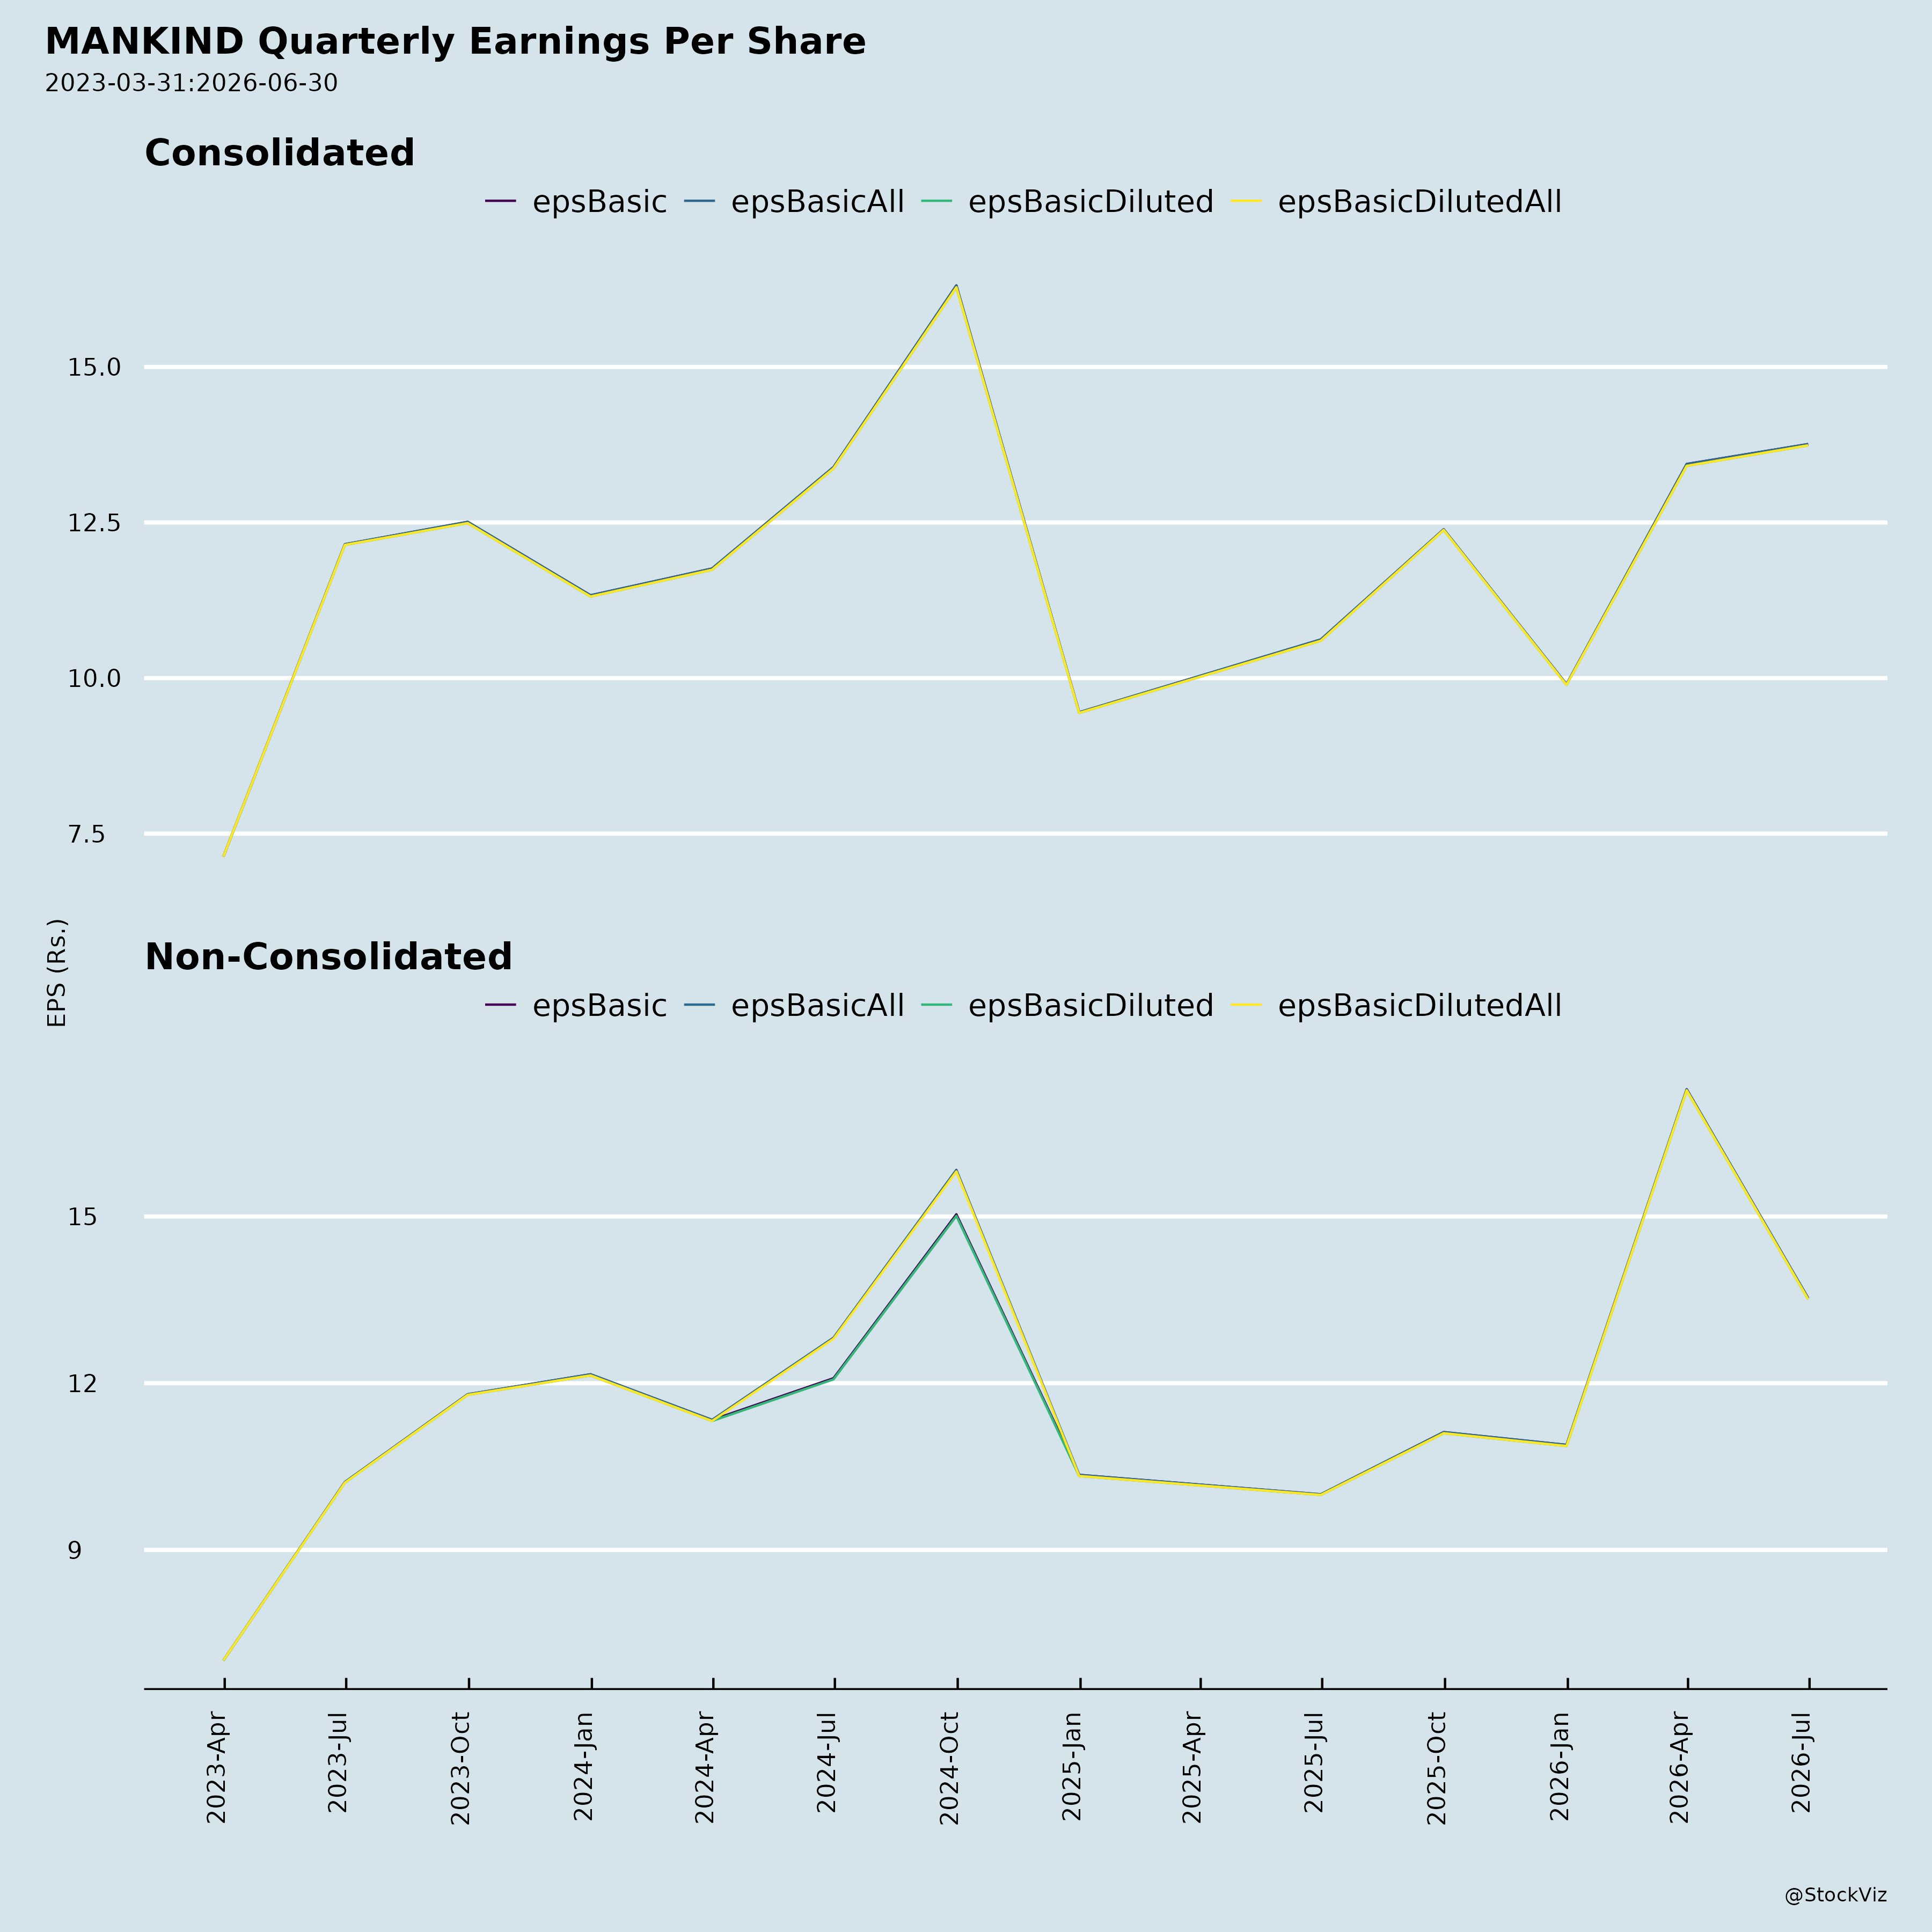
Fundamentals
Ownership
Margined
AI Summary
asof: 2026-09-16
Mankind Pharma — Recent Corporate Announcements: Summary
1. Headwinds and Challenges
- Consumer Healthcare growth was soft. In Q1 FY27, the Consumer Healthcare segment grew ~4% YoY (revenue of INR 246 Cr versus INR 237 Cr in Q1 FY26). The company attributes this partly to the base effect of a discontinued cash-and-carry business. Despite the softer growth, it gained market share in key brands — Manforce, Preganews and Gas-o-fast.
- Acute therapy recovery was uneven. Secondary sales growth of 12.7% in Q1 FY27 was slightly below IPM growth of 13.0%. Anti-infectives had declined 1.1% in Q4 FY26 before recovering to 3.6% growth in Q1 FY27.
- Historical underperformance in some therapies. FY21–26 CAGRs show Mankind trailing IPM in Gastro Int (8.7% vs 10.5%), VMN (7.8% vs 9.1%) and Respiratory (13.9% vs 12.7% — marginally ahead), indicating mixed long-term positioning in parts of the acute portfolio.
- Leverage remains on the balance sheet. Net debt stood at INR 3,377 Cr with Net Debt/Adj. EBITDA of 0.9x as of Q1 FY27, reflecting the funding impact of prior acquisitions (including BSV).
- Governance transition underway. The appointment of Mr. Anish Vanraj Bafna as a Non-Executive Independent Director requires member approval via special resolution through postal ballot (notice dated August 10, 2026; e-voting from August 19 to September 17, 2026; results on or before September 21, 2026). No Board meeting had been held after his appointment as of the notice date.
2. Tailwinds and Growth Prospects
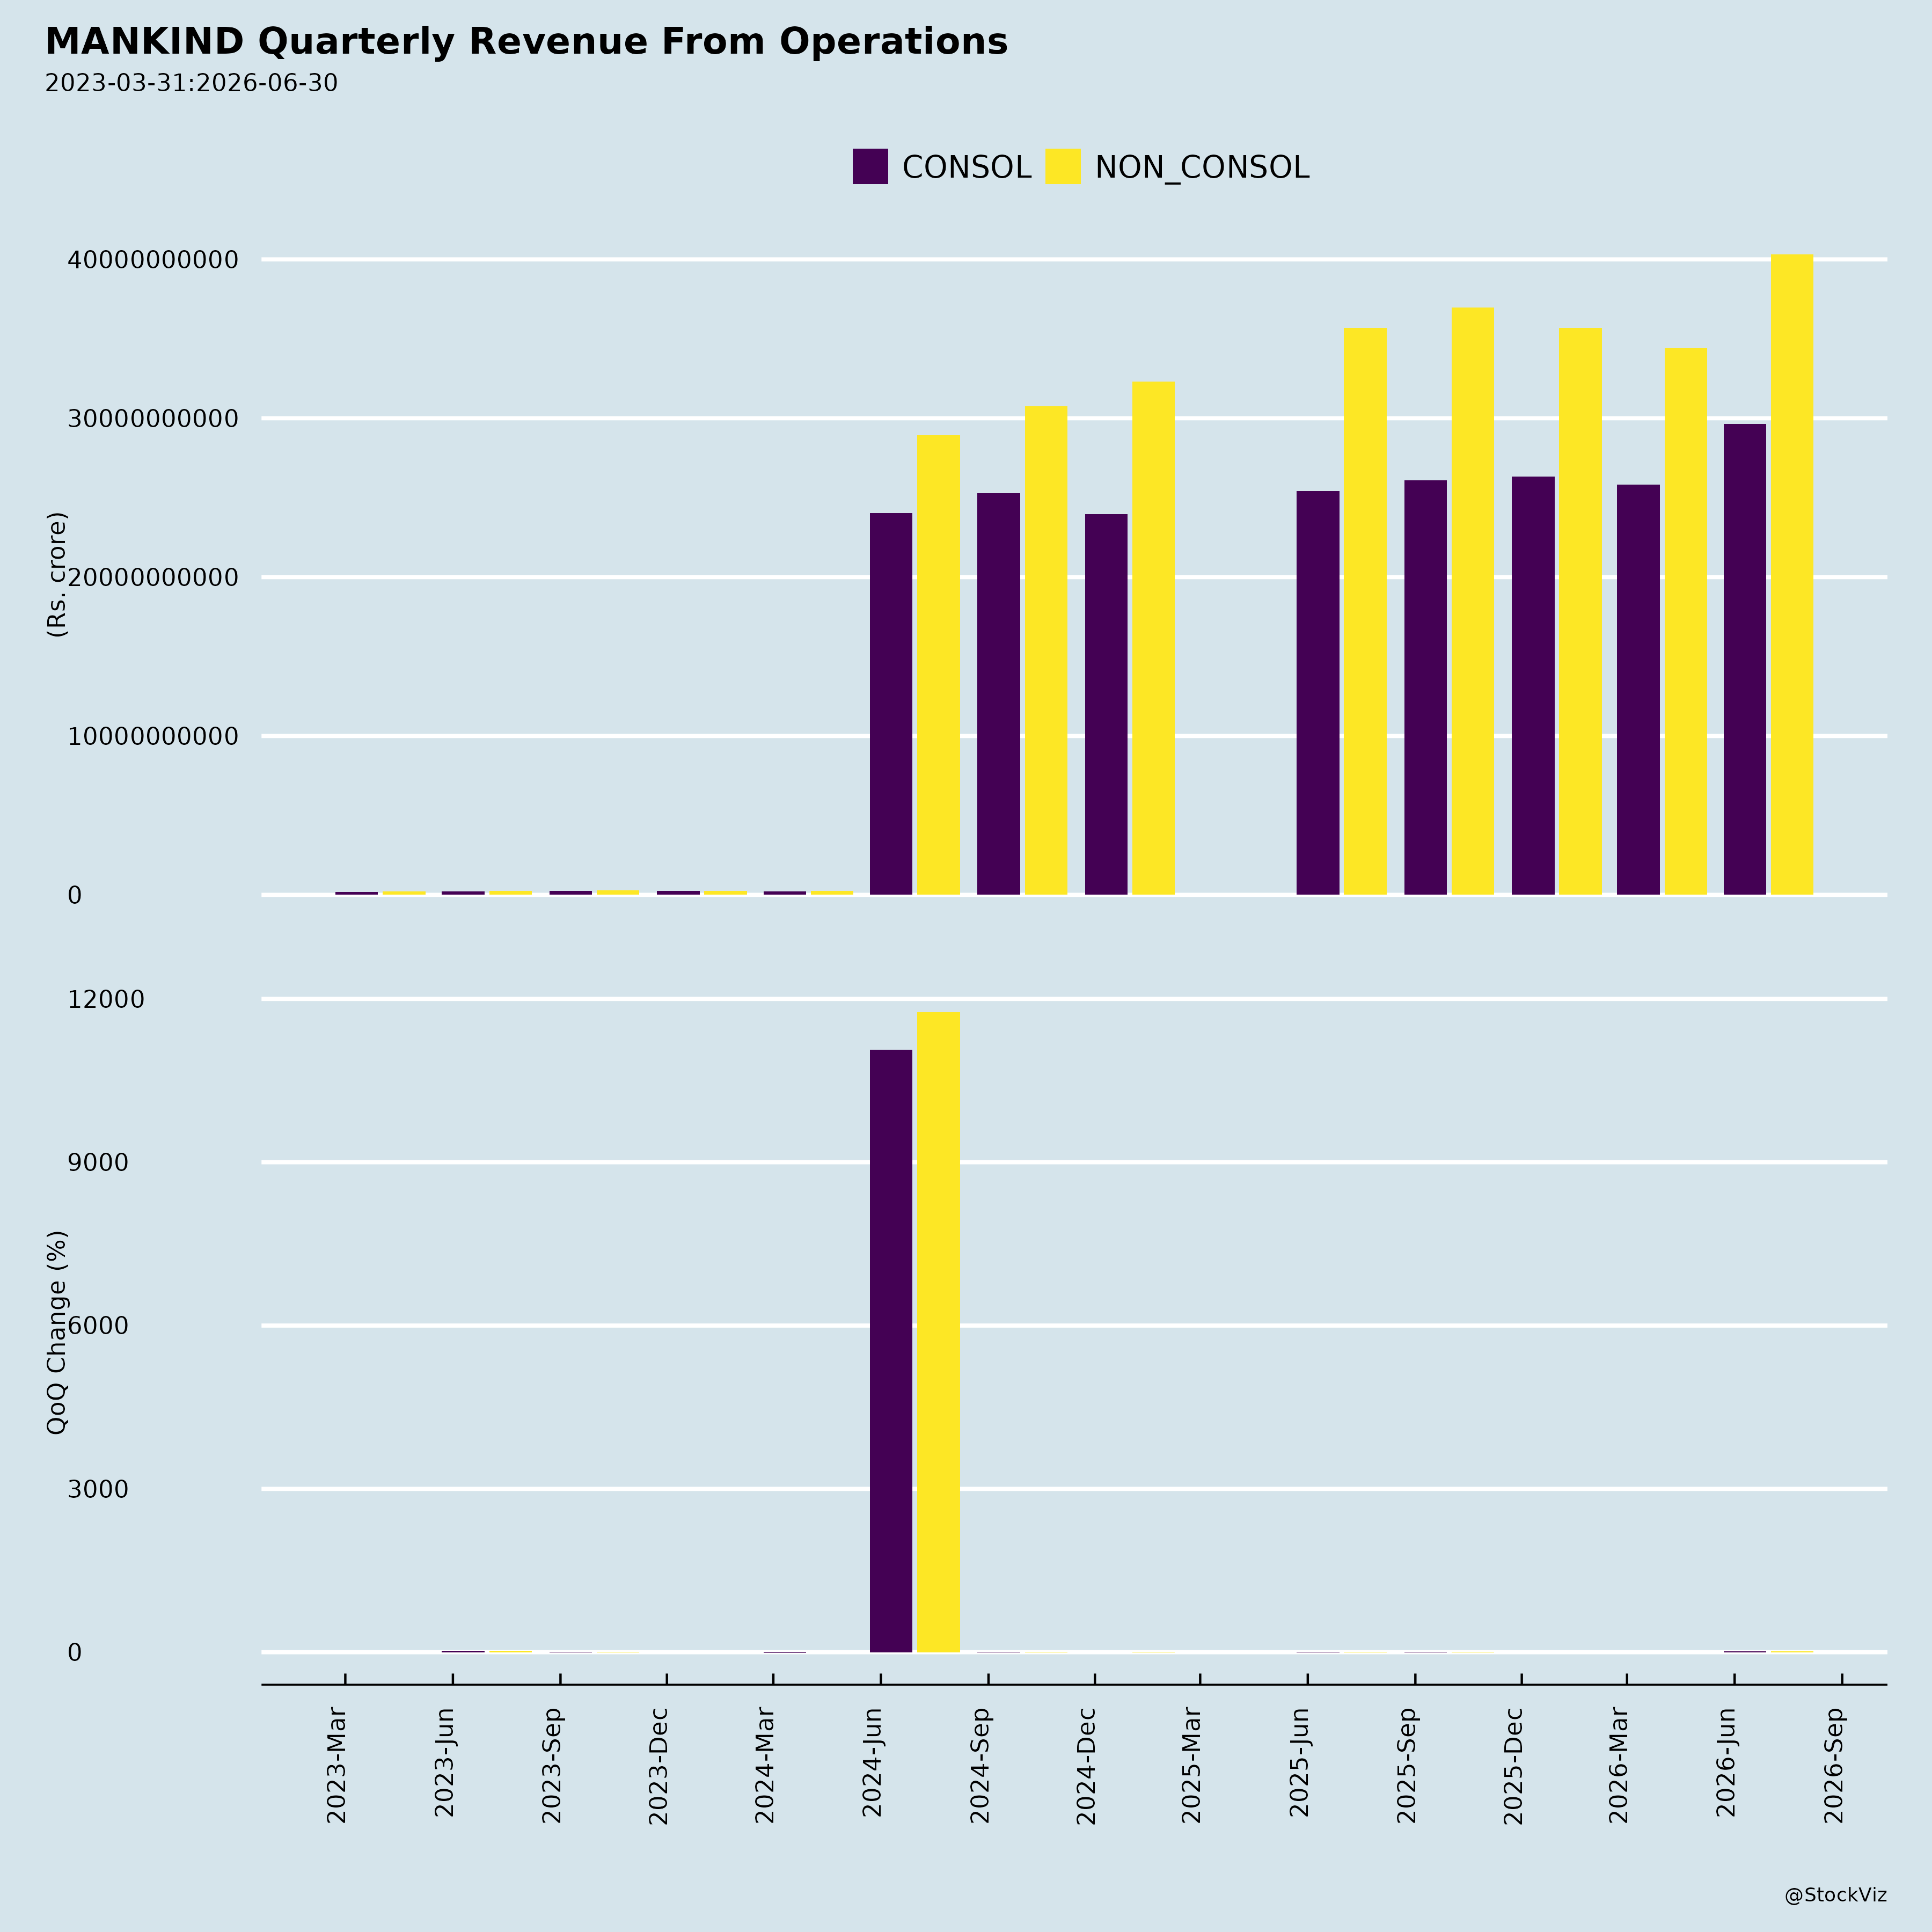
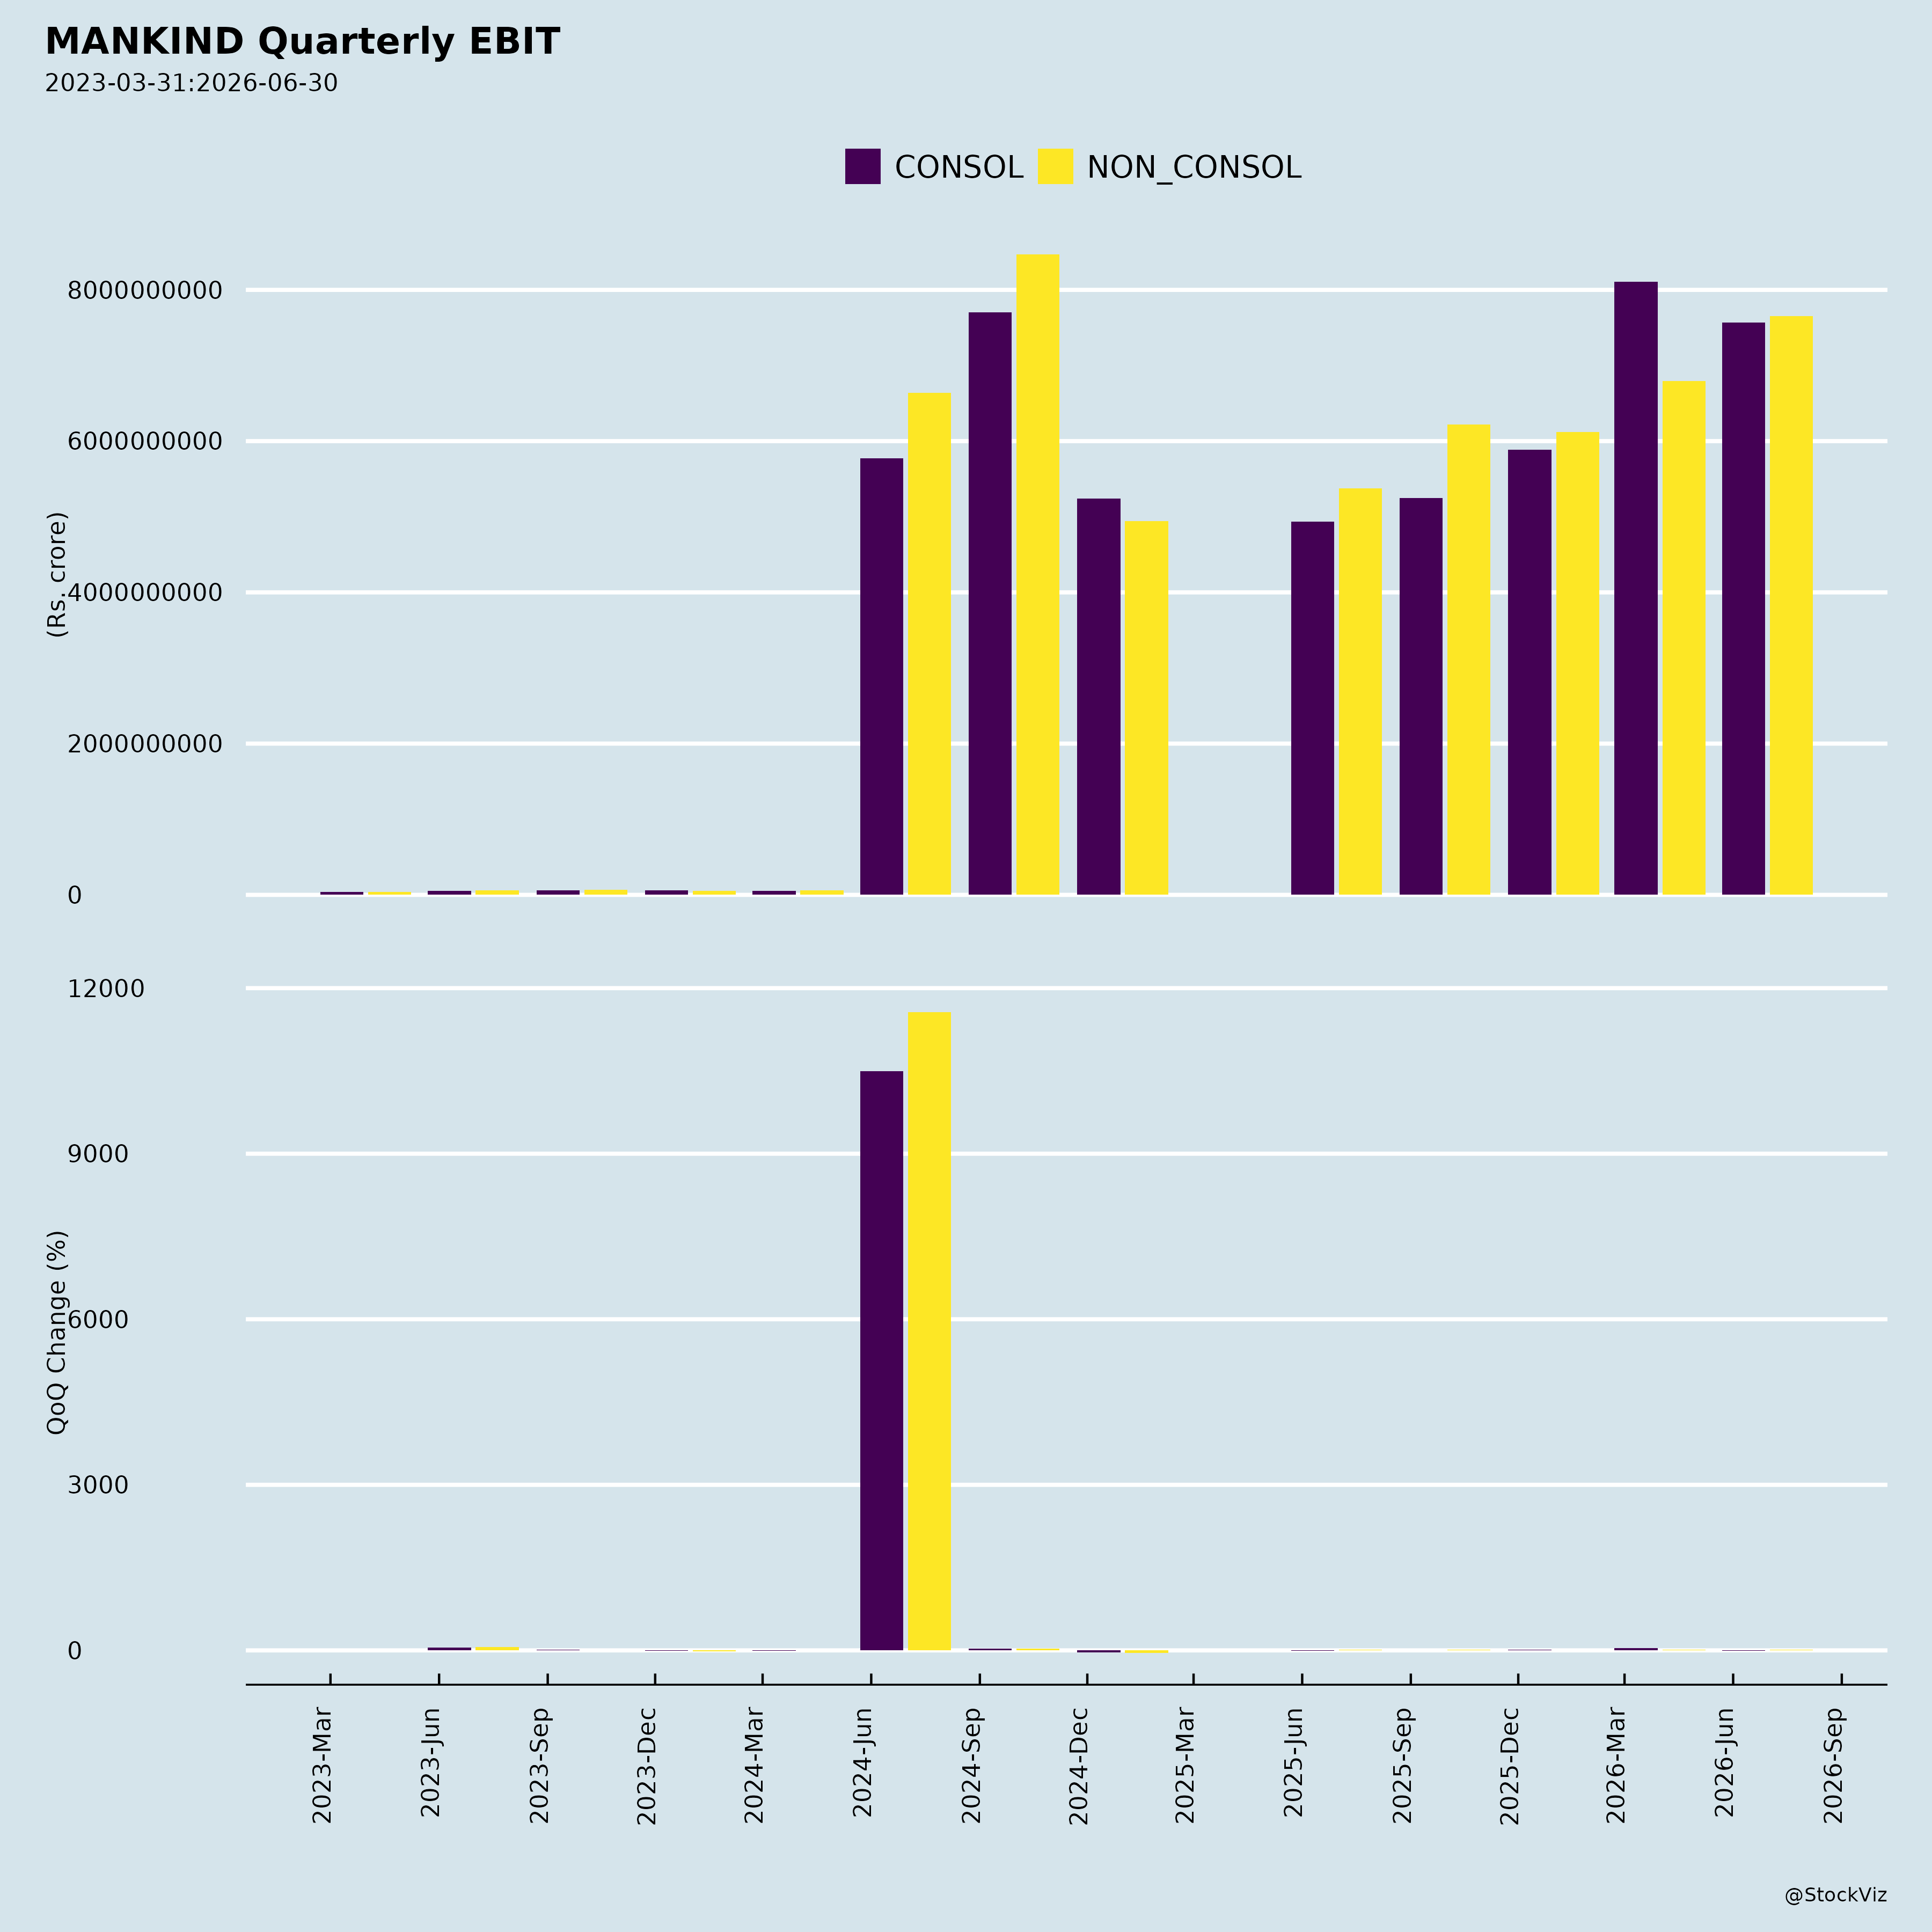
- Strong overall Q1 FY27 performance. Revenue grew 12.9% YoY to INR 4,031 Cr; EBITDA rose 24.7% to INR 1,060 Cr with margins expanding 250 bps to 26.3%; PAT grew 29.1% to INR 574 Cr.
- Domestic business (ex-CH) grew 11.0% YoY, led by 15.8% growth in the Mankind domestic business, with Chronic up 19.4% in cardiac and 12.7% in anti-diabetes. BSV’s domestic specialty business also delivered strong double-digit growth.
- Chronic portfolio momentum. Chronic share increased 80 bps in Q1 FY27. Inhalers (Combihale & Symbicort) grew 23% YoY; Nobeglar (Insulin Glargine) grew 45% YoY. Key brands: Telmikind family +21%, Lipirose/Statpure +30%/31%, Glizid family +29%. BSV brands Foligraf (+39%), Humog (+39%) and Anti-D (+23%) performed well.
- Exports scaled strongly, growing 29% YoY to INR 605 Cr. Mankind (excluding BSV) launched one new product in Q1 FY27, taking total US launches to 49.
- Diabetes portfolio expansion via in-licensing. On August 20, 2026, Mankind entered an exclusive in-licensing and marketing agreement with Chongqing Chenan Biopharmaceutical Co., Ltd., China, for Insulin Degludec and Insulin Degludec + Aspart Combination in India. This builds on prior partnerships for Insulin Aspart and Insulin Degludec and strengthens the injectable diabetes portfolio.
- Market leadership maintained. #1 rank by volume in IPM for nine consecutive years with 15.2% prescription share; #4/#2 rank by value/volume in IPM (FY26); #1 in Gynaecology. Consumer Healthcare holds #1 positions in condoms (28% MS), pregnancy test kits (84% MS) and emergency contraceptives (68% MS).
- Distribution and R&D scale. Field force of 18,500+ professionals (Mar’26), reach across 5 lakh+ doctors, 32 manufacturing facilities and 7 R&D facilities with 740+ scientists.
- Active investor engagement. Management participated in Emkay Confluence and Equirus Annual India Conference (both August 13, 2026) and the Motilal Oswal 22nd Annual Global Investor Conference (August 17, 2026).
3. Key Risks
- Forward-looking statement risk factors disclosed by the company include: cash flow projections; industry and market conditions; ability to manage growth; competition; government policies and regulations; obtaining regulatory approvals; domestic and international economic conditions (interest rates, currency fluctuations); political, economic, legal and social conditions; technological advances; claims and concerns about product safety and efficacy; healthcare reforms; inability to build production capacity; unavailability of raw materials; and failure to gain market acceptance.
- In-licensing dependence. The insulin portfolio expansion relies on partnerships with third parties (including Chinese biopharma partners), which introduces execution and supply dependencies.
- Consumer Healthcare sensitivity. The segment’s growth is exposed to base effects and channel changes (e.g., discontinued cash-and-carry business).
- Competitive intensity in chronic therapies, where Mankind is scaling but faces established competitors; its chronic market share (4.3% in FY26) remains modest relative to its overall IPM position.
4. Management Guidance vs. Observed Performance
- Management commentary (Q1 FY27): Mr. Rajeev Juneja, Vice Chairman & Managing Director, stated that disciplined execution and strengthening business fundamentals resulted in improvements across key operating and financial metrics, “laying the foundation to deliver long-term sustainable growth.”
- Observed performance versus that commentary: Q1 FY27 results are consistent with the stated improvement — revenue +12.9% YoY, EBITDA margin +250 bps to 26.3%, PAT +29.1% YoY, and ROCE/Adj. ROCE of 13%/43%. Domestic (ex-CH) growth of 11.0% and exports growth of 29% support the narrative of broad-based momentum.
- Where performance lagged commentary: Consumer Healthcare growth of ~4% was below the double-digit trajectory implied by the segment’s historical positioning, though management attributed this to the discontinued cash-and-carry base effect and noted market share gains.
- Strategic guidance on diabetes: Management stated it remains focused on expanding its in-licensing pipeline from China, building on Insulin Aspart and Insulin Degludec partnerships. The August 20, 2026 Chongqing Chenan agreement is a concrete step consistent with that stated intent.
- Governance guidance: The Board recommended Mr. Bafna’s appointment citing his 30+ years of healthcare and medical devices leadership, including roles as CEO & MD of Healthium Medtech and President – Japan at Baxter International. Member approval is pending through the postal ballot process concluding September 17, 2026.
Broker Narrative
The narrative shifted from an Accumulate call centered on domestic leadership and near-term margin/cost concerns to a Buy call focused on prescription-led double-digit growth, chronic therapy strength, and margin expansion. Early emphasis on a pure domestic play and consumer healthcare/OTC strength was retained but tempered, as the last report flags muted consumer health growth and cuts FY27 estimates. Persistent themes included chronic/acuten prescription growth, margin recovery, and market leadership; the newer driver added was exports/BSV growth.
Optimism that failed
- The consumer healthcare/OTC franchise, highlighted as a strategic growth driver with marquee brands, saw muted growth and market softness, forcing a 4% cut to FY27 earnings estimates.
- The expectation of strong cash generation was partly undermined by a lower CFO-to-EBITDA ratio of 77% due to higher working capital and an elevated effective tax rate.
Broker Timeline
32 broker calls · 2023-06-02 to 2026-07-31
Copyright © 2023 SAS Data Analytics Pvt. Ltd. All rights reserved.