MANINDS
Equity Metrics
September 24, 2026
Man Industries (India) Limited
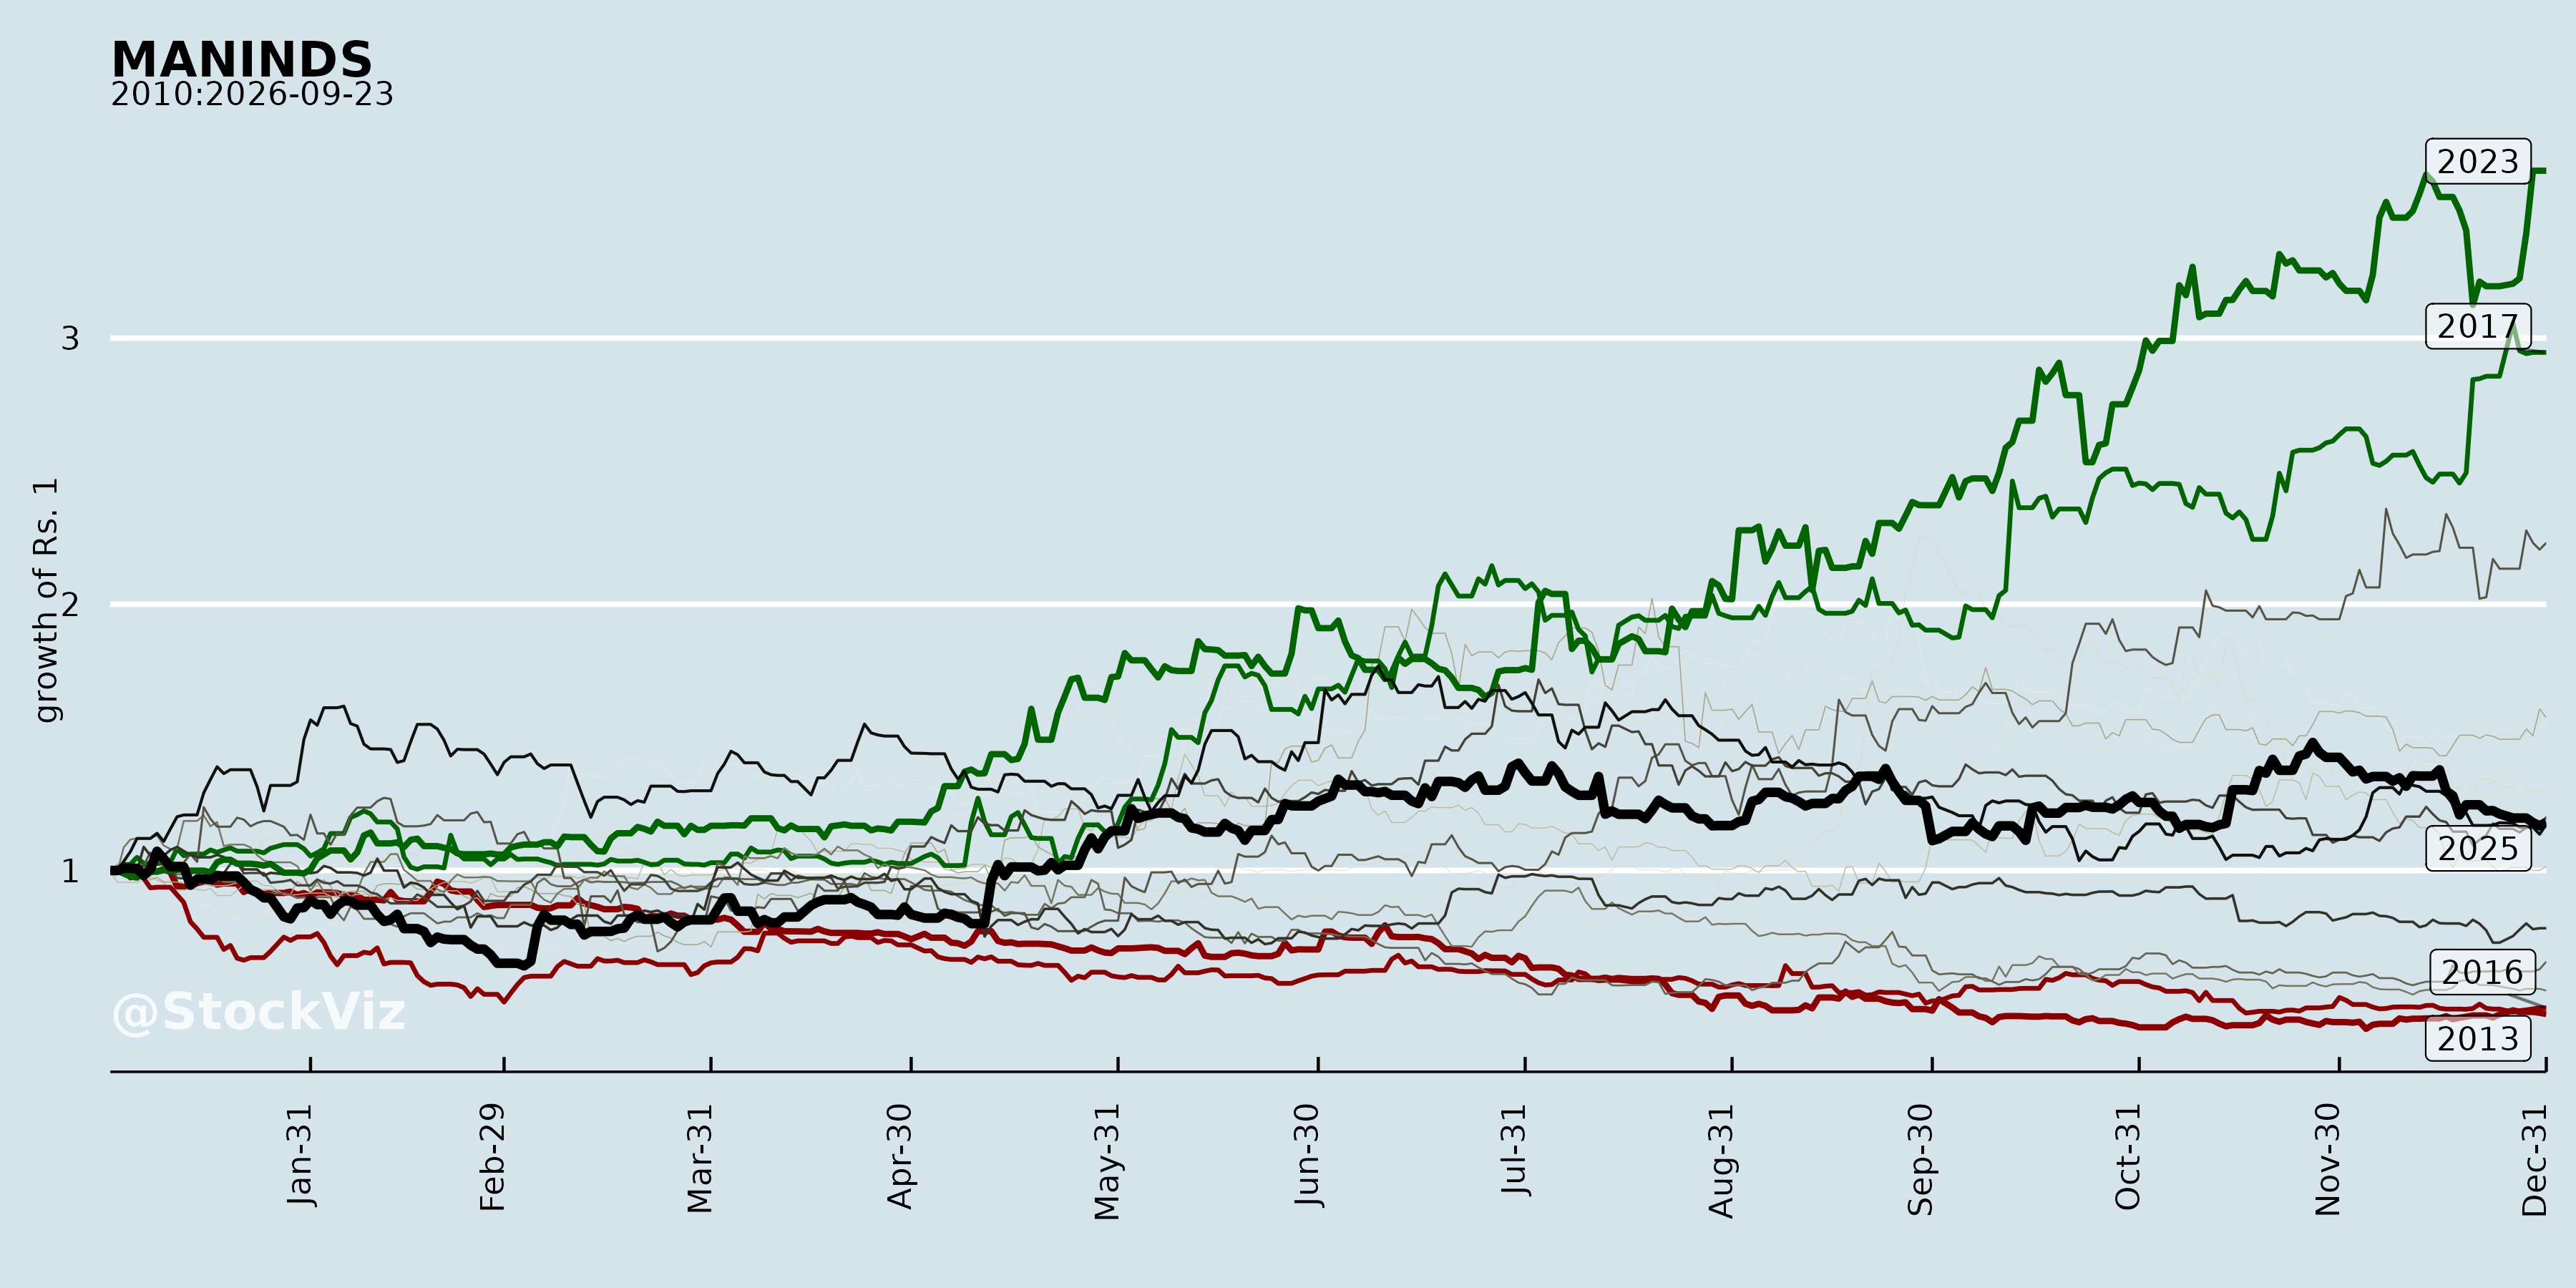
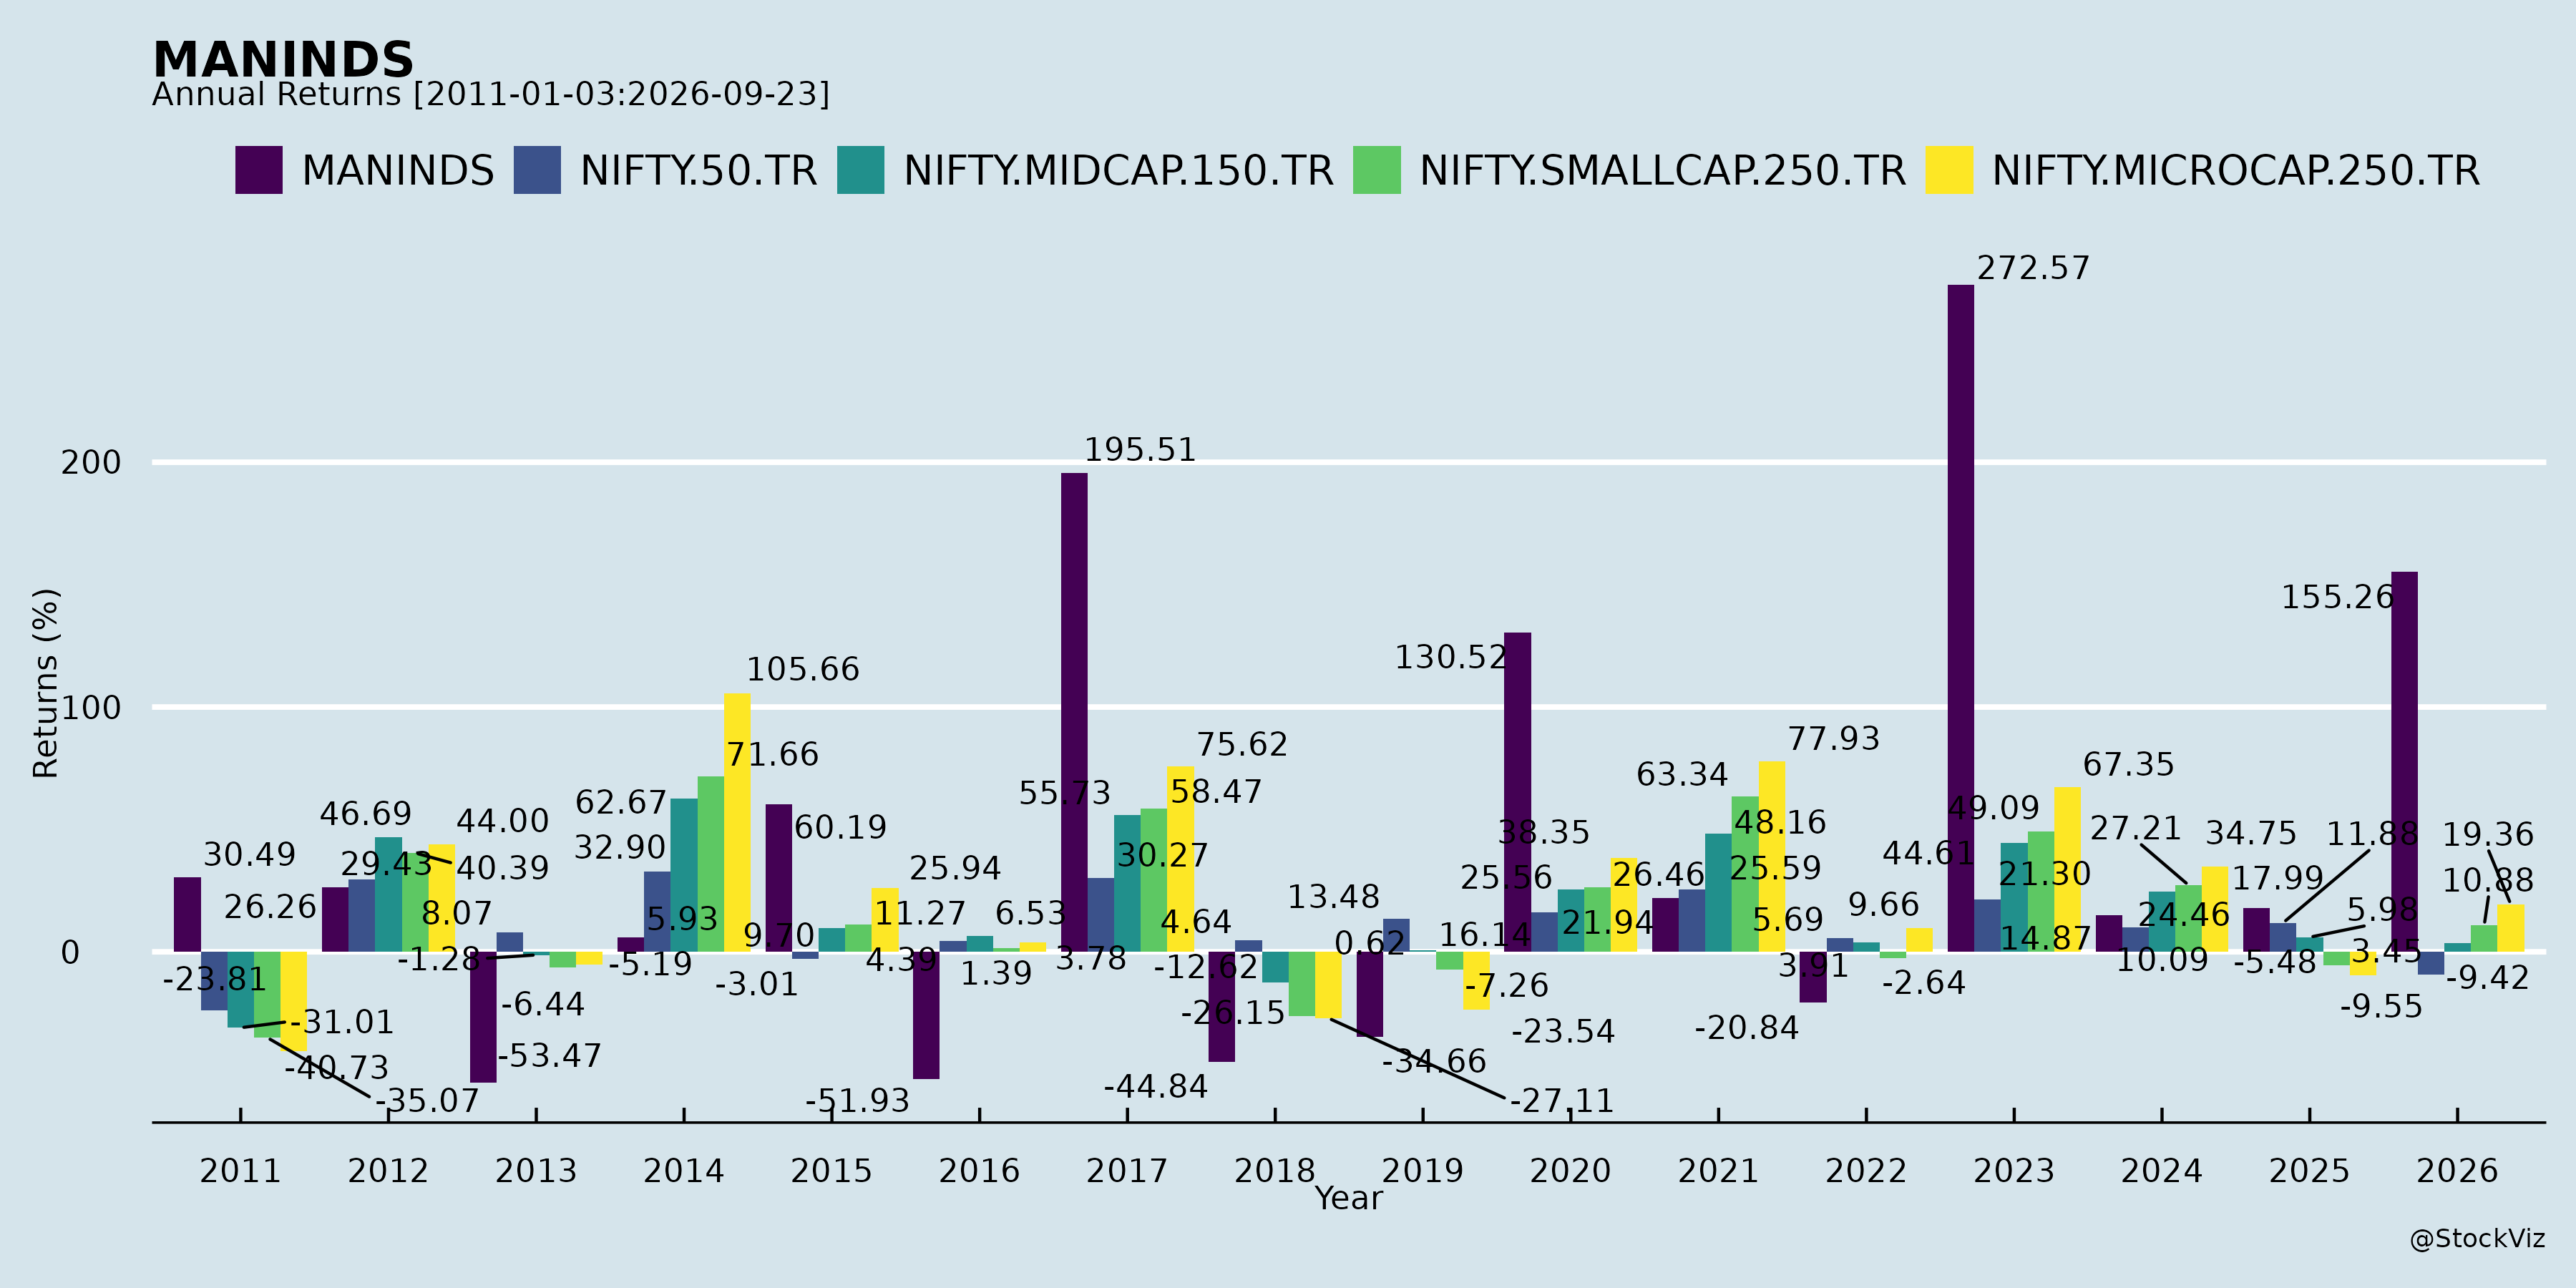
Annual Returns
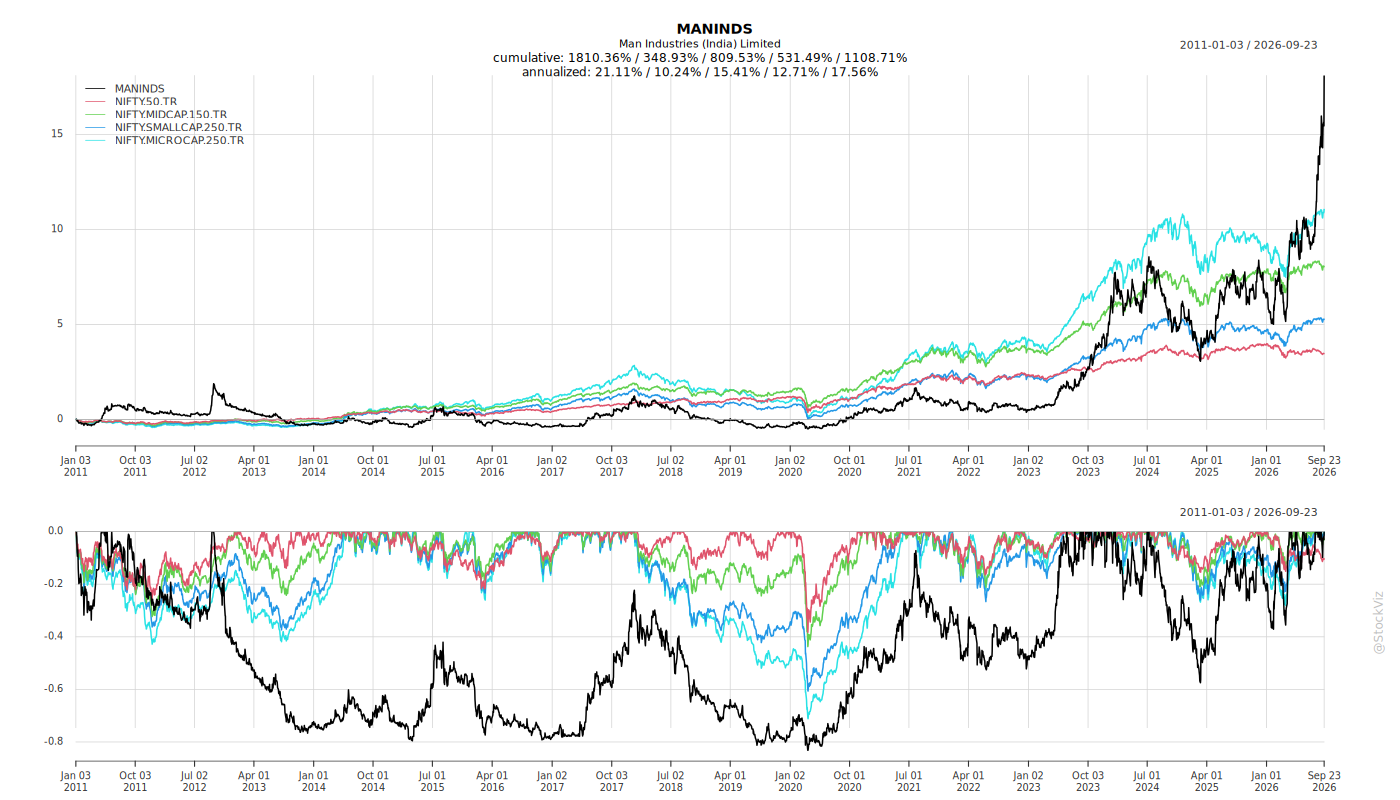
Cumulative Returns and Drawdowns
Fundamentals
Ownership
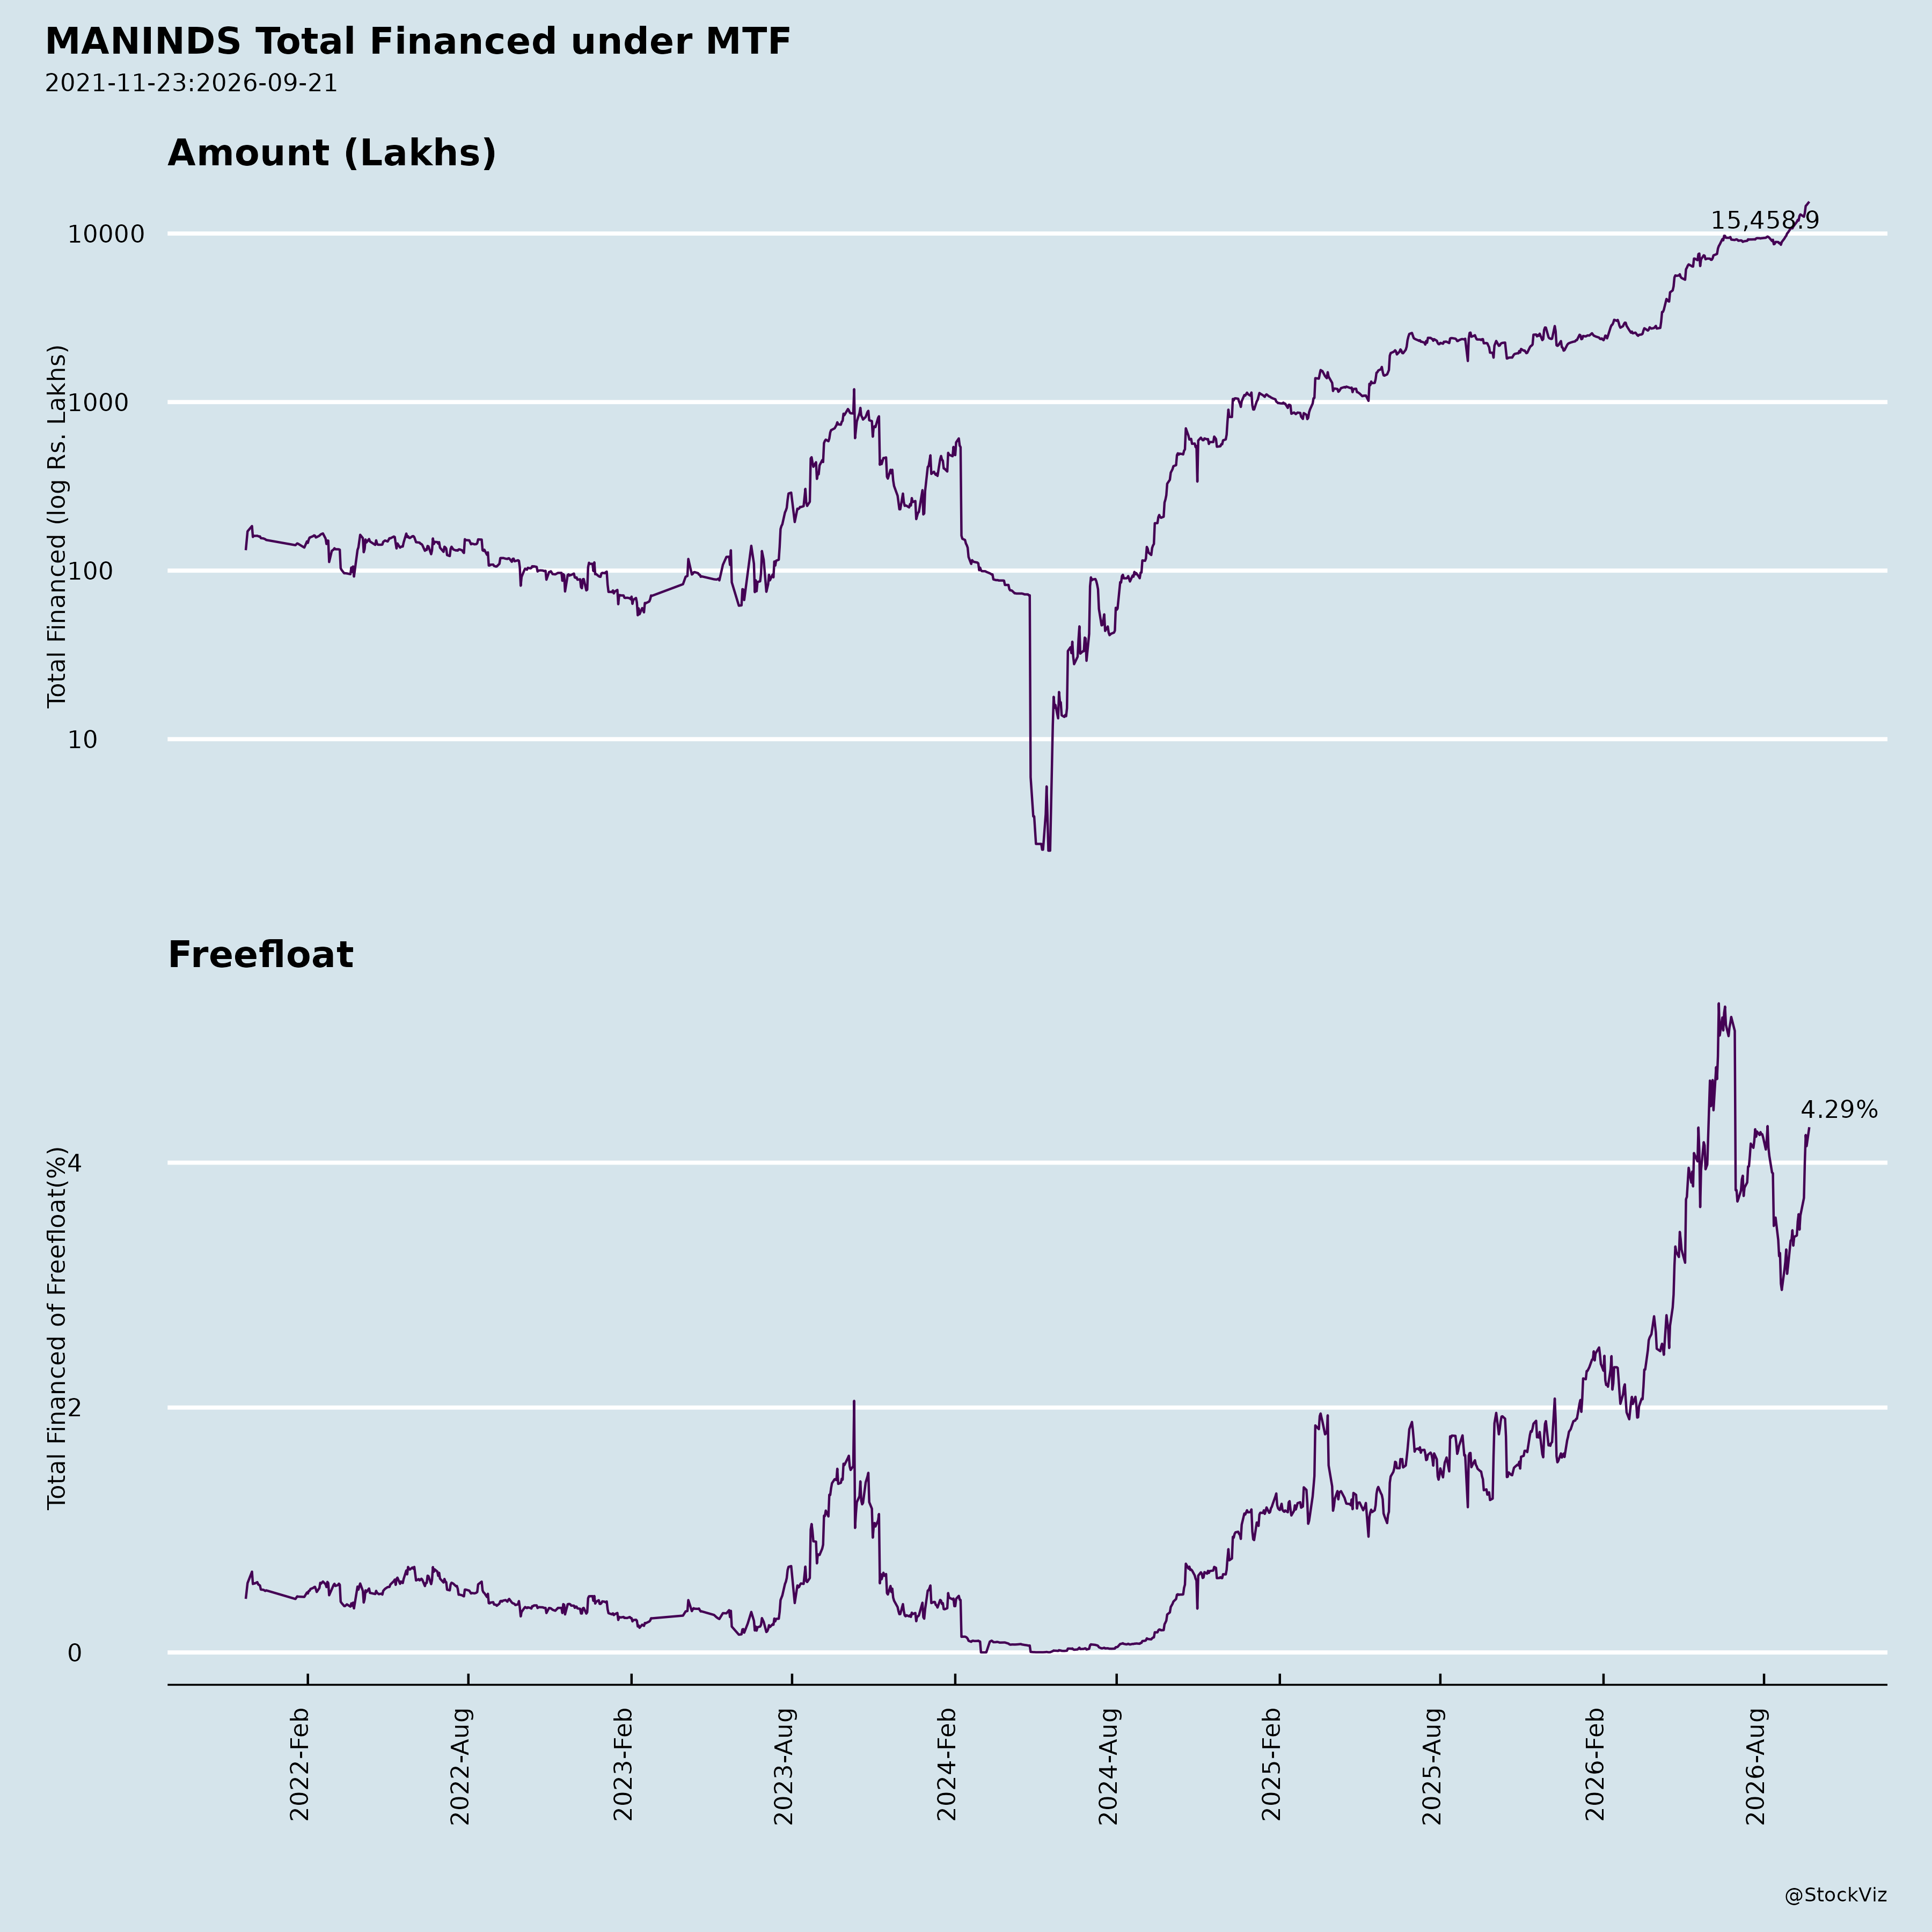
Margined
AI Summary
asof: 2026-09-17
MAN Industries (India) Limited — Recent Corporate Announcements
1. Headwinds and Challenges
- Loss-making overseas operations. For the quarter ended June 30, 2026, the Dubai Branch recorded total revenue of Rs. NIL and a net loss of Rs. 370.66 lakhs, while the Taiwan Branch recorded revenue of Rs. 32,124.84 lakhs but a net loss of Rs. 430.48 lakhs. On a consolidated basis, Man International Steel Industrial Company reported a net loss of Rs. 1,245.99 lakhs, and Man Overseas Invest FZCO a net loss of Rs. 187.83 lakhs.
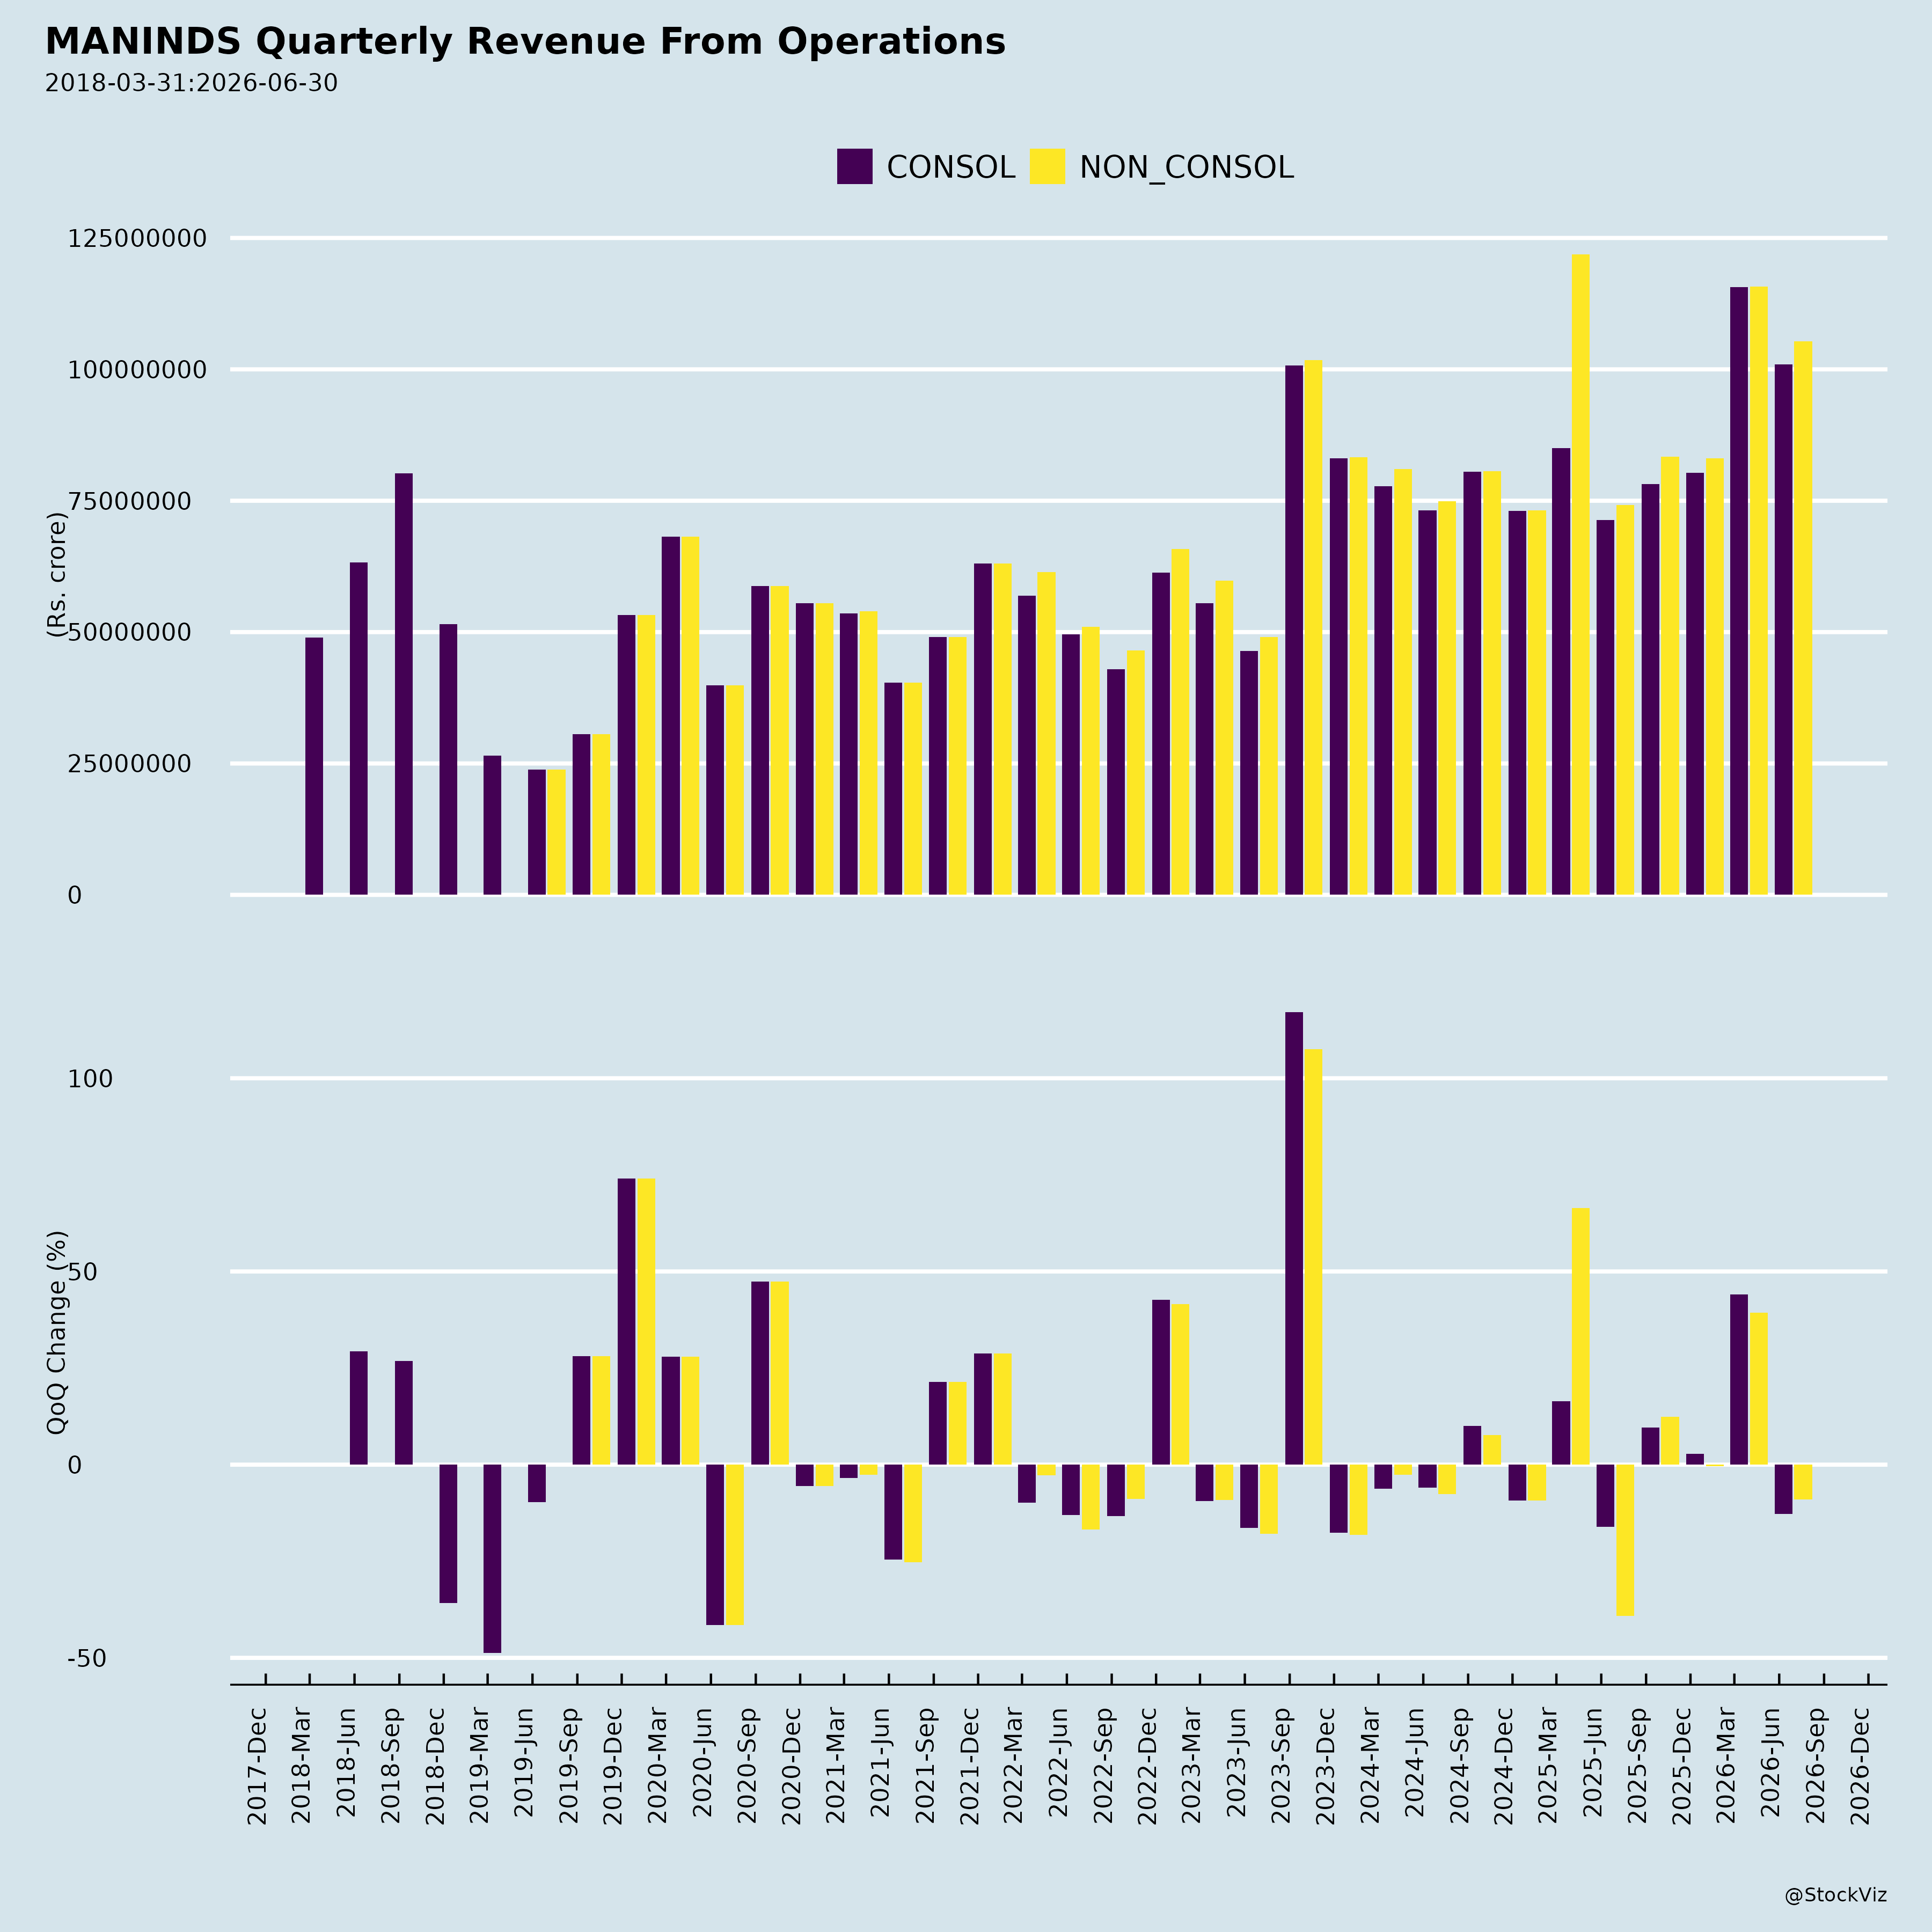
- Sequential moderation in performance. Consolidated revenue from operations declined from Rs. 1,15,730 lakhs in the quarter ended March 31, 2026 to Rs. 1,05,313 lakhs in the quarter ended June 30, 2026, and consolidated net profit declined from Rs. 5,085 lakhs to Rs. 6,143 lakhs on a comparable basis after a weaker prior quarter. Standalone revenue similarly declined from Rs. 1,15,697 lakhs to Rs. 1,00,992 lakhs over the same period.
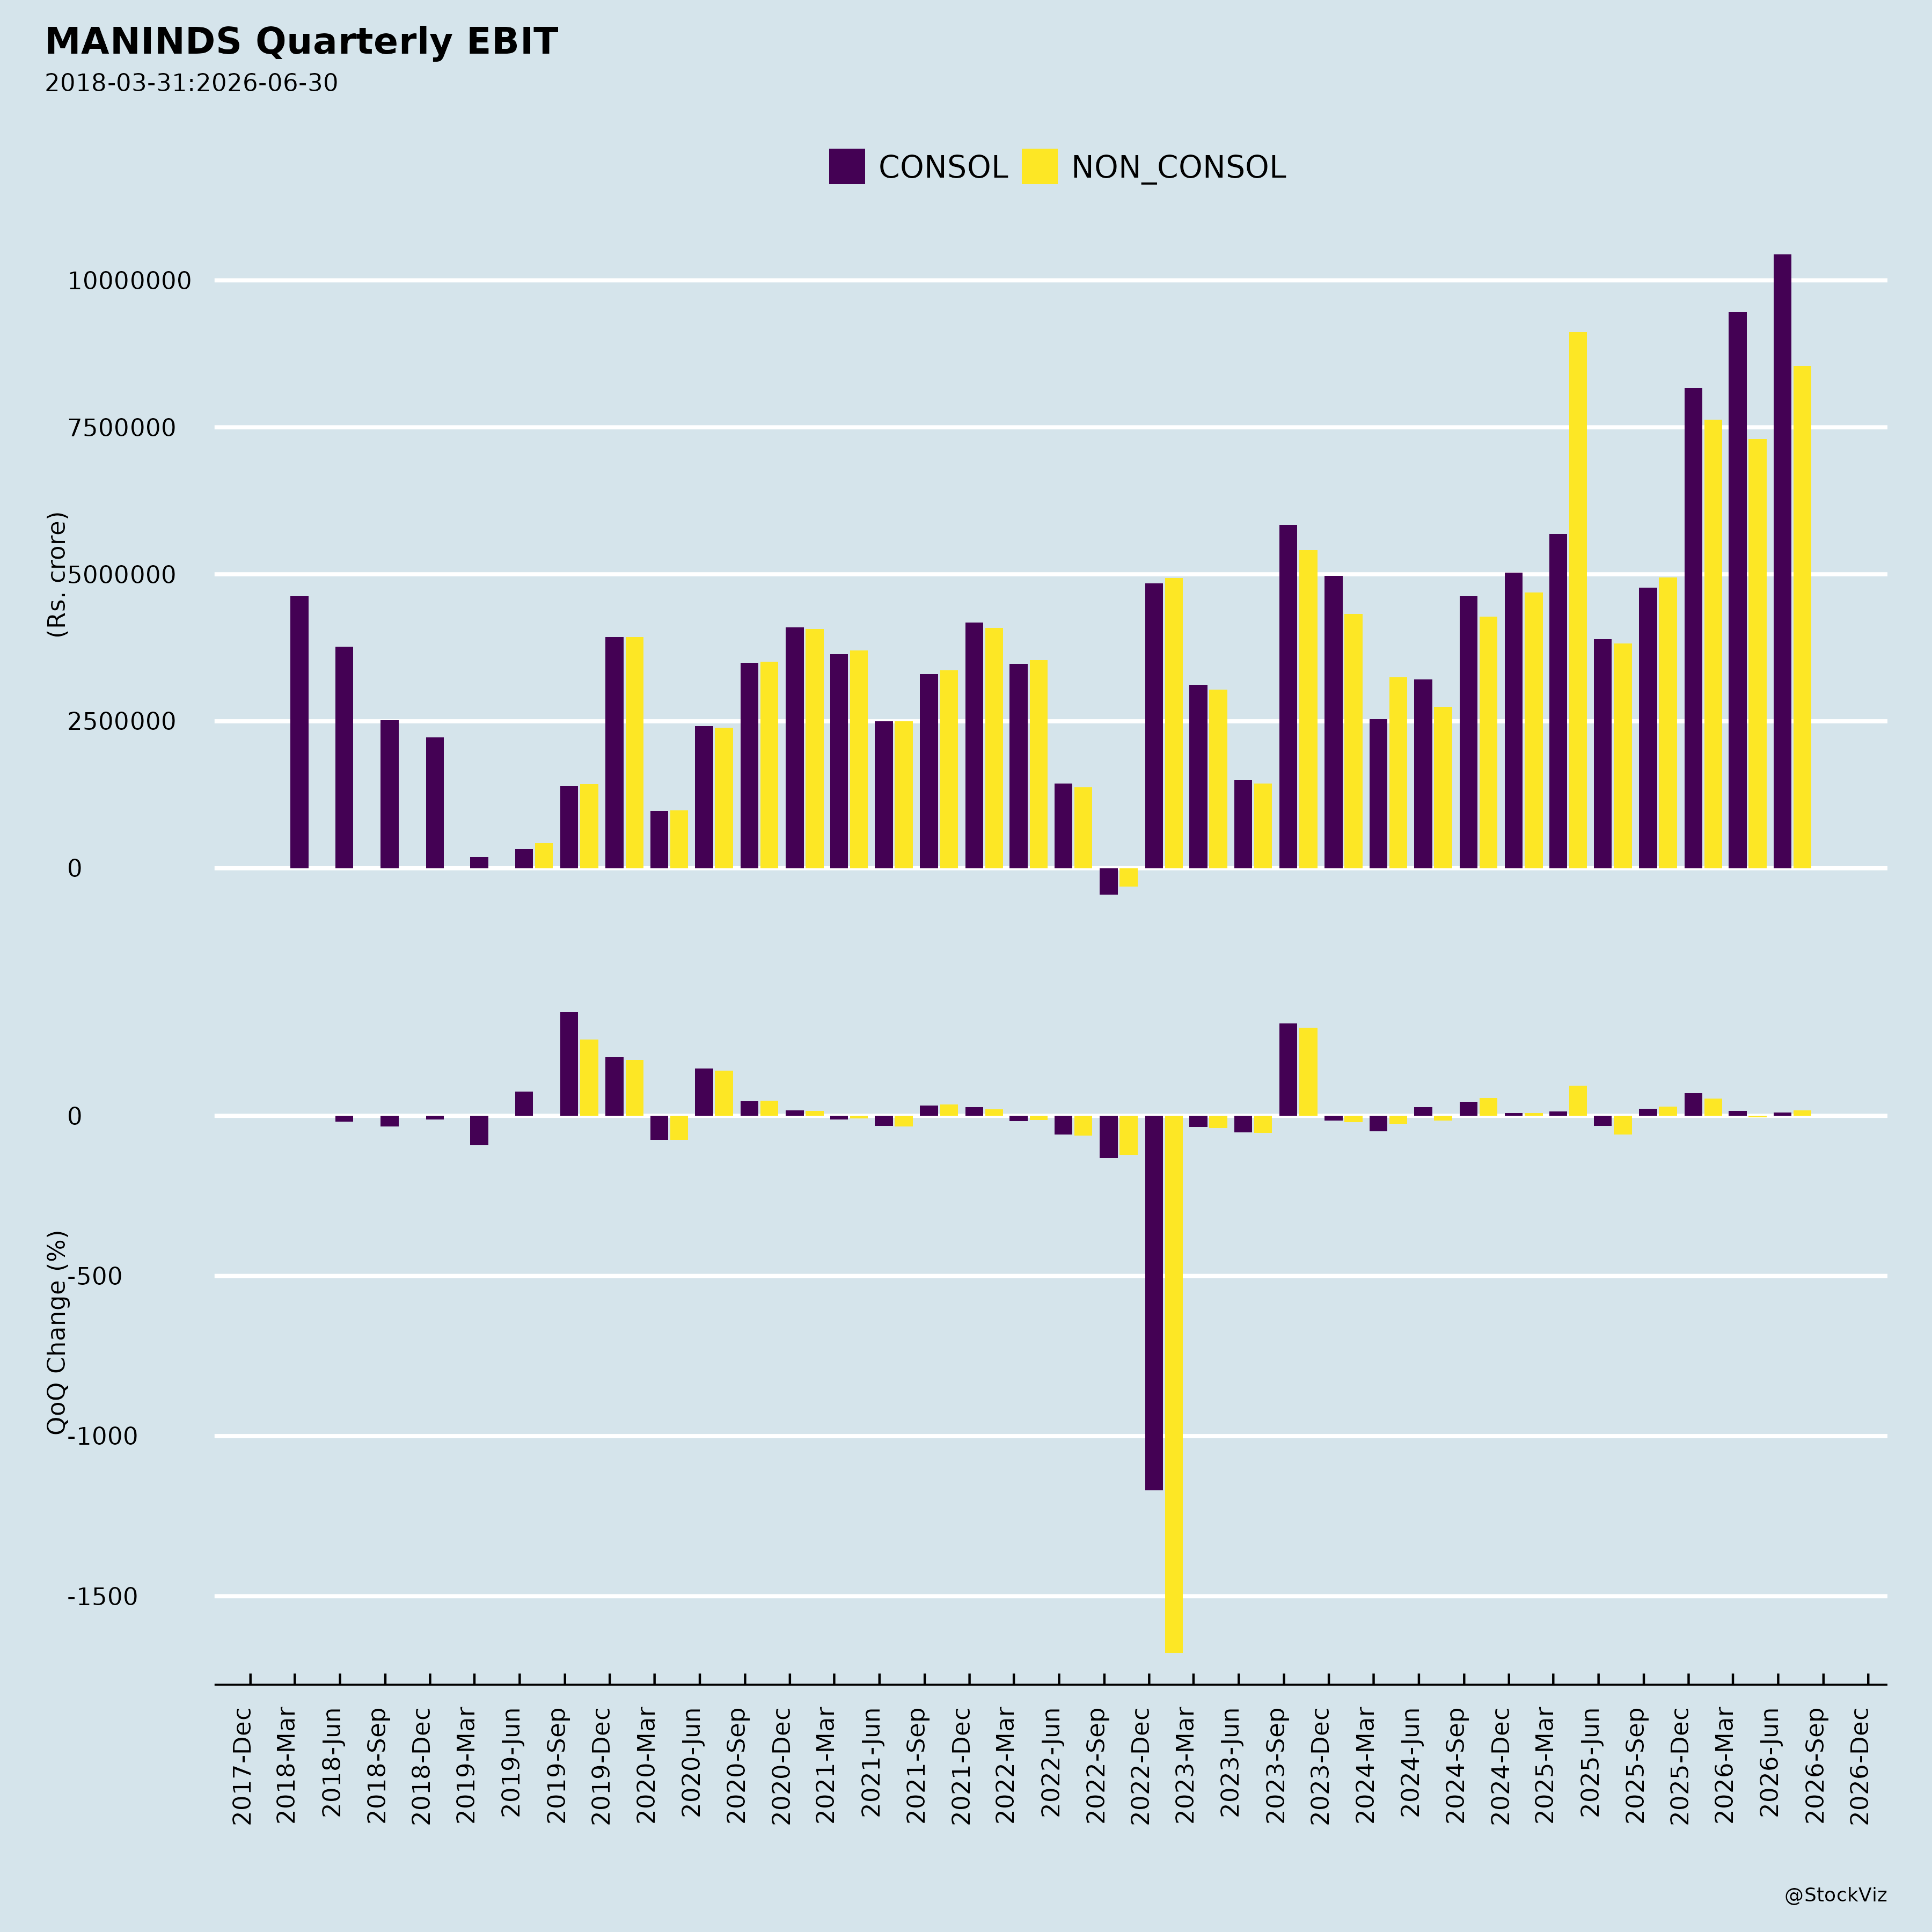
- Rising finance and depreciation costs. Consolidated finance costs were Rs. 3,996 lakhs in the June 2026 quarter, and depreciation and amortisation rose to Rs. 2,984 lakhs, including amortisation of leasehold rights of Rs. 1,068.81 lakhs and depreciation of Rs. 786.50 lakhs relating to a new step-down subsidiary.
- Foreign branch review limitations. The auditors noted that the Taiwan Branch interim financial statements were unaudited and based on management-certified records, and that certain foreign subsidiaries and step-down subsidiaries were reviewed by other auditors or were unaudited.
- General risk factors. Forward-looking statements are subject to known and unknown risks, including future changes in the company’s business, its competitive environment, and political, economic, legal, and social conditions.
2. Tailwinds and Growth Prospects
- QatarEnergy PML approval (August 14, 2026). MAN Industries was included in QatarEnergy’s Preferred Manufacturers List for Carbon Steel LSAW pipes, coating, and bends, making it an eligible bidder for large-diameter pipe requirements across QatarEnergy’s project pipeline. Management described Qatar as one of the most significant energy markets globally and said the approval provides a credible platform to participate in QatarEnergy’s project pipeline over the coming years.
- Saudi Arabia expansion. The acquisition of National Pipe Company (NPC) in Saudi Arabia, described as aligning with Saudi Vision 2030, strengthens positioning across the GCC. The company now operates three manufacturing facilities — Pithampur (Madhya Pradesh), Anjar (Gujarat), and Saudi Arabia — with combined installed capacity of over 1.6 million MTPA.
- Upcoming capacity. The Dammam coating facility is described as upcoming, and production at the Dammam coating plant and Jammu stainless steel plant is targeted for March 2027.
- Order book. The consolidated outstanding order book position is approximately Rs. 3,600 crores, to be executed in 6 to 12 months. A separate announcement reports new orders of approximately Rs. 600 crores to be delivered within 6–9 months, with a total unexecuted order book of approximately Rs. 4,100 crores.
- Demand environment. Opportunities cited include strong global demand for high-pressure cross-country pipelines and a global surge in acceptance of HSAW line pipes for high-pressure applications.
- Real estate monetisation. Merino Shelters is expected to generate annual cash flow of Rs. 80–120 crores from FY28, with total projected revenue of Rs. 700–800 crores over the next 5–6 years.
3. Key Risks
- Forward-looking statements carry known and unknown risks and uncertainties that may cause actual results, financial condition, performance, or achievements to differ materially.
- The company assumes no responsibility for actions taken based on forward-looking statements and undertakes no obligation to publicly revise or update them.
- Execution of the order book is time-bound, with the consolidated order book to be executed in 6 to 12 months and the new orders within 6–9 months.
- Continued losses at certain foreign branches and subsidiaries, and reliance on other auditors or management-certified records for parts of the consolidated results, are disclosed limitations.
4. Management Guidance Versus Observed Business Performance
- Guidance: Management’s goals over the next 5 years include a revenue CAGR of 20–25% and improvement in EBITDA margin to a long-term stable rate of 15%. Production at the Dammam coating plant and Jammu stainless steel plant is targeted for March 2027. Merino Shelters expects annual cash flow of Rs. 80–120 crores from FY28 with total projected revenue of Rs. 700–800 crores over 5–6 years. New orders are expected to be delivered within 6–9 months.
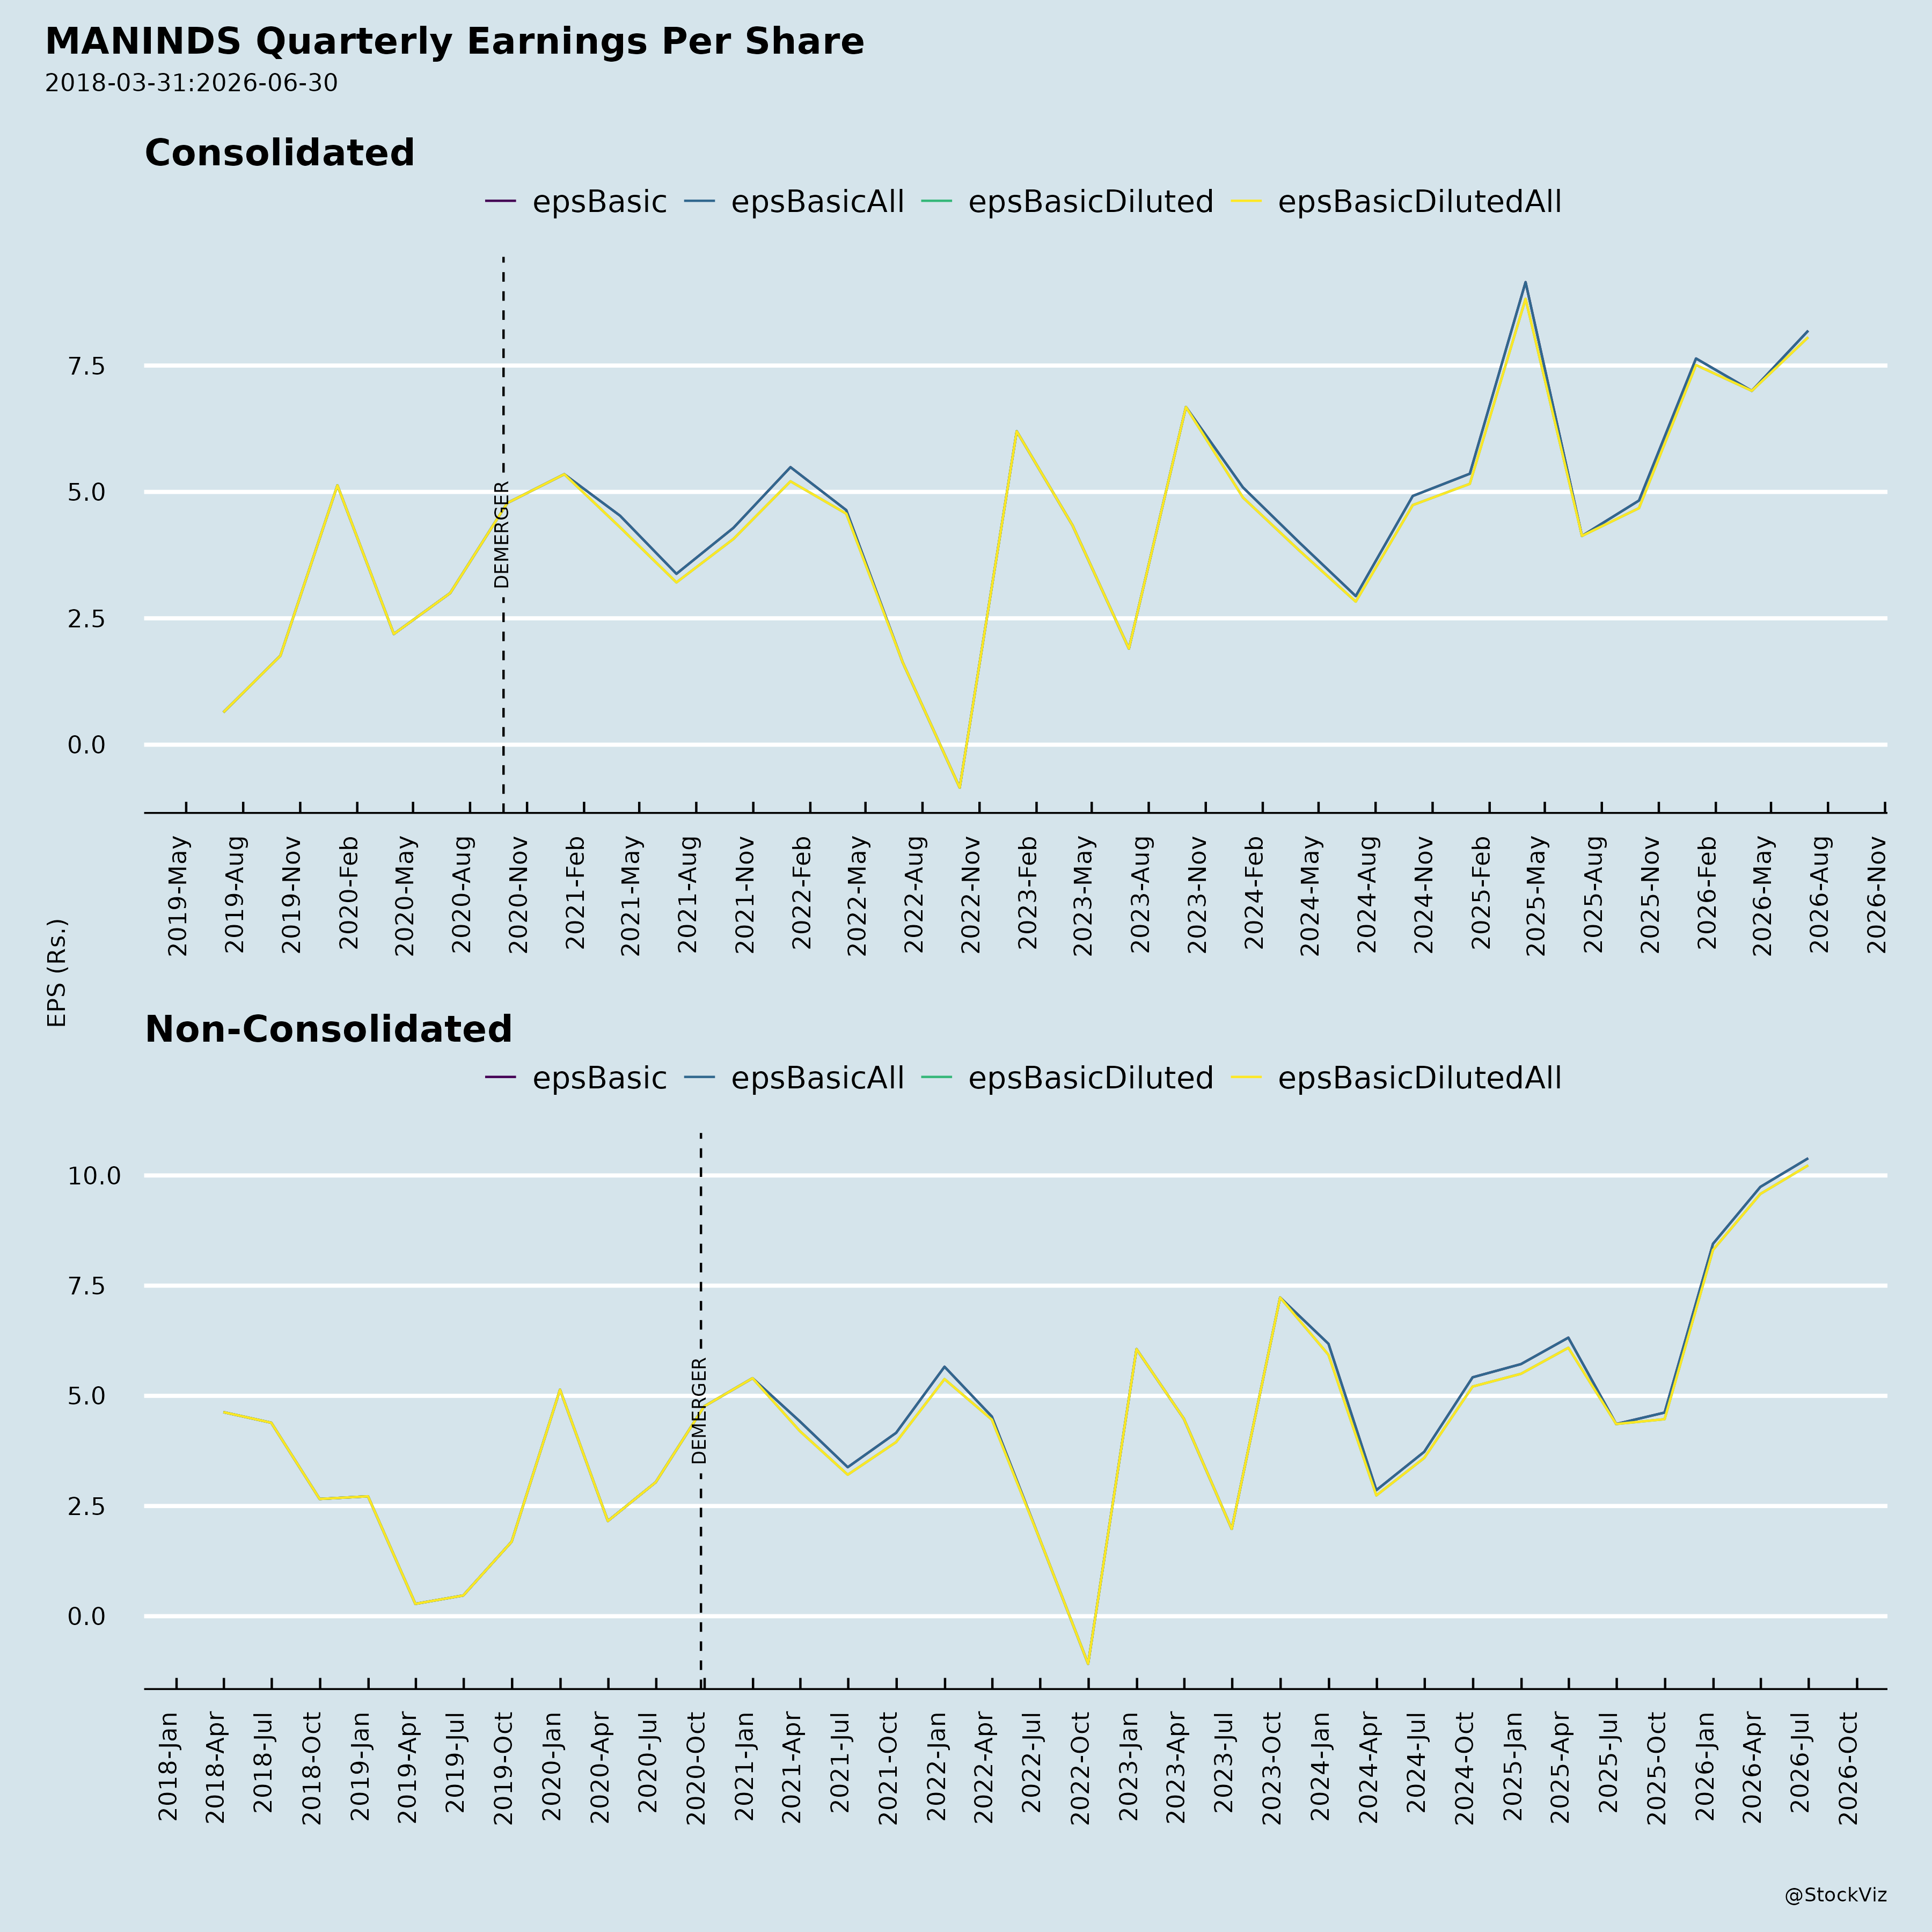
- Observed performance: For FY26, the company reported consolidated revenue from operations of INR 35,639 million and a PAT of INR 1,705 million. In the quarter ended June 30, 2026, consolidated revenue from operations was Rs. 1,05,313 lakhs and net profit was Rs. 6,143 lakhs, with basic EPS of Rs. 8.19 and diluted EPS of Rs. 8.06. Standalone net profit for the same quarter was Rs. 7,795 lakhs, with basic EPS of Rs. 10.39 and diluted EPS of Rs. 10.23. The consolidated order book stands at approximately Rs. 3,600 crores (to be executed in 6–12 months), while a separate announcement cites a total unexecuted order book of approximately Rs. 4,100 crores.
Broker Narrative
The broker maintained a persistent Buy stance and continued to emphasize India’s structural demand, exports/value-added products, and scaling capacities. The first report focused more on macro/import/event risks (elections, China imports, US election) and near-term construction softness, while the last report shifted to company-specific execution—bid pipeline conversion, new capacity ramp-ups, margin expansion, and non-core asset monetisation. The later narrative also added explicit earnings CAGR forecasts and INR-denominated catalysts absent in the initial report.
Broker Timeline
4 broker calls · 2024-03-23 to 2026-08-13
Copyright © 2023 SAS Data Analytics Pvt. Ltd. All rights reserved.