MADRASFERT
Equity Metrics
November 18, 2026
Madras Fertilizers Limited
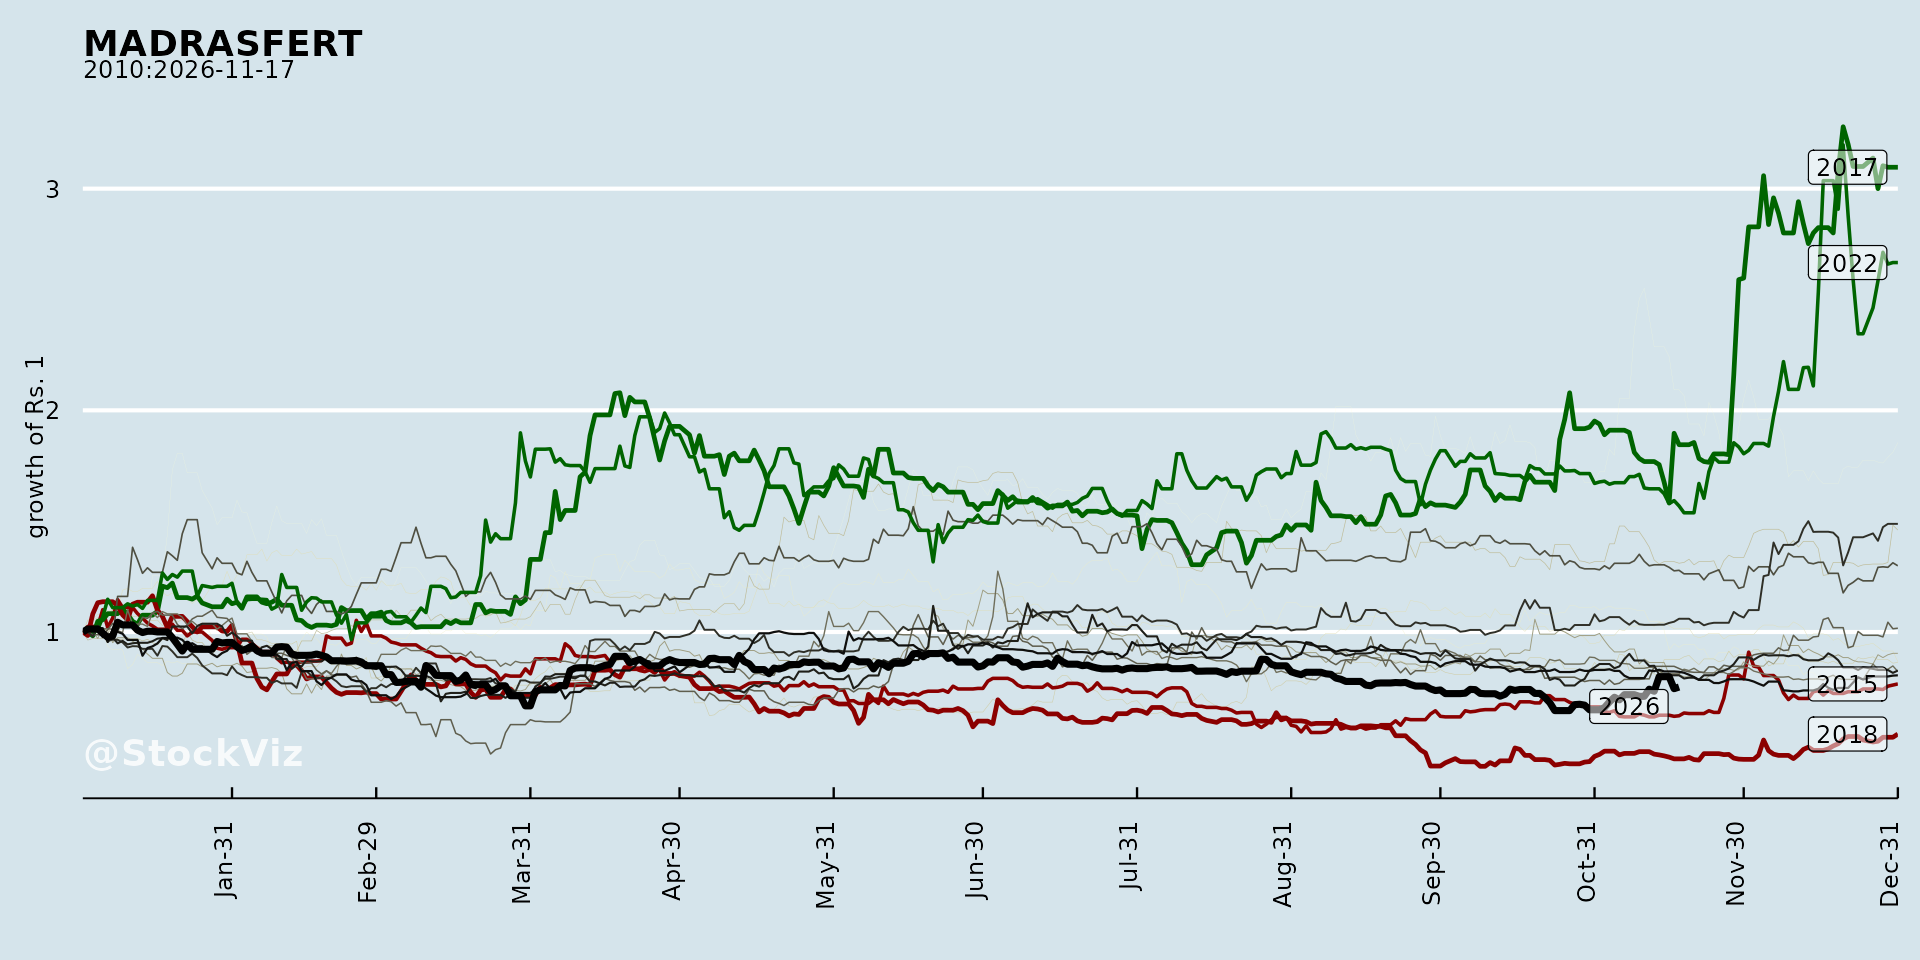
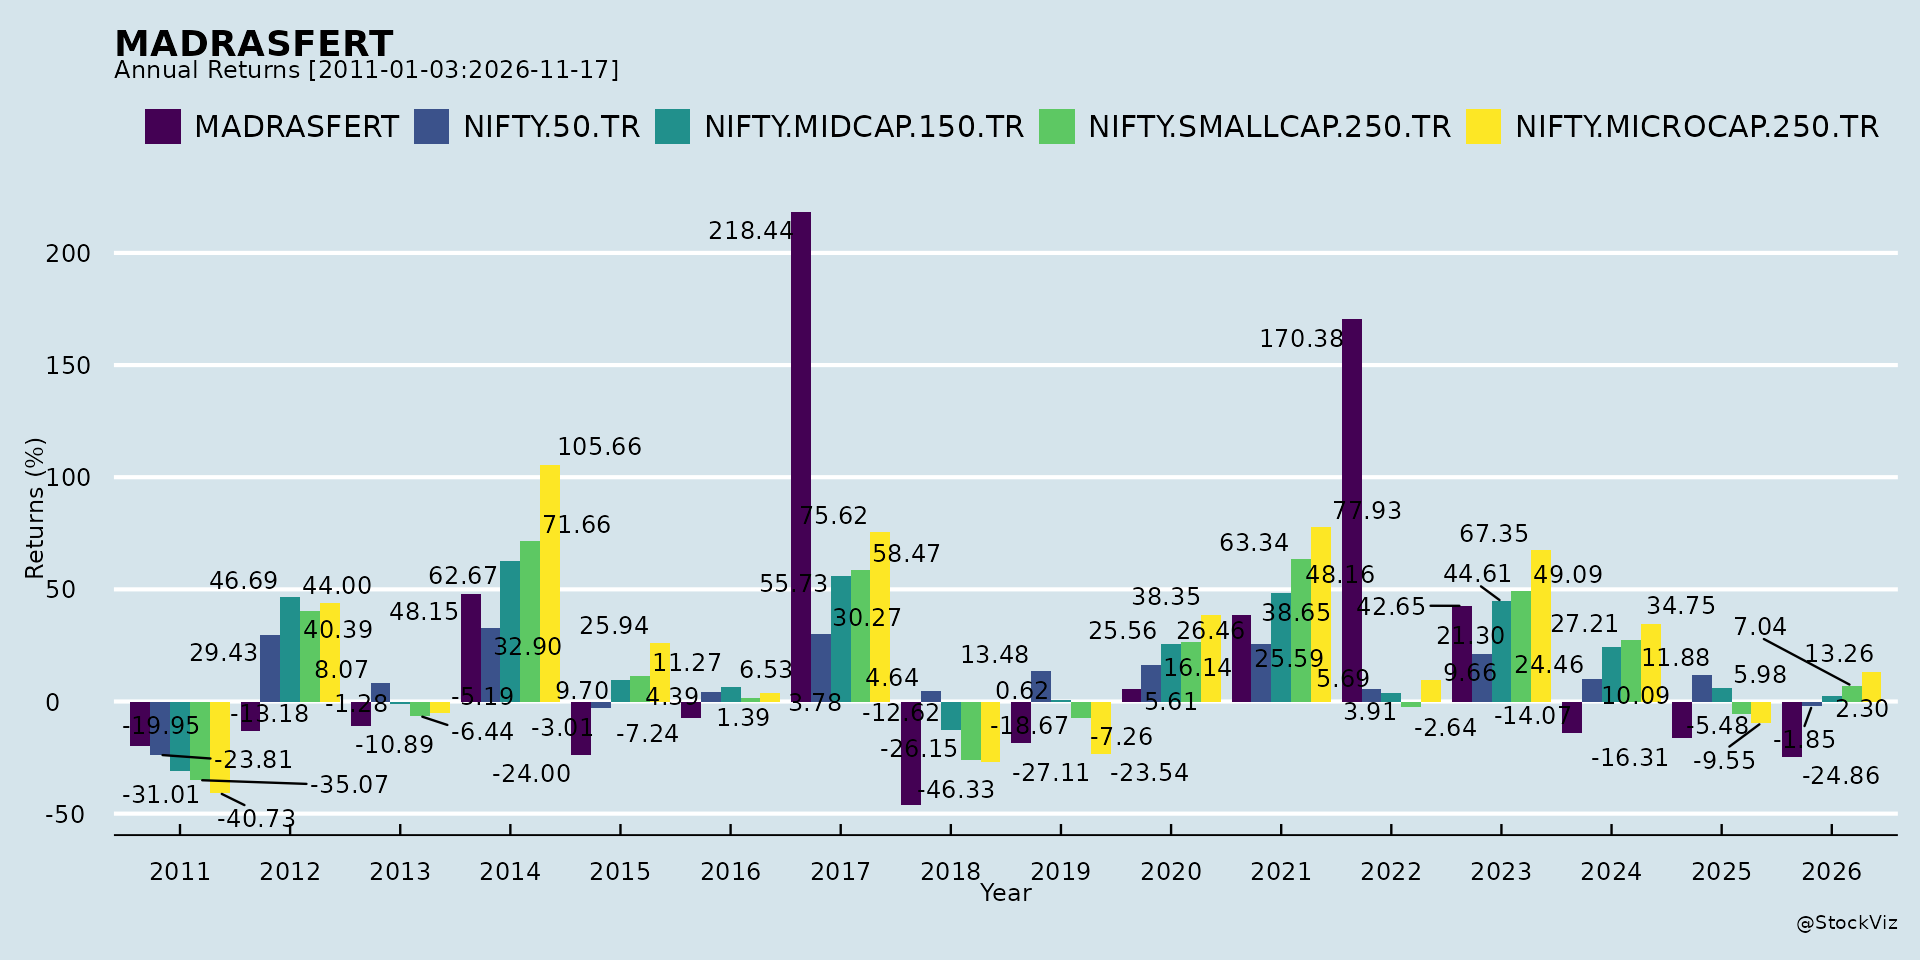
Annual Returns
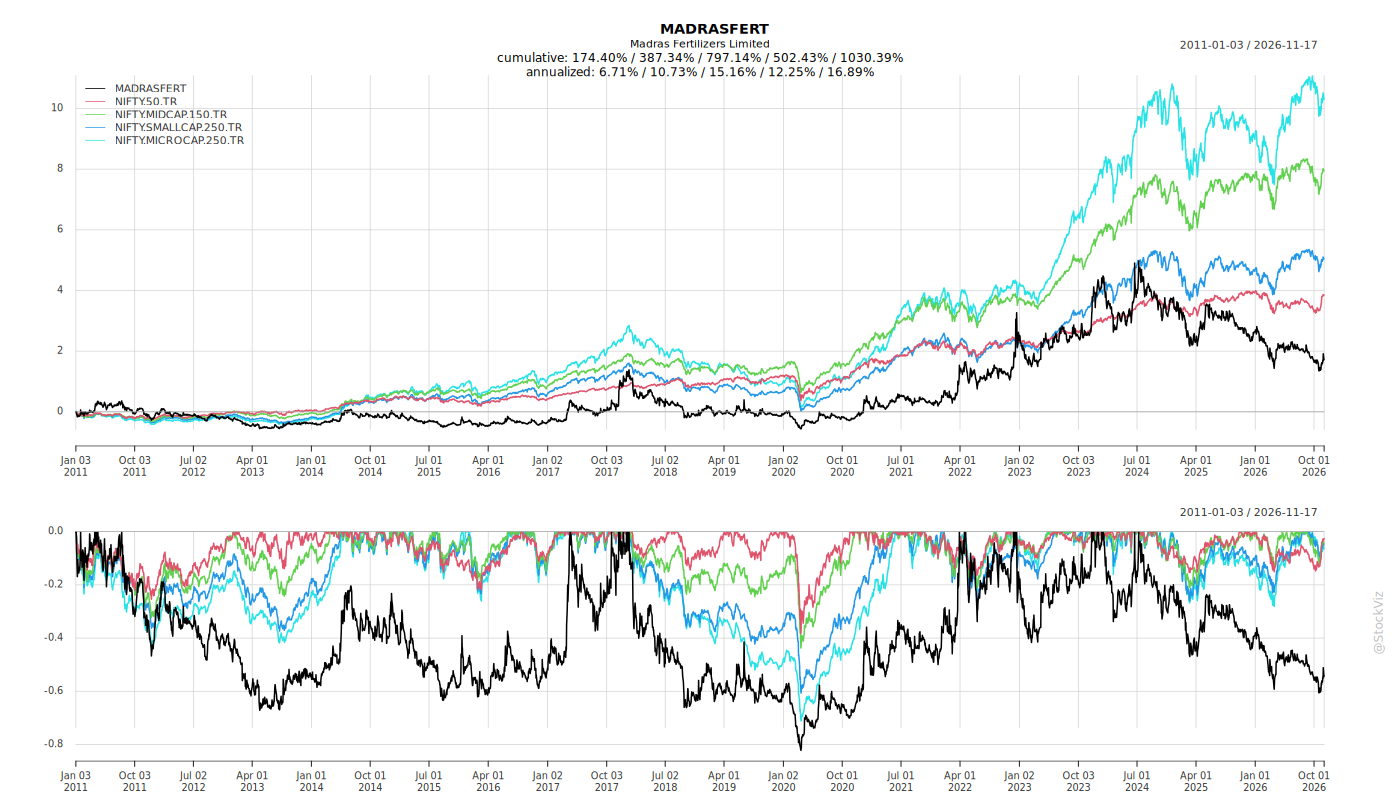
Cumulative Returns and Drawdowns
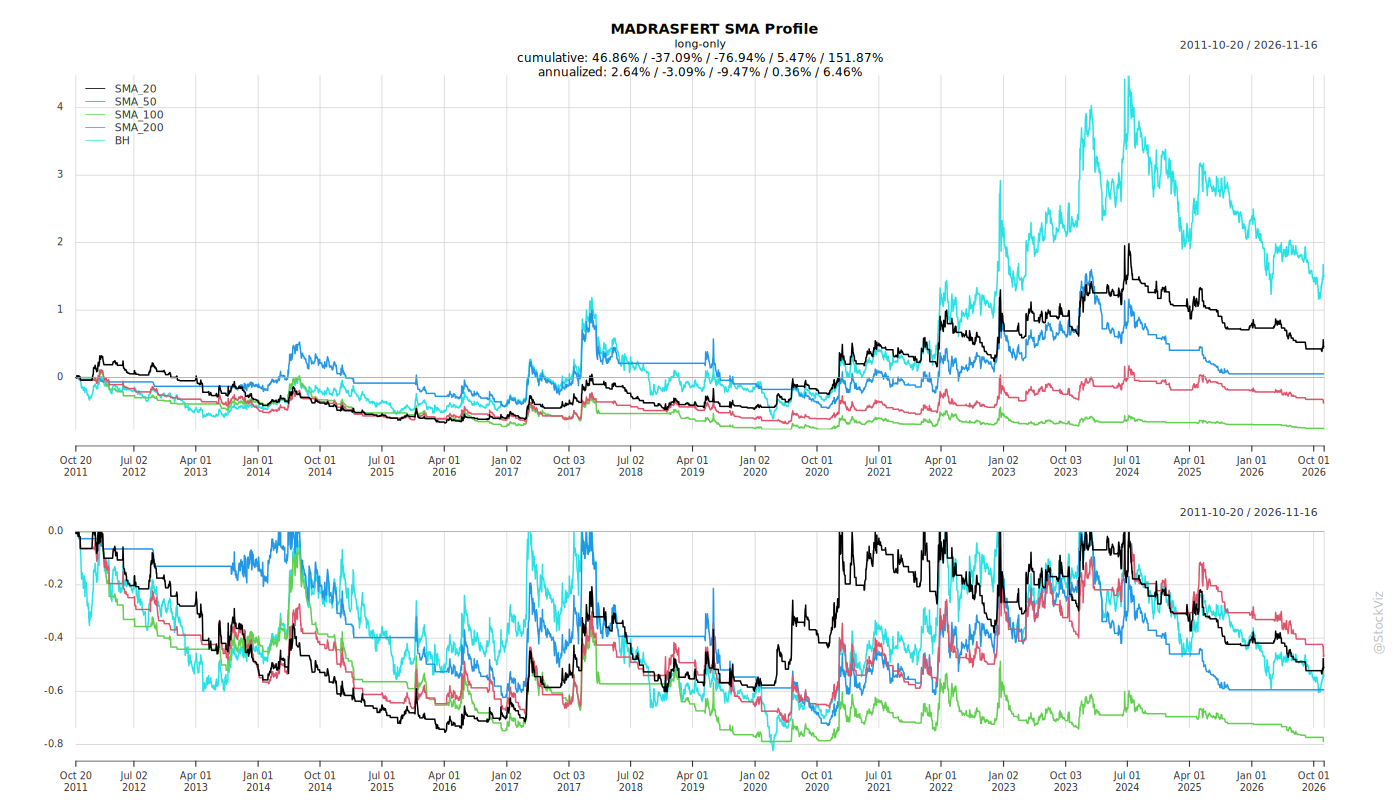
Fundamentals
Ownership
Margined
AI Summary
asof: 2026-09-18
Headwinds and Challenges
Madras Fertilizers Limited is navigating a set of material headwinds that span input costs, operations, policy, and compliance:
- Raw material and supply chain pressure: Volatility in international raw material prices and supply chain disruptions affecting imported inputs create cost uncertainty for the business.
- Currency exposure: Foreign exchange fluctuations add further unpredictability to imported input costs.
- Vintage plant operations: The company operates a vintage plant, which presents ongoing operational challenges.
- Policy dependence: Changes in government subsidy policies represent a structural risk given the regulated nature of the fertilizer sector.
- Climate and agricultural variability: Climate variability affecting agricultural production flows through to fertilizer demand.
- Compliance and penalties: Non-compliance issues regarding board composition have led to stock exchange penalties.
Tailwinds and Growth Prospects
Several factors support the company’s outlook:
- Balanced nutrient management: Growing demand for balanced nutrient management supports the core fertilizer business.
- Product diversification: Diversification through traded fertilizer products offers an avenue to broaden the revenue base.
- Sustainability adoption: Increasing adoption of environmentally sustainable agricultural practices aligns with evolving demand patterns.
- Operational modernization: Improving operational efficiencies through process modernization is identified as a lever for performance.
- Greenfield expansion: Plans for establishing a new Greenfield Ammonia-Urea Complex with an annual capacity of 1.32 million metric tonnes per annum represent a significant long-term growth prospect.
Key Risks
- Financial obligations: The company has defaulted on the repayment of principal and interest on Government of India loans totaling Rs. 1,554.53 crores.
- No dividend capacity: No dividend is proposed for the year due to accumulated losses.
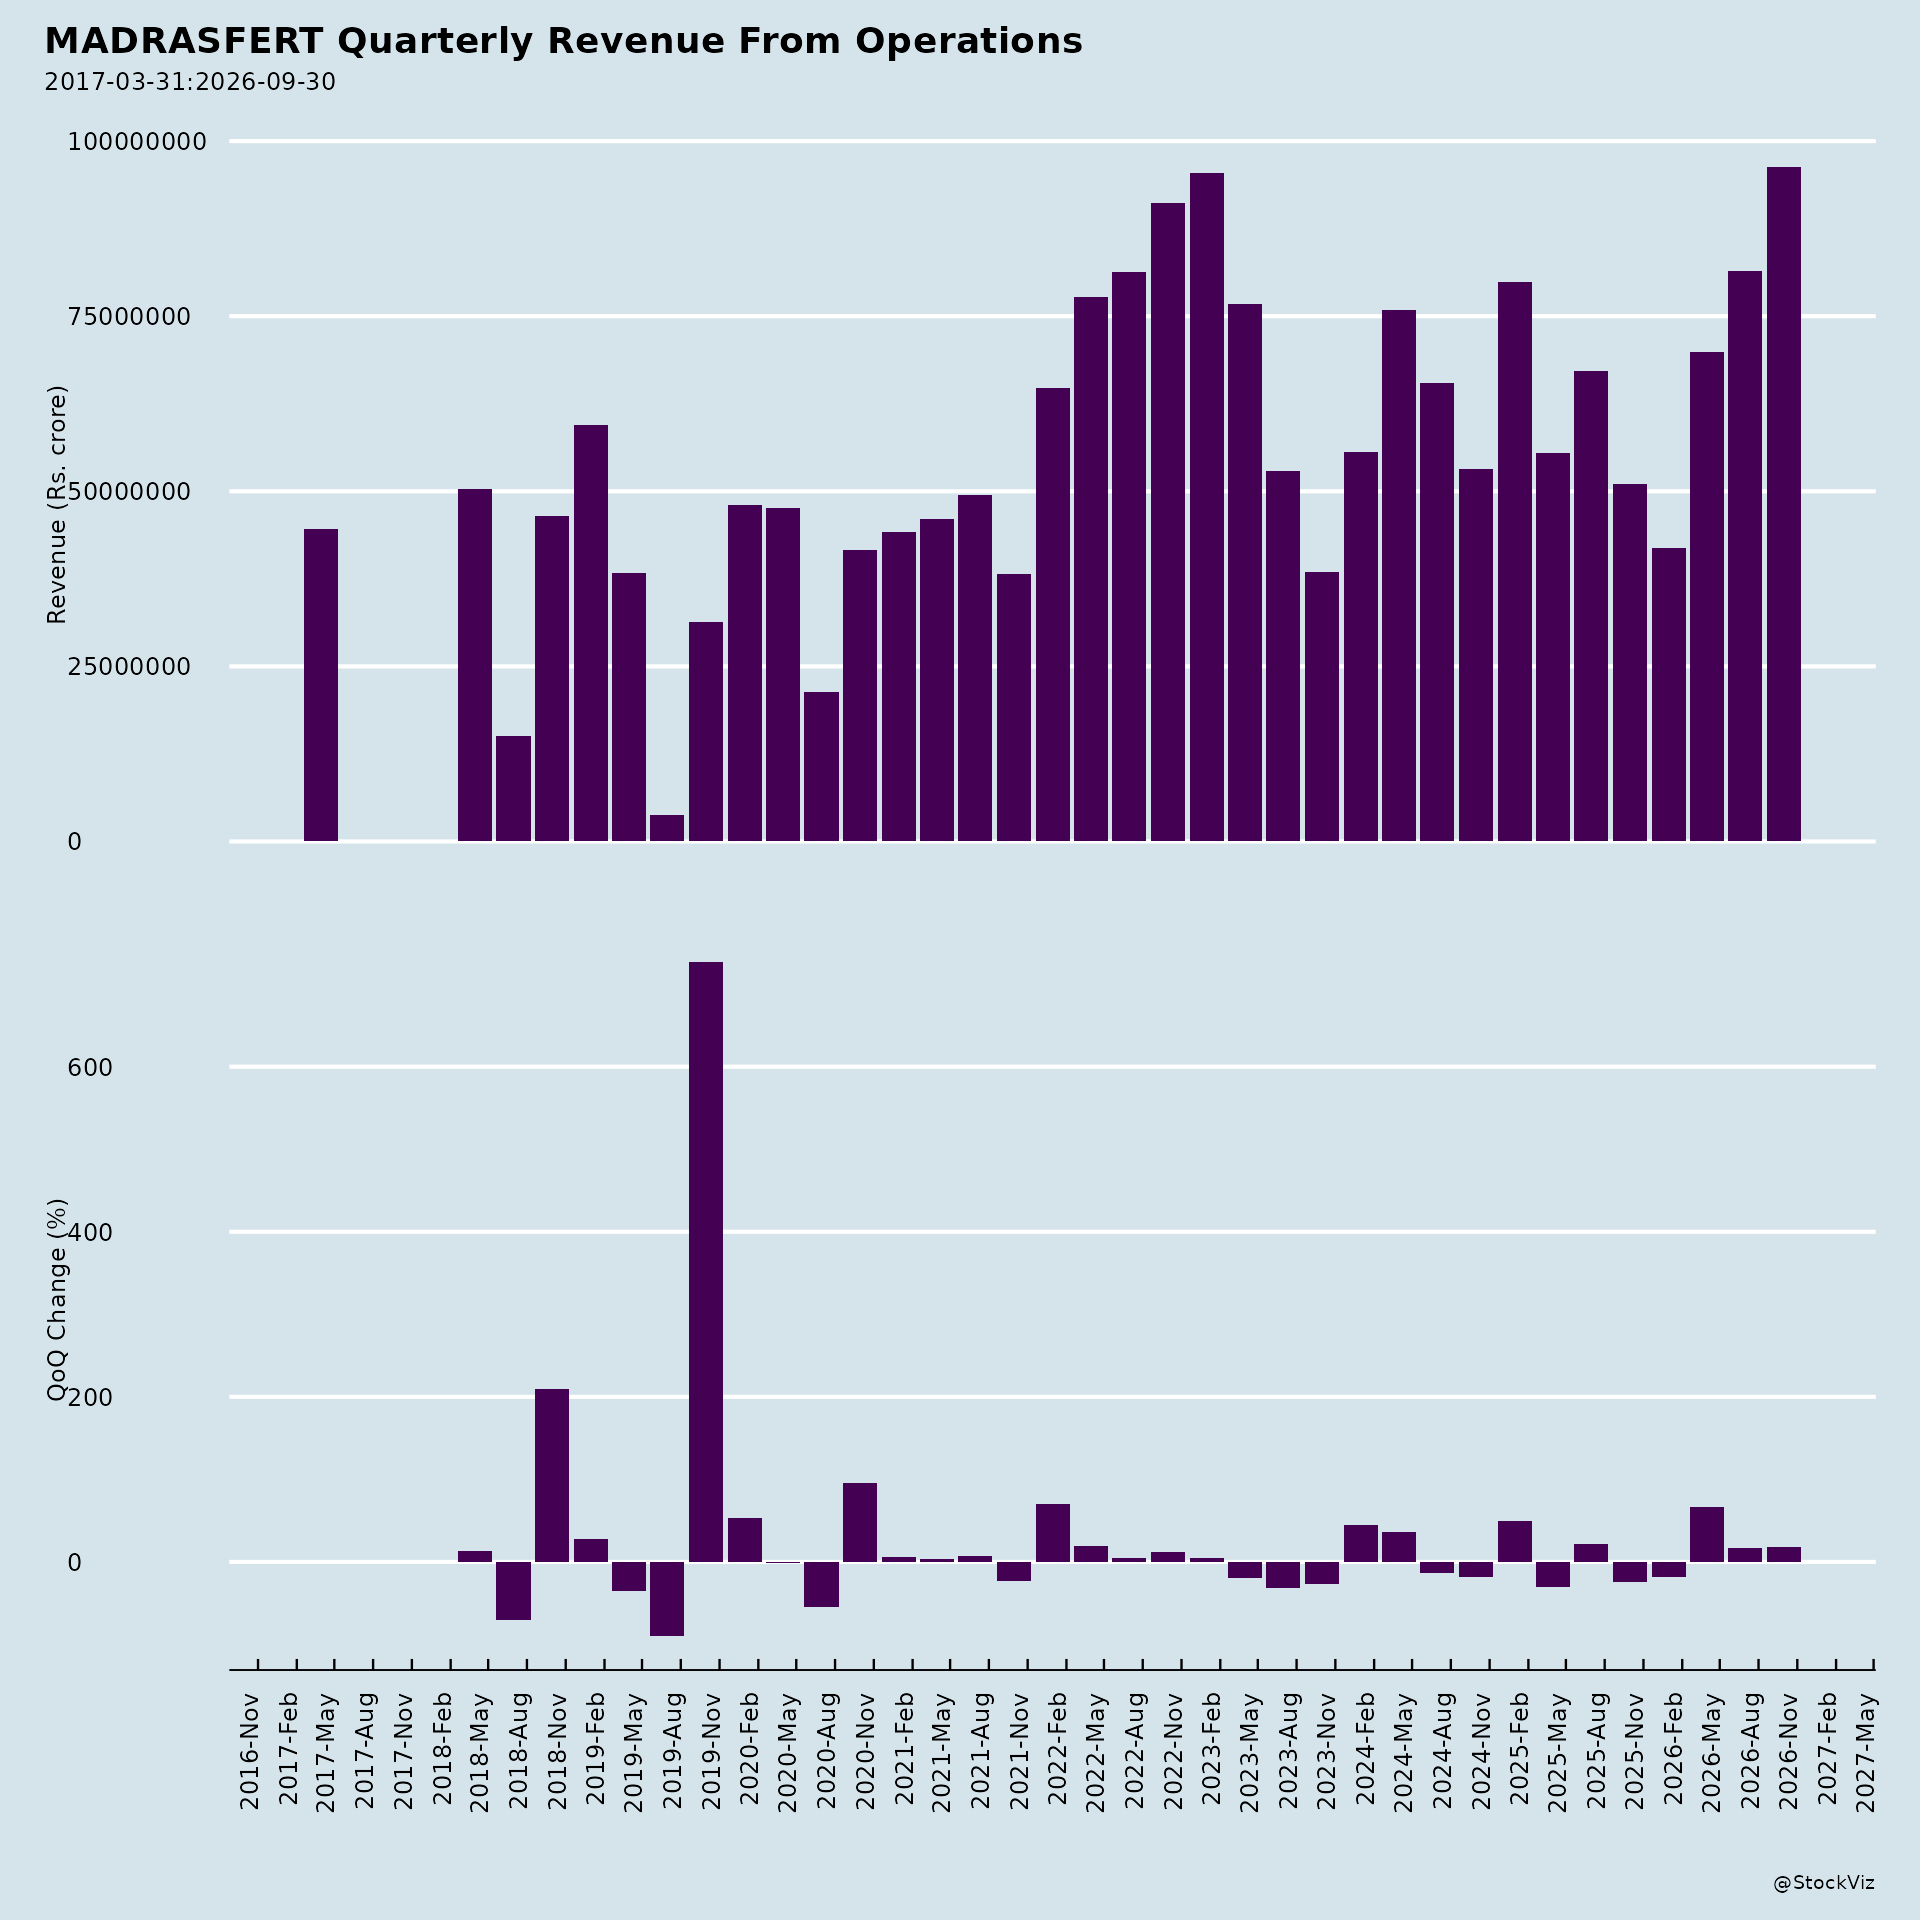
- Turnover decline: Turnover declined to Rs. 2,300.35 crores in FY 2025-26, even as profitability improved.
- Subsidy and policy risk: Continued dependence on government subsidy policies leaves earnings exposed to policy shifts.
- Compliance risk: Board composition non-compliance has already resulted in stock exchange penalties, signaling governance-related exposure.
Management Guidance vs. Observed Performance
Management’s forward-looking commentary is positive: the outlook for the Indian fertilizer industry is described as remaining positive, supported by favorable agricultural fundamentals, continued government policy support, and an increasing emphasis on food security and sustainable farming. Demand across Southern India is expected to remain stable, and the company intends to focus on operational excellence, cost optimization, product diversification, and improved customer service.
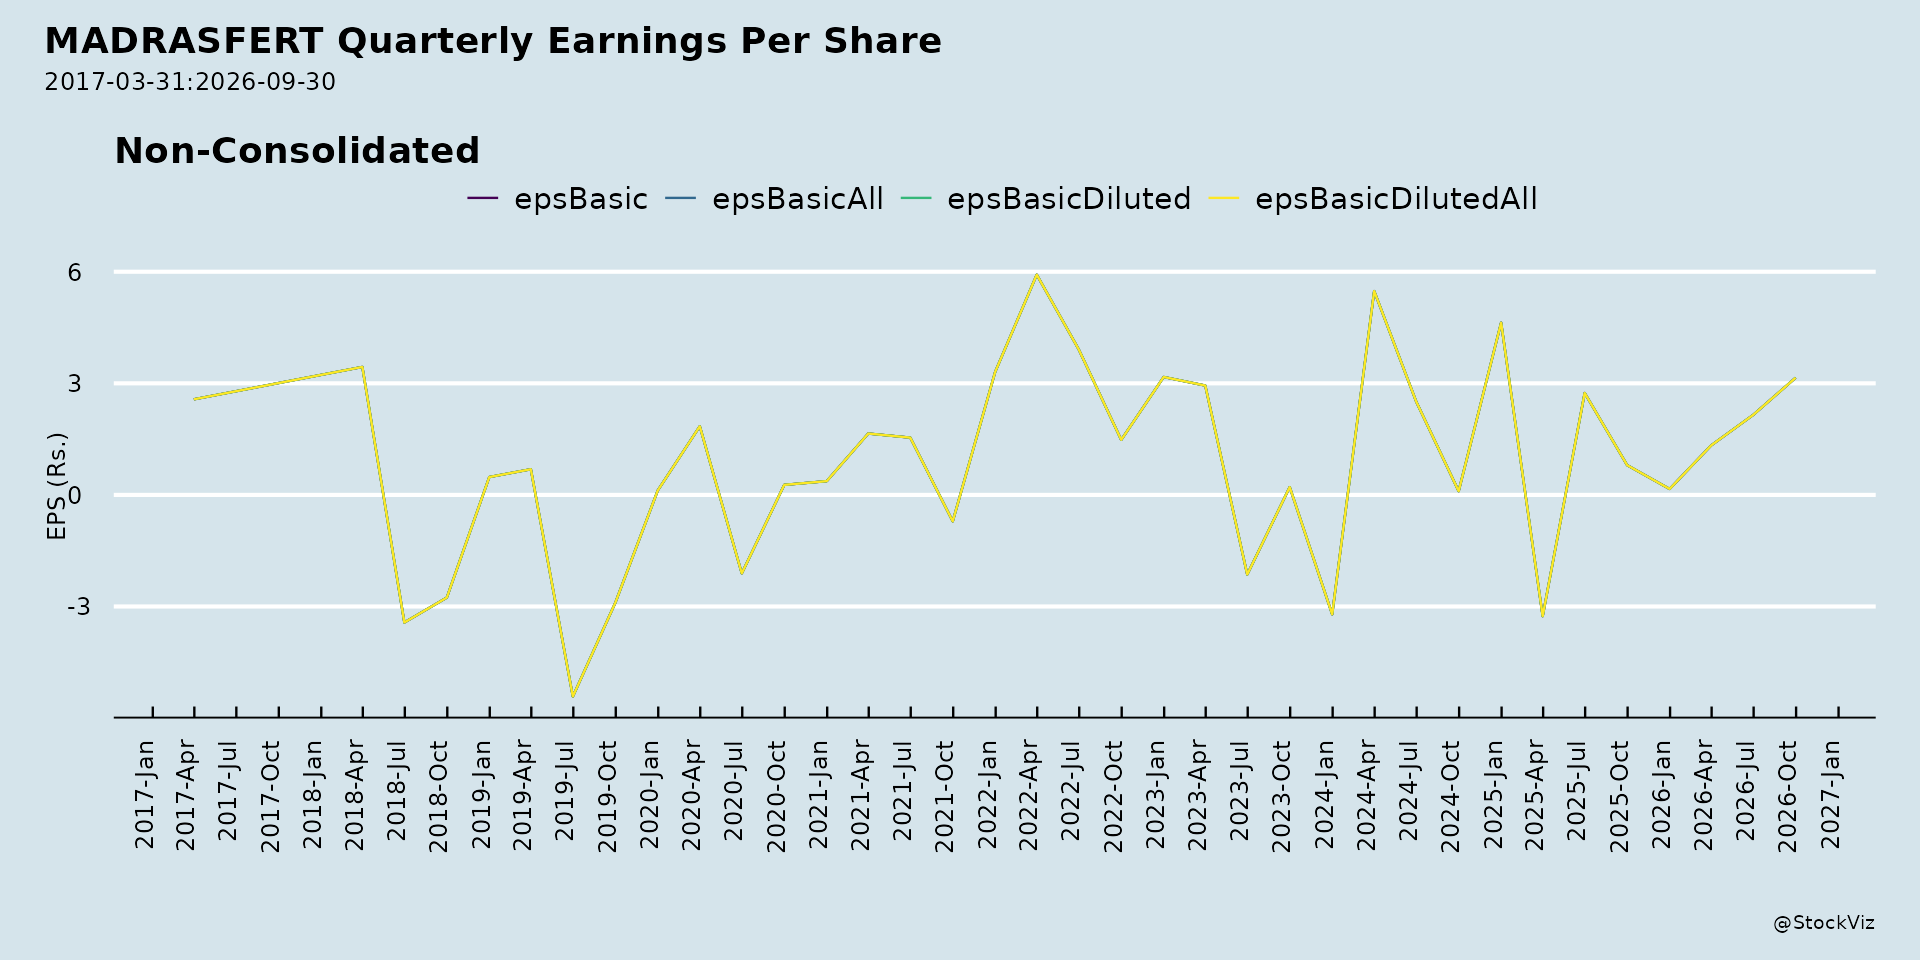
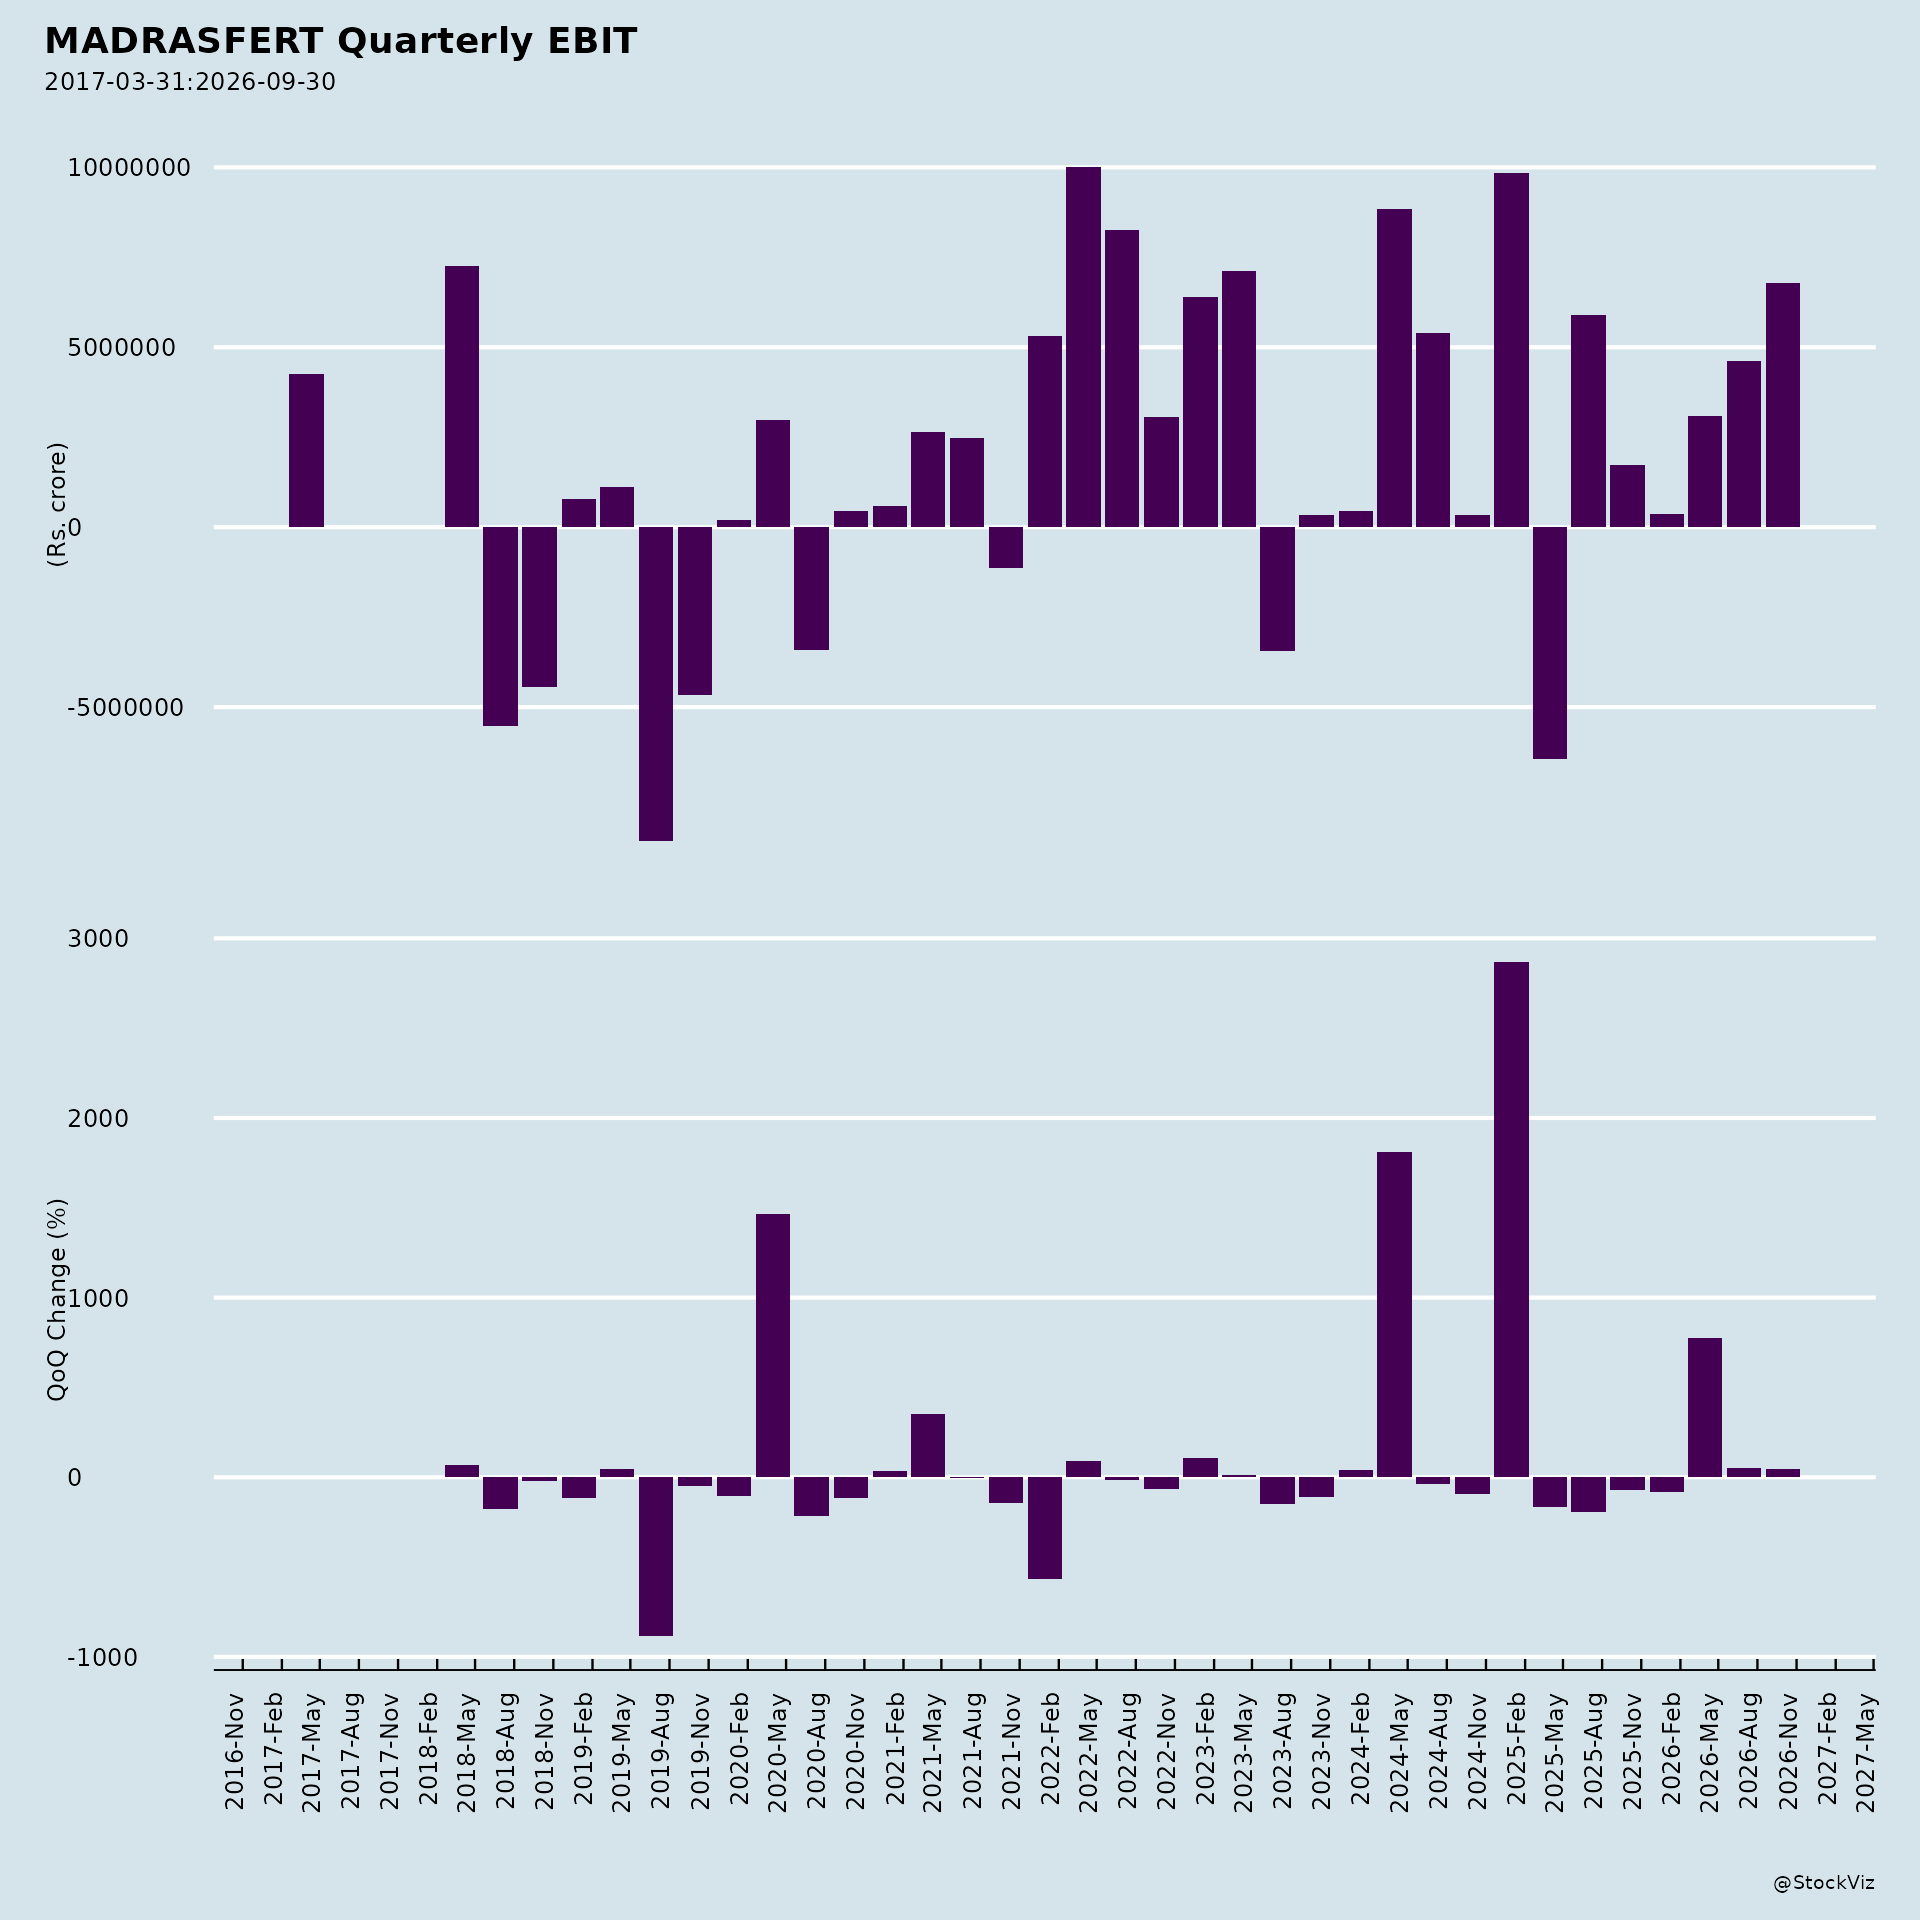
Against this, observed performance for FY 2025-26 shows a mixed picture. Madras Fertilizers achieved a net profit of Rs. 80.42 crores, a 25.17% increase over the previous year, which is consistent with the stated emphasis on cost optimization and operational focus. However, turnover declined to Rs. 2,300.35 crores, indicating that profitability improved even as top-line performance weakened. The company’s paid-up equity share capital stands at Rs. 162.14 crores. No dividend is proposed due to accumulated losses, and the default on Government of India loan repayments totaling Rs. 1,554.53 crores remains a material constraint on the balance sheet, tempering the otherwise positive demand and industry narrative.
CNBC-TV18: ratings, targets and commentary
No recorded CNBC-TV18 statements for this ticker.
Management comments
No recorded management comments with an explicit designation and affiliation for this ticker.
Copyright © 2023 SAS Data Analytics Pvt. Ltd. All rights reserved.