LOTUSDEV
Equity Metrics
November 18, 2026
Sri Lotus Developers and Realty Limited
Residential Commercial Projects
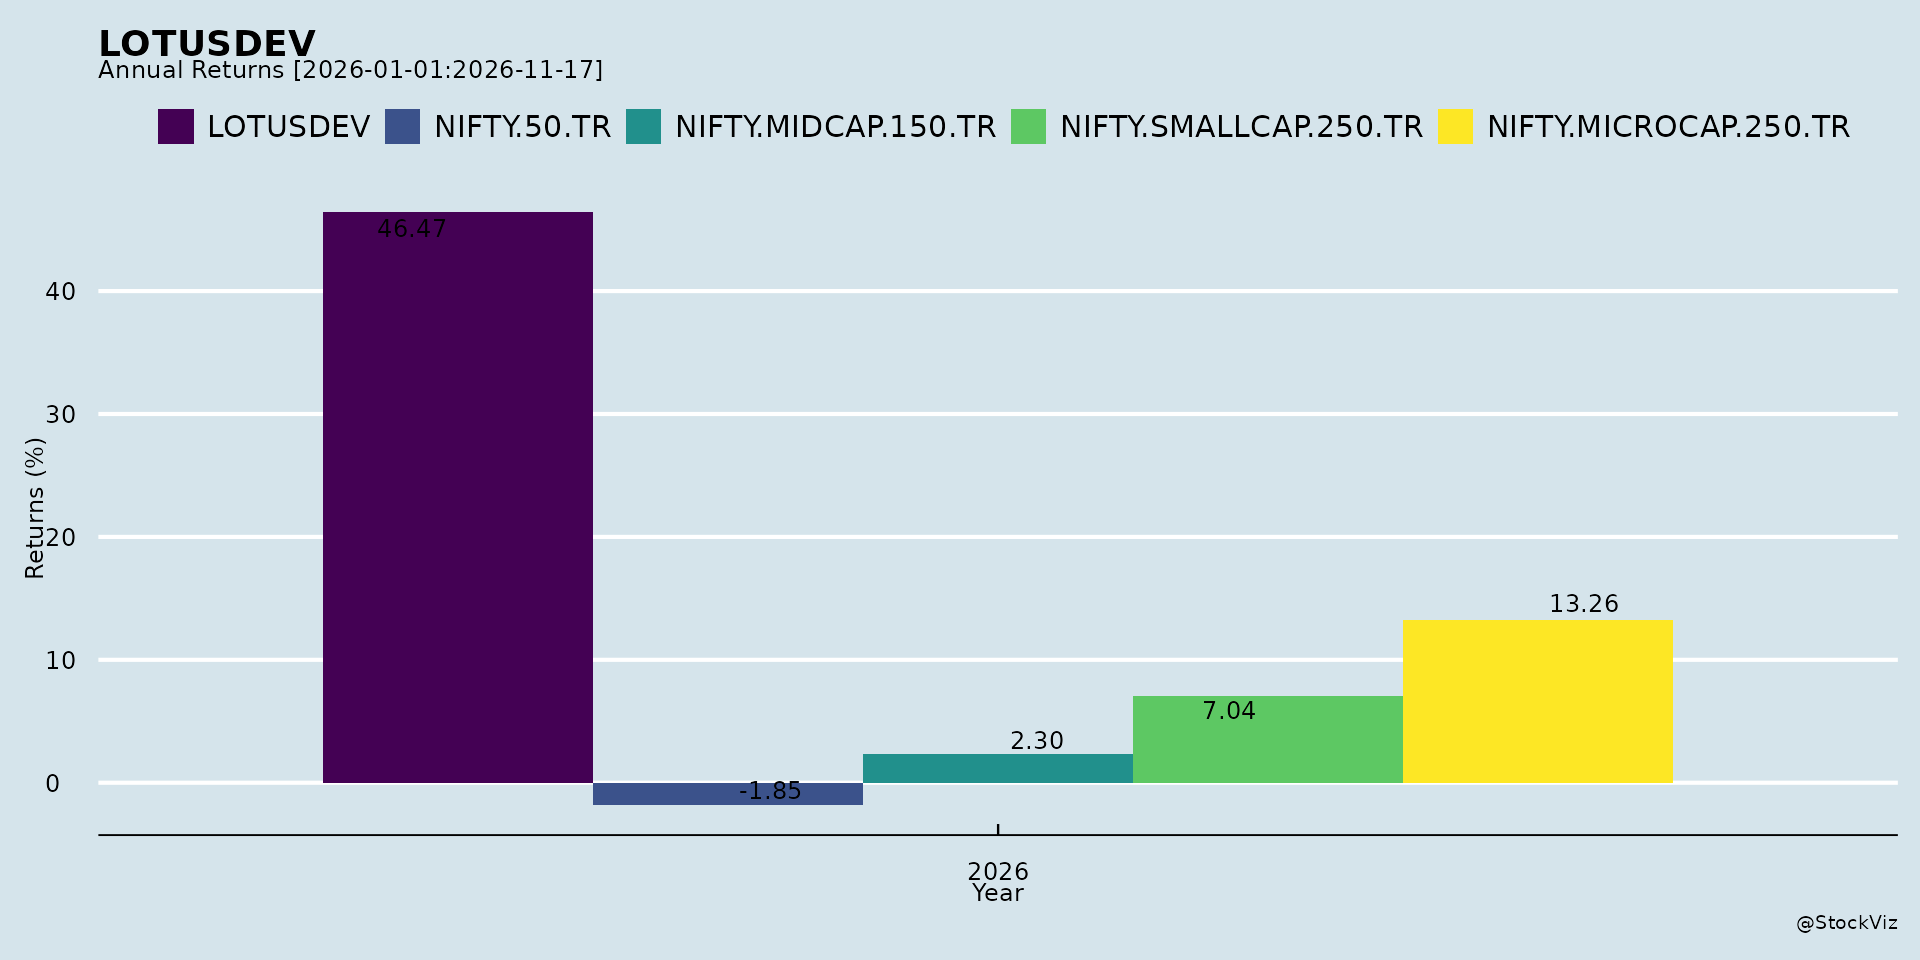
Annual Returns

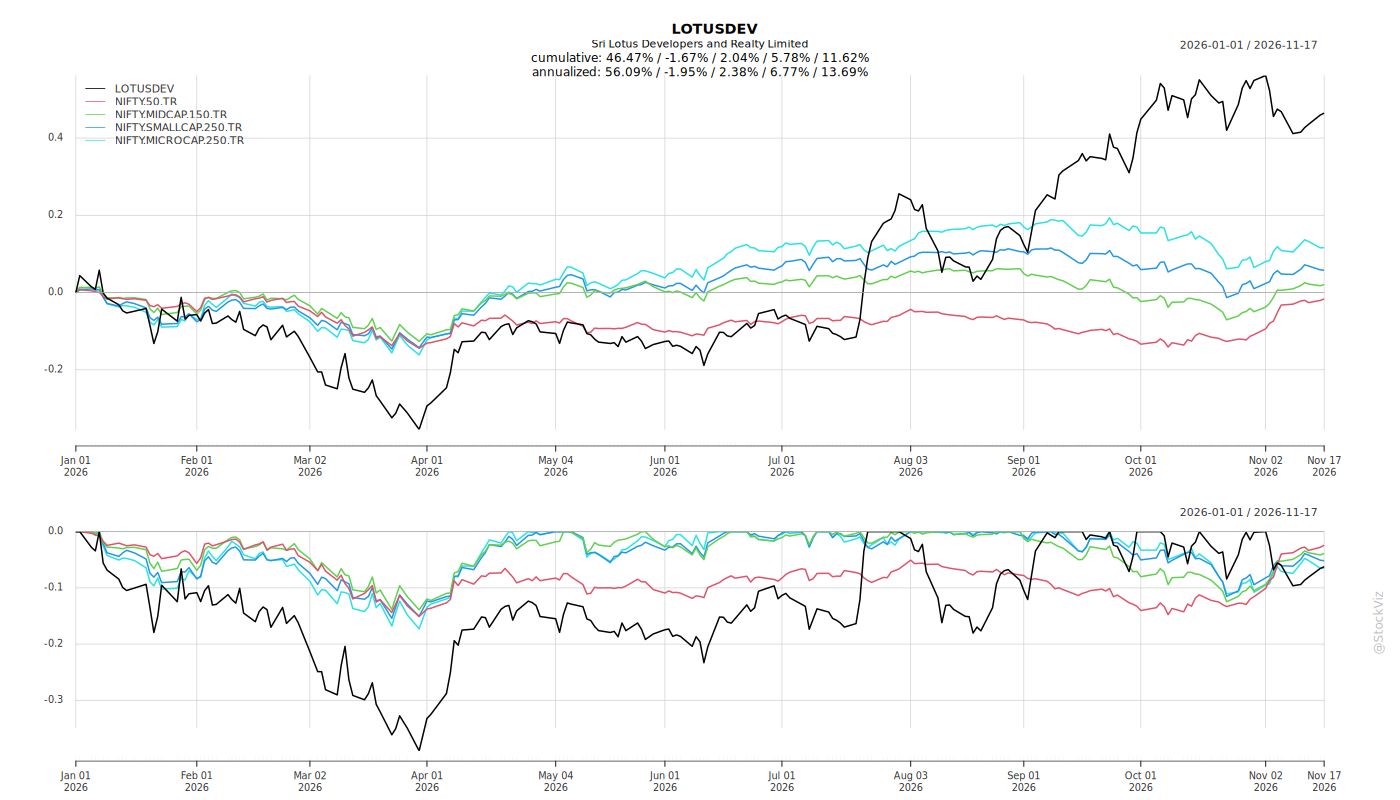
Cumulative Returns and Drawdowns
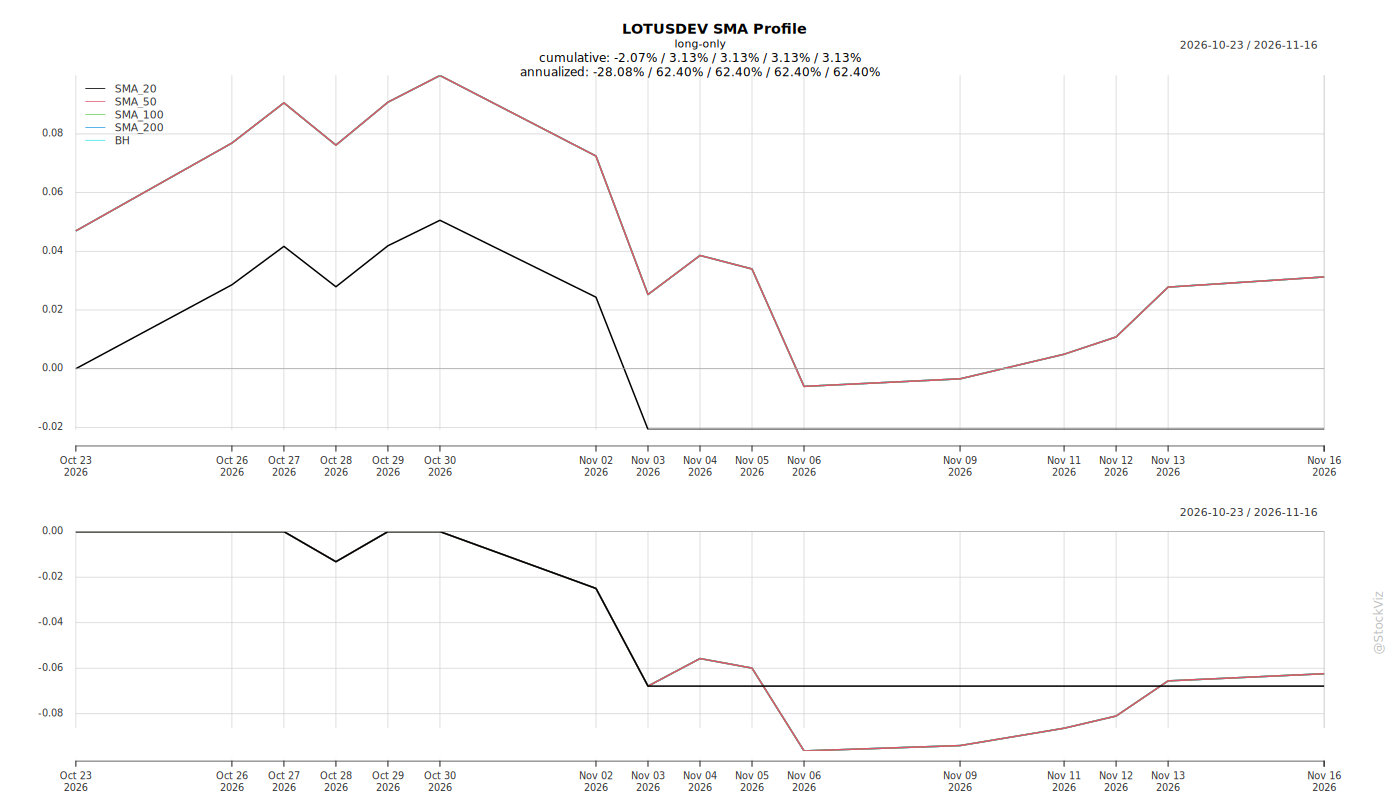
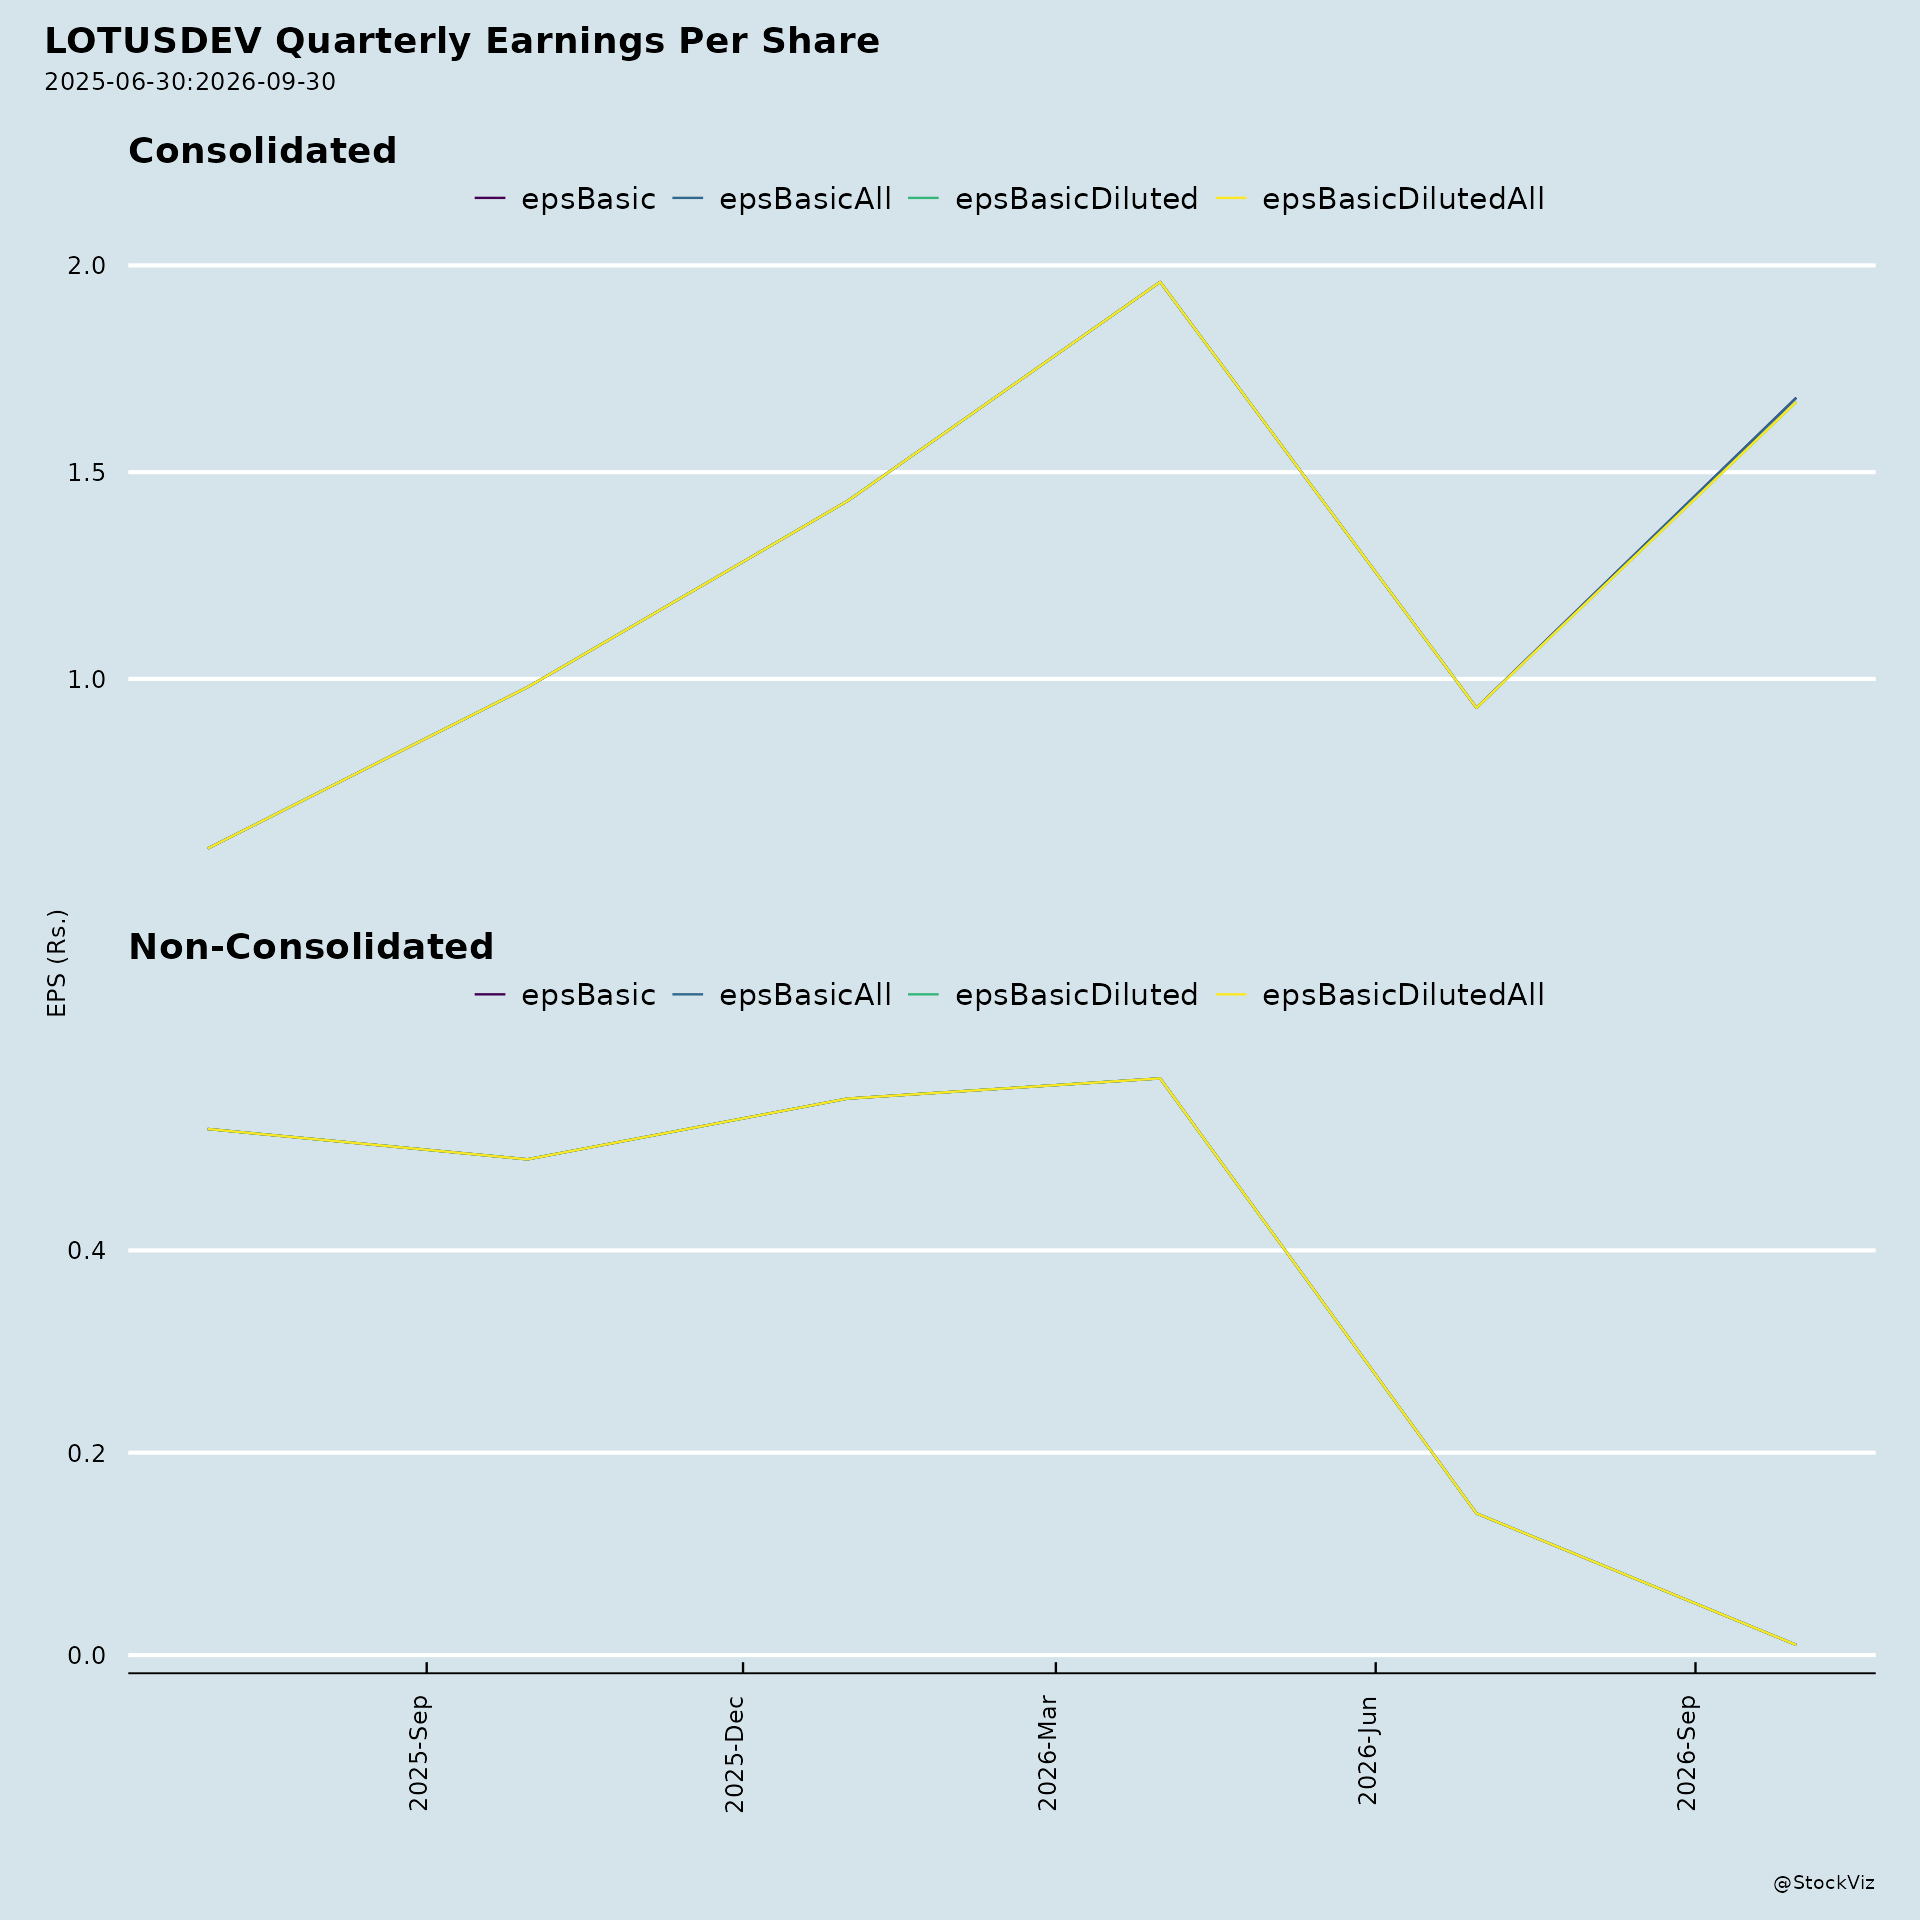
Fundamentals
Ownership
Margined
AI Summary
asof: 2026-09-17
Sri Lotus Developers & Realty Limited — Recent Developments
1. Headwinds and Challenges
- The company operates in a competitive real estate market, and its forward-looking statements acknowledge risks tied to the performance of the Indian and international economies, industry performance, competition, and its ability to successfully implement its strategy.
- Execution and expansion carry inherent uncertainty, including risks related to future growth and expansion levels, technological changes, and changes in revenue, income, or cash flows.
- The Shivaji Park Beach Front redevelopment project is not immediate: commencement is expected only by the end of FY28 or Q1 FY29, with completion targeted approximately 3 to 3.5 years from commencement, implying a long gestation period before revenue realization.
- The promoter stake sale of 97,70,000 equity shares (2.00% of total issued and paid-up equity share capital) on September 10, 2026, reduced promoter and promoter group shareholding from 81.87% to 79.87%, and was undertaken to comply with minimum public shareholding requirements.
2. Tailwinds and Growth Prospects
- Appointment as preferred developer for a residential redevelopment project at Shivaji Park Beach Front, Dadar, with an estimated GDV of INR 550 Crs and saleable area of approximately 44,000 sq. ft. The project offers unobstructed Arabian Sea views on an iconic Mumbai stretch.
- The company describes growing strength and recognition of the Lotus Developers brand and increasing acceptance among housing societies in newer, high-value micro-markets across Mumbai.
- Redevelopment is described as becoming the preferred path for ageing housing societies in prime neighbourhoods, supporting demand for the company’s core focus area.
- The company is consciously expanding into newer micro-markets, seeking distinctive addresses (unobstructed sea views or green outlooks) that command premium pricing.
- Portfolio scale: 4 completed projects aggregating over 4.2 lakh sq. ft. of carpet area, with 8 ongoing and 15 upcoming developments covering ~49.6 lakh sq. ft. of carpet area and ~39.6 lakh sq. ft. of saleable area.
- Presence in Juhu and Andheri West, with expansion into South and Central Mumbai, Bandra, and Versova.
- Growth prospects cited include a strong launch pipeline for the remainder of FY27 with multiple premium residential developments, expansion in the GIFT City Area with a flagship ultra-luxury mixed-use project, robust business momentum, continued healthy demand in the luxury and ultra-luxury residential portfolio, and expected free cashflow of ~INR 8,400 Crs from ongoing, completed, and upcoming projects.
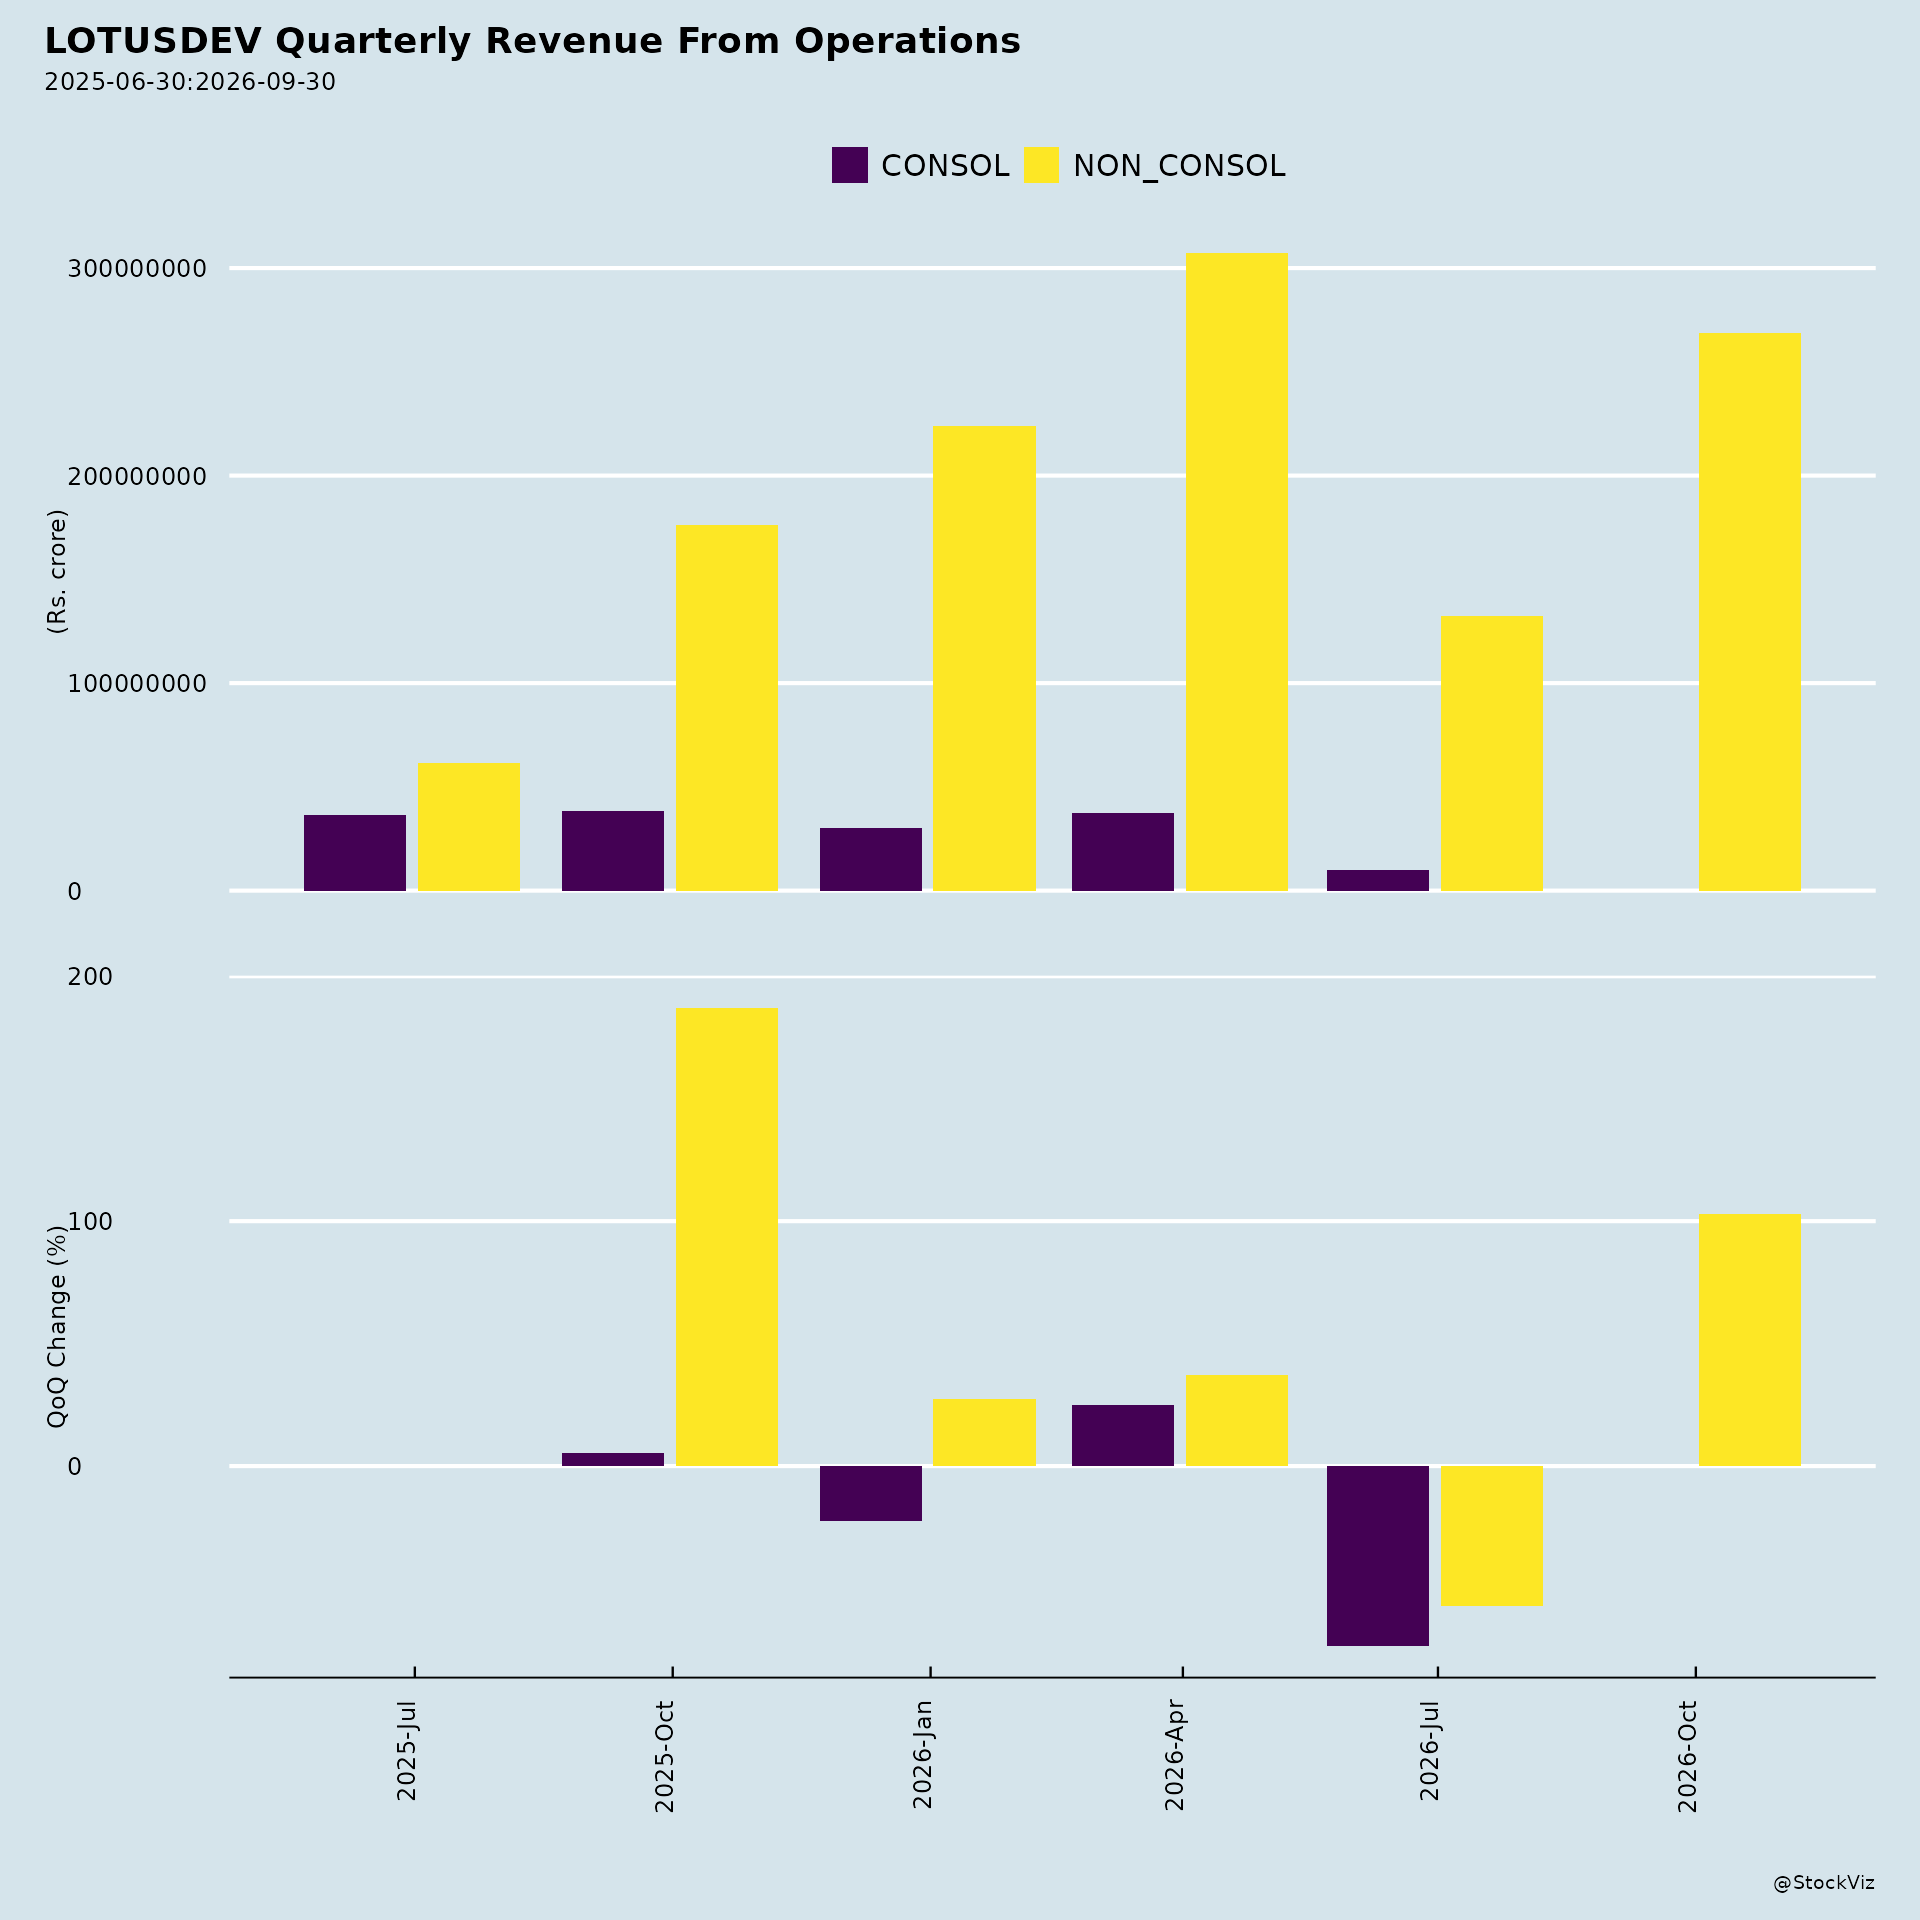
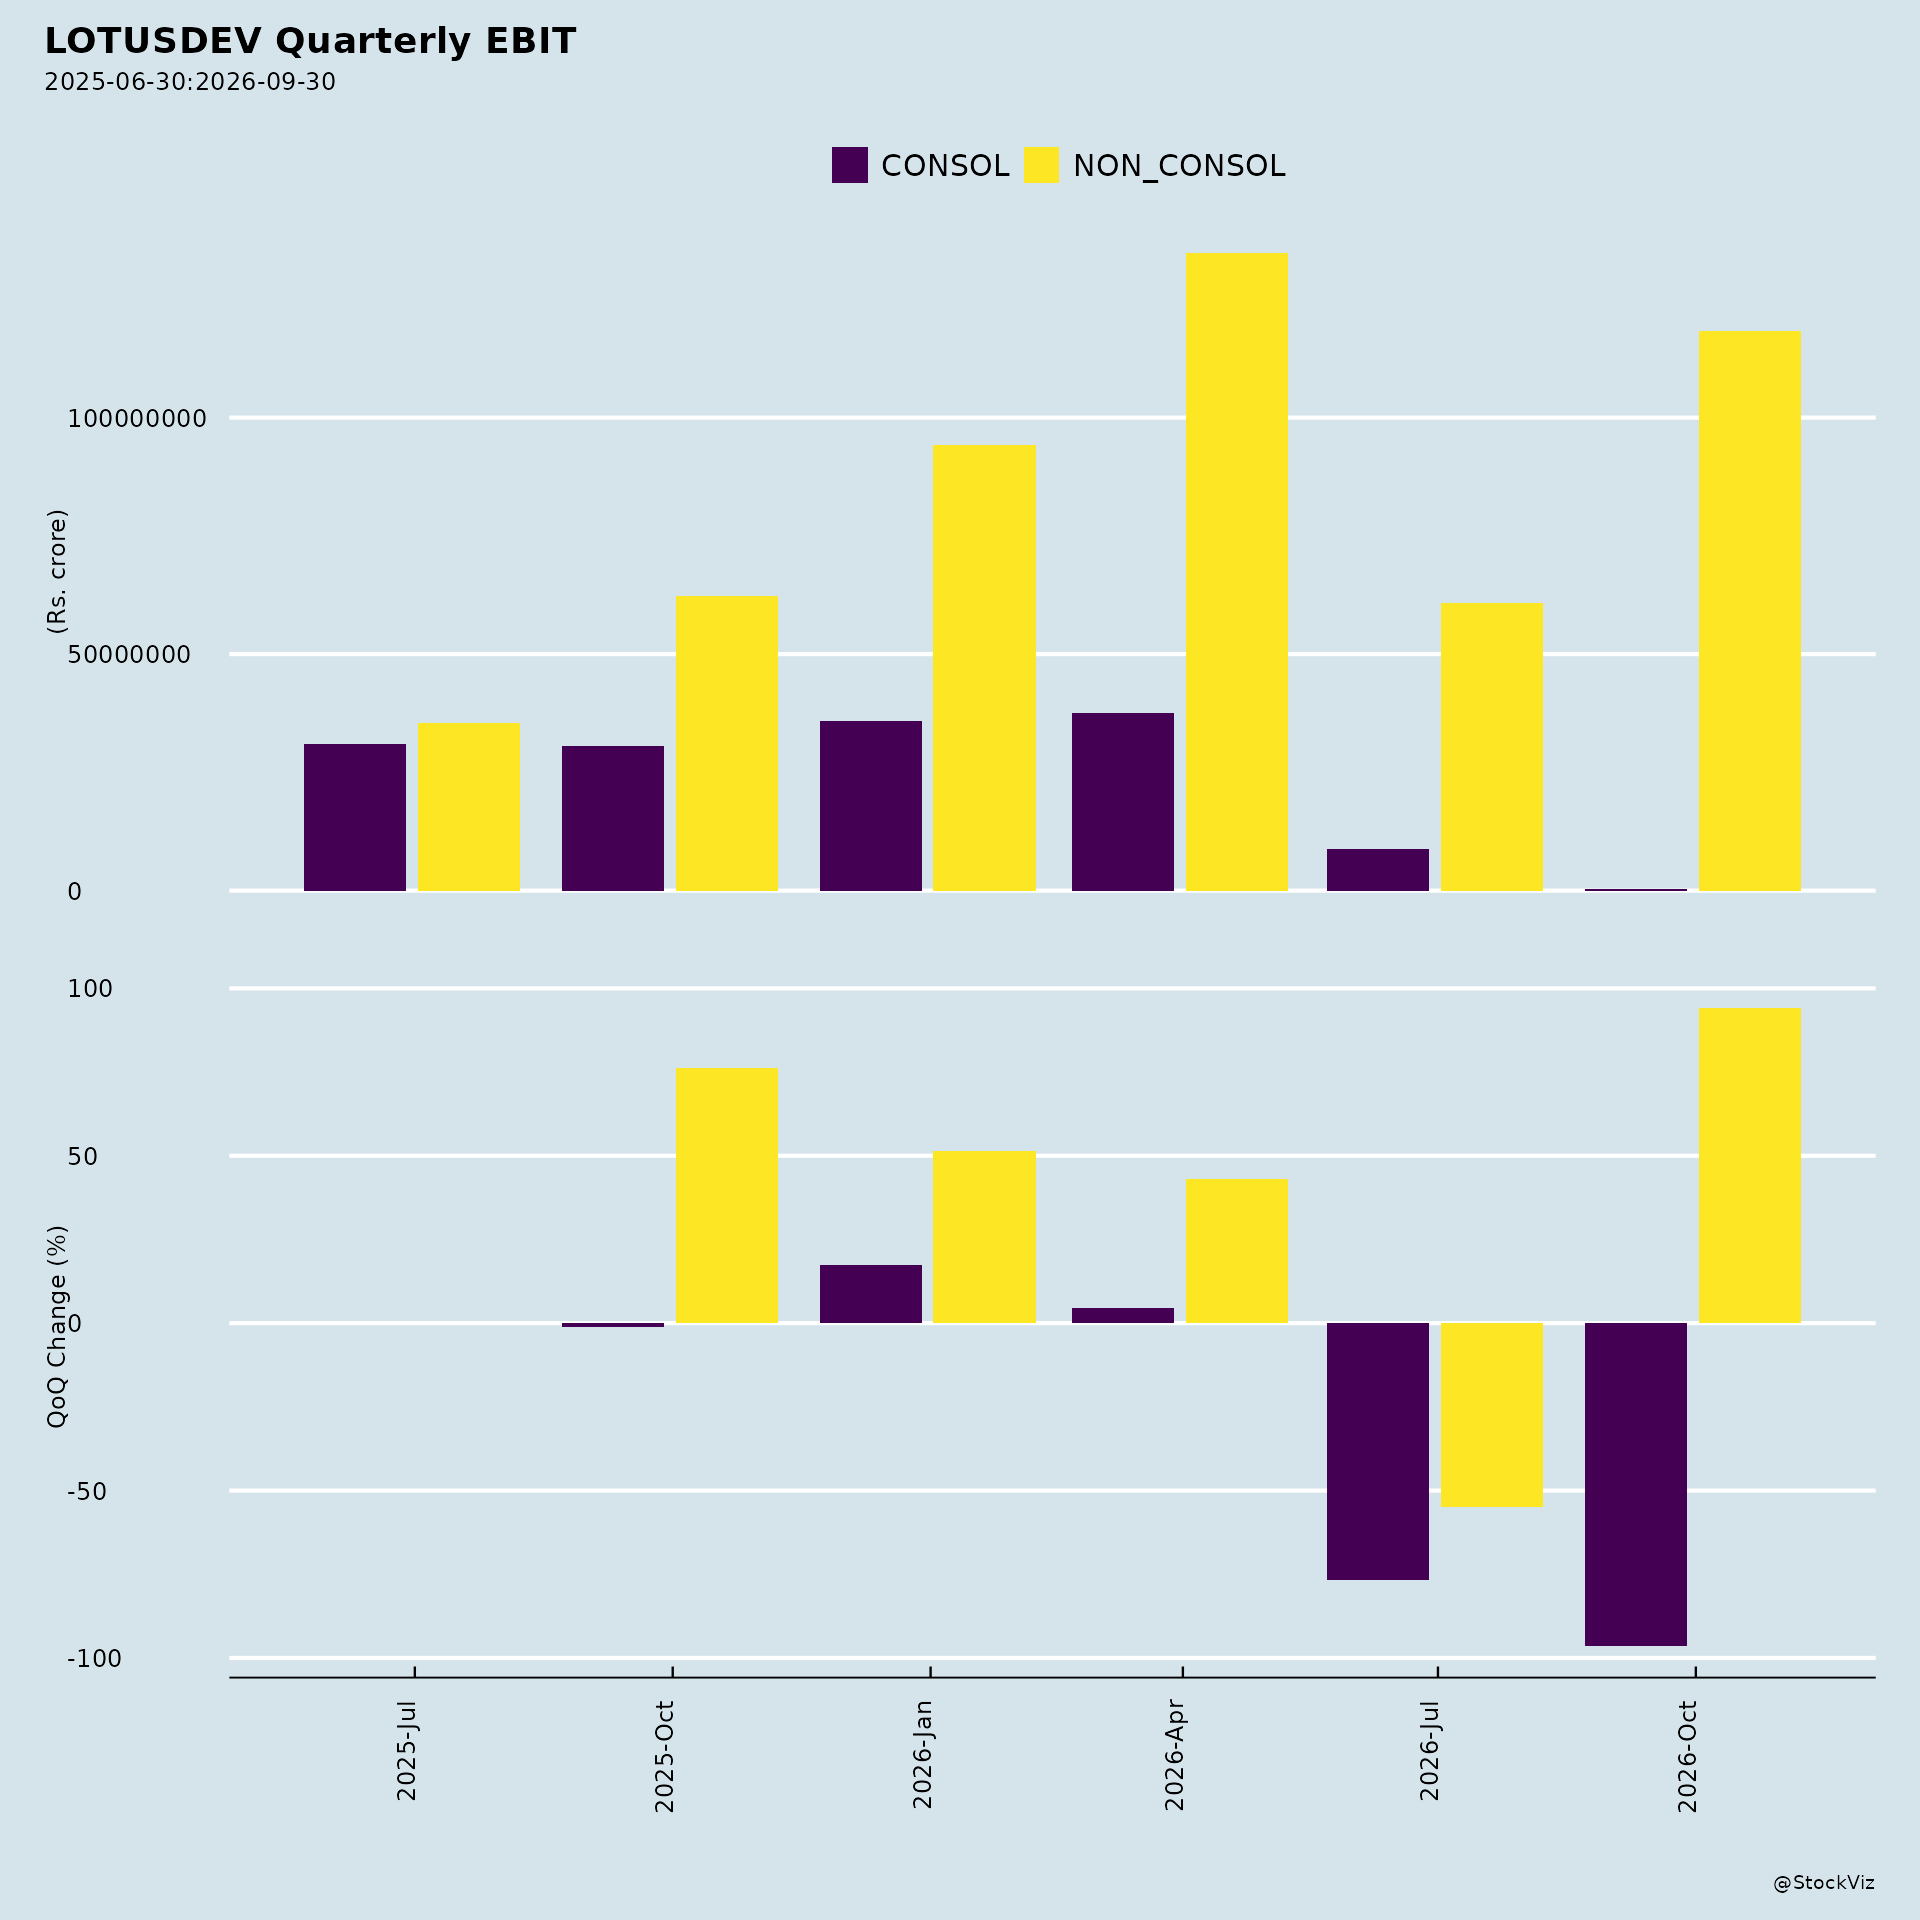
- Q1 FY27 performance: pre-sales increased 567% YoY to INR 409 Crs, revenue reached INR 132 Crs, EBITDA was INR 48 Crs (36.4% margin), and Profit After Tax was INR 46 Crs. Net Cash Balance of INR 623 Crs (Total Cash of INR 777 Crs; debt outstanding of INR 153 Crs) as of June 2026. The company raised INR 792 Crs through an IPO that was oversubscribed 74 times.
3. Key Risks
- Forward-looking statements are subject to known and unknown risks, uncertainties, and assumptions that are difficult to predict, including economic performance (Indian and international), industry performance, competition, strategy implementation, future growth and expansion levels, technological changes, and changes in revenue, income, or cash flows.
- Actual results may differ materially from those anticipated in forward-looking statements, and the company assumes no obligation to update them.
- Project timelines for the Shivaji Park Beach Front redevelopment are distant (commencement end of FY28 or Q1 FY29), creating execution and timing risk.
- The promoter share sale to meet minimum public shareholding requirements altered the shareholding structure, with promoter and promoter group holding declining to 79.87%.
4. Management Guidance vs. Observed Business Performance
- Management guidance for FY27 includes pre-sales of ~INR 1,800–2,000 Crs, revenue growth of ~55–60% YoY, and profit after tax growth of ~55–60% YoY.
- Observed Q1 FY27 performance: pre-sales of INR 409 Crs (up 567% YoY), revenue of INR 132 Crs, EBITDA of INR 48 Crs (36.4% margin), and PAT of INR 46 Crs. The company also holds a Net Cash Balance of INR 623 Crs as of June 2026.
- The company has proposed a final dividend of 50% (Rs. 0.50 per equity share of face value Re. 1) for FY 2025-26, with a record date of September 25, 2026, and an interim dividend of 30% (Rs. 0.30 per share) for FY 2026-27 with a record date of September 11, 2026.
- Corporate governance items: the 12th Annual General Meeting is scheduled for September 29, 2026, at 11:30 A.M. via video conferencing. Proposed items include appointment of Mr. Paarth Deepak Chheda as Executive Director for a 5-year term effective October 01, 2026, re-appointment of Ms. Ashka Anand Pandit, and ratification of cost auditor remuneration of INR 60,000 for Mr. Ankit Kishore Chande for FY 2026-27.
- An investor conference (group meeting organized by Arihant Conference) is scheduled virtually for September 28, 2026, from 11:00 AM to 12:00 PM, based solely on publicly available information with no UPSI intended to be discussed.
Broker Narrative
The broker narrative evolved from a broad thematic call on Mumbai redevelopment and luxury cyclicality to a project-specific growth story centered on record pre-sales, new GDV additions, and a sturdy net-cash balance sheet. Persistent themes included MMR redevelopment potential, resilient luxury demand, and an asset-light, near-litigation-free model, now evidenced by INR4.9b net cash. What changed was the surfacing of near-term execution timing issues—three projects at basement stage delaying payment milestones and a 43% collections drop—alongside specific GIFT City approval delays. Despite strong earnings, the latest Buy call yielded a flat -0.1% actual return, showing the narrative’s price momentum faded even as fundamentals improved.
Fears that came true
- The early risk of dependence on timely regulatory approvals materialized as the GIFT City mixed-use development awaited the town-planning scheme and requisite clearances.
- The warning about execution challenges in complex redevelopment projects materialized, with three projects at the basement stage delaying construction-linked payment milestones and driving a 43% YoY collections decline alongside a flat stock return.
Optimism that failed
- The touted execution track record of completing projects consistently ahead of schedule was undermined by basement-stage delays that deferred construction-linked payment milestones at live projects.
- The promise that premium pricing and in-house execution would drive robust cash flow generation was interrupted by a 43% YoY drop in collections despite strong EBITDA and PAT growth.
Broker Timeline
5 broker calls · 2025-09-23 to 2026-10-16
CNBC-TV18: ratings, targets and commentary
No recorded CNBC-TV18 statements for this ticker.
Management comments
No recorded management comments with an explicit designation and affiliation for this ticker.
Copyright © 2023 SAS Data Analytics Pvt. Ltd. All rights reserved.