LAURUSLABS
Equity Metrics
November 18, 2026
Laurus Labs Limited
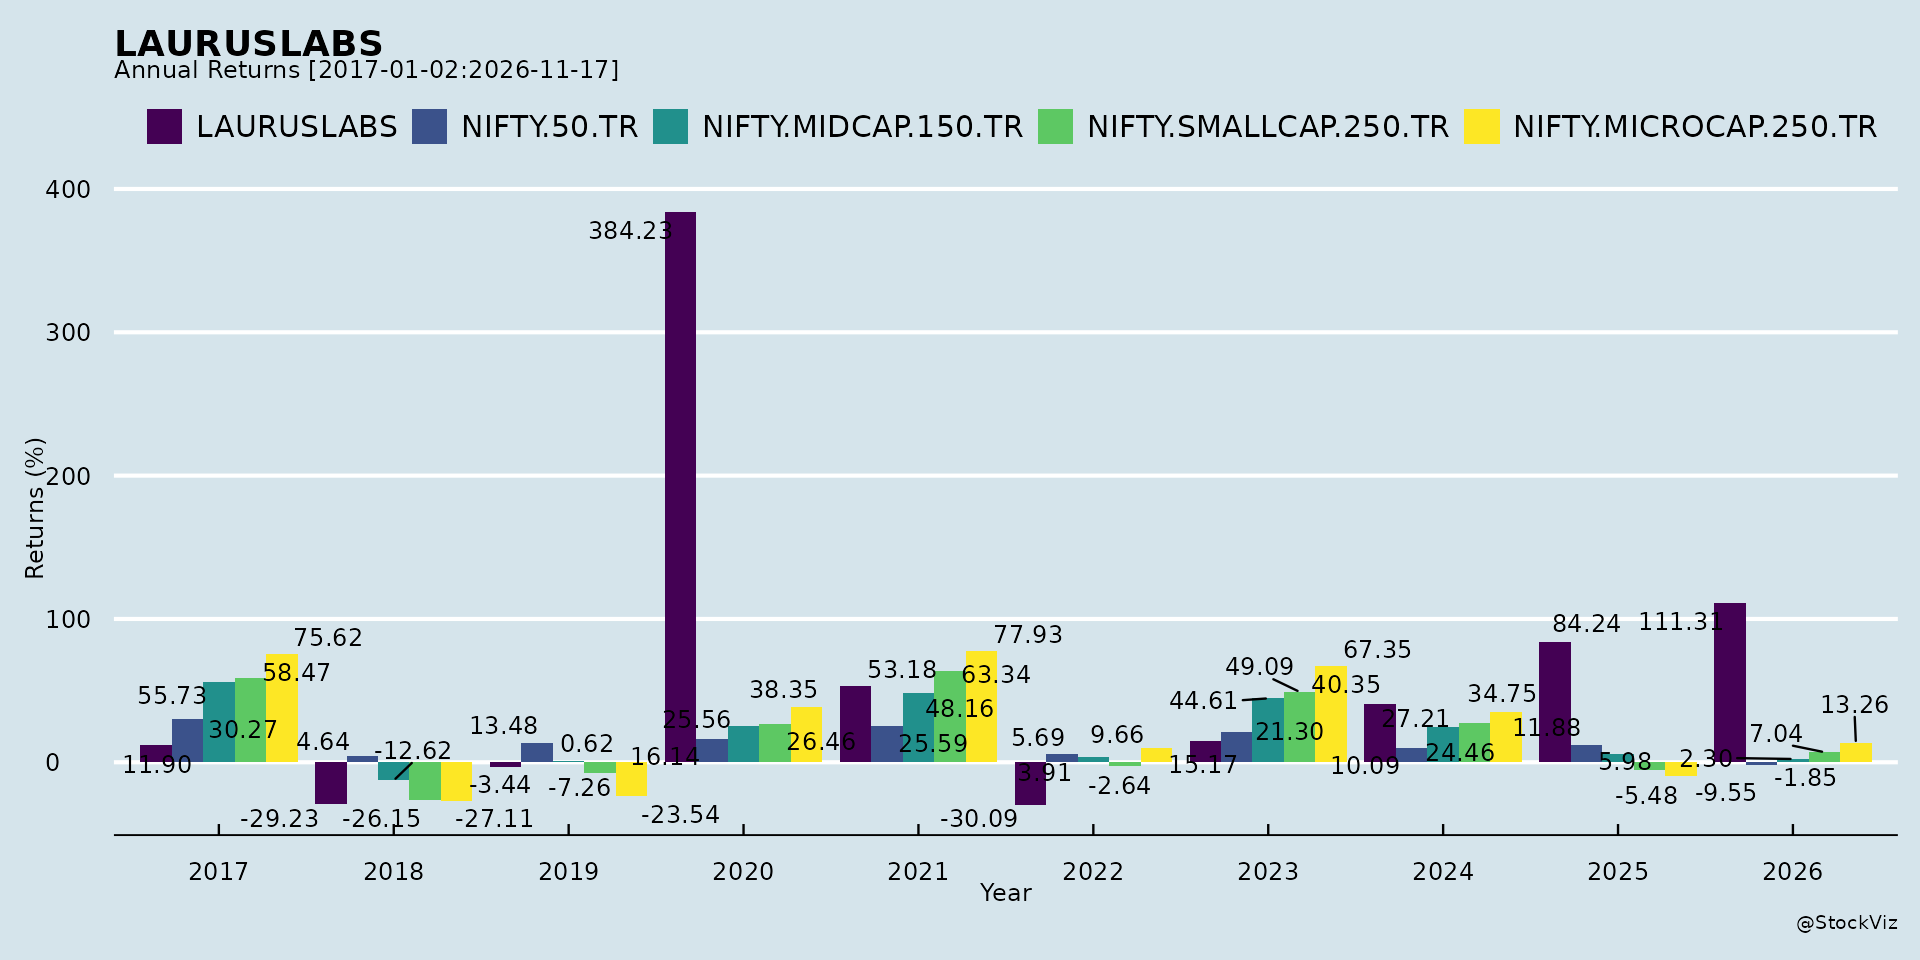
Annual Returns
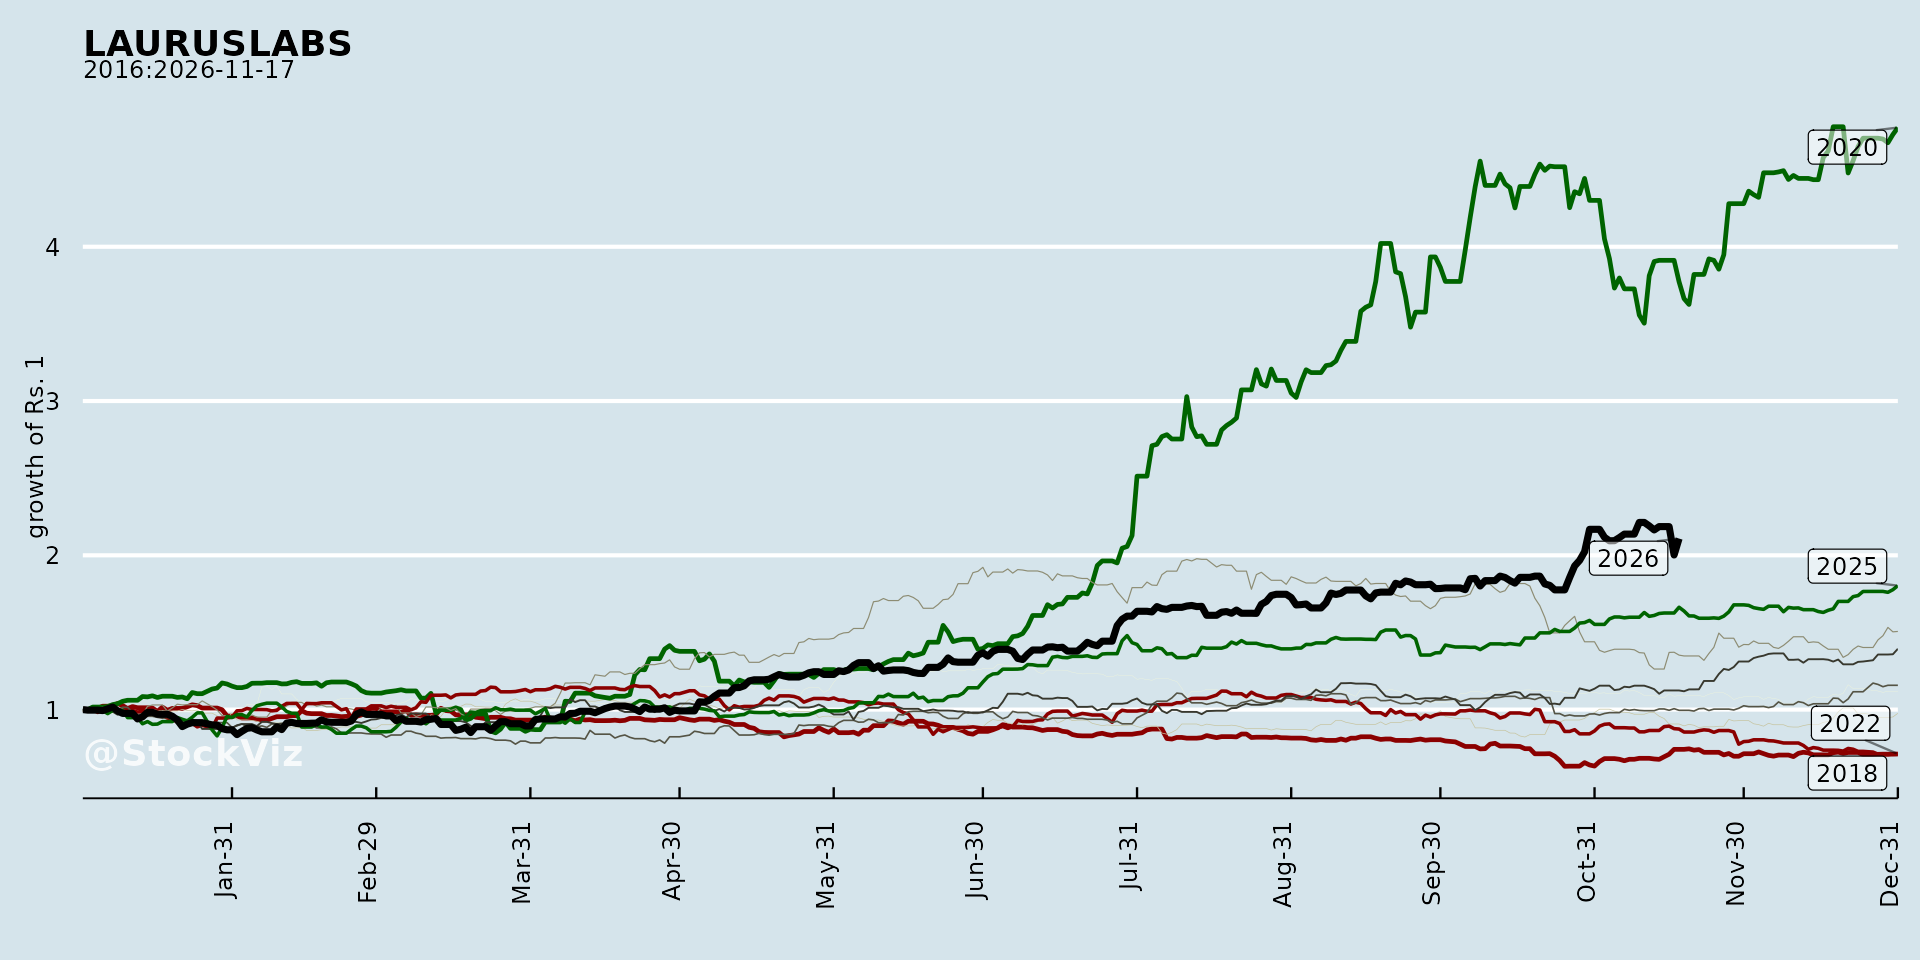
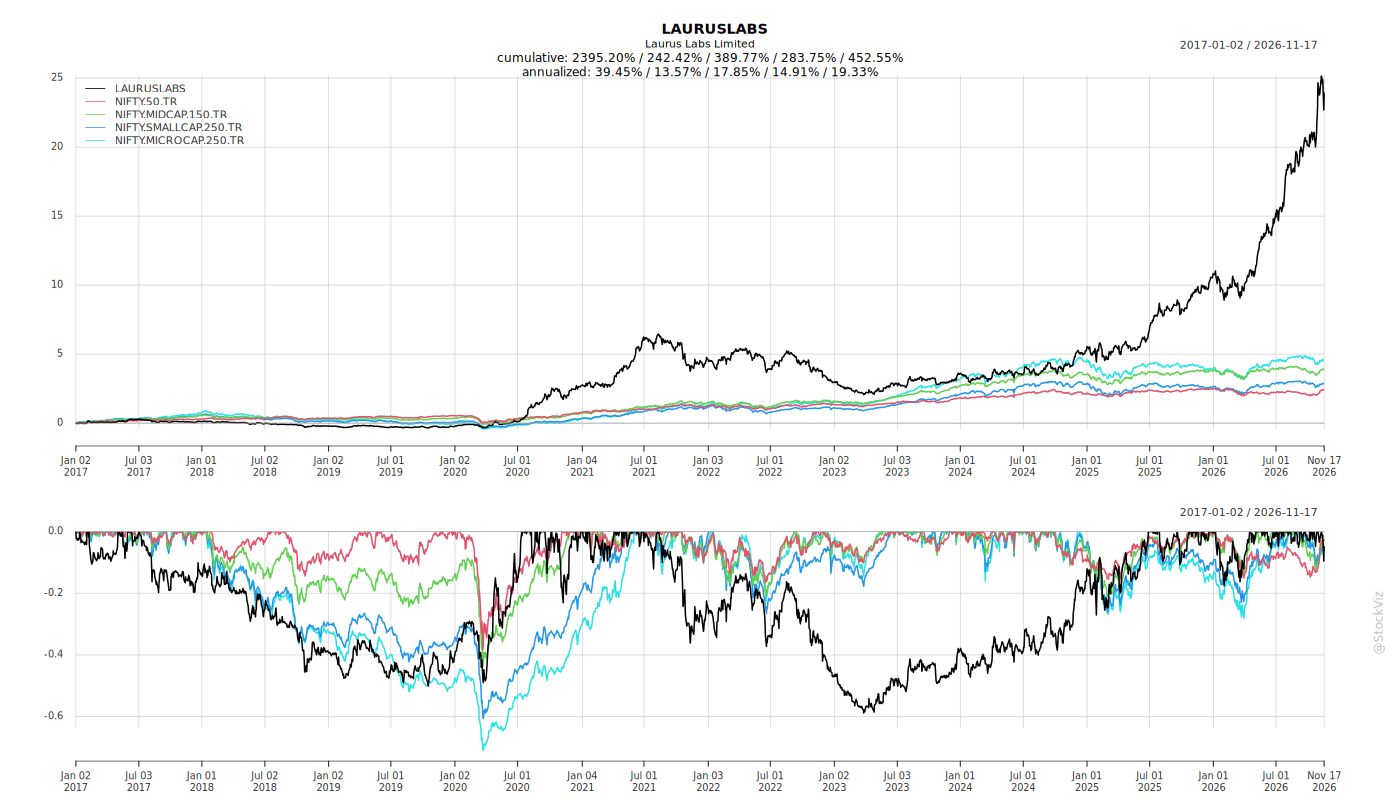
Cumulative Returns and Drawdowns
Fundamentals
Ownership
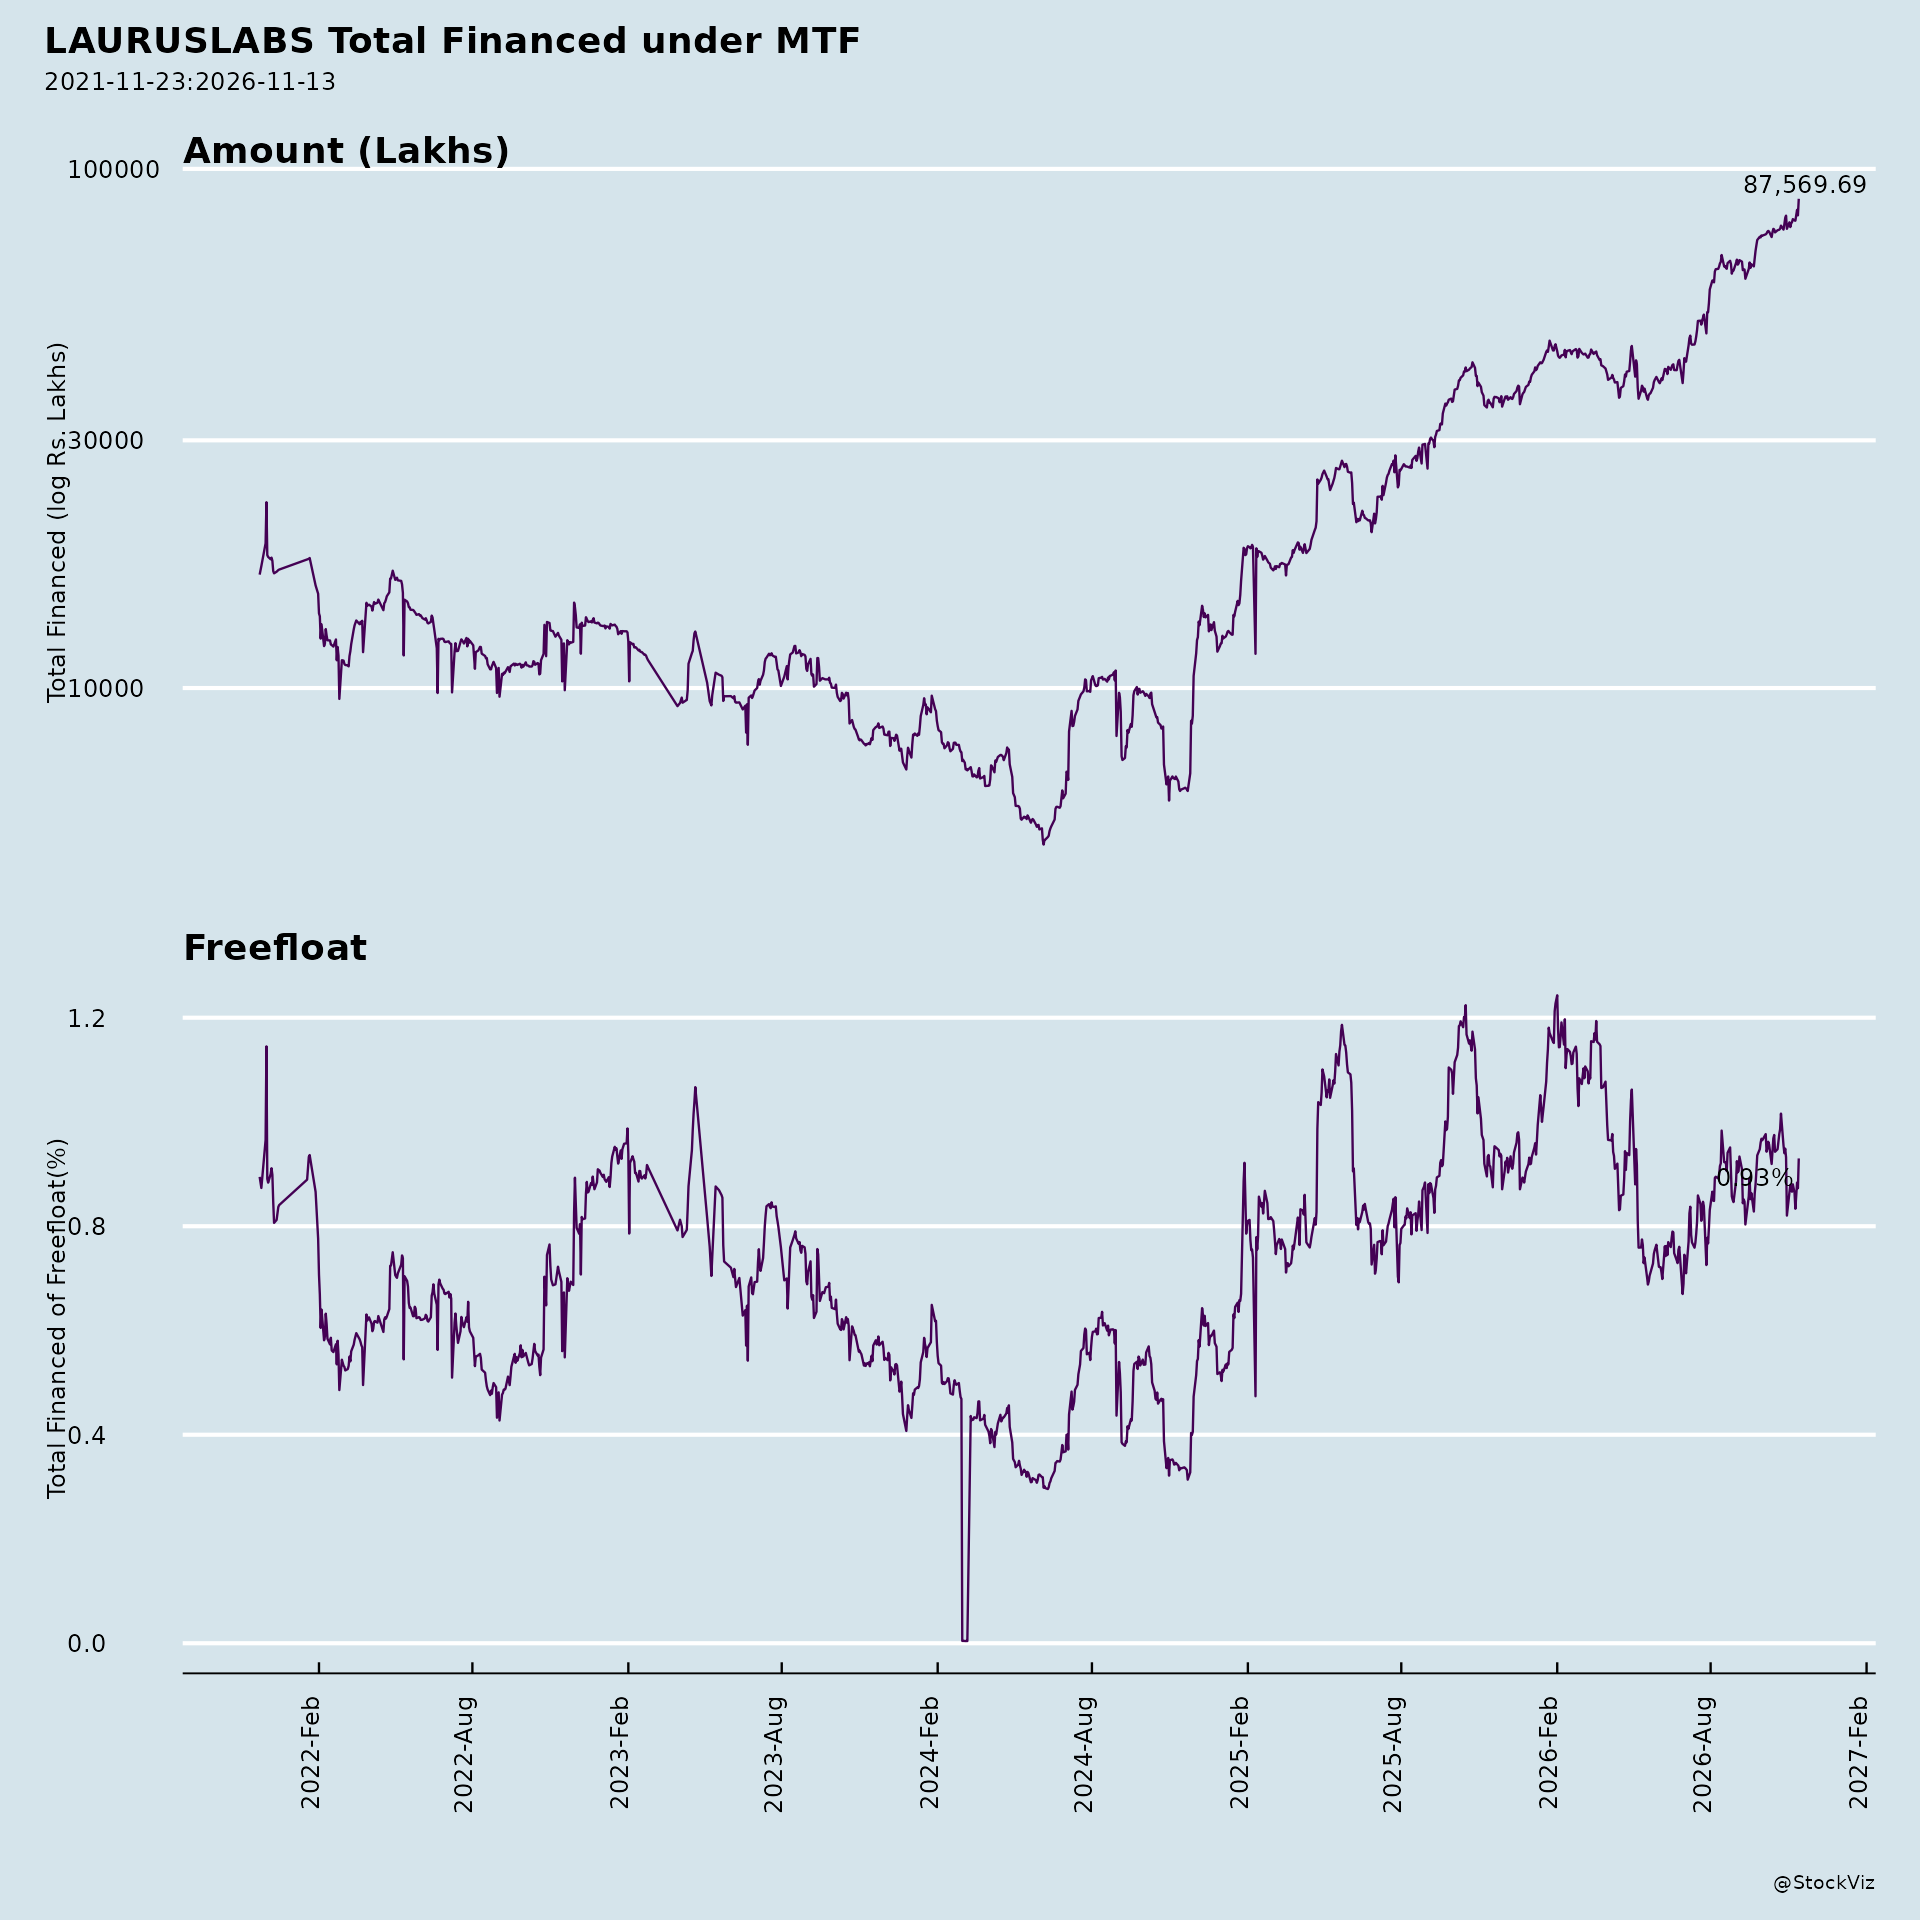
Margined
AI Summary
asof: 2026-09-14
Laurus Labs — Recent Corporate Announcements: Headwinds, Tailwinds, Risks and Guidance vs Performance
1. Headwinds and Challenges
- Macroeconomic volatility: The CFO noted that Q1 FY27’s strong operating performance was delivered “despite challenging macroeconomic volatility.”
- Global supply chain issues: The Affordable Medicines division reported that it “maintained consistent deliveries track record amid continuing global supply chain issues.”
- Modest growth in the ARV/API base: ARV revenue grew only 3% year-on-year (₹669 Cr vs ₹647 Cr), and API revenue grew 3% (₹654 Cr vs ₹637 Cr), indicating limited momentum in these legacy segments relative to the rest of the portfolio.
- Regulatory/approval dependency for the Scheme: The Composite Scheme of Arrangement (demerger of the Identified Business Undertaking of Laurus Synthesis Private Limited into Sriam Labs Private Limited and amalgamation of the Remaining Undertaking into the Company) remains subject to NCLT approval. The financial results are presented without giving effect to the merger pending such approval.
- Subsidiary losses: Six subsidiaries not reviewed by the statutory auditors reflected total revenues of ₹177.14 Cr and a total net loss after tax of ₹5.96 Cr for the quarter ended June 30, 2026.
- Shareholder dissent on certain resolutions: At the 21st AGM (July 2, 2026), the resolution appointing Ms. Sutapa Banerjee as Independent Director passed with 91.65% votes in favour and 8.35% against; the resolution on remuneration to Non-Executive/Independent Directors passed with 88.86% in favour and 11.14% against; and the re-appointments of Mr. Krishna Chaitanya Chava and Mrs. Soumya Chava each saw approximately 0.71% of votes against.
2. Tailwinds and Growth Prospects
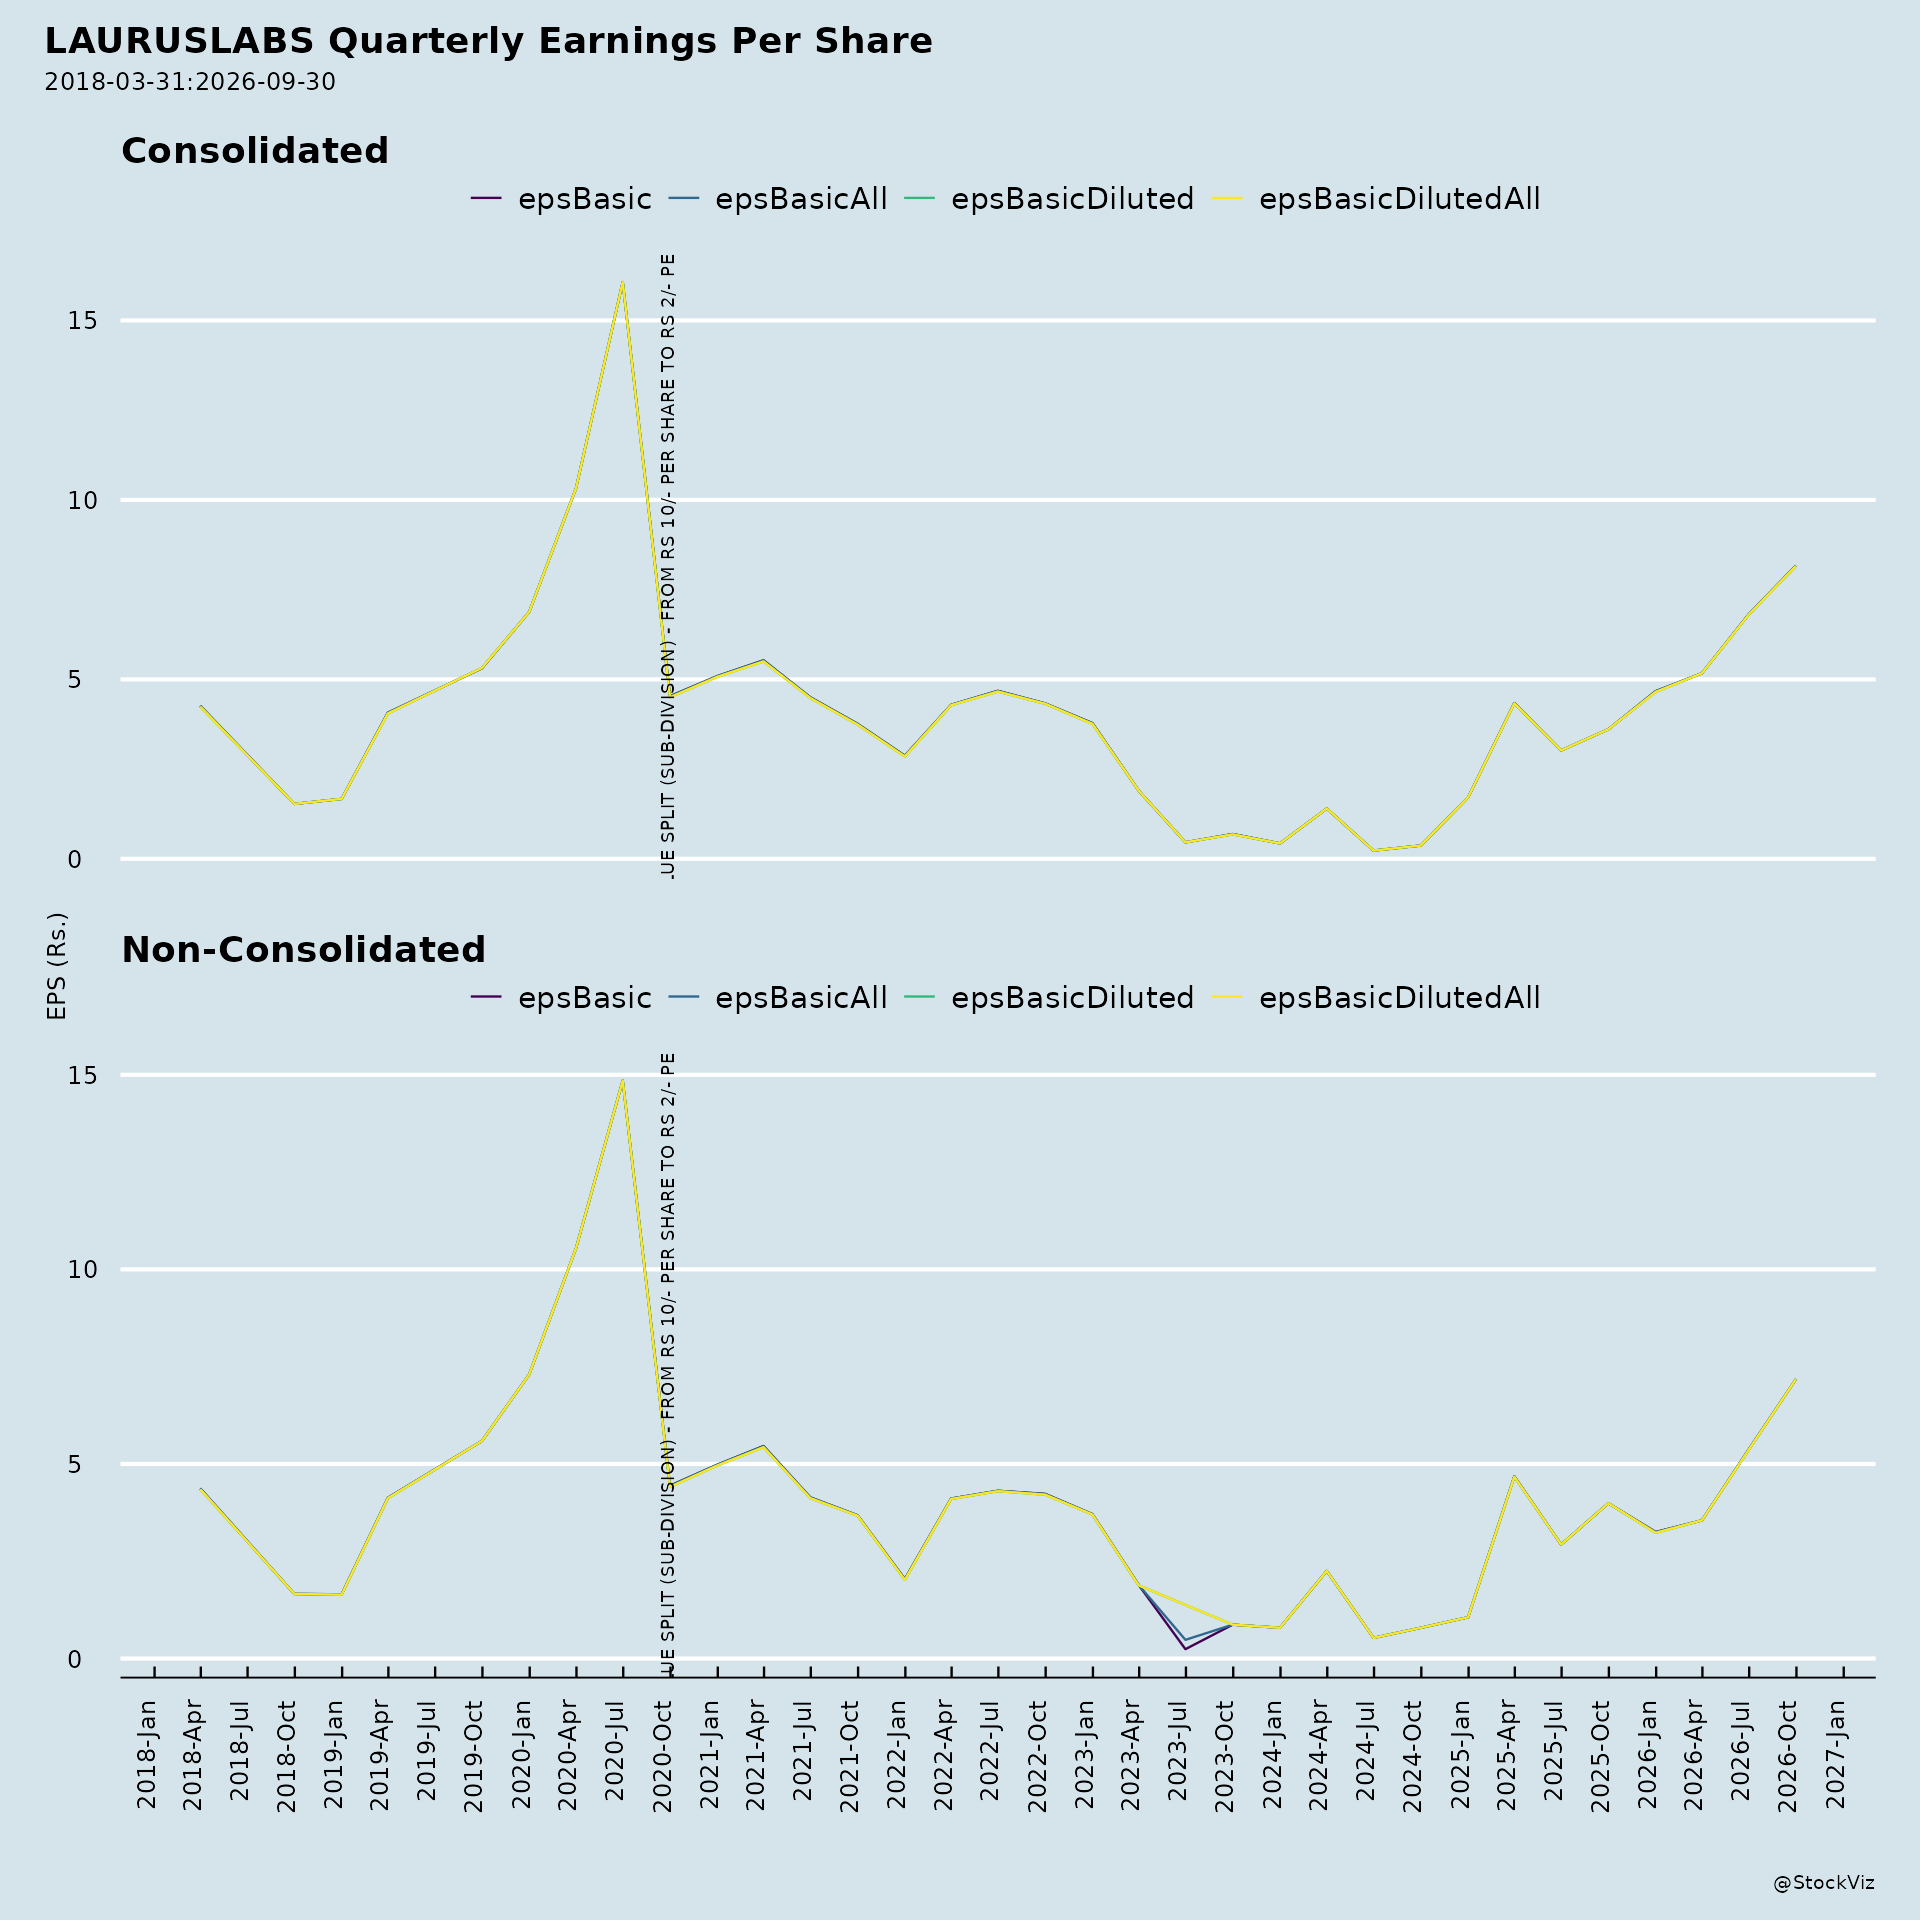
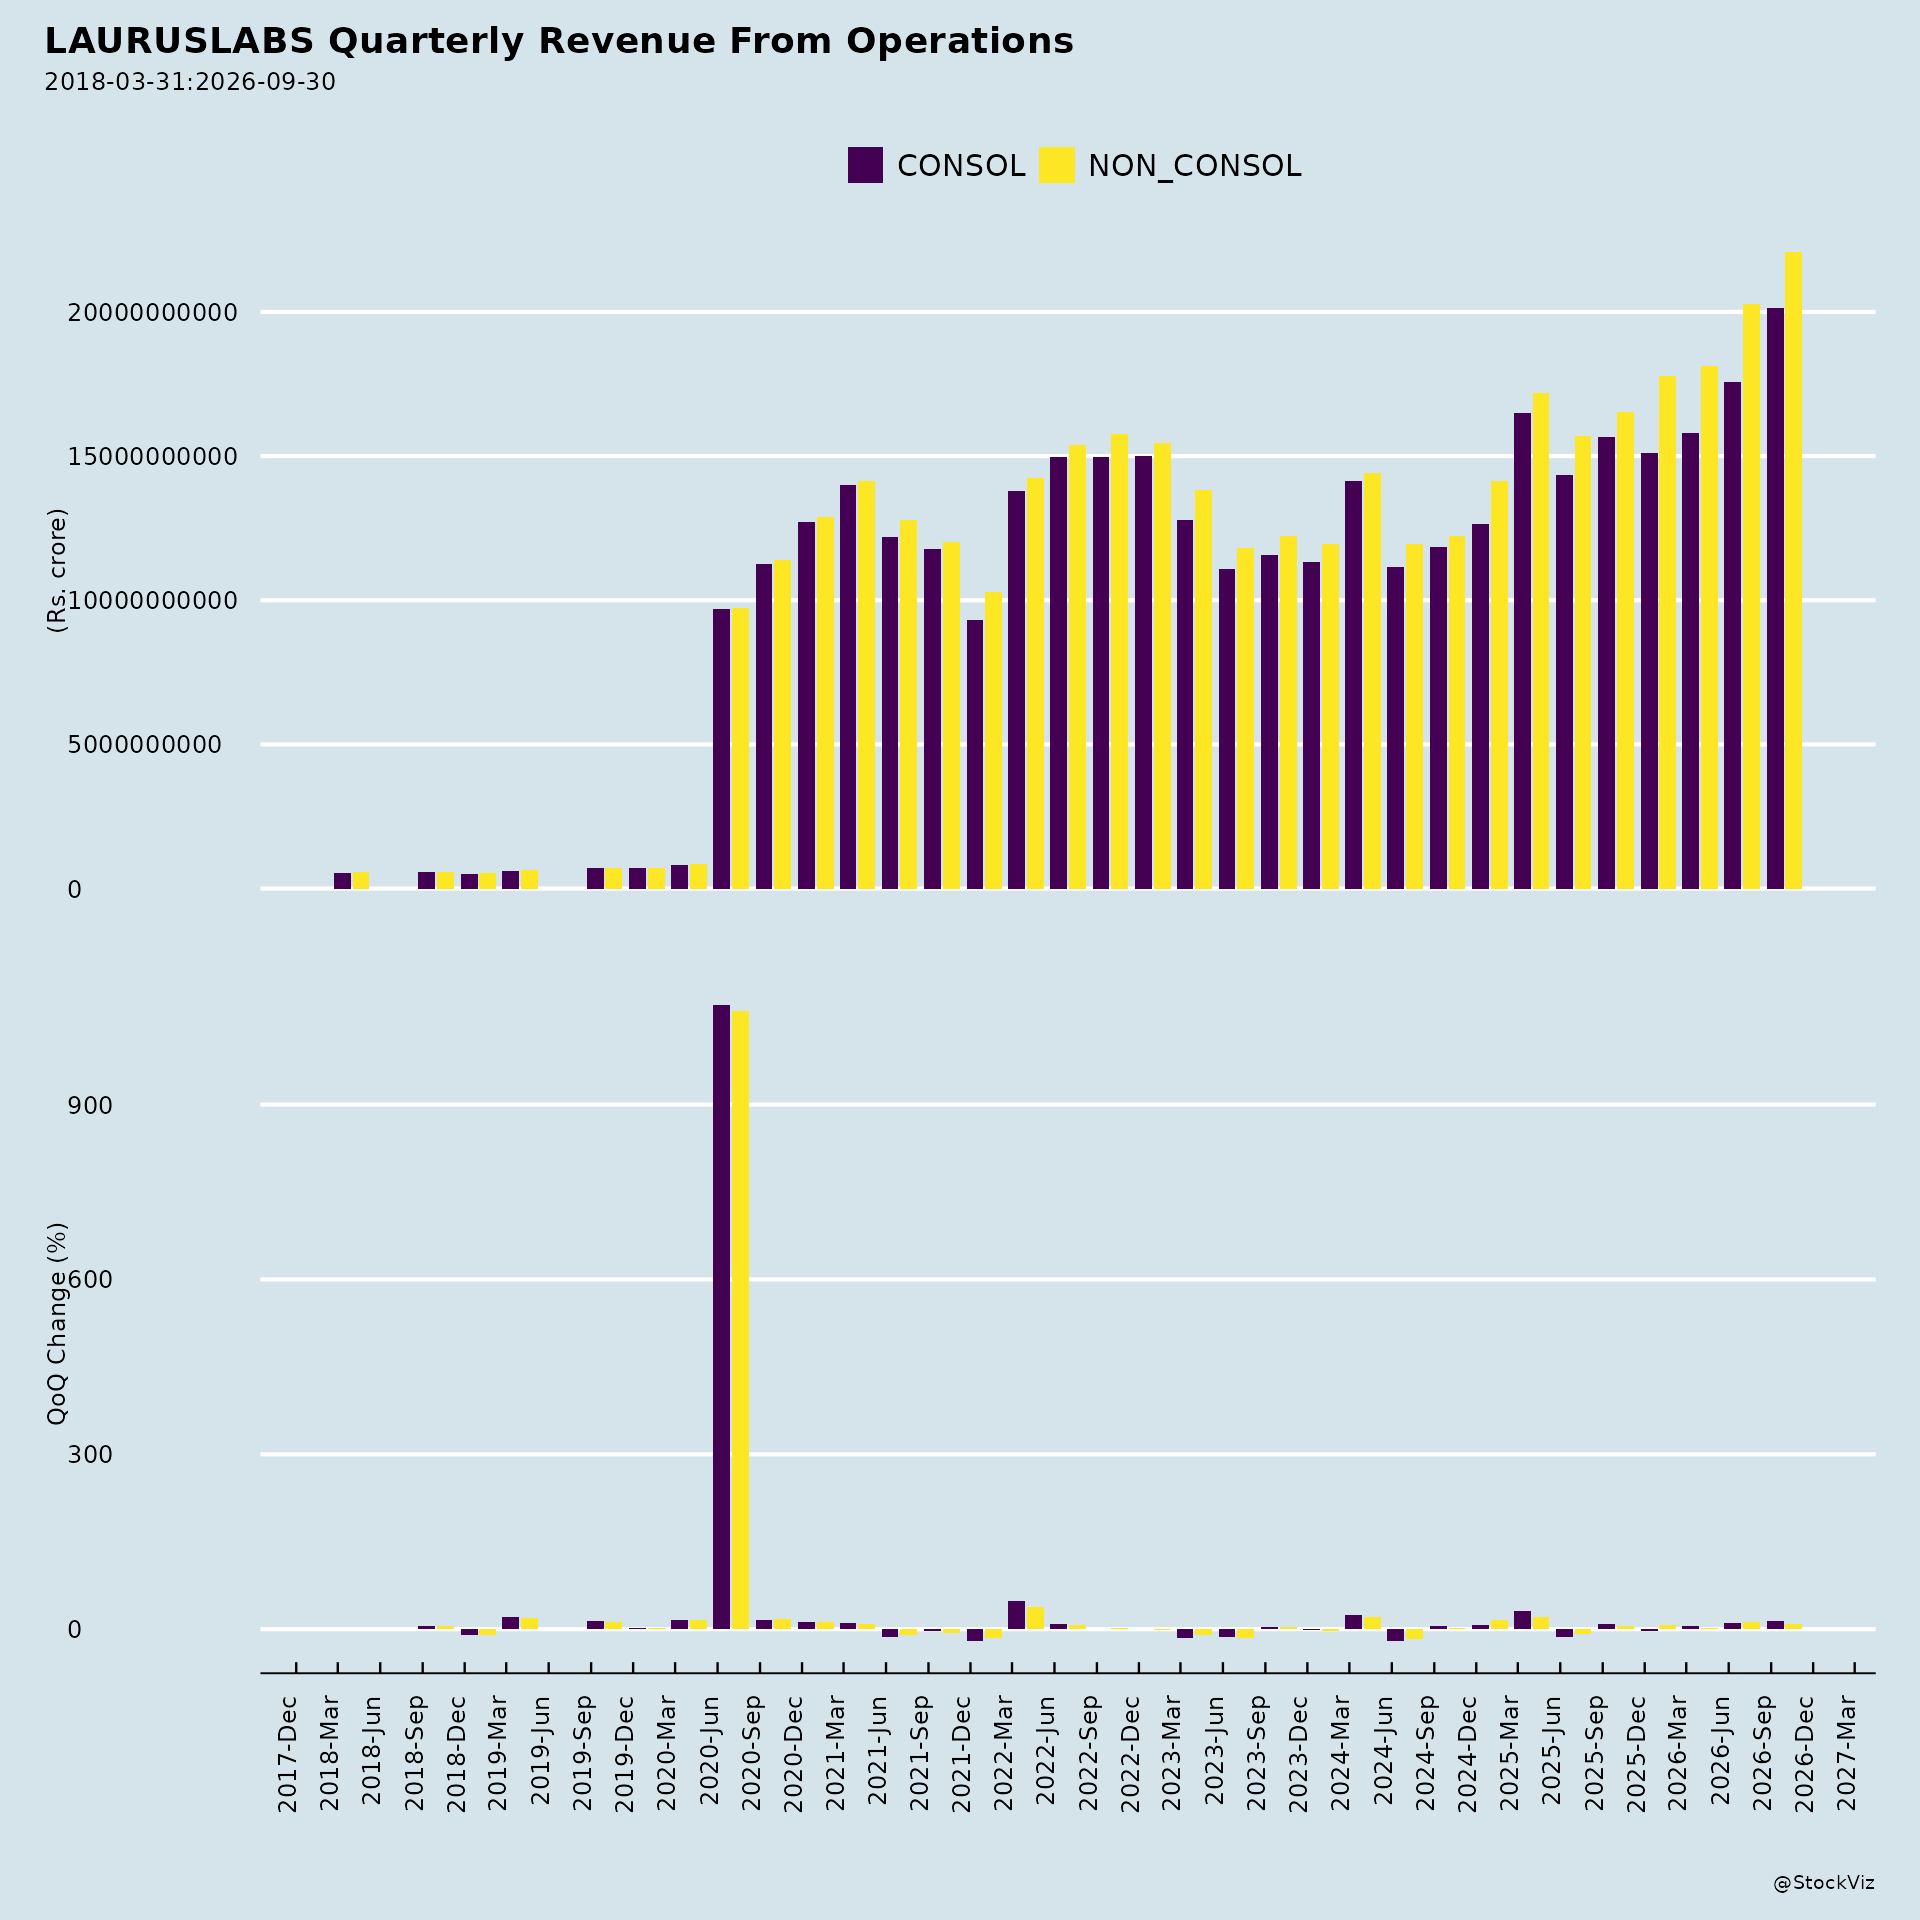
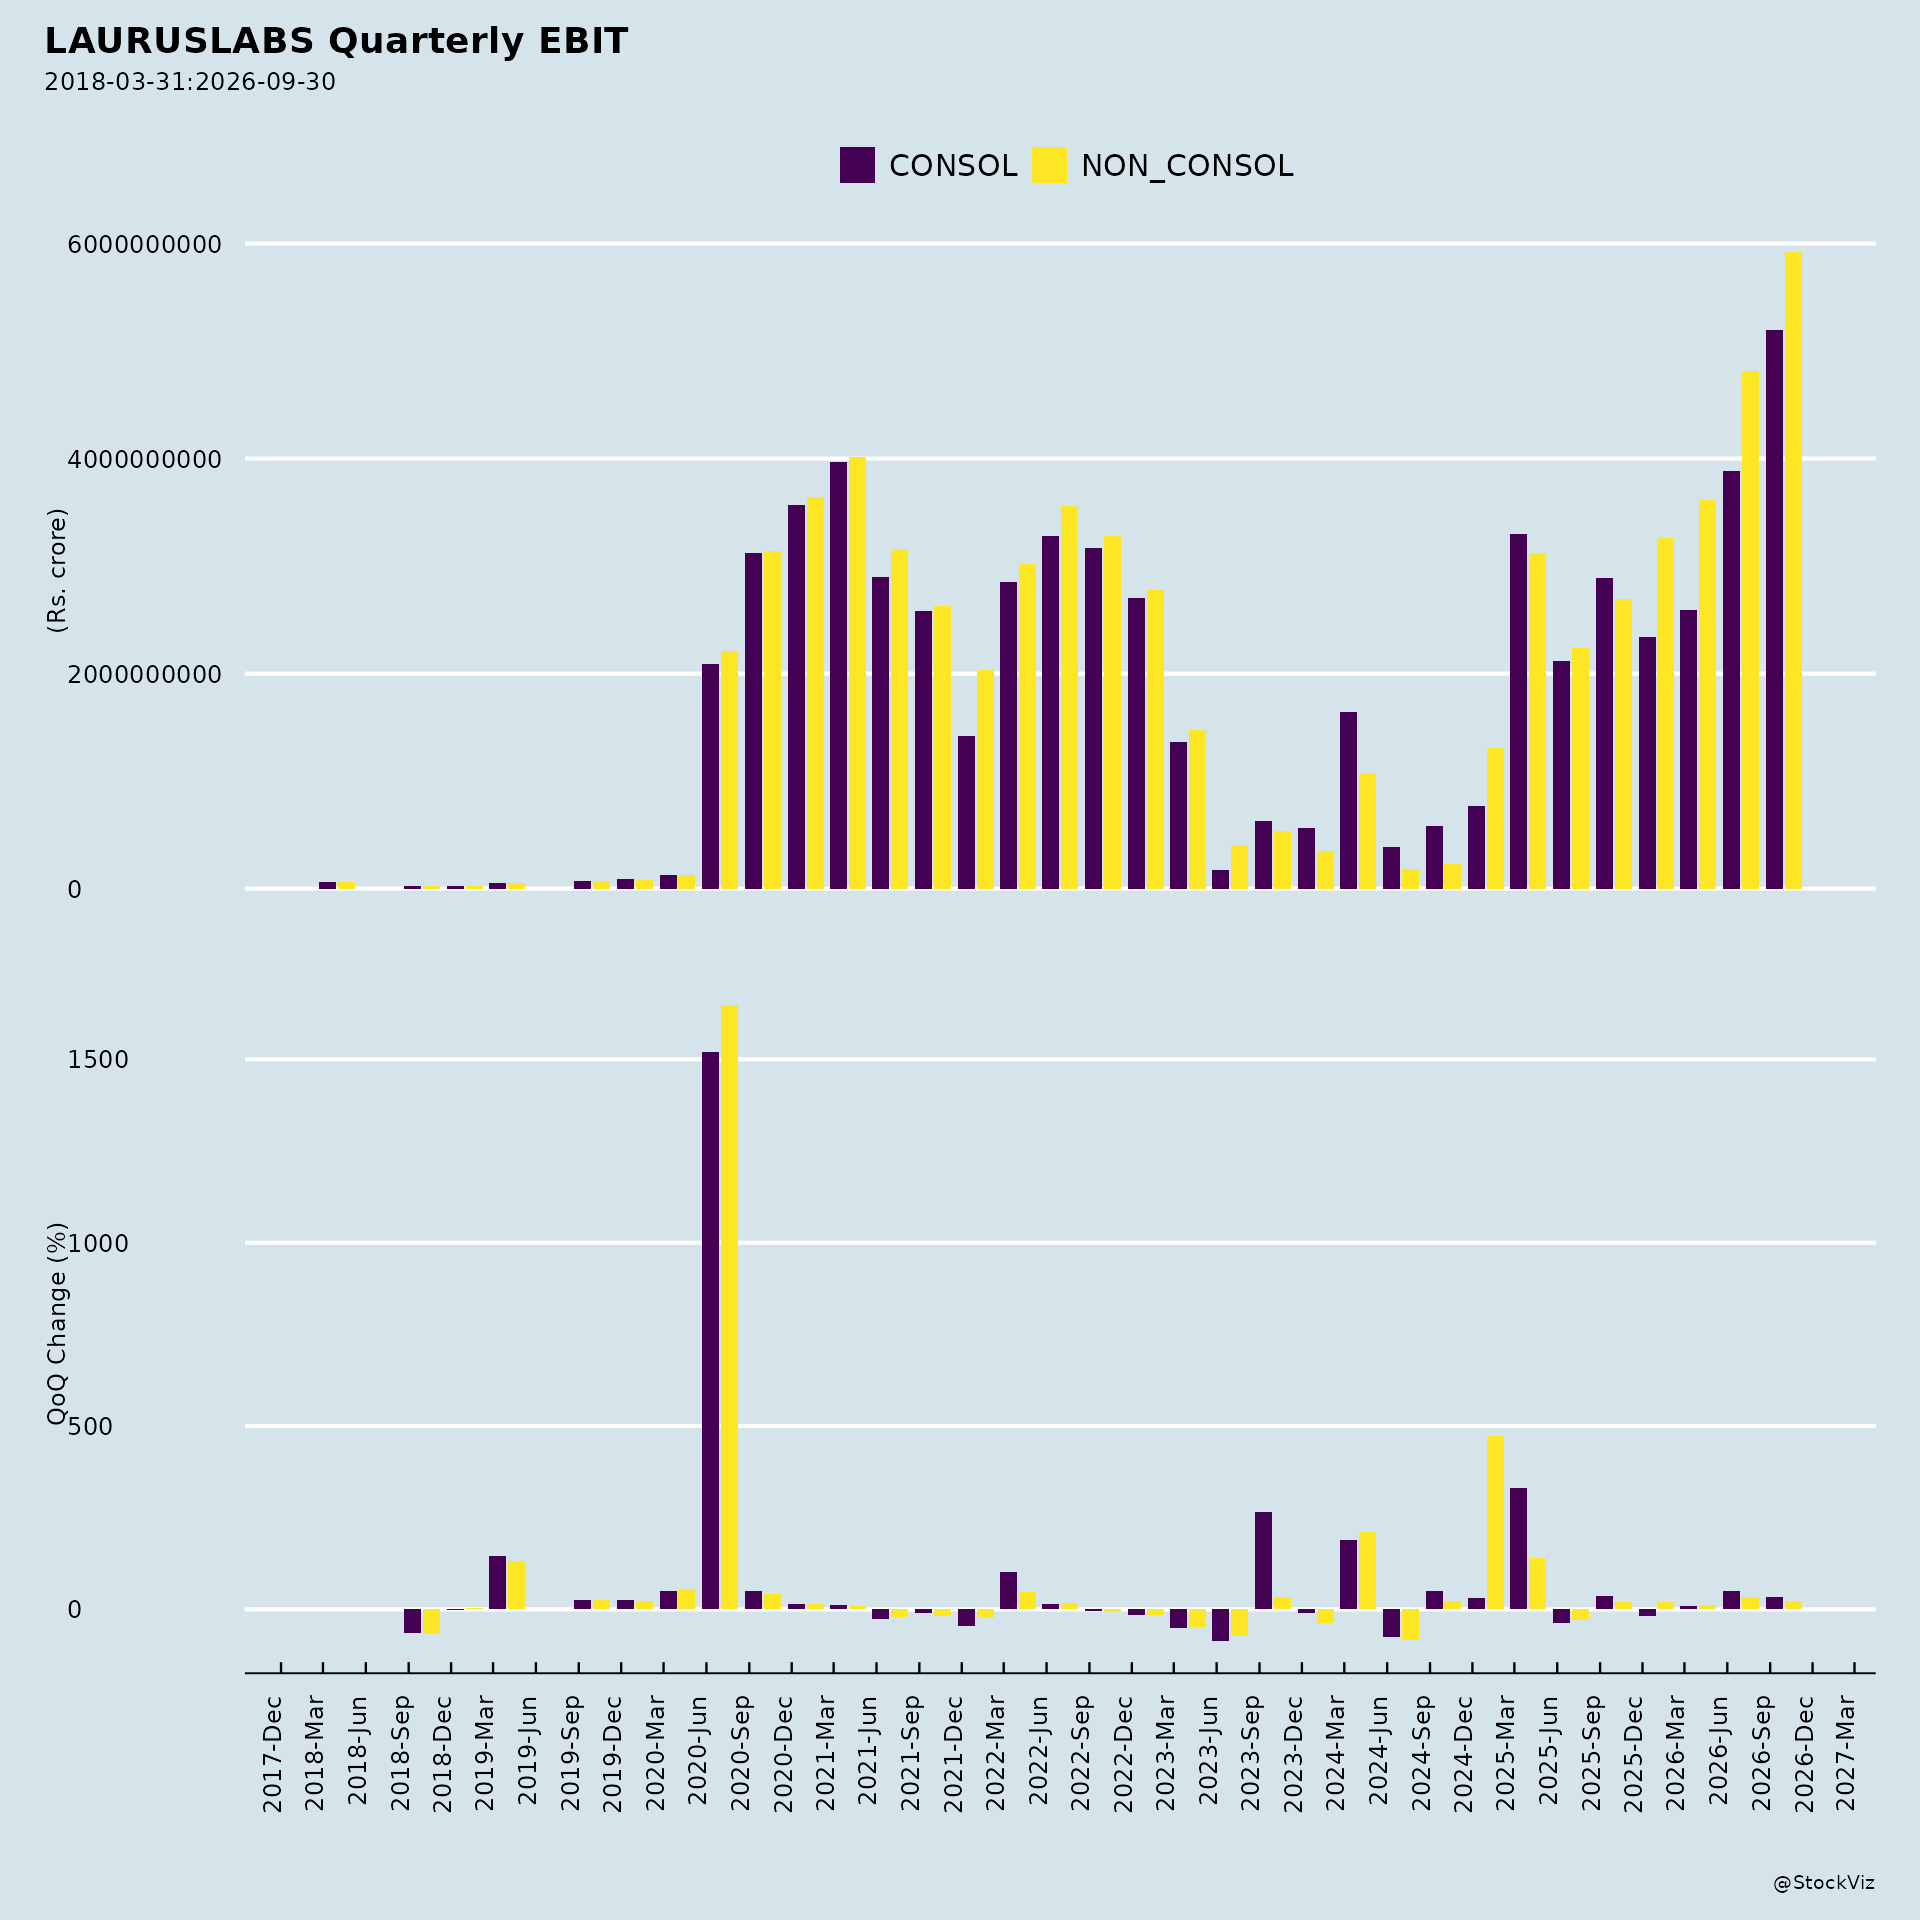
- Record quarterly revenue and profitability: Q1 FY27 revenue was ₹2,026 Cr (up 29% YoY), EBITDA ₹644 Cr (up 66%), EBITDA margin 31.8% (up 7.0 pts), PBT ₹481 Cr (up 115%), net profit ₹368 Cr (up 126%), and diluted EPS ₹6.8 (up 127%).
- CDMO momentum: CDMO revenue rose 67% to ₹870 Cr, with small molecules up 69% to ₹835 Cr, driven by late-stage clinical and commercial API supplies and ramp-up of growth projects. The pipeline includes more than 125 active projects across human health, animal health and crop science.
- Bio business: Bio revenue rose 21% to ₹35 Cr, with strong traction in enzymatic technology applications; the fermentation facility is expected to be commissioned by Q3 FY27.
- Affordable Medicines: Revenue rose 10% to ₹1,156 Cr, driven by steady ARV, established product volume growth and new launches in the US; FDF grew 22% to ₹502 Cr.
- Capacity and capability expansion: CAPEX was 19% of sales, with planned increases over FY27 and FY28 across small molecule (human and animal health), fermentation, peptides, gene therapy and antibody drug conjugates. Large-scale API and fermentation capacity expansion continues in Vizag.
- In-licensing of ADCs: The Company agreed to in-license two Antibody Drug Conjugates from Aarvik Therapeutics for development and commercialization in India.
- KRKA joint venture: The FDF site is fully on track, with Phase-I production blocks to open in mid-2027 focusing on High Potent and General OSD capability.
- Filings: Cumulatively 92 DMFs filed; 2 product dossiers filed in Q1 FY27, taking cumulative developed-market FDF filings to 96 products.
- Quality and ESG: 24 quality audits completed in Q1 with no critical findings; SBTi approved near-term science-based emissions reduction targets; NSE Sustainability assigned an independent ESG score of 63/100 for FY2026.
- Land parcel: Final handover of a new land parcel was secured, reinforcing the long-term growth strategy.
- R&D investment: Total R&D including capex R&D was ₹118 Cr (5.8% of revenue), up 74% YoY, directed at Advanced Biologics infrastructure (gene therapy/ADCs).
3. Key Risks
- Macroeconomic and supply chain uncertainty: Explicitly cited as a challenge in the quarter, with continuing global supply chain issues affecting the Affordable Medicines division.
- Regulatory and approval risk: The Composite Scheme of Arrangement is subject to NCLT and other authority approvals; the appointed date is April 1, 2026 or such other date as the NCLT may approve.
- Forward-looking statement risk: The Company’s disclaimer notes that statements are subject to risks and uncertainties including regulatory changes, local political or economic developments, and other factors that could cause actual results to differ materially.
- Dependence on CDMO commercial projects: The strong CDMO growth was driven by commercial deliveries and ramp-up of growth projects; the pipeline is described as healthy but the business remains exposed to project timing and customer demand.
- Subsidiary performance: Certain subsidiaries recorded a net loss after tax of ₹5.96 Cr in the quarter.
- Governance-related dissent: Notable minority votes against director appointments and remuneration resolutions at the AGM.
4. Management Guidance vs Observed Business Performance
- CAPEX program: Management stated it is “continuing on our key CAPEX program to drive near and long term growth,” with CAPEX at 19% of sales and planned increases over FY27 and FY28 “well on track.” Observed: CAPEX spending and progress on Vizag API/fermentation capacity, peptides, gene therapy and ADC capabilities are consistent with this stated direction.
- Fermentation facility: Management expects the fermentation facility to be commissioned by Q3 FY27. Observed: The Bio business grew 21% YoY in Q1 FY27 with strong enzymatic technology traction, but commissioning is still pending.
- KRKA JV: Management stated the FDF site progress is “fully on track,” with Phase-I production blocks to open in mid-2027. Observed: No contrary evidence in the material; capital contribution of ₹49 Cr for the 49% stake was made in the quarter ended December 31, 2025.
- Portfolio transformation: Management described continued portfolio transformation driven by CDMO commercial deliveries and Affordable Medicines strength. Observed: CDMO grew 67% and Affordable Medicines grew 10%, with gross margin expansion of over 3 pts to 62.7% attributed to favorable segment mix, supporting the transformation narrative.
- Sustained growth confidence: The CEO expressed confidence in delivering “sustained growth and value creation.” Observed: Q1 FY27 delivered record quarterly revenue with expanded profitability, and the Company continues to invest in niche capabilities and integrated offerings.
- Dividends: The 21st AGM ratified a 1st interim dividend of ₹0.80 per share and a 2nd interim dividend of ₹1.20 per share for FY2025-26, both passed with over 99.99% votes in favour.
- Auditor review: The statutory auditors issued an unmodified conclusion on both standalone and consolidated results for the quarter ended June 30, 2026.
Broker Narrative
The broker narrative shifted sharply from a defensive, post-earnings-miss tone in July 2023 — focused on margin contraction, FDF/API weakness, CDMO high-base drag, and estimate cuts — to a confident long-term growth story by July 2026 built on a ~70% CDMO ramp, 31.5% EBITDA margin, and aggressive capex/LPZ expansion. Persistent themes were CDMO strengthening and formulation/bio recovery, while the emphasis changed from near-term operating deleverage and earnings risk to sustainable CDMO mix, targeted capital deployment, and long-term R&D infrastructure.
Broker Timeline
16 broker calls · 2023-07-27 to 2026-07-26
CNBC-TV18: ratings, targets and commentary
Extracted from CNBC-TV18 posts; ratings and targets are as published, not current consensus. OCR may contain errors. Speaker attribution is retained; not all speakers are brokers. These statements are separate from the Broker Narrative and Broker Timeline and have no calculated performance or outcomes.
Other company commentary (not broker ratings)
| Published / source (IST) | Speaker / affiliation | Rating / target | Commentary |
|---|---|---|---|
| 2026-11-17 |
Laurus Labs
Mgmt
|
—
|
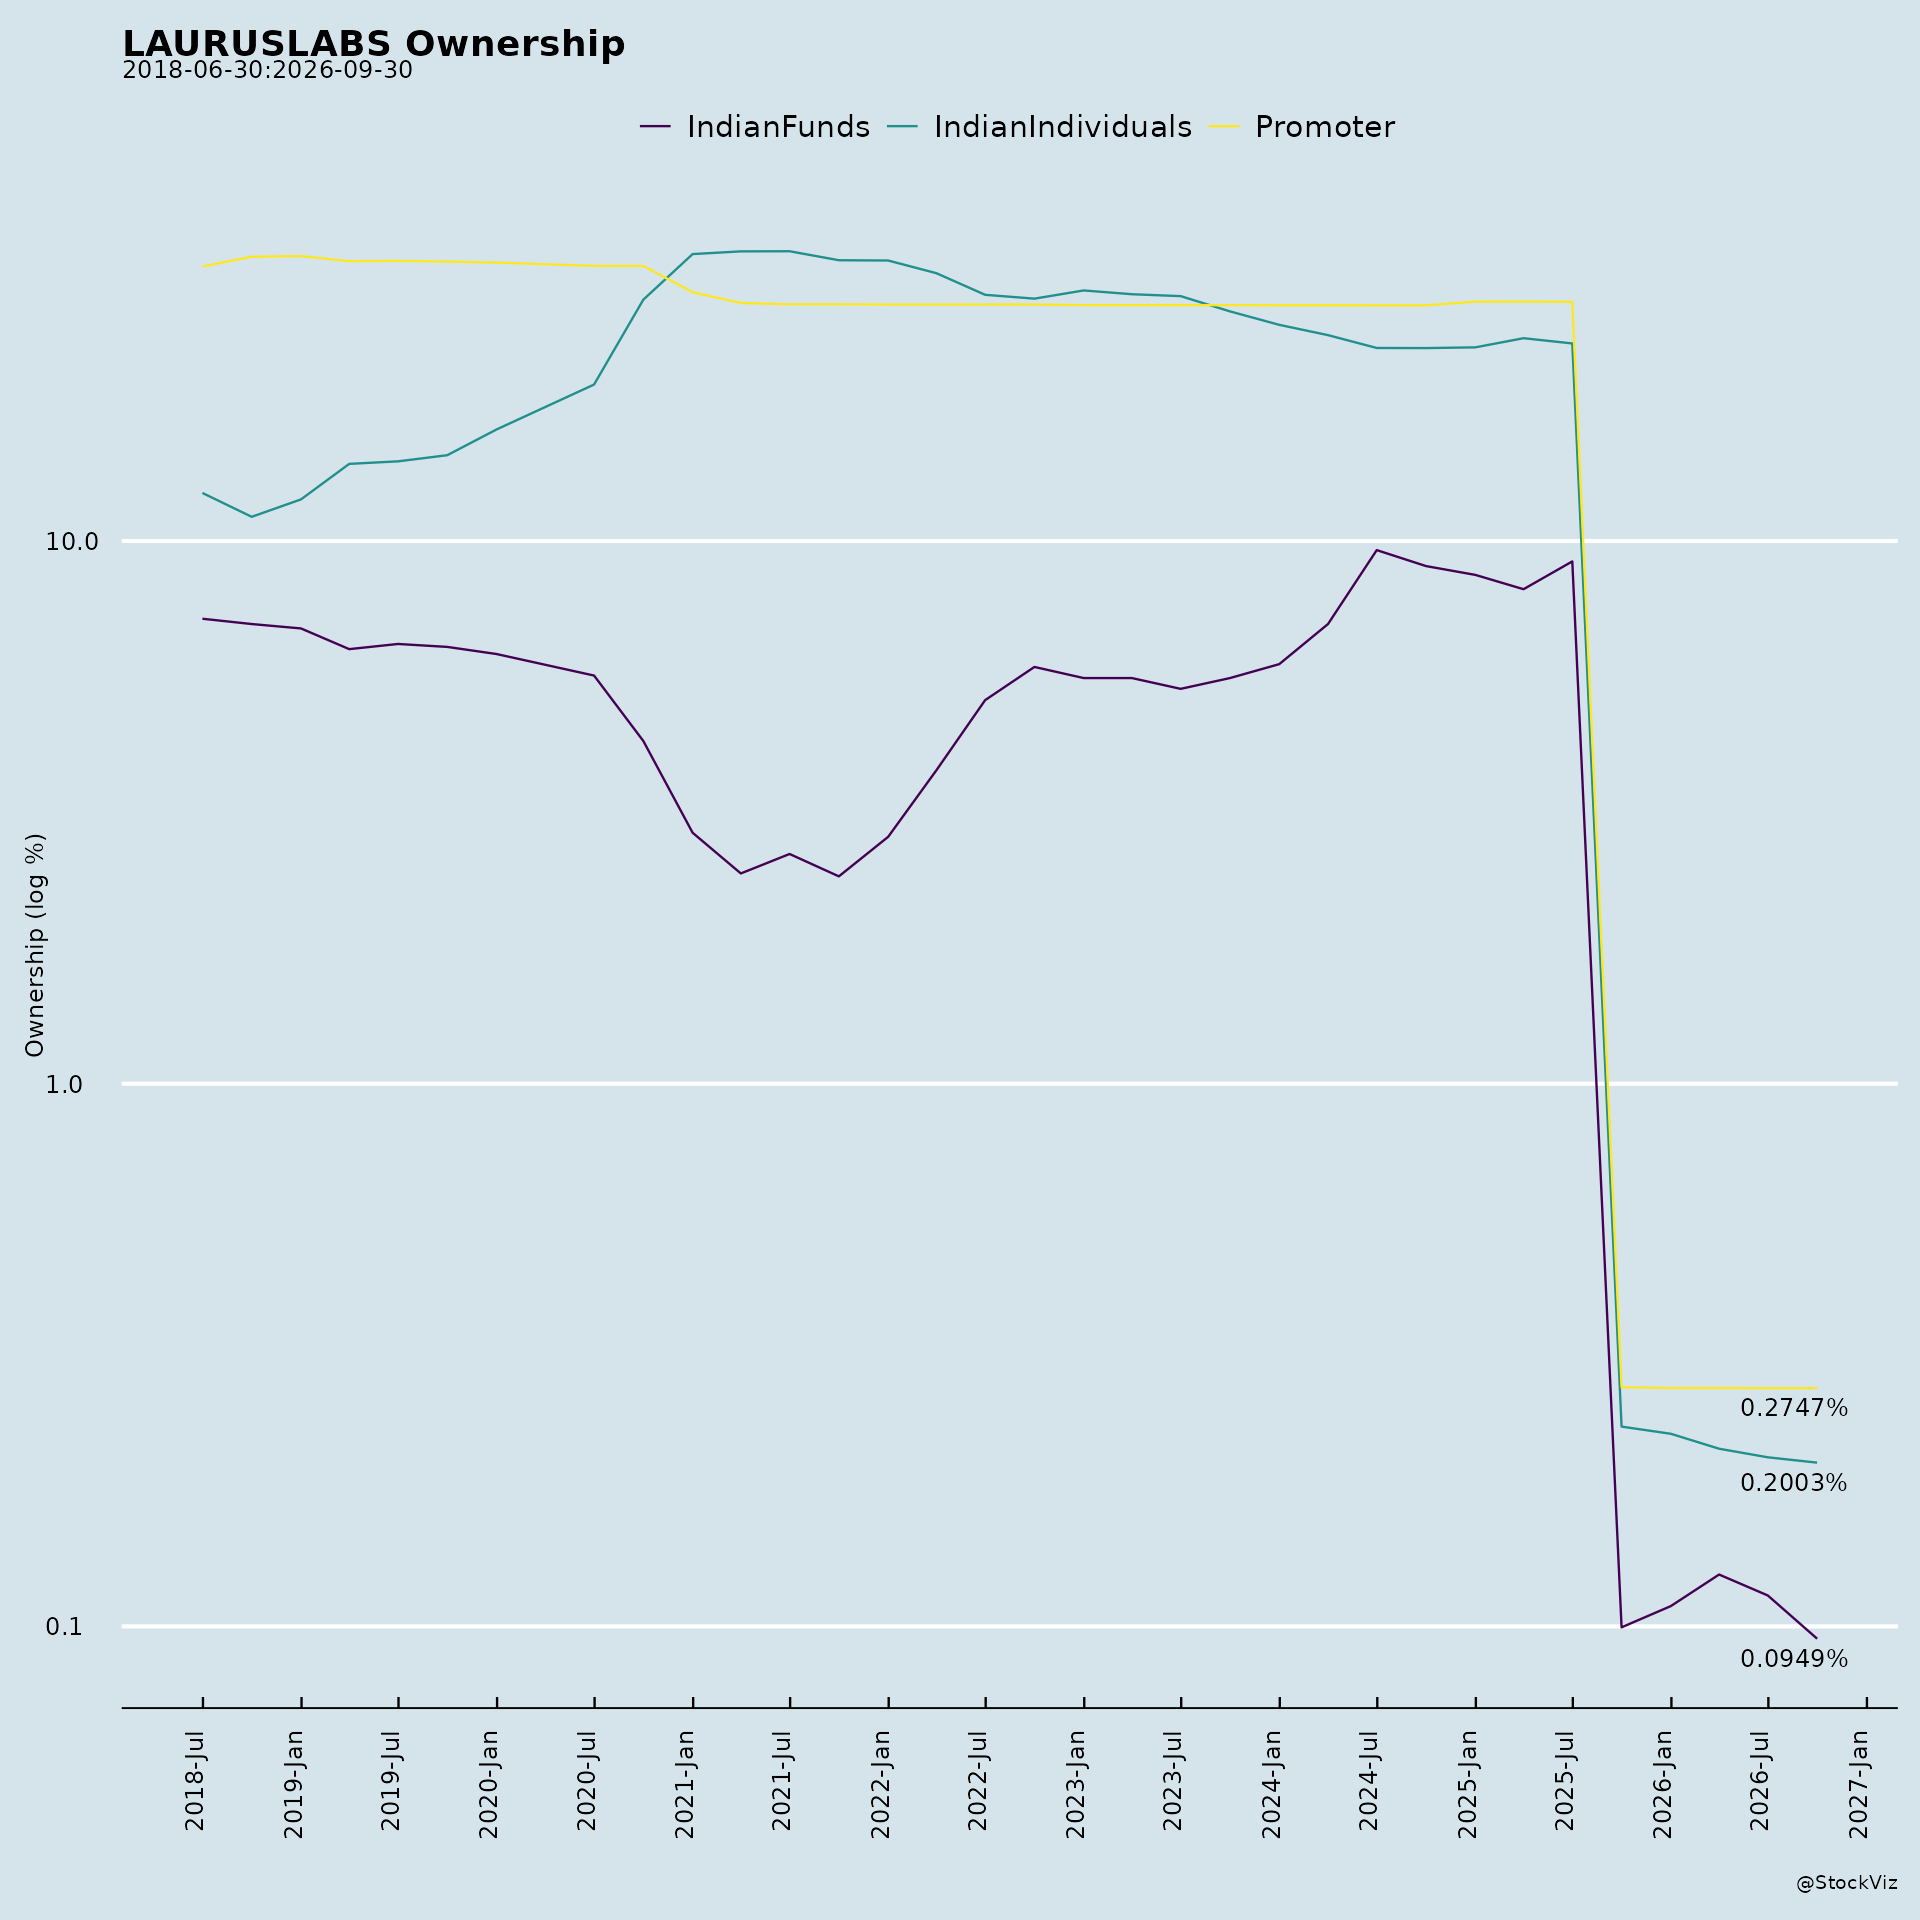
Promoters have no plan for further stake sale. Stake sale was done to pay off debt and for philanthropy purposes. |
Management comments
No recorded management comments with an explicit designation and affiliation for this ticker.
Copyright © 2023 SAS Data Analytics Pvt. Ltd. All rights reserved.